Thousands of courses for $10 728x90
‏إظهار الرسائل ذات التسميات Good Financial Cents. إظهار كافة الرسائل

الأربعاء، 23 يناير 2019

Liberty Tax Review

Whenever tax time rolls around, many people panic. Those returns should be simple to complete. All you need to do is to fill in the correct details on the correct form. It sounds easy enough, and it can be if you know exactly what forms to complete.

For most people, however, knowing what form to use and inserting the right information becomes difficult. This is not an area where you want to make a mistake, either. Leave out a vital piece of info, and it could look like you’re trying to underpay the government.

At the very least, a mistake could cost you that refund that you’ve worked so hard to earn. That’s why so many people turn to tax preparation software to help them get it right the first time.

In this Liberty Tax review, we’ll look at what the company offers and whether it lives up to its promises. Let’s examine things a little more closely before we make a final decision.

Liberty Tax Promises to Make Filing Your Returns a Breeze

Liberty Tax LogoLiberty Tax has a number of beneficial tools both for its basic users with less complicated returns and those with trickier finances, also providing assistance for users facing audits.

The software is built on the motto, “You do life. We do taxes,” and the services it offers aim to take the tedium of tax-filing off your shoulders.

Here are some of the features that we feel make this software an asset.

Key Features

  • Ability to Import Forms: It’s not that hard to fill in the details yourself, but it’s a lot easier if the software can do it for you. With this software, you can download the W-2 from your employer. You can also download your prior return from any source.
  • Credit Maximizer: The main reason that you want help with your return is so that you get the maximum refund possible. This feature analyzes your figures and ensures that every qualifying deduction or credit is accounted for.
  • You Can Amend Your Return for Free: This doesn’t sound like a big deal until you consider that TaxAct software, for example, charges you $19.95 to do the same thing. Hopefully, you’ll get the return right the first time around. It’s nice to know that you have this option, however.
  • Free Customer Support and Expert Advice: Maybe there’s something that you just need to check quickly. The company has several channels open to clients. You can email them, call them, use instant chat, or reach out via social media.
  • Audit Assistance: This has to be one of the scariest notices that an adult can receive. It’s enough to reduce a lot of people to a nervous wreck. Liberty Tax can provide advice on how to proceed.
  • Get Your Return Checked: Liberty stands behind its product. At participating branches, you can take your return to a consultant. They’ll give it the once over to check for correctness so that you have extra peace of mind before submitting it.
  • Useful Online Tools: There are several calculators that make your life easier. You can get a rough idea of the refund you can expect, and there are other tools that help you prep for your return. The Tax Organizer, for example, will help you to get all the proper documents together.

Liberty Tax Lets You File Your Returns with Full Confidence

It Has a Very User-Friendly Interface

The interface has been designed to be easy to use. You don’t have to hunt around to find the right buttons – the navigation and layout are simple enough to read.

What’s more, they’ve been as sparing as possible when it comes to excess information.

You don’t have to scroll through pages of needless information to get what you need.

There is Branch Support as Well

With 4 000 local branches, you are bound to find one nearby you to consult if you get stuck.

The system has been designed so that it is easy to transfer the application from an online one to an in-person one so you get the assistance you need when you visit a branch in person.

You Can Flip Through the Application Easily

With some software, you have to work section by section, always completing one section before moving onto the next. When you’re completing a tax return, this isn’t always convenient.

Maybe you’ve forgotten to get a key piece of information, or you want to skip ahead. This software makes it easy to switch back and forth.

Get Your Refund Upfront

In some cases, you might qualify for a refund advance, and Liberty Tax will be sure to get you the money you qualify for.

The company will lend up to $3,250 as an advance on your refund if you qualify.

That’s quite a big chunk of change for an advance, one of Liberty Tax’s most appealing features.

What If Your Situation Is More Complicated?

If you have rental income or need to file in more than one state, for example, you need to choose one of the more advanced packages like the Deluxe or Premium options that Liberty Tax offers.

If you’re still concerned, you can opt to make an in-person application in a branch instead, where you can get more hands-on assistance from the Liberty’s team of professionals.

File your taxes with Liberty Tax>>

How Much Does Liberty Tax Cost?

Liberty Tax offers users 4 paid levels of service for filing their federal and state returns, ranging from as low as $14.95 to as high as $69.95 for federal returns.

  • EZ package: Federal return: $14.95; state return: $39.95
  • Basic package: Federal return: $28.95; state return: $39.95
  • Deluxe package: Federal return: $43.95; state return: $39.95
  • Premium package: Federal return: $69.95; state return: $39.95

Let’s take a closer look at all of the features that you can access with each of those levels of service. Which package is the best fit for you boils down to how complex your tax needs are.

Liberty Tax Versions

EZ

This is the software version for you if your return is simple.

You don’t get to list deductions, and there is no room for extra income, but filing with this package means there are no complications at all.

Basic

This plan encompasses a bit more than the EZ package.

The basic package is not going to be much use to you if you have a complicated tax situation, like if you have multiple sources of income.

 But it does allow you to itemize your deductions a little more than the EZ package.

Deluxe

If your situation is more complex, this plan is where you should start looking.

The deluxe package is popular with those who freelance or run a small home business. It won’t handle issues related to capital gains, however.

Premium

If you want to be able to do it all, this is the package for you. The Premium plan comes with professional tax advice from Liberty’s experts and audit consultation.

It’s also a good option for those with a medium business, farmers, and those with multiple income sources.

Other Considerations

Now that we’ve gone through the pros, let’s have a look at the negatives.

  • Liberty only offers paid options. Most companies allow their clients some form of basic free service. Liberty is not like most in this respect.
  • The packages border on pricy. You get a lot of features, but the prices are higher as well.
  • The site can be annoying because it times out quickly. If you’re inactive on the site for what seems like a few seconds, it will time out. What really annoyed us here is that it timed out even if we were checking out the “Learn More” links.
  • The customer service aspect needs to be improved. Don’t get us wrong; they deliver excellent customer service, but only as long as you’re able to contact them during normal business hours. In this day and age, we expected at least a 24-hour chat option for basic queries.

The Verdict

With Liberty Tax, results and accuracy are guaranteed. The company promises to get the best possible results and create completely accurate returns.

Overall, the positives do outweigh the negatives. You’ll battle to find software with quite so many useful features built into it. You do have to pay a bit more, but you are getting a better-quality product overall.

The support hours are an annoyance, but it’s not a deal-breaker. Overall, we’d say that the experience is a positive one. We’d be confident about submitting our returns through this service.

Get started with Liberty Tax>>

The post Liberty Tax Review appeared first on Good Financial Cents.


Source Good Financial Cents http://bit.ly/2R6DRi1

FreeTaxUSA Review

Doing your own taxes can be an overwhelming and confusing task, especially if you don’t have sufficient experience in tax return filing or if you have a complicated situation. Since hiring a CPA or other professional can be cost-intensive, many people opt to undertake the task themselves.

Tax software became increasingly popular for preparing and filing federal and state returns, not only because they are reaching new levels of sophistication, but also because filing online saves time and money. It also makes tax return filing error-free.

FreeTaxUSA is one of the fastest-growing tax platforms and IRS-authorized e-file providers. Their services are reliable, and they offer free federal filing. Even if you have a complicated financial situation, FreeTaxUSA may be the most suitable tax software for you.

How it Works

FreeTaxUSA logo

FreeTaxUSA uses an interface that prepares your federal and state returns by taking an online step-by-step interview approach. As you answer questions and import your information, the software will prepare and fill out your tax return.

Upon completion of your information entry, you can review your return before submitting it to the IRS via mail or e-file. The software interface is user-friendly and intuitive.

If you have no prior experience with tax filing or software, you will be able to find your way through the process with little difficulty.

Keep in mind that the interface has a somewhat clinical appearance and doesn’t feature the same slick design and color schemes that you will see with other prominent tax software.

When you enter your information, you can import forms in PDF format from competitor platforms like TurboTax, H&R Block, and TaxAct. You can also import from your internal storage. When you fill out your information, the interface will not allow you to skip forward.

You will only be able to edit the sections that you are currently working or the ones that you already completed. FreeTaxUSA supports various complex tax situations, and you will be able to view your tax refund or liability in real time as you enter your information.

Features

Affordable Care Act

If you didn’t have healthcare coverage during the tax year, FreeTaxUSA will accommodate any fees that you may have to pay.

The platform will also assist you if you want to claim exemption from the penalty, a valuable asset to many tax filers looking to save.

Refund and Payment Options

You can use a credit or debit card to pay for FreeTaxUSA’s tax preparation and filing services.

If you are eligible for a tax refund, FreeTaxUSA can facilitate the payment through either a direct deposit into your bank account in less than 21 days or through a check, which can take up to six weeks.

Filing After Deadline

If you’ve missed the tax deadline, you may be panicking about getting your taxes filed on your own, let alone getting them filed affordably.

Luckily, FreeTaxUSA offers tax return preparation and filing services at the same price, even after the tax deadline passes. 

However, they encourage their clients to file their returns as soon as possible to avoid IRS penalties. 

Audit Assist

FreeTaxUSA often receives recognition for the Audit Assist services that they provide to Deluxe clients. With Audit Assist, you gain access to tax and audit specialists that will help you prepare for an IRS audit. They will answer any audit-related questions that you may have.

This service also includes access to FreeTaxUSA’s audit center, which is a knowledge bank that contains information on the audit process.

However, Audit Assist is only applicable to federal returns and not state returns, and FreeTaxUSA doesn’t offer any audit representation services.

Free Tax Calculator

By setting up a FreeTaxUSA account and entering your tax information as well as you can, you can use the platform as a calculator to estimate your taxes, determine your refund or liability, and find deductions and credits like the Child Tax Credit.

After you’ve entered your information, you will see an estimate of your taxes, refund or liability, and credits and deductions.

Since you can view this information without filing your return, you can keep it on record and edit your data before you have to submit.

Accuracy Guarantee

FreeTaxUSA accepts responsibility for all errors on the system’s end. If the IRS imposes interest or penalties for incorrect tax calculations, the company will pay them.

This feature offers peace of mind to filers who don’t want to worry about the financial repercussions of a miscalculation. As long as you’ve entered all your information correctly, you’re covered.

Free Support

Regardless of the FreeTaxUSA version that you use, you can visit their customer support page to search for support topics or email their customer support team if you have a problem.

If you are subscribed to the Deluxe plan, you get access to free support chat and the Q&A database.

Online Backup

FreeTaxUSA backs up all tax returns online and carries information over from one year to the next, even if the client uses the Free version.

If you haven’t used FreeTaxUSA the previous year, you can import your tax information in PDF format from competitor software, your internal storage, or your employer’s platform.

Uploading your PDF in this manner is incredibly easy, and it saves a lot of time.

Versions

FreeTaxUSA offers two versions: Free and Deluxe. There is not a big difference between the two of them regarding the actual process of preparation and filing.

Both support complex tax situations and schedules, and you can use either of them for federal and tax filing. State tax returns, however, cost an additional fee with either version.

One of the significant advantages of FreeTaxUSA as a whole is that both versions support Schedule C filing for self-employment income, Schedule E filing for rental property income, and Schedule D for capital gains transactions.

You can also report several K-1 related income sources with these plans. The difference between the two versions has more to do with the customer support you receive.

Pick a FreeTaxUSA version>>

Free

Clients that select the Free version can prepare and file federal tax returns, they have access to FreeTaxUSA’s e-file service, and their account information is carried over to the next tax year.

Free version clients can also print their tax returns on paper or PDF, backup their completed tax returns online, and file for a federal tax extension.

As mentioned above, they can also use the free platform to prepare and file complex tax returns. State return preparation and filing are not free with this version, however, and the client has to pay $12.95 per state return.

If you are subscribed to the Free plan, you can get additional services at a nominal fee, including:

  • Completed tax return amendment
  • Priority customer assistance
  • Professional return printing
  • Return printing and binding

Audit Assist is not available to people who are subscribed to the Free addition as an included or additional service. If you need such assistance, you will have to upgrade to the Deluxe plan.

Deluxe

The Deluxe version costs $6.99 and includes everything in the Free version, as well as Audit Assist and professional printing. As is the case with the Free version, state filing also costs $12.95.

With this version, clients also receive free technical and tax support.

Pros

  • An affordable alternative for people with complex tax situations
  • Free federal return filing and accessible state return filing
  • Intuitive interface that is easy to understand
  • Audit Assist for Deluxe clients
  • Suitable for people with varying levels of tax situation complexity
  • Supports Schedule C, D, and E

Cons

  • Neither version supports all tax situations
  • Customer support options are limited
  • This software offers fewer features than its competitors

Should You File with FreeTaxUSA?

FreeTaxUSA has a whole host of features to benefit tax filers with both its free and premium versions. Whether you’re filing the most basic of taxes or facing an impending audit, FreeTaxUSA can help.

Overall, FreeTaxUSA is the best bet for those on a tight budget or those who have a bit of experience filing their taxes. If you fit one of those descriptions, then FreeTaxUSA could be a great affordable tool for your filing needs.

You can also use my federal income tax guide alongside FreeTaxUSA to work through your taxes this year.

Get started with FreeTaxUSA today>>

The post FreeTaxUSA Review appeared first on Good Financial Cents.


Source Good Financial Cents http://bit.ly/2B2FF6x

الجمعة، 18 يناير 2019

Best Tax Software Programs

Tax season is a stressful time of year, but there is help available for those who want to file returns themselves.

Online tax software simplifies the filing process without costing you a lot of money.

But choosing the right software for your needs can be a challenge, so we’ve broken down each of the best tax software options for you.

Each of the tax products on the list has unique features and packages to choose from.

The best pick for you depends on how much you want to spend and how complex your filing needs are.

Without further ado, let’s dive into the top software picks so you can file your taxes with confidence this year.

Top 15 Best Tax Software Programs in 2019

1. TurboTax

TurboTax is widely regarded as one of the most user-friendly systems available to help you navigate through the process of filing your taxes.

This software features intuitive tools to help you find deductions, notify you of errors, and help you file your state return.

One of the most significant drawbacks of this software is pricing, and you can expect to pay a premium when you use TurboTax when compared to others.

There is a free option, however, but it is limited and more suitable for filing simple returns.

TurboTax is free in the following situations:

  • W-2 income
  • Limited interest dividend reported on 1099
  • Standard deduction claim
  • Earned income tax credit
  • Child tax credits

If you’re filing a basic 1040EZ or 1040A, the Free version will be sufficient. 

However, when it comes to itemized deductions, like business and side-hustle income, stock sales, rental property, Schedule 1 to 6, credits, deductions, and income, you will have to upgrade to the Deluxe version.

This version offers high-end features to ensure your tax filing experience is as quick and painless as possible.

You can read more about TurboTax here.

2. H&R Block

H&R Block produces popular software for filing taxes that features straightforward imports and 24/7 customer support via chat.

Another benefit of using H&R Block is it offers complete integration with many mainstream business apps, including Uber.

H&R Block employs a so-called “semi-guided” navigation system to guide users through the process of answering questions, entering income, and importing forms. Upon completion of each guided session, you get the opportunity to review all the information to ensure that there are no mistakes or omissions.

Like TurboTax, H&R Block is user-friendly, especially when it comes to importing forms. The software is also geared towards reducing the time and effort typically associated with tax prep.

H&R Block also offers “knowledge articles” that are easy to understand and provide sufficient information to help users file their taxes in accordance with the new laws. This software is ideal for traders, dividend investors, and landlords.

If your tax returns are simple, the free version of this software may be more than sufficient.

Take a look at our full review of H&R Block for more info.

3. TaxAct

TaxAct is a basic, high-performing tax software that mostly offers the same features as its competitors, including importing last year’s returns and W-2 as well as donation assistance and planning tools.

The software is online as well, so you can log into your account from different devices and locations.

If you need advanced tax software, TaxAct’s products may be the better option as they are, generally speaking, more affordable than packages from H&R Block and TurboTax.

There is also a free version that you can use if you qualify to file the 1040EZ.

If you have to file a 1040 or 1040A, however, you will have to upgrade to one of the paid versions.

TaxAct’s interface is relatively simple in comparison with its higher-end competitors.

If you prefer a straightforward design and value low pricing, TaxAct may be the more suitable option for you.

Get all the insight into this tax software in our TaxAct review.

4. E-file

Many users prefer E-file not because of its user-friendliness, but rather because of its low pricing. E-file is one of the most affordable tax software products available.

What’s more, if you qualify for a 1040EZ, you may be eligible for free federal tax returns.

In addition to the Free Federal E-file plan, you can also opt for the Deluxe Plus E-file or the Premium Plus E-file.

The paid versions are affordable in comparison with similar versions and offer the ability to deduct mortgage interest, receive support for form 1040A, and file with dependents.

In addition to all the features of the Free and Deluxe plans, the Premium plan also offers support for all deductions and credits, itemized tax deductions, and all personal and business income.

Another feature that users love is that they can pay for E-file tax preparation services using a portion of their refund, in addition to the usual debit and credit card options. 

5. FreeTaxUSA

Like E-file, FreeTaxUSA is one of the most affordable tax preparation and planning services available. From the name, you may be forgiven for thinking that it is a free service, but this is not entirely the case.

FreeTaxUSA offers two online filing options: Free and Deluxe. While both of these plans allow for free federal filing, you will have to pay for state filing.

The Deluxe plan is affordable, and the price remains the same, regardless of the complexity level of your taxes. The software navigates you through a straightforward interview process and allows you to import your tax return from competitor software.

In addition, you can access tax and technical support via web chat.

With the Deluxe option, you get Audit Assist to answer your questions and help you prepare in the event of an audit.

6. Liberty Tax

Liberty Tax features a user-friendly interface and is a popular choice for tax software, especially since it allows you to import your W-2 through ADP, which saves time by auto-populating your personal information.

Another feature that users love is that this software shows your risk of being audited.

One of the most significant differences between Liberty Tax and most other tax preparation and filing software products is that it doesn’t offer a free version.

As a result, if you want to file a basic 1040EZ return, you will have to pay.

For itemized deductions or filing a 1040A, Liberty Tax’s basic version will be sufficient, but if you have investment income, you will have to opt for the premium version. With Liberty Tax, you can receive your refunds via direct deposit, prepaid card, or check.

7. Tax Slayer

Tax Slayer has an interface, features, and support that are comparable to that of their higher-end competitors like TurboTax.

There are several options available, including:

  • Free package for 1040EZ filing
  • Classic package for landlords, itemizers, etc.
  • Premium package for audit assistance and access to tax professionals
  • Self-employed package if you have a state return to file
  • If your tax preparation and filing needs are relatively basic, the Free plan may seem like the best options. Keep in mind, however, that this plan only allows you to file a 1040EZ. You also will not be able to access free tax support.

The other plans offer a wide range of valuable features, including the ability to take a picture of your W-2 instead of manually typing in all the numbers. There is also a side-banner to help you keep track of the process.

If you need an effective tax planning service but are not willing to pay a premium for high-end software like TurboTax or H&R Block, Tax Slayer may be a viable option.

8. Credit Karma

Credit Karma is well-known for their credit monitoring service, and now you can use their software for federal and state tax filing for free.

Since it supports almost all forms, you can rest assured that it will be able to meet all your basic tax filing requirements.

If you have strict budgetary restrictions, Credit Karma may be one of your best tax filing service options.

Although this software doesn’t feature interview-style navigation, it has a user-friendly interface, and you will be able to see how your income, deductions, and credits affect your tax refund from your dashboard.

There are some drawbacks to this software.

The only forms you can import are W-2 and tax returns from the previous year. Credit Karma’s tech support is also somewhat lacking. If you are, for example, an active trader, this software may not be entirely suitable for your needs.

On the other hand, if you have basic tax filing requirements and a limited budget, look no further than Credit Karma.

9. Jackson Hewitt

Jackson Hewitt is a high-end tax planning service that allows you to file online as well as at its stores. It also offers a wide array of filing options, and you can choose one that fits your unique financial situation.

Another great thing about using Jackson Hewitt is the unlimited email and chat support.

Jackson Hewitt has three different filing options: one is free and two are paid. The free plan includes 1040EZ filing and straightforward tax return import, as well as unlimited live chat.

The paid plans allow you to report dependents, mortgage interest, student loan interest, and simple self-employed income.

Jackson Hewitt may be a suitable tax planning service regardless of your what your financial situation is. The Jackson Hewitt website is not clear on how each option is best for different users, and their services are not the most affordable in comparison with their competitors.

Their pricing and services are, however, on par with those of the market leaders.

10. eSmart Tax

eSmart Tax is Liberty Tax’s online tax software and features a Free and Premium version.

The Free version is suitable for users that want to manage simple tax filings like child and dependent care credit, while the Premium version takes care of business, investment, and real estate income.

eSmart Tax provides a wide range of additional features to make life easier for their users.

These features include accurate creation of 1040 returns with itemized deductions and quick and easy import of prior year return information from eSmart, as well as competitors like TurboTax, TaxAct, and H&R Block.

The tax preparation software also allows you to import your W-2 and 1099 forms to make return creation quicker and to eliminate errors.

If you have extensive experience with e-filing and are looking for an affordable solution, eSmart Tax may be a suitable option for you.

11. ezTax

ezTax charges a flat rate for federal and state tax filing regardless of the type of form that is required.

This tax preparation software is straightforward and easy to use for essential tax return preparation.

The software is mainly similar to other mid-range products. Before you complete the forms, you can choose from a guided or do-it-yourself option.

If you have some experience and know how to complete the forms, the do-it-yourself option will allow you to move through the process quicker.

ezTax can manage more advanced tax filing processes, but since this service charge the same fee for every type of 1040 that you are required to file, you will pay for, say, a 1040EZ, where other products offer these services for free.

12. Community Tax

Community Tax specializes in debt relief and also provides a complete tax assistance service.

Community Tax uses IRS tax records to ensure that all your income and expenses are accounted for, and their review team analyses returns to ensure that there are no mistakes.

As their client, you will also receive a dedicated tax preparer that has an IRS power of attorney.

Community Tax can help you with all of the following:

  • Rental income
  • Stocks
  • Interest Income
  • Dividends
  • Unemployment compensation
  • Gambling income
  • Revenue out of the sale of assets

If you require assistance with your business’s tax return, Community Tax’s preparation and filing software will be a suitable option for you.

13. 1040.com

1040.com’s software focuses on simplicity and smart solutions to help their clients spend less time on tax return preparation and filing.

This product offers free help via chat and email, and they also have easy-to-read knowledge articles to provide you with sufficient information on tax filing and the procedures involved.

1040.com is aimed at meeting the needs of simple filers. If you qualify for 1040EZ, this software’s free version will be more than sufficient.

If you are a stock market investor, and itemizer, self-employed, or someone with dependents, you will have to upgrade to one of 1040.com’s paid versions.

If your tax filing needs are complicated, you may have difficulty with this software, however.

This product doesn’t offer the additional features like built-in calculators that real estate or stock market investors may need to file their taxes accurately.

14. OLT.com

OLT.com offers low-priced online tax services to support the most common filing situations.

There are two versions to choose from:

  1. Free, and
  2. Premium

The Free version supports all significant schedules with free federal filing and paid state filing.

With Premium, both federal and state filings require payment, but with this version, you will also receive full audit support and tax assistance from a professional.

The software also features informative articles to help clients with their tax filing and preparation.

One of the drawbacks of this tax software is that the interface is somewhat complicated and lacking in terms of user-friendliness.

15. DIY Tax

The most prominent benefit of DIY Tax is that this software offers accurate and free state and federal tax filing for everyone.

Also, it also allows you to import your taxes from previous years to save time and eliminate mistakes.

DIY Tax also provides free technical support. However, if you use this software and need support for the actual tax forms, you will have to pay for Liberty Tax’s support.

Bottom Line

If you qualify for 1040EZ filing, there is no reason for you to pay for tax software. On the other hand, if your tax filing needs are advanced, it may be worth your while to use tax software.

Just make sure you pick a service that offers a user-friendly interface, complete tax and tech support, simple importing, and comprehensive income and expenditure reporting, even if the price tag is high.

With one of the tax software options on this list, you should be able to handle the trickiest of tax filing situations with ease.

The post Best Tax Software Programs appeared first on Good Financial Cents.


Source Good Financial Cents http://bit.ly/2FIUHBB

What to Do When Your Mortgage Application is Denied

You finally found the perfect house, and what seemed like a straightforward process yielded disheartening results.

Your mortgage application was denied, and it happened after all the time spent completing mountains of paperwork, answering countless questions, and having long conversations and meetings with your loan officer.

So, after getting angry and cursing the world, it’s time to soldier up and figure out what went wrong so you can fix it.

While having your mortgage application denied is not an ideal situation, it’s not the end of the world.

Potential Reasons Your Mortgage Application Was Denied

According to the Mortgage Market Activity and Trends report, in 2017, one in nine mortgage applications was denied. So, you are not alone. 

But, what know?

Well, it’s time to figure out what happened and do something about it. Your first step is to find the reason for your mortgage denial. Once you know what went wrong, you can take care of the problem and try again.

As it turns out, there are several reasons why a mortgage application can be denied. And, get this, a few of them may not even be in your hands.

  • Poor Credit History
  • Debt-to-Income Ratio
  • Recently opening or closing a credit card
  • Recent purchase or lease of a new car
  • Owing child support or alimony
  • Not borrowing enough money
  • Poor conduct by the Home Owner’s Association (HOA)

You shouldn’t be too discouraged if your mortgage application was denied.

If you were turned down for any of the reasons above, there are some specific steps you can take to get approved next time around.

Let’s take a closer look.

How to Get Approved On Your Next Mortgage Application

Poor Credit

Insufficient credit history and a low credit score are common reasons why mortgage applications are denied. If you shied away from credit cards, it might not have been the best choice.

Although true that credit cards can lead to more debt and a high debt-to-income ratio, using credit responsibly helps build your credit history and score. Lenders want to see that you are able to borrow money and repay it.

To build your credit history and score, be sure to put regular expenses on your credit card and to pay off the balance each month.

Keep in mind that your payment history makes up a whopping 35 percent of your credit score.

Debt-to-income Ratio

The debt-to-income ratio (DTI) compares your debts to your overall income. It helps lenders see how you handle your money.

It is considered to be the key factor in determining your creditworthiness when applying for a mortgage.

The ratio is calculated by dividing your total recurring monthly debt by your monthly gross income (income before taxes).

The debt-to-income ratio tells lenders whether you’ll be able to make your monthly mortgage payment based on your monthly debt.

The maximum DTI ratio for a would-be home buyer is 43 percent. It’s common for borrowers who have a higher debt-to-income ratio to run into problems trying to meet monthly payments.

The lower the debt-to-income ratio, the better. If your mortgage denial was due to a high DTI ratio, your best bet is to increase the monthly payments toward your debt, effectively lowering your overall debt and decreasing your DTI.

Recently Opening or Closing a Credit Card

Recently opening or closing a credit card adversely affects your credit history. Although it is true that having some credit card debt shows lenders that you know how to manage credit, you should refrain from applying for new credit at least six months before applying for a mortgage.

Remember that whenever you apply for credit, lenders check to see your credit utilization, which generates a hard inquiry that is reflected on your credit score. However, it’s not just applying for credit that affects your score.

Make sure that you don’t close any accounts either. If you do close an account, your credit score could decrease since you are removing the available credit, thus increasing your credit utilization percentage.

One thing that can prevent this situation is having made appropriate use of your other credit cards by maintaining low balances or better yet, paying the full balance every month.

If this was the case, monitor your score, pay as much debt as you can, and when the numbers are on your favor, apply again.

Recently Purchasing a New Car

Did you recently purchase or lease that new car you were eyeing? If so, you added an extra obligation that increases your monthly debt and your debt-to-income ratio.

If the new debt carries you over the 43 percent limit, there’s a very high possibility that your mortgage application will be denied.

Remember: A higher debt-to-income ratio means that more of your money goes out to creditors, and as lenders see it, you have less money to make mortgage payments.

And if that wasn’t bad enough, your credit score just dropped a few points as well. I’m not saying that you should not buy that dream car of yours.

However, you have to decide what’s more important at the moment. And if you are reading this, I’m guessing that it is the house.

Owing Child Support or Alimony

Owing child support or alimony will be considered to calculate your debt-to-income ratio as it is part of your fixed monthly expenses and, as such, counts toward how much of your money is tied on obligations.

Regarding your credit history and score, if you pay as agreed all is well.

Making child support payments on time is not included in your credit report. However, if you have back-child support, it can be reported to credit agencies.

Additionally, if there is a collection effort, it will show up on your credit report and can lower a high credit score by about 100 points.

If the collection shows up on your credit report, the negative information can remain on there for up to seven years.

If you owe child support, be sure to tackle the debt before the matter reaches a collection agency.

Not Borrowing Enough Money

Not borrowing enough money can also be the culprit of your woes. Many lenders have minimum loan requirements, and if you intend to borrow less than the institution’s minimum amount, your mortgage will be denied.

For example, if property values in your area have significantly dropped, and the amount you need to borrow is less than $50,000, large financial institutions could deny your mortgage application.

To some lenders, it’s not worth the trouble of approving a loan under $50,000; it’s just not profitable.

If that is why your application was denied, you merely need to look elsewhere.

Credit unions or community banks are good options because they can offer mortgages for significantly lower amounts.

Poor Conduct by the HOA

Poor conduct by the Home Owner’s Association (HOA) along with several other factors could make your condo non-warrantable in the eyes of the Federal National Mortgage Association (Fannie Mae) and the Federal Home Loan Mortgage Corporation (Freddie Mac).

When the Home Owners Association is named in lawsuits, the project is not completed, most of the units are rented to non-owners or are short-term rentals, or the developer is still in control of the condominium, your mortgage might be denied, or the interest rates can be higher.

Not because of your credit but because of the high risk involved. If that is the case, you may want to look for another condo, or you could make a more substantial down payment.

Bottom Line

Lesson learned? Great! Now you know that even though a mortgage application denial might feel like the end of your home ownership dreams, it doesn’t have to be.

Your best bet is to understand what happened. With that knowledge in hand, you can get back on track to financing your home.

After you know exactly what went wrong, you can tackle it, fix it, and try again.

The post What to Do When Your Mortgage Application is Denied appeared first on Good Financial Cents.


Source Good Financial Cents http://bit.ly/2QWHMOn

الاثنين، 10 ديسمبر 2018

Where Should You Keep An Emergency Account?

Like it or not, emergency accounts are kind of boring.

And they need to be.

The main purpose of an emergency account is to sit around and wait for an emergency.

That certainly limits your options as to where to hold the money.

Because you may need the money on very short notice, the safety of principal needs to be the primary concern.

But that doesn’t mean you can’t try to earn some income on your emergency account in the meantime.

6 Best Places to Put Your Emergency Account:

  1. Local Banks
  2. Online Bank Accounts
  3. US Treasury Bills
  4. Laddered CDs
  5. Betterment
  6. Roth IRA

You don’t want to take risks in doing it, but you should attempt to earn at least a little bit of income while you’re keeping your money safe.

Here are six emergency account options to consider…

1. Your Local Bank

Your local bank is always a solid option.

Unfortunately, most don’t pay much in the way of interest. And it usually doesn’t matter whether that’s interest-bearing checking, savings, money markets, or certificates of deposit (CDs).

Because they have a network of local branches, they don’t need to pay high-interest rates to attract customers.

For example, according to the Federal Deposit Insurance Corporation’s Weekly National Rates and Rate Caps, average rates on bank savings vehicles look something like this:

  • Savings, 0.09%
  • Interest Checking, 0.06%
  • Money Markets, 0.16%
  • 3-month CDs, 0.19%
  • 6-month CDs, 0.31%

Those interest rates are downright microscopic. But the one advantage to local banks is that they can provide immediate physical access to your money in the event of an emergency.

And even though the interest they pay amounts to little more than dust, it’s better than nothing.

2. Online Bank Accounts

If you want to keep your money absolutely safe but earn higher interest than you can at a local bank, seriously consider online bank accounts.

In today’s world of electronic money, you can often get access to your funds from an online account just as quickly as you can from a local bank branch.

In fact, most provide various options for you to get your money, including transferring it into a checking account at a local bank.

But the interest they pay on your savings are a welcome relief from the fractional rates being paid at local banks.

For example:

  • Ally Bank currently pays 2.00% APY on all balance tiers on its Online Savings account.
  • CIT Bank currently pays 1.85% APY on its Online Money Market account.
  • Barclays Bank is currently offering 2.55% APY on it’ 12-month CDs.

Online banks may not have local branches, but they’re the next closest thing in terms of liquidity. And when you consider that the interest rates they pay on savings instruments run between 10 and 20 times higher than what local banks are paying, it’s well worth keeping most of your emergency account with at least one of them.

You can open an account with Ally, CIT, or Barclays today.

3. US Treasury Bills

US Treasury Bills are short-term debts issued by the US government. And because they are issued by the US government, they are considered the safest of all investments, backed by the full faith, credit, and taxing power of the US government.

They can be purchased in denominations of as little as $100 through do US Treasury’s portal,
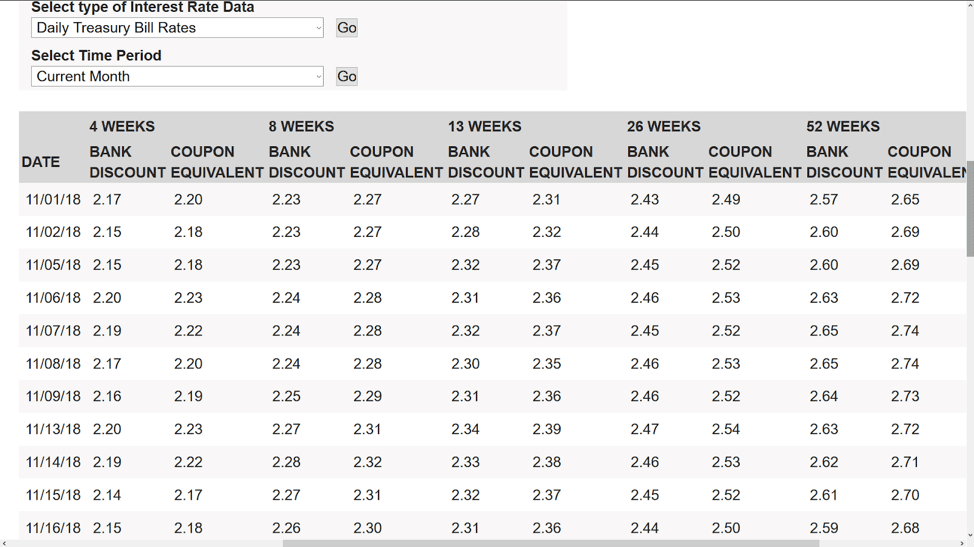
Treasury Direct, and with terms of 4 weeks, 8 weeks, 13 weeks, 26 weeks, and 52 weeks. You can both purchase and redeem them through Treasury Direct.

Current yields on these securities are all in excess of 2% APY, with specific rates as of November 16, 2018, as follows:

Treasury Rates

4. Laddered Certificates of Deposit

CDs generally pay higher rates of interest than what you will get on savings accounts or money markets.

But the best rates go to the CDs that have longer terms. Typically, the better paying rates start with 12-month CDs.

That creates a bit of a problem if you’re looking to build an emergency fund. After all, emergencies don’t wait 12 months for your CD to mature. You’ll need an ability to access funds before a CD matures.

Now you can usually liquidate a CD early.

But if you do, you’ll be subject to an early withdrawal penalty. That can cost you several month’s worth of interest.

An alternative might be to have some money in a savings account or money market account, with most of your money in 12 months CDs earning higher interest.

But an even better strategy will be to create a “CD ladder”. The laddering part has to do with staggering the maturities.

For example, under Online Bank Accounts we noted that Barclays Bank offers a 12-month CD paying 2.55% APY.

You can divide up your emergency account into 12 equal parts and invest the funds in 12 different 12-month CDs.

If you have $12,000 in your emergency account, instead of investing it all in a single CD, you can instead invest $1,000 in one CD each month.

You’ll get the benefit of the 2.55% APY, but each month you’ll have one CD maturing, while investing in a new one.

Because one CD is maturing each month, you would have at least $1,000 available for that month, and for every month.

That’s how you can use a CD ladder to earn higher interest on your money, but also add a measure of liquidity for emergency purposes.

5. Betterment

If you want to add even higher returns to your emergency account, and you’re willing to take on some risk to do it, you can consider putting at least some of your money into a robo-advisor.

The most popular, and perhaps the best robo-adviser overall, is Betterment.

For a low annual fee of just 0.25%, Betterment will provide you with a fully managed investment portfolio, that will be diversified across stocks and bonds.

Stocks are the more risky asset allocation, so if you plan to use a Betterment account as an emergency account, you should favor a higher bond position.

That will make it easier for you to liquidate funds at more predictable valuations than you can with stocks.

But maybe the best use of a Betterment account is to put the bulk of your emergency account into it, to earn higher returns on your money. But you should also hold a portion in more liquid assets, such as those listed above.

You would then be able to tap your liquid savings for immediate emergencies, and access funds from Betterment only when either a larger amount of money is needed, or the emergency lasts longer than expected, such as in the case of a job loss.

Either way, you probably won’t want to put all of your emergency account into Betterment. There is the risk of loss in the event of a general stock market decline.

The best way to protect against that risk is to make sure you always have at least some funds sitting in a completely liquid account, using the Betterment account as a secondary emergency account.

Start earning with Betterment today >>

6. Roth IRA

This one’s a bit controversial as an emergency account, but it can actually make perfect sense.

If you put money into a traditional IRA – or virtually any other retirement account – and you need to withdraw funds before you turn 59 ½, you’ll have to pay ordinary income tax on the amount withdrawn, plus a 10% early withdrawal penalty.

But the Roth IRA is the exception to that rule.

Under what is known as IRS Roth IRA Ordering Rules, you can withdraw your contributions to a Roth IRA at anytime, free of both ordinary income tax and the 10% early withdrawal penalty.

That’s because under the ordering rules, the first funds withdrawn from a Roth IRA are considered to be your contributions. And since contributions to a Roth IRA are not tax deductible, they are not taxable on withdrawal.

Apart from the fact that you can take tax-free early withdrawals from a Roth IRA, using one as an emergency account has several advantages:

  • They can be used to earn higher rates of return, such as by holding the Roth IRA with Betterment.
  • Investment earnings on a Roth IRA are tax-deferred, so they’ll build up more quickly than in a taxable account.
  • Since a Roth IRA is first and foremost a retirement account, any funds not withdrawn for an emergency will continue to help you save for retirement.

Once your Roth IRA account gets big enough, you may be able to keep a small portion in liquid assets, like bonds, to use as an emergency account.

But the rest of the account, the majority, can be invested for growth as part of your retirement strategy.

Where You Should Put YOUR Emergency Fund?

As you can see, there are more options as to where to put an emergency account than just the local bank. Best of all, you don’t have to pick just one type of account.

You can use several, effectively turning your emergency savings into something of a diversified portfolio.

For example, you can hold a small amount, say enough to cover 30 days of living expenses, in a high yield savings account or money market.

You can put a larger amount into higher yielding (but safe) investments, like CDs and Treasury Bills.

Then you can put the largest amount into a growth account, like Betterment and/or a Roth IRA, to earn even higher returns for the long-term.

That will enable you to have the liquid funds you need for an emergency account, while earning a lot better than 0.09% in a local bank savings account.

The post Where Should You Keep An Emergency Account? appeared first on Good Financial Cents.


Source Good Financial Cents https://ift.tt/2UzPFMD

الأربعاء، 5 ديسمبر 2018

Best Credit Cards for Bad Credit

Creditors hear a lot of interesting stories from applicants with low credit scores:

You lost your job and couldn’t pay the student loan for a few months.  You thought you’d gotten a deferment but were too busy job hunting to find out for sure. 

Then your roommate moved out without paying the bills that were in your name.

And most of the time, creditors don’t care.

Your credit score — that little 3-digit number — has already answered the only question they ever wondered about your life.

Even the most convincing explanations won’t slow the denial message, which is frustrating for applicants with bad credit.

Credit cards can help rebuild your credit, offer advantages like cash back, make booking hotel rooms easier, or bail you out if your refrigerator goes out or your muffler falls off.

How Bad Credit Affects Credit Card Approval

Wouldn’t it be great if credit card companies understood and made special exceptions to help people out?

As most of us already know, that’s not typically how credit works. Credit cards are backed by banks, and banks have rules for a reason.

Statistically speaking, someone with a low credit score is more likely to default on a credit card.

Since banks usually make unsecured loans when they issue most credit cards, they have little recourse if you don’t pay.

They can’t repossess what you bought the way a car dealership could. All they can do is hurt your already hurting credit score.

You can find a few exceptions, though. If you look around enough, you’ll find some credit cards specially designed for applicants with bad credit.

The Downside of Credit Cards with Bad Credit

There’s no magic bullet, though. While your odds of getting approved for one of the cards below may be high, expect some trade-offs:

  • Higher fees: Someone with good credit can shop around for cards with no or low annual fees. Not so if you have bad credit. Expect to pay some of the highest fees out there.
  • Higher interest rates: You’ll see ads about low or no interest for a set number of months with some credit cards. Cards for people with lower credit scores tend to charge the highest interest rates.
  • No perks: Looking for features like cashback on purchases or points toward plane or movie tickets? You’ll need to wait until your credit score climbs back into “good” or “great” territory. Even if you can find a card for applicants with bad credit that offers cashback, your rewards won’t make up for the high fees.
  • No balance transfers: If you’re looking for relief from other out-of-control credit card balances, look elsewhere because these cards don’t allow balance transfers.
  • Low credit limits: These cards tend to start out in the $300 to $500 range with the possibility of increasing to $2,000 after a year of keeping the account in good standing.
  • Paying a security deposit: Some of these cards may surprise you by asking for a security deposit. This isn’t necessarily a bad thing. By paying a deposit you may be able to reduce some of the high fees and interest rates since your creditor will be taking less of a risk.
  • Having a checking account: Most new credit card accounts now require cardholders to pay bills online, which means you’ll need a checking account. Cards don’t usually allow you to pay a balance using another credit card.

Best Cards for Bad Credit

Looks pretty grim, doesn’t it? You may be wondering whether you should even consider getting a card like this.

I can think of one really good reason to go this route: To speed up your credit rebuilding process.

If you’re serious about rebooting your credit score so you can flex your borrowing muscles in the coming years (think new house or car), these cards can help:

1. Total Visa

First, the good news: You can qualify for a Total Visa credit card with a credit score as low as 300, and you’ll get an instant decision on whether you qualify.

Now for the not-so-good news: You’ll have to spend some money up front to get this card, and you’ll have to pay an annual fee to keep it.

Fees include:

  • Application fee: Processing your application will cost $89. So don’t apply unless you know for sure you want the card and have a credit score of 300 or higher.
  • Initial annual fee: A $75 annual fee that kicks in when you open the account.
  • Ongoing annual fees: The annual fee goes down to $48 the second year, but a $6.25 monthly fee also begins.
  • Late fees: Like most cards, you’ll be hit with a fee if you don’t pay your minimum balance on time. The fee for Total Visa will not exceed $38.

These fees may seem steep because, well, they are.

But when you have bad credit, you have fewer options from creditors. You’ll have to decide whether having the card will be worth the money.

Another disadvantage to a Total Visa Credit Card is its low credit limit. Normally the card starts with a $300 limit, minus the $75 annual fee, which means you’ll initially have only $225 in spending power.

Is that enough to make getting the card worthwhile? Not necessarily, if you’re getting credit to have in case of an emergency or to do a little more Christmas shopping than you can afford.

It could be worth it, however, if you’re working to rebuild your credit.

Improving your credit score includes making payments on time and having open credit accounts. This card can help give you the opportunity to make regular payments.

Someone working to improve a credit score should pay off the card’s entire balance every month. This approach will also help you avoid Total Visa’s high annual percentage rate of 29.99 percent.

At that rate, a card’s balance can get out of control pretty quickly if you don’t stay ahead of it.

2. FIT Mastercard

Looking for a little more spending power than the Total Visa?

Mastercard’s FIT program offers a $500 initial credit limit. Depending on whether you make regular payments for a year, you can get a credit limit increase to $2,000 after the first year.

Other than the higher spending limit, FIT Mastercard behaves a lot like Total Visa. You should have at least a 325 credit score to apply.

Unlike Total Visa, you won’t need to pay an application processing fee just to apply, but expect higher annual, then monthly, fees:

  • Processing fee: If approved, you’ll be charged an $89 processing fee for your application.
  • Annual fee: Fit Mastercard’s $125 annual fee for the first year is higher than Total Visa’s $75 annual charge. The fee goes down to $96 the second year.
  • Monthly fees: After the first year, you’ll pay $10 a month, $3.75 more than Total Visa’s monthly fee.
  • Late fees: Miss a payment? Expect up to $38, and remember you’ll pay interest even on fees. Fit Mastercard charges 29.99 percent.

Just like with Total Visa, you as the consumer should decide whether opening a Mastercard Fit account helps you. It can offer more spending power than Total Visa, but once again you’re starting in the hole because of the card’s high fees.

This card works best for someone trying to rebuild credit. Having an open account in good standing looks good to credit agencies.

Again, just be sure to keep the card’s balance paid off. At nearly 30 percent interest, the Fit Mastercard can get out of control if you let it.

If that happens, your credit score will probably get even worse.

3. Reflex Mastercard

The Reflex Mastercard, another credit card for applicants with bad credit, works almost exactly like the Fit Mastercard. It’s likely you’ll get approved for the card, either with an unsecured or a secured account requiring a deposit.

Your spending limit will start out at $500, and a chunk of that amount will go to your initial fees:

  • Annual fee: Like Mastercard Fix, expect a $125 annual fee for the first year and a reduction to $96 at the beginning of year two.
  • Monthly fees: Also like Fit, Reflex Mastercard charges $10 a month after the first year, which equals $120 a year.
  • Late fees: The same $38 late fee applies, as does the high annual interest rate of 29.99 percent.

As with other credit cards for people with bad credit, the question becomes not whether you can get approved but whether you should. After getting approved you’ll face a three-digit balance to cover the annual fee, leaving $375 as an available balance.

So you wouldn’t be getting much of an emergency fund with a card like this. You would, of course, be getting a way to improve your credit score.

The Reflex Mastercard, like the Fit and the Total Visa, reports to the three credit agencies each month.

Getting the card, managing to pay off the fees and keep the balance paid down, would be a first step to rebuilding your credit score.

After a year, your credit limit could increase as high as $2,000. With the card’s high fees, though, you may want to consider another card at that point if your credit has increased enough.

4. First Access Visa

Applicants with bad credit, even scores in the low 300s, can often get approved for a First Access Visa. This card works a lot like the Total Visa card we’ve already discussed.

You’ll pay an $89 application processing fee just to apply. If approved, you’ll also pay:

  • First annual fee: The card charges its initial $75 annual fee as soon as the account opens.
  • Ongoing annual fees: The $75 annual fee goes down to $48 beginning in year two, but you’ll also pay a $6.25 fee each month beginning in the second year.
  • Late fees: First Access Visa will charge up to $38 if you’re late making a payment.

Like Total Visa, expect a low initial opening limit of $300, $75 of which will be tied up in the initial annual fee.

No, it’s not a lot of spending power, but it can be a step toward a more stable credit score if you pay the balance down each month and avoid the 29.99 percent interest.

This card has been known to allow credit limit increases after six months of keeping the account in good standing.

First Access Visa reports to the three major credit bureaus each month, so you’ll get quicker results improving your credit score as long as you keep the card up to date.

5. Surge Mastercard

This card also fits the same mold: It’s accessible to people who are rebuilding their credit scores, but it costs money to open the account and to keep it open:

  • Annual fee: Surge Mastercard charges a $125 annual fee which lowers to $96 the second and subsequent years.
  • Monthly fees: Expect an additional maintenance fee of $10 a month ($120 a year) beginning the second year.
  • Late fees: The card charges up to $38 for late payments and 29.9 percent interest, like most cards for people who are rebuilding their credit.

You can get up to $500 spending power when you open the account, but remember $125 will be already spent on the annual fee.

The main reason to apply for a Surge Mastercard, like any of the other cards we’ve reviewed in this post, is credit rebuilding.

Rebuilding your credit score can lead to a lot more opportunities for building a more stable financial future. Let’s get into that next.

Tips to Improve Your Credit Score

Benefits of Improving Your Credit Score

People with bad credit often consider their personal finances a lost cause. You may wonder if it’s worth it to bother improving your credit score.

Having a solid credit history has some obvious advantages:

  • Higher credit limits: The better your score the more you can borrow.
  • Lower interest rates: Higher credit scores mean creditors will take less of a risk lending you money, so your interest rates can be lower.
  • Lower payments: Borrowing at better terms means you can usually get lower payments on a home loan or a car loan.
  • Ability to shop for loans: When you’re an ideal candidate for a loan you can shop around to get the best deals on a credit card or secured loan.
  • Ability to help others: If your kid wants to buy a car and has no credit history, wouldn’t it be nice if you could help by co-signing? If you have bad credit you won’t be much help there.

On top of those reasons, most insurance companies now consider your credit score when you apply for coverage: life, auto, and home insurance rates tend to be lower for people with higher credit scores.

Why? Because research has shown people with high credit scores tend to file fewer insurance claims.

Your credit score can also impact your ability to open a bank account or rent a new apartment.

When you sign up for public utilities such as electricity or water, people with lower credit scores often need to pay higher security deposits.

How to Improve Your Credit: Slow and Steady

When you have bad credit you have two options:

  • Wait a decade or so until the bad marks age off your score: Depending on when your creditors give up and write off your debt, you may only have to wait eight years or so. At that point, you’ll have limited credit.
  • Take action to add some good to the bad: You can recover sooner by giving the credit bureaus something good to digest, like making regular payments or having some available credit.

If you decide to take action, the credit cards on this page can help. They’ll give you an opportunity to show the credit bureaus that you’ve changed your ways.

It’s not all about having a credit card, though. Credit bureaus consider several factors when they calculate your score:

  • On-time payments: Paying all your bills on time, including credit cards, makes up a sizeable chunk or your credit score.
  • Outstanding debt: How much you owe matters, which is why paying off your credit cards each month or as often as possible helps your score.
  • Available credit: If you have a $2,000 credit limit on a card but you’re using only $50, the credit bureaus take note — another reason to pay off those balances.
  • New credit inquiries: Usually, applying for credit can lower your score a bit, so don’t apply for every card on this list.
  • Balance of account types: Having a variety of open accounts impresses the credit bureau algorithm gods. So mixing in a credit card can help. If you already have four or five credit cards, back off a little.

Yes, it’s a lot to think about, but now you can get an app to do a lot of the thinking for you. Look into an app like Credit Karma, one of my favorite tools, to help you improve your credit score.

These apps keep your credit score at your fingertips and they analyze your score to make recommendations for ways you can improve it.

An added benefit to keeping an eye on your score with an app: If your score changes drastically, you’ll know it right away.

A fast-changing score could mean a lot has changed in your life, but it could also mean someone else is using your identity.

The sooner you know, the sooner you can report the fraud and limit its damage.

Should You Use a Credit Card to Rebuild?

Banks issuing credit cards to people with bad credit may seem like they’re doing you a favor. Closer inspection shows you’re paying enough in fees and deposits to remove much of the bank’s risk.

How you view these credit cards makes a huge difference:

  • If you’re looking for spending power, these cards won’t help much, and I’d stay away from them.
  • If you’d like to reboot your credit history, they can help and be worth your while.

Credit cards for people with bad credit won’t solve all your credit problems. In fact, they can make things worse if you don’t keep the account current.

But if you’re determined to improve your score, they can speed things along. Yes, the fees and terms are unattractive. But if they lead to a more stable financial future, they may be worth it.

The post Best Credit Cards for Bad Credit appeared first on Good Financial Cents.


Source Good Financial Cents https://ift.tt/2APyAp0

Best RV Insurance Available for 2019

No matter how well you plan it, your next RV adventure could include something unexpected.

And that’s OK. You’re on the road in an RV to escape your work clothes, your alarm clock, and those rambling staff meetings.

Why not make some unplanned stops and meet some new friends?

Sometimes, though, the unexpected isn’t so pleasant:

  • collisions on the highway could injure you or your passengers and damage your RV
  • you could be held responsible for damages or injuries to other drivers, or
  • bad weather could destroy your RV while you’re far from home

This is why you may want to spend just a little time finding the best RV insurance you can before you spend a LOT of time on the side of the road.

A mechanical breakdown, or even just a flat tire, could leave you stranded. An injury at a campsite could leave you responsible for someone’s medical bills.

Yes, these perils could stall your adventure, but more importantly, they can cost thousands of dollars and risk the money you’ve already invested in your RV.

So before you step on the accelerator, let’s learn about the insurance coverage you would need to protect yourself from these unexpected curves down the road.

If you’re already an experienced RVer, check your current policy to be sure it’ll protect you the way it should.

Even if your state doesn’t require your RV to have its own insurance policy, you should consider getting enough insurance to protect your investment and cover your liability.

First, The Different Types of RVs

Other than a brief blip during the Great Recession, the number of RVs on the road has steadily increased for the past 20 years.

You could attribute this increase to the obvious — that RVing is cool and lots of fun — but there’s a more statistical explanation, too:

RV manufacturers have done a great job making a wider variety of RVs, campers, and trailers, which has allowed more people to join the fun.

Roaming the great outdoors with your indoor comforts in tow no longer requires a life-changing commitment. Your RV type also has a direct impact on the kind of insurance coverage you’ll need, so let’s start there.

Two Main Types of RVs

Let’s break this down as simply as possible. There are two main types of RVs: RVs with steering wheels, also known as Motorhomes, and RVs you pull behind another vehicle, which we also call trailers or campers, or in some cases, Toterhomes.

Each type of RV calls for its own approach to insurance coverage.

You could add some towable RV models to your existing auto insurance policy, but a motorhome will need its own policy, mixing elements of homeowners and auto coverage.

Of course, RVs are too complicated to be confined by this neat little breakdown. Some towable RVs are bigger and more expensive than some motorhomes.

We’ll need to dig a little deeper into these broad categories to find out for sure what kind of coverage you need.

Three Types of Motorhomes

First, let’s look at motorhomes, the castles of the RV world. They’re huge, comfortable, and all-inclusive, and since you can drive them, they need their own insurance policies.

Not all motorhomes are created equally, though.

  • Class A Motorhomes: If you’ve passed one of these guys on the highway, it probably took a minute or two. They’re huge — up to 75 feet long — and they can include all the comforts of home, from plumbing to an entertainment center. You can spend half a million dollars on something like this.
  • Class B Motorhomes: Many Class B motorhomes could pass for a beefed-up van. The ceiling is usually raised to help passengers move around more easily, but space is at a premium. The price range here runs from $50,000 to $150,000 depending on amenities.
  • Class C Motorhomes: Class C motorhomes cover the middle ground. They’re bigger than Class B models and are usually built on a truck chassis. They often have sleeping quarters above the driver’s cab, giving them a distinct look. You’d likely spend $100,000 to $200,000 on one.

The Wide Array of Towable RVs

If you thought motorhomes came in a variety of colors and flavors, wait until you see the variety of RVs you can attach to your SUV, pickup, or even sedan.

The list, which seems to grow every few years, includes:

  • Conventional Travel Trailers: Think Motorhome without the motor: your pickup or SUV provides the power. Conventional travel trailers can be up to 35 feet long and sleep about 10 travelers. This can easily be a 6-figure investment.
  • Fifth-Wheel Trailers: These guys look more like Class C Motorhomes with the bi-level layout. The higher level up front hitches inside the bed of your pickup. These typically sleep up to 6 and cost up to $150,000.
  • Folding or Tent Trailers: If you’re looking for something easier to tow yet large enough to provide a little comfort on the road, a folding or tent trailer may be for you. About 6 people could probably sleep in one of these, but you’d want to plan on outdoor living for the most part. Expect to spend up to $30,000.
  • Expandable Trailers: An expandable trailer works a lot like a folding or tent trailer, but you can expect more durability and protection from the elements since the hard-sided trailer itself expands. Prices can climb toward $50,000.
  • Truck-Bed Campers: Take towing out of the equation by turning your truck bed itself into living space. These can be surprising elaborate and comfortable, sleeping up to 6 and costing up to $50,000.
  • Teardrop Trailers: If you’ve seen one of these you know what inspired the name — they’re small and curved like a drop of water. If you’re traveling alone or as a couple, a teardrop trailer may do the job. You may even be able to tow it behind a mid-size car. You can find one for a few thousand dollars or spend well into the $30,000s depending on your tastes.

Why You Need RV Insurance

Traveling the countryside with your own personalized hotel room in tow should be fun and relaxing.

But like any kind of adventure, RVing does not always play out as imagined.

We can’t control everything, and there’s a chance you could face perils such as:

  • Crime: The typical RV carries valuables — food, electronics, small appliances, tools, cash, firearms, jewelry — making them targets for seasoned burglars. Common sense precautions go a long way, but sometimes you’re just in the wrong place at the wrong time.
  • Weather: Out there in the elements, expect to deal with… well, the elements. Most likely you’d reschedule a trip to avoid a hurricane or a tropical storm. But tornadoes and even common thunderstorms can do a lot of damage, and these storms can be harder to predict.
  • Accidents: A car crash while on vacation is bad enough. A crash that also damages your living quarters can ruin any plans for adventure. You may even be stuck in a faraway place while you make other arrangements.
  • Personal injuries: Since your RV can function as a home, it’s a place where you, your family, a friend, or even a random person wandering a campground, can be injured.
  • Breakdowns: Even well-maintained equipment can fail. If your RV won’t start (or if the AC goes out or the expandable camper won’t expand) you may be looking at a big repair bill and a lot of hassle before you can get on the road again.

Insurance exists to protect your financial investment if something goes wrong and to protect you from being personally liable for accidents you legally caused.

If a wreck or a storm damages your RV, if a thief cleans it out, or if someone gets injured, for example, your policy should help pay for it. Whether your policy will cover all, some, or none of your losses depends on the coverage you have in place.

Most insurers also offer extras such as towing, roadside assistance, or even help paying for a hotel (use a hotel card, of course) if you can’t stay in your RV because it’s damaged.

Let’s look at various kinds of RV coverages to find out what you need.

What Kind of RV Coverage Do You Need?

To understand RV insurance it’ll help to first refresh our knowledge of car insurance.

Though you pay your auto insurer one payment, you’re actually buying several different policies:

  • Liability: If you caused a wreck, this coverage should pay for the other driver’s auto repairs and medical bills. (It should also cover the other car’s passengers’ medical bills.)
  • Collision: This would pay for your own repairs if you legally caused the wreck. (If you were not at fault, the other driver’s coverage should pay.)
  • Comprehensive: For damage not related to a collision. Hail damage, theft, vandalism, and such.
  • Medical payments: Also called MedPay, this coverage can help pay your medical bills if you caused a wreck. (If you’re not at fault the other driver’s liability should cover your medical bills.)
  • Personal Injury Protection: Especially for states with no-fault accident policies, this coverage will pay for your own medical bills even if someone else hit your vehicle.
  • Uninsured or underinsured coverage: If the other driver is at fault but has little or no insurance to pay for your repairs and medical bills, you can carry this coverage to help protect yourself.
  • Extras: Many insurers offer AAA-style benefits such as roadside assistance, towing, and help finding alternative accommodations.

Having great auto coverage depends on finding the right mix of these coverages to match your car and your situation.

Your RV insurance should work similarly. You’ll need to take a look at each of these coverages and decide how much coverage to buy.

Your RV type and frequency of use will determine a lot about your coverage, and we’ll get into that below.

  • If you’re buying a bonafide Motorhome — Class A, B, or C — you have the most to lose, and every state requires you to carry insurance to protect yourself and other drivers. We’ll look at this coverage first.
  • If you’re buying a travel trailer or something simpler, your state probably will not require you to be a separate policy for your RV. It’s up to you to make sure you’re covering your investment and liability. (Your lien holder may require you to have a minimum amount of insurance.) We’ll get to that in a bit.

Insuring a Class A, B, and C Motorhome

Let’s face it. You can do a lot of damage with an RV, especially a Class A Motorhome which can be up to 75 feet long.

Any Motorhome, whether Class A, B, or C, is a moving vehicle and must meet your state Department of Transportation’s insurance requirements.

Just like with a car, you’ll need to address:

Liability

If you collide with another vehicle on the highway, or even in a parking lot, and investigators determine you were at fault, you’ll be personally responsible for the other driver’s injuries and for the damage to the other vehicle.

In an RV, you also have to consider liability while you’re parked. Someone could trip on a power connector and land on a hot grill, suffering second-degree burns, for example.

Whatever the case, if you don’t have enough liability insurance coverage, you will be personally responsible to pay the damages out of pocket.

If you can’t pay, a judge can order your assets be seized to compensate the people you’ve inadvertently harmed.

Your state will have a minimum liability coverage requirement, but some states’ limits just aren’t high enough to protect you from financial losses if you have an at-fault accident.

State limits also don’t always reflect the reality of RV living. They usually consider only on-the-road liabilities.

A lot of financial advisors suggest carrying enough liability coverage to cover your financial assets, regardless of what your state requires.

If you have $50,000 in the bank and own a $150,000 house, for example, make sure your insurance can cover $200,000 in liability.

If you’re worried about having enough liability coverage, ask your agent about an umbrella policy which pools liability coverages from a variety of policies: RV, home, auto, etc.

Collision

Collision, of course, covers damage to your own vehicle if you have an at-fault wreck while driving your RV. How much coverage you need depends in part on your lien holder.

If you’ve financed the RV, the bank or another creditor will want your policy to protect its investment. If you bought the RV outright, it’s up to you to decide whether you want to protect your purchase.

I recommend carrying at least some collision unless you have the financial flexibility to pay for expensive repairs. Even then, why pay out of pocket for expensive repairs when you can find affordable collision coverage?

Comprehensive

Comprehensive coverage pays to fix damages from perils other than a wreck:

  • vandalism
  • hail
  • theft
  • etc.

Just like with your collision coverage, your lien holder may require comprehensive in case someone steals your RV or something happens to damage its value.

Why do banks care about this?

If you failed to pay and the bank repossessed the RV, it would need to sell the vehicle. An RV in great shape brings a higher price. Basically, the bank wants to prevent future losses.

If you’ve paid outright or have paid off the RV, you have more freedom to decide about comprehensive.

However, losing the RV and everything in it to theft or a tornado would be a sad, sad day. It would be even worse if you couldn’t file an insurance claim to help pay you back for your losses.

That’s why an RVer needs to pay special attention to comprehensive coverage. In many ways, your comprehensive coverage should serve as a homeowners policy for your home away from home.

Or, if you’re a full-timer, you are essentially buying homeowners coverage and will need to give the purchase some close scrutiny.

We’ll get into some of those nuances below.

Other Coverages In Your Policy

MedPay: In most states whether you buy medical payment insurance to cover your own medical bills after an accident depends on you.

If you have solid health insurance you may not need to add this coverage to your RV policy. If you’re not so sure how much your health insurance would pay if you had an at-fault wreck, I’d consider adding MedPay.

If someone else causes the wreck his or her insurance should help pay for your medical bills. Unless, of course, the other driver doesn’t have enough insurance.

Uninsured or underinsured coverage: Getting coverage to fill in the gap if someone without insurance (or without enough insurance) collides with you can help prevent losses.

About 20 states require this coverage, and your independent agent (or captive agent) will let you know whether your state requires it.

If your state doesn’t require it, you can still opt in.

Personal Injury Protection: Ask about this coverage if you live in a no-fault state, especially if you don’t have good health insurance.

Insuring a Trailer or Camper

Though it may be bigger than a motorhome, your camper or trailer (also known as a Toterhome or towable RV) is not a vehicle.

As such your state will not require you to insure it. However, your lien holder will have other ideas.

If you owe money on your camper, the bank will want it adequately covered against losses in value, just like your mortgage company wants to know about your homeowner’s policy.

And most importantly, you’ll want to protect your own investment. Insurance exists to protect you from losing your hard-earned property.

An Endorsement Isn’t Enough

When you buy a towable RV and call your friendly auto agent, he or she may suggest adding an endorsement to your auto policy to cover the RV when you’re towing it.

An endorsement may be enough to protect a teardrop camper or a small folding camper while it is tethered to your insured motor vehicle.

An endorsement will not protect your investment in a travel camper or trailer, and it won’t address the liability issues connected to how you use your RV.

In other words, it’ll help cover the ‘V’ part of RV, but not the ‘R.”

To get fully protected, you’ll need an RV-specific policy, just like you would with a Motorhome.

RV-Specific Insurance Options Protect You Best

So let’s review:

A Motorhome has a motor so it needs on-the-road coverages like a car: liability, comprehensive, and collision in case you have an accident. MedPay, uninsured/underinsured motorist, and Personal Injury Protection coverages may be required, too.

A towable RV does not need these on-the-road coverages. Instead, you’ll need these coverages on the vehicle you’re using to tow your RV.

But remember: State laws exist to protect other drivers from damages you may inadvertently cause, not to protect your investment.

While it may meet the legal requirements, a simple auto policy for your motorhome, or an auto policy endorsement for your towable camper, will not necessarily protect your investment or shelter you from out-of-control liability.

For that kind of protection, we need to look at RV-specific insurance policies.

Full-Time Coverage For Full-Timers

Some people take RVing to the extreme and live in their vehicle year-round. The most committed RVers do not even own or rent a stationary home.

Their RV is their home. If you plan to use your RV for six months a year or more, you’ll need Full-Time RV Insurance.

Full-time coverage combines elements of a homeowners policy and an auto policy. You’ll be covered as a vehicle while in motion and as a home when roadside or at a campsite.

The homeowners-style coverage includes liability for personal injuries that happen in the RV and on the property the RV occupies, even though the policyholder doesn’t actually own the property.

Yes, you could possibly strengthen your comprehensive coverage on an auto-style Motorhome policy to address this reality. But, keep this in mind as you weigh options:

An insurance company can deny a claim if it didn’t know you were living in the RV full time. Insurance companies write policies based partly on how you plan to use the RV.

By getting Full-Time RV Insurance you’re declaring your intention to use the vehicle as your home. Since not all insurers offer full-time coverage, you can also narrow down your list of potential insurance carriers this way, saving time as you shop for coverage.

Storage Coverage Can Save Money

RVers on the other end of the spectrum may hit the road only occasionally or for just a few weeks out of the year.

For occasional RVers, Storage Coverage can save a lot of money. After all, if your RV is not on the road, it won’t be in a wreck, so you shouldn’t be paying insurance to cover a collision or for bodily injury related to a wreck.

You should, however, maintain comprehensive coverage because storms and thieves don’t care whether you’ve parked for the winter. They’re just as happy to wreak havoc on a stored RV.

A Storage Policy reflects this reality and can cut your premiums in half.

Just don’t take your RV out during the storage period without adjusting your insurance first. If you do, your lack of collision and liability coverages will leave you exposed. If you have a wreck your insurance company won’t help.

Personal Effects Coverage

Homeowners insurance policies cover personal property such as computers, jewelry, firearms, TVs, small appliances — basically, valuables which are not integrated into the home.

Homeowners policies usually extend coverage to personal belongings even when they’re away from home — even when they’re on vacation with you in the RV.

This simplifies things for RVers who have stationary homes with homeowners policies. But full-timers who don’t have a stationary home should consider adding Personal Effects Coverage to their RV policy.

You can add Personal Effects coverage to a Motorhome or a Toterhome.

Just like with a homeowners policy, you should keep an inventory of personal belongings, complete with photographs and serial numbers, to make it easier for your insurance company to pay your claim.

A personal belongings inventory can be a hassle to keep up with. Now, you can find apps that make this a lot easier.

Personal Attachments Coverage

The joy of RVing includes doing things your way — watching satellite TV while someone else drives or having drinks under an awning on a cool fall evening in the Smokies.

Attachments to your RV such as a satellite dish or an awning can be the first property damaged during a thunderstorm, or if that bridge back there was lower than you thought.

Such mishaps have inspired insurance companies to add Personal Attachments Coverage as a separate product. It’s certainly not essential, but it can simplify a claim.

Total Loss Replacement

Let’s say a tornado tears through your campground.

Fortunately, you and your family survive the disaster, but the RV takes a beating. Fixing it would cost more than replacing it.

And that’s why you have insurance. To replace your RV and your personal belongings. End of story. Right?

Not necessarily. Your insurance company’s idea of “replacing” your RV may not match your idea.

Unless stated otherwise, your policy probably replaces your property at market value. If you paid $150,000 for your Motorhome six years ago but it would now be worth only $100,000, your insurance company would reimburse you for $100,000.

With the payout, you could probably buy another 6-year-old RV, which is fine if that’s what you wanted to do.

What if you wanted your coverage to replace your 6-year-old RV with a new RV, though? You’d need to upgrade your coverage:

  • Agreed value: With an agreed-value policy you can tell your insurance company what the RV is worth and insure it for that amount. Keep in mind you’ll pay premiums based on the agreed value, so don’t choose this option unless you really need it. This open can be particularly useful if you’ve restored a classic RV. Your agreed value can reflect the time and money you’ve invested in the restoration.
  • Total loss replacement: Upgrading to total loss replacement value would pay you back the price of a new RV that’s comparable to your aging model. Read the fine print carefully if you choose this option. It usually lasts only five years and can be purchased only if the RV two years old or younger. After five years the coverage will reimburse you the purchase price of your RV. As more time passes expect more reductions in coverage.

Other RV-specific Insurance Products

As more and more people join the RV life, insurance companies have responded with a wider variety of insurance products. If any of these might help you, ask your agent about including them:

  • Mexico coverage: With many policies traveling into Mexico automatically suspends your coverage. (This isn’t usually true for Canada.) Mexico coverage usually includes only comprehensive and collision coverages, and repairs must still be made in the United States. You’ll still need separate liability coverage while in Mexico.
  • Fire department coverage: A local fire department responding to a fire at your parked RV may send you a bill since you’re not a property owner or taxpayer in the jurisdiction. This kind of coverage will help cover those costs.
  • Gap coverage: Just like with a car, you can get gap insurance to pay back your lender if your market value reimbursement isn’t enough to pay off the loan. Your lender may require this.
  • Vacation liability coverage: This coverage can help a part-time RVer who wants more robust liability coverage while parked at a campsite or parking lot.
  • Storage shed contents coverage: For full-time RVers who keep belongings in storage. It protects your stored items if something happens to the storage facility and your stored contents are damaged, destroyed, or stolen.
  • Pet coverage: Taking your pets along? You should probably have a separate pet insurance policy, but you could add coverage to your RV policy.

When You Need Help: Add-Ons Can Be Handy

Protecting you from liability while using your RV? Protecting your financial investment from loss if something unexpected happens? That’s plenty for your RV insurance to do.

But it can do more if you don’t mind adding on to your premiums.

Most insurance companies offer add-on benefits to make life easier if something goes wrong while you’re out there.

Roadside Assistance

The more miles you put on your motorhome or towable RV, the more likely you’ll need help along the way.

Flat tires, dead batteries, overheated radiators, broken air conditioning belts — a lot of small things can grind your adventure to a halt.

Roadside Assistance programs can help get you up and running again quickly and without out-of-pocket expenses.

Towing

Not all problems can be fixed while you wait beside the road. When your RV needs serious mechanical help, you may need to have it towed to a shop.

Towing coverage from your insurance company can take on the job of finding and paying for a reputable towing service.

When you’re towing a Motorhome or a larger camper or trailer, a little help can go a long way because not just any tow truck will do.

Rental Cars

If your RV needs to be towed in for service, you may not want to sit around waiting for the repairs.

When you opt for a rental car service, your insurance company can pay for your rental car so you can at least get from place to place while you wait for your RV.

If you’re towing your RV you may not need this service on your RV policy. Instead, you can add it to your auto policy.

And if you’re towing your own car behind your Motorhome, you may already have things covered.

Hotel Accommodations

An RV in the shop may mean you have nowhere to sleep.

With hotel coverage, your insurance company can pay for you to stay in a hotel while you wait for the mechanics to finish things up.

Before adding these sorts of extras to your policy, decide how much you need them and if you can get the same services elsewhere.

If you have AAA’s RV package, for example, you probably won’t need to add the same services to your insurance policy.

Insurance Coverage When You’re Renting an RV

Naturally, a full-time RVer will want to own his or her own rig. Occasional RV users, though, may consider renting an RV when they need it. Advantages to renting include:

  • Avoiding property taxes.
  • Ability to try different RV models without committing to one.
  • Avoiding the need to store a large RV when not in use.

But what about insurance?

When you rent an RV, can you avoid paying premiums, too?

You most likely will have some liability coverage from the RV owner’s policy, especially if you’re renting from a company and not an individual.

But it’s up to you to find out for sure. Even if you’re covered as a renter, consider the ways your own insurance could provide better protection.

With liability, for example, you may need stronger coverage than the owner’s policy provides. You may also want more add-on coverages such as roadside assistance. It’s easy enough to find your own RV rental insurance if you need it.

How to Score The Lowest Premiums on Your RV Insurance

You probably have a good idea how much RV coverage you’ll need to protect your investment and to shield you from liability.

So it’s time to think about how much you should pay for this protection.

Traditionally, RVers haven’t been all that concerned about insurance costs.

If someone could afford to go on the road and take their way of life with them for several months at a time, they could afford just about any kind of insurance.

Plus, more mature drives often get better insurance rates anyway.

Now, as more people join the RV lifestyle at younger ages, RVers are paying more attention to what they’re paying for insurance coverage.

To keep your premiums down, compare quotes from several companies, and keep the following tips in mind as you shop:

Your Driving Record Matters

Insurance companies calculate premiums based partly on your driving history. If you’ve been cited for moving violations or have had a couple at-fault wrecks, be prepared to pay more.

You can’t erase your record, but you can prevent future problems by driving safely and obeying traffic laws. In many states, at least three blemish-free years on your driving record saves you money.

Your Credit History Matters, Too

When you apply for insurance in almost all states, your insurance company will run a credit check. It’s not because they’re worried about whether you’ll pay your premiums on time.

Instead, it’s because they’ve found a correlation: People with lower credit scores file more claims.

You can tell them they’re wrong about you, but they probably won’t listen. If you raise your credit score, though, you’ll have their attention, and you’ll probably see a decrease in premiums.

Need help? Check out Credit Sesame or Credit Karma.

How Much Coverage You Get Matters

As you can tell above, I’m all for having enough insurance coverage to protect your investment and to shield your personal property from a lawsuit.

The more coverage you have, though, the more you’ll pay in premiums. If you’re trying to keep premiums at a minimum, make sure you’re not buying more coverage than you need. Let’s say you’ve bought a 2-year-old Class C Motorhome for $100,000.

You won’t need $125,000 in comprehensive or collision coverages. Added-on services like roadside assistance or towing coverage can add a lot to your premiums, too.

If you’re OK making and paying for your own arrangements if something goes wrong, it’s OK to ditch these services and save money month to month.

Just think twice before reducing your liability coverage. An at-fault wreck that injures a group of people in another vehicle could clean you out financially if you don’t have enough coverage.

Look For Discounts While Shopping

Most insurance companies offer a wide array of discounts. The most common discount kicks in when you bundle policies.

If you have an auto and a home policy with one company, your agent can give you a discount when you add more coverages, such as an RV policy, to your account.

You can also get discounts when you’ve driven a specific amount of time with no accidents or when you have certain safety features installed on your RV.

Also, ask about low-mileage discounts for your RV or paid-in-full discounts which kick in if you pay your premiums annually instead of month to month.

Balance Your Deductibles

As anyone with health or auto insurance already knows, a higher deductible can save you money on premiums.

A deductible is the amount of money you pay out of pocket to unlock the insurance coverage you’ve bought. (It typically doesn’t apply to your liability coverage.)

It can be tempting for a careful shopper on a tight monthly budget to opt for high deductibles since they result in lower monthly premiums.

Careful, though: If you buy a policy with a deductible so high you’d never be able to pay it, you may not be able to use the insurance coverage you’re buying.

Instead, you may choose not to repair a dent which can lead to rust which can lead to more expensive repairs down the road.

Look for balance: You should be able to afford to meet your deductible, but it shouldn’t be so low you can’t afford your monthly premiums.

What About Disappearing Deductibles?

Some RV insurance plans offer a program called disappearing deductibles. Each year without an accident results in a percentage reduction in your deductible.

If enough time goes by without an accident, your deductible could reach $0 even while you’re paying premiums based on a higher deductible.

Not all companies offer this option, but companies specializing in RV coverage tend to have it.

Your RV Itself Makes a Difference

Just like with cars, nicer and newer RV models cost more to insure.

If you’re shopping for an occasional use RV and want to save money on insurance premiums, consider a 5-year-old model. This will save money on property taxes, too.

RV Storage Coverage

I mentioned this above under RV-specific insurance coverages, but it fits here too since it can save you money.

If you park your Motorhome for most of the year, storage coverage can save you some real money. In essence, this coverage allows you to pay premiums based on how often you use the RV.

If it’s parked out behind your house for 9 months out of the year, you don’t have to pay collision or liability rates during that time.

Again, not all companies offer this option, but I’d make a point of finding it before buying a policy for an occasional use RV.

Top 5 Best RV Insurance Companies

And, of course, the company you choose for your insurance impacts your premiums as well as the quality of your coverage.

As you shop around, look for a company whose policies meet your specific needs. Cost matters, but the lowest quote doesn’t always mean you’ve found the best company for you.

Only you can decide whether a company meets your specific requirements. But as a shopper looking for RV insurance, I’d consider these companies first:

1. Good Sam Insurance Agency
Good Sam Insurance LogoFor more than 50 years Good Sam Insurance Agency has specialized in RV insurance. They know campers and trailers from the hitch to the brake lights. They know Motorhomes, too.

You’ll find just about any RV-specific insurance coverage mentioned in this post at Good Sam, and you’ll also get some of the best rates out there. Good Sam has solid marks from the independent insurance rating agencies, which means they’re likely in great shape financially.

Discounts include disappearing deductibles, low mileage, and bundled policies. Good Sam also offers boat, motorcycle, and auto policies. Good Sam’s RV club includes benefits such as roadside assistance and towing, and membership gives you a discount on your premiums.

Best for: An RV owner looking for an insurer who specializes in RV coverage and the RV lifestyle.

2. RVInsurance.com
RVInsurance LogoJudging by its name, you’d think RVInsurance.com may be new to the market and might not have the experience you’re looking for.

But National General backs the site, and it also works with other insurance stalwarts such as Safeco, Nationwide and Foremost. So you’re getting experience and decades of financial stability.

You’re also getting great customer service and a slick online interface which should make changing your policy or filing a claim simpler. RVInsurance.com specializes in finding you the precise coverage you need. It includes just about every kind of RV-specific insurance coverage, including Mexico coverage and disappearing discounts.

Best for: A shopper interested in customizing RV coverage to meet his or her specific insurance needs.

3. Progressive
progressive logoFor more than 75 years Progressive has insured cars, boats, motorcycles, and RVs. The company has grown steadily and now is the fifth-largest insurer in the country.

Progressive has top financial health ratings and stresses customer service.

But what about its RV-specific options?

They are pretty robust, though not as thorough as the earlier entries on this list. If you already have policies with Progressive, you can save by bundling in your new RV policy.

Best for: If you’re looking for a solid choice that offers the most opportunities to save through bundling with your other policies, Progressive deserves a close look.

4. SafeCo
Safeco LogoSafeCo has been around for almost a century. Its partnership with Liberty Mutual gives it credibility in the marketplace.

You can find companies with more diverse options for RV insurance, but if you’re looking for low premiums while still working with a reliable company, SafeCo can fill that niche.

These savings will depend in part on your RV’s safety features and your driving record. Paired with the company’s disappearing deductibles plan you can save even more.

Best for: The owner of a newer RV looking for solid insurance on a budget.

5. Foremost
Foremost LogoYou’ve probably heard of Foremost’s parent company, Farmers Insurance. Foremost extends Farmers’ coverage into the RV and mobile home market.

While its RV-specific coverage is not as thorough as Good Sam’s or even Progressive’s, Foremost covers a wider variety of towable vehicles than most companies, and that’s why they made this list. Foremost also offers an Emergency Expense Allowance for trips that caught my attention.

However, customer service could be an issue if you like dealing with your insurance company online. The Better Business Bureau has given Foremost an F for failing to respond to customer complaints online.

Best for: The owner of an uncommon type of camper or trailer who is most likely to seek help via phone instead of online.

Like the First Humans, You’re a Wanderer

I’m guessing if you’ve read this far you’re serious about actually doing it — about taking your life on the road in a recreational vehicle.

If so you’re doing something people have done for thousands of years. Long before we developed cities and jobs, people wandered the countryside with their friends, family, and pets.

They sat around campfires and were awoken by the rising sun. They gathered food along the way and existed as part of the landscape.

OK, maybe I am romanticizing it a little. The modern world has given us a lot, including insurance so you can wander without wondering so much what would happen if the RV broke down or if someone collided with you.

Take a few minutes to find the right insurance. It can help give you back your freedom.

The post Best RV Insurance Available for 2019 appeared first on Good Financial Cents.


Source Good Financial Cents https://ift.tt/2UizIu3