Thousands of courses for $10 728x90

الاثنين، 2 أبريل 2018

Here Are 7 Ways to Support Good Health for Everyone — Including Yourself


National Public Health Week may not be as unusual as National Button Week or as oddly specific as National Aardvark Week.

But I’d argue that public health is just as important — if not more so —  than collectibles and burrowing animals.

The American Public Health Association must think it’s a pretty important issue to commemorate, too. In honor of National Public Health Week, the association has come up with a few ways for people to get healthy while advocating for a strong public health system.

7 Ways to Commemorate National Public Health Week

Here are a few ideas from the American Public Health Association on how to support National Public Health Week, along with some additional other tips to keep you healthy throughout the year.

  1. Join the Generation Public Health community and take the pledge to help create a healthy America.
  2. Join APHA’s 1 Billion Steps Challenge and help the organization reach 1 billion collective steps in time for next year’s National Public Health Week.
  3. Take a look at APHA’s initiatives to address the nation’s public health concerns and find out how to get involved.
  4. Visit your local public health department for free or low-cost health screenings to detect everything from prostate and cervical cancer to sexually transmitted infections.
  5. Keep your brain in tip-top shape with healthy food and regular exercise.
  6. Learn the art of healthy cooking on a shoestring budget.
  7. If you’re a smoker, consider quitting.

Lisa McGreevy is a staff writer at The Penny Hoarder. She loves telling readers about affordable ways to stay healthy, so look her up on Twitter (@lisah) if you’ve got a tip to share.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder https://ift.tt/2JaEOTE

Auto Bits: 3 ways soybean farmers’ biodiesel helps clear the air

Tip of the WeekSoybean farmers in Minnesota wear many different hats: small-business owner, agronomist, equipment expert, accountant and environmentalist. Yes, they are the original stewards of the land, continually evolving their practices to keep natural resources healthy for the next generation.But it doesn’t end there. Soybean farmers have been at the forefront of developing a homegrown renewable fuel that has resulted in a dramatic improvement of the air quality in the [...]

Source Business - poconorecord.com https://ift.tt/2pZty3P

The Top 10 Principles to Optimize Your Web Design for Mobile Users

It’s time for you to adapt to the latest marketing trends. Your company can no longer afford to ignore mobile users.

Your website must be optimized for mobile devices. Why?

Well, for starters, 80% of the top websites according to the Alexa rankings were optimized for mobile users. Plus, 80% of all Internet users have smartphones.

It’s easy for people to browse the Internet from their mobile devices. Doesn’t it seem like everyone is glued to their smartphones all the time?

Even those who aren’t holding their phones right now, I’m sure, have them within arm’s reach, either in their pockets, purses, or on nearby tables.

This is great news for your company and your website. Our love for mobile devices makes it easier for your current and prospective customers to access your site.

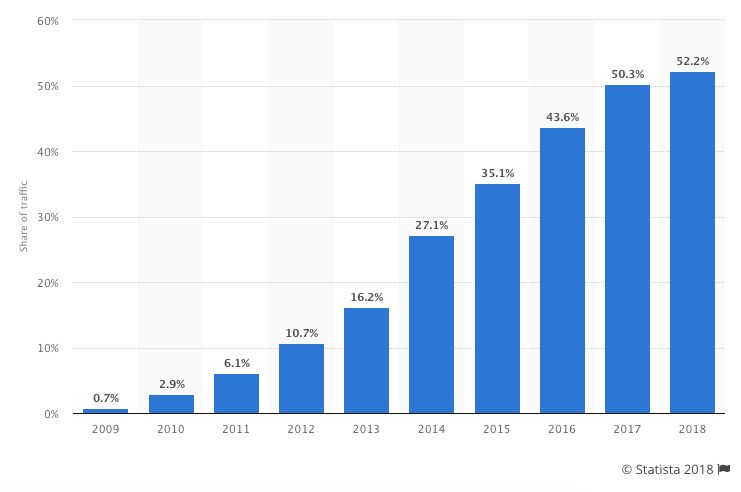
According to Statista, more than half of the global web traffic comes from mobile devices:

image2 11

As you can see from this graph, this number continues to grow each year. I expect this trend to continue in the years to come.

This percentage is even higher in some areas of the world. For example, more than 65% of web traffic in Asia comes from mobile devices.

No matter what industry you’re in or where you’re located, your site needs to accommodate mobile users. How can you do this?

I’m here to explain the top principles of an effective mobile web design. If you can apply these concepts to your mobile site, you’ll benefit from an increase in traffic and more engaged users.

Ultimately, this will lead to higher conversion rates. Here are the top 10 tips you need to know.

1. Simplify your menus

Obviously, mobile screens are significantly smaller than laptop or desktop screens. Keep this in mind when designing your menu options.

The menu of your desktop site can be more extensive and have lots of options. But this complicates things on a smaller screen.

You don’t want visitors to have to scroll or zoom in and out to see all the navigation choices. Everything needs to be concise and fit on one screen.

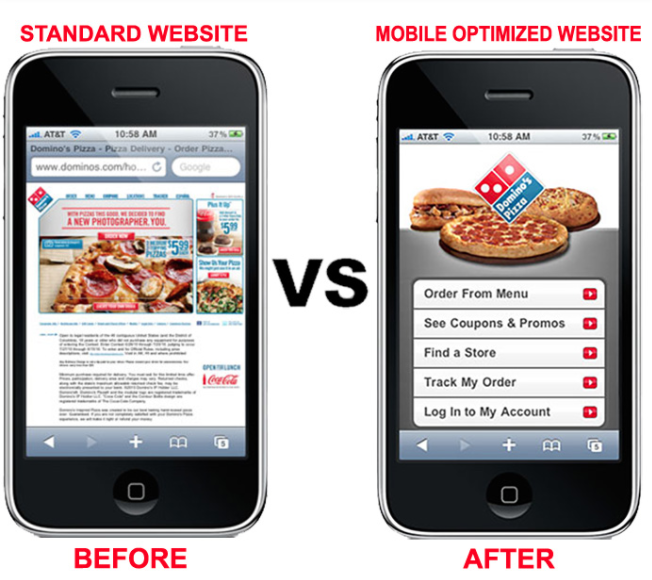
Here’s a great example of this concept applied by Domino’s Pizza:

image7 10

Take a look at what their standard website looked like on a mobile device before it was optimized. Navigation was nearly impossible.

Users had to zoom in to see the menu to find out how to proceed. If your mobile site is the same, it will crush your conversions.

But look at how simple this menu is on a mobile-optimized site. Dominos was able to simplify its entire website into five menu options.

Each option fits on the screen and has a clear destination. Evaluate your current website, and try to simplify the menu options for mobile users.

2. Keep forms as short as possible

Think about all the different forms you have on your website. If you’re asking the visitor for a lot of information, it’s not an effective approach.

Instead, you should change the design to keep your forms short.

Again, if someone is filling out a form on their computer, it’s not as big of an issue because it’s easier to type and navigate on a larger screen. But this isn’t the case with smartphones and tablets.

Evaluate your forms, and ask yourself whether you need each line.

For example, if you’re trying to get users to subscribe to your email list, you don’t need their home addresses and phone numbers.

Forms designed for buying conversions shouldn’t ask the user what their favorite color is. Get their billing and shipping info, and end it.

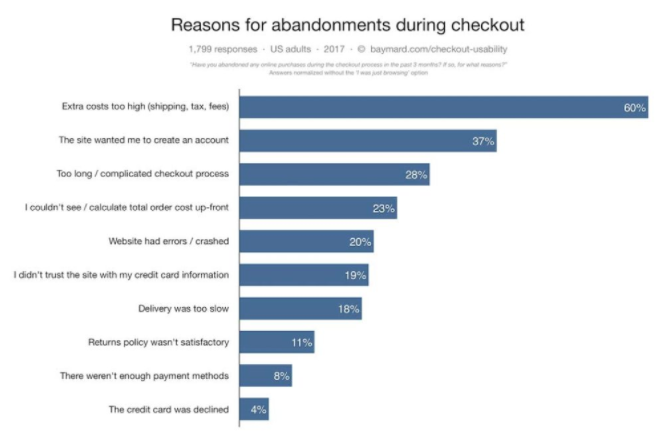
In fact, a long and complicated checkout process is one of the top reasons for shopping cart abandonment:

image5 11

If you want to reduce shopping cart abandonment rates from mobile devices, you’ll need to change the design of your mobile website forms.

3. Clearly display your CTAs

Let’s continue talking about conversions. To have an effective mobile web design, your call-to-action buttons need to be obvious.

Since we’re dealing with a smaller screen here, you don’t want to overwhelm the user by trying to squeeze more than one CTA on the screen.

Think about your goal for each landing page. Are you trying to get downloads? New subscribers? Increase social media presence? Get visitors to buy something?

Your CTA needs to focus on that primary goal.

Focusing your attention on your CTA buttons will give you an edge over your competitors. That’s because 53% of websites have call-to-action buttons that take users more than three seconds to identify.

That’s far too long. Your CTA should be easy to spot in just one or maximum two seconds.

4. Include a search function

This design principle relates back to what I previously said about your menu options. Right now, some of you may have a menu with 20 or 30 different options.

It may seem impossible to try to simplify those options to fit on just one page. Well, it can be done, especially if you add a search bar to your mobile site.

Encouraging users to search for what they want reduces the need for you to rely on a large and complex menu. Too many options will confuse the visitor and kill your conversions.

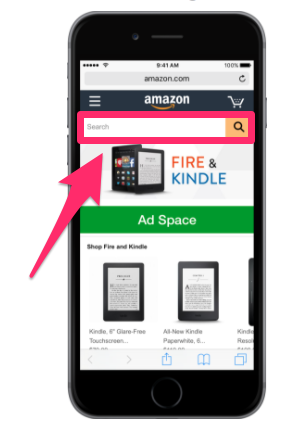
This feature for sure needs to be incorporated into the web design of ecommerce sites. Let’s take a look at the home screen of an industry giant Amazon:

image1 11

Amazon sells over 12 million products. Take a minute to let that number sink in. I’m willing to bet your website doesn’t sell nearly as many products.

I’m not saying this to make you feel bad. But I want you to realize that if Amazon can use a search bar to help mobile users browse through millions of items, your company shouldn’t have any issues applying the same concept for hundreds or thousands of products.

Implement a search bar to simplify your design and make it easy for mobile users to find exactly what they’re looking for.

5. Make customer service easily accessible

No matter how much time and effort you put into simplifying your mobile web design, people will still have issues.

Don’t worry, it’s all part of running a successful business and website. But the key here is being able to quickly and effectively help your mobile site visitors work through their problems.

Make sure you’ve got obvious customer support information on your mobile site.

Provide your phone number, email address, and social media profiles. Display anything that gives the user an option to contact a representative from your company as fast as possible.

Put yourself in the shoes of a frustrated mobile user who has a question or problem. If they can’t get help from your customer service team, it’ll leave them with a bad impression of your company.

Adding obvious customer support information to your mobile web design is something that can’t go overlooked.

6. Size matters

Navigating a website from a desktop or laptop computer is simple. It’s easy to control a cursor from a mouse or keypad.

But browsing with your thumbs on a 4-inch screen isn’t as easy. Keep this in mind when laying out different elements of your mobile site.

Buttons need to be large enough to be tapped with a finger. Make sure you keep enough space between buttons so someone doesn’t accidentally click the wrong one.

Having to tap the same button several times to make it work will frustrate mobile users visiting your website.

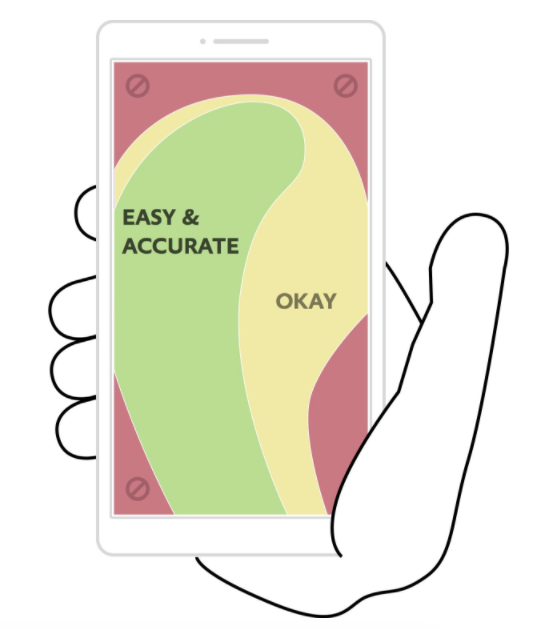
You also need to keep in mind the placement of clickable items on the screen:

image4 11

Keep in mind 75% of smartphone users use their thumbs to tap on the screen.

This image shows you the best location on the screen to place buttons. Avoid the corners: it’s hard for a person to reach those places with their thumb while holding a mobile device.

The reach decreases further as the screen size becomes larger. It’s in your best interest to place the most important elements and clickable buttons toward the middle of the screen.

7. Eliminate pop-ups

Get rid of pop-ups on your mobile site. For the most part, people don’t like pop-ups as it is. They are annoying and hinder the user experience.

The problem with pop-ups on mobile devices is they become even more of a nuisance because they are so difficult to close.

Recall that people use their thumbs to tap on small screens. The small “X” button to close a pop-up will be so small on a mobile device that users won’t be able to close the window.

They might even accidentally click on the ad while trying to close it. They’ll get brought to a new landing page, which will ruin their experience.

Sometimes users will try to zoom in on the close button to make it easier to tap, but then the dimensions of the screen get messed up as well.

It’s best to remove these pop-ups altogether. Come up with other ways to promote whatever your pop-up is advertising.

8. Avoid large blocks of text

Reduce the amount of text on the screen of your mobile website. Obviously, you’ll need to use some words to communicate with your visitors, but keep sentences and paragraphs as short as possible.

Large blocks of text are overwhelming and difficult to read. Remember, if a paragraph is two lines long on your desktop site, it might be six lines long on a smartphone.

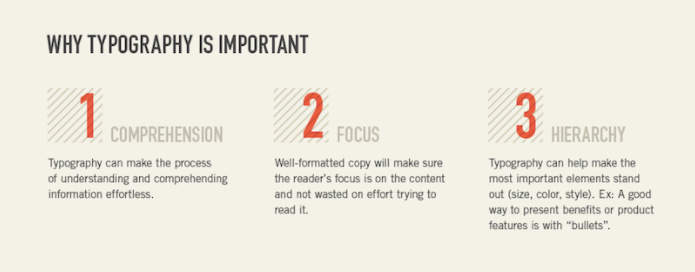
Take a look at how typography affects conversions:

image6 11

Keep these three elements in mind whenever you’re adding text to your mobile site.

Can the visitor comprehend your message? Where is their point of focus? What is the visual hierarchy?

Eliminating large blocks of text makes this possible.

9. Choose the right font

Let’s continue talking about the text on your mobile site. Picking the right font is a crucial design principle as well.

Fonts need to be clear and easy to read. But you can also use fonts to set two lines of text apart.

You don’t want the text of one line to run into the text of another.

For example, you could use all capital letters and bold font for the headline of a section. Then use regular capitalization rules and non-bold font for the line underneath to show a clear separation.

You’ve got a small space to work with, so you can’t rely on a page break or image every time you want to separate text.

10. Prioritize speed

No matter what changes you implement on your mobile website, you need to keep its speed in mind.

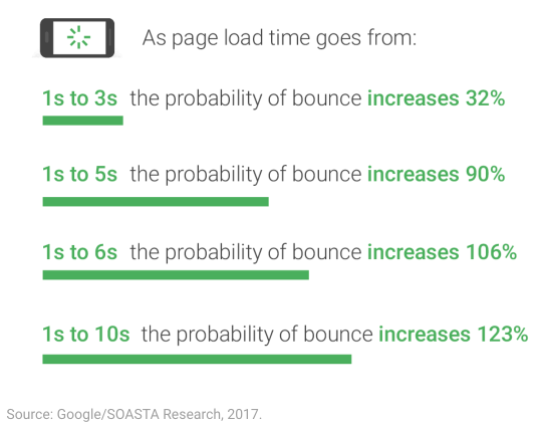
Research shows that 53% of people will abandon a mobile website that takes more than three seconds to load. Take a look at how these bounce rates increase with increasing page loading times:

image3 11

The best way to keep your page loading time as low as possible is by simplifying your design.

Fortunately, if you follow all the other principles I’ve outlined so far, this shouldn’t be an issue.

Eliminate unnecessary heavy images and flashing lights. Simple websites load faster and have higher conversion rates.

Conclusion

Your website needs to be optimized for mobile users. To do this effectively, you need to understand some important design principles.

Simplify your menu choices, and keep forms short. Make sure your CTAs are clearly displayed, and stick to one CTA per page.

Add a search bar to help improve navigation while clearing up space on the screen. You should make it easy for mobile users to contact your customer service team.

Realize that people are using their thumbs to tap on the screen, so buttons need to be sized accordingly. Get rid of pop-ups as well.

Carefully select an appropriate font that’s easy to read. Eliminate large blocks of text on the screen.

No matter what, make sure your mobile site loads as fast as possible.

Follow these top 10 mobile design principles to maximize conversions on your mobile website.

What design elements need to be changed on your mobile website?


Source Quick Sprout https://ift.tt/2EdVtlB

Questions About Unit Pricing, Social Security, Cloth Napkins, and More!

What’s inside? Here are the questions answered in today’s reader mailbag, boiled down to summaries of five or fewer words. Click on the number to jump straight down to the question.
1. Unit pricing
2. Waiting for Social Security
3. Handling leftovers
4. Relocating as a contractor
5. Sudden credit score decline
6. Relocating as a contractor
7. Second jobs for additional income
8. Digging out of tax problem
9. Vanguard and conflict of interest
10. Cryptocurrency question
11. Lifestyle inflation
12. Cloth napkins versus paper

As many of you know, I relish the warm weather of spring and summer. I spend all winter looking forward to the warm days of spring, where I can go on hikes in the woods looking for morels and exploring trails.

Sometimes, however, Iowa likes to hold onto winter, stretching it out well into April. Yesterday, on the first, my family drove through a snowstorm after visiting people for the Easter weekend. The extended forecast rarely shows temperatures breaking 40 F and shows many patches of snow.

Some years, I’ve already hiked for many hours in the beautiful spring weather at this point. Other years… not so much. This is one of those very late springs, and I’m counting the weeks, days, hours, and minutes until warm weather arrives.

Q1: Unit pricing

As I was walking through the grocery store last night I was looking at unit pricing on a few items and thought to my self I am surprised I have never seen Trent do an article on Unit Pricing. Just thought it might be a money saver for some people who some of which likely don’t even know what it is.
– Jim

I haven’t written about it in a while (the last time I really covered it well was in this article a couple of years ago) but it’s a good topic to touch on regularly.

Unit pricing is a simple way to compare very similar products in the store – for example, the four roll package of toilet paper and the nine roll package of the same kind of toilet paper. To do that, you break the item down into individual “units” – in this case, individual rolls. What’s the cost per “unit” of the four roll package? Well, the cost per roll is the price of that package divided by four. What’s the cost per “unit” of the nine roll package? It’s the price of that package divided by nine. Buying the one with the lowest cost per roll is the best bargain.

The actual “unit” to be compared varies a lot. You might compare the cost per ounce or the cost per bag or the cost per tablet, for example. You should also consider whether there’s any chance of it going bad before you’d use it up.

Using unit pricing to decide which particular package to buy at the store is a good way to minimize cost provided you have the storage space for bulk items. However, it isn’t always the bulk items that have the best unit price (though it often is) – it’s worth your time to calculate it.

Q2: Waiting for Social Security

My question is about Social Security benefits. We are both waiting until 70 1/2 because we are doing fine, even saving. When we start getting SS, what is the best way to save it? We both have some investments, I have a nice deferred compensation account from my job. We have no debts, own our home, live frugally. We might take one major travel adventure in the near future.
– Anna

I would delay getting Social Security benefits for as long as possible. The longer you wait, the larger the monthly benefit will be.

Once you do start receiving them, I would make absolutely sure that you’re fully funding your Roth IRA each year. As you’re over 50, your annual contribution limit is $6,500, so I’d hit that cap. With money beyond that, I would shore up your expenses by putting money aside for your next vehicle replacement, an emergency fund, and any upcoming major home repairs. All of that can (and probably should) be done in an ordinary savings account.

Without a full picture of your retirement, I can’t really give you more specific advice than that, but that plan will serve almost everyone who nears retirement.

Q3: Handling leftovers

I just read the answer below about how to be sure that leftovers are safe to eat. The system I have used for many years is to simply put the leftovers in a sealed container, put a small piece of Scotch tape on the lid of that container, and use a Sharpie black pen to write the current date on the piece of tape. My husband and family use this system too, and know that anything not eaten within one week should be composed or thrown away. When the container is washed, the tape is removed and the process begins again. This system minimizes food waste and maximizes food safety.
– Monique

I received a bunch of emails about leftovers over the last few days; this was one of the most clear ones.

Over the course of my life, I’ve lived in several distinctly different climates. For example, I grew up living in a very warm and humid climate. We didn’t have air conditioning and lived very close to a very large body of water. Food would go bad at the drop of a hat, sometimes within an hour or two, and it would even go bad in the fridge in a couple of days depending on what it was.

Today, I live in a much drier place – it’s simply never very humid outside – and it’s colder, too, as I moved quite a bit northward. Here, things seem to last for ages without going bad. I can leave food in the refrigerator for insanely long periods without any problem, things that would go bad in a few days back where I grew up.

If you add on top of that the fact that some foods just go bad faster than others depending on salt content, acid content, and so on… it is just really hard to come up with hard and fast “leftover rules” that would work for everyone.

My sincere best advice for anyone, especially anyone that moves around much and/or eats a widely varied diet, is to simply know how to identify when food goes bad. You should be able to look at food, smell food, touch food, and know whether it’s safe to eat with a very high rate of success. Using actual day counts might work in your specific area, but they’re going to not work for other areas and they’re not always going to work from dish to dish.

Q4: Thoughts on Fundrise

What do you think about Fundrise as a way to diversify investments? Appears to be low cost and beat Vanguard’s REIT, at least in its short history. Although the yearly account management fees are small, it appears that a larger percent of money is taken out on distributions?
– Kara

I think you’ve got the right take on Fundrise.

Fundrise is basically a somewhat diversified way to invest in real estate. Essentially, they offer a selection of real estate that you can invest in at your choice (or let them choose for you using certain criteria). You’re investing in these with lots of other investors and you’re effectively co-owners of this property. Naturally, Fundrise charges some fees for this, which appear to be low by some measurements, but it’s unclear in other areas because this is a privately-held investment and isn’t subject to some of the disclosure that other investments must provide per SEC regulations.

Their returns look great, but the properties on offer through Fundrise are ones that are what I would describe as big winners when the real estate market is good and fairly shaky when the real estate market isn’t as good. Real estate has in general been pretty good since 2008.

I would categorize investing with Fundrise as being relatively risky, with the potential for high returns but some significant chance of bad returns and losses if the real estate market goes bad. I wouldn’t invest everything you have there regardless, but nothing strikes me as inherently flawed, either – it’s just a fairly high risk and (potential) high return investment opportunity with fees that are really hard to clearly identify (they may be pretty high and are being disguised by great returns at the moment).

Q5: Relocating as a contractor

I am considering relocating to another state (I presently reside in MA). In MA, I benefit from legislation which requires that employers make 401K plans and health insurance available to any employee, even if contracted to a client but paid via W2 through an agency. I am having difficulty discovering what will be available to me should I relocate to a different state where the employer/contractor distinction is very different, and I am treated more like a 1099 worker.
– Anna

It’s very likely that you’re signed to a contract that spells out your benefits that you’re receiving, as well as a termination date and other such information. As long as you have that contract in place, your employer and you will follow the terms of it.

When you move, your employer may choose to enact their termination clause in the contract and offer you a different one in line with the laws in your new state. There’s not much you can do about that. Likely, they’ll just stick with the current contract and offer you something different the next time around.

You need to look up laws for contracted employees in the state you’re considering moving to. Google really is your friend here. Then, you need to figure out if offers that follow those laws are something you can live with.

Q6: Sudden credit score decline

My credit score has been above 610 for long time. On March 21 it tanked to 525. Signed up today with credit repair service to fix score. dont know why score tanked as there have been no changes for a while. looking for possible loan of up to 1000 to repair van, get it tagged, buy washer and dryer. Just got approved for rental property but it doesnt come with any appliances. Need frig, stove, washer, dryer, dishwasher. can you offer any suggestions thank you gail sayre husband is a disabled vet. I just retired from nsg. and can no longer work.
– Ron

The first thing I’d do is head over to the Federal Trade Commission’s credit report site, where they allow you to get one credit report from each credit bureau each year. Get your credit report, go through it, and see if there’s anything on there you don’t know about. I’d do this first because my instinct is telling me that someone may be using your identity illegally.

If everything checks out there, make sure you’re not behind on any bills or carrying a large balance on any of your credit cards, as both of those things can ding your credit score.

If none of those things are true… I’m really not sure why your credit score would have fallen so much without more details. I’d say it’s extremely likely that one of the above things explains it.

Q7: Second jobs for additional income

I was wondering what your opinion is on second jobs for additional income. I’m thinking of getting a second gig to build up my savings faster. My pretax salary a year is around 75k. I put 175.00 per pay period (biweekly) into a 457 account pretax. I also use flex spending which comes out to 720.00 a year pretax. I work for city government so I have IPERS for a retirement in addition to my 457. I’m 42 years old, divorced, and no children. I have my mortgage and truck payment for debt. I save about 25% of my take home pay. I guess my question is if I get a second gig to save more, should I be concerned with making more and therefore paying income taxes next year?
– Will

I started The Simple Dollar as a “second job” and built it up while working a full time salaried job with a significant amount of travel.

Yes, if you earn more, you will be paying more in income tax next year, but the increase in taxes will be far, far less than your increase in income. The first $15K or so that you earn at your second job will be taxed at 25%; everything beyond that that you earn at your second job will be taxed at 28%. Nothing about your current job will change in terms of taxes.

Getting into a higher tax bracket doesn’t change anything about the taxation of your current income. It just means that any additional income will be taxed at a slightly higher rate, and the highest federal rate right now is 39.6%, which people don’t hit unless they’re making over $400,000 a year. Even then, their first $10K (approximately) in income is taxed at only 10%, and so on.

Q8: Digging out of tax problem

I think I’ve gotten myself into a very bad tax situation and I’m wondering what is the least costly way to proceed.

Several years back I was gifted a share of a limited partnership which holds some small businesses and commercial rentals- each year I receive a K-1 and a distribution that usually covers the extra taxes and a tiny bit more. The partnership is starting to wind down its investments and I just received my 2017 K-1: the partnership sold some assets which added an extra $100K of capital gains to my 1040 and also triggered AMT and investment surcharge so my tax liability went up quite a lot – my 2017 income taxes are $46,639 federal plus $12,778 state. I’d paid estimated taxes based on 2016 partnership income so while I don’t owe penalties I do owe an extra $25K.

I’ve been informed that the partnership will distribute around $35K in the next few weeks, and also to expect significantly higher capital gains next year as the sale closes on a larger real estate parcel. The remaining gains from the 2017 sale will be put into site-work for another parcel which may sell in 2018 or 2019. Note that I can’t sell my shares nor do I have any voting rights over how the partnership is run. My problem is 2018 estimated taxes. Given that I expect a higher tax liability in 2018 I need to pay the safe harbor rate 110% of 2017 taxes in order to avoid penalties. This comes to a total of $65,359 between federal and state. Looking at my payroll numbers so far this year and using tax withholding calculators, given that I’m contributing to my 401k the maximum $18K, my take-home pay after withholding the necessary taxes would be $242 per semi-monthly paycheck. I will also owe my usual property and car taxes, a yearly total of $4012, which necessitates saving $167 per paycheck. This leaves me with $75 per paycheck after taxes and retirement savings. I can’t live and work on $150 per month- my mortgage is $1260, my condo fee is $430, my utilities are $160 (electric, gas, and minimal internet and cell which are required for work), my gas for commuting to work is $80 and car insurance is $83… I live in an expensive real estate market – my current home is designated as “market-rate affordable housing” so I don’t expect I could find a better deal by moving; also we are in the midst of roofing and foundation work which make the place rather unappealing to buyers.

I do have ~$25K cash savings and ~$10K left from the 2017 distribution, but it seems too risky to spend down all of my savings in expectation of a large lump-sum distribution over which I have no control. I could stop 401k contributions for 2018 to free up an extra $18K but this seems like a terrible move given that my marginal tax rate will be at its max in 2018 compared to future years. I don’t think I could commit to a second job given that my main job in cybersecurity has long unpredictable hours and I don’t have any valuable assets to sell other than my condo, car, and a lot of retirement savings. I really don’t know what to do to pay my 2018 estimated tax liability. Furthermore, I’m concerned that the situation will repeat in 2019 given that another parcel is still for sale and the 2018 capital gains are projected to be significantly higher than the 2017 sale.

Something seems off about the situation to me – I shouldn’t be in such dire financial straits with a 110K salary and no debt except a reasonable mortgage (compared to rentals in the area it is a great deal), but as far as I can tell these are the numbers.
– Cal

I would take this whole situation to a tax specialist, because either (a) something is wrong with your numbers or (b) this partnership is being managed with an incredible level of incompetence that’s negatively affecting everyone involved with it.

If you find that the tax bill really is this onerous, you can talk to the IRS about a payment plan. I speak from experience when I say that the best route for dealing with the IRS when you are worried about your ability to pay taxes is to talk to them directly. They will help you figure out a way to pay it without putting yourself in dire straits and without stiff penalties.

If this really is bad management of your partnership (if that’s what your tax specialist concludes), I’d try to get ahold of some of the other partners and see if anything can be done about it. If a partnership is throwing out huge tax burdens to the partners like this, then it’s not benefiting anyone.

Q9: Vanguard and conflict of interest

I was reading on another messageboard about how Vanguard is better than other investment houses because it protects people from conflict of interest. I tried to figure out this statement but I don’t understand what it means. Help?
– Alan

Unlike most other investment houses, Vanguard is actually a collective of a bunch of smaller companies that essentially share a lot of business features (like marketing and account management and administration). Each fund is operated as an independent business with pretty thick walls between each fund.

What that means is that you don’t have situations where someone is involved with a whole bunch of funds and has personal reasons for favoring one fund over another one. This can happen at other investment houses, though it’s pretty rare today.

While this is an interesting feature of Vanguard, it’s not the reason to use it as your primary investment house. I use Vanguard, but that’s mostly because I agree with their philosophy of intense focus on using index funds.

Q10: Cryptocurrency question

I don’t understand why you are negative on crypto. High risk = high reward has a place in everyone’s portfolio.
– Daniel

High risk / high reward investments make sense as a part of a portfolio in an established and regulated market. Crypto is not an established or regulated market. It’s the Wild West out there, with hundreds and hundreds of different cryptocurrencies and many of them amounting to little more than pyramid schemes or pump-and-dump schemes.

The blockchain idea behind Bitcoin is brilliant. There are people, especially early adopters, who have become very wealthy because of it. That doesn’t mean it’s a sound investment, especially now that the “early adopter” period is over.

Most new cryptocurrencies being started right now are very questionable in terms of their support, their reputation, and their organization. That’s not to say that people won’t make money, but it’s pure speculation. It’s not something I’m ever going to recommend to someone as an investment.

Now, if you have some cash and are enamored with crypto and can afford to gamble, go for it. I’m not going to question what people do with money that they can afford to lose without disrupting their future.

Q11: Lifestyle inflation

Why do so many personal finance books and websites tell people to not spend any more when they get a raise or to not spend inheritance or lotto winnings? What is the point?
– Alex

The point is that if you’re living a content life right now, there’s no real reason to start spending more money. Instead, you should use that money to secure the life you have now against things that will inevitably come in the future.

No matter what, your car is going to wear out. No matter what, you’re going to get older and eventually want to retire. No matter what, you’re going to face some life emergencies and have to figure out how to handle them.

If your life is pretty good and you get a raise or a windfall, why not use that extra cash to preserve the life you have now and protect it against those kinds of things that you know are coming up? If you just spend that windfall or inflate your spending to gobble up that raise, you’re just going to get walloped by those events down the road, knocking your life down to worse than where it was.

If you have a good life, ensure you keep that good life. Don’t chase a very slightly better life for a short while before you stumble down into something worse.

Q12: Cloth napkins versus paper

Can cloth napkins ever pay off against paper ones? Decent ones cost so much that I don’t think you could ever use them enough.
– Drew

So, let’s start with the napkins. My preferred cloth napkins in terms of bang for the buck are these, which are simple and elegant and stand up to a lot of rewashings and bleach to remove stains. They cost $1.25 apiece.

What’s comparable with paper? These are supposedly good for the price (I don’t use many paper towels, so I’m not sure). You’re buying 12 rolls of 158 sheets each for $24.25, and you’d probably use 2 sheets as a napkin substitute. That’s almost exactly two and a half cents per napkin replacement. (This is an approximation, of course, depending on whether a folded paper towel is okay or you want an actual paper napkin.) So, in this case, you’d need to use a cloth napkin 50 times to replace a paper napkin. A good cloth napkin will last a lot longer than that.

Now, with cloth napkins, you’ve also got to wash them and replace them, but the cost to wash a cloth napkin in a big batch of whites is negligible.

So, if you’re going to use napkins a lot, then cloth napkins are worth it. If they’re rarely used, then don’t bother.

Got any questions? The best way to ask is to follow me on Facebook and ask questions directly there. I’ll attempt to answer them in a future mailbag (which, by way of full disclosure, may also get re-posted on other websites that pick up my blog). However, I do receive many, many questions per week, so I may not necessarily be able to answer yours.

The post Questions About Unit Pricing, Social Security, Cloth Napkins, and More! appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2EdCEz0

I Used to Get Paid to Write Greeting Cards — Here’s How You Can Get Started

From Surveys to Blogging – How This Mom Found the Path to Six Figures

Anna Thurman's work-at-home journey started with surveys, writing articles, and working online for sites like ChaCha. Through these side hustles, she was able to replace the income she had previously earned outside the home. But even though she was earning a steady income, she was amazed at what was going on in the work-at-home niche […]

The post From Surveys to Blogging – How This Mom Found the Path to Six Figures appeared first on The Work at Home Woman.


Source The Work at Home Woman https://ift.tt/2GqHXwT

529 Plans: How They Work and When to Use Them

If you’re thinking about saving for your child’s college education, you’ve probably heard of 529 plans.

They’ve been the go-to college savings account for a while now, and with the recent changes to our tax code they’ve become even more flexible. That’s because the tax breaks offered by 529 plans have been expanded to include K-12 expenses in addition to higher education expenses.

But there’s a lot of confusion around 529 plans and when it makes sense to use them, and this post will clear that up. You’ll learn what 529 plans are, how they work, and what the pros and cons are.

Let’s get into it!

What Are 529 Plans?

A 529 plan is simply an investment account that offers tax breaks when the money is used for qualified education expenses like tuition, fees, books and other supplies, and room and board. In fact, they function much like a Roth IRA, but for education instead of retirement.

Contributions to a 529 plan are made after-tax, though some states allow you to deduct your contributions for state income tax purposes. Money inside a 529 plan grows tax-free, and money can be withdrawn tax-free for qualified education expenses. If it’s withdrawn for any other purpose, the earnings are subject to taxes and a 10% penalty.

Until December, qualified education expenses only included higher education. But with the passing of the Tax Cuts and Jobs Act, you can now withdraw up to $10,000 per year, per child, tax-free for qualified K-12 expenses as well.

Which means that 529 plans have become tax-advantaged education savings accounts instead of being limited to college savings like they were previously.

529 plans are run by states with almost every state offering one or more options. There are two main types of 529 plans, each of which has its own pros and cons.

529 savings plans allow you to invest your contributions in a pre-selected set of mutual funds, similar to how you’re offered a set of investment options within your 401(k). Your account balance rises and falls based on your contributions and the performance of your investments, and the money you have in your account can be used at any time for any qualified education expenses.

Although 529 savings plans are run by states, you’re not obligated to use your home state’s plan. In fact, you may save money by using another state’s plan, which we’ll get into below.

529 prepaid tuition plans allow you to pre-purchase college credits at public in-state universities, essentially allowing you to lock in the current cost of college. They’re not as flexible as 529 savings plans, which can be used for any qualified expense incurred at any eligible school across the country – but they do offer a little more certainty in the sense that you know exactly how much school credit you’re purchasing.

For the most part, you must be a state resident to enroll in a particular state’s prepaid tuition plan.

While 529 prepaid tuition plans can be useful in the right situations, they can also be fairly restrictive, and the terms and conditions vary by state.

529 savings plans are more flexible, more widely available, and generally make more sense for most families. For those reasons, the rest of this article will focus specifically on 529 savings plans.

Pros of 529 Savings Plans

1. Tax-Free Growth and Withdrawals

The tax benefits are the big draw of 529 plans. The money you invest grows tax-free and can be withdrawn tax-free for education expenses, which means that every dollar you save goes further than it would in a regular investment account.

Let’s say that you can afford to invest $1,000 per year from the day your child is born and that you earn an 8% annual return. Two percent of that annual growth is in the form of dividends taxed at 15% per year, and the rest of that growth is from capital gains that are taxed at 15% when you sell.

After 18 years, you would end up with approximately $36,999 after taxes in a regular taxable investment account. But you would have $41,446 in a 529 plan, because all of the growth would be tax-free.

Those tax breaks translate to an extra $4,447 available for education expenses.

2. State Income Tax Deductions

While you can’t deduct your 529 plan contributions for federal income tax purposes, there are currently more than 30 states that offer a state income tax deduction, and in some cases you don’t even have to contribute to your home state’s plan in order to get it.

If you live in one of those states, that deduction could allow you to contribute a little bit more because of the tax savings you receive on the back end.

3. High Contribution Limits

Unlike Roth IRAs, 529 plans have no income restrictions that prevent people from contributing, and very little in the way of contribution limits.

Most 529 plans have lifetime contribution limits that range from $235,000 to $500,000, but most of them do not have annual contribution limits. Though for the most part annual contributions from any individual are effectively limited to $15,000 per year, per child, due to the federal gift tax.

Married couples filing jointly can combine that limit and contribute up to $30,000 per year, per child, and there’s even a way to contribute five times that amount in a single year without gift tax consequences.

The bottom line is that if you want to save a lot of money for education, a 529 plan will allow you to do it.

4. Flexibility to Change Beneficiaries

Each 529 plan has a named beneficiary, which is the person that the money is being saved for. But you can change the beneficiary to just about any other family member, which means that if one child doesn’t need all the money for education you can simply use it for another child, or even for yourself or a grandchild or a niece or nephew.

Cons of 529 Savings Plans

1. Limited to Education Expenses

The big downside to 529 plans is that if you don’t use the money for qualified education expenses, the earnings you withdraw are both taxed and subject to a 10% penalty.

There are exceptions for scholarships, but beyond that, those penalties should make you wary about over-contributing to a 529 plan.

2. Potential State Penalties When Used for K-12 Expenses

While the federal law has been updated to allow tax-free and penalty-free withdrawals for qualified K-12 expenses, some states may not be quite as generous.

There are concerns that some states might still apply penalties for withdrawals that aren’t used for higher education and may also recapture any state income tax deductions from prior years for early withdrawals. Given how new all of this is, it’s probably a good idea to speak to an accountant before using 529 money for K-12 expenses.

3. Potentially Costly Investments

Each 529 plan offers its own limited set of investment options, and in some cases those investment options can be quite costly.

For example, Montana’s 529 plan offers several investment portfolios that each cost around 0.80% per year, compared to New York’s 529 plan where every investment option costs 0.15% per year.

Cost is the best predictor of future returns, with lower costs leading to better performance. If your state’s investment options are high-cost, you’ll have to weigh the savings offered elsewhere against any potential state income tax deduction before deciding which plan to use.

4. Don’t Forget About Other Financial Goals

While saving for your child’s education is great, it’s usually a good idea to prioritize other financial goals first. Contributing to a 529 plan typically only makes sense once you’ve already handled other financial responsibilities like saving for retirement, getting insurance, and paying off debt.

529 Plans the Smart Way

529 plans can be a great way to save ahead for your child’s education, especially now that the money can be used for K-12 expenses as well. That added flexibility simply increases the opportunities you’ll have to use the money for whatever you need.

But the fact that withdrawals from a 529 plan are taxed and penalized if they’re not used for qualified education expenses means that you should contribute carefully. You don’t want to contribute money that might be needed for other financial priorities, and you don’t want to over-contribute and have more saved up than you actually end up needing.

Matt Becker, CFP® is a fee-only financial planner and the founder of Mom and Dad Money, where he helps new parents take control of their money so they can take care of their families.

Related Articles: 

The post 529 Plans: How They Work and When to Use Them appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2EgtOkg

This Guy Gets Paid to Turn Your Backyard Into a Real, Buzzing Honey Pot

الأحد، 1 أبريل 2018

Cheap DIY Solutions to Spring Yard and Household Hassles

When spring arrives, plants return to life and many creatures stir from dormancy.

Sometimes, you wish they hadn’t.

When my wife and I bought our house five years ago, it was the first home of our adult lives that wasn’t an apartment. We found ourselves surrounded by 80 acres of neighboring farm and, suddenly, with roughly two acres of property to maintain along with our house.

We moved in during December, but received an introduction to most of our household headaches by late March and early April. Ants suddenly made trails to any piece of kibble left behind by cats. The cats, meanwhile, had their paws full with the random shrews and field mice that had appeared in our basement. Moles and voles left dirt piles in our yard, moss began to show up in small green patches on our roof shingles, wasps appeared from under the eaves, and weeds of all sorts appeared amid the grass.

We learned the hard way that we couldn’t buy our way out of every problem. Ant traps were largely ineffective. Mouse traps and poisons were out of the question thanks to the cats. Moss killer would damage some of our gutters and surrounding plants. Two people using weed killer on two acres of property is like trying to bring down an elephant with a pellet gun. But through our continuing battles with pests of all stripes, we learned some lessons about how to deal with them both effectively and frugally.

The following are just a few of the problems we’ve encountered along the way, and some of the solutions we’ve adopted to help them out. We don’t claim that they’re perfect, and I encourage tips and feedback in the comments if you have better solutions. But if they help out some poor homeowner besieged by the same issues, we’ll have done our part.

Ants

Cleaning out a bowl of cat food crawling with tiny sugar ants is no fun. It took only one invasion of that nature for my wife and I to head to the local Albertsons and stock up on Raid Ant Baits ($3.49 for a pack of four).

The ants proceeded to walk by those as if they were roadside hotels that just looked riddled with bedbugs. The next step was a trip to Home Depot and a 1.3-gallon jug of Ortho Home Defense for about $13.50. It worked well for a time, but with cats a bit too close to the spray areas for comfort, we sought other solutions.

One site suggested sprinkling Borax detergent booster ($6.79 for 65 ounces) and granulated sugar ($7.99 per 10-pound bag) around the places ants get in, like door thresholds and window sills. The ants are drawn in by the sugar and take the Borax, toxic to ants, back with them. That worked well, but left us with candied doorways and windows by the end of the season. Also, the sugar-Borax mixture isn’t great for pets that run afoul of it.

This year, however, we’re going with DIYNatural’s suggestion of taking Borax and powdered sugar instead of granulated ($2.99 for two pounds), rolling the mixture up in cotton balls ($2.79 for 200), and placing them on shallow dishes near the ant trails. So far, no ants beyond the first sighting and, at $12.57 total, it provides roughly 16 batches of bait while giving us roughly 200 traps — making each worth just cents apiece.

Shotweed

It’s a pleasant-looking weed that resembles clover with a bit of daisy, but shotweed gets everywhere and will turn into unwanted ground cover if you don’t take care of it. For years, our approach was to simply pluck it as soon as we saw it in the spring. But shotweed is small, delicate, and resilient. It’s also crafty: Hiding beneath boxwood or laurel and reappearing in a more sizable patch a year later.

The most effective solution, however, was to raid the kitchen for some white vinegar, salt, and dish detergent and spray areas where shotweed was most prevalent. We had to restrict spraying in areas close to beloved plants, reverting to hand weeding in those instances, but it was more effective than simply weeding and less damaging to the yard than a commercial weed killer.

Paper Wasps

Small, round, grey nests began appearing under the eaves of our house and around some of the outbuildings. Our first line of defense was a $4.27 can of Spectricide Hornet & Wasp Killer ($3.27 at Home Depot). It was relatively cheap, it put 20 feet between me and the nests, and it was incredibly effective at killing wasps.

Unfortunately, it left an oily sheen behind that posed a danger to a nearby colony of wild honeybees. Searching for a safer solution, we found that simple soap and water did the same job, and that a strong spray bottle or hose attachment could give me just as much distance from the wasps. It’s worked on both our house and goat shed so far, and some strategically planted mint (which wasps hate) have kept them away since.

Moss

Living in the Pacific Northwest, moss is just a fact of life. It’s in your sidewalks, its in your lawn and it’s on your roof. While a moss-covered roof under a grey sky may fuel some romantic notions about life in this portion of the country or places like Ireland and Scotland, that moss will turn into a leaking roof if you let it sit around long enough.

During our first year, we bought bags of Rid Moss for the grass ($10.99 at Home Depot) and cans of Moss Out ($18.95) and a pump sprayer for the roof and sidewalk ($49.95). The Rid Moss met with limited success after the first year of spreading, but the Moss-Out was far more effective — clearing out the sidewalk and keeping low roofs on the house and garage moss-free. However, it wasn’t all that great for the higher, more steep-pitched second-story roof of the house. I turned to a garden hose attachment in ensuing years ($15.98), but there are other options.

Fortifying a lawn with lime and fertilizer can restore pH balance enough that moss can be killed with a simple soap-and-water solution. Meanwhile, you can make moss killer at home by mixing either vinegar, dish detergent, or bleach with water.

Thistle

Thistle appears everywhere and is a nasty-prickly weed to get rid of once it’s established. Weed killer was never really an option for us, and spray made of vinegar solution that was so effective for others never seemed to work out as well for us.

However, after crushing apples for cider and feeding the skins to our goats near a particularly thistle-ridden patch of their pen, we found that thistles that came into contact with decaying apple bits withered and never returned. We began using apple cider vinegar ($6.59 per gallon at Safeway) cut with water, and have steadily slain thistle since.

Dandelions

They are everywhere and it’s nearly impossible to kill two acres of them. While we haven’t given up or resorted to Roundup, we’ve performed some triage and addressed them where they’re most visible.

During the first years, we were simply uprooting as many as we could. However, as anyone who’s battled dandelions knows, leaving any part of the root just means you’ll have another dandelion next year.

We were advised that boiling water would kill dandelions, but it turned out to be a less-than-permanent solution. However, this is the one instance where vinegar absolutely works. While you can use undiluted white vinegar or a combination of vinegar and lemon juice, you really need to follow up. Either pull the withered plant and spray again or, if you’d rather leave it, make another pass with the vinegar before rinsing out the area with water.

Moles and Voles

Moles and voles will make your yard a mess of high-piled dirt mounds if left unchecked, but even checking them doesn’t always work. We started out with $20 mole traps, but ended up with a handful of dead moles and no fewer holes. We tried friendlier solutions like vibrating mole spikes $15 and glass bottles and pinwheels stuck in the ground (with wind creating vibration). The moles and voles laughed. We’ve even poured castor oil down holes. Nothing.

With that said, the best way you can save time and money in this instance is with the $20 Victor mole traps we’ve mentioned. All mole-related advice says this — not $50 jugs of castor oil or $15 packs of mole stakes — is the only way to get rid of them permanently. Maybe one year, we will.

Mice and Shrews

We live on a two-acre property surrounded by a neighboring 80-acre farm. We couldn’t eliminate mice or shrews if we tried. However, they were ubiquitous during our first year in the house despite the presence of two barn cats and two indoor cats. While we’d used $16 plug-in sonic deterrents while living in an apartment in Boston, we can’t recommend them for everyone since experience with them varies drastically. Also, our house is a bit bigger than the apartment.

We began using D-Con mouse bait from Home Depot ($11) in our closets, but were warned off of it because of its toxicity to our cats. The same went for the $35 self-contained traps we tried using next. Friends recommended peppermint oil ($10 for 4 ounces) on cotton swabs placed throughout the house, but the answer that worked best was under our nose the entire time: Cats.

When a barn cat passed away, we brought a young tabby into the house who, like the remaining barn cat and one of our existing cats, loved hunting down mice and shaking them to death. His first year in the house, the mouse and shrew body count was roughly eight. The next year, it dropped to four. This year, we’ve had the cats leave us just two, with no signs of permanent mouse activity anywhere in the house.

We adopted our tabby from a local shelter for just $50, which also covered his first vet visit and shots. It costs just slightly more to feed him than it did to feed the existing cats, but the cost was well worth it for both the mousing and the companionship. If you’re allergic to cats, the peppermint oil or sonic deterrents are inexpensive solutions. If not, a compatible, low-maintenance cat is a fine solution.

Related Reading:

The post Cheap DIY Solutions to Spring Yard and Household Hassles appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2GoMOP9

Here’s How Much We Made Selling Our Media Collections to Decluttr


Editor’s note: This post was originally published  in June 2016 and updated by The Penny Hoarder staff in 2018.

In college, I liked to show off my movie collection.

The shelf stood proud in my living room, not far from my TV. It was like a status symbol — in my mind, at least. When people came over, they knew they had options.

Over the years, I’ve amassed about 100 movies and TV shows on DVD and Blu-ray.

Looking back, I’m not sure which status it might have bestowed on me. At what point do you cross the line from hobbyist to hoarder?

But I was proud of it.

A decade later, the collection is less something I brag about and more something I’m forced to deal with every time I move.

So far, it’s been easier to wrap my movie shelf in packing tape and shove the whole thing into a U-Haul than to actually sift through and decide what’s worth keeping.

But I got married recently, so maybe I’m finally feeling like an adult. Maybe.

My wife and I have been listening to The Minimalists podcast, and it’s making us look twice at all the junk we have lying around.

The podcast raises the question, “Does this add value to my life?” If not, why keep it?

These DVDs and Blu-rays used to, in one way, add value to my life. But now, they just collect dust in a cabinet.

But now I’ve found a way to make them literally add value to my life.

The Easiest Way to Sell My Clutter Online

Even though I hate the clutter, I hate the idea of throwing away perfectly good movies way more.

And I don’t want to just dump them at a thrift store. I paid good money for those once!

There are a few ways I could go about selling them.

I could list everything individually on Amazon or Ebay — but for dozens of titles, that sounds like a nightmare.

I’ve seen some people do OK selling CD and DVD collections on eBay. But even those aren’t guaranteed to sell. And if they do, I’d have to deal with shipping and, potentially, an annoying buyer.

Extra closet space doesn’t seem worth the trouble.

Instead, I tried Decluttr.

Decluttr buys your old media and electronics. The service saves you the hassle of managing a listing, handling payment and dealing directly with buyers.

It accepts CDs, DVDs, Blu-rays and video games, plus hardware like cell phones, tablets, game consoles and iPods.

It looked like a simple way to unload some of our junk, so I decided to give it a try.

How Much Can You Make on Decluttr?

I had no idea what to expect going in.

I’m a huge movie fan, and even I haven’t touched most of these DVDs, Blu-rays and Playstation 3 games in years. Would they be worth something to anyone else?

I did some research, and other people who have sold their collections to Decluttr report getting about 50 cents per item.

One user, Gil Flores, sold about 100 DVDs and 75 CDs — he had so many, he said, that he’s not certain of the exact number anymore — and made $275, an average of $1.57 each.

Flores had tons of media just sitting in his garage, because he’s moved everything he wants to watch or listen to over to his digital library. He was ready to clear it out — and why not make some money while you’re at it?

My collection was less impressive, but I had 86 items to sell. It could definitely add up.

I downloaded the Decluttr app and used my phone’s camera to scan the barcode of each item I wanted to sell. The app gives you an instant offer.

For most of my DVDs, the offers were consistent with my research — between 10 cents and $1 each.

A few surprised me.

I got a $2.10 offer for “MacGruber” (the 2010 Will Forte “Saturday Night Live” spinoff movie) on DVD. I can’t believe I just let it sit on the shelf for six years! I only watched it once, but not for lack of trying. My friends just don’t get the humor.

These are some of the best offers I received:

  • Grand Theft Auto: V (PS3) — $6.81
  • “Hot Rod” (Blu-ray) — $4.50
  • “The Lord of the Rings: The Fellowship of the Ring” (DVD) — $1.88
  • Flip Skateboards: Extremely Sorry (DVD) — $1.42 (I was stoked it would pay so much for something so niche!)
  • “Full Metal Jacket” (Blu-ray) — 75 cents
  • “World War Z” (Blu-ray) — 74 cents
  • “National Lampoon’s Christmas Vacation” (DVD) — 50 cents

Altogether, Decluttr offered $54.60 for a combo of 86 titles, including DVDs, Blu-rays and a few PS3 games. Shipping is free, and the company takes everything in one order, up to 500 items.

Not a bad way to make a little extra money.

More recent and easier-to-sell titles command the highest offers. Reddit users discussing the service note offers of up to $3, $4 or $5 for a few titles in each order.

With about standard prices, a few things about Decluttr stood out and made me choose it over similar services.

It Pays Cash, Fast

While you might earn the same amount of money selling to Amazon Trade-In, it only pays in Amazon gift cards.

Decluttr pays in real dollars, via direct deposit, and the payment would hit my bank account the day after the company accepted my order.

Best Prices on Electronics

When we compared offers from several buyback sites, Decluttr came out on top for prices on electronics.

For example, we asked Decluttr for a quote on an iPhone 4, which one of our writers has been thinking about selling. The site quoted her $75.

Compare that with just $31.85 in her pocket through Glyde, which quotes a marketplace range, connects you with a seller, takes a 15% cut and charges $1 to $6 for shipping.

Just for kicks, we looked up what a 32GB iPhone 5 would go for — it could net $120! The same item would only get $45 from competing site Gazelle.

Decluttr also offered me $55 for my 32GB Playstation 3 game console. I recently upgraded to a PS4, so I only use the PS3 for Netflix — might as well get paid for it (and have six months of Netflix free).

Free Shipping

Speaking of shipping your order, did I mention Decluttr covers it for you?

Once you accept the offer, the company emails you an order pack with shipping labels to cover the cost. Just print the labels, pack your items in any box and ship it.

Make it easy and free for yourself, and ask for a box from your local grocery store. They’re usually happy to hand them over — and it’s environmentally-friendly.

Easier Than Selling Direct

I’ve held onto these DVDs for years, partly because selling items directly on Ebay and Craigslist is a ridiculous hassle.

As Flores put it, when he found out he could sell his clutter with a simple app, “A problem became nothing.” The hassle is gone.

My main goal was to get rid of these things. That’s what Decluttr is really good for.

You don’t have to manage several individual listings and wait to catch a buyer’s interest.

You don’t have to deal with sales, payment and shipping for dozens of buyers.

And you don’t get stuck with those duds in your collection absolutely no one wants to buy. Typically, you can unload your most unsellable items through Decluttr.

Practically Guaranteed Sales

It was much easier getting offers for my movies from Decluttr than it would have been to find a seller for each in the market.

Decluttr reports it makes an offer on nearly every item customers scan — over 97% of barcodes are usually accepted.

Who’s looking for a “Stripes” DVD, if I’m being honest with myself? I mean, someone should be. It’s a classic.

Get Cash for Something You’d Otherwise Throw Away

Some 54 bucks might not sound like much, but it’s basically free money for something I would’ve either thrown away, donated or left unused in a box in the closet.

And, Clements pointed out, when you get rid of CDs, you don’t even lose the media. He still has access to any music he wants through iTunes.

Even with a relatively small clearing out like I did, the extra money can add up! And my experience isn’t unusual. According to Decluttr, the average basket price is between $50 and $60.

Plus, Penny Hoarders can enter FREE5 at checkout to get an extra $5 on your trade-in.

Will Decluttr Accept Your Items?

As you might expect, it would be a pretty big risk for Decluttr to guarantee money for your items, sight unseen.

It’ll determine the final amount you receive after inspectors look at the items you ship in.

Almost all items will be accepted, users report. Decluttr boasts a 97% acceptance rate and operates on a “reasons to say yes” strategy when going through your stuff.

Here are a few helpful tips from Decluttr’s terms and conditions:

  • All items must have a barcode.
  • Artwork must be intact and in good shape — no tears, marks or stickers.
  • However, it doesn’t matter if the disc itself or the case is slightly marked.
  • When you ask for quotes for electronics, be clear about their condition.

Decluttr’s site explains what “good,” “poor” and “faulty” condition mean, so make sure you get a quote based on the honest condition of your items.

The company guarantees to pay the first price a customer was offered for any electronics, or the customer can request to have the item(s) sent back for free, no questions asked.

Overall, scanning barcodes into an app and packing the movies into a recycled box is simple enough work to earn $54.

I think we’re really going to enjoy this minimalist thing.

Better get to work on the spare closet next.

Know anyone who needs a surfboard?

Matt Wiley (@wile_style) is an editor at The Penny Hoarder. Find him skateboarding around and frequenting local breweries, dingo in tow.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder https://ift.tt/2Gsbq9L

Got an Old Laptop? These 7 Sites Could Help Turn it into Cash


As I write this article, my beloved 2012 MacBook Air model sits nearby, collecting dust, waiting to be sold. I know I can get at least a few hundred bucks for it; I just need to narrow down my options and figure out which site to sell it on.

Even if your laptop is older than mine, and you’re skeptical about how much you can get for it, it’s worth checking out the following sites — especially the ones that only sell tech products.  They make it convenient to sell and can even give you an estimated selling price.

If you’re ready to get rid of your laptop, here are the best sites to sell your laptop for cash.

1. eBay

In 2017, eBay reached 170 million active users. The online auction site is a great place to sell your laptop, especially since tech is one of its hottest-selling categories.

I’ve used eBay since 2008, and I’m delighted by how much the platform has changed for the better and how it’s become simpler for sellers to list items.

I think eBay’s recommendation tool for setting a price is quite helpful. You can easily post your laptop with eBay’s expert advice on a start price for the auction. It even predicts the likelihood of selling your item at the asking price.

A common misconception from people who aren’t familiar with eBay is that everything must be bought and sold in an auction format. Not true. There is a “Buy it Now” option that also allows buyers to submit a best offer.

eBay fees depend on the item’s final price.

2. Facebook Marketplace

The idea behind Facebook Marketplace is to sell locally on a more trusted platform than sites like Craigslist, where scammers (and flakers) can be prevalent.

Buyers can make payments directly through Facebook or any other form, like PayPal or cash, as long as the seller and buyer agree.

There are no fees to sell on Facebook Marketplace.

3. Amazon

Amazon is the world’s largest internet retailer, so why not take advantage of this marketplace powerhouse to get rid of your laptop?

Selling your used stuff on Amazon is a straightforward process that starts with setting yourself as an Amazon seller. Because the item up for sale is a laptop, chances are, it’s already been sold on Amazon. If that’s the case, you can search Amazon to find the same model and list it with ease.

If your laptop is an obscure make and model that’s not on Amazon, you’ll have to create your own product file.

For individual selling plans, Amazon charges 99 cents per item plus referral fees and variable closing fees.

4. Swappa

Swappa claims an edge over eBay because it does not charge seller fees. It has a robust and easy-to-use platform that gives you an estimated selling price for your laptop.

Swappa’s laptop selling page features images of MacBooks and Chromebooks, making it simple to put together your sale. For my MacBook Air, Swappa estimated I would sell it for $407. Not too shabby for a nearly 6-year-old computer — a grandma in tech years.

You can sell other gadgets, like mobile devices, tablets and smartwatches, too. They don’t allow sellers to list non-functional items.

5. Gazelle

Gazelle is a convenient solution for sellers who are in a hurry. Similar to eBay and Swappa, you can get an estimate, but it also asks you for the laptop’s serial number.

The $216 price estimate Gazelle offered for my MacBook Air was much lower than Swappa. It’s probably less because there are more overhead costs in the advertised conveniences Gazelle promises sellers, including sending me a shipping box and covering the cost to ship my MacBook to the company.

If you don’t want to ship your item, Gazelle also has drop-off kiosks. There were more than 10 kiosks in the San Francisco Area, but the closest one to me was 10 miles away.

6. OfferUp

OfferUp is a free local marketplace app where people sell all kinds of new and used items, from snowboard equipment to tech gadgets.

After downloading, you can snap photos of your laptop directly from the app and post it, along with a brief description.

Similar to Facebook Marketplace, OfferUp is a step above Craigslist and gives you peace of mind because each profile is validated with a state-issued ID and Facebook profile.

7. LetGo

Similar to OfferUp, LetGo is another useful app if you want to sell locally. The company, now worth over a $1 billion, shows you consumerism at its best with tons of items for sale, from clothing to cars, in a Pinterest-like feed.

The app will automatically suggest messages buyers and sellers can send to each other, such as, “Is this item still available?” or “Is the price negotiable?” Buyers and sellers can also use the app to send custom messages to directly to each other.

I’ve used LetGo to buy a used snowboard, and thought the whole process was really simple and the app was easy to use.

If you’re not in a hurry to sell your laptop, sites like OfferUp and LetGo might be the easiest since you don’t have to mess with shipping or fees. If time is of the essence, sites like Amazon, Facebook and Gazelle would be best.

Claire Tak is a content strategist and regular contributor at Well Kept Wallet and when she’s not working, she’s planning for her next trip. You can find her shenanigans on Clairesholiday.com.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder https://ift.tt/2Im7Q1l

السبت، 31 مارس 2018

Organic food sales on the rise in Pa.

Does it feel like the line at your local health food store has gotten a bit longer over the years? Well, you might be right.According to a U.S. Department of Agriculture (USDA) report, Pennsylvanians are buying into the organic food movement and account for nearly 10 percent of organic food sales in the nation.“I can’t say what’s happening in every state of course, but I will say it is true that there is more interest in more organic and more local,” [...]

Source Business - poconorecord.com https://ift.tt/2pUtovn