Thousands of courses for $10 728x90

الأحد، 17 يونيو 2018

Rethinking These Eight ‘Normal’ Behaviors Can Save You More Than $100,000

Growing up, it often felt like other kids were doing fun stuff I wasn’t allowed to – whether they were getting treats from the ice cream truck, the latest pair of Nikes, a ride on the go-karts, or the chance to climb something exciting (and definitely dangerous). Any protests to my parents were, of course, met with the old saying: “If everyone else jumped off a bridge, would you?”

That well-worn adage is still relevant in adulthood, because it’s exactly what many of our peers are doing financially: jumping headlong into a chasm of debt. And even though we know better, it can be really tempting to follow them overboard.

After all, on some level, there’s still some of that adolescent kid inside each of us who’s just desperate to fit in and be normal. But “normal” in America often means “in debt.” The average American carried $6,375 in credit card debt in 2017, and nearly half (43%) of Americans have carried a credit card balance for two years or more — paying a heavy price in interest as a result. Total credit card debt in America now tops $1 trillion, an all-time high. The same can be said for auto loans and student loans, too.

At the same time, a survey by Pew Research found that only 46% of Americans earn as much or more than they spend each month; more than half of us are living beyond our means. That’s one reason the average personal savings rate in the U.S. — the percent of disposable income we save for emergencies, retirement, and other financial goals — was just 2.8% in April. Financial advisors recommend a savings rate of 10% or more for a comfortable retirement, a target we used to hit regularly from the 1950s to the early 1990s.

When the Joneses are paying more in credit card interest than they’re saving toward retirement, keeping up with them is a terrible idea.

This is why there’s so much power in ignoring media influences and what other people are doing and focusing on what’s really important to you. “You absolutely have to stop worrying about what other people think,” Trent said when writing on this topic last month. “If you want to improve your financial state, there’s almost nothing you can do that’s more important than this.”

Instead, Trent continued, “Recenter your life around what you think and what you value, not what the people around you think or value. Live your life and make your financial choices in accordance to what you care about, not what the people around you care about.”

This is easier said than done in the age of Instagram (and it’s one reason avoiding social media can save you money). But we all have finite time, money, and energy, and what we spend those limited resources on should ideally align with our own values, not someone else’s.

Here are eight behaviors that are all but taken for granted in American culture — all of which are potentially expensive. Before you blindly follow the presumed cultural custom, it’s worth at least giving each some thought and deciding whether it’s truly a priority of yours – or just something everyone else seems to be doing.

Some or all of these might be really important to you, things you feel are well worth the money — and that’s fine! At least you’ll have come to that decision mindfully.

But if you’re able to ignore the societal pressures — from ads, media, family, and friends — pushing you toward even one or two of these tropes, you stand to save money. And before too long, the Joneses will be wondering how to keep up with you.

The Nice Car

Unless you live in a city with good public transit, owning a vehicle is just about required in American life. But owning a nice vehicle is not. You certainly need a reliable way to get to work, go grocery shopping, and bring the kids to practice. Anything more than that, though, is a want — a luxury we’ve managed to convince ourselves is more like a need.

The average sales price of a new car was $35,265 in March, according to Kelly Blue Book. To finance that small fortune, the average new car payment hit an all-time high of $523 a month in early 2018, according to Experian, and the average length of a new car loan is 69 months. If sitting in traffic makes you feel trapped, consider that financing the average new car will cost you $17 a day, every day, for nearly six years (even before gas, insurance, and maintenance).

The average new car depreciates 35% in its first three years – which means you should be able to get that $35,000 car or truck for $22,275 slightly used. The average age of a car on the road today is over 11 years old — for every new model, there’s a 20-year-old beater still chugging along — so a three-year-old vehicle still has plenty of life in it.

But even if you want to buy a new car — and believe me, after driving a string of junkers in my 20s, I’m with you — you needn’t be held captive to a crushing car payment. Toyota makes great, reliable cars in the $18,000 to $25,000 range, as do Honda, Ford, and Hyundai. All-wheel drive Subarus like the Outback and Forester — which get great marks from Consumer Reports — start at around $25,000; we bought our smaller Impreza hatchback new for a hair under $20,000 in 2014, and we love it.

And we’re going to drive that thing long after the roughly $300 monthly car payment disappears. Every month you can hang onto a paid-off car amounts to hundreds of dollars in your pocket. Yes, at some point, an old and battered vehicle can cost almost that much in monthly repairs. But until then, try to squeeze every last mile out of it before you give in and buy a replacement.

  • Savings: $12,500

Carrying a Credit Card Balance

As mentioned earlier, 43% of Americans report having a credit card balance they’ve carried for two years or more. (I’ve been there myself, swamped in five-figure credit card debt.) We preach the advantages of credit card rewards, but “revolvers” — cardholders who carry a balance — are one of the reasons credit card companies can afford to pay those lucrative rewards.

The average American consumer has 3.1 credit cards with a total balance of $6,354, plus 2.5 store credit cards, with another $1,841 on those. With the average credit card APR at 16.75% as of early June, according to CreditCards.com, a consumer who takes two years to pay off those balances — without adding to them along the way — would pay $1,505 just in interest.

The solution, of course, is simple in theory, but more difficult in practice: Don’t charge anything you can’t afford to pay off this month. Build up an emergency fund so that, even if you do need to put a car repair or new furnace on credit, you can pay it off that month and avoid interest.

  • Savings: $1,505

Equating Spending With Love

Whether it’s buying Christmas gifts for everyone we know or celebrating anniversaries with an expensive piece of jewelry, it’s easy to feel pressured to spend more money than you can afford on loved ones.

The prime example of this is the pervasive notion that one should spend two (or even three) months’ salary on a diamond engagement ring. It’s one of those long-held rules of thumb you hear tossed around everywhere, like changing your oil every 3,000 miles. But just like the oil change “rule,” it’s utter nonsense, devised by a marketing department — the result of a brilliant mid-century ad campaign designed to sell more diamonds when nobody really needed them.

As Rohin Dhar explains for Priceonomics, Americans buy diamond rings as part of the engagement process because an ad man named Gerold M. Lauck, hired in 1938 by De Beers, told us to — as a status symbol. Within three years, Dhar says, “despite the Great Depression, diamond sales in the US increased 55%. Twenty years later, an entire generation believed that an expensive diamond ring was a necessary step in the marriage process.”

De Beers continued its relentless marketing efforts through the 20th century — all while keeping a stranglehold on the global diamond supply to inflate prices — eventually suggesting that a man should spend a month’s salary on a diamond engagement ring. “It worked so well that De Beers arbitrarily decided to increase the suggestion to two months’ salary,” Dhar writes. “That’s why you think that you need to spend two month’s salary on a ring – because the suppliers of the product said so.”

Dhar continues: “The next time you look at a diamond, consider this. Nearly every American marriage begins with a diamond because a bunch of rich white men in the 1940s convinced everyone that its size determines your self worth. They created this convention – that unless a man purchases (an intrinsically useless) diamond, his life is a failure – while sitting in a room, racking their brains on how to sell diamonds that no one wanted.”

Thankfully, millennials are increasingly immune to this decades-old marketing ploy: About four in 10 older millennials surveyed by The Cashlorette in 2016 said they would spend one month’s salary or less on an engagement ring. And while American newlyweds spent an average of $5,764 on an engagement ring in 2017, that’s actually down from $6,163 the year before.

Still, even five grand — one month’s salary for someone earning $60,000 a year — is an awful lot of money. And that’s just one ring. For some couples, it doesn’t stop after courtship: birthdays, holidays, and anniversaries can escalate into an arms race of lavishness. Who can prove their love with the more extravagant gift?

It’s not just romantic relationships, either. We love our kids, families, and friends so much that we spend close to $1,000 each year on holiday gifts. But the truth is, while throwing money at the people we love feels good, what they usually want most of all is just our time and attention.

All that’s to say: An engagement ring – or any gift – is merely a symbol of your love. It’s not the love itself. And there are a lot of less expensive, more heartfelt ways to express that love. (For example, here are some ideas for more affordable engagement rings, all under $2,000.)

  • Savings: $3,000 or more

The Big Wedding

Talk about outside pressure: Planning a wedding can be a stressful endeavor, fraught with family politics and heightened emotions. Plus, from photography to flowers, everything costs more once the word “wedding” is tacked on.

American couples spent an average of $33,391 on their weddings in 2017, according to The Knot, not including the honeymoon. And that’s actually down slightly from years past, as millennials embrace less formal (and less expensive) reception settings. That’s a huge chunk of change.

Now, I’m not suggesting anything drastic like eloping (though it would save you a ton of money) or disinviting Aunt Cheryl. Having all your friends and family in one place to celebrate your love story is one of the greatest feelings in the world. It deserves a big party.

But that feeling doesn’t have to cost 33 grand. There are plenty of ways to trim the cost of a wedding while still ensuring everyone has a great time. In fact, our own Drew Housman and his wife were able to throw a 140-person wedding for under $3,000 last year.

You’ll be doing your friends a favor, too: Between gifts, bridal party duties, and bachelor and bachelorette parties, young adults can also expect to shell out up to $20,000 or more attending their friends’ weddings. There’s no shame in toning things down to focus on the most important elements: friends, family, food, and the love of your life.

  • Savings: $10,000 or more

The Big House

Homeownership is a big part of the American dream, and I’m not about to advocate against it. Certainly, owning a home isn’t for everyone — particularly if you’re not prepared to stay at one address for at least five years. But the fact remains that homeownership has been one of the most reliable wealth builders for America’s middle class.

However, there’s a pervasive notion — especially in the low-interest rate environment of the past decade — that you should “buy as much home as you can afford.” TV shows that glamorize and oversimplify the home buying and remodeling processes have created what realtors call an “HGTV effect,” where buyers’ expectations are out of whack with their budgets. And homeowners who have managed to build up equity are constantly tempted to cash it in to match the remodels on Fixer Upper.

A better idea? Buy only as much home as you need and can reasonably afford – or even less. A larger, more expensive home not only costs more upfront — it costs more to heat and cool. It costs more in property taxes, and homeowners insurance. It costs more to furnish and decorate additional rooms and living space – and that extra space encourages the mindless accumulation of “stuff.” And while trendy finishes like quartz counters are no doubt appealing, don’t overlook a modest home just because it’s not your dream house. You can always upgrade later as your budget permits.

The median list price of a U.S. home was $146 per square foot in May, according to Zillow. So scaling back from a 2,000-square-foot home to 1,600 square feet could save you $58,4000, all else being equal. And that’s just on the purchase price; everything from insurance to maintenance to mortgage interest to HOA fees (typically based on square footage) will likely be lower, too.

  • Savings: $58,400 or more

Eating Out

There’s no doubt: Going out to eat or ordering take-out is delicious and convenient. And it’s also the new normal in America, where, in 2016, we spent more on restaurants than on groceries for the first time ever.

Zagat found that Americans eat out an average of 5.9 times a week — 4.9 of which are for lunch or dinner. The same survey found that diners pay an average of $36 per person for dinner out.

You can see where this is going: If that average diner eats out four times a week instead of five, skipping just one $36 dinner per week, that’s $1,872 in a year.

Preparing meals at home can seem challenging at first, but it gets easier (and even fun) with practice. It can also be a whole lot healthier for you, which can lower your long-term medical costs.

If you need a little motivation, here are some tricks to temper your urge to eat out — and some tips to get you started in the kitchen.

  • Savings: $1,872 a year

The Upgrade Cycle

Better than three quarters of Americans now own a smartphone, and we tend to hang onto them for an average of 22.7 months — not quite two years. That’s actually longer than in years past, but most phones can last a lot longer than that.

I’m not saying you have to go through life with a flip phone — although some people do, and they seem to like the freedom of being untethered. But as with car payments, every additional month or year you’re able to squeeze out of your old smartphone is one in which you can put that money into savings instead. With the sales price of a new smartphone averaging $363 worldwide, and a new iPhone, Galaxy, or Pixel topping $800, the savings can add up.

  • Savings: $363 or more

Assuming You Need to Go to College

Like homeownership, this is another institution I’m hesitant to advocate against. A college degree is still worth close to a million dollars in additional lifetime wages, making it a great investment for a lot of people.

However, that’s only if you get a degree. Students who leave school without graduating fare no better than those with just a high-school diploma — and often end up far worse off, bogged down by crushing student loans with nothing to show for them.

Seven out of 10 college students now take out loans, and they graduate with an average debt of $37,172. If you’re committed to pursuing a professional career that requires a bachelor’s degree — and a lot of good jobs do — that’s a pretty good investment.

But don’t just assume you need to go to college because that’s what you’ve heard you should do, or because it’s what most of your classmates are doing. And parents, don’t assume that your kid needs a college degree to be successful. There are many high-paying careers that require just a certificate program or associate’s degree; others even start off with apprenticeships that pay you to learn on the job.

  • Savings: $37,172 plus interest

Summing Up

I won’t lie, a lot of these are nice things to have in your life – that’s why people pay for them even if they can’t afford them. Just be mindful about your motivations: Are you buying a bigger house to impress other people, or because that extra space and expense is truly in service of your goals and your values?

If you want to be a normal American, then by all means, go along for the ride. Just remember that being normal in this country is an increasingly precarious proposition.

Related Articles: 

The post Rethinking These Eight ‘Normal’ Behaviors Can Save You More Than $100,000 appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2JY8kPW

This Woman Taught Herself to Code — And Earned $137,000 in One Year

السبت، 16 يونيو 2018

A Look at My Eleven Frugal Hobbies and Whether They’re a Good Fit for You

One of my most recent interests has been time tracking. I’ve been enjoying tracking my time use as accurately as possible using Toggl and looking at the data that’s produced from doing that over a period of time.

One of the big things I’ve discovered in this process is that I actually have a fair number of hobbies that I devote time to, but they tend to overlap with other areas of responsibility in my life – parental, marital, social, familial, and so on. I started figuring out ways to label various time uses so that they’d show up both as hobby time and as “family time” or “social time” because I really wanted to see how much time I devoted to various hobbies.

Last month, I took a look at what hobbies of mine I spent at least one hour on during the month, and I came up with a list of eleven of them (I combined a few similar time uses into one single group in a few cases). Every single one of them is what I would consider a frugal hobby.

A few days ago, I posted an article entitled The Happy Life on the Path to Your Financial Goals, and one of the big suggestions I made in that article is to find free and low cost things you enjoy doing and dive deep into them if you find them enjoyable.

I thought it might be sensible for me to share a brief description of my eleven frugal hobbies and how I practice them inexpensively. I’ve written up a few of these in detail in the past, but this is intended to be more of a smorgasbord of ideas where you can choose which ones you want to try.

(Note: there are a few practices I do every day like meditation and journaling that could probably count as a hobby, but I chose to exclude them to focus primarily on recreational activities.)

Hiking

By hiking, I simply mean going into natural areas on foot and exploring, whether it’s walking along a quarter mile nature trail in a state park or backpacking in the backcountry of a national park and anything in between. If you’re on foot exploring a natural area, I consider it “hiking.”

This is a wonderful and peaceful hobby that has little cost associated with it. You just need a nice park or nature preserve near you that offers areas for nature walking or hiking.

Hiking provides fresh air and sunshine, exercise at any level of intensity that you desire, and a great way to escape the bustle of everyday life and simply appreciate nature. There’s also a subtle but notable psychological benefit from spending time in nature, too. Hiking provides all of these things.

Low-intensity hiking can be done with virtually no expense using the shoes and clothing you already have. If you get into it and ramp up in intensity, you’ll need a bit of equipment, but nothing too egregious and it’s all stuff you can continuously use. I have a nice pair of hiking shoes and a backpack which were more than enough to tackle several day-long hikes at Yellowstone.

A while back, I wrote a beginner’s guide to hiking and nature walking at minimal cost if you want more information.

Bodyweight Exercises

Bodyweight exercise basically includes any form of strength-building exercise that doesn’t require additional equipment and thus relies on the weight of your own body for resistance. Thus, bodyweight exercise includes things like push-ups, sit-ups, squats, planks, and so forth. There’s an infinite variety of these exercises out there, so you can try lots of them and find ones that really work for you and achieve what you want to achieve.

My main interest in terms of bodyweight exercise is to mostly improve my core strength and balance. I tend to mix up things like planks with things like balancing on one foot with my leg extended, something I’ll get back to in a bit. I also really enjoy stretching and increasing my flexibility, so I also do some yoga (which is definitely a form of bodyweight exercise that targets the core, improves flexibility, and improves balance). I also enjoy rucking, which I tend to think of as more of a bodyweight exercise than anything else.

I try to put aside at least fifteen minutes a day for stretching and some form of bodyweight exercise. I usually do the daily workout from Darebee (which is free) or one of my bookmarked favorite routines from them, such as the Justice Served workout. Again, the goal for me is to improve my balance and core strength and (secondarily) work other muscles and improve cardio without feeling miserable, and this does the trick.

The nice thing about bodyweight exercises is that there’s no cost associated with them. You can just do them at home, any time you want, at no cost whatsoever. Plus, time spent exercising is going to reduce long term health care costs and extend your life, so it’s time spent likely saving money as well as improving quality of life. Not only that, I usually feel great after doing it.

Taekwondo

This is definitely an activity that has a cost associated with it, but I consider an activity to be “low cost” when the out of pocket cost for me is less than a dollar per hour that I spend on it, and taekwondo definitely meets that target.

I participate in taekwondo because it’s an easily available (meaning there’s a class fairly close to where I live, close enough to walk there if I’m okay with a long walk) exercise class with a focus on self improvement, balance, core strength, and technique. I get a killer workout whenever I go to one of the classes – I usually leave with my shirt soaked with sweat.

The cost of the classes themselves exceed that $1 per hour metric that I note above, but the classes basically come with “homework” – there’s almost always something you can be working on at home, whether it’s working on exercises to get your kicks higher, mastering certain moves through repetition, or something akin to that. I spend some time each day working on taekwondo exercises, particularly on days without classes, and adding up all of the invested time pushes the cost well below $1 per hour.

Most of what I said about bodyweight exercises holds true here. It’s a great way to get a workout, which is good for your current quality of life and for reducing long term health care costs. There is a cost associated with taking martial arts classes, but if you actually follow the suggested exercises, the cost per hour of the classes (especially if your school allows for unlimited class attendance) ends up being quite low. See if there are any martial arts classes in your area for adults and sign up.

Check with your local parks and recreation department and see if they offer any inexpensive martial arts classes.

Making Fermented and Pickled Foods

One of my favorite activities is making fermented and pickled foods in my kitchen. Rare is the day when there’s not something fermenting or pickling somewhere in our home, whether it’s cabbage turning into sauerkraut, pickled eggs, preserved lemons, pickled cucumbers, kimchi, pickled garlic, and even drinks like kombucha or kefir.

The process is really easy and requires minimal equipment. I typically use a gallon jar with a special lid that has a small hole with a rubber gasket in it, into which I put a small air lock. The total cost of this lid and the bubbler was about $5, and I’ve used it on dozens and dozens of batches of food. I also have a few glass weights that I picked up somewhere years ago that are useful for weighting down the food and keeping it below the level of the brine.

Mostly, I just cut up a bunch of vegetables or other items that I want to ferment or pickle, add an appropriate amount of salt and, if needed, water, and pack everything down in the jar with the weights on top, then I simply seal it up and wait until the air lock stops bubbling. This general procedure has some variations depending on what exactly I’m trying to do, of course, but that’s the general framework. When a batch of food is finished, I usually keep a container of it in the fridge and I often give some of the product away to friends and family.

It’s a pretty low cost hobby, considering that the ingredients are almost always less expensive on the store shelf than the finished product. I can often buy three heads of cabbage for less than a dollar and turn it into many pounds of sauerkraut by just adding salt and a little water, for example.

In fact, if you like sauerkraut, it’s incredibly easy to make at home and it’s incredibly inexpensive, too, because cabbage is always pretty cheap. This is a great beginner’s guide for making sauerkraut.

Making Homemade Beer/Cider

This is definitely a subset of fermenting foods, but in this case my approach is a little different (and the whole process is a little more expensive). Essentially, all you’re doing is adding yeast to a sweet liquid. The yeast then eats the sugar and converts it to alcohol. When this process is finished up, you move that liquid into individual bottles for long term storage. That’s pretty much it.

Having said that, there are some startup costs. You do need some kind of large vessel to actually make the beer or cider in – a five gallon food grade bucket is great to start with and can be found pretty cheap. You’ll also need a pretty good sized stock pot to actually cook things in and some empty bottles, and each batch of beer or cider that you make will require some basic ingredients (sugar and things to add flavor). This hobby can definitely turn into a “rabbit hole” of expenses if you’re not careful, but if you stick with basic equipment, you’re fine.

This is a great hobby to get into if you enjoy drinking craft beers or cider. You can save a little money over the normal cost of craft beer by home brewing if you keep up with the hobby, but this isn’t a “free” hobby.

If you want to get started, my suggestion is to start saving old bottles until you have several empty six packs, then stop by a local homebrew supply store and get a beginner’s kit with a capper and some caps. The expense will be a little stiff at first, but you’ll refill all of those empty bottles with your product and you’ll have some fun along the way.

Reading

Reading has been a major part of my life since I was a young child, and even today I put time aside each day to sit down with a book of interest and read a chapter or two. Most years, I finish somewhere between 50 and 100 books.

Reading is one of those hobbies that can range from absolutely free (if you rely on your local library for your books) to a fairly expensive hobby (if you buy every book new and buy more books than you’ll actually read, though this tends to segue into collecting books more than reading). If you apply some basic smart principles to the hobby, such as sticking heavily with what’s available at the library and not buying books unless there’s an extreme sale or you’re absolute sure you’re going to read the book immediately, it can be a very inexpensive hobby, since most books take several hours (at least) to read.

A good way to begin with this hobby is to simply go to the library with a topic in mind (if you want to read nonfiction) or a genre in mind (if you want to read fiction) and explore those sections of the library until you find something that looks really interesting. Grab it off the shelf, take it home with you, and dive in. For me, I find it most effective to read fiction when I have a large block of time and can get absorbed into the story, whereas I tend to read nonfiction in little bits throughout the day and let my mind ruminate on what I just read.

Playing Board Games

Once a week or so, I go to a local community board game night where two dozen people or so meet up to play board games. The group is almost entirely professional adults, with a few college aged people and a couple older children accompanied by their parents. People bring whatever games they happen to have and then people just divide up into groups to play them.

In addition to that, Sarah and I host a board game day at our house about once a month for several of our adult friends. We get together to have a potluck dinner and play games until late in the night.

Board gaming is another hobby that can be expensive if you move away from actually playing games and focus more on collecting them, but if you keep the focus on simply playing games rather than buying them, it’s a pretty inexpensive hobby all around. The best strategy for keeping it inexpensive is to get involved with a local community board game night (check Meetup, as they’re often listed there) and just show up and play. If you eventually do pick up a game or two, bring it along with you and play it with friends outside of that group as well.

Playing Digital Games

I enjoy playing deep strategy computer games and puzzle games; I’m much less interested in games that require lightning reflexes. I like games that force me to think while I’m playing and make hard choices that run the possibility of backfiring on me later.

I mostly play games like Civilization (which is basically a slow strategic reenactment of the history of human civilization) and Stellaris (also a slow strategic game, but focusing on humankind spreading across the galaxy) and Factorio (a logistics game where you try to run an ever-more-complex factory) and SpaceChem (a puzzle game where you try to build a molecule factory).

Those games individually aren’t free – some of them are actually a bit pricy. However, I tend to research games obsessively when I’m considering buying one and I wait for sales on very specific titles before buying. I usually do this by using Steam and waiting around for their semi-regular sales to see if any of the titles I’ve looked into are on sale.

My goal with such games is to get the money I’ve invested in them below $0.50 per hour of play. I don’t buy a game unless I’m quite confident that I’ll be able to reach that level.

I tend to play such games in bite-sized bursts. Most of them are turn based (imagine a board game with an extremely large board and lots and lots of choices to make) and I’ll occasionally load up a game and take a few turns. When I was younger, I used to play in much longer sessions, but now I’d rather take two or three turns and go on a walk.

Solving Combination Puzzles

A combination puzzle is perhaps best illustrated by an example – the Rubik’s Cube is a perfect example of a combination puzzle. They’re usually handheld puzzles that you rotate in some way in order to solve them and typically take a fair amount of spatial reasoning to solve them.

I greatly enjoy learning how to solve such puzzles. At first, I’ll tackle them completely on my own, trying to figure out how to solve them without any assistance. If I struggle to the point of frustration, I’ll go look for help on the section I’m struggling with. Eventually, I’ll solve it, and then I’ll mix it up again and solve it again. I try to get to a point where I can do it fairly quickly without long pauses, and then I’ll move onto another puzzle (there are many in the genre, often appearing to be more complicated versions of a Rubik’s Cube using different shapes and more faces). It’s a nice hobby as well because you can pick up a puzzle and work on it for just a few moments here and there, or you can sit down and really try to master one of them over a longer period of time.

I find this to be a great mental workout, plus learning the skill of solving such a puzzle is a neat party trick. It’s also been a great tool for bonding with my oldest son, who’s into speed cubing (basically solving some of the most common puzzles, like the Rubik’s Cube, as fast as possible). As you might guess, this hobby is in part fueled by family bonding, as most of our family can now solve the 3x3x3 Rubik’s Cube and a few other similar puzzles fairly quickly.

It’s a pretty inexpensive hobby, too. You can actually buy off-brand puzzles very inexpensively online (they actually tend to work better than the name-brand Rubik’s puzzles and are less expensive, too) and they’ll provide many hours of entertainment if you enjoy these types of puzzles. For example, my son received this set of four puzzles for his birthday at a cost of less than $20 and he has invested countless hours into solving each one – in fact, he’s still working on the 5x5x5 puzzle. All you need is the puzzle itself and perhaps a few easily-found online tutorials.

Studying a New Subject

One of my favorite activities is to simply bury myself in learning about a new topic, usually starting with a general Wikipedia entry or a free online introductory class on the topic. I’ll usually pull out a cheap notebook and pen and start going through the materials online, taking notes as I go.

For example, let’s say I wanted to learn more about philosophy. One great place to start would be Wikipedia’s general entry on philosophy, then dive into each of the sub-pages listed on the menu over on the right, which will give me a good background and avenues to dive further into specific areas that interest me. Another approach might be to listen to the lectures of a free online class, like this introduction to philosophy course from MIT for which the full lectures are online.

Again, as with many of the other hobbies listed here, this is a hobby that can be broken down into bite-sized chunks. I actually like to use that approach because it gives me time to think about what I’ve just read or listened to. I’ll usually read a section of a Wikipedia entry or listen to about a fourth or a fifth of a lecture, write down the big ideas from that, and then go do something else for a while, letting those ideas percolate in my head.

This is one of the most beautiful things about the internet – it provides almost endless opportunities to learn, absolutely for free. The only cost I’ve incurred with this approach to self-guided learning is that I’ve blown through a lot of cheap notebooks and pens, but I can usually get quite a few hours out of both the notebook and the pen, meaning that the cost per hour for this is on the order of pennies.

I suggest doing the same for your topic of interest. Just visit Wikipedia and look up the general page on that topic. Go through it slowly and take notes as you go, and stop regularly so you can process what you’re learning as you do other things. If you prefer to listen, see if you can find an online course related to that topic with free audio or video lectures.

Gardening

The final hobby on this list is one that tends to eat up a lot of time in the spring, a little time in the summer and fall, and zero time in the winter. We simply have a couple of small vegetable and flower patches on our property that we plant in the spring, maintain in the summer, and harvest and winterize in the fall.

It’s a peaceful and pretty low cost activity that gets us outside during the most beautiful seasons of the year (fall and spring) and puts a lot of fresh vegetables on our kitchen table while also making our property look nice. It gives us a chance to work the earth and get our hands down in the soil. Usually, we garden as a family, with several of us out there weeding and turning the soil over and planting all at once.

It’s an inexpensive hobby to get started. You can get started with any available area of land or a large pot with some soil in it, along with a few tools and some seeds. Prepare to do a bit of homework, though, as you figure out how to fertilize the soil (I like to use compost and “compost juice”) and how and when to plant. The internet is a wonderful resource for gardening questions, however.

Once you have a good system in place, the costs are pretty minimal and you’ll find yourself with an abundance of vegetables and/or flowers throughout the seasons.

Final Thoughts

This post isn’t intended to be a checklist of hobbies that everyone should try. Instead, I recommend a “pick and choose” approach – read through the list, find one or two that might be of interest to you, and dive into them. Most of these hobbies are very low cost, and every single one of them has provided me with many hours of joy over the years.

Good luck!

The post A Look at My Eleven Frugal Hobbies and Whether They’re a Good Fit for You appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2HVlGay

This is Why SPF 100 Sunscreen Isn’t Worth It (and What to Buy Instead)

الجمعة، 15 يونيو 2018

Put Down the Cellphone, Keep Your Eyes on the Road to Win This $10K Contest


Being a safe driver pays off. You can avoid costly auto repairs and medical bills. You may be able to get a discount on your auto insurance for a good driving record. But wouldn’t winning $10,000 for your safe driving habits be an even better reward?

Right now, drivers in San Antonio, Texas, have the chance to cash in on their impeccable driving skills. USAA, a national insurance company that serves military members and their families, recently launched a safe driver contest in support of the city’s efforts to eliminate road fatalities.

To participate, drivers living in the San Antonio area must download a free app (available on the App Store or Google Play) on their smartphones. The app detects driving habits when the phone is in the car and turned on. Contest participants must be at least 18 years old but do not need to be insured through USAA, which is headquartered in the Texas city.

Drivers don’t interact with the app while driving. It just runs in the background, collecting data about speed, acceleration, braking, turning corners and phone distraction. The app scores drivers at the end of their trips.

San Antonio’s Safest Driver Contest started June 11 and runs until Sept. 3. Grand prizes of $10,000 will be given to the highest-scored driver in each of three categories: overall safest driver, safest military driver and least distracted driver. Drivers must enter the contest by July 9 to be eligible for the grand prize.

Every two weeks during the contest period, USAA will also give out nine $500 prizes — to the three highest-scored drivers in each of the three categories. Drivers must have made at least 10 trips within an entry period to be in the running for any prize.

Even those who aren’t stellar drivers have a chance to win some cash. Every driver who downloads the app will be entered into a random drawing to win a grand prize of $2,000 or one of 18 prizes of $150 each. Three people will be selected to win $150 every two weeks during the 12-week contest period.

San Antonio residents can also submit one write-in sweepstakes entry without downloading the safe-driving app. See the official rules and frequently asked questions for more details.

Nicole Dow is a staff writer at The Penny Hoarder.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder https://ift.tt/2JNf8wh

Do You Sell Items on Etsy? Expect a Transaction Fee Hike Starting in July


Etsy sellers can expect change, and as a result, they’ll find less of it in their pocket.

The e-commerce site through which people can sell handcrafted merchandise announced on Thursday that it's raising the seller transaction fee to support new initiatives to grow the platform.

As of July 16, nearly 2 million Etsy sellers will see transaction fees increase from 3.5% to 5%; the fee will also apply to shipping costs. For example, an item sold for $30 will have a transaction fee of $1.65 plus a $3 shipping fee.  

Etsy says that the money generated from the fee increase will help fund its efforts to attract more buyers to the website and build new suites of tools to help sellers manage their businesses. You can find out more about the new seller services here.

As of March 31, more than 34 million shoppers used Etsy to purchase artisan items during the previous year. The company spent $78 million on marketing in 2017 and says it plans to spend more than $110 million this year.

Matt Reinstetle is a staff writer at The Penny Hoarder. His buddy once used Etsy to find him a Christmas gift — a 3-D-printed replica of Kylo Ren’s Lightsaber from “Star Wars.”

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder https://ift.tt/2yf2nJF

Forget the Piggy Bank: Here Are 6 Better Ways to Save for Your Kid’s Future


File this under “Things You Already Know” — kids are expensive.

The cost of raising a child from birth through age 17 is roughly $233,610. And this figure doesn’t even factor in a college education.

Four years at a private university will cost a whopping $303,000 18 years from now, according to CNBC. (Before you pick your jaw up off the floor, know that a public university won’t save you all that much money: In 2036, your child will need roughly $184,000 to collect their diploma.)

These numbers can be downright scary. But you have options to start saving for your child’s future today, no matter what your budget.

Ways to Save For Your Kids

Money Girl host Laura Adams explores several different opportunities in “6 Ways to Save and Invest Money for Kids.” In the blog post and accompanying podcast, Adams outlines six ways to save money, whether you want to open a college savings plan or start a rainy-day fund.

1. 529 College Savings Plans

If you think higher education is in your child’s future, consider a 529 savings plan. You make contributions and invest the money with this plan, and funds can be used at any accredited school in the U.S. When the time comes to pay for college-related expenses such as tuition, book, and room and board, you can withdraw this money tax-free.

Anyone can use a 529 savings plan (no annual income restrictions!) and you can change the 529 beneficiary to another family member without incurring a tax penalty.

2. 529 Prepaid Tuition Plan

Want to save money for your child’s college education without the risk of investing? Then a 529 prepaid tuition plan might be for you.

With this plan, you can lock in future tuition costs at today’s rate to save money. But, do your homework: Not every state offers these plans, and if your child chooses to attend an out-of-state school, you’ll pay the cost difference out of pocket.

3. Roth IRA

Yep, you can open a Roth IRA in your child’s name. However, they must have an earned income (part-time jobs count), so this option would most likely apply to teenagers.

With this account, they’ll get tax-free money when they retire. And unlike other retirement accounts, these funds can be used for qualified college expenses. While your child will have to pay taxes on the earnings, they won’t face an early withdrawal penalty.

4. UGMA/UTMA Account

If you want to invest in your kid’s future without choosing an account that’s for education expenses only, look into a UGMA (Uniform Gifts to Minors Act) or UTMA (Uniform Transfers to Minors Act). Parents can set up a custodial account and then make withdrawals to cover child-related expenses. Once the child is of legal age, the assets are transferred to their name.

5. Brokerage Account

Looking for more options that aren’t exclusive to education? You can invest in a taxable brokerage account. Choose from a variety of investments and make withdrawals at any time. But take note: The value has to be included in financial aid calculations.

6. Savings Account

Don’t forget the old standby: a traditional savings account. While interest rates are low and whatever interest you earn is taxed as income, an FDIC-insured bank savings account is — in the words of Adams — “one of the safest places you can squirrel away money for a child’s future.”

Listen to the Money Girl podcast episode for Adams’ full breakdown of these six ways to save money for your child, including the pros and cons of each method.

Kathleen Garvin is an editor for The Penny Hoarder. She just finished paying off her student loans and is worried about her own savings account at the moment, OK? You can follow her on Twitter @itskgarvin.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder https://ift.tt/2JVlVHG

Warby Parker Is Hiring a Part-Time Rep to Help Customers Via Email


How should I frame this?

Designer eyewear retailer Warby Parker is looking for a part-time, work-from-home customer experience advisor, and perks include new spectacles.

You’ll need to be available to work at least 20 hours per week, including weekends and holidays. The role requires you to respond to customers via email, with the opportunity to get promoted to live chats.

The company has a three-week, on-site training program in Nashville, Tennessee, and you must live in the area to apply.

Not the job for you? Then feast your eyes on our Jobs page on Facebook. We post new opportunities there all the time.

Work-From-Home Customer Experience Advisor at Warby Parker

Responsibilities include:

  • Assisting customers via email with styling advice and order completion
  • Using the internal management system to process sales orders
  • Directing customer inquiries to appropriate departments

Applicants for this position must have:

  • Creative problem-solving abilities
  • Expert-level online communication skills
  • Detail-oriented organization prowess

Benefits include:

  • Retirement plan with a company match
  • Annual eye exam and free eyewear (plus discounts for friends and family)

Apply here for the work-from-home customer experience advisor job at Warby Parker.

Tiffany Wendeln Connors is a staff writer at The Penny Hoarder.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder https://ift.tt/2l9SB20

How to Track Your Leads with UTM Parameters

No marketing strategy is complete without an effective lead generation strategy.

Those of you who are making a conscious effort to generate new leads are on the right track so far. But where are your leads coming from?

When you’re running multiple campaigns, how are you able to identify the source of your new leads? If you can’t answer these questions, read this guide.

UTM parameters will tell you exactly where the traffic from your digital marketing campaigns is coming from.

I’ve advised some marketers who haven’t implemented this strategy because they think it’s unnecessary. They see their site traffic increase, so they automatically assume this is the result of their lead generation campaigns.

While this may be true, you can’t make assumptions. The only way to know for sure is by putting your theory to the test.

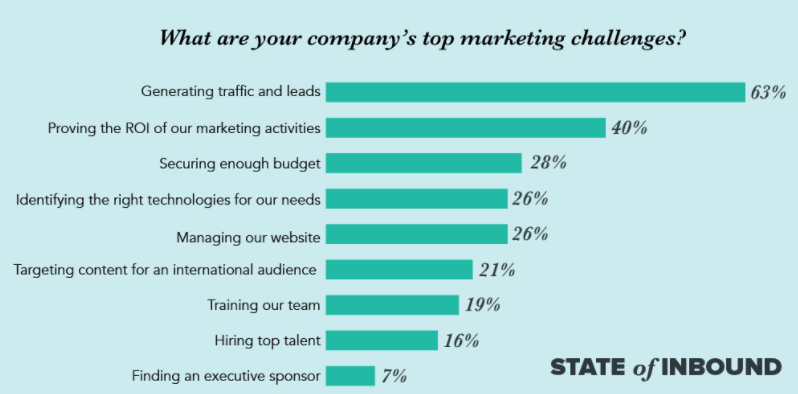
According to the HubSpot’s 2018 State of Inbound Marketing report, getting leads and traffic are the top challenges faced by marketers.

image1 1

It’s obvious the majority of businesses can benefit from a strategy that helps improve their lead generation efforts.

Once you’re able to pinpoint your most effective marketing campaign, you can focus the majority of your efforts on that strategy.

On the flip side, you may also realize some of your lead generation strategies aren’t working at all. So you can stop wasting money on those by eliminating them completely, or you can decide to rework them with an improved approach.

Ultimately, UTM parameters will make your marketing strategy more efficient.

In this guide, I’ll show you exactly how you can track leads with UTM parameters. I’ll also give you some examples of ways you can implement these tactics.

Setting up your UTM parameters

Before we go any further, it’s time to show you how to set up a UTM parameter for your marketing campaigns.

To those of you who are unfamiliar with this, it may sound a little bit intimidating. But don’t worry, you’ll soon realize this is actually fairly easy.

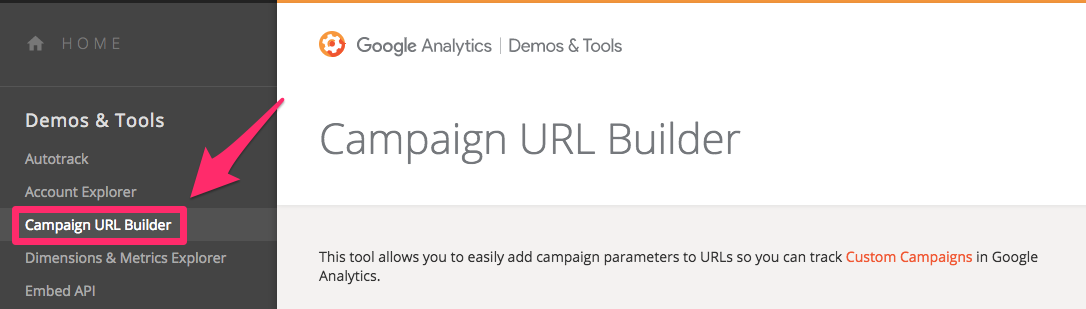
Just navigate to the “Campaign URL Builder” option from your Google Analytics menu.

image3 1

From here, you’ll see simple instructions for creating a custom link to track your leads.

If you’ve only got a handful of marketing campaigns and you’re distributing them on a couple of channels, your custom URLs won’t be too complex.

But eventually, you should diversify your marketing efforts across as many channels as possible. That’s why it’s important for your UTM parameters to be very specific. It can help you stay organized in the long run.

Google Analytics has five potential parameters that you can add to each customized URL:

  • campaign source
  • campaign medium
  • campaign name
  • campaign term
  • campaign content

The source is used to identify exactly where the link is going to be embedded. This could be something like an advertiser, another website, or publication.

Email newsletters, banners, or CPC campaigns would all fall under the campaign medium category.

The campaign name is where you can be specific with your promotion. You could enter terms related to a slogan, promotional code, or something like “summer sale” to specify.

Campaign terms are for those of you who are paying for keywords. To keep track of any paid keyword promotions, you’ll want to include those words in this field.

Your campaign content parameter will help you separate similar links within the same promotion. For example, let’s say you have multiple CTA buttons within the same newsletter. You’d use this parameter to differentiate among them.

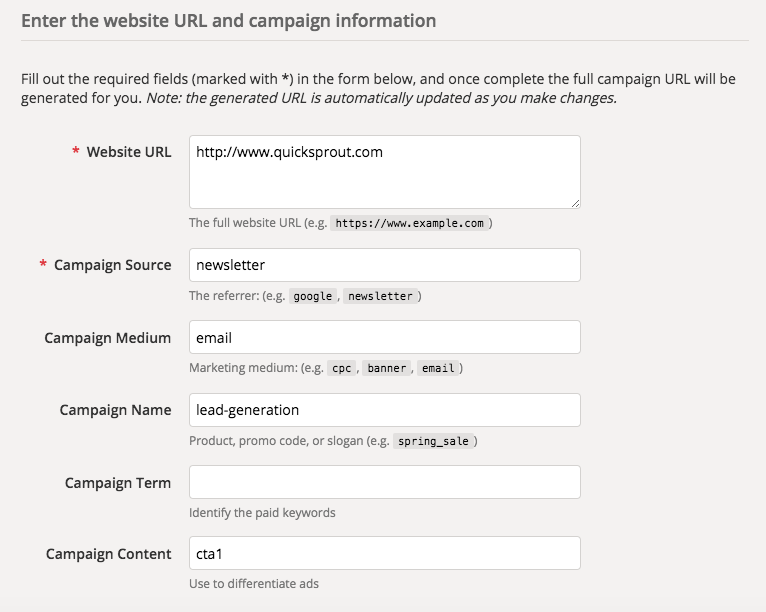
Here’s a look at an example I made to show you how this would look:

image5 1

I’m obviously using Quick Sprout as the example here, as you can see in the website URL field.

Based on my parameters, this link is going to be from an email newsletter about one of my lead generation campaigns. This link is specifically for the first CTA button in case I’m planning to have more than one in the same newsletter.

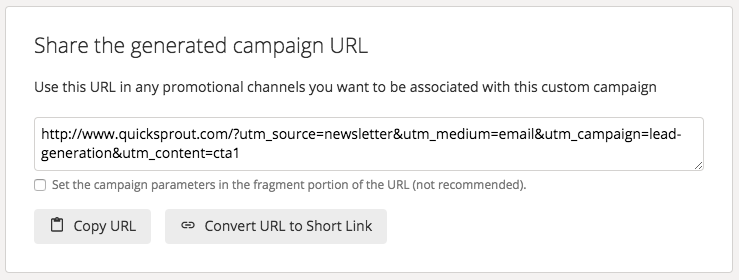
Once you fill out the fields, the Google Analytics tool will automatically generate a custom link for you. Here’s what the link looks like from the above example:

image2 1

As you can see, all of those terms are included in the link.

Once your link is live, all you need to do is copy and paste it for use in that specific campaign. Google Analytics will track all the data from each link.

Now, you’ll be able to see exactly how successful all of your various lead gen ads are.

Best practices for naming UTM parameters

Now that you know how to set up your parameters, I want to give you a little bit more insight on naming them.

Sure, no matter what you put in the term fields, Google Analytics will still generate a working link to track your leads. But there are definitely ways to make things easier for yourself to avoid confusion.

For starters, your UTM parameters should be as simple as possible.

Simplicity is a common theme in marketing. Websites with simple designs have higher conversion rates.

While the complexity of your UTM parameters may not impact conversions, it will certainly have an effect on your organization. It’s easier to keep track of everything if you have fewer terms.

It’s also essential that you stay consistent with your capitalization. The easiest way to do this is by using all lowercase letters. That’s because this tool is case sensitive.

For example, if you have one link with “utm_source=newsletter” and another that’s written as “utm_source=Newsletter”, Google Analytics will track them as different sources.

I know some of you may be thinking you would remember which words to capitalize and which ones not to. So what’s the issue?

We’re humans. Any time you do something manually, you risk human error. That’s why it’s in your best interest to stick with all lowercase letters like I did in the example we saw earlier.

Use hyphens.

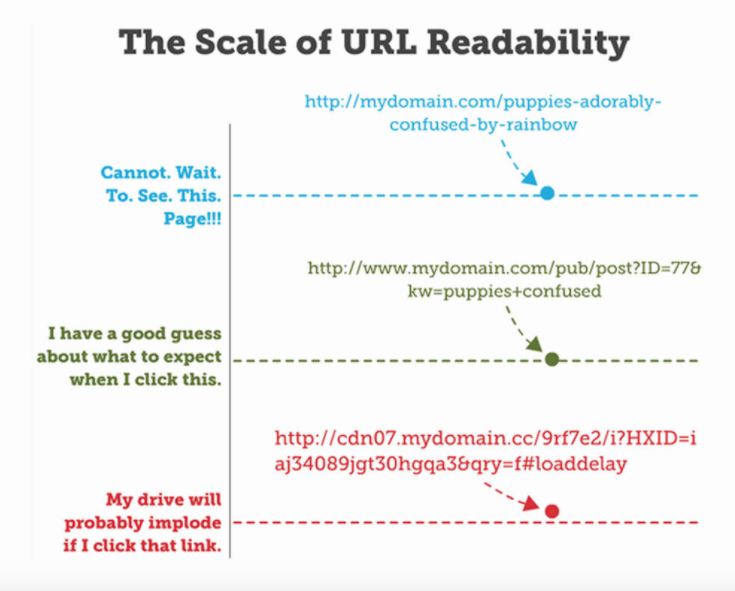
Take a look at this graphic about URL readability. Which of the following three links is the most appealing?

image8 1

Obviously, the first one is the most readable of the three. It’s simple, and it uses hyphens.

But readability aside, using hyphens also helps you with SEO purposes. Matt Cutts told us that the Google algorithm won’t penalize you for using hyphens. But underscores can decrease the chances of getting higher organic search traffic.

So if you look at the example URL I built earlier, you would see I used a hyphen between the words lead and generation.

Since there can’t be a space in a website URL, the Google Analytics default character to replace spaces is the % symbol, which looks even worse than an underscore.

It’s also important that you don’t repeat yourself when you’re naming your parameters. Here’s what I mean by that.

If your campaign source is Facebook, you wouldn’t want your campaign name to be something like “facebook-promo” because it’s repetitive.

You already know the promo is on Facebook because that’s what your source is labeled. The redundancy isn’t simple and can end up confusing you in the long run.

Banner advertisements

For those of you who are paying other websites to promote your brand through banners, creating UTM parameters is an absolute necessity here.

Let’s say your brand is being advertised on three separate websites as a banner ad.

Don’t you want to know which one is yielding the highest results?

Yes, increasing traffic and getting new leads is great. But why pay for three websites to promote your brand if 90% of the traffic is coming from one website?

Using your data from the UTM parameters, you can eliminate ineffective websites from your banner campaigns. This will help you save money and increase efficiency with these types of promotions.

Use custom links for your social media strategy

Your social media marketing campaigns are essential to your lead generation strategy.

Using these profiles to drive traffic to your site will definitely help you grow your business. But how do you know which social media profiles are generating the most leads?

You can find out with UTM parameters.

We’ll keep it simple. Let’s say you wrote a new blog post and you’re going to use your social media channels to distribute this updated content. Great idea.

You can see that your blog post is getting lots of new traffic, but you can’t identify the source. By implementing this tactic, you’ll be able to tell the sources of traffic right away.

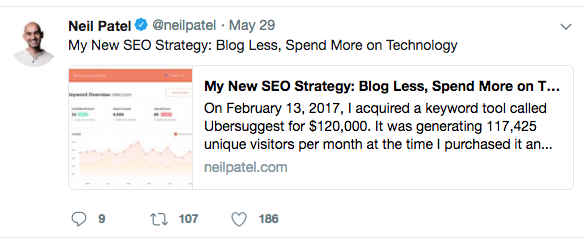
Here’s an example of a recent blog post I wrote on the Neil Patel website. I used Twitter to share it with my followers:

image4 1

But that’s not the only place where I’m promoting this new content.

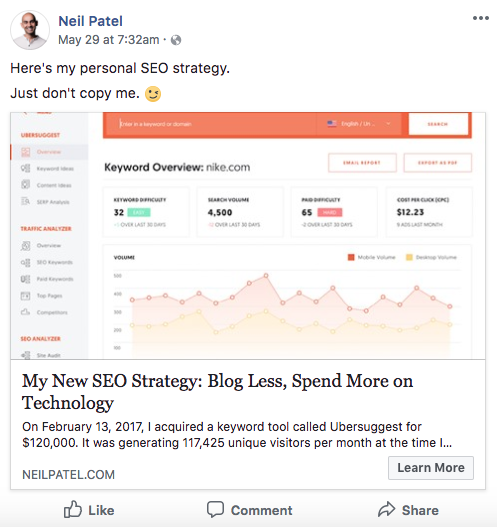
If you look at my Facebook profile, you’ll see a similar post there as well:

image7 1

I’m sure your brand has a similar approach when it comes to marketing new content on your social media profiles. So this is definitely something that you can relate to.

By assigning different source parameters for Twitter and Facebook campaigns, you’ll be able to see where your new leads are coming from.

Based on this information, you can adjust your strategy accordingly. Let’s say you learned that 80% of your leads came from Facebook. There are a couple of ways in which you could act on this information.

First, you may decide to double down on your Facebook marketing tactics. You could increase spending to generate leads with Facebook ads.

Or you may try leaving your Facebook campaigns alone for now and focusing more on rebuilding your presence on Twitter instead. Maybe you’ll implement a combination of these strategies.

But either way, you learned this valuable information because you implemented UTM parameters.

Do NOT use UTM parameters to test links on your website

While it may seem tempting and applicable, UTM parameters should not be used for internal linking within your website.

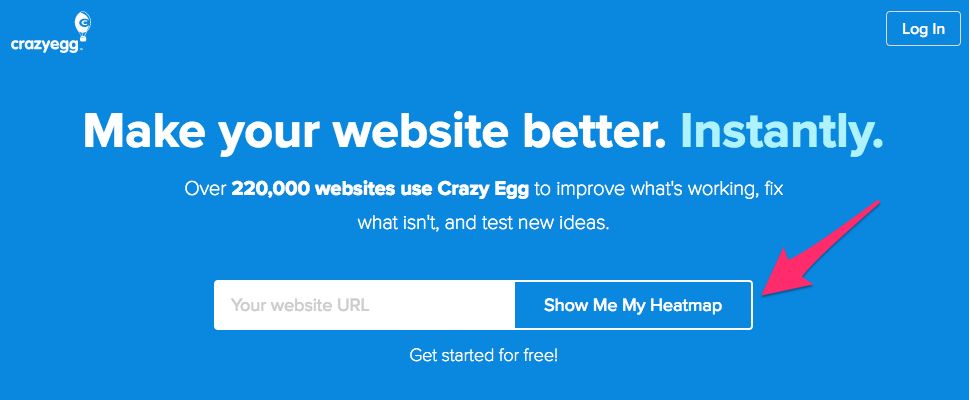
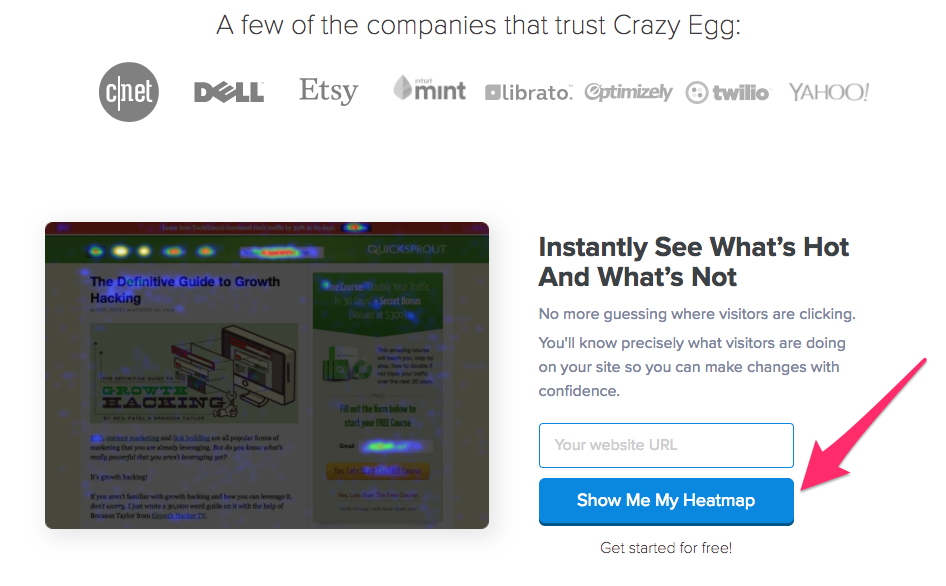
I’ll give you an example of what I’m referring to. Let’s take a look at the Crazy Egg website. Here’s one of the CTAs on the homepage:

image6 1

Simple, right?

But if you continue scrolling on this homepage, you’ll find that this isn’t the only location where “show me my heatmap” is written.

Here’s a screenshot from further down on the same page.

image9 1

It has the same exact phrasing as the CTA above.

So if you get new leads from your homepage, UTM parameters will be able to tell you which link they came from, right? Wrong.

Using UTM parameters internally will just create another visit in Google Analytics data. In short, this will inflate your site visits numbers and cause several other metrics to be inaccurate.

You’re better off using event tracking or setting up A/B tests for this purpose. Use your UTM parameters for all external sources outside of your website that generate leads.

Conclusion

Running campaigns to generate new leads is important. But this strategy isn’t effective if you can’t track the source of your leads.

That’s why you need to start using UTM parameters.

It’s easy to create custom links with this Google Analytics tool. Just make sure you follow the best practices for naming them.

Keep it simple. Use hyphens. Stick with lowercase letters. Don’t be repetitive.

Use UTM parameters to help keep track of your banner advertisements. Implementing these links with your social media strategy is effective as well.

While there are plenty of ways you can use UTM parameters to your advantage when it comes to tracking your leads, you should not use them to monitor internal links on your site.

If you follow these tips, you’ll be able to adjust your marketing strategy accordingly based on the results of your analytics.

How is your business using UTM parameters to track new leads?


Source Quick Sprout https://ift.tt/2yfylFz

Jumbo Student Loans Increasing: What Indebted Students Should Do

Jumbo shrimp may be quite enjoyable. Jumbo debt? Not so much. Learn how the profile and outlook of jumbo student loan borrowers have changed recently.

Source CBNNews.com https://ift.tt/2la8Koj

How to Overcome Projection Bias with Your Finances

One of my favorite exercises for planning ahead for the future is for people to make a detailed picture of what their future will look like. It’s a practice I do all the time.

In that practice, I just sit down and think about the future I’d like to have five years from now (or ten or twenty or whatever my timeframe is) in as much detail as possible. I make the assumption that things will go well, but not unbelievably well. It usually incorporates some significant degree of success on the goals I’m working on.

That type of visioning has a few powerful purposes. The biggest one is to somewhat clarify what goals are most important to me, because success with those goals tend to be the first elements I think about in that vision. A secondary benefit is motivation, because I’m visualizing a great outcome to a goal.

Still, there’s a pretty big problem underlining this practice, and that problem has a name: projection bias.

Projection bias is pretty simple to understand. When people think ahead to their future, they often make a ton of assumptions that center around their life being pretty much exactly the same as it is right now. This heavily extends to their current emotional state – if you’re upset, your projection of the future will have a negative tinge to it. If you’re happy, your projection of the future will have a positive tinge to it.

Wikipedia offers a solid explanation:

Projection bias is the tendency to falsely project current preferences onto a future event. When people are trying to estimate their emotional state in the future they attempt to give an unbiased estimate. However, people’s assessments are contaminated by their current emotional state and thus it may be difficult for them to predict their emotional state in the future an occurrence known as mental contamination.

In other words, we tend to visualize our future self as being much like the person we are now, with similar preferences and interests, but that visualization is often strongly tinted by our current emotional state.

So, if making a detailed picture of your future is shaded both by your current preferences and by your current emotional state, what value does that picture have? I argue that a detailed picture still has a lot of value, but there are a few caveats that should be attached to it.

First of all, you should make projections for the future on a regular basis, not just once. If you make a picture of what your future looks like just once and then try to stick with it over time, you’re going to find yourself working toward a future that probably isn’t really what you want, and it’s a picture of the future that you’ll gradually drift away from over time.

Instead, you should visualize the future in detail regularly. This corrects both for your emotional state as well for your other changing preferences in life.

For example, let’s say I’m visualizing the future when I’m in a mood where I feel like my relationship with one of my children is a bit strained, as I had to take away a privilege from them due to some behavioral problem and they got really upset. That feeling will probably have an impact on my vision for the future, even if I’m aware of it.

It’s a bad idea for me to bank all of my plans on that vision of the future. It’s not going to be very accurate in terms of my likely relationship with my child at that point.

Instead, what I should do is re-visualize the future on a regular basis. I do it about once a month, where I write down all of the details I can think of about where I want my future to be headed. The actual goals I’m working toward are something of an average of those visualizations over the last year or so. If there are consistent threads that show up over and over again, I know those are important to me. However, if something pops up only once or twice, I know those things are probably just tied to my emotional state and my focus at the moment.

In terms of specific, concrete plans, stick to what you know will happen. You know that you’re going to get old and you know that there will come a point when you physically and mentally don’t want to work at your current job, so plan for that. You know that your children are going to grow older and you know that, no matter what career path they might choose, they’ll probably need at least a little financial help with the education needed (whether it’s a trade school or a community college or a university). You know that you’re going to eventually have to replace your car. Those things are about as guaranteed as possible, thus it’s okay to make concrete financial plans for them.

You should be saving for retirement. You should be saving for the future education of your child (assuming, of course, you believe you should play a role in helping to pay for it). You should be saving for your next vehicle, provided you have any sort of need to drive anywhere. You should have an emergency fund. Those things cover issues that you know are going to happen.

The same thing is true for other aspects of long-term planning. You know you’re going to get older and thus more susceptible to declining health, so it’s a very good idea to be proactive about your health starting right now so that you’re not stuck in a bad situation later on.

What about the other plans you might have for the future? If you’re not dead certain something will occur, plan for it in a flexible way.

For example, let’s say that you intend to move to a new house in five to 10 years, ideally one that you build in the country. There are several ways you can start preparing for this.

One way is to simply start saving for that goal. Start putting aside some money each month for a down payment on the land and the expense of building the house. That’s a good approach.

Another approach is to start shopping for land right now and, if you find a decent piece of land, take out a mortgage on it right away and start making mortgage payments. That’s a bad approach.

Why is the first one good and the second one bad? With the first approach, if your goal changes, you still have a big pool of cash in savings with which to use for your new plans. With the second approach, your money is tied up in a chunk of land with a mortgage on it and most of your mortgage payments have gone to just pay off the interest and you’ve been footing the property tax bill, too. Because you locked into a specific plan early, you’ve been pushing your money into a mortgage for years and property taxes for years and your only hope is that the value of the land has gone up a lot.

The thing to remember here is there are a lot of ways that this goal could go off the rails. You might have been intending it as a retirement home, only to get divorced or to have one of you pass away unexpectedly. You could simply decide together that you don’t want a house in the country any more. Maybe a job offer takes you away from realistically being able to live in the country.

The moral of the story? Stay as flexible as possible with your savings as you work toward a big goal that isn’t a guarantee. If you’ve got a big goal that’s five or 10 or 20 years down the road and it’s not something that’s guaranteed to happen, you should be saving for that goal in the most flexible way possible, so that those financial resources can be used for other things. This is why people often save for big goals in a normal taxable investment account that can be used for anything when the time comes. Other accounts, like a Roth IRA or a 529, are designed for tax advantages when used for specific purposes (retirement and college education, namely) but usually have a tax penalty if used for other purposes.

So, let’s summarize what’s going on with projection bias.

It’s a good idea to visualize your future because it helps you see things that are coming down the road and to set long term goals for yourself. However, those visualizations are often at least somewhat flawed thanks to projection bias. You can work around those flaws by only making specific plans and taking specific actions for things that you know are coming, like your own aging, and being much more general in your savings plans for all other goals that could change over time as your life situation and perspectives change.

No matter what, it’s a good idea to save for the future, because you’ll always have big things you want to achieve. It’s just a good idea to not lock down those future plans unless those big goals are inevitable.

Good luck.

The post How to Overcome Projection Bias with Your Finances appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2ydwSj7

I Feel Like I’m Screwing Up by Holding Out for Student Loan Forgiveness


Lucky,

Congratulations on your degree! What an accomplishment.

But oh, student loan guilt. It’ll take the shine off your new diploma in an instant.

Even when you have a repayment plan to follow, and even when you know you’ll be saddled with this debt for much of the rest of your mortal life, there’s still the guilt factor. The feeling that you should be doing more.

Have you ever grabbed a calculator to fiddle with the numbers and see if you have any hope of paying off your student loan debt quicker? I’ve done that. It usually ends in the fetal position on the couch. A high balance makes it difficult to make headway unless you come into some cash, like lottery or long-lost aunt cash. Otherwise, every month when the bill is due, you get a reminder of just how long you have to go.

But you’re doing it right, even if your income-based repayment (IBR) amount seems trivial. Interest rates for federal student loans are lower than for other consumer debt, such as credit cards. Long-term student loans are gross, but they’re just a third wheel in your relationship with your money. Everyone’s got a third wheel.

To knock out some of that guilt, stop thinking about your student loan balance as debt, and start thinking of it as just another bill. Instead of focusing on the total balance, take it month by month and focus on what’s due now. Then, free up some mental space to think about your other financial goals, like paying off your credit card debt or saving for retirement.

Don’t feel bad about the loophole — seriously. From you to me to the rest of the United States, we collectively have more than a trillion dollars of student loan debt. Take the way out.

Now, for a few words of caution about that way out.

I asked two experts about your situation: attorney Adam Minsky, whose Boston-based law firm specializes in student loans, and student loan consultant Heather Jarvis.

If you don’t already have proof of your forgiveness date in writing, make sure you get it and triple-check it. Minsky explained that since IBR wasn’t created until 2008, the earliest someone could get their loans forgiven with the 25-year payment plan would be 2033 — 15 years from now. If you had income-contingent repayment before IBR came into play, your situation may be different. It would behoove you to have a conversation with the federal Student Loan Support Center to verify your status and ask for proof. Always get proof, especially when you think there’s a loophole in play.

As for your income, remember that income-based repayment. “Your currently low payments are likely based on last year's lower income, and so [they] won't last,” Jarvis warned.

You’re smart to also be thinking about the tax obligation for the forgiven loan balance.

Jarvis explained that Public Service Loan Forgiveness, for those who work in government or nonprofits, is not taxable as income. But income-driven repayment plans of 20 or 25 years, depending on the plan, require forgiveness be taxed as income.

Minsky suggests working with a tax adviser or accountant if you haven’t done so already. “They would have a better handle on potential tax consequences of loan forgiveness,” he said in an email. “Any tax resulting from cancellation of debt typically must be paid either all at once, or over a relatively short installment period with interest and penalties added, and the IRS has powerful collections tools if the borrower cannot pay.”

Changes to federal law could impact your situation, too, Minsky warned. “We don’t know what the tax legal landscape will look like 10 to 15 years from now,” he said.

The inbox is open. Send your worries to dearpenny@thepennyhoarder.com, and I’ll see what I can do to help.

Disclaimer: Chosen questions and featured answers will appear in The Penny Hoarder's “Dear Penny” column. I won't be able to answer every single letter (I can only type so fast!). We reserve the right to edit and publish your questions. Don’t worry — your identity will remain anonymous. I don’t have a psychology, accounting, finance or legal degree, so my advice is for general informational purposes only. I do, however, promise to give you honest advice based on my own insights and real-life experiences.

Lisa Rowan is a senior writer at The Penny Hoarder.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder https://ift.tt/2JTYJK0

Married to Someone Who’s Bad With Money? 11 Tips From Financial Experts


For richer, for poorer… ’til death do us part.

Marriage is the merging of lives. Also (often) the merging of salaries, bank accounts and financial futures.

But what do you do if you’re married to someone who’s terrible with money?

You love them. But you hate the way they spend money, rack up debt and can’t avoid overdraft fees at the bank.

It’s important to do the smart thing here, because fighting over money tears marriages apart. Money fights are the No. 1 predictor of divorce, according to this study of national data.

What to do instead? For tips, we talked to experienced financial advisers who counsel couples about their money problems.

1. Understand Why

If your spouse is terrible with money, veteran financial adviser Maggie Johndrow offers a fundamental piece of advice: “Understand why your partner is bad with money.”

This might be a good place to work with a financial advisor or a marriage therapist, says Johndrow, a financial adviser with Farmington River Financial in Hartford, Connecticut.

“Is your partner a big spender because they grew up poor and now they have the means to buy what they want?” she asked. “Or are they very risk-averse because of a financial tragedy that occurred in their past?”

Understanding each other’s money story will increase the likelihood you’ll work together financially.

2. Separate Bank Accounts Can Help Protect Your Money

“When it comes to couples, there’s typically only one person who wants to handle the finances, and sometimes the other person may quietly have their own money struggles the other person doesn't know about — large credit card balances or excessive monthly spending,” says Brett Anderson, president of St. Croix Advisors in Hudson, Wisconsin.

“I’d have separate savings, checking, investment accounts,” he said. “This should also include credit cards, loans, etc.”

If you need a quick, easy way to set up a secure checking account online, check out Chime. Bonus with this online account: You might get your paycheck up to two days early, which can help with money management. Unlike most banks, Chime doesn’t wait until your pay date to give you access to your money.

“I find it pretty common for married couples to have one spouse that runs point on the family’s finances and one spouse that usually isn’t as good with money,” says Andy Yadro, a financial planner with Googins Advisors in Madison, Wisconsin.

He recommends each spouse keep their own checking account, then open one jointly owned account. Most of your earnings funnel into the joint account, which you use for living expenses and savings goals. Each of you has a small percentage of your own pay that you can spend guilt-free on whatever you please.

3. Automate Your Savings

“Another best practice is to automate your savings program,” Yadro says. “Have a set amount each pay period automatically transfer into a savings or investment account that doesn’t have a debit card attached to it. That helps keep the money out of sight and prevents easy access so it can continue to grow untouched.”

Automating your savings doesn’t have to be hard. Digit is an automated savings platform that calculates how much money you can afford to save.

Simply link Digit to your checking account, and its algorithms will determine small (and safe!) amounts of money to withdraw into a separate, FDIC-insured savings account. Plus, Penny Hoarders will get a $5 bonus just for signing up.

4. Plan for Your Future Together

It’s no brilliant secret that investing can be a smart way to make money.

Sometimes, though, it feels restricted to a few wealthy elite.

But Stash is different. This app lets you start investing with as little as $5 and for just a $1 monthly fee for balances under $5,000.

Stash curates investments from professional fund managers and investors and lets you choose where to put your money. But it leaves the complicated investment terms out of it. You just choose from a set of simple portfolios reflecting your beliefs, interests and goals.

5. Agree on Who Holds the Purse Strings

If your spouse is bad with money, you’re going to have to decide how much control you want to try to assert over the family finances. Only you can answer that question.

“It is not unusual with couples that one person is better at dealing with money than the other. After all, opposites tend to attract,” said financial adviser Karen Lee, president of Karen Lee & Associates in Atlanta, Georgia.

“The most important part of this situation is to recognize it and to mutually decide to let the person who is better with money handle it. But if the person who isn’t good with money is also a ‘spender,’ this can be a challenge.”

If you end up handling more of the financial load and managing your family’s money, consider helping yourself out with a free financial assistant.

Charlie is a money-saving penguin, a digital financial assistant who lives in your SMS text messages or Facebook Messenger (your choice, though Charlie is more fun and reliable on Messenger).

The bot offers help with a little bit of everything, such as tracking your spending, reminding you when you have a bill due and reminding you when it’s time to save.

6. Turn Their Shopping Habits Into a Moneymaker

Is your spouse a shopaholic?

You might as well harness that and get some cash back on their many purchases.

Here are a couple of our favorite tools:

Does your spouse shop online? Enter Paribus, a tool that gets you money back for your online purchases. It's free to sign up, and once you do, it will scan your email archives for any receipts. If it discovers you’ve purchased something from one of its monitored retailers, it will track the item’s price and help you get a refund anytime there’s a price drop.

Ebates is a cash-back shopping site where you can earn 1% to 25% on purchases you make from more than 2,500 online retailers through Ebates’ online shopping portal. It’s super easy — you don’t have to pay any fees, mail in forms or redeem points to get your money.

Remember, this is money you otherwise wouldn’t get back.

7. Reward Yourselves for Good Financial Decisions

If you end up managing your family’s money, help yourself out with a useful app or two. The power of the digital age is at your command!

One app we’ve road-tested is MoneyLion, a free all-in-one app for managing your personal finances.

MoneyLion offers rewards to help you develop healthy financial habits and will literally pay you for logging onto the app. Based on your income and spending patterns, it offers personalized advice to help you save money, reduce your debt and improve your credit.

8. Cut Your Expenses Where You Can

You’re going to have to cut your family expenses wherever you realistically can.

To track your expenses, try checking out Trim, a free bot that keeps track of all your transactions. Connect your checking and savings accounts and credit cards for a big-picture look at your spending habits. Set alerts that’ll let you know when bills are due or when you’ve hit a spending cap.

9. Watch Your Credit

A little reality check here: Remember that once you’re married, your spouse’s debts can become your problem.

Your spouse’s shaky credit score can also hurt your chances of getting joint credit at good interest rates — like if you want to buy a house.

To get a better handle on what your credit looks like, check out a free app like CreditWise© from Capital One. You’ll get a free credit report card to show you exactly where your credit shines… and where it could use some improvement.

Advertiser Disclosure: Capital One compensates us when you enroll in CreditWise using the links we provided above.

10. No Matter What, Work Together

Money management guru Dave Ramsey has strong feelings on this subject.

“Marriage is a partnership,” he writes. “Separating the money and splitting the bills is a bad idea that will only lead to more marital problems down the road … Put all of your money together and begin to look at it as a whole.”

Whatever you decide is best for your bank accounts, heed the point of his message: You’re both on the same team, so work on the budget together.

11. Above All, Communication is Key

All the experts I spoke with said some version of the following:

More than anything, it’s important for you two to really communicate. Perhaps schedule a weekly sit-down just to talk about money. That way, each of you understands where your spouse is coming from.

“When I have couples who are paying off debt, struggling to keep a budget or otherwise experiencing financial friction with each other, I invite them to hold a weekly financial meeting,” says Justin Chidester, owner of Wealth Mode Financial Planning in Logan, Utah. “No judgment, no blame and open listening.”

Know this: Being secretive about finances is the No. 1 financial deal breaker for couples, according to a GoBankingRates survey. It outweighs overspending, having too much debt, being too cheap or not making enough money. Keeping secrets was the biggest sin.

For Richer, for Poorer

And remember:

Whenever you get frustrated, think of those marriage vows.

For richer, for poorer… ’til death do us part.

Mike Brassfield (mike@thepennyhoarder.com) is a senior writer at The Penny Hoarder. He is married, and he’s terrible with more things than money.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder https://ift.tt/2JNPmbs