Thousands of courses for $10 728x90

الاثنين، 2 يوليو 2018

16 Tips for Naming Your Startup

So you’ve got a great idea for a new business.

You took the time to write a business plan for your startup. After long and grueling months of conducting market research, coming up with prototypes, and analyzing your competition, you’re finally ready to turn this plan into a profitable business.

You even came up with a plan to raise the funds to get your company off the ground.

But before you can proceed any further, you need to name your startup company.

You may have had an idea or two. But how do you know if that name will work?

Naming your startup may seem minor, but it’s actually one of the most important and undervalued aspects of your business. This name will be attached to your brand image for years to come. You need to get it right from the beginning.

Otherwise, you’ll face some challenges if you try to change your name down the road. That’s a headache you won’t want to deal with.

With this in mind, I wanted to show you how you can simplify this process. These are the top 16 tips to keep in mind when you’re naming your startup.

Use this guide as a reference before you finalize your name.

1. Keep it short

The name of your business should roll off the tongue.

People shouldn’t have to take a breath midway through saying your name out loud. Just think about some of the brands that dominate worldwide.

Nike. Apple. Walmart.

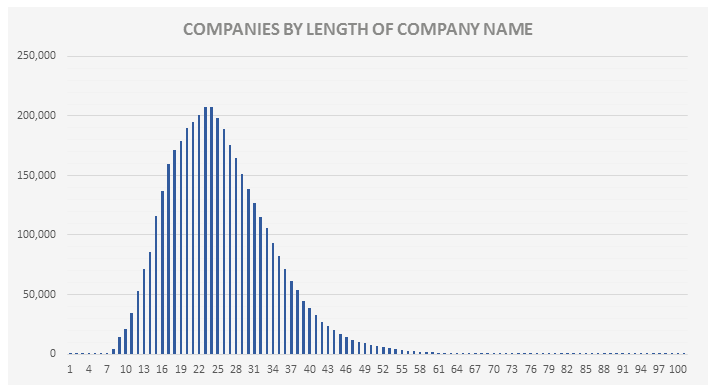
I found a really interesting study conducted by a UK insurance broker. They discovered that the average length of a company name in their region had 22 characters.

image1 11

More than half of these businesses fell within the 17 to 24 character mark.

While these are obviously longer than names such as Apple or Nike, they still fall within the lower end of the spectrum, as you can see from the graph.

Your business shouldn’t sound like a sentence. Sure, in some instances, two words might be appropriate. I’m talking about names such as Waffle House or even Quick Sprout. Ha! But both of these names are still short and roll off the tongue.

Most importantly, keeping your name short will make it easier for consumers to remember it, which will help you tremendously with your marketing campaigns.

2. Make sure it’s easy to spell

Put yourself into the minds of consumers.

Let’s says they hear your brand name somewhere. Whether it’s on TV, the radio, or in a conversation. Next, they search for it online, but can’t find you because they don’t know the spelling – it’s too complicated.

Stick with names that are spelled exactly how they sound.

Even if they see your oddly spelled brand name written somewhere, they may not remember how to spell it when they look for it.

Don’t do anything weird, like using the number 8 to replace the “ate” sound or use the letter “Z” in a place where you should have an “S.”

3. Don’t restrict growth

Right now, your startup may be focusing on something specific, whether it’s a product, location, or target market.

But that doesn’t mean you should name your business something extremely specific.

For example, let’s say you’re creating a fashion brand selling men’s jeans. Naming your company “Jeans for Men” is a bad idea.

What happens when you want to start making shirts, shorts, hats, or women’s clothing? The new directions no longer fits with your name.

Or let’s say you name the startup based on the location of your first physical store. You may be thinking something along the lines of “Tuxedo Shop of Seattle.” But when you want to open a new location in Chicago or San Diego, you’ll be faced with a challenge.

Instead, name it after something like a street if you want to have some connection to your local area. Just make sure it’s easy to spell.

4. Check the domain name

So you think you’re ready to settle on a name.

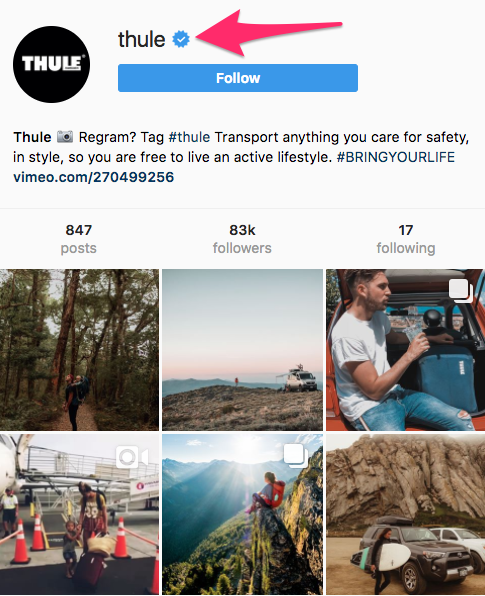
Next, use an online tool, such as GoDaddy to see if the domain is available:

image4 11

I see businesses make this mistake often. A company settles on a name, but someone already has the .com domain. So instead of trying to purchase it, they decide to use another extension, such as .net, .biz, or .org, instead.

I don’t recommend that. Consumers have grown accustomed to associating .com domains with credible and established businesses.

But that also doesn’t mean you should make your domain different from the name of your startup just to secure a .com domain.

My suggestion is this. If your domain name is taken and you can’t buy it, try to come up with a different name for your business.

5. Be original

You want your brand to be unique. Your name needs to be memorable and stand out from the crowd.

Do your best to avoid common names. “John’s Plumbing.”

How many plumbers out there do you think have that name? I’m willing to bet there is more than just a handful.

You want your name to stand on its own, without any confusion or association with other companies.

6. Say it out loud

Your name may look good on paper. But what happens when it’s spoken?

Earlier I said names should be easy to spell, but they should also be easy to pronounce.

Make sure that when you say it out loud, it doesn’t get confused with other words. You don’t want it to sound like something that could be inappropriate.

I won’t give you any examples in this instance. I’ll let you use your imagination.

7. Ask for feedback

You don’t have to struggle alone naming your company.

Sure, you can come up with some ideas and ultimately have the final say. But if you’ve got a team or partners, make it a group discussion.

Write down your ideas. Narrow the list down to five or ten names.

Then reach out to your family and friends. See what they think. If one name by far stands out from the crowd based on that feedback, you should consider it more than the others.

8. Research social media profiles

This is similar to your domain name search.

You want your branding to be consistent across all your marketing channels. See if certain social media handles are taken.

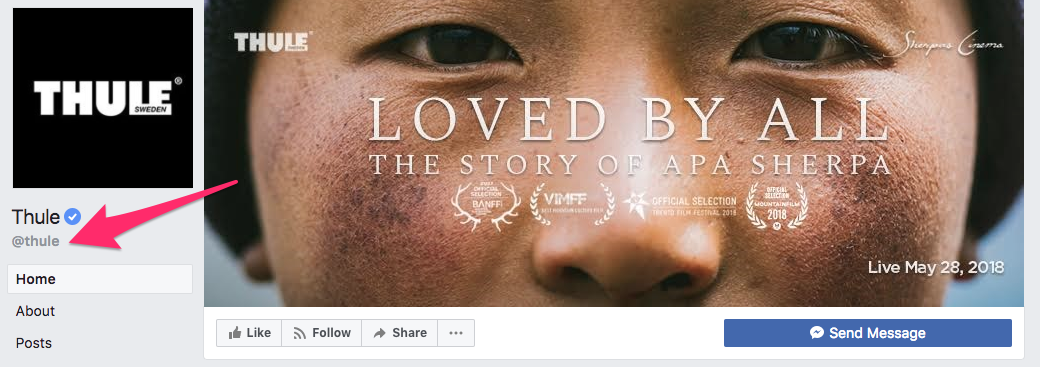
Here’s an example from Thule. Let’s look at its Facebook page first:

image3 11

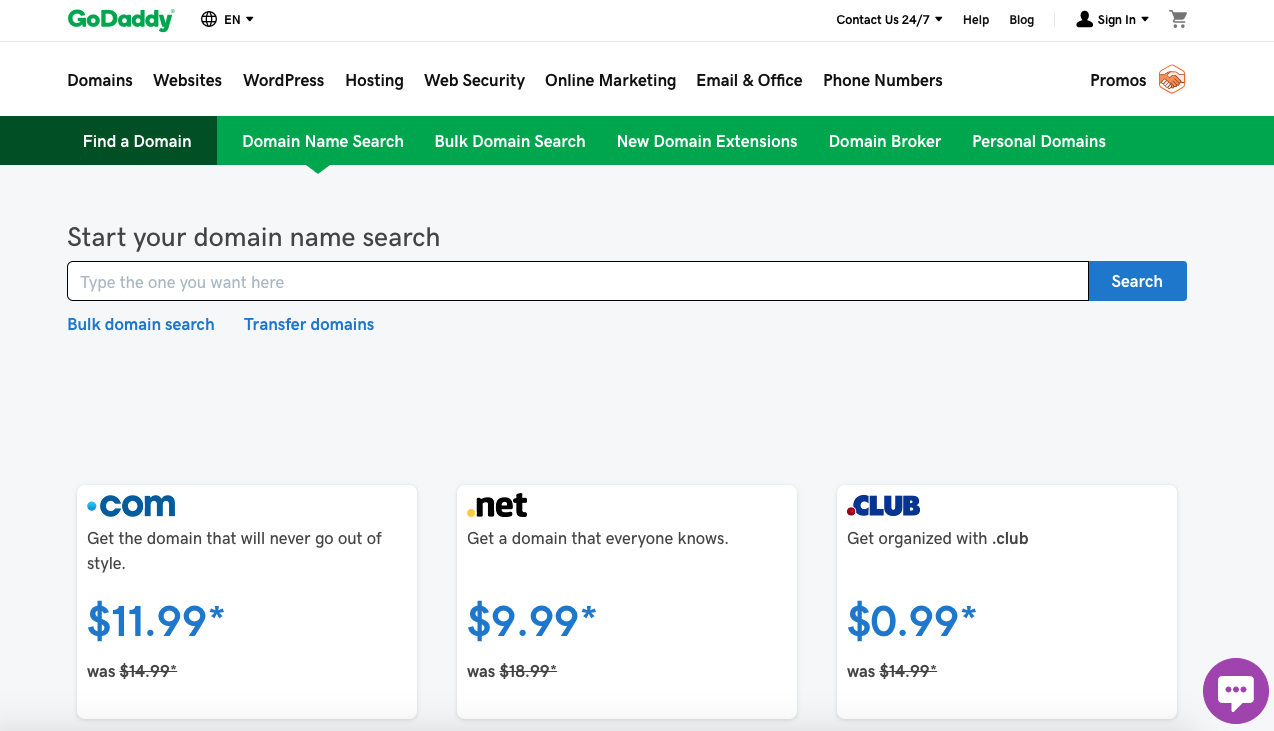
And now let’s check out its Instagram profile:

image2 11

As you can see, the company uses @thule everywhere.

It may sound simple, but you want to make sure all of this is squared away before you name your startup.

Having different social media handles on each platform will confuse your customers. It’ll complicate your efforts to build brand awareness for your new company.

If your name is available on all social media platforms except for one, reach out to the user and see whether you can purchase it from them, or consider coming up with a new name.

9. Make it catchy

Your brand name needs to resonate with consumers. It shouldn’t be forgettable.

Even though you’re in the early stages of your business, you should always be looking toward the future and thinking about potential marketing campaigns.

How will this brand name fit with your campaigns? Will it be easy for you to come up with a company slogan that flows well with the name?

You can’t pre-determine whether something will be catchy or not, and there aren’t any tools that can help you with this. But you can still figure it out based on your gut feeling and feedback of others.

10. Search the Secretary of State records

Once you come up with a name, you’ll need to register your new business.

You’ll probably form an LLC or corporation. In the US, check the Secretary of State records to make sure the name isn’t too close to a business that’s been previously registered.

If the name is too similar, the state may disallow you from registering that name.

Find a lawyer to help you register your new business. They can potentially help you with this research as well.

11. Do trademark research

You don’t want someone else to be able to steal your name.

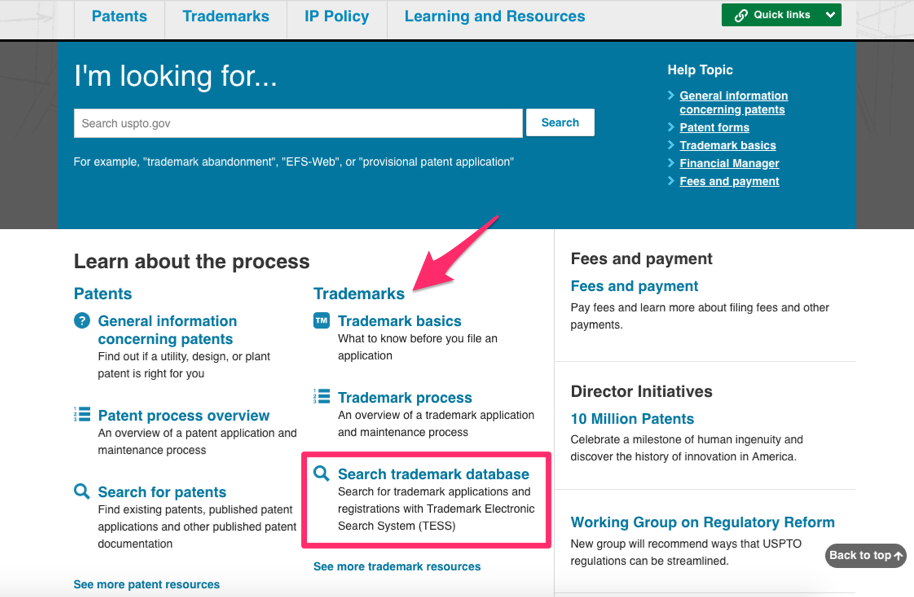
Do a search on USPTO.gov to see whether you can trademark it.

image6 11

This website will provide you with the resources and information you need to know about existing trademarks and the application process for your own trademark.

12. Make it relevant

Earlier, I talked about picking a name that doesn’t restrict your growth.

But that doesn’t mean you should pick something random or obscure.

Let’s say your startup company focuses on Internet security. Don’t name it “Bunny Ears LLC.”

Is the example a bit extreme? Probably. But you get the point.

13. Keep your logo in mind

Your brand name will be tied to all your marketing efforts. Keep your logo design in mind as well.

Different color schemes can impact sales. That’s because visuals are processed faster than words.  Consumers will remember a name if the logo is memorable.

Think about McDonald’s. The “M” golden arches are iconic.

How will your brand name translate to your logo and will it be recognizable? Ask yourself that when coming up with a name.

14. Take advantage of brainstorming tools

If you’re stuck on a name, you can use technology to help.

Use a tool such as NameMesh to come up with a unique domain name. Or use Namium to choose a name based on specific themes.

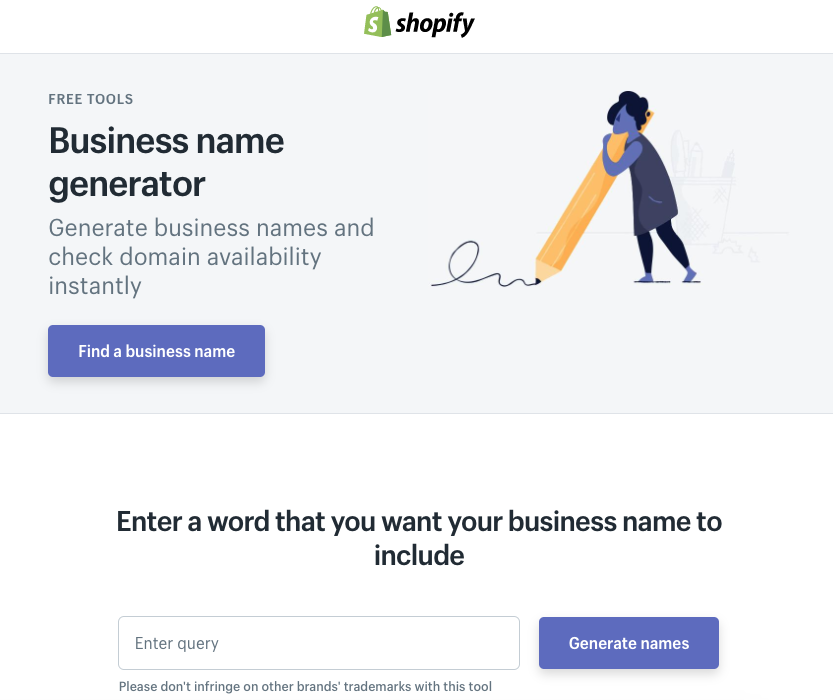
But one of my favorite tools is from Shopify:

image5 11

This business name generator helps you come up with ideas while checking for domain availability at the same time.

15. Don’t drive yourself crazy

Picking a name is important. But don’t let it consume your life.

It shouldn’t turn into a six-month project. If you take time to work things out, you’ll be just fine.

Will the name be perfect? Maybe not. But what is?

Don’t keep second-guessing yourself. Go with it if:

  • all the pieces line up
  • the domain is available
  • nobody has the social media handles
  • the feedback is good
  • you’re able to trademark it.

16. Make sure you’re happy with it

The name of your startup will be something you hear, say, write, and think about all the time.

If you don’t like the name, don’t use it. This startup is your baby. You wouldn’t name your baby something you don’t like, right?

The same concept applies here. Otherwise, you’ll regret it, and that could impact your behavior and the way you run the business moving forward.

Conclusion

What’s in the name? More than you think.

The name of your startup company will be your new identity. Don’t approach this task haphazardly.

Whether you’re struggling to come up with a name or you have a name in mind but unsure how to proceed, use this guide to help you finalize the decision.

It’s better to take the time and be sure of it now as opposed to trying to change your name in the future.

What’s the name of your new startup company?


Source Quick Sprout https://ift.tt/2IKc9Ue

How to Budget if Spreadsheets Make You Want to Gouge Your Eyeballs Out


If you’re anything like me, you’re perpetually swinging between vowing to cut all unnecessary spending cold turkey and humming “Treat Yo Self” as you order your third UberEats meal in 12 hours.

Which one you are depends on the day — and how long it’s been since your last paycheck.

The result: a pitiful savings account balance, scrimping to pay the minimum on your credit card, and feeling like you’re still living paycheck to paycheck even though your income has come a long way since your first job out of college.

You know there is a way to solve this problem. You know that if you just create a budget — and by some miracle, stick to it — you could finally get the financial freedom everyone else seems to have already figured out.

You also know budgeting is a buzzkill.

But if you give it a genuine shot, I promise I will, too. We’re in this together.

How to Budget in 4 Easy Steps

Creating a budget doesn’t have to be a grueling process. If you take some time to prepare and learn how to budget in a way that makes the most sense for your lifestyle, you can start on the road toward controlling your finances in no time.

We laid out exactly what you need to do in four pretty easy steps.

Step 1: Know How Much You Make and Spend

Before you can make a budget that works, you need to know your numbers. Log in to your bank account online, and grab your last couple statements. While you’re at it, grab your credit card statements, too.

First, write down how much you bring in each month.

Your biweekly paycheck. Any extra money that comes in from your side hustles. Child support payments. Recurring bonuses or stipends. Financial aid payments. Include it all.

Up next, the painful part: It’s time to log your expenses.

Start with the recurring stuff: Your rent or mortgage, car note and car insurance, health insurance, phone bill, internet and utilities. Don’t forget the fun stuff, like your Netflix and Spotify Premium accounts.

From here, you’ll want to start adding up your discretionary expenses. How much are you spending on shopping, eating out and drinks with friends?

To get a full picture, you can put these things in categories. For example, movies, concerts and museum visits can all go under entertainment. Your gym membership, yoga membership and the drop-in rate on that one CrossFit class can all go under fitness.

Look at a few months of statements for this part, too. That will give you a more accurate picture of your finances.

Step 2: Set Your Financial Goals

If you’re going to succeed at this budgeting game, you need have an idea of what you’re hoping to accomplish.

It can be a simple short-term goal like learning to budget so you can save for a vacation with your college besties. Or a long-term one, like learning to budget so your kid can go to college without student loan debt.

Set a goal, and make it good — it could be the only thing that stops you from buying yet another pair of shoes this weekend.

I take it a step further and mix my financial goals with my personal ones.

For example, I tend to overspend on restaurant meals. But budgeting less for eating out means I cook more healthy meals at home, so I save while staying on track to accomplish my weight loss goals, too. Then, I can use the money I save to build up my emergency fund as I pay down debt a bit faster.

Step 3: Find Your Favorite Budgeting Method

Once you have a complete picture of your finances, it’s time to pick the budgeting method that works best for you. The one you choose will depend on how much time and energy you have to devote to it. If you feel comfortable with an Excel file, you can do that.

But we’ve got a few super simple ideas you can try if charts make your eyes glaze over.

Bare-Bones Budget

You don’t have to spend several hours a month working on a budget. The easiest way to budget is to grab a pen and paper and simply write down how much you make and how much you need to spend and save.

That’s it. You’re done.

I’d suggest keeping that sheet of paper somewhere visible to remind you to rein in your spending.

Zero-Based Budget

The zero-based budget takes the bare-bones budget one step further. The goal here is to get to zero at the end of each month. It helps you account for each dollar on the way.

Write down how much you make, and divide it to cover all your bills, savings and discretionary spending until you hit $0 at the end of the month.

Although this plan encourages you to get down to nothing, the idea isn’t to spend without regard; it’s to make sure every dollar goes exactly where you intend for it to go every month.

50/20/30 Budget

This takes all the guesswork out of deciding which expenses should stay in your budget and which ones need to go.

With the 50/20/30 plan, 50% of your money goes to essential expenses like housing, utilities and your car payment. From there, 20% will go to financial goals like savings and investments. The final 30% is yours to spend on the fun stuff like restaurants, movies and drinks with friends.

Once you’ve picked your favorite budgeting method, don’t be afraid to bend it a little to fit your financial situation.

Step 4: Find the Best Budgeting Books, Apps and Software for You

While budgeting by hand works great, your smartphone can streamline it.

My favorite free app is Mint, which is available on iPhone and Android devices. You can connect your bank account and credit cards, and set a dollar amount for how much you plan to spend in each category.

Mint will then automatically analyze your spending and notify you when you get close to your budget or overspend. It’s pretty easy to use and can save you lots of time. The only downside is that the “You’ve exceeded your budget” emails can sometimes feel a little judgmental.

If Mint isn’t for you, there are a few other books and software apps you can try that come highly recommended by my Penny Hoarding co-workers:

You Need a Budget: This started out as an app and then became a book, too. It hinges on four rules:

  1. Give every dollar a job.
  2. Embrace your true expenses, not your ideal ones.
  3. Roll with the punches, and adjust your budget as you spend.
  4. “Age your money,” and start to break the habits that leave you living paycheck to paycheck.

This is more hands-on than other apps. It’s also the only option that’s not free. After the 34-day trial, you’ll pay $6.99 per month for the service.

Every Dollar: If you’re a fan of the zero-based budget, this is the free app for you. It’s also perfect for the side hustlers whose income can fluctuate from month to month. As you manually track your spending with the app, use it to make sure every dollar you make is accounted for.

Prism: This isn’t technically a budgeting tool. But it’s still worth mentioning. This free app puts all your bills in one place so you always know exactly how much money you have and how much you owe. You can connect everything from rent and car insurance to student loan payments and your Tidal music streaming account, and you can pay your bills right from the app.

“The One Week Budget”: This book is an Amazon bestseller by Tiffany “The Budgetnista” Aliche. We’ve even got a copy in our library at The Penny Hoarder HQ. With a series of worksheets, it walks you through how to analyze your income, track your spending, and pay down debt fast so you can get back to saving for the life you want.

“The Total Money Makeover”: This book was written by financial guru Dave Ramsey. A few Penny Hoarders who have paid off heaps of debt swear by his teachings. His book is also an Amazon bestseller and could be the perfect place to start if you want to break some of those not-so-great money habits and start building a budget that works.

Desiree Stennett (@desi_stennett) is a senior writer at The Penny Hoarder.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder https://ift.tt/2KA8A7T

Why Women Should Invest and How to Get Started

Lately, women hear a lot about gaps: how to combat the gender pay gap, how to avoid a resumé gap when you take time off to raise children, whether or not a thigh gap matters (it doesn’t).

One “gap” that isn’t discussed enough is the gender investing gap.

Women Are Less Likely to Invest Than Men, and That’s a Problem.

According to Ellevest, an investment platform created by women for women, “of all the assets controlled by women, 71% is in cash – aka not invested.” Statistically, women are less likely to invest, and even those who do invest tend to wait until they are older to start.

Most women don’t think they know enough about investing to properly grow their savings; therefore, they wait to start investing until they feel they’re more financially stable and believe they can risk the possibility of losing money. A common misconception around investing is that you have to be an expert in the industry to succeed when the reality is that there are so many tools and resources that make easy to start investing with as little as your pocket change.

Why Should Every Woman Invest?

According to a study by Merrill Lynch, 41% of women wish they invested more of their money. But why is it such a necessary part of personal finance?

Financial Equality

First and foremost, it’s important for women to be able to achieve a sense of financial equality and independence. In the face of issues like the gender pay gap and the pink tax, investing is one of the best ways for women to ensure that they have the potential to accumulate the same amount of wealth as men.

“It’s important for women to be able to walk away from situations that are hurting or not serving them – whether that’s a bad job or a bad relationship,” comments Ellevest’s Susan Thompson. “You should be able to have your own financial power to make decisions that enable you to care for yourself.”

Reaching Financial Goals

Whether you are looking to go back to school, save up an emergency fund, send your kids to college, save up for a large spend like a house or wedding, or just grow your overall wealth, investing is arguably the best way to reach those goals.

Saving for Retirement

Women earn approximately 83 cents to every dollar a man earns, on average. That means that even if we’re saving the same percentage of our income as men, we’re not going to save the same amount. In addition, women also tend to live longer. Basically, less money has to last longer when women simply save their money without an investing strategy.

Many employers do a match on a 401(k) or similar retirement savings plan. If you’re unsure about whether or not investing is really a good option for you, enroll in your employer’s program and watch as your savings grow.

Why Is a Savings Account Alone Not Enough?

Cash that sits in a checking account, safety deposit box, or under the mattress is actually depreciating in value year-over-year because of inflation. That means you’re essentially losing money when you aren’t actively growing your savings.

Check out the chart below, and you can see that a solid investments strategy can help you grow your savings exponentially over the course of 10, 20, and 30 years.

Men are five times more likely to name investing as their number one financial goal, meaning that more men are achieving those exponential returns throughout their lifetime than women. Investing allows women to earn more money than a savings account alone, even with small monthly deposits.

How to “Invest Like A Woman”

Despite the stereotypical belief that we aren’t good investors, women actually tend to possess quite a few qualities that give us an edge in the market.

Kiplinger’s article on the secrets of women investors puts it perfectly: “Studies show that men are more included to behave like baseball sluggers, who swing for the fences, even if it means running the risk of striking out for more often. Women, by contrast, are more like contact hitters, who are satisfied with a string of singles.”

Because women approach risk differently, we’re less likely to see large swings in our portfolio values, meaning a steadier growth over time.

Studies have also found that women are:
Less likely to trade investments, which translates into almost a 1% higher increase in investment earnings per year than men (who trade 45% more frequently than women).
Long-term planners, meaning we focus on our specific growth goals rather than chasing risky returns that may end up costing us.
More likely to ask for financial help. Just because 60% of men think they are experts at investing does not mean they know everything there is to know about the market. Women being more willing to seek out trusted financial advice from experts in the industry give us more opportunities to grow our wealth.

So, how do you leverage these qualities in your investments strategy?

Choose a Strategy That Works for You

Not all investing strategies are created equal, and unfortunately, most of the “gender-neutral” investing tools available to the public ultimately hinder the potential earnings for women.

Ellevest released a side-by-side comparison of a retirement scenario where a man and a woman both started saving at 30 years old, earning $85,000, and investing 10% of their salaries over the course of 37 years.

The study found that because of the gender pay gap and the natural progression of women’s careers (our salaries tend to peak at 40 while men’s salaries tend to peak at 55, and women are much more likely to take long career breaks), the woman would have about $320,000 less by the time she retires based on average market returns. That means she’ll have less money to live off of even though she’s likely to live years longer than the man.

Take these differences into consideration when you’re defining your goals, retirement plan, and investment strategies.

Figure Out Budget Allocation

Experts suggest a 50/30/20 philosophy when allocating your budget. You should strive to keep your “needs” at 50 percent of your income – food, rent/mortgage, clothes, utilities, etc. Then, 30% should be dedicated to self-care. Have some fun, get a manicure, go out to eat with friends. Lastly, 20% should be saved or invested.

Figuring out how much you should invest vs. set aside in a short-term savings account comes down to how much risk you’re willing to undertake. Year over year, the market has been steadily rising, but that doesn’t mean that a return is guaranteed. The golden rule is to never invest more than you’re willing to lose, especially if you’re going after aggressive or volatile markets.

Once you decide, Susan Thompson suggests setting up automatic withdrawals each month, even if it’s only $20 a month.

“In our mind, investing should be a ritual like any other that we undertake,” said Thompson. “Make a habit of putting money back towards your future, even if it’s a small amount.”

Know the Basics

Even though you don’t have to be a stock market expert, knowing the basics can help you communicate your goals and understand what’s happening with your money.

Some of the different types of assets you can invest in:

Stocks. They represent a part ownership in a company or corporation, also known as business equity. Basically, when a company performs well, the stock tends to increase in value. Stocks tend to be more volatile investments, meaning they can give you a high return on your investment long-term but tend to have larger swings in value in the short-term.
Bonds. Also known as fixed-income investments, bonds are one of the most popular assets for conservative portfolios. While they tend to be more stable than stocks or other volatile investments, they also have a lower return potential.
Money Market Accounts. When investing in these types of accounts, you’re allowing the bank to make low-risk investments into certificates of deposit (CDs) or government securities. The best money market accounts are low-return, yet stable investment assets.
Real Estate. Property has a tendency to rise in value over time, and there is a subset of investors who specialize in transforming real estate investments into high returns.
Cryptocurrencies. Bitcoin and blockchain technologies are continuing to grow in popularity. Experts expect for the current volatile market to become more stable in the coming years, which means

Conservative vs. Aggressive Investment Strategies

Investing and portfolio strategies are typically broken down into two main categories: aggressive and conservative. Aggressive strategies will put more money into stocks or other volatile markets such as cryptocurrencies. Conservative strategies will put more into bonds and money market accounts.

Aggressive investments typically get you a much higher return over time, but they’re also riskier. By contrast, conservative investments are more stable, but without the opportunity for the maximum return.

Your personal strategy can be a mix of both, and your strategy should ultimately be based on your financial goals, timeline, and risk tolerance.

If you’re looking at short-term financial goals such as saving up for a wedding or looking to pull together an emergency fund, a more conservative route will work best. This limits the risk of you losing money while still promising a good return.

However, if you’re looking to save for retirement over the course of 20 or 30 years, an aggressive strategy is going to get you the best return possible. While aggressive markets tend to fluctuate widely in the short term, the overall market trends upward an average of 10% each year. When you can afford to be patient in the market (something women are proven to be better at than men), an aggressive strategy can definitely pay off in your favor.

Also, remember that your investment strategy is not set in stone. As your financial goals change and as you get closer to when you plan on pulling money out of your investment accounts, it’s important to readjust your priorities and risk tolerance.

Choose the Right Investment Platform

If you don’t consider yourself an investment expert (and frankly, even if you do), getting professional help is a good idea. There are a lot of options out there for both the DIY-er and someone looking for one-on-one help. However, be careful about who you choose to trust with your money.

1.  Choose a fiduciary.

A fiduciary is a company or organization that is legally bound to do the right thing by their clients. Not all brokers or investment firms classify as a fiduciary, so make sure to ask before officially signing with anyone. If you find a great firm that isn’t a fiduciary, just make sure that they put client security and well-being above personal gain.

2. Know their strategy.

Talk to any potential firms about their strategy for investments. Some firms craft personalized portfolios that you have a heavy hand in selecting. Others use a formula and automated system for choosing your investments. Every firm and platform is different, so make sure that the firm you choose uses a strategy that will work best for you.

For example, most robo-investment platforms use an investment algorithm that is based on a man’s salary projections and career lifetime, so they aren’t always the best choices for a personalized approach to fit a woman’s financial goals for the long-term.

3. Consider your budget.

Take a serious look at the minimum balance requirements and fees for each platform or firm you’re considering. If you have a tighter budget, it will be worth it to find a platform or firm structured like Ellevest, where you can choose an account

4. Trust your gut.

If you get an “off” feeling about a firm or platform that you’re considering, trust it. You are trusting a company with your financial future, and in order to do that, you have to trust that they are acting in your best interest. Take the time to find a platform or firm that serves you and your financial goals.

5. Look for firms that support women.

While women investors are on the rise, there is still a gap between the number of men and women are in the investments market. Make sure you’re choosing a firm that will support your financial goals and understand the unique challenges that women face in the industry. Also take a look at the companies that these firms and platforms invest in. Are any of them led by women? Do they support women? While it may not immediately affect the return you get, choosing a firm or platform with a pro-women mindset will help us gain financial equality in the long-run.

Resources: Where to Look for Help and Inspiration

Ellevest’s Susan Thompson’s first piece of advice for women looking to get started was to dig into some research.

“Women are very fortunate today because there is an abundance of really good quality content online,” said Thompson. “Go places where the content can just get you thinking about your options.”

Check out a few of these resources for a deeper look at why and how you should be investing your savings and how you can maximize your return:

  • Ellevest’s “What The Elle” Newsletter. The Ellevest site as a whole is my favorite resource for women-specific investment research and advice. They have content about the gender pay gap, how to invest responsibly, how to negotiate for a raise, and every financial topic in between. Their co-founder and CEO Sallie Krawcheck has a monthly newsletter called “What The Elle” that gives insights into everyday investing and financial advice for women.
  • Women Investing Network’s Podcast. Twice a week, this podcast talks with powerhouse authors, entrepreneurs, financial experts, and top-tier investors about insider tips and tricks to mastering your personal finances.
  • The Everygirl. While this site isn’t purely focused on finance or investing, they have a great resource pool of advice from everyday women. They cover topics on how to bridge the gender pay gap, investing 101, investing apps, and more.
  • Money Girl. This podcast covers the entire sphere of personal finance in short, 10-minute episodes that break down incredibly complex topics.
  • Stock Market Simulator App. This app will let you try your hand at the U.S. stock market to invest in virtual funds without any real risk. While this isn’t recommended as a decision-making tool, you can get the hang of the stock market and learn more about the investments industry.
  • Wall Street Journal. Sometimes this publication can seem like a daunting resource tool for the beginner, but it’s one of the best platforms for staying up-to-date on all things wall street. You’ll be able to take a look at investment trends, tips and tricks to maximize your return, and more.

If you’re looking for a way to automate your own investment strategy or want to start investing on a small-scale without using a broker or firm, an investment app might be the right platform for you. If you type in “investment apps” in the app store search tool, hundreds of options will pull up, but not all will help you grow your savings to hit a solid return.

Robinhood

Robinhood is a commission-free trading app. While it’s functionality is basic without many research or analytic tools, if you’re looking for a basic platform for trading stocks, this is a great option for you.

Fidelity

The College Investor lists Fidelity as their favorite app that allows users to invest for free. They offer no-minimum IRAs and a range of commission-free ETFs, making this the perfect app for those of you who are looking to manage your own investments on a budget.

E*Trade

One of the more well-known trading apps, E*Trade started as a desktop online broker. The app works similarly to their website, including offering an Investor Education Center.

Acorns

While it’s not really a trading app, you can invest your extra change or add a scheduled auto deposit to continually invest. You choose your strategy (aggressive, mildly aggressive, mildly conservative, or conservative), and the app takes care of the rest for you.


Whether you’re looking to save for retirement, bridge the gender pay gap, or just grow your wealth and financial security, investing is a great option. Do your research, trust your gut, and get started. When you see how much your savings can grow, you’ll wonder why you didn’t start sooner.

“Don’t be afraid,” advises Thompson. “Investing is less expensive and less intimidating than you think.”

The post Why Women Should Invest and How to Get Started appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2Kr7T1G

Questions About Camping, Potlucks, Allergies, Kindles, and More!

What’s inside? Here are the questions answered in today’s reader mailbag, boiled down to summaries of five or fewer words. Click on the number to jump straight down to the question.
1. Finding time for home cooking
2. The “perfect” potluck dish?
3. Free campsites?
4. Receipts and renters insurance
5. Sell house or rent it?
6. Advice for shut-ins?
7. Portable office?
8. Frugal allergy solution
9. Fridge in garage cost effective?
10. Cleaning out grandpa’s house
11. Breaking Kindle book buying addiction
12. Strong pay for difficult job?

As we sit at the midpoint of 2018, I can’t help but spend some time reflecting on the half year that’s past and the half year to come. In fact, I spend a good hour yesterday doing exactly that.

My conclusion? As is often the case, I’m doing really well on a couple of goals and initiatives, and doing not nearly as well on other ones. Most years, I set 3-5 goals – for 2018, I set 4, of which 2 are doing great and 2 are not.

So, the question becomes what I’m going to do with the rest of the year. Do I try to recover those two lagging goals? Do I accentuate the positive and make sure the two that are succeeding continue to do well?

I decided to stick with the latter. I decided to drop the goals that weren’t doing well and reconsider them at the end of the year, and instead focus on the two that are doing well and make sure that they carry through until the end of the year.

It’s much easier to focus hard on one or two things than to split your focus even more than it already is.

Q1: Finding time for home cooking

I enjoy your posts on making food at home and it obviously saves money but it seems impossible in terms of time. I’m at work from 7:30 AM to 5 PM every weekday and often later. My husband doesn’t get home until 6ish either. We have two kids in child care that I drop off and pick up on my commute. I get home at about 5:45 PM most days and I’m dead. Husband gets home between 6 and 6:15. About all I want to do is either order delivery or cook something from the freezer and delivery tastes a lot better.
– Angelina

There are a lot of things you can do.

For example, one thing you can do is start making stews or other simple things in a slow cooker a couple of nights a week. Stews are incredibly easy – you just dump a bunch of vegetables and cut up meat in there and just cook it on low all day while you’re at work. You can cook a pot roast or a whole chicken with vegetables in much the same way – just put everything in in the morning and cook it all day. If you get one with a timer or use an outlet timer, you can have it start at like 10 AM or so so that it doesn’t cook the vegetables into oblivion.

Another thing you can do is make a casserole or something on Sunday evenings and just make 2 or 3 extra pans. Make lasagna, except make 4 pans at once and freeze the other three. Do this every Sunday you can and fill your freezer with those kinds of meals. You can easily freeze such meals in Gladware containers. Then, 1-3 nights a week, grab one of those frozen meals and move it to the fridge. Two days later, when it’s fully thawed in the fridge, throw it in the oven.

That takes care of most evenings and requires minimal effort in the evenings, not any more than you’re doing now. It just requires advance planning.

I find that the “I don’t have enough time!” issue is mostly the result of not planning ahead a little bit. If you know that you’re going to come home dead in the evenings and not want to cook at all, plan ahead so that you don’t have to cook.

(And there’s nothing wrong with takeout or delivery at least once in a while.)

Q2: The “perfect” potluck dish?

Summer is here, and we (my husband, me and two children) go to BBQs and evening get-togethers, and in the wintertime we go to dinner at a friend’s house probably once a month (we are very lucky to have such a network). Usually it’s asked that you bring a side, dessert or drink (or sometimes a main dish if it’s a big potluck). To save money, we try not to bring a six-pack or store-prepared sides and I try to make something instead. But I haven’t found the “perfect” potluck dish that is both inexpensive and gets eaten (easy to make would be a major plus as well). I was wondering if you had any creative ideas or portable food recipes that are low in cost yet still tasty?
– Amy

I don’t really have a “go to” because it depends on the crowd at the potluck. I like to bake, so often we’ll bring bread items, but that doesn’t really work for something that’s super quick (though it is easy).

We often bring things in a small slow cooker for such events. We’ll make it at home, then bring it in the slow cooker so it can easily sit out with the other foods and be eaten as desired. A few things we’ve done that seem to go over well are a small batch of chili (we usually do it very low liquid as people often put some on hot dogs) or spinach artichoke dip or buffalo chicken dip – any kind of dip will do as long as you bring along things upon which to put the dip (i.e., tortilla chips).

Another good option, if you have access to cheap strawberries, is to bring chocolate covered strawberries. You basically just pat the strawberries dry, dip them in heated chocolate, lay them flat on a baking tray, and stick then in the freezer for a while until the chocolate is hard. After that, just keep them in a big container in the fridge. I guarantee they’ll vanish.

When I was a kid, my parents would bring ham and cream cheese roll-ups. They were my favorite. Just take some deli ham, spread cream cheese on them, then roll them up and slice them. Some people put a quartered dill pickle in the middle of the slice.

Q3: Free campsites?

I found this website that lists free campsites (https://freecampsites.net/). Have you ever used a free campsite while camping? Seems like they would fill up super quick and you would run a risk of not getting a spot if you were traveling.
– Jeremiah

I have camped at free campsites in the past, but it is a bit of a risky proposition. You will sometimes show up and find them to be full or find them to be in utter disrepair. On one memorable occasion, I’ve found them full of sketchy people (apparently I came across a cult reunion or something). However, when they work, they work well.

You should expect that free campsites will probably not be highly maintained. You probably won’t find convenient fire rings or sometimes even clear spots for camping. There will sometimes be trash-related issues and the restrooms may be completely unavailable or poorly maintained. However, the cost is free – you just show up and pitch a tent – and that can make up for a lot, especially if you’re fairly self-sufficient.

The best success I’ve had in terms of quality free camping experiences have been in US National Forests and Grasslands – they call this “dispersed camping” and offer a nice guide. For the most part, if you’re outside of recreational areas, you’re allowed to camp anywhere you wish within National Forests and Grasslands. Most of the time, you’ll just park in one of the parking areas and carry your gear into the grasslands or the woods. You may have a park ranger check on you at some point, but you’ll usually be off by yourself. Be aware that the expectation is that you will leave no trace and the link above offers some guidance on that.

Q4: Receipts and renters insurance

Is a profound declaration with all the stolen goods in case of theft out of an apartment enough for the renters insurance in order to pay for the damage, or do you need receipts also to be able to accept the damagepayment?
– David

You don’t need the receipts as long as you’re honest about the list. Insurance adjusters are extremely adept and clever about figuring out what constitutes an honest list of possessions and whether someone’s making things up.

The best approach, however, is to do a regular photographic or video review of the contents of your apartment or house, capturing all of your significant possessions. It’s probably good to do this once a year or so and save the pictures on your phone or elsewhere. This makes it easy for you to assemble a list later on.

Naturally, receipts are pretty clear evidence that you owned an item. I would keep receipts for major purchases around anyway, because it never hurts to have them and they don’t take up a whole lot of room.

Q5: Sell house or rent it?

My husband and I have a 7 month old and would like to move out of the city to the burbs. We have great credit, owe a bit on our car and heating system. No credit card debt. We have two options: sell the current house and dump the money into a low mortgage amount and payment, or keep the current property as a rental. Take a HELOC, buy the new property. Rental has enough profit that out monthly mortgage cost from our 9-5 paycheck will stay the same. I see the rental as a way to have passive income and two mortgages paid off in 15 years, with the rental highly appreciating. I’m interested in your thoughts.
– Alison

Are you planning on managing this property yourself? That includes the process of finding someone to rent it, doing background checks on them, handling any and all renter issues that come up (repairs, renters who refuse to pay, evictions, etc.), and so on.

If you are, then you’ll probably make money doing this, but you’ll sink quite a bit of time into it – more than you probably expect. If you aren’t, then the management company will devour a lot of your profits in the form of a significant chunk of the rent plus the costs of significant repairs (depending on the arrangement).

I don’t think you should assume that renting out the property will guarantee you enough money to cover the mortgage. It has a good likelihood of producing enough money to mostly cover the mortgage most of the time if you put in your sweat equity, or cover some of the mortgage most of the time if you hire a management company to take care of the property.

Now, if that still sounds good to you, go for it. If not… I wouldn’t. I have seen firsthand how much work it can take to deal with even a single rental house and I have no interest in ever doing it.

Q6: Advice for shut-ins?

You must have some other readers in my position. I am essentially shut-in and relatively elderly (67.) I live alone except for my feline companion, and have calculated that I am by myself 97% of the time. I use a wheelchair and due to particular physical disability, can only use a Paratransit van for transportation. (Because of the hills in San Francisco, and the fact that the elevator in my building is out of service 5% of the time, I cannot count on being able to get out, although I do try to sit in the sun outside the building’s doorway when possible.) Therefore, many thrift ideas are out of the question for me. For example, I cannot go to a dollar store or to Costco, and have to rely on home delivery services.

Recently, my 17-yr-old cat passed away from cancer and I had to invest nearly $2K on the transition to a kitten, even with shelter adoption. (The house-calls vet is very expensive.) Note that I live in one of the most expensive cities in the country, San Francisco. I felt very badly about reducing my savings so much (in order to repay my credit cards within the coming two months, I have only half of my former savings left) but absolutely -especially since several of my disabilities are mental illnesses, having company is an imperative. I make everything I can from scratch – bread, broth, even ketchup! I don’t part with a dollar w/o careful consideration, but as I have implied, everything has to be delivered (generally, I use Amazon. I invest in Prime only one month out of every few yrs, and make the most of it with many deliveries quickly. The new kitten is an example of such a time for Prime use.) I occupy myself as a writer of self-help works for people with brain injuries like me and/or mental illnesses like me.

Do you have any ideas for me and those others who are shut in? I live on Section 8 housing and have Medicaid and Medicare. Food Stamps are not worthwhile since I can’t get to the stores. I do get Food Bank home delivery weekly. I am a client under scholarship of a wonderful social services agency that visits me monthly. Many thanks in advance.
– Connie

It really, really, really,/em> depends on the specifics of your situation, particularly what your disability enables you to do, and that’s why it’s hard to give “blanket advice” for all situations. The disabilities and specific conditions that shut-ins face vary widely, and those varieties of conditions drastically change what that person can take on.

What is your current financial situation? What debts do you have? What family support do you have? What community support do you have? What physical activity are you capable of taking on? Those answers vary greatly from shut-in to shut-in, and those answers drastically change what advice I can give.

Quite honestly, you’re probably in a far better position to assess strategies that can help shut-ins improve their financial situation.

Even given all of that, I have one big suggestion for every shut-in: make it your daily goal to improve your situation in some fashion, even if it’s just a tiny improvement. What can you do today that will make tomorrow (and the days after that) just a little bit better than today? No matter how difficult your situation is, there is always something you can do to improve tomorrow (and, ideally, subsequent days). Maybe it’s something as simple as getting a bit of exercise, or taking care of a task you’ve been dreading, or preparing for an upcoming event. Whatever it is, take on that task today instead of putting it off, and make sure that at least once a day, you do something to make tomorrow a little better than today.

Also, question every single thing you take for granted in your life. What is it that you actually need? What is it that actually provides genuine value to you? If you’re not sure, try going through days without various elements. Turn off the television for a day or for a week. Turn off the internet for a day or for a week. Don’t eat prepackaged food for a day or for a week. Don’t get delivery for a day or for a week. See how it goes. See if the things you just take for granted are really requirements in your life.

A final tip of advice is to make sure you’re getting every kind of assistance you’re eligible for. A great place to start with this search is benefits.gov. The search can be a little overwhelming at first, but invest the time to actually do this and you may find a surprising number of things that help.

This is one of those situations where I’d love to help, but the variables are so many that it’s impossible to give good advice that works for even a significant percentage of shut-ins.

Q7: Portable office?

You’ve mentioned before how you use your backpack as a portable office. Could you explain what you mean by that?
– Aaron

At all times, I keep all of the material that I need for work that I’m not actively using at home in my backpack. This usually includes a few personal finance and other books I’m reading that might relate to Simple Dollar articles, my laptop, my tablet, a few notebooks, headphones, power cables for those devices, a water bottle, and all of the other odds and ends I might need to work almost anywhere I might go.

The reason for this is that I can just grab that bag at any moment and go to the library or a coffee shop or some other environment and be completely ready to take notes, brainstorm, or write articles. I’ve worked in all kinds of environments – in the woods, at an interstate rest stop, in what seems like half the public libraries in Iowa, and so on.

My “portable office” is one of those trusted elements in my life. I know it’s always going to contain what I need for work, so when I want to work somewhere outside the house, I just need to grab that bag and I’m ready to go.

So, what are the specs? It’s a North Face Surge II backpack. It has an older (circa 2012-2013) MacBook Pro in there with a charging cable and a more recent iPad with a charging cable. I have a Nalgene water bottle in there. I have an external mouse in there – a cheap generic Amazon one for when I’m doing things on my laptop that go beyond what I want to be doing with a trackpad. I have a legal pad in there and a smaller notebook with some pens. I currently have four books in there – one is a dog-eared copy of Your Money or Your Life that’s been in there for years. I have a toothbrush and a small tube of toothpaste and some dental floss and a stick of deodorant in there. I have some aspirin in there. I have a few granola bars in there. I have a couple of mix-in packets for my water bottle in there. I have a small flashlight and a multi-tool in there. That pretty much covers it.

Q8: Frugal allergy solution

Do you have any frugal solutions for allergies? I get them in the spring and early summer really badly. I used to take prescription Claritin but can’t afford it any more. All I find online are weird homeopathy solutions that don’t work. Suggestions?
– Gina

The first thing I’d do is see whether or not your health insurance covers immunotherapy shots. If they do, head down to your doctor and see about getting the shots. This is a permanent (or close to it) solution to allergies.

Another solution is to try a store brand version of an over-the-counter allergy medication. For example, Zyrtec is just cetirizine hydrochloride, and these are cetirizine hydrochloride tablets for less than $20 for a year’s supply.

The only harmless natural solution I’d try is local honey, which usually has a ton of the local pollen in it and also is naturally soothing to the throat. Start drinking local honey in a cup of tea each morning and see if that helps.

Q9: Fridge in garage cost effective?

I enjoyed your recent article about buying a new fridge. My question is whether or not a refrigerator in the garage is cost effective, which you didn’t really address. If you have a free fridge, is it cost effective to put it in the garage for additional cold storage?
– Jasper

As I mentioned in that article, the energy cost of a 20 year old fridge is about $120 per year. Add on top of that the fact that such a fridge is already past its average expected lifetime and there’s a decent chance it will fail in the future.

That being said, if you are primarily using it to support bulk buying of refrigerated items and otherwise using it to store things that won’t spoil, there really is a good chance that such a fridge will be cost effective. All you need is for that refrigerator to save you about $2.50 a week in bulk buying, on average, for it to break even in terms of cost, and then beyond that it basically just provides a free (or even money saving) convenience.

Want to buy 20 pounds of peaches to make peach cider and you found a cheap bulk buy, but need to keep them cool for a while so that they don’t go bad as quickly? That’s the kind of thing that a garage fridge can help with. Want to keep a lot of bottled water and soda and beer cold for a party? That’s the kind of thing that a garage fridge can help with.

In other words, if you can think of lots of good use cases in your life, it’s probably worthwhile. If you can’t think of many uses, it’s probably not.

Q10: Cleaning out grandpa’s house

My grandpa died suddenly a few months ago. I am his only living relative (his only son was my dad, who died a few years ago) so I am his executor. He left everything to me which wasn’t much after all debts were paid but I do own his house free and clear. The problem is I don’t want to go in there and empty it out. I’ve tried three times and I can’t do it. I want to get rid of 99% of the stuff and save just a few possessions and then sell the house but every time I go in there I can’t deal. I considered hiring a service but I know I’d wind up losing things I’d regret if I did that. Suggestions?
– Marcus

Honestly, I’d talk to a few of your closest friends about it. Tell them flat-out what you’re going through and ask them for help in cleaning out that house.

Get them to do most of the work in going through the house while you focus entirely on evaluating things. Keep or not to keep? That way, this doesn’t turn into a lonely project for you.

A good friend will definitely step in and help with a task like this, so I’d definitely start with my innermost social circle.

Q11: Breaking Kindle book buying addiction

I am very good financially except for one thing. I buy waaaaaaay too many Kindle books. I am an avid reader and use the library but I still find myself often buying interesting books on my phone almost without thinking about it and then the credit card bill comes in and yikes. I don’t realize how many I’ve bought. Do you have a good solution for this?
– Tammy

From this, I’m getting that you would like to buy a few Kindle books a month, but you often fall into the trap of buying too many – or more than you planned for, anyway.

In that situation, I’d recommend getting a reloadable prepaid Visa card and using that as the primary form of payment on your Amazon account. Load it up each month with whatever your Kindle budget for the month is and buy away. Whether it’s $10 (and you’re the queen of the Kindle Daily Deal

The advantage here is that when the prepaid card empties out, Amazon will just decline the transaction and then you have to wait until you reload it. (In fact, you can actually automate that reloading – on the first of each month, transfer some amount onto that prepaid card for Kindle stuff!)

Or else stop using Kindle. That’s another option.

Q12: Strong pay for difficult job?

Your recent column from 6/23 on finding meaning and purpose in financial progress and Drew’s article on satisficing from 6/27 really struck a chord with me. I work for the government in a job I really enjoy most of the time, with good pay and mostly good work-life balance (when it’s good, it’s good; about 1-2 months/year it is horrid). My wife and I have a decent sense of what we’d like our future to look like, and a plan that should get us there.

However, the timeframe for arriving at that future seems so far away. I could probably get a job working for private companies with a salary that would make our planned future happen much sooner. Ideally, I’d do that for 2-3 years, and then return to my current job (a fairly common occurrence at my agency). During that time, we would keep our spending in check, so as to not get addicted to the higher pay, and I’d be focused on learning as many lessons for future governmental work as I can. However those 2-3 years would likely be bad, in terms of stress, life balance, and not feeling good about the work I’d be doing.

I’m kind of stuck between staying or going. Do you have any suggestions for how to approach this decision
– David

If you have a very strong likelihood of being able to fall back to your current position, then I’d go for it. You have a light at the end of the tunnel and as soon as the other opportunity gets to be overwhelming, you can bail. You’re not signing yourself up for something painful with no other options. You have options.

Here’s the truth: I’ve been in a couple of really miserable working environments. A big part of that misery is that many of the people there didn’t really see good options for themselves, so they were stuck in a difficult situation with an onerous boss. Having an “out” from that situation makes it far more tolerable, and by having this fallback position, you’ll have an “out” from day one.

If I were you, I’d jump at this chance. Just be very careful to not let your lifestyle inflate because of it. Right off the bat, lock yourself in to the salary you had before and use every other dollar to build a firm financial foundation. That way, when you “fall back” in a few years, it won’t feel like much of a change, but you’ll go back having a much stronger financial foundation. Get rid of debts. Build a big emergency fund. Make giant contributions to retirement. Then fall back to the previous job when things get overwhelming.

Got any questions? The best way to ask is to follow me on Facebook and ask questions directly there. I’ll attempt to answer them in a future mailbag (which, by way of full disclosure, may also get re-posted on other websites that pick up my blog). However, I do receive many, many questions per week, so I may not necessarily be able to answer yours.

The post Questions About Camping, Potlucks, Allergies, Kindles, and More! appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2MIOt4L

Flexible Home-Based Business Ideas for Women

Many years ago, when I started brainstorming home-based business ideas, many occupations came to mind, event planner, professional organizer, doula, and personal concierge. But when I asked myself, “How do I envision my daily life?” it didn’t include running all around town, being on call, working holidays, nights or weekends. When I sat down and […]

The post Flexible Home-Based Business Ideas for Women appeared first on The Work at Home Woman.


Source The Work at Home Woman https://ift.tt/2lPEsYo

Here’s a Quick Way to Snag a Free $20 Amazon Gift Card


We've found an exciting way to get free money today. (Bonus: This will help you keep an eye on your money, too.)

Today's free cash comes from Personal Capital, a portfolio management site. It's giving away a $20 Amazon gift card to anyone who joins and opens a free account.

We love this site because it helps you keep you track of your investments, credit card balances, and changes to your checking or savings accounts. For example, once you've set it up, it keeps track of your net worth in real time.

Here's how to grab a free $20 Amazon gift card:

1. Sign up for Personal Capital using this link.

2. Add your financial account(s) to your Personal Capital dashboard. You must link an investment account within 30 days of registering (for example, your brokerage, 401(k) or IRA) to receive the bonus.

3. You'll get your e-gift card through Amazon within six weeks from registration to the email address you provide.

To claim the bonus, you must be a legal resident one of the 50 U.S. states or Washington, D.C. and 18 years or older.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder https://ift.tt/2tMFj0i

Don’t Repeat These Five Mistakes Boomers Made on the Road to Retirement

As a generation that famously came of age amid postwar prosperity, baby boomers experienced a level of wealth and opportunity largely unheard of by their parents or grandparents.

All of that wealth, however, has not necessarily translated into being financially prepared for retirement.

According to research from Legg Mason, the average baby boomer has saved less than half of the $658,000 they think they’ll need to comfortably transition out of the workforce. The survey of 900 investors found that the average amount boomers have in employer sponsored retirement plans is $263,000. Older boomers, those 65 to 74, have an average of $300,000.

It’s a reality that’s left many boomers worried about making ends meet during retirement and contemplating the reality of working much longer than expected. But financial professionals say younger generations can learn from the mistakes of boomers. In other words, pay close attention to where they went wrong and don’t fall into the same traps yourself.

So what are the biggest financial missteps made by baby boomers? Here are some of the top answers from experts across the country.

Mistake No. 1: Buying Too Much Real Estate

Overextending and buying a large home is a losing strategy when it to when it comes to laying the groundwork for retirement, says Robert Johnson, principal at the Fed Policy Investment Research Group and former president and CEO of the American College of Financial Services.

“Larger homes have greater initial costs and greater ongoing costs, including maintenance and property taxes, when compared to smaller, starter homes,” explained Johnson. “Many younger people, or older people for that matter, would be much better off by renting or buying a smaller home and investing the savings in financial assets for the long run.”

People also mistakenly continue to believe real estate is a good, safe investment and that their home will dramatically rise in value over long periods of time. What they don’t realize, said Johnson, is that from 1890 to 1990 the inflation-adjusted appreciation in the U.S. housing market was just about zero.

Viewing your home as a vehicle to prepare you for retirement, at the expense of adequately channeling savings into other more liquid wealth accounts, can have lasting consequences, says Drew Kellerman, founder of Phase 2 Wealth Advisors in Gig Harbor, Wash.

“Don’t misunderstand: Paying down a home loan and eventually being debt-free is an excellent plan,” Kellerman explained. “That said, counting on your home equity for your future living expenses can be highly problematic.”

Home equity can be accessed in one of three ways – selling the home, taking out a line of credit, or obtaining a reverse mortgage.

“What do all three options have in common? They all assume that housing prices will forever continue to rise – or at least not crash – just before you need to get at that equity,” Kellerman noted. “This means you’re treating your home as a retirement asset, or investment. If so, and all your savings are tied up in your equity, this’s a disturbing lack of diversification.”

By all means, obtain the lowest interest rate mortgage you can and pay it down quickly, but not at the expense of building other, well diversified retirement assets.

Mistake No. 2: Investing Too Conservatively

When it comes to building wealth, one can either sleep well or eat well, says Johnson.

Investing conservatively allows one to sleep well, as there isn’t much volatility in that approach. But, it doesn’t allow you to eat well in the long run because your account typically won’t grow much.

“Since 1926, according to data compiled by Ibbotson Associates, the average annual return for large capitalization common stocks is 10%. Government and corporate bonds return around 6%, while cash is in the neighborhood of 3%,” Johnson explained. The surest way to build wealth over the long run is to invest in stocks, Johnson said, but too many people invest very conservatively and miss out on that opportunity. “If you have a long time horizon, you should invest in a diversified portfolio of common stocks.”

Mistake No. 3: Underestimating How Long They Will Live

The parents of many boomers may have only lived until their 50s and 60s, and as a result, boomers figured they wouldn’t live much longer than that themselves, says Misty Lynch, a Boston-based certified financial planner with John Hancock Advice.

“That may have kept them from saving a lot for retirement because they didn’t think it would be necessary,” said Lynch.

As we all know, however, times have changed and life expectancy is much longer thanks to improvements in health care. The average life expectancy in the United States is about 78.6 years old, according to data from the National Center for Health Statistics. And if you manage to make it to 65, you’re likely to live into your mid-80s on average.

Underestimating their own longevity has resulted in at least two problems for boomers: many don’t have enough cash socked away to cover two or three decades of retirement, and they’re not prepared for the health care costs they’ll face during that lengthy stretch.

“Young professionals should be aware of health care costs and take advantage of things like Health Savings Accounts if they’re offered through their health insurance,” added Lynch. “If you’re young and don’t have a lot of medical expenses, these accounts can grow and be used tax-free to cover those costs when you retire.”

Mistake No. 4: Over-Investing While Carrying High-Interest Debt

It’s not unusual for baby boomer clients, or clients of any age, to come into Kellerman’s office talking about their $15,000 credit card balances — on which they’re paying 21% interest while simultaneously trying to save for retirement.

“Carrying high-interest consumer debt is, unfortunately, quite common today. What is utterly bewildering, though, is when we hear it from a boomer who’s also maxing out their IRA and 401k contributions,” said Kellerman. “In other words, they are aggressively saving while carrying high-interest debt.”

If the plan is to pay that credit card debt down aggressively within one year, while also still contributing to a 401k program in order to get the matching employer contribution, then Kellerman says that may be a good approach.

“The time I shake my head is when people are making minimum payments on their credit card debt and then maxing out a 401k or contributing over and above the employer match,” continued Kellerman. “There is no leverage to that additional contribution to the 401k. Yes, there’s compounding interest, but at the same time you’re putting an extra $50 in your 401k, you’re paying $75 in credit card interest each month.”

Moral of the story? Get your credit card debt under control before making excessive 401k contributions, otherwise you’re not really gaining any financial ground.

Mistake No. 5: Starting Too Late

The one thing nobody can get back is lost time, says Matt Reiner, CEO and co-founder of the finance app Wela and author of “Ready to be Rich: Smart Financial Advice for People on the Way Up.”

“Many baby boomers started saving for retirement too late and expect to live the same lifestyle,” says Reiner. If you wait until your late 50s to start investing in your retirement plan, no financial advisor or technology solution will be able to miraculously make you the money you need to retire by 65, says Reiner.

Younger generations should begin by automating their savings, he advises. Even if you start small, the most important part is to simply get started.

Related Articles: 

The post Don’t Repeat These Five Mistakes Boomers Made on the Road to Retirement appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2lP0WZk

Hey Alexa, Stop Spying on Me! 5 Places Where Your Info Lives Forever

Beauty, Cleaning and Even Heartburn: This One Kitchen Staple Can Do it All


If you’ve ever baked a cake, chances are your pantry houses baking soda.

You might use it occasionally, but for the most part it stays hidden and waits for the next time you break out the cake pan.

Rather than saving it for special baking occasions, consider some of these uses for baking soda around your house. It’s one of those versatile ingredients that can replace numerous other products, so you can save your hard-earned cash for what really matters.

Clean and Deoderize With Baking Soda

One of the best-known uses for baking soda around the house is cleaning.

Whether used alone or mixed with other ingredients, baking soda is a cheap alternative to many of the more expensive (and chemical-laden) products on the market.

First and foremost, baking soda is a powerful stain remover. Good Housekeeping recommends removing stubborn stains from plastic food storage containers by soaking with a mixture of 4 tablespoons of baking soda and 1 quart of warm water.

You can also use it to erase your kids’ crayon “artwork” from walls. Sprinkle a little baking soda on a damp sponge or cloth and wipe down the walls to remove the masterpiece.

Baking soda is also great at ousting unwanted smells. You’ve probably heard that storing a box of baking soda in your fridge keeps it smelling fresh, but its use as an odor-killer extends way beyond that.

I use it around my house to remove dog stink from blankets and carpet by sprinkling a little on the offending surface, waiting about 10 minutes and then vacuuming.

For foul-smelling kitchen sponges that aren’t quite trash-worthy yet, Good Housekeeping advises soaking them in a mixture of baking soda and water to freshen them up.

Unclog a Drain with Baking Soda

A clogged drain can also benefit from baking soda (and you’ll actually have fun with this chore). I’ve tried this numerous times after my coconut oil hair mask clogged my shower drain. Crunchy Betty explains the best way to perform this trick.

First, pour a pot of boiling water down the drain to loosen the clog. Next, throw a 1/2 cup of baking soda down there and leave it for a few minutes. Finally, pour 1 cup of vinegar mixed with 1 cup of very warm water down the drain and cover with a cloth or drain plug. You’ll notice a lot of satisfying fizzing when the vinegar meets the baking soda.

Let this mixture do its job for five to 10 minutes before flushing one final time with boiling water. Your drain will run clear in no time!

Baking Soda for Personal Use

Wouldn’t it be great if you could replace multiple expensive beauty items in your bathroom with something cheap and easily available? Baking soda has your back.

Wellness Mama explains that baking soda can even help replace your store-bought deodorant. If you look at the ingredients of most natural deodorants, you’ll notice baking soda listed along with other easy-to-find ingredients. Rather than buying natural deodorant, try making your own using this recipe.

Just remember that some people are sensitive to baking soda, so you might experience irritation from using a natural deodorant made from it. (I personally can’t use it for this reason, which is a shame because I found it works very well).

Baking soda can also replace your store-bought face scrub. Wellness Mama recommends making a paste from baking soda and water and gently massaging it into your face for 10-20 seconds.

She notes it’s best to use this mixture as an occasional exfoliator rather than a daily because its alkaline properties can have an adverse affect on your skin if used too frequently.

Health Benefits of Baking Soda

Like many ingredients you can find around the house, baking soda has numerous health benefits. Ryan Raman, MS, RD, lists out a number in an article for Healthline.

If you suffer from heartburn, baking soda could provide you with much-needed relief. Raman recommends drinking 1 teaspoon of baking soda dissolved in a glass of cold water. While this might not replace your preferred medication for extremely bad cases of heartburn, it’s a good remedy to remember if your ailment unexpectedly strikes.

Baking soda can also help freshen your breath and improve your dental health thanks to its antibacterial and antimicrobial properties. Raman suggests replacing your usual mouthwash with 1/2 teaspoon baking soda mixed with a glass of warm water. Swish it around your mouth, as you would mouthwash, before spitting it out.

If you suffer from itchy skin or a sunburn, try a baking soda bath. Raman advises soaking in a warm bath that contains 1-2 cups of baking soda to relieve skin ailments. You can also make a paste using baking soda and water and apply directly to particularly itchy or damaged areas.

Many sources, such as DrAxe.com, explain that you can use baking soda to absorb the lactic acid in your muscles after exercising.

This allows you to recover more quickly so you can get back to your routine with minimal soreness. The site recommends drinking a mixture of 1 teaspoon baking soda in a glass of water to maximize the benefits.

Baking soda is an extremely versatile ingredient you probably already have in your kitchen. Rather than saving it for baking cakes and muffins, use it to benefit your home and your health.

Catherine Hiles spends a good amount of time cleaning up after her toddler and her dog. Baking soda helps make her life a little simpler (and cheaper)!

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder https://ift.tt/2KCC6Kg

الأحد، 1 يوليو 2018

Should You Buy a Duplex, Rent Out One Unit, and Live in the Other?

Investing in real estate can be a smart move, but that doesn’t mean this wealth-building strategy is attainable for everyone. You usually need at least 20% to put down on an investment property and saving that much money can be a tough task for almost anyone – especially in this real estate market.

But, what if you could buy an investment property that brings in cash every month and live there yourself? Believe it or not, this strategy — buying a multi-family unit and using it as your primary residence — is one many new homeowners and investors have used for decades to get their foot in the door.

There are numerous benefits that come with buying a duplex (or any multi-unit property) and living in one of the units, but there are drawbacks, too. Before you decide to buy a multi-unit property like a duplex or a triple-decker, experts say you should explore both the pros and the cons.

The Benefits of Buying a Duplex

If you’re eager to become a homeowner but also want to invest in real estate for the long haul, buying a duplex to live in can help you kill two birds with one stone. Not only will you secure a roof over your own head, but you’ll have at least one other unit you can rent out for profit. Depending on your goals, you could use the rental income to either a) reduce your own cost of living or b) snowball into more real estate investments down the line. You could even do both.

One reason buying a duplex is such an appealing idea is that there’s a lower barrier to entry than if you were buying a free-standing rental property. We already mentioned how you typically need at least 20% to put down on a single-family investment property, but the rules are a lot different if you’re buying a property to live in yourself.

With a home loan from the Federal Housing Administration (FHA), for example, you may be able to buy a duplex to live in with just 3.5% down. FHA loans also come with easier credit requirements and low closing costs, which can make them an even better deal.

In addition to being able to bypass the usual down payment rules with certain loans, there are other benefits that come with buying a duplex to live in. Some of these include:

  • You can use your rental income to begin pursuing financial freedom. Jason Reed, a Minnesota real estate investor who also runs The Duplex Doctors, says buying a duplex is a great way to set yourself up for financial success. Why? Because you can use the rental income you collect to free up more cash for yourself. “By collecting rental income from the unit opposite or above yours, you have the ability to potentially nullify your mortgage payment and live at a very low cost – thus helping to build financial momentum,” says Reed.
  • You may be able to afford a nicer home for yourself. Another benefit of buying a duplex is the fact that you can usually count a portion of your future rental income in addition to your own income to qualify for a mortgage. This increases your borrowing potential, says Reed. As a result, you may be able to afford a duplex that is in better shape or in a better area.
  • You can reap some tax benefits. Being a landlord is a business, which means you can usually write off certain expenses like repairs to the rental unit. But when you live on site, you can also typically deduct a portion of common area maintenance that impacts both the rental unit and yours, like landscaping or snow removal.
  • You may wind up with a better tenant this way. Buying a duplex you intend to live in could lead to better tenants than you might get if you purchased a single-family rental property. After all, renters who might cause problems or be prone to paying late may not want to live next door to their landlord, right?

At the end of the day, buying a duplex you plan to live in offers a lot of benefits. It’s also important to note that duplex living doesn’t have to be forever, and that you can use this strategy to get started as a real estate investor without saving up huge sums of cash.

Eric Bowlin from Ideal REI is the perfect example of someone who used a duplex to get started in real estate investing when he may not have been able to otherwise. Bowlin says that when he was working on his Ph.D. in New England, they purchased a multi-unit property to live in with the goal of getting their living expenses covered.

However, the income from the property changed the course of their lives, he says, and just a few years later he had dropped out of his Ph.D. program to invest in real estate full-time.

These days, Bowlin is living off of rental income and investing in real estate in lieu of another career. Ultimately, he says buying a duplex or multi-family unit is a great way to transition into investing until you can move into a single-family home. And, you never know, you may even get hooked on the process like he did.

The Drawbacks of Buying a Duplex

While investing in real estate has definite advantages, there are drawbacks as well — particularly when you’re buying a property you’ll actually live in. Some of the biggest downsides of living in your own investment property include:

  • You may have trouble setting boundaries. Bowlin says that living in your own investment property alongside tenants means the work never ends. “Tenants will think they can ask you to check something out at 9 p.m. at night, even if they’d never ask that of you if you lived elsewhere,” he said.
  • Things can get ugly fast if you need your tenant to move. Bowlin says that, when you need a tenant to leave or you have to evict them, living next to them can make the process a lot more uncomfortable. Imagine serving your tenant an eviction notice but also having to see them every day.
  • Bad tenants can make your life a nightmare. It’s one thing to have a bad tenant from afar, but it’s another thing to share walls with one. Reed says that duplex owners have to be extremely careful in their tenant screening process because some tenants don’t treat a property as well as they should, or don’t pay their rent on time. Remember that this person isn’t just your tenant; they will also be your neighbor — for better of for worse.
  • Being a landlord isn’t for the feint of heart. Reed also notes that being a landlord isn’t as easy as some people make it out to be. “As a property owner with a tenant, you’ll have to be ready to handle potential problems that may arise at a moment’s notice,” he says. “Even if you choose not to do maintenance yourself, you’ll likely be the one fielding calls from tenants.”

Deciding Whether to Buy a Duplex

Should you buy a duplex and live in one side? Reed says the most important thing to consider before buying a multi-family home is your end goal. What do you hope to accomplish?

“If you’re looking for a way to subsidize your mortgage, you might buy a completely different property than someone who’s buying the first of many real estate investments,” he says.

Obviously, a duplex you plan to live in needs to be a place you feel comfortable — at least for a while. It doesn’t need to be your forever home, but it needs to be sufficient for your family’s needs. Also, it needs to make sense as an investment property when you no longer live in it and rent out both sides.

At the end of the day, it’s all about the financials. Before you buy a duplex to live in, you should calculate potential rental income based on comparable rents in the area. From there, subtract at least 10% of your rental income to set aside for repairs, upgrades, and maintenance. Also remember that you’ll have to pay taxes and insurance on the property. Once you begin the search for a duplex or multi-family unit, your real estate agent should be able to talk over these expenses with you and help you run the numbers.

In addition to making the financials work, you’ll also make sure you’re mentally prepared to become a landlord. The internet is a treasure trove for landlord horror stories, and you have to remember that owning real estate is a lot of work. Not only will you deal with tenants themselves, but you’ll have to complete or outsource maintenance, upkeep, repairs, and cleaning. If your tenant damages your property, which is bound to happen eventually, you’ll be the one dealing with the aftermath — whether you fix issues yourself or hire out for the work.

For this reason and others, real estate agent and expert Evan Roberts of Dependable Homebuyers in Maryland says you may want to consider hiring a property manager to oversee your duplex. While hiring a property manager usually costs between 8% and 12% of your monthly rental income, they can help you avoid some of the headache.

Roberts says property managers can help you find renters, screen tenants, and set a professional tone for your business. But, most importantly, their existence can make living in your duplex less stressful.

“The property manager will act as a buffer so that grievances and requests go to them instead of the tenant knocking on your door,” he says. “The tenants don’t even have to know that you’re the owner while you live next door.”

But, you’ll still be living next door… which means you’ll have a good idea of what is going on with your investment. If you think you can handle the responsibility with or without a property manager, buying a duplex may just be a good way to get started investing in real estate.

Holly Johnson is an award-winning personal finance writer and the author of Zero Down Your Debt. Johnson shares her obsession with frugality, budgeting, and travel at ClubThrifty.com.

Related Stories:

The post Should You Buy a Duplex, Rent Out One Unit, and Live in the Other? appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2IDC7bX

To Read or Not To Read (E-books). Are Paper Books Cheaper than E-books?