DELAWARE WATER GAP — Skip Scheetz and Rich Spezzano want to make sure if they create a multi-million dollar artists’ space in the Poconos, that it is exactly what any local artist could ever want.Scheetz and Spezzano, founders of Pocono Center for the Arts, held their third meeting on Wednesday night to try in an effort to engage the public and gather as much input as possible when planning the proposed space.“We’re getting a lot of different [...]
Source Business - poconorecord.com https://ift.tt/2mSgYlI


الأحد، 29 يوليو 2018

Back to the Nest? Tips for Living in a Multi-Generational Household
One in every five Americans now lives in a “multiple generation” household, according to a Pew Research Center analysis. Using data from the U.S. Census, the center determined that multi-generational family living is rising in most age groups and almost every racial group.
A bit of backstory: This is almost as high as 1950, when 21 percent of people lived in households with at least two adult generations or households of grandparents and grandchildren younger than 25. By 1980, the figure was down to 12 percent. During and after the Great Recession, it jumped up to 17 percent and by 2014 it was 19 percent.
So: Living with the folks! Or with the grandfolks! Depending on your interpretation, this could be:
- a big step backward for millennials (those entitled crybabies!), or
- a great opportunity for young and old alike.
When you consider the crazy cost of housing and health insurance for millennials, plus the fact that many baby boomers still don’t have enough saved for retirement, multi-generational living could add up to a solution that works for everyone.
Young people get a chance to save for places of their own, pay off that vehicle they need to get to work (not everyone has public transit), and maybe tackle some student debt. Additionally, they’ll be better positioned to recover from any rookie errors as they figure out the whole adulthood thing. (Hint: If you make a mess of your finances on your own right out of college, you could lose that first apartment – and an eviction notice doesn’t look good on your credit score.)
Meanwhile, their parents reap the benefits of even a small amount of rent along with the extra pair of hands. Young adults can help with siblings (e.g., babysitting or shuttling them to sports practice or the orthodontist). They can take on tasks that are increasingly taxing for middle-aged homeowners, such as yard work and cleaning out the rain gutters. In households that include grandparents, millennials can provide rides and companionship to their elders (and respite care for those experiencing Alzheimer’s and other health issues).
And, of course, there’s the chance for parents and their offspring to spend time together and get to know one another on a different plane: as fellow adults.
Win-win, right? If you do it correctly. Here’s how.
Figure out why you’re there.
Is it because you want to be, or because it’s the smart thing to do?
If your culture is one that expects young adults to live at home and you feel fine about doing so, then congratulations: You’re staying true to your roots and getting a big financial boost. All the money you aren’t spending on rent and utilities can be used to help secure your future.
And if you wish you could afford to be anywhere but home, but realize this is the best option right now? Congratulations anyway, because you just made a very adult decision: to do the strategic thing and sort out your finances. This is a better choice than trying to make it on your own and winding up in additional debt (and ultimately having to slink back home with your tail between your legs).
Sometimes adulthood stinks. This is one of those times, but it won’t be forever. Speaking of time constraints, you should…
Write up a contract.
Maybe your parents would be happy if you lived there until you get married, or forever. But not everyone’s folks feel that way. In fact, your parents may be a little glum about your return to the nest, because they were just about to turn your room into a man cave and/or take some long-awaited trips.
They might wonder whether your presence will mean more work and expense, or fear the conflict that could result from their need for certain ground rules. For example, having a bunch of your old buddies in the family room playing video games until 2 a.m. might be disruptive to parents who have to get up early for work.
Thus you need some kind of written agreement – one that not only informs, but also protects. It’s all too easy to fall back into old parent-and-child patterns. If they start to grumble about how often you go out, you can remind them that nothing in the agreement says you have to be home every night (or any night). And if you start to get a little too comfortable, they can point out the clause that describes the chores you will do or the rent you will pay.
Wait… rent? Chores? Yes, and yes. The free rides should end once you hit adulthood. Your presence means added utility costs and likely higher grocery bills; if you’re using a family vehicle regularly, their auto insurance rate could go up. Work with your parents to decide which chores will be yours, and how much (if anything) you’ll contribute for rent and utilities.
The contract also needs an exit strategy (assuming your parents aren’t encouraging you to stay forever). Instead of saying, “I’ll leave once I get a good enough job,” specify the steps you plan to take to make this happen. For example:
- “I need $4,000 to set up a basic emergency fund and cover rental deposits and moving expenses.
- “Currently I have about $600 a month left after my student loan payment, commuting costs, and the rent I pay to you. That means it will be almost seven months before I can safely move out.
- “As you know, I’m looking for a side hustle to save the money faster. I’m also looking for a shared-housing situation, and if that happens then I’ll be able to move out sooner because overall costs will be lower.”
Abide by that contract.
It will be harder for your parents to treat you like a flighty kid if you don’t act like one. Thus if your contract says you’ll pay $75 rent from every paycheck, transfer the money or hand over the cash on payday. If you agree to spend two hours cleaning each weekend, do this willingly. Now that you’re an adult, your parents should not have to nag you about shoveling the snow or unloading the dishwasher.
Oh, and don’t ever let these words cross your lips: “There’s never anything good to eat around here.” If you want something good to eat, then shop for it and cook it – and make enough to share.
Learn to deal with conflict.
How easy it is to become a college student again: the golden boy or girl home on break, sleeping in and letting parents take care of all the details of life. Except it’s no longer cute when you’re in your 20s or 30s.
Look at it from your parents’ point of view: There you are – except there you aren’t. Other than showing up for meals, you’re either at work or out of the house. And if you’re leaving a trail of destruction (or at least unfulfilled chores) in your wake, then your folks have a right to be miffed.
Not that they can tell you what to do, outside of the terms of your contract. They don’t have the right to demand that you hang out en famille every night, or order you to accompany them to Grandma’s for Sunday dinner. Which you can politely remind them:
“I’m an adult roommate now, not a dependent. While I’m happy to spend a certain amount of time with family, I have other interests (and maybe a side hustle that keeps me hopping). How can we create a compromise that meets at least some of everyone’s needs?”
About those last two sentences: Much, much better than screaming “You’re not the boss of me!” and slamming out of the house. If you want to be treated as an adult, model some adult behavior. This won’t always work; your parents may have trouble thinking of you as anything except the kid who needed a nightlight and always left wet towels on the bathroom floor. Politely, lovingly remind them that you are all grown up now and that you are living up to the terms of your contract.
If they still try to tell you what to do, you have two options. One is to move out early. The other is to learn to deflect with (courteous) phrases like, “Thanks, got it!” and “I’ll certainly keep that in mind.” Remember, they are doing you a big favor by letting you live there. Now, do yourself a favor by doubling down on that exit strategy. One way to do that is to…
Regularly rethink your budget.
If you really want to move out on your own, then you need to make smart financial choices. Otherwise you run the risk of remaining an eternal adolescent, one who buys whatever he wants whenever he wants it.
A good way to do that is to remember the timeline you set for your parents. Except that it isn’t just for your parents: It’s a launch strategy for your adult life.
So instead of regularly going out for drinks after work or becoming an online shopping addict, set up some simple, smart goals for your money. Lots of people swear by the 50/30/20 budget: Spending no more than 50% of your take-home pay on essentials, 30% on wants, and 20% on saving (including retirement planning and an emergency fund). Plenty of budgeting apps exist as well (some are even free).
As your savings grow and you get in the groove of paying your bills in full vs. running up consumer debt, you’ll be able to plan your move-out. Among other things, you should:
- Monitor rents in different areas.
- Seriously consider shared housing – the savings can be huge.
- Figure out related costs of moving, including but not limited to truck rental, deposits for an apartment and utilities, and the price of any household items you’ll need to buy.
Make up a checklist, and savor crossing off each item. Every task that’s completed means you’re one step closer to self-sufficiency.
Keep that budget private.
In some families, each working person is expected to contribute. Otherwise, your money is your business. Be willing to ante up what’s fair, but don’t let parents take advantage of you because they can’t handle their own finances.
That’s especially true if your dad is hitting the racetrack, or your mother decides a younger sibling should be in a private high school. Suddenly you’re being asked to contribute more than your original agreement specifies. That’s a sticky situation, to be sure, but you cannot jeopardize your own future to shore up the family budget.
No one needs to know everything about your finances. If you’re contributing as agreed upon, that’s enough. While you might want to give more in case of an emergency like illness or layoff, be careful not to give too much. Pay your share, but don’t routinely cover someone else’s obligations. This is your financial future we’re talking about, here.
Keep your parents apprised.
Again, your money = your business. But it doesn’t hurt to let the folks know how that exit strategy is shaping up. When they hear things like, “The nights-and-weekends pizza delivery gig will let me retire that credit card debt a lot sooner than I thought,” they’ll be glad to know you’re making progress.
As you get closer to launch, let them hear more:
- “Two more paychecks and I’ll have my emergency fund built.”
- “I’ve got utility deposits and first and last month’s rent saved.”
- “My college roommate is looking for a fourth person to share his place – I’ll be meeting with him and his current roomies this weekend.”
And if you really want to demonstrate maturity, here’s another thing to say: Thank you. That can be a general, heartfelt, “I appreciate your help,” or a more specific phrasing:
“Your letting me move back home has given me a big financial boost. Instead of having to use a credit card to pay for basic living expenses, I’ve been able to take care of the consumer debt I already had.”
And here’s another thing they might want to hear:
“Because of that side hustle, I’m reaching my savings goal much faster. Your letting me pay such a low rent has made a huge difference in the kind of life I’ll be having later on. But because I’m making more money, I’d like to pay an extra $50 (or whatever) a month toward rent/groceries/utilities.”
That’s another hallmark of adulthood: Paying your fair share vs. taking advantage of someone else’s kindness. Even if your parents refuse the money, they’ll be pleased by the offer.
Veteran personal finance writer Donna Freedman is the author of “Your Playbook for Tough Times: Living Large on Small Change, for the Short Term or the Long Haul” and “Your Playbook for Tough Times, Vol. 2: Needs AND Wants Edition.”
Related reading:
- Breaking Away from Financial Dependence on Your Parents
- 12 Smart Financial Strategies for People Struggling to Get Started
- Avoiding the Trap of Financially Dependent Children
The post Back to the Nest? Tips for Living in a Multi-Generational Household appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2NQzGG4
السبت، 28 يوليو 2018
Restoration franchise opens Pocono office
STROUDSBURG — A nationally ranked franchise in the property restoration and water damage remediation industry, 1-800 WATER DAMAGE has opened its Poconos location on Rimrock Drive in Hamilton Township.Serving Monroe, Lackawanna and Luzerne counties, 1-800 WATER DAMAGE of The Poconos provides water/flood damage restoration, fire/smoke/sewage cleanup and mold remediation, as well as cleaning for tiles, grout, upholstery and carpets."In Pennsylvania, we experience a variety [...]
Source Business - poconorecord.com https://ift.tt/2mSfnws
Source Business - poconorecord.com https://ift.tt/2mSfnws
A Look at My Morning Routine
Carl writes in:
I’ve been reading The Miracle Morning by Hal Elrod that talks about the benefits of a morning routine and includes some examples. I was wondering what your morning routine looks like. Managing to write a long article every single day has to involve a killer routine!
I took a quick look through the site archives to see if I’d written about my morning routine before and it turns out that I hadn’t done so in quite a while, so I thought it might be fun to talk about this a little.
I’m a morning person, and I’m a huge believer in getting up early to get some things done and get the day started off right. What I’m going to describe below is what my normal morning routine is on an average day, but it’s worth noting that this varies a little, particularly on weekends or during time crunches when I’m preparing for a trip. Most mornings include most of these things, but I will sometimes drop one or two of them if necessary.
So, here’s what a good morning looks like for me.
I wake up around 5 AM. I set an alarm as a fallback measure that goes off around 5:30, but I’ve trained myself to naturally arise around 5 AM almost every morning. I try my best to stick to a standard bedtime when I am at home, which is around 10 PM, and when I go to bed, the focus is on falling asleep, with no smartphone or anything like that (I’ll sometimes get into bed a little before then and read for a while, but I’m pretty consistent about going to sleep starting at 10 PM.)
I drink some water and stretch. The first thing I do after getting out of bed (and using the bathroom, of course) is head downstairs to drink some water and stretch. I grab a water bottle out of the fridge – I use a 32 ounce Nalgene bottle that I filled the night before and put in the fridge to get nice and cold – and start drinking it. I’ll usually look out the windows a little, then I’ll stretch for about twelve minutes while drinking the water bottle.
The stretching that I do is stuff I was taught at the taekwondo classes that will help with getting one’s kicks higher. It mixes some general body stretching with some stretches intended to help me get my legs higher in the air when kicking and doing other things. Honestly, it all feels pretty good first thing in the morning. I do a sequence of ten stretches for 30 seconds each, then repeat the cycle. It takes between twelve and fifteen minutes, depending on how much I pause to sip water and how long it takes me to move from stretch to stretch.
After that’s done, I pour myself a cup of cold brew coffee with some almond milk or regular milk in it. I make my own cold brew coffee using a simple cold brew setup I was gifted a year or two ago that basically rests coffee grounds in a filter inside of a pitcher of water. I just fill up the filter with coffee grounds, put it in the pitcher, and let it sit for a day or so, then I remove the grounds. This makes enough coffee for about four cups.
I sit down with that coffee and spend about an hour with my journal doing three things.
First, I write three morning pages. The “three morning pages” practice is one introduced by Julia Cameron in her book The Artist’s Way. The practice is simple: just open up a notebook and fill three pages with whatever is on your mind. If you’re thinking about something, write it down, no matter how serious or how inane it is. What you’ll find is that, often, the time you spend thinking carefully about that thought as you write it down leads to another related thought, and then as you write that down, you’re led to another related thought, and then eventually you lead yourself down some kind of path to a deeper truth about yourself or the world.
I tried “three morning pages” as a thirty day challenge a while back and I was absolutely amazed how useful it was to me on a daily basis. Not only did it seem to help me either clarify something that was bothering me or help me explore an idea literally every single day (and often two or three things), it also seemed to lead to an incredible clarity of mind throughout the day. Since then, this has become an essential part of my routine, something I try really hard to do every single day if I can. I usually fill up three pages, but the truth is that I set a timer for myself for 60 minutes for this and I stop whenever the timer goes off. I average three pages in that timeframe.
After that, I draw a big line in my journal and then answer Michael Hyatt’s eight daily questions. This is kind of where I begin to transition into the more practical part of my day, where I’m starting to think about what I’m going to get done that day. I find that doing this right after the three morning pages just seems to click well for some reason.
Hyatt suggests answering eight questions as a daily journaling routine:
“What happened yesterday? I don’t chronicle everything, of course. I write the highs, lows, and anything I want to remember later.
What were my biggest wins from yesterday? This gives me a sense of momentum to start the new day.
What lessons did I learn? I try to distill my experience down into a couple of lessons I want to remember. It’s not what happens to us but what we learn from it that matters most.
What am I thankful for right now? This is one practical way I can cultivate a sense of abundance and gratitude.
How am I feeling right now? Feelings aren’t the be-all-end-all, but they’re a clue. In the past, I just ignored or suppressed them. This gives me an opportunity to check in on myself.
What did I read or hear? Here I list important books, articles, Bible passages, or podcasts I consumed since I last journaled.
What stood out? I don’t want to lose what I learn in my reading and listening, so I record key insights.
What can I do next to move forward on my goals? I think through my goals and my schedule and identify a few key actions I could take to make progress. This helps me prioritize.”
One quick note: for the “what did I read and hear” part, I usually refer to my pocket notebook and to Evernote because that’s where I keep track of such things. I carry anything that I considered noteworthy forward to here, which is how I make use of “random” notes that are just ideas and quotes and other such things.
This takes about fifteen minutes to twenty minutes, depending on the day.
Finally, I pull out a separate notebook and review my “triggers.” This is an idea that I learned from Triggers by Marshall Goldsmith, with a bit of assistance from Ben Franklin, that I’ve been using for the last several months. Basically, the idea behind it is to nudge myself into reflecting on what behaviors I want to naturally develop in myself and practice every day. Here’s how it works.
Once every three months, I go through my life and spend some time thinking about what behaviors I really want to work on within myself over the next three months. What do I think is bad about myself that I want to improve? What do I think is good about myself that I want to accentuate? I come up with a list of twenty or twenty five things.
Then, I pull out a small fresh notebook and write all of those things out. I write down a description of what I want to change and then I end it with a question: Did I do my best today to… do whatever it is that I’m describing. This is a trigger question, one meant to motivate me not to achieve something in a black and white sense, but to simply do better in regards to that aspect of my life.
For example, one of the things I’m really working on this quarter is humility. What do I mean by that? I want to confront my prejudices. I want to ask questions and listen to others rather than talking about me and my thoughts. I want to intentionally give credit to others for their ideas and achievements. I want to never consider myself “too good” for anything. I want to accept that I’m not the best at everything and that others often achieve more. I wrote all of that out (and a few other things) under the heading of “Humility” and then, at the bottom, I wrote “Did I do my best today to be humble?”
In my morning routine, all I do is read through those pages I wrote about the things I want to work on in my life. I read one, then for about fifteen seconds, I visualize myself doing at least one of those specific elements. I just move through all of them this way. This takes perhaps ten minutes.
(This notebook also has a chart in it. On a single page, I have 22 rows – one for each thing I’m working on this quarter – and 31 columns – one for each day this month. At the end of the day, I give myself a score from 0 to 10 on each of the things I’m working on. “Did I do my best to be humble?” I score myself somewhere between 0 (complete fail) to 10 (the person I want to be) and write it down on that page. I find that the self-scoring is really, really powerful, and paired with the morning review, it pushes me quite effectively to be a better person in terms of my behavior, not my achievements.)
Yes, I spend an hour and a half with my journals almost every morning. The thing is, when I’m done doing that, I feel like I’m incredibly primed for the day, like I’m ready to take off like a rocket ship. On days when I’ve devoted that time to journaling, I’m just simply more productive and a better person all day long. Furthermore, when I chain together lots of days of consecutive journaling practice, the effect gets even stronger, and there’s actually a residual effect where I still get benefits for a few days if I don’t complete that routine.
I use whatever notebook I can inexpensively find for my journaling and use a gel pen for writing, usually a Uniball 207. My favorite notebook is a Leuchtturm 1917, which I sometimes receive as gifts and promptly fill up.
I don’t save old journals. Instead, I usually scan the pages and save them digitally, then burn them.
Then, I eat a small breakfast of some kind. It’s usually a bowl of oatmeal or something else small. On school days, this is usually timed so that I can eat with my kids before they go to school, and then I help them get ready for school.
At this point, Sarah is usually awake (she’s usually gone if it’s a workday), so I’ll brush my teeth, make the bed, take a shower if this isn’t an exercise day, and get dressed. If I’m planning to do some exercise later in the day, I don’t shower until after my exercise routine, but I do put on some deodorant.
After that, I take a second cup of coffee and my full water bottle into my office and then meditate for fifteen minutes. I turn on some kind of mellow audio, usually this, and do a really simple mindful meditation where I just focus on my breathing for fifteen minutes. I basically just close my eyes and pay attention to the in and out of my breathing, doing my best to keep my focus on that, and if I notice my mind wandering, I gently bring the focus back to my breathing. This not only calms me down and helps me focus, it trains my ability to focus.
I take a big gulp of water along with a couple daily vitamins and then start off with my work launchpad to start working for the day. After that, it’s off to the races.
I know some people will ask about the vitamins. I eat a vegetarian diet that’s often pretty close to vegan, mostly for health reasons. With that kind of diet, there are some nutrients that are in short supply. You can get most of these missing nutrients if you make sure to eat an extremely wide range of fruits and vegetables each day, but I know that even if I make an effort to do so, I’m probably missing the target. So, I take supplements to cover those seven things that I might be missing: vitamin B12, vitamin D, long-chain omega 3 fatty acids, iodine, iron, calcium, and zinc. These are mostly covered by a multivitamin and an oil pill. I do not believe that people on a full omnivorous American diet need to take vitamins regularly.
That’s the routine I follow most mornings. I start at about 5 AM and I’m usually working by about 7:30 AM.
Here’s the thing: I’ve found that if I do this, I end up having achieved far more with my work by the mid afternoon than I do on days where I don’t do this and just start at 5 AM or if I sleep in and start at around 7:30 AM with no routine. Furthermore, I feel like I have a lot more left in the tank when I stop working for things like family time and evening activities and housework and exercise and hobbies and community commitments. I also feel like I’m genuinely building better behaviors and becoming a better person, both in terms of my conscious choices and in my head in an unconscious way. I haven’t ever taken direct statistics on this, but I’d be willing to bet that my actual work productivity and my housework productivity is somewhere around 20% to 30% higher on days that I do this even with the first hour or two used by this routine.
Why does that happen? My entire morning routine is about “sharpening the axe,” to paraphrase a quote often attributed to Abraham Lincoln. Lincoln supposedly said, “Give me six hours to chop down a tree and I will spend the first four sharpening the axe.” The idea here is that preparation makes the time you actually invest in a task much more efficient and effective, often reducing your overall effort and usually increasing your productivity. If I view everything before 1 or 2 PM as my “work time,” the two hours I invest in “sharpening the axe” makes the other hours much more productive, usually resulting in more overall productivity, plus I feel better and more able to tackle the other challenges of my day when I’m done.
I tinker with this routine fairly often. I used to do more direct visualization of a good day and less journaling, and I used to exercise in the early mornings. What I found over time was that, for me, the stretching fulfilled the mental awareness I really wanted in the early morning and that a workout later in the day when I was starting to fade in terms of my professional work really primed me for family time and other commitments later in the day. So, I exercise after work now, most of the time. I also discovered the benefits of meditation (helping to clear and calm my distracted mind) and journaling (helping to clear my mind and clarify things I’m struggling with).
Sometimes I fall off of this routine, and when that happens, I usually coast on the inertia for a week or two with good results. However, I eventually start to become less and less productive and less in less in tune with myself and I feel generally out of whack and overwhelmed with work. This routine is incredibly worth the time investment for me, so when I fall out of that routine because of other life urgencies, I make it my goal to get back to the routine as quickly as I can.
I don’t expect anyone to adopt this exact morning routine. Rather, I hope you’ll mine it for ideas for things that will work for you. Go through these things and try some of them out for yourself and see how they work. I highly recommend a thirty day challenge of trying new things for yourself just to see if they click with you. Sticking with something for thirty days allows you to see the benefits of repetition without making something that isn’t quite working seem like an endless slog that you’re committed to.
Good luck!
The post A Look at My Morning Routine appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2LUDaXb
5 Things To Know Before Getting a Credit Card: Get the Most Out of Your Choica
If you don't use credit wisely, it's easy to get into bad situations that can have long-lasting effects. Consider these points before opening a credit card account.
Source CBNNews.com https://ift.tt/2LtKJIq
Source CBNNews.com https://ift.tt/2LtKJIq
Trump's Trade Triumph
The media and other Trump haters can't seem to let themselves admit it, but Donald Trump scored a big victory for the American economy on trade last week.
Source CBNNews.com https://ift.tt/2vccvhy
Source CBNNews.com https://ift.tt/2vccvhy
The Death Of The Fiduciary Rule: What No Fiduciary Rule Means for You
The Fiduciary Rule that compels all financial advisors to act in your best interest has been struck down. Discover how this affects the advice you receive.
Source CBNNews.com https://ift.tt/2OlUKoJ
Source CBNNews.com https://ift.tt/2OlUKoJ
What’s a Kindermoon? Something You Don’t Need to Spend a Bunch of Money On
My daughter’s face lit up, and after the commercial ended, she declared, “Mommy, I want a kindermoon!”
I didn’t even know what a kindermoon was.
For those just as clueless as I was, a kindermoon is similar to what a honeymoon is for newlyweds looking to celebrate the beginning of their married lives. Or what a babymoon is for a couple who plan a trip to spend some memorable alone time together before their tiny human is born.
A kindermoon is a special getaway in that sense, but its purpose is to mark a child’s impending entrance into kindergarten.
And Disney found a perfect way to capitalize on a kid’s transition to elementary school — by promoting an expensive trip to one of the costliest theme parks in the country.
A Disney blog post from 2016 advertised a two-day, three-night kindermoon package for a family of three for $987. A similar current promotion (though it’s not tagged as a kindermoon) starts at $1,009. Fantastic, right?
Now, I’m all for celebrating your children’s milestones. Your preschooler starting kindergarten is a big deal. And I’m not anti-Disney. I took my daughter to the Magic Kingdom near Orlando the week before her third birthday. Penny Hoarder tip: The park doesn’t charge admission for children under 3. We had an awesome time.
All I’m saying is you don’t need a grand vacation at a theme park (or to spend all your savings) to celebrate your little one officially achieving big-kid status.
You could plan a special parent-kiddo outing. Take your kid to a cheap movie and then go out for lunch afterwards. Or take your child to dinner. Several chain restaurants have designated nights where kids eat for free, or practically for free. Some promotions are for the entire day, not just evenings.
You could host an end-of-summer barbeque with family and friends to celebrate. Invite loved ones who have children in elementary school, and ask the kids to share their first-day-of-school stories with your child. Ask the adults to bring clothing or things their kids have outgrown to save on what you’ll need to buy for the upcoming school year.
Or since you’re going school shopping anyway, shop without your kiddo and then wrap the goodies up and surprise your child with them. You could even arrange some sort of scavenger hunt. Hide the clothes in the closet, the book bag near the bookshelf and the lunch box in the kitchen.
It doesn’t take an extravagant trip to please a 5-year-old. If your kid is anything like mine, all he or she really needs to feel special is some undivided attention and a big dose of love.
Unless kindermoons really become a thing — let’s hope that they don’t — your children won’t be missing out if you don’t plan one. But if you still want to go the Disney route, here’s some advice from a Disneyland employee and tips from a regular Disney visitor on how to save while you’re there — plus info on what freebies you can score.
Nicole Dow is a senior writer at The Penny Hoarder.
This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.
source The Penny Hoarder https://ift.tt/2uVARN6
الجمعة، 27 يوليو 2018
President Trump Delivers a Stronger Economy as Promised
If the economy does grow more than 3 percent for the entire year, it will be something of a milestone, in that it will be the first time since 2005 that we've seen that growth rate.
Source CBNNews.com https://ift.tt/2uVq8m1
Source CBNNews.com https://ift.tt/2uVq8m1
Save money using recyclable coffee cups

News of Starbucks’ new 5p disposable cup fee may spark a groan among coffee connoisseurs and frappe fanatics alike.
Edmund Greaves and Francesca Bloor
Despite the government’s proposed ‘latte levy’ proving unsuccessful, many coffee shops have voluntarily decided to introduce a charge on disposable cups in an attempt to reduce waste.
There are, however, some money-saving schemes that have also been introduced in order to reward environmentally-friendly customers who bring their own reusable cups. Here are the details for some of the big coffee chains:
Caffe Nero recyclable cup discount: Double reward stamps towards a free coffee
Caffe Nero doesn’t have a discount per se, but it will give you two loyalty stamps for each coffee you get in a reusable cup instead of the normal one per coffee.
A spokesperson for Caffe Nero says: “Caffè Nero is a signatory of the 2016 Paper Cup Manifesto, a cross industry public commitment recognised by the Department for Environment and Rural Affairs (DEFRA) to increase the sustainable recovery and recycling of paper cups. We will continue to work with fellow members of the Paper Cups Recovery & Recycling Group (PCRRG) to understand and address the current issues which prevent the widespread recycling of paper cups.”
- Flat white price with a recycled cup: Buy five flat whites with a reusable cup for an overall cost of £13.75 (£2.75 each) to get your sixth free, meaning each one effectively costs £2.30 – a 45p per-cup saving.*
Costa recyclable cup discount: 25p
Costa offers a 25p discount on all hot drinks if you provide your own cup. It states: “Through our nationwide in-store recycling scheme we have recovered over 12 million cups for recycling since February 2017.
“To encourage our customers to use reusable cups we already offer a 25p discount, which we will be further promoting this year.”
- Flat white saving: £2.45 discounted from £2.70.*
Department of Coffee and Social Affairs recyclable cup discount: 10%
Department of Coffee is a small chain with shops based in several major UK cities. Typically its prices are higher than those of the big chains as it serves ‘speciality coffee’ – or coffee with a higher quality grade than is typical for bigger competitors.
It gives customers a 10% discount if they bring in their own cup.
- Flat white price with a recycled cup: £2.70 discounted from £3.*
Pret a Manger recyclable cup discount: 50p
Pret offers a 50p discount on hot drinks for those who bring in a reusable cup. This came about after Pret’s chief executive, Clive Schlee, tweeted in November 2017: “How do we encourage customers to bring reusable coffee cups to @Pret? We’re thinking of increasing the discount for bringing your own cup from 25p to 50p. Our organic filter coffee would cost just 49p. I’d love to hear your thoughts.” Based on the feedback he got, Pret boosted its discount.
- Flat white price with a recycled cup: £1.95 discounted from £2.45.*
Starbucks recyclable cup discount: 25p
Way back in 1998 Starbucks introduced a 10p discount for those bringing reusable cups, which was raised to 25p in 2008. In 2016, it trialled a 50p discount but a spokesperson for Starbucks says the scheme wasn’t a success: “We found that this did not move the needle in the way we thought it might.”
As of July 2018, Starbucks has introduced a 5p charge for customers who buy their drink in a disposable takeaway cup, instead of bringing in a reusable one. The decision followed a trial in 35 London stores, which saw a 126% increase in customers bringing their reusable cups and claiming the 25p discount.
- Flat white price with a recycled cup: £2.40 discounted from £2.70.
*Prices based on visiting a central London branch.
Section
Free Tag
Related stories
Source Moneywise https://ift.tt/2LqXinG
Cheesecake Factory Is Doubling Up With 50% Off Slices This Monday
It’s thick. It’s rich. And frankly, it’s amazing!
There are two kinds of people in this world: those who love cheesecake and weirdos.
For the first group, this Monday could be magical. To honor National Cheesecake Day, everyone’s favorite purveyor of this decadent dessert, The Cheesecake Factory, will offer half-priced cheesecake slices on July 30! To make the deal even sweeter, the chain will also be unveiling two new cheesecakes: Very Cherry Ghirardelli Chocolate and Cinnabon Cinnamon Swirl.
Standard menu pricing for a slice of cheesecake at The Cheesecake Factory is $8, which may seem pretty steep before you taste it. But the slices are huge, and their flavor combinations are a steal at $4.
The offer is good for one slice per guest and dine-in only. But before you groan at the rules, check this out: I called my local Cheesecake Factory to ask about the rules, and learned you don’t even have to order a meal. You can stop in just to have dessert!
Though you don’t have to order a meal, I do recommend a nice glass of wine to pair with the cheesecake. It’s OK. You deserve it.
Think of the possibilities. You could go classic with a slice of original cheesecake. You could feed your chocolate cravings with the Godiva chocolate cheesecake. You can even go guilt-free with a slice of low-carb original or low-carb original with strawberries. You have nearly 40 options to choose from on its tantalizing cheesecake menu.
Call your friends, make a date with your spouse or significant other, or just treat yourself to a solo date. It’s a treat we all deserve.
Tyler Omoth is a senior writer at The Penny Hoarder who loves soaking up the sun and finding creative ways to help others. Catch him on Twitter at @Tyomoth or snarfing down a slice of cheesecake around Tampa, Florida, this weekend!
This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.
source The Penny Hoarder https://ift.tt/2LrqyuC
How to Turn Your Business Idea Into a Startup Company
Ideas are a dime a dozen. Everyone has them.
Some ideas are great, and others could be improved.
As an online marketer, I’ve heard countless business pitches from prospective entrepreneurs over the years. While I admire their creativity, just coming up with an idea alone is far from having a viable business concept.
If you are ready to put your idea to the test and launch a startup company, I encourage you to read this guide.
Your idea needs validation.
The last thing you want to do is launch a new business and realize six months down the road that it wasn’t a good idea. By this point, you’ve already sunk too much time and money into the venture.
Don’t skip any steps in the startup process.
Here’s what I’ve done. I’ve outlined how you can take an idea and turn it into an actual business. I’ve tried to keep this guide as general as possible so that it can speak to the widest audience of entrepreneurs.
For example, some businesses will need to buy or lease retail space. Other brands will need production equipment or partnerships with manufacturing facilities.
Some of you may even need permits and have to meet certain legal obligations before your launch. I stayed away from going into depth on these types of details.
That said, this is an excellent reference for anyone with a business idea and no experience launching a startup.
Even if you’ve been part of startup launches before, this guide can help you avoid some mistakes you may have made in the past.
Write a business plan
When you approach your new business venture without a plan, you increase your chances of failure.
The odds are already working against you since such a large percentage of new startup companies fail.
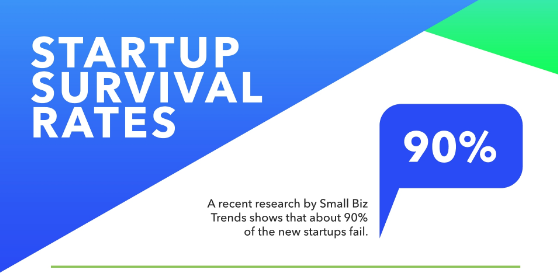
You need to do everything possible to try to give yourself an advantage and increase your chances of success.
Here’s a pretty common conversation I have with entrepreneurs. They pitch me an idea and follow up with something like, “Wouldn’t that be a great business?”
My honest answer is I truly don’t know. And they don’t know either.
Many ideas sound good when they’re verbalized. But when it comes to the logistics, finances, and other important details, the idea may not be as good as you initially thought.
That’s why you need to learn how to write a business plan for your startup company.
Your business plan will help you tremendously and ultimately increase your chances of succeeding.
Startups with a business plan have a 29% greater chance of securing funding, which we’ll discuss in greater detail shortly. Writing a plan also increases the chances of business growth by 50%.
These are the common components of a business plan:
- executive summary
- description of the company
- market analysis
- competitor analysis
- organizational structure
- details about products and services
- marketing plan
- sales approach
- budget and funding
- finances
Your plan will outline everything you need to do, even if your idea is very simple. For example, let’s say you’re planning to sell shirts.
How are you going to sell them? Where will you sell them? Whom will you sell them to? At what price will they be sold?
You’ll explain in detail your costs to produce the shirts. The business plan will even outline when you plan to break even on your investment.
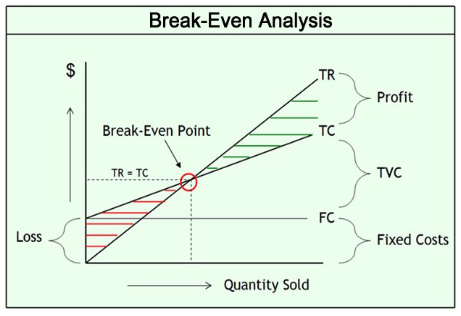
The financial projections section is arguably the most important part of the entire plan.
You need to come up with realistic numbers. In addition to listing all your expenses, you need to project your sales.
This information will help you determine if your new business can generate money. You’ll be able to come up with price points so you can turn a profit.
Again, you must figure all this out before you open the doors of a new business. It starts with proper planning.
Define your target audience
The idea for your new business might sound good, but for whom is it a good idea?
Whether you have a product, service, invention, or modification to an existing product, you need to clearly define whom you’re selling to.
I hear people say all the time:
“Everyone will like this idea.”
This is simply not true. Plus, from a marketing perspective, it’s unreasonable to try to launch a brand intended for everyone.
Imagine trying to come up with promotions that appeal to men, women, and children of all ages from every corner of the world. It’s not a realistic approach.
You need to learn how to identify the target market of your startup.
Start with broad assumptions about your prospective customers, and narrow it down even more.
Begin with factors such as their ages, genders, and physical locations. Then get more specific, and identify their interests and lifestyle habits.
Here are some ways for you to segment your audience based on geographic, demographic, psychographic, and behavioral categories.
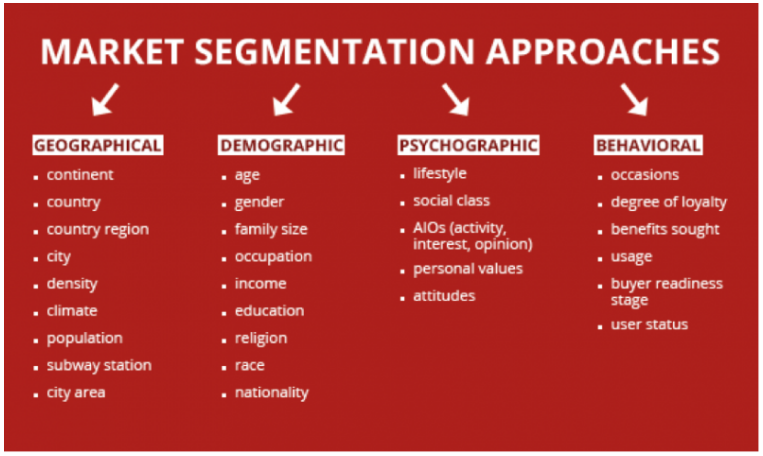
For example, let’s say your product is intended for males between the ages of 25 and 40. That’s still a broad audience.
You can make it more specific by saying you’re targeting males between the ages of 25 and 40, who live in the United States, make more than $60,000 per year, and are interested in fitness.
Do you see the difference? That’s much more detailed. You can develop a customer persona to help you with this process.
Also, you need to look at your target audience from different perspectives. Let’s say you’re launching a startup that sells toys for young children.
That’s not necessarily your target market.
Three-year-old kids don’t buy stuff. You need to target their parents instead. Make sense?
Conduct market research
Now that you have an idea of whom you want to target, it’s time to test that theory. Just because you think your idea is great for a specific market doesn’t mean this is true. You can use:
- surveys
- interviews
- focus groups
- beta testers
- product samples
You need to get out there and talk to people. Validate your idea.
It’s also necessary to figure out who else is offering the same thing you are. Today, it isn’t easy to come up with an idea that’s 100% unique.
Don’t get me wrong: it doesn’t mean you can’t make money by having the same idea as someone else. But if the market is oversaturated, it might not be in your best interest to proceed.
I’ll give you a simple example to explain what I mean. Let’s say you want to open a pizza shop in your city.
You’ve scouted out a location that can fit your ovens and tables. You can rent it at a reasonable rate. Your pizza recipe is outstanding. Plus, everyone likes pizza, and more than 100,000 people live in the city.
This idea must be a homerun, right? Not if there are 20 other pizza shops within a few blocks of your prospective location.
It’s going to be too difficult for you to compete with a market that’s so saturated.
This is an example on a small level, but you can scale it to any industry. Look at the ecommerce space. There is a huge competition globally.
In addition to niche brands, you’ll also be competing with giants such as Walmart and Amazon.
The number one reason why startups fail is that there is no market need.
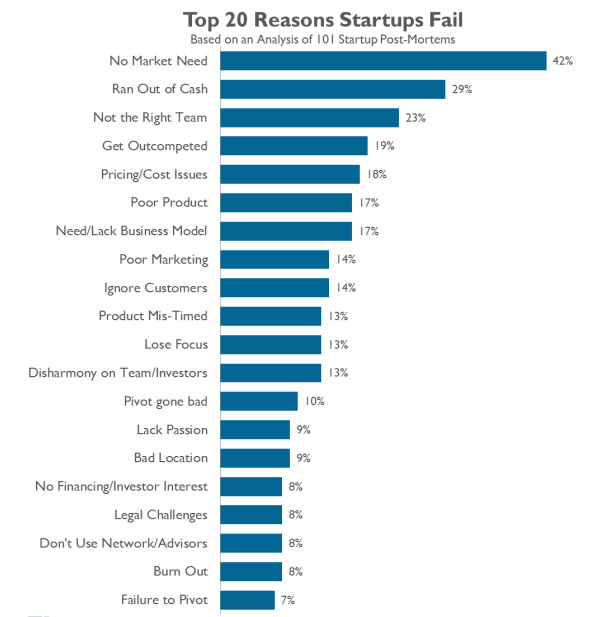
While your idea might be cool, there may not be a need for your product or service.
Or even if the market needs what you’re offering, it could be getting it from someone else already.
Market research will also require you to analyze your competition.
Establish your brand
Your startup company needs to have a differentiation strategy that separates you from your competitors.
What’s your identity?
Your brand may be cool, edgy, and trendy. Or maybe you’re going for a brand identity that is conservative and family-oriented instead.
Some startups launch with a mission to help a greater cause, such as a nonprofit organization.
No matter what your brand identity is, it needs to be clear to your audience. All of your branding campaigns will reflect the image you’re trying to portray.
Your website colors, marketing campaigns, and promotions will speak to your brand identity. This even relates to your logo and the name of your startup.
Come up with a name that doesn’t restrict your growth. Even if you’re focusing on something specific right now, you don’t want the name of your brand to put you in a box, preventing your expansion in the future.
Your brand needs to speak to your target audience, which was already defined. A proper branding strategy will nurture your brand reputation.
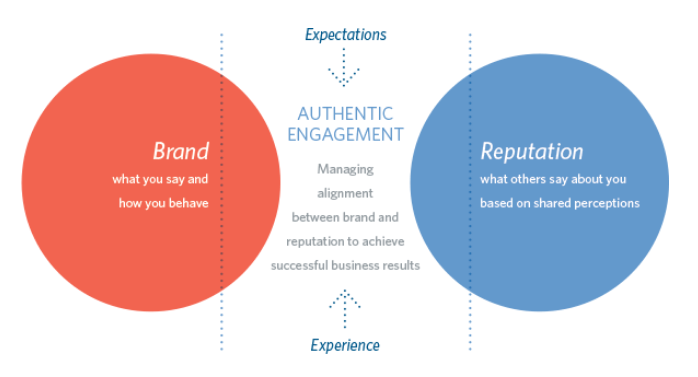
In a perfect world, your brand image and brand reputation will be the same. You want people to see your company in a positive light.
So it’s important to get your branding strategy right the first time because your reputation is going to stick with you for years to come.
It’ll be hard to rebrand yourself in the future if you make a mistake during the launch stages, so don’t rush into anything.
Surround yourself with the right people
It’s time to assemble your team.
The size of your team will vary based on the type of business you’re launching.
You want to find people strong in areas where you are weak. For example, if you’re extremely creative but don’t have managerial skills, it doesn’t make sense to bring another creative mind on board without hiring someone who can manage employees.
Or let’s say you’re building a mobile app but don’t have any experience with coding or design. You’ll need to hire a developer and designer.
Surround yourself with people whom you are compatible with. You want to build strong working relationships with your team.
Here’s another problem I see all the time. People launch a startup and just start hiring their friends and family.
Don’t get me wrong — this can work. But you need to think long and hard about this decision. Do you want your personal relationships to be impacted by the business?
Can these people take directions from you? What if you need to fire your best friend?
These are all sticky situations, so tread carefully. You also need to make sure every member of your team can bring something to the table.
Just because you were bouncing ideas off a friend a few months ago doesn’t mean they’re part of the business.
I’m not saying you need to be selfish or stingy, but ultimately, you need to do what’s best for you and your business.
Secure funding
Your startup will need some money to get off the ground. Depending on what you’re doing, this can range anywhere from a few thousand dollars to millions of dollars.
Everyone’s situation is different. You’ll need to recognize all your business costs. Here are some examples to consider:
- research and development
- equipment
- cost of property to buy or lease
- website and server
- inventory
- insurance
- legal fees
- payroll
- startup costs
- operating costs
You need to realize you won’t have any income when you first launch, but you’ll still need to cover all your expenses.
Based on this information, you’ll be able to determine how much money you need. Learn how to get your startup funded.
Use your business plan and financial projections when you’re speaking with prospective lenders or investors.
You may consider getting a bank loan and pay interest fees for the funds you borrow. But big banks may not be your best bet. Just look at these approval rates for small business loans:
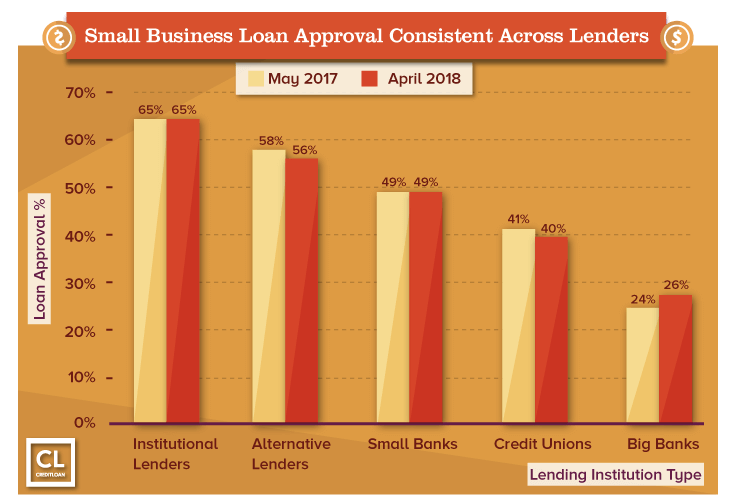
For your startup company, you may want to consider some alternative options:
- venture capitalists
- angel investors
- personal savings accounts
- friends and family
- crowdfunding
These are all reasonable sources to raise capital to launch your startup. You’ll just have to consider these options and decide which ones are the best for your scenario.
Figure out if it’s worth giving up equity in your company. Will your investors bring anything else to the table besides cash?
While it may be nice to have other opinions, you want to make sure you have the final say in all decisions. There is nothing wrong with giving up some equity, but just don’t lose control of your company.
Build hype before you launch
Everything is falling into place.
Your business plan looks good. The target market is clearly defined. All your market research is complete.
The team you assembled is qualified. All of your funds have been secured.
Now it’s time to put your company branding strategy to work.
Buy a domain name. Launch your website. Create social media profiles.
Start to market your brand. Even if you’re not officially launched or selling anything just yet, you can still take pre-orders.
Create a blog. Try to get featured on press releases or news articles. Send free samples to influencers.
Do anything that will make your presence known. Get creative with guerilla marketing and content marketing strategies.
Be prepared to work
Before you officially launch, you need to ask yourself if you’re ready to work.
Sure, you know your idea is great and it’s been validated through your research. But are you ready to take the plunge into entrepreneurship?
Just look at how many hours the average entrepreneur works per week:
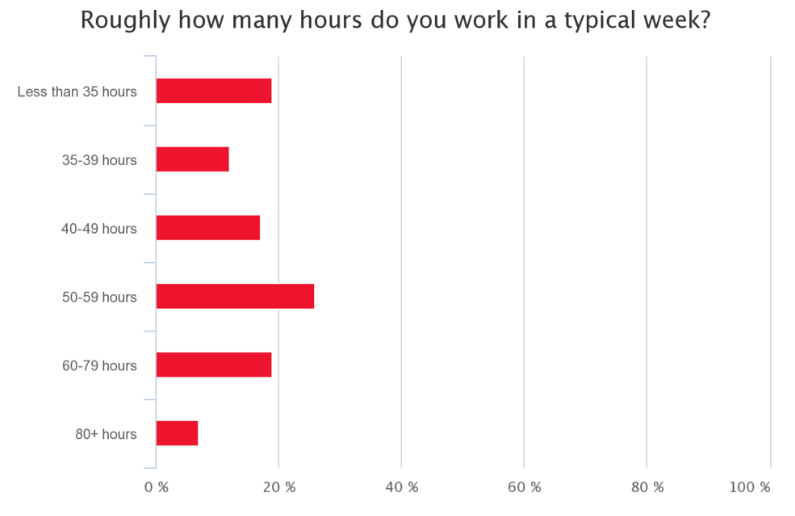
In order to launch your startup, you might be leaving a job with a steady paycheck to work twice as hard on your new business, without being able to pay yourself for years.
Is this something you can handle mentally and financially?
Research shows 41% of entrepreneurs say they feel stressed almost every day. An additional 33% say they feel stressed a couple of times per week.
But only 7% of entrepreneurs say they never feel stressed.
Unlike with a regular job, there’s no quitting on your own business. You can’t call in sick when you don’t feel like working.
You’re the boss. You set the tone for the entire culture of the company.
While being your own boss definitely has lots of benefits, it also comes with added responsibility and plenty of sleepless nights. You need to recognize that your startup can still fail.
I’m not saying all of this to discourage you from following through with your plan, but you need to accept this reality.
But if you’re willing to take these risks and get to work, proceed with your business plan, and make it happen.
Conclusion
There is a big difference between an idea and an established business. You need to take steps to validate that idea before you launch a startup company.
Write a business plan. Identify your target market. Conduct market research.
Then you’ll need to come up with a branding strategy.
Assemble your team. Surround yourself with people who can contribute to the success of your new business.
Recognize your costs and outline your financial projections. This will give you a better idea of how much money you need to launch your company.
Being an entrepreneur can be rewarding, but it’s no walk in the park. You need to ask yourself if you’re capable of being a business owner.
But if you’re ready to work and you’ve taken the steps I’ve described in this guide, you can turn your business idea into a reality.
What steps have you taken to turn your concept into a startup company?


Source Quick Sprout https://ift.tt/2LQDeHA
Why It’s Crucial to Start Saving for Retirement Now
One of the main reasons that people choose not to start up their 401(k) (or 403(b) or TSP or other such plan) at work is because they’re simply overwhelmed by all of the options available to them and they’re worried about not choosing the “best” one and losing money. This was a concern I had at my first job when signing up for my retirement plan for the first time, and it was voiced by others in the room during the orientation session. It’s also been a concern noted by many readers over the years. They didn’t sign up because of option overload – they partially filled out the form, then felt overwhelmed by the options, then just sat it aside and took no action on it.
This is a bad move. You are better off choosing almost any investment option and starting to save now rather than putting it off.
Let’s look at two case studies.
Jane is 25 years old. She has her first “real” job and plans to retire at 65. On the first day, she goes in to sign up for her retirement plan and chooses an investment that offers a 7% average annual return on her contributions. She starts contributing $2,600 a year and her employer matches that, also contributing $2,600 a year.
After 40 years of this, when Jane is 65, she’ll have $1.15 million set aside for retirement.
Now, let’s look at Robert. He’s also 25, at his first “real” job, and also plans to retire at 65. On his first day, he goes in to sign up for retirement and balks at the options. He stuffs the forms in his desk and forgets about them. At age 30, he is finally nudged by his parents and wife into contributing to his retirement account, so he carefully studies the options and chooses that same 7% option that Jane chose. He starts contributing $2,600 a year and his employer matches that, also contributing $2,600 a year.
After 35 years of this, when Robert is 65, he’ll have only $800,000 set aside for retirement. Waiting just five years cost Robert $250,000. Another way of looking at it: waiting for 12.5% of his working years cost Robert around 22% of his total retirement savings. That’s a big loss.
There’s almost no doubt that starting now is better than starting later, but what about the fear of choosing a bad investment? Wouldn’t you be better off waiting and doing the research and choosing a much better investment in a year?
Here’s the issue with that: you can do that regardless of whether you’re contributing right now or not. If you start contributing right now and put it in a money market fund – meaning there’s virtually no risk and something around a 2% annual return – you can still make your investment decision a year from now and already have a year’s worth of contributions sitting there. If you don’t do that, you have nothing a year from now. In the case of Jane and Robert, that means they’d have about $5,250 or so ready to invest in something at the end of the first year if they just chose a money market account (with basically no risk) instead of choosing no contribution at all.
So, starting now and contributing to something extremely safe, then choosing a better investment and moving later is better than contributing nothing now, choosing a better investment, and starting later.
Let’s address another common issue that comes up in these discussions: the “market timing” scenario. You’re about to sign up for your 401(k) but you’re simultaneously afraid that the stock market is about to have a 1929 or a 2008 year and drop 40% in value, so you don’t sign up.
In this scenario, the same thing holds true: Just start contributing now and put it into something safe, then move it over when you feel the time is right. By not signing up, you simply miss out on those years of contributions.
However, the idea that you can time the market is a fallacy. As I wrote late last year in Why You Can’t Time the Market: Thoughts on Investing in Stocks:
Do you have a time machine? No? Then market timing isn’t worth it.
You can’t guess day to day where the peaks and valleys of the market are, and if you miss it by much, you’re going to cut enormously into any advantage you might get from market timing. Add into that the fact that you’ll be paying brokerage fees and you’re devoting a lot of time to study, and the disadvantage grows.
The much better approach is to do things passively. Only invest in stocks if you have a goal that’s more than a decade in the future. Buy a broad based index fund (like the Vanguard Total Stock Market Fund) and reinvest the dividends. Then ignore it until you actually need the money. The market will go up. The market will go down. It doesn’t matter.
If you’re not able to actually predict the day to day peaks and valleys of the stock market – and even large scale investors who do this for a living can’t do it really well over a large period of time – then market timing isn’t going to help you. In fact, if you’re very much off the peaks and valleys at all – and as a casual investor, you will be – you’re likely going to do worse than if you just put money in there and didn’t think about it at all.
In other words, for people just signing up for a 401(k), timing the market is a fool’s game that will probably result in losing money.
What about the worry of a “lemon investment”? This is another concern that people often bring up in these situations. They’re concerned that the retirement investment option they choose is a “lemon” with poor returns and high fees.
That’s true – you might wind up in an investment that doesn’t have great returns or might have high fees. That’s still better than contributing nothing. A 6% return on your money when you could have had 7% (by picking a better investment) is still way better than a 0% return on your money when you could have had 6% (by contributing to the lemon).
Furthermore, with almost every retirement account out there, you have the ability to change your investments at any time. If you keep researching and realize you’re in a lemon, you can move your money to a better investment within that account with no tax consequence. Just log in and change it.
In short, if you end up making a bad choice, you can always correct it later, and whatever reduced amount you earned in that investment is better than earning nothing by not contributing at all.
Okay, one final question. What if you literally have no idea what to choose, and that fear keeps you from making a choice?
The first thing I’d do is simply ask the human resources officer or other employee that is helping you sign up for retirement for their recommendation. They’re typically given some basic guidance to help people find a retirement option that’s right for them. Follow that advice for now. Often, this advice will lead you to a “target retirement” fund, which is a solid default choice.
Later on, as you learn more about investing (or you have someone advising you), you (and/or your advisor) can research the investment you’ve chosen as well as the other options available within your retirement account and, again, if you find something that seems to be a better option, you can move at that time.
The moral of the story is this: You are better off saving for retirement right now rather than later, regardless of how you choose to invest that money. If you choose to leave it in cash for a year or two within your 401(k), you’re still better off in the long run than doing nothing at all. If you put it all into stocks and the stock market bottoms out next year, you’re still better off in the long run than doing nothing at all. If you put it into an awful investment and don’t figure it out for a few years, you’re still better off than doing nothing at all.
Why? Because even after all of those potential issues, you still can’t beat the sheer power of saving for retirement early and letting the power of compound interest work in your favor for as long as possible. The only way to do that is to start now.
If you have a retirement plan at work that you haven’t signed up for, do it today. Don’t wait. Start the contributions now, even if you can afford very little. If you don’t have a retirement plan at work, sign up for a Roth IRA and start contributing, even if you can afford very little. Make moves in your life (like adopting frugality or paying off debts) that will allow you to bump up those contributions as soon as possible. That way, you’ll be as ready for retirement as you can possibly be, and that’s one less little piece of background stress on your shoulders as you move through the many years of your life.
Good luck!
Related Reading:
- The Snowball Effect of Retirement Savings
- The ‘Perfect’ Investment
- How Do I Even Start With Saving for Retirement?
- Don’t Let These Fears Stop You From Investing
The post Why It’s Crucial to Start Saving for Retirement Now appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2NRAYRc
Compare broadband, phone & TV packages
- Lowest Prices
- Compare & save £200 +
- See deals in your area
Image

CTA
Legal
Terms & Conditions apply
Section
Source Moneywise https://ift.tt/2LFDOLy
8 Tips for Anyone Who’s Counting the Minutes Until Their Next Paycheck
And people with low incomes aren’t the only ones struggling. About 1 in 10 workers surveyed who said they earn six figures or more reported living paycheck to paycheck.
Breaking the paycheck-to-paycheck cycle is never easy; if you plan to try, you’ll have to take a hard look at your mindset and habits.
8 Ways to Break the Paycheck-to-Paycheck Lifestyle
“Money Girl” host Laura Adams outlines tactics for breaking the paycheck-to-paycheck cycle in the episode “8 Tactics to Stop Living Paycheck to Paycheck.” By saving even a small amount each month, you can achieve greater financial security and finally feel less stressed about money.
1. Acknowledge the Problem
If you’re not saving money, you’re one emergency away from financial disaster. Your first step is to figure out why it’s so hard for you to save. Maybe you’re overspending, or perhaps you need a side hustle because your paycheck barely covers your bills. Once you figure out the “why,” you can change your habits to start saving money.
2. Stop Worrying About Your Self-Image
When you obsess about looking successful, you risk living a lifestyle you can’t afford. No amount of material goods will make you happy. Focus on yourself and your goals, and find ways to fill emotional voids that don’t require spending.
Another pro tip: Learn to say “no.” Repeat it whenever someone pressures you to overspend or distracts you from your goals.
3. Track Your Spending
If you want to have cash left over from your paycheck, you need to track everything you spend. There are tons of tools that you can use to track your spending, including budgeting apps, Google Sheets and Excel. Or you could take the old-school approach to budgeting by documenting each transaction in a paper notebook.
4. Focus on Your Biggest Expenses First
If you’re living in a home you can’t afford or drive a car that’s beyond your budget, you’ll probably never stop living paycheck to paycheck, no matter how much you cut the smaller stuff.
Try to avoid spending more than 20-25% of your gross income on rent or your mortgage, even if that means you need to downsize by finding a smaller place, get a roommate or move in with family. Your car payment shouldn’t eat up more than 10% of your gross budget, so consider a cheaper ride or alternative transportation if you’re paying too much.
5. Re-evaluate Your Debt
By refinancing your home or consolidating your credit card debt, you could save big bucks on interest. Adams’ Online Loan Comparison Chart can help you compare your lending options.
6. Set Up Automated Savings
Automation is your friend when it comes to saving money. You’ll be less tempted to spend money when you save it before you have the chance to touch it.
If you contribute to a workplace retirement account like a 401(k), you’ve already automated savings because contributions can only be taken out of your paycheck. Consider setting up automated transfers to an individual retirement account (IRA), 529 savings plan for your child’s education or a savings account.
7. Find Ways to Earn More Money
Sometimes cutting expenses isn’t enough. If you need to make more money, consider getting a second job, working extra hours at your primary job or taking on a side hustle. There are tons of ways to earn extra money, such as driving for Uber or Lyft, grocery delivery, taking online surveys, and more. Or, perhaps it’s time to make the case to your employer that you deserve a raise or promotion.
8. Focus on Future You
It’s frustrating when you feel like your paycheck never goes far enough, but change takes time. Focus on where you want to be in the long term — think five, 10 or even 20 years down the line. By thinking about the big picture, you can set smaller goals that will help you get there someday.
Listen to the full podcast for the full eight tips on breaking the paycheck-to-paycheck cycle, plus find bonus tips for saving on your electric bill from The Penny Hoarder’s Lisa Rowan.
Robin Hartill is a senior editor at The Penny Hoarder.
This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.
source The Penny Hoarder https://ift.tt/2JZ2ZUx
US Economy Surges to 4.1 Percent Growth Rate in Q2, Best Showing Since 2014
The U.S. economy surged in the April-June quarter, growing at an annual rate of 4.1 percent. That's the fastest pace since 2014, driven by consumers who began spending their tax cuts and exporters who sought to get their products delivered ahead of retaliatory tariffs.
Source CBNNews.com https://ift.tt/2mLLC05
Source CBNNews.com https://ift.tt/2mLLC05
We’re in College. We’re Newlyweds. We’re So Broke. Where Can We Turn?
Getting married is challenging. Being young and newly married — even more so.
I got married three weeks into my freshman year of college. Not long after, I sauntered into my old high school feeling pretty invincible. Look at me: I am an adult, married lady. I swung by my favorite biology teacher’s room to chat, and when he asked how we were doing, I made an offhand comment about being broke.
He stopped sorting student papers and looked at me squarely. “The money will be tight for a while,” he said. He told me a few details from when he and his wife were starting out, when their kids were young. He didn’t make any comments about how old I was or why I had gotten married so soon after high school. He just leveled with me about how hard it can be to make ends meet in a young marriage.
So if everything feels impossible for you right now, it’s probably because it kind of is. So many of us are not prepared to be fully functioning adults when we leave home. And then you have to be a functioning adult in the same house as another newly functional adult? It’s ripe for conflict.
Filing for bankruptcy at 20 is probably not a viable option. But applying for government assistance can be a huge help for you during this time when you’re juggling health issues along with the pressure to earn as much money as possible.
You may be eligible for SNAP, the benefit formerly known as food stamps. The government assistance program is designed for working adults with limited assets. You can even apply for SNAP online in many states, so you don’t even need to talk to someone to ask for help.
You could also consider dropping down to half-time status at school. You can usually retain financial aid if you’re taking at least six credits each semester, although school rules vary. It may take longer to complete your degree, but reducing your course load for a semester or two could bring extra peace of mind while you determine the best way to figure out work schedules and medical needs with your husband.
Asking for help is hard, but asking for help now can set you up for greater stability in the future. This is not a time to hide your fears about your finances from family members, friends, and most importantly, each other.
If you don’t talk about what’s worrying you, it’ll eat away at you both.
Lisa Rowan is a senior writer at The Penny Hoarder.
This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.
source The Penny Hoarder https://ift.tt/2mNJsNK
الاشتراك في:
الرسائل (Atom)