Thousands of courses for $10 728x90

الخميس، 2 أغسطس 2018

The Wisdom of Frugality: The Environmentalist Case for Simple Living

wisdom of frugalityThis is the seventh entry in an eight-part weekly series that provides a detailed look at the book The Wisdom of Frugality by Emrys Westacott. If you’re new to the series, feel free to hop back to the first entry.

This chapter of The Wisdom of Frugality takes direct aim at one of the biggest benefits often cited for living a simpler frugal life: it’s environmentally friendly. A frugal person, as the argument goes, uses far less resources than an affluent person and thus puts less of a strain on the global environment. Many people carry this concept forward and use it as a big part of their moral justification for frugality.

Historical Background

This part might not seem relevant to frugality, but bear with it.

Prior to the Industrial Revolution, there was no need for people to be concerned about the environment. The individual actions of humans in a pre-industrial society did not add up to nearly enough to cause environmental damage on a scale that could consistently cause significant and widespread harm.

Nature was seen as a wild force for man to exploit. It was far beyond the ability of man to control it or interfere with it in any significant way; rather, man found ways to accentuate the benefits of nature and minimize the negative impact on human life.

Over the centuries, humans gradually developed technologies that allowed them to exploit more and more of the earth’s resources, eventually leading to the Industrial Revolution and widespread exploitation of those resources.

Alongside the Industrial Revolution, a backlash of sorts arose in the form of Romanticims, which lauded natural untamed landscapes and distrusted artificial things. This eventually developed into a broad tradition, with people like Henry David Thoreau rejecting many aspects of technology and eventually growing into the modern environmental and political movement.

The Environmentalist Argument for Frugality

Frugality and environmentalism find a great deal of overlap because of similarity in tactics. Both of them find a great deal of value in minimizing one’s use of the Earth’s resources and getting as much value as possible out of the resources that we do use.

The idea of “reduce, reuse, recycle,” for example, is as much at home with an environmentalist as it is with a frugal person. Both will seek to get as much value out of things as possible, but for somewhat different core reasons. The environmentalist wants to reuse and reduce in order to minimize their impact on the Earth, while the frugality wants to reduce and reuse in order to minimize the expense.

The specific tactics that both groups use in their daily life tend to match up really well, too. Strategies like using less water, consuming fewer manufactured goods, using less electricity, and finding low impact things to do with one’s time are strategies that both frugal people and environmentalists share, even though they may be doing those things for different reasons. Often, frugal people and environmentalists are on the same page with broader initiatives in the community, like having an effective mass transit system, which lowers overall environmental impact (great for the environmentalist) while also lowering individual cost (great for the frugal person).

Objections to the Environmental Argument

However, a great deal of synergy in tactics doesn’t add up to full agreement. While there may be some overlap between the beliefs and tactics of the environmentalist and the frugal person, there isn’t perfect alignment.

First of all, ecological impacts are often difficult to articulate and evaluate. Things like biofuels and rechargeable batteries might seem to be environmentally friendly on the surface, but the full picture of their environmental impact often isn’t nearly as clear cut. For example, rechargeable batteries often require some very environmentally unfriendly practices and materials requirements to manufacture, for example. They may be frugal, but are they environmentally friendly? It’s a bit harder to tell for sure.

This is true for larger strategies that might seem like great synergy between frugality and environmentalism. Is it more environmentally friendly to install solar panels on your home than to keep buying from the grid? What about the manufacture of those panels – what kind of impact does that have? Figuring that out becomes very difficult, whereas crunching the numbers to determine the cost-effectiveness of such a choice is much more cut and dried.

The thing to remember when being skeptical of ecological impacts of individual choices is that it’s good to be skeptical of the individual practices, but recognize that the overall principle – reduction of environmental impact – is a good one.

The second issue to consider is the fact that simple living isn’t always green living. A great example of this came from the “burn barrel” we had when I was growing up. We didn’t have trash service and the only real option for trash removal was to haul it to a dump that was many miles away, so instead we had a “burn barrel” – an old barrel that my dad picked up somewhere – in which we burnt our trash. When the barrel became full of ash (and with a few unburnt items in there), then we’d pay to have it hauled away. It was far cheaper than actually having trash service, but far less environmentally friendly.

In retrospect, the environmental cost of services out in the country where I grew up was much higher than it would have been in the city. The environmental cost of running power lines, water lines, roadways, and other such services to us out in the country was enormous. Furthermore, to have access to other services, like grocery stores, we had to drive quite a few miles.

The idea of “simple living in the country” is really only environmentally friendly if you decide to completely go without a lot of basic services. Some people in rural areas do eschew a few services that people in urban or suburban areas might expect (such as speedy internet), but people in rural areas do expect an awful lot of the basic services that all Americans expect, like drivable roads, drinkable water, and so on, and those services have a pretty big environmental footprint when they’re offered in rural areas.

Another great example of how the frugal option isn’t always the most environmentally friendly option is the choices faced when buying fresh produce. Local, organically produced items are going to have a lower environmental impact than produce that came from a factory farm several thousand miles away… but the local organic produce is going to be more expensive because the factory farm methods squeeze a lot of cost out of the system.

How does a person decide what the right choice really is? It’s not an easy decision no matter what you choose. There ends up being several reasonable choices when it comes down to balancing various environmental factors, and often the “best” choice ends up being influenced by other factors like health benefits, the impact on the local community, and so forth. Often, this best choice does not end up being the least expensive choice, which can put a price conscious person at odds with an environmentally focused person.

Furthermore, it can be argued that the choices of individuals make no real difference. The actions of governments and corporations will make the real difference, not individual frugal choices. The things I do in my daily life have very, very little impact on the environment compared to the impact of large scale agricultural businesses and manufacturing businesses.

This is the reasoning that many people use for individual poor behavior. “I can’t possibly make an impact,” goes the logic, “so it doesn’t matter what I do.” Thus, people excuse their own unethical and damaging behavior.

The thing is, individual actions multiplied many times can make an enormous difference. Consider, for example, a community that has limited water in its reservoir that agrees to some general water use rules within the town. If everyone chooses to conserve a little, everyone has enough water for their needs. An individual person isn’t going to be able to fix the water issue through severe cutbacks or non-use, nor is that individual going to be able to singlehandedly drain the reservoir, but when lots and lots of individuals agree to limit their water use to merely meet their needs rather than all of their wants, there ends up being enough water for everyone to meet their needs.

This pops up over and over again. When people agree to use restraint when utilizing common resources like water and wood and other such things, there’s enough for everyone to have their needs and sometimes their more important wants met. If individuals assume they have no impact and then uses the resources recklessly, then simple arrangements where everyone has their needs met can never occur and some will be left without needed resources.

When lots of people take little steps, economies of scale kick in. For example, if everyone in America gave a single dime toward a cause, that cause would suddenly have $30 million dollars. Little efforts are only small when they’re seen in isolation – if they’re repeated by everyone and looked at from a distance, they appear enormous.

Another counterpoint is the idea that our best hope for fixing the environment lies in technological innovation.. Many of the tools that we have for keeping our environment healthy come from technological innovation – solar panels (and their steady improvement), wind power, algae power, tidal power, tools for environmental cleanup, and so on. As powerful as frugal living can be, it can’t fix the damage of the past and it can only somewhat alter our trajectory going forward. Technology has the capacity to fix our past mistakes and radically alter our path going forward.

The problem is that technological innovation, as it’s happening, often has a huge environmental impact itself. It can take a ton of resources to go from whiteboard idea to something that works, and that first version that works is usually very rough and takes a long time to refine. In other words, development of the technologies that we really need to make things better is going to require some significant short term environmental impact, and there’s not even a guarantee that those technologies will help. Furthermore, other technological innovations will likely continue to increase our use of resources while we stumble towards any kind of solution to the environmental impact of that resource use.

Stepping up activities that are causing the problem is illogical. It’s the equivalent of eating more when you’ve just been given a prescription for diabetes medication. Yet it’s essentially a requirement if we believe technology will just fix everything.

Many people hope that this research will happen as a result of the economic booms that have come from the development of earlier research into high-demand products. The reality is that the kind of research that’s done in the wake of a successful product is usually not in solving big societal problems, but in developing a follow-up product. Apple’s R&D department didn’t start trying to solve humanity’s deep questions once they developed the iPhone. Instead, they went to work on the iPhone 2 and the iPad.

Final Thoughts

Most of the arguments that people make in favor of frugality are individual arguments. They look at things purely in terms of the individual – how can I get the most value out of this situation, considering my needs and wants and my financial bottom line? The environmental angle is an attempt to move beyond that individual approach. How does frugality come into alignment with larger societal needs? It happens to line up well with being green.

When you start looking at frugality through the lens of what our moral obligations to others actually are and how we live them out, it’s clear that frugality can be a major part in terms of living out our obligations to our community and the world. If we live a less expensive and simpler lifestyle, we’re left with more resources with which to use to make the world a better place, plus we’re consuming fewer resources ourselves. There are a lot of ways we can use those resources to make the community and the world a better place.

In short, frugality is a powerful supplement to a public service oriented lifestyle. If volunteerism and other forms of public service and public work are a major part of your life and you want to actively work to make the world a better place, then frugality plays a strong complementary role in that because it reduces the amount of time and energy and money you need to commit to meeting your living expenses, which thus increases the amount of time and energy and money you have available to commit to the causes you care about.

There’s another interesting underlying issue in all of this: just because something feels right doesn’t mean that it is right. It might feel “right” (for an example that hits home here in Iowa) to buy ethanol-supplemented fuels, but the significant reduction in fuel efficiency plus the environmental cost in the conversion of plant matter into ethanol means that I’m not convinced that what “feels” right actually “is” right (the jury is still out for me on this one, to tell the truth). It takes a lot of work to move from what “feels” right to what actually “is” right, and that sometimes means giving up on some tightly-held beliefs. That’s a kind of effort that’s in short supply in the world, sadly enough.

Next week, we’ll tie up this book with some final thoughts on the book as a whole and what it means for people practicing frugality today.

The Wisdom of Frugality Series:

The post The Wisdom of Frugality: The Environmentalist Case for Simple Living appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2n5unap

Tame the Lifestyle Inflation Beast Now… or It Will Devour Every Extra Cent


As an entry-level newspaper reporter on a $28,000 salary, I drove an ugly Gumby-green Toyota Corolla with nearly 200,000 miles and just one hubcap. I ate a lot of macaroni and cheese. A couch wasn’t in my budget, so I plopped my brother’s old futon mattress on my living room floor.

I seldom had more than a few bucks left over from my paychecks, so I had no savings, but at least I wasn’t accruing more debt. If I budgeted properly, I’d even have enough for a couple rounds of drinks with friends.

But several years and salary bumps later, my savings remained paltry — and I was still driving the green machine. So where was my extra cash going?

Well, there was the extra $30 a month to have a washer and dryer in my apartment. And the furniture that I gradually put in said apartment. And the takeout food that I substituted for mac and cheese. And the gym membership upgrade. And the drinks with friends that evolved into dinner and drinks.

None of these upgrades sounded like a big deal. But combined, they added up to major lifestyle inflation, and they ate away my potential savings.

What Is Lifestyle Inflation, and When Is It Bad?

Lifestyle inflation, also known as lifestyle creep, happens when your spending increases as your income rises. It does not include those unavoidable increases in your cost of living, like a rent hike or a rise in grocery and gas prices.

Lifestyle inflation is a choice. It happens when you upgrade to a fancier car or apartment because you have more money to spend. Or you start dining out more or buying slightly pricier clothing.

The tricky thing about lifestyle inflation is that it isn’t inherently bad. Lifestyle inflation is the reason I’m not shopping at Forever 21 at age 35. It’s the reason I have a real couch now. It’s the reason I was able to take on a car payment and send my old Corolla to scrap-metal heaven.

The danger of lifestyle creep comes when you don’t have long-term goals. Without a plan, you’re more likely to spend extra money mindlessly. You’ll stay broke even as the numbers on your W-2 soar.

7 Ways to Avoid Lifestyle Inflation

The good news is, by establishing priorities and good habits now, you can fight excess lifestyle inflation later.

1. Learn to Live Within Your Means While You’re Still Broke

If you’re in college or working in a low-paying job, just being able to pay your bills without taking on more debt is a win. Focus on spending no more than you bring in, so your future earnings won’t be eaten up by debt payments.

You might be surprised by how much a little grocery strategery can save you on food. Making small changes at home can add up to huge savings on utility bills.

2. Create a Budget ASAP

Accounting for every dollar you spend now will help you make smart decisions about how to allocate extra money in the future. Are you a budgeting novice? It’s OK — this easy guide to budgeting will get you started.

3. Spend More Money (but Only in Your Head)

How would you spend an extra $5,000? Maybe you’d pay down student loans, save more for retirement or sock it away to use toward a down payment on a home.

Imagining how you’d spend cash you don’t actually have may sound like a futile exercise in daydreaming — but identifying what you want now will help you decide what long-term goals to focus on. And having goals will help you avoid mindless spending when you actually have more cash in hand.

4. Got a Raise? Congrats, but Figure Out What You’ll Actually See

OK, suppose that $5,000 raise becomes reality. Nice! But hold on before you pop open the bubbly. Do you know how much of that money you’ll actually see?

First, calculate how much extra you’ll pay in taxes. Pro tip: Figure out how much you’ll owe now if you don’t want to pay at tax time, and adjust your withholdings accordingly.

Next, account for inflation — the kind you can’t avoid. As of May, the 12-month inflation rate was 2.8% in the U.S. That means if you were earning $50,000 a year as of May 2017, on average you’d now have to earn $51,400 annually just to maintain your lifestyle.

Also, if you contribute a certain percentage of your salary to your 401(k), you’ll need to account for that.

Once you’ve determined how much extra money you’ll take home, you’ll have a realistic picture of how much extra you can spend.

5. Pretend That Raise Never Happened for Now

Sure, you could spend that extra money on a pricier apartment. And if that’s your long-term goal and you can afford it, go for it. But maybe your ultimate goal is to buy a house. That’s when you might want to keep up the frugal habits you developed when you were broke, so you can save the extra money for a down payment.

Avoiding lifestyle creep is especially important if you’ve got credit card debt or student loans. Putting extra money toward what you owe will have a huge payoff, because you’ll save on interest payments.

Stashing extra income in a retirement account now, instead of spending it, is also a great way to build wealth. For example, if you’re 20 years old and put $5,000 in a Roth IRA now, it could be worth $180,000 by the time you’re 65, even if you never contribute another cent.

6. Ignore What You See on Instagram

Scroll through Instagram and it seems like everyone else just bought a five-bedroom house and spends their weekends sunbathing on a yacht in Martinique. But sometimes, avoiding lifestyle inflation is as simple as focusing on your own goals and ignoring everyone else. You know your goals, your budget and your values. You never know whether there’s a financial mess behind the fabulous lives you see.

7. … but Treat Yourself (Within Reason)

Fighting lifestyle inflation doesn’t mean you never get to treat yourself. You’ve put in hard work to score those raises or earn extra income. So if you can afford it, go ahead and take a vacation or splurge on a piece of clothing occasionally. Celebrating the wins can keep you focused as you strive toward your goals.

When Is Lifestyle Inflation OK?

Like I’ve said, lifestyle inflation isn’t a bad thing when you have a long-term plan. Here are a few examples of when it makes sense to let your lifestyle inflate.

Your needs change: You don’t want to automatically start blowing extra money on rent just because you can afford to do so. But when your needs change — say, you’re preparing to start a family and need more space, or you have a new job that you want to live closer to — it’s reasonable to consider spending more.

You’re spending on a long-term goal: Remember when I told you to imagine how you’d spend money you don’t have? If you’ve finally saved enough money to make that happen, you have permission to stop daydreaming.

You’re investing in yourself: When spending extra can help your professional development, or it’ll make you happier and healthier in the long term, it’s worth considering. If you’re starting your first real job after college, it probably makes sense to invest in a real adult wardrobe. Taking on a car payment might make sense if driving an old, not-so-faithful car is a constant source of stress.

We’ll even give you a pass to order takeout or have your groceries delivered if that little bit of lifestyle inflation means you have extra time to invest in your side hustle.

Robin Hartill is a senior editor at The Penny Hoarder.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder https://ift.tt/2LRFrpD

How do you rate your providers?

Moneywise Home Finances Awards 2018

  • £500 cash prize for one lucky winner
  • £100 shopping vouchers for five others
  • Free copy of Moneywise for the first 10,000 participants


Image

CTA

Legal

Section


Source Moneywise https://ift.tt/2O5JY5j

Secondhand Clothes from a Personal Stylist: I Tried ThredUP’s ‘Goody Box’ Service

Whether or not you enjoy shopping for clothes, sometimes a little assistance for time-saving or style-shifting purposes can be helpful. Until recently, companies that specialize in new apparel such as Stitch Fix and Nordstrom’s Trunk Club have cornered the online personal shopper market. The basic process works like this: You create a profile detailing your budget, style, and fit needs, and a stylist sends you a box full of clothing, accessories, and shoes for a fee. You choose the items you want to keep and send everything else back within a designated timeframe.

I’ve been intrigued by the concept, but as someone who keeps her wardrobe to a minimum, likes to host clothing swaps, and generally shops resale stores wherever possible to cut back on supporting the throw-away, fast-fashion industry, I’ve been hesitant to try such subscription crate services.

Enter ThredUP’s new customized “Goody Boxes,” and an excited me.

ThredUP’s Goody Box: New-to-me, just-for-me

ThredUP, the largest online thrift store, has been in the secondhand business for almost a decade. The company used to deal only in one-to-one buying and selling, but recently debuted its online customized curation program: the Goody Box. Instead of a getting a crate full of new clothes chosen by a personal stylist, you receive an array of custom-picked secondhand fashions.

The process will sound familiar. After setting up a profile, you have the opportunity to include additional notes to your stylist; I asked for no leather or fur, and wrote that I tend to wear a lot of black and would appreciate some bright color options. You can also share more details about your style by favoriting items currently available on the site, or by linking to a personal Pinterest board.

Right now, the fee for the service is $10, but it’s technically a non-refundable deposit: You receive $10 in credit toward whatever items you decide to keep. Once a box arrives at your doorstep, you have seven days to try everything on and return what you don’t want. ThredUP includes an itemized sheet that lists each piece and its price, along with a free USPS return label. They’ll also send you multiple reminder emails about the return deadline, so you don’t accidentally get stuck with everything if you don’t want to add all of it to your wardrobe.

I ordered my first box last month, and a second box immediately after receiving my first, and here’s what I found.You

You can get high-quality secondhand goods online.

My biggest worry about buying secondhand items online concerns quality. As a resale shopper, I’m used to rigorously checking every inch of each item I want to buy, and I still sometimes bring home pieces that are more used than I first expected.

And if I’m honest, while the ThredUP site is clean and user-friendly when it comes to filtering for sizes, colors, price, and the like, the photos of the clothing aren’t the most appealing. The clothing is secondhand… and it shows. It’s often floppy, wrinkled, and doesn’t quite fit the display mannequins. You only get two photos of each item, typically front and back, and the descriptions are fairly minimal.

However, all the clothing I received in my two Goody Boxes was in good shape — no tears, holes, stains, weird markings, or otherwise heavy use. A few items I received were brand new with the original tags still in place. I’ve also watched a handful of Goody Box unboxings online, and while some people had concerns with sizing and style, only one person complained about a quality issue. It’s given me more confidence in purchasing one-off resale items, at least from ThredUP.

I loved the element of surprise.

I don’t typically like a lot of surprises, but the possibility of finding something completely unexpected and perfect for me is one of the reasons I love resale shopping. Others may find digging through disorganized racks at their local Goodwill, Arc, or consignment shop tedious (like my husband), but the hunt has always been part of the appeal for me.

I was giddy when my Goody Box arrived, and I dove in with a treasure-hunting attitude. You can choose a theme for your box, such as “9 to 5 Styles,” “Take Me Out Outfits,” or “Tropical Getaway,” if you’d like a little more control, but you can also pick the “Just for You” custom mix and let your stylist go wild (or classic, or boho, or whatever you ask of them). As thredUP co-founder and CEO James Reinhart admits in a letter sent with my first box, “We know we won’t get it all right all the time,” but their mission is to “inspire a new generation of consumers to think secondhand first.”

When it came to my boxes, Reinhart’s quote hit it on the button. I did receive some of the brightly colored items I requested, but I also received two leather purses, a leather skirt, and a petite-size dress for my 5-foot 7-inch body. They went straight back into the box, and when they asked why I was returning these items, I made sure to let them know. (It is worth noting that a few weeks after giving this feedback to thredUP, the company sent me a “Second Chance” email. It explained that they had noticed I didn’t love many items in my box, and if I was willing, wanted to give me a deposit-free opportunity to try another. I get that they want to sell more product, but I did appreciate that someone noticed — and, of course, I said yes.)

The cost is low.

While ThredUP does charge that non-refundable, $10 upfront fee for its Goody Box service, you do get the 10 bucks back as a discount if you keep and spend at least that much on an item.

In the box, you get about 15 items in minimal packaging — each priced to fit the “ budget per item” cost you choose when you sign up. I selected the lowest possible, $20-$40, which seemed high to me, until I realized it’s really just a guide. About half of the designer label clothing and accessories I received came in around $12 an item. I felt like most of the prices were comparable to those I typically find at a locally owned boutique consignment shop I frequent.

A big cardboard box, cheery polka dot tissue paper, and some bubble wrap is the extent of what you’ll find around your nicely folded items — all of which you can reuse when packing up for returns. Shipping is free, as are returns, which are processed through the U.S. Postal Service. You’re not required to commit to a subscription plan, so you can order as many or as few times as you like, on your timeline.

Compared to Stitch Fix, which charges a creditable $20 stylist fee for items that average $55 apiece, or Trunk Club, which sends items in the $100-to-$300 range and charges a $25 creditable stylist fee, ThredUP’s Goody Boxes are a consignment-shop caliber bargain.

The impact is potentially high.

No, I don’t anticipate that a Goody Box will change your life. The impact I’m referring to here is the environmental one — which, of course, you can contribute to simply by buying secondhand locally or online. The Goody Boxes just offer another way to access the resale market and make an impact on the world around you.

“Fashion is the second-most polluting industry in the world surpassed only by petroleum,” wrote Emily Farra in Vogue last fall. “Basically, when you buy something old and previously-loved, you’re extending its lifespan and reducing its carbon footprint. Picking up brand-new clothes all the time (and disposing of them just as quickly) drives demand for nonstop manufacturing, which contributes to the fashion industry’s incredible waste.”

Cheers for more options.

Related Articles

The post Secondhand Clothes from a Personal Stylist: I Tried ThredUP’s ‘Goody Box’ Service appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2vw95pU

Get Paid to Hang Out With People: What It’s Like to Work for RentAFriend

الأربعاء، 1 أغسطس 2018

3 MoviePass Alternatives for Anyone Who’s Bitter About the Latest Changes


My mother always said: “All good things come to an end. And then they come back. And then they come to an end again.”

It looks like Mom was right because this week, MoviePass made headlines again as it announced a price increase that will — fingers crossed — keep it from going bankrupt.

Now that the popular movie ticket subscription service has placed more restrictions on its offerings, we thought it would be good to compare MoviePass and its competitors to see if it’s time for you to say “hasta la vista, MoviePass!”

The Latest MoviePass Changes

New Price: $14.95 per month

MoviePass prices will increase to $14.95 per month in the next 30 days, a press release announced Tuesday.

The original allure of MoviePass was the ability to see any movie at any time for $9.95 per month. Now you’ll still get access to one 2D movie per day, but blockbuster movies will have limited availability during the first two weeks of their releases. No one really knows what that means, but MoviePass did state that special promotions could open up availability for certain movies.

3 MoviePass Alternatives for Big-Screen Lovers

I’m sad for MoviePass because people really love it. Even with the $5 per month increase, its Twitter supporters have come out to say they’ve saved money and will continue to subscribe — which makes you think this whole thing could’ve been avoided.

But since we’re here now, let’s explore the other options.

Sinemia

Price: $12.99-$34.99 per month

Sinemia has two tiers: Classic and Elite. In the Classic tier, you can choose one or two movies per month. It includes any 2D movie anytime — even opening weekend. There are no blackout dates, and advance ticket purchasing is available (something MoviePass has always lacked).

The Elite tier includes everything from the Classic with the addition of 3D movies and one Imax-4DX movie every 30 days.

Elite and Classic family plans are also available.

Sinemia is having a summer sale right now: The one movie per month Classic plan is starting at $3.99 per month. Two movies for two people each month is $15.99 per month during the sale. If you decide to forgo an annual plan and pay monthly, you’ll have to pay a $19.99 initiation fee per person.

You can also book movies through third-party ticket processors like Fandango, Atom Tickets or MovieTickets.com if you’re looking for reward points.

AMC Stubs A-List

Price: $19.95 per month

You can see up to three movies every week in any format with no blackout dates.

AMC Stubs A-List will even let you see all three of those movies in one day. And they can all be Dolby Cinema, Imax, 3D or whatever combo you can feasibly stomach.

There’s a three-month minimum commitment, but your price is locked in for 12 months.

The A-List also includes advance ticket reservations, 10% cash back on food and beverage purchases, and its Stubs Premiere benefits, which include free drink and popcorn upgrades.

Benefits reset every Friday morning.

The glaring disadvantage is that the program is only good at AMC theaters, so if you’re not near one, it won’t help you see cheap Prime, RealD or BigD movies. (I’m still figuring out the difference between them.)

Cinemark Movie Club

Price: $8.99 per month

Probably the best program on the list for light moviegoers, but again — not useful unless you live near a Cinemark theater.

For less than $9, you get one 2D movie ticket every month, 20% off concessions for you and friends, waived online fees and extra tickets for $8.99 each. And if that isn’t enough, unused tickets roll over, never expire for members and are usable for up to six months if you need to cancel.

It’s limited to 2D movies, but you can add premium upgrades like Imax and 3D for an additional charge.

Jen Smith is a staff writer at The Penny Hoarder. She likes seeing movies but probably wouldn’t go more than once a month. She gives money-saving and debt-payoff tips on Instagram at @savingwithspunk.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder https://ift.tt/2O31WVX

MadTime Fitness puts women first

TANNERSVILLE — For Madeleine Southern, fitness and nutrition have always been a passion, but throughout her career she noticed the field has not always been welcoming to her and other women.Southern, and her fiancé John Besser, set out to change that and created MadTime Fitness in Tannersville to offer women in the region their own alternative fitness center.“I found working at gyms that for a lot of women, when you walk in it's huge and it can be [...]

Source Business - poconorecord.com https://ift.tt/2OBRXbe

Pack Your Bib: Reynolds Wrap Will Pay You $10K to Travel and Eat Barbecue


Let’s just get straight to the point on this one, because a job this tasty needs little preamble.

Travel the country for two weeks. Gorge yourself on the best barbecue money can buy. Document your experience. Get paid $10,000.

Yes, you read that right. And no, it’s not a trick. Reynolds Wrap is searching for its first ever Chief Grilling Officer.

As Chief Grilling Officer, you’ll be responsible for hitting cities across the country known for mouth-watering barbecue to sample the goods. You’ll learn about grilling culture, as well as tips and tricks and new techniques in the grilling world. Then you’ll share your newfound barbecue wisdom and some nice photos on the company’s social media accounts and the Reynolds Kitchens website.

Sounds easy enough, right?

The CGO will be paid thousands of dollars for two weeks of what can’t be called “work,” and Reynolds Wrap will foot the bill for all of the travel and lodging. That means you can spend that cool $10K on whatever you please.

And if free travel, delectable barbecue and a boatload of cash aren’t enough to entice you, the Chief Grilling Officer also gets to bring a friend along on this journey of sauce-filled discovery.

It might only be a temporary job, but you’ve got to admit it’s a pretty sweet one — or should I say savory?

How to Become the Reynolds Wrap Chief Grilling Officer

Ready to jump in the pit and get your hands greasy?

The only qualification you need for this gig is a devotion to grilled food — and a willingness to be in a constant state of meat sweats for two weeks.

Even more good news: The application process is very easy.

All you have to do is type up 100 words on why you’re the best candidate for this role and snap a picture of your favorite grilling recipe. If you’re a barbecue fanatic, you were probably already going to whip up something on the grill this week anyway.

Send your application to ReynoldsCGO@gmail.com by August 13.

And if you’re the lucky carnivore that snags this coveted role, here’s a tip from one barbecue lover to another: Pack more wet wipes than you think you’ll need. And then pack some more.

Kaitlyn Blount is a staff writer at The Penny Hoarder. She’s already had the best barbecue in the country, and it’s from The Brick Pit in Mobile, Alabama. Don’t @ me.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder https://ift.tt/2O1OuSc

$33 Trillion: The True Costs of Government-Run Health Care

It's long been a dream of liberal Democrats: a government-run health care program that covers all Americans, and Vermont Socialist Senator Bernie Sanders has proposed such a plan, called "Medicare for all."

Source CBNNews.com https://ift.tt/2n0ZOT1

Keep Your Budget Cool This Summer With 6 Tricks to Beat the Heat

How to Increase Profits by Focusing on Customer Retention Strategies

There’s a common misconception that businesses need to acquire new customers if they want to make more money.

Getting new customers is obviously beneficial and can help your business grow. But that’s not the only way to boost your profits.

Focusing on customer retention is a much more viable and cost-effective marketing strategy.

In fact, it will cost you six to seven times more money to acquire a new customer than it will to retain an existing one.

Not only is retention cheaper than acquisition, but it also has a very high ROI. Research shows that you can increase your profits anywhere from 25-95% just by increasing your retention rates by 5%.

Imagine how much more money you’ll make if you increase those retention rates by 10% or even 20%.

Don’t get me wrong: I’m not saying you should completely ignore your acquisition efforts. But if you are looking for ways to market your company on a budget, it’s in your best interest to focus on your existing customers.

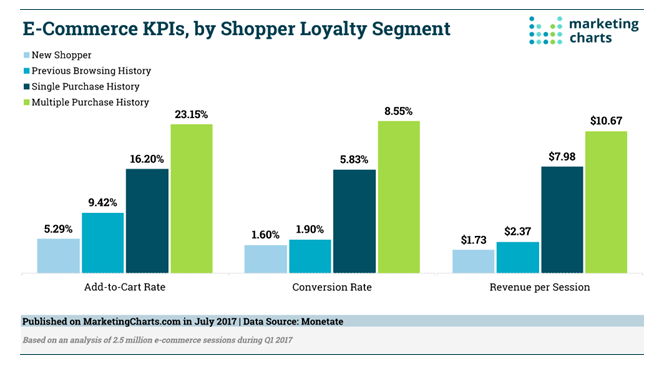
Take a look at these loyalty statistics for ecommerce brands:

loyal shopper

As you can see, customers who have made multiple purchases with a brand have a higher add-to-cart rate and conversion rate than new shoppers.

These customers also generate more than six times the revenue per session than new shoppers.

So it only makes sense that you should be prioritizing these customers.

I’m sure you’ve heard this age-old proverb: “A bird in the hand is worth two in the bush.”

You’ve already got these customers in your hand. Don’t risk losing them by putting all your effort into customer acquisition.

I’ll show you the best ways to increase profits with customer retention.

Leverage your blog to establish loyal readers

Most people may not associate blogging with customer retention. But blogging overall is one of my favorite content marketing strategies.

In addition to helping you increase website traffic and generate new leads, blogging can also help you engage with your loyal customers. This is especially true for ecommerce brands.

Ask yourself this question.

How often does the same customer visit your website?

I’m guessing you’re not getting repeat purchases from the same customer on a daily basis.

But if you’re releasing new blog posts each day, or even a few times per week, you give your customers a reason to keep checking your website.

Hook these readers with your content. If they use your products and read your blog, your brand will be on their minds more often.

Plus, the more they visit your site, the greater chance you have of getting them to buy something else. This strategy is extremely cost-effective.

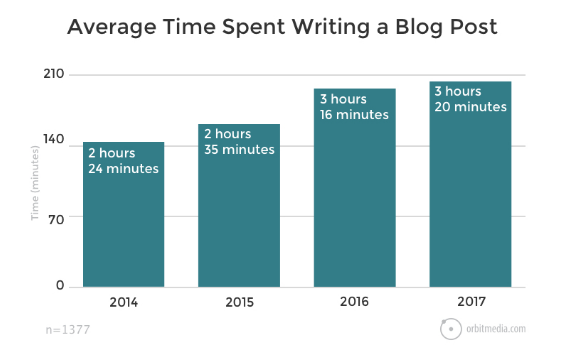
The only major cost is the time it takes to write each post. In 2017, the average time it took people to write a blog post was just over three hours.

blog post

It’s well worth your time and effort if you’re able to leverage this strategy to create loyal readers and retain your existing customers.

Use surveys and interviews to get feedback

In order for you to properly focus on retention, it’s important for you to understand what causes customers to leave a business.

Research shows 68% of consumers leave a business because they don’t feel the brand is valuing them.

Only 14% will leave because they’re unhappy with your product or service. And 9% of customers leave because of your prices.

What does this tell you?

Customers care significantly more about how they’re treated than the products and prices of what they’re buying.

One of the best ways to show your customers how much you care about their opinions is by asking them directly. You can use surveys and interviews to generate more revenue for your business.

This strategy accomplishes a few things.

First, it shows customers you care about them, which we already established. But the results of these surveys and interviews can also help you make your business better.

If you’re doing something wrong or your brand could use some improvement, you’ll find out from these campaigns.

Once you’re able to identify what needs to be fixed, customers will be happy to see these changes get applied.

This type of service enhances the customer experience, which I’ll elaborate on in greater detail shortly.

Implement a customer loyalty program

The name says it all. The purpose of establishing a customer loyalty program is to create loyal customers.

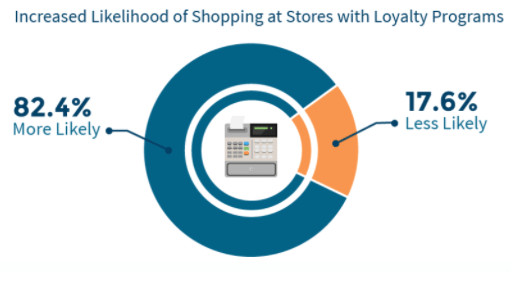
Research shows that consumers are much more likely to shop at stores with loyalty programs.

increase chances of shopping

Give your customers what they want.

There are many different ways to approach your loyalty program. For example, you can reward your customers based on how often they shop.

These types of programs have been around forever, and I’m sure you’ve participated in them during your life.

A local pizza shop in town may give out punch cards to their customers. After ten visits, they get a free pizza.

But with the advancements in technology, this type of “punch card system” has evolved. Businesses with mobile apps have been able to eliminate the need for customers to carry a physical card. We’ll discuss mobile apps in greater depth as we continue.

If your business operates online, you can track your customers’ purchases through their profiles.

Another type of loyalty program rewards your best customers. For example, let’s say two customers each made a purchase from your store ten times in the last six months.

Should they both be rewarded equally?

If one customer spent $100 and the other customer spent $1,000, it makes sense to reward the customer who spends more money.

You can implement a customer loyalty program with various spending tiers. Each time a new customer reaches another level, they’ll receive a more significant benefit.

This strategy gives your existing customers an incentive to spend more money since they know they’ll be rewarded. As a result, it will be much easier to retain these customers.

Grow your email list

Another great way to focus on customer retention is through email marketing.

ecommerce email

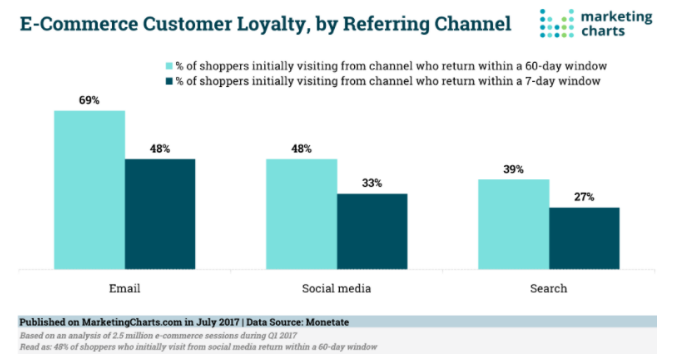
As you can see from this chart, email yielded the highest results for customers who return to ecommerce websites compared to other referring channels.

You should be collecting email addresses from your current customers.

Once you have their email addresses added to your list, you’ll be able to send them exclusive offers and promotions.

This will increase the chances of them buying again. They won’t not be making repeat purchases so frequently if you aren’t reminding them of these offers via email.

Just don’t go overboard with these messages, or it could backfire.

Don’t send promotional content to your subscribers on a daily basis. This will annoy them and lead to lots of unsubscribes from your list.

Instead, only send content that adds value to their lives. For the most part, you can’t go wrong with a discount. It’s a great way to drive sales from your existing customers.

Incentivize customer referrals

Most businesses would consider customer referral programs as an acquisition strategy.

While I’m not disputing that, I want you to understand that they can also double as a retention strategy if you set them up properly.

The whole idea of a referral program is to get your current clientele to bring in new customers. But most people won’t do this out of the kindness of their hearts.

Sure, they might like your brand and be happy with your products, but do they love you enough to go out of their way to spread the word to their friends and family?

That’s why you need to offer an incentive for referrals. Check out this example from Airbnb.

airbnb

It’s a simple structure. Customers who refer their friends will receive a $20 credit after the person they referred books a trip.

So yes, they’re getting a new customer. But their existing customer also has a reason to make another purchase since they want to take advantage of their credit.

The more people they refer, the more money they’ll receive in travel credits.

You can implement this same type of referral structure to your business. It will reward your customers for their efforts and give them a reason to continue making purchases in the future.

Offer product suggestions

You should be encouraging your customers to create a profile on your platform.

This will help you personalize their shopping experience. Personalization has major benefits to consumers and brands alike.

These customer profiles will allow you to monitor their purchase history and browsing behavior.

Now you can use this information to recommend products to your customers.

product suggestions

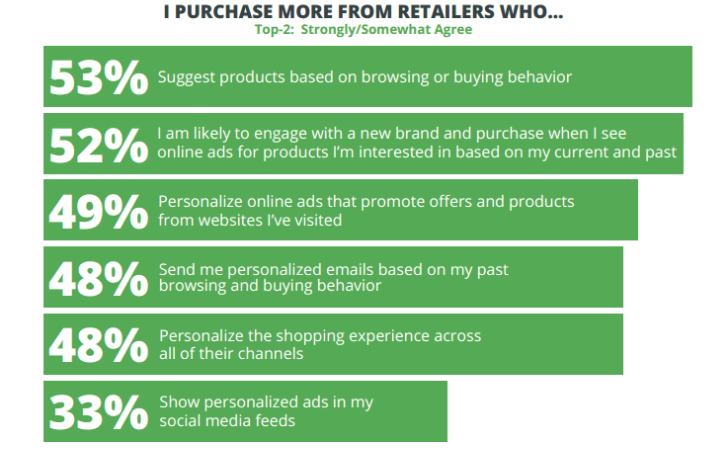
As you can see from these numbers, consumers are more likely to buy from brands that suggest products based on their purchases and browsing behavior.

Nearly half of consumers say they purchase more from retailers who personalize their shopping experience and send personalized emails.

These product suggestions are a great way to make more money. For example, let’s say you have an ecommerce store that sells sporting goods.

If a customer adds soccer cleats and a soccer ball to their shopping cart, it’s a pretty good indication that they’re playing soccer.

So before they checkout and complete the purchase, you could recommend shin guards, soccer socks, and a water bottle as potential suggested items they might be interested in buying.

This will help increase the average amount of each transaction.

Provide excellent customer service

I briefly touched on this subject earlier when we talked about using surveys and interviews to get feedback from your customers.

But excellent customer service goes far beyond that.

This needs to be a priority for your business. Customer service needs to part of your overall company culture.

From the CEO all the way down to the employees at the bottom of the organizational chain, everyone needs to know how to treat customers.

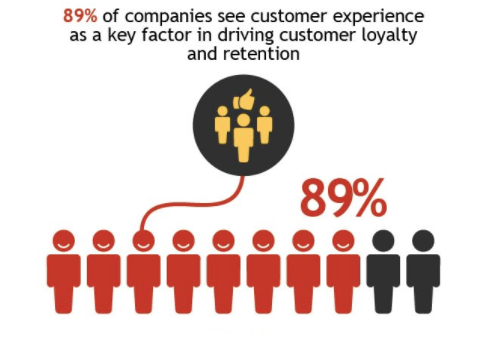
Improving the customer experience will help you drive loyalty and retention.

customer experience

Make sure you’re available to help your customers.

Let them reach out to customer service agents via as many methods as possible:

  • phone
  • email
  • live chat

Just because your business operates from 9 AM to 5 PM EST on Monday through Friday doesn’t mean your customer service hours end then.

What if a customer on the West coast has a question on Friday at 6 PM local time? Don’t make them wait until Monday morning to call you.

Give them options. Go the extra mile to keep your customers happy.

According to studies, 86% of people say they are willing to pay more money for better customer service.

That’s right. You could charge more for your products and services if you treat your customers the right way. They’ll still keep coming back to buy more.

Segment your email list

Earlier I explained that you need to add subscribers to your email list.

Now I’m telling you to take that strategy one step further. You need to segment your subscribers to maximize your email campaigns.

There are plenty of ways in which you can do this. For example, you can put them in lists based on their age, gender, or location.

You can even segment your target audience with generational marketing.

Putting your email subscribers on separate lists helps you deliver more personalized content to each person.

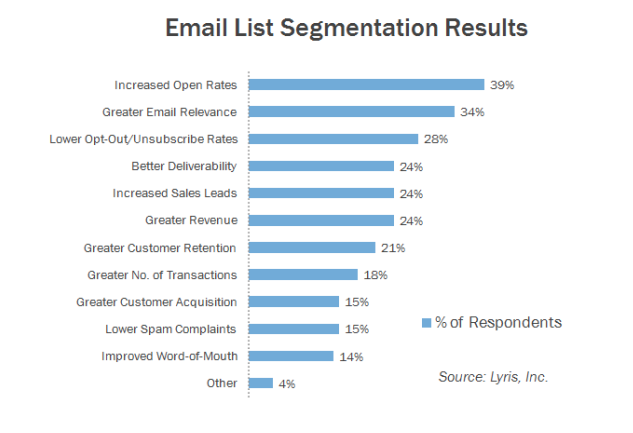
Take a look at some of the top benefits of email segmentation:

email segment

If you go through each one of these benefits, you’ll notice they all translate into one common result.

All of these will help you generate more profits.

Develop a mobile app

We live in a world where mobile technology has seemingly taken over.

When was the last time you saw someone without a cellphone?

Building a mobile app can have tons of benefits for your business.

As I explained earlier, an app can replace a physical customer loyalty card. You can also use your app to implement other strategies I’ve discussed, such as a customer referral program, product suggestions, and a platform for customer surveys.

Furthermore, you can use your app to improve your customer service. Allow app users to contact a representative directly from within the app.

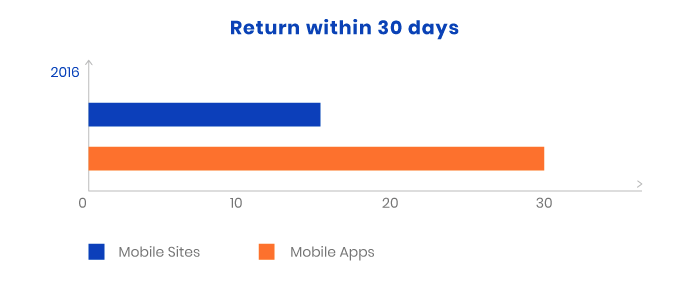
As far as retention goes, mobile apps create a 50% greater chance that an ecommerce customer will return to your online store within 30 days.

mobile app

Mobile apps also have extremely low shopping cart abandonment rates.

The average shopping cart abandonment rate for a desktop site is 68%. When customers add an item to their shopping carts from a mobile browser, that number jumps to 97%.

But with mobile apps, the shopping cart abandonment rate is only 20%.

You can get that percentage down even lower if you follow my high ROI shopping cart abandonment prevention tactics.

Conclusion

New customers aren’t the only way to increase profits for your business. Focusing on customer loyalty is more effective and cost-efficient.

Use your blog as a way to get your customers to visit your website on a more frequent basis.

Show your customers you care about them by asking their opinions with surveys and interviews. Create a customer loyalty program.

Provide incentives to your customers who refer friends and family.

Add customers to your email list and segment those subscribers to personalize your marketing campaigns. Take that personalization one step further, and suggest products based on the browsing history and previous purchases of your customers.

If you enhance your customer service, you can even charge more money for your products and services.

Develop a mobile app to help you implement these strategies and drive more sales.

By prioritizing customer retention, you’ll be able to generate higher profits.

What customer retention strategies does your brand use to drive more sales?


Source Quick Sprout https://ift.tt/2n2EJI7

The Hidden Key to Frugality: Seeing More of the Options

Recently, I was talking to a friend that I hadn’t seen in ages about what we might do if Sarah and I visited them. Naturally, we started talking about sharing a meal.

My friend immediately suggested that we meet and dine somewhere in her area and offered up a handful of suggestions. I looked them up and it turned out that they were all pretty pricy.

I made another suggestion. “Maybe we could just meet in a park somewhere and put together a simple picnic. You can just bring some stuff you have on hand and we can bring the rest. Just tell us what we should bring. We can stop at a grocery store on the way.” To me, this sounded better anyway, as it let us be outside in the nice weather and enjoy the beautiful landscape of a park rather than the ordinary decor of a restaurant. Even better: the cost of such a picnic for all of us was far, far less than any of those restaurant options – and likely cheaper than any restaurant in the area.

This idea had never even crossed her mind. She seemed to love the idea, but it had never even occurred to her to do such a thing. She had simply locked onto a few particular options (mostly expensive restaurants in the area) and chosen from among them.

I’m not here to shame my friend or anything. What she did is something that we all do: we’re trying to solve the so-called “problem of choice.”

What I mean by that is that in any given moment or situation, we’ve got a ton of different choices we can make. If we were to examine all of those choices, we’d never get around to actually making a decision. So, instead, we instinctively rely on some simple rule that we pull out from somewhere inside of us to cut down the options drastically. My friend’s internal rule was obvious: a good friend is coming from out of town and we’re going to share a meal, so let’s go to a good restaurant together so that it’s a simple dining situation and we can focus on conversation.

We make this kind of mental cut-down all of the time. We do it when we’re grocery shopping and see 35 different kinds of pasta sauce, which we quickly trim down to a couple of options. We do it when we’re thinking about what we want to do this evening. We do it when we’re choosing a book at the library.

We’re faced with a ton of options, so many that we can’t really devote adequate time or consideration to each one. Instinctively, we find some way to pare down those choices into a tiny subset, and then we make our choice from that subset.

One of the most powerful things I learned during my transition from being a heavy spender to being a rather frugal person is that altering that instinct of paring down choices was absolutely crucial in living a more frugal life.

My instinct, when I come across a situation with a multitude of choices, is usually to cut off most of the expensive options right off the bat. When a friend comes to town, I don’t even consider a dinner at one of the most expensive places around. When I’m buying pasta sauce, I don’t even consider the stuff that costs several dollars a bottle. When I want to read a new release, I don’t even consider buying it at the bookstore. Instead, I start considering the options that are left. Maybe we could have a dinner at the park, or I could make something at home. Maybe I’ll buy this inexpensive brand that doesn’t add any sugar to the sauce, or this medium-level brand that’s on sale today. Maybe I’ll check out the book at the library, or wait until it’s in paperback, or put it on my Amazon wish list.

That’s my initial instinct, but that instinct did not come naturally. I had to build up that instinct within myself, and it’s really not easy to change that kind of instinct. Here’s how I manage to reprogram those kinds of instincts.

First, I started second-guessing a lot of my choices when I had more time to think about them. I started thinking deeply about my specific shopping or dining or other choices when I was driving my kids to soccer practice or waiting for the dentist or using the bathroom or anything else that didn’t require my mental focus. I’d go back through those situations where I spent money and I’d simply walk through them, piece by piece.

I would try to re-evaluate those situations through the lens of a factor that was really important to me and that I wanted to change in my life, which, at the time, was being a more frugal person. I wanted to make those decisions in a way that was more careful with my money and my time and my energy – but particularly my money. So I would try to re-evaluate the things I had done solely from the perspective of money. Did I do things in the least expensive way possible? Were there other approaches that were less expensive that didn’t bring other problems to the table.

Along with that, and I consider this the most important part, I started intentionally looking for more options than the ones I initially considered.

For example, let’s say that my gut instinct when my friend came to town was to go out to eat at an expensive restaurant and that I initially chose from the three or four best and most expensive places in town because my instinct was to cut the many, many options down to those three or four places. But what if I looked at more options? There are a lot of places to eat within a 30 minute radius of here. There are also many possibilities centered around making food myself.

The question becomes how do I actually filter down all of these options? A good place to start is to ask why I filtered them so quickly down to the three or four expensive places. Well, my reasons there were that I wanted to have a good meal with my friend, one that wouldn’t require me to invest my attention in food preparation when he was around so that I could instead focus on my friend, and perhaps, to a lesser extent, I wanted to impress my friend with my restaurant choice.

So, if my goals really are to have a good meal that we’ll all enjoy, to be able to focus on my friend instead of food preparation, and (to a lesser extent) impress my friend, how can I achieve those things while spending less money? As I noted earlier, why not have a picnic meal at the park? I could choose a park with a great natural view and pack some interesting foods to eat that might surprise his palate. With a picnic, the food prep work is done in advance – we don’t even have to stop our conversation to order food! The location and some nice food choices would serve the lesser desire to impress, such that it is.

What other choices are there that could fulfill those goals? I could make a meal at home that’s largely finished when my friend arrives, with the table already set, and I could just toss the dishes in the sink when it’s done, which would make for a good meal and time to focus on a friend rather than a meal. The “impress” part would come from a decent homemade meal and the openness of my home. I could also seek out a low cost “hidden gem” restaurant in my area, which would definitely cut the costs and perhaps impress my friend with my bargain-finding ability.

What this thinking process does is that it allows me to reset the instinctive “cutting down” of decision making in my mind, moving me to another set of options in common situations. When a friend comes to town now, I usually think of a picnic in the park (as I did with an old friend from Wisconsin just a month or so ago when he and his family came through town) or a simple dinner at my house (as with a visit from another old friend less than a week ago) or a low cost “hidden gem” restaurant (as with an old co-worker a month or so ago). My cut down includes the old desire to be able to focus on the friend, but it adds in the cost constraint and reshapes the desire to impress. That’s now my instinct in those situations.

This type of “reshaping” of my spending instincts takes time and it also takes creativity and assessment of more options than I once considered. I can’t just rely on the expensive instinctive choices that I relied on in the past. Instead, I have to figure out what my real constraints are, then look for options in my life that meet those constraints. The thing is, once I begin to see that there really are a number of options that fit those new constraints, that old instinct starts to fall and the new “instinct” starts to rise. The new choice becomes the automatic one.

If you follow this process with the decisions you make in your life, you will start to reshape your instincts over time. That’s exactly what happened to me as I gradually shifted from instinctively wanting to spend money to instinctively finding other options. When I do find situations where I instinctively want to spend, I put time and thought into rebuilding that instinct in a better way. Again, the challenging part is creativity and thinking about more options than you’re initially considering.

Master your instincts and you master your spending.

Good luck!

The post The Hidden Key to Frugality: Seeing More of the Options appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2AuQsbJ

These Tips Will Help You Stay Fit Safely — and Affordably — as You Age

The Average Credit Score Is Getting Higher

You don’t have to look far to find troubling financial news. Whether it’s excessive student loan debt or an increase in credit card delinquencies, it seems like there’s never any good news coming out of the consumer finance world.

When it comes to credit scores, however, the news is actually quite encouraging. In fact, the average credit score is going up and a surprisingly large number of people have great credit scores.

Both FICO and VantageScore routinely keeps tabs on the country’s average credit scores, also known as a score distribution. According to FICO, America’s average credit score has been trending upward for around a decade. In fact, in 2017 the average FICO score topped 700 for the first time in history. And, according to VantageScore, the average VantageScore credit score is 675, and 35% of its scores are above 760, which is an elite score using any definition.

Why Credit Scores Are Higher

It is not a surprise that the meltdown from a decade or so ago coincided with a drop in average consumer credit scores. In October of 2009 the average FICO credit score in the United States dropped to 686. Prior to the peak of the housing crisis, 18 months earlier in April of 2008, the average FICO score had been 690.

Since the recession, the average score has been steadily climbing upward. Why? There are certainly many factors that contributed to the increase, but the bottom line is credit scores have increased because our collective level of credit risk has improved, and our credit reports are cleaner.

Less Risk = Better Credit Scores = Cheaper Credit = More Disposable Income

Both VantageScore and FICO’s credit scoring models are designed to help lenders and other companies predict risk. The stated design objective of these credit bureau-based scoring systems is to predict the likelihood that a consumer will pay 90 days late or worse on any credit obligation within the 24 months after their score is calculated. That’s called a Performance Definition.

When actions on your credit reports indicate that your level of risk has improved, credit scoring models reward you with higher credit scores. For example, if you previously had late payments on your credit reports, but you’ve been on time with all of your bills for the last few years, your credit scores will climb slowly over time.

According to FICO, the following factors have contributed to the rising average score:

  • Fewer people have serious delinquencies on their credit reports in the last two years. Remember, payment history is the most important component of your credit scores, accounting for around 35% of your score points. With the number of serious delinquencies on credit reports decreasing, it makes perfect sense for scores to be on the rise.
  • Fewer people have minor delinquencies on their credit reports in the past year. FICO considers not only the number of delinquencies on a credit report, but the recency of those delinquencies as well. According to FICO, repayment behavior by consumers has been improving overall.
  • There are fewer collection accounts on credit reports. Normally collection accounts are bad for your credit scores. This drop in the number of consumers with collection accounts is one more reason for the average FICO score improvement.
  • Fewer people are applying for new credit. This is somewhat of a surprise. There are fewer credit pulls from lenders, and therefore fewer “hard inquiries” on people’s credit reports. That equals lower risk, and higher scores.

That’s just the average though — has your credit score risen in the past few years? If you’re trying to improve your credit, here’s a 12-month plan to get your score in good shape, and a trick to give your credit score a quick boost.

Related Articles:

John Ulzheimer is an expert on credit reporting, credit scoring, and identity theft. He has written four books on the topic and has been interviewed and quoted thousands of times over the past 10 years. With time spent at Equifax and FICO, Ulzheimer is the only credit expert who actually comes from the credit industry. He has been an expert witness in over 230 credit related lawsuits and has been qualified to testify in both federal and state courts on the topic of consumer credit.

The post The Average Credit Score Is Getting Higher appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2LFv3BX

The top current accounts for students heading off to university

Students’ credit ratings exposed to housemates’ poor financial choices

Whether you’re a student heading off to university this autumn or a parent or grandparent keen to ensure your children or grandchildren are armed with the best financial start when they leave home for the first time, Moneywise has picked the top student current accounts for all your needs

When it comes to picking the right account, you should consider the benefit of having a nice perk versus the practicality of an interest-free overdraft or in-credit interest.  

Financial expert and founder of personal finance website MoneyComms, Andrew Hagger, comments: “Don’t leave it until the last minute and end up rushing your decision about which provider to bank with; start comparing accounts now so you get the one that works best for you.

“All the banks will look to woo you with freebies and offers but for many students a higher interest free overdraft limit will be the smarter financial move.”

Here are Moneywise’s top picks for student accounts for the academic year 2018/19. See the tables for full details of our best buys.

Best for overdrafts

Most students will need an agreed overdraft, the HSBC Student Bank Account comes with a guaranteed £1,000 in the first year, up to £2,000 in the second and up to £3,000 in the third. For opening the account you’ll also get an £80 Amazon voucher and a 12-month Amazon Prime Student membership. This gives free access to next-day deliveries and Amazon video content.

Alternatively, the Nationwide FlexStudent account offers a £1,000 arranged overdraft in the first year, rising to £2,000 in year two and £3,000 in year three, providing you pay in at least £500 a term. Note that while HSBC provides a guaranteed arranged overdraft limit in year one, Nationwide is the only provider to guarantee you’ll get the advertised overdraft level every year – other providers offer an “up to” amount depending on the person. This account also comes with 1% interest on balances up to £1,000 and cashback on certain spending.

Top for perks

If you’re looking for an account that will give you great perks or rewards there are a few to consider.

The Santander 123 Student Current Account comes with a free four-year 16-25 Railcard, which gives one third off off-peak rail travel around the UK. Four-year 16-25 Railcards aren’t currently sold separately but a three-year railcard costs £70, while a one-year railcard costs £30. This account also pays interest of up to 3% on funds of up to £2,000.

Alternatively, NatWest and RBS (both part of the Royal Bank of Scotland Group) offer  one-year membership of Amazon Prime (usually £39), a £10 Amazon gift card and a one-year National Express Young Persons Coachcard (usually £12.50 and available to those aged 16 to 26), which offers a third off coach travel around the UK. These accounts also come with a Tastecard which offers deals on eating out and is worth £79.99. You do, however, need to pay in at least £750 every six months and have at least three monthly direct debits set-up.

Provider Maximum arranged interest free overdraft limit In-credit interest Additional perks
  Year one Year two Year three Year four Year five    
HSBC £1,000 Up to £2,000 Up to £3,000 Up to £3,000 Up to £3,000 N/a £80 Amazon gift card. One year of Amazon Prime student benefits. Access to regular savings account paying 3%
Lloyds Bank Up to £1,500 (£500 in first six months, then £1,000 during months seven to nine) Up to £1,500 Up to £1,500 Up to £2,000 Up to £2,000 (and in year six) N/a NUS extra card for three years (worth £32)
Nationwide Building Society (i) £1,000 £2,000 £3,000 £3,000 £3,000 1% up to £1,000 max. Cashback from specified retailers via Simply Rewards. Free cash withdrawals abroad
NatWest/RBS (ii) Up to £2,000 (£500 in first term, followed by £2,000 from second term onwards) Up to £2,000 Up to £2,000 Up to £2,000 £2,000 N/a 1 years free Amazon Prime plus £10 Amazon gift card. National Express+ - 1/3rd off coach travel. Tastecard - 2 for 1 restaurants and up to 40% off cinema.
Santander (iii) Up to £1,500 Up to £1,500 Up to £1,500 Up to £1,800 Up to £2,000 1% on £100 to £199, 2% on £200 to £299, 3% on £300 to £2,000. Free four-year 16-25 Railcard
(i) Must pay in at least £500 per term to qualify. (ii) Requires £750 to be paid in every six months and have at least three monthly direct debits. (iii) Must pay in a minimum of £500 a term. Source: Moneycomms.co.uk, 1 August 2018.

‘Budgeting is an essential life skill’

Once you’ve nailed the best student account for your circumstances, you then need to turn your thoughts to how to manage your student finances. Mr Hagger says: “For many students, starting university will be the first time they’ve really had to seriously manage their own finances and to ensure there’s enough cash to pay for books, accommodation, food and going out.

“Unless you draw up a budget of your incomings and outgoings you could soon get in a mess with your money and end up having to go cap in hand to your parents to bail you out.

“Budgeting isn’t fun or sexy but it’s an essential life skill that will save you from worry, heartache and being hit with bank charges you can ill afford.

“Putting together a quick spread sheet on your laptop or a smartphone app is all it takes to make sure you have a regular handle on your money matters and to know how much you’ve got in the bank to last you until the end of term.”


Provider Authorised overdraft fees Unauthorised overdraft fees
HSBC Interest-free No access to unauthorised overdraft
Lloyds Bank Interest-free 1p per £7 borrowed per day
Nationwide Interest-free No access to unauthorised overdraft
NatWest/RBS Interest-free No access to unauthorised overdraft
Santander Interest-free £5 a day (max £50 per month)
Source: Moneycomms.co.uk, 1 August 2018.


Section

Free Tag

Related stories

Twitter


Source Moneywise https://ift.tt/2vnzsyz

Why T.J. Maxx Is a Must-Stop if You’re Eating Bougie on a Budget