Thousands of courses for $10 728x90

الاثنين، 29 أكتوبر 2018

How to Use the 2018 Holiday Season to Drive Sales

With the holiday season quickly approaching, your business needs to take steps to prepare for a potential surge in sales.

But you can’t assume people will buy from your brand during the holidays if you sit back and do nothing. The brands able to recognize the latest marketing trends will have success in the coming months.

Consumers are willing and able to spend money during the holidays. It’s a fact.

How you prepare and position yourself will determine how much of the market share your company will control.

Even though the ecommerce industry is a competitive space, there is plenty of money to go around.

In fact, experts predict ecommerce sales to increase by 17-22% during the 2018 holiday season. November 1st to January 31st is considered the holiday season.

I know what some of you are thinking. There are holidays throughout the entire year. What makes the ones during those dates so special?

Research shows consumers say they will spend nearly $800 during the winter holidays:
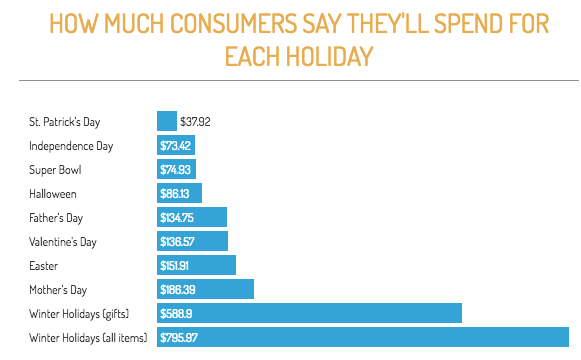
winter

On average, they spend more money during the winter holidays than during all the other top-spending holidays combined.

It’s the season of giving, and it’s usually a happy time of year. People are feeling generous when buying gifts for their friends and family.

However, the holiday season can be stressful. The weather starts to get colder. Stores get busier. Consumers feel overwhelmed with the length of their to-do lists.

As a marketer, you need to make the buying process as easy as possible for the customer.

With your ecommerce platform, there is no reason for people to fight the crowds at their local shopping malls. They can buy holiday gifts from the comfort of their homes.

I’ll explain how you can use this situation to your advantage and benefit from a major boost in ecommerce sales during the 2018 holiday season.

Don’t wait to start your promotions

When is it appropriate to start running holiday ads?

Right now.

You need to learn how to build hype for the holiday season as an ecommerce brand.

This is your chance to let people know what to expect. Tell them what type of sales you’ll be running or whether you’re planning to release a new product around that time.

They may not necessarily buy something the first time they see your holiday ad, but be persistent. Continue running promotions on all your distribution channels.

When consumers are ready to buy, your business will be on their minds.

All too often I see ecommerce brands hesitant to start these promotions early. They think it’s a waste of money because people don’t start shopping until late November at the earliest.

But that’s not the case. Research shows that only 27% of consumers don’t purchase any gifts before Thanksgiving:
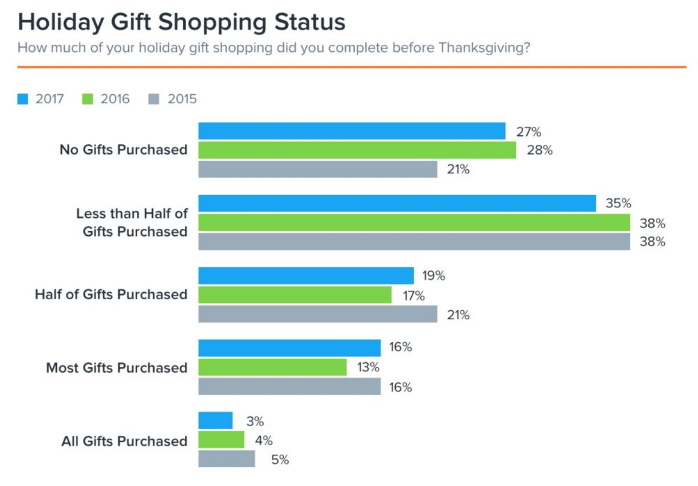
before thanksgiving

This means that more than 70% of people have done at least some holiday shopping before Thanksgiving.

It’s not unreasonable for a customer to buy gifts during the first week of November.

The earlier you can start your holiday promotions, the greater chance you’ll have of driving more ecommerce sales.

Recognize the most popular shopping days

As you can see, there is a surge in ecommerce sales between November and January. But some days are more popular than others during that time.

Over the past five years, Cyber Monday and Black Friday have consistently been the most popular days for holiday shoppers:
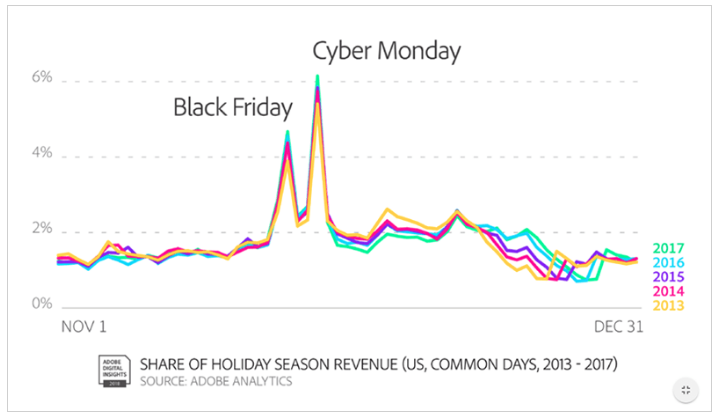
popular days

We’ve all seen those crazy Black Friday videos every year. Hundreds of customers running into stores, trampling on anything and anyone who gets in their way.

Six people fist-fighting over the last TV in the store. It’s madness.

Why does this happen? It’s because everyone loves to get a deal.

As an ecommerce brand, you need to run ads promoting ways customers can save money by shopping online. They don’t need to deal with that mayhem to get a bargain.

Here’s another strategy you can consider. There’s no need for you to wait till Cyber Monday to slash your prices.

Since so many people are shopping during those two days, your brand could get lost in the shuffle.

To stand out, create your own brand holiday that same week.

Send out email reminders, post on social media, and update your website. Then your customers will know they can get great deals on the Tuesday or Wednesday before or after Cyber Monday.

If you implement this strategy, you should still continue to run deals on Black Friday and Cyber Monday.

The last thing you want to do is let your competitors steal your customers during the two most popular shopping days of the year.

Put emphasis on your return policy

Obviously, you don’t want to deal with returns. However, your return policy is important to your customers.

This is especially true during the holiday season. When people buy gifts, they don’t know whether the recipient will like what they get.

What if they already have one? What if the size is wrong?

That’s probably why holiday ecommerce return rates are so high.
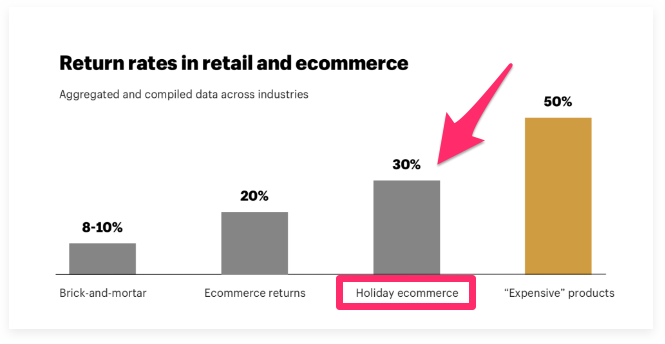
return rates

Customers are more than three times as likely to return a holiday ecommerce purchase than a standard brick and mortar purchase.

Ecommerce return rates are 10% higher during the holidays than the rest of the year.

Furthermore, 80% of consumers expect free returns. However, only 25% of retailers have a free return policy.

This is your chance to differentiate yourself from the competition. Offer free returns.

We know that 83% of customers read return policies before buying something, so make sure this information is easy to find on your website.

Here’s something else you should keep in mind: 72% of consumers are willing to shop more frequently and spend more money with businesses offering easy returns.

If you make this process simple, you can boost revenue by optimizing the customer experience.

Consider extending the length of your return deadlines, especially during the holiday season. Here’s why.

Even if your company has a 30-day return policy with no questions asked, it still may not be good enough. What if someone buys a gift for Christmas in early November?

The return policy could be invalid before the recipient even opens their gift.

Take all of this into consideration when you’re creating your return policy. Advertise how easy it is for customers to return gifts without any hassle.

Don’t charge for shipping

In addition to offering free returns, you should offer free shipping as well.

I already discussed how much money people plan to spend during the holidays. They’ll do whatever they can to save money when they have the chance.

If they are torn between buying something from two different brands, they’ll ultimately decide to go with the company that will ship their items free.

Don’t underestimate the importance of this. Free shipping was cited by consumers as the most important option when buying online:
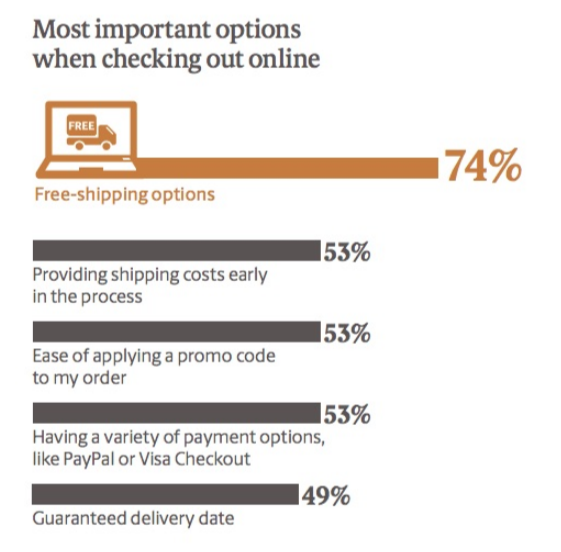
free shipping

The reason why businesses don’t offer free shipping is because they don’t want the cost to come out of their pockets, which is understandable.

To offset the shipping cost, just raise the prices of your products.

Your customers won’t know the difference. They’re still paying for the advertised price and can benefit from free shipping.

Here’s an analogy.

Have you ever stayed at a hotel offering free breakfast?

Obviously, that breakfast isn’t free. Its cost was included in your nightly rate.

The same concept can be applied to free shipping.

Offer rewards for customer loyalty

The holiday season shouldn’t be a time for you to start focusing on customer acquisition.

Would you be happy with getting new customers? Absolutely.

But that doesn’t mean you should be marketing to a new audience. Instead, focus on generating sales from your existing customers.

These people already know who you are and what you stand for. They’re familiar with your products and don’t need any introduction.

You can increase sales by implementing a customer loyalty program. You can use this strategy all year.

Research indicates 82% of consumers are more likely to buy from brands offering loyalty programs.

If you have these programs in place, make sure you remind your loyal customers they can save money with their rewards during the holidays.

As I said before, people are spending a ton of money during this season, so they’ll gladly look for any way to save a few bucks whenever possible.

During the holidays, 86% of consumers will stay loyal to businesses that have rewards programs:
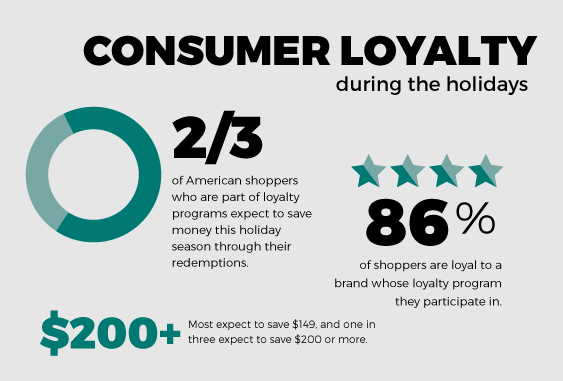
loyalty

Furthermore, 90% of shoppers say they plan to take advantage of rewards programs during the holiday season.

And 50% of consumers plan to use those rewards to buy more gifts than they normally would.

But just because someone is a member of your rewards program doesn’t mean they won’t buy from another brand.

The average consumer participates in four different rewards programs.

To ensure your customers buy from you instead of your competitors, you need to offer better rewards and incentives.

Make it easy for customers to track shipping

Earlier I mentioned that people are stressed during the holidays.

They have much to do and have many things on their minds. To stay organized, people want the ability to track the progress of their orders.

You should send shipping notifications and tracking numbers to your customers.

This is a great chance for you to create an actionable drip campaign.

First, send an email to the customer confirming their order was completed. Then, send a second email notifying them the order has shipped. This is an appropriate time to include the tracking number.

Finally, send a third email when the product has been delivered.

Click-through rates to tracking pages increase during the holiday season:
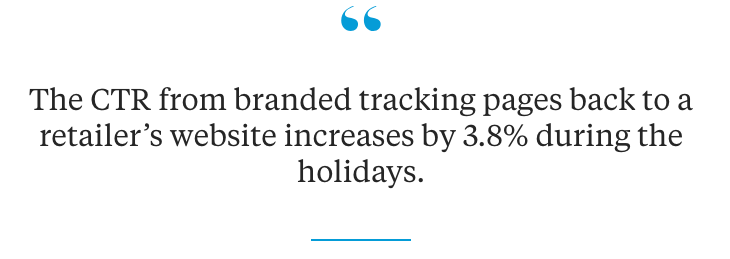
track shipping

This should tell you that consumers are genuinely interested in tracking their orders. It gives them a chance to make sure everything is going according to schedule.

Studies show 93% of consumers refer to their emails for these notifications, and 38% of people want to be contacted on multiple channels.

If applicable, consider sending text messages and push notifications.

Here is another reason why tracking packages is such an important feature for you to offer.

Statistics indicate that 33% of people have had packages stolen from their doorsteps. Nearly 26 million Americans had packages stolen from their doorsteps or front porches during the 2017 holiday season.

With ecommerce sales expected to rise during the 2018 holiday season, it’s safe to assume theft will rise as well.

These are alarming numbers, but it’s reality. By alerting your customers their orders have been delivered, you can help reduce the chances of theft of their purchases.

Prioritize mobile commerce

By now, I hope you’ve recognized the importance of mobile optimization.

Your website should be mobile friendly, and some of you may have even developed a successful mobile commerce app.

Don’t overlook mobile commerce during the holidays. It should remain an important part of your marketing strategy.

On Black Friday of 2017, 57% of ecommerce traffic came from mobile devices. People were using their smartphones even while shopping in stores.

Mobile commerce held a 37% revenue share last year during the holidays. This was up from 17.5% in 2016.

I expect this trend to continue rising in 2018 and the coming years as well.

Consumers will turn to their mobile devices to buy during the holidays.
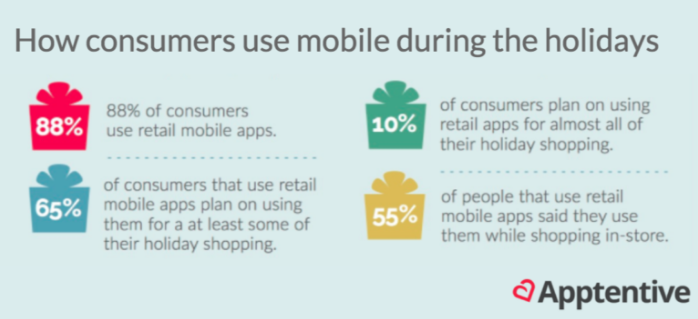
mobile

As you can see from these numbers, ecommerce brands with mobile apps will have a competitive advantage here.

Make sure you utilize all the features at your disposal.

Send out push notifications to mobile app users to remind them of flash sales. You can also send notifications about order updates, which I discussed when talking about tracking orders.

Appeal to those last-minute shoppers

Earlier I told you that you should start advertising as soon as possible because people start shopping for the holidays sooner than you may think.

But some people just love waiting until the last minute.

Don’t stop running your holiday campaigns until the season is officially over. Make sure you find ways to appeal to last-minute shoppers.

The best way to do this is by offering fast shipping options:
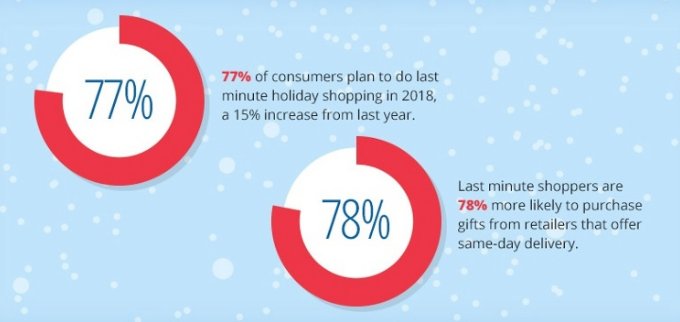
last minute

As you can see, people who wait until the last minute to buy gifts are significantly more likely to buy from retailers offering fast delivery.

Last-minute shoppers are 39% more likely to abandon their shopping carts if the delivery options are too slow.

Overall, 67% of consumers abandoned ecommerce shopping carts in the last year because of slow delivery times. This is a 16% increase from last year.

And 92% of consumers said that receiving their delivery on time was the most important factor they considered when purchasing a gift.

Unfortunately, it may not be reasonable to combine your fast delivery feature with your free shipping incentive.

If a last-minute shopper needs something shipped overnight two days before Christmas, they’ll have to pay a premium for shipping. But by this point, they’re willing to pay as long as it arrives on time.

Conclusion

The holiday season is a great opportunity for you to take advantage of consumer spending habits.

Since they spend more money, you have a chance to make more money. But this won’t come automatically.

Start promoting your holiday sales as early as possible. Run your best deals on the most popular shopping days of the year.

Make it appealing for customers to buy from you instead of your competition.

Offer free shipping. Have a hassle-free return policy. Reward your most loyal customers.

Allow your customers to see their order status and track the shipping of their packages.

Don’t forget about mobile customers and last-minute shoppers.

Follow the advice I’ve outlined above, and use this guide as a reference to generate sales during the 2018 holiday season. Happy holidays!

How is your business planning on appealing to holiday shoppers this season?


Source Quick Sprout https://ift.tt/2EThawX

Questions About Losing Income, Ryze, Winterizing a Lawnmower, Taxes, and More!

What’s inside? Here are the questions answered in today’s reader mailbag, boiled down to summaries of five or fewer words. Click on the number to jump straight down to the question.
1. Tax impact of income loss
2. Consolidating secured loans
3. Bluetooth headphone recommendation
4. Thoughts on Ryze
5. Doubt about financial success
6. Winter storage for a lawnmower
7. Legitimate investment manager
8. Programmable slow cookers and safety
9. Office alternatives not by Google
10. Frugality affects other life choices?
11. Thoughts on Fortnite
12. Tricks for staying focused

Several people have written to me in the past week expressing some degree of skittishness about the stock market. If you’ve not been paying attention, the stock market has dropped about 10% from its highs earlier this year. Unsurprisingly, some people are concerned about seeing 10% of their retirement savings seemingly disappear.

My reaction is different. When I see the stock market is down 10%, I’m thrilled, because that means I’m buying more shares with every retirement contribution.

Let’s say that, at the peak, shares of my preferred retirement index fund were $50 a pop. If I contribute $500 a month, I was buying only 10 shares each time I contributed.

Now, after a 10% drop, they’re $45 a pop. Without changing my contribution, I’m now buying 11.1 shares a pop. I’m getting 1.1 shares more than before for the same price.

I have many, many years left to go before I’ll need those shares. Over the long term, the average annual return of the stock market is going to be about 7%. All this decline really means to me is now I have 1.1 more shares than before, and they’re going to grow at that same 7% rate.

A drop right now is good for me. It’s only worrisome if I’m in retirement and I have too much of my retirement savings exposed to stocks. If you’re not retired yet, a stock market correction is a good thing, especially if you can keep buying in throughout it. You’re getting more shares for your dollar.

On with the other questions.

Q1: Tax impact of income loss

I live and work in NJ. While married, I file single 0 on both federal and state. If my gross annual pay dropped to below 90k from 115k where would it put me in the tax bracket and what would be my tax hit on both federal and state?
– Adam

You’re dropping $25,000 a year in income and claiming no dependents, so let’s use that as a basis.

In New Jersey, you’re going to remain in the $75,000 – $500,000 tax bracket, which pays 6.370% in state income tax. 6.370% of $25,000 is $1,592.50.

At the federal level, you’re dropping out of the 28% tax bracket ($91,901 to $191,650) and into the 25% bracket ($37,951 to $91,900), but just barely. This means that you’re saving 28% of your previous income above $91,901 – $23,099 – and 25% of your previous income below $91,901 – $1,901. 28% of $23,099 is $6467.72 and 25% of $1,901 is $475.25, for a total of $6,942.97.

Those numbers are going to change – going down a little bit – if you have any deductions on your taxes. I’m assuming no deductions at all.

Q2: Consolidating secured loans

I have 6 secured loans the total I owe is $8,500. I need to consolidate my loans I’ve checked with just about every company online and also with my own credit union and I’ve been turned down, it’s stressful. Can you please help me to consolidate these secured loans?
– Linda

It really depends on why you’re being turned down, which is something you should be asking, especially at the credit union.

If you’re being turned down because your credit is bad, then you need to work on improving your credit. The first step is to simply make sure you’re paying all of your bills on time. That’s probably the biggest step a person can take to ensure that their credit is fine.

If you’re being turned down because some of those loans are individually problematic, consolidate what you can and pay off the problematic ones first.

You need to find out why you haven’t been able to consolidate before you can solve the problem.

Q3: Bluetooth headphone recommendation

I am looking for some Bluetooth headphones to use while going on hikes. Tired of dealing with the headphone cable! Don’t want to spend a ton. I am not an audiophile. I’m more interested in ones that will last and have good charging time.
– Andrea

My favorite low cost Bluetooth headphones are probably the Anker Spirit X over-the-ear headphones. They have a short cable that you dangle across the back of your neck, connecting the two. You basically just hit a button to connect them to your phone, put them on, and hit play and you’re good to go. The cord stays out of the way.

Those are my preferred ones and, honestly, the only flaw I can point to with them is that they’re easy to misplace. I’ve lost my pair two or three times now… maybe I’m just really bad at remembering where I put things.

Anyway, they work well, don’t have an annoying cord, seem to have a very long battery life, have good sound quality, and are pretty inexpensive. In general, I find stuff made by Anker to be very good quality for the price.

Q4: Thoughts on Ryze

I looked up Ryze (need to build more friendships myself and thought the reminders would help with ADD, which makes followups challenging). But it’s intended for business networking. Thought your article should have mentioned that.
– Danielle

Ryze certainly markets itself as a business networking app (because, let’s be honest, that’s how a lot of people will probably use it), but it’s engineered in such a way that it works as a personal contact manager that reminds you to keep in touch with people, and it does that really well.

I’ve been using Ryze since the beta and I have a ton of personal contacts jammed in there. It works just fine as a system to regularly remind me to keep in touch with old friends – not that I would forget to do so, but that I’m just as guilty as anyone of letting friendships fade over time, and this tool helps me to not do so.

It replaced a kludge that I used to use that involved a mix of to-do lists, calendars, and contacts. This is just way easier.

Don’t sweat how the app is promoted as a business contact app. It works well for making sure you’re keeping up with your friendships.

Q5: Doubt about financial success

I don’t believe you can be close to retiring early on little more than the average American household income.
– Adam

You can believe what you wish, but we are, and it’s actually not even that hard.

We live on about $30,000 per year and make substantially more than that. We fully own our own home – no mortgage – and we just don’t have expensive tastes in anything. My biggest splurge is buying an occasional board game or a Kindle book and I actively try to trim that to as little as possible. We don’t have cable. We buy mostly store brands at the store. We eat out maybe once a month unless we’re traveling.

We take our leftover income and bank it into retirement accounts and, because there’s some overflow, a bit into taxable accounts, too.

The key is just not spending income even though we know we could easily afford to do so. I can think of lots of things that I know I could easily buy. I’d enjoy those items. But… why? I already have a bunch of stuff I haven’t adequately explored to my satisfaction? Why buy more stuff that we’re just going to have to store?

Rather than worrying about the details of my story, though, consider your own. Why can’t you implement those same things and see if they work for you?

Q6: Winter storage for a lawnmower

I’m a new home owner in April. Bought a push mower for my yard and spent about $400 on it. Winter is coming and grass is dormant. I read a guide about winter storage of lawnmower. How much of that really needs to be done? Seems like a ton of work for a push mower.
– Alex

For our push mower, all I do for winter storage is add a bit of fuel stabilizer to the gas tank, run it for a few minutes, and siphon out the remaining gas. I then change the oil, the spark plug, and the air filter so it’s ready for spring. I leave the spark plug cable disconnected. While it’s tipped up for the oil change, I clean out the bottom of the mower deck a little bit while the oil is draining. Some mowers will require you to remove the blade while changing the oil, which is just a matter of loosening a bolt.

That takes about 15 minutes all told, plus a stop at the hardware store first.

I usually include it as a November task on my maintenance checklist. If the weather is still nice, I postpone it to December. I think this is going to be a “November” year.

If you’re only going to do one thing, just put a bit of fuel stabilizer into the gas tank, then run the mower until it runs out of gas. You can do that in about a minute, as long as you’re willing to just tie down the handle and let the mower run in your garage for a while as you’re doing other things.

Q7: Legitimate investment manager

How can you tell if someone is a legitimate investment manager who isn’t just scamming for your identity?
– Tony

FINRA (Financial Industry Regulatory Authority) offers a far better checklist than I could offer, and you can find that checklist right here.

In general, the best way to do it is to go to an unbiased store like FINRA BrokerCheck and your state securities regulator (found via Google) and see whether or not the person you’re dealing with is legitimate. If they are, FINRA will know about them, as will your state securities regulator.

The financial services industry is very highly regulated to ensure that legitimate participants can’t just rip people off. (They can offer some weak investment choices, but they can’t just steal identities or take money.)

Q8: Programmable slow cookers and safety

I don’t believe you can set the start time on those programmable slow cookers. Probably something to do with food safety. I think your best option would be the outlet timer you mentioned as a second option.
– Alex

It turns out that the vast majority of programmable slow cookers actually just allow you to program the length of time it stays in “cooking” mode before it switches into a “keep warm” mode (that keeps the food at a temperature where it’s not really cooking but hot enough that it’s not going to develop bacterial colonies or anything).

So, if you leave at 7 AM and get home at 6 AM, the slow cooker will start cooking immediately and when it reaches the end of the time that you set (matching the recipe), it’ll just switch to “keep warm” mode.

Using an outlet timer with a non-programmable slow cooker is probably a bad idea for meat-based dishes because of the risk of food-borne illness. As a vegetarian, this isn’t something I run into, but it’s a good thing to remember.

Q9: Office alternatives not by Google

Looking for free alternatives to Word, Excel, and Powerpoint for small business use. Everyone seems to point to Google Docs but I don’t want to share my info with them. What other solutions do you recommend?
– Dane

While I use Google Docs for some things, I do like having my own offline documents and spreadsheets that aren’t on the cloud. I’ve been using LibreOffice for that and it works well.

If you use a Mac, I highly recommend their free apps Pages, Numbers, and Keynote, especially Keynote – I strictly prefer it to PowerPoint.

All of those options are free, and all of them are off the cloud, meaning that Google won’t have access to them if that worries you.

Q10: Frugality affects other life choices?

Do you think that frugality impacts other life choices that don’t have financial bearing? For example, if you’re actively frugal, might you choose to do things that are less personally risky, like wear a helmet while bicycling or on a motorcycle?
– Tanya

That’s a really interesting question for which I have no idea.

There seems to be some evidence that frugality is more of a “nature” thing than a “nurture” thing. Some people, by their nature and not so much their environment, are naturally more frugal. That would inherently meant that frugality is linked to some other personal traits, but I can’t find any research that delves into this.

If any readers have any research into this topic, I’d love to read about it!

Q11: Thoughts on Fortnite

My kids play Fortnite all the time. When they’re allowed screen time that’s what they want to do. It’s a free game (good) but then they want to spend their allowance on V-Bucks which basically just lets them buy costumes in the game which seems silly. What do you think?
– Jerry

My children also enjoy playing Fortnite when they’re allowed to have screen time. They also want to spend their allowance on V-Bucks, mostly for costumes.

I really don’t have an issue with it, as long as it’s just their allowance or birthday money. They’d likely spend it on some form of entertainment or hobby anyway, and if they’re having fun, it’s fine.

The only issue I have with Fortnite is that my kids are constantly angling for more screen time so they can play more Fortnite. “I’ll clean the living room if I can get an extra hour of screen time to play Fortnite!” It’s a parenting dilemma.

Q12: Tricks for staying focused

Do you have any tricks for staying focused when you’re stuck at your desk for a long period of time? How do you keep from zoning out when writing?
– Brenda

First thing: I spend some time in the morning doing “Three Morning Pages,” where I basically just brain dump out of my head into a journal until I’ve filled three pages. Whatever comes to mind, I write down. I focus far better on days when I do this.

I also spend a bit of time meditating each day – 10 to 15 minutes, though less is still effective. I just find a comfortable chair, close my eyes, and focus on my breathing – in and out. If my mind wanders, I gently bring it back to my breathing. This helps a little on days when I do it, but the power of this comes from chaining together long streaks of doing it each day. It builds in power, I’ve found.

When I really need to focus, I kill as many distractions as possible. I put my phone into Do Not Disturb mode, turn on StayFocusd in my web browser, and throw on some noise cancelling headphones.

I usually turn on some sort of music or sound that helps me focus. Lately, I’ve been mostly using this and this.

I usually have both a cup of coffee and a cup of green tea at my desk, and I drink from them both at the same time, roughly alternating sips. I find that together they’re more effective than either one on their own (but mixing them is not tasty!).

I have a notebook open on the desk in front of me (along with a pen) to jot down loose ideas if they bubble into my head, so that I get them out of my head and don’t have to think about them again for a while. I deal with them later when I have downtime.

That’s usually enough to get me into a good flow state for work (flow state is when I’m so engaged that I genuinely lose track of time and place).

Got any questions? The best way to ask is to follow me on Facebook and ask questions directly there. I’ll attempt to answer them in a future mailbag (which, by way of full disclosure, may also get re-posted on other websites that pick up my blog). However, I do receive many, many questions per week, so I may not necessarily be able to answer yours.

The post Questions About Losing Income, Ryze, Winterizing a Lawnmower, Taxes, and More! appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2Q03RvP

Join Your College Alumni Group to Score New Friends and Career Connections

Your Year-End Investment Checklist

The end of the year is fast approaching, and with it comes the opportunity to check in on your investment plan and make sure everything is on track.

Here’s a checklist that will help you do just that.

1. Check on Your Emergency Fund

Your emergency fund serves as a valuable buffer that makes it easier for you to keep your investment plan on track.

With a safety net in place, you can weather just about any financial storm without dipping into your investment accounts, and potentially without even pausing your contributions.

Here’s a step-by-step guide to building a big, healthy emergency fund.

2. Take Stock of Your Debts

If you have high-interest debt, it may be worth paying that off before putting extra money towards your investments (though it’s almost always worth maxing out your 401(k) match first).

Now is a good chance to take stock of your debts, noting the balance, interest rate, and minimum payment due on each one. Then you can use this guide to decide whether you should be prioritizing investing or making extra debt payments.

3. Update Your Retirement Savings Target

The most important part of your investment plan, by far, is your savings rate. And to get it right, you need to know how much you should be saving based on your personal investment goals.

To see whether you’re on pace or need to step up your savings rate, you can use this spreadsheet to calculate exactly how much you should be saving for retirement each month.

4. Update Your Retirement Contributions

With that savings target in hand, it’s time to update your retirement contributions to make sure that you’re on the right track. You can click here for a complete guide to picking the right accounts, but the following pointers will get you started:

  • First and foremost, do what you can to max out your 401(k) match. That’s almost always the best return available to you.
  • If you have access to a health savings account (HSA), that may be the next best option. It has several features that make it a fantastic retirement account.
  • If your 401(k) offers good, low-cost investment options, you can increase your contributions there up to the annual limit (currently at $18,500, though it may increase to $19,000 for 2019).
  • If your 401(k) doesn’t offer good investment options, or if you’ve already maxed it out, you can contribute to a traditional or Roth IRA. The combined annual IRA contribution limit is currently $5,500 for those under 50 and $6,500 for those 50 and older.
  • If you’ve maxed out all of those accounts and you still want to contribute more, a taxable brokerage account is likely your next best option.

Even if you can’t contribute enough to fully reach your savings target, see if you can increase your contributions by just a bit. Then set a calendar reminder for six months from now to make another small increase, and again in another six months, and so on.

Regular small increases over an extended period of time will have a big long-term impact on your savings rate without ever forcing you to make too big of a change all at once.

5. Check for New 401(k) Investment Options

Every now and then, your 401(k) might update some or all of its investment options, and the end of the year is a good opportunity to make sure that you’re aware of them.

It’s possible that lower-cost options have been introduced or that new funds have been added that are a better fit for your desired investment plan. Or maybe fees on your current fund selections have been raised, in which case it might make sense to switch.

Here’s a guide that will help you evaluate your options and make the right choices: How to Choose Investments in Your 401(k).

6. Rebalance Your Investments

Your asset allocation is one of the most important parts of your investment plan. By choosing the right mix of stocks and bonds, you can shoot for a reasonable return without taking on more risk than you’re either willing or able to take.

But even if you do nothing, your asset allocation can shift over time. Depending on which markets are performing well compared to others, your balances will rise and fall, and your asset allocation could become either more or less aggressive than you’d like.

That’s why it’s so important to rebalance your investments and bring them back in line with your target asset allocation. Doing so will make sure that you stay true to your long-term plan.

7. Check for Tax-Saving Opportunities

With the help of a good CPA, you may be able to take advantage of some helpful tax-saving opportunities.

If you’re in the 10% or 12% tax bracket, any long-term capital gains are actually taxed at 0%. So if you have investment gains in a taxable account, you could take advantage of a strategy called tax-gain harvesting, in which you sell those investments and quickly repurchase them, ensuring that those gains will never be taxed.

If, on the other hand, you have losses within a taxable account, you could take advantage of a more complicated strategy called tax-loss harvesting. In this case, you would have to sell the investments that have a loss and buy similar, but not identical, investments to replace them. Those losses could then be used to offset gains elsewhere, or to reduce your regular income by up to $3,000 per year.

If you have money in a traditional IRA, you could also consider converting some of that money to a Roth IRA. This is generally most effective when your tax bracket is currently lower than what you expect it to be in retirement, and even then should be done cautiously.

The Sooner the Better

The end of the year is the perfect time to take stock of your investment plan and make sure everything is on the right track, but it’s also easy to run out of time once the holidays hit and your life gets hectic.

All of which means that the sooner you start working through this checklist, the better. With the right moves now, you can put yourself on pace for a successful 2019.

Matt Becker, CFP® is a fee-only financial planner and the founder of Mom and Dad Money, where he helps new parents take control of their money so they can take care of their families.

More by Matt Becker: 

The post Your Year-End Investment Checklist appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2CQBYT0

Ever Wonder if Groupon Getaways Are a Good Deal? We Have Answers

الأحد، 28 أكتوبر 2018

How to Work Remotely and Travel the World

Now that my husband and I are empty nesters, we’ve decided to take advantage of our new-found “freedom” and travel more. My husband runs his own business from his office in our home, so, he has the flexibility to determine his work hours and locale. As a veteran remote employee myself, my company offers the […]

The post How to Work Remotely and Travel the World appeared first on The Work at Home Woman.


Source The Work at Home Woman https://ift.tt/2CMG12J

PMSD resource officer both a protector and mentor

When Jason Wile graduated from Pocono Mountain High School in 1996, he never imagined that he'd be back for another five years or more.Yet that’s exactly where he finds himself, as the Pocono Mountain School Resource Officer has become a fixture at the district and ingrained in the community since taking on the role in 2013.“As a former Marine and becoming a cop, and that whole mentality— I never thought my days would be spent running around chasing 14 to [...]

Source Business - poconorecord.com https://ift.tt/2qgFMFC

This Ex-Pitcher’s Product Idea Was a Million-Dollar Hit Right Off the Bat

Costco Without a Car

When my wife and I moved to Brooklyn, we felt lucky that we wouldn’t need to buy a car. Our apartment was close enough to a subway line and our neighborhood was walkable enough that it didn’t make sense to own a vehicle. That being the case, we had a tough decision to make about our grocery shopping habits. Specifically, what were we going to do about our beloved Costco membership? The nearest store was two miles away. We weren’t sure whether we would get enough value out of our yearly membership given the distance and our lack of a vehicle.

We decided we’d keep the membership and walk to Costco. Call it foolishness driven by an unshakeable addiction to Kirkland brand chocolate-covered almonds, but we were determined to do our bulk shopping without owning a vehicle. Turns out it wasn’t that hard, and it could actually be fun with the right attitude.

How We Made Costco Trips on Foot

There were both physical and mental hurdles to overcome before our first trip. It would be taxing to lug several hundred dollars and at least a hundred pounds’ worth of groceries from Costco to our place. We also worried it might look weird to walk the streets weighed down with so many bags. But in the end, I realized I’m the kind of person who’s willing to try all-potato diets and take freezing cold showers, and my wife is supportive of it all. Weird and difficult wasn’t going to stop us.

The first step of preparation was to get our gear ready. This consisted of grabbing a couple of backpacks and stuffing them with every cloth grocery bag in the apartment. That was it. We could have greatly increased our carrying capacity if we used a rolling bag of the type that’s popular at farmers markets, but we never got around to buying one.

My wife and I are fast walkers who quickly took to the local New York City custom of jaywalking, so the two-mile walk to the store took generally took about 30 minutes. We would then load up our cart like it was any other Costco trip, but with a couple of caveats.

One issue was that we had to be a bit more careful about how much we bought. There’s only so much weight two humans can lug. I’ve done all-out Costco trips where you get a workout just pushing your bulging cart through the parking lot to your car and unloading it. It wouldn’t be feasible to carry that much stuff back on a walk. On average, we spent $200 to $300 on food, which resulted in a challenging but manageable load to haul back.

We also chose to exclude any item that was too bulky, even if it was light and cheap, such as jumbo packs of paper towels. Things like trash cans and furniture were also not feasible to carry back.

Another consideration was the temperature. Our walk back took us considerably longer than 30 minutes, so if it was hot out we limited how many frozen goods we bought.

Barring those minor inconveniences, our trips were a success, and we executed them in all weather. I snapped this picture of my wife doing her best pack mule impression walking back through Brooklyn on a bitterly cold March afternoon:

walking home from costco - costco without a car

That’s four tote bags and a backpack, people! I’ve never been more in love. If I could have sent this to friends and family in lieu of engagement photos, I totally would have. But I digress.

We sometimes wore headphones and listened to the same podcast, which was a fun way to pass the time. There are tons of ways you can make the walk a team building adventure rather than a dreary slog. For example, we once took a different route to explore the city and ended up seeing a famous old cemetery that we never would have visited otherwise.

If you look at it purely from the perspective of how much you value your time, it’s hard to make the case for walking. But how do you account for the exercise, the fresh air, the good conversation, and the sense of accomplishment after overcoming a difficult task?

The exercise aspect was particularly salient. I am all about avoiding gym memberships and incorporating exercise into my everyday routine. Plus, one of the main things I do when I have access to a gym is an exercise where I pick up a heavy set of weights, hold them at my sides, and walk back and forth. It’s a great workout. Does that sound eerily familiar to another activity?

Incorporating physical activity into your everyday life that isn’t structured exercise is a good idea, regardless of whether you’re walking to Costco. It makes it easier to meet the healthy activity level guidelines set by the U.S. Office of Disease Prevention and Health Promotion. As obesity researcher Dr. Stephan Guyenet puts it, “Our distant ancestors had a word for exercise: life.”

Also, yes, I could sit in the comfort of my home and order most of the same things from Amazon or a similar store. That would save time. But what did I want that extra time for if not to spend it with my wife doing a challenging activity that gave us a story to tell and brought us joy? If you’re physically able and you enjoy walking, you can consider cutting out the middleman by getting creative with how you do your grocery shopping.

Biking, Rideshare Services, and the Subway

There are other ways to enjoy shopping at Costco when you don’t own a car but also don’t want to walk both ways.

While living in Brooklyn, we easily could have taken a short subway ride to and from Costco. It would have been a hassle getting through the turnstile with all our bulk bounty, but it’s doable. I saw people carrying large amounts of groceries onto the train all the time.

We currently live in Chicago, where our apartment is even farther from a Costco and there are no good train lines leading to the store. Walking nine miles round-trip is too much for even me to stomach, so we made a new plan: We now walk or bike down to the Costco, and pay for an Uber to bring us back.

We take advantage of a bike-share system offered by the city called Divvy Bike, so we can leave our bikes without worrying about the return trip. If you’re an intrepid bike adventurer who owns a bike with a cargo attachment like Mr. Money Mustache, you can absolutely do the whole Costco trip by bike.

An obvious advantage of using a rideshare service like Uber or Lyft on the way home is that you can buy a lot more stuff. If you’re taking advantage of one of Costco’s big-screen TV deals, for example, hailing an Uber makes a lot of sense.

Each Uber trip back from Costco costs about $12, so we have to make sure that we’re capitalizing on deals that are unique to Costco to make sure it’s worth the extra expense. Thankfully, with some pre-planning, this isn’t hard to do.

Finally, be sure to keep an eye out for deals on rideshare services. For instance, my Platinum Card® from American Express gives me $15 in free Uber credits every month (among other benefits). I rarely go to Costco more than once per month, so I now use my card to get a free ride back from the store every month.

Summing Up

There are many ways to enjoy the benefits of Costco without owning a car — if you’re willing to take a little more time and use a bit more energy. Walking, biking, or using a rideshare service can help you stay in better shape and save money on car ownership. It helps to have an awesome and supportive partner to go with you on the journey, but anyone with the right attitude should be able to have some fun with the process.

More by Drew Housman: 

The post Costco Without a Car appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2Oc6nNY

This Man Started a Business Hanging Holiday Lights and Made $138K in Year 3

السبت، 27 أكتوبر 2018

Tactics for Friendships During (and After) Financial Turnarounds

A week ago, I wrote an article entitled Friendships and the Financial Turnaround, in which I discussed the challenge of building and maintaining friendships when you make a major financial turnaround in your life. In that article, I discussed a few broad strategies for doing just that – building and maintaining friendships as an adult without spending a lot of money doing so.

Several readers wrote in with follow up questions that were worthy of the Reader Mailbag. Collectively, those questions pointed strongly toward an article outlining how exactly I have built friendships as a financially careful adult. What exactly did we do to build those friendships?

To summarize: I would guess that I have more strong friendships right now as an adult male approaching middle age than I had at any point in my entire life. This includes high school and college. I built most of those friendships while being pretty careful with my money – I didn’t spend on lavish parties or expensive things to impress people.

I did that by using a bunch of different strategies at once, which I’m going to list over the course of the rest of this article.

One big caveat before we start: doing just one or two of these things is not enough. These strategies work best in concert with one another, and just pulling out one or two, trying them for a while probably won’t have the outcome you desire. You don’t have to do everything I list here, but if you’re going to seriously try to build friendships, you should do a lot of these things.

Okay, let’s dig in.

I Consciously Worked on Improving My Own Social Skills

This might seem a little strange, but this was absolutely foundational for me. I’m an introvert for whom social skills don’t come naturally. My instinct in a place, particularly with new people or people I don’t know well, is to clam up, and it has taken a lot of work to just partially overcome that instinct.

To help me, I have relied on countless Youtube videos and articles, but there are three books that have had a truly profound impact on my social skills. Each of these books can feel really mechanical in places, but it was those specific mechanics that really helped. I recommend reading all of these, for different reasons.

How to Win Friends and Influence People by Dale Carnegie was foundational. It really helped me figure out how to have quality conversations with people I didn’t know well, and how to have the courage to simply start interacting with them. I’d say this book took me from being someone who hated even going to social situations and standing in the back of the room when I did to a person who felt fine in mixed social situations and could carry on conversations that were at least good enough to start building relationships.

The Like Switch by Jack Schafer added a lot of details to How to Win Friends and Influence People. For me, this book was a great follow-up because it focused on very specific things that I could work on to improve my ability to converse and my “likability.” It basically takes a lot of the tactics given in the earlier book and refines them by adding details into something more powerful, or shows you how to connect them together more effectively.

Finally, Never Eat Alone by Keith Ferrazzi and Tahl Raz takes the elements taught in the other books and shows you how to build upon the effective conversations and transform them into lasting friendships and relationships. I particularly valued the focus on how to maintain relationships over time.

I strongly encourage anyone who is interested in how to build friendships and community relationships as an adult and finds doing so to be difficult at all to read those three books.

As I read techniques in those books (and found others in articles here and there), I consciously practiced them. I turned them into thirty day challenges, where I strove to work on that specific tactic for thirty days straight, and sometimes repeated those challenges, in an effort to make that tactic feel completely natural to me.

I worked on things like smiling more (my face naturally has a slight frown to it while resting), starting conversations with people, consciously listening more, following up with people, and so on. Most of the rest of the tactics in this article were practiced by me in some way or another.

You’ve got to practice your social skills and strive to be better or it’s going to be prohibitively hard to build relationships when you’re not stuck in a classroom with the same people for many hours a week. It was easier to build friends in elementary school and high school and college because you were forced to be in proximity. As an adult, that’s no longer true. You have to do better or you won’t build relationships.

I Intentionally Started Attending Community Events That Interested Me

I started blocking off evenings in my calendar to go to community events, both with my family and on my own.

I went to meetings of local civic groups like the Lion’s Club. I went on Meetup, the city website, the parks and recreation website, the library website, and those of nearby towns. I joined a local community group on Facebook and started looking for local event listings. I started going to every single sporting event that my children participated in and intentionally sat near other parents.

My goal was to fill my calendar as much as I could with events out in the community where I could interact with other adults.

In addition, I sought out online communities directly related to my personal interests, particularly my hobbies: books and reading, board games, home brewing and fermented foods, and so on. I particularly looked for groups with a local bent, but wider groups with occasional opportunities for face to face meetings (like conventions) were also on the radar. Social media, like Facebook and Twitter, is a good place to start – just find conversations by searching for key terms of interest and dive in.

For those more distributed online communities, I started planning to occasionally go to conventions where I could mostly meet up with some of those people face to face and hang out together, really cementing the friendship we built online. This came later, however; I met up with people I had conversed with for years in public group settings.

At Those Events, I Intentionally Made It a Goal To Talk To a Certain Number of People in a Meaningful Way

Whenever I go to any kind of public event, whether it’s something as simple as watching my kids play soccer or an ordinary meeting of a civic group or a public lecture or a free concert or something I learned about via Meetup, I make it my goal to have a meaningful conversation with some small number of people there. Three, five, ten – it depends on the event and also on how I’m feeling.

For me, a “meaningful conversation” is one in which I learn a person’s name and something significant about them, or if I casually knew them before, I learn something new about them. I usually do this by asking questions pertaining to what we’re doing there, and then following up.

So, let’s say I’m at a soccer game. I’ll sit my chair down next to a parent I’ve seen at games in the past and introduce myself. “Hey, I’m Trent… my son is #46 over there.” They’ll usually introduce themselves back. Then, I’ll ask some follow-up related to the event at hand. “What do you think of the new coach?” or “I’ve never been to this town… are there any good restaurants here?”

The point here is to serve up a question where I’m interested at least a little bit in the answer and to give them something easy to talk about. Almost always, their answer gives me a route to another follow up question, and then we’re off to the races.

If I ever sense a lull, I’ll usually ask them what they do for a living or what they like to do when they’re not working. Whatever hobby they name, I express interest in it, period, because people are almost always happy to talk about their hobbies.

I can usually figure out by this point whether this is a person I am going to connect with. Not connecting with someone doesn’t mean that they’re a bad person, it just means that we didn’t click for some reason. Sometimes, I’ll find that I “click” with a person later on after having had some conversations with them that didn’t initially click.

I Aim to Obtain Some Way to Follow Up with Each Person I Felt Some Connection With

If I feel some good connection with someone, I try to obtain some contact info that’s low in terms of life intrusion, like a social media handle or an email address. I’ll say something like, “Hmmm… that’s really interesting. I’m going to have to give that some thought. Do you have an email or a social media account? I’d really like to follow up with you about X.”

Most people do this. They usually figure that if they don’t actually want to respond, then they can just ignore anything I send their way. And, yeah, sometimes they do, and that’s fine with me. There are millions of people out there – they’re not all going to wind up being a good friend.

Once I have that contact info, I usually jot down the reason why I want to follow up with them and any information I need to know about that.

Let’s say I went to a presentation at the library and afterwards I found myself talking to a guy named Jim. It turns out Jim is really into heirloom gardening and loves to save seeds, something that’s a mild interest of my own. Because of follow up questions, I find out that Jim has a particular tomato variety that he really loves, but he can’t remember where he got the seeds originally.

I’ll simply say, “I’d love to get a few of those seeds or at least find out where you got them from and try to grow them next year. Do you have an email or something so I can shoot you a message about them?”

When that person shares their contact information, I’ll immediately jot it down somewhere before I forget it. I’ll put it in my pocket notebook (I don’t go anywhere without a pocket notebook and a pen)

Then, a day or two later, I’ll type out an email to Jim.

“Hey Jim!

This is Trent, we met at the talk at the library on Tuesday and you told me about your tomato variety.”

I’ll ask a few questions about it, like where he got the seeds and so on and whether he has any cucumber heirlooms that he really likes for this Iowa climate.

I’ll finish off with friendliness, like “It was great to meet you! I love to find other people who are into gardening, especially someone who got heirloom tomatoes to work well around here!”

This usually results in at least a few back and forth emails that, even if they dwindle away (as they usually do), create a foundation for future contact.

I Use Ryze to Manage Social Follow-Ups

If I feel a connection clicking with someone, I add them to an app on my phone called Ryze.

Ryze is a combination of a calendar and a contact manager. What it does is that it reminds you on a set schedule to get back in touch with each of the contacts that you add. It is incredibly effective at helping me stay in touch with people and maintain older friendships. It’s just a gentle nudge so that I don’t get lazy with my friendships and acquaintances.

For each person in Ryze, I have a few things listed that I want to follow up on the next time I’m nudged by the app to contact that person. This isn’t because I’m not thinking about the person, but just because my memory is fallible and the thing I want to keep in touch about is something I don’t want to forget. It’s like an external social memory for me.

So, let’s say I have an old friend named Tina listed in Ryze, and it’s set to remind me to contact her once a month. I do so by sending her a Facebook message just to say hello and ask about how her job is going (which I’m reminded to thanks to Ryze) and I find out that one of Tina’s family members has cancer. I’ll bump up that reminder to once a week for a while and I’ll ask for updates about her family member and ask how she’s doing. Again, this isn’t because I wouldn’t naturally do this, but that I don’t want it to fall through the cracks – being supportive of this friend and being in contact with her is genuinely important to me and probably valuable to her as well.

It is so easy for a friendship to fall through the cracks and to just forget to follow up with friends. Ryze keeps that from happening. I check it daily and contact anyone it says that I haven’t contacted recently.

I Host Dinner Parties and “Game Nights” Rather Than Going Out with People

This is simply a move for keeping up with friends while being busy with adult life and also trying to keep my spending low. The solution is to just regularly host dinner parties – particularly potlucks, where I ask each person to bring something – at my home.

People come over with some food item in their hands that works as a side for the meal or a dessert or a beverage. I’ve usually prepared something in the slow cooker or have it cooking slowly in the oven or on the stove top when they arrive. We sit around and chat for a while, then we eat a meal together, then we chat for longer.

Sometimes, we’ll play a few board games. I have ones that I bring out for people who aren’t necessarily board gaming fans – nice light fare that stirs conversation, like Codenames. Sometimes, I’ll have a dinner party with other gamers and we’ll play something deep.

Sometimes, we’ll have a movie night and watch a movie together. I particularly enjoy our “bad movie” night where everyone is free to just make fun of the movie.

The goal, as always, is to cement friendships and connect with people and just enjoy time spent with people I like. Plus, it costs very little and it’s often met with reciprocal invitations down the road.

I Never “Eat Alone”

Whenever I eat a meal, I aim to eat with someone else face to face if possible. I eat breakfast and dinner with my family most days, and most meals on the weekends.

If I’m not eating with my family, I try to find somewhere to go where I’m not eating alone, if I can. I have friends that I brown bag with once or twice a week. I set this up by looking for friends in my area that work from home and simply suggesting that we meet up for lunch once a week to “get out of the house.” We usually meet at some neutral place where a brown bag lunch is fine, or alternate houses.

If all else fails, I’ll spend my lunch break eating at my computer while intentionally reaching out to people for social reasons. I’ll go through my list on Ryze and contact everyone on it with care and thought.

I Ask People for Advice All the Time

Whenever I have any sort of issue in my life, I look for people I know who can kick some advice to me. I do this with lots of personal decisions, almost every significant purchasing decision, and many other choices.

I’ll simply identify three or four people that I know and send each of them a message laying out my choice and asking for their advice.

I do this not just because I really get value out of their advice, but because people feel valued when you ask them for advice. It’s a great way to signal “your opinion really matters to me.”

I find that some of those friends often ask me for advice in return, which is great. Sharing advice back and forth cements that relationship.

When People Need Help, I Try to Actually Provide Meaningful Help, Especially When It’s Multiplicative

Whenever I see someone that needs a helping hand that I can actually provide with genuine action, I do so without worrying about it being reciprocated. I don’t worry whether or not my neighbor is going to repay me for a gallon of milk. I don’t worry if a friend is going to give me a couple hours of help after I spent the morning helping him move. I don’t worry if someone is going to give me something after I lend them a helping hand in a public setting. I don’t expect a friend to laud me if I come through for them in a pinch.

This is especially true if it’s multiplicative help – in other words, if I can do a small action that provides a big benefit for that person. I just do it if I possibly can and don’t worry about getting paid back.

I keep my eyes open for situations where help might be useful and I just jump in if I think I can help.

What I find is that a lot of that help isn’t ever reciprocated in any direct fashion, but when I need help, I almost never lack a helping hand. It’s just there.

I Smile and Greet People as Much as Possible When Anywhere Outside the Home

A final strategy that’s been really helpful is that I’ve practiced and become very used to smiling at people and greeting people. If I see people on the street, I look quickly in their eyes and smile and say hello in a warm way. I used to just keep my eyes down and say nothing and sometimes I still fall into that trap, but I consciously strive to do better.

If I see someone I know, I make an effort to say hello to them, even if it’s just a shouted hello and a wave across a parking lot if I’m in a hurry or stopping to talk for a few minutes.

Isn’t a Lot of This Obvious Social Stuff?

Much of it is, but it’s so easy for us to overlook these things in the busy rush of our adult lives and in our own personality quirks. It is much easier to overlook these things, come home and collapse in a heap of mental exhaustion, and then one day notice that our friendships have eroded. On top of that, I’m unabashedly an introvert, which causes me to naturally want to be quiet and clam up in mixed social situations.

For me, digital tools combined with a consistent effort to be better at conversation really help navigate these waters. Filling in my calendar with social events keeps me interacting with people, Ryze helps me follow up with relationships, and good social habits (practiced with thirty day challenges) also helps. This allows me to be social and build lots of friendships as an adult without going out on the town and without engaging in a lot of expensive social activities. These tools all work together to create a social framework for my life, one that has really helped me cultivate a lot of friendships without spending much money at all, and I encourage you to do the same.

Good luck!

The post Tactics for Friendships During (and After) Financial Turnarounds appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2z8NBl2

9 Alternatives To A Reverse Mortgage: Other Ways to Meet Retirement Expenses

A reverse mortgage allows you to convert the equity in your home to cash, but it also has some drawbacks. Consider these alternatives to reverse mortgages.

Source CBNNews.com https://ift.tt/2D9dZ2F

Culture With a Side of Exercise: Try a Bicycle Tour of Your City’s Murals

الجمعة، 26 أكتوبر 2018

Walgreens Balance Rewards Changes Are Coming, So Use Up Those Points Now

Affordable Care Act Open Enrollment Starts Nov. 1. Here’s How to Sign Up


When it comes to electing health care coverage, deadlines matter. Miss one, and you could find yourself facing thousands of dollars in medical bills down the road.

Starting Nov. 1 and ending Dec. 15 (in most states), uninsured Americans can sign up for coverage under the Affordable Care Act or renew the coverage they already have.

If you want coverage in 2019, you must enroll during these 45 days unless you later have a qualifying life event, such as getting married or divorced.

Some younger and healthier people may not think coverage is worth the monthly premiums.

But think again, says Gerald Kominski, a professor of health policy and management at UCLA.

“There’s the idea that ‘I take care of myself, I live a healthy lifestyle, I eat well, I don’t smoke — I’m going to be healthy and live forever,’” he says. “Nobody knows what the future holds. People with perfectly healthy lifestyles get sick every day.”

What’s New This Year Under the Affordable Care Act

For the first time since the Health Insurance Marketplace — a federally run service where people can shop for and enroll in private insurance — opened five years ago, Americans will not have to pay a financial penalty for failing to obtain insurance. But experts say it’s still critical to buy coverage.

It costs up to $7,500 to fix a broken leg, about $30,000 for three days in the hospital and into the hundreds of thousands of dollars to treat cancer, HealthCare.gov says. The average visit to an emergency room in 2016 cost $1,917, according to the Health Care Cost Institute.

Most working people can’t cover that kind of expense with their salaries or savings, says Kominski — who, three decades ago as a graduate student, needed an appendectomy that cost $15,000. Because he had a student policy, he says, his share was less than $100.

In addition, health insurance plans that provide free or low-cost preventive services and promote the early identification of problems reduce the likelihood that more expensive and extensive treatment will be needed later, said Jay Wolfson, professor of public health, medicine and pharmacy at the University of South Florida. Thus, they benefit even people who are healthy — or appear to be.

And when healthier people buy insurance, it costs less for everyone, he said.

How To Shop For an Insurance Plan in the Marketplace

Start by going to HealthCare.gov and clicking “get ready to apply” if you plan to enroll for the first time or “get ready to keep/change” if you had a 2018 plan through the Marketplace, also known as the “exchange.”

Some states operate their own exchanges. If you live in California, Colorado, Connecticut, Idaho, Maryland, Massachusetts, Minnesota, New York, Rhode Island, Vermont, Washington or the District of Columbia, you must apply through your state.

Application deadlines are slightly later in California, Massachusetts, Minnesota and Rhode Island, so be sure to call or check your state exchange’s website. In general, coverage begins Jan. 1, 2019.

Online, you’ll learn how to estimate your 2019 income for the application and find a checklist of information you’ll need, such a such as household size, the Social Security numbers and birthdates of your family members, W-2 forms or pay stubs and policy numbers of any current health insurance. Coverage is available only to U.S. citizens and legal residents.

With insurance through the Marketplace, you’ll pay a deductible and coinsurance — a percentage of a covered health service — of 10% to 40%, depending on which plan you choose. You’ll have to pay only up to an out-of-pocket maximum, and there are no yearly or lifetime dollar limits.

You’ll also get the benefit of discounts that insurance companies negotiate with health care providers. People without insurance pay almost two times as much for care, according to HealthCare.gov.

How to Apply, What’s Covered and What Help Is Available

You can apply by phone, in person with help from a navigator — a person specially trained to walk you through the process — through an agent or broker or by mail with a paper application. Volunteers certified by the Marketplace also may be available through nonprofit organizations such as community health centers or hospitals.

Coverage through the Health Insurance Marketplace is intended for those not covered by insurance at work or by government programs such as Medicaid, Medicare, Tricare (for members of the military, veterans and their families) or CHIP, the Children’s Health Insurance Plan.

Plans that comply with the Affordable Care Act, often called Obamacare, cannot discriminate against people with pre-existing conditions. They also must cover birth control and breastfeeding equipment and counseling, plus 10 “essential” services:

  • Outpatient care.
  • Emergency services.
  • Hospitalization.
  • Pregnancy, maternity and newborn care.
  • Mental health and substance abuse services.
  • Prescription drugs.
  • Mental and physical rehabilitation for people with injuries, disabilities or chronic conditions.
  • Laboratory services.
  • Preventive and wellness services and chronic disease management.
  • Pediatric treatment, including dental and vision care.

You’ll pay different premiums and out-of-pocket costs depending on the plan you choose. The government will subsidize your premiums if your income is between 100% and 400% of the federal poverty level.

Currently, that’s $12,140 to $48,560 for a single person and $25,1000 to $100,400 for a family of four. Income eligibility levels are expected to rise slightly for 2019; the new figures won’t be available until Nov. 1, 2018.

The lower your income, the higher the premium tax credit you’re eligible for (i.e. the help you’ll receive).

What Kind of Plans Are Available?

Insurers sell plans in four categories: Bronze (the least coverage and the lowest premiums), Silver, Gold and Platinum (the most coverage and the highest premiums). Depending on where you live, you may find several types of plans at each level.

You’ll want to make sure your doctors are in the plan you choose and that your prescription medications are covered.

You may have a choice of:

  • An exclusive provider organization (EPO), which covers services provided only by doctors and hospitals in a network, except in an emergency. You aren’t required to choose a primary care provider.
  • A health maintenance organization (HMO), which requires you to obtain care from doctors who work for or contract with the HMO, except in an emergency. You may have to live or work in the HMO service area.
  • A point of service plan (POS), which charges less if you use health care providers that belong to a network and requires you to get a referral from your primary care doctor to see a specialist.
  • A preferred provider organization (PPO), in which you pay less for in-network providers, but you can go to out-of-network providers for an additional fee. You don’t need a referral to go to a specialist.

Average unsubsidized premiums vary widely from state to state. The price of the Silver plan for a 27-year-old single nonsmoker ranges from a low of $278 per month in Indiana to $709 per month in Wyoming, according to the U.S. Centers for Medicare and Medicaid Services.

The figures apply only to the 39 states that use the HealthCare.gov platform. About 9 million people have coverage through those exchanges, according to the federal government.

Catastrophic Insurance

Catastrophic insurance is another alternative available to people younger than 30 and those who can claim a hardship exemption, such as homelessness, domestic violence or bankruptcy. You must apply for the exemption.

On the upside, catastrophic plans cover the 10 essential health benefits, offer specific preventive services for free and cover at least three visits to a doctor annually before the deductible is met. They also cost about one-third as much as more comprehensive plans.

The large downside is that the deductible — the amount the patient has to pay before the insurance company starts sharing the cost — is $7,900. Additionally, these policyholders aren’t eligible for a premium tax credit.

Kominski of UCLA suggests that consumers compare the coverage and cost of a lower-tier plan in the Marketplace before choosing a catastrophic plan.

Coverage That Doesn’t Meet Affordable Care Act Standards

As of Oct. 1, 2018, low-cost health policies became available for a one-year term, renewable for up to three years. Previously, they were sold for a three-month period of coverage only, and were considered stopgap insurance plans for people between jobs or otherwise temporarily without insurance.

It’s important to be aware that these policies don’t comply with the mandates of the Affordable Care Act, meaning they don’t have to cover people with pre-existing conditions or pay for any of the services the act deems essential.

Kominski warns that low-cost policies may seem attractive — until you need medical care. He compares them to a car that’s cheap, but only because it doesn’t have airbags or comply with air-quality standards.

“If you’re shopping for price, you’re going to get what you pay for,” he said. “If you want to expose yourself to risk, we can make health care really affordable.”

Susan Jacobson is an editor at The Penny Hoarder. She also writes about health and wellness. Follow her @SusanJacobson44.

The Penny Hoarder Promise: We provide accurate, reliable information. Here’s why you can trust us and how we make money.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder https://ift.tt/2JmpGU0