Thousands of courses for $10 728x90

الثلاثاء، 27 نوفمبر 2018

Simple and Hard

Personal finance success is simple. Personal finance success is hard. Those two things don’t contradict each other in the slightest.

Simple

The things that you need to do to be successful when it comes to finances are really simple.

Spend less than you earn. You can do that by either cutting back on your spending or figuring out a way to earn more money. You do this because eventually you won’t be able to or really won’t want to work any more and the leftover money is for that point in the future.

Use the remaining portion to pay off debt. When you don’t have any debt, start using the remaining portion away for the future. If you don’t know what to do with it, put it in an index fund so that it’s invested in lots of things.

Literally everything about personal finance is just an expansion on one of those ideas, and even the expansion on those ideas isn’t really very complicated. Everything you really need to know is right there.

Hard

If it’s so simple, why doesn’t everyone do it? Why are 78% of Americans living paycheck to paycheck (source)?

The reason is that actually executing those simple strategies is quite hard, for numerous reasons.

Humans are predispositioned to favor the short term over the long term.

Modern culture surrounds us with seemingly infinite temptation, more easily available than ever.

Financial change requires us to take action to change our behavior, whereas staying in the same place requires nothing from us.

The financial services industry does their best to make simple things seem as complicated as humanly possible so that you feel that you need help with the arcane specifics of money management.

Those elements are individually challenging, but collectively they become quite hard to overcome. It’s the reason that most Americans struggle financially, even people who earn surprisingly high incomes.

It’s not rocket science to know what to do. The challenge comes from actually applying it to your life and doing it.

Most Self-Improvement Is Simple and Hard

This dichotomy of “simple” and “hard” exists with many of the most common things that people want to do to improve themselves.

Losing weight is simple. Eat fewer calories. Done. Actually executing it is hard.

Getting into shape is simple. Move around more and sweat. Done. Actually executing it is hard.

Improving personal relationships is easy. Devote time to that person and really listen to them. Done. Actually executing it is hard.

Acquiring more skills for success is easy. Devote time to study and practice of those specific skills. Done. Actually executing it is hard.

The thing you need to do is simple. Actually doing it is hard. Why?

Limited Resources

The reason why improving your finances – or improving other aspects of yourself – is hard to execute (even though the process is simple to understand) is because we have limited resources in life. I’m not talking about money. I’m talking about the fundamental resources we have as living humans. Time. Energy. Focus.

We only have so much time. In a given day, we have perhaps sixteen hours of wakefulness. We have to choose between different options to fill the limited time we have.

We only have so much energy. No one can keep going forever. Eventually, we get tired and worn out.

We only have so much focus. Eventually, we hit a wall of decision fatigue. We reach a point where we’re unable to keep stuffing more in our head and we have to rest for a while to recharge.

We aren’t robots, either. We need some downtime and leisure time to feel like we’re not just running through life from task to task.

The real question of self-improvement, whether it’s financial improvement or relationship improvement or physical improvement or anything else, is finding a more effective way to use those resources of time, energy, and focus that we already have.

So how do we use those resources more effectively to improve our financial state?

Time

Many of the most effective ways we have for improving our financial state rely on better time use. It’s due to a seeming lack of time that we rely on restaurants to get us through tight moments. It’s due to a seeming lack of time that we put off things like signing up for a 401(k). It’s due to a seeming lack of time that we hire people to fix things rather than investing the time to do it ourselves. It’s due to a seeming lack of time that we don’t build up our skills at work beyond the minimum.

(The same is, of course, true for other avenues of self improvement.)

We all have the same 24 hours in a day and 168 hours in a week. The difference comes in how we use those hours.

Look, I’m a full fledged member of the “sandwich generation.” I have children at home, a marriage to maintain and strengthen, a career to try to build and maintain, and aging parents, all at once. I want to be involved in the community and also have time for my own personal interests. Yet, through all of that, I find time for things like prepping meals in advance on a Sunday afternoon and getting a home-cooked meal to the table virtually every day and devoting time to professional side projects that can earn more income. I manage to find time to write in a journal and meditate and exercise virtually every day, too.

How do I do all of that? I use a handful of basic time management strategies. Here are the key ones that help me free up room for my career.

I basically don’t do anything that doesn’t have a strong long-term purpose or isn’t intentional leisure. If I find myself doing something like idly web surfing or playing a mindless smartphone game or staring at the television, I either go take a nap (or just go to bed for the night) or make myself go do something else. That’s not to say I don’t play games or watch television, but those are things done with intent – I’m playing a game with some social context or I’m watching a planned television program with my wife that we’re both excited about.

I block off time for things that are “important but not urgent.” I keep a weekly calendar and on that calendar I have time blocked off for things that I consider important but aren’t urgent. I have blocks of time for calling my parents. I have blocks of time for focused activities with my kids. I have a “date night” blocked off with Sarah. I have a “game night” blocked off to play tabletop games with some close friends. I have a block most weekends where I literally do frugal tasks and financial tasks, like prep meals or do small home repair or maintenance projects or pay the bills and read statements.

I prioritize “important but not urgent” over “urgent but not important.” I’ll often postpone things like perfect house cleaning to call my parents. I look at the mail once every two weeks or so and chuck most of it at a glance – it’s all “urgent but not important.” I barely read social media outside of the postings of real life friends – instead, I do a lot of little tasks so I can spend real world time with those real life friends. Not only that, I spend time thinking about how I’m spending my time, which seems fairly “meta” but when I recognize that I’m spending time on things that aren’t really important, I try to toss those things out of my life.

I do a lot of “time blocking.” I trust in my calendar. I block off time at the start of each day for the things I want to complete that day (starting from a generic “weekday,” “Saturday,” and “Sunday” template). For example, I’m in the midst of a “writing” block right now, one that I have tagged with the specific task of finishing this article. If I finish this article before the end of the “writing” block, I turn to my to-do list of smaller tasks and handle anything on it that’s tagged with “writing” (which is mostly brainstorming, reading, research, or outlining). When that time block is up, I stop. I try to never have my life in a situation where I have to disrupt that block because something is urgently due – I work ahead as much as I can.

I de-commit from things that decrease in importance to me. I’m not the person I was five years ago. Things I thought were important then, things I strongly committed to, aren’t necessarily the things I’m committed to now. Yet, sometimes, I have big lagging responsibilities and routines from that earlier era. The best thing I can do, both for me and for that thing to which I’m less passionate and committed, is to properly transition that thing into the hands of someone else. If I find that I’m less committed to something like coaching youth soccer or serving a charity than I once was, I make the conscious choice to back away while ensuring that it’s left in good hands.

These strategies all together help me find time for the things I find important in my life, and one of the things I find very important is doing what I can to build a strong financial foundation for my family and my own future. For example, I literally have a “time block” that’s set aside for financial and frugal tasks each weekend when we’re not traveling.

Energy

Like a lot of people, there are times when life just leaves me feeling burnt out and exhausted. No matter what kind of time management magic I can weave, I can’t help the fact that my energy level surges and flags throughout the day. Here are some of the things I do to help accommodate this, so that I have energy left over for doing a frugal task or paying attention to a bill or being mindful at the grocery store.

I get plenty of sleep. I go to bed pretty early most nights, usually around 9 PM. This is so that I can wake up when I naturally want to arise and feel deeply refreshed from a night of sleep (this usually happens between 4 and 5 AM). It is very rare that I feel genuinely tired during the day, though I will often find my energy flagging after 8 PM. I get plenty of sleep so that I can execute the rest of the day with lots of energy and focus. I’d far, far rather have 15 or 16 hours of energized activity in a day than 18 or 19 hours of activity where I’m tired and can’t focus.

I’m aware that I’m a morning person and that I flag badly in the early afternoon and late evening, so I schedule tasks accordingly. I start off the day with a morning routine and then a period of intense work, because I know my energy and focus are high in the morning. In the early afternoon, I do mindless tasks like going on a long walk or doing household chores. After that period of time passes, I usually have another block of productive work until the kids get home. In the late evening, my energy flags pretty badly, so I usually finish the day with a few mindless tasks (emptying the dishwasher) right before bed.

I consistently exercise. I find that if I stick to a consistent exercise routine, my energy level throughout the day is higher, and that if I let that exercise routine fade away, after a few days, my energy level starts to slide, too. Thus, I find it’s worthwhile to block off some time each day for some form of exercise. My goal is to get myself sweaty and make at least one muscle group sore the next day (though I don’t try to make the same muscle group sore multiple days in a row). I don’t aim to kill myself or do anything I don’t enjoy.

I try to eat a healthy diet. I’m not perfect at this, but I make it my goal to ensure that the vast majority of what’s on my plate at each meal is plant based, which seems to help a lot with my energy level, particularly mental energy. I find that when I overeat “heavier” foods, I end up in a bit of a mental fog for a while, so I try to avoid doing that. I eat mostly lighter meals with some snacks here and there.

Together these strategies help to ensure that I have plenty of energy for the things I want to do during the day, which, given the time management elements described above, result in having time and energy for tasks that I want to achieve.

Focus

Focus refers to one’s ability to stay on task. You’re not distracted and you get the task done efficiently and effectively. So much of the modern world eats away at our natural focus – constant interruptions and notifications from our smartphones and the convenience of the internet and social media being chief amongst them. Being able to focus on a task not only gets it done quickly and done well, but it frees up time for other things. An improved ability to focus also improves your ability to make good decisions, especially later in the day.

Here are four things I do to help maintain my focus.

I kill distracting things. I turn my smartphone off for most of the day. As I write this, my smartphone has been off for hours. I have my computer set with all kinds of different blocking tools so that the only thing I can really do with it is write. I’m listening to audio intended to help me focus in my headphones to block out distracting sounds. When my kids come home, we read together for half an hour – I put my phone in “do not disturb” mode and set a half an hour timer and just get lost in a book with them. In other words, when I have a task to do, I do everything I can to focus just on that task and not let distractions interrupt me. I check on potential distractions and interruptions when the task is done. During the task, I keep a notebook open near me to jot down stray thoughts I want to work on later. I do that as much as humanly possible.

I block off time each day to meditate. I practice mindfulness meditation for about fifteen minutes each morning and about ten minutes each evening. It is probably the single best discovery I’ve made in the last five years or so. This simple practice of stopping and focusing on my breathing as intently as I can has made it so much easier to focus on tasks throughout the day. I just sit in a comfortable chair, focus on my breathing, bring my mind back to the breathing if my mind floats away, and let the world pass by until a timer stops me. I find that if I chain a lot of days of meditation together, it builds on itself – one or two days doesn’t really change anything, but a chain of 60 days makes a profound difference. Like exercise, it can fade if you don’t keep up with it, but it’s really powerful if you let it build.

I listen to focus-enhancing audio during many tasks. I like listening to white noise, chillhop, or ambient electronic music – basically anything that’s downtempo without lyrics or simply nonintrusive white noise works. It seems to work magic at helping me focus on whatever it is I’m doing at the moment.

I constantly use “do not disturb” mode on my phone. This keeps my phone from delivering notifications to me and also blocks phone calls except from a very small list of key numbers that are okay for interrupting me (like my children’s schools). I turn this on all the time so I can stay focused on what I’m doing. There are very, very few things in life that are simultaneously important and urgent enough to cut through my ability to focus on a chosen task. What I’m doing right now is important or else I wouldn’t be doing it, so why let it be interrupted by silly small things?

Thought Influence

A final area that’s really worth noting is what I like to call “thought influence.” We fill our world with things that influence our thinking, both positively and negatively. If we fill our world with thoughts that point in a certain direction, our own thoughts are going to inevitably point that way. You’ve probably seen this in the world around you, how people are heavily influenced by the media they consume and the people they surround themselves with.

I want to surround myself with things that influence me to make good decisions regarding the things I care about most in life – good financial choices, for example. Here are a few ways I achieve that.

I intentionally choose close friends that practice frugality and are reasonable with their spending. At this point, it is prohibitively hard for a big spender to build a close friendship with me. While I enjoy having a group of friends that think differently in a lot of ways, what I don’t want in my life are friends that influence me to spend money unnecessarily. If there’s an aspect of my life that I’m really working on, I’m going to accentuate friendships with people who are successful in that area and tone down friendships with people who are bad influences in that area.

I basically avoid the news and only use social media for professional reasons and to directly contact real life friends. There’s almost nothing positive brought into my life by the wilds of social media or by the news media. It doesn’t inform me and it doesn’t make me feel good about myself or other people. I prefer to be informed by reading good reporting (which takes time), thoughtful books, and by having thoughtful conversations with good friends, so I stick to those things in terms of being informed. The most valuable thing on the internet for me is Wikipedia, because it’s a good tool for getting a quick peer-reviewed summary of a topic.

I don’t really care what other people think of me. This may be an aspect of getting older, but I just really don’t worry about being seen as “cool” by other people. I’m okay with being the guy who’s exercising and sweating in his backyard. I’m okay with being the guy who makes his own laundry soap. I’m okay with being the guy who basically doesn’t watch television and has no idea what’s going on on the latest shows. I treat other people exactly as I would like to be treated. This not only helps in terms of how I’m influenced by others, but that also turns into much less of a motivation to spend any money to impress others.

Final Thoughts

The goal with all of these things is to take something that’s simple and hard – personal finance, fitness, weight management, whatever you’d like – and keep it simple while making it less difficult. I do this by amplifying the resources I already have for tackling hard things in my life – my time, my energy, my focus, and the things I allow to influence me. If I put in the effort to maximize those things, then it becomes much easier to accomplish the things I want to accomplish in life. If I have time, if I have focus, if I have energy, and if I have good influences, it becomes far easier to tackle something that seems “hard” like improving one’s finances. It’s still not easy – it still requires attention and behavior improvement – but it’s not as hard if you come at it with plenty of resources in hand, and these strategies are how you get the resources you need to do it.

Good luck!

The post Simple and Hard appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2r8PmLf

Earthships Look Weird, But Could Save You Over $2K in Utilities Per Year

Potential Employer Wants to Contact Your Current One? Here’s What to Say


Some questions on job applications can be worded too simply for their own good.

For example, how are you supposed to answer the question, “May we contact your current employer?” when the only options are “yes” and “no”? Your first thought might be, “No, my current company doesn’t know I’m job hunting.” But is it bad to say no? Will the human resources specialist reviewing your application think you’re hiding something?

We asked four seasoned HR professionals to weigh in.

Why Is This Question on Job Applications?

Lynda Spiegel, founder of Rising Star Resumes and a 14-year human resources pro, says companies ask the question to get a head start on the employment verification process. At some point, the company will want to do a background check, and including this question is HR’s way of getting permission. She adds that it’s much easier to ask for permission upfront versus possibly forgetting to ask deeper in the interview process.

“Nobody is going to contact your current employer just based on you sending in a resume,” she says. “That's going to happen way down the line.”

Most companies contact the applicant's previous organization sometime between offer acceptance and the hire’s official start date, says Laura Sehres, vice president of talent acquisition and engagement at PSCU. During verification, the new company will call the applicant’s former employer to confirm specifics such as job title, employment duration and salary.  

Saying No Isn’t a Red Flag

If you’re currently employed, it is perfectly acceptable to click no when filling out the job application, says Mikaila Turman, the director of people at Inflection. From her perspective, the reason people get stuck on this question is that candidates think there is a right and wrong answer.

“I think there's an assumption that if I say no, then that's going to look bad, but that's not necessarily the case,” she says. “It's more so to inform the HR person whether they could move forward with getting a reference from the current company or not.”

The last thing an HR recruiter wants to do, she says, is jeopardize an applicant’s job by tipping off their current employer that they have someone searching for a new opportunity.

“If you're currently working and you don't want your employer to know that you're looking, you simply say no, and that’s not a red flag,” Spiegel says.

When Should You Say Yes?

Keep in mind, selecting no should not be an automatic response for those gainfully employed. If your current company knows you’re leaving, it’s safe to say yes. Lois Krause, the HR compliance leader at the consulting firm KardasLarson, LLC, says it’s not uncommon for managers to try and help those affected by impending layoffs by providing references.

“They're usually pretty good about giving [employees] a heads-up so that they can find something,” Krause says.

When layoffs are not the driving factor, job seekers might consider selecting yes if the employee has a great relationship with their supervisor. “Maybe [the employee] talked to their manager and said, ‘This isn’t working, and I’m going to look for another role.’ Sometimes people are very honest about that,” says Sehres.  

When Applications Give You More Than Two Options

Depending on the format of the application, you might have the option to give a detailed response instead of being limited to a yes-or-no answer. When the opportunity presents itself to elaborate, Sehres encourages people to add in an extra caveat for clarification.

“I always answer it this way: ‘No’ or ‘Yes, you can contact after offer,’” she says.

Once you’re selected to advance to the initial phone or in-person interview stage, Sehres suggests talking to the recruiter to clarify any confusion on why you said no.

“My advice to someone who is truly concerned about it would be for them to head it off at the pass,” she says. “Say upfront: ‘I answered it this way. I am comfortable with you contacting my employer but only after an offer is given, just out of confidentiality.’”

Matt Reinstetle is a staff writer at The Penny Hoarder. He covers career advice and side gigs. If there’s a career-advice topic you want to be answered, please email him at mattr@thepennyhoarder.com.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.

The Penny Hoarder Promise: We provide accurate, reliable information. Here’s why you can trust us and how we make money.


source The Penny Hoarder https://ift.tt/2AqP32U

The Future of Corporate Megadeals After Amazon HQ2

As details of the huge tax incentives offered by many states to lure Amazon HQ2 became public, some residents of the rejects wondered if their states dodged a bullet.

Source Business & Money | HowStuffWorks https://ift.tt/2ztMpJL

The Future of Corporate Megadeals After Amazon HQ2

As details of the huge tax incentives offered by many states to lure Amazon HQ2 became public, some residents of the rejects wondered if their states dodged a bullet.

Source Business & Money | HowStuffWorks https://ift.tt/2ztMpJL

When Your Spouse’s 401(k) Is the Better Plan

If you and your spouse or partner both have access to a 401(k) or other employer retirement plan, you might be wondering how you should divvy up your contributions between the two of them.

This can be an especially difficult and emotionally-laden question if one of those 401(k)s is measurably better than the other, in which case it may make rational sense to contribute more money to that 401(k) even if it would leave the other spouse or partner with less money saved for retirement.

So, what should you do in that situation? Should you split your contributions evenly, even if it means putting money into a bad 401(k)? Or should you contribute more to the better 401(k) even if it means that one of you will have more money than the other?

Let’s break it down.

What Makes for a Good 401(k)?

Before getting into the details of what you should do, it’s important to define what’s meant by a “good” 401(k). Without that definition, it’s impossible to even know whether one 401(k) is better than any other.

First and foremost, a good 401(k) is defined by a good employer match. And the experts I spoke to agreed that taking full advantage of any match you receive is almost always worth it.

“You want to make sure you get all of the free money from those matches even if it means different contribution rates,” said Lucas Casarez, CFP®, owner of Level Up Financial Planning. “A 100% match on contributions easily outweighs investments with slightly higher investment expenses.”

Along with looking at each 401(k)’s match, Casarez said that it’s also important to understand how those employer contributions vest over time.

“Some employers’ matches are 100% vested immediately, some occur over time,” he said. “The faster the vesting schedule, the higher the probability that you will retain the full employer match.”

Another important factor to consider is cost. Lower costs generally lead to better returns, so prioritizing whichever 401(k) allows you to minimize costs may be a good idea.

“Expenses charged by the plan can be a major drag on returns,” said Jeff Burke, CEO of 7 Street Financial. “Even small fees can add up over time.”

Of course, the investment options offered by each 401(k) are also an important factor. Nicolas Stanley, CFP®, founder of Protogè Wealth Planning, pointed out that some 401(k)s have a relatively limited set of investment options while others allow you to choose from among thousands of mutual funds in a self-directed portfolio, which may make it easier for you to implement your desired strategy in a cost-effective way.

The ability to make Roth contributions could also be a big factor, depending on your specific circumstances.

“While it’s not right for everyone, the tax advantages of Roth contributions are quite powerful,” said Ian Bloom, founder of Open World Financial Life Planning. “Potentially tax-advantaged savings with tax-free money in retirement? Having access to that is a big deal.”

To sum up, the major factors to consider when evaluating whether one 401(k) is better than another are:

  1. The employer match
  2. The vesting schedule on that match
  3. Plan and investment fees
  4. Investment options
  5. Availability of Roth contributions

Is There Risk in Contributing More to One Partner’s 401(k)?

The obvious concern with the idea of contributing more to one spouse’s or partner’s 401(k) is that it would leave the other without as much money saved for retirement, which would potentially leave him or her at risk if the two of you were ever to split up.

But according to the experts, that concern can be alleviated by the fact that there is legal recourse to even out those funds in a divorce proceeding.

“In every state, funds accumulated during the marriage are considered marital property regardless of the name on the account,” said Leah Hadley, a Certified Divorce Financial Analyst (CDFA) with Great Lakes Investment Management. “In a community property state, those funds are divided equally. In other states, the funds may still be divided, but that division is negotiated as part of the divorce settlement.”

Hadley said that if funds need to be moved from one person’s 401(k) in order to even out assets in a divorce proceeding, a Qualified Domestic Relations Order (QDRO) would be filed that would allow that to happen without penalties or tax consequences.

Still, Hadley did warn that there is some risk involved, even with those protections in place.

“Because 401(k)s are only in one person’s name, they are the only one who can request money from the account,” she said. “I have seen some divorce cases where one of the parties leaves the other party with no access to funds. While there is legal recourse, it takes time.”

There is also more risk involved if you aren’t married, as there isn’t a formal divorce proceeding that exists to ensure an equitable division of money.

“If you are not married, things get a little more hairy,” said Bloom. “There’s not necessarily a way for one partner in the relationship to get access to the other partner’s retirement funds. I would not recommend contributing more to one partner’s 401(k) if this is the case. Splitting up can be emotional enough without worrying about your financial future.”

Deciding Whether to Contribute More Money to One Spouse’s 401(k)

There’s one thing that all the financial planners I spoke to agreed on: It’s almost always worth maxing out every employer match available to you, even if it means contributing more money to one 401(k) than another. But even then, they recommended trying to even things out with additional contributions if possible.

“The only scenario in which I would recommend investing in one spouse’s employer-sponsored 401(k) plan over another is if one spouse’s plan has an employer match while the other spouse’s plan doesn’t,” said Ryan Firth, CPA, founder of Mercer Street. “But once that match has been reached, I’d recommend allocating remaining contributions so as to make the total contribution to each account equal.”

Chris Jackson, CFP®, founder of Lionshare Partners, adds that the specific considerations may change depending on where you are in life.

“For younger couples, the focus should be on maximum contribution including employer match,” he said. “Older couples, with larger balances, should focus on keeping the cost down, because an extra 1% on funds for a million dollar account is an extra $10,000 a year in fees.”

Beyond that, it’s important to start with your personal investment plan and what’s important to you. Minimizing fees should always be a priority, as should being able to match your target asset allocation. And depending on your situation, the ability to make Roth contributions may be important as well.

And at the end of the day, while it would be ideal for each of you to have the exact same amount of money in your retirement accounts, it’s helpful to remember that contributing more money to one spouse’s 401(k) doesn’t necessarily leave the other one at risk. Divorce proceedings are designed in part to help even out assets, and there are mechanisms in place that allow you to move money from one spouse’s retirement account to the other.

In other words, if there’s a big difference in 401(k) quality, you shouldn’t be too concerned about contributing more to that 401(k). Doing so is likely to put your family in a better financial situation no matter what.

Matt Becker, CFP® is a fee-only financial planner and the founder of Mom and Dad Money, where he helps new parents take control of their money so they can take care of their families.

More by Matt Becker:

The post When Your Spouse’s 401(k) Is the Better Plan appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2r9keLP

الاثنين، 26 نوفمبر 2018

How to Increase Your Sales ?ith Instagram Stories

No social media marketing strategy is complete without Instagram. But there is much more to Instagram than just uploading pictures and videos to your profile.

With a standard post, you’re somewhat limited to how much content you can upload in a given day or a week.

Let me clarify. Technically, you can post as much as you want. But that strategy won’t work.

On average, most brands post about 10 times per week. Uploading content more than once or twice per day to your Instagram profile will have a negative impact.

According to a recent study from Sprout Social, 58% of consumers say it’s annoying when brands post too much on social media. And 46% of users will unfollow a brand for doing this.

But you want to share your content with your audience. Sometimes, posting once or twice per day isn’t enough to get your point across.

That’s when you should be leveraging your Instagram story.

Unlike a traditional post, your Instagram story won’t flood the timelines of your followers. You can upload more than ten pictures or videos to your story, and it won’t hinder anyone’s experience. This isn’t the case with posts posted directly to your profile.

Instagram has more than 400 million daily active users. One-third of the stories with the most views are uploaded by businesses.

Taking advantage of this feature is a great opportunity for your brand to generate sales on Instagram.

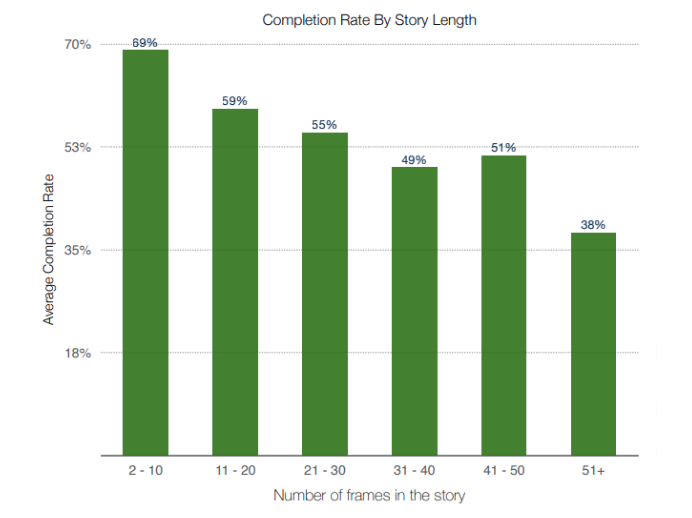
It’s worth mentioning that the longer your Instagram story is, the less of a chance it has of being watched in its entirety:

completion rate

That said, nearly 60% of people will watch your entire story that has 20 frames.

That’s more content than you would upload with traditional posts to your profile in an entire week.

You can create a new Instagram story every day since the old stories disappear after 24 hours. This means you get to start off each day with a clean slate.

There are many different approaches to Instagram stories that drive sales. That was my inspiration for writing this guide.

I’ve identified some of the best examples of Instagram stories from a wide range of brands. Using these approaches in your Instagram posting strategy will help you avoid stale content for upcoming posts.

This is the approach you need to take if you want to generate more sales on Instagram.

Set up a shoppable story

For years, in order for businesses to directly drive sales on Instagram, they had to rely on adding links to their bios to drive followers to  product landing pages.

That was ineffective since the user had to take too many additional steps.

But Instagram recently rolled out an update allowing brands to increase product sales with shoppable posts.

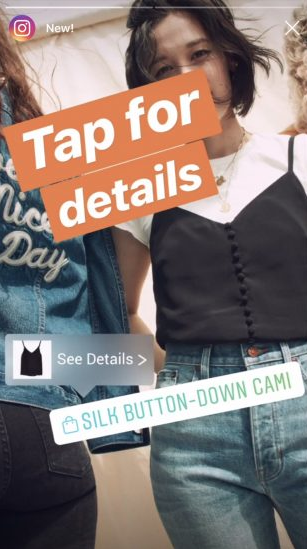
With a shoppable post, you can tag products in an image, the same way you would a person. When a user clicks on the tag, they are directed to a landing page that gives them the opportunity to buy what you’re selling.

Clicking on a shoppable tag has far less friction than having to navigate to your bio.

While many brands are taking advantage of shoppable posts, many don’t realize they can also use shoppable stories.

shoppable story

The same concept applies here.

On your story, just tag an item from your product catalog. Users who view the story will have an option to click on the tag and be directed to a page where they can complete the purchase.

If you want to directly drive sales, this is one of your best options.

You can add dozens of different products to your Instagram shoppable story. Or maybe you’ll take another approach and use your entire story to promote one product.

Whichever option you choose, you’ll be able to generate more sales with these strategies.

Run a poll

Polls on Instagram stories are a great way to drive engagement.

Unlike with a shoppable post, participating in a survey won’t directly drive sales, but it will still pique your followers’ interest.

Polls can triple your engagement metrics on a story.

That’s because they are easy. All a user has to do is click on one of the two options to participate. Plus, that’s the only way they’ll be able to see how other people have voted.

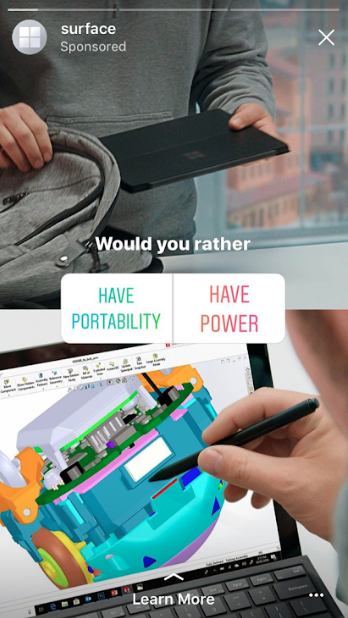
Here’s an example of how Microsoft Surface used this strategy in a sponsored story:

surface

It’s a very simple question.

They’re asking what’s more important to users, power or portability?

Here’s the catch. When users swipe up, following the “learn more” CTA, they’ll discover this product has both power and portability.

You’ll see more of this swipe up style CTAs throughout this guide.

Take advantage of the swipe up feature.

According to a case study from Marketing Land, 15-25% of users who see these links on Instagram stories are swiping up.

MeUndies participated in this study.

On average, 20% of users who saw its story swiped up to learn more. And 90% of those people have never visited the website before.

Adding a poll to your story increases your chances of getting higher engagement rates and, hence, makes it more likely that users will click your CTA. You’ll be able to generate more sales as a result.

Showcase testimonials to increase brand credibility

Testimonials are one of the best ways to increase credibility of your brand, products, and services.

In fact, 92% of consumers refer to testimonials when making a purchase decision.

Further, 88% of consumers trust a testimonial as much as a recommendation from someone they know. And 72% of buyers say they trust a business more after reading a positive testimonial about it.

Adding a testimonial to your story will definitely increase your chances of driving sales.

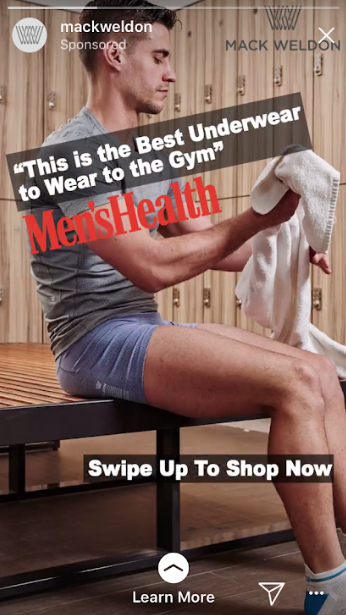
Here’s a great example from Mack Weldon:

mens health

It used a testimonial from Men’s Health to add credibility to its product.

If a reputable magazine such as Men’s Health says this is the best underwear for the gym, then they must be, right? That’s the idea behind this testimonial.

As you can see, Mack Weldon is also taking advantage of the swipe up feature.

By clicking this CTA, users will have a chance to buy products directly from the landing page. This process limits friction, which improves conversion rates.

It’s much more effective than asking your followers to navigate to your website by opening a separate web browser. Conversion rates for that method would be much lower.

Partner with a social influencer

You can also use influencers to increase your product’s credibility.

This strategy works for the same reasons as testimonials do. Followers will see a promotion from someone whom they trust and follow their recommendation as a result.

With influencer marketing, you don’t even need to post any content on your story.

Instead, you can have the influencers with whom you’re working promote your brand with their own stories.

Take a look at how CALIA by Carrie uses this strategy:

anastasia

CALIA by Carrie partnered with professional surfer and model Anastasia Ashley.

Anastasia shares this content on her own story, so it’s viewed by her followers. Now people who may have never heard of this brand are exposed to the promotion.

This strategy is a great opportunity for you to increase your reach.

With this widened exposure, you’ll have a better chance of getting more followers and increased website traffic. Both of these metrics can help you drive sales.

Encourage interactivity

This strategy is similar to that of the story polls, which I talked about earlier.

The whole idea behind encouraging interaction with your followers is they engage with your content. Keeping people engaged will help your brand, products, and services stay fresh in their minds.

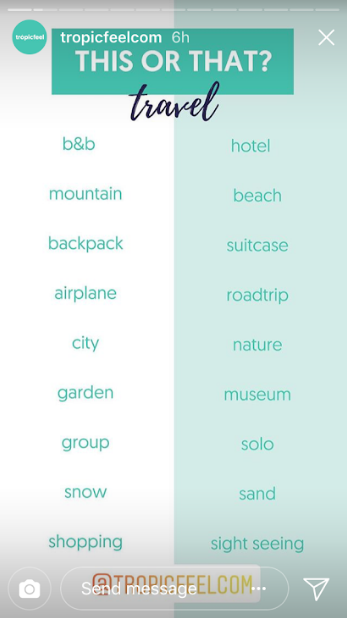
Check out this example from Tropicfeel:

tropic1

Tropicfeel is a startup company that makes the ultimate travel shoe. All of their promotions target people who like to travel.

Everyone travels for different reasons.

Adding this content to its story gave users a chance to share their answers about their travel preferences.

The level of engagement it takes to complete this survey is much higher than just clicking on a poll.

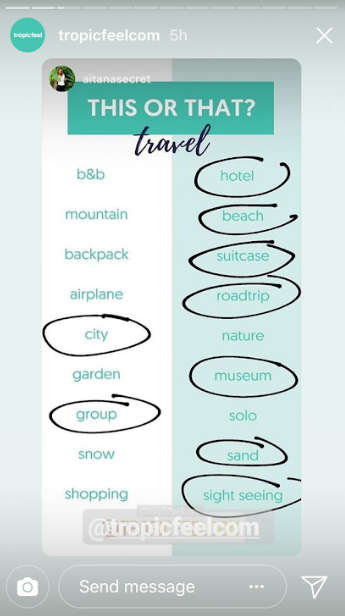
A user has to take a screenshot, then add the same image to their own story with their answers circled.

Then, Tropicfeel shared those responses back on its original story:

tropic2

It’s a clever strategy.

If you plan on doing something like this, you can’t expect the participation rates to be extremely high. That’s because it takes extra effort.

But it’s still effective. Even if some followers aren’t participating, they’re watching the story to view responses from other people.

All of this makes the company’s target audience think about traveling and potentially planning their next trip.

Maybe its followers need new shoes before their next excursions, which would entice them to make a purchase from this brand.

Repurpose user-generated content (UGC)

In the last example, you also saw repurposed user-generated content.

The only difference is it was produced as part of a campaign. But that doesn’t have to be the case.

There will be instances when your customers tag you in their stories without any encouragement from you.

Maybe they put on a new pair of sunglasses they just ordered from your ecommerce shop and want to show them off to their followers. So they upload an image to their story and tag your brand.

You’ll be notified any time your brand is tagged in a story. From here, you’ll have the option to share that same content to your own story as well.

Look at how Patara Shoes uses this tactic:

patara

Repurposing UGC accomplishes several things.

First, this type of content will have the same effect as a customer testimonial, which I previously discussed.

Sharing a story like this also shows your followers you’re willing to repost content your brand is tagged in. This gives them some encouragement to do the same for a chance to be featured.

With more of your followers posting about your brand on their personal profiles, you end up getting social influencers free.

These people may not have thousands of followers as the influencers whom you’re paying, but their content is still valuable and can lead to additional sales from anyone who sees their stories.

Follow a progression

Earlier I talked about how you can upload lots of frames to your story each day, which isn’t recommended for a traditional post.

But the frames shouldn’t be random.

If you refer to some of the examples you looked at so far today, you wouldn’t want to combine all of them into one story.

I see brands make this mistake all the time. They forget that their Instagram story should actually tell a story. This means it needs to follow a logical progression.

Here’s an example from Thule:

thule1

The story starts with a date.

This will grab the attention of anyone watching and make them curious as to what’s happening on this date.

As a result, they’ll continue watching to learn more information:

thule2

As the story continues, they’ll learn there will be some type of celebration.

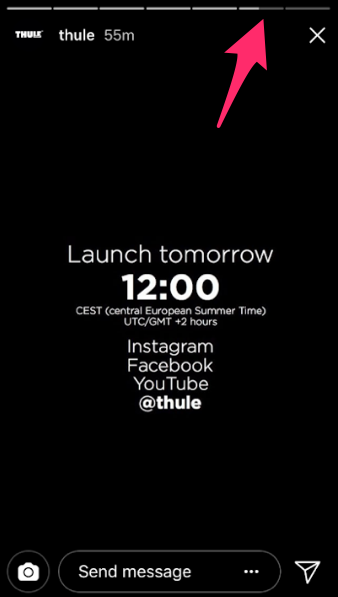
Users will continue on:

thule3

Now things start to get more specific.

Thule shares the time of the celebration and hints at a product launch.

This story had seven frames. We looked at just three.

Imagine if all three of these frames were combined into one. That would be way too much text on the screen.

Now imagine if seven frames of text were crammed into just one.

It would be overwhelming and difficult for people to read. The message would be lost.

A progression like this makes it easier for people to consume it and more likely that they will do that.

If you’re trying to introduce a new product or event to drive sales, you can do it over several images or videos as opposed to just one.

I’ll show you another example of this type of progression below.

Introduce your team

I love the idea of showing your employees on your Instagram story.

This concept adds a human element to your brand, which goes a long way. It allows your followers to see you’re more than just a company. Real people they can relate to are the driving force behind your operation.

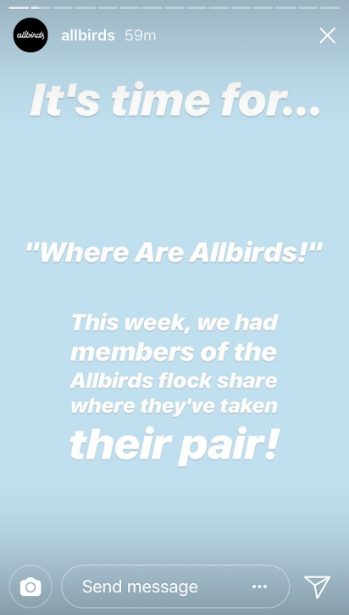
Let’s look at how Allbirds did this on its Instagram story:

allbirds1

As you can see, this story follows a progression as well.

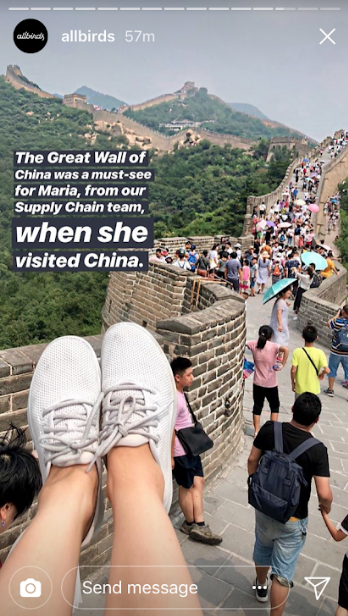
Instead of showing its employees out of context, the company starts the story by saying it wants to share images of where the team has gone with the product.

Here’s one example from the dozen or so posted:

allbirds2

Maria, an employee from the supply chain team, wore the company’s product to the Great Wall of China.

This story shows that its employees stand behind their products. They own them and actually use them.

But if you don’t have this type of content to share on your story, it doesn’t mean you can’t introduce your team.

Another way to do this is by showing behind-the-scenes looks at your operation.

Any time an employee achieves something, you could share that accomplishment on your story.

Again, this strategy will humanize your brand and make you more relatable to your followers. These types of posts are perfect for your story.

Promote a new product launch

As I said earlier, you don’t want to flood the timelines of your followers with promotions all the time.

This is annoying and will eventually cause people to unfollow you.

But if you have a new product coming out soon, it’s a big deal. You want to start promoting it as soon as possible. That way, your customers are ready for it by the time it’s released.

Use your story to accomplish this.

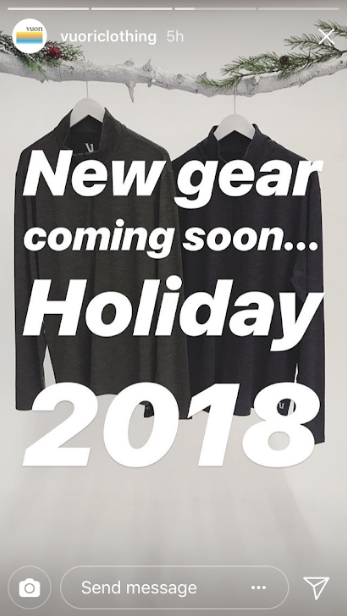
Here’s a simple example from Vuori Clothing:

vuori

It’s a great way to use the 2018 holiday season to drive sales.

You can go into greater detail about your products in your story, depending on what you’re promoting.

For example, you could upload a video tutorial to your story showing how to use the new product.

Combine this strategy with some of the other tactics on this list and have a social influencer do the same thing for you.

Building hype for your products before they launch increases your chances of generating sales when they finally become available for purchase.

Conclusion

Instagram has become a powerful tool for brands. But that’s only the case if you’re taking advantage of all the features available.

Simply posting content to your profile isn’t enough. Plus, you should be uploading only one or two images or videos each day.

You have much more flexibility with the amount of content you post to your Instagram story.

Promote your products directly by using a shoppable story.

Run a poll and encourage interaction to drive engagement.

By showcasing testimonials, partnering with social influencers, reposting user-generated content, and introducing your employees, you’ll be able to add more credibility to your brand and products.

All of your stories should follow a logical progression.

If you follow the tips and examples I’ve outlined above, your Instagram story will help you generate additional profits.

How is your brand using Instagram stories to drive sales?


Source Quick Sprout https://ift.tt/2Rfm3C6

Questions About Coaching, Used Guitars, Family Gift Exchanges, IRAs, and More!

What’s inside? Here are the questions answered in today’s reader mailbag, boiled down to summaries of five or fewer words. Click on the number to jump straight down to the question.
1. Stock market dropping!
2. IRA maximum income question?
3. Simple small business budgeting software
4. Financial coaching services
5. Smartly using a small windfall
6. Improving communication skills at work
7. Environmental benefit of reusable bottles
8. How to find used guitars?
9. Thoughts on nootropics
10. Long lasting computer?
11. Holiday gift exchanges
12. Are Christmas lights just disposable?

I admit it. I went shopping on Black Friday.

I bought a discounted HDMI switch for our television because our old TV has two HDMI ports and we have three devices that need to be hooked up. Now, rather than unplugging and plugging things, we can just hit a button. Total cost? $10.

I also bought a Christmas gift for my wife, something I’ve thought about for years. The retailer that makes them had a Black Friday sale on their site, something I don’t believe they’ve ever had before, so I used their discount code and bought her that long-planned gift.

That was the extent of my Black Friday purchases. I’m a big spender, let me tell you.

On with the questions.

Q1: Stock market dropping!

In the last two months the stock market has lost about 15% of its value. Are you still recommending stock investments?
– Alex

To me, the day to day and month to month ups and downs of the stock market are basically irrelevant.

Here are the questions I care about: are large American blue chip companies in a wide variety of industries failing all at once? Are people simply not creating new startups? If you start answering “yes” to those questions, then we might have something to worry about.

As long as the big blue chip companies keep chugging along without mass failure, and as long as new startups are launching consistently, I’m not worried about the long term health of the stock market one bit. There are always going to be ups and downs, bull markets and bear markets, hot economies and recessions. That’s all cyclical, and this is a normal response to almost a decade of straight positive moves in the stock market. We’re due for a recession of some kind.

If you’re investing in stocks in such a way that short term changes (1-3 years) really matter to you, then you shouldn’t be investing in stocks. You should be in something less volatile, like bonds or cash.

Q2: IRA maximum income question?

My income (filing jointly with non earning spouse) may exceed 189k (not sure as commission based) in 2018. i have already contributed some money in my traditional IRA. what should I do if my income gets over maximum requirement?
– Tim

There are no income limits for traditional IRAs. You can contribute to a traditional IRA no matter what your income is.

However, there are income limits for being able to deduct traditional IRA contributions from your taxes. In 2017, singles with an income of $62,000 and married joint filers with income of $99,000 (or less) were able to deduct their full contribution. Above that, the deduction gradually phases out, disappearing entirely at $72,000 (for single filers) and $119,000 (for joint filers). You’re far above that.

So, to summarize, you should be able to make traditional IRA contributions with no problem, but you won’t be able to deduct those contributions from your taxes.

Q3: Simple small business budgeting software

I am looking for a budgeting software similar to Mint, but that works for small businesses. I read the blog post on budgeting software, but can you recommend one that works for small business budgeting and tracking?
– Jane

The closest thing to Mint for small businesses is Quickbooks, which is actually made by the same parent company as Mint, Intuit. I used an early version of Quickbooks in the past, though my need to do so has passed, and it was very user friendly and convenient.

The only catch is that Quickbooks is that it’s a subscription-based package, with a thirty day trial and plans starting at $6 per month.

I would give that low end version a try, at least through the 30 day trial, and see if it works for you. I really do recommend it.

Q4: Financial coaching services

Do you offer financial coaching services? What are your rates?
– Oleg

No, I do not offer financial coaching services, nor will I ever. It is an avenue by which I could make significant money, as I have had many situations in the past where people have requested my financial coaching services.

There are two big reasons why I don’t do it. One, my first piece of advice to anyone hiring my service would be to cut out non-essential spending, of which one piece would be my services as a financial coach. That, to me, should be the first piece of advice from any financial coach worth their salt – cut out nonessential spending – and that advice, if taken, would result in the elimination of that financial coach. To not give that advice would mean that I wasn’t doing my best job for the client, so I’d be in a situation where I was either telling people to fire me or being a huckster, and I have no interest in either.

Two, all of the advice and “coaching” you need is freely available on the internet. Financial change isn’t complicated at its core – it mostly boils down to having the willpower and discipline to actually execute. If you can’t summon the discipline to say “no” to an unnecessary expense on your own, then no coach can help you; if you do have that discipline, then you don’t need a coach.

Q5: Smartly using a small windfall

I’m a single woman in my mid-40’s with no debt. I have a 6 month emergency savings fund, with an additional $15K earmarked for a car if/when I decide to buy one. My retirement savings include approximately $60K in a Roth IRA (have maxed out for last 4 years and will continue to), $4K in a pension, and a small Acorns fund. I’m great at frugality and saving. Years of low salaries, under- and un-employment have been challenges. My employment is stable for now, but I’m looking to switch careers. I’ve been gifted with $10K I’d like put towards my retirement savings. My goal is to open an account with this money, then contribute $150 weekly. Any suggestions on where to invest or the type of account to open? I like what I’ve read about Betterment and Swell (Swell’s probably too risky for my taste right now). I consider this money as a kick start for more retirement security and want it to grow well.
– Dana

If I were you and were contributing that much to start, I’d just open an account directly with Vanguard and put the money into one of their index funds like the Total Stock Market Index Fund. Sites like Betterment and Swell are good for getting started, but once you get into the five figures, you’re usually better off investing without the training wheels.

Spend some time looking at what Vanguard has to offer, like their LifeStrategy funds (they’re pretty good for targeting a certain risk level) or just browse all of their funds.

I recommend Vanguard because it’s what I use. I have my Roth IRA with them and some additional investments as well.

Q6: Improving communication skills at work

I read in your article that your boss gave you this advice: “You are good at writing but extend that to speaking.“ I am also working on the “data world” and those words exactly resonate with me. At work, i’m just always heads-down busy and focused in my data analysis tasks. But at the end of the day, I keep telling myself “I wish my job will entail more human interaction and communication”. If I could be a good speaker, I will welcome that, too! So, what actionable advice can you give me regarding this “desire”?
– Lisa

I’m assuming from your question that there are limited options to present at work, or even to talk to other people in your field. In that case…

Go to conferences. That’s my number one recommendation. Identify a few conferences related to your field and attend them. Attend only the sessions that really speak to you, and then spend the rest of the time talking to people in your field. You’ll really have to turn on your “social” game when you’re there.

After you have your feet wet, try to get a presentation slot at a conference. Submit a proposal for a talk and, if you get a slot, practice it and hone it until you could give it blindfolded.

Until then, see if there are any professional groups or special interest groups in your area related to your field. Meetup is a good place to start. Start going to their meetings and getting to know people. If there’s a chance to present something related to your work, jump on it.

Q7: Environmental benefit of reusable bottles

I think it’s important to include the environmental saving of Sodastream as well, you’re obviously not adding to the single use plastic bottle problem, I for one use Sodastream knowing that I won’t be discarding a soda bottle and choking a dolphin tonight.
– Erik

This is a big part of why I use reusable water bottles as much as possible. I really don’t want to fill up a landfill with my disposable plastic water bottles. I’d far rather use a water bottle for years and only dispose of it when it actually cracks or breaks.

For carbonated water, SodaStream is basically a specific brand of home carbonator set up to make it pretty easy to do with reusable bottles.

I kind of “weaned” myself off of wanting fizziness in my water. I used to feel like it was essential, but now it’s not a big deal. I mostly just fill up bottles with noncarbonated water from the tap.

Q8: How to find used guitar?

I want to take up playing guitar as a hobby. I don’t want to go buy an expensive new one. Tried finding a used one locally on Craigslist or Facebook Marketplace but no luck. Any ideas on how to find a used guitar?
– Jerry

First, I’d check Freecycle in your area. I have seen used guitars on there. I’d also look at your local Goodwill and Salvation Army stores.

Next, I’d put a shout out to my social network. Ask your friends if they have an old used guitar in the closet that you could have or buy for cheap. You’d be surprised how many people have a guitar stowed away that they intended to learn how to play and never bothered.

If that doesn’t work, you could put out a request in a community group, especially if you are in a buy/sell/trade group. Most towns and cities have Facebook groups dedicated to local buying/selling/trading and if you’re looking for something you can just put out a request.

If you exhaust all of those options, I’m pretty sure you’ll find a guitar.

Q9: Thoughts on nootropics

What do you think about nootropics? Do you use any? Do they help you focus on work and be more productive?
– Alexandra

For those who don’t know what nootropics are, they’re drugs, supplements, and other substances that are intended to improve cognitive function, particularly executive functions, memory, creativity, and motivation. I like to think of them as “vitamins for the mind.”

The only “nootropic” I take is coffee and pretty potent green tea in the mornings. I’ll drink them in an alternating fashion right at the start of my workday and then turn on some “focus” music. I find that it’s a useful part of getting me primed to write in the mornings and I do notice when it’s not present. At the same time, if I do that every single morning, the effect starts to slide. I’m far better off drinking a bunch of coffee and potent green tea once or twice a week rather than every day. (In nootropic terms, this means that I consume caffeine – mostly from the coffee – and l-theanine – from the green tea – in rapid sequence.)

Although I have friends that have tried other things to help cognitive function, I’m not sold on the relative risk and reward of such things and generally avoid them.

Q10: Long lasting computer?

Where can you buy a computer that will last a long time? We are finally getting rid of computer we bought in 2003. We use it for email and internet. Don’t want to get junk that will fail in three years. Suggestions?
– Danny

Computers are not really “buy it for life” items. They don’t slow down per se, but over time software becomes more and more demanding and resource hungry as it’s expected to do more and more things. Since 2003, your computer switched from barely being online to probably being expected to watch high resolution video and that’s a much higher demand on a computer, thus it runs that application much slower.

In my experience, if you’re buying a computer for maximum lifespan for normal home use, you can get a cheap one that will keep up for 4-5 years or an expensive one that will keep up for about 8 years. Since the price of a cheap one is about a quarter of an expensive one, I’d vote for getting a good cheap one.

Consumer Reports suggests that the best budget desktop out there right now is a Dell Inspiron 5680. Dell identifies the model as a “gaming desktop” but it’s actually just a pretty well built all around computer for the price. For basic home use and without intense games on it, it should last for several years. That would be my choice.

Q11: Holiday gift exchanges

At Thanksgiving our family decided to draw names for a gift exchange. We used to give presents to everyone but now with 13 people at Christmas it’s getting expensive. We got into a big argument about how much each person should spend and how to handle the children. The family with children wanted to exclude the children and everyone get gifts for them. They said that they were willing to spend more in the exchange to ‘make up’ for it. Then someone else complained that two people would get great gifts and everyone else would get worse gifts. We ended up voting and putting the kids into the drawing and I didn’t draw a kid and I want to give them something anyway but I don’t want to start a big family fight. How can we fix this mess?
– Jamie

Very simple. Make a rule that you’re only required to give a gift to the person you drew, but if you want to get something small for someone else, particularly the kids, it’s entirely up to you. Suggest that if people do get gifts for the kids outside of the exchange that they be small ones, like a pack of trading cards or a $5 toy or something.

We’ve run into this situation with our own family. The way we’ve handled it is by just giving nicer gifts to people but keeping our kids out of any exchanges. If people want to give our kids a gift, they can do so, but there’s no need to or requirement to. Most of their aunts and uncles get them something small, which is appropriate.

The thing is, in situations of gift giving when people start to add expectations of reciprocity, hurt feelings are inevitable.

Q12: Are Christmas lights just disposable?

So I was going through the Christmas lights from last year and half of the strands didn’t work. I saved some replacement bulbs and tried to figure out which ones to replace because there were blocks of burnt out bulbs but it didn’t matter what I replaced it didn’t work and it was clear the problem is in the cords. Are Christmas lights just disposable nowadays?
– Amber

Most of the holiday light sets you buy at the store are pretty cheaply made. They’ll usually make it through a holiday season or two, but beyond that, it’s really a crapshoot. The issue I’ve found is that replacing bulbs usually doesn’t fix what’s wrong with them, as you’ve noticed. It’s in the socket, and fixing that is beyond what the strand itself is worth.

I don’t know of a good solution to the problem other than just being careful with your strands. We wrap our external lights up carefully after taking them down and store them in the garage on a hook and they’ve worked for about ten years. Our internal lights are looped and stored in a box just by themselves and those have lasted about five or six years.

I think you just buy bulb strands, hope for the best, and decide about replacement when the strand starts to fail.

Got any questions? The best way to ask is to follow me on Facebook and ask questions directly there. I’ll attempt to answer them in a future mailbag (which, by way of full disclosure, may also get re-posted on other websites that pick up my blog). However, I do receive many, many questions per week, so I may not necessarily be able to answer yours.

The post Questions About Coaching, Used Guitars, Family Gift Exchanges, IRAs, and More! appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2ScF6x1

9 Ways to Avoid Early Withdrawal Penalties From Your Retirement Accounts

Want Free Baby Stuff? 23 Freebies for New and Expecting Parents

Do You Qualify for These Class-Action Settlements? Wendy’s is Paying Millions


What do a burger data breach, vehicle crash parts, unwanted phone calls and a fire-prone lawn tractor have in common? They all include circumstances surrounding alleged violations of consumer law that could result in compensation due to the most important customer of all: You.

See if you qualify for one or more of the following class-action settlements. Hurry, many of these offers will end faster than it takes to get through most drive-throughs.

Wendy’s Data Breach

Would you like a few bucks with that burger?

Wendy’s has agreed to pay a $3.4 million class-action settlement over allegations the company failed to protect consumer information from a data breach in 2016.

Class members include customers who used a credit, debit or other payment card at particular Wendy’s locations between Oct. 25, 2015 and June 28, 2016 and had their personal information compromised in the February 2016 data breach.

Potential awards range all the way up to $5,000 for those who submit documented evidence; without documentation, eligible class members may collect a total of $30 for two hours of undocumented time spent tending to data breach issues (calculated at $15 per hour).

For more details and to submit a claim by the March 21, 2019 deadline, click here.

State Farm Vehicle Repair

Did you make a vehicle repair claim on your State Farm casualty insurance policy between July 1987 and February 1998?

If so, you could be eligible for a portion of a $250 million class-action settlement with the insurance giant.

Class members include “All persons in the United States, except those residing in Arkansas and Tennessee, who, in between July 28, 1987, and February 24, 1998, (1) were insured by a vehicle casualty insurance policy issued by Defendant State Farm and (2) made a claim for vehicle repairs pursuant to their policy and had non-factory authorized and/or non-OEM (Original Equipment Manufacturer) ‘crash parts’ installed on or specified for their vehicles or else received monetary compensation determined in relation to the cost of such parts.”

The $250 million settlement stems from allegations State Farm contributed to campaign funds for a judge’s re-election on the condition the judge reverse a $1 billion consumer fraud class-action lawsuit judgment regarding the use “crash parts” on State Farm policyholders’ vehicles. State Farm admits no wrongdoing under the settlement terms.

The settlement award will depend upon the number of class members who submit timely and valid claims.

Class members should be notified by mail, but if you qualify and do not receive a postcard, click here and file a claim by the Jan. 31, 2019 deadline.

Sekure Merchant Solutions ‘Do Not Call’ Phone Calls

If Sekure Merchant Solutions contacted you on your cell phone between July 26, 2013 and Feb. 1, 2018, you could be eligible for a portion of a $6.25 million settlement.

Sekure allegedly violated the Telephone Consumer Protection Act by calling cell phones to make a sales pitch even when certain numbers were on the National Do Not Call Registry.

The TCPA prohibits telemarketing calls that invade cell phone users’ privacy by contacting the consumers without explicit written permission.

If you received a robocall from Sekure Merchant Solutions during the specified time period, you could be eligible for an estimated payment of $30.

Qualified class members should receive a postcard in the mail with a claim ID number on it, but you may also complete a claim form by clicking here by the Nov. 30, 2018 deadline.

Campus Debt Solutions Unwanted Phone Call

Education Financial Solutions LLC, doing business as Campus Debt Solutions, has agreed to a $1.1 million Telephone Consumer Protection Act class-action settlement.

Campus Debt allegedly used an autodialer to contact consumers regarding programs for loan forgiveness or loan consolidation without the consumers’ consent to receive such calls.

Class members who received such a call on or after Oct. 16, 2013 are eligible for a potential reward of $20.


Those who received notice of settlement do not need to submit a claim form, but if your address has changed since you received the robocall or if you did not receive notice of the settlement, click here to file a claim.

Sears Craftsman Riding Lawn Tractor

Did you buy a Sears Craftsman Riding Lawn Tractor between Jan. 1, 2009 and Dec. 31, 2015?

If so, you could receive a free inspection, repair and/or up to $125 cash in a Sears class-action settlement regarding allegations a fuel line defect poses a fire risk.

The $125 is available for class members who paid for fuel line repairs on their own.

Sears denies the allegations but agreed to the settlement to avoid further expenses of ongoing litigation.

Class members should have received an email with a Notice ID number, but if you didn’t receive the notice, you can click here to see if the model you purchased is covered and to submit a claim by the Dec. 19, 2018 deadline.

GameStop Online Data Breach

Did you buy (or attempt to buy) an item from GameStop’s website between Aug. 10, 2016 and Feb. 9, 2017?

If so, you could receive a portion of a data breach class-action settlement. GameStop notified affected customers about the breach of about 1.3 million debit and credit card numbers in June 2017.

Class members can claim up to $10,000 for out-of-pocket expenses linked to the data breach, including fraudulent debit and credit card charges.


Consumers also may be eligible for up to $235 for out-of-pocket expenses incurred to reverse fraudulent charges, including bank fees and long distance phone calls.

GameStop admits no liability under the terms of the data breach class-action settlement.

To make a claim, click here to submit a form supporting documentation by the Dec. 13, 2018 deadline.

Suunto Dive Computers Incorrect Depth Readings

If you purchased a Suunto dive computer by Aqua Lung that was made between Jan. 1, 2006 and Aug. 10, 2018, you could be eligible for compensation from a class-action settlement.

Consumers allege the functions of their Suunto dive computers took a dive once placed in the water. Allegedly defective pressure sensors caused the depth and temperature readings to be incorrect.

Class members may qualify for a replacement or repair of their defective Suunto dive computer, but this settlement does not include coverage of claims of wrongful death or personal injury that may have resulted from incorrect readings.

For a full list of affected Suunto dive computers, serial numbers, required documentation and a claim form, click here by the Feb. 24, 2019 deadline.

Cricket CDMA Phones

When Cricket and AT&T merged, many consumers complained they couldn’t get as much as a chirp out of their Cricket Code Division Multiple Access (CDMA) phones.

After several years of litigation, a class-action settlement has been reached for consumers who bought a Cricket phone between July 12, 2013 and July 9, 2018.

Under the settlement, class members are eligible for one of three benefits:

  • Unlock Benefit: Settlement class members will be able to unlock their qualifying CDMA phone, which may allow them to activate the phone with another wireless carrier.
  • Data Benefit: Settlement class members will be able to port an existing wireless number onto a new line of Cricket service without paying an activation fee and receive an additional 1 GB of high speed data for free after maintaining one month of service.
  • Four Month Data Benefit: Settlement class members who maintain one month of future Cricket service on either an existing or new line of Cricket service will be able to receive 1 GB of free high speed data for up to four subsequent consecutive months of timely prepaid service.

Click here for more details and to submit a claim form by Feb. 4, 2019.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.

The Penny Hoarder Promise: We provide accurate, reliable information. Here’s why you can trust us and how we make money.


source The Penny Hoarder https://ift.tt/2BxAvA1

11 Mental Mistakes That Can Ruin Your Holiday Season

The holidays can be pretty fraught, thanks to tons of familial and social pressure to create a picture-perfect setting (looking at you, Pinterest) plus a relentless onslaught of advertising.

The pressures are both complicated and formidable, which is why otherwise reasonable people lose their dang minds every November and December. We’re so anxious to do things the right way – the right décor, the right gifts, the right entertaining – that we can lose sight of our everyday values.

Ever taken on too many projects and wound up stressed and exhausted by Dec. 24? Or overbought wildly and then dreaded the arrival of the January credit card bills?

You’re not a bad person. You’re just human. Understanding what you’re up against will help you avoid seasonal mistakes that can wreck your budget and your peace of mind.

Mistake #1: Trying to Compete

At last year’s big family Christmas gathering, you gave your fiancee a pretty necklace and a book by her favorite author. At the same event, your brother gave his girlfriend a weekend ski getaway.

Boy, did you feel cheap. So this year you plan to buy your now-wife a car and really show up your brother.

No one wins in this game, because the recipients wind up overindulged and maybe developing a sense of entitlement. Meanwhile, the givers feel additional pressure as the bar gets raised higher each year. Oh, and those January credit card bills are murderous on your finances.

Don’t let other people – relatives, friends, marketing experts – decide what’s right for you to give. It’s not a competition.

Mistake #2: Seeking Perfection

“The perfect gift” is a phrase you’ll hear and read a lot at this time of year. A common inference: “If I give the right gift, it shows how much I love the recipient.”

And the corollary inference: “If I don’t give the right gift, I’ll be a failure.”

That’s not how any of this works. Give gifts if it makes you happy to do so, and put some thought and care into the giving (e.g., don’t give a steakhouse gift card to a vegan). But don’t put pressure on yourself to be “perfect.”

Mistake #3: Succumbing to Marketing Ploys

My main trigger is music. When I hear stores playing the carols I once sang in the junior choir, I am suffused with nostalgia and want to buy another round of gifts for everyone I know. It’s scary how quickly this Ghost of Christmas Past could wreck the budget. I’ve learned to stick to my list and get the heck out of the store.

Maybe for you it’s television commercials or online ads about “the perfect gift” that lead directly to temptation. Identify your weak spots and deal with them. Make a list of your own and stick to it. Bring along a shopping buddy to talk you down. Wear headphones blasting Brahms or Black Sabbath to drown out a store’s holiday music.

Whatever your particular weak spot, know that it can be conquered. And if you give in and buy too much? Return some of it, right away.

Mistake #4: Being Cyber-Careless

You’re at the coffee shop or at a fast-food place when your phone or laptop displays a flash sale. “Just this once” you figure it will be okay to enter your credit card number on a shared public network, so you can snag a screamin’ online deal that’ll stretch your holiday giving budget.

Or maybe you caught a glimpse of the store clerk doing something a little off with your card (e.g., running it twice), but you were on the phone apologizing to the babysitter for running late and felt too harried to confront the employee. And on the way home you realized you didn’t have enough to pay the sitter, so you used the ATM outside the convenience store to get some quick cash.

Credit card fraud is a big deal all year long, but the holidays really kick it up a notch. We’re distracted, we’re super-busy, and we’re buying a lot of stuff online. According to Experian, holiday fraud is most likely to happen on Thanksgiving Day, Dec. 21 (the cutoff date for express shipments), or Christmas Eve.

Being careful about credit is a good idea year-round, but be ultra-vigilant in November and December. For more on this topic, see “Protecting Against Credit Card Fraud.”

Mistake #5: Succumbing to the ‘Easy’ Buy

One-click sales and saved credit card info makes it feel less painful when we overdo it for the holidays. Behavioral science expert Jeff Kreisler says such options make us “less aware” of our spending.

Would you be quite so blasé about purchasing that expensive bauble or well-advertised toy if you had to take a series of $20 bills out of your wallet? Maybe. But maybe not.

“We should be skeptical of the latest technologies, especially those that are designed to demand less of our attention and make it easier for us to part with our money,” Kreisler says.

One workaround is not to complete the online shopping trip. Revisit the virtual cart in a couple of days and decide whether you really should buy. The retailer may send you a discount code during that time, but don’t be swayed: If you can’t afford a purchase, then it’s no bargain. And if you decide you can swing the purchase, any discount will make the deal a little sweeter.

Mistake #6: Ignoring Opportunity Cost

The National Retail Federation predicts the average U.S. shopper will spend a little over $1,007 on gifts, special foods, and other items during the 2018 holiday season. Even if you don’t spend that much, think about the long-term impact of the money you do spend (or overspend) — and what you could do with the money you don’t.

Let’s say you ordinarily spend the average amount, but instead keep the tab at a much more modest $500 this year. Next, think of that extra $507: What could it do for you in some other capacity? For example, you could pay extra on a student loan, shore up your emergency fund, purchase the start-up equipment needed for a money-making side hustle, or add those five Benjamins to your retirement fund.

Finally, think about a decade’s worth of profligacy versus restraint. Assuming you don’t go over budget by the same amount every year, that’s $5,000. How much closer to your long-term financial goals will you be once you learn to rein in your impulses?

Mistake #7: Treating Holiday Spending Differently

Throughout the year, price jumps on essentials like groceries and gasoline make you really nervous. But come the holidays, the logic center of your brain may shut down.

For 11 months it’s painful to come up with an extra $100 for a new tire or a medical co-pay, yet in December you decide that a $99.99 Harry Potter Lego set is a must-have.

Spending is spending. It’s the same $100 whether it’s going toward heating oil or toys. If you struggle to balance the books all year long, it’s not OK to overbuy for the holidays.

Try this exercise: Divide that $99.99 (plus tax and shipping, if applicable) by your current hourly salary. You’re looking at just how long you had to work to pay for that ugly Christmas sweater or the plush Christmas tree that sings “Jingle Bells.”

Hours of your time traded for stuff that will be used rarely, if at all. Ho-ho-no!

Mistake #8: Taking on Too Much

If you’ve got two kids in the community theater production of “A Christmas Carol” and work full-time and throw a huge mid-December open house and have to drive for five hours to be with your folks for Christmas, maybe this isn’t the right year to declare it an “all gifts will be homemade!” holiday.

Similarly, if you work full-time and are in a men’s chorus that performs half a dozen holiday concerts and volunteer for Toys For Tots, perhaps you could say, “Sorry, not this year,” to additional entreaties for your time. Just because someone asks doesn’t mean you have to say “yes.”

Too many activities can lead to financial stress, e.g., lots of additional miles on your car and more takeout because you’re too overscheduled to cook. The constant busy-ness can also take its toll on your peace of mind, and on your own enjoyment of the season.

When you take on too much, something’s got to give – and it might be you.

Mistake #9: Losing Sight of Value

Somehow we take the major retailer’s word for it that the Lego set really is worth a hundred bucks. That is, we let someone else decide the value for us.

Instead, why not look around for the best prices with a site like PriceGrabber.com or NexTag.com? And even then, we’re the ones who should decide what we buy — and if a particular item’s worth those extra hours at work.

Resist following the crowd. It’s up to you to decide whether to buy a gag gift or wear an ugly Christmas sweater vs. blindly following the crowd.

Mistake #10: Automatically Buying Retail

If you do decide to wear that ugly Christmas sweater, your friendly neighborhood thrift shop can probably hook you up. Check a few thrift shops. Gag gifts abound there, too.

But so do some pretty great regular presents, too. I particularly enjoy browsing the books section, which bulges both with bestsellers and classics alike.

(Pro tip: Some secondhand shops have sales every so often, or even every week. Find out when the next discount days take place.)

Mistake #11: Not Learning From the Past

Last year you went into debt for the holidays. Serious sacrifice plus a part-time gig delivering pizzas helped you pay it all off by the end of April.

Not exactly a happy ending. Again, think of the opportunity cost of the interest paid and the fact that the extra money you earned went toward unnecessary debt rather than future goals.

Trusting past decisions means we aren’t learning from our mistakes, which means we’re doomed to repeat them.

Award-winning journalist and veteran personal finance writer Donna Freedman is the author of “Your Playbook for Tough Times: Living Large on Small Change, for the Short Term or the Long Haul” and “Your Playbook for Tough Times, Vol. 2: Needs AND Wants Edition.”

More by Donna Freedman:

The post 11 Mental Mistakes That Can Ruin Your Holiday Season appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2Qk7SP4