Thousands of courses for $10 728x90

الأربعاء، 28 نوفمبر 2018

The Best Website Builder

Quicksprout is reader-supported. That means we use affiliate links. When you click, we sometimes earn a commission. Learn more.

The best thing about using a website builder is knowing that, in a world where an online presence is absolutely mandatory, the technical proficiency to build and publish that presence isn’t.

Sure, you can sign up for web hosting, implement a template, and launch your own WordPress website. But there is an easier way. We should know: We’ve built some of our own business sites with website builders. It’s easy, fast, and unobtrusive to use an all-in-one tool.

Every one of our picks for the best website builders will help you get your site up beautifully and simply:

  • Wix
    Best for: Automating the tough choices
  • Squarespace
    Best for: Beautifully designed templates
  • Ucraft
    Best for: Building a one-page site for free
  • Onepager
    Best for: Quick set-up

What we look for in a website builder

  • Ease of use: everything’s all in one place, and it lets you get on with your real business. No technical proficiency required. No need for a designer or other outside help.
  • A beautiful final product: a professional, well-designed website that reflects your business.
  • Customer support: It’s there if you need it, but everything is intuitive enough that you don’t feel like you do.

We also ask questions in 5 key areas

  1. Style and templates
    What do the templates look like?
    How customizable are those templates?
  2. Usability
    How easy it is to get started?
    Or, how long does it take to build a nice looking site?
  3. Ecommerce and business needs
    Can I sell things on my site?
    Can I add a menu?
    A form?
    A map?
    Reservations?
  4. Pricing
    How much does it cost?
    Which tier should I start on and when will I need to upgrade?
    If it’s free, what’s the trade-off?
  5. Domains, emails, and other bonuses
    Does it come with a free domain?
    Does it come with email addresses?
    Any other extras I should be looking for?

Our top picks for the best website builder

Wix

  • Quicksprout Pick
  • Best for: Automating the tough choices
  • Paid plans start at $11 / month (billed annually)
  • Free trial period: 14 days
  • Sign up

It’s easy to choose Wix as a website builder. It truly takes on the name. Wix’s artificial intelligence asks you a few questions and literally builds your website before your eyes — unique color palette, features, and design all in one. It’s the best tool we’ve seen to get a site that matches your vision, even if you don’t know yet how you’d articulate that vision. Honestly, building a site with Wix’s AI felt a little like getting our minds read.

Wix has been at the forefront of this revolution, and is looking to closely combine AI and website building.

—Why AI is the best tool to help build your next website, TechRadar

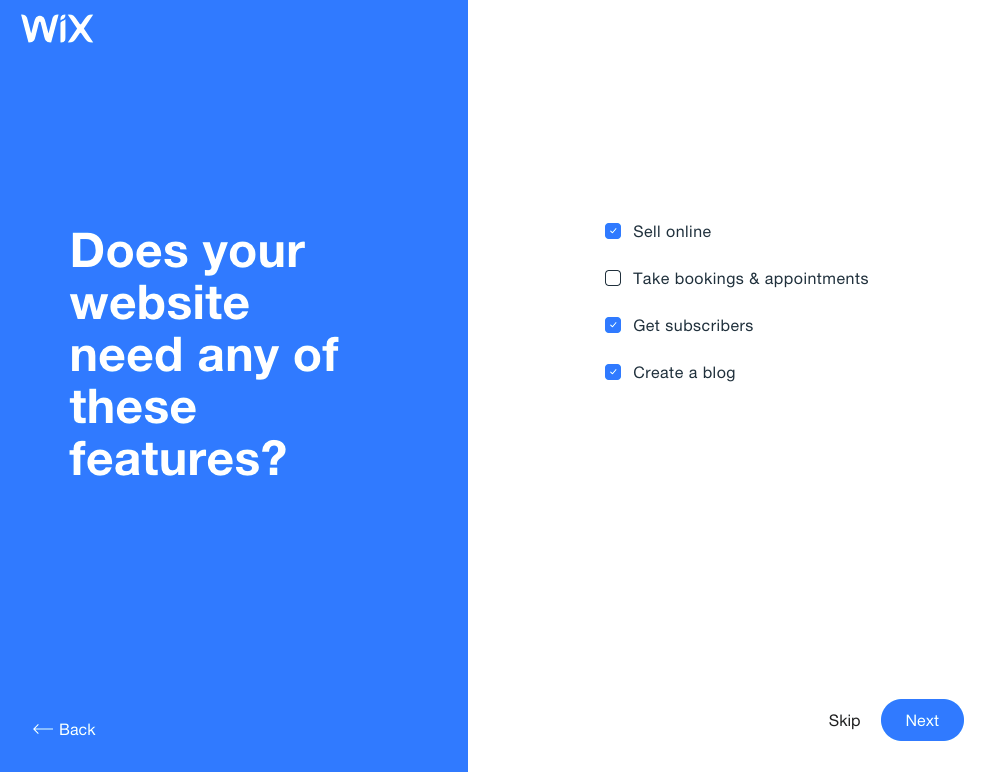
To start, click create site. You’ll be asked a question: What kind of website do you want to create? From there, the AI will help you build your website. (You can opt-out and go it alone at this point, too, but we appreciated the AI’s help.)

Wix artificial intelligence website builder questions
One of the first screens you’ll see when you build a website with Wix.
We loved how easy it was for us to find a template that matched our vision. The AI stayed with us as we edited the page, a little pink square in the bottom (it looks like a chat pop-up) helping us pick the next thing to edit and showing us how to do it. The Wix AI matched our business to its online presence, used our logo to create a color palette for our site, and gave us a template pre-populated with our logo and address. Connecting images from existing social media accounts made it easy to pull in all the assets we already owned.

As AI progresses, it will be harder and harder to know which site was built via AI and which was built via a designer. You can think of it like passing a “design turing test”, i.e. in the future humans will not be able to differential between the two. Then, it’ll have to get innovative. Instead of mimicking what it is learning from what’s created, it will get better and more experimental. It’s easy to see how soon most websites that are created use AI in some way.
—Wix VP & GM of Consumer Experience Nitzan Achsaf told
TechRadar

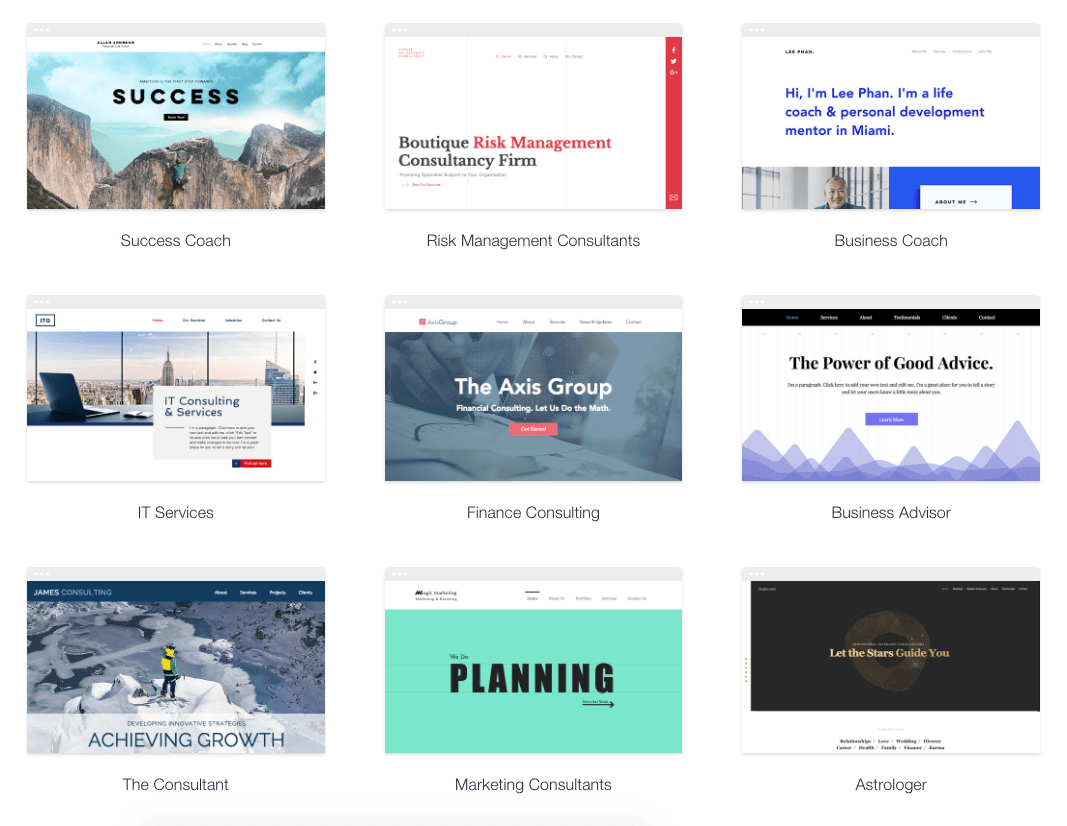
There’s a lot of variety between the Wix themes, and the personality of each theme matches its name well. The Business Advisor had a spot-on graphic of an analytics dashboard, while Astrologer features an astral hero image.

Wix theme template designs for marketing
Some of Wix’s business-centric themes.
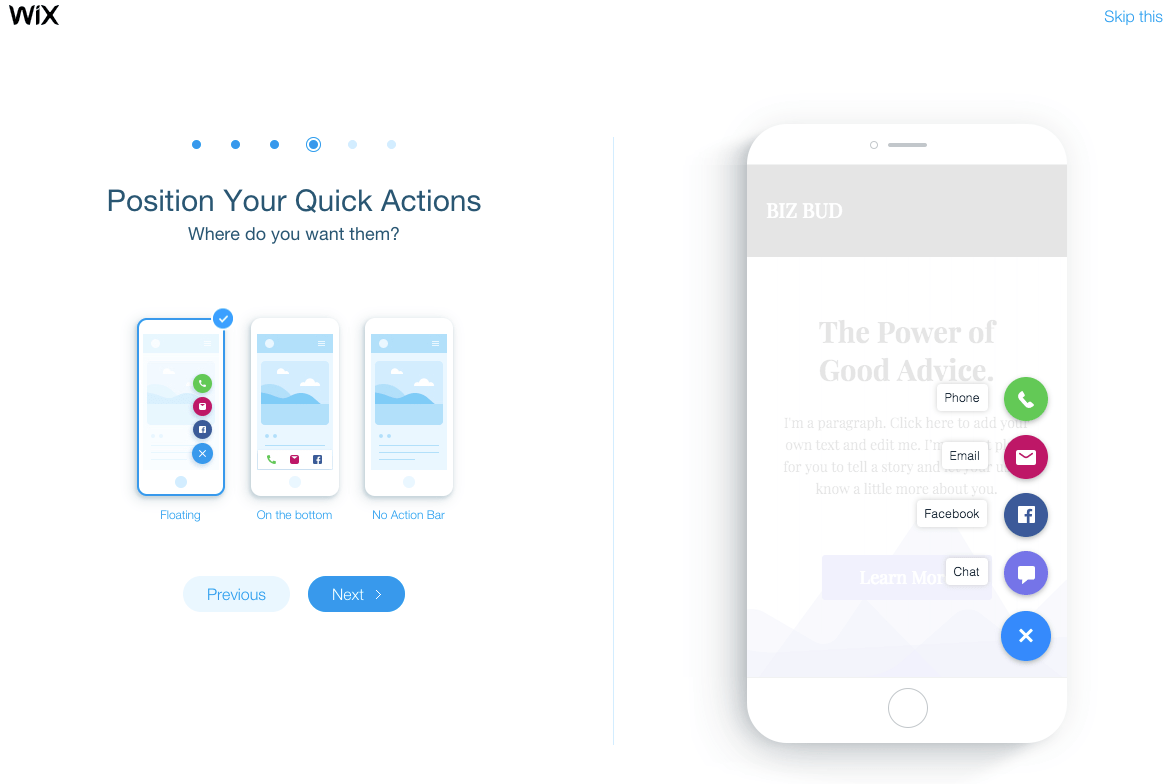
Editing your desktop site with Wix requires some patience. To change the text on a text box, you’ll need to hover precisely in the right spot. We did some deep breathing and were able to find enough inner zen to make all the changes we needed. The mobile editor has the serene helpful feel we wish the rest of the editor maintained. It’s super easy to click through the options for how your menu, quick actions, and scroll options work on your mobile page. What you change in the mobile editor doesn’t affect anything that happens on the desktop.

Wix website builder menu overwhelm
Wix’s editor requires patience — and some clicking around.
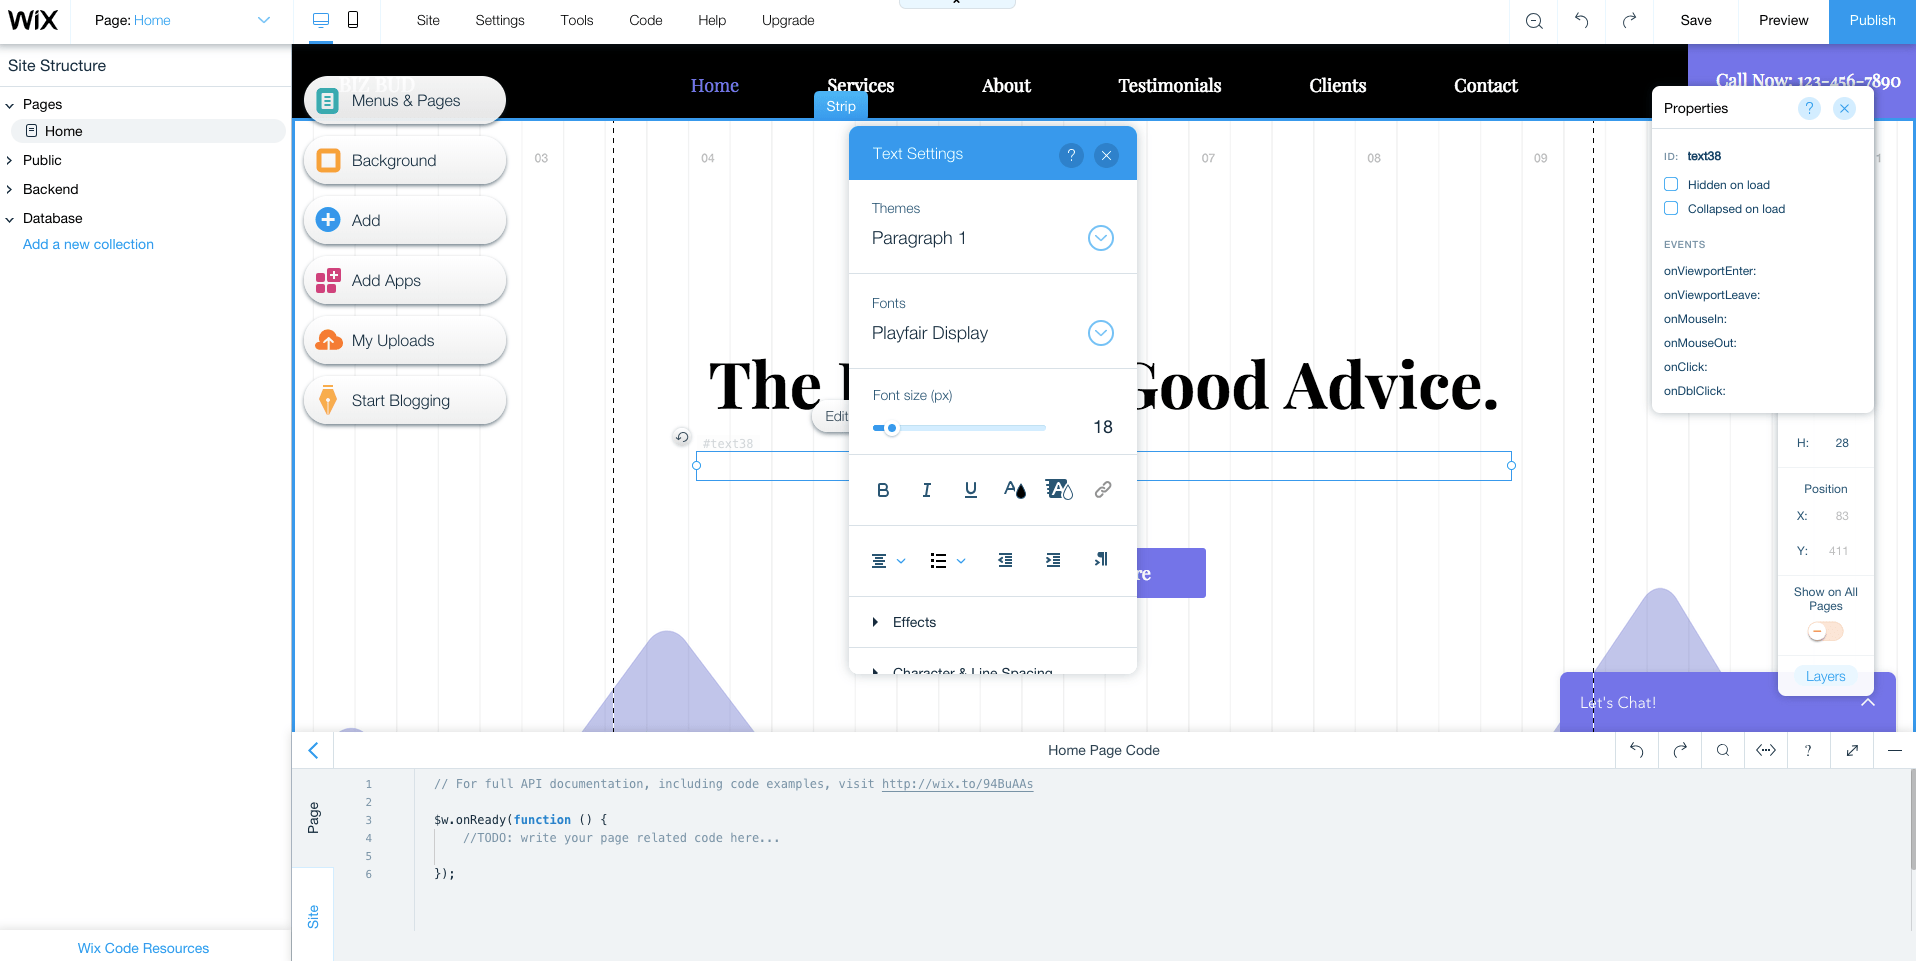
Wix website builder mobile user interface
We prefer its easier-to-use mobile editor.
Wix does have a free tier, but we don’t recommend it. It has some of the most in-your-face “this was not paid for” company branding we’ve seen — an instant trust breaker. Wix free sites also have one of the most cumbersome domain structures: yourusername.wix.com/sitename so we’d be QuicksproutEditorial.wix.com/Quicksprout. Connecting your actual domain also allows you to attach a Google Analytics profile and add email accounts if you’d like ($5 / account / month, or about half that with an annual plan). Unfortunately, none of this pricing is very upfront. Wix wants you to connect your domain before you see the email pricing, for example. We found answers to pricing questions in the support center, not the user flow.

Take note: all of Wix’s plans are automatically set to auto-renew. Sticker shock is real, especially if you signed up with an introductory promo pricing (at the time of publish, premium plans were a full 50% off, for example). There are many frustrated customers on TrustPilot who’re unhappy with this. It is possible to turn off your auto-renew, but you’ll need to do it more than 14 days before your plan’s anniversary — and if you do it during your 14-day free trial, your trial will be cancelled immediately.

As for which paid plan to pick, you have 7 options: 4 “regular” and 3 “ecommerce.” The difference really boils down to whether you’ll be accepting payments on your site or not. If you’re not sure about how much bandwidth you need, you can always start with a smaller subscription: if you go over the limit, you’ll get a notice from Wix (with no penalty) and use that as your signal to upgrade.

Squarespace

  • Quicksprout Pick
  • Best for: Beautifully designed templates
  • Plans start at $12 / month (billed annually)
  • Free trial period: 14 days (plus an additional 7-day extension)
  • Sign up

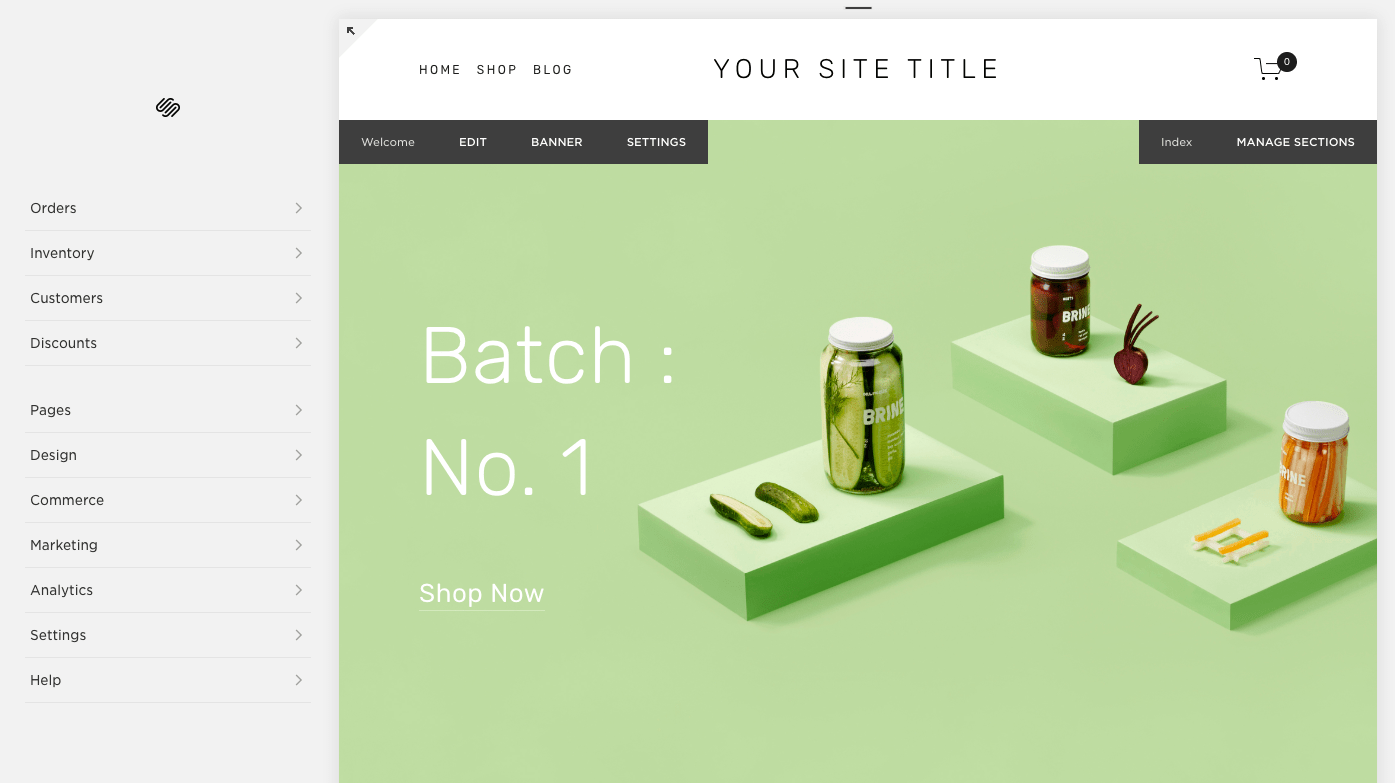
“Build something beautiful” is right. There’s no doubt that Squarespace wins the design and beauty contest here. The user interface has a bit of a learning curve and there’s not much of a Squarespace community to help you out, but the page you’ll end up publishing will be phenomenally good-looking.

Squarespace website builder template editor user interface
Squarespace’s templates are all modern and beautiful.
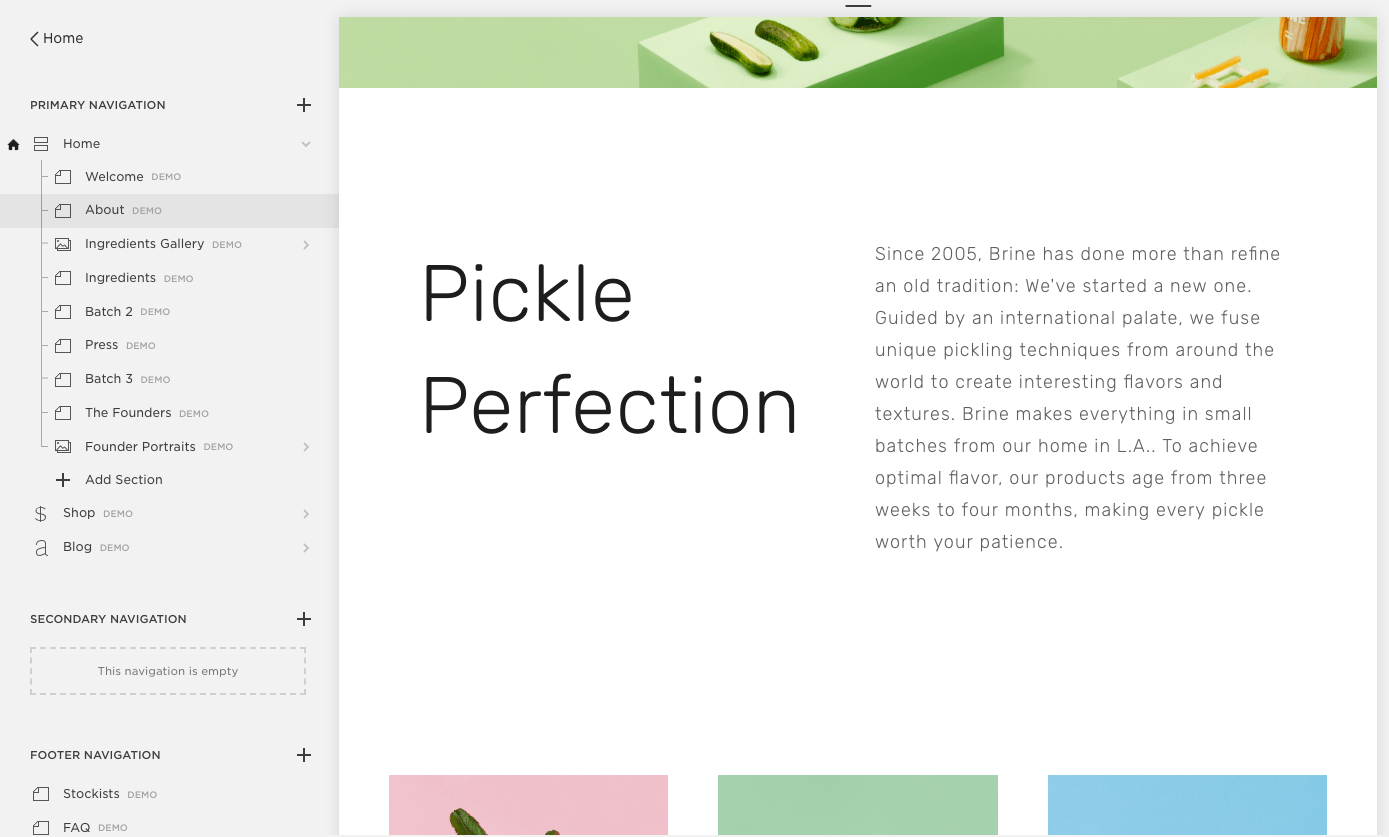
But, building a website with Squarespace can feel a little like building IKEA furniture: in the showroom it’s all so beautiful and simple, but somehow it feels a little more complicated to put together than it promised. It can be hard to understand where exactly you are in the editor. We kept getting notifications that we were editing demo content, or that we would see the social logos once we connected our social media, or that we could unlock this or that feature with a paid subscription, but Squarespace didn’t go the extra step to make it easy to make that required move. It was a lot of fumbling through a beautiful interface, not exactly sure what changes were real, or where to head next. We also had some issues saving changes — an error message popped up and we had to move on, without our changes.

Squarespace website builder editor and page selector
Editing a site in Squarespace has a bit of a learning curve.
Unlike IKEA, Squarespace is pricier than other website builders. That all being said, we love the way sites built with Squarespace look, and think it’s one of the simplest ways to create a beautiful, contemporary site.

Ucraft

  • Quicksprout Pick
  • Best for: Building a one-page site for free
  • Paid plans start at $6 / month (billed annually)
  • Free trial period: 14 days
  • Sign up

We love the free Landing Page option from Ucraft: create a single, mobile-ready page and connect your domain for free. The free version doesn’t get rid of the Ucraft branding but it’s minimal and not invasive. The template has all the features we’ve identified in our anatomy of a high-converting landing page. You can drop the branding by upgrading to a $6 / month Basic Website plan, and sell up to 50 items on the $14 / month Pro Website plan. If you have more items to sell, upgrade again, but note that once you upgrade, you can’t drop back down to a less expensive plan.

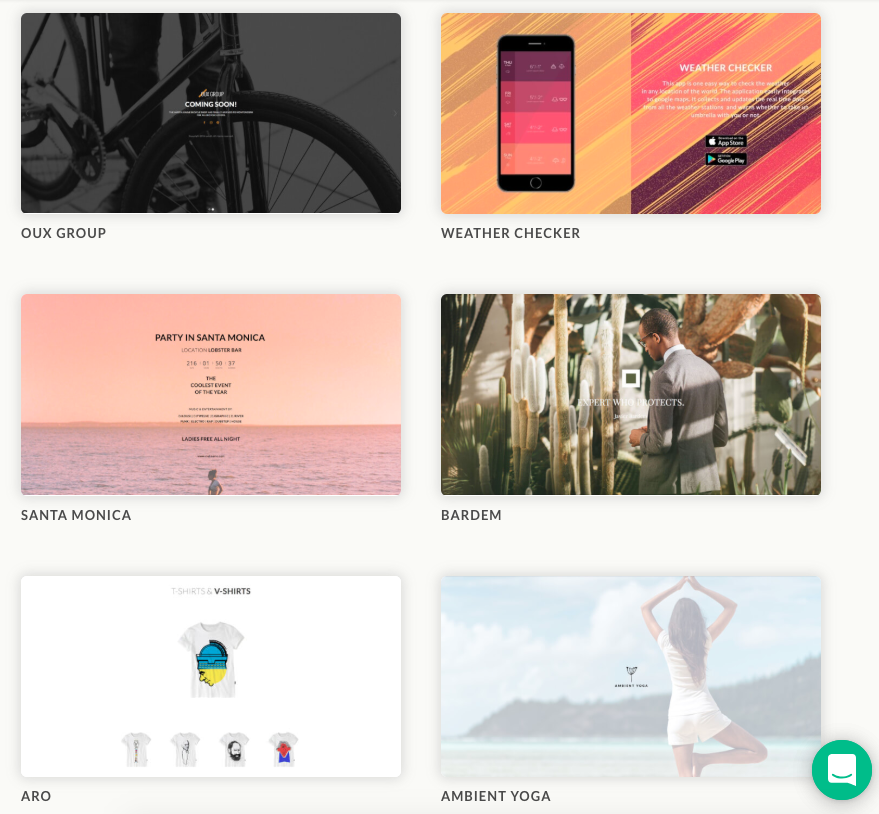
Ucraft Landing Page Template Theme Options
Ucraft’s themes are elegant and streamlined. It’s one-page free sites are designed to be a long scroll with anchored sections.

Ucraft Website Builder User Interface
Build a Ucraft site using drag-and-drop blocks and elements.
We’re also impressed with the $229 Lifetime plan. If the subscription set up (and realization that if you love the site you build, you’ll be paying that monthly fee for… forever) isn’t your favorite, then this is a nice compromise. You still get the easy-to-use editor and tools of a website builder, and the one-and-done payment.

Onepager

  • Quicksprout Pick
  • Best for: Quick set-up
  • Paid plans start at $8 / month (billed annually)
  • Free trial period: Unlimited free editing; simply pay when you publish
  • Sign up

We were so surprised to name Onepager a top pick. The templates look dated and the product tour video hasn’t been updated in six years. But Onepager is so dead simple and easy to set up that we were able to publish a workable website for a local pizza shop in minutes. Yes, every webpage builder claims you can get started that fast, but with so many options, templates, and features, we’ve found that we’re distracted and deep in the weeds of perfecting our site, not publishing it. That wasn’t the case with Onepager.

Onepager template theme selector
Onepager is a simple website builder with a simple interface.
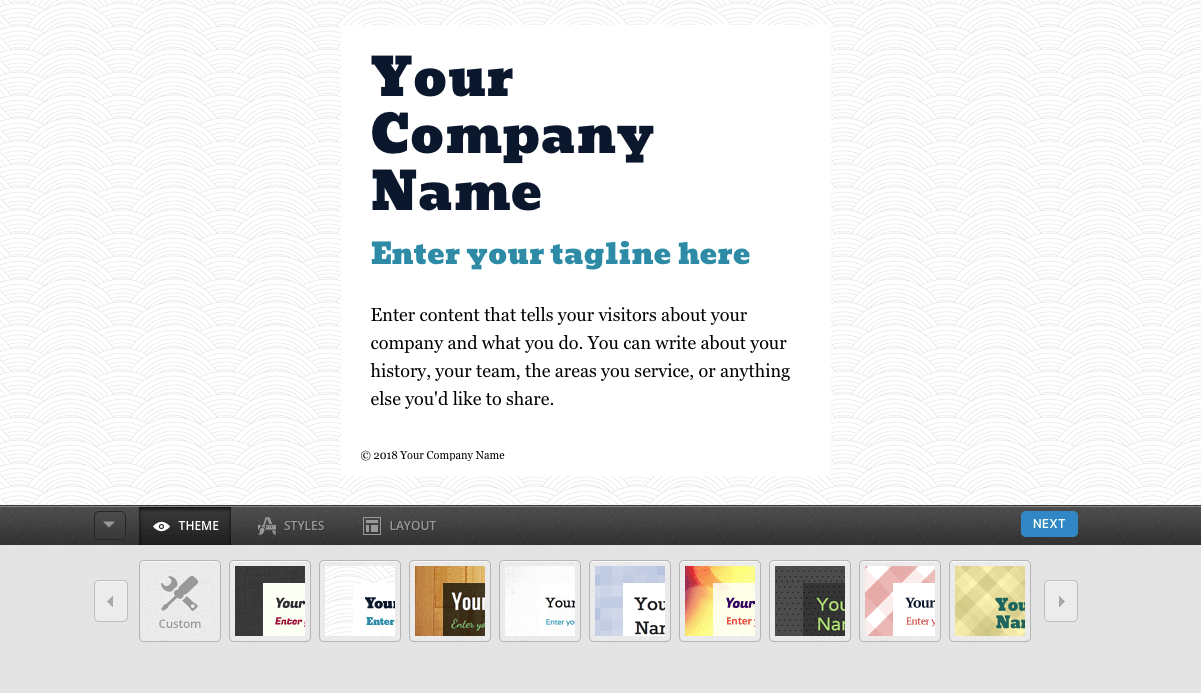
The Onepager templates aren’t very modern, but they’re straight-forward and the user interface is helpful, and we were pleased with the overall look of our super-quick site. (And, as we written about before, websites with simple homepages convert better.) For a small business that just wants to stake out its territory online — as opposed to, say, building an online empire — we think Onepager fits the bill.

We’d also recommend it to anyone who gets asked all the time to build a website for a friend, a family member, so-and-so’s neighbor who has a family business. For $15 a month, you can build up to 5 sites. With the $199 per month agency plan, you can build up to 150 sites with a white-labeled version of Onepager’s editor platform.

The 26 other website builder platforms we considered

  • Adobe Muse

    As of March 2018, Adobe has stopped releasing updates to its website builder software, acknowledging that simpler site builders like Wix and Squarespace have taken over: “For simpler websites, we’ve seen the emergence of Do-It-Yourself (DIY) website creators that use customizable templates to quickly create responsive websites that can be easily modified by the designer or a client.” — End of service for Adobe Muse

  • Cargo Collective

    Honorable Mention Amazing templates and designs perfect for artists and art galleries, but definitely not for everyone. If you’re after templates designed for displaying images and image galleries, definitely take a look.

  • Cindr

    True to its slogan, Cindr is very fast to use: add in new “blocs” and move them, but want to do much customization (say, if your team doesn’t have exactly 2, 3, 4 or 6 people on it…) and you’ll quickly get frustrated. We certainly were.

  • Duda

    There were too many deal-breaker annoyances on Duda’s own website (broken links, unclear organization, scroll bars on pages that don’t scroll, and typos) for us to recommend building your site with theme. And it’s just as well, as its primary focus is on white-labeling and reselling web designs, not on creating and building your own site.

  • GoDaddy GoCentral

    We’ve never loved the customer support from GoDaddy and GoCentral is no exception. There are only 8 templates, and you can only make extremely limited font and color changes on them. No moving or resizing. The GoDaddy forums are full of frustration and confusion. Case in point: GoDaddy updated live templates so their headers no longer looked the same. Support recommended changing themes if you didn’t like the new header. What a nightmare.  

  • Homestead

    The Homestead website itself looks like its from a different era. And the 27 featured templates from its collection of hundreds! have that same late-90s look.

  • Jimdo

    We really like using an AI questionnaire to launch our website, and we adore the ease of pre-populating the images from our Google Places, Facebook, and Instagram feeds. But, Jimdo’s editor was glitchy (images would appear as blank boxes, then reappear) and the design customizations were super limited. (Is it impossible to have a full width image header without a color filter? Seems so.) Wix makes all the same promises, and delivers.

  • Moonfruit

    We really wanted to love this Moonfruit. It’s clean, it’s modern, it’s easy to flip into mobile view as you edit, it has a helpful dashboard that lets you know how much of your 500 free MB storage you’ve used. And maybe it’s worth considering. But we found that the template-free starting point left us feeling more confused than empowered. The result: a lot of haphazard clicking and website that looked more amateur than any other we’d built.

  • Simvoly

    Not recommended. We were intrigued by the marketing lingo Simvoly opens with: funnels, analytics, A/B testing. Oh my! But, this platform shows lots of sloppiness that keeps it out of any competition for the best: typos in the animations on the Simvoly homepage are just the beginning. The builder doesn’t have an undo/redo function, or any way to save a draft page without publishing it. Simvoly knows the right buzzwords but doesn’t back it up with its product.

  • Site123

    We wanted to like the AI assistance for building our theme, but didn’t. We answered one question about our site (we’re a DJ, or a Diner) and got sent to a pre-built page for us to customize. There’s no sense of adding your own personal style or browsing through templates to pick the site structure you’d like. Want to change templates? You’ll need to go back and answer that one question differently. To get a design we liked, we felt like we had to cheat the quiz.

  • SiteBuilder

    You have to sign up before you can even browse the templates. That’s a dealbreaker for us, but they also have no free plan and once the promotional pricing wears off, your cost will double.

  • SiteZulu

    Not much to love here. Only 31 themes, the mobile version of our test site was buggy, and its the ecommerce “upgrade” is the free PayPal embed button.

  • SnapPages

    SnapPages is one of the most expensive website builders on the market. For the price, it doesn’t offer anything you can’t get elsewhere. Recently acquired by Subsplash, we expect SnapPages to focus on selling its services as part of the Subsplash service packages aimed at churches and nonprofits.

  • Strikingly

    This Y-Combinator-backed one-page web builder shouldn’t be compared to a full-fledged website builder like Wix, Weebly, or Squarespace. It’s in the simplicity of getting something launched where single-page builders work best. But, Strikingly just isn’t as good as uCraft, which lets you connect your own domain for free and has a more beautiful and user-friendly interface, or Onepager, which is so dead simple you can literally publish a complete (albeit super simple) site in minutes.

  • uCoz uKit

    uCoz has a clean and modern interface, that is intuitive and easy to use (though noticeably slow to load). We didn’t love that we needed to sign up to see the templates, that most of the templates are very similar, and you’re extremely limited in editing the templates. Once you’re in a template you can’t change things like text styling and can only choose from one of three colors. This keeps you from making bad design choices, but also makes picking a template a much more important choice.

  • Virb

    We don’t recommend Virb, the MySpace competitor that pivoted to become a website builder in 2010 — while the one $10 plan is simple, but there’s no way to preview the editing tool, and honestly we couldn’t even figure out how to sign up. We clicked log in (but were told we didn’t already have an account…). Let us know if you can figure it out. By watching the Virb tutorial videos on its Vimeo account, which were uploaded six years ago, we got a sense that the tool hasn’t been updated recently, and here’s the deal breaker of deal breakers: it’s not WYSIWYG. To add social buttons, you’ll need to go to a menu, click add widget, and who know where they’ll show up on the page. We live in a world with the ease of drag-and-drop editors and can’t go back.

  • Vistaprint

    Vistaprint does offer some limited templates you can build yourself under its “Digital Marketing” offerings, but it’s still a business-card first business. In fact, one of the major selling points it offers is just that: your website can match your business card.

  • Voog

    Voog advertises that it’s the simplest multi-lingual site builder, that is you can build your site in one language and then add all of the copy in up to 10 other languages. Your user will choose the appropriate language with the little flag logo in the corner (you can also pre-select language based on user location). But, this is a feature Wix, Squarespace, and others also offer. We think it’s better to go with one of those bigger names for a few reasons: Voog’s site itself loads very slowly with noticeable lag on pages with more than one image, and its own pricing page doesn’t automatically notice the country you’re in. When your big claim is matching content to the user country, this is a big miss.

  • Web.com

    A hard no from us here. Before you even get to browse the template, you’re signing up for introductory pricing that’s $1.95 for the first four weeks, then bumps up to the “current rate” which is $22.95 a month right now, with no promise that it won’t be more later. And the fine print asserts there are 4 weeks in a month, so there are 13 “monthly” billing cycles in a year. No thanks.

  • Webnode

    A simple (almost too simple) designer with a super high price point. For no ads, you’ll pay $11.95 a month on the required annual plan. At that price, you can do far better.

  • Webs

    Built by three brothers and then acquired by VistaPrint in 2011 for $117.5M in cash and stock, Webs looks like it hasn’t been touched since. The editor is slow, and the templates are dated — the default “line” has the scrollwork of a fancy wrought-iron fence, for example — and the templates, which are arranged in an awkward horizontal scroll, don’t respond to the system’s filter so premium and free templates are intermingled. Can’t recommend.  

  • Websitebuilder.com

    A strong no. Uninspiring templates, buggy interface, a support chat portal that doesn’t work (and legitimately suggests unplugging your router to solve the problem), and terrible customer reviews that call out inaccurate billing and incorrect charges. We don’t doubt it: the terms of service say in order to unsubscribe from auto-renewals, you’ll need to turn to phone or chat, not simply update your account settings.

  • Webstarts

    There’s so much freedom with Webstarts: you can literally move anything you want anywhere on the page. The problem with this is that it’s easy to move something on the desktop editor in such a way that it won’t show up on mobile. For a website builder, it’s freedom to a fault. We like to see when the software stops us from making bad decisions we don’t even know we’re making, without any fuss. Mobile-optimization doesn’t click in until the Pro Plus level, which is $14.32 a month, billed annually (~$172).

  • Weebly

    In Q2 2018 Weebly was acquired by Square and has been increasingly geared towards entrepreneurs and online store owners (really gunning for online shops like Shopify). At least in its marketing, that is. When we checked out the one-star reviews on TrustPilot, we knew we couldn’t recommend Weebly. Another dealbreaker? There’s no undo button. Once you exit a module in the editor all of the changes you made are permanent. Delete a module, and want to undo it? Sorry, you’re simply out of luck.

  • WordPress.com

    We love WordPress and run our site on WordPress, but an easy-to-use website builder it’s not. Dive into WordPress.com and you’ll be quickly launched into a world that feels like you need technical expertise. (You don’t really need much, but the menu layout and wiki-style simplicity feels much more demanding than others. And it most certainly is not drag-and-drop intuitive.) If you’re up to using WordPress, we recommend picking a great web host, registering a domain name, and going through WordPress.org’s “famous 5-minute installation.” You won’t pay the monthly subscription you’d pay with WordPress.com and you get all the same features — you’ll just need to do some of the hands-on work. Read more about the difference between self-hosted WordPress.org and fully hosted WordPress.com on the WordPress.com blog.

  • Yola

    Yola is expensive and wants to upsell left and right. You’ll need Silver ($119 annually or $14.99 monthly) to ditch the Yola branding, and they’d like you to get Mobile Plus (an extra charge to make your business phone number and address show up on the bottom of mobile pages — this is free with Wix) and the $10/month ecommerce upgrade is simply a free Ecwid plugin Yola would love to charge for. The editor is a bit buggy, you can’t add a blog (Yola suggests embedding a Tumblr page…) and we don’t think the high price point and upselling are worth it for the mediocre product.

Recap: The best website builders

  • Wix Best for automating the tough choices
  • Squarespace Best for beautifully designed templates
  • Ucraft Best for building a one-page site for free
  • Onepager Best for quick set-up


Source Quick Sprout https://ift.tt/2KGN4Mh

9 Scams To Watch Out For This Holiday Season: Don’t Get Grinched!

Holidays are supposed to be a joyous time – but scammers can replace the joy of the season with the headaches of fraud. Learn a few simple precautions you can take.

Source CBNNews.com https://ift.tt/2Atxz5S

Why Potlucks are the Perfect Alternative to Expensive Dinners With Friends

The Financial Benefits of Adopting A Pet

Overcrowding is a serious problem in America’s animal shelters. According to the ASPCA, an estimated 1.5 million animals are euthanized every year due to overcrowding — and that’s only dogs and cats.

If you’re considering bringing home a pet in the new year, adopting your furry friend from a shelter can help alleviate this growing problem. You’re also helping end pet homelessness, unhealthy breeding techniques and puppy mills, which subject more than 2 million dogs to devastating and inhumane conditions every year.

As if that weren’t enough, you can actually save money by adopting over shopping. Breeders and pet stores come with considerably higher costs — both up front and over the life of your pet — especially when compared to animal shelters and rescue organizations.

Saving Through Adoption

Adopting your pet from a rescue group or shelter can save you significantly up front. Breeders typically charge $1,000 or more for their pure-bred animals, and pet stores are equally as expensive. What’s worse, these fees rarely include the costly vaccinations, spay or neuter surgery and initial medications that the newly purchased animals need.

Though shelters and rescue organizations may charge an adoption fee, it typically covers the following services:

  • Initial vaccinations
  • Flea treatment
  • Microchipping and registration
  • Heartworm testing and medication
  • Spay or neuter surgery

The adoption fee may also cover the cost to treat an animal that arrived at the shelter with a pre-existing injury or illness, something that isn’t typically covered by a breeder.

Better for Your Wallet (And the World)

Aside from the differences in up-front fees, pets from shelters also cost owners less money throughout their lifetime — especially when compared to animals from breeders or pet stores.

The first reason stems from the overall health of the animals. Shelter animals — particularly mixed-breed ones — tend to be healthier than the pure-bred animals most breeders and pet shops specialize in. Pure-bred animals are more prone to health issues like hip dysplasia, enlarged hearts, breathing difficulties and more, all of which result in higher veterinary bills (and, in many cases, a shorter lifespan). Puppy mill animals, where many pet stores buy their animals from, also have significantly more health problems due to poor living conditions and unhealthy breeding practices.

Shelter pets are often crate-trained and potty-trained (at least partially) and are already socialized with people and other animals. Breeder and pet store animals often need additional training to achieve these milestones, resulting in even more up-front costs.

By adopting an animal from a shelter or rescue group, you can feel confident that your money is helping animals in need. Rather than being used to further puppy mills or inhumane inbreeding practices, your fee will fund an organization that’s actively working to help animals in need.

As Francis Battista, co-founder of the Best Friends Animal Society, explains, “When you buy a pet, you not only deny a homeless pet a home, you are supporting an industry that thrives on short-changing the welfare of animals. Puppy and kitten mills, which sell to pet stores, are in business to make a profit, so they churn out puppies and kittens as fast as they can. These animals are often in ill-health and have problems like poor socialization skills due to lack of human companionship and genetic defects due to inbreeding.”

Pet Store Costs

Pet stores typically purchase their animals from puppy mills and mass breeders. The animals usually do not come with any training or socialization skills and may have serious health problems due to their poor care.

Up-Front Fees: Initial Medical Care and Training: Lifetime Vet Bills:
$500-$1,000 High High

Breeder Costs

Breeders usually specialize in pure-bred animals, which have higher rates of serious health issues like hip dysplasia and breathing difficulties. They also may live shorter lives as a result. Professionally bred animals also typically do not come with vaccinations, spay/neuter, microchipping or other necessary treatments.

Up-Front Fees: Initial Medical Care and Training: Lifetime Vet Bills:
$1,000-$10,000 High Medium

Shelter Costs

Shelter animals are usually brought in as strays or by owners who are no longer able to care for them. They often have free or very low adoption fees and may include some vaccinations, microchipping or other medical fees.

Up-Front Fees: Initial Medical Care and Training: Lifetime Vet Bills:
Up to $50 Medium Low

Rescue Organization Costs

Rescue organizations focus on rehabilitating animals or nursing them back to health after injury or ill-treatment. They often cover all medical treatments, as well as services like microchipping and vaccinations. Rescue groups sometimes specialize in one type of animal or breed.

Up-Front Fees: Initial Medical Care and Training: Lifetime Vet Bills:
$50-$450 Low Low

Potential pet owners should always consider the upfront and lifetime costs of an animal before adopting one. Should you have trouble paying for your pet after adoption, there are many organizations that offer financial help to pet owners in need. There are also loans and credit cards that can assist — even if you have not-so-perfect credit.

Adoption Misconceptions

Some would-be pet owners are hesitant to adopt shelter or rescue animals, despite the significant cost-savings they offer. Many think these animals are unpredictable, unhealthy or will have some sort of social or emotional condition.

In most cases, these assumptions are unfounded. Here are a few of the most common myths about shelter animals:

  1. You don’t know what you’re getting. Many rescue and shelter animals are former pets or have been in extended foster care with an experienced pet owner. Their foster owners or shelter caretakers can often tell you detailed information about the animal’s personality, habits, abilities and even quirks. This is typically not information a pet store or breeder is able to provide.
  2. Shelter animals are pets gone bad. Just because a past owner gave an animal up doesn’t mean the pet was poorly behaved or a nuisance. In fact, most owners relinquish their pets due to a move, allergies, having children or because of financial difficulties, not because of the animal’s behavior or personality.
  3. Shelters and rescues don’t have the animals you want. Tools like Petfinder make it incredibly easy to see animals across nearly all the shelters and rescues in your region. And they don’t just have cats and dogs, either. Many of these facilities house rabbits, birds, ferrets and even pigs. Finding a shelter or rescue animal that fits in with your family is often just a click away.

Many also assume a low-cost adoption means a lower-quality animal. This just isn’t the case. Overall, shelter and rescue pets are well-socialized, healthy and will likely live longer lives than pure-bred animals or puppy mill pets.

Adopt, Don’t Shop

There are countless reasons to adopt your next pet. From saving a life (and hundreds of dollars) to helping put an end pet homelessness, puppy mills and the unnecessary euthanization of millions of animals every year, adopting a pet doesn’t just feel good, it does good, too.

The post The Financial Benefits of Adopting A Pet appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2Q0BlOR

How Blockchain Is Changing the Digital Marketing Industry

Cryptocurrencies have been a hot topic lately to say the least.

You probably heard about Bitcoin years ago—the most popular cryptocurrency with the most media coverage. In the early days, it was primarily used for transactions on the dark web.

But today, cryptocurrencies have evolved and are starting to gain traction.

Everyone knows someone with a cryptocurrency story. Either a friend, family member, or a friend of a friend invested in Bitcoin years ago and made a fortune off it.

Or maybe you’ve talked to someone who regrets selling too early before some of the most recent surges took place.

That said, I didn’t create this guide to spark a cryptocurrency debate. Everyone has an opinion on this method of payment, and I don’t want to get into all the pros and cons.

Instead, I want to focus on one specific area that makes this technology work.

Blockchain.

On the surface level, people associate blockchain with buying and selling cryptocurrencies, but it’s much more than that.

As a marketer, you need to recognize the latest trends and understand how blockchain technology works.

It will potentially impact your business today and in the future. It’s in your best interest to start educating yourself now.

Even if you’re not planning to implement cryptocurrency as a payment method just yet, knowing the concepts of blockchain is still important because it’s changing the digital marketing industry.

Here’s what you need to know.

What is blockchain?

Let’s start with the basics.

Blockchain technology can be compared to a shared ledger or an open record system.

These records are used to keep track of different transactions. There are multiple uses for the records on file.

As I said before, cryptocurrency is what comes to mind first. But blockchain can also be used to keep track of data such as home records, voting records, and medical information.

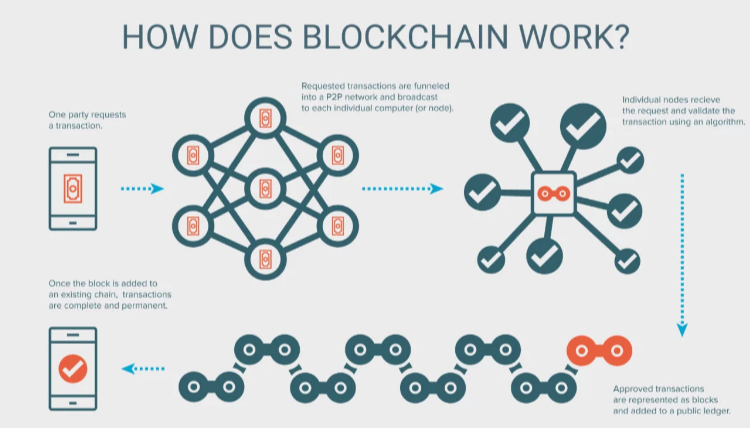
Each transaction is segmented by blocks, hence the name.

These blocks get verified by other users within the system. Blocks cannot be changed once they are verified.

The permanent blocks become added to a chain of other blocks that have already been validated as well.

It may sound a bit confusing, but here’s a great visual representation of the way blockchain works:

how does blockchain work

Right now, people are constantly buying and selling goods on the web. You might be one of those people.

But let’s look at third-party marketplace websites such as eBay.

Marketplaces turn a profit by charging buyers and sellers fees to use their platforms. If you buy something on eBay, the platform will use your bank and the seller’s bank to verify the transaction.

They will also confirm that the buyer and product actually exist.

Blockchain technology allows buyers and sellers to cut out these middlemen. This makes it possible to process transactions without the need of a third-party marketplace.

There won’t be any banks involved or transaction fees associated with the purchase either. Neither party will have to worry about exchange rates, even for international purchases.

It’s supposed to be a safe and fast way to make transactions. Blockchain is the backbone behind peer-to-peer electronic payments.

The first blockchain was created when the first cryptocurrency was created.

The software is open-source, allowing anyone to see the coding and make modifications to it. Next, different people and companies came out with different versions of blockchain without using the original coding.

Any user can see transactions made with blockchain.

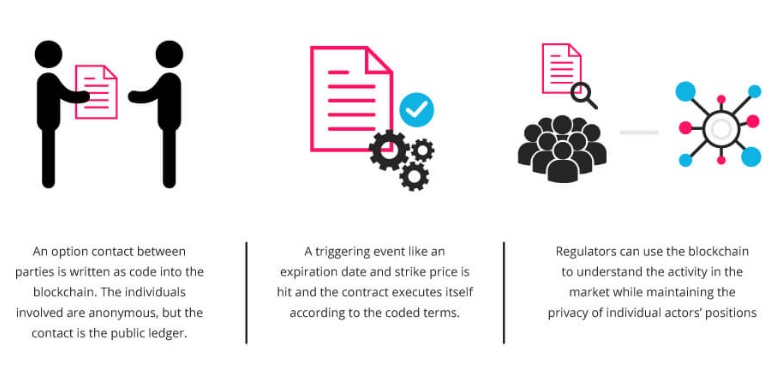
They are visible to everyone, even when completed between two people. While the blockchains are visible to anyone, the identities of the users can remain anonymous:

annonymous

Instead of having a name, each user in the system has a public address.

Algorithms can be written to automate the transactions. This is similar to the way you pay a Spotify subscription each month with your credit card.

Now that you understand the basics of how blockchain works, I’ll show you how this technology is being used to revolutionize the digital marketing industry.

Middlemen in digital marketing can be eliminated

Blockchain technology makes it possible for advertisers to avoid middlemen.

Right now, marketers go through third parties to handle their advertisements.

Let’s go through an example.

Let’s say a company wants to offer banner advertisements on its website. But it doesn’t want to sell its ad space to just anyone.

Ads linking to low authority or sketchy businesses won’t add credibility to your website.

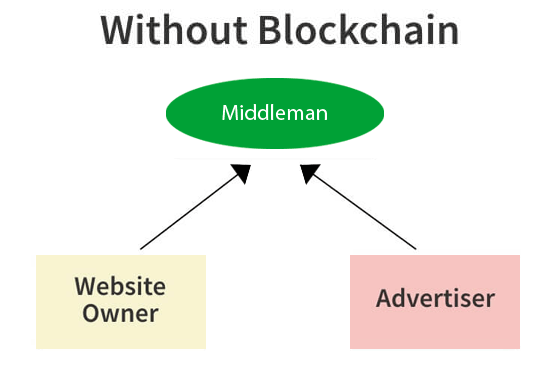
How does this company proceed? It goes through a platform such as Google. In this case, Google will act as the middleman.

By participating in Google Adsense, the company is assured that it will be connected only with credible businesses that want to buy advertising space.

This process makes both parties feel secure about the ads.

The site selling the space knows it won’t have any malicious content from unreputable brands being displayed on its pages. Furthermore, the company buying the advertisement knows that its ads will be run on legitimate sites.

Google processes the transaction and charges a fee for its part in the deal.

That’s the current system that marketers are using without blockchain technology:

without blockchain

Now, let’s apply the blockchain concepts to this example.

Companies won’t have the need to go through a third-party platform such as Google with the blockchain structure.

That’s because blockchain users can be verified through its networks. People would know they’re getting what they’re paying for as opposed to potentially paying for clicks that aren’t genuine.

It’s still a safe and secure way to process each transaction.

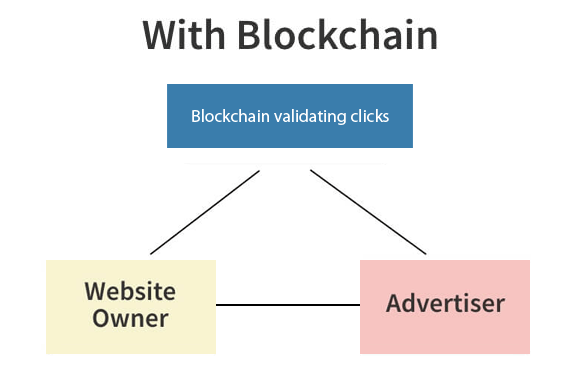
Blockchain, ultimately, eliminates the need for intermediaries in the procedure:

with blockchain

Don’t get me wrong.

Google and its advertising platform aren’t going anywhere just yet. That’s not what I’m saying. It’s still arguably the biggest powerhouse in the marketing industry.

I’m not telling you to ditch your Google AdSense strategy either.

All I’m saying is the concepts behind blockchain technology will make it possible for companies to avoid these types of third-party platforms.

Ditching the middleman will make advertisements more profitable since marketers won’t have to pay additional fees for the transactions.

Consumers can control content

As a marketer, you don’t want to hear this, but consumers don’t want to see ads all the time.

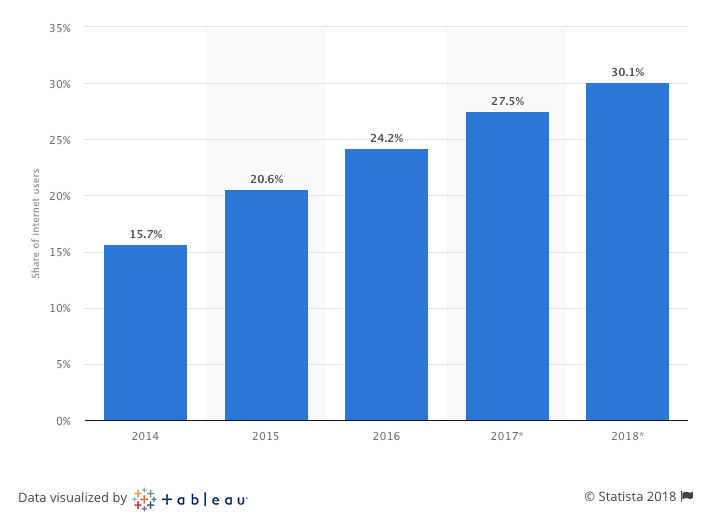
That’s why ad blocking penetration continues to rise each year in the United States:

ad blocking penetration

People have different reasons for using ad blockers.

According to a recent study, 51% of people justify their use of ad blockers because it’s their Internet experience and they want to be in complete control of it.

Other top results from the survey include convenience and wanting on-demand content without waiting for an ad to load.

In some instances, it seems ads have grown out of control. But that’s the nature of the modern digital world.

Ad targeting has become much better with new technology. The ability, for example, to use lifetime value to create Facebook audiences that convert makes it much easier for businesses to reach their target markets.

Sometimes when a customer makes a transaction or gives out their information to one party, they receive advertisements even when they never opted in to it.

Blockchain technology can give consumers the right to charge companies for their contact information.

If a company wants a consumer to subscribe to their newsletter, the customer can reply with their price to receive that content.

For example, each consumer who reads an email could cost brands fractions of a cent. Transactions would be processed through cryptocurrencies automatically.

This concept gives consumers complete control over who has their information.

It will also make it more challenging for marketers to showcase their relevance and level of importance to the consumer. Brands will need to learn how to create a highly effective value proposition in these instances.

Transparency and accountability will build trust

It’s not always easy for brands to gain the trust of their consumers. This is especially true for smaller, less-known businesses.

With so much information out there, people have become skeptical about what they’re being told and which brands are telling the truth.

People want answers.

They want to know where their food is coming from.

They want to make sure their clothes are coming from factories with appropriate working conditions for the employees.

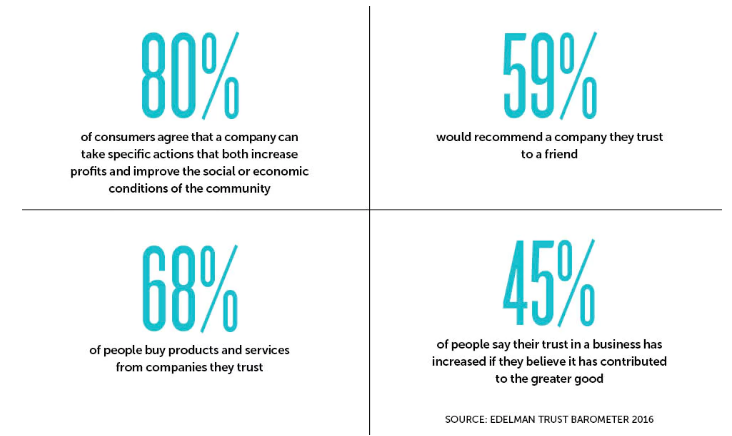
Trust has a major impact on purchasing decisions:

trust

Blockchain will force businesses to become more transparent about their operations.

That’s because every step and record can be verified and documented for everyone to see on these open source networks.

Consumers can have complete access to the supply chain of a retailer or distributor.

This type of information will show everyone exactly how and where their products are being manufactured. Each step of the process is tracked with blockchain.

Since this information will become public record, companies will be held more accountable for their actions.

They can’t claim their goods were manufactured in a factory with good health conditions if that’s not true. Otherwise, it won’t be verified in the blockchain.

Do you think this sounds crazy? Too good to be true?

Think again. Companies have already started doing this.

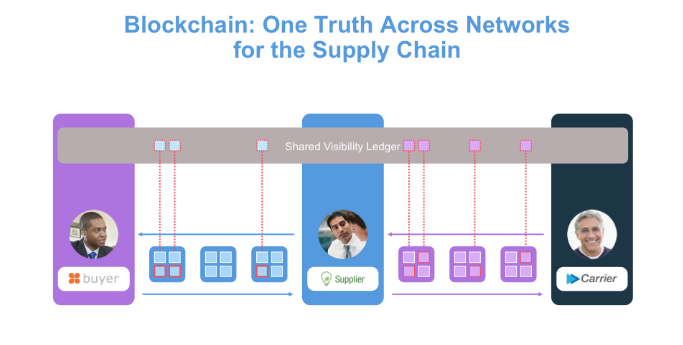
I recently read a case study on this subject conducted with IBM and Walmart. It covers the supply chain process with blockchain technology:

IBM walmart

Technology was used to track where the products were coming from.

In this case, it was tracking food. The idea was to trace the source and supply chain of pork products through each step of the supply chain.

It started all the way back in China—the world’s largest pork producer.

Blockchain holds companies accountable and builds trust between the brand and their customers. This is a brand’s way of showing everyone it has nothing to hide.

With blockchain technology, the public can see digital contracts between two parties.

This forces everyone involved to keep up their end of the deal.

Security must be a priority

With this technology becoming part of our lives fast, businesses need to prioritize security more than ever.

Don’t get me wrong, businesses always needed to emphasize website security and protecting customer information.

However, since blockchain can be used to process transactions, malicious advertisements could potentially become an issue.

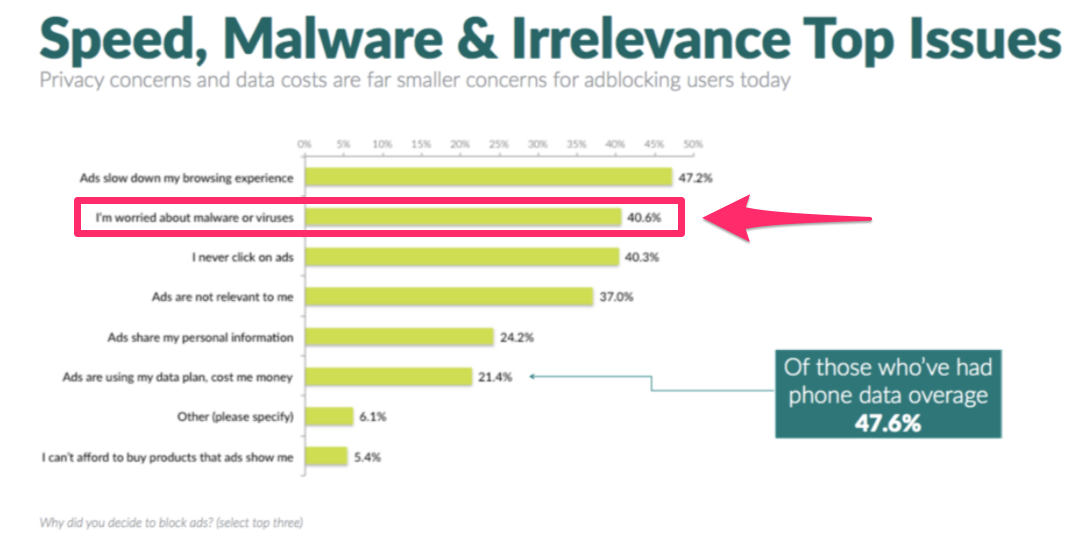
People are already concerned about malicious malware and viruses when it comes to their privacy and ads:

security

As a result of these concerns, we should see a growth in the fraud verification industry.

They will implement blockchain technology.

The verifications required to add blocks in this system can prevent criminals and bots from stealing precious information.

Businesses will accept more alternative payment methods

Right now, you probably can’t walk into your local coffee shop and buy something with Bitcoin or another cryptocurrency.

But we may not be too far from those days.

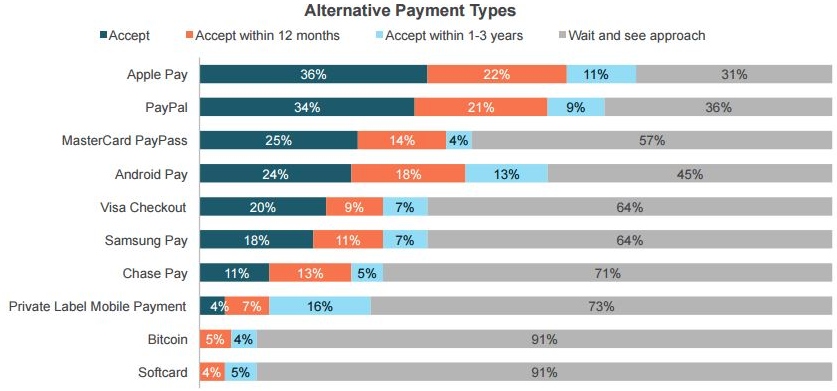
Some companies are already preparing to adapt to alternative payment types:

alternative payment

Only about 9% of businesses plan to accept Bitcoin within the next three years.

We’re still not at the point where it has penetrated the mass consumer market. But this could be approaching us faster than you might think.

Blockchain technology is making this possible.

As a business owner, you need to recognize this and at least prepare yourself to adapt when these types of payments gain more traction at the mass consumer level.

Conclusion

Blockchain is almost always associated with processing cryptocurrency payments.

However, this technology can be used for much more than that. Its applications have the ability to change the digital marketing world as we know it.

Blockchain gives marketers the ability to cut out middlemen when buying or selling advertisements, such as a PPC campaign.

Consumers will have more control over which companies can send them information.

Since blockchain transactions are an open ledger for anyone to see, businesses will be held accountable for their actions and forced to be more transparent.

Your business might not be ready to accept cryptocurrency just yet, and I’m not saying it should be. But it should keep an eye on this emerging trend in the coming years.

How is your company preparing for digital marketing changes associated with blockchain technology?


Source Quick Sprout https://ift.tt/2FJdTAY

This Free Program Trains Students and Matches Them With Paid IT Internships

When Careful Consideration of Purchases Backfires

One money strategy I’ve used since the very first day of my financial turnaround is to carefully consider all of my purchases. I try to avoid buying things unless I’ve given that purchase some serious thought, especially expensive items, but even most inexpensive ones.

While this works extremely well for me in a bubble where my relationships with others are secure and I’m concerned mostly with my financial future and my family’s stability, it’s not exactly a good strategy in other respects.

For starters, using that approach in social situations with every little purchase can indicate to others that you’re a complete cheapskate, which can damage relationships because people interpret that “cheap” behavior as personal disrespect when none is intended. While I do advocate for not worrying what other people think, blatantly displaying character traits that others would think of as negative is not something you generally want to be doing.

This is particularly true when your behaviors have an impact on others. Many people don’t like bad body odor or bad breath, for example, so even though you might not care what other people think, basic hygiene standards are still important. In a nutshell, you should treat other people as you would like to be treated, and that does mean thinking of others in many of the ways you act in public. What you shouldn’t worry about is what other people think of your choices in ways that don’t impact their lives, but being a cheapskate can definitely impact the lives of the people you associate with.

For example, let’s say that I’m hypothetically going out to dinner with an old friend or Sarah and I are going out with a couple that we want to build a friendship with. While I’m not going to spend like I’m crazy, I’m certainly not going to inspect the menu for the absolute cheapest options, order water, refuse to share a bottle of wine, or anything like that.

Let’s say that I was going out on a date (hypothetically… I haven’t been on a date with anyone other than my wife in more than twenty years). I probably wouldn’t want to sit there counting pennies if we went out to eat or went to a movie. I’d also not be doing myself any favors if I sat there judging my date for choosing to order a side salad or a cup of tea instead of free water.

Let’s say that I have friends over for a dinner party. While I’m not going to drop hundreds of dollars on gourmet foods for everyone, I’m also not going to serve them instant ramen or peanut butter sandwiches, items that I might otherwise occasionally eat for lunch if I’m going solo or with my family.

There are even some non-social situations where you cost yourself by overly considering purchases. Let’s say I’m at a yard sale and I come across an item that I know I can flip for ten times the value, but it far exceeds what I intended to spend at yard sales this time. It would be silly of me to pass it up.

The reality is that sometimes “carefully considering purchases” isn’t the best strategy. Social situations are often an example of this, but so are situations where a truly exceptional bargain falls on your lap (and I’m not talking about a sale at Kohl’s here) or some other outsized opportunity.

Here are some principles I use to figure out the specific situations where “carefully considering purchases” can backfire on me and when I should loosen the purse strings a little.

I don’t worry about spending during out of the ordinary social situations. If I’m seeing a friend I haven’t seen for a long time or I’m trying hard to build a strong relationship with someone, I don’t really worry about the expense. To me, bonding that relationship takes priority over relatively small expenses. I’ll go out to dinner with an old friend and I really won’t worry about the cost of it, because the expense there isn’t the meal. It’s an investment in the relationship.

“Out of the ordinary” situations are ones that are unlikely to repeat in the foreseeable future; I remain cost conscious in ordinary situations that are likely to repeat. If I’m doing something with my usual good friends, or if I’m on another date with someone I’ve been dating for a while and things are going well, then I’m going to be very conscious about the expense. At that point, I’m surrounded by people who know me well and they’re also almost entirely people who share at least some of my financial values, so I don’t feel bad about being cost conscious. I would not want to hang out with people who insisted on blowing a bunch of money every weekend. I would not want to date someone who wanted to blow a wad of cash on every date.

To make it very clear, if I can state an approximate date when this event or something similar will recur, I’m much more likely to be cost conscious and think about minimizing the expense. If I can’t state when it will recur, I’m much less cost conscious.

If I don’t want to eat at a super-expensive restaurant, I say so; if I’m the host and I’m choosing, I generally choose something local that’s unusual but not overly expensive. I have a handful of local places that I like to choose from when people come here from out of town and want to eat out. They’re all interesting places, but none of them are wallet busters.

If I am sure I can profit from a situation (without harming anyone), I pretty much have no limits, but I need to be absolutely sure. I have to be extremely confident about this, however, so it needs to be something well within my own domain knowledge. I’m not going to merely trust someone’s word on it. I’m also not going to “invest” in someone else’s idea or business plan without a ton of careful consideration. So, in that yard sale instance, you better believe I’ll pony up when situations like that happen if I know without a doubt that I can make a profit for myself.

I have some “flexibility” in my budget for these kinds of situations. In fact, I literally call that item “flex.” The “flex” item in our budget is so that we can afford to go over budget during situations like these, where the normal “careful consideration of purchases” has negative consequences, socially or otherwise.

A quick side note: I tend to avoid social shopping if at all possible. “Retail therapy” virtually never improves my feelings over the long term. If I’m hanging out with a friend, I’d rather be engaging in an activity that isn’t centered around money if possible; if not, then it should be a special occasion and shopping is not a special occasion.

The best approach is to not view stores as any type of entertainment or social venue. They serve the sole purpose of acquiring goods, and you’re far better off knowing exactly what you want before you go in the door. Going to the store to “kill time” or to browse or to socialize or to be entertained results in the spending of money that you weren’t intending to spend without any real benefit. If you want to just hang out somewhere other than your house, go to a park or a free exhibit or a free museum or some kind of public event.

One final tip: don’t worry much about what other people are spending. If someone else chooses to order a glass of wine or a side salad, it’s not your concern in that moment. You may later on decide that you don’t want to build a relationship with someone who spends a lot of money, but as a one-off choice, it doesn’t really matter. Your goal in such situations should be to build or maintain a positive relationship with this person, not to obsess over what they’re spending.

This might sound silly, but my preferred approach for this at a restaurant is to request to order last and then study the menu while others are ordering. I converse up until the waitstaff comes to take down our orders, then request to order last and make my decision quickly while others are ordering. That way, I generally don’t even know what they ordered, so it has zero impact on me whatsoever. I’m usually half-surprised at what comes to the table for the people I’m dining with.

In a nutshell, don’t be cheap in social situations or in situations where there’s a guaranteed upside for you. Save your cheapness for when you’re alone, with just immediate family, or with friends who feel similarly. That doesn’t mean that you should start throwing money around when others are around, but that you might find it worthwhile to relax those spending guidelines a little.

Good luck!

The post When Careful Consideration of Purchases Backfires appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2ArlE8s

How I Spent Under $1,000 to Furnish My Entire Apartment

الثلاثاء، 27 نوفمبر 2018

Should Your Small Business Hire a Lawyer?

Before I became a small business owner, I was a lawyer. This leap from one very different career path was reminiscent of Elle Woods in the movie Legally Blonde going from fashion to law school. Only I started out as a practicing attorney, and later became the CEO of a small business. While, admittedly, there […]

The post Should Your Small Business Hire a Lawyer? appeared first on The Work at Home Woman.


Source The Work at Home Woman https://ift.tt/2RjPIdE

This 30-Day Challenge Will Help Any Married Couple Conquer Their Money Woes


Congratulations! You’ve said your vows. You’ve thrown that bouquet (who knew Grandma could jump like that?). You’re even rocking a nice tan from your honeymoon.

Now married life really begins. Like it or not, your finances are a major factor in your marriage. According to Dave Ramsey, 86% of couples who got married in the last five years started out in debt.

It’s OK. Take a deep breath. We’ve put together a one-month challenge for married couples to get your finances in shape for your happily ever after.

Do you accept the challenge? If so, say, “I do” (again).

Day 1: Check Your Credit Scores

Your credit score is important, now more than ever. The better your score, the better deal you’ll get on a mortgage, rental deposit, car loan or credit card. If either you or your spouse has a less-than-ideal credit score, it’s time to start working on it.

To keep a closer eye on your credit, get your credit score and a “credit report card” for free from Credit Sesame. It breaks down exactly what’s on your credit report in layman’s terms, how it affects your score and how to address it.

Signing up for Credit Sesame will only take you a couple of minutes each, and it’ll even help you tackle any issues you see.

Day 2: Tackle Your Credit Card Debt

Sometimes “for better or for worse” includes taking on your spouse’s credit card or other high-interest debt. Don’t let it get you down. Instead, take those balances down in a smart way.

A good resource is consumer financial technology platform Even Financial, which can help match you with the right personal loan to meet your needs.

Even searches the top online lenders to match you with a personalized loan offer in less than 60 seconds. Its platform can help you borrow up to $100,000 (no collateral needed) with fixed rates starting at 4.99% and terms from 24 to 84 months.

Day 3: Get Paid to Get Fit

Your honeymoon was full of buffets, decadent desserts and pina coladas. Totally worth it. Now it’s time to make up for those fun times.

There’s a cool company, HealthyWage, that will literally pay you for losing weight.

Here’s how it works:

  1. Read our full HealthyWage review, and sign up.
  2. Define a goal weight and the amount of time you’ll give yourself to achieve it.
  3. Place a bet on yourself ranging from $20 to $500 a month.

Depending on how much you have to lose, how long you give yourself to do it and how much money you put on the table, you could win up to $10,000!

Wondering if it can really work? We talked to one woman, Teresa Suarez, who lost 68 pounds — and made over $2,400.

The couple that gets fit together stays together, right?

Day 4: Budget Your Wedded Bliss

A budget is not fun, but you’ll be surprised at how freeing it can really be, especially for a married couple. You’ll know your limits and take the mystery out of your monthly spending.

The Empower app is a powerful budgeting tool that can help you figure out how you’re spending your money and develop a budgeting plan to keep you on track.

Link the app to your bank accounts, and it will track your spending. It will also categorize your spending so you can see exactly where you are overdoing it.

That’s right: It will show you just how many times you went out for dinner because it was your turn to do the dishes.

Day 5: Start Adulting With a Life Insurance Policy

When you’re married, you have someone else who counts on you. If you have a family, the last thing you want is to leave them without any financial support once you’re gone.

Getting a life insurance policy is a smart move — and it’s not as hard as it used to be.

Ethos, for example, can get you term life insurance in less than 10 minutes — with no medical exam — for coverage up to $1 million. Ethos offers a digital application, and customer service is available if you have questions.

It partners with a major life insurance carrier to quickly offer policies as low as $6 a month.

You don’t really want to think about “‘til death do us part,” but it’s a conversation you need to have. You’ve got this!

Days 6 and 7: It’s the Weekend! Find Free Stuff in Your City

What? You thought we’d make you work every day? Good marriages need room for quality time to have fun together, too, right? Just don’t spend a lot of money doing it.

From museums to community movie nights, there’s most likely a rich menu of 100% free things to do wherever you are!

Check your local newspaper or city website, and see what you can get into — without paying a dime.

Day 8: Find out If You’re a Power Couple

How do you compare to your peers? Are you the neighborhood’s power couple, or are you barely keeping up with the Joneses? It’s time to find out.

Status Money is an app that allows you to anonymously compare your financial situation with your peers without asking those awkward, prying questions. Link an account to tap into this database and you’ll be able to compare your income, debt, interest rates, credit score, spending… you name it.

By seeing how others are doing, you can see what you need to work on — or where you can sit back a little and just breathe easy.

Day 9: Wash Your Car, and Clean up Your Car Insurance Bill

You each have a vehicle. One took you on your first date. The other was topped with streamers and balloons on your wedding day. Now it’s time to give them both a good wash — and then clean up your insurance bills.

Yes. There’s no getting around car insurance, unfortunately. But one way you could save money is by shopping around and comparing rates at least once a year. So, just like you compare the prices of flights, shoes and laptops before purchasing, why not compare car insurance?

The Zebra, an online car insurance search engine that offers “insurance in black and white,” compares your options from 204 providers in less than 60 seconds.

Day 10: Make a Shopping List — and Get Paid

You probably shopped online before you were married. You won’t likely stop now, right? But now it’s even more important to save money where you can.

One of our favorite ways to save is with Ebates, a cash-back site that rewards you nearly every time you buy something online. For example, Ebates gives you 10% cash-back on online purchases at Walmart.

Plus, you’ll get a free $10 gift card to Walmart for giving the site a try.

Day 11: Stock the Fridge and Pantry With Savings

They say that 90% of marriage is asking “What should we have for dinner?” That number may actually be a bit low.

One of the best ways to avoid this trap is to get ahead of it. If you plan your meals for the week and shop accordingly, you’ll be all set. You know what makes your meals taste even better than butter or salt? Savings.

Believe it or not, Ibotta will pay you cash for taking pictures of your grocery store receipts.

Before heading to the store, search for items on your shopping list within the Ibotta app. When you get home, snap a photo of your receipt and scan the items’ barcodes, and earn cash back.

Ibotta is free to download. Plus, you’ll get a $10 sign-up bonus after uploading your first receipt.

Pre-planned dinner plus a pay day? That’s romance, right there!

Day 12: Put the Gold in Your ‘Golden Years’

When you said “I do,” you made a promise to make a future together. That future will look a lot better if you plan for your retirement right now.

If you’re like most people, you have no idea whether your 401(k) is on pace for retirement or just sputtering along.

Chances are, your 401(k) could be doing a lot better. Take control with help from Blooom, an SEC-registered investment advisory firm that can optimize and monitor your 401(k) for you and keep it speeding toward retirement.

It just takes a few minutes to get a free 401(k) analysis  that will show you whether your investments are allocated properly and whether you’re losing money paying hidden investment fees. It’ll even tell you just how much more money your account could earn by the time you want to retire.

After that, if you sign up, it’s just $10 per month to have Blooom monitor and maximize your 401(k). Bonus: Penny Hoarders get the first month free with the code PNNYHRD.

Think of Blooom like a mechanic constantly fine-tuning your car’s engine so it gives you the best possible performance and gas mileage. Except it’s your 401(k) — and your future.

Days 13 and 14: It’s The Weekend! Relax, and Grab a Glass of Wine

You’ve made great strides! Hey, marriage isn’t all work. Give yourself a break today. You’ve earned it.

Tonight, kick back, relax and enjoy each other’s company with a glass of wine. Of course, you don’t want to go overboard and spend a bundle on that bottle. Find a great bottle of wine for under $20, and toast to your financial progress.  

Day 15: Clear Your Clutter

Wow. Now that there are two of you, all of your stuff really adds up, doesn’t it? It’s not just the things you have two of, like ironing boards and disco balls; it’s clothes, shoes and furniture.

Set up shop, and make some extra money from the stuff you don’t need (and probably don’t have room for anymore).

You can sell virtually anything on Letgo. This intuitive app lets you snap a photo and upload your item in less than 30 seconds. It removes a lot of the hassle of selling things online, and it’s 100% free to use.

Marriage tip: Only sell your stuff. Posting your spouse’s items is a one-way ticket to the dog house.

Day 16: Feel the Thrill With a Free Lottery

There’s something so satisfying about those gas station scratch-off tickets, but it’s better to avoid them because, well, that’s not Penny Hoarding.

Instead, try scratching for free using an app called Lucktastic. Each day, it releases a new assortment of digital scratch-off tickets. Lucktastic says instant wins range from $1 to $10,000. You can also earn tokens that you can exchange for free gift cards to retailers, including Amazon, Walmart, Kohl's, Sephora and more.

You can even compete with your spouse. Who can win more tonight?

Day 17: Relax, and Watch a Good Show

OK, you’re ready for a little snuggle time. That’s fair.

Tonight, pop some popcorn, pour a cool beverage and plop down on that loveseat. But instead of watching a movie, earn some money by watching movie previews or other short videos.

InboxDollars lets you actually get paid to watch TV online. The site hosts a ton of stuff to watch, including cooking, entertainment, news and health shows. The shows are sponsored by brands that need to get them in front of as many eyeballs as possible.

Every time you watch one, InboxDollars will credit your account with a little bit of cash.

Day 18: Get Money for Past Purchases

What couple couldn’t use a little extra money? Here’s an easy way to see whether you could get money back on purchases you’ve already made.

One of our secret weapons is called Paribus — a tool that gets you money back for your online purchases. It's free to sign up, and once you do, it will scan your email for any receipts. If it discovers you’ve purchased something from one of its monitored retailers, it will track the item’s price and help you get a refund when there’s a price drop.

Plus, if your guaranteed shipment shows up late, Paribus will help you get compensated.

Day 19: Protect Your Nest Without Robbing Your Nest Egg

If you own a car, you know that you need to protect it (and yourself) with insurance. But did you really check out your options? You could be paying too much for your coverage. Shopping around for insurance can be time consuming, though.

Fortunately, a service called Gabi will do it for you, and you don’t even have to fill out any forms. Simply link your insurance account and provide your driver’s license number, and Gabi will go to work.

Once you link your insurance account to Gabi, it will:

  • Scan your existing insurance plan.
  • Analyze what coverage you have.
  • Compare the major insurers’ rates for that same coverage.
  • Help you switch on the spot if it finds you a better rate.

Gabi says it finds an average savings of $720 per year for its customers.

It is a true apples-to-apples comparison at the same coverage levels and deductibles you currently have. Once you sign up, you never have to shop again. Gabi's software has your policy on file and keeps on monitoring for savings as your life changes.

Day 20 and 21: It’s the Weekend! Enjoy Free Stuff at Your Gym or Apartment Complex

If you have a gym membership or a fitness lounge at your apartment complex, you might be missing out on lots of luxurious freebies.

Think tanning beds, massage chairs or complimentary personal training sessions.

Get down there, and treat yourself!

Day 22: Take the First Baby Steps to Investing

Marriage makes you think about the future. A lot. A big part of preparing for your financial future is investing. Now that you’ve invested in that ring, it’s time to go further.

Consider starting an investment account through Acorns.

You can start small and stack up change over time with its “round-up” feature. That means if you spend $10.23 at the grocery store, 77 cents gets dropped into your Acorns account.

Then, the app does the whole investing thing for you.

The idea is you won’t miss the digital pocket change, and the automatic savings stack up faster than you’d think. For example, we reviewed how Penny Hoarder Dana Sitar was able to save at a rate of $420 a year!

At that rate, you could set aside $1,000 in about two and a half years — without trying.

The app is $1 a month for balances under $1 million, and you’ll get a $5 bonus when you sign up.

Day 23: Optimize Your Credit Card Rewards

So you want a credit card, but there are too many to choose from. What to do?

Should you leaf through your junk mail and just accept one of those credit card offers that show up in your mailbox? That would be quick and easy, right?

No, no, a thousand times no! Don’t do that. That’s a good way to end up unhappily shackled to a credit card that’s all wrong for you.

At least one in five cardholders are carrying around a credit card whose fees and rewards don’t match their actual spending habits, according to a 2016 study from J.D. Power.

To help you avoid becoming a statistic, here's our guide to everything you need to know about credit cards — including how to pick the one that's right for you.

Day 24: Focus on Some Extra Cash

You and your spouse take the most awesome pics, right? If you have a smartphone and a photographic eye, making money might have just gotten a lot easier.

An app called Foap lets you turn your smartphone photos into cash.

Here’s how it works:

  1. Download the free app and create an account.
  2. Take a quality photo and upload it to Foap’s marketplace.
  3. Someone buys the license to your photo for $10. You make $5.

If your photo sells 20 times, you make $5 each time and end up with $100 in your pocket — all for about five minutes of work and probably a nice stroll in the park with your spouse. Pretty cool, right?

Day 25: Put Your Bills on a Diet

Good news: As a married couple, you’ll share bills. Bad news: They’re still bills.

The price of internet — and cable, if you’re still into that kind of thing — certainly isn’t decreasing. If anything, prices are steadily climbing.

And if you’ve had to chat with a representative from your internet/cable company recently, you know how long you can sit on hold.

That’s why it’s time to call in a robot. The negotiation bot Trim will negotiate your cable or internet bills down for you.

It works with Comcast, Time Warner, Charter and other major providers.

You can sign up simply with Facebook or your email address. Then, upload a PDF of your most recent bill, and Trim’s AI-powered system gets to work. If at first it doesn’t succeed, it’ll keep negotiating until it can save you some money.

Also, if you have any outages, Trim believes you deserve a credit, and it’ll handle that for you. Trim takes 25% of the savings tab, and you get the rest.

26: Go Window Shopping, and Earn Gift Cards

No extreme physical activity or pulled muscles required for this money-making trick that’s fun for couples. All you need to do is download the Shopkick app.

Once you sign up, the app pays you in “kicks” for walking into certain stores (including Walmart, Target, TJMaxx and more). You can redeem them for gift cards to a number of retailers, including Amazon, Target, Walmart, Starbucks, Sephora and Best Buy.

It pays you even more kicks for photos of receipts that include qualifying items you purchased in-store with a connected credit or debit card. You can also earn kicks for online purchases. You don’t have to do anything; your linked cards will automatically apply your kicks.

But don’t make the mistake of buying things you don’t need just for kicks, you know better than that.

Once you’ve earned your gift cards, you can enjoy them with a little quality time together.

Day 27 and 28: It’s the Weekend! Go to a Park

When’s the last time you went to the public park in your area?

You might be able to walk nature trails, goof around on a swing set, or just sit and watch the leaves fall. Take the time to simply be together and enjoy nature. It’s relaxing and relationship-building.

Day 29: Plan for a Bad Day. Seriously.

Few things stress marital bonds like sudden financial drama. A car breaks down. Someone breaks a toe, and medical bills pile up. The roof starts to leak.

The simplest way to avoid letting life’s little mishaps turn into financial disasters is to start an emergency fund. It’s simply a bank account with enough money to get you through a minor emergency or surprise bill.

But if you’re going to save, you might as well make some interest on that money, right?

An iOS app called Varo Money combines traditional banking tools with modern technology to help its customers become financially healthy.

Here’s the best part: Pair your Bank Account with a Varo Savings Account where you’ll earn 1.75% annual percentage yield. That’s nearly 30 times — repeat, 30 times — the average savings account, based on a 0.06% average reported by CNN Money.

Day 30: Play the Slots — and Earn More Interest Than at Your Bank

It’s Day 30!! Go ahead; relax, and play some games. But you’re not done helping your finances just yet.

The folks who created Long Game have you covered with a game that’s fun and helps you achieve your financial goals.  

As you save and accomplish missions, you’ll earn coins to play mini games for cash prizes. We’re talking the classics, like slot machines, scratch-offs and spin-to-win wheels.

Once you link your bank account, you’ll earn 300 coins, so you can start playing while you wait for payday. If you sign up before Nov. 30, 2018 and enter the code PENNY5, you’ll also get a bonus $5 in your account!

You Did It!

See, that wasn’t so bad, was it? When you start thinking long-term, you need to think about your finances. When you bring someone else into the picture, it becomes even more important.

Tackling a few of these items can help set you up for a much better financial future. That’s worth a month’s work, right?

Now… let’s talk about having kids.

Tyler Omoth is a senior writer at The Penny Hoarder who loves soaking up the sun and finding creative ways to help others. Catch him on Twitter at @Tyomoth.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.

The Penny Hoarder Promise: We provide accurate, reliable information. Here’s why you can trust us and how we make money.


source The Penny Hoarder https://ift.tt/2AqmS40

Use Your Health Insurance Before Year's End and Your Dental Insurance, Too

Are insurance concerns not high on your holiday list? You could be wasting money by not reviewing your insurance usage before the holiday madness starts in earnest.

Source CBNNews.com https://ift.tt/2P6Mb08

We’ll Tell You How to Pay off Credit Card Debt — in Just 100 Words


So you’re falling behind on your credit card payments. You’re paying so much in interest every month, you can’t pay off the principal you owe. You’re just treading water financially.

If you have a lot of credit card debt, look into consolidating it. Borrow money at a lower interest rate, and use the loan to pay off the balances on your high-interest credit cards.

It’s a twofer: You save money on interest payments, freeing up cash to pay down your debt faster.

An online marketplace like Even Financial will search the top lenders to find the best loan for you.

Mike Brassfield (mike@thepennyhoarder.com) is a senior writer at The Penny Hoarder. He’ll be brief.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.

The Penny Hoarder Promise: We provide accurate, reliable information. Here’s why you can trust us and how we make money.


source The Penny Hoarder https://ift.tt/2FTqba2

#GivingTuesday: How You Can Participate, Even If You Don’t Have Extra Cash


I rarely participate in Black Friday or Cyber Monday, but I’ve always been excited about the day that follows: #GivingTuesday.

Rather than spend money on things you may or may not need, this international movement asks you to donate to causes you care about.

The day started in 2012 and, with the help of social media, it spread quickly. Last year, it raised more than $274 million for charity.

I love #GivingTuesday because it’s a reminder to support the organizations that work tirelessly to make our world a better place.

And you don’t need to give a lot. If everyone gave a few bucks — or a few hours of their time — to their favorite cause this #GivingTuesday, it would go a long way. Plus, you’ll get a tax deduction!

How to Participate in #GivingTuesday

Want to get involved in this warmhearted movement? Keep reading for step-by-step instructions.

Find a Cause to Support

What cause speaks to you? Perhaps you already have an organization you love, or perhaps you just know you’re passionate about homelessness or animal rights.

Once you’ve determined which cause you want to support, look for an organization that works in that field.

Choose an Organization

Charity Navigator is my favorite website for finding and vetting new organizations.

It allows you to search by cause, location, size and keyword — then, more importantly, it displays ratings for each charity based on its finances, transparency and accountability.

It’s an easy way to see which charities are responsibly effecting change with the money they receive.

Don’t skip this step; make sure you’re giving your hard-earned money to a worthy cause.  

Keep Records for Your Taxes

If and when you decide to donate, keep a record of your contribution.

Donations to a 501(c)(3) non-profit organization are tax-deductible — meaning if you donate $100, you can reduce your taxable income by that same amount.

Giving to a good cause and saving on your tax bill? Win-win!

Think of Alternate Ways to Give

Even if you’re broke, don’t worry; you can still get behind #GivingTuesday.

Though the day’s goal is to raise money for good causes, remembering its altruistic inspiration is just as important.

If you don’t have any money to spare, here are a few ways to participate without opening your wallet:

  • Look for a local or virtual volunteer opportunity on VolunteerMatch.
  • Give blood.
  • Donate used clothing or goods to a charitable thrift store.
  • Simply strive to practice kindness and gratitude with everyone you meet.

And if nothing else, you can spread word of the movement on your favorite social media site using the hashtag #GivingTuesday!

Susan Shain is always seeking adventure on a budget. Visit her blog at susanshain.com, or say hi on Twitter @susan_shain.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.

The Penny Hoarder Promise: We provide accurate, reliable information. Here’s why you can trust us and how we make money.


source The Penny Hoarder https://ift.tt/2FJ3jK1