

الخميس، 13 ديسمبر 2018

6 Simple Steps to Paying Off Up to $100,000 in Credit Card Debt
Many of us carry credit card debt.
It’s an unfortunate fact, and it’s becoming more and more commonplace in today’s society.
But getting rid of your debt doesn’t have to be this huge life event. It doesn’t have to take days and days of strategizing, years and years of strict budgeting or even decades and decades of payments.
Trust us: You can — and you will — make it out.
You just have to know where to start.
6 Simple Steps to Get Rid of Up to $100,000 in Credit Card Debt
The key to paying off your debt is to not become overwhelmed. It’s easy to build it up in your head until it’s this huge, mountainous task that’s impossible to scale.
Nope! Don’t let that happen. Instead, take away the stress and follow these simple tips to embark on your debt-payoff journey.
1. Let This Company Pay off Your Credit Cards Upfront
When you think about how much debt you have, you might feel a little anxious.
That’s where a company like Fiona can be helpful. It can help you find personalized lending options to refinance or consolidate your debt to potentially save thousands of dollars in interest.
Fiona will show you all the lenders willing to help you pay off your credit card and eliminate the headache of paying bills by allowing you to make one payment each month.
You can borrow up to $100,000 (no collateral needed) and compare interest rates, which start at 4.99%. The idea is to secure a loan at a lower interest rate, potentially helping you save thousands. Repayment plans range from 24 to 84 months.
Take, for example, Katherine, who faced $12,000 in credit card debt. Holding her back? The 15.24% interest rate. By refinancing with a 5%-interest, seven-year personal loan, she saved $12,000 in interest.
If she’d kept on the same road, she would have paid something like $14,000 in interest alone over 25 years. Yikes.
So even if you’re simply curious about what’s out there, know that checking rates on Fiona won’t hurt your credit score — and can probably save you in interest.
2. Start Trimming Your Monthly Bills
If you can cut down your monthly bills, it will leave more money to pay down your debt faster. But we’ve all got inescapable monthly bills. In terms of fixed expenses, your car insurance bill probably ranks right up there with your rent or mortgage payments.
Well, we’ve got some good news and bad news about car insurance: You’re probably overpaying.
But how would you know, really? Have you shopped around lately? Have you compared rates from the 20 largest auto insurers that do business in your area? That sounds kind of difficult and time-consuming, doesn’t it?
Fortunately, a service called Gabi will do it for you, and you don’t even have to fill out any forms. Simply link your insurance account and provide your driver’s license number, and Gabi will go to work.
Once you link your insurance account to Gabi, it will:
- Scan your existing insurance plan.
- Analyze what coverage you have.
- Compare the major insurers’ rates for that same coverage.
- Help you switch on the spot if it finds you a better rate.
Gabi says it finds an average savings of $720 per year for its customers.
It’s a true apples-to-apples comparison at the same coverage levels and deductibles you currently have. Once you sign up, you never have to shop again. Gabi’s software has your policy on file and keeps on monitoring for savings as your life changes.
3. Clean Up Your Credit Cards and Find Some Hidden Cash
Have you ever asked yourself: “Where the heck does all my money go? How is my credit card bill that high again this month?â€
It’s time to take a few minutes to clean up your tab. You can negotiate your bills, cut unnecessary subscriptions and wipe out bank fees with a service called TrueBill.
Yup. Download TrueBill, and it’ll negotiate your bills, cancel unwanted subscriptions and refund your bank fees for you. On average, TrueBill says it helps customers save more than $700 a year.
You can also try digging up some extra cash with Paribus — a tool that gets you money back for your online purchases. It’s free to sign up, and once you do, it will scan your email for any receipts. If it discovers you’ve purchased something from one of its monitored retailers, it will track the item’s price and help you get a refund when there’s a price drop.
Another way to save money? Shop through Ebates, a cash-back site that rewards you nearly every time you buy something online. For example, Ebates gives you 10% cash back on online purchases at Walmart. Plus, you’ll get a free $10 gift card to Walmart for giving the site a try.
Disclosure: Paribus compensates us when you sign up using the links we provide.
4. Earn Rewards When You Pay Off Your Debt on Time
When you were a kid, your mom probably gave you an allowance for washing the dishes and sweeping the floor. Now all you get for doing that is a kitchen that’s clean for, like, 15 minutes.
Now that you’re a grown-up, you no longer get rewarded for just doing the things that are expected of you — like, for instance, making payments toward your debt on time.
Not until now, anyway. MoneyLion, a free app for managing your personal finances, will reward you for things like paying your bills and monitoring your credit — even just setting up an account in the app.
Much like that childhood allowance, it’s basically bribing you to be good.
You’ll earn points in the app’s rewards program, and you can redeem them for gift cards to more than 15,000 retailers, including places like Walmart, Applebee’s and Amazon.
If you want to take it a step further and work on paying down debts, for example, MoneyLion can help with a loan to consolidate your debt and potentially reduce your interest rates. And it’ll reward you for that, too!
5. Start Saving Without Even Trying
Although you’re taking strides to pay off a chunk of debt, you can’t forget about your emergency savings. If something were to happen, you could land in another pile of debt — and the cycle would sadly continue.
But here’s a simple way to save money while paying off debt: Use Digit, an innovative app that automates saving for you. Simply link it to your checking account, and its algorithms will determine small (and safe!) amounts of money to withdraw into a separate, FDIC-insured savings account.
Bonus: Penny Hoarders will get an extra $5 just for signing up. Additionally, savers will receive a 1% bonus every three months.
Using this set-it-and-forget-it strategy, one Penny Hoarder saved $4,300 without noticing — read his Digit review.
If you need that money sooner than expected, you’ll always have access to it within one business day.
Digit is free to use for the first 30 days, then it’s $2.99 per month afterward.
6. Increase Your Income if Necessary
If you’re still struggling to make payments toward your debt, consider taking on a flexible side gig. Plan to put your extra income directly toward your debt.
One fun option that will take your mind off your debt? Playin’ with pups!
Rover just might be your perfect gig.
The online network connects dog walkers and sitters to local dog owners through its 4.9-star-rated app, so you don’t have to staple flyers on every utility pole across town.
Rover says sitters can earn as much as $1,000 a month.
Rover dog-sitter requirements vary by location. In general, you must:
- Be 18 years or older.
- Pass a background check.
- Have access to the Rover app (iOS or Android).
Here’s how it works: You’ll create an online sitter profile where you’ll answer questions about your experience with puppers and your schedule availability.
You can choose to offer a variety of services, including dog walking, overnight boarding at your home or theirs, and day care. Boarding is the app’s most popular service, so offering it can get you more gigs. You set your own rates. (Rover keeps a small percentage as a service fee.)
Dog owners will reach out to you. Accept which gigs you want, then start snugglin’ pups. As soon as you complete a service, you’ll be paid within two days.
Carson Kohler (@CarsonKohler) is a staff writer at The Penny Hoarder. She’s a very anxious person, so she totally understands how big financial to-do tasks can quickly become overwhelming.
This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.
The Penny Hoarder Promise: We provide accurate, reliable information. Here’s why you can trust us and how we make money.
source The Penny Hoarder https://ift.tt/2SJMqR1
Apple plans new $1 billion Texas campus, 5,000 more jobs
Source Business - poconorecord.com https://ift.tt/2UFa6rz
How to Buy a Domain Name
Your domain name is very important. It would be a mistake to gloss over the process of coming up with a name. If you take your project seriously, then you need to start off on the right foot with your name. After all, it’s going to be with you for the lifetime of whatever business or project you intend to use the domain for.
Many of the guides on how to buy a domain name or how to build a website tend to gloss over this process as well. It is often assumed that the best approach is to just register whatever domain name is available and call it a day. I think this is a big mistake.
There’s nothing wrong with registering a domain name that is available, as long as you’ve thought it through and are intentional about it. In fact, I would encourage that. The issue is that in many cases, people don’t even realize that there are other options. Getting your hands on the optimal name is more doable than you might think.
In this guide, I want to walk you through my process for buying a domain name, starting with how I go about coming up with a name in the first place.
Understand the Cost of a Domain Name
First and foremost, I suggest that you do put some budget behind your domain name — especially if it’s for your business. If your budget is tight, then you’ll be more limited in what you can do.
There are two options when it comes to getting your domain name
- Register a name that isn’t already currently registered.
- Acquire a name that is already registered from the person or company that owns it.
Regardless of which option you go with, you’ll still need to pay the annual registration fee of $7–$15/year on average.
The cost of acquiring a domain name will vary widely: You can easily spend 4–5 figures on a name. In some cases you can find a good one for hundreds of dollars. Some domain names aren’t for sale at all, while others have sold for millions of dollars.
Brainstorm Concepts and Ideas
Before you even think about buying a domain name, you’ll need to do some ground work.
Get creative, because it’s time to do some brainstorming.
Your domain name is going to be used for something. Maybe a business, or a campaign, or maybe just a blog. And you probably already have some ideas around what it’ll be called, so you’ve already started the process.
Create a Concept List
I like to call this a concept list. It’s the list before your final name list. It isn’t necessarily names, but for now, just concepts.
Take your project and write down of all the words, descriptors, phrases, ideas, mantras, etc. that come to mind. Come up with as many words as possible. Use a thesaurus to help.
I personally find a mind map useful for this process.
Create a List of Potential Names
Once you have a thorough concept list, you can develop a more refined list of potential names. Start by listing all the names that you like. Since you might not have an unlimited budget, make sure you dig deep here. You can’t be too picky yet, because that will end up limiting your options. Write everything down that you think might work.
Narrow Down The List According to Viability
You can narrow your list down quickly just by typing in the .com for each name that you like. Type it into your browser and see what is there.
- If there is an established website built on the domain name, cross that off your list. It is very unlikely to be a viable option.
- If nothing comes up at all, then keep it on your list. That could mean that the domain name isn’t registered yet, which is great!
- If a landing page with ads comes up, that means the domain name is parked. It is owned by someone already, but might be an acquisition target. Keep this on your list.
- If the domain name is for sale, then that is the best case scenario. That’s exactly what we are looking for. Keep it on your list, and take note of the listed price if there is a listed price.
I find that my best domain names are generally ones that are for sale (as opposed to unregistered). I recommend browsing through the following websites to get more ideas. You might get lucky and find something you like just by browsing. If you do, add those to your list as well.
BrandBucket — They put together more creative, brandable domain names and then sell them. I’ve found a lot of names here that I would not have thought of on my own.

BuyDomains.com — They have a huge selection of domain names for sale. They have transparent pricing and offer a seamless experience. This is always my starting point, and preferred approach to acquiring a domain name.

Sedo.com — Probably the biggest selection of domain names and the most well known place to acquire a name.

BuyDomains.com and Uniregistry are the biggest players in selling domains. More times than not, if a domain name is for sale when I type it into my browser, it is one of those two companies that is behind the sale. I find them to be the most reasonable. HugeDomains.com is another one that I have bought from.
Once you have the narrowed down list. The next step is to dig even deeper to determine what your final options will be.
Choose Your Name
You’re ready to go through the process of choosing your domain name.
Some high level rules:
- Don’t worry about SEO or keywords. That doesn’t matter.
- Avoid hyphens.
- Stick with a .com only. If you are in the UK, Australia, etc. then of course a .co.uk, .au, etc. is also good.
- The shorter the better, generally speaking.
Quick checklist for your domain name options
- Do you feel good about the name? Do you like it? Are you confident when you say it? Does it feel good when you write it down? When you read it?
- Is it brandable? Is it unique, easy to remember and meaningful? Is it easy to read and spell?
- Does it pass the google test? Google the name. Ideally there are not any other organizations that pop up. If there are, you at least want to make sure they are not in the same industry, or even in a closely related industry.
- If it passes the Google test, you are probably good to go, but just in case, you also want to check for trademarks.
A Note on Social Handles
In a perfect world, you’d pick a domain name whose social handles are also available. This isn’t a perfect world. My take on this is that it’s hard enough to get a good domain name. Don’t make it even harder or nearly impossible by also adding this criteria. When it comes to picking up the social handles, you’ll have options. You can get creative, or even potentially acquire the handles from the current owners.
It’s a good idea to consider social handles when making your final decision, but don’t let that alone stop you from picking the right name.
The Starter Domain Approach
An approach that I am a fan of is to use the starter domain approach. The idea here, is that you can start with a domain name with the intention to move to another one down the road.
Let’s say you identify a domain name that you really like, but it is out of range for your budget. For example, when I was coming up with a name for my latest company, I really liked GoodLife.com. Someone else owns it, and isn’t necessarily looking to sell it. If I wanted to buy it, I would have to offer a lot of money — a lot more than I was ready to pay. If I wanted to take the starter domain approach, I could have gone with the name Good Life Media, and acquired GoodLifeMedia.com which is for sale for $24,500. (That price must have gone up, because it wasn’t that high when I was actually considering this as an option.)
Anyway, I could start with GoodLifeMedia.com and eventually try to acquire GoodLife.com. It would be very easy to rebrand from Good Life Media, to Good Life. Internally, we would just go by “Good Life.” The day that we eventually acquire GoodLife.com would be a huge milestone and would create a built-in company goal that we could go after as a team.
If you want a real life example, The Wirecutter just recently rebranded to WireCutter.
Considerations for the starter domain approach
- Make sure it will translate cleanly. The two names have to be very closely related, and you could ideally even use the desired name everywhere outside of the actual domain name, including in your logo.
- Remember that there is no guarantee your desired target domain name will be there when you are ready.
- I recommend getting into discussions with the broker or domain owner of your desired name as soon as possible. Even if you know there isn’t any chance you can afford it today. They don’t need to know that. This is actually a huge advantage for you, because it is common that over time the owner will drop the price as they realize their high price isn’t going to happen.
Acquire And/Or Register Your Domain Name
At this point you should have a narrowed down list of viable options for your domain name. The next step is to own it.
Each of your options should fall into one of three categories.
- The domain name is available and unregistered.
- The domain name seems to be acquirable, but it is not clear.
- The domain name is clearly for sale.
What to Do If the Domain Name is Unregistered
In this case, all you need to do is go to NameCheap and register the domain name. You’ll find out for sure if that is an option or not once you type it into the search bar on NameCheap.
Our domain isn’t for sale…

But www.mathsoeasy.com is for sale — for less than $1,500.

You’ll go through a straightforward process here. Don’t buy any of the add ons or worry about web hosting or any of that yet. You want to use NameCheap to simply register your domain name. That’s it. They are the best domain registrar, and I use them exclusively. I do not use them for anything else, because there are other companies that I use for the rest of my web needs.
After you finish registering the domain name, that’s it. You are officially the proud owner of your new domain name. All you have to do moving forward, is be sure to renew the domain name each year. If you fail to renew it, then someone else will be able to replace you as the owner.
What to Do If the Domain Name Seems Acquirable
If the domain name seems acquirable, but it isn’t clear — you have two options. Either you can try to figure out who owns the domain name yourself and reach out to them. Or, you can hire a broker to do it for you.
If you hire a domain broker, there isn’t much risk. Typically, the only way you will have to pay a fee is if you buy the domain name. The downside is that you do have to pay a fee if you buy the domain name.
Sedo is a good place to start if you want to hire a domain broker.
In the case of doing it yourself, you can start with a WHOIS search to try to figure out who owns the domain name. Googling the domain name and seeing if it is tied to any social media profiles or other websites is also a good approach.
More times than not, I will fail at finding out who owns the domain name myself. It is common for people to use privacy features that hide their contact information. Most domain registrars offer this for free, so people tend to do it by default.
The benefit of a domain broker is that they have a huge network. They almost always know who owns what, and if they don’t, they have ways of figuring it out. Back to my GoodLife.com example. There is no way I ever would have figured out who owns that domain name if I didn’t have a broker to figure it out for me. Of course, I still do not know who owns that domain name, but at least I have a broker who does.
Another benefit of a broker is that you do not have to deal with the awkwardness of negotiating price. You have a middle man who can be the bad guy for you.
What to Do If the Domain Name Is Clearly for Sale
Domain names that might be acquirable, as outlined above, can be challenging. I much prefer to focus on names that are clearly for sale. These are easy.
If the name is already for sale, then the process is straightforward. The only thing you really need to think about is negotiating price.
Negotiating Price
There is often opportunity to negotiate price. Depending on who you are dealing with, there could be some room to get the price down.
I don’t recommend pushing too hard or overthinking this. That might just lead to wasting time and potentially losing out on the name. However, there is no harm in giving it a shot and doing some level of negotiating.
After The Acquisition
Once you acquire the domain name, the next step is to transfer to your domain registrar. Again, I recommend NameCheap. You can see the process for transferring your domain name here. It also helps to understand how domains work.
Regardless of how you acquire your domain name, the final step is to see it sitting inside of your NameCheap account. That is when it’s official!


Source Quick Sprout https://ift.tt/2QS0mv5
Looking Up the Ladder: A Different Perspective on Spending
A few years ago, I wrote an article entitled Looking Down the Ladder: A Different Perspective on Spending. The article covered the idea of a spending ladder, and I’m going to quote the explanation of a spending ladder here:
One idea that really stuck with me, though, was his idea that one’s preferred level of spending constitutes a rung on a ladder. The idea of a “spending ladder” is easier shown by example than by explaining it, so let’s hop right to an example.
One might look at the money one spends on housing through this type of ladder, where housing options are listed by monthly cost:
– A mansion
– An above average house in an expensive neighborhood
– An average house in an expensive neighborhood
– A below average house in an expensive neighborhood
– A very high end apartment
– An above average house in an average neighborhood
– An average house in an average neighborhood
– A high end apartment
– A below average house in an average neighborhood
– An above average house in an inexpensive neighborhood
– A below average apartment
– An average house in an inexpensive neighborhood
– A below average house in an inexpensive neighborhood
– A rented trailer
– A small hardbody camper
– A popup camper
– A tent
– A car
– Couchsurfing
– Sleeping under the stars
You can add many, many more rungs to this with options like condos and townhouses, and they might vary a little depending on the area you’re in and other factors, but this should make the idea clear.
When a person looks at a ladder like this and identifies which rung they’re on, several thoughts might run through their head.
A person might look at higher rungs on that list with envy. Some may wish they had a nicer or bigger house in a nicer area and thus, when they see this list, they feel envy because of all of those options out there that they don’t have.
A person might look at lower rungs on that list with relief and, perhaps, pride. A person might feel relieved that they have the housing that they have and that they don’t have to “settle” for less housing. […]
Instead, when I look at this kind of “ladder,” I look for the lowest rung that meets my needs. Then, I ask myself why I’m not at that rung. If I am at that rung, great. If not, why not?
So, let’s look back at that list of housing options. I’d probably describe our house as a slightly below average house in an average neighborhood. There are definitely neighborhoods with smaller and older homes in our area and neighborhoods with much bigger and nicer homes.
As I noted at the end of the quote, I tend to look at the lowest rung that meets my needs and, if I’m not at that rung, I ask myself why I’m not.
So, for me personally, I would want some sort of permanent shelter over my head. I’d probably consider a car or a tent to be the lowest rung that meets my needs. This isn’t as strange as it might seem – after all, a Major League Baseball pitcher lived in his own car for years by choice. It met his needs and, for me personally, it would meet my needs.
- Read more: The Daniel Norris Code for Success
Yet, I’m not living in a tent. There are many rungs between where I actually live and where I could theoretically do so.
Why is that gap there? If I would be okay living in a much simpler place, why do I have a pretty average house in an average neighborhood?
I find that answering that question seriously – and answering virtually the same question about any other spending ladder in my life where I’m currently sitting at a higher rung than I actually need to be – digs up some interesting and difficult things to think about in my life.
I strongly invite you to do this exercise on your own. Look at that housing ladder I shared earlier in this post. Figure out exactly where you are on it. Then, figure out which is the absolute minimum option that would meet your needs. Why are they not the same?
For myself, I can make a list of reasons that explains that gap. Some of them are sensible and justifiable, other ones really aren’t. Let’s dig through some of my reasons.
I have a wife and children and that requires more living space. I suppose it would be possible to live in a large tent, but living in a vehicle would be incredibly difficult.
I live in a climate with very cold winters and family concerns make moving unlikely. Sarah and I live in central Iowa. We are within driving distance of both of our extended families. Sarah has a steady job in this area that requires physical presence. So, for the time being, we’re staying here in central Iowa. The climate here basically requires a warm living environment, so that nudges me out of the tent range at least to a hardbody camper or trailer.
Owning a decent home is an investment, as that home is likely to appreciate over time. The options close to the bottom of the ladder are going to depreciate in value, while the home I live in is going to appreciate in value even after maintenance costs.
Those are sensible reasons. Now, for some less sensible ones.
I have a lot of stuff, way more than I actually need. Storing that stuff takes space. If I had less stuff – and the same is true for the other people in my family – then I wouldn’t have a reason to have as much space as I do. It’s not as if we have a giant home, either – it’s less than 2,000 square feet. I simply realize that I had a pretty fulfilling life back in the late ’90s when I was able to live out of my backpack and a small plastic tub for a couple of years.
I enjoy having people over to my house and have room for many people to congregate. It would be prohibitively difficult to entertain and host people in a smaller home. It sometimes stretches even our current home to host the type of events I want to host.
I take a sense of indescribable personal pride in being a homeowner. When I think about that feeling rationally, it doesn’t make a whole lot of sense, but that feeling is still there. I think that some of it comes from the sense of pride my parents had in being homeowners.
I feel safer in my home than I ever did in an apartment, so I associate “safety” with a decent sized home. The real reason for this is that we chose an area to move to that was extremely low in terms of crime rates, which we wanted so that our children could play and explore some personal freedom without a strong threat of crime. After living here for a while, it feels safe, a feeling I now value and one I associate with owning a home. Of course, there are apartments within a few blocks of us, so it’s not necessarily a rational feeling.
I want my children to have their own bedrooms. For most of the time growing up, I didn’t have my own room. I shared a room with one of my brothers throughout most of my childhood, and sometimes I slept on the living room couch. One thing I really always wanted when I was little was a room of my own, which I did finally have when I was just a few years from moving out. I’m fully aware that I’m transferring those feelings onto my kids.
Those aren’t particularly rational reasons for owning a larger home than we need. They don’t move me toward my goals in life, and any sort of careful reflection shows those thoughts to be nonsensical, yet I’m not really considering moving, either.
I can repeat this exact experiment with almost any “spending ladder” I might decide to look at. Let’s look at transportation, for example. A “spending ladder” for transportation might look something like this:
– A private jet
– A high end new car
– A mid range new car
– A high end late model used car
– An entry level new car
– A mid range late model used car
– A high end old car
– An entry level late model used car
– A mid range old car
– An entry level old car
– A mass transit pass
– A bicycle
– A pair of shoes
– Bare feet
Again, there are definitely more rungs that could be added in each of these gaps, but it gives you an idea of what we’re working with.
On this ladder, I’d probably put us currently either an entry level or a mid range late model used car. Given where we live, an entry level old car would be the absolute floor for us; to go lower than that would likely require our family to move to the nearest large city with a metro system (Des Moines, in other words).
So, why is there a gap between what we could own (an entry level old car) and what we do own (a mid range late model used car)? Again, there are a lot of reasons, some sensible and some not so sensible. Here are a few.
I want a certain level of reliability, as getting to my destination on time virtually every time is of very high importance to me. I generally don’t want to own a car from a low reliability brand if I can avoid it. Also, in general, the older a car is, the less reliable it is.
I want a certain level of safety, as keeping my family safe while riding is of very high importance to me. I generally want to feel very confident in the safety of the car I’m driving, so I tend to prefer cars with strong safety records. Again, in general, the older a car is, the less safe it is.
There are a handful of comfort features that I really, really like in a car, though most other features don’t matter to me. For example, I like a decent audio system that can be adjusted so that the volume is different on different sides of the car. I like seats that can be widely adjusted, more so than is often found in entry level cars (my wife and I have more than a foot in difference in height). Those aren’t strictly needs, but they’re important to me, and they tend to add to the cost of the car.
Significant rust on a car makes me very worried that it’s about to become unsafe or unreliable. This isn’t exactly a rational viewpoint, as visible rust usually has little to do with what’s going on under the hood or inside the frame, but it leads me to feeling that the car is unreliable and less safe.
Again, as with my reasons for the housing ladder, there are some concerns that are very reasonable and there are some that are not. If I actually dig into why I would choose something higher up the ladder than what I actually need and I start listing out the reasons, I often start coming up with things that are more about personal feelings than objective reasoning.
Digging into those feeling-oriented reasons for doing something is really worthwhile, as it can help a person to let go of some of the less objective reasons for spending money, not just on the matter at hand, but on other things, too. This thought process alone has opened me up to a desire to really learn more about the effects of rust, to consider what features I really need in a car, to take a more sober look at my possessions, to consider how much “homeowner pride” is really worth to me, and to consider how much being able to host social gatherings is really worth to me. Those are great things to think about because they can help me figure out what’s sensible in terms of my spending and what isn’t, and doing this kind of thinking regarding many of my “spending ladders” is really useful in terms of exposing my less sensible spending motivations.
Furthermore, I’ve come to realize through looking at things through the lens of a “ladder” that it is much easier for me, and for most people (I believe), to look up the ladder than down it. Whenever we go down to a lower rung of a particular spending ladder, it usually feels like a loss, even if the reasons for doing so are completely rational and sensible. For example, if I were to choose to move into a smaller home right now, it would feel like I’m somehow losing something, even though I might have every reason to do so in terms of my broader life ambitions.
I think, as a frugal person, I’ve been much more successful at quashing my internal desire to look up the ladder and consider upgrading than I’ve been at nudging myself to look down the ladder and consider downgrading. I’ve been able to recognize my own desire to look up the ladder and I’ve been able to convince myself that most upgrades aren’t particularly useful in terms of my overall life goals and that I need to make a very strong case when upgrading.
So, what grand lessons can I really learn from all of this?
When I’m making a purchase I’m unsure about, I should absolutely aim for the lowest end possible. I should look for that item used. I should try to borrow that item. I should look for the store brand version. If I have no idea what I’m buying, I should trust the “bang for the buck” recommendations from trusted sources like Consumer Reports rather than their top recommendation.
I should keep on the same path when it comes to being able to resist looking up the ladder. I already have a very strong resistance to moving up the spending ladder on virtually everything, and that has guided me very well when it comes to saving money and keeping on track with my financial goals. I need to stick with that, because it works.
If I find myself almost compulsively drawn to a higher rung on the ladder than what makes sense at first glance, I need to back off and figure out why I’m making that choice. In both of the examples above, I explained why I felt that a certain rung was my “bottom rung,” yet when it came around to the actual spending decision, I aimed for a higher rung. Why did I do that? Digging into that question is a really worthwhile endeavor if you truly want to cut back on your spending.
I really encourage you to give this idea some thought in your own life. What’s the “bottom rung” for you on those ladders above, in terms of the minimum you actually need? What rung are you actually on? Then, most important of all, why does that gap exist? Figuring that out is really worthwhile.
Good luck.
The post Looking Up the Ladder: A Different Perspective on Spending appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2C9G0oR
الأربعاء، 12 ديسمبر 2018
11 Tips To Avoid A New Year's Credit Hangover: Start 2019 Regret-Free
Source CBNNews.com https://ift.tt/2SDVsPq
9 Easy Ways To Save At Christmas: Tips for Keeping Christmas Affordable Yet Beautiful
Source CBNNews.com https://ift.tt/2QqSscG
More Americans buy groceries at dollar stores than Whole Foods, report says
Source Business - poconorecord.com https://ift.tt/2PAjHfJ
PV guard's quick thinking saves life of hall monitor
Source Business - poconorecord.com https://ift.tt/2zSBxFt
Pocono airport receives grant
Source Business - poconorecord.com https://ift.tt/2PAjBVp
My money lessons: Coin enthusiast turns to cryptocurrency collecting

Jon Bannister (pictured below) was challenged by friends to collect a complete set of 54 rare 50p coins. But when coins became harder to collect, he switched to cryptocurrency. Here, he shares his experiences as a collector
When I was originally challenged to collect a whole set of 54 rare 50p coins, I managed to complete the challenge within two months.
I have now collected four whole sets of every coin including rare coins, such as the Kew Gardens 50p, the London 2012 Olympic 50p series and the 2005 50p commemorating the 250th anniversary of Samuel Johnson’s Dictionary.
At the time I completed the first collection, the value for all 54 coins was nearly double its face value. Recently, I have seen some Samuel Johnson’s Dictionary coins on eBay for up to £3,000 and I’ve actually got 50 of them in my collection.
But now that I have four complete sets of the 54 rare 50p pieces, I’ve stopped collecting. Each set is worth between £500 and £600, and I think I’ve withdrawn around 18,000 to 20,000 50p coins while collecting.
I’ve found getting valuable 50p coins by withdrawing from the bank to be harder and harder. When I first started, I was probably getting around 200 or so good coins, but more recently I would withdraw £1,000, and would only get around 15 to 20 valuable coins.

My feeling is that over time more people have started to collect, so it has become more difficult to find rare coins. I ended up wasting three to four hours, only to find around £10 to £15 of rare coins. It wasn’t worth the hours I spent.
I’ve given sets of rare 50p coins to my wife, son and daughter, and kept one for myself, so we have a collection each to hold on to and decide if we want to sell one day.
Now I’ve moved on to digital currency, as I think it is more financially rewarding. For instance, the Kew Gardens 50p is valued at between £180 and £200 and I have five of them, but the value of a cryptocurrency coin can go much higher. Bitcoin peaked at $19,000 (£14,850) in January 2018.
I had a few friends who were buying and selling digital currency. I’d heard of Bitcoin a while back and ended up dipping my toe in the water.
As a result, I’m now working for a number of different initial coin offerings (ICOs). They’re trying to raise funds to launch their own cryptocurrencies, with some quite large and high-profile companies raising up to $19 million (£14,853 million) each.
I’m also thinking about starting a business offering hints and tips on buying cryptocurrency.
I was quite sceptical at first. I have an IT degree and I’ve done a lot of computer development. I understand computers but it was hard for me to get my head around crypto – that you can’t physically hold it in your hand or put it in a bank.
I use a Trezor hardware wallet [a special type of bitcoin wallet that stores the user’s private keys in a secure device] to store my crypto coins. Right now, I have around five million coins in my portfolio.
I’m aware that I need to do my own research on each company and each coin before investing. I need to see the team behind it too. I want to know if the coin solves a problem and I try to find innovative companies. For example, I’m working with a company called AirWire. It is developing a way to send cryptocurrencies via email, text message or social media.

I try to keep my portfolio at around 40 to 50 different tokens, so I have a diverse spread.
If some go off really well, then fantastic. But you have to be careful about what you are investing in. Find out more about how it works. Some currencies I bought for less than 1 cent are now worth around $5.
Those who got into Bitcoin at the right time could have bought it for around 3 cents. It was valued at $19,000 at one point. I kick myself that I didn’t get involved four or five years ago.
Unfortunately, though, I’ve been scammed a number of times. I’ve lost some money on certain companies as well. That’s something you have to be alert to.
You need to know what you’re buying and selling, and the apps you use, or you could end up losing a lot of money.
It’s also easy to lose your money if you lose the password to your digital currency wallet or your hardware wallet. Your currency could be gone for ever. That’s a big risk.
The hacking of an exchange and theft of your cryptocurrency is a risk too. It’s not regulated, and there’s no financial protection.
I think the age of physical coins is coming to an end and digital currency will be the future of money. That’s why I’m collecting cryptocurrency now, in case some become big winners in the future, like some of my 50p coins.
Do you have a lesson you’ve learnt about money you’d like to share? Please email editor@moneywise.co.uk
Section
Free Tag
Workflow
Source Moneywise https://ift.tt/2UDk64L
12 Tips for Taking Better Marketing Photos for Your Social Media Campaigns
Every business needs to be active on social media to be relevant in today’s digital world.
So if your company is on social media, it’s a safe bet that you’re uploading photos to your profile on a regular basis. Pictures and other visual elements will improve your marketing strategy.
But it can be challenging to find the right pictures to post.
Let’s say you want to upload at least one new picture to a social platform each day. That’s 365 images per year.
Lots of businesses don’t have a library of that many original photos. So they just take a random picture and post it to their profiles last minute without putting too much thought or effort into it.
This is going to be a major problem for your business if you’re using a similar strategy.
Everything you share with your followers on social media must have a purpose. In order to get the best results from your campaigns, everything needs to be high quality.
Fortunately for you, technology has advanced to the point where you have a professional quality camera in your hand or pocket in nearly all waking hours.
You don’t need fancy equipment to take great marketing photos. All you need are some basic photography skills and inspiration for your subject matters.
Every day, 300 million pictures are uploaded to Facebook. Instagram has an average of 95 million photos uploaded daily.
If the photos you add to social media don’t look professional, it’s going to hurt your brand image. That’s why I identified these 12 tips to improve your social media marketing photos.
1. Create balance with grid lines
The rule of thirds is one of the most basic photography skills that you should get familiar with.
This technique will improve the composition of your photos and create balance, which is more visually appealing to anyone who sees the picture.
Your smartphone allows you to enable grid lines when you’re taking a photo.
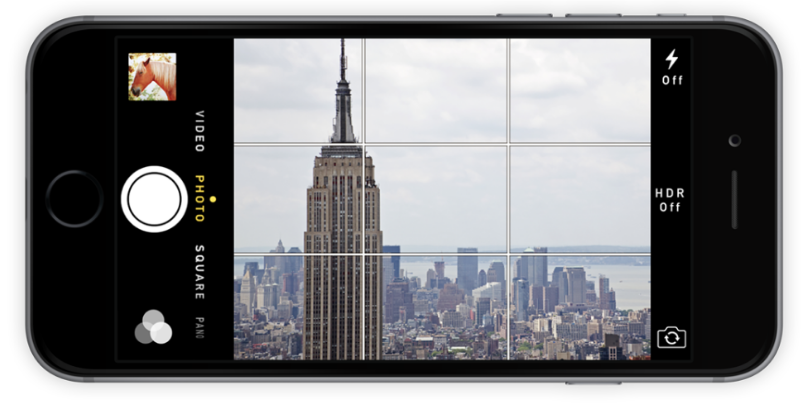
This feature makes it easier for you to follow the rule of thirds.
The grid is very simple. It’s just two vertical lines and two horizontal lines that are all spaced apart equally.
You should position your subject matter and anything important in your photo where those lines intersect.
An amateur photographer just centers everything on the screen. But that’s not as appealing.
By using the rule of thirds, the image has more room to breathe.
Just look at all of the open space in the skyline above. This puts more emphasis on your subject matter.
Plus, people are used to this tactic being applied in professional photography, whether they realize it or not. So when someone sees a photo without the rule of thirds applied, it will automatically not seem as attractive to them.
2. Find symmetry
Symmetry is another visual element that we are just naturally drawn to.
So if you have the opportunity to capture symmetry in an image, you should definitely do so.
Here’s a great example of a photograph with symmetry.
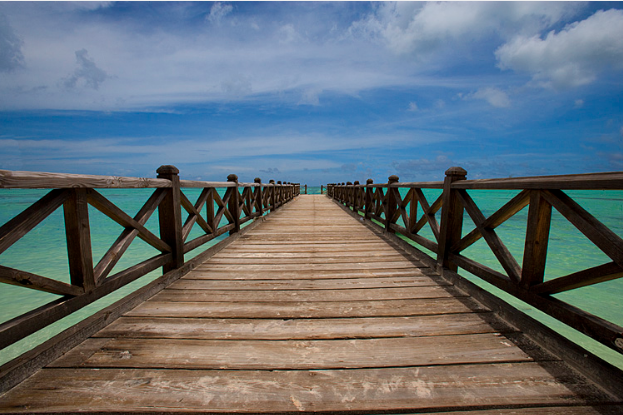
It’s simple, but it works.
Now, take a moment and imagine what this photo would look like if it weren’t taken from this angle.
If the camera was positioned slightly to the left or right, the symmetry would be lost.
Sure, it may still seem like a nice picture of a walkway going out into a clear ocean on a beautiful day. But capturing the symmetry elevates the image and brings it to a more professional level.
Your pictures need to stand out to draw attention from your followers.
If it looks like an amateur is taking all the photos, it will reflect poorly on your brand. We both know you don’t want that to happen.
3. Crop instead of zooming
Another rookie mistake that I see people make all of the time is using the zoom feature.
Manually zooming in on a subject is a big no, unless you’re using a professional camera to take pictures.
But like I said before, that type of equipment is unnecessary. Your smartphone will capture pictures that are good enough to post.
However, once you start zooming, it damages the quality of the photo.
Instead of zooming, just get closer to your subject. If that’s not possible, don’t worry about it. Take the picture from where you are and use the rule of thirds to improve the composition.
After the photo is taken, you can just crop the image to your liking.
Here’s an example of how to do this in Adobe Photoshop.
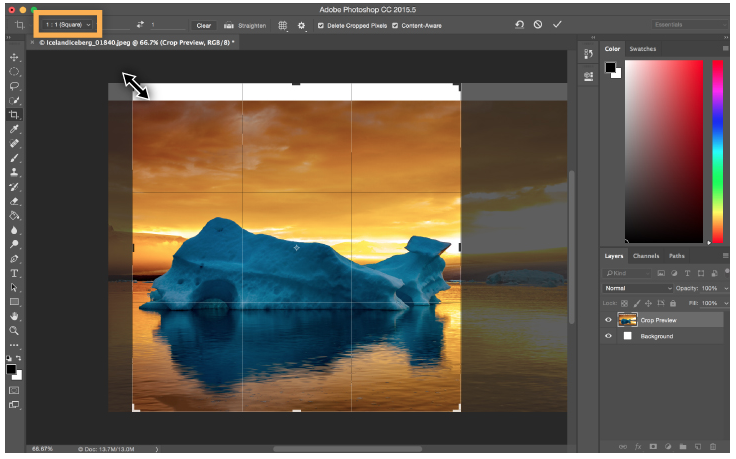
For the most part, you shouldn’t need to do this on your computer. You can crop photos directly from your smartphone.
Notice how even though this picture is being cropped, the rule of thirds is still being applied.
The reflection in the water is also a nice touch, but we’ll talk more about that shortly.
4. Embrace natural frames
Framing your image is another basic photography skill. No, I’m not referring to developing your photo and putting it into a wooden box.
Sometimes subject matters are perfectly positioned to be captured within a natural frame surrounding it.
Any time you have the chance to use a natural frame, you should take advantage of it.
Here’s a simple photo of an airplane wing that has a natural frame.
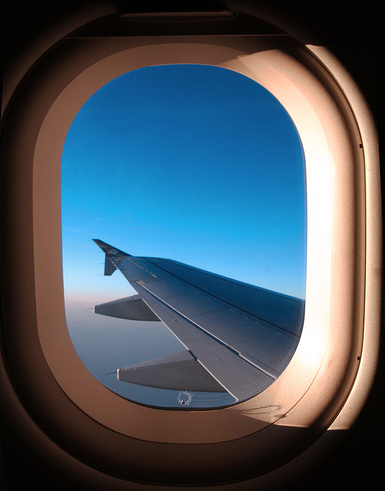
This image is perfect for so many reasons.
First, if you try and get too close to the window to take the picture, you’ll end up getting a glare. Second, the wing by itself is just too boring.
By adding the window to the picture, it elevates the quality of the picture to the next level. You get the see the lighting changes and the shadows as the natural light from the sun comes into the plane.
Here’s the thing, if you’re not happy with the natural frame you can always just edit it out by cropping the image, as we previously discussed.
When you’re taking a photo, keep an eye out for natural frames such as trees, fences, bridges, archways, or anything else that creates a similar framing effect.
5. Look for reflections
I briefly mentioned this before when we were talking about cropping. Taking photos of reflections can add a really unique perspective to your photo.
Check out this example from Todo Bien Tours.
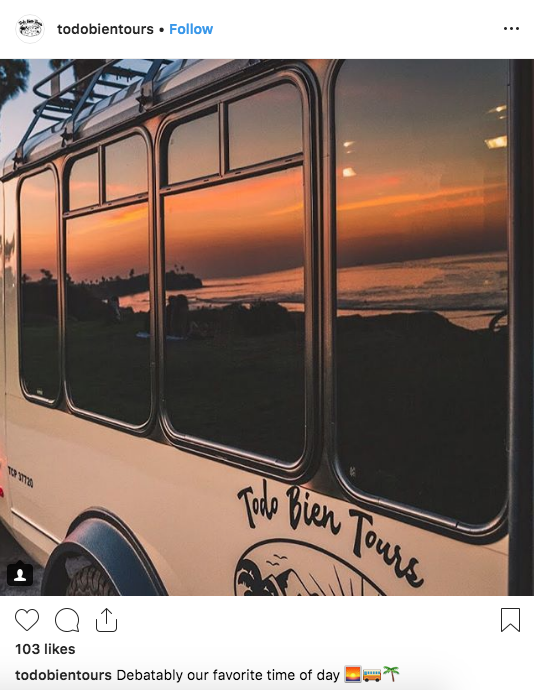
Todo Bien gives private coastal bus tours in southern California.
So obviously they want to show their social media followers what their bus looks like. But rather than just showing a boring picture of the bus, they use a reflection to capture the water and coastline during a sunset.
It’s a creative way to show off your photography skills.
Taking a picture of just the bus or just the sunset would be average and pretty basic. But by capturing both in the window reflection, it elevates this campaign to new heights.
6. Shoot repeating patterns
Just like symmetry, patterns are another great way to capture the attention of your followers.
Sometimes finding the right pattern is all about shooting from the right angle and perspective. Just look at this photo of bike wheels to show you what I’m talking about.
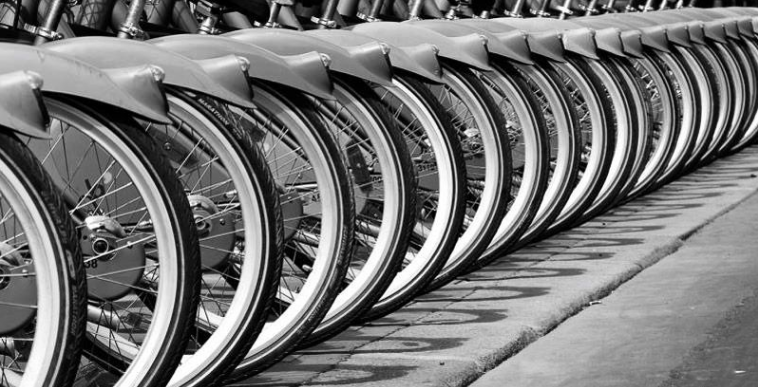
This pattern isn’t necessarily present from every angle.
If you step back and photograph these bikes from above, or head on, the pattern wouldn’t be the same. It would just look like a row of bikes.
Yes, the subject matter may still be relevant enough and usable for your marketing campaign, but it can be improved by using this strategy.
7. Get a tripod and mount for your mobile device
Earlier I briefly mentioned how you don’t need a professional camera or expensive equipment to take high quality photos for your social media campaigns.
But with that said, it can’t hurt to invest in something small, like a tripod and mount for your smartphone.
The tripod will allow you to go hands-free when taking a picture. Plus, it helps ensure that the image is level.
You can also use this type of equipment to extend your range and make it a little bit more comfortable to hold your phone securely.
Joby has a bunch of great products for this purpose.
You can check out their website to browse for what you need.
Otherwise, there are thousands of other similar products available online from other retailers as well.
Most of these are pretty inexpensive. You can find a quality stand and mount for under $50. It’s worth having, even if you don’t use all of the time.
8. Create a new perspective
You don’t want your social media marketing photos to look like everything else out there.
It’s important for your brand to come up with new perspectives to separate yourself from the crowd.
I really like this example from Tropicfeel on their Instagram page.
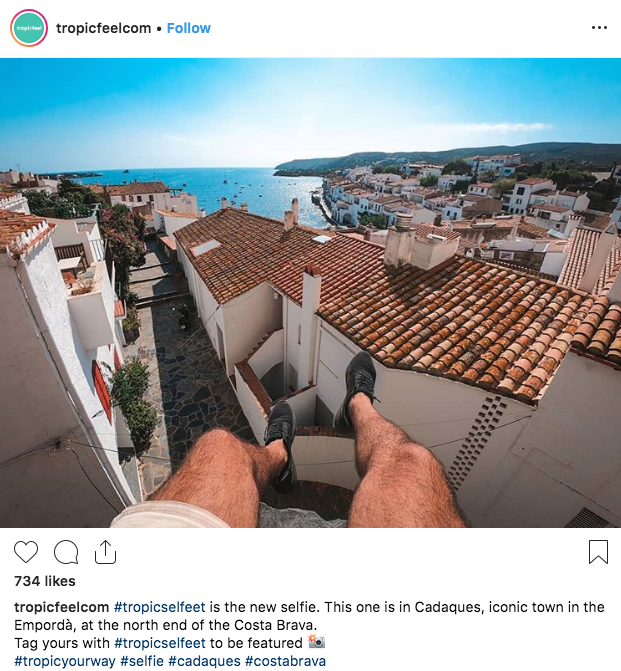
The picture itself is beautiful. The houses, ocean, and coastline grabs the attention of an audience right away.
But something about this photo is a little bit different than you normally expect.
It’s not typical for people to put their legs and feet in this type of shot. Usually, you’d expect this to be a selfie or just a landscape shot.
But Tropicfeel uses this unique perspective to showcase their product, which is the shoes in the photo.
Look at the caption.
They created a new hashtag of #tropicselfeet to encourage other people to take this type of photo as well. This is a great way to write instagram captions that drive engagement.
So find a perspective that’s unique to your brand.
For example, let’s say your company sells skateboards. Rather than just taking a picture of a guy on a skateboard, you could mount a camera to the nose of the board.
9. Take candids
You don’t always want to just take pictures of your products.
People are a great subject matter for your social media campaigns. In fact, photos with faces get 38% more likes and 32% more comments than photos without them.
But your subjects don’t always need to be posing.
Candid shots add a human element to your brand. They show people in action, as opposed to just putting on a show for the camera.
Take a look at these photos that were uploaded to the Thule Facebook page.
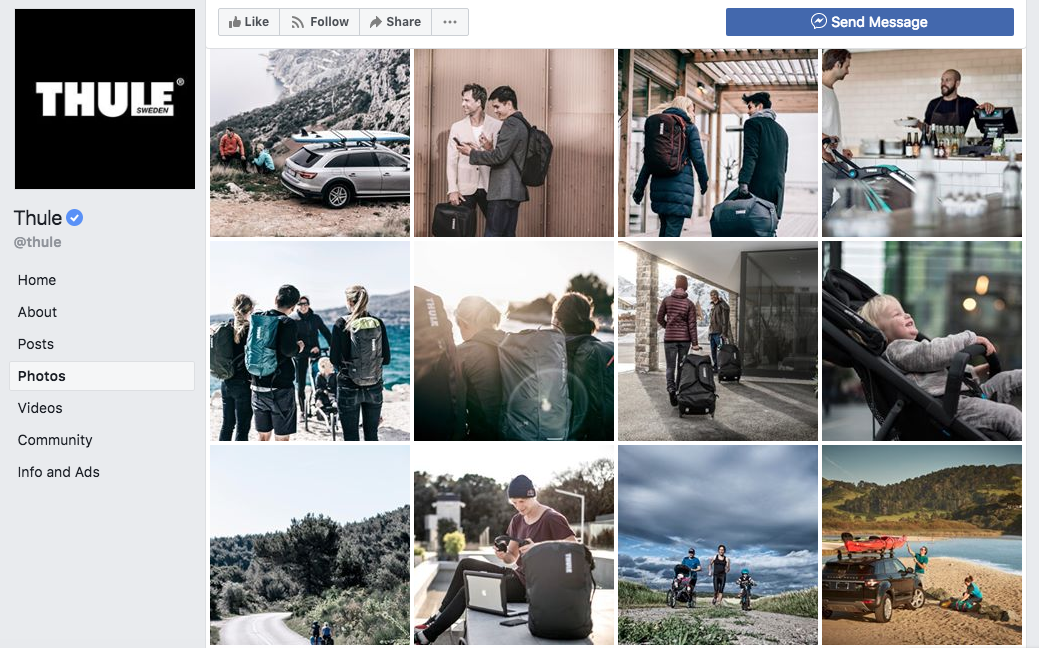
None of the people in these pictures are posing.
All of the shots are candid.
The reason why this works is because it shows an audience how people behave naturally when they are doing something.
This is an opportunity for you to showcase how your products and services can be used on social media.
I also like the idea of taking candid photos of your employees. By showing your staff in photos, it creates a more authentic interaction with your audience. Your followers will realize that there are real people behind the scenes of your brand.
10. Get abstract
Think outside of the box.
You need to realize how many pictures are flooding the timelines of your followers on a daily basis. If your marketing photos don’t jump off the page at them, they’ll just simply keep on scrolling.
Abstract images are a great way to capture attention, like this one from the Allbirds Instagram page.
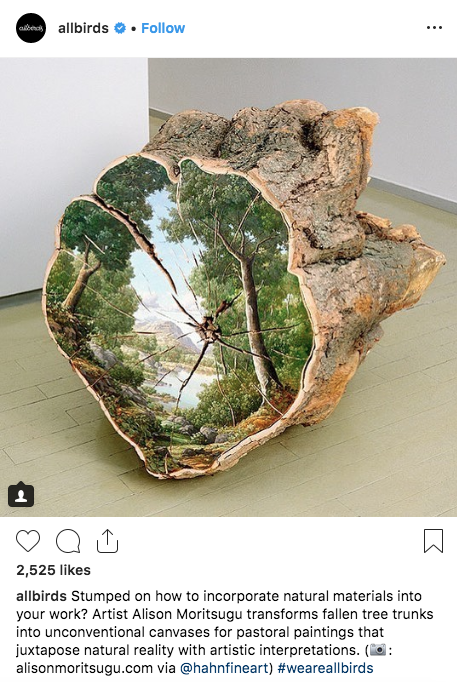
Allbirds has a line of shoes called tree runners. So lots of their posts encompass nature and different photos of trees.
This one is definitely one of the most unique photos that you’ll see on their profile.
It’s art painted onto a fallen tree trunk. The image on this unconventional canvas is a nature scene, which also includes trees.
At first glance, a social media user might not even realize what they’re looking at.
But it’s definitely enough to stop them in their tracks for further examination.
11. Be funny
Stop taking yourself so seriously.
OK, there are certain businesses that need to more serious than others. If your company specializes in things financial investments or funerals, you probably shouldn’t be cracking jokes on social media.
But those types of brands are just a small percent of the population.
If your company sells products or services to a target audience that can appreciate some humor, don’t be afraid to take a funny photo for your social media campaigns.
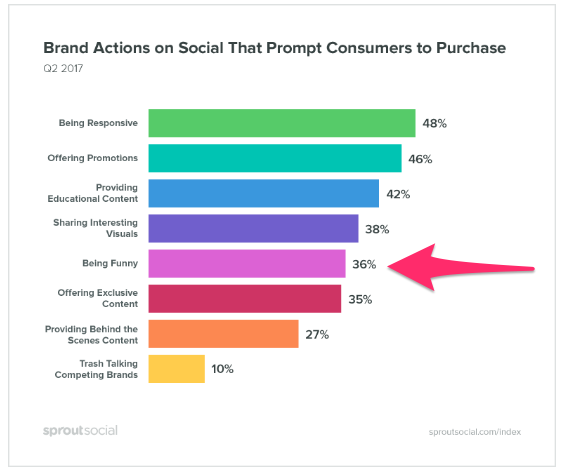
36% of consumers are prompted to make a purchase after seeing a funny post from a brand on social media.
So taking a humorous photo can do much more for you than just drive engagement. This strategy can directly lead to sales.
Just make sure you stay away from controversial subjects.
I definitely don’t recommend making jokes about subjects like politics or religion. Photos like that can really damage your brand.
So keep it light, but stay professional.
12. Don’t be conventional
How can you make your marketing photos jump off the page to social media users?
You want your posts to make people say, “Wow!”
Leave them in awe. Here’s an example from the Vuori Instagram page.
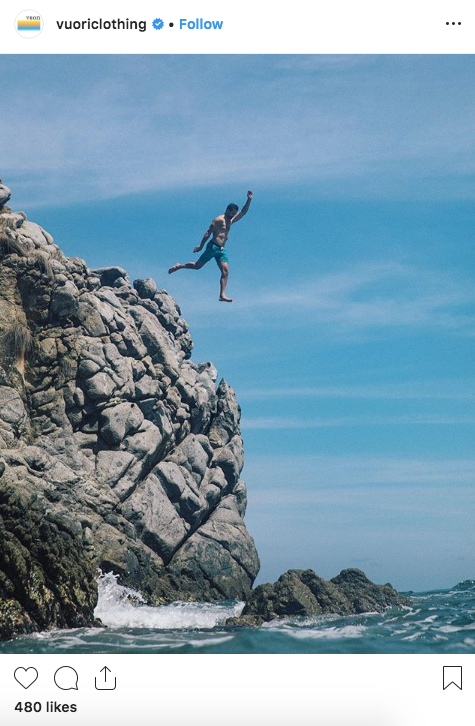
This post is advertising their men’s swimwear.
A conventional idea would be just to photograph a picture of the swim trunks. That’s boring.
Another idea could be showing a model wearing the bathing suit, or even swimming in it. But again, that’s boring as well.
It’s conventional, and audiences expect those types of posts from brands.
You know what’s not conventional? A guy jumping off a cliff into the ocean wearing those shorts.
This photo is awesome. It’s definitely the type of post that will grab the attention of users on social media.
Conclusion
If you want to run successful social media campaigns, you need to focus more attention on the quality of your marketing photos.
Don’t worry, you don’t need to buy expensive equipment or hire someone to do this for you. It’s easy to take and edit photos without hiring a professional.
All you need is some basic photography skills to get you started in the right direction.
After that, it’s just all about deciding what types of photos will speak to your target audience on these platforms.
Use this guide as a reference and inspiration for your future marketing photos.
What types of photos does your brand share with people on social media?

Source Quick Sprout https://ift.tt/2BdrVFg
The Difference Between What You Should Be Doing and What You Are Doing
Several times during the course of writing an article, I feel a bit stuck for what I should write next. How exactly do I say what’s on my mind? I know the general topic of a paragraph or a section of an article, but actually converting it into words for a first draft eludes me in that moment.
The solution, of course, is to do something else.
The problem, of course, is that I often choose something less than useful with that “do something else” option.
What I should be doing is something directly useful to my life goals. I should spend that time doing a household chore. I should spend that time meditating. I should spend that time reading a section of a challenging book. I should spend that time making a homemade batch of some food item. I should spend that time exercising or going on a walk. You get the idea.
What I often do is play a game or chat with one of the guys I know who also work from home. I’m in a group of several people who work from home and hang out in a Slack chatroom and we often agree to play some quick multiplayer computer game together for fifteen minutes.
It’s not the worst thing I could be doing. I am at least building camaraderie with my local professional peers. However, it’s far from the best thing I could be doing.
That gap between the best thing I could be doing and what I’m actually doing seems like a little deal in the moment, but it adds up over time. Let’s say that twice during a given day, I choose to play a game for fifteen minutes instead of doing household chores. That means in the evening I have thirty minutes of undone chores to do… but this evening my son wants me to help him with his homework and there are a bunch of other things going on. Eventually those undone chores end up eating into something else I really value, something I genuinely regret missing out on, and it’s because I spent that time playing Fortnite or something instead of doing that household task.
Often, it’s because I’ve accumulated lots of those little decisions, where I’ve made a relatively poor choice in how to use my time here and then another poor choice there and then it adds up to a ton of things left undone and I feel overwhelmed.
It’s that difference between what I should be doing and what I actually am doing. It really adds up.
The same exact thing is true with money. We all sometimes use our money in ways that are less than optimal. We spend it on something unnecessary when we could put it to better use buying something else. We buy something frivolous when we could use the money to invest in our future.
Most of the time, those expenses are small. We buy a bottle of Gatorade at the convenience store. We buy a pack of gum in the checkout aisle. We pick up a latte at Starbucks. We keep paying the cable bill even though we don’t watch it much these days. Those little expenses are easily forgotten, too.
Sure, sometimes those expenses are big ones, too. We buy a bigger house than we probably should. We go on a really expensive trip. We decide to go for the car with the upgrades rather than the base model.
All of those things add up, little by little, until one day you find yourself in what feels like an insurmountable financial hole. Is it even possible to save much for retirement at this point? Can you even help your kids much with college? is it all hopeless? Will you be working until you fall down on the job?
With money, with time, with everything, it’s the difference between what you actually do and what you should be doing, added up over thousands upon thousands of choices, that ends up putting us in a place that we don’t like, wondering where it all went wrong, completely overwhelmed by the challenge before us.
The solution to this problem isn’t to become perfect. The solution, rather, is to be conscious of how those little choices add up and tweak things so that just a little more often, we make the better choice. A few times a day, we choose to do what we should be doing rather than our impulsive desire in the moment.
Maybe once or twice a week, I’ll go take care of a task instead of chatting with the other stay at home workers I know. A little decision that’s much closer to what I should be doing.
Maybe today, instead of going inside the gas station to pay and talking myself into a Gatorade, I’ll just pay at the pump and get home and find something in the fridge there. A little decision that’s much closer to what I should be doing.
Maybe instead of buying a new board game, I’ll find one on the shelves that I’ve not yet played. A little decision that’s much closer to what I should be doing.
Over time, those little decisions add up to something bigger, something that amounts to genuine life change.
The challenge, of course, is to be mindful of all of those little choices throughout the day. Saving the difference between what you should be doing and what you’re tempted to do comes down to making a better choice on the many decisions we’re faced with each day, and doing that consistently comes down to habit.
For me, the most successful way I know of to nudge that kind of everyday behavior in a better direction is to just remind myself regularly. Just set up a reminder on your smartphone to remind you once a day or so to try to do what you should be doing instead of what you are doing. Let that thought burrow deep in your head and act on it every so often.
Perfection isn’t what you’re aiming for. Rather, you’re aiming to just reduce that overall gap between your perfect behavior and what you’re actually doing by just a little bit, by making a few of your choices a little better without making other ones worse.
Do that consistently over a long period and it begins to feel natural.
Do that consistently over a long period and the trajectory of things in your life begin to change.
Good luck.
The post The Difference Between What You Should Be Doing and What You Are Doing appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2BdxF1H
Fund briefing: are the biggest funds the best to invest in?

We look at the biggest funds across different sectors, why they’re so popular, whether it’s justified and if they’re better investments than smaller rivals
They are the giants of the fund management industry, with billions of pounds under management and an enthusiastic following of investors.
Their status as major shareholders in companies also means they often wield enormous power inside boardrooms.
They can influence business decisions, ratify or block managerial appointments, and campaign for cultural changes within organisations.
But is that enough to make the largest UK funds attractive? Should you be putting your faith and money into these portfolios or opting for smaller alternatives?
Unfortunately, there is no simple answer. Funds grow for a variety of reasons – and these will determine whether or not they should warrant your attention.
In many cases, the size – and popularity – of a fund will be driven by past performance figures, according to Patrick Connolly, a chartered financial planner with Chase de Vere.
“Many investors will jump into top-performing funds, hoping and expecting that the strong performances will be maintained,” he explains.
However, there are no guarantees – which is why there are constant warnings that past performance is never a reliable indicator of future success.
A fund’s rapid growth may also be due to a strong, well-resourced sales and marketing operation behind it that is constantly reaching out to investors.
Past performance often drives the size and popularity of a fund
Such investment houses will plough millions of pounds into high-profile advertising campaigns on social media, as well as paying for billboards at railway stations.
Funds can also benefit from being in fashionable asset classes, despite the fact their soaring popularity can easily nosedive should investors get seduced by the next trend.
Having a well-respected manager making the investment decisions can also attract investor interest, as can having particularly low charges.
The situation is further complicated by the fact these large funds don’t all concentrate on the same areas. In fact, they may buy into totally different asset classes.
Some of these portfolios will be focused on equities, some on fixed income. Then there are multi-asset products that embrace equities, bonds and alternative investments.
Quick guide: Is this approach right for me?
Consider investing in larger funds if…
- You want to be in funds that are popular with other investors.
- You want to be with a manager who has power in boardrooms.
- You like the fund’s aims and objectives and they align with yours.
They can also differ in the way they manage money.
For example, active funds are run by managers who enjoy a greater degree of flexibility when it comes to buying and selling stocks.
Passive products, meanwhile, have far less scope as their role is to replicate and track particular indices.
An examination of the largest funds in the UK illustrates the point, with those focused on generating income sitting alongside multi-asset portfolios pursuing absolute returns.
This list also includes a number of UK stock-market trackers and even a portfolio that invests in large and medium-sized equities across the Asia Pacific region.
Passive funds can usually compete in terms of charges because they replicate particular indices, rather than being actively managed, so there are less costs involved.
In many cases, these can track a popular index, such as the FTSE 100, which gives people broad access to the largest UK companies, points out Mr Connolly.
“As the popularity of passive investments has grown, with more investors deciding it isn’t good value to pay the extra costs of active management, some passive funds have also grown large,” he explains.
Distribution channels can also play a vital role in influencing the size of an investment portfolio – especially in the current environment.
“If a fund is too big, it makes it hard to invest in small caps”
“All funds with aspirations to be larger need to be available on the main investment platforms,” adds Mr Connolly.
Many of them can boost inflows substantially by appearing on the ‘best buy lists’ of industry players, such as Hargreaves Lansdown.
Of course, there is always the possibility that a well-performing fund may continue to deliver, points out Darius McDermott, managing director of Chelsea Financial Services.
“However, funds can get too big, which means the manager has to change or tweak their strategy to deal with the extra assets – and then it doesn’t perform so well,” he says.
He cites the example of a multi-cap manager investing in the UK.
“If they get to a certain size, it makes it difficult to invest in small caps at that point as you would own too much of individual companies,” he explains.
Of course, the same golden rules apply with any investment.
Whether or not a fund is suitable will also depend on your goals, the length of time you’re willing to lock away money, and your attitude to risk.
Therefore, the best advice is to monitor a fund to ensure it still meets your needs and there haven’t been significant changes to its size, objectives or management.
“Keep an eye on performance and that the fund is still investing in the same style and strategy as it was when it was growing,” adds Mr McDermott.
Fund to watch: M&G Optimal Income

This hugely popular fund, which aims to deliver income and capital growth, has more than £23 billion of assets under management.
Richard Woolnough has been at the helm of the portfolio since its launch back in December 2006 and is one of the most respected names in the industry.
A graduate of the London School of Economics, he boasts more than 20 years of experience in fixed-interest investing and has been with M&G since 2004.
The Optimal Income fund invests in a broad range of fixed income securities, governed by where he sees the greatest opportunities.
It may also hold up to 20% of the portfolio in company shares when he believes they offer better value than bonds.
Exposure to these assets is gained through physical holdings and the use of derivatives, with an in-house team of credit analysts on hand to help select individual bond issues.
Currently, the fund is 48.6% invested in investment-grade corporate bonds, with 26.3% in government bonds and 12.3% in high-yield corporate bonds.
As far as credit ratings are concerned, it has 38.1% in those rated BBB, with 23.7% in AA, 12% in AAA and 10.8% in BB.
Meanwhile, the largest issuers in the fund – excluding government bonds – are Verizon Communications (4%), Microsoft (3.1%), AT&T (2.8%) and Bank of America (2.1%).
Value of £100 invested in the fund over five years
| Year | *Year to date | 2017 | 2016 | 2015 | 2014 | 2013 |
|---|---|---|---|---|---|---|
| Fund percentage movement in year (%) | -1.52 | 5.77 | 8.14 | -0.86 | 5.16 | 7.67 |
| Value of £100** (£) | 126.46 | 128.4 | 121.4 | 112.26 | 113.23 | 107.67 |
* To 22 October 2018 **The £100 was invested on January 1, 2013
| Manager | Richard Woolnough |
| Launch date | 8 December 2006 |
| Total fund size | £23.2 billion |
| Minimum investment | £500 |
| Initial charge | 0% |
| Ongoing charge | 1.41% (including AMC) |
| Annual management charge | 1.25% |
| Performance fee | None |
| Contact details for retail investors | Mandg.co.uk |
Rob Griffin writes for the Independent, Sunday Telegraph and Daily Express
Section
Free Tag
Workflow
Source Moneywise https://ift.tt/2Lb5hSH