Thousands of courses for $10 728x90

الثلاثاء، 25 يونيو 2019

Third Federal Mortgage Rates Review: Today’s Best Analysis

Third Federal was founded in 1938 in Cleveland, OH as a mutual association. It offers loan products in 21 states and the District of Columbia through 21 full-service branches in Northeast Ohio, eight lending offices in Central and Southern Ohio, and 17 branches throughout the state of Florida. Third Federal offers a selection of home loan products, providing both conforming and non-conforming loans to mortgage customers regardless of their financial situation.

Third Federal Mortgage Facts

  • Services 21 states and the District of Columbia
  • Offers a variety of mortgage deals and affordable rates for vacation home buyers, first-time buyers, and borrowers whose current home is still on the market
  • May require borrowers to take out escrow if they put less than 30 percent down on the home
  • Once borrowers are approved, Third Federal charges one flat rate that is not based on their credit score
  • Offers Low-Cost Smart Rate loans with closing costs of as little as $295

Overall

third federal mortgage rates reviewInitially servicing the state of Ohio alone, Third Federal has since expanded its business to offer loan products and 21 states. The financial institution extends flexible mortgage options at low costs to empower borrowers to buy their dream homes.

The bank’s offer includes affordable fixed and adjustable-rate mortgages as well as jumbo loans, bridge loans, vacation home financing, and other flexible options for first-time buyers, seasoned loan borrowers, and everyone in between.

Current Mortgage Rates

Third Federal Loan Specifics

This bank offers a variety of home mortgage products, including:

Fixed-Rate Mortgages

With fixed-rate loans, interest rates stay the same throughout the life of the loan. Third Federal offers fixed-rate mortgages with loan terms of 30, 15, and 10 years. Homebuyers who plan on staying in their home for several years can benefit from fixed-rate mortgages.

Smart Rate Adjustable Rate Mortgage

Third Federal offers borrowers lower interest rates than they might receive with a fixed-rate loan. Borrowers who choose this option can save about $12,000 over the first five years. The bank’s Rate Relock allows borrowers to “relock” their loan payments to the current 3/1 or 5/1 rates throughout the loan’s lifetime. These types of loan products are recommended for homeowners who may sell or refinance their homes in the next few years.

Third Federal $295 Low-Cost Mortgages

Individuals who don’t want to deal with steep closing costs can opt for this type of mortgage and pay only $295 in closing costs—Third Federal will cover the rest.

10-Year Mortgages

Homebuyers who want to pay their mortgage off as quickly as possible could benefit from 10-year home loans. These types of mortgages are a good choice for buyers with excellent savings on interest paid, who can afford to keep up with higher payments over a 10-year period. This option may also be especially advantageous for those wanting to benefit from historically low-interest rates, which can offset the cost of larger monthly repayment amounts over a shorter loan period.

$750 First-Time Homebuyer Credit

Homebuyers who are investing in their first home can take advantage of this option. Third Federal puts a $750 credit toward the loan’s closing costs. Additionally, the bank allows first-time buyers to make down payments as low as 5 percent.

Jumbo Loans

Unlike other banks, Third Federal does not offer higher rates for jumbo mortgages. In fact, the company offers a rate reduction for jumbo loans over $453,100. These jumbo mortgages are available on all 3/1 and 5/1 Smart Rate loans and can benefit buyers who are investing in high-value properties that require larger loan amounts than Freddie Mac and Sallie Mae typically allow.

Bridge Loans

These types of loans allow borrowers to buy a new home while their house is still on the market. They can use the equity in their current home for the new home’s down payment and suspend payments toward the new mortgage until the first home is sold. With this loan type, borrowers have the advantage of not having to pay principal or interest payments for the first 12 months of their bridge loan.

Vacation Home Financing

Third Federal offers low rates for borrowers interested in purchasing vacation homes. Unlike other mortgage lenders, it does not increase mortgage rates for secondary or investment properties. Vacation home financing through Third Federal is currently available in OH, FL, and KY.

Third Federal Mortgage Customer Experience

Third Federal offers plenty of useful online resources and allows customers to apply for pre-approval through a simple online form that only takes a few minutes to complete. Applicants don’t have to provide their Social Security Number or contact information to receive a quote estimate.

The bank also has a mortgage rate calculator, an extensive FAQ section and a Mortgage Purchase Guide, which advises individuals on how they should proceed when working with a mortgage lender.

Third Federal Lender Reputation

Founded in 1938, Third Federal has provided affordable home mortgage rates for decades under its Nationwide Mortgage Licensing System ID of 44940. The bank has an A- rating with the Better Business Bureau and has received only 17 customer complaints in the last three years.

  • Date Collected: Nov. 7, 2018

Third Federal Mortgage Qualifications 

Credit score

Quality

Ease of approval

760+

Excellent

Easy

700-759

Good

Somewhat easy

621-699

Fair

Moderate

620 and below

Poor

Somewhat difficult

No credit score

n/a

Difficult

Reputable mortgage lenders look at borrowers’ credit scores when determining their rates and whether or not they should be approved for at all. FICO reports that the industry standard credit score is 740. With Third Federal, however, applicants who qualify for approval will receive the same rates as applicants with higher credit scores. Things may get trickier is if the borrower has no credit history, as they may be required to apply with a cosigner.

Buyers can put less than 30 percent down on their home, but doing so may require them to consider escrow. This involves a third party, such as title company or escrow agent, holding onto funds and documentation until both parties meet the contract terms and conditions.

Third Federal Phone Number & Additional Details

Homepage URL: http://bit.ly/1RXGAcL
Company Phone: 1-800-844-7333
Headquarters Address: Third Federal, 7007 Broadway Ave., Cleveland, OH 44105

The post Third Federal Mortgage Rates Review: Today’s Best Analysis appeared first on Good Financial Cents®.


Source Good Financial Cents® http://bit.ly/2YehM5s

USAA Mortgage Rates Review: Today’s Best Analysis

USAA began operations in the 1920s, when 25 Army officers in San Antonio, Texas, created a small cooperative to insure each other’s vehicles. USAA operates offices across the country and internationally to serve customers on duty overseas.

The company also offers traditional mortgage options as well as those only available to servicemembers and veterans.

USAA Mortgage Rate Facts

  • Provides support and assistance specifically designed for active-duty and retired service members, as well as eligible family members
  • Extends a host of financial education resources and support through the USAA Home Learning Center
  • Has a variety of loan products, from VA loans to first-time homebuyer loans, jumbo loans, conventional loans, and ARM loans
  • Offers zero percent down payment VA loans and down payments as low as 5 percent with other loan options
  • Provides online preapproval as well as real estate agent referral with cash rewards ranging from $350 to $24,000 for qualifying customers

Overall

usaa mortgage rates reviewUSAA has operated for close to 100 years, with a consistent mission of offering a variety of financial services to a specific group: active-duty and retired servicemembers, and qualifying family members.

USAA provides home loans across the U.S., originated 63,000 home loans in the first three months of 2018, and ranks No. 20 in Fortune’s list of the World’s Most Admired Companies for 2018.

USAA has more than 12 million members, and clearly defines its share of the overall home loan market. Because a strong majority of its members qualify for VA loans and other programs designed to benefit active-duty military and veterans, the bank can use its experience and expertise to provide highly relevant, targeted services.

Current Mortgage Rates

USAA Loan Specifics

Understanding the mortgage options offered by a lender is crucial to making an informed decision. While mortgage rates play a major role in that process, the loan type is another crucial aspect to consider.

USAA Adjustable Rate Loans

As the name suggests, Adjustable-Rate Mortgages (ARMs) feature a lower initial rate that can increase or decrease with market fluctuations throughout the life of the loan.

USAA offers a five-year guarantee on the initial rate, meaning that borrowers who plan to move or refinance before the five-year period expires will likely benefit the most from this type of loan. ARM Loans have the lowest initial interest rate of any mortgage offered by USAA.

USAA Conventional Loans

This type of mortgage provides predictability by maintaining the same interest rate for the entire loan term. Borrowers can count on the constancy of that rate when making financial decisions, whether related to the loan or general budgeting.

Fixed rate loans are especially useful for those who plan to remain in their home for a long time. They are also attractive when interest rates are low, as they provide greater value over time.

USAA Jumbo Loans

These debt instruments are specifically designed for USAA members who need a loan of over $453,100, the Jumbo Loan lower limit that was recently increased by the Federal Housing Finance Agency.

USAA Jumbo Loans are available for up to $3 million, making them a good choice for those interested in owning a high-value home. Nevertheless, those looking into jumbo loans need to have a significant amount of cash on hand, as these types of loans typically come with a 20-percent down payment requirement.

USAA First-Time Homebuyer Loans

Created with first-time home buyers in mind, these loans are similar to those insured by the Federal Housing Administration, but are not endorsed or secured by that agency. USAA offers attractive terms and conditions for first-time homebuyers, such as down payments as low as 3 percent. Through USAA, borrowers qualify for first-time home buyer loans as long as they haven’t owned a home in the last three years.

USAA VA Loans

With membership limited to active-duty and retired service members and their immediate family, it’s not surprising that VA Loans are a common USAA offering. Current service members, those retired from the armed forces, and certain surviving spouses all qualify for this type of loan.

With no down payments or private mortgage insurance required, and generally lower interest rates than conventional loans with the same terms, VA loans are especially attractive to those who qualify.

USAA Mortgage Customer Experience

USAA earned an overall rating of four out of five stars in JD Power’s 2017 Primary Mortgage Originator rankings, with a Loan Offerings rating of five stars. This overall rating has decreased slightly since 2016, when USAA received five stars.

USAA emphasizes its commitment to its members, and the restrictions on joining help it create a strong sense of community for those who qualify. The lender offers an online home loan preapproval process and a customer service number, 800-531-0341, that leads directly to its department of loan specialists.

By combining these offerings with short, FAQ-style answers to common mortgage questions and longer articles on mortgage loan specifics all on one main page, USAA makes it simple for members to determine which loan product best meets their needs.

The lender also provides an on-site mortgage calculator tool that allows members to input the home price, desired interest rate, anticipated down payment, and the length of the loan term to generate a sample repayment amount.

Although based on assumptions and estimates, this tool can help members understand what they can afford early on. That, in turn, allows them to focus on the types of loans best suited to their needs.

While quotes aren’t available through without going through the preapproval process, completing that step makes it that much easier to explore available options and choose the one that offers the best terms and conditions for individual needs.

With preapproval in hand and loan specialists readily available to answer questions, choosing a loan product with USAA is a hassle-free experience.

USAA enjoys an overall positive reputation for customer service. Unlike a a few other mortgage lenders, it does not appear on the Consumer Financial Protection Bureau’s ranking of Most-Complained-About Companies for Mortgages.

The organization has earned praise from customer service experience software provider Satmetrix in its Net Promoter Benchmark Study as earning the highest score for eight consecutive years, 2000-2017.

However, USAA has also received its fair share of legitimate complaints from members. One drawback noted on its message board forum is the lack of physical USAA offices, requiring borrowers to make contact via phone and email.

Those who have had negative experiences cited issues with interdepartmental communications, extended timelines, and other concerns that caused problems with third parties involved in the home purchase process.

To be fair, some commenters asked for, received, and reported the satisfactory resolution of their issues once they got in contact with the company’s customer service staff.

USAA Lender Reputation

USAA is a diversified financial services group that was founded in 1922. Its Nationwide Mortgage Licensing System ID number is 401058. The banking portion of the company has a Trustpilot ranking of 2.4/10 stars and USAA life insurance is highly rated among the various rating agencies.  Its BBB rating is “A” and the lender has closed 927 BBB complaints in the last three years.

  • Data collected Nov. 5, 2018

USAA Mortgage Qualifications

Credit score

Category

Likelihood of Approval

760 or higher

Excellent

Very likely

700-759

Good

Likely

621-699

Fair

Somewhat likely

0-620

Poor

Somewhat unlikely

None

N/A

Unlikely

A borrower’s credit score has a significant impact on the rates and terms they are offered. A score above 760 puts borrowers in the highest category and frequently leads to the provision of favorable rates and terms across the industry.

A good score of 700-759 isn’t as strong, but it’s still more of an asset than a hindrance in terms of loan specifics. With “fair” credit, “poor” credit and situations where they have little or no credit history, borrowers should anticipate receiving offers with less-favorable terms and conditions.

Loan Type

Down Payment

Conventional Loan

5 percent

VA Loan

Zero percent

First-time Homebuyer Loan

Zero percent

Jumbo Loan

Variable, but often 20 percent

Down-payment requirements vary depending on the loan type offered by USAA. Members benefit from more than one type of zero-down loan but also have the option of offering a larger down payment to secure more favorable loan terms.

This flexibility and array of options allows USAA members to choose the loan product that makes the most sense for them in the long term.

USAA Phone Number and Additional Details

Homepage URL: https://www.usaa.com/
Company phone: 210-531-8722
Headquarters address: 9800 Fredericksburg Road, San Antonio, TX, 78288

The post USAA Mortgage Rates Review: Today’s Best Analysis appeared first on Good Financial Cents®.


Source Good Financial Cents® http://bit.ly/2IIiyCl

4 Strategies This Woman Used to Beat $30K in Student Loan Debt in 2 Years

Missing Next delivery means I can’t get a mortgage

Moneywise helps a reader unable to get a mortgage because of a disputed debt

I can’t get a mortgage because I refused to pay for a Next order that never arrived.

I ordered £2,700 worth of clothes from Next in 2017. The parcel was apparently delivered and signed for by someone named Scott, but it never arrived at my home.

I have had a lot of rows with Next over the issue as I refused to pay for something that I didn’t receive.

The case has been reopened twice but on both occasions Next has closed it saying I owe them the money and it will affect my credit rating if I don’t pay it.

When I checked my Equifax account, I saw that the ‘debt’ is destroying my credit rating – despite me having agreed to pay £5 a month until I could get it sorted.

My husband and I want to buy our first property next year after saving up for our deposit, but Next has ruined our chances because of the hit to my credit file.

I’m distraught and have now made the decision to reopen this case. Why I just accepted the fact I had to pay it I will never know.

ZS/Nottingham

This is not a standard complaint about a lost delivery but something that has escalated to become a major problem for your hopes to buy your own home.

You highlighted inconsistencies with the statements that the delivery driver made, which back up your claims that the items were never delivered to you – but then you rashly agreed to repay the money that Next said you owed it at a fiver a month. While you did that in an effort to protect your credit rating, that action proved fruitless when you decided to stop making repayments to the company because you thought it was unfair.

But agreeing to repay the money in small instalments has hit your case against Next.

Effectively, Next has evidence that you were repaying a ‘debt’ – and now that you’ve stopped, that information has been added to your credit report as a black mark.

You told me: “Due to the situation, I have now been unable to get a mortgage with high street banks because of this on my credit file. It’s had a huge impact.”

Next told you to take your complaint to the Financial Ombudsman Service (FOS) if you were still unhappy with its response, and this is something you have done.

I contacted Next to see if we could sort things out but the company told me:

“The matter is now in the hands of the FOS, to which Next will make a written submission, robustly defending its position that the goods were delivered to the customer in April 2017.  

“The company is therefore unable to comment further at this stage.” 

Therefore, I can only wish you all the best in your dealings with the Ombudsman and warn other readers not to enter into any financial agreements – such as agreeing to repay a disputed debt – without considering the impact on the rest of your finances.

If you’re unsure of your rights, contact your local Citizens Advice for help.

OUTCOME: Reader turns to the FOS in case against Next


Section

Free Tag

Twitter

Workflow

Published


Source Moneywise http://bit.ly/2xb0lH5

Is your old banger a future classic?

One of the most enjoyable ways to see your money grow is to combine investing with a hobby. Find out which of today’s cars could be worth a mint tomorrow. And if you’re not driving a future classic yet, read our expert buying tips

A rusty 1936 Bentley, which had been locked away in a Stockport garage for 30 years, recently sold at auction for £450,250. While you’re unlikely to have anything similar hidden away, you could potentially own a future classic car.

Alternatively, if you wish to buy a car that will actually appreciate in value you might like to consider buying a future classic.

But what attributes make a classic car and which models are likely to become future classics?

The Historic Automobile Group International (HAGI) has created the iconic HAGI Top Index, which tracks the 50 most investible cars in the world. These include cars such as Ferraris, Bugattis and even two Aston Martins. A left-hand-drive version of the DB5 — the car that first appeared in the James Bond film, Goldfinger — can trade at more than $1 million now, which is approximately six times what it sold for 10 years ago, for example.

Dietrich Hatlapa, the founder of HAGI, explalins what makes a car a classic.

“It is a combination of the following: rarity and type – a convertible or a race car is more likely to be collectible than a limousine – originality, documentation, provenance, technical condition and accessories,” he says.

Of course, this index represents the absolute top end of the classic car market. Yet, with the index showing more than 12.5% annual growth over the long term, it provides an indication of how good an investment the higher-value segments of this market can be.

Graham Eason has been hiring out classic cars as a business for 12 years and also collects them (see below). He believes that what makes a classic car of the future is “heritage, rarity, desirability and innate capability”.

Commenting on his list of future classics, he says: “The DB7 has the right badge, while the XJS is all of these things plus a car that is fundamentally very useable. The Golf is a part of many people’s youth and, unlike later models, is very capable. Rarity comes into play at different stages – there were a lot of Golf GTIs and XJ6s, but very few remain in good and unmolested condition.”


In terms of car marques, he argues that Jaguar is the undisputed ‘gold’ of classic cars.

“These are the cars people want to drive. MG is also popular for the same reason.

“Sports cars, particularly convertibles, are also strong contenders. People reach a certain age, have some money to spend and want a car they can enjoy. A convertible delivers that, hence why I think the MGF will eventually take off, like the MGB,” he adds.

For anyone thinking of buying a car in the hope that it will appreciate in value and become a future classic, Peter Gascoigne, a director at auctioneers Barons, has a word of advice: “A classic car is something that the original owner bought as a pleasure to drive, not as something to get from A to B.”

Asked to pick a car produced in the past 20 years that is likely to achieve classic status, Mr Gascoigne suggests the Peugeot 406 Coupe.

“You can buy them for a couple of grand, styled by Pininfarina in Italy; it has all the bells and whistles and drives really nicely,” he explains. “Unfortunately, it says Peugeot on the front. At the moment, it is going almost for nothing but eventually someone will want one and will pay a lot of money for one, as they’re very pretty and there will be none left.”

Over at Brightwells auctioneers in Herefordshire, consultant Will Daniels explains that the company looks for a few key characteristics in a modern classic.

“Essentially, is it interesting? Is it a rare or high-power version, low mileage, with unique spec, colour or history? And do we think it might have legs for future growth in value and desirability,” he asks.

Mr Daniels advises buyers to do their research and understand the difference between models because that is a crucial factor that makes one car more collectable than another and will also ensure buyers don’t overpay.

He explains: “For example, a standard BMW 3-series is much less likely to become a modern classic than, say, the M3 version, or a 330Ci Clubsport, a rare higher performance version of the standard car, which was built in fewer numbers.”

How to buy?

There are various ways to buy one of the future classics mentioned above. The safest way is probably to buy from a franchised dealer although that is also likely to be the most expensive.

If buying elsewhere, check the car out for issues, such as rust and mechanical problems, and ensure any paperwork proves that it is what it purports to be. Ideally, the car will have a full service history but failing that, some evidence that it has been well looked after, such as repair bills.

Buying privately is probably the cheapest way to own one as you won’t pay dealer or auctioneer fees. That said, you will need to do more online research to find a bargain.

Mr Gascoigne argues there are bargains to be had at auctions but advises that you do take the time to check out any car before the auction begins: “You need to look at the car beforehand and decide if it is worth buying, as if you buy from auction there is no comeback.”

If you don’t have a friend who is a mechanic, the AA and RAC both offer pre-purchase inspections. Prices start from £128 at the AA, which will inspect vehicles up to eight years old. With an RAC basic inspection (from £99), the vehicle age limit is 10 years, while RAC’s comprehensive (from £189) or advanced inspection (from £239) has no age limit.

While the services of a competent mechanic are useful, you will also need to ensure that you look after your car, regularly servicing it and taking care of the bodywork. Ideally, you would have a garage to keep it in, but it may be going too far to wrap it in blankets and hide it away without driving it.

As Mr Eason explains: “The advantage of an appreciating classic is that you have something you love and enjoy, which has the potential to pay you back at the end. You also have something that other people increasingly want and admire.”

“‘Fast Ford’ is a relatively reliable future classic”

Graham Eason, who runs classic car-hire firm Classic Cars, bought a Ford Mondeo ST200 for £800 just over a year ago.

“I had several Mondeos in the 1990s as company cars – they followed a Sierra and were a total revelation. I’ve never forgotten just how good they are and always wanted to drive one again. That is really why I started looking at the ST200, not because I saw an investment opportunity,” he reveals.

Nevertheless, he does believe it will be a future classic. “It is a ‘Fast Ford’ – all quick Fords go through a value curve because so many are made. This means that for a while they are common and therefore not valued” he says.

“Eventually most get scrapped, leaving a small number – and there is then increasing demand for that small pool of cars. In recent years, the Ford Capri, Sierra Cosworth, XR2 and XR3 all went from being sub-£1,000 cars to now being five figures and beyond. There are no guarantees, but a good Fast Ford is a relatively reliable future classic.

“I think it takes about 20 years for a Fast Ford to begin to appreciate – Capris were sub-£1,000 until 10 years ago. They began picking up in this decade, and now they are £10,000 or more for average condition,” he adds.

In the meantime, he feels free to enjoy it but is careful with the mileage.

“It will need restoring over the next few years as its value increases, but for now I don’t have to treat it with kid gloves. I also garage it and it is maintained in my own workshop.”

Top 10 future classics

from Graham Eason at Escape Cars

  • Aston Martin DB7
  • Jaguar XJS V12
  • Ford Focus ST170
  • MG ZT V8
  • MGF ZT V8
  • Ford Mondeo ST200
  • Alfa Romeo GTV V6
  • MK2 Golf GTI
  • Ford Mondeo ST200
  • Jaguar XJ6

HPI’s list of future classics

Jeremy Yea, senior valuations editor at HPI, says: “With this selection of future classics we’ve identified 10 models that not only perform well but also represent excellent value for money, making them a hot prospect for motorists looking to gain a healthy return on their investment.”

  • Range Rover Sport SVR
  • Alfa Romeo Stelvio Speciale
  • BMW 1M Coupe
  • Honda CR-Z
  • Ford Fiesta ST200 (16-17)
  • BMW Alpina 5 Series 18
  • Ferrari F430 coupe (05-10)
  • Audi TT Coupe Quattro 3.2 V6 (99-06)
  • Toyota IQ 1.33 VVTi (98)
  • Volkswagen Phaeton W12

Top 5 future classics

from Will Daniels, a consultant at auctioneers Brightwells

  • BMW E31 series 840 and 850
  • BMW M3 E46
  • TVR Cerbera
  • Renaultsport Clio 182 Cup
  • Mercedes C43 from late 1990s

CHRIS MENON is a freelance journalist and runs the Safestocks blog

Section

Free Tag

Twitter

Workflow

Published


Source Moneywise http://bit.ly/2RIgZrj

الاثنين، 24 يونيو 2019

Fashion Jobs: Work-at-Home Careers for Fashionistas

Are you of the philosophy that playing dress-up should never have an age limit? Do you spend time and thought into picking out your outfits daily? Do you believe that the right handbag can help you take on the day? If yes to any (or all!) of these, you might be a fashionista. You may […]

The post Fashion Jobs: Work-at-Home Careers for Fashionistas appeared first on The Work at Home Woman.


Source The Work at Home Woman http://bit.ly/2FvILSS

New CLU Club taking shape; tentative opening in August

EAST STROUDSBURG — A little more than two years after fire destroyed the CLU Club in East Stroudsburg, work is underway to convert the former M & S Grocery Store on Mill Creek Road to the new CLU Social Club.On Monday, club steward Jerry Hoover gave a reporter a tour of the work site and predicted the club will be up and running and back in business by late August."Eight months and $10,000 later we got our building permit," Hoover said. "Now we are starting to move. [...]

Source Business - poconorecord.com http://bit.ly/2KCdeD0

New CLU Club taking shape

EAST STROUDSBURG — A little more than two years after fire destroyed the CLU Club in East Stroudsburg, work is underway to convert the former M & S Grocery Store on Mill Creek Road to the new CLU Social Club.On Monday, club steward Jerry Hoover gave a reporter a tour of the work site and predicted the club will be up and running and back in business by late August."Eight months and $10,000 later we got our building permit," Hoover said. "Now we are starting to move. [...]

Source Business - poconorecord.com http://bit.ly/2RB1YHt

Buying a Foreclosed Home Doesn’t Have to Be Scary. Here’s How to Do It

Defunct retailer Toys R Us planning U.S. comeback

Defunct retailer Toys R Us is planning a comeback.The New Jersey-based chain, which closed in 2018, plans to start small, relaunching its website and opening six brick-and-mortar stores, according to Time magazine.The new stores will be about a third of the size of old Toys R Us locations, spanning about 10,000 square feet. The new stores are expected to be experiential in nature, with numerous [...]

Source Business - poconorecord.com http://bit.ly/2NaN1gW

Stop With the Bank Fees: Our 8 Favorite Free Checking Accounts of 2019

Questions About Libra, Campfire Cooking, Investment Books, David Bach, and More!

What’s inside? Here are the questions answered in today’s reader mailbag, boiled down to summaries of five or fewer words. Click on the number to jump straight down to the question.
1. Using rewards card for everything
2. Thoughts on Monat
3. Work, motivation, and retirement
4. Campfire cooking advice
5. Using 403(b) loan for debt
6. Uses for old spices
7. Easy beginning investment book
8. Cast iron worth the work?
9. Libra?
10. David Bach
11. Usefulness of cookbooks
12. Privilege

Sometimes, the questions are plentiful and the answers are easy. Sometimes, it’s the intro that’s hard.

On with the questions.

Q1: Using rewards card for everything

What do you think of the idea of putting every possible expense on a rewards credit card and then paying it off in full each month? This not only gets me rewards but also gives me some protection on everything I buy and keeps my actual checking account safe.
– Jerry

This works if and only if you have a very, very firm grasp on your spending and aren’t spending more than you earn. This can be easy to lose track of with a credit card because it’s so easy to just swipe for everything.

I absolutely would not recommend this for anyone who has had any problems accumulating credit card debt in the last, say, decade or so.

If you have that kind of firm grasp, then running everything you can through a credit card with a good rewards program and then paying it off in full every month makes a good deal of sense. You’ll likely accumulate quite a lot of rewards points as time goes on and it makes financial management easier. Just watch very, very carefully for any sort of spending increases, as that’s a sign that this whole system is in danger of falling apart leaving you holding a bunch of credit card debt.

Q2: Thoughts on Monat

My sister has started selling this Monat shampoo and I think it’s a scam. She has convinced several of her friends to start using the shampoo and cut her hair way different supposedly to show off how great the shampoo his but her hair has always been shiny. She keeps trying to get me to sell it too but the whole thing seems like Mary Kay or Amway. Do you know anything about this?
– Audrey

You pegged it – it’s pretty much just like Mary Kay and Amway. Monat is a network marketing company with shampoo as the product this time around.

In short, Monat works like every other network marketing company. It requires people who sell it to pay a significant up-front fee to become a salesperson for the product. For that fee, Monat gives the individual salespeople a bunch of marketing material – in essence, the salespeople on the ground paid a ton for marketing material that they then use to sell Monat. They also get a commission for what they sell. They also get a cut of anything sold by anyone else they convince to be a Monat salesperson.

This is almost exactly how every other network marketing business works, with a few insignificant variations. It’s all about selling to your friends and family and trying to convince people to start selling it so you can get a cut of their sales.

It essentially functions like a pyramid scheme, where the only people who really make money are the people at the very top – the people who actually make the marketing materials and the handful of initial people who got a lot of people to sign up through them. Everyone else ends up with a bunch of overpriced marketing materials and rarely recoups their cost while often just annoying their friends by pushing products that their friends really don’t want to buy.

Stay away. There are far better ways to make money than this.

Q3: Work, motivation, and retirement

61 years old, set to retire with state pension and additional 403(b) at 63, don’t plan on touching SS until max benefits and then scale back 403(b) withdrawals. In short, I am set for retirement. The problem is that I have nineteen months to go and I just want to be retired. I have to force myself to go to work and I find myself counting the minutes and hours every day. This doesn’t appear to have really affected my work as of yet as I just had a positive performance review. I don’t want to be a deadbeat employee but I just hate going to work. I have to last out these last 19 months so just quitting now isn’t an option. What can I do?
– Otis

I don’t know exactly what your job entails, but there are a number of things you can do to make this time go better.

Perhaps the most powerful thing you can do is start transferring your domain knowledge to other workers who will be filling your role when you’re gone. What are the things that you know how to do really well that others may not know to do? What things do you just take care of and fix? What ordinary routines do you handle?

One thing you might want to start doing is thoroughly documenting all of that knowledge. I found that, as I was leaving my previous job, I very much couldn’t wait until my last day, but the one thing that really clicked with me was writing a ton of documentation for my replacement. I wrote out step-by-step operating procedures for all of my normal routines. I wrote out step-by-step explanations for how to solve a number of common problems. This filled up a lot of time at work as the clock ran out on my tenure.

Another approach is to take on a mentee. Look for someone who’s an up and comer at work and take them under your wing, guiding them as to how to make the most out of their career. What things can they avoid? What help can you give them as you’re getting ready to leave? Choose someone who could really use the opportunities, who might remind you of yourself a little when you were younger.

Another good thing you can do is to make it your goal to leave a positive mark on the lives of the people you’re working with. Go in there with the aim of being friendly and kind and building up other people. Try to leave the workplace in a better state than it is right now.

These things can fill a lot of your time, so let them. Let such things be the focus of your last year and a half at this job, to leave the people there and the job in a better place than it is right now, and give the people you think are deserving of opportunity as much help and opportunity as you can give them.

Q4: Campfire cooking advice

Loved your recent post on camping basics. Do you have any advice on how to make anything other than sandwiches and hot dogs when camping?
– Mary

This could be a post all its own (and it might be someday soon), but here are the big tips that come to mind.

First of all, get a Dutch oven. A Dutch oven is a cast iron pot that you can put literally on your campfire and scoop some coals on top to cook pretty much anything. Just get a good campfire going with a bed of coals, then put your meal in the Dutch oven, set it on the campfire with a hook, then scoop a few coals on top with a long-handled spoon. When you first get started, follow some campfire Dutch oven recipes to the letter because cooking times are kind of finicky, but you’ll get used to it. You can cook all kinds of things in a Dutch oven over a campfire. We often make “stone soup,” which is basically just soup cooked in the Dutch oven with everyone choosing an ingredient to add that they like. It’s always a little different and there’s always something you like in it.

Another really good tip is to do a lot of the preparation steps for your meals at the campsite at home. Chop up your vegetables and prep any mixes beforehand and store them in Ziploc bags or small containers in your cooler. That way, you can usually just toss things in the Dutch oven when you’re ready to cook and have it on the fire pretty quickly with minimal campsite gear.

So, for example, you can easily make lasagna in a Dutch oven, but it’s a good idea to make the cheese mix at home before you go. Bring along a box of oven-ready noodles, a jar of sauce, and a container of your cheese mix and any other layers you might want in the cooler. Then, when it’s time to cook, just put together the layers in the Dutch oven and put it on the campfire with a few coals on top. Check it occasionally and when it looks close to being done, put some cheese on top and put it back on the fire for five or ten minutes. Yep, campfire lasagna.

Q5: Using 403(b) loan for debt

When I first graduated from college, I didn’t know what I was doing and consolidated my student loans badly into a single loan with a 7.4% interest rate. I have been making payments on this for 3 years while working for [a university] and contributing to my 403(b) plan. I am wondering if it makes more sense to stop contributing to 403(b) and borrow against it to pay off this debt. I recently learned that you can take interest free loans from your 403(b) if you repay at a certain rate. So should I take that loan, pay off my student loans, then pay back the interest free loan?
– Maria

This one is honestly kind of a coin flip. Given that this is a loan from your 403(b), you’re not actually missing any contribution cycles, but you are missing out on growing that money during the period when you borrowed it. In effect, borrowing that money is “costing” you whatever the returns might have been on that money had you left it in your account.

So, the question is whether the returns on that money would be better than the 7.4% interest rate on your student loans.

My thought is that if you can strongly commit to paying back this loan as fast as you can, then it’s a wise move, but if you’re not able or willing to do so, then it’s not a good move. You should be making payments to your 403(b) loan at least as large as the payments on your student loan each and every month. If you can do that, you will have paid back the 403(b) loan much faster than you would have been able to pay off the student loan, which means that in theory you should be financially ahead at that point unless you miss an extreme uptick in the value of your retirement savings.

My recommendation is that once you pay off the loan, you seriously upgrade your 403(b) contributions going forward from that point, which shouldn’t be a big issue because you have neither the student loan or the 403(b) loan hanging around your neck.

Q6: Uses for old spices

What do you do with old spices that have lost most of their flavor? Can anything be done to get more out of them or are they headed for the trash?
– Susanna

Honestly, if a spice is getting old, I usually just start using it in larger quantities until it’s all used up. If a soup recipe calls for a teaspoon of basil, I’ll put in a tablespoon of old basil, or even more. It still has some flavor, just not as much as recently dried basil.

This is very dependent on taste, so I really only do this with recipes where I know what I want it to taste like, like vegetable soup (which I’ve made a thousand times) or black beans for burritos or tacos. I know the flavor I’m aiming for, so I trust my tongue.

If it appears to just be flavorless dust, I usually sprinkle it in the yard, as at least it’ll provide a bit of nutrients to the soil.

Q7: Easy beginning investment book

Do you have a book for beginning investors that’s easy to understand? Tried reading The Intelligent Investor and then The Bogleheads Guide to Investing and they both went rapidly from making sense into insider lingo that was unreadable. What’s a more basic intro?
– Dennis

I wouldn’t recommend The Intelligent Investor to anyone outside of those purely academically curious. I think Bogleheads is pretty approachable, but it does lay on the terminology thick in places.

The Simple Path to Wealth by J.L. Collins is probably the book I’d point at for you. I’d describe it as being a notch or two simpler than Bogleheads but covering much of the same material.

Another good book on investing that I think would work for you is The Four Pillars of Investing by William Bernstein. This book is more of an introduction to semi-professional investing in layman’s terms rather than what individual investors saving for retirement might want to be doing, but it’s written in a very approachable style.

I’d give those two a try. Check them out from your local library.

Q8: Cast iron worth the work?

Thinking about getting a cast iron skillet because of how you can cook everything on it, but it seems like a ton of work to get it in good shape.
– Amy

It can take some time to really season a cast iron skillet so that the surface is very low stick, much like Teflon except without the potential risk of cancer if the coating starts to flake. It’s not difficult work, though, and it’s pretty hard to mess it up.

Basically, when you first get a new cast iron pan, you need to bake it a few times with the insides coated in oil or Crisco or some other fat. Just coat the insides, put it in the oven for a while, and then wipe it out thoroughly and repeat.

After that, you can cook foods in it that have a high fat content with no problem for the next several months. Anything that involves oil in the pan is going to be fine.

Once the surface seems smooth, you can pretty much cook anything in them with minimal sticking. Cleaning them is easy, too, but you can’t run them through the dishwasher. You just run water over the pan and scrub it a little with a pad and it’s done.

I really like cast iron skillets with double handles, like this one. If you need to adjust it, just put a hot pad on your hand(s) and move it where you want. Most of the time, it just sits in place while you’re cooking. When you’re done, you can carry it to the table easily with two hands if you wish, and then just let it cool down and wash it with some running water and a scrub brush to get out any debris, which comes right out in a few seconds for almost everything.

Q9: Libra?

Do you think Libra is a worthwhile investment to get in on early?
– Barry

If you have some extra money that isn’t allocated toward a goal that you don’t mind losing, then sure, why not? I’d never object to someone using entertainment money or “fun” money for it. However, I wouldn’t put a dime of money that I was counting on into Libra.

For those aware, Libra is a online currency introduced by Facebook that appears to be a mix of a Bitcoin competitor and a PayPal competitor. From what I can tell, it’s probably going to be much more stable than Bitcoin, but at the same time, I don’t think it makes a particularly good investment. I actually think it will just hold steady value for a long time and be used as a pretty stable way to make online transactions rather than as a fluctuating investment on its own.

So, if you want to put a bunch of money into Libra, do so, but make sure that it isn’t money that you actually need for your future. I don’t have any idea what it will do, but what I suspect is that it will end up being like money sitting in your PayPal account.

Q10: David Bach

What are your thoughts on David Bach? It seems to me that his books just take the same two or three ideas and remix them over and over again, never saying anything new. If you’ve read one, you’ve read them all.
– Brian

I largely agree with you. I think it’s worthwhile for most people to read a David Bach book, one that matches their own personal interests the best, and then there’s much less need to read other ones.

Bach’s big idea is that there is a ton of power in the multiplicative effect of making little changes to frequent routines. His big one is what he calls the “latte factor” – if you simply move from a $5 daily latte to a $0.50 cup of coffee at home or work, you’re saving $4.50 a day. Over the course of a year, that’s $1,642.50. Sock that away at a 7% return and do it for a decade and you have roughly $25,000 in cash in your hand, tax free.

The thing is, while those core ideas are good, most of his books are just remixes of those core ideas, tweaked to a specific readership.

Q11: Usefulness of cookbooks

Do you think that cookbooks are still useful in an era where there are infinite recipes online?
– Mary

Absolutely, for several reasons.

For one, cookbooks are available if the internet is down. If you don’t have the internet, you can’t access online recipes. You can always access a cookbook.

For another, cookbook recipes tend to be pretty reliable and high quality. A lot of recipes on websites are pretty dodgy, though there are some sites that I do implicitly trust (like Serious Eats). However, if a cookbook is well regarded, I generally trust everything in it.

For yet another, cookbooks often do a much better job of addressing techniques than online recipes – how exactly to do things in the kitchen. I often get more value out of techniques than I do out of the recipes, though I do often supplement the techniques with Youtube videos.

I also like the flexibility of using a cookbook in the kitchen. I can flop it out on the table, highlight it, move it around, and so on. I can do that with tablets and phones and laptops to an extent, but it often involves having to scroll and being worried that my device is near something messy in the kitchen, something I worry about a lot less with a cookbook.

I have a shelf full of cookbooks. I love them, and I add new ones every once in a while.

Q12: Privilege

Have you ever considered that some of your financial success comes from the advantages you had in life and not because of your personal choices?
– Amelia

Absolutely. I had a number of advantages in life, not least of which was two loving parents who did everything they could to raise me with good values and a strong work ethic. On the other hand, I didn’t grow up with “every advantage.” My family was at the very best lower middle class, and I think that’s a stretch to even call it that. I spent much of my childhood sick and missed more than a year of school due to fifteen different childhood surgeries I went through. I am naturally very introverted and have to work hard just to do well in social situations when my strong, strong preference is to be quiet or leave.

The point is that the advantages I did have certainly gave me a boost in life. I like to think of it as being like a sprinter running a race with the wind at their back or starting at the ten yard line.

The issue is that I still had to run the race. For some, the race was easier than it was for me. For some, the race is harder. But we are all running that race. The vast majority of people that achieve success had to work and work hard to get it. Very few people are handed success in life. Sure, some people start out closer to the finish line than others, but they couldn’t just sit on their rear end all day and success just arrived in their mailbox.

I’m interested in helping people in their own run, whether they start off with the wind at their back and 50 yards past the starting line or whether they’re starting off at the back of the pack with the wind in their face. I can’t change anyone’s starting position, but I can certainly do my best to put a little bit of wind to everyone’s back. We’re all running, and we all want to make something more of our lives.

Got any questions? The best way to ask is to follow me on Facebook and ask questions directly there. I’ll attempt to answer them in a future mailbag (which, by way of full disclosure, may also get re-posted on other websites that pick up my blog). However, I do receive many, many questions per week, so I may not necessarily be able to answer yours.

The post Questions About Libra, Campfire Cooking, Investment Books, David Bach, and More! appeared first on The Simple Dollar.


Source The Simple Dollar http://bit.ly/2WZzNDh

4 Ways to Entertain Guests Without Spending a Lot of Money

PayPal vs. Stripe For Ecommerce

As I’m sure you’ve figured out by now, building a website takes lots of hard work. This is even more so the case for those of you who are creating an ecommerce site.

In addition to your website design, architecture, and all of the standard website elements, you also need to figure out how you’re going to accept payments online.

If you’ve never done this before and you’re just starting some preliminary research, there’s a good chance that you’ll come across two names; PayPal and Stripe. These are both industry leaders in the online payment processing industry.

Both platforms will essentially let your customers buy products or services from your ecommerce shop, but the way that these services are provided are different from platform to platform.

So what’s the difference between PayPal and Stripe? Is PayPal or Stripe better for accepting payments online? These are questions that I hear all of the time when I’m consulting with ecommerce companies.

Truthfully, you probably can’t go wrong with either one. But with that said, I want to give you as much information as possible about each platform so you can decide which one is right for your ecommerce business.

Basics of payment gateways

Before we continue, I want to make sure you understand exactly how PayPal and Stripe work. There are two terms you need to know:

  • Payment gateway
  • Payment service provider

Payment gateways give ecommerce sites the capability to accept payments online. These gateways are like a middleman between a business payment processor and credit card network. PayPal and Stripe both have payment gateways, which you’ll need if you’re planning to authorize online payments.

A payment service provider (or PSP for short) on the other hand is a bit more involved. PayPal and Stripe are both PSPs as well. They link businesses with merchant accounts by providing the technology required to process online payments, as well as other forms of payment.

PayPal and Stripe group all of their merchants into one account, as opposed to each business having a dedicated account.

Basically, both of these platforms have everything you need to authorize payments as an ecommerce website.

PayPal for ecommerce

Paypal for Ecommerce

Even if you have no prior experience with running an ecommerce website, PayPal is definitely a name that you’ve heard before.

The company has always been known for payment processing. They have the reputation for being a safe and secure way for PayPal users to buy from merchants using a PayPal balance as well as a debit or credit account linked to their PayPal profile.

But PayPal offers much more features and services to accommodate ecommerce shops. So the days of PayPal only being suitable for things like eBay or other P2P payment situations are long behind us. Now they have a variety of plans for launching a business, whether you want to sell online, in person, or both.

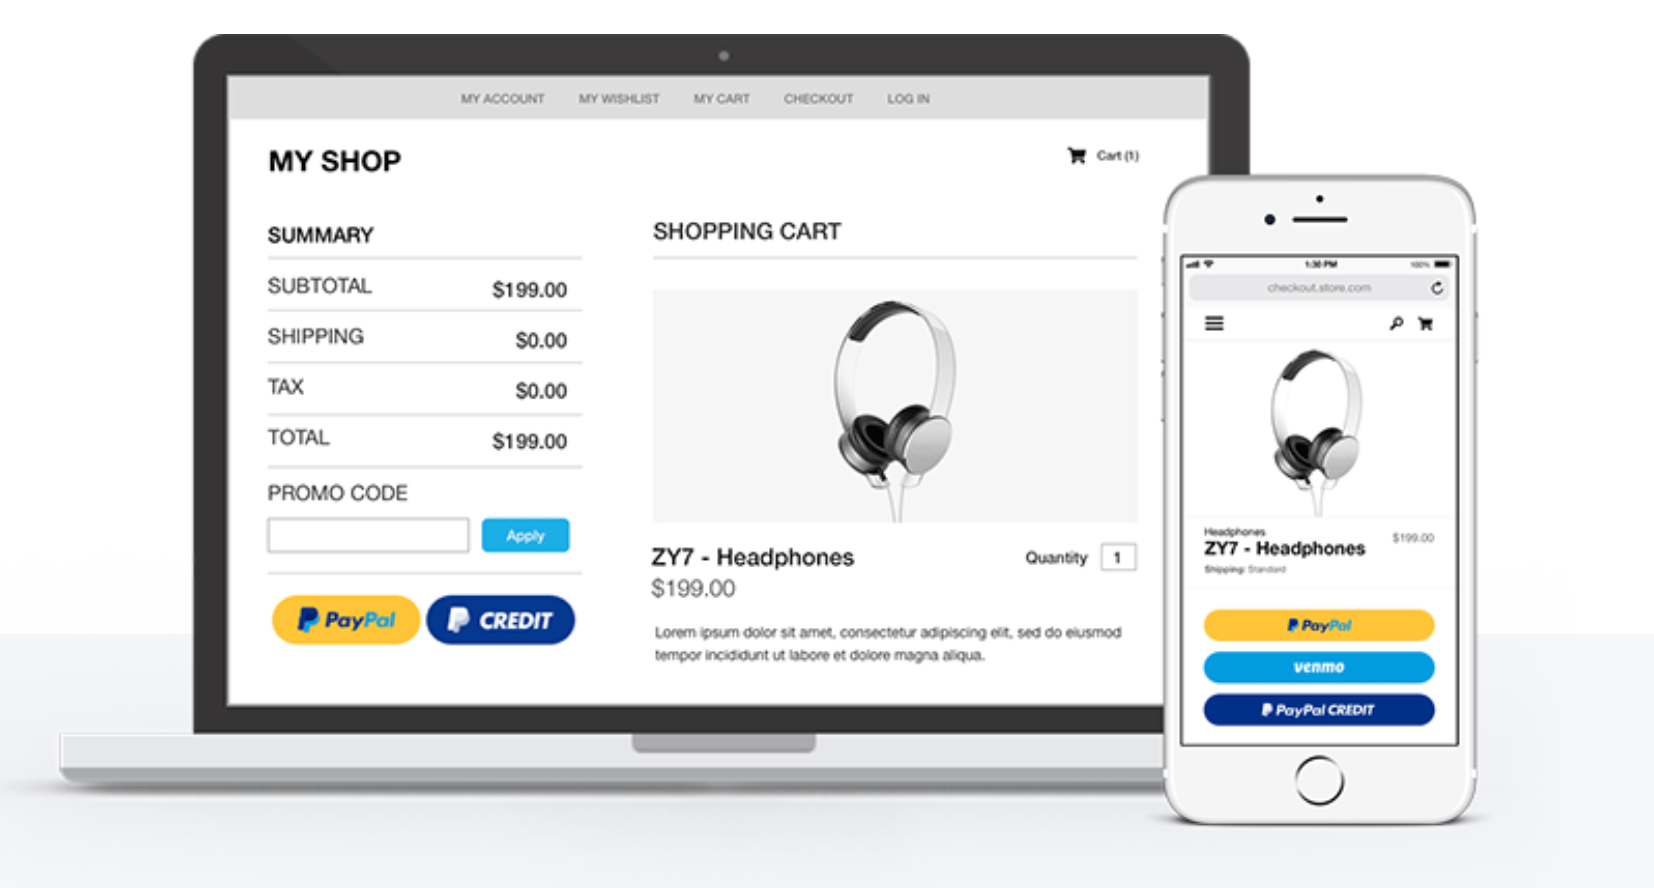
You’ll be able to accept payments from credit cards, debit cards, PayPal credits, PayPal accounts, and Venmo as well.

With PayPal, you can design your own shopping cart. They have customizable solutions that are fully scalable for growing businesses.

PayPal offers three main plans for you to choose from. I’ll cover each one in greater detail below.

PayPal Checkout

Paypal Checkout

For those of you who already have an existing payment processor that you’re using to accept credit cards on your ecommerce site, PayPal Checkout might be a good option for you to consider.

Basically, you can just add the PayPal button to your current payments page with this supplemental plan. It’s easy to integrate with your existing ecommerce platform. Once the button is added, your customers will be able to use PayPal, PayPal credits, or Venmo to buy from your online store.

Conversion rates are up to 82% higher when PayPal Checkout is added to ecommerce sites. That’s because shoppers can complete the purchase in just a click or two, if they have PayPal on their phones or if they’re already logged into PayPal on their computers.

There is no setup fee or monthly fee for this plan. PayPal charges merchants 2.9% + $0.30 per transaction in the United States.

PayPal Payments Standard

The PayPal Payments Standard plan is made for merchants who don’t have an existing payment processor or want to switch providers.

In addition to the PayPal payment options, you’ll also be able to accept Visa, Mastercard, American Express, and Discover cards. Adding the button to your website is as simple as copying and pasting some code. The checkout pages will be hosted by PayPal.

This plan will cost you 2.9% + $0.30 per US transaction. There are no monthly fees or setup fees for the Payments Standard plan.

PayPal Payments Pro

Payments Pro is the top-tier plan offered by PayPal. It allows you to create a fully customizable checkout experience on your ecommerce site.

Unlike the Payments Standard plan, website visitors won’t have to leave your site to complete the checkout process. It also has a mobile-optimized checkout process and easy shopping cart integration. Payments Pro gives you a virtual terminal, which makes it possible to accept payments over the phone as well.

With the added features, this plan costs $30 per month, plus the standard 2.9% + $0.30 per transaction.

Stripe for ecommerce

Stripe for Ecommerce

Unlike PayPal, Stripe doesn’t have their services segmented into tiered plans. Stripe’s payment processing will be the same, regardless of what features you’re taking advantage of.

With that said, depending on which tools you want to use, it will cost more. But the nice part about this is that you’re only going to be charged for the features that you actually want, as opposed to paying for a plan that includes tools you don’t need.

You can easily add Stripe to your ecommerce site with just one simple integration.

Once that happens, the platform makes it easy for you to accept payments, process them, settle, and reconcile. You’ll be able to process credit cards and ACH transfers both online and via mobile app payments. In fact, big mobile app brands like Lyft are already using Stripe.

Stripe lets you build a checkout process from scratch, or select one of their pre-built templates.

The platform has features for invoicing and setting up recurring payments for subscriptions as well. Let’s take a look at some of those add-on features I was talking about earlier.

Connect

Stripe Connect is made so that marketplaces and platforms can accept money and pay it out to third parties. It supports ecommerce sites, crowdfunding, on-demand businesses, and travel or event platforms.

Take advantage of Stripe’s UI components that are pre-built, or use their tools to create and customize everything on your own.

Sigma

Sigma helps businesses analyze data from stripe using SQL. It can help improve the efficiency of business operations, finance departments, data teams, and product management.

It’s a great way for you to get to know your business better with data. Then you can make necessary adjustments based on your findings. Pricing for Stripe Sigma varies based on the volume of monthly charges.

Atlas

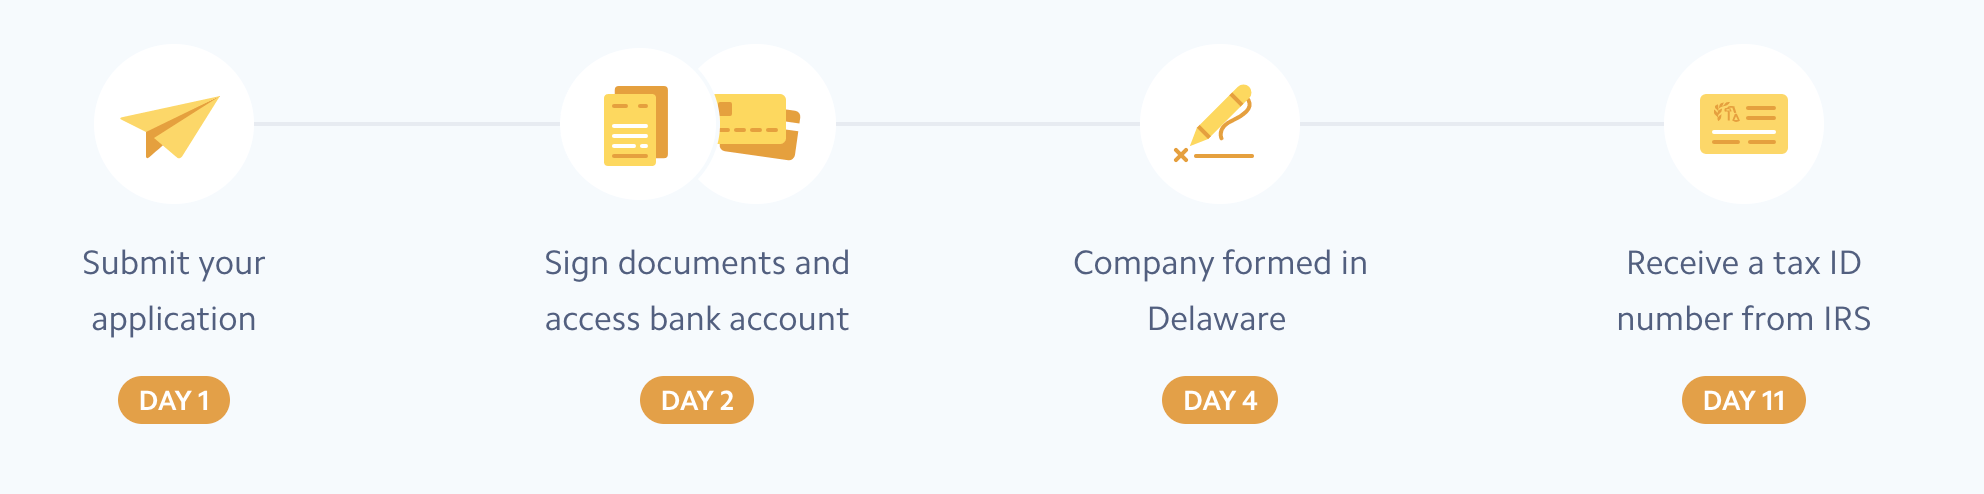
Stripe Atlas is made for those of you who are starting an online business from scratch. The startup toolkit guides you through the process of forming a company, establishing IP ownership, filling out the right documents, and getting a tax ID number from the IRS.

Stripe Atlas

Atlas also sets you up with a new bank account and debit card for your business.

There is a $500 one-time fee for using this service. Services like bank account maintenance, tax filing, and registered agents are not included in the setup fee. These are all billed individually at an annual rate.

Radar

Radar is Stripe’s fraud detection, prevention, and management tool. It’s designed to analyze your data and stop potential fraud cases before they are processed.

They take data from your checkout flows, payments, and financial partners to determine irregularities. Stripe’s partnership with major credit card companies and banks make it possible for them to identify fraudulent charges before you need to make a dispute.

Issuing

Stripe Issuing is made for ecommerce businesses that want to create, distribute, and manage both physical and virtual cards for in-house purposes.

You can use these cards for things like employee expense accounts. It’s supported by Google Pay and Apple Pay as well. It’s also worth noting that Stripe Issuing is a beta program that’s only being offered in the United States.

Terminal

For years, Stripe was better known for its online payment processing. But now they offer Stripe Terminal, which is a POS system for in-person payments.

This is a great option for those of you who have physical store locations in addition to your ecommerce shop. You can get everything you need both online and in-store from the same provider.

PayPal and Stripe compared

As you can see from everything that we’ve covered so far, these two payment service providers are very different from each other. But with that said, they have some things in common as well.

Deciding between PayPal and Stripe will mostly come down to personal preference and exactly what you’re looking for. Let’s take a look at some specific features to see how each platform stacks up against the other.

Price

The pricing for PayPal is very straightforward. Only the Payments Pro plan has a monthly fee, while all three plans charge 2.9% + $0.30 per transaction.

Stripe also charges 2.9% + $0.30 per transaction. But they do have custom pricing packages for things like volume discounts and multi-product discounts, which can be useful for those of you who want to take advantage of the products we looked at earlier.

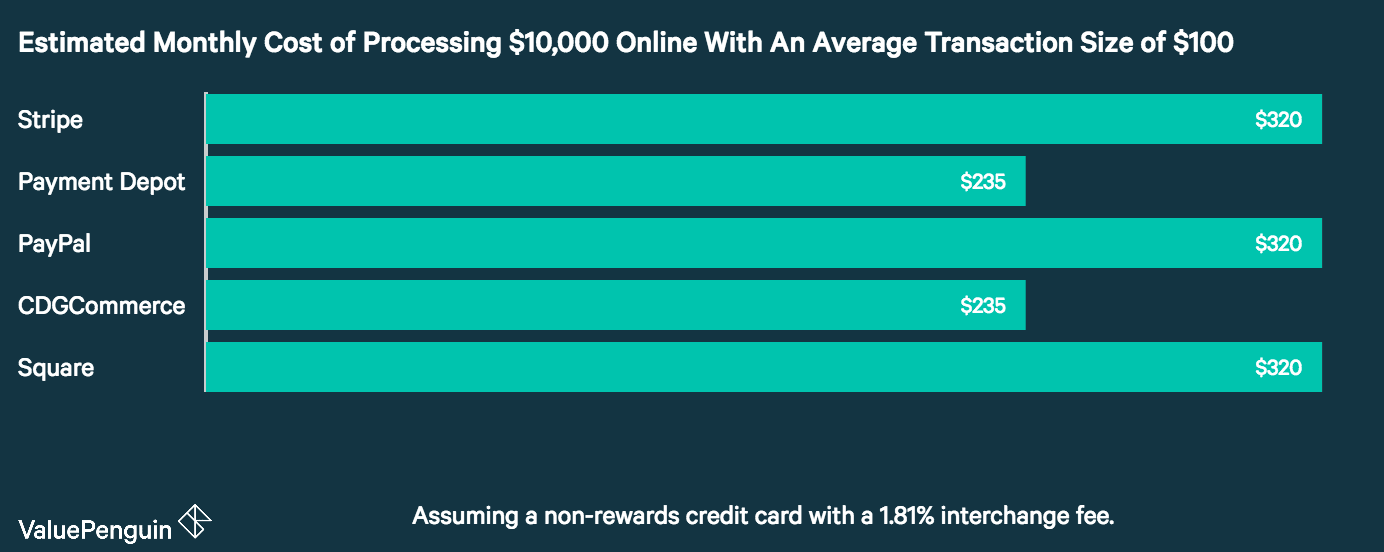
According to research Value Penguin, Stripe is more expensive than PayPal.

Stripe vs Paypal cost

It can be argued that Stripe has more to offer, which might justify that higher amount. But when you compare the cost per transaction rates head to head, both services are even.

Support

Both PayPal and Stripe offer excellent customer service and technical support options. They each have their own variation of a help center, with different tools, guides, FAQ, and resources needed to troubleshoot on your own.

You can also get help using:

  • Email
  • Live chat
  • Phone
  • Social media

Based on all of this, I don’t think that I can definitively say that one platform has better support than the other, so this category is a tie.

Ease of use

Stripe and PayPal are both easy to use. But with that said, Stripe is definitely more developer-friendly, meaning it could present more of a challenge to ecommerce store owners who don’t have that type of technical knowledge.

PayPal is as simple as copying and pasting some code to get set up, which is about as straightforward as it gets. So I’d say PayPal is better for beginners, while Stripe has more customizable options for developers.

Contracts

Both PayPal and Stripe offer pay as you go contracts. So you won’t get locked into anything long term and can cancel at any time. You also won’t be charged a cancellation fee by either service if you decide to do so.

This category is another tie.

Reputation

PayPal always had a reputation for its P2P payments through third-party platforms like eBay. Although now they’re taking aim at providing more services for ecommerce sites. Stripe has always been known for ecommerce solutions, but not offers POS solutions as well.

Both of these companies have the tools, services, and resources you need to run an ecommerce shop. They both have exceptional online reviews as well.

PayPal is the most popular digital wallet in the United States and is the most popular mobile payment method in North America. There are more than 277 million PayPal users worldwide.

Based on these numbers, I’d have to give the edge to PayPal in terms of reputation. But by no means am I saying that Stripe doesn’t have an excellent reputation as well.

Conclusion

If you have an ecommerce shop and you’re trying to figure out the best payment service provider, both PayPal and Stripe are top options to consider.

At the end of the day, it’s going to come down to personal preference. Based on the information I gave you above, you can decide which plan meets your needs the most.

I can’t definitively give an edge to one platform over the other. I’d strongly recommend both options.

For those of you who still aren’t sold on PayPal or Stripe, you can review my guide on the best payment methods for your ecommerce site to find some alternative solutions.


Source Quick Sprout http://bit.ly/2Ycnntc

الأحد، 23 يونيو 2019

8 Types of Work-at-Home Jobs with Google

In my opinion, there are two companies that are significantly changing the landscape in how we do things, one being Amazon, and the other being Google. Just think back to when you had to purchase a license download Microsoft Word, Excel, and PowerPoint to your computer. Nowadays, everyone uses Google Docs for these functions, and […]

The post 8 Types of Work-at-Home Jobs with Google appeared first on The Work at Home Woman.


Source The Work at Home Woman http://bit.ly/2IAMEaW

Save Hundreds on Your Wedding By Shopping Secondhand

السبت، 22 يونيو 2019

Pa. jobless rate sets record low; nonfarm jobs at record high

Pennsylvania’s unemployment rate remained at a record low level in May, while the number of nonfarm jobs rose to a record high, the state said Friday.The jobless rate remained at 3.8%, the same as in April and the lowest since records were kept dating back to 1976. The unemployment rate is 0.5 percentage point lower than May of last year, the Department of Labor and Industry said. Those jobless rate figures are adjusted for seasonal hiring factors.By comparison, the [...]

Source Business - poconorecord.com http://bit.ly/2J35whI

“The Simple Dollar” Is Not “The Easy Dollar”

Most of the strategies I write about on The Simple Dollar are quite simple for most adults to understand. They’re not complex ideas. They’re not difficult to understand. They’re not challenging to visualize. They are things that almost all of us can do – some might require us to have a little bit of money in hand first and use that to grow more, but most don’t. Most of the techniques are just refinements of things people do all the time in ordinary life.

Personal finance success is not rocket science – it’s the furthest thing from it.

Spend less than you earn. Do something smart with the difference, like contributing to your 401(k) or paying off debts. That’s pretty much the core of it. Everything else is just details, like getting better at anticipating upcoming expenses.

It’s simple… but it’s not easy.

Many things in life are simple, but not easy.

A push-up is simple. Lay on the ground, stomach down, then push yourself up off the ground until your arms are fully extended, then lower yourself back to the ground. A push-up isn’t easy, depending on your fitness level and the exact technique you use.

A solution to a Rubik’s Cube is simple. When each side of the cube is solid in color, you’ve solved it. Actually solving the Rubik’s Cube, especially with speed, isn’t easy.

Shooting a basketball is simple. Position one hand on the side and one hand on the bottom of the ball. Push off with the bottom hand, using the side hand to guide the ball just as you release it. Of course, actually consistently making baskets isn’t easy.

Eating healthy is simple. Eat mostly plants and not too much. Almost all successful long-lasting diets in the world center around this. Of course, actually doing this with so many tasty and convenient options around us isn’t easy.

Being a good friend is simple. Listen. Laugh. Be there when they’re down. Actually being a good friend, especially during the tough times, isn’t easy.

Personal finance is no different. It’s simple… but it isn’t easy.

The problem is that people often mistake “simple” and “easy.” If something is simple to understand, they assume that it’s easy to achieve or master and thus drastically underestimate what it takes to succeed at it. Then, they wander through life for a while and eventually begin to wonder why they’re not succeeding at this “simple” thing.

That kind of feeling often leads straight to frustration and anger and self-doubt. “Why can I not succeed at this simple thing?” sings the refrain in their head.

They’ve accepted that something simple must be easy, and thus failure at this simple thing must mean a deep personal flaw within themselves. That is not true, not in the least.

One can fully understand a simple thing and what needs to be done to achieve it or succeed at it, but then utterly fail to achieve it because that thing turns out to not be easy.

So, then, how does one succeed at things that are simple but not easy? How does one succeed at personal finance? How does one succeed at losing weight and keeping it off? How does one succeed at getting in good physical shape?

It’s simple.

Discipline

The things you need to do to succeed on your financial journey are really simple, but they don’t actually work if you don’t follow them. You have to make yourself follow them.

There is no magic trick. There is no easy way out. It comes down to this: can you, week in and week out, month in and month out, year in and year out, decade in and decade out, spend less than you earn?

Doing that is hard. Doing that means resisting a lot of temptations. Doing that means making tougher choices than the people around you are making. Doing that means saying “no” sometimes when your heart and gut are screaming “yes!”

In fact, I would argue – and have argued in the past – that self-discipline is the single most important element when it comes to financial success.

Back then, I wrote some pretty solid tactics for practicing self-discipline, which I’ll share again now:

1. Start now, not later.
Spend less today. Not tomorrow. Today.
Make the things you need to do to make this your new life pattern your highest priority for the next few days.
Don’t shy away from giant steps, but remember that little steps are successes, too.

2. Remove temptations from your regular environment.
Delete your passwords and credit cards from websites.
Avoid places where you might be tempted to spend money.
Don’t carry cash or credit cards with you unless you intend to spend.

3. Establish fresher routines for your day-to-day life.
Purchase more energy-efficient devices when it’s time for replacement.
Find the most efficient commute.
Renegotiate your bills.

4. Don’t get hung up on individual mistakes; instead, focus on a new day.
Recognize always that one misstep does not mean the end of your progress.
Spend time figuring out why you made that misstep and don’t just merely excuse it.
Focus on today and tomorrow – only use the past and far future as inspiration until you’ve mastered your new habits.

5. Schedule treats.
Give yourself a certain amount of room and freedom for spontaneity.
Choose “time” splurges rather than “money” splurges.
Enjoy the anticipation and the afterglow.

Discipline means that you’re always doing something to improve your financial state, each and every day, while avoiding things that undo your progress, each and every day. You’re not going to be perfect at this, but you must not excuse failure, you must pick yourself up when you do stumble, and you must press onward with the intent of not repeating those stumbles.

Sometimes it’ll come really easy. Sometimes it’s going to be really hard. That’s where the next element becomes important.

Grit

Grit is the art of persevering when things get hard. There are going to be moments when you want to be irresponsible with your money. There are going to be times when this all seems impossible and overwhelming. There are times when you don’t want to be disciplined.

That’s when grit makes the difference.

Again, I’ve written about grit in the past, though I mostly applied it to careers. The advice as it relates to personal finance boils down to this in a nutshell:

Dream up a big goal. Break it down. Automate your steps toward that goal. Motivate yourself at work, internally and externally. Push through when it’s tough and rely on that automation.

When it’s tough, what do you do? You focus on today. You take care of what needs to be taken care of today. Yeah, it might feel like you’re going through the motions. Go through the motions. Yeah, you might be tired of this. Do it anyway. Focus on the absolute very next step and push yourself through that. Nothing else matters.

What if focusing on today feels like an intense struggle? Focus on the very next action – nothing else. What do I need to do next? What is the very next thing I need to do to keep all of this moving forward. Execute that, then see how you feel once you’ve moved forward a bit.

Grit works well for getting you through the tough moment. More is needed to continually move forward.

Routine

One of the most powerful ways to maintain discipline in your life is to make a day-in-day-out routine of it, so that the ordinary routine of your day moves you step by step toward your goal. You need to create a situation so that your default ordinary day moves you a step or two closer to where you want to be.

It’s simple to see how this works when it comes to things like exercise. You simply have a block of time where you get some exercise in. Maybe you work to establish a routine where you get up half an hour earlier than you used to so you can spend half an hour each day doing some kind of vigorous bodyweight exercises, focusing on specific muscle groups every other day and doing it with an intensity so that you’re out of breath. You do this day in and day out until a day doesn’t feel normal if you don’t start off with this routine. It’s your normal.

It’s simple to see how this works with food intake. Just come up with a few simple dietary rules and follow them constantly. For example, you might aim to keep yourself at 1600 calories a day, with at least 800 of them coming directly from plants. Do this day in and day out and it will eventually start to feel normal.

How does this work for money, though? Perhaps you establish a routine of eating every single meal at home. You establish a routine of thirty minutes of meal prep a day, which should be more than enough to have simple tasty meals at home. Step by step, this routine improves both your finances (by reducing the average cost of all of your meals) and your cooking skills (making home food preparation even tastier and more efficient).

Maybe you establish a grocery shopping routine that starts with the grocery store flyer and an examination of your pantry, continues with creating a meal plan and then a grocery list from that meal plan, and then heading to the store with that list. Grocery lists cut down drastically on unplanned (and often wasted) purchases at the store.

Perhaps you establish a routine of simply buying everything in store brand form that you possibly can, and stocking up when you spot a sale.

The goal of such a routine is to emphasize one end or the other of the “spend less than you earn” equation, and often it’s on the “spend less” side of the balance. However, it really only works if it’s a routine. From now on, it’s how you do these things. You don’t toss out meal planning and grocery list preparation because it seems like too much work. That’s what grit is for – you buckle down and stick to your routine. Eventually, and this takes several months, it starts to seem normal.

What if you want to take routine to the next level?

Automation

Automation is a great tool for establishing and maintaining a routine oriented around saving money or moving money from one account to another. It just removes the need to do it manually; instead, it happens automatically.

Automation can save for retirement automatically. Automation can build up an emergency fund automatically. Automation can make extra debt payments automatically. It’s just a simple matter of contacting your workplace’s HR or your bank and setting up the right regular transfer.

This might seem simple, but it takes commitment as well. Almost every automation you do drains money from your paycheck or from your bank account for some higher purpose, but with that comes an inherent pledge to cover the rest of your expenses with what’s left in your paycheck and in your account. Automation is powerful, and it’s a great way to ensure that you stick to a routine, but it still requires you to be able to deal with the rest of your life without the money you’re automating away.

Again, it’s simple, but it isn’t easy. Here’s another piece that’s simple but not easy.

Good Social Support

Social support is vital for making changes to your life, but not in the way you might initially think. It doesn’t come from announcing your big upcoming goals to your friends, as that won’t actually help very much and is likely to actually backfire on you.

Rather, good social support comes from surrounding yourself with people who have very similar goals and routines as you and are even willing to work together to help each other achieve those goals and maintain those routines.

Much like it’s easier to keep going to a fitness class if you have a bunch of friends in the class or how it’s easier to go for a jog in the morning if you’re meeting a friend, it’s easier to stick with good spending routines if you surround yourself with people who have good spending routines.

If you have friends who share the same priorities, you don’t have to shout your goals at them or even tell them at all. Just simply emulate what they’re doing and talk about those efforts. If you have friends that are all into running, you can talk about running and find people to go running with and feel supported as a runner. If you have friends that are all into vegetarianism, you can talk about vegetarianism and easily find people to eat vegetarian meals with and feel supported as a vegetarian. If you have friends who are frugal and interested in retiring early, you can talk about frugality and retiring early and easily find people to help you with frugal projects and who will be great pals when you’re both fifty and out of the rat race.

Find people who share your goals and ambitions and are disciplined about it. Establish friendships with them. Again, it’s a step that sounds simple, but is it easy? How do you find these people? Look for free community events where you actually interact with people before, during, or after the event. Look for people in your workplace who use lunchtime as a social opportunity but do so by bringing their own meals or leftovers. Check out Meetup or your library for social groups that seem to overlap with keeping spending low and get involved.

There’s one final tool you can apply to help you succeed at something that seems simple but actually isn’t very easy.

Elimination of Temptation

What are the things in your life that tempt you away from making the best choices for you and your future? Get them out of your life or minimize them wherever you can.

Do you see things you want on the television programs you watch? Cut out the television, or at least those programs. Life will go on. Do you see things you want or are envious of on social media? Cut out the social media. Life will go on. Do you find yourself wanting all kinds of stuff after reading websites or magazines? Stop visiting those websites and reading those magazines. Life will go on.

Life is full of abundant entertainment that doesn’t try to sell you on things. Go read a book or take a walk or learn how to play a musical instrument or learn how to solve a Rubik’s Cube in under 20 seconds or take up a martial art or watch a ton of classic films or… well, anything else.

Again, this circles back to routine. If part of your routine involves absorbing media that causes you to want to buy things, you need to change that routine. Delete that app. Cancel that cable service. Delete that website bookmark.

Minimize the things that tempt you in your life and you’ll find that temptation bubbles its way into your life much less often.

Simple, Not Easy

All of these steps are conceptually simple, but if there’s anything to be learned on the road to financial success, it’s that simple does not mean easy. There are many things in life that are incredibly simple to understand but incredibly difficult to actually execute in our lives.

There’s a reason why 60% of Americans essentially never exercise, why 78% of Americans live paycheck to paycheck, why most people have huge regrets at the end of their life for simple things left undone. Quite often, the simple things are the hardest to do.

Don’t sit back and just read about financial change. Do it. Make financial change happen in your life. Do it with the tools you have at your disposal. Discipline. Grit. Routine. Automation. Good social support. Elimination of temptation. Focusing on one day at a time, one action at a time if you have to.

You can do this, but you have to do it.

Go get ’em.

The post “The Simple Dollar” Is Not “The Easy Dollar” appeared first on The Simple Dollar.


Source The Simple Dollar http://bit.ly/2N6nJjT

Looking Forward to Your Next Vacation? Save on Air Travel With These Tips