

الأربعاء، 3 يوليو 2019

الثلاثاء، 2 يوليو 2019
9 Home-Based Business Ideas for Food Lovers
If you spend any time scrolling through your favorite social media channels, chances are you’ll be bombarded with an array of stunning food imagery. We’ve all become a little obsessed with food in its many and glorious forms, haven’t we? The great news is that now, more than ever, is the perfect time to start […]
The post 9 Home-Based Business Ideas for Food Lovers appeared first on The Work at Home Woman.
Source The Work at Home Woman https://ift.tt/2RQYcKd
How to Sell Food Online
The ecommerce industry is booming. It seems like everyone is coming up with different ways to get into this space.
But when we think of ecommerce our minds typically don’t jump to food. Most entrepreneurs seem to focus their efforts on inventing or modifying a new product that can solve problems
With that said, there is lots of money to be made in the online food industry.
As of 2018, the online grocery shopping in the United States is a $17.5 billion industry. But there are plenty of other ways to sell food online as well.
For example, maybe you have a restaurant and want to expand the way your customers order takeout. The global online food delivery market is growing at a 14.8% year-over-year rate.
That’s not all. Take a look at this graph from eMarketer on the projections for total online food and beverage ecommerce sales in the coming years.
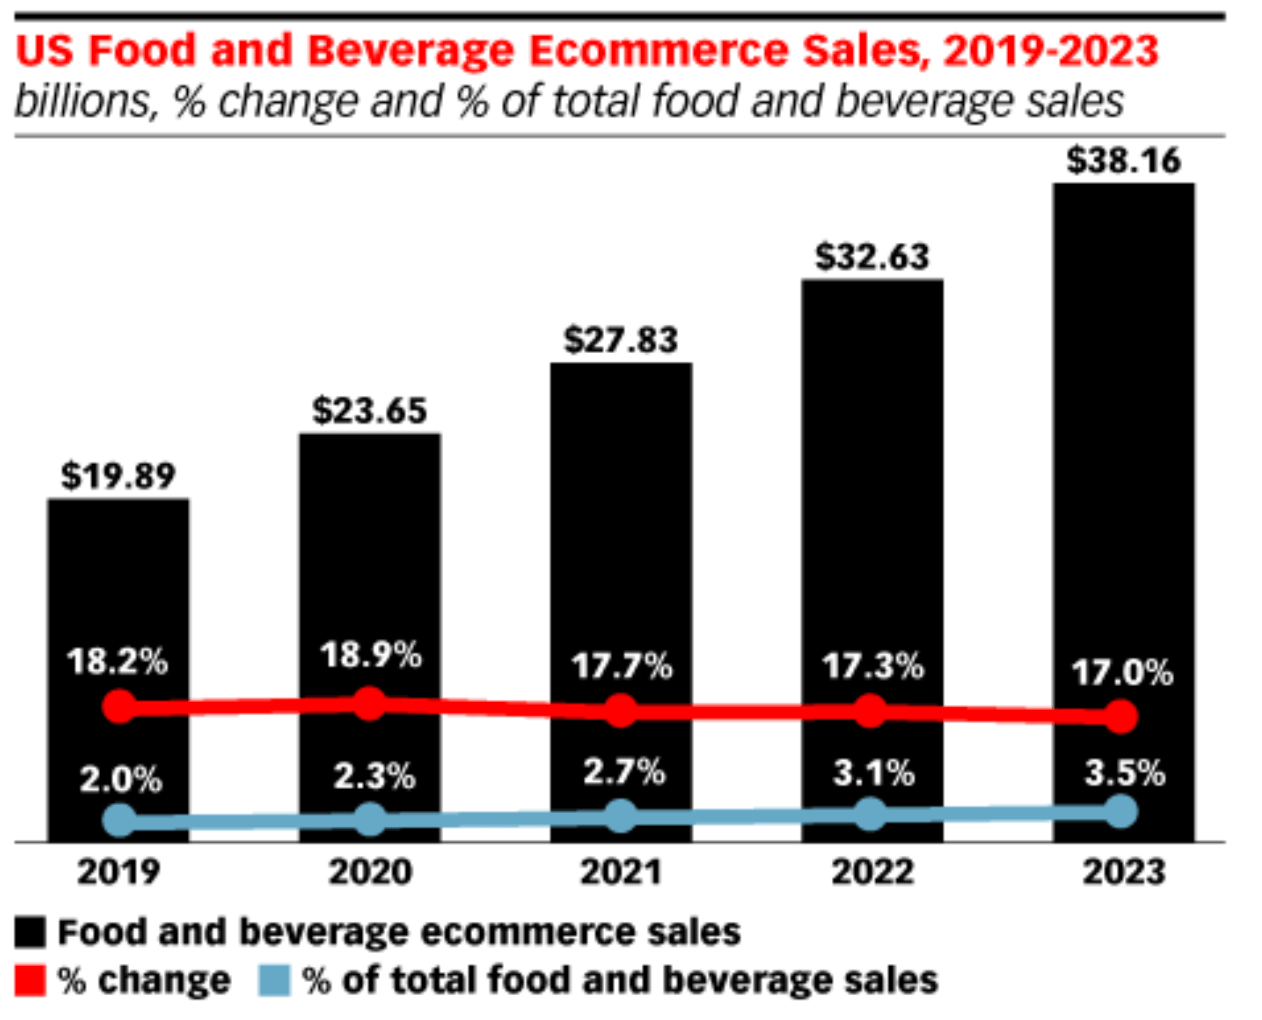
Online sales in the US alone are expected to double over the next four years. So it’s safe to say that there is plenty of money to be made in this space.
Here’s the reality of the situation. Everything in our lives has gone digital. We’re ordering everything else online, so it’s only natural that online food sales is the way of the future as well.
But when you search the web for how to create an ecommerce site, the resources for selling food online are pretty scarce. That’s what inspired me to create this guide. I’ll tell you everything you need to know about building an online platform for selling food.
Understand the law
Before you do anything, you need to make sure that you’re familiar with all of the legal regulations for selling food online. This will vary depending on your location, as well as the type of food you’re selling.
For example, if you’re selling in the United States, you’re going to have to follow different guidelines than if you were selling in Europe.
Here’s something else to take into consideration. Are you planning to prepare and sell food out of your home? Or are you selling out of an industrial kitchen?
Let’s say you were making homemade cupcakes in your kitchen at home. The rules that apply to you will be different than someone who is jarring sauce in the kitchen of their restaurant.
In the United States, you’ll need to follow the Cottage Food Laws, which vary slightly from state to state. Regardless of your location, here are some guidelines that are pretty standard across the board:
- Annual inspection from the department of health.
- Zoning permits from the department of health and/or the department of agriculture.
- Valid business license in your operating state.
- Ability to properly store food (cold, dry, etc.).
- No pets in the home or kitchen.
These are just the minimum requirements, and it barely scratches the surface. So be sure to fully review your local requirements before you start selling any food online. Otherwise, you’ll risk violations that can shut your operation down.
Find a supplier
No matter what you’re planning to sell, you need to source a reputable supplier. Whether you’re planning to sell pre-made products or if you’re cooking everything on your own, this still applies to you.
The most challenging part about finding the right supplier is establishing their legitimacy.
For example, let’s say you’re planning to prepare food in your home kitchen. Costco would be considered a reputable supplier for your ingredients. Picking apples, tomatoes, or peppers from your neighbor’s garden is not reliable, reputable, or trustworthy.
If you’d rather use an online supplier, you can try using a resource like Food Master.
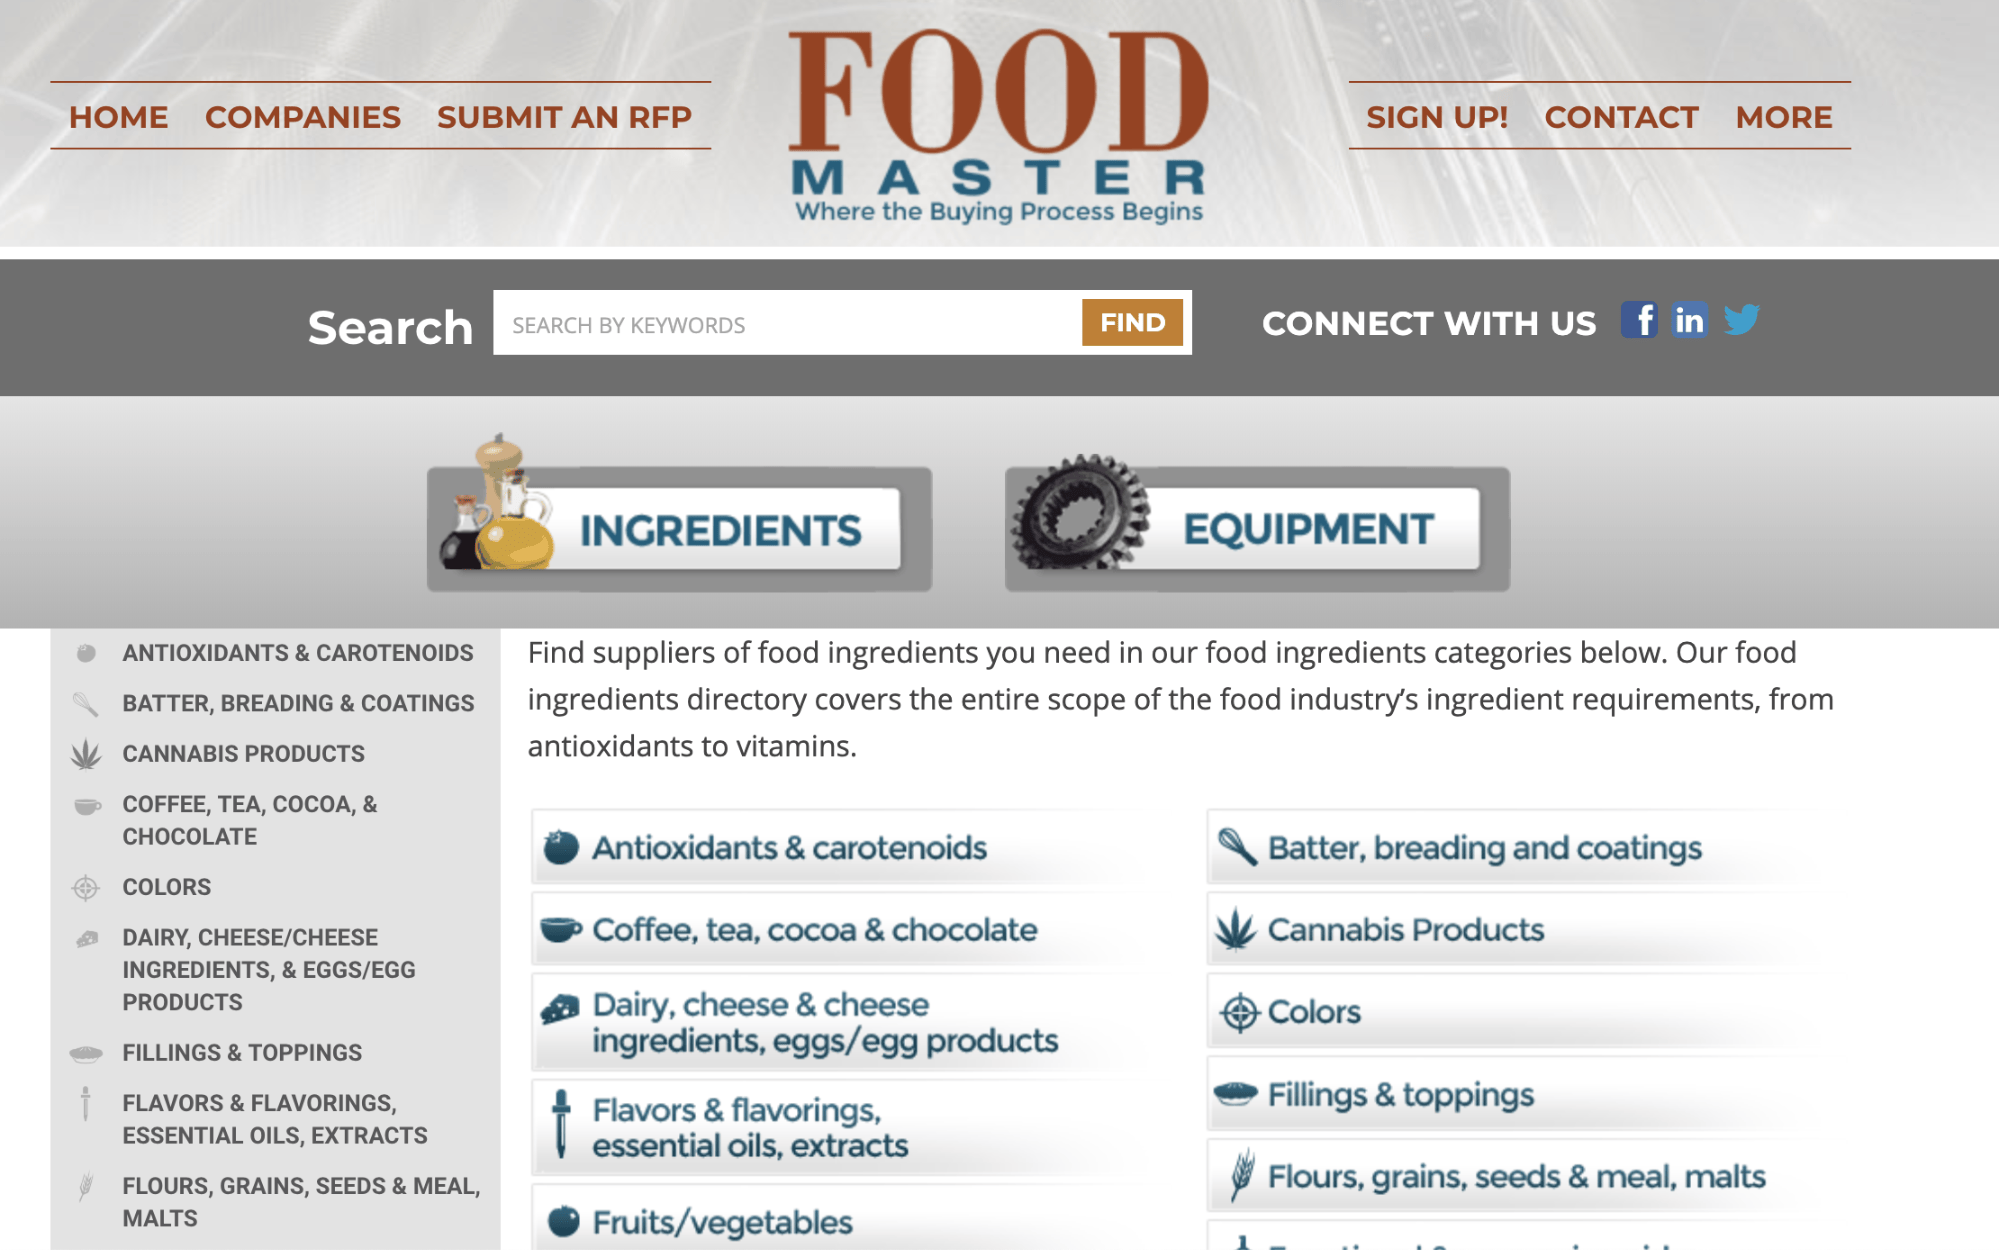
This is a massive online directory of ingredients. You can browse what you’re looking for by category, or search for specific keywords.
If you’re on the fence about a supplier’s reputation, it’s perfectly reasonable to ask them for their credentials. After all, the products you buy from your supplier will ultimately be consumed by your customers. So whatever you buy from them will directly impact your business.
Just because your supplier claims that it’s selling organic produce, it may not necessarily be true. Follow the supply chain to fact check everything.
Know your niche
Everybody eats. But that doesn’t mean that everyone is a potential customer.
This is a mistake that I see new entrepreneurs in the online food industry make all of the time. They assume that everyone will enjoy what they’re selling, and they don’t go after a specific niche.
You’ll have much more success if you can clearly define your target audience before you proceed. Then you’ll be able to make necessary adjustments to meet their needs.
For example, take a look at the meal plan options offered by Green Chef.
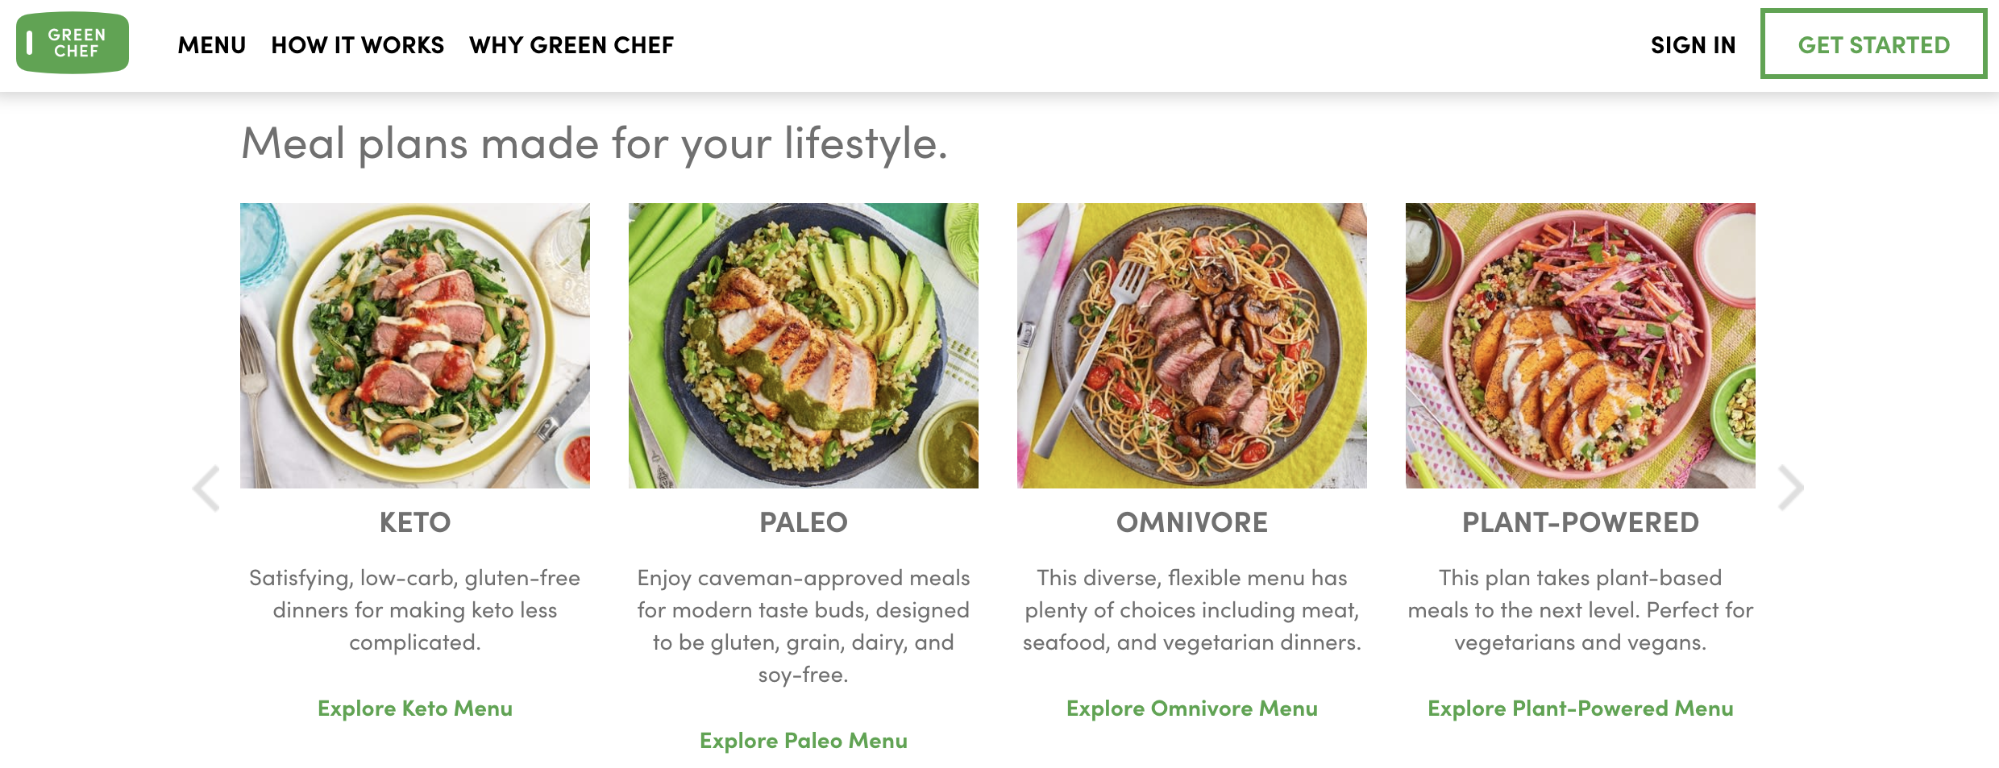
This company is targeting people with special diet needs, such as keto, paleo, or plant-based diets.
Are you going to target working professionals who don’t have time to cook? Or are you targeting families who need healthy options for their children?
Does your site want to focus on college students living in dorms? Or elderly residents who are living on their own?
As you can gather from just these handful of potential examples, the food you’re selling and the way you market yourself would be drastically different in all of these scenarios.
So rather than trying to compete in an over-saturated industry, pick a niche and run with it.
Focus on branding
Once your niche has been established, it will be much easier for you to go through the branding process. Your brand will be a combination of what you’re offering as well as who you’re offering it to.
People can buy food anywhere. Your brand needs to explain why they should buy it from you.
Think of a company like McDonald’s. When you hear the name or see their golden arches, you automatically have an association with what they’re offering. They are the epitome of a fast food burger chain. You know exactly what you’re getting and how you’re going to get it.
That’s because they’ve done an excellent job branding themselves. In the online food industry, these are the components you need to prioritize to establish proper branding.
Brand name
Your name should go far and beyond what you’re selling. This is another common mistake that I see new food entrepreneurs make all of the time.
For example, let’s say you currently sell cupcakes out of your home kitchen. You might be tempted to name your company something like Cassie’s Cupcakes.
But this name puts you in a box. What happens when you want to start selling brownies, cookies, and other baked goods? Don’t let your brand name restrict the future expansion of your company.
Use a domain registrar like Namecheap to see if the domain name for your brand is available.
If your name isn’t available, and can’t be purchased for a reasonable price, it’s definitely in your best interest to think of another name. I’d also recommend reviewing my guide on how to choose a brandable domain name for help with this process.
Colors
Your brand’s colors will be synonymous with your branding strategy.
Don’t think colors are that important? Think again. Let me give you an example to show you what I’m talking about.
Starbucks.
Without even showing you a picture of this company, their website, or their products, I can almost guarantee that a color popped into your head when you saw the name. That’s because the brand has done a great job with their branding strategy.
I’ll give you another example from the online food space. Let’s take a look at the Blue Apron website.
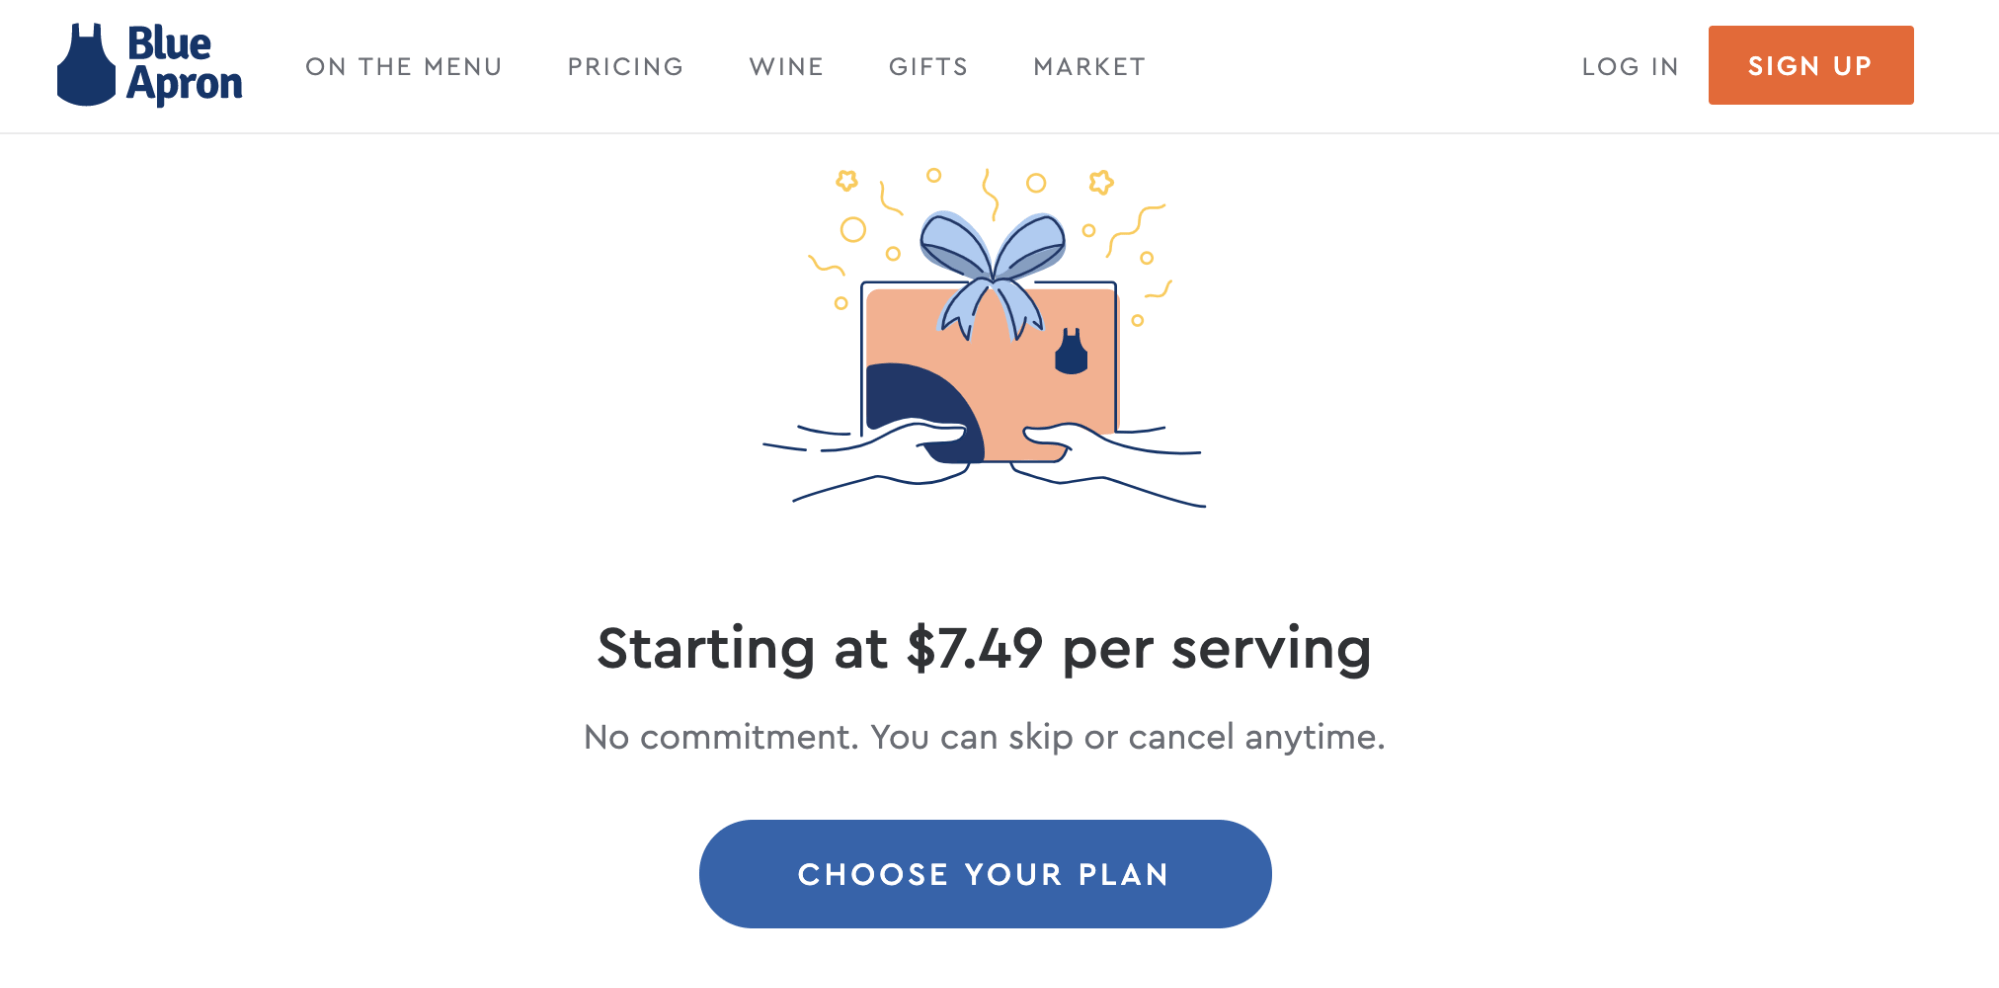
This is a fairly obvious example since there’s a color in the brand name. But as expected, the business has a blue logo and the website has a blue theme. If this company had a red or an orange color scheme, then it wouldn’t make sense.
Make sure your colors appeal to your niche. It’s also important to know how certain colors are perceived.
For example, let’s say you’re planning to sell fruits and vegetables online. Having a black or brown color scheme isn’t very appealing. It doesn’t give the perception of products that are fresh. In this case, you’d be better of going with some lighter and brighter tones.
Packaging and labeling
Like any product, the packing of the food that you’re selling online needs to be carefully thought out. In addition to having your brand name, logo, and colors integrated on the package, there are other things to take into consideration as well.
Food needs to be packaged in a way that keeps it preserved. If perishable items need to be kept cold, the packaging should reflect that.
There are also certain regulations that need to be followed for shipping foods that are perishable or fragile.
Furthermore, there are other requirements for labeling food. Your labels need to include:
- Complete list of ingredients.
- Net quantity.
- Weight of all combined ingredients.
- Name and location of the company.
- Names and locations of suppliers.
- Expiration or “best by” dates.
Some of the packaging and labeling aspects of selling food online will fall within the legal scope of your operation, which we discussed earlier.
But it’s important to find a balance between a packaging that’s appealing to your customers while meeting all of those legal requirements.
Figure out your pricing strategy
Now it’s time to figure out how your online food store is going to make money.
You can’t just pull a price out of thin air. It’s important to factor in all of your operational and business costs to ensure that your products are priced in a way that is profitable for you. Your pre-defined niche will also factor into your pricing strategy.
For example, a business professional living and working in New York City will likely be willing to spend more on a single serving than a family of five living in the midwest.
You’ve got to come up with a pricing formula that drives ecommerce conversions. Take a look at Freshly’s pricing as a reference.
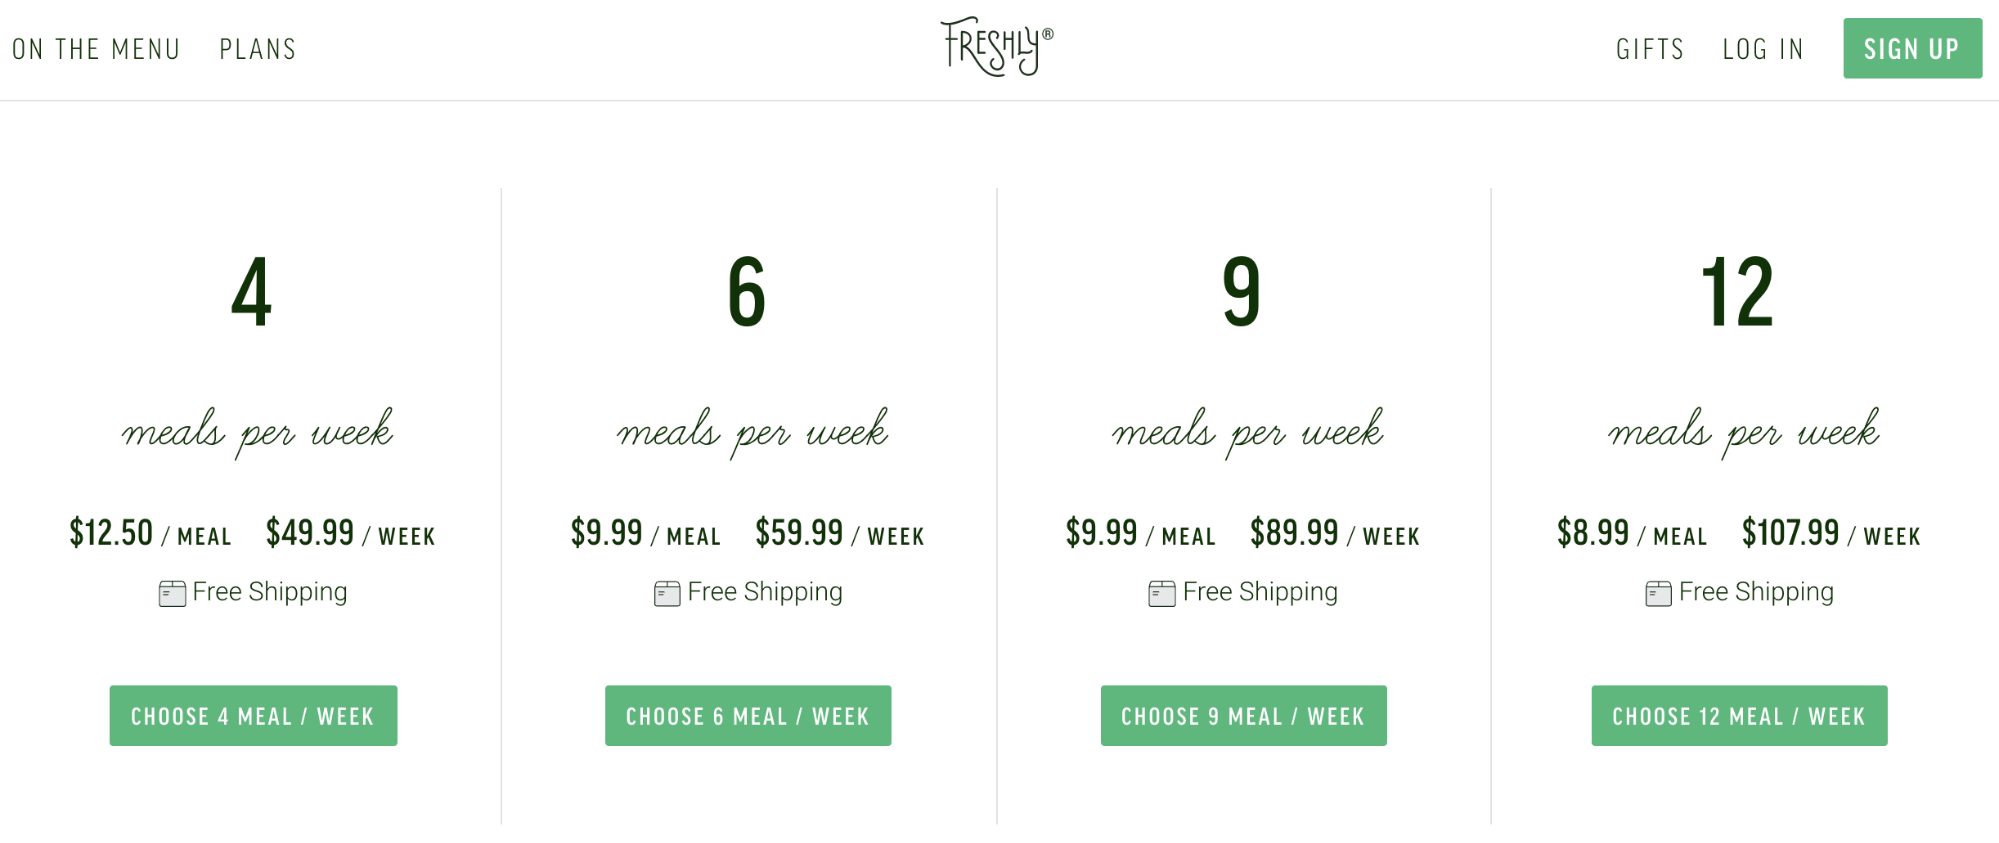
They’re using an age-old strategy, that’s not limited to the online food industry. As quantity increases, price decreases.
The cost per meal drops nearly 30% if a customer orders 12 meals per week as opposed to just 4. Sure, they’re making less per meal, but they’re getting more than double the weekly revenue from one subscription over the other.
If the cost per meal didn’t change based on quantity, then it doesn’t give your customers an incentive to spend more money.
Here’s something else to consider with the Freshly pricing strategy. All of the plans offer free shipping.
This is all related to perceived value. If you charge extra for things like shipping, it lowers the overall value of what you’re selling.
Review my guide on how to generate more profits by focusing on your pricing strategy. All of these concepts can be applied to businesses that sell food online.
Create an online store
There are two ways to sell food online. Each one is very different.
First, you can sell through online marketplaces, like Etsy or Amazon. Alternatively, you can sell through your own ecommerce platform.
If you’re going to use a marketplace, you need to meet additional regulations. These are put in place by the marketplace to protect themselves, as well as their customers. You’ll also need to get your company approved to sell through a marketplace by following specific standards.
You won’t have to take responsibility for managing a website and you’ll be able to reach an existing global audience if you decide to go through a marketplace. However, you lose some control and credibility with this method.
Personally, I’d recommend building your own ecommerce website to sell food online.
It might take a bit more effort on your end to get everything set up and running, but it gives you complete control.
In order to create your own online food store, you’ll need to choose a platform. Shopify is a great option for this.
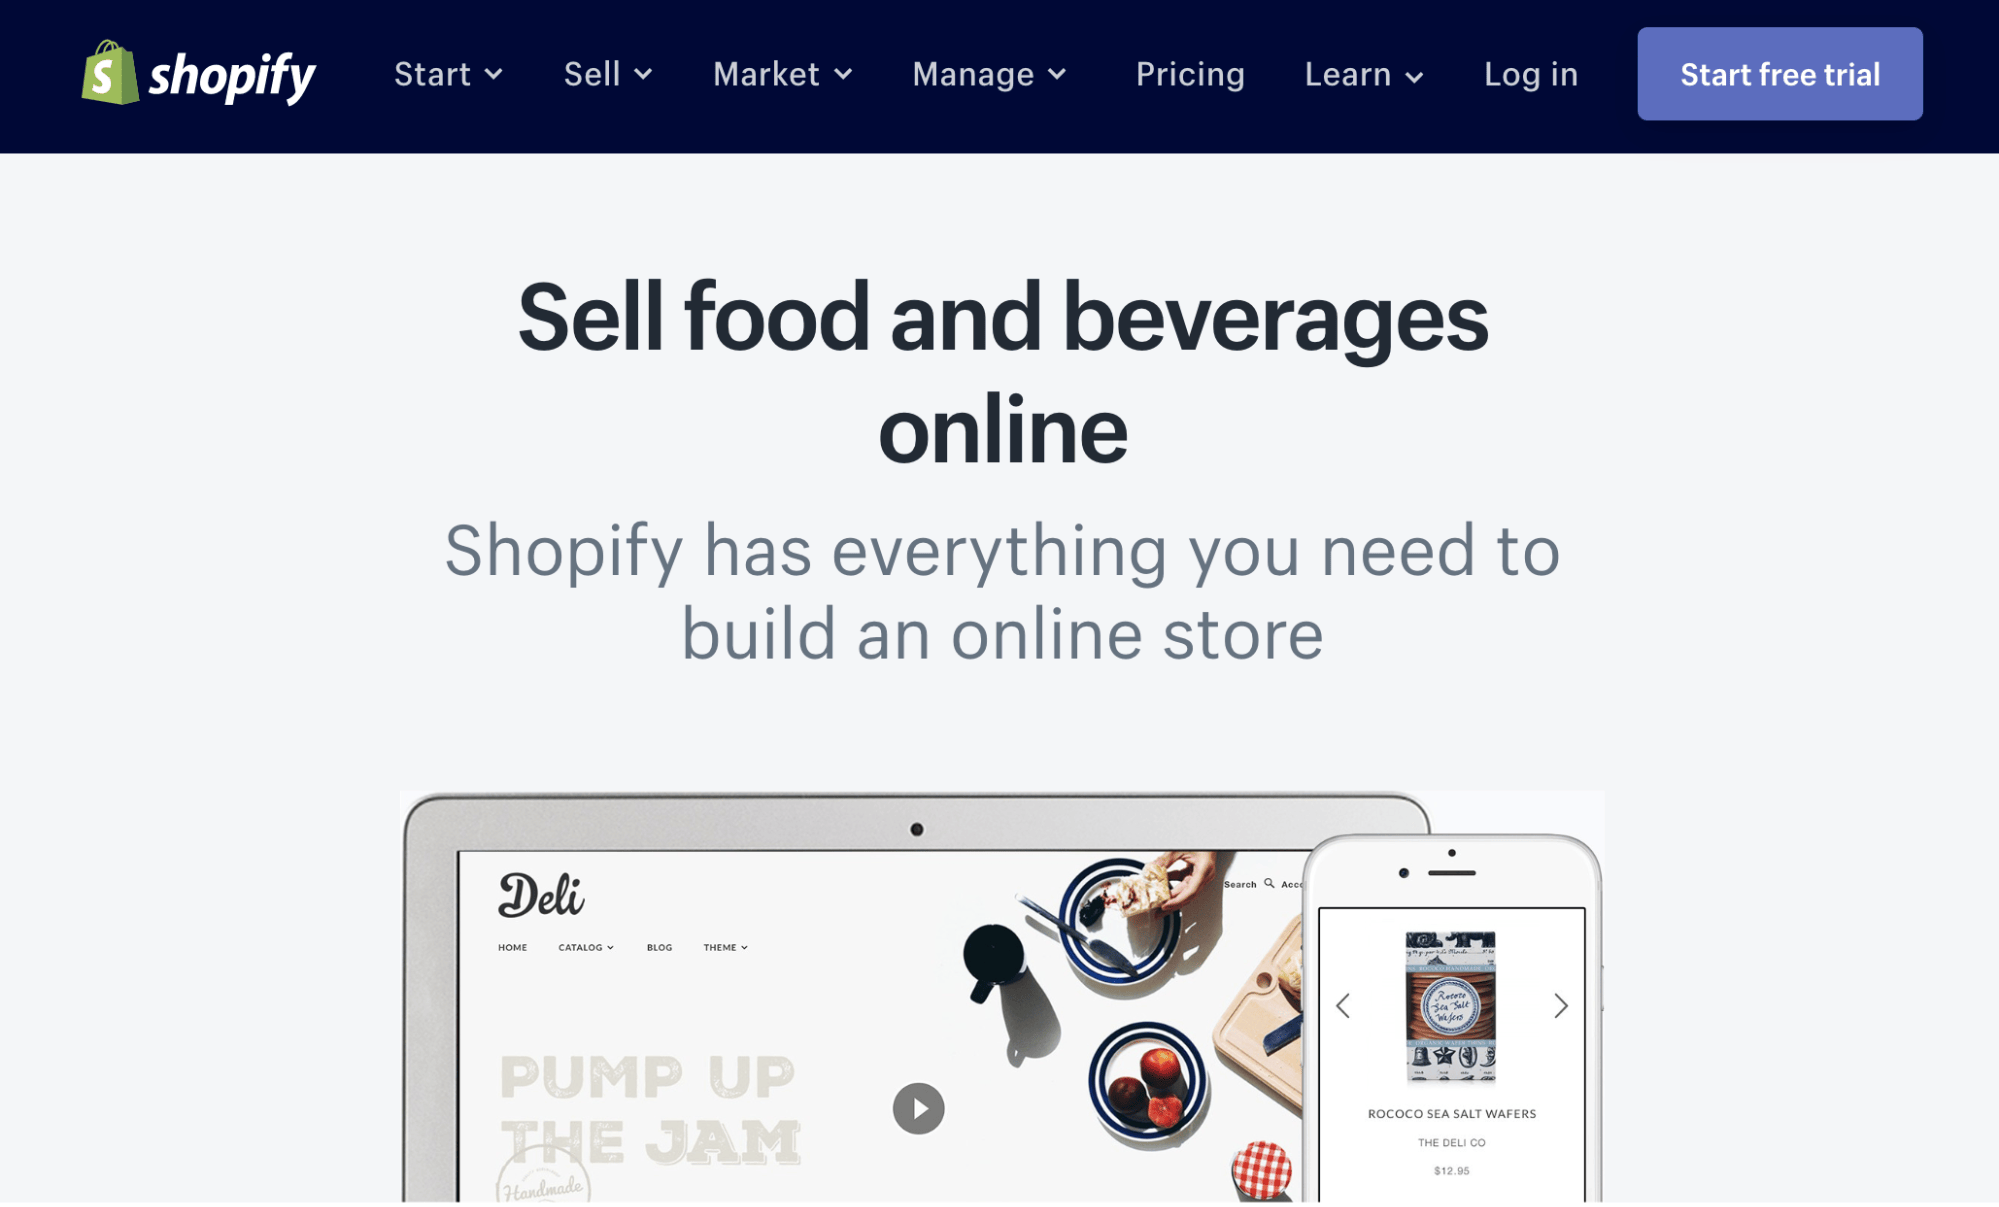
They’ll provide you with an easy to use interface, all the tools you need to track your orders, and professional templates that are specifically designed for selling food online.
If you’re not sold on Shopify, I’d recommend Wix and BicCommerce as alternative options.
Conclusion
There is a huge demand for online food. As ecommerce continues to grow and evolve, people are buying online more than ever before.
The online food industry is growing at a rapid rate. This is the perfect opportunity for you to take advantage of this situation.
But before you can start selling online, there are some preliminary steps that you need to take.
- Educate yourself on the legal side of online food sales.
- Source a reputable supplier.
- Identify your target market.
- Create a brand.
- Learn how to properly package and label your products.
Once all of that has been taken care of, you’ll be ready to build an online store. After that’s set up, you’ll be able to sell food online with ease.


Source Quick Sprout https://ift.tt/2JioWj0
Home decor chain Z Gallerie closing many U.S. stores
Source Business - poconorecord.com https://ift.tt/2KUjNRA
BECU Mortgage Rates Review: Today’s Best Analysis
Boeing Employees Credit Union (BECU) was founded in 1935 by employees of Boeing Company with the goal of helping fellow workers purchase tools needed on the job. Headquartered in Tukwila, Washington, the financial institution now provides member services for everyday banking, business banking, loans, mortgages, and investing and has an A+ BBB rating.
Metatitle: BECU Mortgage Rates Review | ConsumersAdvocate.org
Meta description: Stay abreast of BECU mortgage rates and loan options for which you may qualify.
States Serviced: Washington and South Carolina.
BECU Mortgage Facts
- Provides toolkits, calculators, and helpful online tools for members to use when interested in buying, building, or remodeling their homes, as well as refinancing their mortgages
- Offers popular home loan options like fixed-rate, adjustable-rate (ARM), home equity, first-time homebuyer, jumbo, military & special, and construction
- Extends unique mortgage loan options including FHA, land loan, VA home loan, and 30-year fixed high-balance loans, among others
- Periodically reviews members’ accounts for money-saving opportunities by assessing increases in credit scores and whether members would then be eligible for lower rates
- The BECU Home Rewards program pairs house hunters with member advocates and hand-picked real estate agents with local expertise, resulting in rebates on agent commissions, no origination fee, and cashback after closing, among other benefits
- BECU mortgages may include home buying grants and down payment assistance
Overall
 BECU has been in business 83 years and by 1989 had begun installing ATMs around the country, expanding its reach to 150,000 members and 200 employees. To this day, BECU continues to grow, with recent locations opened in South Carolina and Spokane, Washington.
As a credit union devoted exclusively to its members and their families, BECU’s services are dependent on eligibility requirements. Those include geographical location, as members must live or work in Washington, or select counties in Oregon and Idaho. Furthermore, anyone looking to sign up with BECU must also be either employees or family members of those employed at BECU, Boeing Company, or a credit union. Association with various other local institutions – CUSOs, University of Washington Alumni Association, etc. – can also secure membership.
Compared to industry standards, BECU’s mortgage options and qualifications are in line with what is expected at other financial institutions. Where it stands out is in its exceptional customer service and reputation among members.
The multitude of free resources, specialist consultations, user-friendly web options, and organizational transparency policies provide members with a more personalized banking experience.
Current Mortgage Rates
BECU Loan Specifics
The mortgage loan products offered by BECU are divided into seven categories. Based on the differing structures of credit unions versus banks, BECU specifically caters to consumers interested in becoming not just customers but members of a financial institution. As a not-for-profit cooperative, BECU returns profits to its members in the form of fewer fees, better rates, and additional personal services such as free financial education, to ensure that its members make smart financial decisions.
The mortgage loans available to BECU members include:
BECU fixed-rate loans
For prospective homebuyers expecting their income levels to remain roughly the same in the future, don’t plan on moving anytime soon, and prefer the stability and assurance of steady, predictable monthly payments, a fixed-rate mortgage may be the best choice. Conventional fixed-rate loans are available in 10-, 12-, 15-, 20-, and 30-year terms, and no origination fee applies on the original purchase or on a potential refinance.
BECU adjustable-rate loans
Homebuyers who are unsure whether they will live in the same home 10, 20, or even 30 years from now may be better suited with an adjustable-rate mortgage. Payments are typically lower during the loan’s early years, and borrowers may qualify for a more substantial home loan amount, granting them more buying power. ARMs are available in 3/1, 5/5, 5/1, 7/1, and 10/1 term arrangements. The first number in each of those pairings represent the period during which the ARM rate remains fixed, and the second number is the term during which it changes. So, a 5/5 ARM keeps a fixed rate for the first five years and then changes every subsequent five year period.
BECU jumbo loans
Jumbo loans through BECU are offered as both fixed- and adjustable-rate loans and afford borrowers the ability to finance homes that are more expensive than a conventional purchase. The Federal Housing Finance Agency sets the minimum jumbo loan amount at $453,100, though this may be slightly higher in some states with base expensive real estate costs. Buyers interested in high-value properties can opt for a 15- or 30-year fixed jumbo loan or for 5/5, 5/1, 10/1, or 7/1 ARMs.
BECU first-time home buyer loans
As the name suggests, this loan is geared toward first-time homebuyers and, through the First-time Home Buyer Grant Program, loans can be fixed, conventional or 5/5 ARM. Eligible BECU members need only to make down payments of 1%, and BECU pays the rest. Another $6,500 may be granted by BECU to help fund a down payment, and borrowers benefit from not having to pay origination fees. The design of this loan makes it ideal for younger borrowers unable to afford upfront down payments, who can benefit specifically from additional real estate agent support.
BECU VA loans
VA loans provide qualified veterans, reservists, active-duty servicemen and women, and eligible family members with financing in the form of fixed- or adjustable-rate mortgages with low or no down payment options. Private mortgage insurance is not required, and closing costs and fees are minimal. Veterans can apply their VA Certificate of Eligibility (COE) through a BECU VA loan, and flexible credit qualification guidelines make it easier for borrowers with suboptimal credit scores.
BECU construction loans
Borrowers building homes themselves can benefit from BECU’s interest-only terms during the construction phase. Once the home is completed, mortgage terms convert to a permanent mortgage without having to file additional paperwork or pay extra fees. Borrowers who hire professional builders can use BECU’s Hired Builder program, whereby mortgages may be designed to account for up to 80% of loan-to-acquisition costs, or the appraised value of the to-be-built home.
BECU HELOC
Home equity line of credit (HELOC) loans enable borrowers to access and leverage the existing equity in their homes for various financial obligations such as consolidating debt, making a significant home improvement, or purchasing other sizable assets. Through BECU, HELOCs are offered with no fees for origination, appraisal, title insurance, pre-payment penalty, escrow, and document mailing. Designed as an open-end loan, homeowners can continue to borrow against their equity as they go, rather than taking out a single sum upfront. For credit union members who are uncertain what their eventual project costs may be or who have multiple assets that require financing, a HELOC can be preferable.
BECU Mortgage Customer Experience
BECU offers a host of easy-to-find member resources throughout its website. In addition to mortgage calculators, a native “Ask a question” search bar, and helpful blog articles dedicated to each of their primary services, the financial institution’s “BECU & You” page is full of interactive resources like infographics, webinars, self-paced courses, and instructional guides. Parents can also use these to engage their children with financial-literacy tips.
BECU also conveniently provides methods with which to connect with financial advisors in a more personalized setting. One of those programs is the free Financial Health Check, which is a one-on-one, real-time consultation with a specialist who helps members take action on budgeting, savings, investing, and debt management. Appointments typically last between 40-50 minutes.
Free classroom presentations are also available to Western Washington residents and are led by BECU financial educators. Classes can be customized to high school, college, or adult audiences, with topics ranging from risk management and credit to budgeting and first-time homeownership.
These member-centric services complement intuitive appointment-booking features and simple online applications. Borrowers applying for home loans online must sign E-consent forms and be prepared for the process to take about 20 minutes. A sample checklist of items needed to apply online include:
- Social Security number
- Current address of the past two years
- Employment history of the past two years
- Income information of all kinds (salary, bonuses, commission, dividends, etc.)
- Price of the prospective home, as well as the requested loan amount
- Address of prospective property
- Bank and brokerage account information
- Basic information about existing real estate assets
- Basic information about existing debt obligations
Quotes are available via an appointment with a BECU mortgage advisor, and interested homebuyers can book online or call 206-439-5772.
BECU does not appear in annual J.D. Power Primary Mortgage Originator rankings, or in the Consumer Financial Protection Bureau’s monthly complaint report.
BECU Lender Reputation
BECU enjoys an A+ rating from the Better Business Bureau, though the online directory shows that 43 members have filed complaints against BECU since 2015. Additionally, the credit union has a 1/5 rating from members who submitted reviews online through the BBB.
Based on internal quarterly surveys of BECU members’ satisfaction and loyalty, 70% of respondents indicated they would recommend BECU to a friend or colleague. According to BECU, the average score of other mortgage institutions is just 35%.
As a credit union founded in 1935 during the height of the Great Depression, BECU prides itself on a philosophy of “people helping people.” Notable associations and accreditations include being:
- Federally insured by the National Credit Union Administration (NCUA)
- An equal housing opportunity lender
- An approved Federal Housing Administration (FHA) lender
- Certified by the Fair Mortgage Collaborative
- NMLS ID 490518
*Information collected on November 14, 2018
BECU Lender Qualifications
|
Mortgage type |
Down payment requirement |
Minimum credit score needed |
Down payment assistance programs available? |
Median income or debt-to-income requirements |
|
Fixed-rate |
0-20% |
740+ |
Yes |
NA |
|
ARM |
0-20% |
740+ |
Yes |
NA |
|
Jumbo |
20-30% |
740+ |
Yes |
NA |
|
First-time homebuyer |
1-3% |
|
Yes |
NA |
|
VA |
0% |
740+ |
Yes |
NA |
|
Construction |
30% |
740+ |
Yes |
NA |
|
HELOC |
NA |
NA – equity required |
NA |
NA |
Mortgage qualifications are unique to the type of loan, the lender, and the borrowers, among other factors. While BECU mortgage rates most often list credit score requirements of 740 or higher, those are generalized guidelines that may not accurately represent the full scope or detail of each given mortgage.
Fixed- and adjustable-rate mortgages typically require standard down payment amounts of 20-30%, although terms that include FHA assistance or mortgage insurance can bring that figure down. Additionally, VA and first-time home buyer loans are designed to provide greater access to the real estate market to those unable to produce a 20% down payment.
BECU’s many home buying programs can defray some of the costs associated with homeownership, such as waived origination, appraisal, or refinance fees in some instances.
BECU Phone Number & Additional Details
- Homepage URL: https://www.becu.org/
- Company Phone: 800-233-2328
- Headquarters Address: 12770 Gateway Dr. S Tukwila, WA, 98168
The post BECU Mortgage Rates Review: Today’s Best Analysis appeared first on Good Financial Cents®.


Source Good Financial Cents® https://ift.tt/2XiE1ea
Handling Stressful Super-Busy Periods Without Overspending
For the most part, my domestic and professional lives run along quite smoothly. However, there are a few times a year, namely April through about mid-June and late August through the end of October, that tend to be quite stressful. Our schedules compress for a number of reasons and we find ourselves often with more things to do and more things to get done than we have time to complete.
This leaves us feeling overwhelmed and often exhausted, which means that we’re much more prone to looking toward convenient options to handle some of our life’s needs. We consider eating out more often, something we rarely think about outside of those crunch times. We think about things like laundry services or even hiring a one-off housecleaner. We used to look at hiring babysitters on occasion.
The thing is, we don’t want to have these expenses, at least when we’re thinking of things outside of those moments of overextension and exasperation. It’s in those moments of overextension and exasperation, when we just feel completely overwhelmed by our schedule, that such decisions feel like a good idea, and if we recall those expenses later, it’s usually with a twinge of regret.
So, what can you do to prevent those choices? Our solutions boil down to two kinds: preventive measures and emergency solutions. Preventive measures are things we do when we know such periods are coming so that they’re easier to deal with when they do arrive. Emergency solutions are things we do during those periods to avoid extra expenses.
Let’s dig in.
Preventive Measures
As I noted above, these are things that we do before such a period to prevent them from becoming overwhelming. Here are nine such tactics.
We get fully caught up on laundry and refresh our clothes. When times are slower, we get every stitch of laundry clean in our house. We’ll pack up out of season clothes and put them in the back of the closet in boxes. We’ll get all of our nicer clothes hung and ironed. We’ll get every single article of clothing we have cleaned. If we have clothes that need to be donated because our kids outgrew them, we donate them. If we have any clothes that need to be replaced, we add the ragged ones to our rag bag and get replacements. We assess shoes and buy replacements if needed.
In short, we try to make our clothes as little of an obstacle as possible. Our goal is to make it so that everything is clean, everything fits, and everything isn’t worn to shreds when we begin to enter into a more hectic period. That way, we’re not considering things like emergency purchasing of clothes or having to consider hiring a laundry service.
We stock our pantry with the ingredients needed for a bunch of simple meals, like pasta and sauce, as well as all household supplies. We usually try to have ingredients for a bunch of quick meals in the pantry as we enter a busy period. This means we have lots of pasta, sauces, diced tomatoes, rice (which is easily cooked in a rice cooker), and so on in the pantry for easy use. This allows us to quickly make a number of simple pasta meals, stir fries, casseroles, and other things at the drop of a hat.
We do the same thing with household supplies, making sure we have plenty of things like dish soap, laundry soap, hand soap, shower soap, toilet paper shampoo, toothpaste, floss, and so on. We watch for sales on the store brand version of these items and stock up on them so that we have plenty in the cupboard.
We do a thorough maintenance run on house, automobiles, and appliances. I follow a maintenance checklist from a homeowners guide we received when we first moved in (as a housewarming gift) and when I know things are going to get crazy in a month or so, I take care of all of the maintenance through that period, including things like changing the furnace filters and checking windows for leaks and so on. I do the same with our cars, where I follow the checklist in the owners manual and do any tasks I can easily do myself and have the shop handle other tasks. I also give our major appliances a quick check to make sure they’re doing well.
I do this so that the odds of a major issue during an already busy time in our life is minimal and so that I don’t have to deal with things like a “maintenance due” light when things are already crazy. It doesn’t take all that long to do these things and it just reduces the chance of yet another unexpected (and undesired) issue during the crazier times.
We do a bunch of meal prepping to fill our freezer with additional meals that just need to be pulled out of the freezer and cooked. I get really into “meal prepping” during the slow times so that I can refill the freezer with ready-to-go meals. I make things like pans of lasagna, pans of tuna casserole, bags full of all of the ingredients needed for a slow cooker soup (back to that later in the article), lots of frozen burritos, and a lot of individual meals that can easily be heated as needed.
I love it when our freezer is clear full of individual and family meals that can be grabbed and cooked as needed. With family meals, it’s usually better to grab it and let it thaw in the fridge for a couple of days before cooking in the oven, but most individual things can go straight to the microwave.
We do deep cleaning of the house so that it will survive times when we can’t really invest the time to do deep cleaning. We scrub the floors and clean out all of the weird corner areas and scrub the tiles behind the sink and clean out the fridge thoroughly and so on. Basically, we want to get our house looking as nice as we can and as deeply cleaned as we can before things get hectic.
When things are hectic, we mostly do surface cleaning for a while, things like a quick vacuuming and sweeping the kitchen floor and wiping down countertops and keeping the dishes done. That kind of cleaning is pretty quick, and if we know that deep cleaning was done fairly recently and will be done again in the fairly near future, it’s enough. I don’t worry about an imperfect fridge in those situations.
We eat healthy, get exercise, spend time outside, and get plenty of sleep. Basically, we make sure all of the little things that ensure plenty of energy and good health are thoroughly taken care of. It’s never a guarantee of personal health, of course, but it drastically decreases the chances of a major illness when we’re stressed out and busy.
We go on a ton of walks in parks when things aren’t as stressful. We eat as healthy as I can with lots of fresh fruits and vegetables. We get plenty of sleep – I usually aim to go to bed early enough so that I awaken naturally without a need for an alarm clock. I go to a ton of taekwondo sessions (which is my preferred fitness choice these days) and do a ton of exercises at home that complement it. In short, I usually get near the end of a slow period feeling great.
Sarah and I give each other a lot of blocks of “me time” where we can each engage in personal hobbies. We both have solitaire hobbies and hobbies that don’t interest the other that we like to engage in, so we let each other engage in them. Sarah will spend a day doing something she enjoys and I’ll take care of any responsibilities that come up, and then she’ll do the same for me.
This type of leisure time is a great extension of the “health” steps I describe earlier. They’re extremely effective at keeping our stress levels low – I like to call them “stress absorbers.”
As soon as schedules are available, we put every detail we can into a central calendar system that we can both access. If I have a long practice schedule for an upcoming event for any member of the family, I enter it into a Google Calendar that Sarah and I have read-write access to and the kids have read access to. We also record this info on a paper calendar on our wall, and, in addition, we have an ongoing whiteboard that we refresh each week that draws upon the upcoming week’s events from the calendar.
Being proactive with this data is an enormous time saver later on. Simply having everything ready to go in our calendar for the next few weeks makes a huge difference when times get tough.
We maximize time spent on volunteerism and other commitments so we can dial back a bit later. Our family is in a number of community organizations and volunteer groups that usually need some commitments. In general, we try to schedule our commitments during the months when things are less busy so that when things are more busy, we don’t also have those commitments.
For example, our local food pantry asks volunteers to work one shift a quarter (they have a lot of volunteers), so when I’m on the volunteer roster, I’ll ask to do my shift outside of the boundaries of these busy periods, or I’ll trade my shift with someone else well in advance.
We take care of work tasks in advance. If there’s any extra work that can be done now instead of later, we do it now. I’ll write posts to “bank” for busy upcoming periods and I’ll also brainstorm and outline articles that I probably won’t use for a month or two. This lets me get content finished quickly when times are really busy.
Sarah is a teacher, so she’ll get test forms made and copied and make handouts and lesson palns and things like that well in advance of our busiest times so that she doesn’t have to deal with those matters later on.
Emergency Solutions
Those advance tactics help us a lot when we know things are coming, but what about when things arrive? Here are nine tactics we use to keep us from giving into expensive convenience spending during the busiest periods.
We communicate clearly about the reality of things with each other and with our children. We communicate a ton about everything during these periods. There’s tons of texting, tons of face to face conversations, and tons of talk as we’re going to sleep or getting up in the morning. These conversations are all about the minutiae of what just happened and what’s about to happen, but it’s also about how we’re feeling and whether we’re feeling overwhelmed. Understanding how we’re each feeling can really help with making these times go more smoothly.
We also aim to communicate thoroughly with the kids for similar reasons, so that they have a very clear understanding of what the next day or two will look like and so I know if they’re feeling overwhelmed or there are any other issues going on. Communicate, communicate, communicate.
We prioritize adequate sleep, because without it we’re not very efficient and prone to all kinds of mistakes. This might seem like an unusual thing to do during “crunch time,” but I’ve learned over and over again that I’m way less productive and way more prone to making massive screwups if I’m tired. I do things at about half speed and then things get messed up if I try to hurry at all.
I am far better off getting a couple more hours of sleep and then addressing the day’s challenges with a thoroughly refreshed mind and body.
We make incredibly simple meals. Our meals during crunch time are deliberately very simple. Here’s one of them: take a box of pasta, a bag of frozen vegetables, and a jar of pasta sauce. Put the pasta in the pan with the frozen vegetables, the sauce, and four cups of water, raise to a low boil, and simmer for about 15 minutes until the water is almost entirely absorbed. Serve. That’s it. It’s our super simple pasta bowls.
Or put some rice in the rice cooker and start it, then an hour later or so put some mixed vegetables in a skillet with a bit of oil over high heat and stir vigorously until the vegetables are cooked, then add the sauce and coat the vegetables, then serve it with the rice. That’s it.
We aim for those simple meals because they don’t take long and they can be done with almost no thought at all. They’re very handy for super busy evenings.
We use the slow cooker. A lot. Another meal strategy that keeps us from eating out is heavy use of our slow cooker. In fact, we actually have two of them, just in case one needs to soak with hot soapy water while we’re prepping another meal in the other one.
We often just use the bagged meals that I discussed earlier, where I put all of the items for a slow cooker meal in a gallon freezer bag or other large container. These can just be dumped into the slow cooker and turned on low for several hours, sometimes with some water added, and that’s it.
In any case, a slow cooker meal usually means people can just arrive home and eat whenever it’s convenient for them, as there’s usually a three hour window or so where the meal is perfectly good and ready to be consumed as desired.
We start dishwasher loads and laundry loads before the workday begins, then put them away when we’re home (usually when supper is in the oven). Quite often, I’m starting a dishwasher load or a laundry load as I’m waking up the kids and getting them started in the mornings. This load runs and I’ll either unload it at lunchtime (or move clothes to the dryer) or just do it in the evening when there’s a window of time.
This takes these tasks out of super busy evenings and moves them to other parts of the day when I can multitask with other simple tasks, like getting the kids up and getting ready for the day.
We do minimal house cleaning until the weekend. If you come to our house on Thursdays or Fridays during these busy periods, it looks like a dump unless someone had a bit of free time and some extra energy during the week. We usually have everyone in the family do 10-15 minutes of blitz cleaning right after supper most weeknight evenings, but most of the cleaning waits until the weekends.
Since we commit to doing much deeper cleans during the less busy times and we do “blitz cleaning” each evening with all hands on deck, it doesn’t get too bad, but there are often undone tasks like taking out the trash in the bathroom and so on that just wait until Saturday.
We do “week preps” on Sunday, where we lay out clothes and other necessary items in outfits for the whole week. I find that having all of my clothes ready to go in complete “outfits” on Sunday is a huge time saver for me, and having things on my dresser for specific days is another huge time saver. I don’t have to worry about finding clothes or laundry or anything – my clothes are right there.
This system has somewhat rubbed off on family members. Knowing that your outfits are ready to go for the week is a surprisingly huge boon.
We cooperate with parents of other children that are in after school activities to minimize time invested in picking up and dropping off kids. When our kids are in the midst of a sports season or a choir season or a series of practices for a concert or in some other activity, we network with a few other parents in those activities to share rides. We swap cell phone numbers and work out arrangements for alternating pickups and drop-offs.
For us, there are two other families in our town with which we have a lot of activity overlap, so we share a ton of rides and other conveniences with them. It saves us both a lot of time to know that we only have to worry about picking kids up from the practice on Thursdays and they’ll just be delivered home like magic on Tuesdays.
We block off time at least once a week to spend time outside and moving around as a family. We find a period of time where we’re all available, usually on Sunday, and all of us go do something together, usually outside and usually involving moving around. We’ll go on a hike or we’ll go on a long walk or we’ll go play soccer in the park.
The goal of this is to have a period of time we can spend together that doesn’t involve being dead tired in the evening or isn’t in the car on the way to an activity. The fact that it often involves sunshine, fresh air, and exercise makes us all feel a lot better, too. I consider it essential for busy-time sanity.
Final Thoughts
The purpose of all of these steps is to ensure that things flow as smoothly as possible during the busiest times in our house, with minimum chances of big unexpected events and also minimum desire to throw money at problems just to get them out of our way. Most of these tasks just shoehorn on top of things we’re already doing, like planning and shopping for the pantry and for bulk meals during our normal shopping runs, and they have other benefits, too, like helping us feel healthy and de-stress during trying times.
The end result? We very rarely spend money on things out of pure convenience, even during the busiest times of the year, and that really helps us keep our finances in good shape.
Good luck!
The post Handling Stressful Super-Busy Periods Without Overspending appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2J4BPy2
الاثنين، 1 يوليو 2019
Achieve Better Time Management in 20 Minutes a Day
As long as I can remember, I've been a neat freak. My closet, bedroom, desk, and dresser drawers were always tidy and organized with meticulous care. This trait followed me wherever I went. I remember one day, looking at the stickers at Target, and they were all out of order. Not being able to stand […]
The post Achieve Better Time Management in 20 Minutes a Day appeared first on The Work at Home Woman.
Source The Work at Home Woman https://ift.tt/2JkCevb
Stroudsburg's Philly's Pub to get facelift
Source Business - poconorecord.com https://ift.tt/2KOefYw
Guardianship for Young Adults with Disabilities: What to Expect and How to Afford It
As a parent or guardian of a young adult with disabilities, you know full well that your child may or may not need help making important decisions, financial or otherwise. There’s no one-size-fits-all solution to special needs guardianship, but there are there are degrees of need when it comes to guardianship.
This guide will help you know what to expect financially if you do decide to become a guardian of your child or loved one. It’s sometimes tricky to be sure you’re making the right decision for everyone, but this article will guide you through how parents and other interested parties can become legal guardians of a young adult with disabilities.
What is guardianship?
As soon as a young adult turns 18, parental authority no longer exists. You must then decide whether to seek guardianship, or decision-making authority for the child. The person given the authority to make decisions is called a guardian. Financial decisions can be some of the most challenging for a disabled young adult. Managing bank accounts, investments, small and major purchases and more are some of the most valuable ways in which a guardian can help an incapacitated person.
There are good reasons why you may want to be the legal guardian of your disabled young adult if you’re a parent (or even if you’re not a disabled young adult’s parent). Specifically, a guardian is appointed by the courts, and the laws are different in every state. Once a disabled young adult has a guardian appointed to him, he’s then called a “ward” or “respondent.”
There are two types of guardianship: guardianship of the person and guardianship of financial matters, says says Margaret “Pegi” S. Price, J.D., a family lawyer and is the author of the book, “The Special Needs Child and Divorce: A Practical Guide to Evaluating and Handling Cases.”
Guardianship of the person
Guardianship of the person involves making decisions about and managing the person’s care. Guardians (who can also be called conservators) must act in the ward’s best interests. The powers and duties of a guardian or those which the court may grant to a conservator include, but are not limited to:
- Deciding where the ward will live.
- Administering to a ward’s comfort and maintenance needs, including food, clothing, social and recreational requirements and other day-to-day matters for the ward’s comfort and well-being.
- Taking care of a ward’s personal effects, such as clothing, vehicles and more.
- Making day-to-day decisions about medical or other professional care, treatment or service.
Guardianship of financial matters
Guardianship of the financial matters is also called a conservatorship. This guardian will use the ward’s assets or income to pay the ward’s bills and apply for government assistance like Social Security disability benefits (SSDI) Supplemental Security Income (SSI), Medicaid or Medicare, as well as other programs. This guardian will handle insurance issues and all other financial matters on behalf of the ward, including the power to approve or withhold approval of any contract involving finances.
Don’t wait until age 18
Many families think they don’t need to worry about these factors until a disabled child turns 18, but that’s not true.
“What happens if something happens to the parents before the child turns 18? We also make the mistake of assuming that because the child has a disability, the child needs a guardian,” Price says.
Not every child who has disabilities needs to have a guardian. If the child is able to make good decisions, then he or she may not need full guardianship. Price cautions those considering guardianship not to assume that because there’s a disability “label” or diagnosis, that there should be a cookie-cutter approach to everyone with special needs.
“Just because a person has a disability doesn’t mean they can’t think for themselves or make a decision. They might actually be a genius at financial matters but not be able to figure out how to keep groceries in the house. Some need help with daily things, everyday living things,” Price said.
Anyone considering guardianship must understand the full ramifications of changing a disabled person’s status to incapacitated. Once the judge finds a person incapacitated, the disabled person loses his right to enter into contracts, sign a lease, make significant purchases like a house, make a will or living trust or get a loan or mortgage.
Who can be a guardian?
A guardian must be 18 years old, a resident of the United States, not of unsound mind, not disabled and not be convicted of a felony, according to Protected Tomorrows. Public agency or not-for-profit corporations found capable by the court of providing care required and a corporation willing to accept and execute trusts may also serve as guardian of the estate.
Most states have an ordered preference of who serves as guardians of an adult child with disabilities. The preference is usually for the parents. If parents are not available, an adult sibling or other adult family member is the next best choice. If no family members are able to serve as guardian, the task may go to a close friend. If no friends are available, then the court can appoint a professional guardian.
Steps to take to obtain guardianship
A guardian might be necessary when the child is unable to make decisions in his or her own best interest or provide for his or her own welfare.
Here are the steps to getting legal guardianship:
- Fill out forms at probate court and ask for a hearing.
- The court will determine when you’ll need to be present for a hearing to determine guardianship.
- The adult child will be evaluated by a doctor or other mental health professional to determine how well you make decisions.
- At the hearing, the doctor or mental health professional will present his or her findings about the adult child’s level of competence.
- The judge will determine what level of guardianship an individual may need. Here are a few options:
| Type | Description |
| Power of Attorney | Power of Attorney (POA) is not a type of guardianship. An incapacitated young adult who is incompetent because of a severe disability does not have the legal capacity to grant anyone the authority to act on her behalf through a POA. |
| Full Guardianship | A guardian with all powers allowed by law is called a plenary guardian, or a full guardian. |
| Partial Guardianship | A guardian with only some powers is called a partial guardian or limited guardian. |
| Conservatorship | A conservatorship grants those who are court-appointed the power to make estate planning decisions for someone who is incapacitated and unable to manage his or her affairs. |
Cost of legal fees
Top of mind for many families are the legal fees they’ll incur. The full costs will depend on many factors, such as how complicated your particular case is, the number of hearings the lawyer has to attend, the amount of investigation and documentation the court requires and whether the proposed guardian and family is easy to work with.
“If the family is easy to work with, provides all the information the lawyer needs, aren’t squabbling among themselves and shows up at all the hearings — if people just act like civilized, intelligent professionals throughout, then the costs really don’t have to be that much,” says Price.
Here is a list of legal fees and their general cost, though it can vary widely by location:
Person representing the alleged disabled person: Will look at medical records, meet with the disabled person, find out that person’s wishes, meet the proposed guardian(s) and write a report: Around $3,000 and approximately $250 per hour
- Attorney fees: A few hundred dollars per hour
- Service fees (for the sheriff to personally serve the papers): About $100-200
- Court fees: $200-300 range
- Medical, psychiatric, vocational expert or some other expert on disabilities: $500-600 an hour (you can spend up to $10,000 on an expert, and when people do not agree on a guardianship, that the costs can be prohibitive).
After the guardianship has been established, court costs, attorneys’ fees for both the petitioner and the proposed ward/protected person and any ongoing guardian fees are all paid from the protected person’s estate. Guardians are also allowed to charge a fee for their services. The county court or social services department may have a policy regarding paying for some of these costs if the ward has no money to pay for guardianship services. Review your financial situation regularly to determine how you can best afford to take care of your loved one.
Affording the costs
In the vast majority of cases, the family members (usually the parents of the ward) pay the legal fees and court costs for guardianship, though some charitable organizations cover or help with the costs of guardianship.
Social Security Disability Disability Insurance (SSDI) and Supplemental Security Income (SSI)
Social Security Disability Insurance (SSDI) offers benefits to those who are disabled or blind and are “insured” by workers’ contributions to the Social Security trust fund. These contributions are based on the disabled person’s earnings as required by the Federal Insurance Contributions Act (FICA). The amount of your monthly disability benefit is based on your lifetime average earnings covered by Social Security.
Supplemental Security Income (SSI), on the other hand, is a federal income supplement program funded by general tax revenue. SSI is designed to help aged, blind and disabled individuals who have little to no income and provides cash to meet basic needs for food, clothing and shelter.
Health care
The low-income aspect of Medicaid requirements can make it the best and most affordable option for health care for disabled young adults. Medicaid provides basic medical care to low-income individuals. Most states also have Medicaid programs covering residential, day care, career and other services.
Personal loans
A personal loan is one way you can pay the costs of guardianship. You’ll need to prove that you’re a good candidate to pay back a personal loan through a credit check. Personal loan is an unsecured loan, which means you don’t have to put up collateral (like a car or house) to get one. Fixed interest rates, good credit scores and fixed monthly payments are some of the main characteristics of a personal loan and can cover some of the costs for guardianship or other needs for the disabled young adult’s care.
Consult legal aid organizations
Legal aid organization funding can help with fees or handle them completely. Legal Services Corporation (LSC) provides financial support for civil legal aid to low-income Americans. Find a legal aid organization near you.
Consider a special needs trust
You could also consider a special needs trust, which enables assets to be held on behalf of someone with disabilities without affecting their eligibility for government aid like Medicaid or SSI. For example, if a well-intentioned aunt decides to leave money to the disabled person upon the aunt’s death, the disabled person may make too much to be able to receive disability. Price recommends getting a lawyer to set up a special needs trust. “Do not use an online form. It’ll vary so much by state,” she says.
Ultimately, when you’re considering guardianship, remember to balance your child’s financial needs with your own. It’s a good idea to consult with a financial expert if necessary and talk to an estate planning attorney to consider your life insurance policy, particularly if you’re the parent of a disabled young adult.
“Always keep in mind how a guardianship or conservatorship will affect the person’s rights to act on her own behalf,” Price says. “Try to achieve what is best for the person by using the least-restrictive means possible. Do everything you can to honor the disabled person’s pride and dignity.”
The post Guardianship for Young Adults with Disabilities: What to Expect and How to Afford It appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2XeYifN
If You Really Need a Private Student Loan, Here’s How to Do It Responsibly
If you need to borrow money for college, you’ll want to start with federal student loans instead of private student loans.
What’s the difference? Private loans typically come from lenders like banks or credit unions and tend to be more expensive, while federal loans come from the government and offer flexibility, with options like income-based repayment and loan forgiveness.
However, you might need a private student loan if you can’t borrow enough in federal loans to cover your tuition and other college costs.
If that’s the case, make sure to shop around for a good interest rate. One quick and easy way to do that is through Credible. Credible is a private-student-loan marketplace where multiple lenders will compete for your business.
Whether you’re a student or a parent who’s co-signing a student’s loan, you can type in some basic information and see multiple loan offers within minutes. You can compare loan terms and interest rates, which start at 3.99% APR for variable-rate loans and 4.50% APR for fixed-rate loans.
It’s important to get the best interest rate you can find, because interest rates for private student loans can rise as high as 14%. A lower interest rate could save you thousands of dollars over the life of the loan.
If you find a loan you like, you can apply directly on the site. Plus, none of your info is shared with the lenders until you’ve chosen a lender and loan option that’s right for you.
So you really have nothing to lose by shopping around. Comparison-shopping is always a good idea, whether you’re looking for a new car, a new phone or a student loan. Credible makes it easy.
Mike Brassfield (mike@thepennyhoarder.com) is a senior writer at The Penny Hoarder.
This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.
source The Penny Hoarder https://ift.tt/323tVMX