Thousands of courses for $10 728x90

السبت، 21 سبتمبر 2019

The Fight and the Results

Almost every self-improvement goal, whether it’s straightening out your finances or losing weight or getting yourself fit or earning a challenging degree or getting a black belt, comes down to two elements: the fight and the results.

The fight is the journey to get there. It’s the work you put in. It’s the struggle against internal signals telling you to quit and encouraging you to be lazy.

The results are what you see when you win that fight. It’s the outcome you can show to the rest of the world.

The fight is internal. It’s a battle inside of you, above all else. Are you willing to overcome the resistance inside of you, the voice telling you that you can’t do this, the desire to be lazy, the negative habits you’ve built up over the years? That’s an internal battle.

The results are external. The results are what most of us want when we get into the fight. We want to have that trimmer waistline. We want to have that degree. We want to have no debts. We want to have that black belt. They’re things we can look at to tell ourselves that we did it and to show others that we did it.

There are two main approaches to winning the fight and getting the results.

One approach is to simply survive the fight, to push through it every day, to look for shortcuts to get to the results quickly, even if it’s not sustainable. Think of a crash diet or a thirty day money challenge or a series of all-nighters to finish a project. This project is often littered with shortcuts, unsustainable leaps toward the desired results.

That’s a path that will often get you some positive result fairly quickly at a specific moment in time. If your goal is to look as thin as possible for your friend’s wedding or to get approved for a mortgage or to get a particular project don reasonably well and on time or to simply get caught up on all of your bills, then the “survive the fight” strategy is probably a good choice.

The only problem is that when you merely “survive the fight,” you are virtually guaranteed to fall back from that result and not sustain it. A crash diet never leads to lasting weight loss on its own. A hyper-frugal month and selling off a bunch of stuff never leads to lasting financial stability on its own.

Why? Because you didn’t really win the fight. Rather, you just lasted through a few rounds of taking lots of punches.

“Surviving the fight” is great if you just want to be a person who looks sort of healthy for the wedding. A different approach is needed if you want to be a healthy person.

“Surviving the fight” is great if you just want to get caught up on your bills. A different approach is needed if you want to be a financially stable person.

“Surviving the fight” is great if you just want to get that report in on time. A different approach is needed if you want to be a valuable employee who naturally earns and deserves raises.

That “different approach” is all about creating a system for your life that produces the results you want. That’s where you don’t just survive the fight, but you win the fight, and the one after that, and the one after that. The results you want just magically appear, time and time again.

The problem is that it’s a lot harder to begin with (taking perseverance) and results are often slow to appear (taking patience), and we live in a society that does not seemingly value perseverance or patience very much.

So what is a system that produces results?

It Starts With Who You Are

The fundamental difference between surviving the fight and getting quick but non-lasting results versus winning the fight and getting lasting results starts with defining who you are.

Are you a financially stable person, or are you a person looking to just get their bills paid for the moment?

Are you a fit and healthy person, or are you just looking to squeeze into some clothes for a big event?

Are you a successful professional, or are you just looking to get that project done and keep skating by?

That’s a fundamental choice, and I’m not going to say that one choice is the right one for everyone. Some people enjoy a lot of life’s expensive momentary pleasures and value that more than lasting financial success. Some people want to put in the minimal effort to get a paycheck and keep their job. Some people want to look good at the wedding and eat extravagantly the rest of the time. Those are valid choices. It depends on what you want out of life.

When I started my own financial turnaround, for example, my initial aim was to just get caught up and ahead on our bills. I didn’t really have any major life changes on my radar at all. I read some specific strategies for getting out of debt, mostly Dave Ramsey stuff, and I just threw myself into those. I wasn’t a financially stable person. I was just looking to get my bills paid for the moment.

What changed? How did I decide to go from being a person who just wanted to get my bills paid up to being someone far along the path to financial independence?

It’s simple. I decided I wanted to not just be a dude who had his bills paid. I wanted to be a financially successful person with a lasting financial foundation under me. That was a key decision. I changed my vision of who I was.

What Does a Successful Person Do?

The question then becomes: what does a person who is successful in this way do every day to be successful?

What does a financially successful person do every day to move forward their financial success?

What does a healthy and fit person do every day to move forward their health and fitness?

What does a professionally successful person do every day to move forward their career?

What does a great parent do every day to move forward their parenting skills?

What does a great partner do every day to sustain a great lasting relationship?

That’s the thing: it’s an every day (or close to it), permanent thing.

Getting caught up on your bills is something you can do for two or three months and then you’re done. Being a financially successful person is a permanent change that is a permanent alteration of your daily routines.

Squeezing into those clothes for the wedding is something you can pull off in eight weeks. Being a healthy and fit person is a permanent change that is a permanent alteration of your daily routines.

That’s the key word: permanent. Going from being an ordinary person to being a financially successful person or a healthy person or whatever the case might be means that you’re going to alter your daily routines, forever.

You want to alter them in such a way that a normal day is one where you’re taking steps, either directly or indirectly, toward being what you’ve decided that you are. You’re no longer a financial train wreck. You’re a financially successful person cleaning up a mess. You’re no longer an unhealthy mess. You’re a healthy person cleaning up a mess that will eventually be cleaned up and then you’re just a healthy person.

The Misery Factor

The stumbling block that many people run into when facing this is the idea that they are consigning themselves to “misery” for the rest of their entire life.

I can’t buy anything fun for the rest of my life?

I have to eat like this for the rest of my life?

I have to exercise like this every day for the rest of my life?

If those are the kinds of feelings you’re having, one of two things is going on.

One, you value other aspects of your life more than the role you supposedly want. You love gourmet food more than you love the idea of a healthy body. You love spending on splurges more than you love the idea of being financially stable.

If that’s you, that’s okay, but accept that. You can’t do one thing and expect completely contradictory results. If you love to eat delicious high-calorie foods and want it to be part of your daily life, you should expect a constantly excited palate, but you shouldn’t expect a thin waistline. If the activities you are most focused on enjoying in life require constant purchases, you shouldn’t expect financial stability. You are choosing one life role over another one when the two are in direct conflict, and that’s okay. That’s a personal choice based on what you value.

The other possibility is that you are choosing a lifestyle change or routine that’s beyond your current capacity. Going from being almost entirely sedentary to multi-hour extreme workouts every single day is very likely to be miserable. Going from eating whatever you want to a carefully planned 1400 calorie per day diet is very likely to be miserable.

Trying to live up to such extreme change, particularly when such extreme change is a permanent one, has a very good chance of leaving you with negative feelings about the whole thing, and negative feelings are extremely damaging to personal change.

You are much better finding sustainable patterns that lead to slowly emerging positive results than unsustainable ones that can produce faster results but leave you with strong negative feelings. Why? Those negative feelings result in a big backlash where you end up just rolling back to previous patterns that you were unhappy with (but they’re probably a little less unhappy than the radical changes you added to your life).

So, let’s sum it up. If you want to win the fight and keep winning, you need to redefine who you are. If you want to win the personal finance fight, you have to view yourself as a financially successful person. That means answering the question “What does a financially successful person do each day?” and applying that every day going forward. If you find it too difficult, find smaller steps and work up to it, but you have to keep taking steps every day until that becomes your normal path. Over time, the outcomes you desire will naturally emerge from that change in your normal behavior.

So, what does that look like?

The Fight and the Results: Personal Finance Edition

I’ll use myself as an example here.

Before I started The Simple Dollar, before I even began turning things around, I was a complete train wreck in terms of my finances. I spent money constantly without any accountability, fulfilling every little desire that came to mind by throwing money at it. I stopped at coffee shops pretty much every day. I stopped at the local bookstore two or three times a week. I had a bunch of expensive and acquisitive hobbies, including golfing and video games and trading cards. Sarah and I went out to eat quite often.

While we made good money, we were a financial wreck. We lived in a tiny apartment. We both had cars with outstanding loans on them. We both had multiple student loans that added up to a pretty frightening number. We had a bunch of credit card debt and some additional loans. We also had a baby and were dealing with the expense of child care for the first time.

This all culminated on a giant mess where we couldn’t even pay our bills. We were beginning to have to walk a tightrope just to pay rent and utilities and keep enough space on the credit cards to keep living our lifestyle, and eventually that didn’t even work. We reached a point where we couldn’t pay our bills for the month.

At that point, the fight began, but my original goal was just to survive the fight. I didn’t want to radically change my life – I liked my life. What I wanted to do is reach a level of financial stability and not find us walking up to the precipice like that again.

So, I started doing a typical “fix my finances” binge. I sold off a bunch of stuff to quickly pay off a few debts. I remember selling piles of trading cards and lots of DVDs and video games and such, just to generate cash quickly to get myself out of that immediate hole. That was actually a good move, as I purged stuff I wasn’t looking at or using at the moment.

However, I also started making radical changes to my spending. I went on huge spending fasts, where I would try to avoid spending any money at all. It helped a lot in the short term, but it left me with this feeling that I was giving up too much. I was missing a lot of hobbies and having thoughts like “Is this all there is? Am I going to have to not spend any money for fun now?”

That was the point when I started to really think a lot about what I really wanted out of the future and out of my daily life. For all of that spending that I felt I was missing out on, what was I really missing? Furthermore, and perhaps even more important, what exactly does a financially successful person do with their day if they’re not on a steady diet of spending?

I started looking around for examples of such people, particularly wanting to understand what they were doing when they were in my shoes, starting out with a family and a career. I read books like Your Money or Your Life and The Millionaire Next Door. I had some really good conversations with a few mentors that I knew through my career. More than anything, I asked myself what things brought me real joy without costing me money? and what things should I be doing every day so that those inexpensive joyous things become more and more secure?

I started putting aside more time for reading and became a big patron of the library near my apartment. I started going on lots of walks, often pushing my infant son around in a stroller, because I realized I liked how it felt, and that eventually turned into going on lots of hikes and walks in nearby state parks. I started playing through some of the video games I’d accumulated and kept, not just playing them for a few hours and looking for the next thing. I started making a lot of my own meals, not just because it saved money, but because it was enjoyable and interesting and I learned pretty quickly that I could make some really tasty stuff without much of a mess.

I also realized that I made most of my spending mistakes when I had cash just sitting in my hand, so I started moving to automate a lot of the good financial moves I wanted to make. I bumped up those automatic retirement contributions. I started making automatic 529 contributions for my son and, very shortly after, my daughter, too. Whenever I saw cash in my checking account, I intentionally quelled a lot of temptations and moved a lot of it either into an emergency fund in a savings account at another bank or made a big extra payment on an unpaid debt. I stopped using credit cards entirely for a long while, cutting up a couple and leaving others at home most of the time, and I deleted my credit card numbers from online stores. I started buying everything store brand at the store and figuring out how to grocery shop effectively.

These were all obvious positive moves. They were all things that became daily or weekly routines. Most importantly, they weren’t things that made me feel miserable. If I realized I was feeling unhappy about my life and longed for something that I was doing in the past, I didn’t try to “shut it down.” Rather, I tried to understand it.

It’s because negative feelings when you’re trying to make permanent changes are a sign that the permanent change is going to fail, that you’re building a system in your life that’s destined to break down. When you make changes, they should either feel neutral (most of them) or good (some of them). If they feel bad, and you feel like you’re missing something, you need to dig into that now and figure out how to balance the change you want to make from the thing you desire and value in your life right now.

For me, that means having a hobby budget. I figured out before long that I do have a number of hobbies and that some of them do require some spending, but that I don’t need to spend a lot to feel good about it, just a little. It’s one of those situations where, over time, I figured out how much hobby spending was “just enough” to feel good about my explorations of my interests, and I put a firm cap on that “just enough” amount. I can’t afford nearly everything I might want, but I know that if I do want something hobby related and I’m patient and really figure out if I want it and search for a bargain, I can afford it without a problem and I get that pleasure.

Most days, I don’t spend a dime on anything non-essential, and the resources I do use were usually purchased inexpensively, like store brand dish soap an dos on. When I do spend money on something nonessential, it feels like a treat. I genuinely enjoy things like going out for an $8 fast casual meal with one of my friends who also works from home; we meet up for lunch sometimes just to have that contact. There’s no reason for me to have an $8 lunch somewhere every day, but on the days when I do, not only is it a social occasion, it feels like a treat.

That’s my system. That’s how I’m not just surviving the financial fight, but winning it. It’s a day-in-day-out life that is sustainable and enjoyable and each day I basically automatically move a few steps along the path to complete financial independence. I am a reasonably financially successful person and I can say that with complete seriousness, and it’s because my daily system keeps me on that path without resentment and with plenty of joy.

What’s Your System?

Whatever the challenge you face, whatever it is you want to change in your life, you have two ways of approaching it. You can survive the fight by just taking some emergency temporary action, or you can aim to win and keep winning by becoming the person you want to be and putting together daily systems and habits for success.

There is no right answer for every situation. It depends on what you want most out of your life, and not everyone wants the same things. What matters is that you decide what you want and that you move forward accordingly.

Good luck!

The post The Fight and the Results appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/30EnIFs

I Did it. I Broke up With Amazon Prime

الجمعة، 20 سبتمبر 2019

This Could Lower Your Monthly Student Loan Payment — but Is It Worth It?

Filling Prescriptions? Save Money With a Drug Discount Card

Some Thoughts on Leverage and Retirement

James writes in:

Do you have any opinions on people leveraging their retirement savings in their 20s and early 30s? You use your retirement savings to buy lots of stocks and other investments on margin, moving all of the risk to the early part of your career. Read a book about it and wanted to know what you think.

I’m not sure which book James read, but there’s a decent chance that it’s Lifecycle Investing by Ian Ayres and Barry Nalebuff, which was a hugely popular investment book several years ago and more or less recommends this exact strategy.

Basically, the authors recommend that young investors – those in their 20s, mostly – leverage their retirement investing when they’re young. Leverage simply means that you’re borrowing money in order to be able to invest more right now, with the idea that you’ll pay back that money in a few years and keep the extra returns.

As a simple example, imagine that you’re 22 years old. You’re putting away $5,000 a year into retirement, which is great, but you want to really kickstart things. So, you borrow $100,000 from someone willing to lend you money (perhaps your brokerage, perhaps a bank, whatever) and you put all of that into aggressive investments, intending to pay it back in ten years.

In that situation, you have a greater than 50% chance of making money on that move and a small chance of making a lot of money, but you have a very significant chance of losing money on that move (because you’re not making enough on the investment to cover the money you borrowed). However, if you are able to do well here, you get a huge jump start on your savings for the future.

If, for example, the loan has a 5% annual interest rate and you earn 10% a year on that money, you could pay the loan back after 10 years and still have $96,000 in savings. On the other hand, if you borrow money at 5% and the stock market only earns you 2% per year, you will owe almost $50,000 at the end of that loan (even after selling off all of your investments) and have nothing to show for it other than that debt.

What you’re doing here is moving a lot of the risk of your retirement savings to the earliest years of your savings. Those first ten years are loaded with risk, but if it turns out well, your retirement savings are very well in hand. If it doesn’t turn out well, you may have a hole to dig out of, but you’re still just in your 30s and have plenty of time to save in a more stable fashion.

On paper, this all seems like a reasonable plan, but there’s a big problem with it: the real world consequences of the downside of this are more impactful than the real world consequences of the upside of this, as compared to simply saving as much as you can and putting it into index funds or target retirement funds within your retirement account.

It simply comes down to some realizations about life.

In terms of your annual living expenses, there’s a certain “happiness point” that, depending on how you calculate it and where you’re at in American, means a significant drop in happiness if you’re below that annual income level and very little difference in happiness if you’re above that income level. Once you have enough money coming in to secure your basic needs and have enough left over for a little bit of travel and a few hobbies, additional money does not add significantly to your personal happiness. This has been an area of significant study in economics and this landmark paper by Daniel Kahneman and Angus Deaton sums it up and even identifies the approximate number – about $75,000 a year in 2010 dollars, varying widely depending on where exactly you live in the United States (much less in some areas, more in others).

The thing is, if you have a decent job and follow a more traditional route to retirement, meaning you put adequate money into a 401(k) or 403(b) or some similar plan, you’ll very likely get to somewhere near that number in retirement, especially when you add in Social Security and other benefits. Of course, “adequate money” means you’re putting in 10% of your pay per year starting in your 20s and that you’re reasonably aggressively invested up until you start getting close to retirement (just putting everything in a Target Retirement Fund matching your retirement year is probably adequate). You are very, very likely to reach that “happiness point” by following this basic plan.

On the other hand, if you use leverage and debt to invest for retirement early on, moving the risk to your earliest career years, one of two things will happen. Either you’ll do well with it and make it easier to save for retirement and potentially early retirement, or you’ll do poorly with it and find yourself in the hole for retirement savings in your early 30s, actually owing money.

The upside? You have some extra cash in retirement or you get to retire several years earlier. You probably wind up a bit past that “happiness point,” which basically means you don’t feel any noticeable difference in your personal happiness level.

The downside? You start your 30s with a big debt on your lap and nothing saved for retirement. You’ll have a harder time even getting to that “happiness point” as you have to both pay off your debt and likely “catch up” on retirement.

The upside is a little more likely than the downside, but the downside is so awful that, in my judgment, it’s not worth the risk for most people. The small amount you gain (some extra money beyond the “happiness point” or a few extra years of retirement) don’t add up to enough to counterbalance the risk of being in extra debt with no savings at age 30.

My advice? Put as much money as you can afford into your retirement accounts as early as you can. If your workplace offers a 401(k) or similar plan – especially if they offer matching – start contributing immediately. Choose a Target Retirement fund if one is available; if not, put the money into something aggressive and low cost, like a Total Stock Market Index. Then, just let it ride until you’re about ten years from retirement, at which point you should start giving it some more focused attention.

The key thing to remember is this: once you get above a certain fairly low financial threshold, you don’t gain happiness. Your best bet for happiness now and happiness in retirement is to aim for that threshold now while also working toward getting there in retirement. That means putting away a small portion of your money now, at a slow pace, and letting it build with aggressive investing so that it can be enough to help you reach that happiness point in retirement. That doesn’t mean taking on enough risk that you add a significant chance of a large amount of debt now and a total depletion of your retirement savings just so you can overshoot that happiness point by a little bit or retire a couple of years earlier.

A bird in the hand isn’t worth two in the bush when it comes to retirement. Invest aggressively, but don’t leverage your retirement, because the downside just isn’t worth the upside. Just keep plugging away. Keep the risk within your investments, not outside of it.

Good luck!

The post Some Thoughts on Leverage and Retirement appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2QjAhG9

Dear Penny: I Just Graduated. Now How Do I Tackle My Student Loans?

Dear H.,

You’re probably armed with a few copies of “Oh, the Places You’ll Go” right now, but not much in the way of cash or certainty. 

Fortunately, you’re graduating at a time of low unemployment. You picked a practical field of study. In the words of Dr. Seuss: You’re off to great places. Today is your day!

I wish I could tell you don’t worry, don’t stew. But the truth is, it’s scary when loan payments come due.

OK, enough with the Seuss talk: There are no easy ways to make student loan debt go away, as you probably know. 

Your action plan for paying off your debt will depend on so many factors: how long it takes you to find a job and how much it pays, your outstanding balance, and whether you have other debt.

Chances are good that if you have federal loans, they’re currently in a grace period, which is a temporary window you often get to find a job and get your finances together before you have to start paying for that degree. (Private lenders sometimes offer this option as well, but it varies by lender.) 

If your loans are in a grace period but are accruing interest, start making payments as soon as you can for at least the interest. But if they aren’t wracking up interest and you find a job relatively quickly, you might take advantage of any grace period to funnel the amount you’ll soon be paying toward your loan into an emergency fund.

Which brings me to my next point: Do you know exactly how much you owe and what your monthly payments will be? 

For federal student loans, use the National Student Loan Data System to access information such as your outstanding balance, loan status and who the loan servicer is, i.e., the company that manages your loan. (P.S. Your student loan servicer will always be your starting point if you have a question or have trouble making payments.) For private loans, you can find this info by getting a free copy of your three credit reports from AnnualCreditReport.com. 

You can estimate your monthly payments on federal loans using the repayment calculator at studentloans.gov. There are a ton of online calculators that can help you figure out what you’ll owe each month on private loans as well. These will give you an idea of the minimum amount you’ll need to work into your monthly budget.

When the bills come due, you could take the debt avalanche approach, where you prioritize your loan with the highest interest rate first, or the debt snowball method, where you tackle the lowest balance. While technically you’ll save money with the avalanche, paying off student loans is a long-haul journey, so if seeing a loan balance completely disappear will motivate you, the snowball method might be right for you.

But probably the best way to tackle your debt once you find a job will be to keep living like a student so that you can make progress faster. If you can avoid lifestyle inflation by living with a roommate or using public transportation, or if you can take a second job, do it. 

A final thought: With all the hype about America’s collective $1.5 trillion student loan debt, you might be tempted to look at getting rid of yours as your only priority. But your student loans are just one piece of your finances. While paying off your debt is important, saving for your future is just as vital — even if that means it will take a little longer to be free of student loans.

As Dr. Seuss said: Remember that life’s a great balancing act.

Your mountain is waiting. So… get on your way!

Robin Hartill is a senior editor at The Penny Hoarder and the voice behind Dear Penny. Send your questions about student loans to AskPenny@thepennyhoarder.com.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder https://ift.tt/2QvjTlU

Boomerang millennials forcing parents to dip into their pension pots

Where can I find a new home for my grandchildren’s savings?

Where can I find a new home for my grandchildren’s savings?

Can you suggest a similar children’s savings plan to the plan Baillie Gifford has offered? I have investments for my three grandchildren with Baillie Gifford, which are being discontinued.

I have been given the option to transfer to Hargreaves Lansdown, but l am not happy with its timetable for reinvestment of the funds.

Ray Black Wed, 09/18/2019 - 11:32
From
TL/Halifax

Before providing you with an alternative for your grandchildren’s savings plans, it is worth pointing out that the Hargreaves Landsdown offering is competitively priced, and that Hargreaves Lansdown has also confirmed that it will maintain Baillie Gifford’s low charging structure for the next three years.

In addition, there are lots more funds to choose from in the Hargreaves Lansdown stable than there were with Bailie Gifford. So, in my opinion, Baillie Gifford is not offering a terrible solution to its investors with children’s savings plans. Having said that, you will also find a lot of choice and flexibility via other platforms.

I cannot be sure from your question how these savings plans have been set up, but you may wish to consider using each grandchild’s Junior Isa (Jisa) allowance.

To do so, you will need to liaise with the children’s parents to get the Jisas set up, but once they are up and running you can save as little as £25 a month and top up with lump sums as and when you like until the £4,368 annual Jisa allowance has been reached – and with no restrictions on which investments you can hold within them.

Hargreaves Lansdown charges a 0.25% custody fee and dealing fees are £1.50 for funds and £9.95 for investment trusts and equities.


Source Moneywise - 29 years of helping you with your finances https://ift.tt/2M8nO2I

Can you explain how annuity payments work and how they are taxed?

Can you explain how annuity payments work and how they are taxed?

Could you explain how annuity products work? Looking at the comparisons in the Best Buys section of the magazine each month, is the first column of figures the amount paid out each month or is the third column this figure?

Also, when buying an annuity, is tax paid on the whole sum put forward or is tax deducted from the monthly contributions instead? Roughly how much monthly income might be attainable from an annuity of £250,000?

Helen Morrissey Fri, 09/20/2019 - 00:22
From
JP/Kendal

We give you the figures for two types of annuity: conventional annuities, which are for people with no health conditions; and enhanced annuities, which can be bought by people who may have smoked or have various other health conditions – these generally give a bigger income than conventional annuities. 

Looking at the Best Buy tables in this issue (page 81), the figure in the first column after age is the annual amount you can expect to be paid out if you bought an annuity with a level income – an income that will not change over time.

The amount in the third column is the initial annual income you would get if you wanted your income to be linked to inflation, otherwise known as index linked. This means you will generally receive a lower income at the start of your retirement, but it will increase over time.

This means it should cover increases in the cost of living, including food and energy bills.

In terms of taxation, you can take 25% of your pension tax free before you buy an annuity. Tax will then be deducted from the monthly payments.

The amount of income you can get from an annuity will differ depending on the type of annuity and which provider you choose.

However, as a rough estimate, if you bought an index-linked annuity, £250,000 worth of pension savings should generate an annual income of around £9,000 a year – this equates to approximately £750 a month.


Source Moneywise - 29 years of helping you with your finances https://ift.tt/2Ig2V4O

Bulb Energy is slow to sort out bill error

Bulb Energy is slow to sort out bill error Simon Read Fri, 09/20/2019 - 00:12


Source Moneywise - 29 years of helping you with your finances https://ift.tt/30x8l1A

Should young people ever pay for financial advice?

Should young people ever pay for financial advice? Edmund Greaves Fri, 09/20/2019 - 00:03


Source Moneywise - 29 years of helping you with your finances https://ift.tt/2IfMYeB

Booking.com still pressuring holidaymakers to book hotels, despite crackdown

Hargreaves Lansdown to scrap controversial exit fees

الخميس، 19 سبتمبر 2019

The Best SEO Courses and Guides on the Internet

By now, marketers are business owners all over the world have recognized the importance of SEO. It’s no secret that your website needs to improve its search engine ranking.

What is SEO?

The acronym stands for “search engine optimization.” Essentially, it’s the practice of driving organic search traffic to a website. The keyword here is organic, meaning you’re not paying for a top position through PPC campaigns.

More traffic, more conversions, more dollars. That’s why SEO is a crucial component of every website on the planet.

In my experience, so many marketers and entrepreneurs out there have this false sense of belief that they understand the ins and outs of SEO and how it works. In reality, this is usually not the case.

SEO is like anything else. Unless you’ve gone through practice, training, or some type of education, it’s going to be difficult to master.

Fortunately, the digital era has made it possible for you to learn SEO on your own with the help of online courses and guides. But which ones are the best? I’ve narrowed it down for you.

Who needs SEO certification?

SEO courses and guides are great for anyone, regardless of their experience with the subject.

It doesn’t matter if you’re an SEO beginner, have years of experience dabbling with SEO, or fall somewhere in-between; SEO certifications are for everyone.

SEO courses are well worth the investment. In some cases, the only investment will be your time. There are plenty of free SEO courses out there, and I’ll cover some of the best ones in this guide.

Some courses you’ll need to pay for. But again, it’s still worth the investment. The cost is marginal compared to the benefits of watching your SERPs skyrocket toward the top position.

Plus, SEO is a high-demand skill. Even if you don’t have your own website, any marketer, entrepreneur, or freelancer can make money by charging websites for SEO services.

The Best SEO Courses

Now that you understand the importance of proper SEO training, it’s time to see where you can get it from. I’ve identified the best SEO courses on the Internet today.

As I mentioned before, there’s a mix of some free and some paid options. Some courses are made for beginners, while others focus on more complex SEO components.

Regardless of what you’re looking for, I know there’s an option for you on this list.

SEMrush Academy

SEMrush

SEMrush is a big player in the world of SEO. This SaaS company sells software for online visibility and digital marketing. SEO is a huge component of this.

SEMrush has been around since 2008, before the surge and popularity of SEO as we know it today. The company started as an SEO tool and browser extension before diving into the SaaS model.

With such a strong history in SEO, it’s no surprise that the SEMrush Academy offers some of the best SEO courses out there.

Right now, they have just under 20 courses specifically focusing on SEO. These courses cover things like:

  • SEO toolkits
  • Site audits
  • Keyword research
  • Competitive analysis
  • On-page and technical SEO
  • Link building
  • SEO fundamentals

The courses and exams range anywhere from 10 minutes to 5 hours. So there’s definitely plenty of variety here.

SEMrush Academy teaches SEO with a series of video tutorials and lessons.

In addition to the lessons, they also offer several different SEO certifications. You can take an exam, and get a certification if you pass. This is a great option for marketers, agencies, and aspiring SEOs. You can use these certifications to show prospective clients that you’re an expert in different areas of SEO.

SEMrush Academy also has courses and exams on social media marketing, content marketing, affiliate programs, and PPC. So check these out while you’re on the site as well.

The best part? All courses and exams offered by SEMrush are 100% free, including the certifications.

Udemy

udemy

With more than 100,000 online courses, Udemy is one of the most popular platforms for learning something new. Online training is their specialty.

One of the reasons why I like Udemy so much is the way that they present courses on their website. Each course has ratings and reviews, so you can see what others have to say about their experience. It also tells you exactly how many other people have enrolled to date.

Some of Udemy’s most popular SEO courses include:

  • SEO for WordPress
  • SEO for local businesses
  • Keyword research
  • Site audits
  • Link building

The more advanced courses will tell you if you need to have any prior experience with certain components of SEO before you get started. So make sure you’re taking courses that align with your skill level.

Courses start at $10.99 and can be accessed on your mobile device as well.

When you buy a course from Udemy, you have full lifetime access to it, and you’ll also receive a certificate of completion.

Udemy also specializes in courses for teams. If you want training for five or more people, check out Udemy for Business. This is a great choice for those of you who run an agency. You can get your entire team certified at the same time.

Yoast Academy

Yoast Academy

Yoast is a name that many of you may already be familiar with. If you’ve read my guide on the best WordPress plugins, you know that the Yoast SEO plugin was ranked as the best overall SEO plugin for WordPress.

Yoast Academy offers SEO training courses for beginners, content SEO, technical SEO, and bundles as well.

Here are some of their most popular SEO courses:

  • SEO copywriting
  • Keyword research
  • Site structure
  • Content SEO
  • Structured data
  • Multilingual SEO

The vast majority of the courses are paid, but they do offer a free beginner training course as well.

Prices range from $39 to $349. Most courses fall in the $150 – $250 range. So if you’re interested in taking multiple courses from the Yoast Academy, your best bet is the bundle deal.

For $41.58 per month (billed annually), you’ll have access to all of the SEO courses. If they come out with new SEO courses while you’re subscribed, you’ll have access to those as well.

HubSpot Academy

Hubspot Academy

HubSpot is another well-known name in the digital marketing industry. They offer marketing and sales CRM software to businesses.

In addition to their great products, services, reputation, and blogs, HubSpot also has an academy offering educational tools for various subjects.

While HubSpot doesn’t have a large variety of SEO courses like some of the other options on our list, they have one course that covers several components of SEO.

In total, the course contains 21 videos, four lessons, and three quizzes. The total completion time is less than two hours. The lessons are broken down into the following categories:

  • Finding the SEO strategy that fits your business
  • Scaling your backlink strategy
  • SEO for blogging
  • Guest blogging

By completing the lessons, you’ll be able to evaluate and improve your website’s SEO with a new perspective from experts who know how to rank on Google.

Another reason why I love this HubSpot course is because they focus on how to build backlinks, which is something I’ve covered extensively here at QuickSprout.

Overall, it’s a free course from an industry leader that will take less than two hours of your time. I can’t find any reason why you wouldn’t want to take advantage of this.

The Blueprint Training

Blueprint Training

The Blueprint SEO Training has 13 SEO courses; four of which are free. These courses are designed for agencies, so the paid ones are a little bit pricier compared to some of the other sites we’ve seen.

Courses range anywhere from $99 to $999, with average price point right in the middle of those two numbers.

They offer SEO training for things like:

  • Agency sales
  • Content audit
  • On-page SEO
  • Competitive analysis
  • Link acquisition
  • Keyword research
  • Technical SEO

Since the course is made for agencies, it also includes helpful educational guides on agency staffing, client onboarding, and project management.

Rather than purchasing each one individually, you can save by buying in bulk. It’s $2,999 for full access to all of their courses.

The Best SEO Guides

If you don’t want to take a course on SEO, there are plenty of outstanding free guides on the Internet as well. While the courses are definitely better for actionable training and certifications, the guides are a great way to get your feet wet with SEO.

Check these out if you want to learn the SEO basics from different experts in the industry.

MOZ – The Beginner’s Guide to SEO

MOZ is one of the most well-known and reputable names in the SEO industry. They specialize in SEO software and data tools for websites of all shapes and sizes.

So it’s no surprise that their Beginner’s Guide to SEO is one of the best on the web.

The guide is broken down into eight chapters, making it easy for you to skip and scan based on what you’re looking for. It covers the following SEO components:

  • How search engines work
  • Keyword research
  • On-page SEO
  • Technical SEO
  • Link building
  • Measuring and Tracking SEO

MOZ also includes a helpful SEO glossary, which is a great way to get familiar with terms you’ll come across as you’re studying, learning, and applying SEO.

Google – Search Optimization Starter Guide

I’m sure you’re familiar with the term, “straight from the horse’s mouth.” Well, in the world of SEO, Google is the horse.

Your entire SEO strategy needs to revolve around Google’s algorithm. So reading the Search Optimization Starter Guide published by Google should be a top priority for everyone.

The guide details things like:

  • How to help Google find your content
  • Tell Google which pages should NOT be crawled
  • Help Google understand your content
  • Manage your SERPs
  • Website hierarchy
  • Optimize content
  • Mobile optimization
  • Analytics

It’s extensive, to say the least. The format of each section takes you through SEO best practices and things to avoid. So if Google is telling you to avoid it, then you better listen to them.

Shopify – The Beginner’s Guide to Ecommerce SEO

It’s tough to talk about ecommerce without mentioning Shopify. Their ecommerce platform is an industry leader. Shopify also does a great job of setting merchants up for success.

The Beginner’s Guide to Ecommerce SEO is worth the read.

As the name implies, it’s niche-specific. So if you’re running a blog, small business site, or something other than ecommerce, then you don’t need to read it unless you want to further your personal education on the subject.

The post outlines and explains how ecommerce sites can approach SEO differently. It’s a great angle and includes a free SEO checklist as well.

Search Engine Land – Guide to SEO

Search Engine Land is a popular blog on, you guessed it—search engines. They’re constantly posting updates about search engine news, and have detailed guides on Google algorithm updates.

As experts in this space, it’s no surprise that their Guide to SEO is nothing short of spectacular. The guide includes SEO success factors for:

  • Content
  • Site architecture
  • HTML code
  • Trust and authority
  • Link building
  • Penalties and violations
  • Social media

I like the guide because it falls somewhere between a beginner’s guide and an expert guide. It has some SEO basics but takes an easy approach to some more advanced SEO strategies as well.

Quick Sprout – Everything You Need to Know About SEO

I couldn’t write a post on the best SEO guides without including my own. I’m obviously biased, but Quick Sprout’s guide on Everything You Need to Know About SEO covers exactly what the title says.

The page is set up slightly different from the others we’ve seen so far. I have so much content published about SEO, that I use this guide to link to more specific and in-depth guides on certain subjects.

There are more than 70 different SEO guides on this page. It includes SEO topics like:

  • Site audits
  • SEO vs. PPC
  • Keywords
  • Content creation
  • Augmented reality SEO
  • Common SEO mistakes
  • WordPress SEO
  • Link building
  • Guest posts
  • Technical SEO

The list goes on and on, and I’m constantly updating it and adding more. So if you want a wide range of both beginner, intermediate, and advanced SEO strategies, this is a great place to look.

Conclusion

We live in a world where you can find nearly anything you want online. So why not take advantage of the SEO courses, guides, and learning tools at your disposal?

The problem is there is too much saturation in this space. Everyone seems to have an “expert guide” or “best course” on SEO. It can be overwhelming for you to find the best one.

So rather than spending hours searching on your own, just use this list instead. I’ve narrowed down the best SEO courses and guides on the Internet today.

Be sure to check back on this page soon. I’m always updating it with suggestions when I find something new or better.


Source Quick Sprout https://ift.tt/2OatH21

Here’s How to Visit Your Favorite Museum for Free on Sept. 21

Finding a museum that offers free admission seems more difficult every day. Sure, sometimes there are deals: Come by after 5 p.m. on the third Thursday of the month, excluding leap years, and show your latest tax return to prove you’re a local.

It’s never that bad. And I know museums need to charge admission to stay open. But sometimes that $25-per-adult entrance fee just hurts.

Luckily, museums across the country join together each year in the spirit of the Smithsonian Institution — where admission is always zero bucks! — and open their doors to visitors for free.

On Saturday, Sept. 21, celebrate the annual Museum Day with free general admission for two to any participating museum.

How to Visit Museums For Free

To get in on this freebie, find a participating museum near you that you’d like to visit, and register for your free ticket — which is good for you and a friend.

To register, you’ll need to choose the museum you’d like to visit and then enter your email address and your name. Remember, you can only register for one Museum Day ticket per email address.

Once you’re registered, click the “Download Ticket” button, print the PDF file, grab a buddy and go! 

The download will specify whether you must print out your ticket or if you can display it on your phone. One caveat: Museum Day tickets don’t cover parking or extras, like Imax movies.

Lisa Rowan is a former senior writer at The Penny Hoarder.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder https://ift.tt/32Piok3

How to Create an Ecommerce Website in 9 Easy Steps

We’ve covered the high-level strategy of building an online store that makes real money here.

But how do you create the ecommerce website itself?

In this guide, I’ll cover the 9 steps you need to take to create an ecommerce site in this guide. I’ve broken this guide into four sections:

  1. The Prep Work — These are the things you’ll need to do before you start customizing your actual shop
  2. The Framework — In this section I’ll help you pick the right theme for your online store
  3. The Build — You’ll actually customize and create the ecommerce website in this phase
  4. Get Paid — Connect a payments processor to your store and set the right prices

More specifically, this guide includes:

  • The one and only ecommerce tool we use to build our sites
  • The payment setting that can accidentally reduce your revenue by increasing refunds and chargebacks
  • The biggest myth of pricing and how real ecommerce website owners set their prices
  • What to put on your homepage to convert more customers
  • What an SSL certificate is and why you need one (also how to get one for free)
  • How to create an ecommerce website that’s profitable

You don’t need to finish all four phases in a day, though you could take a rough first draft approach and whip through them in a day, then iterate from there. Your choice! Let’s get building.

The Prep Work: Before You Build Your Ecommerce Website

Before we get into the actual work, I need to make a quick note: I’m going to assume that you’re creating an ecommerce website from scratch.

If you already have an ecommerce store and want to transfer that store to Shopify, we have a detailed guide for that here.

There’s a bit of prep work to do before you start building your Shopify store (or whatever ecommerce software you decide to go with). Don’t skip this stuff — it’s the foundation of your online business and if you get it wrong, your ecommerce business will not succeed.

Step 1: Search for Your Domain

Before going any further, make sure your company name has a good domain you can grab.

I’ve started several stores in the past, had a company name picked out, and then had a terrible time trying to find my domain. Eventually, I went with a completely different name so I had to backtrack and change a bunch of settings, or even recreate my store from scratch.

The whole process goes much smoother if you make sure the domain you want is available from the beginning. Then you won’t have to redo anything.

My go-to resource for checking which domains are available is Namecheap, which is our pick for best domain registrar. A domain registrar is just a fancy name for a company that registers domains on your behalf.

Not only is Namecheap our favorite domain registrar, they also have a wicked fast domain search. Even when I’m not planning on buying a domain, I always use them to search for available domains.

Ecommerce Site - Namecheap Domain Search

Don’t Buy Your Domain Name Yet

Why? Shopify has the option of buying your domain for you. If you use Shopify to buy your domain, they’ll also configure the entire domain. There’s nothing you need to configure or set up, it’s super easy.

I use Namecheap as our domain registrar and to manage all our domains. I believe it’s the best out there. It makes sense for us because we have a ton of sites and domains that we manage. Once you’re managing dozens of domains, keeping them all in one location helps a lot. It’s easier to keep them from expiring, update their settings, and sell them if you want.

But if you only plan on having a couple of domains for your ecommerce site, buying them through Shopify is the easiest option. So hold off on buying for now and just check to make sure your domain isn’t taken.

Step 2: Start Your Shopify Free Trial

Now that you’ve made sure that you won’t have any trouble grabbing the domain for your company, head over to Shopify and start your 14-day free trial.

Why Shopify? Aren’t there other ecommerce site builders?

Yes, there are other ecommerce software options. To be honest, none of them compare to Shopify, it’s not even close.

Years ago, ecommerce sites used to be fairly difficult to manage and build. Then Shopify entered the category and completely changed the game. And in the last few years, they’ve added lots of advanced functionality so they’ll easily scale with you no matter how big your site gets.

Shopify completely outshines the competition in ease of use, feature depth, ability to scale, and price.

Whenever I build an ecommerce site these days, I immediately go to Shopify. I don’t give a second thought to any of the other options out there.

There’s no credit card required so you can get a good feel for how Shopify works without any risk on your end. The 14 days are also perfect for getting your site built. I recommend setting a goal to get your store live by the end of the trial period. Then you’ll be making money as soon as you start paying for Shopify.

The trial will ask you a few questions about your company name, your address, and other standard details.

Step 3: Get Your Domain

With your Shopify store created, it’s time to grab that domain you spotted earlier. The easiest option is to buy your domain within Shopify.

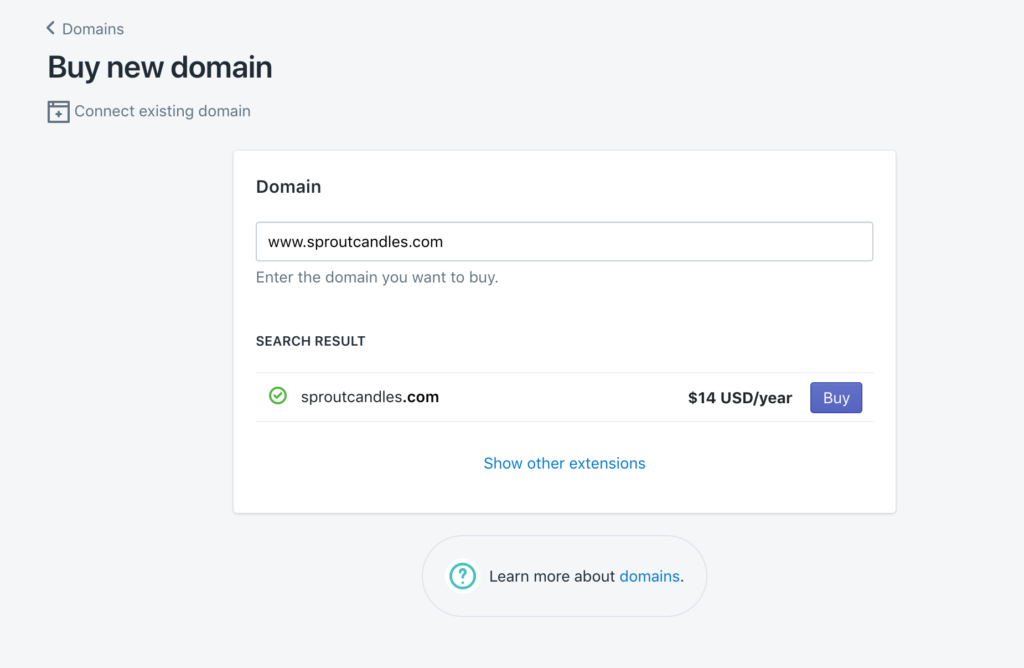
In Shopify, you’ll find a domains section that allows you to search for a domain.

Ecommerce Site - Shopify Buy Domain

Shopify sells .com domains for $14 per year. This is slightly higher than average. Most domain registrars will sell an available domain for $10 per year. If you’re creating your store from scratch and haven’t purchased your domain yet, I wouldn’t worry about trying to save $4 per year. Purchasing your domain directly from Shopify will save you the several extra steps you’d have to take to point your domain from your registrar to Shopify.

I also recommend that you purchase the .org and .net versions of your company name. So you should have three domains in total:

  1. company.com
  2. company.net
  3. company.org

What if you want to manage your domains outside of Shopify? In that case, choose a domain registrar like Namecheap and buy the domain there.

Once you have your domain, you’ll need to configure a few domain settings to point the domain to Shopify. You’ll find detailed instructions on how to do this here.

If you’re pointing your domain to Shopify, do this as soon as possible. It can take a few hours for domain settings to go into effect so you’ll want to make the changes and confirm everything is working before you’re ready to launch your store.

The Framework: Use Shopify Themes to Create Your Ecommerce Website

Step 4: Choose Your Theme

Your Shopify theme determines how your store will look. It’s also how ecommerce stores are able to brand themselves using their site. You can also change the look and feel of your site without having to transfer off Shopify itself, simply by changing the theme.

There are three ways to get your theme in place:

Free Shopify Theme

Shopify has plenty of great-looking themes that are also completely free. They’ve gotten so good over the years that it’s often difficult to tell what’s a free theme and what’s paid.

Paid Shopify Theme

Shopify also has plenty of paid themes in its marketplace. Most of them sell for $180. They offer a more polished site and extra features than the free themes.

Custom Shopify Theme

Yes, it is possible to get a theme built from scratch. If you go this route, an ecommerce marketing agency can build your site however you want. It can be completely customized to match your brand.

The costs for a custom theme will vary widely. It depends a lot on how big of a business you have and your requirements. Pricing will range anywhere from a few thousand dollars to over a hundred thousand dollars for an enterprise ecommerce site.

My Recommendation: Create Your Ecommerce Website with a Standard Shopify Theme

Unless you already have a thriving business, it’s best to use one of the standard Shopify themes. This gives you the ability to get started without having to spend much money. Then once your business has taken off and you have a good idea for how to evolve your site and brand, you can consider a customer Shopify theme.

When we look for themes, we go to the Shopify theme store and rank all themes by popularity.

Then we start at the top and scroll down until we find a few that could work.

Ideally, you’ll find one that has a good “feel” for the type of customers your store will target. If you’re targeting men that spend time outdoors, a more rugged feel is ideal. If you’re selling luxury products, a polished and refined feel would be better. Don’t worry about getting this perfect — you only need a theme that’s “good enough” at this stage.

We typically don’t worry about the free versus paid Shopify themes. We’re more focused on finding the theme that’s a good fit. If it happens to be free, even better. If it costs us $180, we consider that a small cost and don’t hesitate to purchase the theme. If you’re watching every dollar and would prefer to stick to a free theme, you’ll still find plenty to choose from.

Once you’ve found the theme you want, get it installed on your Shopify store. That’ll make the next few steps a lot easier.

The Build: How to Create an Ecommmerce Site that’s Unique

Step 5: Create Product Pages

This is where you’ll want to spend the most time.

Product pages have a huge impact on how many of your website visitors end up converting to customers. And it’s one of the key parts of the business that you control. You can’t always control traffic. You can’t always control your suppliers. But you can control how much effort you put into making your product pages really high quality.

Let’s go through the key parts of a product page and how to make them amazing.

How to Pick the Right Product Name

Great product names have a huge impact on product sales. Just think of the legendary infomercial products like the Shamwow, Thighmaster, or OxiClean. Legendary product names are distinctive, instantly communicate the product benefit, and are easy to remember.

I’ve named my share of products and all I have to say is that this is a lot harder than it looks.

When I tried to name my first few products, it was really easy to fall into the trap of making the name too cute. There’s a fine line between a legendary name that resonates with your market and a cute name that everyone ignores.

This is why it’s generally better to focus on names that are clear instead of trying to be too creative. Until you have a lot of naming experience, it’s really easy to pick a name that falls flat.

A clear and boring name for a great product will still generate tons of revenue. A cute name will destroy it. So focus on clear names that your market will instantly understand.

How to Write a Product Description that Sells

This is your one to two paragraph pitch for the product. Really spend time on this copy.

Here’s a good structure to use in a standard product description:

  1. One or two sentences describing the problem that your product solves
  2. One or two sentences painting the dream of what it will be like when the product is solved
  3. Two to three sentences explaining how your product achieves that dream and the specific features that help accomplish that goal

This is a very common copywriting script that’s used for a lot of products, particularly any product that solves a distinct problem.

That said, not all products solve problems. Apparel is a great example. If I buy a trendy shirt, what problem am I trying to solve? None really. Instead, my purchase is aspirational. I’m aspiring to feel more confident, refine my identity, and change my look. In this case, it’s less about the product description itself and more about how the shirt looks and makes me feel. The product photos end up carrying more weight than the product description itself.

In other words, if the product description template above doesn’t work for your product because it doesn’t solve a distinct problem, don’t try to force it. Instead, use the photos to paint the dream your customers have the best you can.

How to Shoot Professional Product Photos

Photography standards have gotten super high these days. Everyone has an amazing camera on their smartphone and great photography has become super prevalent with Instagram, so ecommerce websites have to take their product photos really seriously.

Don’t skimp here.

Set up a small area to take high quality photos for your products and use the highest quality camera that you can get your hands on. Also make sure to take photos from multiple angles. If possible, you should also take a few photos of the product in action. If you’re selling bed sheets, take a photo of the sheets on a real bed. If you’re selling hiking shoes, take a photo of somewhere wearing them on a hiking trail.

Use your photos to paint the dream as best you can.

Step 6: Create Your Company Pages

After your product pages are done, there are a few more pages you’ll need to create.

Build a Simple Homepage with a Few Popular Products

The simplest and most effective way to approach your homepage on an ecommerce website is to feature your most popular products.

Take your most popular product of all time and include a giant photo of it along with a call to action to its product page above the fold. Then include the next 3–5 most popular products on the rest of the homepage. This ensures that new site visitors are exposed to your best products immediately, increasing the percentage of people who purchase.

Every six months or so, check your product popularity and rotate products as necessary.

Large ecommerce websites rotate their featured products at a much faster pace. As they should! They have a lot more customers and a product catalog that’s constantly changing. As you get larger yourself, you’ll also want to increase the pace that you change your homepage. Start doing quarterly changes, then monthly, then weekly, and so on.

Write a Compelling About Us Page

A lot of visitors will go to your about page to figure out who you are and what you’re doing. This is a perfect opportunity to tell your story and inspire your customers to join you on your mission.

Here are some questions and topics that you’ll want to cover on your about page:

  1. If there was a particular moment that changed your life and set you on your path to create this business, tell that story.
  2. Include any values or principles you use to build or select your products.
  3. If there’s a goal or milestone that you’re trying to achieve, share it.
  4. If you’re committed to living a certain lifestyle, paint that dream.
  5. Clearly define the type of person you’re offering products for.

Be authentic and write your copy as clearly as possible. The more that you can make this page resonate with your target market, the better.

Add a Contact Page

This page is nice and easy. Keep it simple: include your phone number, address, and a contact form for people to reach out.

The most important thing is to make sure that the contact form goes to an email address that’s actively being monitored. If you’re the only person working on your website, have it go to your email at that domain. For example, if I had a site called Sprout Candles, I’d create an email for lars@sproutcandles.com and have my contact form send messages there. That way I can respond to any customer requests really fast.

Once you gain traction, one of the first areas of the business that you’ll want help on will be customer support. Lots of ecommerce websites hire folks part-time or for a few hours each day to go through all the customer messages for the day. At that point, send your contact form to a generic support email that can easily be managed by anyone on your team. If I reached that point with my hypothetical business, I’d change the email to support@sproutcandles.com.

An easy and low-cost way to get a phone set up for your business is Grasshopper. They give you a public phone number that can route to any phone number of your choosing. In the early days, you’ll have it redirect straight to your cell phone. That lets you respond to any phone calls directly without having to post your personal phone number publicly.

Get Paid: Connect Payments and Set Prices in Your Ecommerce Site

Selling stuff — and getting paid — is the whole point of creating an ecommerce website. Otherwise it’d be a blog or a personal webpage, or even a hobby site. No matter how many hours of work you’re pouring into your website, if you’re not making sales and getting paid, your store isn’t a business; it’s an expensive hobby. This section is all about linking your payment processor and setting prices.

Step 7: Set Up Your Payments

One of the best parts of building your site on Shopify is how easy it is to set up payments. Shopify does just about everything for you — all you need to do is configure a few settings and tell Shopify when to send your money. It’s really that easy.

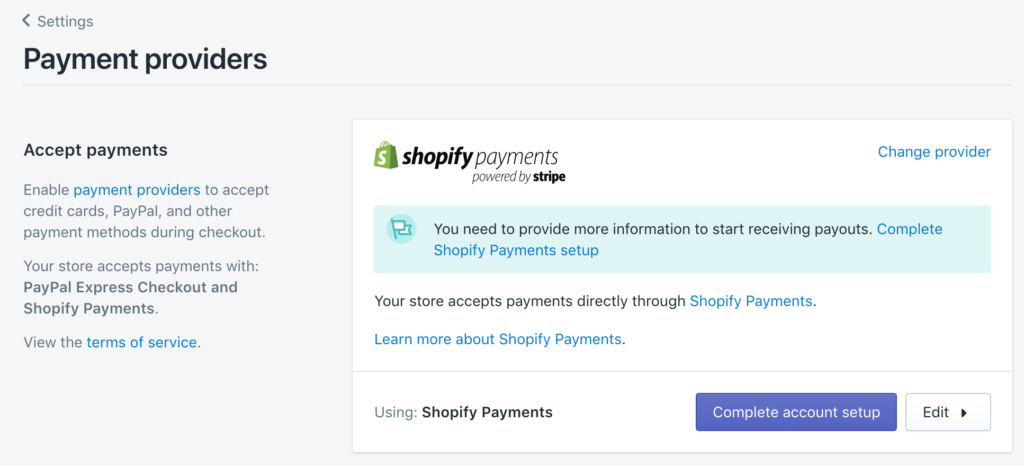
Those payment settings are under the Settings section in your Shopify account.

Go ahead and set up Shopify Payments:

Ecommcer Website - Payment Providers

Most of the info that’s required is pretty standard. It includes basic business info, some personal info, and your bank account so Shopify can transfer money to you.

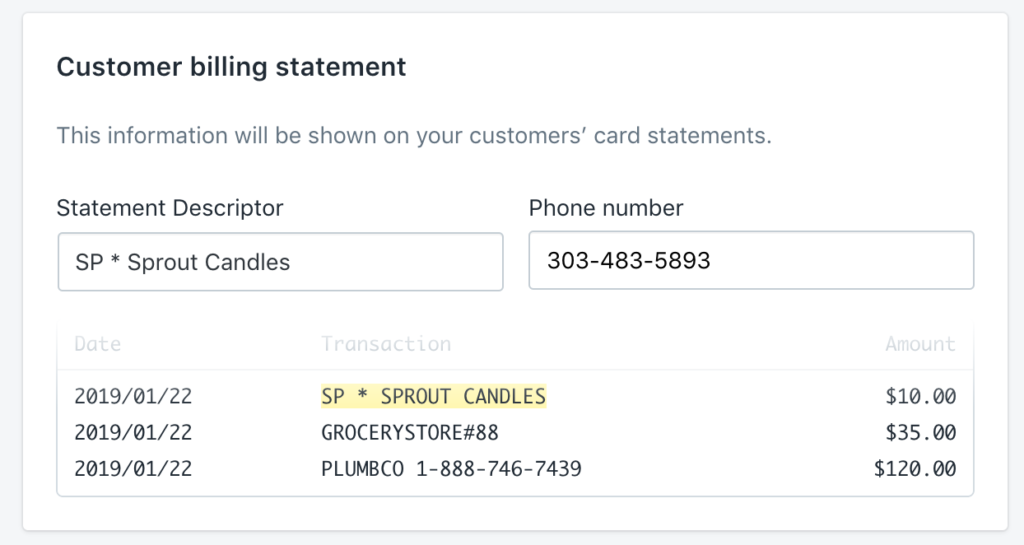
There is one setting that you should pay close attention to for your payments: your customer billing statement.

Ecommerce Site - Billing Statement

Have you ever looked through your credit card statement, seen a charge, and thought to yourself, “What was that for? Did I get charged for something I didn’t buy?”

It happens to us all. With the number of online purchases we make these days, it’s easy to forget what we bought.

As an ecommerce store owner, the last thing you want is for your customers to get confused when they see your billing info on their card statements. If there’s any doubt or confusion, your refund and chargebacks will go up. The best way to avoid this is to make it as clear as possible which store the charge came from. Use the primary name your customers will recognize from your site. This will save you money and frustration later.

Also, we do recommend setting up PayPal on your site as well. Some customers prefer using PayPal since they don’t have to enter their credit card info all the time. Especially on mobile, it’s a lot easier to pay.

If you don’t have a PayPal account for your business already, they’re super easy to create. The only charge is the small percentage of each sale that PayPal will keep, which is standard across the industry. Go through the PayPal settings in Shopify and get it connected to your store and a PayPal option will appear in your checkout.

Now that you can accept payments — how do you know you’re charging the right amounts?

How to Set the Right Product Prices

The biggest myth about pricing is how businesses set prices.

As consumers, we always assume that a business figures out how much something costs, adds a fair percentage to make some profit, and that’s how we get the final price.

In reality, it never works like that.

Consumers are willing to pay certain prices and if that price has a good margin, there’s a business. If there isn’t a good margin, the business model changes or there aren’t any good businesses in that category.

Mobile apps are the best example of this. Regardless of what it costs to develop an app, people are only willing to pay about $5 for it. The app could do incredible things and literally change lives but it doesn’t matter, the ceiling is about $5.

So how do consumers figure out what they’re willing to pay?

Price comparisons. As consumers, we only understand relative pricing. When we try to evaluate if a price is fair, we find the nearest comparison and judge based on that.

“After all, as bargain hunters know, comparison shopping is a cinch online. The result is that merchants are leery of raising prices. The ease of entering the marketplace, regardless of location, further ratchets up the competition. At the same time, internet retailers can often operate at a lower cost than their brick-and-mortar competitors.” — E-Commerce Might Help Solve the Mystery of Low Inflation, The New York Times

Why is it possible to only charge $5 for a mobile app? All the other apps are about $5.

Why is it okay to charge $5 for a latte? Starbucks charges about $5.

If you try to sell me a t-shirt, I’ll instantly compare your price to the standards I’ve come to know. Cheap, plain t-shirts are about $5, nicer t-shirts about $20, and luxury fashion brand t-shirts $70–100. Depending on what kind of apparel company you have, I’ll compare to those benchmarks.

But if there’s a felt-need and reasonable price point, I’ll buy. This is one of the key factors to ecommerce success.

The bottom line is that every business needs to factor in the comparative pricing. Yes, you can stretch it a bit if you’re delivering more value. For example, some mobile apps charge $10 and make it work. But there are limits.

Find the best comparison price to your product, nudge the price up or down depending on your value, then set your price.

And as a ecommerce website owner, it’ll be up to you to decide if your business works at that price.

Step 8: Get Your SSL Certificate

SSL Certificates allow you to say that your site is extra secure. They’ve been around awhile and have become standard for any site that handles private information like email addresses and payment information.

In the last few years, Google has made SSL certificates more prominent in its Chrome Browser. Here’s what a site looks like with an SSL certificate:

HTTPS URL

Here’s what one looks like without it:

HTTP URL

There’s a very clear trend that sites with SSL certificates are being highlighted while sites without them are getting subtle warnings. While SSL certificates used to a “nice-to-have” feature, these days they’re considered a requirement for any ecommerce site.

The last thing any ecommerce site owner wants is to make a customer hesitate because there isn’t an SSL certificate on the site.

We strongly recommend that you set up your SSL certificate when you create your site.

The best part?

Shopify gives you a free SSL certificate for your store. That’s right, it’s 100% included with your store.

Something to keep in mind for later on: there are different levels and types of SSL certificates. When getting a free SSL certificate, you’ll only get the basic options. More advanced SSL certificates come with extra monitoring, insurance, and extra security. Prices range from $150 to $2,000 per year depending on the exact package.

The only folks that should worry about the more advanced SSL certificate options are those that handle credit cards themselves (you’re not; Shopify is doing it for you) or run very large enterprise sites.

In other words, the free SSL certificate from Shopify is more than enough right now. If your ecommerce site gets super large, you can look at the other SSL certificate options later.

After you get your domain purchased or connected in Shopify, you’ll find an option to add an SSL certificate in your Domains area.

Step 9: Launch Your Store

The big day has arrived!

Everything is in place and now it’s time to launch your store.

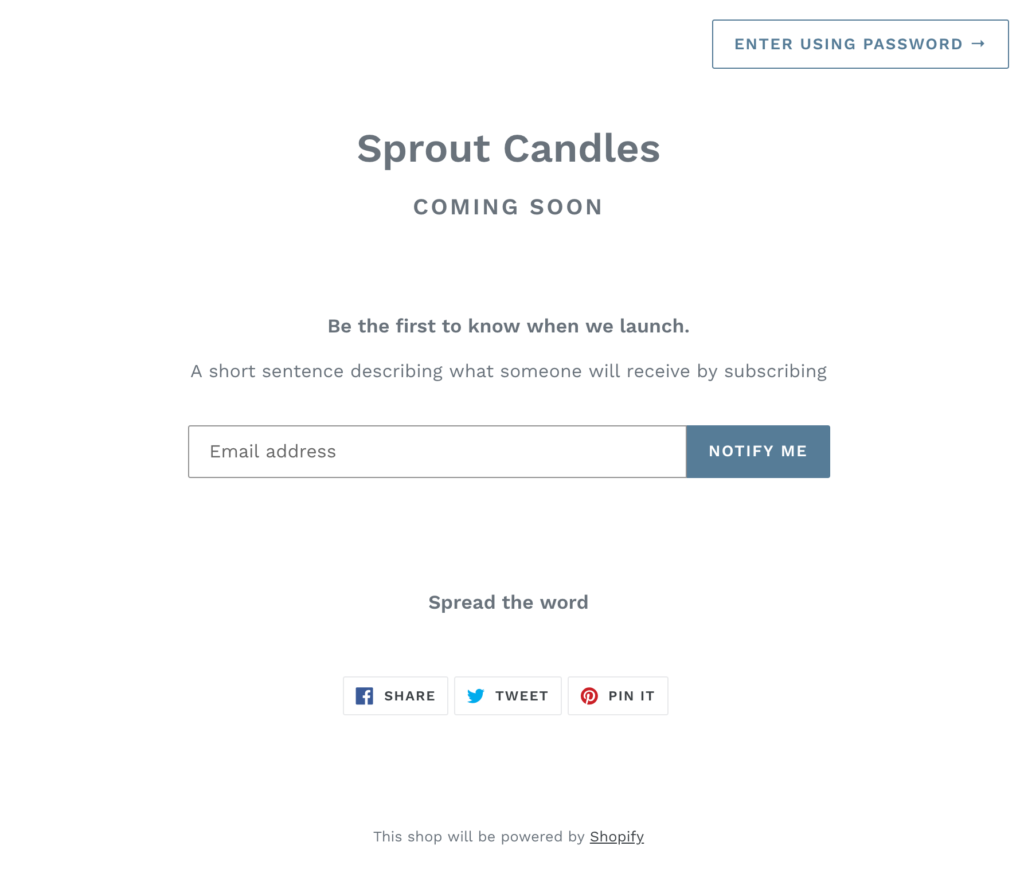
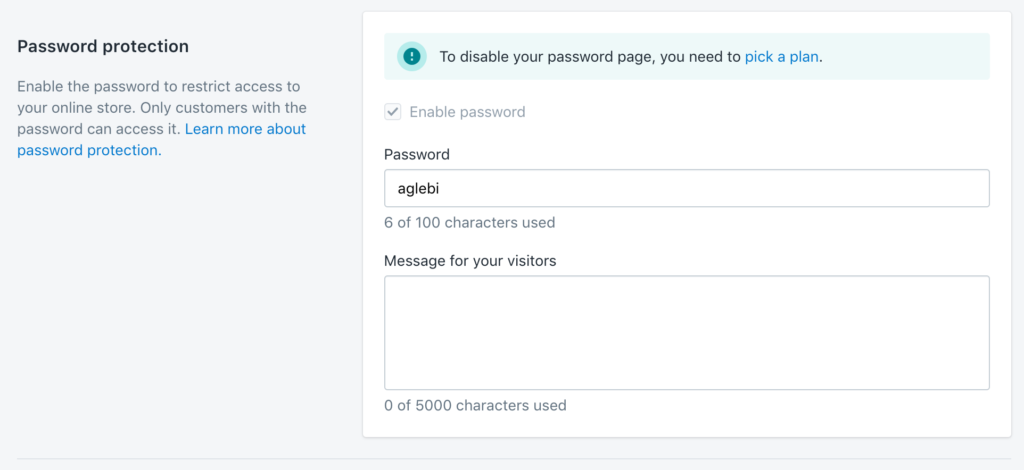
Shopify stores are password protected by default, so no one has been able to see your store until now. If anyone tried to visit your store until this point, this is what they saw:

Ecommerce Website - Shopify Password Page

As soon as you remove the password protection, people will go straight to your real store without needing to enter a password.

Before Shopify will let you launch your store, they require you start one of its paid plans. You’ll still get full credit for your trial; the billing period won’t begin until after the trial ends. But you do need to get your paid account set up before you can open your store.

If you haven’t picked a paid plan yet, go ahead and do that now.

Then go into your store settings and look for the password section:

Ecommerce Website - Shopify Password

All you have to do is uncheck the “Enable password” box, save the settings, and your store will launch.

Congrats!

From here, it’s all about growing traffic to your ecommerce website, improving your products, and finding new products to offer. The better you get, the larger your business will become.

Bonus Step: Add A Custom Search

A custom search helps your users find the product they want as quickly as possible. WordPress comes with its own search but the problem is it is very limited – especially if you have a large, complex e-commerce website.

A good custom search will provide multiple filters so your users can narrow down the search until they find what they are looking for. For example, if you are selling homes you might have filters for the number of bedrooms, the price, the location, size and many other features. 

There are other search add-ons you might need such as AJAX updates so you can get new results on-the-fly and pagination which splits your results into pages.

Not only is the search itself important but also the way you display your results as well. You might want to present your results as a list, a grid or even on a map.

Toolset Search is a great option to build your search and customize your results as you do not need PHP coding. Experienced developers will save time building a search while novices will be able to add an important e-commerce feature they didn’t think they were capable of creating. Toolset also offers a Custom Types Training Course which will teach you how to create your search as well as other important features for e-commerce websites.


Source Quick Sprout https://ift.tt/2AylzAx