Thousands of courses for $10 728x90

الاثنين، 4 نوفمبر 2019

The Different Types of Web Hosting Options

Every website in existence is hosted on the Internet. But not every website is hosted the same way.

If you’re starting a new website for the first time, it’s normal to have some questions about what web hosting is and how it works. You definitely want to learn about the different types of web hosting so you can figure out which option is the best for your website.

Don’t rush through this process. Choosing the wrong web hosting type can cause big problems for your site down the road.

Some of you might be unhappy with your current web hosting situation, so you’re looking to switch to another type. That’s what brought you to this page.

Regardless of your situation, this guide will explain everything you need to know about your web hosting options. Once you figure out the type of web hosting you want, then you can review the best web hosting providers and select a plan to meet your needs.

What is Web Hosting?

Before we go any further, I want to start with the basics to make sure you have a full understanding of what web hosting is and how web hosting works.

Websites are hosted on servers, which are powerful pieces of hardware that house websites and data related to those sites. Every component of your website is stored on a server and accessed through your web host. This includes elements like files, text, images, videos — everything.

Servers are physically located in data centers, which are typically run and managed by different web hosting companies.

Web hosts provide the technology and server space required for your website to be accessed on the Internet. This allows users to search for your site and view your web pages online.

Different Types of Web Hosting

All servers are not the same, which is why different web hosting options exist. Some servers are shared by multiple websites, while other servers are dedicated to just one website.

There are four main types of web hosting:

Reseller hosting and WordPress hosting are also specific types of hosting that fall within these categories. We’ll cover all six types of web hosting as we continue.

How do you know which hosting option is best for your website?

Lots of factors will determine this answer. The type of server you choose will impact elements like performance, security, scalability, and management level of your website.

The type of website you have and the amount of traffic you’re getting will also impact your decision on choosing a web hosting option. For example, a small personal blog with 5,000 monthly visitors will have different hosting needs than a large ecommerce site with 250,000 visits per month.

It’s also worth noting that different hosting options and plans are offered at varying price points. So it’s important that you find an option that falls within your budget as well.

I’ve outlined and explained the six different web hosting options below. You can use this information to figure out which hosting type is the best choice for your website.

Shared Hosting

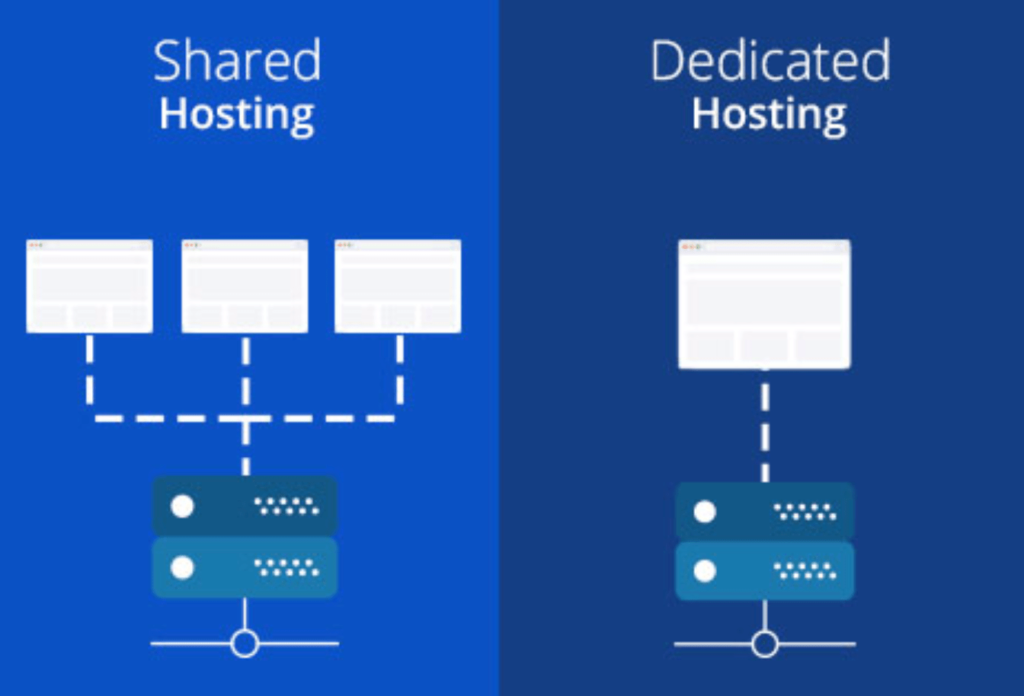
Shared hosting is the most basic type of web hosting. It’s cost-effective and the best choice for small or entry-level websites. As the name implies, websites using shared hosting will be sharing resources with other websites on a singular server.
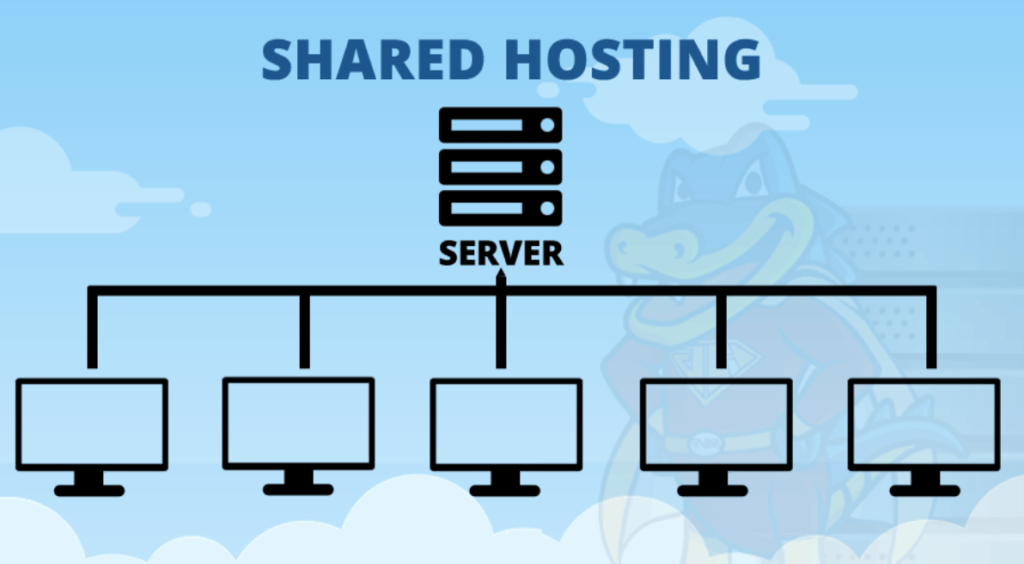
Shared Hosting

That’s one of the reasons why shared hosting is so cheap compared to other types of web hosting.

Each website on the server will have a limited amount of resources as defined by their specific hosting plan.

Shared web hosting can be compared to renting a room in a house with other people. You have your own bedroom, but you and your roommates will share resources like water, electricity, and common spaces throughout the house.

The nature of sharing a server with other websites has its drawbacks. If another website on your server has a traffic spike, it can potentially cause performance issues with your site. These situations are out of your control.

So while shared hosting is a great option if you want to save some money, it definitely won’t deliver the most high-quality web hosting experience for you or your website visitors.

Who is Shared Hosting For?

Shared hosting is a great choice for beginners and smaller websites. It’s cost-effective and doesn’t require lots of technical knowledge to get started.

I’d recommend shared web hosting to websites that are on a tight budget. Bloggers and small business owners who have simple websites are great candidates for shared hosting. Any website that doesn’t require too much on-site interaction or lots of resources will be fine with this hosting type.

If you’re not expecting more than 10,000 or 20,000 monthly visits to your website, you can save some money by selecting a shared web hosting plan.

Shared web hosting pros:

  • Most cost-effective type of web hosting.
  • Easy to set up.
  • No technical knowledge required.
  • Great for beginners and small websites.

Shared web hosting cons:

  • Sharing server resources with other websites.
  • Performance issues are out of your control.
  • Slower loading times and lower uptime rates.
  • Not scalable.

Best Shared Web Hosting Provider — Bluehost
Bluehost

Our recommendation for shared hosting is Bluehost. So if it sounds like shared hosting is the best option for your website, this is the most logical place to start your search.

This provider has an outstanding reputation in the industry. More than 2 million websites across the globe trust Bluehost for web hosting.

Bluehost offers shared hosting plans starting as low as $2.95 per month.

All plans come with a free domain, free SSL certificate, and free marketing credits for Google Ads and Microsoft Advertising.

If you have questions, problems, or need any assistance, you can contact Bluehost support 24/7 via phone or live chat.

VPS Hosting

VPS stands for “virtual private server.” This hosting type is a step above shared web hosting. When a website outgrows their shared plan, it’s common for owners to upgrade to a VPS.

With a virtual private server, your website will still be sharing a single server with other websites. However, the number of websites you’ll be sharing it with is significantly lower.

The main server is split into multiple virtual servers—hence the name. These virtual servers can be customized by individual websites.

Even though the main server is shared with other sites, your website will have dedicated resources with a VPS.
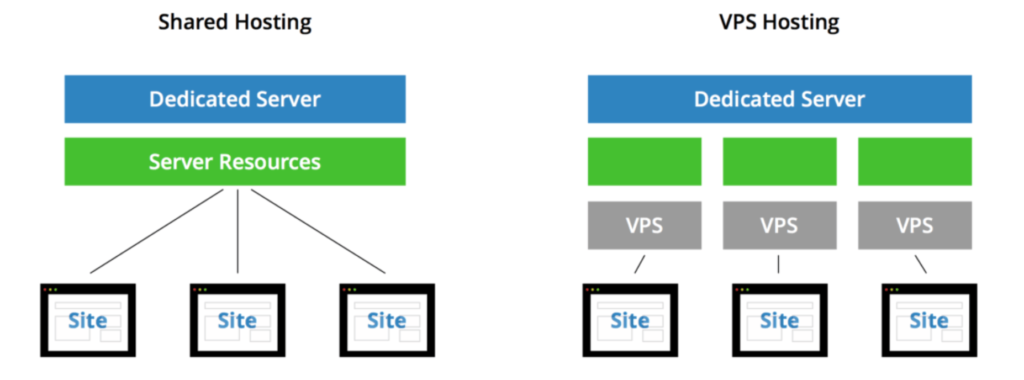
VPS Hosting

For those of you who want to run custom configurations to your server, you can get optional root access with your VPS hosting plan.

Since you won’t be sharing resources with other websites, your site will perform better than it would with a shared hosting plan. This means you’ll benefit from faster loading times and higher uptime rates. You won’t have to worry about another website causing your site to crash.

Most websites do not need a dedicated server (we’ll get to that next). But a VPS gives you some of the benefits of dedicated hosting at a fraction of the price.

A virtual private server is like renting an apartment on your own. You won’t be sharing a kitchen, bathroom, living room, or other common spaces with any roommates. This gives you much more freedom and flexibility to do what you want with the space.

However, you’ll be sharing some resources with the other units in the building. So there will still be some limitations.

Who is VPS Hosting For?

VPS hosting is best for small or medium-sized businesses that can’t afford to have unexpected downtime on their website. It’s a great option for website owners who have outgrown the resources of a shared hosting plan.

A virtual private server can benefit website owners who are tech-savvy and want to make custom changes to their server configuration.

Websites with large files like videos and images should consider a VPS. Interactive websites with complex files will perform better on a VPS as opposed to a shared server.

VPS hosting pros:

  • Dedicated server resources.
  • Ability to make custom configurations to your server.
  • Higher uptime rates and faster loading speeds.
  • More cost-effective than a dedicated server.

VPS hosting cons:

  • Sharing the main server with other websites.
  • Not as easy to set up as a shared server.
  • Still has limitations in terms of what you can control.

Best VPS Hosting Provider — InMotion
InMotion

Lots of hosting providers offer VPS plans, but InMotion is our top recommendation for this type of web hosting.

The VPS plans offered by InMotion come with root access, which gives you the ability to make custom changes to your virtual server. This is a great option for those of you who are more technically advanced.

InMotion offers free cPanel and WHM, making it easy for anyone to view and manage their VPS.

You’ll also have the option to choose your data center for maximum speed. InMotion has VPS plans that are optimized for ecommerce shops as well.

All VPS plans from InMotion come with a 90-day money-back promise, which is one of the best satisfaction guarantees that you’ll find in the industry.

Dedicated Hosting

Dedicated servers are the top of the line in web hosting. As the name implies, you’ll have a dedicated server that belongs to you, and you alone. This is the most expensive type of web hosting, but it comes with added benefits.

Since you won’t be sharing resources or anything else with other websites, your site will operate at peak performance.

Websites being hosted on a dedicated server have complete technical control over the server settings. You choose the software, configurations, and anything else you need.

If you get a dedicated server, you should expect extremely high uptime rates and lightning fast loading speeds. You won’t have to worry about traffic from other websites impacting your performance.
Dedicated Hosting

A dedicated server is like owning a house. If you want to build a fence, plant a tree in the yard, build a patio, or renovate the kitchen, everything is completely up to you.

Who is Dedicated Hosting For?

Dedicated hosting plans are typically reserved for enterprise-level websites. These servers are intended for websites that have high volumes of traffic.

I wouldn’t consider a dedicated server unless your site was getting upwards of 100,000 monthly visits.

Large ecommerce sites and enterprises should consider a dedicated hosting plan because they can have complete control over the functions of their server. Sites that require the highest levels of security, such as websites that store financial data or medical information would benefit from a dedicated server.

Dedicated servers come with varying management levels. You can look for a hosting provider that will manage your server for you, or you can manage it on your own. The downside of managing the server on your own is that you’ll be responsible for installing updates and monitoring everything for glitches or errors.

Only consider a dedicated server if you can afford it. In most cases, a dedicated hosting plan will be out of your price range, especially if you are starting a new website. These servers can cost up to $2,000 per month.

Dedicated hosting pros:

  • Complete control over the server.
  • Not sharing resources with any other websites.
  • High security.
  • Fast load times, high uptimes, and optimal performance.

Dedicated hosting cons:

  • Most expensive type of web hosting.
  • Requires technical knowledge.
  • You are responsible for everything.

Best Dedicated Hosting Provider — HostGator
HostGator

HostGator is my top recommendation for dedicated server plans. While dedicated hosting definitely isn’t cheap, the plans offered by HostGator are actually pretty affordable.

Introductory pricing specials for their dedicated servers start at $118.99 per month.

One of the reasons why I like HostGator is because they offer fully managed plans. If you want, their team of technicians can handle system monitoring, software patching, updates, offsite backups, data migrations, and more.

You’ll have access to 24/7/365 priority customer support as well.

So if you think your website needs a dedicated server, check out the plans and options offered by SiteGround.

Cloud Hosting

Cloud hosting is a newer type of web hosting. It can best be described as a hybrid version of a VPS, but more cost-effective.

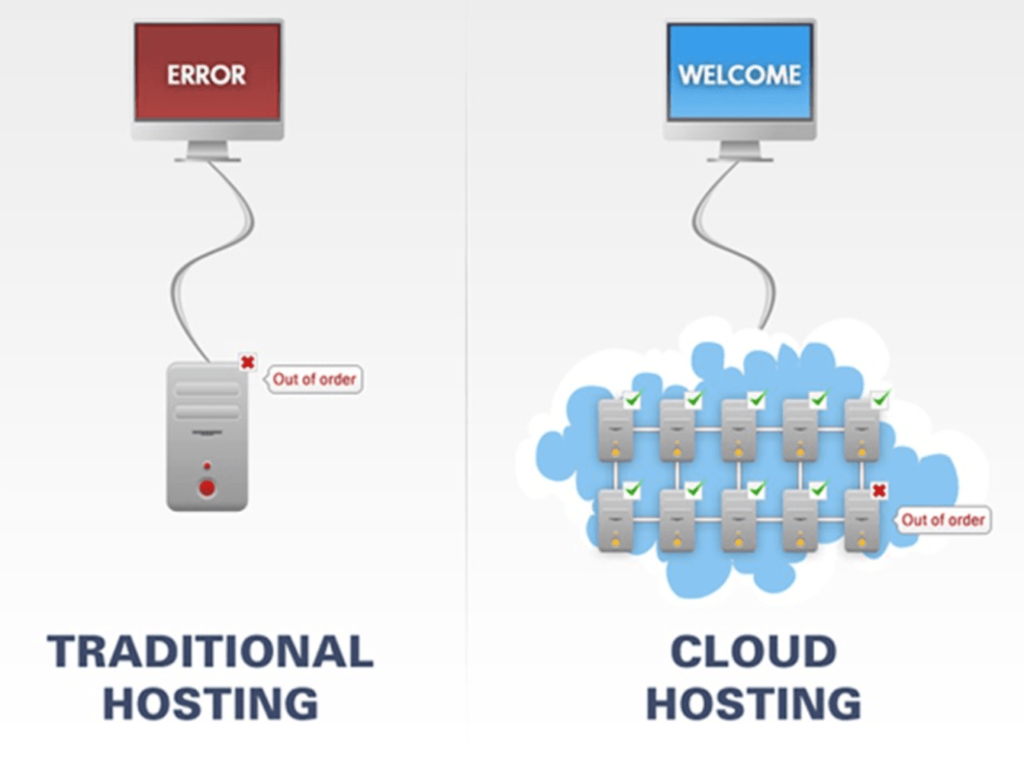
Cloud hosting plans come with multiple remote servers. Each server has different responsibilities. If one of the servers is compromised or has a problem, the other servers on the network will take over those responsibilities and pick up the slack.
Cloud Hosting

That’s what makes cloud web hosting such an appealing alternative to traditional web hosting.

With cloud servers, your website will have higher uptime rates and won’t have as much unexpected downtime due to server errors. Your site will remain fluid and perform at a high level.

The best part about cloud web hosting is scalability.

With traditional hosting, there is always a constant dilemma between server resources and price. You don’t want to overpay for a plan with resources that you’ll never use, but at the same time, you don’t want to exceed the resources of a lesser plan and negatively affect the performance of your website.

Unless you know exactly how many page views your site will get per month, then this is nearly impossible to predict.

But website traffic is never an exact science. At times, you’ll experience spikes or surges to your site—which is great news. You just need to make sure your plan can accommodate that traffic.

That’s why cloud hosting is the ultimate solution to this dilemma. The best cloud hosting plans allow you to scale your resources on-demand.

You pay for what you use, and you can always adjust these resources within your admin dashboard.

Who is Cloud Hosting For?

Cloud hosting is the best option for medium and large business websites that are growing at a rapid rate.

If your website traffic is unpredictable and you’re planning on it scaling at a steady rate in the coming months or years, then you should consider a cloud hosting plan.

Any website with more than 50,000 monthly page visits could consider a cloud plan. Websites that have outgrown their shared plan and need to upgrade could seek cloud hosting as an alternative option to a VPS.

Cloud hosting pros:

  • High security.
  • Scale resources on demand.
  • Less unexpected downtime.

Cloud hosting cons:

  • Pricing isn’t always fixed.
  • Unpredictable traffic can increase costs.
  • Limited customization.

Best Cloud Hosting Provider — SiteGround
SiteGround

If you’re interested in cloud hosting, look no further than SiteGround. Siteground has always been an industry leader in web hosting. Their cloud plans are suitable for a wide range of businesses and website sizes.

Their entry-level cloud plans come with 2 CPU cores, 4 GB of memory, and 40 GB of SSD space. But you can fully customize a cloud with up to 32 CPU cores, 128 GB of memory, and 1 TB of SSD space. Although most of you won’t need all of that, it’s nice to know you have those customizable options to deliver exactly what your website requires.

SiteGround’s cloud plans are fully managed. Their IT team will take care of all of the technical aspects of your hosting experience. This allows you to focus on everything else.

All cloud plans come with a free SSL, free CDN, private DNS, and daily backups. You’ll also benefit from SiteGround’s advanced priority support if you ever need assistance.

Reseller Hosting

Reseller hosting is definitely not for everyone. If you’re building a small website from scratch or just looking to host a website on your own, then this will not be the best option for you.

But if you want to sell web hosting to other sites, then you should look into reseller hosting plans.

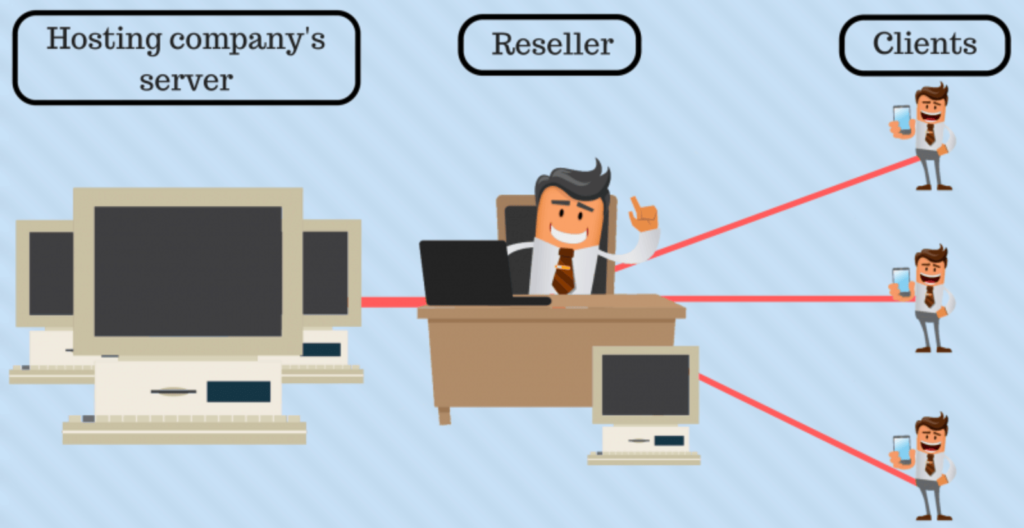
Reseller hosting is basically white label web hosting. You buy hosting from a provider and then resell those services to your clients.
Reseller Hosting

As the reseller, you get to choose the pricing options for your clients. Since you’ll be paying wholesale rates to the provider, then you have the opportunity to make substantial profit margins.

Who is Reseller Hosting For?

For the most part, reseller hosting is for agencies, web designers, and web developers. These are people who already have clients in this space, so they can just add web hosting to the services that they currently offer.

You can make it easy on your clients by allowing them to get all of their website needs in one place, as opposed to finding a web hosting plan on their own.

One of the best parts about being a reseller is sustainability. If you design a website for someone, they won’t necessarily need your services forever. But if you can get those clients to buy web hosting services from you, then you’ll benefit from a steady monthly income for the lifetime of that website.

I wouldn’t consider reseller hosting unless you’re planning to manage at least 10 different websites. Otherwise, it probably won’t be worth it for you.

Reseller hosting pros:

  • Set uncapped prices to your clients.
  • Get recurring and sustainable income.
  • Improve your existing services.

Reseller hosting cons:

  • Need lots of clients to make it worth your time and effort.
  • If something goes wrong, your clients will turn to you.

Best Reseller Hosting Provider — A2 Hosting
A2 Hosting

A2 Hosting is known for speed, which is one of the reasons why it’s my top recommendation for reseller hosting.

When you white label hosting to your clients, you want to make sure that you deliver high performance. Even though the hosting technically isn’t coming from you, any problems will be a poor reflection of your personal brand. But with A2 Hosting, your clients will still get high uptime rates and fast loading speeds on a shared server.

Another top benefit of A2 Hosting is that WHMCS comes free with all reseller plans. You’ll definitely need this to effectively manage all of your clients and their resources. Other hosting providers charge extra for this.

Overall, client management with A2 Hosting is the best I’ve seen in the industry. You can even set up simple hosting support as well.

A2 Hosting also offers a 99.9% uptime commitment to you. So you can pass that along to your customers.

WordPress Hosting

WordPress hosting is another very specific type of web hosting. As you can probably imagine from the name, it’s intended for websites using WordPress as a CMS.

In the simplest terms, WordPress hosting is basically web hosting that’s been optimized for WordPress.

The best WordPress hosting plans come with one-click WordPress installations as well.

WordPress hosting usually has added security that’s specifically designed for websites that are running on WordPress. Since WordPress is the most commonly used CMS across the globe, those websites are a higher risk for cyber crime. So that added security is definitely a great benefit.

You’ll normally see two different types of WordPress hosting offered by providers.

  • Shared WordPress hosting
  • Managed WordPress hosting

Shared WordPress hosting works the same way as regular shared hosting, except WordPress might be pre-installed.

Managed WordPress hosting provides added benefits like enhanced security, server caching, staging, and faster loading speeds.

Who is WordPress Hosting For?

This isn’t rocket science. WordPress hosting is for WordPress users. If you want your hosting to be optimized for your WordPress site, then you should look into this type of web hosting.

WordPress hosting pros:

  • Optimized for WordPress.
  • WordPress pre-installed or one-click installations.
  • Enhanced security for WordPress sites.

WordPress hosting cons:

  • Less control and flexibility.
  • Updates aren’t always smooth.
  • Sharing resources with other WordPress sites.

Best WordPress Hosting Provider — WP Engine
WP Engine

I should start by saying I’m a little biased here. We use WP Engine here at Quick Sprout, so naturally, this is my top pick for the category.

It’s not necessarily the best choice for beginners. But for those of you who have some experience with web hosting and plan to build a blog or business website with high-traffic, WP Engine is your best bet.

WP Engine has WordPress hosting plans starting at $35 per month. This is another reason why I don’t think it’s the best choice for a beginner. There are other WordPress hosting plans out there starting for less than $5 or $10 per month.

The speed and security is the best part of WP Engine. They offer managed WordPress hosting services, so everything is handled at the server level.

This means that you won’t have to install lots of extra plugins that can weigh your site down.

Another reason why I recommend WP Engine is because they have excellent customer support. All plans come with 24/7 live chat, and some of the higher-tier plans even come with 24/7 phone support.

I’ve been impressed with the quality and level of service whenever I’ve needed to contact them.

What is the Best Hosting Type For Your Website?

This answer will be different for everyone. It all depends on factors like the type of website you have, the resources you need, your budget, and traffic.

To figure out what category you fall in, here’s a quick recap of the different hosting types and who they are for:

  • Shared Hosting — Most cost-effective plans for entry-level websites. – Recommended Shared Host = BlueHost
  • VPS Hosting — For websites that have outgrown shared hosting. – Recommended VPS Host = InMotion
  • Dedicated Hosting — Enterprise-level servers for large websites. – Recommended Dedicated Host = HostGator
  • Cloud Hosting — Best for websites that are growing rapidly. – Recommended Cloud Host = Siteground
  • Reseller Hosting — For agencies, web developers, and web designers. – Recommended Reseller Host = A2 Hosting
  • WordPress Hosting — Hosting optimized for WordPress sites. – Recommended WordPress Host = WP Engine

Once you figure out what type of web hosting is the best option for your website, then you need to pick a hosting provider and plan. I gave my top recommendation for each category in this guide, so that’s the best place for you to start your search.


Source Quick Sprout https://ift.tt/2NjdV4l

Motorcycle Insurance and Anti-Theft Devices

Installing an anti-theft device on your motorcycle can be beneficial in more ways than one. Not only can an anti-theft device do its job and protect you against vandals and thieves, but having certain types of devices can even lead to lower motorcycle insurance premiums.

Before you run out and install an anti-theft device to save on insurance, however, it helps to know which devices deter thieves the best and which ones actually lower insurance costs. Believe it or not, insurance companies don’t offer discounts for having an anti-theft device.

This guide will break down which devices can make a positive impact on your premiums, how much you can save on motorcycle insurance, and other ways you can protect yourself.

Anti-Theft Devices that Help You Save Big On Motorcycle Insurance

While you may believe that any anti-theft device could help reduce your motorcycle insurance premiums, this isn’t normally the case. Like with auto insurance, companies that offer insurance in this space only offer discounts on certain anti-theft devices that might deter criminals the most.

Anti-theft devices that lead to the biggest discounts include:

Tracking Systems

Owners who have a tracking system installed on their motorcycle are most likely to qualify for sizable insurance discounts. A tracking system allows motorcycle owners to use radio or GPS signals to track down their bike once it’s been stolen.

While owners should never try to repossess a stolen bike on their own, they can use information from tracking systems to help law enforcement track down their stolen property so it can be returned.

Disabling Features

This type of anti-theft device may be offered on its own or in conjunction with a tracking system. Disabling features allow motorcycle owners to disable their bikes so they cannot be driven away. Some disabling features can even be set up to activate on their own based on factors the owner sets up themselves.

Keep in mind that there are plenty of other anti-theft devices you can buy for your motorcycle and that many of them work quite well. You can buy motorcycle locks and alarms along with typical chain locks you can find online or in stores.

For the most part, anything you can purchase that will make it more difficult (or louder) to steal your bike will leave you better off. Just remember that only a few anti-theft devices can lead to savings on motorcycle insurance premiums.

Also, note that purchasing comprehensive coverage within your motorcycle insurance policy is another great way to recover from theft. After all, comprehensive coverage was created to cover losses not caused by an accident — for example, damage from hail or inclement weather or damage from vandalism or outright theft.

If you want to make sure you aren’t left in the lurch of a thief takes off on your bike and never comes back, you’ll need to make sure your insurance policy comes with sufficient coverage for theft. 

How Much Money Can You Save On Motorcycle Insurance?

How much you’ll save with an anti-theft device depends on several different factors. These can include:

  • Which motorcycle insurance company you buy coverage from
  • How much your premiums cost
  • Which anti-theft device you purchase and install

With most companies, installing a qualified anti-theft device will help you save 10% off your motorcycle insurance premiums or more. Keep in mind, however, that some motorcycle insurance carriers will only extend this type of discount to customers who have an approved anti-theft device installed by a professional.

Others may let you install the equipment yourself, although you may need to provide proof of purchase.

Before you purchase an anti-theft device, it makes sense to find out which devices your insurance company provides discounts for and any requirements they have that might prevent you from qualifying.

Also, note that this is also a factor to consider when you shop around for motorcycle insurance coverage since your premiums could vary based on whether you qualify for an anti-theft discount or not.

Other Ways to Save On Motorcycle Insurance

Installing an anti-theft device is a smart way to save some cash on insurance premiums while protecting yourself from the drama of having someone steal your bike. However, there are other ways you can save on motorcycle insurance. Some of the best money-saving measures you can take include:

Shop around and compare policies

One of the best ways to reduce motorcycle insurance premiums is shopping around to make sure you’re getting the most bang for your buck. Make an apples-to-apples comparison of different insurance companies to see how much you’ll pay for a policy with similar inclusions and coverage limits.

You may need to switch insurance companies to get the best deal, but the savings can be well worth it.

Choose a higher deductible

Motorcycle insurance policies come with an out-of-pocket deductible you must pay before coverage kicks in. With that in mind, it’s important to note that choosing a policy with a higher deductible can help reduce your annual insurance premiums. 

Check for other discounts

Make sure to check for other motorcycle insurance discounts you could qualify for. While available discounts can vary, check for options like safe driver discounts, safety course discounts, multi-policy discounts, and policy renewal discounts.

5 of the Best Ways to Prevent Motorcycle Theft

According to the National Highway Traffic Safety Administration (NHTSA), more than 750,000 vehicles were stolen nationwide in 2017. That makes vehicle theft a multi-billion-dollar crime, but it’s also a crime that may be preventable.

If your goal is preventing theft of your motorcycle or any other vehicles you own, there are some steps you can take right away that could help. Some tips from the NHTSA include:

  • Don’t leave your key in the ignition. The NHTSA says that many motorcycles and other vehicles are stolen each year due to driver carelessness, including leaving the key in the ignition. Make sure you never leave your key in an area that’s easy to access or on the motorcycle itself while you’re away.
  • Buy anti-theft devices and have them properly installed. Anti-theft devices that slow down the theft process or make it burdensome can go a long way when it comes to protecting your bike. Make sure any device you buy is properly installed to ensure maximum protection.
  • Purchase a vehicle recovery system. A vehicle recovery system that uses radio signals or GPS can help you recover your bike once it’s already been stolen. This type of device may also lead to lower insurance premiums, so it could be a win-win.
  • Purchase an alarm system. An alarm system, and preferably a loud one, can also help protect your motorcycle and your investment. Make sure your alarm is properly installed and loud enough to deter thieves.
  • Park your bike in a well-lit, public space. If you’re planning to park your motorcycle in public — and especially overnight, make sure you look for a parking space that is out in the open with plenty of lighting.

Anti-Theft and Motorcycle Insurance

If you’re worried about theft, there are many steps you can take to protect yourself. For starters, you can purchase a wide range of anti-theft devices that might deter thieves including recovery systems, disabling mechanisms, motorcycle alarms, and traditional locks and chains.

On a side note, you may also want to make sure your motorcycle insurance policy comes with comprehensive coverage that will replace your bike if it’s stolen and never recovered. This is crucial since, no matter how hard you try, some motorcycle thieves are so skilled that your anti-theft devices aren’t much of a deterrent.

Some of the best criminals know how to disable tracking devices and turn off alarms while they’re loading your bike onto their truck or flatbed. There’s nothing you can do about that except make sure you have proper motorcycle insurance coverage that will step in to help when you need it most.

The post Motorcycle Insurance and Anti-Theft Devices appeared first on Good Financial Cents®.


Source Good Financial Cents® https://ift.tt/34v1d8i

Questions About Used Cars, Small Windfalls, Vanilla Extract, Motivation, Soup, and More!

What’s inside? Here are the questions answered in today’s reader mailbag, boiled down to summaries of five or fewer words. Click on the number to jump straight down to the question.
1. Family doesn’t save or plan
2. Note about used cars
3. Getting small windfall into retirement
4. Staying motivated in retirement
5. Real vanilla extract worth it?
6. Soup freezer containers
7. Sharing cost of holiday meal
8. 401(k) aggressive investing?
9. Sports and trading cards?
10. Worried about hack
11. Recommendations for travel toiletries
12. More on “black belt” theme

I dislike everything about the switch back and forth between Daylight Savings Time and regular time. Just end it, please.

On with the questions.

Q1: Family doesn’t save or plan

I’m 36/M married to 32/F. My parents died when I was young and I essentially don’t have any family. My wife’s family more or less “adopted” me when we started seriously dating and now I’m basically a full-on part of their family. Great in most ways, but they’re all struggling financially, every single one of them. They don’t save for the future and don’t plan. When I suggest making financial plans to my wife she goes along with it as long as they’re vague but when I start talking about actually doing specific things she puts the brakes on immediately. We’re not in any financial trouble right now but we have very little saved for retirement. We use credit cards for an emergency fund. I signed up for a 401(k) on my own last year and contribute 4% to get 4% of employer matching and my wife was actually kind of annoyed by it and only begrudgingly accepted it when I pointed out my contributions were doubling. Not sure how to convince my wife to save, even for retirement.
– David

The thing is, you’re probably not going to be able to “convince” her. I’ve found, over and over again, that making smart financial moves is usually something that people have to come to on their own and when external forces are trying to push them there when they’re not ready or not interested, it’s a waste of time.

Rather, I would encourage you to approach this from a “this is important to me” angle. Make it clear that this is something you believe in strongly and that you want to do it.

There will come a point – maybe not tomorrow, but at some point – where the lightbulb goes off for her and she understands the value of what you’re doing. It’ll probably be at that point when she’s thinking ahead to the future and realizes the only way that you’re both going to be able to retire before your mid 70s is due to the money you’ve been socking away for retirement. Obviously, the younger this realization comes to her, the better, because she’ll be much more on board with the savings and you’ll have more years to rapidly build your nest egg before retirement.

For now, just ask for her trust in doing this, that it’s important to you to do it. Let it build, and then when the light bulb clicks on for her, she’ll be glad you did it.

Q2: Note about used cars

I agree with most of what you wrote about how used cars are not the great deal they used to be, but I wanted to fill in a reason why: there aren’t as many used cars as there used to be. The truth is that in 2008-2010 the car makers simply didn’t make as many cars because of the economic crisis. That means in the last few years there haven’t been many cars in the ~10 year old range that you could sell for $5-$8K. This means people are either holding onto cars for longer or buying more recent used models. People are trying to get a 10 year old car for $5K like they used to and they simply don’t exist so they decide to either buy something newer usually with a loan or keep driving what they have. So the newer cars have more buyers and that always pushes the price up when you have more demand and equal supply and because of that used isn’t a big bargain right now. I think that it’ll rebound in 3-5 years when the 2012-14 models reach that age as those are around in much more abundance. I think things will go back to something like they were and used will be a bit of a bargain again.
– Shaun

Great insight! I hadn’t thought about the used car market in that way before, but it certainly makes sense.

I went and looked at a few dealer websites and, sure enough, there were very few cars in that 2007-2010 model year range. There were a few, but not many at all. There were more cars on the old end of that range being sold for around $4,000 than ones in that range. It’s almost like a chunk of the market is missing.

So it makes sense that people are either waiting for a while longer or buying something more expensive if there simply aren’t any cars at the age that they’re looking to buy in. If you have people buying the 2012-2014 used instead, then that market is emptier, and that drives people who would buy those to even newer used models, and when you have more buyers than cars, the prices go up.

It completely makes sense. Thanks for the insight!

Q3: Getting small windfall into retirement

I received about $50K from my grandfather’s estate when he passed away. There were only two grandkids and everything was split up evenly among all descendants. I am 28 and I would like to get that money into retirement savings as I think that would be what he would want, as he told me again and again over the last several years that I should be saving for retirement. I almost feel like that’s why he gave me this money so I would be 65 and have a good life and would remember him.

How do I do this, though? How do I get that $50K into a retirement account? I looked at a Roth IRA but you can only contribute $6,000 a year. Are there other options?
– Max

A Roth IRA is probably the best option for you. I’m assuming that you’re already contributing to a 401(k) or something similar at work if it’s available to you.

If I were you, I’d open an account with an investment firm that you trust – say, Vanguard or Fidelity. Put all of the windfall in there – $6,000 of it into a Roth IRA and the rest into a normal taxable investment account. Put all of the money in the Roth into a Target Retirement fund aiming for your retirement year. Put all of the money in the normal investment account into something aggressive that you can just sit on and forget about. I’d probably put half of it into a total US stock market index fund and the other half into a total international stock market index fund, and set it to reinvest your dividends. Then, just let it sit.

On January 1 of each year, move $6,000 from the taxable investment account into the Roth IRA. Each year, you’ll have a small amount of taxable growth in your normal brokerage account – probably on the order of $1,000 the first year and progressively less each year after that as the money moves into the Roth IRA. You’ll have to pay taxes on that, which will be a couple hundred dollars at first (probably just a couple hundred dollar reduction in your tax refund) and progressively less each year.

Eventually, all of it will be in the Roth and then you just sit on it until retirement. It’ll grow and grow and grow, tax free, as long as you wait until age 59 1/2 to withdraw.

Be sure to keep an eye on the income limit for a Roth IRA. Once you start getting north of $100,000 a year in income, you start to run into limits on how much you can contribute to a Roth. In those situations, consider instead bumping up your 401(k) contributions at work and then using the taxable money for living expenses if needed.

Q4: Staying motivated in retirement

Can you offer some advice on staying motivated after retirement? I started reading The Simple Dollar in 2008 and you encouraged me to live a little leaner and save more for retirement. When I retired last year I had a lot more in retirement than I expected and the actual financial part has been easy. My retirement fund is actually bigger now than when I retired.

The problem is I don’t feel motivated to do anything. I mostly just putter around the house and read magazines and watch television. I go on a walk once a day. I call my kids sometimes. I don’t feel motivated to do much of anything any more.

What can I do to find that motivation? I don’t want to just sit here and wither but I don’t really have a reason to do anything.
– Max

For many people, motivation comes as a result of responsibility and commitment, and it sounds like there isn’t much responsibility or commitment in your life right now. People are motivated because they’re responsible for their kids or they’re responsible for a work project or because they’re committed to something they agreed to do. My list of commitments and responsibilities is comically long if I were to list it out, and I feel pretty motivated each and every day.

My suggestion would be to find something for your idle hands to do and then commit to that. I think volunteer work is a great opportunity for this. Are there volunteer programs in your community that you could sign up to help with regularly? Are there committees you could serve on and help make decisions? In most communities of any size, there are tons of opportunities out there if you dig a little bit. You could be doing anything from being a school crossing guard to helping shelve books at the library or delivering flowers at a hospital or helping build a Habitat for Humanity house or participating in a political campaign for a candidate or cause you believe in.

Agree to bite off a big commitment with whatever it is you’re doing and you’ll likely find motivation starting to grow again. The difference is that you have a lot of options before you and you can choose the option that really matters to you based on what you personally value.

Q5: Real vanilla extract worth it?

Found an old article of yours where you talk about making vanilla extract with vanilla beans and vodka and letting it sit for a very long time. Seems good in principle as you’re basically making vanilla cordial which would work great in baking and most uses. My grandma used to make peppermint cordial doing the same thing with a bunch of peppermint candies. Anyway I was thinking about making some homemade because the price of real vanilla extract versus artificial at the store was huge, but the price of vanilla beans is really high too. Trying to decide if it’s worth it or not.
– Daria

My understanding is that different people taste different things from vanilla extract, much like how different people taste cilantro differently. Many people think that artificial vanilla and real vanilla extract taste basically identical, while others report a huge difference.

I’m somewhere in the middle. I can tell the difference at room temperature and when it’s used in cold things, like ice cream. However, when it’s baked, I usually can’t tell the difference or, if I think I can, it’s pretty subtle. That being said, there have been a few specific kinds of artificial vanilla that have tasted awful to me, something I attribute to some ingredient in the mix that’s not the actual vanillin.

If you plan on using it mostly for baking and the people you’re baking for can’t tell the difference, use the artificial as it’s much cheaper. If you plan on using it for a variety of things, including things like ice cream, I’d make my own.

Q6: Soup freezer containers

What is the best way to freeze soup without making a mess? Tried Ziploc freezer bags but it was real messy!
– Brenda

I’ve tried a bunch of different containers and I think these are the best ones I’ve tried. They come in 32 ounce and 16 ounce sizes depending on what you want (16 ounce is good for a large individual serving, 32 ounce when full works well for our family), you can freeze them and microwave them and wash them in the dishwasher with no problem (though you’ll want to have them in the top rack), and they seem to last and last.

I agree with you that Ziploc freezer bags can be tricky with soup. I tried using them for a while but there were so many incidents of spillage if I was trying to fill them myself that I stopped using them pretty directly for soups.

That being said, good on you for trying to freeze soups. I eat soup that’s been reheated quite often and it’s delicious and quick.

Q7: Sharing cost of holiday meal

I have hosted our extended family Thanksgiving for 12 years. That includes putting up several people for three or four nights, feeding everyone countless meals, and putting on a huge Thanksgiving dinner with homemade sides and all of the trimmings. It often costs $200 to put on the big meal alone and hundreds more to host everyone. I asked my siblings to each chip in $50 this year to help offset the cost and now I learned that they are all calling me “cheap” behind their back. I have never even stayed at most of their houses ever. Am I wrong here or are they just a bunch of selfish jerks?
– Carrie

It’s hard to tell 100% from this story what is going on. Quite often, situations like this are borne out of a misunderstanding or out of something said in frustration that was taken the wrong way.

It’s very likely that the manner in which you requested the money was taken with an intent that you didn’t want. They perhaps felt like it was a demand, or that you were holding the family Thanksgiving holiday “hostage,” and that often doesn’t sit right with people. This is particularly true if it’s perceived that you aren’t really struggling financially at all.

If you want others to pitch in, your approach shouldn’t be tied to a dollar amount or anything like that. Rather, you should simply say that the expense is becoming difficult to manage and that if anyone can offer a little bit of help with the groceries, that would be greatly appreciated.

At this point, I would probably issue a clarification and roll back your request to something like that. Just say that your first message might not have been clear. Don’t demand a specific amount and make it clear that this is about you struggling financially, not about an ultimatum regarding ending Thanksgiving dinner.

Remember, you can only control what you do, not what other people do. These are things you can control.

Q8: 401(k) aggressive investing?

I am 26 years old and have started contributing to the 401(k) plan at work. I am putting in 8% of my pay and my employer is matching 4% so 12% is going in which is good. I have been looking at the investment options and I don’t think the Target Retirement Fund is aggressive enough for someone as young as me. Even the one matching my retirement year still has money going into bonds and cash. I think for me something that’s pure stocks or maybe stocks and real estate is better until I’m maybe 45 or so and then I just move everything back into the target retirement fund. What do you think?
– Brian

I think that if you’re aware of the risks with taking an even more aggressive stance, then that’s perfectly fine.

The big reason many Target Retirement Funds have at least a little bit of bonds and cash, even when they’re 35 or 40 years from their target date, is that they don’t want people logging onto their 401(k) accounts in the midst of a downturn, seeing a huge loss, and bailing. Rather, they want people to see a loss but not a huge one, not quite as big as they heard on the news, and they feel a bit of relief and keep on trucking. The drawback, of course, is that the gains won’t be quite as big, either.

Over long time periods, the gains should notably outweigh the losses and thus an even more aggressive investment strategy can pay off. It does throughout the historical data, though that’s absolutely not a guarantee going forward. You just have to be able to stomach some pretty big downturns when the stock market goes south.

Q9: Sports and trading cards?

What are your thoughts about investing in sports and trading cards? I have seen data that says you can easily make a 30%-40% return annually on them.
– Eric

There are a ton of caveats with those kinds of numbers.

First of all, you have to know the market you’re investing in. You need to know exactly what you’re investing in and which products are going to retain value and grow. That requires a lot of learning and domain knowledge and perhaps most of all separation of your personal emotion from the investments.

Second, there’s a ton of risk baked in, as trading cards and sports cards are entirely luxury goods bought by people who do it for pleasure. If times get tougher, people will stop buying. If tastes change, people will stop buying. A trading card does not address any sort of fundamental need – it aims entirely at entertainment and pleasure, and those things are fickle.

I don’t see any problem with having a hobby budget where you invest in these things and then try to flip them for a profit. I have a friend who does exactly this – buying and selling Magic: the Gathering cards is his hobby and it’s a profitable one. It’s fun for him in many ways, and he’d just stop doing it and sell everything if it stopped being fun.

Treat it as a hobby. Set a fixed monthly budget for yourself, an amount you don’t mind losing, and use that to buy and sell to your heart’s content. You might make money. You might lose your shirt. In either case, you’re doing it because it’s enjoyable.

Don’t put your retirement money into baseball cards or Magic: the Gathering or Pokemon cards.

Q10: Worried about hack

The other day I got an email that appeared to be from myself. It said that someone had gained access to my email and other accounts and that they gave me seven days to pay them or else they would drain my bank accounts. I don’t know what to think.
– Brian

This is a junk email, a waste of your time. Just delete it.

Someone spoofed your email address making it appear as though they were sending an email from your own account. They have a program that lets them send emails to people with a fake “From” address so that it looks like it comes from whatever address they want. To spook you, they made it look like it came from your address.

Most likely, they just bought a huge list of email addresses from someone and sent the exact same message to everyone on that list, spoofing the “From:” address on each one to make it appear as though everyone on that list was getting an email from themselves.

It’s an extremely low effort way to try to get people to send them money via Venmo or Bitcoin or whatever. Ignore it. They’re trying to scam you.

Q11: Recommendations for travel toiletries

How do you pack toiletries for travel? You can’t take anything big through airports or they’ll confiscate it. I use to put stuff in my suitcase and check it but I have had two different items explode and make a huge mess recently.
– Bonnie

Personally, I usually stop at a Target or something at my destination and pick up a few essentials or use what’s available for free at the hotel. I rarely pack much for toiletries, particularly anything that won’t make it through security screening.

When I’m traveling, my goal is to be clean and hygienic and odor free and clean shaven. What do I minimally need to accomplish those goals? Soap and shampoo are usually free at the hotel. I can usually request a small tube of toothpaste, too. I take a toothbrush and a small deodorant stick through airport security. I can pick up a razor at the hotel or, if they don’t have anything I like, I grab one at Target for a few bucks that will work for the length of the trip. That pretty much covers it – it’s one or two things in my carry-on, a few free items at the hotel, and maybe one or two items from a store at the destination. Just buy any consumables in their smallest possible form.

It can get trickier if you have more esoteric or specific needs, but that’s what I do.

Q12: More on “black belt” theme

You wrote recently that your theme for 2020 was “black belt” in that you wanted to get a black belt in taekwondo but that there were other reasons too. Would you mind sharing what that means?
– Adam

Sure. I actually wrote a little more about it in an introduction to the mailbag a couple of weeks ago, which I’ll share again here:

My theme for 2020 is “black belt.” A big part of the reason for that is that, as I’ve mentioned a few times, my family gradually joined a community taekwondo class several years ago (some of us joining before others) and I’m aiming to be able to test for my black belt in December 2020 (possibly February 2021). That will require a lot of work and practice throughout the year.

The theme goes deeper than that, though.

I’ve realized in the past few months that there are several things in my life that I do well, but I could do much better if I “leaned in” on them a little and improved with some deliberate practice and care and thoughtfulness. Personal communication with others is definitely one, as are some spiritual and meditative practices, some dietary practices (mostly eliminating some bad things from my diet), and a few other specific things. I want to lean in on those things in the coming year in a deliberate and careful way so that I can be even better at them.

Basically, I want to improve on a number of things I’m good at with deliberate practice so that I’m great at it. I think I’m good at communicating with others, but I want to work toward being great at it. I think I have a good set of spiritual and meditative practices, but I want them to be great. I think I’m good at eating healthy foods, but I want to be great at it.

This boils down to a list of four big goals for the year:

1. Black belt fitness and preparation
2. Adopt a maximally healthy and still sustainable permanent diet
3. Deep study of life philosophies and religion through reading and meditation and reflection
4. Improve personal communication and relationships – improve or rebuild every significant relationship in my life via better communication

Each one of those fairly neatly breaks down into some daily steps and daily deliberate practice and habit building, and that’s what I want to fill 2020 with.

The first one is all about taekwondo. I have a training regimen, both inside and outside of class, that should have me ready for my black belt test later in the year. It involves a lot of stretching, a lot of kicking, and a lot of building of core strength.

The second one is mostly about a careful analysis of what I eat and drink. I mostly eat really healthy stuff, but I think I mostly eat too much of it and I want to dig to the bottom of that. I’m going to try a number of different practices to see if I can figure out the best possible permanent diet for me that’s really simple to follow and doesn’t make me crave stuff. My focus is health, not hitting a particular weight.

The third one is about finding more contemplative time and better practices within it. Meditation has been a life-changer for me over the last few years and I want to explore more avenues and practices. I want to read a number of challenging books within the realm of philosophy and theology and religion as I’m pretty passionate about those areas right now. I feel like this is my own riff on a “midlife crisis” (I don’t know if I’m too young for that or not) but I have this strong sense that I’m kind of in the process of carving out who I want to be for the rest of my life.

The final one is about improving my personal communication skills, particularly face to face communication but also using digital tools, and making positive improvement to every meaningful relationship in my life. I’m going to try to consciously reconnect with a lot of people throughout the year and work on being a better listener and friend. Again, this is something I think I’m good at but not necessarily great at.

(I do have a fifth goal, but it’s highly personal and tied to some specific people in my life who probably don’t want things in their life shared on a popular website.)

So, overall, it’s really about leaning in to some things I think I do well, but that I’d like to do very well.

Got any questions? The best way to ask is to follow me on Facebook and ask questions directly there. I’ll attempt to answer them in a future mailbag (which, by way of full disclosure, may also get re-posted on other websites that pick up my blog). However, I do receive many, many questions per week, so I may not necessarily be able to answer yours.

The post Questions About Used Cars, Small Windfalls, Vanilla Extract, Motivation, Soup, and More! appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2NgZSvK

Why You Should Definitely Have More Than One Bank Account

Whether you’re living paycheck to paycheck or starting to build a nice nest egg, you’ve probably asked yourself, “How many bank accounts should I have?” It’s a fair question. 

Today, you have more options than ever, but is there such a thing as too many bank accounts? Do you even need more than one?

While the answer isn’t written in stone, here are some basic guidelines to help you figure out just what the optimal number of bank accounts for you. 

How Many Bank Accounts Should I Have? The Bare Minimum

OK, let’s start with the basics. The absolute bare minimum for accounts that you should have is two. You need a checking account and a savings account. Each of these accounts will serve a separate purpose. 

Checking Account

This serves as your primary money account. You put money in here to handle your bills and other spending. You may (or may not) actually use checks, but you’ll probably use a debit card. If you want to have your bills automatically paid, this is the account to do it. 

Savings Account

Even if you’re living paycheck to paycheck, you’ll want a savings account. This is where you stash money for emergencies. It’s essential to have an emergency savings account to avoid financial disaster when life happens. 

Cars break down, medical emergencies happen and sometimes even jobs are lost. This account is your safety net. Try to add whatever you can into it and leave it alone until you really need it. 

The Case for Multiple Savings Accounts

While it’s important to have your checking and emergency savings accounts, you may decide that you want to have one or more other savings accounts, too. Why? You may have several separate savings goals and want to keep the money separate so you can measure just where you stand on each.

For instance, you may have one account to save for a car purchase and another for that down payment on a house. Even short-term savings like money you’ve budgeted for Christmas or your vacation fund can have their own accounts. This is called the bucket method. Each savings goal has its own account or “bucket.” 

On the flip side, you want to be careful about the accounts you open up. If you have too many accounts with small balances, you could get hit with maintenance fees. You may want to start with just a few. You can always open new accounts if you realize it will be beneficial.

Consider Having Multiple Bank Accounts With Different Banks 

If you do decide to use multiple savings accounts, you should consider using more than one bank. While having them all in one place may be convenient, it also comes with some risks. 

Deposits up to $250,000 are insured by the FDIC at any bank or by the National Credit Union Association at any credit union. So overall, your money is safe. 

But if your account gets hacked, you may have trouble getting your money back immediately. Having money in another bank works as a sort of safety net. Also, you get to test drive multiple banks and maybe you’ll find a new favorite.

As you shop around for savings accounts, look for features that will make the account a better fit for your specific saving goal. Here are some common savings account features to consider. 

  • Interest rate: The average savings account is just 0.09% APY, but some savings accounts pay 2% or more. If you’re opening an account for a long-term savings goal like a down payment for a house, it’s worth it to find an account with a favorable interest rate that helps your money grow.
  • Minimum balance: Some accounts have a minimum deposit to open the account or have a minimum balance requirement. If you need to start out small and don’t think you will have $500 or $1,000 in the account at all times, you may want to consider a different account.
  • Direct deposit: Will you be able to have money go directly to this account? Setting up direct deposit from your paycheck or from your checking account is the easiest way to ensure that you put money into your savings on a regular basis.
  • Online transfers: Will you be able to move money from the savings account to another account easily? You may want that kind of flexibility, but if you’re prone to dipping into your savings too frequently, you may not. 
  • Fees: Keep an eye on the small print for monthly maintenance fees. These fees should either be minimal or nonexistent. 
  • ATMs: Do you want access to cash from your savings when you are out and about? Pay attention to whether the account allows you to use ATMs for free and how ATMs many they have.

Find the Right Number of Accounts for You

If you were hoping to get a concrete number for how many bank accounts you should have, we’re sorry. It’s just not that simple. 

The answer depends on your needs and even your personality. If you find that you’re having trouble keeping track of your accounts, it may be time to combine a couple and simplify. Do what works best for you.

As you try to figure out your best plan of attack is, be sure to build a budget. You need to be able to pay your bills first. Then, if you can set it up to have money automatically withdrawn from your checking to your various savings accounts (preferably right after each payday), you’ll be saving money without even thinking about it.

Start with your two basic accounts and let the number grow naturally from there as your income and your savings goals grow. Set goals, choose accounts wisely, and enjoy watching your savings stack up.

Tyler Omoth is a freelance writer covering topics from personal finance to career advice and even lawn care. His work has been featured on TopResume.com, Writersweekly.com and more. He is also the author of over 70 educational books for children and a proud parent of twin toddlers. 

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder https://ift.tt/2PKekhJ

Chime Bank Review

Think about it for a second: when’s the last time you went into a physical bank branch? Can’t remember? That might mean Chime, or a bank like it, is for you. Designed originally as a bank for millennials, Chime can be a good bank for nearly anyone interested in mobile banking.

The bank was created in 2013 by Chris Britt and Ryan King. It’s completely online, so there are no branches or ATMs of its own, but it does offer a large fee-free ATM network through partner banks. For most users, that is not necessarily a bad thing. Accounts are protected by the FDIC just like the branch on the corner, so you still have all the security of a traditional bank without all the fees and fluff.

And that’s really where Chime shines: banking there is as fee-free as you can get. Here’s a bit more about the bank and how it works.

Chime Bank

Minimum Savings Deposit Maximum Savings APY 1-Year CD Rate J.D. Power Survey Score Key Benefit
$0 .01% N/A N/A No fees

What we like about Chime

The most important thing to love about Chime Bank is the absence of fees. Essentially, the bank makes money from Visa each time you use your Visa debit card. Without the overhead of large banks, they don’t need to rely on fees to support a large infrastructure. In fact, the only fee you’ll normally encounter will be a $2.50 out-of-network ATM fee.

Even that is not likely. You can use any MoneyPass or Visa Plus Alliance ATMs for free. The app and interface are both easy to use, the app has some great features and opening an account takes only five short minutes. You can either use the micro-savings feature, and round up purchases to the nearest dollar and put the rest in savings, or you can automatically have 10% of your payroll direct deposit routed to savings. Both are optional.

So users are saving money by not paying recurring bank fees and overdraft charges, and actually saving money becomes simple with Chime.

Things to consider

Every bank has downsides, and Chime is no exception. First, due to lack of physical locations, depositing cash is extremely difficult unless you do so through another external account you have linked to the Chime app.

There is a mobile check deposit feature, but some users have complained that it is difficult to use. Direct deposit seems to be the best way to get money into your account. To add to the frustration, customer service also takes a long time to respond through the app — a matter of days, not hours.

The only other major issue? The savings rate is exceptionally low, approaching zero. It’s almost not worth putting money in the account and leaving it there. The only advantage is that it won’t show on your checking balance, so hopefully, you will not be as tempted to spend it.

If you’re looking for high, or even decent, yield, Chime is not the place to get it. There are also no physical checks available, although there is a workaround.

Checking accounts

When you first sign up, you’re signing up for Chime’s Spending account. This is essentially a checking account. There is no minimum balance, and you can and should use direct deposit. Getting money into the account, especially cash, is really difficult and must be done through Green Spot, which usually charges fees.

For a checking account, there are no physical checks offered. However, once you have an account for more than 30 days, you can send a check through the app’s checkbook feature. Essentially, they’re printing a check and sending it for you.

There are also some other handy features. There are cash-back rewards from some retailers and other places, and they change from time to time, giving the program some flexibility. There is also a great Split the Bill feature, which will send a text message to the person of your choice with a link to pay you back through Venmo or Chime if they also have an account.

Savings accounts

There are a couple of cool ways to save with Chime. The first is the micro-savings feature, which is similar to other banks’ “round-up” features. Purchases can be rounded up to the nearest dollar, and the remainder put in savings. It’s amazing how fast those small amounts can add up.

You can also set the account up so that 10% of direct deposits are put automatically into savings. Both of these programs are not required.

There are two things to consider about savings. For one thing, when you sign up for Chime, you are signing up for a spending account first. To sign up for a savings account, you will have to sign up a second time through the app, giving them all of your information all over again. The second issue is the savings rate, as discussed above: at 0.01%, it is so close to zero that it’s almost like it isn’t even there.

The savings account is more to keep your balance out of your spending account so you won’t touch it.

Money-market accounts, CDs, IRA account, credit cards, and more

Chime only offers checking and savings — no MMAs, CDs, or other accounts. That means that if you want those things, you will still have to bank elsewhere. This makes Chime a great cash management account for those with simple banking needs, but not a good option for those who want everything in a single bank.

Investing

Chime has no investing plans, so you’ll need an app like Robinhood, a more traditional trading app like E-Trade or another similar app if you want to trade in mutual funds.

The bottom line

Chime is a great bank for those who are more comfortable with virtual banking than with a brick-and-mortar institution, and also those who only need pretty basic financial services. If you need full-service banking or work with cash a lot, Chime may not be the right answer for you.

If you’re looking for a fee-free checking alternative, however, Chime is worth a closer look.

The post Chime Bank Review appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2WGn35N

How To Become A Doula In 4 Easy Steps

Have you considered becoming a doula, but you’re not sure how to get started on this rewarding career path? Are you yearning to support other women as they welcome their baby into the world? Or perhaps it’s the postpartum period that you feel you have a passion for? Becoming a doula isn’t as difficult as […]

The post How To Become A Doula In 4 Easy Steps appeared first on The Work at Home Woman | Legit Work From Home Jobs.


Source The Work at Home Woman | Legit Work From Home Jobs https://ift.tt/2oJxRDM

MPs call for banks to reimburse push payment frauds retrospectively to 2016

MPs call for banks to reimburse push payment frauds retrospectively to 2016

A Treasury Select Committee report says banks should consider retroactively reimbursing victims of push payment fraud

Stephen Little Mon, 11/04/2019 - 10:56
Image

MPs have told banks that unless they introduce certain fraud measures by March 2020 regulators should consider sanctioning them.

The Treasury Select Committee says banks should also consider reimbursing victims of authorised push payment fraud (APP) to help tackle the “serious and growing problem” of economic crime in the UK.

In the first half of this year, £616 million was stolen from UK bank customers, according to UK Finance.

Of this, a total of £207.5 million was lost due to APP scams, where people are duped into authorising a payment into another account.

A new industry voluntary code offering consumers protection APP fraud was introduced on 28 May.

Customers of banks that have signed up to the code will be reimbursed for their losses provided they have taken reasonable care.

Banks that have signed up to the voluntary code include Barclays, HSBC, Lloyds Banking Group, Metro Bank, Nationwide, Royal Bank of Scotland, NatWest and Santander.

MPs are now calling for it to be made compulsory, with customers retroactively reimbursed back to 2016.

With money transfers going through so quickly, customers of banks have little time to be aware if fraud has taken place, the committee’s report says.

It recommends a 24-hour delay on all initial payments between accounts to give consumers time to consider if they are being defrauded.

From next year March banks will have to alert customers if they transfer money to a new account and the name does not match as part of the new Confirmation of Payee scheme.

"If the implementation date of March 2020 begins to look in doubt, regulators should consider introducing sanctions, such as fines, to firms who have not met the deadline,” the report says.

Currently, when you send an electronic payment you enter the name, the sort code and the account number. However, the account name is not checked.

Fraudsters are becoming increasingly sophisticated and are using this to trick people into sending money to the wrong account.

Under the new scheme, banks will be able to check the name on the account of the person or organisation you are paying when setting up a new payment or amending an existing one.

You will then be alerted if the name does not match the account.

Rushanara Ali MP, leader of the Treasury Committee’s inquiry, says: “With scams getting ever-more sophisticated, it’s clear that economic crime is a serious and growing problem in the UK.

“The Treasury Committee’s report examines the scale of economic crime faced by consumers, ways that financial firms are combatting economic crime, how economic crime is investigated, and consumer’s rights and responsibilities.”

UK Finance chief executive, Stephen Jones, says: “Investing millions in security systems to defend customers, supporting law enforcement in disrupting criminals and helping customers protect themselves from scams are core priorities for the finance industry.

“We welcome the committee’s recommendations that issues of liability and reimbursement should best be addressed by new laws rather than just a voluntary code alone, and the recommendation that third parties should be liable for the associated costs to financial services when they are responsible for data breaches that increase the risk of payment scams.”


Source Moneywise - 29 years of helping you with your finances https://ift.tt/2NCoazn

الأحد، 3 نوفمبر 2019

Ready to Leave Your Bank? How to Make the Switch in 5 Easy Steps

Love them or hate them, there’s no escaping the fact that you need a bank to keep your money safe. But if your current bank isn’t cutting it, you may be wondering how to switch banks and if switching to a new one is more trouble than it’s worth.

If you’re looking to change banks but aren’t sure where to start, this step-by-step guide will set you in the right direction.

What to Consider Before Switching Banks

Before you do anything with your current bank account, you’ll need to choose a new bank. Here are some things to consider.

Bank or Credit Union?

The first decision you’ll need to make: credit union vs. bank. 

The main difference between the two is how they are run. Banks are designed to make a profit by investing their money and growing their business. Credit unions are owned by members, who receive dividends on annual profits. Each have their pros and cons.

Online or Traditional?

Many credit unions are local organizations, so you’re likely to have an ATM close by you. 

Banks can be trickier. Local banks and larger national banks may have physical branches in your area so you can stop by and speak with someone in person with any questions or issues. But if you choose a bank without a physical branch near you or an online bank that doesn’t have brick-and-mortar locations, you’ll need to ask your questions online or over the phone. That can be stressful if customer service isn’t up to scratch.

You could also end up paying ATM fees if your bank doesn’t have a location near you, but many online banks will reimburse these fees.

Perks and Benefits

When you choose a bank, consider how much interest your money will earn, as well as any perks or benefits offered. You might be eligible for a cash bonus just for joining. 

But you’ll also need to weigh the perks against the fees, including overdraft charges. Also be aware of any minimum balance requirements.

Read Reviews

You might find a bank or credit union that looks perfect for you, but what do current customers think? Look for reviews online and ask your friends or family members to share their experiences. You might be put off by bad reviews and continue your search, or you might find good reviews of your chosen bank that put your mind at ease.

How to Switch Banks in 5 Steps

Ready to say goodbye to your bank? Here’s how to switch banks in five easy steps.

1. Open Your New Account

Once you’ve decided on a bank or credit union, you can start the process of opening a bank account. Whether you do this online or in person, it’s important to be prepared with the right documents, including a photo ID.

You’ll want to open your new account at least a few weeks before you want to make the official switch. This will ensure that your bills will be paid and you won’t be hit with late or overdraft fees.

2. Redirect Automatic Payments

You probably have a lot of your bills set up to autopay from your bank account. It’s vital that you switch these automatic payments to your new account as soon as possible to avoid missing payments.

Make a list of all the automatic payments you have. This might include, but isn’t limited to, the following:

  • Mortgage or rent
  • Car payment
  • Student loan payments
  • Credit card payments or other loans
  • Utilities, including gas, electric and water
  • TV provider, including cable, satellite and streaming services
  • Car insurance
  • Internet 
  • Cell phone bill
  • Gym or other club memberships
  • Charitable donations

Check previous bank statements to make sure you have all automatic payments listed. Once you have your list, start switching over your autopay information. It’s a good idea to ask for an email receipt for confirmation.

Pro Tip

Go back through 12 full months of bank statements to make sure you don’t miss automatic payments that you only make quarterly or annually. 

3. Contact Your Employer

Many employers, especially larger ones, pay via direct debit. Contact your employer ASAP to let them know your new account details to avoid a paycheck delay.

Your employer may require you to fill out a form with the new information or provide a voided check. Make sure you ask exactly what they need from you to ensure the switch goes smoothly.

If you have more than one employer or receive other direct deposits, such as child support payments, make sure you update that information as well.

4. Transfer Your Money

Once you’re sure your automatic bill payments and direct deposits are up to date, move any remaining money from your old checking and savings accounts to your new ones. 

Depending on your bank, you may be able to transfer the money to your new account free of charge. If you’re faced with a fee for the privilege of moving your money, you can request a check from your old bank that you can deposit into your new account.

5. Close Your Old Account

Once your new account is set up and established, it’s time to close your old account. Wait a month or two to make sure all direct deposits and automatic payments are set up properly with your new bank before closing your old one. The last thing you want is to have your water cut off for non-payment when you thought you’d switched that bill over.

Make sure you’ve paid off any outstanding balances on your old accounts before moving funds. Failing to do so could make it harder to open bank accounts in the future.

No matter why you’re switching banks, it’s important that you feel confident in your decision. Follow these steps to ensure an easy transition between your old and new banks.

Catherine Hiles is a writer, mother, runner and avid reader. She enjoys cooking (and eating), good beer and spending time with her husband and two young children.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder https://ift.tt/2qeHSJA

السبت، 2 نوفمبر 2019

Inspiration from Rumi, Libby, Kurt Vonnegut, and More

Once a month (or so), I share a dozen things that have inspired me to greater personal, professional, and financial success in my life. I hope they bring similar success to your life. Please enjoy the archives of earlier collections of inspirational things.

1. Harry Truman on credit

“It is amazing what you can accomplish if you do not care who gets the credit.” – Harry Truman

Part of the reasoning for my goal of financial independence is that I want to reach a point where I don’t need or even want the credit. I just want to do good stuff.

Why do I need credit? One of the big reasons people take credit for things is that they want to secure their income. Many people take a very strong-arm approach when it comes to getting credit in their professional lives and even their community lives because their finances aren’t rock solid and they’re very wary about losing their job. It’s an extremely short term approach – over the long term, it’s much more valuable to have humble people who just want to produce things – but often some level of credit for hard work is needed just to keep one’s job and one’s career on track.

(The best thing you can do for your career, in my opinion, is to stand on a stage and dole out credit. You inherently get the credit for being in the spotlight, but you appear humble because you’re doling out the credit.)

I look forward to a day for me when credit essentially doesn’t matter and all that matters is the good results. I want to spend a day weeding a community garden or restocking a food pantry shelf or putting some vegetables on the front step of someone who is food insecure or fixing a maintenance problem in the headquarters of a charity or emptying the trash there. Those things don’t win you credit and they certainly aren’t going to earn you an income, but they do make things better.

2. Libby

The last five books I’ve read have all come into my hands for free using the Libby app.

Basically, it’s a very slick app for getting e-books and audiobooks from your local library for free. Most libraries check out books in a format you can easily read or listen to on your phone, and Libby lets you download them (or get into the reserve queue for them) at your leisure. And, again, it’s all free.

I have a whole bunch of books I’m waiting on in the Libby app and when one comes available, I can snag it with ease. Because several have come available in a very short succession, I’ve found myself using Libby a ton.

3. Marcus Aurelius on needing help

“Don’t be ashamed to need help. Like a soldier storming a wall, you have a mission to accomplish. And if you’ve been wounded and you need a comrade to pull you up? So what?” – Marcus Aurelius

American culture often lauds the “go it alone” mindset, implying that “going it alone” makes you seem tough and leads you to accomplishing great things. The reality is often the opposite – many of the greatest moments in American history are almost purely team efforts, starting with the American Revolution itself and continuing with basically every significant development and moment in American history. Those moments are very rarely due to one person alone – they’re almost always a team effort, with people working together for some cumulative effort.

Even when you do hear stories about people “going it alone” and succeeding, you’re hearing the one success that stands in rare opposition to a thousand failures you never hear about.

Why does a team work better? Because, inevitably, some members of a team will struggle, and there are teammates around to lift that teammate up and get that teammate back on track. Without a team, if that person starts to struggle, they fall.

You don’t have to “go it alone” with anything in your life. It might seem like a better storyline, but it’s much less likely to lead to success. Surround yourself with people who will help pick you up when you slip, and help pick other people up when they slip.

4. George Harrison – All Things Must Pass (demo)

This song has gotten me through many rough moments in my life – not the overly loud album version, but this stripped down demo (and this even more stripped down earlier demo).

For me, it’s a gentle audio reminder that bad things will happen in life, but they will pass and joy will be fond again. Furthermore, the people in my life that brought about the pain – often people I loved passing away – would never want me to dwell on that pain. They would want me to remember them fondly with a laugh and a smile, not tears.

Things in life can hurt, but if they were worthwhile, they shaped you in a positive way. As they pass, remember not the pain of losing them, but the shape they impressed on you while they were with you.

5. Paul Gauguin on learning

“The public wants to understand and learn in a single day, a single minute, what the artist has spent years learning.” – Paul Gauguin

I take this in two ways.

On the one hand, many people want to become masters of a particular craft super quickly when, in reality, you cannot master some crafts without a lot of work. I think it’s possible to become competent in a particular area pretty quickly, but to master it? That takes a long time. I understand the feeling of having worked for many years to build a particular skill, watch someone else build a skill to a reasonable level quickly, and then feel like they’ve achieved equal mastery. It can be frustrating.

On the other hand, isn’t the purpose of art to make the viewer see the world a little differently, and doesn’t that rest on the back of many years of skill built by the artist?

I think this quote speaks to two different things, depending on how you read it. A craftsperson who has achieved a lot of skill thanks to a lot of work can be frustrated by other craftspeople. At the same time, a craftsperson who builds a high level of skill deserves appreciation from the general public.

This quote made me think, and anything that makes me think and keeps resonating in my head inspires me.

6. C.S. Lewis on someone

“There is someone that I love even though I don’t approve of what he does. There is someone I accept though some of his thoughts and actions revolt me. There is someone I forgive though he hurts the people I love the most. That person is …… me.” – C. S. Lewis

Literally no one on this earth is perfect. We all make mistakes. We all do things that hurt the people around us, often without even realizing it. We all let our emotions get the best of us sometimes.

It happens. It’s life.

All you can do is pick yourself up, do what you can to honestly admit your sorrow and make amends, and then strive to do better the next day. You have to do those things with honest intent, though. Apologize honestly, with true intent. Aim to do better, with true intent.

No one is ever going to be perfect, but we can all be better than we used to be.

7. Robert Wright – Why Buddhism Is True

This is a book that I’d be very tempted to write a full “Books with Impact” article on if it wasn’t just a bit too far outside of the purview of what makes sense on this site.

The point of this book is simple: Wright takes the secular elements and practices of Buddhism and analyzes them from philosophical, psychological, and medical perspectives and makes a pretty good argument for the life benefits of secular Buddhism, which I’ve written about before.

I tend to view Buddhism as two distinct pieces: a secular philosophy free of theological entanglements and as a religion. I’m also of the belief that the secular philosophy couples well with handling modern life, and it couches itself well with other religions. You can practice secular Buddhism hand in hand with any religion you want, including atheism.

What does it address? As I wrote in the other article, secular Buddhism tackles the problem of desire. We all desire things, and at times those desires can become all-consuming. Secular Buddhism is effectively a set of practices for helping you quell endless desire. This doesn’t mean you don’t have goals or other things, but that you’re able to quiet the constant churn in your gut of wanting more and more and more things.

This book does an amazing job of addressing desire and it’s well worth reading.

8. Mary Anne Radmacher on courage

“Courage does not always roar. Sometimes it is the quiet voice at the end of the day saying, I will try again tomorrow.” – Mary Anne Radmacher

Life knocks all of us down sometimes. There are days where you spend all day working and feel like you didn’t make an iota of difference. There are days where you just feel defeated and don’t make any real progress on anything.

Many times, courage is simply getting out of bed and tackling it all again. Courage is someone who is really struggling who managed to make it out of the house this morning. Courage is a 16 year old girl, almost completely forgotten by her parents in their alcohol and drug-fueled world, managing to make it to class most of the time.

Courage often doesn’t scream. You often don’t see it. But it’s all around us.

9. Herman Narula on the transformative power of video games

From the description:

A full third of the world’s population — 2.6 billion people — play video games, plugging into massive networks of interaction that have opened up opportunities well beyond entertainment. In a talk about the future of the medium, entrepreneur Herman Narula makes the case for a new understanding of gaming — one that includes the power to create new worlds, connect people and shape the economy.

I am an enormous believer that games – in reasonable moderate amounts – are a profoundly powerful way to connect with other people while nudging you to think in different ways, a true social art form like music can be and painting can be. The downside of games is when they become too much and you allow them become too much of your life – they work best in moderation.

Over the years, games have led me to connect with many, many people, build quite a few lifelong relationships, learn how to think in new ways (both creatively and strategically), and learn new ideas (like, for example, the history of Afghanistan).

There’s a lot of power and beauty in a good game, both for the thinking it nudges in your brain and for the connections it nudges you to make.

10. Stephen King on talent and persistence

“Talent is a wonderful thing, but it won’t carry a quitter.” – Stephen King

You can have all of the talent in the world, but if you don’t put in the work, it won’t take you to where you want to go. At the same time, it doesn’t take much talent to be wildly successful – less than you might think – if you combine it with tenacity and hard work.

Hard work is the key. Almost all of the time, when you see someone who’s wildly successful, there has been a ton of work done in the background that you don’t see, even when you might not think so. There’s often considerable planning, considerable thought, and tons of effort.

Effort is the magic, not talent.

11. Kurt Vonnegut on six seasons

“One sort of optional thing you might do is to realize that there are six seasons instead of four. The poetry of four seasons is all wrong for this part of the planet, and this may explain why we are so depressed so much of the time. I mean, spring doesn’t feel like spring a lot of the time, and November is all wrong for autumn, and so on.

Here is the truth about the seasons: Spring is May and June. What could be springier than May and June? Summer is July and August. Really hot, right? Autumn is September and October. See the pumpkins? Smell those burning leaves? Next comes the season called Locking. November and December aren’t winter. They’re Locking. Next comes winter, January and February. Boy! Are they ever cold!

What comes next? Not spring. ‘Unlocking’ comes next. What else could cruel March and only slightly less cruel April be? March and April are not spring. They’re Unlocking.”
– Kurt Vonnegut

This absolutely nails something I’ve long felt about the seasons, that there is a distinct difference between early and late fall and early and late spring.

In my part of the world, early fall is when you’re harvesting from your garden, and late fall is the season of frosts and minor snowfalls and cold weather that’s cold enough that you bundle up but you still want to go on walks. Here, the transition between the two happens sometime between October 15 and, say, November 30 most years; I’d estimate it happened around October 24 this year.

In the spring, the reverse is true. Early spring is a period where the days are consistently above freezing and the winter snow accumulation slowly melts, but it’s not warm enough to really encourage much green growth. That’s usually March to mid April or so. At some point, it kicks to a warmer level and the green growth takes off – grass becomes bright green and starts growing rapidly, trees and bushes bud and grow leaves, the asparagus grows like wild, you can find morels in the forest. This usually hits sometime around April 10 or so and lasts until maybe mid-June, when summer begins in earnest.

This passage struck me because it was one of those moments where someone expressed something I’d understood and felt before but never really expressed, and it’s those moments that the beauty of human communication really comes through.

12. Rumi on your words

“Raise your words, not your voice. It is rain that grow flowers, not thunder.” – Rumi

If you want to say something meaningful, shouting it won’t get the message across. People might hear you, but they won’t listen. People listen to words, not shouting. In fact, a loud voice often harms the message you’re trying to share. All it often gets across is intense emotion.

A much better approach: learn to craft your words to say what you mean rather than shouting to try to get a message across.

This was a lesson I had to carefully learn after becoming a parent. When a toddler does something wrong and you know it’s going to be a lot of work and a lot of frustration to fix it, there’s a desire sometimes to shout. Yet, again and again, I found that kneeling down to their level and talking to them quietly with carefully chosen words was far more effective than shouting 99% of the time, and if you save the loud voice for very rare occasions, it has far more impact.

The post Inspiration from Rumi, Libby, Kurt Vonnegut, and More appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2qb9mzU