Thousands of courses for $10 728x90

الاثنين، 11 نوفمبر 2019

Veridian Mortgage Review

Veridian Credit Union was founded in 1934 by a group of employees working for Deere & Company, who established its headquarters in Waterloo, Iowa. Originally named The John Deere Employees Credit Union, this banking institution has operated as a not-for-profit entity since its inception, but only extended its field of membership in 1986.

Today, individuals and families living in Iowa and parts of Nebraska can take advantage of Veridian’s full-spectrum banking service, which includes a range of conventional and government-backed home loan products.

Table of Contents

Veridian Credit Union Background

Since 1934, Veridian Credit Union has supplied its members with home loan options that suit a diverse range of financial needs. Formal membership is required to qualify for Veridian’s mortgage programs, which are widely available to residents living in Iowa and some counties in Nebraska.

Once a membership is obtained, borrowers can choose from conventional and jumbo fixed or adjustable-rate mortgages, along with government-backed options like IFA, USDA, and VA loans. Qualified first-time homebuyers may be eligible for a fixed-rate mortgage with down payments as low as 3 percent and financing up to a 97 percent loan-to-value ratio, though some restrictions may apply.

As a not-for-profit credit union, Veridian is solely dedicated to providing affordable rates and personalized service to its members. Borrowers can apply for a home loan in person, over the phone, or through the credit union’s website.

Veridian also provides prospective customers with a host of educational resources and tools that can help them secure the best mortgage option with monthly payments they can afford.  While specific credit score and debt-to-income requirements are not readily available via the website, Veridian’s live chat feature makes it easy to get in contact with a lending agent for further details.

Overall, this lender is a great fit for first-time homebuyers and low-to-moderate income borrowers living and working in Iowa.

Current Veridian Mortgage Rates

Today's Best Home Mortgage Rates
Select your state to get started

Veridian Mortgage Options

Veridian Credit Union provides its members with a diverse selection of mortgage options, including fixed and adjustable-rate, IFA, USDA, VA, and jumbo loans. It also offers a range of specialty programs and promotions that are uniquely tailored to meet the needs of Iowa residents, first-time homebuyers, and borrowers who are unable to make large down payments.

Fixed-Rate Loans

This traditional mortgage option maintains stable interest rates and monthly payments over the full life of the loan, regardless of any fluctuations within the market index. Veridian offers fixed-rate loan terms of 10, 15, 20, 25, and 30-years, though a longer repayment period typically results in higher rates.

Eligible first-time homebuyers can put as little as 3 percent down on this lender’s 15- and 30-year loan products, though some restrictions apply. This loan type is well-suited for homebuyers that want to stay in one place for the long-term.

Adjustable-Rate Loans

These types of loans are based on variable interest rates, which means monthly payment amounts can vary depending on market conditions. Rates may increase or decrease over time, though Veridian has a yearly cap of 2 percent and a lifetime cap of 6 percent on all rate adjustments.

Borrowers can select from an initial fixed-rate starting period of five, seven or 10 years, though longer periods may result in higher rates. Overall, adjustable-rate mortgages feature lower interest rates than other loan types, making it a solid choice for homebuyers with comfortable incomes or those that plan to move before their rates begin to adjust.

IFA Loans

These mortgages are backed by the Iowa Financial Authority and provide low-cost title protection for purchases up to $500,000. The IFA offers two mortgage programs, both with 30-year fixed-rate terms. The FirstHome Program is available to first-time homebuyers who want to purchase a primary residence in Iowa.

The Homes for Iowans Program can be obtained by both first-time and repeat homebuyers who qualify, though eligibility guidelines are strict. IFA’s mortgage programs have income limits, purchase price limits and borrowers must have a minimum credit score of 640 and a maximum debt to income ratio of 45 percent.

USDA Loans

This loan option is facilitated by The United States Department of Agriculture and extends 100 percent financing options to qualified borrowers. Homebuyers with low to moderate-income are encouraged to apply, but the property in question must be located in a designated rural area.

Eligible borrowers with credit scores above 640 can benefit from zero down payment requirements and affordable interest rates. Income limits for these types of loans, however, are strict.

VA Loans

Qualified veterans and service members may benefit from this mortgage type, as it features no down payment minimums and does not require private mortgage insurance. Backed by the Department of Veterans Affairs, these home loans provide eligible borrowers with affordable rates and a range of financing options, though a minimum credit score of 620 is typically required.

Government-backed loans tend to have lower interest rates than conventional mortgages, along with reduced closing costs. This loan type also allows the seller to pay up to 4 percent of the purchase price toward closing costs, but gift funds are not allowed.

Jumbo Loans

Veridian provides jumbo loans on mortgages that exceed $417,000, though the conventional conforming limits are typically set by the Federal Housing Finance Agency (FHFA). The agency recently announced that the 2019 maximum conforming loan limit for one-unit properties will be $484,350.

Eligible homebuyers can obtain either a fixed or adjustable-rate jumbo mortgage, though specific information about credit score and down payment requirements is not available on the credit union’s website.

Veridian Mortgage Customer Service

Veridian Credit Union mainly operates in Iowa, with membership open to persons living in or working for a business within any of the state’s 99 counties; it also services a few communities in Nebraska, including Cass, Douglas, Lancaster, Sarpy, Saunders, and Washington counties. Members can extend their benefits to any family member, making it easy for Iowa residents to partner with this credit union.

Veridian’s small service area allows it to focus exclusively on the unique needs of residents in this region. Interested homebuyers can contact a representative by visiting a physical branch, via phone or email, or by using the live chat feature on Veridian’s website. Borrowers must first obtain formal membership with the credit union before they can apply for a home loan from this lender.

In addition to information on its various loan products, Veridian’s website contains a host of educational resources that can help members understand the mortgage application process and secure affordable rates, including blogs, checklists, FAQ pages, and a video series tailored to first-time homebuyers.

The website also permits members to apply for pre-qualification and to submit a mortgage application entirely online, without the need for visiting a branch in-person. Additionally, Veridian’s home and mortgage calculators make it easy to compare different loan options, but members cannot receive personalized rate quotes through its website.

Veridian Grades

Veridian has earned the reputation as a member-focused credit union with over 80 years of experience serving the banking needs of Iowa residents. The financial entity has been accredited as an Equal Housing Lender and its members are insured by The National Credit Union Administration for up to $250,000.

While Veridian does hold an A+ rating from the Better Business Bureau, its BBB profile currently features a one-star customer rating based on a handful of reviews. In total, only 15 customer complaints have been filed against this credit union over the past three years.

  • Information collected on Jan. 17, 2019

Veridian Mortgage Qualifications

Loan Type Rate Type Loan Terms
Fixed-Rate Loans Fixed 10, 15, 20, 25, and 30 years
Adjustable-Rate Loans Variable 5-1 ARM, 7-1 ARM, and 10-1 ARM
IFA Loans Fixed 30 years
USDA Loans Fixed 30 years
VA Loans Fixed or Variable 30 years
Jumbo Loans Fixed or Variable N/A

Home loans from Veridian are only available to homebuyers who have obtained official credit union membership and each program has unique eligibility guidelines. The credit union’s website does not provide any information on median income or debt-to-income requirements, nor does it specify whether its mortgage offerings have minimum credit score qualifications.

According to FICO, the standard credit score stands at around 740, which is needed to secure the best available mortgage rates. Most lenders will consider applications from borrowers with credit scores as low as 680, but direct confirmation from a lending agent is advised. It is unclear whether Veridian considers non-traditional credit history for determining program eligibility or interest rates.

Many of Veridian’s government-backed mortgages feature less strict qualification requirements. For example, USDA loans can be obtained with little or no down payment and up to 100 percent financing, but the property must be located within an eligible rural or suburban area.

Veridian also extends a number of affordable fixed-rate programs for first-time homebuyers, allowing down payments as low as 3 percent for 15 and 30-year repayment terms. Additionally, closing costs can be paid for with borrowed funds, a gift, grant or other permitted source, though some program restrictions apply.

Veridian Phone Number & Additional Details

The post Veridian Mortgage Review appeared first on Good Financial Cents®.


Source Good Financial Cents® https://ift.tt/2p99H5Z

Hard vs. Soft Inquiry: What You Should Know Before a Credit Pull

Every time you turn around, someone wants to run your credit. 

New apartment? The landlords want to see your credit. Applying for a job? Same thing. Oh, and that really cool “freebie” blanket you could get just for signing up for a new credit card? They’ll definitely run your credit first.

One thing you’ve probably heard is that credit pulls can hurt your credit score. How can that be? If you’re going to get credit, there needs to be a credit inquiry first, right?

There are two types of credit inquiries: hard and soft inquiries. What are they? How are they different? Here’s what you need to know to keep your credit score looking shiny.

Soft vs. Hard Credit Check

Both types of credit pulls involve someone checking in on your credit, but that’s about where the similarities stop. Here’s the difference between a soft vs. hard credit check and what it means for you.

Hard Inquiry

Simply put, a hard inquiry happens when a lender, like a bank or credit card company, runs your credit history as a part of its decision-making process. They may run your credit with one or more of the major credit bureaus. 

Will they give you that loan? Will you get that credit card? What they see on your credit report may make it happen…or not. 

Soft Inquiry

A soft inquiry happens when you check your own credit score or even if a lender checks it for the purpose of prequalifying you for a loan or credit card. 

If a potential landlord or employer does a credit check, that would also count as a soft inquiry. Think of it as a glance at your credit rather than a deep dive. 

How Do Credit Inquiries Affect Credit Score?

Here’s where it gets interesting. Each type of credit pull affects your credit differently. Here’s how it breaks down for soft vs. hard credit checks. 

Hard Inquiry

Because a hard inquiry is used by someone who is actually checking your creditworthiness for the purpose of issuing you some form of credit, it factors into your credit score. 

Having multiple hard inquiries in a short amount of time could mean that you’re attempting to open multiple accounts. Why is that an issue? Because it could mean that you’re trying to use credit to stay afloat during financial troubles. 

Since that’s a red flag to lenders, hard inquiries have a negative effect on your account for a short time.

Soft Inquiry

Soft inquiries are not used to issue new credit to you and, therefore, do not affect your credit score. In fact, with a couple of exceptions, you are the only one who can even see soft inquiries on your credit report at all. 

The two exceptions are that insurance companies can see other insurance company inquiries, and lenders can see if you’ve had inquiries from debt settlement companies. 

Soft inquiries are not a factor in your credit score at all, so there’s no need to sweat them. 

Pro Tip

Before applying for a loan, show the lender your credit report and ask them to prequalify you. This way, you don’t have to apply multiple times and risk denial. 

3 Reasons Not to Worry Too Much About Credit Inquiries

Anything that can affect your credit score is worth your attention, but with credit inquiries, there’s little reason to panic. Here are a few things to keep in mind.

1. Multiple Inquiries Won’t Count Against You When You’re Loan Shopping

The credit bureaus understand that smart consumers are competitive shoppers. If you have multiple hard credit inquiries for a car loan, mortgage, or something similar, they’ll simply flag it as one hard inquiry. They want you to be a smart consumer, so why would they penalize shopping for the best loan? 

Pro Tip

If you’re shopping around for a loan, keep your search window to a two-week period. If it stretches out longer, you could end up with multiple credit inquiries on your report.

2. A Hard Pull Matters Less Than You Think

Most consumers will only see a drop in their score of five points to less for a single hard inquiry. Unless you have a bundle of inquiries happening at once, it’s not a big deal.

3. Other Factors Have a Bigger Impact on Your Score

There are five factors that determine your credit score. Credit inquiries only make up 10% of that. Your payment history and credit utilization ratio are much greater factors in the big picture.

Yes, you should be aware of credit inquiries and how they can affect your score, but there’s no reason to panic. There’s no need to worry that a potential landlord or employer doing a credit check will hurt your score. Shopping for the best car loan online? Go crazy. 

As for that cool freebie blanket? You’d do better to save up and buy one rather than get a credit card that’s not right for you. You’ll sleep better that way. 

Tyler Omoth is a freelance writer covering topics from personal finance to career advice and even lawn care. His work has been featured on TopResume.com, Writersweekly.com and more. He is also the author of over 70 educational books for children and a proud parent of twin toddlers. 

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder https://ift.tt/34NAL9W

Councils need billions more to fund adult social care, IFS report warns

Councils need billions more to fund adult social care, IFS report warns

A growing elderly population and rises in the number of disabled adults mean councils face unprecedented pressures on their finances

Stephen Little Mon, 11/11/2019 - 10:39
Image

English councils will need billions in extra funding over the next parliament if they are to meet the rising costs of providing adult social care, a new report warns.

Analysis from the Institute for Fiscal Studies (IFS) shows that a gap is likely to open up between council's income and what they need to meet the rising costs of adult social care.

It calculates that with council tax rising in line with inflation, by the end of the parliament councils will need an extra £4 billion a year from the government maintain social care services at current levels. This would rise to £18 billion a year by the mid-2030s.

Councils are now largely dependent on council tax and business rates to fund their spending.

They also face a number of pressures on their finances, including a growing elderly population, increases in the number of disabled adults, and increases in wage and other costs.

The IFS says that even if council tax goes up by 4% a year every year, councils may need an additional £1.6 billion a year in real-terms funding by 2024–25, growing to £4.7 billion by 2029–30.

Election pledges

The IFS says the costs of any increases pledged by parties in the election campaign would come on top of these pressures.

Labour has pledged to introduce free personal care for all people over 65, providing help with daily tasks.

The Conservative Party has so far been less specific about its plans, as its manifesto is yet to be published, with Boris Johnson saying the it would “solve the problem of social care and end the injustice that means people have to sell their home to pay for their old age”.

The government has allocated £1.3 billion in funding for the 2020–21 financial year, and councils with social care responsibilities will be allowed to increase council tax by up to 4%.

The IFS says that even if this additional funding was spent in full, it would only be enough to undo around one-fifth of the peak-to-trough fall in councils’ spending on services.

However, not all councils benefit equally from the additional funding planned for next year and some may even see their funding fall.

This is because because some councils have benefited from pilot schemes allowing them to retain more of the growth in local business rates revenues, and most of these pilots will come to an end in March.

Plugging the funding gap

The IFS is calling for local councils to be given additional tax raising powers - such as via a local income tax – to help plug the long-term funding gap.

It says this would give councils and their residents more discretion over how much to tax and spend, and stronger financial incentives to grow the local economy.

Additional grant funding from Westminster would also allow money to be targeted at places where spending needs are the highest or local revenue-raising capacity is the lowest.

David Phillips, author of the work and an associate director at the IFS, says: “The additional funding announced for councils next year could be just a lull in the storm. Detailed public spending plans for 2021–22 and beyond have not yet been published.

"But we do know that councils will rely on council tax and business rates for more of their funding going forwards.

“And those revenues just don’t look like they will keep pace with the rising costs of services like adult social care – even with council tax bills going up at 4% a year, which is double the rate of inflation.

"That means finding billions more in funding to top up existing local tax revenues, even before thinking about new initiatives like free personal care.”


Source Moneywise - 29 years of helping you with your finances https://ift.tt/2Kbp0Ch

الأحد، 10 نوفمبر 2019

6 Reasons You’re Struggling to Get Your Online Business Off the Ground

It’s not uncommon for confusion to replace enthusiasm when a budding entrepreneur comes to realize just how many moving parts there are in a successful online business. It’s all too easy to get discouraged when earning that first dollar takes longer than expected. If you’re still wondering how to get your online business off the […]

The post 6 Reasons You’re Struggling to Get Your Online Business Off the Ground appeared first on The Work at Home Woman | Legit Work From Home Jobs.


Source The Work at Home Woman | Legit Work From Home Jobs https://ift.tt/2Ka516Y

The Best Phone Services for Small Business

As a small business owner, it’s crucial for you to stay up to date with the latest technology and trends. Yet there are still so many businesses out there using traditional phones for work purposes.

The fact that you’ve landed on this page means that you’ve at least recognized the need for a change.

Business VoIP phone services are increasing in popularity. This relatively new technology offers an alternative option to traditional phone lines.

What is a VoIP phone service?

The acronym stands for “voice over Internet protocol.” In simple terms, this is a phone service that operates over the Internet.

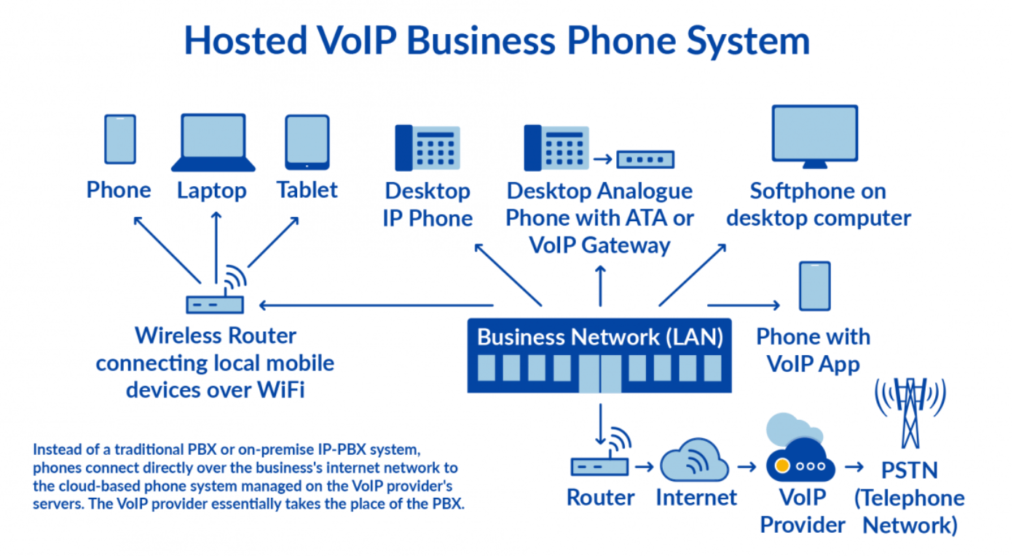
A VoIP creates a digital signal from any incoming or outgoing call. Then it converts that signal to reach any non-VoIP numbers as well. This cloud-based solution allows you to receive calls from a computer, VoIP phone, any phone with a VoIP adaptor, or mobile hotspot. Here’s a visual explanation of how it works.

How VOIP Works

But if you run a quick search for the best VoIP phone services, you’ll quickly learn that there are dozens, if not hundreds, of options to choose from.

That’s what inspired me to write this guide. I’ve identified the top phone service providers for small businesses. I’ll explain all of the benefits and show you the methodology for my conclusions. You can use this information to upgrade the phones at your company.

The Value of a Business Phone Service

Why do you need a business VoIP phone service?

Most small business owners rely on traditional landlines or mobile phones for communication. But landlines can take up lots of extra space around the office. Plus, you can’t take those with you on the go.

The majority of you might be using your personal cell numbers to handle business calls. While the system might work for you, it’s not as professional.

Sure—you could always get a business plan from a traditional wireless carrier. But those plans are pricey, especially when you add more lines.

These are some of the top benefits of using a business phone service:

  • Make and receive calls from multiple devices (computer, mobile, desk phone).
  • Track usage, hold times, and duration of calls.
  • Share one number with multiple users.
  • Add new employees without going into a store to buy a new phone.
  • Local and toll-free calls from anywhere with high-speed Internet.

Most business VoIP phone services also come with features like call recording, call waiting, call forwarding, and call routing.

Overall, a business phone service can add professionalism to any small business or website. It can improve communication in-house as well as with your customers.

The Best Business Phone Service Providers

Not every business phone service is the same. To find the best choice for your situation, read through the reviews of the best phone service providers for small businesses below.

You can compare the pricing, plans, and features of each one to identify the best fit for your small business.

RingCentral

ringcentral

With more than 350,000 businesses using RingCentral for VoIP phone services, it’s one of the most popular solutions in the industry.

I like RingCentral because they have plans that have been specifically designed for small businesses. It’s reliable, secure, easy to use, and delivers high-quality voice for crystal clear calls.

RingCentral is also affordable. You can save over 30% if you sign up and prepay with an annual plan as opposed to a month-to-month contract.

Here’s a quick overview of the plans and pricing:

Essentials

  • Starting at $19.99 per month per user
  • Up to 20 users
  • 100 toll-free minutes per month
  • On-demand call recording
  • Unlimited calls within US and Canada

Standard

  • Starting at $24.99 per month per user
  • 1,000 toll-free minutes per month
  • Unlimited Internet fax
  • Unlimited audio meetings
  • Unlimited video conferencing (up to 4 people per meeting)
  • On-demand call recording
  • Custom app development and deployment

Premium

  • Starting at $34.99 per month per user
  • 2,500 toll-free minutes per month
  • Unlimited video conferencing (up to 100 people per meeting)
  • Automatic call recording
  • Multi-site support
  • Salesforce and Zendesk integration

Ultimate

  • Starting at $49.99 per month per user
  • 10,000 toll-free minutes per month
  • Unlimited video conferencing (up to 200 people per meeting)
  • Automatic call recording

As you can see, RingCentral has a plan for everyone. You can also customize your plan to pay extra for things like additional toll-free numbers, vanity numbers, international numbers, and international toll-free calling.

All of the plans come with basic features like unlimited business SMS and MMS, mobile apps for iOS and Android, HD voice, team collaboration, call log reports, and 24/7 customer support.

The plan you choose will largely depend on how many toll-free minutes you plan to use as well as the number of users you’re going to onboard.

Grasshopper

grasshopper

Grasshopper is another popular option made for small businesses and entrepreneurs alike.

More than 135,000 users trust Grasshopper as their business phone service. The provider is responsible for over 140 million calls per year.

Grasshopper makes it easy for you to find toll free numbers, vanity numbers, 800 numbers, local numbers, and more. This simple solution is a great way to add professionalism to your business.

Here’s a quick breakdown of the plans and pricing:

  • Solo — Starting at $26 per month (1 number, 3 extensions)
  • Partner — Starting at $44 per month (3 numbers, 6 extensions)
  • Small Business — Starting at $80 per month (5 numbers, unlimited extensions)

The solo plan is the best option for an entrepreneur who has a small side business. You’ll want to upgrade to the partner plan if you have a small group of up to three employees working for you. For anything more than that, you’ll need the small business plan to accommodate your needs.

All Grasshopper plans come standard with the following features:

  • VoIP and Wifi calling
  • Virtual fax
  • Mobile and desktop apps
  • Business texting
  • Ability to handle simultaneous calls
  • Call reporting
  • Call forwarding
  • Voicemail
  • Call transfers
  • Extensions

Unlike other business phone services on the market, Grasshopper doesn’t have any restrictions for calling limits. You’ll also benefit from 24/7 live support.

Grasshopper also gives you the option to integrate your business interactions into one inbox that’s easy to manage. You can access your emails, texts, business calls, and contacts in one place.

Nextiva

nextiva

Nextiva is an industry leader in the business phone service space. More than 1 billion calls were made on their network in 2018. That is an astronomical number.

Overall, Nextiva is a larger company compared to some of the other providers on our list. They have more than 1,000 dedicated staff members on their team, which explains why they have a 94% customer satisfaction rating.

Nextiva has three simple plans. The price depends on the number of users and the length of your contract. There are plans to accommodate businesses of all shapes and sizes, with options for businesses with 1-4 users, all the way up to 100+ users.

Here are the starting rates for each plan, per user, for an annual contract:

  • Basic — $20 per month
  • Pro — $25 per month
  • Enterprise — $30 per month

These are the most affordable enterprise-level plans that we’ve seen so far.

Some other highlights of Nextiva’s small business phone service include:

  • Unlimited calls
  • Call queuing
  • Automatic call forwarding
  • Hold music
  • Free online fax
  • Free local and toll-free number

Unfortunately, some sought-after features are not included in the basic plan. If you want to use the Nextiva app, get unlimited conference calls, pre-recorded greetings, and text messaging, you’ll need to upgrade to the pro plan.

Call recording, voice analytics, and voicemail to text delivery are only available on the enterprise plan.

Phone.com

phone.com

Phone.com offers some of the most straightforward and simple VoIP business phone plans that you can find. The simplicity is one of the main reasons why their rates are so affordable.

You can sign up and get started in minutes. Building and managing your entire business phone system from the intuitive dashboard is easy for anyone, regardless of their technical skill level.

Phone.com has more than 50 standard features, including:

  • Fax to email
  • SMS messaging
  • International dialing
  • HD conferencing
  • Call screening and blocking
  • Call routing
  • Call queuing
  • Auto attendant

You’ll also benefit from E911 dialing, which is not offered by all VoIP providers. Premium features like caller analytics, call recording, video conferencing, and CRM integration cost extra.

Phone.com is HIPAA and HITECH compliant, which means it’s safe to use if your company is in the medical field.

Compared to other business phone services that we’ve seen, Phone.com offers a unique pricing structure.

They have standard plans with unlimited minutes starting at $24.99, $32.99, and $49.99 per month with an annual contract. Each tier comes with extra numbers, extra text messages, and added features that you would expect with the price increase.

However, Phone.com also has pay per minute plans starting as low as $9.99 per month. This is the lowest monthly rate that you’ll find from a reputable VoIP phone service provider. These plans are reserved for businesses that don’t need lots of minutes. The pay per minute plans offer 300 monthly minutes, 500 monthly minutes, and 1,000 monthly minutes, respectively.

So if your calls are relatively short and infrequent, you can definitely save some money with one of these budget plans.

Vonage

vonage

Vonage is a reputable and well-recognized name in the phone industry. They have been in business for nearly 20 years. Back in 2003, Vonage became the first VoIP platform for 911 calls.

While the company has a rich history, they just recently started providing business solutions.

They offer three different plans, with rates based on the number of lines you need. Here’s a brief overview of the plans and costs.

Mobile

This plan lets you make and receive calls from your mobile device and desktop computer. It’s best for smaller businesses that don’t need office phones.

  • 1-4 lines — $19.99 per month per line
  • 5-19 lines — $17.99 per month per line
  • 20+ lines — $14.99 per month per line

Premium

The Premium plan is made for traditional office teams. It allows for calls from any device, including desk phones.

  • 1-4 lines — $29.99 per month per line
  • 5-19 lines — $27.99 per month per line
  • 20+ lines — $24.99 per month per line

Advanced

This is the best option for businesses that need a phone service for team setups and onboarding.

  • 1-4 lines — $39.99 per month per line
  • 5-19 lines — $27.99 per month per line
  • 20+ lines — $34.99 per month per line

If you want CRM integrations, you’ll need to sign up for the Premium or Advanced plan. The Advanced plan also comes with on-demand call recording, group calls, and virtual voicemail.

All plans come with a 14-day free trial.

Ooma

Ooma has VoIP phone plans that are specifically made for small businesses. It’s an ideal solution for businesses with traditional offices that need desk phones.

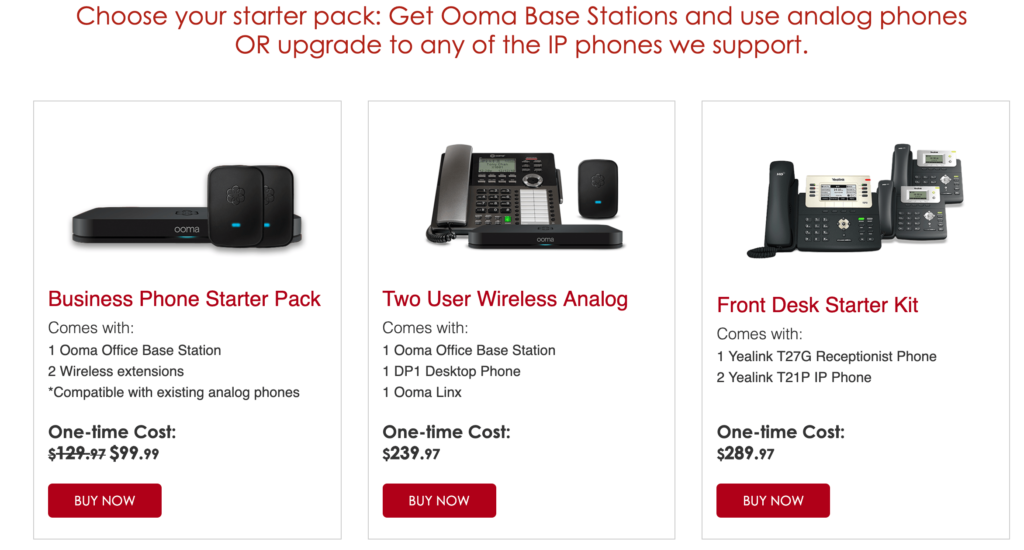
They have an extremely appealing pricing structure for new businesses. Just pay a flat rate of $19.95 per month per user. There are no contracts and you can cancel at any time.

However, there is a catch. The monthly rates don’t include hardware costs.

ooma

If you compare these to similar hardware offered by other providers, you’ll see that Ooma is definitely on the more expensive end of the spectrum. This balances out the lower monthly rates.

Ooma does have a mobile app, which allows you and your staff to make calls on the go from your smartphones. So theoretically, you could opt to go mobile-only and skip the hardware costs.

Although I would not recommend this. There are better options out there if you’re looking for a business VoIP phone service without any hardware.

So stick with Ooma if you want straightforward rates for your office phone. For those of you with a growing team, Ooma can scale with you. It’s easy to add on users, devices, and manage everything on your own.

Your plan will come with unlimited calling, a toll-free number, low international rates, and a virtual receptionist. Ooma also has exceptional customer support if you have any trouble setting up the hardware or managing your service.

Jive

jive

Jive is one of the best VoIP business phone services for those of you who want lots of all-inclusive features.

I like Jive because they strive to make enterprise-level communication available for small businesses. Their system is very easy to use, no matter how large or small your team is.

With Jive, you’ll get basic features like:

  • Call recording
  • Auto attendants
  • Call monitoring
  • Conferencing
  • Virtual fax
  • Custom greeting
  • Custom hold music
  • Dial by name or extension
  • Individual call logs

Other providers make you pay extra for some of these.

Jive makes it easy for you and your entire team to connect to your phone system from any computer or mobile device with an Internet connection. This is ideal for those of you who aren’t always tied to a traditional office setting.

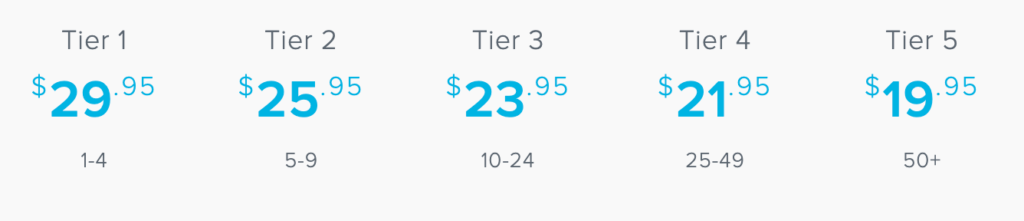
Pricing for these plans is based on users. Here’s an overview of Jive’s tiered-pricing structure.

jive pricing

As you can see, the more users you have, the less you’ll pay per month. But even the entry-level plans are affordable. When you factor in the premium features that are all-inclusive, it makes Jive a more appealing option than some other providers on the market.

Jive phones are extremely easy to set up. All you need to do is plug them in and you’ll be ready to make calls in minutes.

1-VoIP

1voip

1-VoIP is cost-effective and flexible. It’s a great option for small businesses on a tight budget that want a reliable phone service provider.

With plans starting as low as $14.97 per month, 1-VoIP doesn’t have the absolute cheapest rates that we’ve seen in this guide, but it’s very close.

If you don’t make calls often, you can take advantage of 1-VoIP’s metered pricing structure. Only pay for what you use. In this case, you’ll be charged just $0.02 per minute.

Unlike other providers on the market, 1-VoIP doesn’t cut out basic features if you sign up for the metered plan. You’ll still have all of the features that come with the other plans, including:

  • Queues
  • Hold music
  • Virtual fax
  • Digital call forwarding
  • Call recording
  • Hours of operation
  • Extension transfers
  • Call waiting

Altogether, there are 40+ features that come standard.

If you’re only using up to 200 minutes per month, the metered plan will be your best bet. Otherwise, they have package plans starting at $19.97 and $29.97 per month per extension.

How to Find the Best Business Phone Services For You

Now that you are more familiar with some of the top business phone services on the market, it’s time for you to choose a plan for your small business.

To make this easier for you, I’ll explain the process that we used to evaluate the plans and services on our list. You can use the same criteria to find the best business phone service for you.

Business size

The first thing you need to do is figure out how many lines and users you’ll need. There are certain plans out there that are geared toward small businesses with just a handful of people, while other options are best for teams of 20, 50, or more.

In most cases, you’ll pay less per month per line if you have more users. Larger companies should look for these plans to get the best rate.

But if you have a small team and only need a couple of lines, then it’s best to stay away from tiered-pricing models. Instead, look for package deals that are made for smaller organizations.

Price

In addition to the size of your business, the length of your contract can also have an impact on the price you pay. Some providers try to lock you into an annual deal to lower monthly rates. But this structure can be an expensive upfront cost.

For simplicity sake, let’s say you’re signing up for a $20 per month per user plan, renewed annually.. If you have 10 users, this plan will cost you $2,400 upfront when you sign up.

So make sure that you’re happy with your provider before you lock in any long term deals. I’d recommend a service that offers month-to-month rates. Try them out before you consider something long term.

Whatever you decide, just make sure that your VoIP business phone plan fits your budget. There are some cheap plans out there with fewer features, as well as some higher-cost plans with lots of extra benefits.

Reputation

Make sure you choose a provider that is reliable and has a good reputation in the industry. Read third-party online reviews to see what customers are saying about them.

Think of this the same way as your mobile phone plan. Networks like Verizon, AT&T, and Sprint have better reputations than some of the lesser-known brands out there.

Sure—sometimes a smaller or lesser-known carrier can offer a cheap alternative. But in many cases, you get what you pay for.

A trusted provider might be a bit more expensive, but it’s better than having a poor connection and calls dropping.

Ease of use

Although the concept of a VoIP phone may seem complex, using a business phone service shouldn’t be difficult.

In terms of setup and onboarding, you should look for a service that can be up and running in minutes. If you’re making calls from a mobile app or desktop computer, then you can start instantly.

For those of you who will be using VoIP desk phones and other hardware, look for providers that have simple solutions. If the hardware setup takes too long, it’s just not worth the hassle. Plus, the more complex the setup, the more difficult any troubleshooting will be.

Taking calls, making calls, transferring calls, recording calls, reviewing call logs, setting up your voicemail, and everything else should be simple as well. If you and your team are having problems doing these things during your first month or free trial, you should look elsewhere for an easier to use service.

Free features

Every business phone service comes standard with basic features depending on the plan you choose. Some of these will be more useful to you than others.

It’s up to you to review those features to see which ones you’ll actually use. Then find a plan that includes those features for free.

For example, you might be drawn to a plan that has 50+ features, even though you’re only going to take advantage of 10. But if that plan doesn’t include something you need, such as call recording, then it’s not worth it to pay extra for that if you can get it for free elsewhere.

So shop around and compare feature lists to make sure you’re getting the best value for your needs.

Conclusion

Business VoIP phone services are a great option for small business owners. These phone services add a higher level of professionalism to your company. They are also cheaper and more flexible than traditional landline office phones.

So what’s the best phone service for small business? It depends on what you’re looking for.

  • RingCentral — The most popular VoIP phone service for small businesses.
  • Grasshopper — Best phone service for solo entrepreneurs.
  • Nextiva — Most affordable enterprise-level plans.
  • Phone.com — Best cheap small business phone service plans.
  • Vonage — Pioneer in the VoIP phone industry.
  • Ooma — Best for traditional office settings with desk phones.
  • Jive — Tiered pricing with all-inclusive features.
  • 1-VoIP — Flexible and cost-effective metered pricing for small businesses on a budget.

I made sure that this guide included something for everyone. No matter how big your team is or how small your budget is, you can definitely find a reliable phone service for your small business on the list above.


Source Quick Sprout https://ift.tt/2KaPT9v

What Makes or Breaks an Ecommerce Purchase?

Every ecommerce sale can be tied to a decision made by the consumer. There’s a moment in the customer journey process that sways people to buy or pass on a product.

What defines this moment?

I often get asked what makes or breaks an online purchase. If you don’t know the answer to this, then you can’t run a successful ecommerce operation.

Lots of experts out there will tell you to “do this” or “do that” to increase ecommerce sales. But I always let the data do the talking for me.

Sure—in theory, nearly every strategy sounds good. However, if you can’t tie those strategies to concrete evidence, then it’s just guesswork. I don’t know about you, but I wouldn’t let my business rest in the hands of someone’s best guess.

That’s why I’m always on the hunt for the newest research and studies related to ecommerce and consumer behavior.

I recently stumbled upon an ebook called Understanding the Future of Ecommerce Personalization, published by AB Tasty.

The ebook reports the findings of a study where 2,000 people were surveyed throughout the globe. The survey questions were used to discover the advantages, concerns, and frustrations of consumers shopping online.

Based on these findings, I was able to draw conclusions on the factors that make or break an ecommerce sale.

When in doubt, turn to the data. All of the data below came from the AB Tasty report. I’ve thrown in my own two cents as well to provide actionable steps for ecommerce websites.

Improve Your Product Pages

Any visitor that lands on your product pages didn’t do so by mistake. By this point in the buying process, the consumer has already identified their need or want for a specific product.

From your product page, people are just a click or two away from finalizing a purchase. That’s why these pages need to be perfect.

It’s no secret that the ecommerce industry is booming. People are buying online more than ever before. But with that said, the process of buying something online has its flaws.

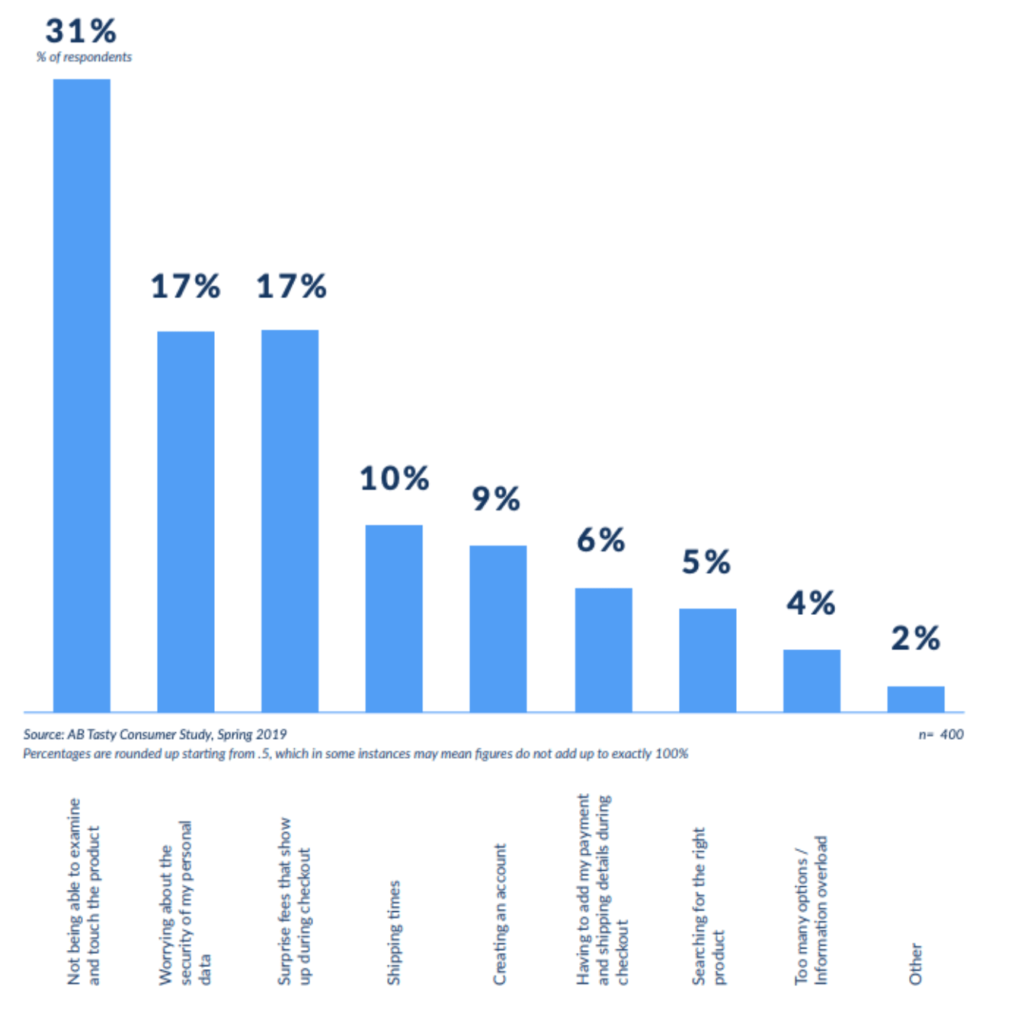
According to the research by AB Tasty, being unable to touch, feel, and examine a product is the most frustrating part about shopping online.

AB Tasty Study

As you can see from the graph, this response dominated the other pain points.

Touching or feeling a product through the Internet is obviously not realistic, at least not in this lifetime. So your product pages must emulate that in-store experience as much as possible.

One or two images just won’t get the job done. You need to use lots of high-quality images of whatever you’re selling and show the product from every angle. The idea here is that you don’t want your customers to be surprised when the product arrives at their doorstep. It should be clear based on the product page. If there is any doubt, the consumer won’t buy.

Subtle changes on your product page can make a huge difference.

For example, Seafolly, an Australian swimwear brand, increased transactions by 7% after simply enlarging photos in their shopping carts.

A highly optimized product page goes beyond photos. It encompasses your branding, pricing, product descriptions, and more.

Analyze your existing product pages and ask yourself if you’re telling the full story. Can a customer look at this page and get all of the information that they would get if they could touch or feel it in a store?

I could argue that selling online gives you an advantage to brick and mortar shopping. In a store, customers can’t read a product description or watch a video demonstration of how to use the item. Use these tools to your advantage.

Offer Free and Fast Shipping

Price will always have an impact on the consumer’s decision to buy. People will look at the cost of your products and immediately decide if they are still interested.

There is nothing wrong with this. Your pricing strategy shouldn’t appeal to everyone and anyone with Internet access.

But when you add on extra fees, like shipping costs, it can turn people away who were previously interesting in buying.

If you refer back to the graph about the biggest pain points of buying online, you’ll see that “surprise fees” is tied for second in terms of the highest response rate at 17%. Furthermore, 10% of people surveyed said that “shipping times” were the most frustrating part about shopping online.

That means more than one-fourth of consumers worldwide have frustrations and pain points related to shipping when they shop online.

This is something that you can’t afford to ignore. Your shipping practices could be turning away one in four shoppers that land on your website.

Whether you’d like to admit it or not, you’re competing with Amazon. Your customers are used to getting two-day or even next-day free shipping. That’s become the new standard in online shopping.

So it’s hard for people to justify paying $7.99 in shipping costs to get their package delivered in a week. You need to offer fast and free shipping. There’s no way around it.

If necessary, adjust the prices of the products to make up for the difference. Even if it means a 10% or 20% raise in your pricing across the board. As long as your customers aren’t seeing prices that they perceive as “extra” it will increase their chances of buying.

Run Sales and Promotions

Personalization was a major theme in the study published by AB Tasty. After all, the word “personalization” is in the title of their ebook.

The reason why personalization is such a key factor in making or breaking an ecommerce sale is because it starts early on in the buying process. You can’t wait until the checkout page to try and implement a personalization strategy. But personalized sales and offers will guide your customers to make a decision.

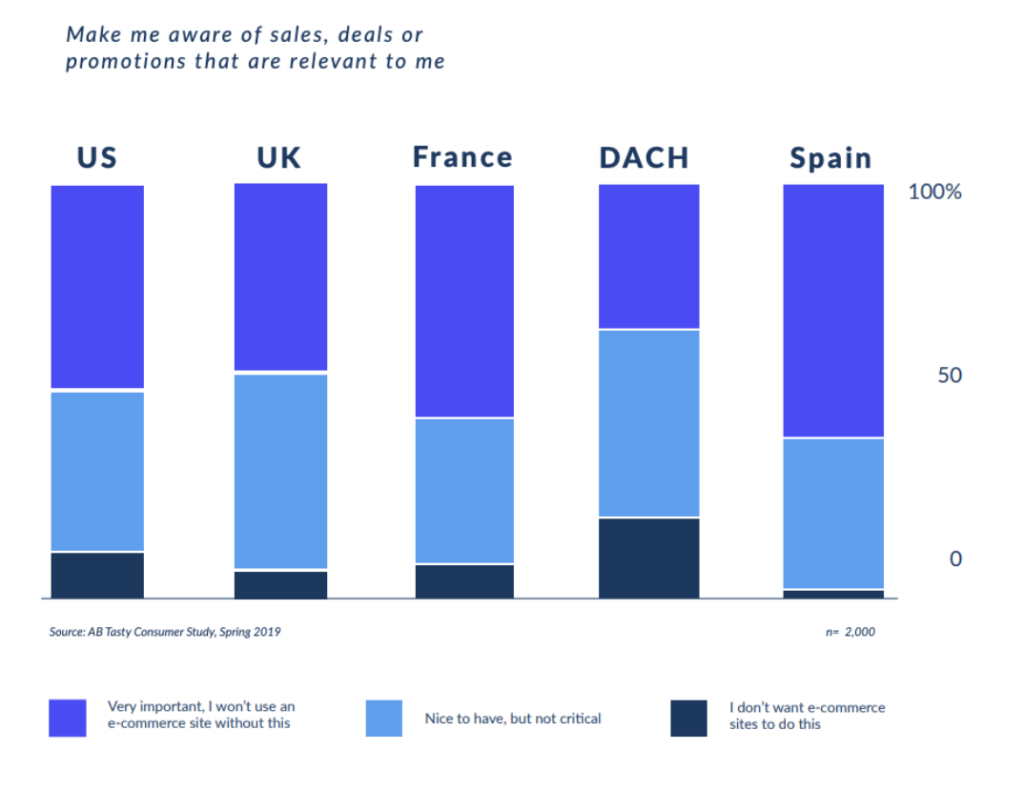
Take a look at this graph, which gives a global perspective on how consumers feel about personalized sales, deals, and promotions.

promotions

While the results vary slightly by region, you can see that the majority (nearly 50% or more) in four of the five regions say they wouldn’t even shop at an ecommerce site that didn’t give them personalized offers.

At a minimum, the overwhelming amount of consumers surveyed agreed that personalized options were nice to have.

Just a fraction of respondents in every region said that they don’t want personalized offers. But you need to stick with the majority here.

Personalized offers can come in all different shapes and sizes. For your existing customers, it could mean sending them an email with a new product or discount related to their purchase history.

For example, let’s say you own an online sports equipment store. A customer buys a snowboard and snowboarding boots. After they make that purchase, you can send them an email for discounts on things like snowboarding goggles, a snowboarding jacket, a ski mask, and gloves.

Sometimes personalization can be based on something simple, like the physical location of your website visitor.

If someone is shopping from Hawaii, you probably shouldn’t be promoting snowboards and skiing equipment on the homepage. A surfboard, kayak, or paddleboard would be a better option.

Be Transparent About Data Security

To truly personalize the customer experience, ecommerce brands are collecting data related to the browsing behavior of website visitors.

While consumers want personalized offers, they still have concerns about privacy. Based on the graph we saw earlier about the frustrations of online shopping, 17% of consumers say they are worried about the privacy of their personal data. That was the second highest response on the list.

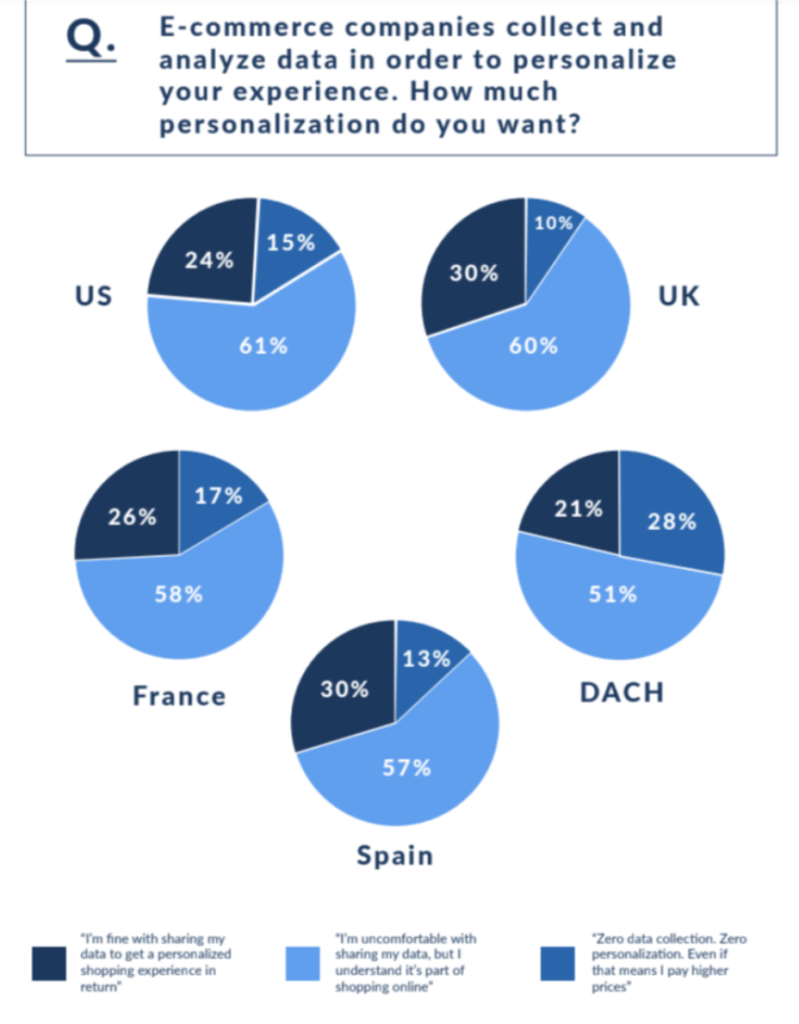
AB Tasty took that one step further, by asking consumers how they felt specifically about this topic. These are the results:

The results are pretty similar in every region. The majority of people admit that they are uncomfortable sharing their personal data, but they understand that it’s part of shopping online.

Roughly 25% of consumers are fine with data collection and don’t have any concerns about it.

A small, but still significant, percentage of respondents say they don’t want any data collection. They would even be willing to pay higher prices to avoid it.

I found these results interesting, especially when you compare them to the graph that we saw earlier related to consumers wanting personalized sales and promotions.

There is no doubt that people want personalized offers. But they are still uneasy about where those offers come from. The idea of being tracked online makes people uncomfortable.

It’s all about context. As an ecommerce store, you need to understand this.

Be transparent and tell your website visitors how and why you’re using data collection practices. Emphasize the benefits, instead of just stating that you collect data. Explain that the value of personalization outweighs any perceived disadvantages of data collection.

Entice Customer Loyalty

One of the biggest benefits of ecommerce personalization is customer loyalty.

It benefits you as the store owner because your customers will keep coming back and buying more products. But it also benefits the customer because it improves their online shopping experience.

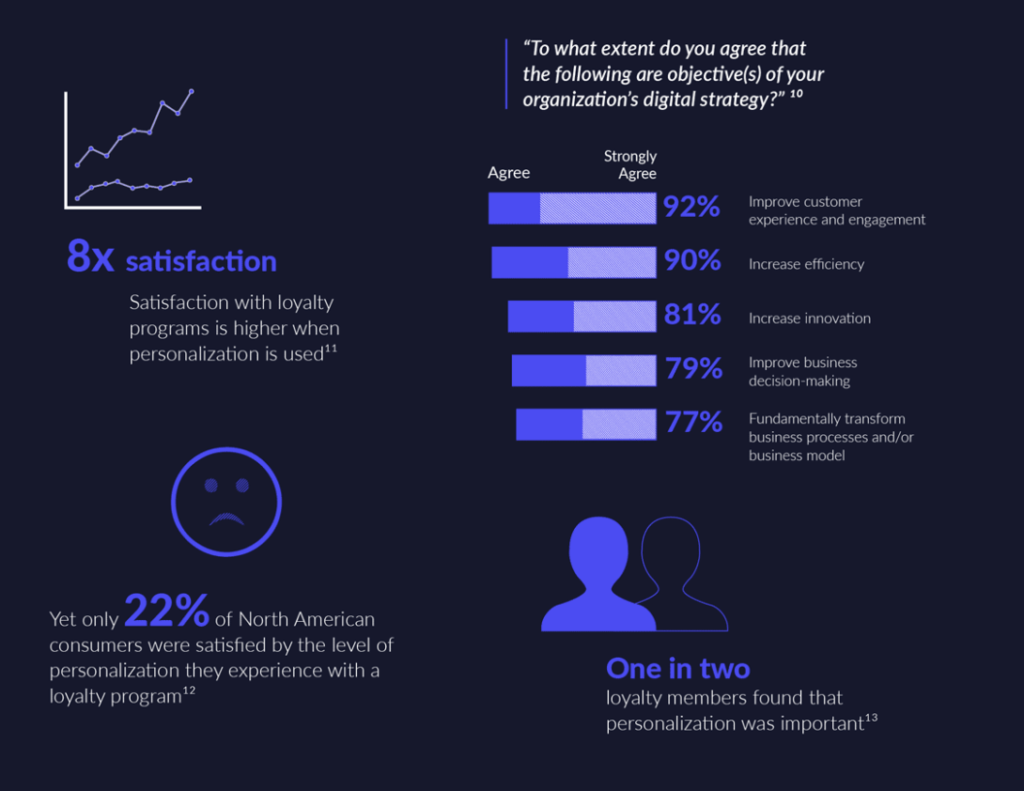
Check out the statistics on this infographic related to personalization and customer loyalty.

loyalty

The results show that simply offering a customer loyalty program isn’t enough. The most successful loyalty programs are paired with personalization.

In fact, customer satisfaction with loyalty programs is eight times higher when personalization is used. So how can you accomplish this?

The best customer loyalty programs are based on rewards. So you need to find a way to reward your customers for shopping. But if you treat all customers and purchases the same, it won’t add any personalized value to each person.

Think of a punch card at a local coffee shop. Every time you buy a coffee, the cashier punches a hole in the card. After you buy nine coffees, the tenth one is free. That’s a basic loyalty program.

The problem with this system is that it treats all purchases the same. Customers buying a $1 espresso are getting the same rewards as someone buying a large $7 specialty drink.

So when you create an ecommerce loyalty program, you could reward customers based on the amount they spend, rather than just the frequency of their purchases.

This adds a higher level of personalization to the program since no two people will have the exact same total spending. When a customer tracks their status in the loyalty program, they can clearly see that the offers are geared specifically toward them.

AB Testing

Your ecommerce store will never be perfect.

Yes—you can use the tips I’ve used in this guide to make changes to your product pages, homepage, and checkout process. But there will always be room for improvement.

The best way to fully optimize your website for conversions is by running A/B tests. Again, this takes the guesswork out of your decisions.

Rather than just assuming that your CTA button phrasing, color, and placement is correct, test out different variations to see which one converts at the highest rate. This is a constant process. You should always be testing different elements of your site to optimize it for conversions.

Conclusion

So what makes or breaks an ecommerce purchase? It’s not just one thing.

As a whole, there are several elements and factors that influence a consumer’s decision to buy or look elsewhere for their needs.

Refer to the data. Overall, personalization converts.

Brands that use digital tools and data to create a personalized shopping experience increase revenues two to three times faster than brands that don’t.

98% of marketers say that website personalization is a valuable method for improving conversion rates. 59% of businesses say that sales revenue is a direct benefit of digital personalization.

If you want more information and data about ecommerce personalization from a global perspective, you can read the full report published by AB Tasty.


Source Quick Sprout https://ift.tt/34PmNVa

ChexSystems: Like a Credit Score for Your Banking Habits

You’re probably well aware of the existence (and importance) of credit scores, even if you couldn’t cite your own off the top of your head.

But did you know there’s a similar consumer reporting system for your banking habits? It’s called ChexSystems — and just like your credit report, your ChexSystems report could have serious effects on your future financial endeavors.

Here’s what you need to know about this often-overlooked reporting agency and how it could impact your money.

What is ChexSystems?

ChexSystems is a consumer reporting agency that collects banking-related information, such as account inquiries, misuse, fraudulent activity and unpaid fees. In short, it’s a lot like a credit score for your bank account — and just as lenders often pull your credit report before deciding whether or not to offer you a loan or line of credit, some banks will request a ChexSystem report before allowing you to open a checking account.

However, unlike your FICO score (the three-digit credit score consumers tend to be most familiar with), the negative information on your ChexSystem report is generally removed after five years as opposed to seven. 

That’s a good thing, because without a bank account it’s difficult, if not impossible, to pay certain bills, especially in the all-digital-everything age of automated electronic payments. 

A bank account also keeps your money more secure than it is in your piggy bank, and certain accounts even pay interest. In short, you probably want a checking account — and if your ChexSystems report doesn’t pull up clean, it could be more difficult to open one.

What Shows Up on a ChexSystems Report?

So what kind of activities are reported by ChexSystems?

Well, just as your credit report does, your ChexSystems report will list a variety of personal identifying information, including your name, address(es) and Social Security number.

But the majority of the report will focus on your banking history — particularly any history you’re eager to forget, including:

  • Negative balances, such as existing unpaid overdrafts or involuntarily closed accounts
  • Unpaid banking fees 
  • Fraudulent or suspicious activity, including identity theft
  • Account inquiries and applications
  • Public records, such as bankruptcies or judgments 

Just like the major credit bureaus, ChexSystems is governed by the Fair Credit Reporting Act, which means you’re entitled to one free copy of your ChexSystems report every calendar year. You also have a right to a ChexSystems report if a bank uses its information to deny your application for a checking account. You can learn more about pulling your free annual report here, and you can also see a sample report if you’re curious to know what it might look like.

If you find an error on your ChexSystems report, you can (and should) report it immediately. You can do so easily online by filling out the ChexSystems online dispute form, or by mail or fax. 

Most ChexSystems investigations are completed within 30 days of filing a dispute.

What to Do If You Have a Negative ChexSystems Report

If your ChexSystems status is keeping you from opening a checking account, the good news is you have options. 

Some financial institutions offer “second chance” bank accounts for those with negative histories, though they do sometimes come with additional fees. These are more common with online-only banks, like Chime, but some major nationwide banks offer similar options. For example, Wells Fargo’s Opportunity Checking account is available in 39 states and Washington DC, and offers some attainable ways to avoid its $10 monthly service fee. 

You may also be able to use a prepaid debit card to settle bills that are tough to pay in cash, like utilities. Although some prepaid cards come with monthly fees, you can often get them waived with recurring direct deposits.

Whether your ChexSystems report is clean as a whistle or could use some TLC, the first step is to educate yourself. If you’ve never heard of this consumer agency, go ahead and request your free report today. In this case, knowledge really is power — the power to open a checking account that could help you better manage your money.

Jamie Cattanach’s work has been featured at Fodor’s, Yahoo, SELF, The Huffington Post, The Motley Fool and other outlets. Learn more at www.jamiecattanach.com.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder https://ift.tt/2p3QRNp

السبت، 9 نوفمبر 2019

6 Alternative Housing Options That Can Help You Save Money

The rent is too darn high, and it’s hard to catch a break. The same can be said about paying the mortgage each month.

With housing costs eating up about a third of many household budgets, it’s typically the highest single expense Americans face each month. Still, you’ve got to have a roof over your head.

Here are six alternative housing options with the potential to significantly cut costs while keeping you comfortably sheltered.

1. Coliving

Imagine living with a bunch of strangers for the sake of saving money on housing.

Coliving is an alternative housing concept where multiple, unrelated individuals live under the same roof sharing common space like living rooms and kitchens while enjoying private bedrooms … and private bathrooms, if they’re lucky.

While the living arrangement is not new, it has gained popularity in recent years among cash-strapped millennials in urban areas. But coliving can also be found outside major metropolitan cores.

Jillian Warwick moved into a St. Petersburg, Florida, coliving space this summer. She pays $600 in a city where rent on a studio apartment can exceed $1,200. Her monthly payment includes utilities and high-speed internet, and the home includes free laundry access and is stocked with complimentary coffee and household supplies.

2. Tiny House

According to the National Association of Home Builders, a median new single-family home was 2,355 square feet in the beginning of 2019. Tiny homes, in comparison, are typically less than a quarter of that size.

Though the living space is smaller, the potential to save is larger. In addition to spending less on the home itself, tiny house dwellers often pay less in utilities, and they buy less things because of the limited space.

Andrew and Gabriella Morrison and their two kids cut roughly $300 in monthly expenses (or about $3,600 a year) from their budget by switching to tiny house living. Joel Weber built his own tiny home while in college. After spending between $13,000 and $16,000 for the build, his combined cost to park his home and pay for utilities came to about $300 a month — almost a third of the cost of living in a dorm.

3. RV

Experience a nomadic lifestyle by living in an RV. These tiny houses on wheels are a fraction of the size of a typical home but also a fraction of the cost.

Cortni Armstrong ended up moving to an RV five years ago. Her living situation was the catalyst to a new career: renovating and flipping RVs. Armstrong has sold remodeled RVs in the $30,000 range — which can sometimes be a mere down payment for a traditional home.

Like with tiny house living, don’t forget to factor in the rent at a campground or RV park if you don’t own land to park on.

4. Skoolie

Similar to an RV but in a more unique package, a skoolie is a decommissioned school bus that has been converted into a home on wheels. It can also be less expensive than an RV.

Phil Risher bought a bus for $5,000 and spent $2,000 transforming it into his living quarters for a 95-day trip around the country. He and his father took on the renovation themselves using a free layout from Pinterest and tips from YouTube videos.

5. Off Grid

Ever want to distant yourself from the constructs of modern society? Off-grid living is an alternative housing option that requires you to be self-sustaining. You rely on independent power and water sources rather than municipal services. You grow or hunt your food rather than shopping at a grocery store.

Tyler and Ashley Selden and their daughter Sydney maintain an off-grid lifestyle in Alaska. Though it’s a lifestyle choice rather than a financial one, they estimate they save up to $10,000 a year just by growing, fishing or hunting their own food.

6. House Hacking

House hacking, in a nutshell, is buying property and recruiting others to help you pay the mortgage.

Riley Adams and his girlfriend (now wife) lived in a three-unit residential property in New Orleans cost-free for three years. Their house-hacking arrangement involved renting one unit out and having Airbnb guests in the other, which covered the mortgage.

House hacking is also possible without living in a multiunit property. Kristine Dowhan became an Airbnb host, listing three bedrooms of her four-bedroom home to afford her mortgage. She even made a $1,200 profit her first year renting out rooms.

Even if you don’t have extra bedrooms in your home, you can get creative with the space you do have. John Potter rented out a tent in his backyard on Airbnb. Talk about thinking outside the box!

Nicole Dow is a senior writer at The Penny Hoarder.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder https://ift.tt/32tqAG8