Thousands of courses for $10 728x90

الاثنين، 29 يناير 2018

When It Makes Sense to Scale Back Retirement Savings

A lot of financial advice is laser-focused on retirement. You hear it in commercials. You hear it on the news. You read about it on blogs and in books.

You need to be saving for retirement. Actually, you need to be saving more. What you’re doing now isn’t enough. You need to save more money and invest it smarter. Retirement is the ultimate financial goal and you can only reach it if you step up your game.

It’s been this way for a long time, but in the past few years there’s been a new trend that’s only added to the urgency: FIRE, which stands for “financial independence/retiring early.” This idea has gained steam as more and more people have started sharing their stories and strategies that have either allowed them to retire early – sometimes as early as 30 or 40 – or put them on the path to do so.

And while all of this focus on retirement and financial independence comes from a good place, sometimes we get so caught up in the rush to save more that we lose sight of the fact that scaling back is occasionally the right thing to do.

Here’s the thing: This isn’t a race. There’s no trophy for retiring early. There’s nothing inherently good about reaching financial independence sooner rather than later. “Retirement” in of itself is a bit of an empty goal.

What does matter is the life you want to live, both now and in the future. The things you want to do. The people you want to be with. The places you want to go.

Your financial plan should be geared toward making those things possible. And while that absolutely includes saving for the future, it should also include a focus on your present needs and aspirations.

With that in mind, here are a few situations in which it makes sense to scale back your retirement savings.

Starting a Family

Many of us, myself included, view starting and raising a family as one of their highest priorities. It’s a source of pride, joy, love, and fun.

It’s also hard. And expensive. And for many families some of the biggest expenses, like childcare, come at a time when you’re still early in your career and therefore haven’t yet reached your full earning potential. Or, if you or your spouse or partner decides to stay home with your children, you may be living on significantly less income than you’re used to.

Quite simply, starting a family is a big financial challenge. It’s just the reality of the situation. Financial sacrifices often have to be made.

Now, you can obviously cut back on discretionary spending like eating out, shopping, and traveling. And some of that is often a good idea.

But sometimes there still isn’t enough money to go around, and in that case it may make sense to temporarily scale back your retirement savings. Because again, the goal isn’t to retire. The goal is to create a life you enjoy both now and in the future.

And if having a family is a part of what that life means to you, making room for it is absolutely worthwhile.

Pursuing Meaningful Work

One of my pet peeves with the whole idea of retirement is the focus on quitting your job.

Look, I understand that not every job can be enjoyable. I also understand the responsibility to provide for your family and that sometimes that means taking a job you’d rather not have to do.

But you shouldn’t aspire to work just as long as you have to in order to stop doing a job you hate. You should aspire to do work you love. Because work that’s fulfilling, work that aligns with your values, is an incredibly enjoyable way to spend your life.

Unfortunately, pursuing that kind of work often means taking a financial step backwards. Whether it’s going back to school, changing careers, or starting a business, there’s often a loss of income and/or an increase in expenses that comes with it.

Which means that, sometimes, pursuing work you love now might require some kind of compromise on your ability to retire later.

It’s up to you how much of that tradeoff you’re willing to accept. Maybe the idea of retiring sooner is more appealing than the idea of doing work you enjoy.

But I wouldn’t assume that staying in a job you hate is the smart move simply because it allows you to save more for retirement right now. There are many situations in which taking a step back to do something you love is the right thing to do.

You Can Afford to Save Less

I’ve had clients who came to me because they were worried about their retirement savings, only to run the numbers and find out that they were actually ahead of where they needed to be. That they could, if they wanted to, save a little less and still be on track.

This is obviously a good place to be, but it’s not always an easy situation to adapt to. Because again, we’re so conditioned to save more, more, more, that the idea of voluntarily saving less feels weird.

And saving less isn’t always the right move. Life can change quickly and saving more money gives you more room to weather whatever storms come your way.

But if you do find yourself in this situation, it’s worth considering what you would do with the extra cash flow if it wasn’t going toward retirement savings. Would you travel more? Work less? Spend more time with your friends and family? Take up a hobby?

Sure, continuing on the path you’re on now might allow you to retire sooner. But scaling back might allow you to enjoy more of your life in the meantime.

Planning for a Lifetime

None of this is to say that you should neglect saving for retirement. Whatever your goals are, there will come a point at which you are either no longer able to work for money or no longer want to, and it’s important to prepare for that.

But retirement should never be the only goal. You have a lot of life to live before retirement and lot of life to live after it, and your biggest financial goal should be filling all of those years with as much happiness as possible.

Sometimes that means saving a little less for retirement, at least for a little while. If you do it right, both your present and future selves will thank you for it.

Matt Becker, CFP® is a fee-only financial planner and the founder of Mom and Dad Money, where he helps new parents take control of their money so they can take care of their families. His free book, The New Family Financial Road Map, guides parents through the all most important financial decisions that come with starting a family.

Related Articles:

The post When It Makes Sense to Scale Back Retirement Savings appeared first on The Simple Dollar.


Source The Simple Dollar http://ift.tt/2rNNESM

الأحد، 28 يناير 2018

Itemize Or Take The Standard Deduction On Your Federal Income Tax? How to Choose the Deduction to Minimize Your Taxes

Should you itemize deductions or take the standard deduction for the tax year 2017 (the taxes you will file in early 2018)? Either path may be right for you, but don't just assume the standard deduction is your best option.

Source CBNNews.com http://ift.tt/2DPOrrl

Seven Life-Changing Ways to Use Your Tax Refund

In 2017, the average individual who received a tax refund for the year before got a cool $3,050 of their federal taxes back. That’s a lot of money, and perhaps a life-changing amount of cash in some instances. On the other hand, what people do with that money determines whether it helps them build wealth — or simply scratch a fleeting consumer itch.

Think about it: With $3,050 in the bank, you could splurge in ways that don’t really affect your bottom line either way. You could buy a basic hot tub for your back deck, pay for an all-inclusive vacation to the Caribbean, or piss it away on clothes and whatever else you desire.

On the flip side, you could spend your tax refund in ways that actually leave you worse off. You could put $3,000 down on a brand new $35,000 truck that saddles you with a $600 monthly payment, for example. You could put that money down on a boat you always wanted – a boat with costly repair bills and a value that literally sinks overnight.

Seven Ways Your Tax Refund Could Leave You Better Off

If you want to gain some real momentum with your finances in 2018, it’s smart to start thinking about your tax refund early. With several thousand dollars potentially coming your way, what’s the best way to make that money count?

Instead of spending that cash infusion in a way that leaves your finances neutral or even worse off, consider these tried-and-true savings strategies that will improve your finances no matter what:

#1: Pay off high-interest debt.

High-interest debt is one of the biggest hurdles to overcome if you want to build wealth. When you owe money on credit cards or carry personal loans with high interest rates, it’s difficult to get ahead when so much of your payment goes to interest only.

Here’s the good news: Throwing $3,050 (or whatever your tax refund amounts to) toward high-interest debt will always leave you better off. Making an extra payment toward the principal of your credit card or loan balances will help you save on interest automatically while moving your debt payoff date that much closer.

Just how much can you save? Imagine you have a $3,050 credit card balance at 18% APR and you have the opportunity to pay it off in one fell swoop. If you used your tax refund to repay this debt, you would save yourself almost four years of monthly minimum payments, and a whopping $1,210 in interest payments alone.

#2: Save an emergency fund.

Whether you carry some high-interest debt or live a debt-free lifestyle, building an emergency fund is essential for your financial health. Without an emergency fund, you’re prone to struggle if you face unexpected financial emergencies like surprise medical bills, expensive home repairs, or a layoff.

Ask yourself how long your money would last if say, you lost your job this week or you could no longer work due to an injury or illness. With no emergency fund, your savings would likely dwindle and you might even need to use credit to stay afloat. With a healthy emergency fund, on the other hand, you’d have time to figure things out.

While most experts suggest you stock an emergency fund with at least three to six months of expenses, even a smaller amount is a good place to start. Saving $3,050 now can even turn out to be life-changing later on if you find yourself in a situation where you’re suddenly desperate for cash.

If you have a savings account, consider adding your tax refund to the pot. If not, open a high-interest savings account and start funding it today.

#3: Contribute to a health savings account (HSA).

A health savings account (HSA) is a tax-advantaged savings account set up specifically to pay for healthcare costs. Once you open this account, you’ll be able to deduct contributions up to a certain limit, watch your money grow tax-free, then use your funds for qualified healthcare expenses on a tax-free basis. And if you don’t use up your HSA funds by the time you turn 65, you can withdraw funds for any purpose – even to pay for retirement.

The myriad tax advantages this account offers are the reason it’s commonly referred to as the best retirement plan you’ve never heard of. HSAs are helpful when it comes to saving for healthcare expenses, but they may be even more advantageous for retirement.

Either way, individuals can contribute up to $3,450 and families can save up to $6,900 in an HSA account in 2018, provided they have a high-deductible healthcare plan. The IRS defines high-deductible plans as those with a minimum deductible of $1,350 for singles and $2,700 for families. Maximum out-of-pocket amounts on qualified plans are also limited to $6,650 for individuals and $13,300 for families in 2018.

#4: Contribute to a traditional or Roth IRA.

Even if you contribute to a 401(k) or another type of employer-sponsored retirement account, you may also be able to add money to a traditional or Roth IRA. Both traditional and Roth IRAs are easily opened online and simple to use and understand.

The big difference between them is that traditional IRAs allow you to contribute pre-tax dollars and deduct your contributions if you meet certain income requirements. Roth IRAs, on the other hand, let you contribute after-tax dollars and allow you to take tax-free distributions when you retire. Roth IRAs also have income limits that make it harder for high earners to contribute.

If your emergency fund is in good shape and you don’t have a lot of high-interest debt, opening one of these accounts or adding to an existing account could be a smart move.

Just keep in mind that, for 2018, your total contribution to both a traditional and Roth IRA cannot exceed $5,500 (or $6,500 if you’re ages 50 and older).

#5: Start several savings buckets.

If you have competing financial goals and want to save for all of them, starting several different savings accounts can be a smart move. Maybe you want to update your kitchen within the next few years, but you also want to save up for a newer car and a summer vacation. By starting a few different accounts, you could give yourself a head start toward achieving everything you desire.

You could spread your tax refund across several accounts for starters, then commit to weekly or monthly contributions so each savings bucket will grow. Just make sure you stash your cash in a high-interest savings account so you can earn at least a little interest on your deposits.

#6: Invest your refund.

Maybe you’re already invested in your workplace retirement plan or an IRA, and want to try something new. There are many other worthy to invest, so you could always open a brokerage account and invest separately from your retirement funds. The best online stock brokerage firms for 2018 make it easy to learn investing basics online, start investing with small sums of money, and do it all without excessive fees.

Beyond opening a brokerage account, there are other investing avenues to consider as well. If you’re saving for college, a 529 plan is an obvious choice. Riskier alternative investment options might include investing in peer-to-peer lending with a company like Lending Club or Prosper, in real estate notes with a firm like Fundrise, or even in small amounts of cryptocurrency if you can handle the volatility.

At the end of the day, any way you can learn more about investing while also growing your wealth is probably a good thing.

#7: Invest in yourself.

Finally, don’t forget about the most important asset you’ll ever have – yourself. If you receive enough cash in your tax refund to invest in anything, spending that money to improve yourself or your life may pay off more than anything else.

Fortunately, there are a ton of ways to invest in yourself – and some of them don’t cost a dime. You could invest in your mental and spiritual health by meditating, getting a good night’s sleep, or exercising regularly, for example.

In terms of financial investments, there are a ton of ways to use $3,050 (or any other amount) to your advantage. You could pursue an advanced certification that makes you more valuable to your employer, for example. You could take a course in a subject that interests you, purchase the start-up equipment or software needed for a side business, or invest in continuing education that could leave to higher pay and better job security in your current career path.

Any investment you make in yourself will likely pay off in the short term and over the course of your life and career. So, once your other financial ducks are in a row, don’t forget to spend your money where it counts – on self-improvement.

The Bottom Line

Whether you receive $500, $3,050, or considerably more in your tax refund this year, it’s up to you to put this cash to good use. You can use it to splurge on something you’ve always wanted, or you could invest it in a way that could make you richer in the long run.

And, if you can’t decide which way to go, maybe you should do a little of both. Buy something you want for sure, but stash the rest of your cash away for a rainy day. While it’s hard to do the right thing when you receive a windfall, your future self will thank you.

Holly Johnson is an award-winning personal finance writer and the author of Zero Down Your Debt. Johnson shares her obsession with frugality, budgeting, and travel at ClubThrifty.com.

Related Articles:

How do you plan to spend your tax refund this year?

The post Seven Life-Changing Ways to Use Your Tax Refund appeared first on The Simple Dollar.


Source The Simple Dollar http://ift.tt/2DCtCMr

QUIZ: Should You Put on Pants and Pick Up Dinner or Just Have It Delivered?

السبت، 27 يناير 2018

Do You Qualify For An Earned Income Tax Credit?

The Earned Income Tax Credit (EITC) is a program designed to provide tax relief for American workers with low-paying jobs. Could you qualify for this tax credit? If you have a relatively low income, take some time to find out.

Source CBNNews.com http://ift.tt/2GkYIKz

Books with Impact: Walden

The “Books with Impact” series takes a deeper look at specific books that have had a profound impact on my financial, professional, and personal growth by extracting specific points of advice from those books and looking at how I’ve applied them in my life with successful results. The previous entry in this series covered Voluntary Simplicity by Duane Elgin.

I was first introduced to Walden by my high school English teacher, who told me more than once that it was something I should revisit throughout my life because it would read much differently at different stages in my life experience and intellectual growth. He was completely right.

Walden is a book written by Henry David Thoreau and first published in 1854, in which Thoreau describes his experience of spending two years, two months, and two days living in a small house that he built himself on the shore of Walden Pond, near Concord, Massachusetts. He spent that time in near-solitude, rarely seeing another living person and doing most life tasks for himself.

Walden compresses that experience, for narrative purposes, into a single year, and the book’s overall purpose is to make the argument that being close to nature, being comfortable in solitude, and spending a lot of time in contemplation combine together to transcend the “desperate” existence that most people feel in their day to day lives.

So, why is this a “book with impact” that’s being discussed on a personal finance site? Walden essentially boils down to an argument for the benefits of self-reliance and minimal spending, of spending time in contemplation and enjoying nature rather than in the artificial environments we create for ourselves. In an era where people spend hours upon hours daily staring at screens and being constantly distracted, in a world where money woes bring untold stress and the vast majority of Americans live a paycheck to paycheck existence, Walden‘s message is a powerful one.

Having said that, let me forewarn you that reading Walden is a slow process. Thoreau writes in a very dense fashion and sometimes will rapidly hop around from serious analysis to sarcasm and flights of fancy. He also uses somewhat dated language; while I personally find him much easier to read than other authors of the 19th century, it’s not fully written in modern language. I consider the effort to be worth it, but this is one of those books that deserves to be read slowly with a little notebook open beside you to jot down interesting ideas and thoughts, which you’ll find constantly while reading it.

The full text of Walden is freely available via the Project Gutenberg website; you can simply click here to start reading. If you prefer to read it in the Kindle app on your phone, you can open the mobile page for Walden and, in most mobile web browsers, just click on the Kindle link and it’ll automatically open in your Kindle app so you can read it like any other e-book and your place will be saved.

What follows are some of the interesting ideas that I took note of during my most recent reading of Walden, ones that I felt were particularly relevant for the modern challenge of spending less, finding personal independence, and being in control of our resources and of our mind.

But men labor under a mistake. The better part of the man is soon plowed into the soil for compost. By a seeming fate, commonly called necessity, they are employed, as it says in an old book, laying up treasures which moth and rust will corrupt and thieves break through and steal.

Thoreau’s point here is that we sacrifice a lot of our lives working in order to earn external rewards, and those external rewards fade quite quickly.

Think of the many, many things we buy, use for a while, and then discard, or the things that we buy and don’t even use at all.

Think of the piles of stuff stowed away in our closets that we don’t use and will likely never use, that we’ll probably eventually throw away or sell for a pittance or let our children deal with.

What is the good in working for all of that stuff? Why not work for the internal things? Why not work instead to have a great sense of peace and security? Why not work so that you have the time to understand the world more deeply and feel at peace with the big questions in life?

The thing is, working primarily for those internal things often means that you don’t have to work nearly as hard. You don’t really need much to provide basic care for yourself, and if you then spend most of your energy on finding true inner contentment… well, isn’t that a pretty good life?

It is hard to have a Southern overseer; it is worse to have a Northern one; but worst of all when you are the slave-driver of yourself.

This is a quote that marks the timeframe in which Thoreau wrote Walden. While he is unquestionably an abolitionist, he’s also aware that slavery does exist and talks of it as an ongoing human condition in widespread use, which is true for his time.

However, his core point here is that we are often the worst of all masters to ourselves because we can never escape that slavery. Wherever we go, we’re there. If that voice in our head is a cruel, critical master, full of nothing but contempt for the people that we are, that’s perhaps the cruelest outcome of all.

It is hard to find joy when your internal voice is constantly criticizing you.

It’s also easy to fall into situations where we’re tempted to find easy solutions to that criticism. If the voice in your head is shouting at you that you’re not good enough in some way and then a product comes along telling you how it will improve that very thing, it becomes incredibly tempting. The marketer and that foul voice in your head are working in tandem to empty your pockets.

The mass of men lead lives of quiet desperation. What is called resignation is confirmed desperation. From the desperate city you go into the desperate country, and have to console yourself with the bravery of minks and muskrats.

From the debts we owe to others to the critical voices in our head, from our desire to keep up with the people next to us to our desire to find pleasure because we “deserve” it, we’re often rushed along through life, through a series of hard choices that we sometimes feel stuck in.

The thing is, those chains never really go away. I can find temporary peace when I go on a long hike in the woods, but the internal monologue comes with me, as do many of the worries of life.

The only escape from it that I have found is to turn away from materialistic aims and try to soothe the feelings within to the best of my ability, to eliminate as many sources of stress and worry from my life as I can, and to drink deeply from the natural world (those long hikes, for example) and from great books.

Those things don’t cost money at all, but they do require some realignment of life’s priorities, often in an uncomfortable way.

For more than five years I maintained myself thus solely by the labor of my hands, and I found that, by working about six weeks in a year, I could meet all the expenses of living. The whole of my winters, as well as most of my summers, I had free and clear for study.

This is the culmination of what Thoreau’s earlier points are. He essentially works for about six weeks out of the year and earns enough in those six weeks by his own effort to pay for his expenses for the year. The other forty six weeks, he spends it in “study,” which, as we learn later on in the piece, means spending time in nature, in reading, in contemplation, and in the company and worthwhile conversation of people of his own choosing.

This is a very true expression of the often-quoted saying “work to live, don’t live to work.” Work is a necessary act for him, providing just enough so that he could get on with living.

He didn’t work to accumulate material possessions. He didn’t work to acquire property or to appear better than the neighbors. He didn’t work to acquire the latest gadgetry.

He worked so that he could spend his life doing things that brought him peace and contentment – spending time in nature, reading, contemplating, and having good conversations with thoughtful people.

What things do you do that truly do bring you peace and contentment? You’ll probably find that, if you take this seriously and back away from what you think you’re supposed to say, your answers involve very simple things, too. Mine involve reading and spending time in nature, just like Thoreau; I also find a ton of contentment in playing challenging games (like chess, for example) and in time spent with my family, teaching my children life skills and sharing experiences with my wife and with my children.

These aren’t activities that require tons of activity or tons of possessions. A lot of my possessions are centered around things that have little to do with the things in my life that provide the most peace and contentment.

As I preferred some things to others, and especially valued my freedom, as I could fare hard and yet succeed well, I did not wish to spend my time in earning rich carpets or other fine furniture, or delicate cookery, or a house in the Grecian or the Gothic style just yet.

In the end, Thoreau valued freedom above all else – freedom to spend his time in the way that he most saw fit, in the things discussed above that brought him peace and contentment.

What keeps you from doing this? Why is your life not centered around investing the bare minimum time needed to enable you to spend the rest of your life engaged in the things that bring you the most peace and contentment?

It is so, so easy to come up with weak answers to that question, justifications for why we don’t live this way. Instead of listening to and following those justifications, perhaps our lives would be better off if we ignored those justifications a little and strove for freedom instead.

In short, I am convinced, both by faith and experience, that to maintain one’s self on this earth is not a hardship but a pastime, if we will live simply and wisely; as the pursuits of the simpler nations are still the sports of the more artificial. It is not necessary that a man should earn his living by the sweat of his brow, unless he sweats easier than I do.

When I read this, I am reminded of the fact that when I am not pressed up against the wall with financial demands and workplace issues, work is often quite enjoyable. There are few things I’ve enjoyed more in my life than being deeply engaged in a project, calling forth my whole mind and spirit to really accomplish something challenging, and feeling great when it happens.

Work is joyful in that context. It becomes drudgery when we have to earn certain high levels of money in order to pay our bills and pay off our debts, which usually means that in order to earn enough to make that happen, we have to submit ourselves to doing a lot of things we really don’t enjoy. We often end up facing a lot of stress and anger, both from our coworkers and from ourselves.

The best route out of this that we have at our disposal is to be minimal in our spending. What do we really need? Is going beyond that worth exposing ourselves to more of the stressful and negative aspects of work? Is it worth earning less to have more joyful work?

Every morning was a cheerful invitation to make my life of equal simplicity, and I may say innocence, with Nature herself.

By choosing a life of minimal need and want, Thoreau found a deep peace that caused him to awake cheerful at the promise of the day ahead.

He didn’t have much in terms of wealth or possessions, but he had what he needed and valued most: freedom. He had basic shelter, food, nearby access to clean water, clothing, a warm place to sleep, and he was surrounded by opportunity to engage in the things that really lifted his spirits.

What more does one really need in life? What are we chasing that’s more than this?

We must learn to reawaken and keep ourselves awake, not by mechanical aids, but by an infinite expectation of the dawn, which does not forsake us in our soundest sleep. I know of no more encouraging fact than the unquestionable ability of man to elevate his life by a conscious endeavor.

Thoreau was strongly encouraged by the ability of a person to improve themselves by their own continuous and conscious effort. We are all capable of being more than we currently are if we choose to direct our efforts in that way.

We can be better people. We can find contentment. We can be healthier and more virtuous. It’s up to us.

There is no magic machine that will do those things for us, either. In the end, it is our own choice that will make us better. You can have all the workout machines in the world, but it is still up to you to choose to exercise. You can have the best alarm clock in the world, but it is still up to you to rise out of bed in the morning.

What will you make of yourself? Remember, you don’t need stuff to do this – you already have everything you need.

With a little more deliberation in the choice of their pursuits, all men would perhaps become essentially students and observers, for certainly their nature and destiny are interesting to all alike. In accumulating property for ourselves or our posterity, in founding a family or a state, or acquiring fame even, we are mortal; but in dealing with truth we are immortal, and need fear no change nor accident.

Thoreau is making a subtle argument here for being a lifelong learner. If we spend at least some of our time learning new things and contemplating those new things into a deeper understanding of the world, and then we share at least some of the truth that we uncover, we’re doing something truly timeless, far more than collecting wealth.

Think about it this way. What will have a more profound affect on the world – buying a latte at Starbucks, or spending an hour learning about something new that unlocks understanding in your head which you’re able to share with a few people? Which will have a more profound and lasting effect on you?

His argument that ideas are timeless and things are far from it is one worth thinking about.

I learned this, at least, by my experiment: that if one advances confidently in the direction of his dreams, and endeavors to live the life which he has imagined, he will meet with a success unexpected in common hours. He will put some things behind, will pass an invisible boundary; new, universal, and more liberal laws will begin to establish themselves around and within him; or the old laws be expanded, and interpreted in his favor in a more liberal sense, and he will live with the license of a higher order of beings. In proportion as he simplifies his life, the laws of the universe will appear less complex, and solitude will not be solitude, nor poverty poverty, nor weakness weakness. If you have built castles in the air, your work need not be lost; that is where they should be. Now put the foundations under them.

In this final quote, Thoreau is making the point that if a person rushes toward their dreams, that person is in danger of losing them if there is not a firm foundation underneath them.

What is that firm foundation? Well, certainly, a financial foundation is part of that. Knowing that your meals and shelter is secure for the foreseeable future is undoubtedly going to help make things more secure in your life.

It’s more than that, though. Another part of a foundation is that you have a good character and good values to rest your life endeavors upon, so that your own personal failings don’t undermine everything you’ve worked for. Yet another part is the things you’ve learned, and another part is the core relationships you have.

It is easy to strive for great things in life – a beautiful house, a booming career, a wonderful partner. However, if you ignore the foundations under them – a strong character that won’t fail you, good values, a firm sense of your finances, strong and healthy relationships, a good understanding of the world – the great things you build won’t suddenly fall apart underneath you.

It is worth pointing out that I took note of many other things while reading Walden – thoughts on human relationships, on morality, on appreciation of nature, on doing things for myself, on the power of reading challenging books. Walden is far from one-dimensional; in fact, it reads more like a series of essays that are interconnected by the overall narrative of life on the shore of Walden Pond.

This is not the easiest read in the world, but it offers up a great deal of value if you take it slowly, read it in pieces, jot down a few notes, and reflect on them. It will open up some very deep thoughts about one’s direction in life and how one should participate in the modern world and what one owes to themselves. Those are weighty questions, indeed, but they form the true foundation of personal finance.

The post Books with Impact: Walden appeared first on The Simple Dollar.


Source The Simple Dollar http://ift.tt/2DT0a8w

How Much Do You Need To Retire? Learn how to Calculate your Retirement Income Needs

I find when meeting with individuals for the first time that they typically have no idea how much they will need to be able to retire. The typical answer of $1 million is absolutely worthless since everyone has different income requirements and different income sources that must be added into the equation when determining when and how much will be necessary.

Source CBNNews.com http://ift.tt/2DF9bi2

How to Pay a Crazy Expensive Vet Bill (Without Making Your Dog Get a Job)

الجمعة، 26 يناير 2018

This Program is Giving Out $2,000 College Scholarships to 700 Military Kids

The members of our armed forces make great sacrifices — and so do their families.

They deserve all the support they can get.

The Scholarships for Military Children program gives money to the children of military service personnel to use toward college tuition, fees, books and other expenses.

The program has given more than $16 million to military kids in the its 17-year history.

The scholarship program is currently accepting applications for this year’s batch of eligible students. Each military commissary that receives a completed application will be awarding at least one scholarship.

Apply for the Scholarships for Military Children

Scholarship Amount: $2,000

Number of Scholarships Awarded: 700

To qualify for the scholarship, applicants must:

  • Be a child of an active duty military personnel member, a reserve/guard or retired military member, a service member who died while on active duty or an individual who died while receiving retired pay from the military
  • Be enrolled in the Defense Enrollment Eligibility Reporting System (DEERS) database and have a current dependent military ID card
  • Be under 23 and unmarried
  • Be enrolled or planning to enroll full time at an accredited U.S. college or university in the fall of 2018, specifically in an undergraduate program that will lead to a bachelor’s degree (community college students must have intent to transfer to a four-year school)
  • Have a 3.0 GPA if currently in high school or a 2.5 GPA if currently in college

To apply, applicants must:

  • Fill out the application, which can be downloaded here or picked up at the nearest military commissary
  • Write an essay — 500 words or less — responding to the following: “With the development of high speed internet you are now living in a world that is completely different than 20 years ago. What are the pluses and minuses for society and the family? How would you address the minuses?”
  • Submit the application package (in person or by mail) to the nearest military commissary. Emailed or faxed submissions will not be accepted.

Scholarship Deadline: February 16, 2018

Scholarship recipients will be notified by letter, which should be mailed out around May 15.

See here for more information and for an application to the Scholarships for Military Children.

Nicole Dow is a staff writer at The Penny Hoarder.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder http://ift.tt/2rGA3MV

Money, Cars and Kids: What 2,000 People Said It Means to Make It in America

At The Penny Hoarder, we love to share ways for our readers to make and save money. But the goals people have for what they want to do with their money vary widely.

For some, it’s the freedom to travel. For others, it’s to have capital to start their own businesses.

My money goals center around the ability to one day enjoy homeownership and to afford to expand my family.

Thermosoft, a U.S. manufacturer of electric floor heating products, recently polled 2,000 people to get an idea of what it means to “make it” in America — their vision of what a successful life looks like.

The company asked people about how different aspects of their current lives — including income, employment and family life — stacked up against their opinions of how they imagined their ideal lives to be.

Not surprisingly, those polled seemed to view success with having more… or having more expensive things!

Respondents wanted a home worth an average of $461,000 and a car worth an average of about $42,000 for their ideal life. In reality, their home and car values averaged about $248,000 and under $16,000, respectively.

More education was a goal for some. Half the people polled believed “making it” meant having an advanced degree, though only 15% had a master’s degree or doctorate.

And, of course, making more money was viewed as a big benchmark for success. For those who replied that they hadn’t yet reached their ideal life situation, 67% said having the income they desired was the main thing missing.

The average person polled thought a salary of about $147,000 was the standard for having “made it,” while their real salaries averaged about $57,000.

They also defined success as working fewer hours, commuting less and having more vacation time. When asked about their ideal workplace environment, more would work from home.

The survey’s respondents viewed wealth and freedom as higher priorities above respect, fame or having less responsibility.

But having more money wasn’t all for greedy pursuits. When asked, “What’s the epitome of ‘making it’ financially?” the top responses were not worrying about medical bills, being able to loan money to loved ones and being able to donate a significant amount to charity.

And despite the desired boost in pay, 77% of those polled said they wouldn’t want more than $1 million in annual income, even if it were offered.

Having someone to share their lives with was important to respondents. Only 46% of the people polled were married, but nearly 80% said their ideal life included being married. Four out of five also said having kids was a part of their vision for the life they wanted.

The poll showed once they “made it,” people would want to spend the biggest chunk of their time with family and friends — above exploring, working, relaxing or helping others in need.

Tips for Accomplishing Your Life Goals

If you find what you ultimately want in life is similar to those who took Thermosoft’s poll, we have some posts to help you get there.

Want to make a higher salary? Here’s how to negotiate your pay.

Or try job hopping. This woman shares how switching jobs led her to a major salary boost. Here’s advice on how to write a shining resume and cover letter to land your next gig.

Do you desire a work-from-home job? Make sure to “like” The Penny Hoarder Jobs page on Facebook. We post about opportunities for remote work all the time.

Or convince your boss to let you work from home. This guide to asking for a flexible work schedule might help.

Looking to upgrade to a better home? This Realtor shares tips for navigating the home buying process.

Want to drop your dough on a new car? Here are 10 tips to keeping you from overspending on your new vehicle purchase.

Found that perfect person to spend your life with? If you’re heading down the aisle, we’ve got some helpful posts for keeping the costs down.

Get inspiration from this couple who spent under $7,000 on a 130-guest wedding. Another couple saved an estimated $21,781 on their wedding with help from eight websites. You’ll also want to check out this ultimate guide to saving money when you get married.

A budget wedding isn’t for everyone though. While your financial adviser may frown at borrowing money for the big day, here’s how one couple benefitted from a wedding loan.

Is having kids is in your vision of an ideal life? You’ll want to be aware of the cost to raise a child (and not be as clueless as some expecting parents). Start your journey into parenthood on a thrifty level with these 31 ways to save on baby gear.

P.S.: Here’s a whole bunch of free baby stuff.

Nicole Dow is a staff writer at The Penny Hoarder.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder http://ift.tt/2nfMDy0

How Much a Medalist Makes and Other Fun Money Facts About the Olympics

When the 2018 Winter Olympic Games begin February 9, 2018, I’ll be parked in front of my television to take in all the action.

Like many fans, I’ll be dreaming of what it‘d be like to land a triple axel jump in figure skating or scream down the luge track on a hyped up sled with no brakes.

While shopping for affordable snacks to munch on during the events, I got to wondering about the costs associated with the Olympics.

Check out what I learned:

  1. The Pyeongchang Olympic Stadium cost $109 million to build and will only be used four times.
  2. This year’s figure skating costumes cost between $1,000 to $5,000.
  3. You can buy your very own Polo Ralph Lauren Team USA closing ceremony pants for $398.
  4. Fans can watch some coverage for free with NBC’s online streaming feed or a digital antenna, or see all of NBC’s coverage live or on demand with a $39.99 per month Hulu with Live TV subscription.
  5. NBC paid almost $1 billion for the rights to the 2018 Games and will spend another couple hundred million on its production.
  6. A trip to see the 2018 Winter Olympics in person would set you back an estimated $4,683.
  7. It costs $100,000 per year to train a U.S. Olympic skier and each athlete must contribute $30,000 of their own money to help cover expenses.
  8. The least costly Winter Olympics were held in Innsbruck, Austria, for $22 million. The 2018 Winter Games in PyeongChang, South Korea, are expected to cost about $12.9 billion.
  9. Most U.S Olympic athletes don’t get paid to train or compete but they get a bonus from the United States Olympic Committee for winning a medal ($25,000 for gold, $15,000 for silver and $5,000 for bronze) – and they have to pay federal income tax on it!

Since I only spent about 10 bucks for salsa and mocktails, I’m perfectly content sitting in my warm living room and watching the action from 7,500 miles away.

Go Team U.S.A.!

Lisa McGreevy is a staff writer at The Penny Hoarder. She never pursued becoming an Olympic athlete it would have required her to be exponentially less lazy than she actually is.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder http://ift.tt/2Gkrrio

Make Trump Tax Cuts Permanent - Now

Just one month into the new tax bill, only those wearing left-wing ideological blinders‎, which unfortunately is still millions of anti-Trumpers, can deny that the Trump tax cuts are helping just about everyone.

Source CBNNews.com http://ift.tt/2ne4sxy

Despite Rise in Mental Health Issues, College Students Aren’t Getting Help

The end of high school can be a stressful time.

And the transition from high school to college? That can be even scarier.

The last few months before graduation are a jumble of grades and finals and applications and forms and goodbyes and financial worries that just won’t quit.

Add to that the (looming threat? promise?) of a new city, a new living situation, new friends, new structures and schedules, new jobs and new expectations, and it can be a really scary time for even the most prepared and supported young person. (Don’t get me wrong: These things are also exciting and fun and open so many doors — but that doesn’t mean they’re not intimidating.)

And for those who don’t get the support they need? The transition can be really, really difficult.

Truthfully, even if you have a great support system, important things often fall through the cracks — and unfortunately, it seems that one of those things is mental health.

Teens’ Mental Health May Be Being Overlooked

A recent survey from WebMD/Medscape and The JED Foundation says that while teens are more stressed and anxious than they have been in the past, parents are still sending them off to college with little or no focus on their mental health.

Of the more than 500 health care professionals involved in the survey, 86% said that in the last five years, they’ve seen an uptick in signs of anxiety and stress in teens. Eighty-one percent said they’ve seen more anxiety disorders in their teen patients, while 70% reported seeing more mood disorders like bipolar disorder and depression.

Of the parents who took the survey, 45% said their child had been diagnosed or treated for a mental health issue, substance abuse problem or learning disorder. Fifty-one percent said that their child had seen a therapist at some point.

Still, only 17% of the parents surveyed said they took mental health services and on-campus counseling into account when considering schools for their teen.

Even among the parents of teens with an anxiety, mood or stress disorder, only 28% said they had given any thought to the mental health care at their teen’s future school.

A Rise in Teens With Mental Health Problems

The college years are a critical point for mental health, with about 75% of all mental health conditions starting by the age of 24.

“College presents… sort of a perfect storm,” says Stephanie Pinder-Amaker, PhD, director of the College Mental Health Program at McLean Hospital on WebMD. “You not only have a young person entering the stage where they’re most likely to develop a mental health issue, but you also have a significant amount of stress.”

While the number of teens affected by mental health disorders is on the rise, it’s unclear whether this is due to a higher incidence of mental health problems or simply an openness to talk about them that wasn’t there before, experts say.

But while teens and parents are more open than ever to talking about mental health while the teen is at home, it isn’t quite enough.

“I think it’s a good idea for all parents and students to consider counseling and mental health resources in the pre-application process,” Pinder-Amaker explains.

Make Mental Health a Priority

If you’re a parent to a teen who will soon be going off to college, be sure to look into the mental health care at the universities your child is considering.

Check to see if counseling services are free, how much they cost if they’re not, how long students usually wait to book an appointment, and if there are any limits on how many sessions one student can have.

Then, make sure that your teen knows how to access the help they may need.

Be sure to talk to your teen often and openly about their mental health. Check in to ensure they’re still going to their appointments and make sure they feel they’re getting the help they need.

If you’re a student who is navigating this process on your own, there are plenty of people who are ready and willing to help.

Contact your student health services department to ask about mental health care. You can usually find a contact phone number or email on your school’s website.

Ask about how much the services will cost, and how you should pay for them. Do they offer any free services? If not, does payment have to be taken care of on the day of your appointment? Or can it be added to your tuition bill?

The counselors and medical professionals at the health services center want to help, and they’ll often work with you to create a treatment and payment plan that works for you.

If you don’t have access to student health services or you’d prefer other treatment options, here are nine ways to get free or cheap mental health care — even if you don’t have insurance.

Either way, work to make your mental health a priority. It’s easy to get caught up in college life and forget to take care of yourself, but it’s important to address and treat any mental health problems you may be dealing with.

However you choose to go about it, don’t ignore your mental health.

Grace Schweizer is a junior writer at The Penny Hoarder.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder http://ift.tt/2DIPf1J

Hilton Is Hiring Work-From-Home Customer-Service Reps in These 29 States

Do you have excellent customer service skills, the ability to troubleshoot problems and a desire to work from home?

Hilton may just have the perfect job for you.

The global hotel chain is looking to hire part-time remote reservation sales specialists.

As a reservation sales specialist, you’ll answer customer calls in a friendly manner and respond to inquiries regarding availability, accommodations, sales promotions, transportation to and from properties and more.

This is part-time position, working an average of 25 hours per week. Schedules are flexible, but you’ll need the ability to work mid-day or evening hours as well as some weekends and holidays.

While this is a work-from-home position, the company needs these employees to live in the following 29 states: Alabama, Arkansas, Delaware, Florida, Georgia, Idaho, Illinois, Indiana, Iowa, Kansas, Kentucky, Louisiana, Michigan, Mississippi, Missouri, Nebraska, New Hampshire, New Mexico, North Carolina, Ohio, Oklahoma, Pennsylvania, South Carolina, Tennessee, Texas, Utah, Virginia, Wisconsin, and Wyoming. Here’s a link to why some work-from-home jobs are restricted by state.

How to Land This Work-From-Home Job With Hilton

For this gig, Hilton is looking for someone with at least one year of experience in a customer-oriented or sales role.

You should also have at least six months’ experience in a sales-oriented, performance-driven role where you’ve had to successfully meet metrics or goals, upsell or cross-sell, overcome objections and use negotiating skills.

A college degree is not required.

Job candidates also should:

  • Have a positive attitude with high energy
  • Have strong communication and active listening skills
  • Possess excellent customer service skills
  • Be computer literate
  • Be able to provide a quiet work environment, free from noise and distractions

Job interviews and training will be done virtually.

Once you’re hired, the company will provide you with specific hardware to get the job done. However, you’ll already need to have:

  • A monitor
  • Surge protector
  • High-speed wired internet connection of 10 Mbps or higher (wireless is not permitted)

Click here to apply for this job. If you’re interested in other work-from-home jobs — or jobs in general — then make sure to like The Penny Hoarder Jobs on Facebook.

Nicole Dow is a staff writer at The Penny Hoarder.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder http://ift.tt/2ildvxy

Why the Study Saying Millennials Have $100K Saved Is Super Misleading

You probably scrolled across a pretty wild statistic recently: It claimed one in six millennials — 16% — has saved at least $100,000 in 2016.

That’s according to a Bank of America survey made exclusively available to USA Today.

I did an actual spit-take when I saw that number (with La Croix rather than coffee — I’m a millennial, after all). As my wife and I hurriedly tallied up our savings, even including home equity, we barely touched that total.

How could this be true? A sizable portion of a generation saddled with student debt and wanted for killing everything from cereal to bars of soap has still managed to save six figures?

Well, don’t freak out like I did, because it’s probably not true.

Millennials’ median net worth sat at about $11,000 in 2016, according to the latest Survey of Consumer Finances conducted by the U.S. Federal Reserve. And I was even more skeptical of the that $100,000 whopper after digging deeper into panel data from a government survey released by the Consumer Financial Protection Bureau last year.

Indeed, a Penny Hoarder analysis of that data tells a much different story.

Millennial Retirement Savings Are Probably Way Less Than $100,000

First off, the Bank of America study only classifies millennials as those between ages 23 and 37 in 2015, which is skewed older than the accepted age range recognized by the Pew Research Center. The U.S. Census Bureau has a similar range to Pew, as does the CFPB survey, which collected millennial responses from those aged 18 to 35.

We found 12% of millennials are likely to refuse even answering how much they have in savings, according to a weighted analysis of CFPB financial well-being survey data. And I don’t blame them.

Overall, only 3% of millennials have $75,000 or more in savings. Even with the larger age range, it’s quite a stretch from the 16% that apparently have $100,000 in the Bank of America study.

A little more than a third of millennials — 37% — are likely to have less than $1,000 in savings, according to our analysis. And 12% of us have no savings at all.

It’s not much rosier for other generations, either. Sure, 13% of folks older than 34 are likely to have $75,000, but even for this more mature cohort, more than a third have $1,000 or less in savings.

When you look at all ages, more than half of those surveyed said they weren’t optimistic about their futures. It doesn’t have to be this way.

4 Ways to Pad Those Retirement Savings Right Now

See, plenty of people are in your shoes and don’t have $100,000 saved. But there are definitely steps you can take to be on your way to whatever your savings goal might be.

Try a few of our favorite hacks for tackling savings.

1. Start Robo-Investing With These Tools

OK, this sounds totally weird. You might be imagining a metallic bank teller, but robo-investing is actually a way of investing for the future without even thinking about it.

Stash will automatically pull money from your bank account with just $5 to start. You sort of trick yourself into saving, and by the end of the year, you’ll be happy you started it.

Acorns, which will give you a free $10 to start, automates your savings by rounding up purchases you make on a connected credit or debit card, then investing the change into a fund.

As for which one is best, that’s totally up to you.

2. Switch Banks and Make Money Off Your Savings

Aspiration’s Summit checking account, an online-only bank account, is a favorite around Penny Hoarder HQ.

There are no monthly fees, you can get reimbursed for ATM fees and Aspiration pays up to 1% interest on your balance. You could start socking away money for retirement in no time.

3. Get the Most out of Your 401(k)

Got a 401(k)? You’re on the right track.

Now, you just need to make sure it’s doing what you need it to. However, tapping into that account and deciphering the information — or lack thereof — can be hard.

There’s a robo-advisor for that. Blooom, an SEC-registered investment advisory firm, will optimize and monitor your 401(k) for you.

A few of us Penny Hoarders use the service.  It gives you an initial 401(k) checkup for free, and you’ll get to know your account a little more intimately. Find out if you’re paying too many hidden fees, have the appropriate amount invested in stocks versus bonds, that kind of fun stuff.

After that, the tool is $10 a month to use to continue to monitor your retirement account. Let Blooom know your target retirement age, and it can help you get there by investing more and less aggressively.

4. Snag a Side Gig and Rake in That Extra Cash

One way to save money is to make more money. And as you know, that’s our specialty.

From online surveys to Airbnb to Uber and Lyft, here are 12 ways to save an extra $5,000 for retirement this year.

But most importantly, don’t get down when you see sensational news articles about how much your generation is saving. There might be more to the numbers than you think.

Alex Mahadevan is a data journalist at The Penny Hoarder. He doesn’t quite have six figures in savings, but he’s made a dent in his goals since starting this job.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder http://ift.tt/2Ebuhpi

How To Invest in Real Estate (11 Different Ways!)

9 Ways to Get Your Startup Funded

Don’t let money stop you from pursuing your dreams.

If you want to start your own business but don’t have the funding, you can still get it off the ground in a number of ways.

As an entrepreneur myself, I admire anyone who wants to create a company.

It’s not easy.

In fact, only half of small businesses in the United States will survive through their fifth year of operation.

Furthermore, just 30% of those businesses make it through ten years.

Based on this information, it’s clear that failure is more frequent than success when it comes to startup companies.

So I commend you for wanting to pursue this path.

While running a startup may be difficult, it’s also extremely rewarding.

You’ll learn a lot along the way. There are plenty of things I wish I knew before starting my first company.

But getting your startup off the ground is the first step.

Like with most aspects of business, you’ll need some money to do this.

If you’ve never been through this process before, it may seem intimidating.

Not sure where to start?

There’s no one right answer.

In fact, you can get money from multiple sources.

I’ve outlined 9 ways for you to get your startup funded.

I’ll let you decide which ones are best for your startup company.

1. Create a detailed business plan

Before you do anything else, you need to have a clear understanding of how you plan to operate your business.

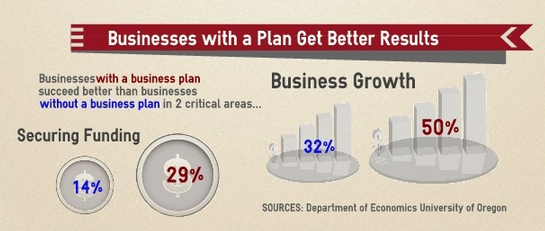
A business plan will increase your chances of securing funds:

image2 1

Companies that have a business plan also have higher growth rates.

Here’s why.

First of all, it’ll be hard for you to raise money from anyone without a business plan.

Different types of investors, which we’ll discuss shortly, will need to see financial projections before they even consider giving you a dime.

This plan will also set you up for success.

Once you get into the daily grind of your business operations, you’ll always have your plan as a reference to remind you how to proceed.

You may forget some ideas a year or two down the road if you don’t have everything in writing.

Your business plan should have a clear description of your business.

Who are you?

What do you do?

It should also include a market analysis.

This will discuss information and research about your competitors as well as your target market.

You’ll also want to outline the organizational structure of your company.

Have clearly defined roles for managers and other positions within your organization.

Arguably the most important part of a business plan is the financials.

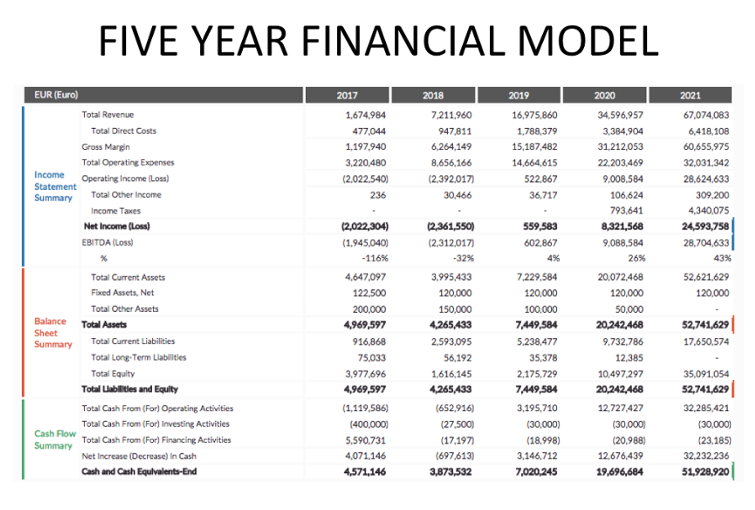
Do your best to include financial projections for the next three to five years:

image4 1

Make sure your projections are realistic.

As you can see from the example above, this company doesn’t project profitability until the third year of operation.

That’s okay.

You don’t need to turn a profit on your first day or even your first year.

Just try your best to accurately predict your finances.

This section of the business plan will help you secure funding from other sources on our list as well.

2. Visit your local bank

Go to the banks you use for your personal banking needs.

I recommend starting there because you already have a relationship with those companies.

Set up an appointment with a loan officer.

Show up to your meeting prepared.

Dress professionally. Bring your business plan.

Explain to the loan officer how much money you need and what it will be used for.

Depending on your situation, you may qualify for loans for certain aspects of your business, such as equipment.

If the bank denies your small business loan application, you could also try to get a personal line of credit from that institution.

You can use that line of credit to fund your initial business expenses.

Don’t quit after your first appointment.

You could try other banks and financial institutions if your first stop is unsuccessful.

3. Seek help from friends and family

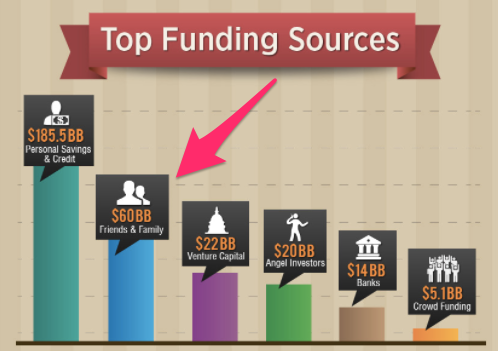
In the United States, friends and family are second on the list for top startup funding sources.

image1 1

These are the people who love you and trust you.

Most importantly, they believe in you and your potential.

Don’t be afraid to ask your loved ones for a loan.

Plus, unlike with a bank, you’ll likely be able to get some money from your friends and family without having to pay any interest.

Who knows, if you’re lucky, you might even get funds as a gift.

So talk to your parents, siblings, grandparents, or even your rich uncle.

Just know there are some risks associated with this approach as well.

You definitely don’t want to take a loan your friends gave you in good faith and lose it.

That could put both of you in a very uncomfortable situation.

With that said, I’ve talked to some entrepreneurs who said this had the opposite effect on them.

Loans from their family contributed to their success because they had extra motivation to not lose the investment.

They didn’t want to let their loved ones down.

4. Venture capitalists (VCs)

You can also secure funds from venture capitalists.

VC firms invest in the early stages of your company in exchange for an equity share.

If you decide to take this route, be prepared to give away a portion of your business.

That’s not always a bad thing.

If VCs have some skin in the game, they may be able to provide you with other resources that can contribute to the success of the company.

But just understand that smart VCs will only structure these deals if they are in their favor.

They don’t want to make a return on their investment in 30 years.

VCs want to make their money back, plus some, as soon as possible.

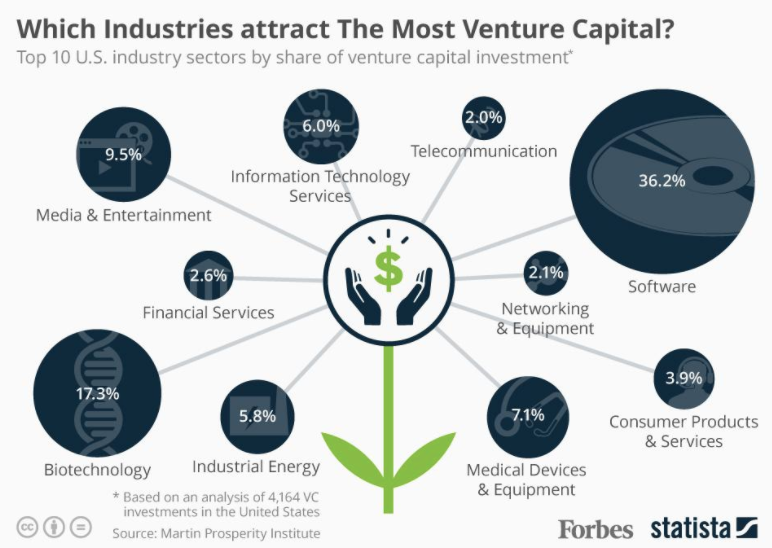
The likelihood of you receiving VC funding largely depends on your industry.

image7 1

As you can see from this data, venture capital firms are typically drawn to startups within software and technology sectors.

So if your startup company is a local pizza shop, you probably won’t have luck with VCs.

5. Angel investors

Although these terms are often used interchangeably, angel investors differ from VCs.

While angel investors can take an equity share of your startup in exchange for their investment, their funding can also be exchanged for convertible debt.

It’s not uncommon for these investors to be entrepreneurs or former entrepreneurs themselves.

Although money is their motivation, they are more likely to be genuinely interested in your business as well as the growth and development of particular industries.

If you find the right angel investor, you may benefit from their expert advice and management skills.

It’s more common for angel investors to supply funding to businesses when they are still in the early stages, whereas VCs typically look to get involved a little bit later.

Unlike a VC firm that has a committee and advisors working together, an angel investor may make a decision on their own.

They may simply like your plan, trust your goals, and believe that your business will be successful.

That’s why it’s important for you to be able to articulate your business plan well.

A short meeting over coffee or lunch with an angel investor might be all it takes to get them on board to fund your startup.

6. Crowdfunding

Take advantage of the resources available to you online.

You can use crowdfunding websites to raise capital.

While most people think of Kickstarter when it comes to these platforms, there are some alternative websites you can consider as well.

Here are a few popular choices for startup companies:

image6 1

All of these sites operate in more or less the same way.

Some put you in a pool of professional investors, while others let you raise money from anyone.

If your project is promoted properly, you can raise a ton of money.

Here’s an example to show you what I’m talking about.

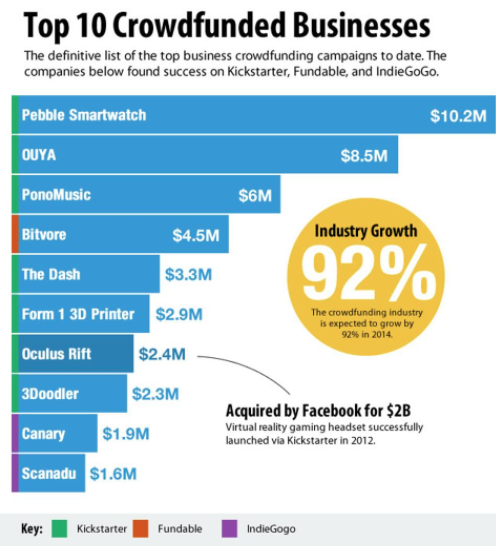
In 2012, a company called Oculus Rift launched a campaign on Kickstarter with a goal of $250,000.

The company aimed to produce virtual reality headsets.

They ended up raising $2.4 million dollars, which was nearly ten times their goal.

It’s safe to say that funding was successful.

The money led to rapid success and growth of the company.

Just two years later, Facebook bought Oculus for $2 billion.

It just goes to show crowdfunding isn’t just for college students or small side projects.

There’s real money to be found out there.

You just need to look for it.

Here’s a look at some of the other top crowdfunded startups in terms of capital raised:

image3 1

But just because you secure millions in funding doesn’t mean your company will automatically be successful.

Pebble Watches raised over $10 million in 2012, which largely exceeded their $100,000 goal.

But a highly competitive space made it difficult for this company to stand the test of time.

In 2016, Pebble announced they were ceasing daily operations. They stopped producing watches and honoring warranties.

The company folded.

7. Dip into your personal savings

You could also consider funding the startup company on your own.

If you’ve got money saved up for a down payment on a house or some other big purchase, you could use it to launch your business instead.

It’s risky because you won’t have any money to fall back on if your business is unsuccessful.

But if you’re willing to bet on yourself, there are plenty of positive factors to this route.

First of all, you won’t have to give up any equity in your company.

You get to keep all the profits instead of sharing them with investors.

You also won’t have to pay any interest on a line of credit or bank loan.

If you pay for everything yourself, you won’t be letting down friends or family members who may have loaned you money.

This isn’t an option for everyone.

But if you have an extra $20,000 in the bank, consider using it if your startup costs are low.

8. Look for a strategic partner

I’m sure you’ve heard the saying, “Two heads are better than one.”

Getting a strategic partner for your startup company can help accelerate the development of your business.

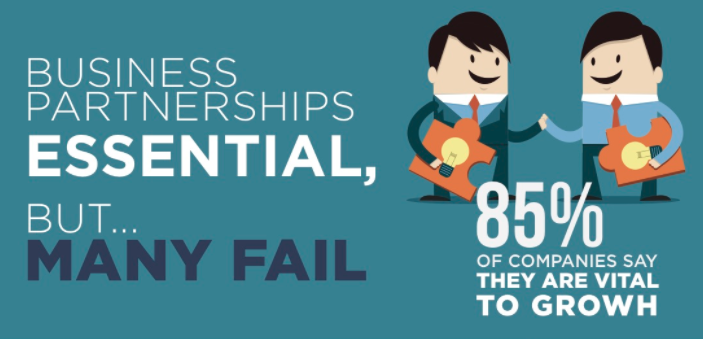
In fact, over 80% of companies say partnerships are essential to their growth.

image5 1

Your partner has a bank account as well.

Between the two of you, you might have enough money saved to get your startup off the ground.

If not, it’s another person to help you secure funding through the other methods I’ve outlined in this post.

Partners also reduce your liability. You won’t be on the hook for as much if things go south.

On a flip side, you’ll only get half the profits.

You may get even less if you give away equity to other investors.

Make sure you find someone you can trust.

While your strategic partner may be able to bring new ideas and solutions to the table, there can also be conflicts and disagreements.

9. Try to minimize initial business costs

Reevaluate your startup costs.

You may not need to raise as much money as you initially thought.

Make the money you already have last as long as possible.

Instead of paying for an office, you could work from your home or a shared office space.

Pay for goods and services as you go instead of paying upfront for large quantities of products.

Use cost-effective materials.

Think outside the box.

And while this may not work for every startup, you can also barter.

Instead of paying for certain products or services, offer your own services in return.

This may be successful if you’re working with other startup companies in a similar to yours situation.

Just do your best to keep costs as low as possible.

Conclusion

Starting a new business is exciting.

But it’s not cheap.

Not everyone has enough money to get their startup company off the ground.

If you can’t fund your business on your own, try getting a loan or line of credit from your local bank.

You could always ask your friends and family for help.

Venture capitalists, angel investors, strategic partners, and crowdfunding platforms are also great options to consider.

It’s important that you always start with a strong business plan.

Come up with realistic financial projections.

This will make it easier for you to get money from investors.

You also need to keep all your costs as low as possible to make your funds last until you can get a steady income stream.

Follow these tips, and you’ll be on the right path toward raising money for your company.

Good luck!

What strategies are you using to secure funding for your startup company?


Source Quick Sprout http://ift.tt/2GhL2j8