Don't believe everything you hear about taxes. Here are six of what the IRS considers the most common tax filing myths debunked.
Source CBNNews.com http://ift.tt/2GPdKY6


الثلاثاء، 27 فبراير 2018

Twenty Frugal Ways to Get Yourself Out of a Bad Place
I’m kind of a cyclical person. I’ll go for a month or two where I just feel great and happy all the time, and then I’ll hit a rough spot where I’m frustrated and unhappy with myself. I find myself being far less productive, and I end up wasting a lot of time not doing anything of value at all.
When I’m in that kind of state, it isn’t fun. I’m not happy with myself. I often feel like I’m putting on a mask of happiness when interacting with people around me. I sleep more, and find I often get sick more, too. I often find myself overspending via online shopping, too.
There are several things that I do to shake myself out of this bad state, none of which involve spending any money. I usually find that a few days of filling my time with these things really helps and I’m back to my typical demeanor.
Please note that I am not a doctor or a therapist, just someone who gets a mild case of the blues sometimes and has found some good ways to get himself out of them. If you feel listless and sad on a frequent basis, you should talk to a doctor.
Go for a walk outside. Get up from whatever it is you’re doing, put on appropriate clothing, and go for a walk around the block. Let some sunshine hit your skin. The combination of those little pieces – simply moving around, getting some vitamin D from the sunshine, changing your environment a little, allowing the sunshine to affect your serotonin levels – will naturally lift you up a little, especially if you’ve spent a lot of time inside lately. I have a “mile walk” that I often take even on cold days; I can complete it in fifteen to twenty minutes depending on my pace and I almost always end up feeling better afterwards.
Visit a natural area, preferably one with trees. You can easily do this in conjunction with a walk if you live near a park. If not, drive to a park somewhere and go on a walk in that park. Just wander around in a natural environment for a while, which gives you all of the benefits of a normal walk, plus there’s a little something extra that one finds in a natural environment, particularly a wooded one. There’s a ton of historical and scientific evidence that “forest bathing” offers some nice mental health benefits. I know that, for myself, a slow walk in the woods almost always leaves me feeling more “together” than before.
Get some mild exercise – anything that you enjoy doing that gets your heart pumping and your breath elevated for a while. This is another thing that you can combine with a walk if you so choose. Just raise your walking pace until you’re at the point where you’re breathing heavier and your heart rate is up and you’re maybe sweating a little bit. If there’s a different exercise you prefer, do that instead – maybe it’s squats or planks or push-ups. The goal is to simply convince your body to release a big pile of endorphins, which feel really good.
Call a friend or family member and have an actual conversation. Don’t just text them or like their social media posts. Call that person up and have an actual conversation with them. Simply say that you wanted to hear their voice, or perhaps reference something they shared, or simply ask how they’re doing. Listen. Ask questions. You’ll get off the phone and feel a lot better about yourself and about the world in general.
Invite a friend over to do something at your house. It really doesn’t matter what you do. It’s simply an opportunity to have some face to face social time with someone, where you positively interact with each other. Invite that person over for a simple dinner or to plan for some future event or to work on crafts or to work on a home repair or home improvement project. Whatever it is you choose to do, the key thing is to do it with someone else. That basic social interaction will do wonders for lifting your spirits.
Change a few elements of your daily routine. Instead of listening to the same radio station on your commute, listen to something different. Have something unusual for lunch. Instead of just watching television in the evening, do something else with that free time. Make something a bit unusual for supper. Just change up some of the elements of your ordinary workday and see how it makes you feel.
If you have a pet, curl up with that pet. Spend some quality time with your pet. Encourage your dog to climb up next to you and take a nap by your side while you pet him or her. Do the same with your cat. If you have another type of pet, spend some time with it, simply talking to it and taking care of it in some fashion. The act of caring for and bonding with a pet releases a lot of positive chemicals inside of people.
Focus on just the big three, and don’t worry about the rest. Identify the three big things you want to achieve today and simply don’t worry about anything else. Just focus on getting those done, then recognize that today was a pretty big success and just fill the rest of your hours with whatever comes to mind, knowing that you’ve taken care of the big things in your day.
Do a mindful meditation or prayer, and repeat it every day. This is one of those things that might help a little when you do it, but the benefit comes from making it a daily practice. Just spend five or ten minutes in a comfortable place with your eyes closed, focusing on your breathing or on a simple phrase or short prayer. Whenever you notice your attention wandering, bring it back to your breathing or to that phrase or prayer. That’s it. Over time, you’ll find that it brings you a great deal of peace, but it’s not something that happens overnight.
Eat some fruits and vegetables. It is so easy in this modern world to get into a routine of eating convenient foods that don’t contain many fruits and vegetables at all. Making an effort to include fruits and vegetables in your diet can go a long way toward balancing your food intake and leaving you feeling healthier and more naturally balanced.
Fill up a couple pages in a journal with whatever comes to mind. This is a common journaling practice that I’ve found incredibly valuable in my own life. You just sit down in the morning with an open journal before you and try to fill up three pages with your thoughts. Just write whatever comes to mind. You can also set a timer instead and just strive to write for that length of time. What this does is it forces you to address whatever is on the top of your mind at a slower and more well considered rate. As you write down thoughts by hand, you have to think them through a little more, and because of that you often find yourself reaching deeper conclusions than you otherwise would. Again, this is a great daily practice.
List five things you’re grateful for, and do it every day. This is another practice that gets better and better if you do it every day. Simply make a short list of five things that you’re truly grateful for. They can be small things, like the smell of freshly-poured coffee or the feel of warm sunlight on your skin, or they can be big things, like the love of your life. Just think of five things that make your life better and write them down. Then do it again tomorrow. And the next day. And the day after that.
Get a good night of sleep – not too little, not too much. Many Americans sleep too little, getting five or fewer hours of sleep a night. Others sleep too much, getting ten or twelve or more hours per night. The best balance for virtually all people is somewhere in the middle – seven to nine hours of sleep in a given night is pretty healthy. Start striving for that. If you’re sleeping far more than that, start using alarms to awaken yourself earlier. If you’re sleeping less than that, stop setting an alarm altogether and start going to bed earlier.
Watch your favorite movie, or re-read your favorite book. This is a comfort thing. Re-watching your favorite movie or re-reading your favorite book allows you to go through charted territory again, but it’s joyous territory. You know that media will make you think and lift your mood, so let that happen. Explore those familiar stories and ideas again and let them bolster you again.
Sign up for a volunteer shift at a local charity. While volunteering is all about helping others, there’s also an undeniable benefit that comes along with it – you feel good about yourself, too. It’s not so much a pride thing, but a sense that you’re truly making the world a better place. Volunteer Match is a great place to start this process, as the tool will help you find volunteer opportunities near you.
Help out someone in your life that you know could use a helping hand right now. You can take the same volunteerism approach but apply it to the people in your own life. Who in your life could really use a helping hand? Do you have an elderly relative or friend who is having difficulty getting things done? Perhaps you have another friend who is struggling with the blues even more than you are. Maybe you know some new parents who are burning the candle at both ends. Whatever the case, put some of your time aside and give those people the help they need. Help an elderly relative with some household chores. Visit a lonely friend. Help a new parent by running some errands for them or watching their new infant for a while. You’ll make a real difference, and it’ll feel pretty good.
Take a break from social media. Social media is often filled with people showing off the highlight reels of their life, mixed in with very negative political vitriol. Neither one is particularly good for a personal sense of happiness and well being. So, take a break from it. Log out of social media, delete the apps, and simply stop checking it for a while. You may just find some happier results in your life.
Take a long, warm shower, then brush your teeth and com your hair and put on some deodorant. Sometimes, the simple process of cleaning yourself up, putting on fresh clothes, and making yourself a little more presentable to the world can leave you feeling quite good about yourself and those around you. A shower and a bit of hygiene can really liven a person up.
Clean a room in your home. Choose a room in your home that’s a bit messy and put in the effort to clean it up. Put things away, vacuum the carpet, wipe markings off the walls, dust, change some of the wall decorations, you get the idea. Your goal should be to make the room feel fresh and alive instead of dreary and stale. That simple practice can really go a long way toward improving the state of your home.
If you’re in a relationship, hold onto your partner for a while. Even her hand. Just grab your partner’s hand and hold it for a while, or put your arm around your partner, or rest on your partner’s shoulder or lap. Just be close to your partner in whatever way works the best for you and your partner. That type of closeness unlocks a number of positive psychological and physical effects that can go a long way toward lifting your mood.
These strategies offer a repertoire of tactics that can help you get out of a sad phase in your life. They’re not foolproof and they certainly won’t work for everyone, but they often work for me.
Again, as I stated earlier in this article: Please note that I am not a doctor or a therapist, just someone who gets a mild case of the blues sometimes and has found some good ways to get himself out of them. If you feel listless and sad on a frequent basis, you should talk to a doctor.
Good luck!
The post Twenty Frugal Ways to Get Yourself Out of a Bad Place appeared first on The Simple Dollar.


Source The Simple Dollar http://ift.tt/2BTJkor
A HUGE List of Free Resources to Help Run Your Home-Based Business
By Holly Reisem Hanna Leaving the security of a steady paying job to launch a new business can be a scary endeavor. Even if you've planned and saved six months worth of living expenses, often it takes months to start generating income from your business. And guess what? Even if you don't have money coming […]
The post A HUGE List of Free Resources to Help Run Your Home-Based Business appeared first on The Work at Home Woman.
Source The Work at Home Woman http://ift.tt/2sZOHzM
The Tooth Fairy Is a Little Stingier This Year. Here’s What She’s Paying
A quarter? Fifty cents? A dollar?
That’s nothing compared to what children are getting these days.
According to the most recent results of the Original Tooth Fairy Poll, parents are leaving an average of $4.13 per tooth under their kids’ pillows.
The payout actually declined from the previous year’s average of $4.66 — an all-time high for the annual poll conducted by Delta Dental.
If your kid is losing his or her first tooth, be prepared to pay more. The current average first-tooth rate is $5.70 — down slightly from the previous year’s average of $5.72.
Tooth-fairy rates also vary from region to region. The poll found parents in the West give the most: an average of $4.85 per tooth, with a premium of $6.76 for children losing their first tooth.
Parents in the Northeast paid an average of $4.35 a tooth, or $6.45 for a first tooth. Those in the South paid $4.12 per tooth or $5.68 for a first tooth. Midwest tooth fairies left an average of $3.44 a tooth, or $4.37 for a first tooth.
Some parents decide to go a little overboard, keeping the lie magic of the tooth fairy alive. The Original Tooth Fairy Poll found 47% of parents leave a small toy or game, and 35% pen a letter from the fairy herself (a lost-tooth certificate might be a nice accompaniment) .
Thirty-one percent gift a new toothbrush — a great way to promote dental hygiene.
Most (95%) of parents posing as the tooth fairy leave these extras in addition to leaving money. But that doesn’t mean everybody leaves tooth-fairy money and goodies under their child’s pillow.
If you’re on a tight budget (or just don’t feel like lying to your kid about yet another mythical being who sneaks into your home in the middle of the night), don’t feel guilty forgoing tooth-fairy activities. Sixteen percent of poll respondents with kids ages 6 to 12 do not make tooth-fairy visits.
Nicole Dow is a staff writer at The Penny Hoarder. She enjoys writing about parenting and money.
This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.
source The Penny Hoarder http://ift.tt/2sZE1kG
Use a Credit Freeze to Stop Identity Thieves Cold
It’s been just over six months since the now infamous Equifax data breach of 2017. To refresh your memory, this massive data breach potentially exposed the personal information of some 145.5 million U.S. consumers. The exposed data included names, addresses, Social Security numbers, and dates of birth.
Of course, the Equifax data breach is not the only reason you need to be concerned about the security of your personal information. While Equifax’s massive hack was understandably upsetting to consumers, it’s certainly not the only data breach that may have put your personal information at risk. The disturbing truth is that nearly 1,600 data breaches were announced publicly in 2017 alone, according to the Identity Theft Resource Center.
The need to protect your credit from identity thieves only becomes more important with each passing year. Thankfully there are a number of actions you can and should take to protect your personal information and your credit from bad guys. And of all the credit protection strategies out there, the most effective one by far is a credit freeze — especially when you suspect your personal data has been compromised.
How a Credit Freeze Protects You
According to the Fair Credit Reporting Act, your credit reports can be accessed by anyone who’s deemed to have a “permissible purpose” to request them — that includes lenders who wish to view your reports as part of an application for new credit. The trouble for lenders is that they can’t easily tell if it’s you who’s applying for a new loan or credit card — or a crook who’s fraudulently applying for financing in your name.
A credit freeze, also called a security freeze, can help to solve this problem. When you place a freeze on your credit reports, you essentially lock your reports so that new lenders cannot access them without your consent. Unlike a fraud alert, which lasts for 90 days and simply requires businesses to verify your identity before issuing new credit to you, a credit freeze essentially takes your credit reports out of circulation until you say otherwise.
If you’ve placed a freeze on your three credit reports and an identity thief tries to open a fraudulent account in your name, the lender who attempts to process the phony application wouldn’t be able to access your credit report; they’ll get a message back that your report has been frozen.
As a result, the application will be denied, preventing the fraudulent account from being opened. The thief may still be in possession of your personal data, but your credit freeze will prevent them from using that data against you to open unauthorized accounts.
How to Freeze Your Credit
Placing a freeze on your credit reports is simple and inexpensive. The quickest way to request a freeze is online, though you have the option to freeze your reports over the phone or via mail as well.
If you do opt to freeze your credit reports, it’s also important that you do so separately at each of the three major credit reporting agencies: Equifax, TransUnion, and Experian. If you neglect to freeze your credit with all three bureaus, you’ll still be vulnerable.
Below are some links to help you get started putting your credit reports on ice at each credit bureau:
Equifax Credit Freeze
- You can freeze your credit with Equifax here. In the wake of their massive data breach, Equifax is waiving any fees on credit freezes through June 2018.
TransUnion Credit Freeze
- To freeze your credit with TransUnion, start here. TransUnion also allows a less intensive credit lock, which you can turn on and off in real time online.
Experian Credit Freeze
- Freeze or thaw your Experian credit reports here.
Once you place a freeze on your credit reports, you’ll be issued or be asked to choose a PIN. Remember to save all three of your PINs, because you will need them in the future to “thaw” your reports when you wish to apply for credit yourself — or in any other situation where someone will need to access your credit reports. In some states, a credit freeze expires after seven years, but in most cases, it lasts until you request the freeze to be lifted.
Depending on your situation, you may be required to pay a fee to both place AND lift a credit freeze. Fees can vary per state, but they generally fall between $3 and $10.
That’s a small price to pay to avoid identity theft, especially if you believe your data has been compromised. And if you’ve already been a victim of identity theft (and have a police report to prove it), then placing and lifting a credit freeze can be done free of charge.
Related Articles:
- The Other Big Data Hacks Nobody’s Talking About
- Identity Theft Basics
- Why You Need to Check Your Credit Report With All Three Credit Bureaus
John Ulzheimer is an expert on credit reporting, credit scoring, and identity theft. He has written four books on the topic and has been interviewed and quoted thousands of times over the past 10 years. With time spent at Equifax and FICO, Ulzheimer is the only credit expert who actually comes from the credit industry. He has been an expert witness in over 230 credit related lawsuits and has been qualified to testify in both federal and state courts on the topic of consumer credit.
The post Use a Credit Freeze to Stop Identity Thieves Cold appeared first on The Simple Dollar.


Source The Simple Dollar http://ift.tt/2ozPBxn
Do Low-Fat Diets Work Better Than Low-Carb Diets? New Study Has The Answer
People often turn to low-carb diets, but that requires giving up tasty bread and pasta.
Low-fat diets are another popular choice, but that means relinquishing your stash of delicious cheese (yes, low-fat cheese exists but usually tastes like spackle).
If you’re on the fence about which diet choice leads to the most effective weight loss, new research from Stanford University School of Medicine may make the decision easier.
A study of 609 men and women between ages 18 and 50 revealed that dieters can lose roughly the same amount of weight eating a healthy low-carb or low-fat diet.
Researchers acknowledge there was a wide variety of results among the study’s participants. The average weight loss was an average of 13 pounds at the end of one year, but some participants lost 60 or more pounds, while others gained 15 to 20.
But Dr. Christopher Gardner, the lead author of the study, says the basic weight-loss strategy is the same for low-fat and low-carb diets. For the best results, people should eat loads of vegetables and cut back on sugar and refined flour.
“On both sides, we heard from people who had lost the most weight that we had helped them change their relationship to food, and that now they were more thoughtful about how they ate,” Gardner said in a news release.
Low-Fat and Low-Carb Diets Don’t Have to Be a Drag
Since your weight loss results are likely to be the same no matter which of the two diet plans you choose, pick the one that shrinks your waistline, not your pocketbook.
These money-saving tips will get you started.
- Packing vegetables into your diet doesn’t have to be a chore. In fact, YouTube is filled with videos on how to make vegetarian and vegan fare that will make you forget cheeseburgers and bacon exist (well, almost).
- Sugar-sweetened sodas are often among the first thing to go when people start a low-carb diet. Fortunately, there are plenty of yummy alternatives to regular and diet soda you can make right at home.
- We all need comfort food from time to time. These four budget-friendly low-carb alternatives to indulgences like pizza and nachos are a perfect go-to when the cravings kick in.
- If you’re searching the internet for meal ideas, be sure to take a look at other types of dietary programs. Some Paleo, Whole 30 and DASH Diet recipes are naturally low-fat or low-carb and use ingredients you probably already have on hand.
Whichever diet plan you choose, check with your doctor to make sure it’s a good fit for your long-term health goals.
Lisa McGreevy is a staff writer at The Penny Hoarder. She loves telling readers about affordable ways to stay healthy, so look her up on Twitter (@lisah) if you’ve got a tip to share.
This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.
source The Penny Hoarder http://ift.tt/2GNqHlb
Best ways to supplement your pension

If you are banking on the state pension to fund your retirement, the ever-rising state pension age is cause for concern. Last year the government sped up the plan to increase the state pension age – it will rise to 68 by 2039, five years earlier than originally planned.
As the government struggles to come up with a solution to the problem of paying for an ageing population there is always a risk that it will increase the state pension age again, or even cut how much pensioners receive.
So, what can you do to supplement your state pension, or provide yourself with an income if you want to retire before you reach state pension age?
You have several options; which one is right for you will depend on how much risk you are prepared to take with your savings.
Risk averse people choose to keep their savings in cash and pay themselves a monthly income from the interest they earn.
“You can simply choose the best accounts that pay a regular income into your bank account – but you need to tread carefully as not all accounts offer this facility,” says Anna Bowes, director at independent savings website Savings Champion.
“The good news is that many of the best buy accounts on the market offer a monthly income facility, so savers do not need to miss out.”
RCI Bank tops the tables for easy access savings paying 1.29% monthly gross. On a balance of £20,000 that should provide an income of around £21.50 a month. If you don’t need instant access to the cash then Atom Bank has a one-year fixed rate bond paying 1.95%AER, that falls to 1.93% if you want the monthly income facility, but on a £20,000 balance that would give around £32 a month in gross interest.
Unfortunately, with interest rates so low you would need to have almost £400,000 invested in the Atom Bank bond to get a monthly income that matched the full state pension of £159.55 a week in the 2017/18 tax year.
For ideas on how to beat the banks and earn more interest on your savings, visit the Moneywise model savings portfolios.
However, if you want your money to earn more then you will have to take on some risk.
“Many investors have to make difficult decisions in terms of the level of income they want or need and the amount of risk they’re prepared to take to achieve it,” says Patrick Connolly, a certified financial planner at Chase de Vere.
Graham Wellesley founder of alternative property finance firm Wellesley & Co says: “Leaving your money in the bank with very low interest rates has risks of its own as inflation eats away at the capital values too.”
One option to supplement your basic statement pension is making contributions to an additional private pension plan with a pension provider. However, Mr Wellesley says: “For many people the issue is do you wish to lock up your savings to provide this income in retirement? In particular for those who wish to retire before the state pension age one would need to tie up a substantial amount of capital to produce sufficient income and that can only be accessed at 55.”
Nevertheless, investing in a private pension such as a self-invested personal pension is the most tax-efficient way of saving for retirement, as your contributions are topped up by tax relief. Plus, at retirement, you can withdraw 25% of the fund tax free.
Peer to peer (P2P) investments are an increasingly popular way to increase the amount of income. But they come with extra risks and shouldn’t be compared directly with savings.
P2P platforms allow investors to lend money directly to individuals and businesses. In return, they receive an attractive yield - provided the borrower does not default.
Investing in P2P loans is not the same as putting your money in a savings account. There is no guarantee that the cash will be repaid and it is not covered by the Financial Services Compensation Scheme.
Other investments that Moneywise readers have asked about because they often have eye-catching headline rates of interest are retail mini bonds. With these, you lend your money to a company and they pay you interest on that loan, which can be paid as a monthly income.
If you buy company debt via bonds like these, the money you make back depends on the firms issuing them not going bust. The risk here is that mini-bonds are not covered by the Financial Services Compensation Scheme, so you are dependent on the company not going bust before the bond matures so that you get your money back. Also, this type of bond isn’t traded on the stock market so you can’t sell your bond.
Alternatively, you could opt for a retail bond. These are traded on the stock market so you could sell your bond before it matures if you need to access your money.
Inexperienced investors who are unsure about how retail or mini-bonds bonds work or their potential tax liabilities should seek independent financial advice. We certainly wouldn’t recommend them unless you’re a sophisticated investor who understands the risks.
If you want to allocate some of your portfolio to bonds it would probably be better to invest in a bond fund, which offers you diversification by spreading your money between debt from lots of different companies and a professional manager to do all the hard work selecting which bonds are best. You could try Fidelity MoneyBuilder Income or Jupiter Strategic Bond funds which are both members of the Moneywise First 50 Funds list for beginner investors.
Another way to supplement your pension is to invest in a range of income-producing investments in the stock market.
The obvious choice in this scenario is to invest in equity income funds that focus on investing in companies that pay a healthy dividend.
Invest your money here and you can hope to get a better monthly income than you would from cash. For example, Mr Connolly recommends the Threadneedle UK Equity Income fund which has a historic yield of 3.92%, that would give you a monthly income of around £65 on a £20,000 investment, before fees. Just bear in mind that you would receive your money quarterly, from dividends rather than a monthly payment.
However, don’t assume by spreading your money across a few different UK equity income funds you are spreading your risk. “In the UK around 80% of all dividend income is produced by 15 companies and 50% by just five companies,” says Mr Connolly.
“This means that there can be a high crossover of stocks between one UK equity fund and another and so those who invest in a number of equity income funds may not be achieving the level of diversification they might expect.”
Mr Connolly recommends that income hunters spread their money across equity income funds, fixed interest investments and commercial property to build a truly diversified income portfolio. His tips include the Rathbone Income fund, Schroder’s Income Maximiser fund, the Henderson Strategic Bond fund, and Henderson’s UK property fund.
You can find more recommendations for equity income funds – both ones that invest in the UK and those that invest overseas, and commercial property funds in the Moneywise First 50 Funds.
If you do choose to supplement your pension income via the stock market using bond or equity income funds then you also need to consider the tax implications. Invest via a Stocks and Shares Isa and any capital growth or income you receive will be tax-free.
Section
Content Showcase
WellesleyFree Tag
Related stories
Source Moneywise http://ift.tt/2BREfgy
الاثنين، 26 فبراير 2018
NJDOT says I-80 needs safety fence; mayor disagrees
An Interstate 80 project on the New Jersey side of the Delaware River may impact commuters and visitors to the Poconos in 2020.The New Jersey Department of Transportation wants to put rock walls and fences alongside a winding part of the roadway overlooked by tall rock cliffs leading up to the Delaware Water Gap Toll Bridge in New Jersey.Called a 60-foot tall rockfall berm, it is designed to catch falling rocks off the cliffs. The problem is, there aren’t any falling [...]
Source Business - poconorecord.com http://ift.tt/2EZ9ULw
Source Business - poconorecord.com http://ift.tt/2EZ9ULw
Here’s How That Hockey Jersey Can Score You Free Eats at Chipotle
Well, maybe not everyone. But if you weren’t excited before, this news might have you practicing dekes and dangles to the nearest Chipotle.
I’ll wait while you Google those words…
Chipotle is giving out free food!
How to Score BOGO Burritos and More
Wear your favorite hockey team’s jersey to any participating Chipotle on Friday, March 2, 2018 from 10:45 a.m. to 10:00 p.m. and score — see what I did there? — buy one, get one free burrito, bowls, salads or tacos.
Chipotle is an official sponsor of USA Hockey and Hockey Weekend Across America, which has celebrated and promoted hockey since 2008.
And after carb loading on those burritos, you can take a child near you to try hockey for free!
March 3 is Try Hockey For Free Day. Hundreds of rinks will give kids ages 4 to 9 a chance to try out hockey for free. Coaches will be in attendance to show them the ropes and there will be limited equipment to borrow. See if there is a participating rink near you.
Jen Smith is a junior writer at The Penny Hoarder. She gives money saving and debt payoff tips on Instagram at @savingwithspunk.
This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.
source The Penny Hoarder http://ift.tt/2GMyRdV
How To File Your Taxes For Free
Why pay to file your taxes if you don't have to? Discover IRS Free File, and learn if you qualify to file your taxes for free.
Source CBNNews.com http://ift.tt/2GJT6ZG
Source CBNNews.com http://ift.tt/2GJT6ZG
Love to Plan? This Company Is Hiring Work-From-Home Travel Consultants
From booking flights to finding affordable hotels, the abundance of choices available can make the process extremely overwhelming. Throw in a cancelled flight or miscommunication about a rental car, and it becomes downright stressful.
This is where a travel consultant comes in.
If you’ve got stellar customer service skills and enjoy planning and problem solving, then we’ve got a job for you.
Frosch, a travel-management company focused on leisure and corporate travel, is looking for full-time after-hours travel consultants.
This is a virtual position, and you would work from home during evenings, weekends, and holidays.
And if this doesn’t sound like your type of gig, no worries. You can check out our Jobs page on Facebook, where we’re always posting new work-from-home job opportunities.
Work-From-Home Travel Consultant Jobs at Frosch
Pay: Not specified
Responsibilities include:
- Managing clients’ travel reservations, such as coordinating airlines, hotels, and car rentals
- Processing cancellations and alterations and informing clients of these developments
- Resolving travelers’ problems in a timely manner
Applicants for this position must have:
- At least three years of recent experience using the Sabre Global Distribution System
- At least one year of experience using Apollo
- Extensive knowledge of both international and domestic routing
- Thorough understanding of airfare contracts
Benefits include:
- Medical, dental, and vision insurance
- IATA and LifeMart benefits
- Gym reimbursement
- Continued training opportunities
Apply here for the after-hours travel consultant job at Frosch.
Kaitlyn Blount is a junior staff writer at The Penny Hoarder
This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.
source The Penny Hoarder http://ift.tt/2CoaHrR
McDonald’s Loves the Szechuan Sauce Drama. Here’s How You Can Avoid it
So much so that when restaurants ran out in 2017, it led to riots. Yes, seriously. McDonalds even released a series of podcasts about the whole incident. It’s good entertainment if you have a few minutes of downtime.
After what I can only imagine has been months of sadness and frustration, as these rabid fans of the sauce have had to go without since Oct. 8, 2017, McDonald’s is bringing it back. When?
Today. Monday, February 26.
While Ronald, Grimace and the gang promise not to run out this time — they will release 20 million packets of Szechuan Sauce this year — it’s best to be prepared. Why wait with bated breath for McDonald’s to release it each year when you can just make your own (possibly better) version at home?
How to Make Your Own Mulan Szechuan Sauce
For a few months, Reddit users have been upvoting a fan’s tribute recipe for McDonald’s Szechuan Sauce, which he developed somewhere between the fast-food giant’s sauce promotion for “Mulan” and its recent resurgence.
Here’s what it takes, according to user Xeropoint:
6 cloves garlic
4 tablespoons balsamic vinegar
Soy sauce (to taste)
2 tablespoons plum sake (optional)
3 ½ tablespoons Sriracha
2 tablespoons brown sugar
Red pepper flakes (to taste)
How much does that all cost?
Garlic cloves: $1.50
Balsamic vinegar: $2.68
Soy sauce: $1.44
Sriracha: $2.12
Brown sugar: $1.36
Red pepper flakes: $1.40
Plum sake (optional): $7.99
Total cost: $10.50 to $18.49
OK, so it’s not a money saver if you’re starting from scratch. But what would you rather do? Go to McDonald’s with your family, spend about as much to only get a few packets of sauce and be done with it? Or make this tribute sauce at home, where you can enjoy it again and again?
No, seriously, don’t make me solve your time versus money questions. I can’t take the pressure. It’s your sauce, people. Get it however you can get it.
Lisa Rowan is a senior writer and producer at The Penny Hoarder.
Tyler Omoth is a senior writer at The Penny Hoarder who loves soaking up the sun and finding creative ways to help others. Catch him on Twitter at @Tyomoth.
This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.
source The Penny Hoarder http://ift.tt/2wK6GHP
How to Write a Business Plan for Your Startup
Anyone can have a great idea. But turning an idea into a viable business is a different ballgame.
You may think you’re ready to launch a startup company. That’s great news, and you should be excited about it.
Take it from me: as someone who has founded several startup companies, I know what it takes to be successful in this space.
Before you start seeking legal advice, renting office space, or forming an LLC, you need to put your thoughts on paper. This will help you stay organized and focused.
You’ll also be able to share this plan with others to help you get valuable feedback. I don’t recommend starting a company without consulting people first.
A typical business plan consists of the following elements:
- executive summary
- company description
- market research
- description of products and/or services
- management and operational structure
- marketing and sales strategy
- financials
Thoroughly writing out your plan accomplishes several things.
First, it gives you a much better understanding of your business. You may think you know what you’re talking about, but putting it on paper will truly make you an expert.
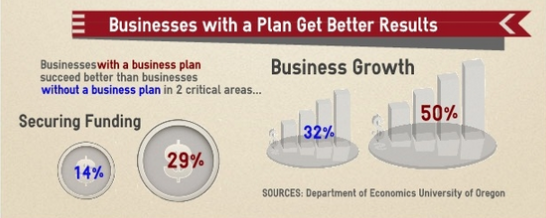
Writing a formal plan increases your chances of success by 16%.
Having a business plan also gives you a better chance of raising capital for your startup company. No banks or investors will give you a dollar if you don’t have a solid business plan.
Plus, companies with business plans also see higher growth rates than those without a plan.
If you have an idea for a startup company but not sure how to get started with a business plan, I’ll help you out.
I’ll show you how to write different elements of your business plan and provide some helpful tips along the way. Here’s what you need to know to get started.
Make sure your company has a clear objective
When writing a company description, make sure it’s not ambiguous.
“We’re going to sell stuff”
isn’t going to cut it.
Instead, identify who you are and when you plan on going into business. State what kinds of products or services you’ll be offering and in what industry.
Where will this business operate? Be clear whether you’ll have a physical store, operate online, or both. Is your company local, regional, national, or international?
Your company description can also incorporate your mission statement.
This is an opportunity for you to gain a better understanding of your startup. The company summary forces you to set clear objectives. The type of company you have and how you will operate should be obvious to anyone who reads it.
Include the reasons for going into business. For example, let’s say you’re opening a restaurant. A reason for opening could be that you identified that no other restaurants in the area serve the cuisine you specialize in.
You can briefly discuss the vision and future of your startup company, but you don’t need to go into too much detail. You’ll cover that in greater depth as you write the rest of your business plan.
Keep in mind, this description is a summary, so there’s no reason for you to write a ton. This section should be pretty concise and no more than three or four paragraphs.
Identify your target market
Your business isn’t for everyone. Although you may think everyone will love your idea, that’s not a viable business strategy.
One of the first steps to launching a successful business is clearly identifying the target market of your startup.
But to find out whom you’ll target, you need to conduct market research.
This is arguably the most important part of launching a startup company. If there’s no market for your business, the company will fail. It’s as simple as that.
All too often I see entrepreneurs rush into a decision because they fall in love with an idea. Due to this tunnel vision, they don’t take the necessary steps to conduct the proper research.
Sadly, those businesses don’t last.
But if you take the time to write a business plan, you may discover there’s not a viable market for your startup before it’s too late. It’s much better to learn this information in these preliminary stages than after you’ve dumped a ton of money into your venture.
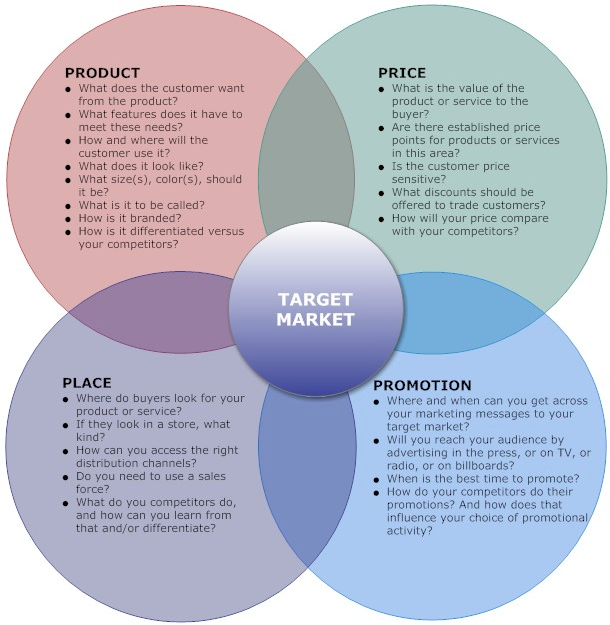
To figure out your target market, start with broad assumptions and slowly narrow it down. Typically, the best way to segment your audience is using these four categories:
- geographic
- demographic
- psychographic
- behavioral
Start with things like:
- age
- gender
- income level
- ethnicity
- location
As I said earlier, start broadly. For example, you may start by saying your target market lives in North America, and then narrow it down to the United States.
But as you continue going through your market research, you can get even more specific. You can target customers living in New England, for example.
By the time you’re finished, the target market could look something like this:
- males
- ages 26 to 40
- living in the Boston area
- with an annual income of $55,000-$70,000
- who are into recycling
This profile encompasses all four demographic segments I mentioned earlier. Plus, it’s very specific.
Your business plan should talk about the research you conducted to identify this market. Talk about the data you collected from surveys and interviews.
You’ll use this target market in other sections of the business plan as well when you discuss future projections and your marketing strategy. We’ll cover both of those topics shortly.
Analyze your competition
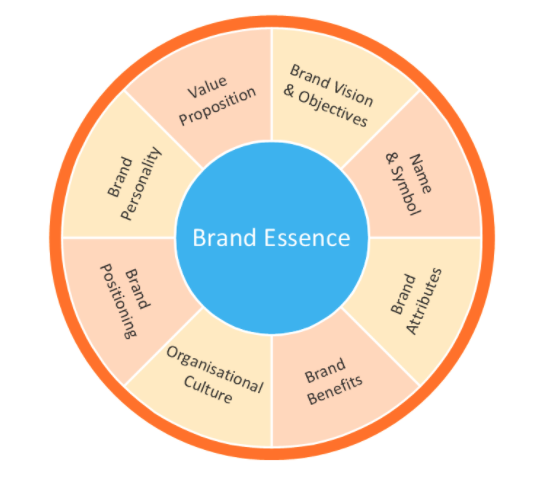
In addition to researching your target market, you need to conduct a competitive analysis as well. You’ll use this information to create your brand differentiation strategy.
When you’re writing a business plan, your startup doesn’t exist yet. Nobody knows about you. Don’t expect to be successful if you’re planning to launch a competitor’s carbon copy.
Customers won’t have a reason to switch to your brand if it’s the same as the company they already know and trust.
How will you separate yourself from the crowd?
Your differentiation strategy could involve your price and quality. If your prices are significantly lower, that can be your niche in the industry. If you have superior quality, there is a market for that as well.
Competitive analysis should be conducted simultaneously with identifying your target audience. Both of these fall under the market research category of your business plan.
Once you figure out who your competitors are, it will be easier to determine how your company will be different from them. But this information will be based on your target market.
For example, let’s say you’re in the clothing industry. Your competitors will depend on your target market. If you’re planning to sell jeans for $50, you won’t be competing with designer brands selling jeans for $750.
Or you can base your price differentiation on what you learned about your target market. From there, you’ll be able to identify your competitors.
As you can see, the two go hand in hand.
Budget accordingly
You need to have all your numbers in order when you’re writing a business plan, especially if you’re planning on securing investment funding.
Figure out exactly how much money you need to start the business and stay operational; otherwise, you’ll run out of money.
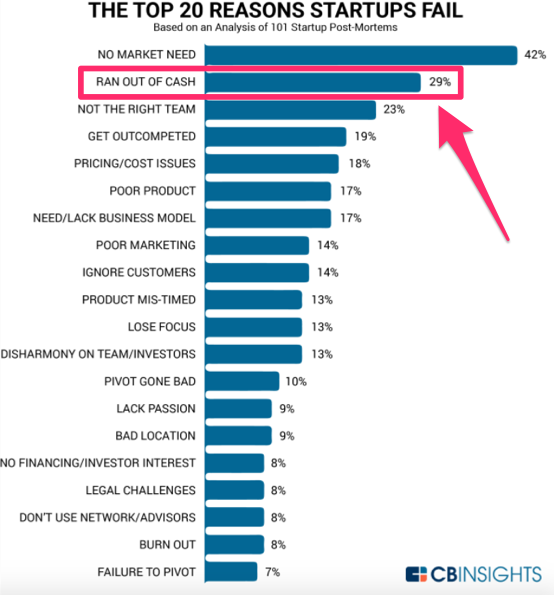
Running out of cash is one of the most common reasons why startup companies fail. Taking the time to sort your budget out before you launch will minimize that risk.
Consider everything. Start with the basics like:
- equipment costs
- property (buying or leasing)
- legal fees
- payroll
- insurance
- inventory
Here’s an example of what this will look like in your business plan:
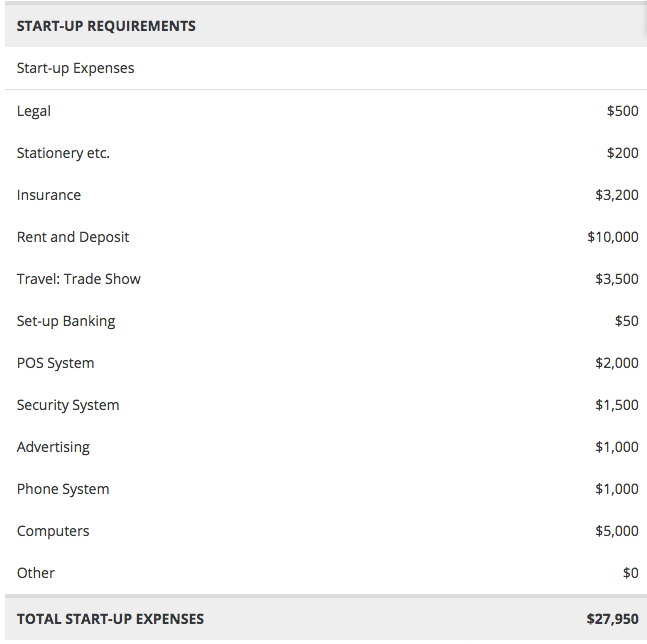
These numbers need to be accurate. When in doubt, estimate higher. Things don’t always go according to plan.
In the example above, although the total startup expenses are less than $28k, it may not be a bad idea to raise $40k or even $50k. That way, you’d have some extra cash in the bank in case something comes up.
You don’t want poor budgeting to be the reason for your startup’s failure.
Identify your goals and financial projections
Let’s continue talking about your financials. Obviously, you won’t have any income statements, balance sheets, cash flow reports, or other accounting documents if you’re not fully operational.
However, you can still make projections. You can base these projections on the total population of the target market in your area and what percentage of that market you think you can penetrate.
If you have an expansion strategy in mind, this would also be outlined in your financial projections.
These projections should cover the first three to five years of your startup. Make sure they are reasonable. Don’t just say you’ll make $10 million in your first year. In fact, your company may not be even profitable for the first couple of years.
That’s OK.
As long as you’re being honest with yourself and potential investors, your financial plan will cover your break-even analysis.
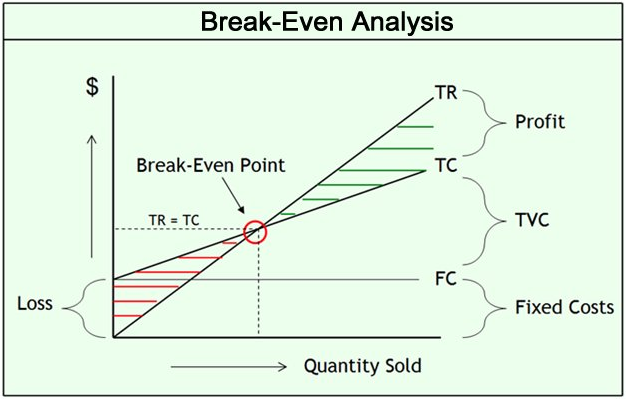
While it’s reasonable to expect your sales revenue to increase each year, you still need to take all factors into consideration.
For example, if you’re planning to expand to a new location in year four, your financial projections need to be adjusted accordingly.
You may not be profitable until your third year of operation, but if you’re opening a new facility in year four, that year may have a net loss as well. Again, this is completely fine as long as you’re planning and budgeting accordingly.
Another example of a goal could be launching an ecommerce store in addition to your brick-and-mortar locations. Just don’t try to bite off more than you can chew. Keep everything within reason.
Clearly define the power structure
Your business plan should also cover the organizational structure of your startup. If it’s a small company with just you and maybe one or two business partners, this should be easy.
But depending on how you’re planning to scale the company, it’s best to get this sorted out sooner rather than later. Here’s an example of what your organizational chart may look like:
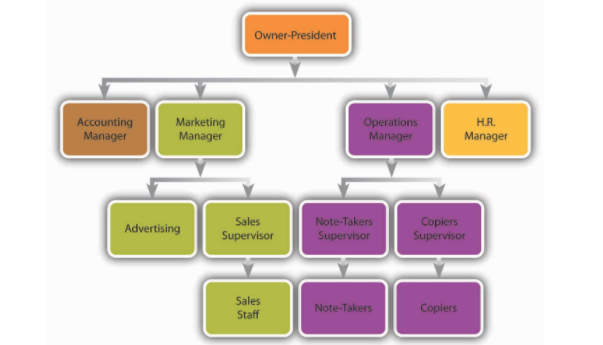
It’s really important to have this hierarchy in place before you get started. That way, there’s no debate over who reports to which position. It’s clear who is in charge of specific people and departments.
Don’t get too complex with this.
If you put too many layers of managers, directors, and supervisors between the top of the chart and the bottom of the chart, things can get confusing.
You don’t want any instructions or assignments to get lost in translation between levels. You also don’t want anyone to be confused about who is in charge.
This is an opportunity for you to outline how your company will operate in terms of board members and investors. Who has the final say in decisions?
While I understand you may need to give up some equity in your startup to get off the ground, I recommend keeping the power in your hands.
Discuss your marketing plan
Your marketing plan relies on everything else I’ve talked about so far.
How will you acquire customers based on the market research of your target audience and competitive analysis?
This strategy needs to be aligned with your budget and financial projections as well.
I could sit here and talk about different marketing strategies all day. But there’s no right or wrong way to approach this for your startup company.
My recommendation would be to stay as cost-effective as possible. Be versatile and well-balanced too.
Acquiring customers is expensive. You don’t want to dump your entire marketing budget into one strategy. If it doesn’t work, you’ve got nothing to fall back on.
Take these categories into consideration when you’re coming up with a marketing plan:
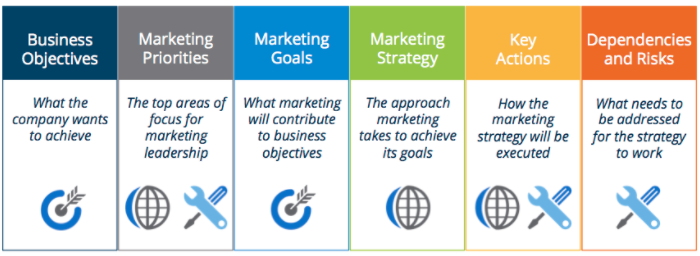
Before you try anything too crazy, get the basics sorted out first:
- launch a website
- stay active on social media platforms
- start building an email subscriber list
- focus on customer retention
- come up with customer loyalty programs.
Don’t ease into this one step at a time. Come out fast. Even before your company officially launches, you can start building your website and social media profiles.
The last thing you want is for consumers to find out about your brand but then be unable to find your website or contact information. Or worse, get directed to a website that’s broken or unfinished.
Keep it short and professional
I’ve talked about many different components of your business plan. It may sound overwhelming, but don’t be alarmed.
This shouldn’t be a 100-page dissertation.
You definitely want it to be detailed and thorough, but don’t go overboard. There’s no exact number of pages it should be, but have at least one page per section.
It should also be written cleanly and professionally. Don’t use slang terminology.
Proofread it for grammatical and spelling errors.
Remember, you may need to use this to raise capital. People may be hesitant to give you money if you overlook the small stuff like proper grammar.
Conclusion
Launching a startup company is exciting. It’s easy to get so caught up in the moment that you rush into things.
If you want to set yourself up for success, you need to take a step back and plan things out.
Going through the process of writing a formal business plan will increase your chances of securing an investment and also improve your potential growth rate.
The market research you’ll need to conduct in order to write this plan will also help you determine whether this is a viable business venture to proceed with.
If you’ve never written a business plan, use this post as a guide for what you should include. Follow my tips for best practices.
Writing a business plan may seem like a tedious task right now, but I promise it will keep you organized and save you lots of headaches down the road.
Good luck!
What elements of a business plan have you started drafting for your startup company?


Source Quick Sprout http://ift.tt/2ETmznv
Should you join the open banking revolution?

Open banking aims to boost competition in the financial sector, making it easier for consumers to compare bank accounts and then switch to a better deal. Moneywise weighs up the pros and cons of this move towards sharing data.
The arrival of open banking in the UK opens a wealth of possibilities for people looking to better manage their finances, laying the ground for apps that tell you when you could get a better bank account elsewhere – and where to go for a better deal.
A Moneywise online poll in January 2018 (see below) found that while one in 10 readers welcome open banking because they think it will make comparing accounts easier and introduce more competition to the sector, the majority are sceptical.
Moneywise reader Chez says: “I have yet to be convinced that it is something I want or need.”
Others say they are worried about the financial security of sharing data with third parties.

Unleashing your data
Open banking launched on 13 January 2018. It means that customers of the UK’s biggest banking brands can share current account data with trusted third parties if you give them permission to do so.
The Competition and Markets Authority is behind this project and wants to stimulate competition in the banking sector by making it easier for customers to compare accounts across multiple providers.
Banks are now required to hold your financial data in a standardised format, which can be used by third parties, such as apps and websites.
At first, only the nine biggest current account providers in the UK: Allied Irish Bank, Bank of Ireland, Barclays, Danske Bank, HSBC, Lloyds Banking Group, Nationwide, RBS and Santander have been required to open their data for customers.
However, five of these brands – Bank of Ireland, Barclays, HSBC, RBS and Santander – have missed the deadline for some customers and won’t be fully integrated until September 2018. There was no financial penalty imposed on the banks who were late. They were simply given extra time to comply with the rules.
Initially only your current account data can be shared with third parties. However, the rules will be extended to cover all credit cards, e-money (services such as PayPal) and savings accounts that are accessible online by the end of 2019.
By then, the rules will also cover all current accounts that are accessible online, regardless of provider. So a building society offering current accounts with no online functionality would not have to comply, but smaller banks who offer online accounts will.
This is part of the second European- wide Payment Services Directive, which aims to create a regulated ecosystem for payments and account information.
Brexit shouldn’t make a difference because this is a directive (and thus is implemented by our national regulator), rather than the rules being imposed directly by the EU itself.
Looking to the future
It will take time for third party companies to understand what customers are looking to get from their data and what can be achieved with the data they have access to.
Open Banking – the organisation set up to promote the scheme – says that firms will initially offer basic services, such as an app that lets users view transactions across all their accounts, so you can better manage your spending. This could be expanded so that customers can transfer their current account overdraft to another provider, depending on which bank is offering the best rate.
However, there are doubts over whether people will engage with the new technology at all. Since the introduction of the seven- day switching service for current accounts in 2013, engagement has been low. Data from Bacs, the company that runs Direct Debits in the UK, shows that just 931,956 of the more than 60 million accounts in the UK were switched during 2017.
Victor Trokoudes, chief executive of money management app Plum, says that while initial progress is likely to be slow, in a matter of years open banking will transform the way consumers interact with their finances.
“We expect that in three years’ time we will have entirely switched to a holistic platform to manage money, beyond traditional banking,” he says.
“Enabling customers to manage all of their finances in one place will remove complexity and, with the application of artificial intelligence (AI) and automation, people will be able to grow their money in the best way, without hassle.”
Open banking could also have a ripple effect on other areas of the finance industry, even if the rules do not directly apply to those products. In future, your data could be used by mortgage lenders to judge affordability as it will document your monthly income and outgoings.
Richard Hayes, chief executive of digital mortgage broker Nuvo, says that third party firms could use open banking data for everything from basic tasks – such as filling in forms automatically – to working out whether lenders are likely to accept your application.
“Open banking means access for brokers and lenders to more accurate information about a customer’s financial situation,” he says.
“This, in turn, speeds up the approval process, as very often delays in decisions are because of inaccurate or incomplete information. It will significantly reduce the amount of documentation and checks that need to be completed too.
“Also, by having access to accurate data on a person’s spending habits, calculating affordability will be much more robust, leading to better decision making.”
The same principles can be used when applying for other types of financial products, such as credit cards and personal loans.
Staying safe
Many people remain sceptical about the benefits of open banking. Moneywise’s poll found that 73% would not use open banking, with most of this group saying they would be unwilling to let a third party access their financial data.
But these concerns may be overblown, according to Francesco Simoneschi, chief executive of financial data firm TrueLayer. He says that the regulator’s checks are in line with other areas of financial services.
“It isn’t surprising that many people are reluctant to share their data with third parties under open banking. A lot of scare stories have been written about the security surrounding it,” he says.
“People should always be careful how and with whom they share their personal information. However, it’s important to note that there is a big difference between sharing personal data freely with an organisation such as a retailer or social media site, and with a third party via open banking.
“The reality is that for a company, app or service to use personal financial data through open banking it needs to pass rigorous security and compliance procedures, including regulatory licensing. The entire process is overseen by the Financial Conduct Authority (FCA) and results in companies having a level of security akin to banks and other financial institutions.”
Consumers can make sure they are dealing with FCA-regulated firms by checking the Financial Services Register at Register.fca.org.uk.
Mr Trokoudes argues that, in time, customers will feel the benefits of open banking. It will force banks to up their game, as consumers with poor products will be more likely to switch.
“More often than not, when it comes to switching, people fail to get the best deal when comparing products or services because they tend to stick with the financial institution they are familiar with and already have an existing relationship.
“With open banking, the banks’ whole approach to selling financial services – not to mention the way they use data – will be forced to change to prioritise the interests of the consumer, rather than their balance sheets.”
Section
Free Tag
Related stories
Source Moneywise http://ift.tt/2sVHn8l
Questions About Food Inflation, Craigslist, Costco, Principles, and More!
What’s inside? Here are the questions answered in today’s reader mailbag, boiled down to summaries of five or fewer words. Click on the number to jump straight down to the question.
1. Finding health insurance
2. Dealing with food inflation
3. Thinking about job offer
4. Enough shopping around?
5. Return of premium life insurance
6. Craigslist scammer
7. Debt after death
8. Costco math
9. List of principles
10. Rolling over 401(k)s
11. Frugal solution to car salt
12. Reflecting on spending mistakes
I’ve had a rip-roaring winter cold the last few days, the first one I’ve really had in a long while. As I write this, I mostly just want to go right back to bed and get a good batch of sleep.
I wish I had some sort of magic formula for feeling better until a winter cold has passed, but I simply don’t. It just takes a few days until your body’s immune system figures it out and eliminates it.
Until then, misery.
On with the questions.
Q1: Finding health insurance
My husband will be switching to a small business which does not offer healthcare. I’m not sure I would be considered a freelancer (I occasionally work as a locum tenens type healthcare provider: my work is intermittent and irregular). Either way, we’ll be losing out health insurance and we don’t know where to find anything that is actually affordable: the only healthcare.gov option in our state is $2500 monthly with a $12,000 deductible [which equates to paying $42,000 a year before the insurance company will pay a dime and we’re healthy, we won’t even come close to meeting that deductible]. We’ll have four kids but our income is too high to qualify us for any kind of discount through the website. Is there any other way to approach finding affordable healthcare? Blue Cross Blue Shield dropped individual plans in our state and I’m finding dead ends every other way. Any suggestions? What are your thoughts on the Christian Health Ministries? It’s really the only affordable option I can find right now and even then I don’t like the idea of paying for well child checks and vaccinations out of pocket.
– Alicia
Unfortunately, health care options in this country are disastrous, especially with people who do not have employer-backed coverage. The fundamental problem of insurance is that people who do not have employer-backed insurance are perceived to be a greater risk than those who do, thus actually finding someone to ensure you when you don’t have such coverage is expensive. The mandate to have insurance wrapped in the ACA was an attempt to fix that, but it only marginally worked.
There really is no good solution in your case. Options for people in your situation are pretty limited. They’re either expensive or limited in most cases.
Christian Health Ministries is an interesting case. While the rates are low, it’s basically a cost sharing service where you’re putting money into an escrow account to pay for the medical expenses of members as they occur, but there is no guarantee of payment and, as you note, what they do and don’t cover is a bit quirky. They do pay out what they have, but if it’s not enough to go around, they simply don’t cover everything. It’s far better than nothing and it is very low cost, but it is not a virtual guarantee of coverage, although it does seem to qualify as coverage for the provisions of the ACA.
Q2: Dealing with food inflation
How do you deal with the cost of food going up when your income is the same? I get a COLA on my pension every year but food goes up a lot more than that and that means I have less for other stuff.
– Esther
Cost of living adjustments these days often don’t match the changes in the cost of food. In some years, food definitely goes up more than a typical COL adjustment. In other years, they’re the same. Your observation is probably true if you live in an area where there is significant growth happening and the overall cost of living is going up faster than the national average.
So, what can you do about it? You can move to an area with a lower cost of living, for starters. That will immediately give you a lot more breathing room in your budget. You can also simply learn to budget your money more wisely.
Another thing I would encourage you to watch out for is a slow elevation in your food tastes. Are you really buying the same stuff you were buying five years ago, or have you slowly slipped into buying more “premium” versions of everything, like coffee or creamer or dishwashing detergent or ketchup? Take a look at the brands you regularly buy now and what you used to buy and see how the prices compare.
Q3: Thinking about job offer
I am 43/M married to 40/F, no kids, paying down a mortgage but no other debt. I make $70K (systems analyst) and she makes $45K (teacher). I like my job well but the pay is not super competitive. Last week, I was contacted by a friend of a friend who offered me a job at his company – I have to apply and interview but the job is basically mine if I want it. Similar work to what I’m doing now, but pay bumps to $93K starting out. New company culture seems fine – a couple of friends say they like it there and I can’t find any horror stories online. What should I do?
– Jeff
Decide what it would take for you to unquestionably stay where you are, then go talk to your current boss about it. Simply tell him or her the truth – you like where you are at, but you have friends who are making more than you for similar work. Don’t mention the job talks. Open with the fact that you’re happy here and stress that you really want to stay, but $25K a year is $25K a year and that’s hard to ignore. State that you want to work together to put a plan in place to get you to a competitive salary. See what the response is.
If the response sees you getting the salary bump you want to the level that would convince you to stay, then you should stay. If you get a negative response or if you get a very minimal offer to stay, pursue the other job offer.
That’s how I’d handle it. If you’re happy where you are, you should definitely tell them what’s going on and give them a chance to match or come close to matching.
Remember, salary isn’t everything and you know you’re happy where you’re at. While you may want the salaries to be closer, don’t just go to where the salary is highest.
Q4: Enough shopping around?
My wife and I decided it is time to move to another bank. Our current bank charges fees for almost anything you can imagine and it’s ridiculous getting hit with $40 in fees each month for normal banking services.
We live in the Chicago area and there are a lot of banks. We have called around to several with local branches and found one or two that are strictly better than our current bank.
How many banks should we contact before we pull the trigger on the best one?
– Steve
You’ve hit upon a good point. A person can basically spend unlimited hours shopping around for a new bank or for other similar things like insurance. When do you stop?
When I am shopping around, I usually keep calling places until I find one that seems like the right one to me. When I find that my attention and focus is drawn back to one particular option, I know I’m close to being done.
At that point, I usually sit on it for a few days, then look through the options again. If I still find that the same option is on top, and I usually do, I go with them.
I don’t have a set number, but there’s almost always one option that starts really looking like the right one.
Q5: Return of premium life insurance
I am looking at life insurance and one company offers a “return of premium” insurance policy. It’s like a normal term life insurance except at the end you get your premiums back if you didn’t die. It costs a lot more than the regular term policy. What’s the catch here?
– Devin
A “return of premium” policy is exactly what you describe. You pay, say, $100 a year for a 30 year term policy and at the end of 30 years, if you’re still alive, they cut you a check for $3,000.
Compare that to a normal term policy that might have a $50 a year premium instead.
Now, the question is, if you just the second policy, can you invest the extra $50 a year well enough to make it to $3,000 by the end of 30 years? By my math, if you put it in the stock market in a broad based index fund returning an average of 7% per year, you would be money ahead with the normal term policy.
There’s a catch, of course: would you actually invest that $50 per year or not? If the answer is truthfully “no,” then there are worse things to do with your money than a “return of premium” life insurance policy.
Q6: Craigslist scammer
I think someone just tried to scam me on Craigslist. They wanted to buy something from me with a check from a local bank. Something about it seemed wrong so I said no and they got really upset. I think they were trying to bounce a check off of me. How do you avoid scammers on Craigslist?
– Julia
You basically don’t avoid scammers on Craigslist. Instead, you just have a few policies that sweep most scammers aside.
For example, have a policy where you only accept cash at the time of sale as a form of payment. You do not accept checks or PayPal or gift cards or anything else. Cash, period.
Stop by your local office supply store and get a pen that’s good for detecting counterfeit cash and take that to the sale with you. Mark some of the bills that they try to use with that marker and make sure they’re legit.
Those two little steps will avoid a lot of the typical scamming going on on Craigslist.
Q7: Debt after death
I was reading an article today about the average American dies with 61k in debt. What happens to this debt? Are relatives supposed to pay the debt?
– Anna
Most of the time, that debt is applied to the estate of the person who died. Their assets are sold off and the proceeds are used to pay off those debts. Anything that remains is then given to the survivors according to the estate plan.
So, let’s say Aunt Marjorie dies and has $61K in debt. You sell off her house and her car and her possessions that weren’t specifically left to anyone and then the proceeds from those sales are used to pay off those debts. This might leave, say, $30K, and that’s then distributed to the beneficiaries of the estate.
This is assuming that all debts are strictly in the name of the deceased person, of course.
Q8: Costco math
We recently renewed our membership at Costco. They now offer two memberships – one for $60/year that’s juts normal and one for $120/year that gets you 2% off everything you buy. My wife just instantly said that we wanted the normal membership and I didn’t make an issue out of it but I went home and ran the numbers and I am not sure that it is a bad deal. Could you help me figure out whether it’s worthwhile?
– Jeremy
For that higher priced membership to be worthwhile, it has to save you more than $60 an a year. To save $60 in a year, that means that you have to buy enough stuff so that 2% of the amount you buy is $60. That amount is $3,000.
So, if you’re going to spend more than $3,000 in the coming year at Costco, the more expensive membership is better. If not, then the less expensive membership is better.
The kicker with Costco – and the reason I lean toward the $120 membership – is that if you save less than $60 over the course of a year, they’ll refund you the difference.
The only real drawback to the $120 membership is the additional up front cost. That $60 may have been more useful to you elsewhere.
Q9: List of principles
In your recent blog post “12 Key Principles for Financial Success in Today’s World” you indicated that you\’ve been making “a giant list of all of…principles”. From your writings, I’ve come to deeply appreciate your life philosophy, not just about personal finance. So would you mind sharing your “giant list” of principles with me?
– Connie
Quite a few people wrote in and asked about this “list of principles” that I’m making. I will probably use it as a Saturday post at some point – on Saturdays, I tend to stray a bit further away from strictly writing about personal finance than I do on other days.
The list of principles is something I’m compiling as part of my ongoing effort to write journals for each of my kids. I’m in the process of writing a journal for each of them that contains a lot of material – reflections on who they are as people, family history, my own life history, advice for life problems that they might face, and a lot of principles to live by. I intend to give them to them when they reach adulthood and are old enough to appreciate it.
I want to convey to them the principles I live by and why so they can hopefully understand me more as a person and also find useful life advice to draw upon if something were to happen to me.
Once I’ve really codified that list, I’ll share it here in a post.
Q10: Rolling over 401(k)s
Item #5 in Helaine Olen’s “Single Retirement Planning Basics” at the end of the article “Retirement Planning for Singles Can Be Extra Tough” (https://amp.usatoday.com/story/83257058/) doesn\’t make sense to me. Assuming the 401(k) contributions are pretax, I prefer to consolidate accounts from different jobs whenever possible with direct rollovers to a single IRA. What do you think? “5. Don’t roll over your 401(k) if you change jobs; just let it be. This will keep the cost basis of your investment lower.”
– Gerry
I think that the issue here is that Helaine is making an extra assumption that’s going unsaid in order to keep the article short, which is a real issue for many publications that aim for a very short word count.
The issue that Helaine is trying to address (I think) is people considering rolling a 401(k) into a Roth IRA, which can cause a tax issue at a time when many people can’t afford that tax hit.
In other words, there are some specific situations where a rollover makes sense, and others where it doesn’t, and this little phrase isn’t nearly enough to explain the difference.
I think that this is a point that should have been explained with more length and it was probably trimmed to hit a word count target. This often happens when an article tries to fit in too many ideas in too small of a word count.
In short, I don’t think you’re doing it wrong, nor do I think the advice is necessarily bad, just under-explained.
Q11: Frugal solution to car salt
What can a person do to keep car wear from road salt from happening? I wash my car constantly during the winter and it’s at just 130K miles and there are already spots of rust on it.
– Jenny
As a lifelong resident of the upper Midwest, the only thing I’ve ever found that keeps rust from winter road salt at bay is constant washing – and I mean constant. If you don’t wash your car after every single winter storm of any kind, you’re basically begging for rust to eventually hit your car.
The only preventive trick I’ve found is to go get your oil changed in the months before winter and ask for an undercarriage coating. They spray on an oil-based solution that helps with keeping rust at bay under your car.
Other than that… just wash it frequently. That road salt is some vicious stuff.
Q12: Reflecting on spending mistakes
You talk about how you reflect on spending mistakes when you’re driving places. Can you elaborate on that a little bit because I’m not really clear on what you mean?
– Derek
I basically apply something known as an after action review to spending choices I made that I regret or at least want to carefully consider to make sure I made the right choice. The idea of an after action review is to carefully consider an action you took in the past and decide both whether it was the right action to take and what is the best action to take going forward.
With an after action review, the first thing you do is you identify what exactly you wanted to happen in that situation. For example, if I bought a big bottle of Gatorade at a gas station, I think through what I ideally wanted to happen when I stopped. I needed gas and I was thirsty and I wanted to solve both of those problems. What would I have ideally done to solve that problem? If everything had been perfect, I would have bought the best bang for the buck gas and I would probably have just filled up a water bottle at a water fountain or from a tap.
Then, you acknowledge what actually happened. I think through what I actually did, step by step. I bought gas that was probably the best bang for the buck gas, then I headed inside without a water bottle. Instead of figuring out what my cheapest option for purchase was, I just grabbed a Gatorade and bought it.
Three, you try to learn from the experience. Where did I deviate from my ideal and why? Well, my big mis-step was heading in without a water bottle in hand. Most gas stations have some way to fill a water bottle, so heading in without one was a mistake. Even without that bottle, I could have found a better bang for the buck beverage than a bottle of Gatorade.
Four, adjust your behavior. When I’m thirsty at a gas station, my goal should be to refill a water bottle from my car, and doing that requires me to keep a water bottle in my car and to remember it at gas stations.
I basically follow that model when reflecting on spending experiences or almost any experience I have in life that I want to reflect on and improve. I use it for social experiences, leadership experiences, and many other things. It not only helps me define a better path forward, it also does a good job of embedding that better set of choices in my head.
Got any questions? The best way to ask is to follow me on Facebook and ask questions directly there. I’ll attempt to answer them in a future mailbag (which, by way of full disclosure, may also get re-posted on other websites that pick up my blog). However, I do receive many, many questions per week, so I may not necessarily be able to answer yours.
The post Questions About Food Inflation, Craigslist, Costco, Principles, and More! appeared first on The Simple Dollar.


Source The Simple Dollar http://ift.tt/2orleKi
الاشتراك في:
الرسائل (Atom)