Thousands of courses for $10 728x90

الاثنين، 16 أبريل 2018

How to Generate Leads with Facebook Ads

Social media marketing has become one of the most effective ways for businesses to have success in the digital era.

In fact, 95% of adults between the ages of 18 and 34 follow brands on social media. Facebook leads the way in this category. According to Statista, Facebook has 2.2 billion active monthly users.

You can see why it’s so appealing for brands to have a presence on this platform. I hope  your company is on Facebook to.

To have success marketing on Facebook, you need to be active on a daily basis. Post content to your profile. Share photos, videos, and run promotions.

Facebook allows you to broadcast live videos to your followers. You should be taking advantage of that as well.

In fact, live videos are such an effective marketing strategy that it made my list of the top marketing trends to look for in 2018. Lots of these promotional tactics can be done  free.

But if you really want to take your social media marketing strategy to the next level, you need to run advertisements on Facebook.

Why Facebook? Well, in addition to  having the highest number of active monthly users compared to other social platforms, Facebook ads deliver a high ROI:
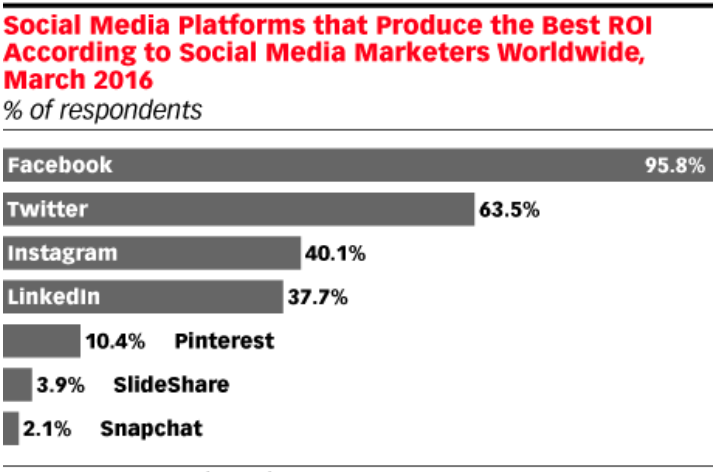
image2 4

Obviously, running these ads isn’t free. But knowing that such a high number of marketers say  this platform delivers the highest ROI compared to other social media networks should make it worth your while.

That said, nothing is guaranteed. Not all advertisements on Facebook are successful. That’s why I created this guide.

If you are new to Facebook ads or need some improvement running your existing ones, this guide is for you. I’ll show you how to set them up and generate leads for your business.

Set your goals

First things first. Why are you running this ad? You need to determine your goal ahead of time.

There are a few reasons for this. First, you want to make sure  the ad you’re creating is aligned with your goals. It’s also much easier to measure the success of a campaign if you have a goal in mind.

But another reason why you’ll need to set up a goal first is because Facebook will ask you what you’re trying to accomplish when you’re putting the ad together.

Here’s a look at different marketing objectives for you to choose from:
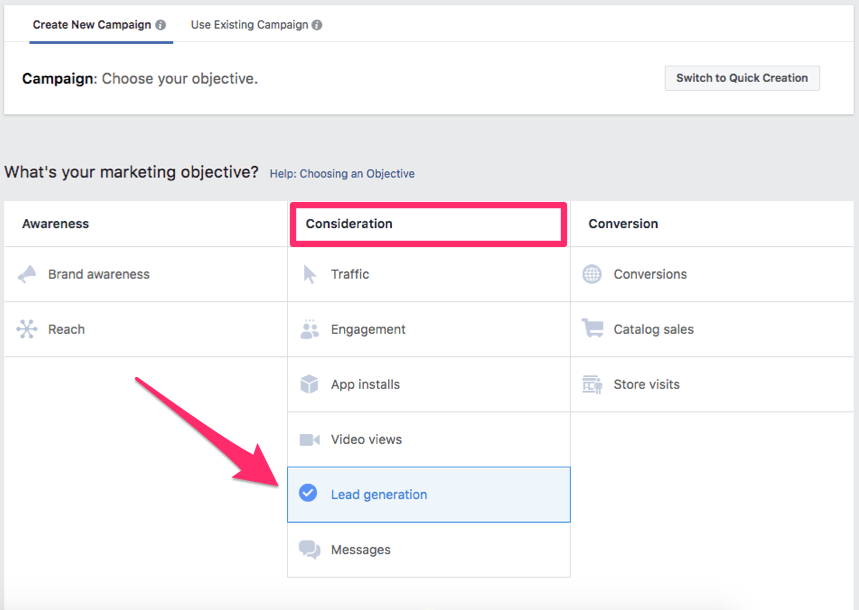
image3 5

As you can see, there is as an option for lead generation under the consideration column.

This will help you collect information from Facebook users interested in your business.

The cool thing about the lead generation campaign is you can set up a split test when you’re running it. I’m a big advocate of using A/B testing to maximize efficiency.

You can run tests of your campaign based on elements such as placement, audience, and delivery optimization. This makes it easier for you to measure your results and make any necessary adjustments. But we’ll discuss this concept in greater detail later.

You can also select one of the choices from the awareness column as an alternative method of generating leads.

Selecting the brand awareness option will aim to get your ad exposed to people who are most likely to pay attention to your message. A reach campaign, on the other hand, will expose your ad to the highest number of people possible.

Identify your target market

Next, you’ll have to determine who will see your ad.

No matter what type of business you have or what industry you’re in, it’s important you know your target market. In fact, knowing how to identify the target market of your startup is one of the first steps of creating a business.

Those of you who have been in operation for a while should have done this years ago.

That said, it doesn’t mean this selection will be cut and dry. You may have a diverse target market. Is this ad for everyone?

For example, let’s say your company sells a wide range of products and services. There’s a good chance you sell items intended for men and women of all ages.

Based on the goal  you’ve previously defined, your ad may be geared toward a specific segment or a larger target market.

Here’s an example of how you could set this up based on your audience:
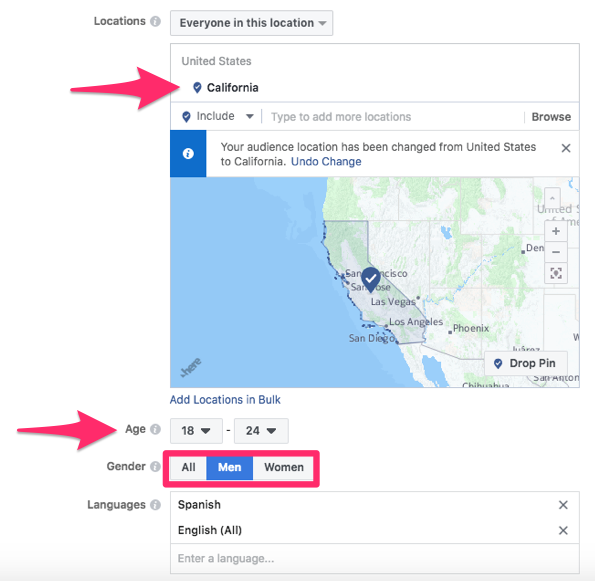
image5 5

As you can see, this ad is targeting men located in California. They are between the ages of 18 to 24 and speak English and Spanish.

Facebook allows you to get specific here. This is great because you can create multiple ads based on different segments of your target market.

Generic ads intended to reach a massive audience won’t be as successful. But if you target a specific group of people with your ads, you’ll be able to generate more leads.

All the information used is based on what each user puts in their Facebook profile. Keep in mind, this won’t be 100% accurate.

You’ll get some people who lie on their profiles about their age, gender, location, etc. But this shouldn’t be drastic enough to skew your results.

Set your budget

After you select your target market, you’ll have to determine how much money you want to spend on the ad.

Facebook makes it easy for you to set this up. Here’s what your options will look like:
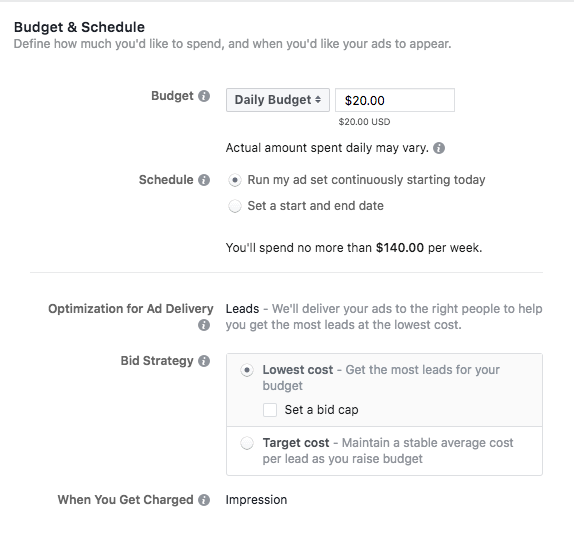
image4 5

This example uses a daily amount. But you can also use the total amount you’d like to spend on the lifetime of the ad.

Even though I set the daily budget to $20, it won’t always be exact. That’s because Facebook automatically shares your ad based on the most opportunities.

Certain days, the ad spend may be higher, but other days, it would be less to keep the daily average at $20. You’ll get charged based on each impression.

You can also set start and end dates for your ad. Or you can let it run continuously and stop it manually when it’s time.

Choose the format for your ad

Not all ads are the same. Facebook lets you choose which type of advertisement you want to run. Here are your options:

  • video
  • image
  • collection
  • carousel
  • slideshow
  • canvas

Video and image are both pretty self-explanatory, but I’ll explain what the others mean.

A collection is when display different items from your product catalog. It encourages users to shop by looking through a few items. Based on what you’re selling and the target market, these items will be customized for each person.

This is a great strategy for sales and conversions—but not necessarily lead generation. You can still use it as a marketing strategy.

Carousels allow you to display up to ten different videos or images within one advertisement. Each one would have its own link.

Slideshows use images, text, and sound to showcase your ad. Canvas ads can be opened as a full-screen display, and they are fully optimized for mobile devices.

Mobile ads are Facebook’s highest source of revenue.
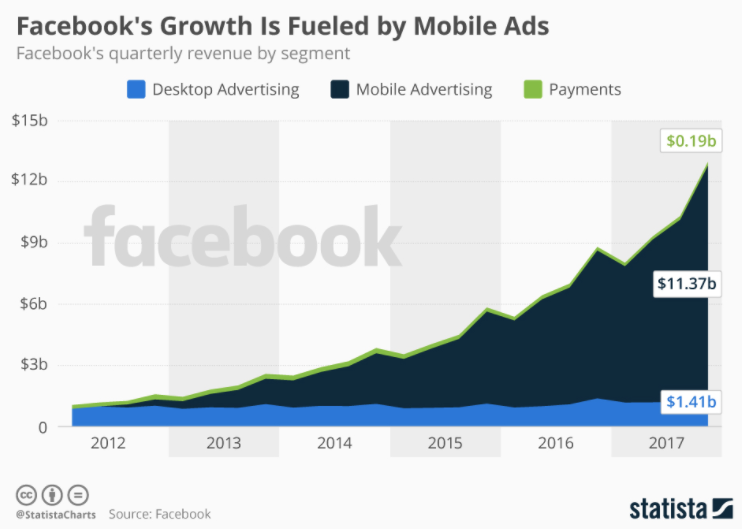
image7 4

That’s because businesses recognize how many Facebook users access the platform from their mobile devices.

In fact, as of January 2018, more than 95% of users access this social media network from smartphones.

But let’s get back to selecting your format. Each format has certain rules and restrictions. I’ve highlighted some of the top specifications for each one you need to keep in mind when designing your ads.

Video

Max length: 240 minutes

Ratio: 9:16 to 16:9

Text: 125 characters

Headline: 25 characters

Description: 30 characters

Sound and captions are both optional for your ads; however, it’s highly recommended that you include these features. Also, if your video thumbnail has more than 20% text, it may not have high delivery rates.

Image

File: png or jpg

Ratio: 9:16 to 16:9

Text: 125 characters

Resolution recommendation: minimum 1,200 x 628 pixels

Just like with videos, if your images contain more than 20% text, it can negatively impact the delivery rate. Make sure to limit the text on your picture ads.

Collection

Minimum image width: 600 pixels

Minimum image height: 600 pixels

Aspect ratio tolerance: 3%

Headline: 25 characters

Text: 90 characters

Carousel

Minimum cards number: 2

Maximum cards number: 10

Maximum video size: 4GB

Resolution recommendation: minimum 1080 x 1080 pixels

Link description: 20 characters

Canvas

Text: 125 characters

Minimum video length: 1 second

Maximum video length: 240 minutes

Bitrate limits: No limit for files under 1GB with 2-pass encoding

If you’ve got a vertical video ad with an aspect ratio taller than 2:3, it needs to be masked to 2:3. It’s recommended that you upload the highest possible video resolution based on the file and ratio limits.

Determine the placement and measure your results

Next, you’ll decide where you want your ads to be placed. Here’s a visual representation to show you what I’m referring to:
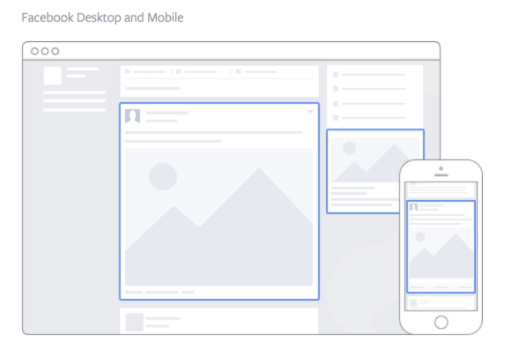
image1 5

You can place your ad on a mobile newsfeed, desktop newsfeed, or right column advertising bar.

Mix this strategy up. This relates back to A/B testing you’d need to run to see which version delivers the best results.

Keep track of everything. See which ads are working and which ones aren’t generating enough leads.

It’s important that you constantly rotate your ads. You don’t want your audience to keep seeing the same ads over and over again.

You should also try to market to different audiences. Just make sure everything always looks professional. Focus on your call to action. Change that as well to see how that changes the results.

Advertise on Instagram

In case you didn’t know, Facebook owns Instagram.

It’s really easy for you to run Instagram ads from the same place where you’re setting up your Facebook campaigns.

Instagram has become such a popular marketing medium that 70% of hashtags on this platform are branded. Furthermore, 71% of businesses in the United States are using Instagram to promote their companies:
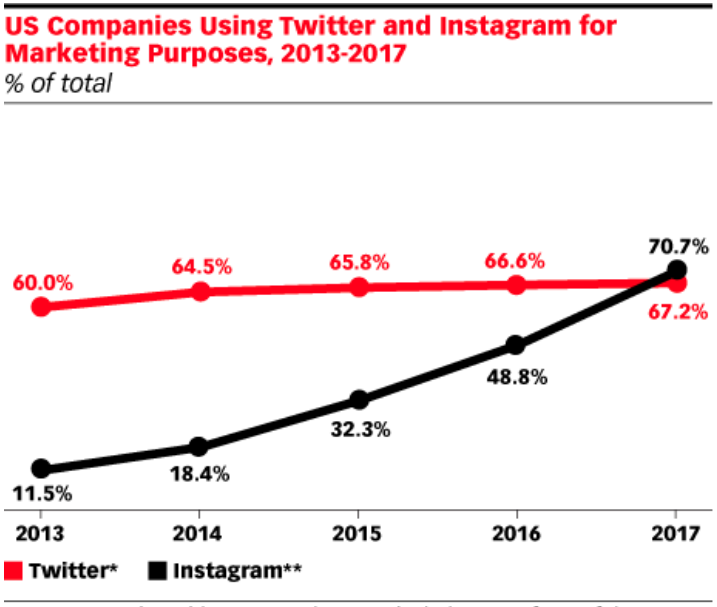
image6 5

They’ve surpassed Twitter in this department.

If you want to stay competitive, you should be running paid ads on Instagram in addition to running them on Facebook. It’s easy to do since you’re setting them up through the same platform. You’ll just need to make a few extra clicks.

Conclusion

Having an active social media presence is an effective way to promote your brand at little to no cost. But if you want to take your social media marketing strategy to the next level, you should consider running Facebook ads.

These ads are perfect because Facebook offers tools specific for lead generation.

They are easy to set up as well. Just follow this guide as a reference to steer you in the right direction.

Start with your goals. Identify your target market. Set a budget.

After that, you’ll have to figure out which type of ad you want to run and where you want to place it. Keep all the ad specifications in mind when you’re going through this process.

Measure your results. Rotate your ads and make adjustments based on how successful they are.

You should also consider running ads on Instagram. Since those ads will be controlled from the same platform as your Facebook ads, it will be just as easy for you to set up.

If you follow these tips, you can turn your Facebook marketing strategy into a lead generation machine.

What types of Facebook ads are you running to generate more leads for your brand?


Source Quick Sprout https://ift.tt/2veIWPE

Auto Bits: MIT survey wants to know how comfortable you are autonomous car technology

Tip of the WeekBestRide.com is working with Car Talk, MIT and the New England Motor Press Association to extend the research done in understanding how comfortable American drivers are with autonomous technology.The MIT AgeLab is again presenting a survey that asks pointed questions about your experience, interest and knowledge of autonomous technologies. To entice you a bit, if you take it before April 27, you’ll be entered into a drawing for one of 10 $50 Amazon Gift Cards. [...]

Source Business - poconorecord.com https://ift.tt/2qyY1qK

Are CDs and Savings Accounts Becoming Viable Investments Again?

Interest rates are on the rise.

The Federal Funds Rate – which sets the market for most interest rates – was up to 1.51% as of March 2018, its highest mark since the stock market crash in 2008.

And while this does mean higher interest rates on mortgages and other loans, it also means that you can finally earn a reasonable return on the money you have in savings accounts and CDs, if you know where to look.

So, are savings accounts and CDs suddenly smart investments? Should you be putting some of your long-term money into these accounts?

The answer depends on what your goals are and what you’re investing for. Let’s figure it out.

The Primary Purpose of Savings Accounts and CDs

Before even considering the idea of using a savings account or certificate of deposit as an investment, let’s take a step back and remind ourselves how these accounts are primarily meant to be used.

The main reason to use a savings account or CD is not to earn a return. The primary purpose of these accounts is to keep your money safe when you either:

  1. know that you’ll need to use it in the near future, or
  2. might suddenly and unexpectedly need to use it.

The first scenario might include saving for a down payment, a new car, or any other goal you hope to reach within the next couple of years. With such a short time period, the safety and certainty offered by a savings account or CD far outweighs the potential extra return you might earn from the stock market.

The second scenario is the primary function of your emergency fund and would also include saving ahead for things like home maintenance, car repairs, and medical bills. You never know exactly when you’ll need to spend that money, but you do need to know that your money will be there when the moment comes.

Both savings accounts and CDs guarantee that your money will be there when you need it. That, more than anything else, is the value they offer.

But Your Return Does Matter

While keeping your money safe is the priority for those types of short-term goals, it’s still helpful to earn a little bit of a return where you can.

Even with the rise in interest rates, many big banks are still paying next to nothing on their savings accounts. As of this writing, Bank of America is paying 0.03% on their Rewards Savings Account and Wells Fargo is paying 0.01%. At that point, your money really is just sitting there doing nothing.

Online banks and local credit unions offer much better interest rates.  is currently paying 1.45% on its savings account and Synchrony Bank is paying 1.55%. You can find more online savings accounts here, and you may also be able to find a local credit union offering even better rates.

While I wouldn’t recommend hopping from bank to bank chasing the best rate, it is worth your time to find a bank you like that offers a competitive interest rate. That way your money will be safe, you’ll have easy access to it, and it will earn you something in the meantime.

Why CDs Might Make Sense as a Long-Term Investment

With that out of the way, let’s get back to the original question: Do savings accounts and CDs ever have a place in your long-term investment portfolio?

The answer is a definite maybe.

First, it’s almost always a good idea to keep some kind of cash reserves, even if you’re completely financially independent. Having that money available is helpful when the need arises and can contribute greatly to your peace of mind.

But even beyond that, a CD in particular could be a useful piece of your investment portfolio.

Most portfolios include some mix of high-risk, high-return investments like stocks and lower-risk, lower-return investments like bonds. The balance you strike is called your asset allocation.

You would never substitute CDs for the stock portion of your portfolio, since they are completely different types of investments. But given where interest rates are today, it may make sense to use CDs for some of the bond portion of your portfolio.

For example, Ally Bank’s five-year, high-yield CD is currently paying 2.50% interest with a $25,000 minimum deposit, or 2.40% with a $5,000 opening deposit.

If you compare that to the 2.86% SEC Yield on Vanguard’s Total Bond Market Index Fund – which is a good estimate of its future return – the CD’s return is a little lower but comes with more certainty. Bonds are a lot less risky than stocks, but they can still lose value. The only real risk with a CD is the potential for paying an early withdrawal penalty.

And while you won’t be able to invest in CDs within your 401(k), Ally and other banks do offer IRA CDs, so it is certainly possible to use them for at least some of your long-term, tax-advantaged investment portfolio.

Bonds do offer some advantages, such as the potential for better returns and easier trading when it comes time to rebalance. And it may be difficult to keep track of multiple IRAs if you’re using one for traditional investments and one for CDs.

But in the right situations, investing some of your portfolio in CDs may be a smart move.

Match Your Investments with Your Goals

There is no such thing as a “good investment” or a “bad investment.” Investments are simply better or worse for the specific goals you are trying to achieve.

If you’re saving for a short-term goal, a savings account or CD is likely the best option, no matter what the interest rate is, simply because they keep your money safe. No other factor is even remotely as important.

But with interest rates on the rise, CDs in particular could be a helpful piece of your long-term investment portfolio. The returns are comparable to what you might expect from a high-quality bond fund, and the extra stability could help you weather even the roughest market downturn.

Matt Becker, CFP® is a fee-only financial planner and the founder of Mom and Dad Money, where he helps new parents take control of their money so they can take care of their families.

Related Reading:

The post Are CDs and Savings Accounts Becoming Viable Investments Again? appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2qCRdIv

Buying a Car From CarMax? Read These Honest Customer Reviews First


When I upgraded my tiny green 2012 Mazda 2 hatchback to a larger Subaru Outback to accommodate my child and her immense amount of stuff, I decided to check out CarMax to sell my car rather than trade it in at the dealer.

I’d dealt with that whole trade-in thing before, and I honestly felt like I’d been screwed over when I saw my former car for sale for a whopping $5,000 more than the dealer had given me for it.

So off I trekked to CarMax, mostly just to see what they would offer me. Kelley Blue Book told me my car was worth anywhere from $6,000 as a trade-in to $8,000 via a private seller.

At CarMax, I was able to get $7,000 for my car, which I received immediately by check. I cashed the check and used it as part of the down-payment for my new, family-friendly car.

My personal experience with CarMax is fairly limited, though it’s good. I didn’t have to wait long, and I got what I thought was a fair price for my car. But the one thing I didn’t do — buy a car — is the main reason most people go to CarMax.

This nationwide retailer prides itself on its no-haggle pricing — a feature that’s very attractive if you’ve ever bought a car from a dealership, where haggling often comes with the territory.

I talked with two customers to get a feel for the buying side of the CarMax experience. Here’s what they had to say.

The Good

Susan Hickey, a physical therapist from Dayton, Ohio, had a great experience at CarMax and says she would definitely buy from them again.

“We found the exact car we were looking for online, and we definitely liked the no-haggle thing,” she says. “We walked in and told them what we wanted. Turns out they had the same model but with fewer miles at their store in northwest Indiana for the same price.” Hickey paid a fee of about $200 to have it delivered to a local CarMax.

It only took a couple of days for Hickey’s car to arrive. Her salesman at CarMax called to let her know it was there, and she went in to test drive it with her husband. It was exactly what they wanted, so they signed the paperwork right there and drove home in their new family vehicle.

“It was so easy,” she says. “There was no stress, no pressure to try to ‘beat the offer. I know that hasn’t been everyone’s experience, but I would definitely do it again.”

The Bad

Just like any car dealership, CarMax has customers who had negative experiences during the car-buying process. One customer, Andréa Van Sickle, a work-from-home mom living in Dayton, told me her story, which was a stressful experience for her family from start to finish.

Van Sickle says she was at the end of her pregnancy and desperate. She and her husband needed a new car for their growing family, and CarMax seemed like the best place to find what they were looking for. However, Van Sickle felt the salesman used their desperation to sell them an overpriced car that ended up having multiple issues.

“There were red flags with the car that we overlooked because of the stress in our lives at that time,” says Van Sickle. “We had issues right away with the car that they ‘fixed,’ or told us wasn’t a concern.”

One of these issues was a revving sound when the car went downhill, which CarMax claimed they didn’t hear and therefore couldn’t fix. Another issue was that the seat belts wouldn’t retract. CarMax claimed to have fixed it but Van Sickle still has issues with the driver seat belt, which gets stuck in the door frequently.

“When we bought it in again later they told us it was our responsibility, even though we had the coverage plan with them,” she says. “Since then, we have had nonstop issues with the sensors in the car as well as recurring issues with the catalytic converter. In hindsight, I should have taken it back for a refund within the first 30 days when the minor symptoms first presented themselves.”

“I love the car, when it works,” says Van Sickle. “But we definitely feel like we were taken for a ride. What we owe now on the car is way more than what it would ever sell for.”

Even though Van Sickle’s experience was a negative one, she won’t rule out shopping at CarMax again.

“I would just be more vigilant about making sure the car is in good shape by getting a third party to evaluate its condition within the first 30 days and knowing the value of the car I’m looking to purchase before agreeing on a price,” she says.

It Comes Down to Your Local CarMax

CarMax has 191 stores located across the U.S., according to its website. As with any dealership, your experience will likely depend on the sales representatives at your local store.

Before you commit to buy, read some reviews online of your nearest CarMax to see if they are overwhelmingly positive or negative.

Even if your local store comes recommended by most reviewers, you should follow your gut when it comes to whether you want to buy there or not. Shop various used cars at local dealerships as well to see if CarMax truly has the best deal.

When you test drive a car, use your own judgment to determine whether you trust the salesperson or not. You are completely within your rights to ask for a different salesperson if the one you meet gives you a bad feeling.

At the end of the day, when it comes to buying a used car, CarMax might be the best choice for many drivers. With so many stores, you’re likely to find what you want even if it’s located elsewhere, and you can easily get the car shipped to your local store, though you might have to pay an additional fee.

But as with any transaction, you could have a negative experience. If this is the case, ask to speak with the manager at your store and relay your concerns to see what can be done.

Buying a used car doesn’t have to be a stressful experience, whether you choose to buy at CarMax or elsewhere. Before deciding on a dealership, shop around to find the best deal, and don’t be afraid to walk away if necessary.

Catherine Hiles is a writer and editor living in Dayton, Ohio. Although she has never bought at CarMax, it remains a possibility should she ever need to replace her beloved Subaru.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder https://ift.tt/2HDKzZX

How I Earned $6K Last Year with My Side Gig as a Yoga Instructor


I recently returned home from a week’s vacation in Punta Cana, Dominican Republic. A warm-weather getaway in the middle of a frigid Philadelphia winter? Heavenly.

Traveling is rarely cheap, but on this vacation, I didn’t have to dip into my savings account to cover the trip.

Instead, I paid for my tropical vacation solely using funds I earned in 2017 from my side hustle: Teaching yoga.

On the side of my full-time job running a communications agency, I earned a little more than $6,000 as a yoga instructor last year.

Let’s break down the numbers: Over the course of the year, I taught 158 yoga classes, translating to about three classes per week — definitely doable for those with day jobs. That means I earned an average of $38 per class, bringing my total earnings for the year to just over $6,000, pre-taxes.

If you consider yourself a passionate yogi, becoming an instructor might be a great way to grow your love for the practice — and earn extra cash.

Why Teach Yoga?

Teaching yoga can be a rewarding side hustle for those who love to practice yoga.

That’s exactly how I decided to become a yoga instructor. Three years ago, I noticed I was already spending most of my evenings and weekends at the yoga studio. While I never dreamed of becoming a teacher, my infatuation with the practice led me to yoga teacher training. I officially became a Certified Yoga Teacher (CYT) in June 2015.

It turns out I’m not alone.

“I often witness that serious students of yoga get an insatiable desire to share their passion with others,” says Dr. Lisa Mitchell, author and owner of Dana Hot Yoga, where I completed my yoga teacher training and currently teach. “For an average cost of teacher training ($2,000 to $4,000), it is a certificate that can almost immediately start a return on investment, making it a viable option for supplemental income in an economic time where a second job, aka ‘moonlighting,’ is a necessity for most people.”

The Cost of Becoming a Yoga Teacher

Here’s the honest truth: Yoga teacher training can be pricy.

It’s an investment, and it’s one that does take time to earn back. However, if you’re serious about yoga and want to develop a lasting side hustle teaching, it’s absolutely worth it.

So how much does it actually cost to become a yoga teacher? There are a few variables to consider. For example, are you completing your training at your local studio, or are you traveling to an exotic location for a more immersive — but also more expensive — experience?

Will you be paying in full upfront, or will you take advantage of a payment plan? In addition, some studios offer a work-exchange program, in which you work at the studio during your training in exchange for an additional discount.

For our purposes, let’s consider the teacher-training program I completed. The training costs $2,450, with a $200 discount for those who pay in full, as opposed to opting for the payment plan.

I paid in full, so we’ll bring that figure down to $2,250.

It took me eight months of teaching 64 classes to recoup the cost of my teacher training — not bad, all things considered.

How Yoga Teachers Get Paid

Payment can be somewhat complicated in the yoga world — it’s not as cut and dry as some other fields of work. Depending on the space in which you teach and your geographic region, rates can vary wildly.
Here are some of the most common ways yoga teachers get paid:

Flat rate: This one is quite simple — teachers earn a flat rate per class, whether one student shows up or the room is filled with eager yogis. This can be paid by the studio directly or negotiated with a special event or group organizer. In the Philadelphia region, I’ve seen flat rates range from $25 per class on the low end to $50 per class on the high end.

Flat rate per range of number of students: Many studios reward teachers financially when their classes begin to grow in numbers. For example, you may earn $25 for a class of 1 to 16 people, then get bumped to the $35 level when your class hits 17 to 25 and max out at the $45 rate when your class is packed with 26 or more students. This payment method encourages teachers to nurture and grow their own classes.

Per-student rate: I haven’t come across this payment method in my personal experience, but some studios pay teachers a low base rate (say $10 or $15), then an additional $3 for every student who shows up above a certain number. Again, this incentive-based payment urges teachers to develop a community in their classes.

After teaching at more than seven studios, it appears that at least in the Philadelphia region, $35 per 60 to 75-minute class seems about average.

Here’s another perk to consider: When you teach regularly at a studio, you often can practice there for free, waiving your membership fees. (Prior to becoming a teacher, I spent $1,000+ on my annual studio membership.)

Consider Other Expenses

As with most side hustles, there are additional business expenses to consider. These are some of the most common expenses yoga teachers will incur:

Insurance

For yoga teachers, insurance is a must — most studios and gyms require it, plus, you wouldn’t want to put yourself at risk by teaching without it.

Insurance policy cost varies, but expect to pay between $150 and $400 depending on variables including how often you teach and whether you teach in a studio setting or privately.

Cost: $161

Registration

Some yoga teachers choose to register with the YogaAlliance, which serves as the governing body of the yoga community. Becoming a Registered Yoga Teacher (RYT) allows teachers access to discounts, online workshops and a listing on the site’s roster of teachers. Registration is optional (and hotly debated in the yoga world).

I registered in 2017, but I won’t be renewing this year. At the time I registered, membership cost $105, but has since increased to $115.

Cost: $105

Continuing education

Practice what you preach! Like in other professions, teaching yoga is a skill, and it’s one you need to continue to hone in order to grow and succeed.

Embarrassingly, I only completed one continuing-education workshop in 2017, so normally this figure would probably range between $100 to $400, depending on the length and intensity of the workshop, class or additional training.

Cost: $20

My 2017 total cost: $286.

Earn More When You Think ‘Outside the Mat’

Here’s a little secret: Teaching in a traditional studio setting or gym is not an instructor’s only option.

In fact, there are far more lucrative and interesting ways to teach yoga than confining yourself to a studio.

I learned this lesson myself when I was approached to teach yoga to a rowing team at a local university. When you teach in a private setting, you often get to set your own rate, giving you the opportunity to earn more.

Fun fact: Teaching an hour-long class to my group of athletes earns me almost three and a half times as much as one class at a studio.

Here are some other creative teaching options to consider:


  • Approach a local winery or brewery for a yoga class and tasting. These types of classes are popping up everywhere, and many times, yoga teachers play a part in setting their rate.
  • Similarly, consider other types of businesses — museums, grocery stores with community spaces like Whole Foods, libraries, outdoor locales, gardens and more.
  • Teach a private lesson. When you teach privately, you have the freedom to choose how much you charge. Keep in mind, if you land a private student through a studio, you will likely have to split your earnings.
  • Advertise your teaching expertise to wedding parties. Many brides choose to start their big day in a healthy way with a pre-ceremony yoga class for their bridesmaids.
  • Go corporate. More and more businesses are recognizing the importance of mindfulness and are offering free yoga to their employees. Teaching in a corporate setting can often be extremely lucrative because these businesses often have more budget to spend on wellness.


When I first stepped onto my yoga mat in 2014, I had no idea the practice would change my life and career path in such a drastic way.

My powerful yoga-teacher-training experience was actually one of the driving forces that led me to quit my full-time PR job to start my own business.

The extra income, ability to pay for vacations and more money to save for my future have certainly been a bonus.

Namaste!

Jessica Lawlor is the president and CEO of Jessica Lawlor & Company (JL&Co), a specialty communications agency. When she’s not in boss-lady mode, she dons yoga pants and teaches yoga in the Philadelphia region. 

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder https://ift.tt/2IX0h1w

Lifetime Insurance cover for your pet

  • Agria provides lifelong vet’s fees cover for illnesses and injuries
  • A massive £12,500 vet fees benefit which renews each year
  • We settle claims quickly and can pay direct to you or your vet
  • 50% off for the first 2 months

Image

CTA

Legal

Section


Source Moneywise https://ift.tt/2EOdY0v

الأحد، 15 أبريل 2018

Eight Amazing Things That Happen When You Finally Pay Down Debt

Living with debt may be seen as “normal” these days, but the damage debt does to our lives is far from okay. After all, carrying too much debt can cause more than budgeting problems; it can stress and personal problems, too.

Experts at Psychology Today say that that your mental health and financial health are irrefutably intertwined. People in debt are more likely to drink and abuse drugs, and there is a distinct correlation between high debt levels and increased risk of suicide, they note. A study from Clinical Psychology Review even showed that indebted consumers are three times more likely to suffer from a mental health condition.

And what about how debt affects your dreams? Carrying too much debt can put your goals out of reach – or even out of mind, since you know you can’t afford them. When you’re deep in debt, you may never take the vacation you’ve dreamed of, purchase the home you’ve always wanted, or have the cash to pursue the hobby you love. You may have to turn down exciting but low-paying opportunities while you toil in service of your debts, or wind up working forever — even until the day you die. That means that debt could be the reason you never actually retire — or at least never have a retirement you can afford to enjoy.

Eight Ways Life Changes After You Pay Off Your Debt

Everything you’ve just read may be depressing, but it’s true. While it’s easy to buy now and pay later, few people are aware of the effect debt makes on their lives until it’s too late. Of course, debt isn’t a death sentence — or, at least it doesn’t have to be. No matter how helpless your situation feels or how much debt you have, it’s possible to turn things around and make dropping debt a priority.

While the road out of debt won’t be easy, there are benefits waiting for you at the very end. And, those benefits extend far beyond the relief you’ll feel when you make the final payment on your credit cards, student loans, and personal loans; some of the benefits of becoming debt-free are so huge they can change your life forever.

If you’re working your way out of debt and wondering what’s in store in the future – and whether it’s worth the sacrifice – here are some things you can to look forward to.

#1: You have a lot more money to spend, save, or invest.

Paying down debt requires a huge commitment of money and time. Whether you choose to utilize the debt snowball or debt avalanche methods or just pay whatever you can each month, most of your expendable income needs to go toward debt repayment if you want your actions to count.

But, something crazy happens the second you make the final payment toward your debts. All of a sudden, all the income you’ve been throwing toward your debts each month becomes yours. With no more debts to pay off, you get to experience what your paycheck actually feels like without the burden of debt payments every month.

As a result, you’ll have a lot more money to save, spend, or invest going forward. At first, you may even feel rich!

#2: Getting a good night’s sleep becomes easy.

The burden of debt may take more of a mental toll than you think when you add up all the worry, stress, and sleepless nights your debt has caused. Especially at the beginning of your journey, it’s likely you struggled financially and emotionally before building up the courage to change your spending habits and your life.

When you pay down your debt, all of that changes. All of a sudden, you no longer have to worry about insurmountable balances, looming due dates, and relentless interest charges. Without any debts to worry about, your monthly expenses will drop, freeing up your personal cash flow and allowing you to focus on savings and daily living expenses.

Few people understand just how free you can feel when you’re no longer beholden to a slew of banks and lenders. But, when you get there, you will instantly feel the power the comes with that freedom.

#3: Your credit score may improve.

The amount you owe on your debts in relation to your credit limits, also known as your credit utilization, accounts for 30% of your FICO credit score. Because of this, your credit score has the potential to improve with each monthly payment you make.

And, since your payment history is the biggest determinant of your credit score, your regular monthly payments will also help boost your score over time.

#4: You can dream up new financial goals.

Getting out of debt can take years, depending on how deep of a hole you’re in, and the process itself takes self-discipline and courage. During your journey, you likely kept your head down and focused on your goal. After all, too much distraction can cause you to get off track or fall back into bad habits.

When you’re finally debt-free, however, your journey comes to an end. And while it can almost be disorienting to stop working toward this goal you’ve held for years, after all your hard work, you can finally come up with new dreams that are a lot more fun than paying off old debts.

Maybe you want to retire early, or perhaps you want to help your kids save for college. Maybe you’re finally ready take that family vacation you’ve been dreaming of for what seems like forever. Heck, maybe you just want to sit back and enjoy the peace that comes with being debt-free for a while.

Whatever you really want out of life, becoming debt-free will help you get there faster. Without a ton of bills to pay each month, you can finally save for what you want and pay for it in cash.

#5: You can work less if you want.

A lot of people make huge changes to finally pay off debt, and often those changes include picking up a second job or side hustle. Maybe you’ve been driving for Uber on the weekends to earn more money for debt repayment. Or, you might have picked up some seasonal work, babysitting, or lawn mowing jobs.

No matter your hustle, paying off debt means that you may not have to work quite so hard anymore. If you’re been putting in more hours than you really want to just to pay down debt, reaching your goal may mean it’s time to work less and enjoy life more. Chances are, having the freedom to work less is one of the reasons you decided to get out of debt in the first place.

#6: You have more options.

In addition to not having the option to work less if you want, paying down debt makes it possible to change your life in myriad ways. Maybe you wished you would change careers but couldn’t afford to take a pay cut in the past, or perhaps you want to go back to school to finally finish your degree.

Maybe you want to cut down to part-time work to spend more time with your kids. Whatever it is you want, becoming debt-free means you now have less financial obligations, and more options than ever. Without all your old bills hanging over your head, you can build the life you want instead of the life you had.

#7: Debt becomes something you strive to avoid.

When you’re already in debt, it’s easy to think that adding to the pile won’t even matter. What difference will another credit card or a new car loan make when you’re already struggling as it is?

When you finally become entirely debt-free, you realize that it does matter how much you owe every month. Each bill may not seem like a lot on its own, but the sum of all your debts can make your life harder in too many ways to count.

Once you’ve spent years paying down debt, chances are good you will never want to go down that road again. As a result, you will likely do anything you can to avoid debt like the plague it is. And, if that means spending less and living more frugally, so be it.

#8: You get to finance your own dreams interest-free.

The final benefit of becoming debt-free is one that may not sound exciting until you actually get there – eventually, you will get to finance some of your dreams in cash.

That living room furniture set you’ve always wanted? Imagine walking into your local furniture store and writing a check to pay for whatever you wanted. Need a new car? Imagine having the savings to negotiate a cash price then driving off the lot with your new ride and no car payment to look forward to.

And, how about retirement? Imagine having enough extra money that you can boost your retirement savings without it hurting your bottom line, then retire earlier than you ever dreamed.

The Bottom Line

These are just some of the things you can do if you pay down debt, but there are endless other scenarios to consider. When you’re finally debt-free, you get to design the life you want instead of enduring a life that was built to keep up with endless bills.

If you’re ready to become debt-free or in the throes of a debt repayment plan, it’s crucial to keep your eye on the prize and remember what your life will be like when you reach your goal. There’s so much more to life than debt and “stuff,” and it’s hard to enjoy the spoils of your hard work when all your money is going to somebody else.

You get to decide how you want to live your life. Become debt-free, and you get to call all the shots.  Spend your life in debt, and your labor will always belong to someone else.

Holly Johnson is an award-winning personal finance writer and the author of Zero Down Your Debt. Johnson shares her obsession with frugality, budgeting, and travel at ClubThrifty.com.

Related Stories:

The post Eight Amazing Things That Happen When You Finally Pay Down Debt appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2qwFBFW

Want to See Real Florida? These Day Trips Are a Fun Break From Disney World

السبت، 14 أبريل 2018

Motorists prepare to pay more at the pump

The price of gasoline in the region is rising.It jumped to an average of $2.91 a gallon, topping the 2017 high by 2 cents.And the price could climb as high as $3 a gallon as the transition to summer-blend gasoline continues and the summer driving season begins, AAA officials said.Gas prices in the Scranton/Wilkes-Barre area have not been above $3 a gallon since Nov. 15, 2015.Since Jan. 1, the cost of a gallon of regular unleaded gas in the area has risen 18 cents, [...]

Source Business - poconorecord.com https://ift.tt/2qyQWW5

Shearer shortage looms over sheep farmers

DERRY, Pa. (AP) — Chuck Penich plopped a sheep onto its butt between his legs and started buzzing away with a set of electric clippers, slowly working his way from her belly to her legs and back.Less than 10 minutes later, he had a sheet of wool and an exhausted sheep piled at his feet.In a good season, he'll repeat this exercise about 1,500 times at farms across southwestern Pennsylvania. But between his aging back and changing farms, the good seasons are getting worse. [...]

Source Business - poconorecord.com https://ift.tt/2H1nW08

You Owe Taxes, But Can't Pay The Bill: How to Minimize the Damage from Uncle Sam

Owe more in taxes than you can afford to pay? Learn what your options are.

Source CBNNews.com https://ift.tt/2GYW6Wv

Financial Success Versus Working Too Hard

Erica writes in:

Loved your recent article about living life true to oneself, made me really think. I wonder if you could address another of those “regrets of the dying,” wishing I hadn’t worked so hard. I feel like I am losing my whole life to constant work. I have a family I don’t see enough and no hobbies to speak of. Feel like I am constantly working, and for what? I have an okay retirement savings but I won’t have friends or hobbies when I do retire. My life is my job and I am starting to regret it.

This is a great question, one that, as many good reader mailbag questions do, goes far beyond what could be answered in a short mailbag answer and requires a full article.

So, in my article about avoiding life regrets, I focused almost entirely on the top regret, which was living a life true to oneself. I didn’t move on to address the other four regrets.

The second regret, which is the one that Erica is interested in, is also very straightforward:

I wish I hadn’t worked so hard.

Bronnie Ware, the palliative care nurse who wrote about the regrets of the dying, described it in a bit more detail: “This came from every male patient that I nursed. They missed their children’s youth and their partner’s companionship. Women also spoke of this regret, but as most were from an older generation, many of the female patients had not been breadwinners. All of the men I nursed deeply regretted spending so much of their lives on the treadmill of a work existence.”

That’s a feeling that I think a lot of us can identify with.

Right now, I feel like I am in a pretty healthy place with regard to keeping my professional life in balance with other aspects of my life, but that was not an easy balance to achieve. I spent most of my first decade of professional life feeling like I was spending far too much of my life on professional goals and tasks and too little of it in other areas, particularly my family. I know almost exactly how Erica feels, in other words, because I was there, too.

The biggest challenge in changing things is that there’s a strong sense that if you rock the boat too much in terms of your career, or if you say “no” too much, you’re going to find yourself without a job or even without a career at all. You’ve spent many years training and likely at least some years establishing yourself in your career and in your current job. It pays reasonably well. You don’t want to lose what you’ve built. So, when you’re asked to put more and more on your plate, you just say “yes” because there’s an underlying feeling that saying “no” means you will lose what you have, which will cause a major professional crisis that will spill over into personal and financial consequences as well.

The first and most important thing to recognize in all of this is this simple fact: if you feel like your life is out of balance, you’re probably not performing well to begin with. As a wise friend of mine once said, “If you’re juggling six chainsaws, you’re probably not cutting down any trees.”

There comes a point in one’s professional life when there is so much on your plate that things simply start falling through the cracks. You can’t give quality work to everything, and you’re likely just failing to complete some things that just fall through the cracks. There is a limit to how much you can actually do, and when you reach that limit or go beyond it, it goes from cutting down trees to juggling chainsaws. Rather than doing things well, you’re just trying not to drop any balls, and that isn’t helpful for you or for whoever you’re working for.

I found myself in this exact position a few times in my career. I was juggling more than I could sustain in my professional life and it left me feeling torn away from my family, my friends, my health, and my other interests. The thing was, once I was able to step back from that, I realized that I wasn’t doing any of my tasks very well. I had transitioned to doing a bunch of things in a mediocre fashion, both because I had too many tasks on my plate and because I wasn’t left with much time or energy for anything else. I was heading down a path of pure regret, in other words.

So, how can you fix that without damaging your career or your income? Here’s what I was able to figure out while moving through those situations.

Build a life that doesn’t require your current salary – a “light at the end of the tunnel.” This is the absolute number one most important thing that you should be doing.

One important aspect of personal finance that I love to hammer on is the idea of “golden handcuffs”. “Golden handcuffs” simply means that your life is set up in such a way that you are reliant on the benefits and salary of your current job and your life would undergo some serious stress if you were to lose that job for even a very short period of time.

Being in “golden handcuffs” means that you do have some nice lifestyle perks that come from having a good income, but you are stuck at that job, period. You can’t take any career risks. If you’re considering jumping to a new job, you have to be very careful not to put your current job at risk. You can’t have frank conversations with your boss or ask for any real changes at work. You can’t rock the boat at all. You just have to swallow what you’re handed.

It’s miserable. But at least you have a lot of money to spend, right?

The thing is, money isn’t everything. Study after study has shown that having money and income beyond the basic level needed to meet your needs and to indulge in a few minor wants doesn’t bring you any additional happiness whatsoever. In fact, if you’re making choices that make you unhappy in order to simply have more disposable income that you then immediately spend on things that don’t actually contribute to your lasting happiness… you’re not really gaining anything, are you?

The most powerful solution I’ve found for this dilemma is to dial back your spending and start using that money to make yourself ready for a possible professional transition. (There are many, many ways to do this – stick around The Simple Dollar for a few weeks and you’ll find a ton of tips and tactics for how to do this in various areas of your life. Here’s a starter kit.) This isn’t to say that you’re going to make such a professional transition, but simply that one becomes easily possible. The first effect will be that if you get fired, it’s not apocalypse. Sticking with it, you’ll begin to see that other job options with lower salary but lower intensity and other perks are not only possible, but completely feasible options.

This transition mostly revolves around spending less than before, which has two key benefits. First, it means that you need less salary to continue to function. You can live your “ordinary life” with less income than before. Second, it also means that you have some financial reserves that can help you through a bumpy transition.

Together, these things create a very interesting effect at work. As you break those “golden handcuffs,” you no longer feel nearly as “forced” into unpleasant job choices as you once were. Your boss has a lot less leverage over you and you don’t feel as though you have to accept the short end of the stick professionally all of the time. You have options. It’s not the end of the world if this job goes away or this career path closes up or changes.

So, what’s the first step here? I generally encourage people to follow something close to Dave Ramsey’s debt snowball, which he prescribes in his book The Total Money Makeover.

First, build a $2,000 emergency fund. Dave’s original advice was to aim for $1,000, but that’s a number from several years ago. Aim a little higher – shoot for $2,000. I suggest doing this by setting up an automatic weekly transfer from your checking account to your savings account for a small amount – say, $50 – and leaving that on permanently, then contributing more than that manually until your savings is at $2,000. Don’t turn off the automatic contribution – that way, when you do need that cash in a pinch, the account isn’t depleted and will continue to refill itself automatically.

Next, start tackling your high interest debts. This includes basically every debt you have with an interest rate over 5% or so. Order them by interest rate or balance size, whichever you prefer (there are reasons for both – I lean toward interest rate, but there are nice psychological benefits for doing it the other way). Then, make minimum payments each month on every debt on the list, but make a big extra payment on the debt on top of that list. When that top debt is paid off, erase it and keep moving down the list. As you eliminate debts, the total of your monthly required bills is going to get smaller and smaller, which is going to make debt payoff faster and faster and give you more and more breathing room. You’re breaking the golden handcuffs!

Just keep moving from there. At this point, as those debts are starting to disappear, you’re going to start feeling like there is light at the end of the tunnel, and that’s an amazing feeling. It sets the stage for being a little more assertive at work in terms of having a balance between work and other aspects of life that you’re happier with.

Now, we’re going to move onto some tactics that might seem impossible if you’re tied up with the golden handcuffs, but become a lot more plausible when you have some light at the end of the tunnel.

Block off time for relaxation, period. Simply create a few blocks of time each week that are dedicated solely to relaxation and leisure. Put them in your planner. Make them absolutely sacrosanct. During those times, turn off your electronic devices and do something that makes you feel whole.

I actually do this pretty often. I meditate each day for about 15 minutes – it’s sacrosanct. I read for about an hour each day – it’s uninterrupted, with the phone off. I have two social evenings each week – again, uninterrupted. I usually spend about an hour with my kids uninterrupted each day. I also usually box off one weekend afternoon a week for a family event of some kind.

During those times, my phone is off. I don’t get interrupted no matter what it is. My focus is on the thing I’m doing right now, and the rest of the world really doesn’t matter.

If you think you don’t have the time for this, make time. Maybe that means you don’t do household routines quite as often as you once did. Maybe that means you have to back off on a few minor unimportant tasks at work. Maybe it just means you have a few less time wasters in your life. Whatever you need to do, make room for uninterrupted leisure and social time in your life. Pencil them into your calendar, turn off your digital devices when that time comes around, and don’t think about anything else when they’re happening.

It is very important that you block this time off and dedicate it to the things you care about. If you don’t, it’ll be lost in the form of minor tasks and idle time. Block off a few hours for a hobby on the weekend or a dinner party on Thursday and you’ll find that the things that are actually important still get done. The only thing you lose is idle time staring at the television or your phone or time spent doing minor and unimportant tasks.

Evaluate your job and figure out what’s working and what isn’t. If you feel as though your job is pulling too much out of you, you absolutely owe it to yourself to figure out what aspects of your job are really worthwhile and which ones are not. What you’re truly looking for is what parts of your job are ones where your particular skills are producing a lot of value for the company and which ones are not.

Most people tend to enjoy the aspects of their job where they feel they’re applying genuine skill and producing good results. It’s the other aspects – the ones where you’re not applying skill and you’re not producing any results – that leave a person feeling as though they’re just dumping hours of their life away into nothing while the other aspects of their life die on the vine.

I like to point at the 80/20 principle here. The 80/20 principle, as I described in an earlier post, simply says that 80% of the value you produce comes from 20% of your time and effort. In other words, most of what you do at work that really produces value comes from a small portion of the time and energy you devote there.

What you need to seek are ways to cut back on the tasks that fill the 80% of your time but only produce 20% of your results.

Now, every job is different. It’s hard for me to have any idea as to what aspects of your job are the 20% that are really productive and the 80% that aren’t. However, I can say that the value you have for your organization mostly comes from that 20%.

You need to amplify that 20%, not drown it with the 80% that’s clogging up your professional life (and other aspects of your life, too).

So, sit down with that question in mind and really look at your job. What things do you do that really produce value for your organization? Set those things aside – they’re probably the things about your job that you enjoy the most, anyway.

What you need to address is everything else – the low value stuff. Start figuring out how to deal with it.

Actively eliminate as many of those negative factors as possible. All of those other aspects – the 80% of your work that produces only 20% of the value – needs to be chopped down or tossed out as efficiently as possible.

Again, there are lots of ways of doing this. You can perhaps automate some of them. Maybe you can come up with a much more efficient workflow to get those drudgery tasks out of the way faster (or ask for help in coming up with that workflow). Maybe there are tasks that make more sense if they’re given to someone else with more appropriate skills. Maybe there are meetings you go to where your input really isn’t needed and those meetings can be cut.

Whatever the case may be, start chopping down that 80%. Your goal with that chopping is to get to a place where you can easily find room in your life to block off plenty of time for leisure, for social events, for other aspects of your life. If you’re deleting or downsizing useless tasks, you’re freeing up time at work that you can use to take care of things you might have previously taken home with you. If you’re getting that stuff done at work, then you’re freeing up time outside of work, time you can devote to things you care about.

Yes, there are probably some aspects of this that you’ll have to talk over with your supervisor. Just simply state that these X tasks are ones where you don’t think you’re providing much value to the company and they’re interfering with these other Y tasks where you are providing a lot of value to the company and look for solutions together. Your boss might push back on whether some tasks are really ones where you don’t produce much value, but it’s likely that some of them are tasks you’ll agree on, and then you’ll have an ally in making them go away in some fashion.

I went through all of these processes during a stretch in time where I felt completely overwhelmed with work and life. I went through a period where I felt completely lost in my career and felt as though everything was badly out of balance and wouldn’t ever change.

For me, the shift away from that started with a genuine commitment to turning around my finances so that I felt like there was some hope for the future and some leverage in my workplace. As I began to find financial leverage in life, I began to make some major career changes, only to find that after a few years, I was right back in that same tight “all work in no play makes Trent a dull boy” corner. At that point, I really just assessed what things I was doing that really produced value and which didn’t, and then made it my goal to cut out as much as I could that didn’t produce value.

Today, I feel like I’m in a very healthy place. My work is mostly joyful. I do not feel that I will regret overworking when I reach the end of my life. The foundation of that is strong finances, with some realization that my income is earned by the things I do well and not by my busywork.

Good luck!

The post Financial Success Versus Working Too Hard appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2GY4k17

The Differences Between Stocks vs. Bonds

New Kid in Town? These 7 Tips Can Jumpstart Your Job Search

الجمعة، 13 أبريل 2018

Love Hanging Out on Your Couch and Writing Code? This Job’s for You


Can you speak the language of the internet? Y’know — Java, Ruby, SQL.

No doubt the demand for computer programmers will continue to grow, so that means more and more people need to learn how to speak the digital language. Are you already fluent? Then you’ve come to the right place.

Codecademy, an online education platform specializing in teaching computer programming skills, is looking  to fill remote, part-time coaching positions — an Advisor and a Project Reviewer.

As an Advisor, your role will be to teach various coding skills to those enrolled in the online program.

As a Project Reviewer, your main responsibility will be to assess projects submitted by students and promptly provide clear feedback.

Both jobs require anywhere between 10 to 30 hours a week, including weekends. You must be over the age of 18 and live in one of these states:  California, Florida, Georgia, Illinois, Maryland, Massachusetts, Michigan, New Jersey, New York, Ohio, Oregon, Pennsylvania, Tennessee, Texas, Virginia, Washington.  

If coding isn’t one of your primary skills, or you don’t live in one of the states eligible for employment, check out our Jobs page on Facebook. We post new opportunities there all the time.

1. Advisor at Codecademy

Responsibilities include:

  • Defining student goals
  • Reviewing coding topics 1:1
  • Helping students find additional learning resources
  • Helping students debug code and pass challenging exercises
  • Motivating and encouraging students
  • Assisting other advisors with supporting and tracking student progress

Applicants for this position must:

  • Have a passion for programming, technology and teaching
  • Be comfortable in a fast-paced and ever-changing work environment
  • Have strong written and verbal communication skills to explain concepts
  • Have a CS background or demonstrated proficiency with most of the core skills we teach
  • Familiarity with the Codecademy platform is strongly recommended

Apply here for the Advisor position at Codecademy.

2. Project Reviewer at Codecademy

Responsibilities include one or more of the following:

  • Acting as an advisor by providing on-demand instruction to learners via 1:1 chat sessions
  • Monitoring Slack channels to coordinate peer-to-peer conversation and answer technical questions
  • Serving as a mentor by providing personalized support to learners in the Pro Intensive program with live 1:1 video sessions, pair programming and recorded video seminars
  • Assisting team throughout screening process to identify new talent via resume screening, evaluating written tests and leading final state (simulated chat) test

Applicants for this position must:

  • Have a  passion about programming, technology and teaching
  • Be comfortable in a fast-paced and ever-changing work environment
  • Have strong written and verbal communication skills to explain concepts
  • Have CS background or demonstrated proficiency with most of the core skills we teach
  • Familiarity with the Codecademy platform is strongly recommended

Apply here for the Project Reviewer position at Codecademy.

Matt Reinstetle is a staff writer at The Penny Hoarder.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder https://ift.tt/2GXU7C1

Free-Spirit Wordsmiths: Here’s a Remote Copywriting and Editing Job for You


Are you in the market for a full-time job, but thinking you would rather avoid the daily commute and cubicle life?

Then you’re in luck, because WebPageFX, an internet marketing and SEO company, is looking for a full-time, remote copywriter and editor to join its award-winning team.

This is a work-from-home, independent contractor position that requires a 40-hour work week, but you can do it from wherever you like, as long as you’ve got a good internet connection.

You might be a total homebody with a deep connection to your couch, or maybe you’d rather spend your days working from your favorite local coffee shop. Whatever the case, this job gives you the freedom to choose.

Oh, and did we mention it pays up to $18 an hour?

On top of the hourly pay, contractors are also eligible to earn performance-based bonuses of up to $1,000 per year.

And if that’s not enough to snag your interest, the company also doles out monthly stipends that the contractors can use as they see fit to better improve work-from-home life. Some examples are personal healthcare, internet costs and home office equipment.

WebPageFX encourages applicants from all backgrounds to apply, as long as you’ve got some relatable experience, stellar communication skills and the ability to get your work done independently.

If copywriting isn’t your thing or you’re not interested in a full-time gig, no worries. You can find more work-from-home opportunities on our Jobs page on Facebook.

Remote Copywriter/Editor at WebPageFX

Pay: $15-$18 per hour

Responsibilities include:

  • Writing and editing multiple types of content, from blog posts to sales copy
  • Working with a variety of publishers on the web and in the media, ranging from entertainment and lifestyle to industry-specific assignments

Applicants for this position must have:

  • Excellent communication skills
  • A flexible schedule with the ability to work 40 hours per week
  • A reliable laptop with high-speed internet access

Benefits include:

  • Paid holidays
  • A monthly stipend that can be put towards remote work expenses
  • Opportunity for performance-based bonuses

Apply here for the remote copywriter/ editor job at WebPageFX.

Kaitlyn Blount is a junior staff writer at The Penny Hoarder.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder https://ift.tt/2v7UVOW

$215 CrossFit Subscription Box Is Great if You Want to PR Your Meat Lifts


The first two words in CrossFit’s Manifesto are: “Eat meat.”

Which is weird because I really thought they were: “Do burpees.”

Now, CrossFit is further embracing the meat sweats by entering the world of subscription boxes.

The CrossFit Box — pun surely intended — is a $215 box of raw meat from Strauss Brands’ Free Raised Direct that you can get delivered to your door every month.

If you’d rather not sit on the couch and wait for your meat to arrive, Strauss will be stocking CrossFit-approved meat in select grocery stores across the U.S. later this year.

The United Steaks of CrossFit: What You Get for $215

CrossFitters are known to clean meat shelves and wrap perfectly good vegetables in bacon — all in the name of being “paleo.”

Paleo purists claim that not only should you deadlift your weight in meat but it should also be grass-fed because if we can’t have grains, neither should the cows!

Here’s what the CrossFit Subscription Box includes:

  • Five packages of 6-ounce cage-free chicken breasts (10 pieces total)
  • 3 pounds of grass-fed ground beef
  • Four 5-ounce grass-fed tenderloin filets
  • Four 10-ounce grass-fed ribeye steaks
  • Four 10-ounce grass-fed strip steaks
  • Two 6-ounce grass-fed sirloin steaks
  • One package of grass-fed beef sticks

By the end of this box, you’ll gain over 14 pounds of animal carcass and about 1,500 grams of meaty protein. And you’ll pay just over 14 cents a gram for it.

PR Your Protein Snatch

While a physically active lifestyle definitely requires more protein, do you really need 50 grams every day? And can you pull up a cheaper price for it?

Sorry vegans: The Harvard Health Blog says you do need 50 grams of protein a day.

More specifically, a 50-year-old sedentary woman needs 53 grams per day. Athletes need even more.

And it turns out that if you are serious about eating lots of grass-fed organic meat, the CrossFit Box might be a good deal.

I found the Whole Foods equivalents of all these meats — subbing out jerky for beef sticks — and at the time of this writing, re-creating the box would cost $221. That’s without delivery and assuming your location carries all these cuts.

But don’t strict-press two Benjamins just yet.

The Harvard article also says “eat more protein” shouldn’t translate to “eat more meat.” People should include “sources low in saturated fat and processed carbohydrates and rich in many nutrients.”

Luckily, those sources are cheaper than fancy-schmancy beef.

A half-pound of ground turkey will get you 62 grams of protein. Three eggs, a single cup of edamame or lentils clock in at 18 grams each. And four tablespoons of natural peanut butter will get you 16 grams.

Plus, if you’re a paleo enthusiast but aren’t back-squatting $215, check out our tips for eating paleo on a budget, muscle up these low-cost paleo recipes, and nom on some of our favorite budget-friendly paleo snacks.

Jen Smith is a junior writer at The Penny Hoarder and pescatarian CrossFitter. She gives tips for saving money and paying off debt on Instagram at @savingwithspunk.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder https://ift.tt/2JIrO8b