Thousands of courses for $10 728x90

الأحد، 27 مايو 2018

The Biggest Retirement Risks and How to Prepare for Them

Over the past century, life expectancy in the United States has dramatically increased, a fact that has profoundly impacted the financial security experienced during our golden years.

After World War II, the first generation of retirees were generally expected to live less than a decade after leaving the workforce. Now, the average American is living to be about 78.8 years old, and as a result retirement can last anywhere from 20 to 30 years, with some people spending more time retired than they did working.

That sort of longevity is wreaking havoc on the best of financial plans, particularly when combined with the rising costs of some of life’s most significant expenses.

“About half of Americans are at risk of not being able to maintain their standard of living throughout retirement,” said Michael Gerstman, CEO of Fort Lauderdale-based Gerstman Financial Group.

Health care (including long-term care) and housing are among the biggest financial burdens and potential threats to your stability during retirement, said Gerstman, often derailing retirement plans.

What’s more, depending on which financial advisor you speak with, there are additional costs that many retirees fail to anticipate or properly plan for, from inflation to the premature death of a spouse, to things like unexpected emergencies, caring for children and grandchildren, and the cost associated with filling all of your newfound free time.

Taken collectively, or even individually, these issues can seem overwhelming at best.

Health Care

A male retiring today can expect, on average, to spend about $245,000 on healthcare during retirement, according to the recently published book Common Financial Sense. It’s a figure that excludes nursing home or long-term care expenses. And because of longer life expectancies, women may have to spend even more than that after retirement to cover general medical expenses.

As for those long-term care costs, they now average more than $43,500 per year, while a bed in a semi-private room in a nursing home carries an average charge of more than $82,000 a year.

“No one really understands healthcare costs and how they can escalate,” explained Greg Makowski, one of the book’s authors. “We’re so used to being under an employer’s plan,” he continued. “All of sudden you hit 65 and are on Medicare, and you could be paying $10,000 a year for premiums.”

Most people don’t pay for Medicare Part A. But if you do have to pay for it (generally because you didn’t pay Medicare taxes for a long enough period), premiums for a couple retiring at age 65 currently average $644 per month, according to the book. By age 75, average expenses escalate to $1,239 a month, and by age 85 they reach $2,387 per month.

Those costs are simply for Medicare Part A costs like premiums and coinsurance. There’s also the financial burden associated with Medicare Part B (which covers 80 percent of outpatient care), and all of the supplemental insurance that people are not necessarily accounting for – such things as vision, hearing, and long-term care. None of these things is paid for by Medicare, and thus typically come out of your pocket.

“As you get older, you lose your hearing, you need eye surgery, and your teeth go because you wear them out,” said Makowski. “And these things – hearing aids, vision, dental – are not covered.”

So what’s the solution, if there is one?

Makowski says as a society we have not yet developed a meaningful way to address the financial realities of retirement other than socking away all the money you can away in 401(k) plans, savings accounts, and health savings accounts, while you’re still working.

“What ends up happening is people can’t live the retirement they thought they could live,” continued Makowski. “They end up living very modestly.”

Meanwhile, Gerstman said he often suggests clients purchase a life insurance policy that includes a long-term care rider.

“How it works is that if care is needed, the amount of the death benefit is the amount that can be used for the long-term care expenses, with certain annual maximums,” Gerstman explained. “If the coverage is not used up in your lifetime for long-term care, the balance is paid out to your named beneficiary.”

Housing

Housing costs make up close to half of the expenses identified by the Consumer Price Index–Elderly (CPI-E).

To help reduce this cost, homeowners and those considering buying a home should plan to pay off their mortgage before retirement, says Steve Wang, a certified financial planner and personal finance expert.

“If your current mortgage doesn’t allow for that, then consider refinancing it to a fixed-rate loan,” said Wang.

Homeowners with traditional 30-year mortgages can eliminate about seven to eight years of payments — and tens of thousands of dollars in interest — simply by making one extra payment annually toward the principal, added Gerstman.

“If you can further increase your monthly payment to your mortgage, let’s say an additional 5%, you can knock more years off of the loan,” said Gerstman.

Renters, meanwhile, have the advantage of not worrying about home repair costs, but will face the disadvantage of having a housing expense that never goes away. If you’re in this boat, it’s important to start saving sooner rather than later for housing expenses in retirement.

“Start saving now and make your money worth more down the road when you retire,” said Wang.

Inflation, Death of a Spouse, and More

While the Federal Reserve currently targets a 2% inflation rate, inflation has averaged about 3% annually since 1913 and 4% annually during the past 50 years, according to data from the U.S. Bureau of Labor Statistics.

“However, there have been periods when inflation exceeded 15%,” says Thomas Walsh, a certified financial planner at Palisades Hudson Financial Group. “While you can’t tangibly see it, inflation, especially unexpected increases in inflation, can do real damage to a retiree’s purchasing power, many of whom are living on a fixed income.”

To address this problem, Walsh says it’s important to continue to maintain some exposure to more aggressive investments during retirement, including equities. Being too conservative with investments during retirement can be costly if inflation spirals out of control.

The premature death of a spouse during retirement, meanwhile, will be made even more difficult if it brings with it a financial surprise.

“It’s important for both spouses to understand how their income is generated and what will happen when one spouse dies,” Walsh continued. “Going from two Social Security checks to one can represent a significant drop in income. The loss of a pension benefit, or a cut in the survivor’s benefits, can lead to the same issue.”

Again, it’s important to plan for such scenarios and to understand how they impact the household finances, in this case for the surviving spouse. Walsh recommends purchasing enough life insurance to make up for any loss of income and to cover funeral expenses.

The Cost of Free Time

One last cost associated with retirement that’s often not properly budgeted for – the expense of filling your free time.

“I like to say that retirement is having your week be comprised of six Saturdays and one Sunday,” says Jeff Motske, who’s recognized as one of the top financial planners in America and is author of The Couple’s Guide to Financial Compatibility. “It’s wonderful to finally have the time to devote to all those activities and projects you’ve been putting on the shelf. Unfortunately, a lot of those projects typically have a price tag attached to them.”

Whether it’s home improvement, traveling, or a new hobby, many retirees’ newfound projects take up both time and money.

Yet another reason to begin saving early, create a well-thought out retirement plan, and minimize expenses wherever possible.

Related Reading:

The post The Biggest Retirement Risks and How to Prepare for Them appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2Ly53ol

Turning 21? Here’s How to Manage Your Money Like a Real Adult

السبت، 26 مايو 2018

How I Get Things Done

One of the most regular questions I get from readers centers around how I manage my time and focus. The questions tend to focus on some specific element of my overall system for managing all of the things that I need to get done in my parallel roles of writer, father, husband, coach, involved community member, child, and all of the other roles I fulfill in a given week, along with some time left over for self-care.

I’ll be the first to admit that it’s hard to juggle all of those things. There are constantly things to be done, appointments to remember, places I’m supposed to be, tasks that need to be done. It is utterly relentless.

Over the years, I’ve tried all sorts of tactics and techniques for managing my time and focus and energy to get as much value out of each day as possible. My systems for doing this have evolved over time, in ways I’ll mention below, but here is my system for getting things done and staying sane.

Key Principles

Before I dig into the specific tools I use, here are the five key principles that underlie the entire system. All of the tools and practices I have follow these five key principles. If I try something and it doesn’t measure up to these principles, I don’t keep it.

Full trust I absolutely have to trust the systems I’m using. If I find that I’m trying to remember tasks or appointments or other things rather than fully trusting my system, then something is wrong with the system.

The entire purpose of all of the things below is to make sure I don’t have to waste any of my thinking on trying to remember appointments and tasks and other random pieces of information. They don’t have to enter my mind, ever. I know that everything I need to know is stowed away in my calendar, my to-do list, or in an inbox that’s about to be entered there.

If I ever doubt that feeling, then something is broken in my system and needs to be fixed. I absolutely have to fully trust it or it’s more trouble than it’s worth.

Positive value Every single element in my system must give me positive value for the time and effort I put into it. If I spend fifteen minutes a day dealing directly with managing my to-do list and calendar, that time better be repaid in efficiency throughout my day (it clearly is, as I’ve discovered when trying to manage life without those tools).

I use this rule of thumb for every single thing I try to add to my life for the purpose of being more productive. Is it a net positive in terms of productive time? Does it make it easier for me to have time left over for self-care? Does it make it easier for me to get everything done in the allotted time I have each day? If the answer is yes, I’ll keep it. If the answer is no, or even if the answer is unclear, I’ll ditch it.

Managing energy above all else The truth is that all of the things I’m describing here manage my energy more than anything else. It’s all about organizing my day so that there’s something to fill the time no matter where my energy level is or where my focus level is.

I know from experience that my focus for writing and other “deep” tasks peaks between 8 AM and noon each day, so I do those kinds of “deep” tasks in that time frame. Before that, I know that my brain is creative and fairly “off the rails,” so I use the early morning time for brainstorming and brain dumping and some small bites of learning. In the early afternoon, I’m often dull and tired, so I do mindless tasks. In the late afternoon, my focus and energy come back somewhat, so I address the class of things I consider “important but not urgent” in my life.

Almost all of the things I mention here allow me to take advantage of the moments in my life when focus is strong and to get the most out of times when focus isn’t as strong. They form a structure in my life where productivity comes naturally to me.

Self care is not optional Spending time and energy ensuring that I am healthy and rested is not wasted time. In fact, it is the most valuable time. It is the time that needs to come first.

I block off time for things like exercise and making home cooked meals and simply enjoying my hobbies, and those times are sacrosanct. They are among the most uninterruptible times on my schedule. If I have a block set aside for hobbies, it doesn’t matter how much I have undone in other areas, I set those tasks aside and go read a book. The same is true for exercise.

This is difficult, don’t get me wrong, but I recognize that self-care and managing core relationships is pretty much the embodiment of “super important but not urgent” and I intentionally make sure I always have room for them. They come first. It’s not that much different than a “pay yourself first” financial strategy.

Always aim for the “flow state” The “flow state” is when you’re so mentally (and sometimes physically) engaged with what you’re doing, you lose track of time and place for a while and just do it. I find that any time I spend in a flow state is incredibly valuable and highly productive time. I get fantastic results from almost anything I do in a flow state.

Thus, a big part of these tools and this system is to nudge me into flow state regularly. The fewer distractions I have and the sharper I am, the more likely I am to fall into a flow state, so this entire system is all about minimizing distractions and getting me mentally sharp.

There are other secondary principles that I use that will come out in the following sections.

Key Tools

Here are the tools that I use to keep everything going. Note that the specific tool of each type is just one that I prefer for my own needs. There are lots of different digital calendars, for example; try some and use the one that works for you.

Digital Calendar
My preferred tool: Fantastical as a front end for Google Calendar

The purpose of my digital calendar is to organize my day. This doesn’t mean just managing appointments, which is of course vital, but organizing my day into blocks of time that I use for different tasks.

Most days, I have blocks of time for exercise, for family, for writing, for brainstorming, for a morning routine, for an evening routine, for household tasks, for self-care, for flex time (to make up for unexpected events), and for sleep. I do my best to actually stick to that schedule each and every day. (I’ll get into the specifics of this again in a little while.) It makes for a calendar that looks quite full, but it really doesn’t feel that full in practice.

The real purpose is that at any given time during the day, I can look at my calendar and know what I’m supposed to be doing. I don’t have to think about it. My thinking in terms of deciding what needs to be done is mostly done well in advance and reviewed the night before and in the morning. I don’t have to think about it during the actual day – I just get stuff done.

Having a digital calendar means that it’s loaded with all kinds of reminders that tell me when I should be switching from one task to another and sometimes with advance alerts of things I need to know are coming up in the next hour or two (like going to my child’s school for a parent/student lunch or something like that). My calendar is one of the few interrupting distractions that I allow, and it also functions as a timer of sorts that tells me when it’s time to switch to something else.

Digital Task Manager
My preferred tool: Omnifocus

A digital task manager is basically just a fancy to-do list that allows me to categorize tasks and move them around without having to erase and recopy tasks in a paper planner. The real purpose is to simply keep track of the multitude of tasks that need to be done.

I keep all of my tasks in various categories that match up with the blocks of time I have during the day. I have a “Work” category, a “Household Tasks” category, and so on. I even have categories for things like “Family/Friends” and “Self Care” and “Hobbies,” though the tasks in some of those areas tend to be sparse much of the time. I will also sometimes make up sub-categories under these for tasks related to specific projects, like planning a trip or something like that.

Most of the tasks have a due date associated with them, and I usually assign a high priority to tasks that I really need to get done today (I do this during a morning review, which I’ll talk about in a bit). My task manager makes it easy for me to find these things.

Again, a key part of what makes this work is trust. I trust that everything I need to do is in my task manager. Without that trust, it’s not a very efficient tool. When I don’t have that trust, I’m always trying to remember things I need to get done. When I have that trust, I don’t think about that at all, just the task at hand. Thus, trusting my to-do list means I can focus much better on the task I happen to be working on, and that means it gets done much more efficiently and with higher quality results than if I didn’t trust my system.

Pocket Notebook
My preferred tool: Field Notes with a Uniball Signo 0.38 mm black pens

One of the big challenges with to-do lists is that I’ll often be in the middle of one task and I’ll suddenly recognize something I need to do in the near future. I’ll be writing an article and it will suddenly occur to me that we need to get some nails to re-shingle our rabbit hutch for our children’s pet rabbit, or I’ll be doing the dishes and see that we only have a little bit of dishwashing detergent left and realize that we need to get more.

For those moments, I keep a pocket notebook in my hip pocket at all times, along with a pen that won’t break or leak. When that fresh idea or task or whatever pops into my head, I pull out that notebook, write down the idea or task or whatever it is, and then go right back to work.

Later on in the day – usually in the evening, but sometimes I’ll do it during the day, too – I’ll pull out that pocket notebook and go through it, copying everything over to where it belongs. Appointments go in the calendar. Tasks go in the task manager. Ideas go in my idea repository (literally the next section in this article). I cross them out as I go along and when everything is crossed out, I move on with life.

This pocket notebook is key. It is a big part of ensuring that things don’t slip through the cracks. It ensures that I don’t forget ideas in the moment and that I don’t lose focus on my current objective while trying to remember them.

Electronic Document and Note Storage
My preferred tools: Evernote and Dropbox

Evernote and Dropbox are my storage solutions for all kinds of information. I use them because they’re easy to access from pretty much anywhere and allow me to organize things how I want them.

I mostly use Evernote for text-based ideas with maybe a few pictures thrown in here or there. I use it as an idea repository for my writing, as I have folders for things like potential article ideas or things I should read or follow up on. I use it as an idea repository for most other projects in my life, too.

I use Dropbox for documents of all kinds that I want to have access to everywhere I’m at. Photos, PDFs, and all kinds of other things are stored in Dropbox in a file folder structure that I understand well. I can find almost anything within a few clicks in Dropbox because I have it organized in a way that makes sense to me.

Every sort of document or note that I want to keep around winds up in Dropbox or Evernote, depending on what type of document it is. When I have tasks in my task manager or appointments in my calendar that require notes or documents, I know I can just find them in Dropbox or Evernote.

Paper Journal
My preferred tools: Leuchtturm 1917 dotted medium journal and Uniball Signo 0.38 mm black pens

The purpose of having a paper journal is for reflection and what I like to call “sharpening the axe.” I use it in both the morning and evening to reflect and brainstorm on my life and get things out of my head that aren’t always easy to extract. For me, it’s less of a recording of the events in my life than a way to make sense of and clarify the mishmash of thoughts and emotional responses in my head so that, when I’m done with the journal, my head is clear and focused and ready to deal with the day or sleep in peace.

There are three big things I do with the journal regularly, usually every day.

First, I write three morning pages. It’s basically just three pages, written by hand, on whatever is in my head. I just dump out whatever is on my mind at the moment onto paper. I don’t question it or guard it, I just let it come out. I find that forcing myself to think about those things at the pace of my handwriting brings a ton of clarity to the ideas I’m struggling with or the life issues I’m trying to figure out. I do this in the morning, usually before anyone else wakes up – I consider it a part of brainstorming.

Second, I go through a modified practice that I learned from Triggers by Marshall Goldsmith. In the morning, I simply write down a list of things that I want to be working on today. These aren’t necessarily tasks, but ways in which I want to behave and interact with the world. I want to do something to encourage my physical fitness. I want to eat healthy foods. I want to write well. I want to spend as little money as possible. I want to work on my virtues. I write each of these as sentences describing what I’m going to do today. In the evening, I review each of those and give myself a score on how I did today on those things. I usually keep them up for at least a week at a time and then reconsider them each week during a weekly review. This is so powerful in terms of nudging me to be a better person.

Finally, I go through a series of eight questions suggested by Michael Hyatt. I usually do this in the morning as well. The biggest one for me is his question of “what lessons did I learn from yesterday?” I usually note a few lessons, but I usually take one and tear it apart, doing an after-action review of it in detail.

I won’t lie – this takes a long time. I probably spend an hour, and sometimes more, doing this each morning (usually from about 5:45 to 6:45 AM) and probably another 10 to 15 minutes in the evening. That seems like a ton of time, but what I’ve learned is that when I’m done with this practice, I am absolutely ready to nail the day. I have a sense of mental clarity about what I should be doing and a great ability to focus for most of the day. On days when I don’t do this, I often feel like a lumbering sloth meandering through the fog in comparison. I more than make up that hour spent on journaling on days when I journal compared to days when I don’t really get it done.

So, how do I actually use these tools?

“Ideal Week”

It starts off with the “ideal week.”

Each week, I spend about an hour or so on Sunday reviewing the week and getting myself prepped for the next week. One part of doing that is reading through my journal for the week. I also go through my to-do list and see if there’s anything really vital that was left undone.

Perhaps the most important part, though, is the “ideal week.” I plan out my week to come, starting off with a calendar template that I call the “ideal week.”

Basically, this just consists of a whole lot of repeating events in my calendar that specify what I would be doing each hour of each day assuming that I am going through an average week that’s going along perfectly with minimal interruptions. Assuming everything was perfect in my normal life, what would an “ideal week” look like? I basically just fill that out in Google Calendar and set every single block of time to repeat every week.

So, on Monday, it starts off with a block for sleep starting at 10:30 PM Sunday and running to 5:30 AM Monday. That’s followed by a block of “morning routine” and journaling from 5:30 AM to 7 AM, followed by half an hour of getting the kids ready for school, followed by another half an hour of “morning routine” (I’ll get back to that in a second). After that, I have a four hour block of “writing” scheduled, followed by “lunch,” followed by “exercise,” followed by “other work tasks,” followed by “deep reading,” followed by “flex time,” followed by “family time,” and so on. You get the idea. I just block out my whole day with what I will ideally be doing during each hour.

When I add events to my calendar, those are deviations from the “ideal week.” During my weekly review, I look ahead and try to resolve any conflicts for the next month or so between my “ideal week” and the things I add to my calendar, usually giving the appointments priority. I figure out what needs to be moved around and make room for the appointment. What am I giving up? I decide that then.

Most of the time, this is pretty easy. I’ll usually shrink down a few things and then expand them on the weekend, which is mostly made up of self-care, family and community commitments, and flex time. For example, I’ll often shrink down my daily “deep reading” (basically research or trying to learn a new topic) and then expand that very activity on the weekend.

I usually try to keep my morning routine and writing routine sacrosanct unless weeks are very exceptional, like family vacations or holidays. Even then, I’ll often still do some smaller form of those routines.

“Morning Routine” and “Evening Routine”

So, what exactly are my morning routine and my evening routine?

My morning routine is the big one, and it usually eats up about two hours of my day if I do it in full, with journaling taking up about half of that or a little more. The rest of that routine involves reviewing my calendar and to-do list (and picking out a few high priority things to be done today), doing some basic morning hygiene, meditating for fifteen minutes, exercising a little (this is mostly stretching and a bit of calisthenics in the living room, usually stuff to supplement my taekwondo classes), and doing a bit of reading.

My evening routine is basically a review of the day. I write in my journal a little bit, peek at my calendar and to-do list, and get ready for bed with some evening hygiene (brushing my teeth and so on). I just try to do the same four or five things every evening so it feels completely natural.

I tinker with the exact contents of my morning and evening routines regularly, but they’re largely settled at this point. My “tinkering” mostly involves messing with the order of things, changing up my exercise tactics, or trying out a new element for a while.

Going Through the Day

During the day, I mostly just follow my calendar, which is usually made up of time blocks. During those time blocks, I follow what’s on my to-do list associated with that time block.

So, when I’m in the midst of a “writing” block, as I am right now, I’m basically just going through my list of to-dos related to writing. Those usually involve drafting a specific article, then editing and formatting that article (a separate task, because I give it some breathing time between those two steps), then scheduling and posting that article, along with some brainstorming tasks and reminders to check the various places where readers send messages. I have other work tasks, but those are the ones really associated with The Simple Dollar directly in terms of what you guys read. I spend my work block mostly doing those kinds of things in 50 minute stretches, with 10 minute breaks to stretch and go on a short walk around the block.

The same is true for other blocks. During household chore blocks, I go through my list of household chores and just knock off as many as possible. During focused family time blocks, I try to do things with my family with all digital distractions shut off. You get the idea here.

If something pops into my head that I want to deal with later, I just pull out my pocket notebook and write it down. This keeps me away from digital distractions. About once a day, as part of my evening routine, I copy everything over to my other systems as described above.

I usually have timers that go off at the end of time blocks, letting me know it’s time to switch to other things.

A big part of this system is freeing myself up to get into a “flow state,” as I mentioned earlier. If I can slip into a flow state during any one of those blocks, it’s going to go really, really well. If I can do it several times during the day during various different blocks, it’s going to be an amazing day.

The Perfect Is the Enemy of the Good

This system might seem complicated at first glance, but it works extremely well for me. It enables me to keep my mind very sharp throughout the day – my mind doesn’t wander due to having things on my mind. I do focused things when my energy and focus levels are high and do less intense things when my energy and focus levels are low. It enables me to prioritize self care without letting go of all of the other things that I’m responsible for in my life, so that I can continue to be responsible for those things into the future.

That being said, I’m not perfect with this system. There are days when I don’t execute perfectly. I don’t write in my journal some days, though I try to at least get something down every day. I don’t exercise as much as I should every day. The one element I really strive to be perfect on is to keep my calendar and to-do list as trusted as possible by writing things down in my pocket notebook and adding them to those tools as needed, but pretty much everything else will sometimes slide if I’m not feeling 100%.

That’s okay. The perfect is the enemy of the good. A bad day doesn’t mean I discard the system and give up and think of myself as a failure. It just means that I do better tomorrow.

I do know that when I nail all of this stuff, I feel practically superhuman in terms of how much I can get done in a day. My mental clarity in the middle of the day if I’m nailing all of these things is just incredible. I genuinely feel like there were earlier parts of my life where I was practically working in a fog at half speed all the time. It’s those ideal days, when I am constantly slipping into a flow state and really getting lots of things done, that makes all of this worthwhile, because those days are amazing and they happen surprisingly often.

What Can You Take Home?

If you pull out anything from this, it’s that those five key principles are the foundation of everything else I’ve written.

Get things out of your head and into a system that you fully trust. Everything you do should have positive value – it’s either improving you (I put self care and genuine leisure time in here, but not time wasting), improving a relationship, making money, or making one of those other things more efficient. Do high energy and high focus things when you actually have energy and focus; do mindless things when you feel mindless. Do not skimp on self-care, which includes genuine leisure time, good healthy food, exercise, good personal relationships, and adequate sleep. Aim for the “flow state” in everything you do, because you’ll never be better than when you’re so engaged that you lose track of time and place and just get lost in the moment.

All of the stuff in this article is an embodiment of those principles that works well for me. Some of those specific tactics might work well for you, or they might completely fall flat. We all have different minds and bodies that work in different ways. Try things and figure out what works best for you, and use the tactics here as things to try out, not things to blindly follow.

Good luck, and may your days be amazing!

The post How I Get Things Done appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2sgHffJ

Gluten Free? These Apps Make It Easier to Grocery Shop, Cook and Eat Out

الجمعة، 25 مايو 2018

FDA Says Claims About Sunscreen Pills Could Burn Sun Worshippers


Bathing suit? Check. Beach towel? Got it. Sunscreen? Absolutely — but you may want to heed this new warning first.

The Food and Drug Administration is cautioning sun worshipers that a pill marketed to keep them safe from damaging rays actually could put them at risk.

Not to mention waste their money.

The agency this week warned four companies to stop advertising sunscreen pills and capsules as effective in preventing sunburn. FDA Commissioner Scott Gottlieb says the companies are misleading consumers and putting people at risk of harmful sun exposure.

“The FDA has not approved any pill for the claims these companies are making, so that should be a red flag,” said Theresa Eisenman, an FDA spokeswoman. “There’s no pill or capsule that can replace your sunscreen.”

At $25 to $50 a bottle, the pills are also pricy — especially if they don’t work.

The warning comes just in time for “Don’t Fry Day,” the Friday before the unofficial start of the summer vacation season — Memorial Day. The National Council on Skin Care Prevention designated the day to encourage people to cover up and use sunscreen to protect against skin cancer, the most common cancer in the U.S.

The FDA on Tuesday sent warning letters to Advanced Skin Brightening Formula, Sunsafe Rx, Solaricar and Sunergetic. The agency says the companies are illegally marketing dietary supplements and making unproven drug claims — namely, that their pills and capsules protect people from sun damage and, in some cases, even skin cancer.

On Friday, one of the companies was still advertising its product on its website as a method “backed by science” to protect eyes and skin from ultraviolet rays.

According to the warning letters, the companies claim their pills are useful in preventing or mitigating disease — an assertion the FDA says illegally establishes them as a drug. The FDA must approve all drugs sold for human consumption in the U.S.

These four companies aren’t the only ones advertising such products on popular sites such as Amazon, eBay and Walmart.com, so consumers have to be vigilant.

The only legitimate sunscreens are sold over the counter as creams, sprays, lotions or sticks, Eisenman said.

Board-certified dermatologist Dr. Thomas Rohrer advises his patients to apply sunscreen liberally, stay in the shade when possible, wear a hat with a wide brim and protect their eyes with sunglasses when they’re outside. And never sunbathe.

An SPF — sun protection factor — of more than 50 isn’t necessary, he said, although he uses sunscreen with an SPF of 85 or 100. Sunscreens with a higher SPF tend to cost a little more, but Rohrer, whose practice is in Chestnut Hill, Massachusetts, said they do no harm and may provide extra protection.

Effective ingredients are critical, but it’s also important to choose a sunscreen that feels good on the skin.

“Find one that is cosmetically appealing,” he said. “You have to find a sunscreen that you’ll use.”

It’s never too early to start protecting against skin cancer, according to new guidelines from the U.S. Preventive Services Task Force. The group advises doctors to counsel their patients about the importance of sunscreen for babies as young as 6 months old.

Rohrer says an annual screening for skin cancer is a good idea, especially for people who have had the disease or have a history of it in their family. May is Skin Cancer Awareness Month.

Finally, don’t ignore moles that change in size, shape or color or pimples in a sun-exposed area that linger, crust over, bleed or get larger. They could be signs of cancer or pre-cancer, he said.

One in five Americans will get skin cancer by the time they reach age 70, according to a 2010 study published in the Archives of Dermatology.

Susan Jacobson is an editor at The Penny Hoarder. She always wears sunscreen.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder https://ift.tt/2s6pv7I

How to Improve the Profitability of Your Small Business Mobile App

If you have been following the latest marketing developments, you know everything is trending in a mobile direction.

Consumers are seemingly glued to their phones and tablets. In fact, 77% of adults in the United States own a smartphone. That number is up from 35% in 2011.

That’s why it’s so important for you to optimize your web design for mobile users. While this is a necessary approach, it’s not enough if you really want to enhance your mobile marketing strategy.

The way people use their phones has changed. People don’t consume information the way they did five or ten years ago.

With the rise in smartphone usage, it makes sense that there is also a growing popularity in mobile app usage.

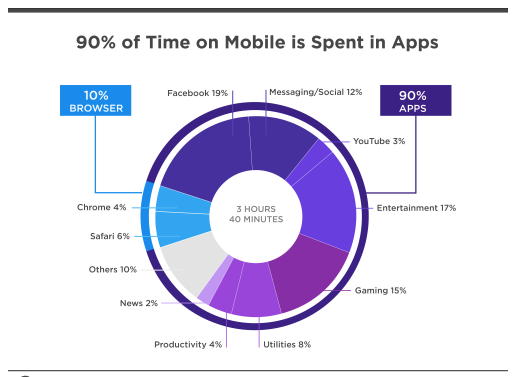
In fact, 90% of mobile usage time is spent on applications.

image4 7

If you are one of the small business owners who recognized this trend and built a mobile app, congratulations.

Developing an app is no easy task, and it’s definitely not the least expensive investment you’ll make in your lifetime. But now that your app has launched, you might be having some concerns about your return on investment.

You expected to see massive profits right off the bat, and that’s not always the case.

Some of you may have had your small business mobile app out for a while now. At first, it was performing well, but over time sales have become stagnant or even declined.

Even if your mobile app is successful, there is always room for improvement. That’s the inspiration for this guide.

I’ll explain everything you need to know about optimizing your small business mobile app to maximize sales and increase profitability. Here’s what you need to know.

Don’t charge users to download your app

I know what you’re thinking. How can you make money with a free mobile app?

Charging an upfront fee for downloads may seem like an appealing way to get some fast cash. It could be the way you forecasted getting your initial investment back. But I advise against this strategy.

As a small business owner, you know how important it is to prioritize customer service. You also know how cost-sensitive your customers are.

The investment to download your app will turn people away. Even if you’re only charging a few bucks, it’s just not worth it to people.

Why?

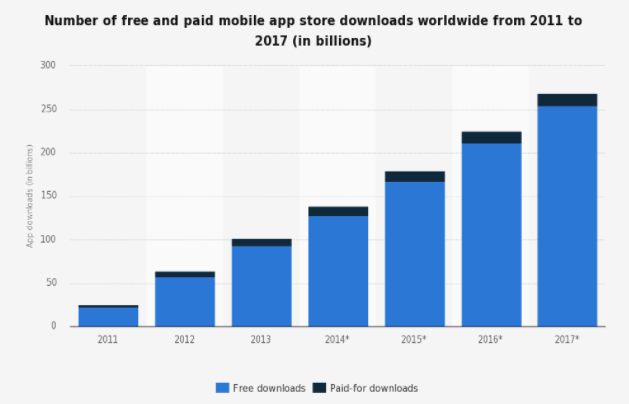
Well, for starters, your customers are not used to paying for their apps. Research shows the vast majority of mobile app downloads are free.

image2 7

Is your app really that much more valuable to the user than all the other free apps on their device? I doubt it.

Removing the cost to download an app will ultimately result in more downloads. Now people won’t have a reason to hesitate when installing your app on their devices.

The more people download your mobile app to their smartphones and tablets, the greater the chances of them spending money.

Here’s another way to think of it. If you’re using this app as a platform to sell your products, what’s the cheapest item offered on your app?

Now, compare that to the cost you were considering charging for a one-time download. It’s just not worth it to collect an insignificant fee when you can cover these user acquisition costs with actual purchases instead.

Focus on app store optimization (ASO)

Since you’ve already developed a mobile app for your business, I’ll assume you’re somewhat tech-savvy.

Even if you didn’t build it yourself, you at least have your finger on the pulse when it comes to the latest technology. You probably have a website and understand the basic principles of search engine optimization (SEO).

Well, app store optimization is basically the same concept. But it’s in reference to the app store as opposed to an Internet search engine.

There are certain elements based on how you set your app up that will affect your ranking in the app store.

However, there’s a catch. These algorithms and factors will differ depending on where your app is available. The two biggest app stores are the Google Play Store for Android devices and the Apple App Store for iOS devices.

Those of you who have your app available on both platforms, which I definitely recommend, need to understand how these elements affect your ranking.

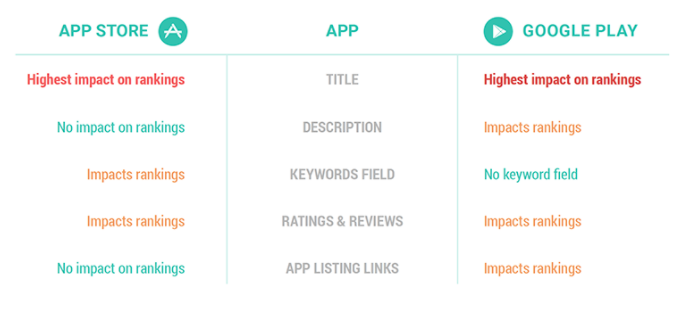
Here is a look at some of the main differences between these two app stores:

image3 7

As you can see, there are definitely some similarities between the two stores that have implications for your ASO strategy. The app title in both the Apple App Store and Google Play Store has the most significant impact on your search rankings.

The way user reviews and ratings impact your search ranking is also similar on both platforms.

However, some of the key differences here include:

  • description
  • keywords field
  • app listing links

You’ll need to make changes to your listing in each store so that it’s appropriately optimized for ASO.

If you have your app available only in one store, you’re missing out on a huge opportunity here. Alienating a large percentage of your customers is costing you money.

Once you have your app offered in both app stores and prioritize your ASO, you will see more downloads.

As I have previously stated, increased downloads will improve profitability.

Personalize the user experience

What happens when someone downloads your app?

Think about what everyone sees on your homepage and interface. Is it the same?

If the answer to that question is yes, you’re making a mistake. You should encourage app users to create a customer profile when they launch your app.

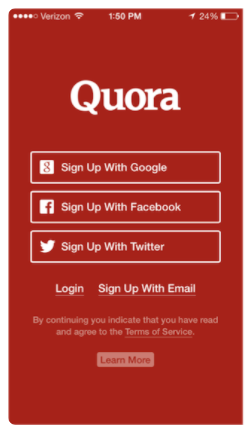
Often, people are turned off and discouraged by the time-consuming and tedious process of creating a profile. You can make it easier for your customers by integrating your app with their Facebook profile or Google accounts. This simplifies the login process.

Here’s an example from the Quora app that illustrates exatly what I’m referring to.

image1 7

This is much easier for your users than having to type in all of their information to set up a profile.

But now that they have an account with your app, every action they make can be tracked to enhance their personalized experience.

Based on things such as their search history and previous transactions, you’ll be able to recommend appropriate products and services to each customer.

You can also recommend items based on age, location, gender, etc. Tracking previous purchases makes it easy for customers to complete repeat orders.

All of these factors will help you drive sales and boost profits through your app.

Personalized offers encourage customers to spend more money. In fact, 39% of customers are willing to spend more after receiving personalized mobile promotions.

Use your app to enhance the in-store experience

I know that some small businesses operate exclusively online. So this tactic may not apply to you at the moment.

But I still encourage you to review this section in case you expand your company to physical locations in the future.

But if you have brick and mortar retail locations, your app can help complement the in-store buying process for your customers. How well have you been tracking your customers’ shopping habits?

If you watch them closely, you may have realized they are already using their smartphones while they are shopping in your store.

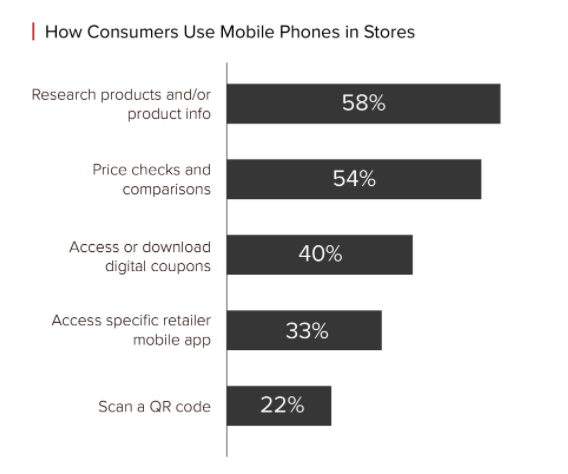
You might as well integrate your mobile app with your physical store to make shopping even easier for your customers. These are the top ways that customers use their phones while shopping in stores:

image5 7

Your app should be able to do all the things on this list.

Make it easy for customers to scan a barcode of an item in your store directly from your mobile app platform. Now they’ll have access to a detailed product description and be able to read user reviews.

Give them an option to save items in a list of their favorites so they can buy it later, even if they don’t want to buy it right now.

This will make it easier and more appealing for them to complete the transaction.

On the flip side, they can browse for an item on your app and save it in their favorites list before they get to your store. When they arrive, your app can tell them exactly where the product is located in the store.

Now they can check it out in person to make sure it’s exactly what they had expected before buying it. This really enhances the customer experience.

As we previously discussed, you want to personalize the customer experience.

Your mobile app can also act as a customer identification card for each user. This will be linked to their account and loyalty rewards program. We’ll discuss this concept in greater detail shortly.

Send push notifications

Your mobile website is a great asset to your small business. But one thing it can’t do is contact your customers at will.

Since you have a mobile app, you need to use push notifications to your advantage and reach out to your customers.

You just need to be cautious when it comes to the type of message you’re sending with each push notification.

We know that 48% of app users want to receive push notifications about special offers based on their preferences. This relates back to one of my earlier points about personalization.

Just don’t send push notifications too frequently. That’s because 52% of users believe that push notifications are an annoying distraction. You don’t want your company to be perceived as annoying. Sending too many notifications can cause damage beyond your brand’s tarnished reputation.

For example, 32% of app users will stop using an app altogether if they get too many notifications.

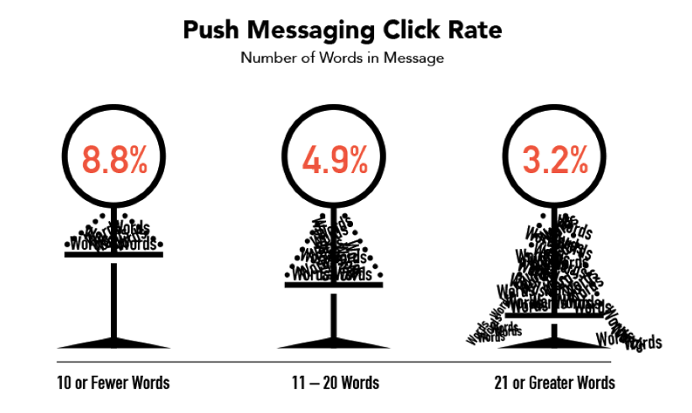
You should also consider the word count of your push notifications.

image6 7

If you have too many words, they may not fit on the screen. This will obviously have a negative impact on your open rates.

That’s why push notifications with ten or fewer words have the highest click rates.

When it comes to your push notification strategy, your best bet is to only send messages that add value to the recipient. I’d recommend discounts or promotions to get started.

Timely notifications are helpful as well. If your company is delivering something to the customer, such as food, a notification “your food has arrived” would definitely be appropriate.

Just don’t go overboard with these, or users can turn off notifications. If that happens, it won’t help you generate more profits.

Set up a loyalty program

You don’t always need to turn to new downloads and user acquisition to make more money. Instead, look at your most loyal customers as a way to increase profits.

As I mentioned earlier, your mobile app can act as a digital customer loyalty rewards card. We’ve all seen these before. Your small business may even have one of these systems already in place.

I’m talking about things such as a simple punch card. For example, if you have a sandwich shop, you may offer a free sandwich on the customer’s 10th visit.

The problem with this system is that cards get misplaced, and it’s not easy to track the purchases. But a mobile customer loyalty program is much more effective.

You can set it up based on the number of visits, but I’d recommend taking your strategy to the next level. If two customers each make ten purchases, does that mean they are equal?

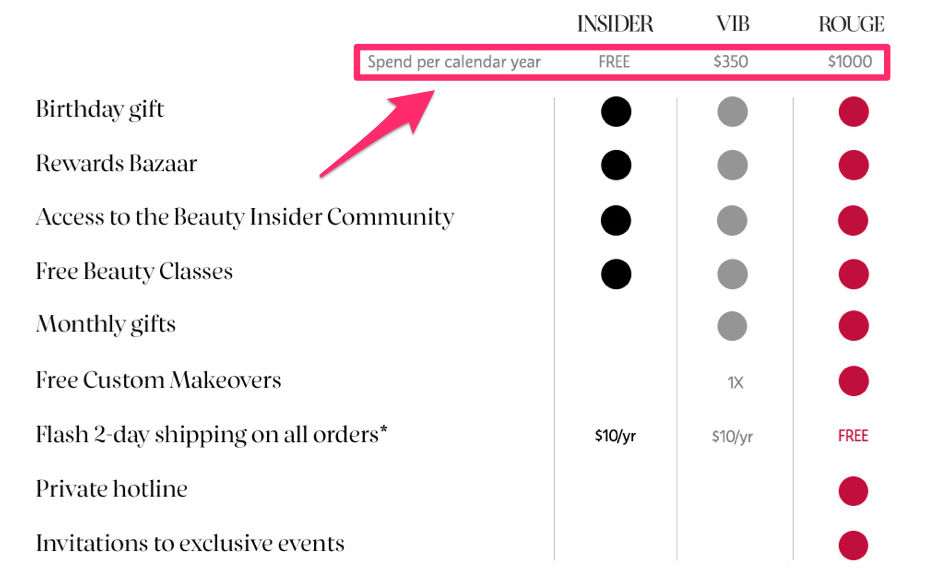
Not if one spends $100 total and the other spends $1,000 total. Setting up your rewards program based on a spending threshold system rewards your top customers.

Here’s a look at how Sephora implemented this strategy based on a customer’s annual spending:

image9 2

Adding this feature to your mobile app will help increase the buying frequency and average purchase order for each user.

That’s because customers are encouraged to spend more money so that they can reach the next level. Once they get to a new threshold, their benefits will increase.

As a result, you’ll see higher profits and improve your customer retention strategy at the same time.

Encourage user referrals

As I just finished saying, you don’t always need new customers to improve your profits. That said, it certainly helps.

A great way to get new downloads is by leveraging your relationships with your current customers. Encourage them to refer their friends and family to your app.

However, this is easier said than done. Simply asking your existing users to refer others probably won’t be enough to get the job done.

Sure, your app may be great, but it’s not enough for someone to help you just out of the kindness of their heart. They’ll be expecting something in return.

Reward customers for their referrals. Give them an incentive, such as a discount off their next purchase.

You can reward the referred user as well. It may seem as if you’re giving away too much, but it’s worth it in the long run since you’ll be getting new customers.

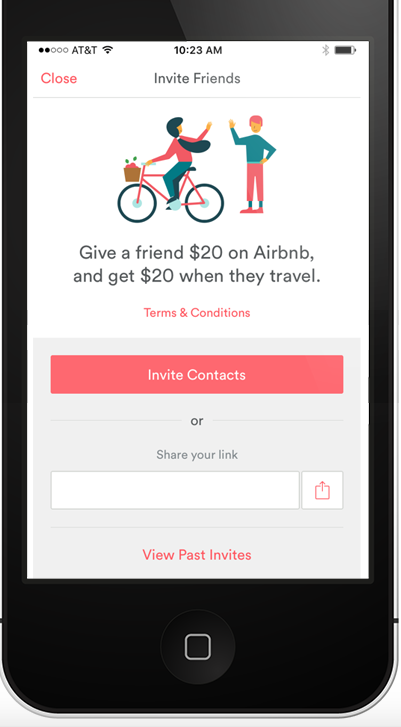
Here’s a look at how this feature looks on the Airbnb app:

image8 6

Research shows that this referral tactic helped boost their app download rates by 300%.

It’s safe to say it’s a winning strategy. It can also create an exponential download effect.

That’s because each time a new user downloads the app, they’ll also be encouraged to invite their friends to join.

This is one of my favorite ways to get your customers to recommend your brand to others.

Optimize the checkout process

Let’s continue our discussion of customer profiles. You want to take full advantage of this feature.

Once the customer makes an initial purchase through the app, you can save all of their information to their account.

Now you have their shipping address and billing information. Unlike on a desktop or mobile site, they don’t have to enter this information each time they want to buy something.

All they have to do is click on what they want and finalize the transaction. The entire checkout process can be completed in a couple of clicks.

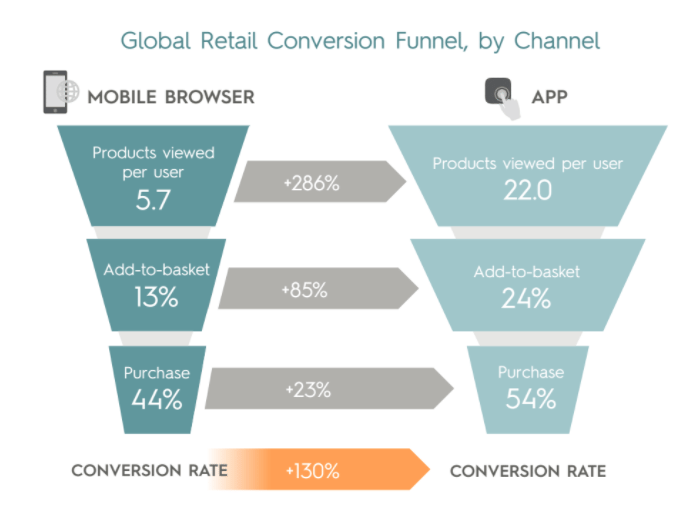
That’s why mobile apps have higher conversion rates than mobile websites:

image7 7

Do everything possible to make your app’s checkout as smooth as possible.

Fewer steps and less friction to complete a purchase will help drive sales. Plus, your app makes it easy to accept alternative payment options, such as Apple Pay.

Constantly monitor the performance

Nobody’s app is perfect.

Sure, you spent the time to make sure it was good enough before you released it, but there is always room for improvement.

Prioritize speed. Avoid glitches. Fix crashes and errors as soon as possible. It will help improve the user experience.

Research found 48% of app users are less likely to use an app if they have a poor experience. And 31% of people say they are less likely to buy something from a company based on a poor app experience. You can’t afford to overlook that.

Read through your user reviews to see the feedback and what needs to be changed.

Use beta testers to help you get valuable insights before releasing new versions and updates.

Conclusion

If your small business has a mobile app, you are already on the right path to success. But if your app isn’t generating high profits, it can feel as if there is a hole burning in your pocket.

One of the best ways to improve your app’s profitability is by finding ways to get more downloads. Ultimately, downloads will translate to dollars.

Make sure you offer your app as a free download. Focus on app store optimization to improve your search rankings in both stores. Encourage users to invite their friends through a referral program.

Personalize the user experience. Use your app to improve the way they shop in your physical stores. Set up a mobile loyalty program, and send promotions through push notifications.

Simplify your checkout process so it’s easy for app users to make a purchase.

If you follow these tips, your small business mobile app will turn into a money-making machine.

How are you using your small business mobile app to drive sales and increase profits?


Source Quick Sprout https://ift.tt/2xfagyk

Meeting an Old Friend: Strategies for Low Cost Meetups

Yesterday, an old friend of mine, one that I’ve known for more than twenty years and talk to online regularly but rarely get to see face to face, came through my area in the midst of a long road trip with his family. We were both excited that our paths were going to cross and we made plans to meet up.

Ordinarily, one might expect that we’d just identify a restaurant somewhere and meet for lunch there. It’d be convenient, right? Well, after some back and forth, we came up with a different plan.

First of all, we decided to meet at a park instead of a restaurant. There were several reasons for this. One, it settled the issue of figuring out a restaurant that everyone would like and that would meet all dietary requirements. Two, it put us in a position where we’d arrive with food already in hand so that we wouldn’t waste our window of time together ordering food and reading menus.

For me, however, the biggest advantage here was that I could just bring a meal made at home. I assembled a sack lunch meal in the morning with stuff I already had on hand and just took that with me. I just made a simple sandwich, took some sliced vegetables and fruit out of the fridge, and grabbed a full water bottle. It was simple, tasty, and incredibly cheap.

That’s really the other advantage of not eating at a restaurant: by not choosing a restaurant, it allowed everyone to choose how expensive they wanted lunch to be beyond the mere choice of what kind of food to eat. I wanted a cheap lunch. Another friend in the area who joined us brought a rather expensive takeout meal, one that probably cost ten times what my lunch did. Our mutual friends had a meal that was likely somewhere in the middle.

It also allowed individual people to consider their own dietary needs and food allergy concerns. This can sometimes be an issue if someone’s on a particular diet and can only eat certain foods or only eat at certain places. This wasn’t a real issue yesterday, but it certainly has been in the past.

Second, it provided a setting to move around. After eating, we went on a short walk together while their child played on the playground. Since they were in the midst of a road trip, it gave everyone in their family a chance to stretch their legs and move around, which felt good.

This was particularly useful for their young child. He seemed to truly enjoy being able to run around in the fresh air for a while and he took full advantage of the playground. (He even convinced the adults to join him on the playground for a while.)

This was the exact reason that we would often stop at parks when our children were younger. It gave them a chance to run around and burn off excess energy from being in the car. They’d run to the playground and wear themselves out with vigorous play while Sarah and I would usually clean up lunch and then take a walk around the park. It gave all of us an excuse to stretch out our bodies after a long car ride and get ready for another leg of the trip.

Third, we could linger for as long as we wanted. At a restaurant, you’re often nudged out the door after a certain length of time, especially if the restaurant is busy at all. At the park, we were free to stay all day if we wished. My sole restriction was needing to get home before my children got off the bus; their restriction was to get back on the road so they could make it to their destination by dark. We were free to hang out on our terms and free to depart on our terms.

We ended up talking for far longer than I expected; I figured they’d want to get on the road quickly, but instead they lingered for quite a while, enjoying the conversation and the nice weather. That probably wouldn’t have happened at a restaurant.

Another big advantage of being in a park is that we could spread out as much as we liked. With a restaurant, you might have a large group jammed into a small booth together or at a small table. At a park, there was no such issue. We spread out a giant blanket near a tree and spread out, with everyone having plenty of elbow room and space.

Finally, stopping at a park gives one an opportunity to enjoy local flavor and roadside curiosities. While this particular meeting didn’t really allow for such events, I have often stopped at great points of interest on road trips, often meeting friends at such places. It can be a great way to add to someone’s road trip while also giving them the freedom to get out and exercise.

Consider what free points of interest are in your area that out-of-towners who are just driving through might enjoy seeing, then plan to meet friends who are stopping by at those places. They get the joy of seeing you and visiting for a while and also enjoying a low cost meal along with the added attraction of seeing something interesting on their trip for free.

In the past, I’ve done this with things like the world’s largest twine ball in Arthur, MN and the statue of Superman in Metropolis, IL. Both of those involved stops in the middle of road trips that added something special to the trip. In both cases, I enjoyed a picnic lunch there, along with time with friends and loved ones. It really added to the trip.

Unfortunately, there aren’t many such places of interest near me, but there are certainly some parks and stops that are more interesting than others. Taking the time to identify a few can be worthwhile for people passing near you, and researching areas where you might stop to visit friends might give you a very interesting place to stop for such a meetup.

So, what can you take out of all of this?

If you’re on a road trip and thinking of stopping for a break at meal time, consider stopping at a park rather than a restaurant. It gives you the opportunity to get some fresh air and go for a walk as well, and if you have children, they can burn off some of that pent-up energy on the playground. You’ll also be far less restricted on the time for the stop – if you want to make it quick, you can just eat and run rather than having to wait for your food and for the waitstaff, but if you want to linger, you can linger for as long as you want to.

If you have friends stopping by as they go through town, consider suggesting a meetup at a park rather than at a restaurant. Again, this eliminates the need to negotiate what restaurant to choose and saves everyone involved money if they so choose. If people prefer food from a restaurant, they can get takeout from any number of fast food and fast casual restaurants. If people prefer food from home, they can bring food from home. You can even bring food for your friends if you so wish.

Look for interesting parks or free roadside attractions as part of the meetup plans. When considering where to meet, consider things in your area that might be interesting for the out-of-towner to see as part of a quick stop and meet there. If you’re going to meet someone as part of a road trip (or just need a place to stop for lunch), research a good stopping point and look for things of interest in that area. Sites like Roadside America and Atlas Obscura are great tools for this type of planning.

If parks are your game plan, come prepared with food in a cooler. Prepare some meals and beverages the night before your departure and stock up your cooler before you leave. Yes, you can always stop at a fast casual restaurant for takeout or a fast food restaurant or even call for something to be delivered, but that adds a lot of expense to the stop. Instead, aim to include the elements of an inexpensive meal or two in your packing and fill up a cooler with cold items just before you leave.

Together, these strategies will save you some money on your road trip while also giving you ample opportunity to stretch your legs and refresh yourself after part of a day of driving (and potentially get ready for another partial day of driving).

The post Meeting an Old Friend: Strategies for Low Cost Meetups appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2s60dXk

To Bee or Not to Bee: Here’s How This Kid Earns $100/Hr as a Spelling Coach

'I'm worried about my credit score after my bank's missed payments'

Tesco bank

Moneywise helps a reader tackle a payment error

I have had a Tesco credit card for more than a year. I have a direct debit set up to pay the amount owed in full every month. In February, the payment wasn’t taken. I rang Tesco and it said the payment date had been changed and advised me not to worry and that it would be taken out in March as usual. The adviser said it was all sorted, there would be no late fee and it wouldn’t affect my credit rating.

Then the payment was not taken in March. I rang again and was reassured by the adviser that it would be taken in April. I was told not to worry as there would be no late payment fee and no effect on my credit score.

But then it wasn’t taken in April either. I rang up in tears. Again, the adviser told me it would be sorted, which I didn’t believe. So I decided to transfer the money and pay off the balance myself. I’m really worried that this has affected my credit score. What can I do?

NJ/Anglesey, Wales

I contacted Tesco Bank on your behalf to seek some reassurance that things will be put right and your credit score won’t be hit.

The bank responded promptly and positively. It said: “We apologise that NJ’s direct debit payment was stopped in error, which resulted in the payments between February and April not being collected. We have confirmed that no fees have been applied as a result, and that the customer’s credit file will not be affected. We apologise for any inconvenience this may have caused.”

“My payment wasn’t taken. I rang up in tears”

I pointed out that you suffered some distress because of the situation and asked if it could give you a gesture of goodwill by way of apology. Tesco Bank told me it has offered you £250 as compensation.

I asked you if you were happy with the outcome. You told me: “I’ve asked Tesco Bank to close my credit card account as I no longer want anything to do with the company.”

I don’t blame you. Despite calling every month, the error wasn’t dealt with, leaving you concerned about your finances. But I’m confident that your credit score won’t have been hit and hope that the compensation goes some way to easing your anger.

OUTCOME: Reader gets £250 compensation for payment error


Section

Free Tag

Related stories

Twitter


Source Moneywise https://ift.tt/2s8fQxi

Water bills: don’t splash the cash

Water from a tap

If you pay for your water supply, then you may want to consider having a meter installed. It could boost your household finances

Water bills are on the up, following increases at the start of April which saw the average water and sewerage bill rise by £9 to £405.

In England and Wales, where a household’s water supplier depends on where you live, the average increase for this tax year was 2%. However, some customers – such as those of United Utilities – faced a bigger increase of 4%.

In Scotland, where water and sewerage prices depend on your council tax band for your home – and are covered by a ‘combined service charge’ – bills will rise by 1.7% on average. This means that those in tax band D, for example, will pay £437 a year.

In Northern Ireland, there are no domestic water charges.

Water is just one of a number of bills that have gone up in recent months for many households, piling increasing pressure on people’s finances.

Tim Robertson, chief executive of Save Water Save Money, says: “With consumers already navigating a year of consistent price increases, high inflation and low wage growth, it is well worth taking steps to mitigate the annual rise in water bills.”

Andy White, charges expert at water watchdog the Consumer Council for Water (CCW), adds: “There are lots of ways you can save money, including trialling a water meter, taking advantage of free water-saving devices, and checking to see if you’re eligible for a cut-price tariff.”

Moneywise takes a closer look.

Install a water meter

While you can’t switch water companies – as you can with gas and electricity suppliers – you may be able to save money by having a water meter fitted.

Mr White says: “For many households, this can be the most effective way to cut water bills, and you can get a meter installed free of charge.” With a meter, the size of your bill depends on your consumption rather than the rateable value of your property.

As a rule of thumb, if your home has more bedrooms than people living in it there’s a good chance you may be able to save money. Mr White adds: “Water meters won’t benefit everyone, but some people can save more than £100 a year.”

In most cases, you’ll have up to two years to switch back to unmeasured charges if you change your mind.

That said, some water companies in the south-east of England are rolling out universal metering programmes, where customers do not have the option to switch back to unmeasured charges. Always check your options with your water company before switching.

To find out if you might be better off switching to a meter, make use of an online calculator – the Consumer Council for Water has a handy calculator (Ccwater.org.uk/watermetercalculator).

Note that in Scotland, it’s not free to have a water meter installed, so you are probably best sticking with what you have. Also, be aware that as there are no domestic water charges in Northern Ireland, there is no need for a meter.

Get help with your water bills

In England and Wales, there are additional ways to save on your water bills – such as via social tariffs and through the WaterSure scheme.

"To find out if you’d be better off with a meter, check online"

Every water company now offers a reduced social tariff for eligible low-income customers. Some of these tariffs can slash bills by as much as 90%. You can find out if you’re likely to qualify for help, and how to apply, by using CCW’s social tariff guide. Visit Ccwater.org.uk/households/help-with-my-bills.

If you’re already a metered customer, meanwhile, but have high usage due to a medical condition or because you have a large family, and also receive income-related benefits, the WaterSure scheme could help. It limits the amount you’re charged and in most cases will be capped at the average household bill for your water company region.

In Scotland, households can find more information about the help available at the Water Industry Commission for Scotland at Watercommission.co.uk/view_HouseholdCustomers.aspx. Also visit Citizensadvice.org.uk/scotland/consumer/water/water-and-sewerage-s/paying-for-water-and-sewerage-in-scotland-s/. For example, if you are entitled to a single person’s discount on your council tax, it will also be applied automatically to the water and sewerage charges on your council tax bill.

People in Northern Ireland can find out about the help available by visiting The Consumer Council at Consumercouncil.org.uk/water/additional-help-for-energy-and-water-customers/. Help with adapted equipment like tap handles and control knobs is available to people on the Customer Care Register, such as pensioners and those with a disability or chronic medical condition.

“We are making big savings now”

Eddie and Jill Joesbury-Clarke (pictured above)from Worcester in the Midlands managed to cut their water bill from £750 a year to less than £400 by switching to a water meter.

The couple, who live in a three-bedroom bungalow, opted to trial a meter with Severn Trent Water back in 2013 to see if that would reduce their costly bills.

Eddie, 84, says: “I went online and put our details into the water meter calculator on the Consumer Council for Water website. The site told me that we could potentially make a pretty substantial saving, so we were keen to give it a go.”

After moving to metered charges, the couple managed to almost halve their bill.

“We now pay less than £400 a year for our water,” says Eddie. “This has made a real difference to our household finances. My only regret is that we didn’t trial a water meter all those years ago when our children left home. But at least we are making big savings now.”

The couple say they have always been conscious of using water sparingly so as not to waste this finite resource. Eddie adds: “We take all sorts of water-saving measures, such as having a dual-flush system in the toilet, and using a water butt to collect rainwater in the garden. I have also only ever used a sponge, bucket and watering can to wash the car – never a hosepipe.”

More top tips to reduce how much you spend on water

  1. Turn off the tap when you brush your teeth This could save a family of four up to £50 on annual metered water bills, according to water efficiency firm Save Water Save Money, as well as 17,520 litres of water per year.
  2. Cut a minute off your shower time This could save you £30 on your energy and metered water bills per year, or £120 for a family of four, according to Save Water Save Money.
  3. Install a water-saving shower head One of these could save a family of four £75 on their gas bill and about £120 on their water bill (if metered), according to the Energy Saving Trust.
  4. Fix your dripping taps A dripping tap can waste around 5,300 litres of water a year, according to the Energy Saving Trust. If you’re on a water meter, this could cost you an extra £15 per year.
  5. Take a five-minute shower instead of a bath A quick shower uses a lot less water than a long soak in the bath. If everyone in a four-person family took a five-minute shower in place of a bath, it could save around £15 on energy bills and around £25 on metered water and sewerage bills a year, according to the Energy Saving Trust.
  6. Fit a dual-flush toilet button Around a third of the total water used in every household is through toilet flushing, so it’s worth investing in a device that lets you choose how much water you use – an average of 4-6 litres per flush instead of 13. A dual-flush button could save a four-person household 50,000 litres of water every year. That would save around £150 a year in metered sewerage water bills, according to the Energy Saving Trust.
  7. Use a bowl to wash up Using a bowl to do the washing-up rather than leaving the hot tap running could save around £25 a year on a household’s energy bill and around £30 on metered water and sewerage bills, according to the Energy Saving Trust.
  8. Store up your washing-up Save up your dishes and do the washing-up in one go to reduce the amount of water you use. Similarly, wait until you’ve got a full load before using your dishwasher – or, for that matter, your washing machine.
  9. Use a garden water butt Collect rainwater in a water butt and then use this to fill a watering can when you need to water the garden. This is much less wasteful than a hosepipe or sprinkler, which can use up to 1,000 litres an hour. A metered household using a hosepipe for one hour a month could typically save about £35 a year, according to the Consumer Council for Water (CCW). Non-metered households won’t save.
  10. Fish for freebies Most water companies offer free devices that help you reduce your usage. This might include £20 low-flow shower heads, £5 inserts to reduce the flow of water from your tap, and Save-a-Flush bags, worth £2, which go in the cistern and save about 1 litre of water each time you flush the toilet. See your water company’s website for details.
  11. Soak away savings If you have a soakaway in your garden, which drains excess water into the earth, you may be able to have surface water drainage charges removed from your bills, saving over £50 a year, according to the CCW. You may also be eligible for a refund of charges you’ve paid, as soakaway discounts first came into force in 2001.
  12. Make use of free online tools to analyse your water use Check out water usage tools such as the aqKWa Savings Engine (Aqkwa.co.uk). This gives you an overview of your total use, with personalised water saving advice for your location, home and lifestyle.

For more water saving tips, visit Ccwater.org.uk, Est.org.uk and Savewatersavemoney.co.uk.

Section

Free Tag

Related stories

Twitter


Source Moneywise https://ift.tt/2IPfdPL

Will My 595 Credit Score Sink My Plan to Buy My College-Age Son a Boat?


Dear Penny,

I’m a divorcee who had recent health problems that kept me off work, resulting in late payments. I’m now healthy and back to work in a great job with a decent income.

My son needs a bass boat in order to compete in college. I can make the monthly payment, and I have a down payment saved, but not the required credit score to purchase a luxury item. I have a pitiful 595 credit score.

What can I do to raise my score to 650 by January 2019? Is there anything? Is it even possible?

B.

Dear B.,

You can definitely increase your score quickly. The majority of your credit score is determined by two factors that you can take simple steps to improve.

The first is payment history, the biggest factor that goes into calculating your score. Paying your bills consistently each month — even if you’re just paying the minimum — helps you build a solid track record. And because payment history is the biggest component of your score, this is where you’ll see an increase the fastest.

The second most important component is your credit utilization: how much of your available credit you’re using right now. As you pay down your balances, you’ll see your score rise. But if you have a lengthy debt payoff plan, it’s going to take longer to see the increase.

You may not get your score to 650 by January, but if you make consistent, on-time payments you’re likely to see a substantial increase. Here at The Penny Hoarder, we’ve featured people who have raised their credit score by more than 100 points in six months; meanwhile, others have spent seven years repairing their credit, working from a 480 score to 764.

Focus on prompt payments for now and build back those good habits.

Can we talk about this boat, though?

I’m not sure if helping your son buy a boat is a wise use of your recovering financial reserves.

What would he do if you were still ill and out of work? How would he pay for the boat without your help?

Talk through this situation with him and determine the true reality of the situation. I would hate for you to make progress in building your credit back up, only to damage it later if something goes wrong with a boat loan.

I understand that the past few years have been rough and you want to help your kid do well in school. But this boat is not likely to help you in your efforts to stay above water.

Lisa Rowan is a senior writer at The Penny Hoarder.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder https://ift.tt/2LtlZfN