

الخميس، 21 يونيو 2018

الأربعاء، 20 يونيو 2018
How to Generate Sales for a New Product Release
So you’re ready to launch a new product.
Congratulations.
Regardless of your business type or industry, it’s important for brands, both new and old, to be innovative to stay relevant. I know how much hard work you’ve put into this new release, so I want to commend you on that.
Whether you’re releasing a new product or an extension of an existing product line, you’ve got to make sure your marketing efforts lead to sales.
Think about all the blood, sweat, and tears you put into this creation. Okay, maybe not blood, but you get what I mean.
This goes all the way back to your early brainstorming sessions as well as your research and development phases. You may have even had some failed attempts.
Oh yeah, and what about all the money you invested in this new product? Can’t forget about that.
If you can’t get consumers to buy your product, you won’t get an adequate return on that investment.
But those of you who are able to effectively promote your new product will enjoy the high sales. I’ll give you some tips and advice that will help you out.
Build hype early
If you wait until your product launches to start marketing it, you’ve waited too long. Those of you who failed to start early are already behind.
But don’t worry. I’m not here to reprimand you. There are still ways in which you can generate sales after the item is released, but we’ll talk about those later.
A great way to build hype in the early stages is by turning the announcement into a big deal. Apple is famous for this with its keynote presentations.
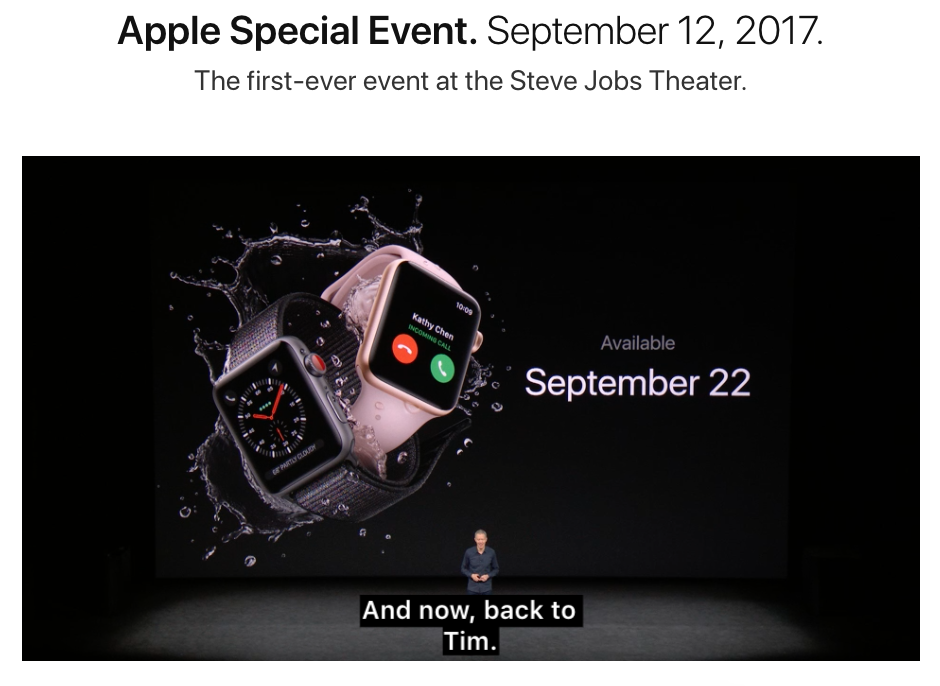
Since the company has been using this strategy for years, consumers now anticipate the announcement itself. By the time Apple announces a new product, people have already decided to buy it.
Announcing new products at a particular event will get your audience ready. They’ll want the latest and greatest product or technology.
The anticipation of the release makes the product that much more desirable. Now you’ve got them hooked before it’s even released.
Consumers will be lined up around the block to buy your new product because they’ve been thinking about it for months. They already know the features and benefits of it because they’ve done the research.
Building hype before the release will help you generate sales on the release date as well as the subsequent days and weeks.
Start taking pre-orders
Again, this strategy relates to the idea of starting early.
You don’t need to wait for your product to be in stock to start generating sales. Let your customers pre-order the product so you can secure profits right away.
Offering pre-orders has tons of benefits. One is collecting money early. But pre-ordering an item also gives your customers a sense of exclusivity.
It will give customers the illusion that they have something before anyone else does. They’ll be one of the first people to have the product in their hands.
Furthermore, if you take pre-orders, people may think there is a chance the product may sell out. If they don’t order it now, they may not have the chance to buy it on the official release date.
Pre-orders ensure your new product gets off to a strong start, which is better than it would do through the average product life cycle.
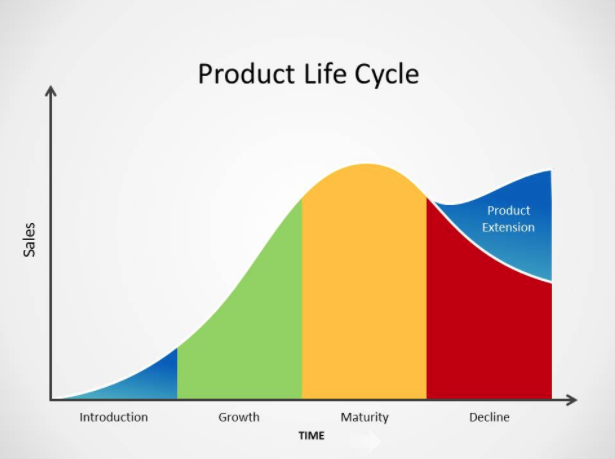
There’s no reason to have a slow introduction phase if you can avoid it.
In addition to wanting to be exclusive or have the product before anyone else, think of other reasons why a consumer may be interested in a pre-order.
Discounts.
Everyone loves getting a deal. Depending on your brand image and pricing strategy, you could potentially offer a discount to customers who pre-order the product to help drive sales.
Taking orders before release can also help you gauge your inventory. You’ll have a better idea of how much of the product you’ll need to have on hand for the initial release.
This is important information in terms of your production costs, and it will help you maximize your ROI.
Target your most loyal customers
Just because you’re releasing a new product doesn’t mean you need to find new customers.
Don’t get me wrong. New customers are great, and they are always welcome to buy. But you already have an existing clientele of people familiar with your brand and existing products. Those are the customers whom you should contact first.
Your email marketing list is a great place to start.
These are the customers who are so interested in your brand and products that they signed up to hear from you on a regular basis. So send emails before and after the product launches.
Here’s an example of an email sent out by Lululemon:
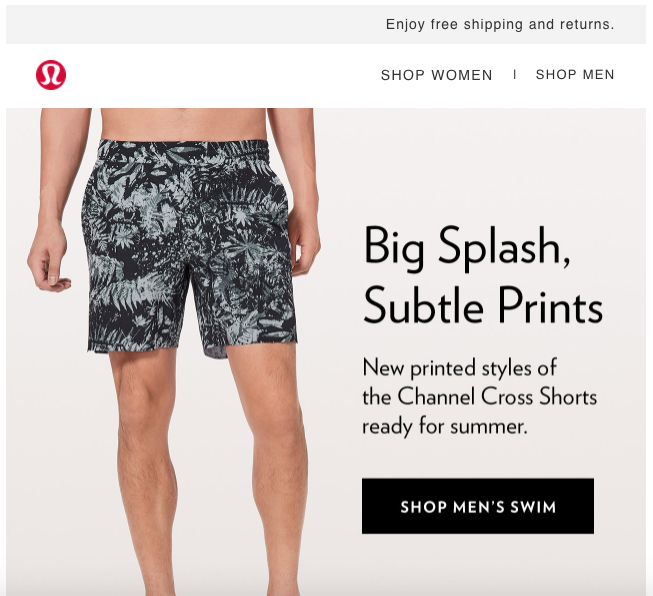
This email is promoting new colors of an existing product. So it makes sense the company is starting with its existing customers, who may already be familiar with this product.
Even if it was a new product, telling your email subscribers about it first is still a viable strategy.
It’s also worth noting that you have a 60-70% chance of selling to a current customer. But you only have a 5-20% chance of a new customer purchasing a product.
If sales are your goal, focusing on new customers won’t be as effective.
Research shows that it’s six or seven times more expensive to acquire a new customer than it is to market to an existing one.
When it comes to your ROI, marketing to your most loyal customers is the best bang for your buck.
Run a contest
Another way to generate sales for your new product is by giving it away.
I know what you’re thinking. This sounds counterproductive. How can you make money by giving something away?
You need to learn how to run a profitable giveaway. Contests will get people interested in what you’re selling. Rather than promoting it by saying “here is our new product,” put a unique spin on it by running a contest.
The cost to run a contest is relatively inexpensive as well. The only major expense is the cost of the item you’re giving away, plus maybe some additional shipping charges.
But the benefits will be worth it. In my opinion, social media platforms are the best places to set up your contests. Here’s why:
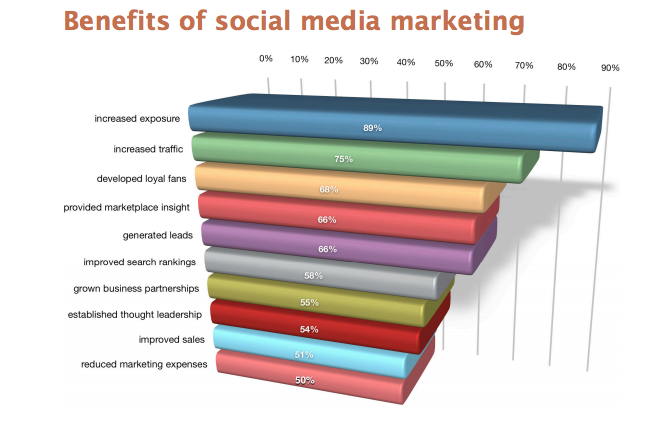
Running your contests on social media will expose your new product to a larger audience. As a result, it will help you generate more sales.
Here’s a hypothetical example to show you what I’m talking about. Let’s say you run a contest on Instagram. To enter, people need to post a picture to their personal Instagram profiles and include a relevant hashtag.
Let’s say 1,000 people enter your contest. That’s 1,000 photos of your brand just from one contest. Tons of people will see these pictures.
Of those 1,000 entries, you’re selecting only three winners. But there are still 997 people who want your product, plus who knows how many people who were exposed to it.
They’ve already built up excitement about using it. There is a good chance a large chunk of that group will still buy it.
As you can see, something as simple as giving away three items can generate hundreds or potentially thousands of sales.
Offer a discount
Typically, most brands don’t offer discounts for new items. When a new product gets released, they discount older items.
While I can understand the thinking behind this concept, it doesn’t necessarily mean it’s correct. People love to get a deal. Put your pride aside for a moment, and recognize that consumers are price sensitive. They’re also more intelligent than you think.
If they realize your new product will eventually go on sale, they have no reason to buy it right now. But by the time it goes on sale, they may have forgotten about it and lost interest.
While the product is fresh in the minds of the consumers, close the deal.
Mark down the price right away. If you want, use an age-old marketing trick. Jack up the initial retail price, then discount it making sure you can still profit.
Psychologically, it’s going to be tough for people to justify paying a full price for a product when they see cheaper items surrounding it on your site and in stores.
Blog about it
Use your blog to your advantage.
Start talking about the product in your posts before it gets released. Continue talking about it after the release as well.
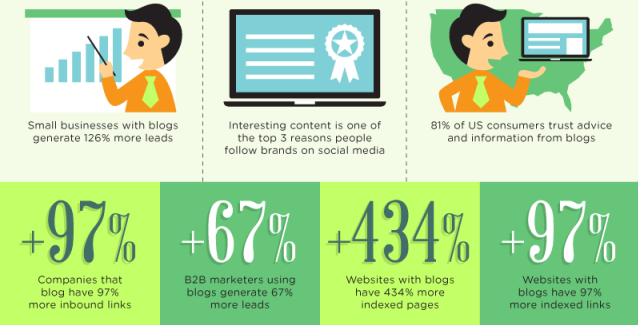
As you can see from these numbers, your blog can help you generate new leads. Consumers trust advice from blogs.
Sure, it’s obvious your readers will know your opinion is biased. They realize you won’t say anything bad about the products you want to sell.
But that shouldn’t stop you from writing about your new release. You can also reach out to other websites and try to get featured in guest posts.
Set up a link directly in the posts that brings the readers to the checkout page with the new product in their carts. Reducing the steps in the process increases the chances of driving sales.
Be innovative
If your new product is boring, is the same as your other items, or is already available from other retailers, people won’t be thrilled to buy it.
But if it’s unique, improves their lives, and enhances their customer service experience, they’ll be much more willing to spend their hard-earned cash.
Be creative.
Start by conducting the right market research.
What do your customers want? Give it to them.
Try to make drastic improvements to existing products that have problems. If your product is revolutionary, it will sell like crazy.
Highlight the new product on your website
Now that your product has launched and is available for purchase, don’t bury it on your website.
Showcase it on your homepage. Take a look at this example from the GAP website:
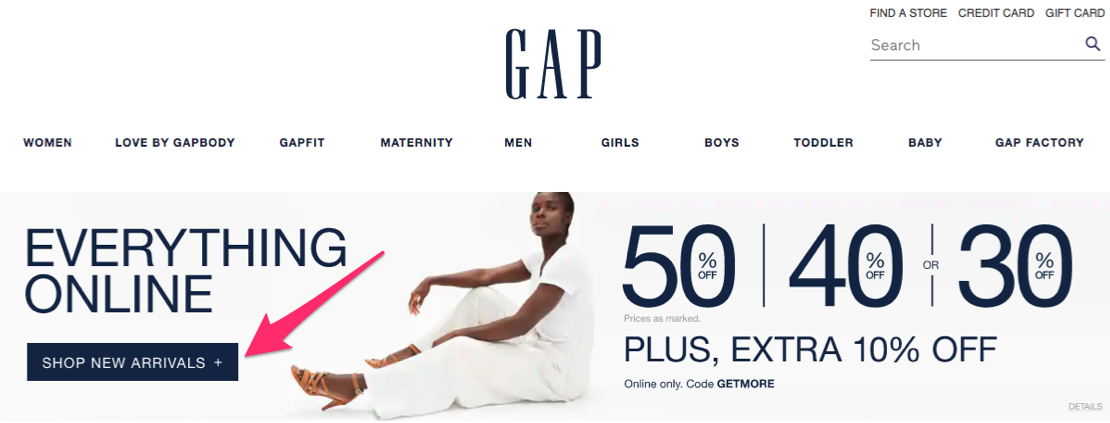
The new arrivals are the first thing featured on its homepage.
Do you notice anything else about this site? It also offers discounts on its new items, a strategy I’ve previously discussed.
You can feature your new product in other places of your website as well.
Let’s say your site has a search filter, which it should, so I’m assuming it does. When someone searches for something by name or by a category that fits the description of your new product, it should be the first item they see on the page.
If they have to navigate through pages and pages of results to find your new product, it will decrease the chances of them buying it.
Here’s a look at how Michael Kors sorts products on its ecommerce page:
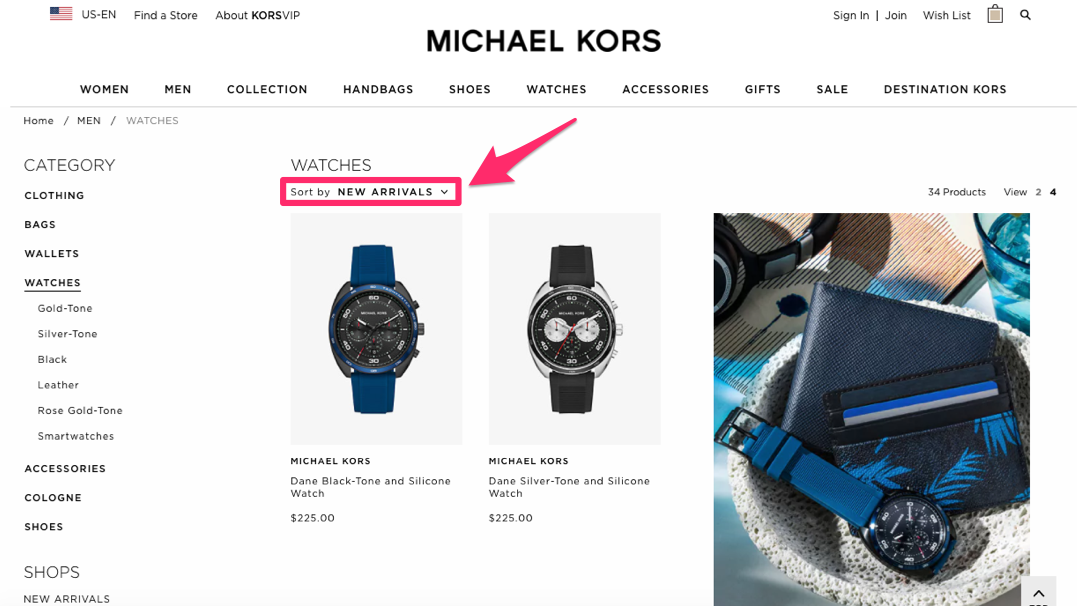
You can employ a similar strategy to increase the exposure of your new products.
This will help you generate more sales.
Timing is everything
Your new product might be great. However, if you release it at the wrong time, you won’t get lots of sales.
For example, let’s say you’re planning to release a product on a Thursday, which just happens to be July 3rd that year. You can’t just do that without taking things like that into consideration.
July 4th is obviously a national holiday celebrated by Americans. Lots of people will take July 3rd off work and enjoy a nice long weekend with family and friends.
They could be having a barbeque, traveling, or spending the day on the beach. They probably won’t have tons of time or incentive to buy something online.
Your opening weekend is going to be a dud. This won’t build much buzz around your product release.
On the flipside, if you were releasing a product that could be used on the 4th of July, such as American flag apparel, you’ve got to make sure the release date gives your customers enough time to get the item before they need it.
If they need it for the 4th, releasing it on the 3rd won’t get you sales either.
You should also keep seasons in mind as well. For example, nobody in New England is going to buy snow gear in the summer.
When it comes to proper timing, ecommerce brands can build hype for the holiday season. You’ll want to release your products when consumers are ready and willing to spend money.
Use video content as a promotion tool
Don’t just share pictures of your new product. You’ll want to give people as much information as possible about what they’re buying.
That’s why video promotions are a viable strategy. There are lots of ways in which you can accomplish this.
You can use commercial style promotions to showcase your product. This can be done before and after your product is released.
Once the new product is available for purchase on your site, include a video demonstration to show website visitors how it works.
Recognize what type of content your target market wants to see. Consumers would rather watch a video about a product than read about it.
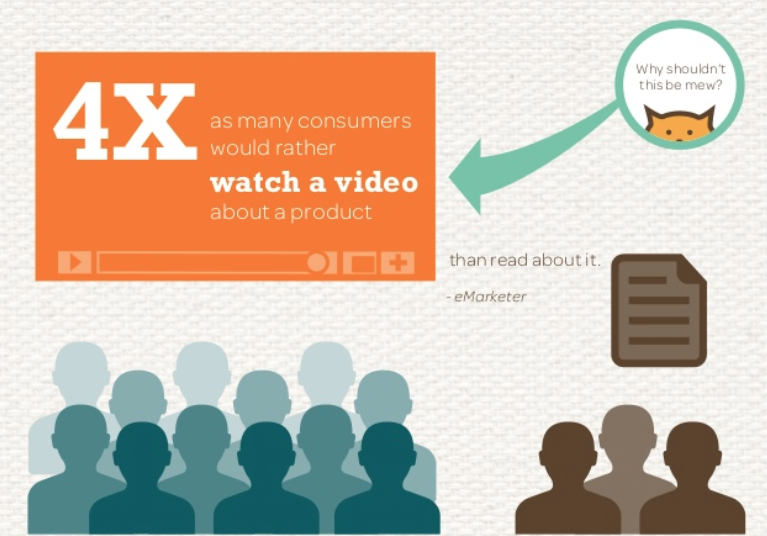
Furthermore, 90% of consumers say videos about products help them make buying decisions. Customers are 64% more likely to buy a product online if they’ve seen a video about it.
Share the videos on your website, social media platforms, marketing emails, and all your distribution channels.
Jump on the live video bandwagon. Showcase the product with live video streams as well.
These tactics will help you drive sales for your new product release.
Conclusion
Releasing a new product can be intimidating. You put so much effort into the release that you need to make sure everything goes smoothly.
If you don’t generate sales, your new product won’t turn a profit.
That’s why it’s important for you to start building hype for your product before it gets released. Take pre-orders, and start collecting money right away.
Rather than looking for new customers, promote the new release to your most loyal customers.
Come up with an innovative product. Run contests, and offer discounts as promotional methods. Talk about the new product in your blog posts.
Showcase the item on your website, and consider the timing of your release.
Create video advertisements, and share them on all your distribution channels.
If you follow the advice in this guide, your new product will generate sales and drive high profits as a result.
What marketing strategies are you using to drive sales for your newest products?


Source Quick Sprout https://ift.tt/2tbrEPV
The Snowball Effect of Retirement Savings
If there was one financial move that I executed well during my first few years of professional life, it was my decision to save heavily for retirement right off the bat. My first post-college employer offered a great retirement plan and offered robust matching and my mentor, whom I trusted deeply, told me I should go in there on the very first day and contribute enough to get every drop of that matching money, which I did. Thank goodness.
At first, the decision to contribute felt like a monumental one, one where I had total control over the situation. My total contribution was about 20% of my salary and that felt like a lot.
I started contributing right at the end of the recession of 2002 and, for the next six years, I contributed steadily to my retirement plans (across two different employers), receiving matching at both places.
In 2008, I stepped away from that career path and moved to my own, starting a Roth IRA and contributing to that without matching because I’d seen the power of those contributions.
Over the years, I’ve watched those initial contributions grow and shrink and grow again. I can’t add more to those accounts at this point, but I can certainly watch them grow like a terrarium inside of a glass bottle, and I’ve learned a few things along the way.
For starters, for most of the last several years, those investments have grown more each year than I ever contributed to them in a single year, without me putting a drop in there. I personally contributed between $5,000 and $7,000 a year to retirement in those early years and those accounts grew by more than $7,000 a year on their own most of the past several years. This is a function of the power of compound interest.
Another interesting note: I’ve contributed more to my Roth IRA than I ever did to those accounts, yet the balance of my Roth IRA is lower in total than those older accounts. This is, again, a function of the power of compound interest, and taken together, it should be clear to anyone that it makes a ton of financial sense to contribute as much as you can as early as you can to your retirement savings.
However, that’s not really what I’m writing about today.
As you progress down the road to retirement, the contributions you make have less and less of an impact and the ins and outs stock market has more and more of an impact.
Let’s say, for the sake of convenience, that you have an investment account that returns either 10% per year and -20% per year. You have five years of 10% returns and then a sixth year of -20% returns and then the cycle repeats itself.
You contribute $10,000 at the start of year one of this cycle, and that’s all.
At the end of year one, where you earn 10%, you’re left with a balance of $11,000.
At the end of year two, where you earn another 10%, you’re left with a balance of $12,100.
At the end of year three, where you earn another 10%, you’re left with a balance of $13,310.
At the end of year four, where you earn another 10%, you’re left with a balance of $14,641.
At the end of year five, where you earn another 10%, you’re left with a balance of $16,105.10.
At the end of year six, where you lose 20%, you’re left with a balance of $12,884.08.
As you can see, over those six years, you earned $2,884.08. You could have altered that return a little by contributing to a different investment – something that returned 7% a year every single year would have earned you $5,007 over that timeframe, for example. That’s a solid difference, but it’s not a huge one. The investment you choose will definitely make a difference early on, but the difference isn’t enormous. Your earnings difference over six years on that $10,000 initial investment will probably range by a thousand or two if you’re comparing similar investments.
Now, let’s look at a different example.
At the end of year one, where you earn 10%, you’re left with a balance of $11,000. You invest another $10,000 at this point, so your new contribution makes the balance go up 90.9%.
At the end of year two, where you earn another 10%, you’re left with a balance of $23,100. You invest another $10,000 at this point, so your new contribution makes the balance go up 43.3%.
At the end of year three, where you earn another 10%, you’re left with a balance of $36,410. You invest another $10,000 at this point, so your new contribution makes the balance go up 27.5%.
At the end of year four, where you earn another 10%, you’re left with a balance of $51,051. You invest another $10,000 at this point, so your new contribution makes the balance go up 19.6%.
At the end of year five, where you earn another 10%, you’re left with a balance of $67,156.10. You invest another $10,000 at this point, so your new contribution makes the balance go up 14.9%.
At the end of year six, where you lose 20%, you’re left with a balance of $61,724.88.
What’s the point of this illustration? Early on, your contributions make an enormous difference to your balance, but as time goes on, your contributions gradually become less and less important. After several years, most of the time the ins and outs of the stock market will have far more effect on your savings than your contributions. Your contributions have a smaller and smaller impact in terms of percentage, but the impact of the market stays the same in terms of percentage. Eventually, your contributions by percentage are substantially below the impact of the return on your investment.
In other words, once you’ve contributed for several years, your investments, if put into something reasonably aggressive, will start to grow so fast that in a typical year they’ll earn more on their own than you contribute. This gets more and more and more true over time, because as your investment grows, the annual returns grow.
What this feels like to me is pushing a snowball down a hill. At first, you have to really push and push and push a snowball around to make it sufficiently big, but there comes a point where that ball starts to have momentum on its own and it starts to roll on its own without you having to keep pushing it. You can keep pushing it, but you’re adding less and less and less force to that snowball rolling down the mountain and it’s picking up more and more and more steam on its own.
It’s at this point that making a good investment choice becomes increasingly important. When your balance on your account is $1,000, the difference between a 9% return and a 10% return is just $10. When the balance on your account is $100,000, that difference jumps to $1,000. Furthermore, that difference accelerates over time because that return is reinvested.
What’s the lesson here? The absolute most important thing you can do for your retirement savings is to just start contributing now. Don’t worry about choosing the perfect investment option. Just start contributing as soon as humanly possible. The earlier you start, the quicker you can get your retirement savings snowball big enough that it starts rolling down the mountain on its own momentum.
Later on, it will make sense to start looking more carefully at your investment options, not so much because a strategy change is in order, but to make sure you have your money in an option that charges low fees. I have every drop of my retirement savings in index funds for this purpose – they’re low fee investments that basically just match the overall stock market.
However, you don’t have to worry about that right now if you haven’t even started saving. The most important thing, by far, is that you get started right away. That’s far more important than what investment you choose. You can sit there blindfolded and choose one at random and as long as you eventually get around to figuring out which one you want in the next several years, you’re going to be in far better shape than waiting.
Start now. Start your snowball. Contribute something to retirement and start doing it consistently. Don’t worry about the specific investment that much, at least not right now. You’ll never regret this.
The post The Snowball Effect of Retirement Savings appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2I7oscR
Honey, They’re Shrinking the Sam’s Club in Texas. What’s Going on?
Sam’s Club will open a new location in the Lower Greenville neighborhood of Dallas later this year, the company said in a blog post last week.
“We’ll lean heavily into grocery and fresh food items, such as grab-and-go meals,” SamsClub.com CEO Jamie Iannone wrote. The store will also offer self-serve returns, same-day order pickup and Scan & Go checkout.
The store will also feature digital signage.
Why open a smaller store when parent company Walmart could simply open a new Express location or a Neighborhood Market?
It’s all about being a member. And that’ll cost you at least $45 per year.
The store will be restricted to Sam’s Club members, who will only need to traverse 32,000 square feet to fill their carts, instead of the chain’s typical 80,000-plus square feet.
At less than half of the club’s typical footprint, the store will likely feel more like a small grocery store, albeit with supersized containers of the items you might pick up regularly.
The new format seems like a play on the largely self-service Amazon Go store, right down to the membership requirement. And with grocery stores vying for customer loyalty, Sam’s Club may be hoping to snag customers for more frequent visits, not just the occasional stock-up trip.
A Sam’s Club representative said that the Lower Greenville store is the only one planned at this time.
Lisa Rowan (@lisatella) is a senior writer covering the retail and grocery industries.
This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.
source The Penny Hoarder https://ift.tt/2toihvI
The Cost of Dog Care is Extreme. Here’s How to Make it More Affordable
If you were my neighbor at the time, you might have even spotted me stripping down to nothing in my backyard at 3 a.m. to shake the fleas out of my sweatpants — but that’s another story.
As the proud parent to two dogs, together weighing 250 lbs., I’ll be the first to admit that pet ownership can be expensive. With vet bills, preventative care, quality food, grooming, toys and cleaning, the costs can make a huge dent in your budget.
To keep costs low, my partner, Nick, and I have gotten creative. Below are some of the ways we have saved money on pet care. While these all apply to raising dogs, I also have included some unique ideas I have found for parents of cats and birds.
DIY Flea Repellent
To keep our home flea free and our dogs safe from the threat of Lyme disease and other flea afflictions, we keep Greyson and our Great Dane, Clyde, on flea meds during the warmer months.
During the flea off-season, it is still important to keep our pooches safe. Rather than spend $30 per month to treat both of them, however, Nick and I create a milder flea repellent that does the trick during low-risk months.
The recipe we use includes water, lemons, lavender and witch hazel. And it makes the dogs smell amazing.
The author of this recipe uses it on her cat in the summer, but after battling fleas in my birthday suit, I still shell out the money for the strong stuff in peak season.
Homemade Dog Treats
Dog treats are great for training your dog, rewarding good behavior and feeding your pooch something extra just to see him get excited. But these treats, especially high-quality dog treats, can be expensive.
Nick and I invested in a food dehydrator for about $35 that has more than paid for itself with the amount of treats we make. The favorite in our house is dehydrated sweet potatoes, but you can find plenty of recipes online for other snacks ranging from chicken jerky to salmon jerky.
Don’t want to invest in a food dehydrator? Try one of these three recipes featured in The Penny Hoarder.
Cheaper Pet Food
For the longest time, Greyson was on Taste of the Wild, while Clyde went through giant bags of Blue Buffalo twice as fast. They are both big dogs with food allergies and sensitive stomachs, so finding the right food for them was a challenge — and a major expense.
But then we got our Costco membership. Costco’s Kirkland brand offers its own Nature’s Domain dog food at a much better price, and the ingredients were comparable to Clyde’s food and the same as Greyson’s.
A 30-lb. bag of Taste of the Wild Pacific Stream (salmon and sweet potato) cost us $50, but the bag of Nature’s Domain Salmon Meal and Sweet Potato ran us just $35. Even if we weren’t using our Costco membership for our groceries and paper products, the membership would more than pay for itself with the amount of food our dogs eat.
I swear by Costco’s dog food. Since switching, Clyde’s digestive problems have improved, and Greyson’s coat is much brighter and more colorful than it ever had been before. The fact that we save roughly $540 a year on dog food is an added benefit.
Bathing at Home
Grooming can be costly, especially for long-haired dogs. Even if your dog doesn’t need special grooming, regular baths are still important, (though the frequency will vary), to keep allergies at bay and skin healthy.
Unfortunately, Clyde is too big for a regular tub. If you own a large dog and can’t fathom how you will bathe him, Nick and I have a few ideas. The first is the more obvious: Buy a kiddie pool. If you have a backyard and a garden hose, fill up the pool, put on your swimsuit and hop in with your dog for bath time. We spent $15 on ours, and it has made baths much more manageable and saved us from having to seek professional grooming.
Our second solution is untested for now. Nick and I just bought our first home together. On our list of renovations in our unfinished, concrete basement is our very own dog-wash station. For the price of a small floor barrier, some piping and a detachable shower head, we will soon have a walk-in “bathroom” in which to wash both dogs without dirtying our shower or trying to find the warmest winter day for a backyard bath.
(A note: The second purchase will run about $75; if you do not intend to regularly bathe your dog and also to continue owning dogs your whole life, the investment may not be as financially sound.)
Durable Toys
Our dogs destroy most of the toys we find at the store within minutes. If your dog is particularly aggressive with toys, consider investing in high-quality, durable toys that may cost more but will last much longer.
The toys that hold up the best with our dogs have historically been Kongs, Nylabones and rope toys, which are great for tug-of-war. Rover.com includes a list of durable toys that are well worth the investment.
Nick and I also get creative with DIY toys at home, particularly when it comes to feeding and separation anxiety. Dogs can bloat from eating fast, so we often make a game out of mealtime using a muffin tin that forces Clyde to slow down.
To help with Greyson’s separation anxiety, we like to line a small bowl with a layer of peanut butter, mash in pieces of his food and then stick it in the freezer. When we leave, we put out this “busy bowl,” which takes a lot of time (and licking) to unfreeze and makes it a challenge for him to find the food.
Here are some more DIY dog toy ideas from The Penny Hoarder.
Boarding Costs
Nick and I love to travel, but it isn’t always easy when you have dogs at home. Even so, we have never paid for boarding — and never plan to.
Instead, we have developed strong relationships with several other dog parents. Some are friends, some are family and some are people we have met at the dog park.
Our rule for leaving our dog with caretakers for an extended time: We have to have had several opportunities to get to know the people and see how they take care of their own animals at home and how our dogs behave with them and their pets. We typically do a trial sleepover as well.
The relationships are mutually beneficial. When we leave our dogs with sitters (or invite the sitters to stay at our place with the dogs), we know that we will, in turn, be asked to watch their dogs — and we love to do it. It saves everyone money on boarding, it is much less stressful for the dogs and it is fun to get to play with extra dogs for a couple weeks each year.
Cleaning
Accidents happen. Whether it’s a muddy dog barreling past you at the back door or a dog on medication that makes it difficult to control bodily functions, there is a strong chance you will need to do some cleaning. Pet hair alone will transform the color of your carpet into something unsightly.
Because I have rented a fair share of apartments and houses — and lost an equally fair share of pet deposits due to stains that I didn’t properly treat right away — I have now invested in a carpet cleaner and a good vacuum.
The Spruce has identified top carpet cleaners for pet owners; Nick and I chose this BISSELL carpet cleaner. As a result, we got our last deposit back in full and intend to get the deposit back at the house we just vacated. A $180 investment has already helped us save more than $1,000 that we likely would have forfeited otherwise. But more importantly, our house feels fresher and cleaner, despite having two dirty dogs roaming freely.
Preventative measures — flea meds, high-quality food and regular exercise — will pay off long-term in vet bills you avoid. They also will ensure a better quality of life for your companion.
Greyson and Clyde have proved to be expensive (yet incredibly rewarding) additions to our family. We use the tips above, and pet insurance to help with vet bills, to keep costs manageable for our family — and it has made a world of difference.
Timothy Moore is an editor and freelance writer based in Ohio. He and his partner love to take their two dogs, Clyde and Greyson, for long hikes and swims in the lake. Clyde and Greyson mostly love to eat, sleep and sniff gross stuff.
This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.
source The Penny Hoarder https://ift.tt/2ljNxZ3
Should You Remodel or Move?
If you’re feeling like you’ve outgrown your current home, you might be considering a move. And with housing markets around the country heating up with the weather, it’s peak house hunting season.
But what if the idea of moving stresses you out? What if you like your yard and your neighborhood, but just not your house? In that case, you may want to consider an alternative option. Moving isn’t the only way to get a larger home or upgrade your living space, after all. You could also remodel what you have — a move that has become increasingly popular as housing prices continue to surge and available inventory remains surprisingly low.
Moving vs. Remodeling: Pros and Cons
Remodeling may not be as exciting as buying a new home, but it could be a more cost-effective move in the end. This is partly because moving itself is costly — as is selling your existing home.
But it’s also because home prices have been rising dramatically. Real estate data firm CoreLogic’s home-price index shows that, nationwide, housing prices were up 6.9% in April 2018 compared to the year before, and they’re expected to climb another 5.2% through May 2019.
Obviously, rising prices are a huge consideration for anyone considering moving. Sellers may receive a higher sales price for their home, but they’ll likely pay more when they go to take out a mortgage for a new property. Plus, there are other costs to be aware of. Surging sales prices can also mean higher prices for other essentials, such as homeowners insurance and property taxes. All of those expenses can and will add up over time.
Should you move, or should you remodel? Experts we spoke to say you should consider the pros and cons of both options before you take steps in either direction. Here are some of the advantages and disadvantages to consider:
Advantages of Moving:
- You can physically move your location. John Bodrozic of Home Zada says one of the biggest advantages of moving is the fact that you get to select a new location to call home. This can mean looking for a considerably larger or smaller home based on your preferences, but it can also mean choosing a better neighborhood or a lot in the country if that’s what you want. You could even move to an area with better schools, which is something you don’t get when you remodel your existing home.
- You don’t have to live in a construction zone. If remodeling your home would require an invasive project like a bathroom or kitchen remodel, moving could save you from dealing with the mess and the stress. A major kitchen overhaul could leave you without a place to prepare food for months, after all. This can be inconvenient and costly.
- You don’t have to deal with contractors. While remodeling your home could seem ideal, dealing with contractors is rarely stress-free. There are always hiccups when you remodel or build, and not everyone wants to deal with the drama or the expense.
- You can purchase a home that’s 100% turnkey. Earl Correll, president of Texas-based On Point Custom Homes, says that moving gives you the option to buy a home that’s been remodeled and upgraded to your specifications. If you buy a home that’s in great condition already, you can pack up your stuff and move right in after closing.
Disadvantages of Moving:
- You may not get exactly what you want. One major reason home prices have been rising is the lack of inventory – and that means you may not have a ton of options in your desired area. According to Correll, it’s pretty common to find homes that check off some of the boxes you want — but not all of them. “This means you’ll probably have to compromise on a few wish list items,” he says.
- You may have to leave an area you love. If you love your current neighborhood and can’t find something bigger in your area, leaving the area to get what you want can be a major disadvantage. You may love your new house, but what if you don’t love your new neighborhood or your child doesn’t like their new school?
- Buying a home and moving can be time-consuming and stressful. Bodrozic says that dealing with finding a new home, getting financing, and closing on the new home while selling your current home can be a huge hassle. Timing can be especially tricky with homes flying off the market in an average of 34 days — the fastest rate in years, according to Redfin.
- Moving is expensive. While you might find a “deal” on a new home that brings it within your price range, don’t forget the costs of selling your home and moving. You’ll likely need to pay around 5% to 6% of the sales price in real estate agent commissions when you sell your existing home. You may also have closing costs on both homes, moving costs, and the costs of upgrades (paint, new carpet, etc.) for your new home.
Advantages of Remodeling:
- You can plan a remodel to meet your exact specifications. Ethan Vickery of Triplemint Real Estate in Manhattan says that remodeling lets you choose exactly how everything is created and finished to suit your needs and tastes. This is a big contrast to selling your home and moving since your new home won’t be designed just for you.
- You may be able to use home equity to pay for the renovation. If you have a lot of home equity, a home equity loan or HELOC would allow you to use your home as collateral and borrow against its value to pay for the remodel. Borrowing against home equity can be less costly and less of a hassle than taking out a new home mortgage as well.
- If you love your neighborhood, you don’t have to move. Remodeling lets you stay where you’re at, which can be a huge advantage if you love the local schools, your neighborhood, or the area in general.
- You can avoid the costs of moving and selling your home. While remodeling isn’t cheap, you can avoid the realtor commissions, moving costs, and the money you’d likely spend getting your new home exactly how you want it.
Disadvantages of Remodeling:
- You’ll probably face some surprise expenses. Correll says it’s extremely common to run into unexpected issues during a remodeling project. “This is especially true if you are taking on a large-scale project that includes tearing down walls, moving plumbing, adding gas lines and so forth,” he says. Unfortunately, these surprise expenses can cause your remodeling budget to surge.
- Remodeling can be a pain. Bodrozic says that the home improvement process can be mentally tough, especially when you’re dealing with budgets, contracts, contractors, product selections, and potential delays. Depending on how intrusive the remodel is, you might have to live in a construction zone for months or even stay with family or in a hotel during the worst of it.
- You may not get your money back out of your remodel. While remodeling your home can be cost efficient, most remodeling projects cannot offer a 100% return on your money. According to the 2018 Cost vs. Value Study from Remodeling Magazine, a minor kitchen model brought an 81.1% return on average nationally last year — meaning a $20,000 kitchen remodel would only increase a home’s value by about $16,220. However, those who paid for a major kitchen remodel only recouped 59% of their costs during resale.
Other Issues to Think Through
In addition to the considerations above, there are financial implications that come with both choices. Bozrodic says you really have to run the numbers on how much equity you have in your current house, the price point of what a new house will cost, and whether either option will leave you better off financially.
It also makes a difference whether you got a great deal on your existing home or not. If you bought low and housing prices are currently high where you live, you may not want to start over with a bigger house and a bigger mortgage. You may have lots of equity in your current home, but you’ll deplete it if you sell and buy a home at a much higher sales price.
On the flip side, there are times when you don’t have much of a choice in terms of what to do. Vickery notes that remodeling isn’t always an option, since there are times when even a full remodeling project won’t address the biggest problems with your home. If you live in a condo, for example, you probably can’t just add a room for more space.
Finally, don’t forget that moving may have tax consequences that could be either good or bad. For that reason, it may be wise to consult your financial advisor or accountant to see how selling your home or moving could impact your bottom line.
Move or Stay Put? Here’s How to Decide
While there are no hard and fast rules to determine whether you should sell your home or stay put, realtor Don Cramer of Urban Nest Realty in Las Vegas says there are plenty of questions you can ask yourself that will help you decide.
For starters, you should ask yourself what your housing goals will be in the next five to 10 years. If you like your home and it works for your job and your family, then it can make sense to remodel and work with what you have. If you plan to move in a few years anyway, then you may want to consider staying where you are and not remodeling, on the other hand. Since it’s unlikely you’ll get all your money back out of a remodel when you sell, spending a ton of cash on a huge project may not make financial sense.
Also consider how your lifestyle will come into play — both today and tomorrow, says Cramer. Are the kids now out of college and starting families on their own? If they are or soon will be, you may not need a larger home at all and could benefit from a simple remodeling project to improve your home’s flow or make it more comfortable.
Also consider your finances. Moving can be extremely expensive, but so can remodeling. Before you choose either option, make sure you can truly afford it. Money you borrow will ultimately need to be paid back, so you should be prepared to pay for your dream home for the long haul.
Holly Johnson is an award-winning personal finance writer and the author of Zero Down Your Debt. Johnson shares her obsession with frugality, budgeting, and travel at ClubThrifty.com.
Related Stories:
- The Simple Dollar’s Home Loan Guide
- Why You Should Work On Your Credit (Even if You Never Plan to Buy a House)
- How Hiring a Housekeeper Saved My Sanity and My Marriage
- Five Things I Was Willing to Give Up to Save Money
Have you ever had to decide between remodeling and moving? What criteria did you consider? What did you decide to do in the end?
The post Should You Remodel or Move? appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2JYPEw9
Should I open a Lifetime Isa?

A reader asks if he should open a Lisa for a house purchase when he has little credit history

I am in my late 30s and don’t own my home. I am considering opening a Lifetime Isa (Lisa) before I turn 39 and using it to save and fund either my retirement or a house purchase. Am I taking a risk in putting money into a Lisa when there is no guarantee that I can get a mortgage?
I am concerned as I don’t have much credit history, having never had a credit card, and in recent years I’ve lived in a property where all utility bills were covered by my partner’s employer.
Initial diagnosis
Scott Gallacher, director of wealth manager Rowley Turton, believes your fi rst task should be checking your credit score through specialist companies such as Equifax or Experian.
You can quickly sign up with either company and download a free credit report to see exactly what information they hold on file about you.
Once you know what potential lenders will learn about your financial history, you can see if there are any mistakes or issues that may cause you problems.
Mr Gallacher says: Martin Bamford, managing director of financial planning fi rm Informed Choice, agrees your poor credit rating might negatively impact your ability to get a mortgage but suggests there are steps you can take to improve this in a relatively short period of time.
“The act of borrowing money and paying it back reliably is all it takes to build a credit history,” he says.
For example, applying for a credit card and store card to use for a few purchases and paying both back in full before any interest charges are applied will help your case in the future.
“You are also likely to have a credit history if you have owned a mobile phone on a contract basis,” he adds.
Treatment plan
However, regardless of the outcome of your credit history research, Mr Gallacher insists this shouldn’t deter you from putting money away.
“The key advantage of a Lisa is that it can be used for buying your first home or being available tax free from age 60 to help fund your retirement,” he says. “Consequently, even if you can’t get on the property ladder it will still be a helpful part of your long-term planning.”
Mr Bamford also concludes that it makes sense to open a Lisa before you reach the 40-yearsold age limit if a home purchase is a possibility.
“You can then continue to contribute through to your 50th birthday and receive the 25% government bonus on contributions each year up to £4,000,” he says.
Alternative treatment plan
However, there are other factors to consider before opening a Lisa. The risk you are concerned about refers to the withdrawal penalty, points out Danny Cox, a chartered financial planner at investment fi rm Hargreaves Lansdown.
“A Lisa receives an annual bonus of £1,000 for every £4,000 saved, but if withdrawals are made other than to buy a first house, or before age 60, a 25% penalty applies,” he says.
So, if you don’t buy a house, there is no risk from a withdrawal penalty as long as the Lisa savings are held until age 60.
That said, Mr Cox concludes: “In my view, it would be a good idea to open up a Lisa before age 39, using the minimum balance, so you have the option to save more later.” It’s also worth speaking to a mortgage adviser who can assess your situation, points out Alistair Cunningham, a chartered financial planner at Wingate Financial Planning.
“It is possible for two people to use a Lisa to buy together, so a joint mortgage might be possible,” he says.
Section
Free Tag
Related stories
Source Moneywise https://ift.tt/2lmfijP
الثلاثاء، 19 يونيو 2018
Best Homeowners Insurance Companies | Our Top Picks for This Year
Ah, dreams. It’s easy to forget we build them with some very real materials.
Take the dream of homeownership.
Your home could be the cornerstone of your financial future, a large asset whose value will grow as time passes.
Owning a home means you can:
- borrow against the home’s value for other needs.
- sell the property and use the profit to gain footing in more valuable property.
- rent it to someone else to earn income.
Or, you can just enjoy never paying rent to anyone for the rest of your life.
These dreams depend on the real materials — the bricks, wood, shingles, glass, aluminum, vinyl — that separate your home from the rest of the world.
Left alone, materials fall apart. They turn moldy, squeaky, rusty, weedy. As a homeowner, you battle against this reality to maximize your property’s value and keep your dream growing.
But if disaster strikes, all your years of loving, regular home maintenance cannot prevent major financial losses.
Be it lightning, wind damage, fire — or even a piece of a falling space station — you’d face expensive repairs or replacement costs which could jeopardize everything you’d worked for.
Which is precisely why getting the right homeowners insurance and knowing how and when to use it matters so much.
Table of Contents
If you have a mortgage, your lender will require you to buy homeowners insurance.
If you’ve paid off the mortgage and own your property outright, that’s all the more reason to protect your investment with the right homeowners policy.
First Things First: What Does Homeowners Insurance Cover?
Just like auto insurance, homeowners insurance comes as a package — it offers a variety of protections for various aspects of your property.
Your homeowners’ insurance should protect:
- Your dwelling, which is a term insurers use for your actual house.
- Other buildings on your property such as a detached garage or storage building.
- Your personal property such as furniture, electronics, and appliances.
- Your liability in case someone gets injured on your property.
- Your additional living expenses in case damage to your home requires you to move out for a while.
These protections seem straightforward enough at first glance, but when buying coverage, you’ll need to make sure you know exactly what your policy covers.
So let’s take a closer look at each area of coverage.
Your dwelling itself
Naturally, your homeowners policy will cover your house itself, along with attached structures such as a garage or attached tool shed. When you think of home insurance, this coverage may first come to mind.
A typical policy will pay to repair or replace your dwelling if it’s damaged or destroyed by common perils such as:
- Vandalism and theft
- Falling objects such as tree limbs
- Damage from aircraft or other artificial falling objects
- Wind damage
- Lightning strikes
- Damage from a volcanic eruption
- Fire and smoke
- Water damage from appliances (but probably not floods; more on this later)
- Being struck by a car
- Damage from civil disruptions such as a riot
- An explosion
- Damage from the weight of snow or ice.
If these sorts of mishaps damaged or destroyed your home, you could file a claim with your homeowners policy.
Depending on your coverage amount, your deductible, and other important policy details that we’ll get into below, your insurance company would help get you back on your feet again.
Other structures on your property
Your homeowners policy includes coverage for detached buildings on your property, too, such as:
- A detached garage
- A pool house
- A storage shed
- A detached apartment
- An in-ground pool
- Even a fence.
Generally speaking, your coverage for these structures will be set as a percentage of your dwelling coverage.
If you need more than that — say you have a detached apartment behind your home — check with your insurer about increasing that aspect of your coverage.
Personal property
Insurers consider stuff in your home that can be removed personal property, and your homeowners policy should protect these items, too.
It makes sense: If smoke or fire, for example, damaged your walls and roof, it would probably destroy some furniture and electronics, too.
Likewise, a thief who breaks a window probably won’t stop there. He’ll steal some of your stuff after gaining access to your home.
Of course, you’ll need to prove that you owned the personal property, so it’s important to have an up-to-date inventory.
We’ll get more into this later.
Liability coverage
If your neighborhood postal carrier steps in a sinkhole in your front yard and sprains her knee, you could be held personally responsible for the resulting medical care or lost wages.
The same could be true if someone tripped over a loose paver or stepped on a rake during your fall barbecue.
Yes, your yard and home most likely won’t be the scene of a blooper reel, but accidents do happen, and the resulting injuries and medical bills would not be funny.
Your homeowners liability coverage should protect you from this kind of unexpected expense.
Additional living expenses
If the worst happened and you couldn’t live in your home — either because it had been damaged or destroyed — you’d need some way to pay for somewhere else to live.
Your homeowners policy should address this through Additional Living Expenses (or ALE) coverage.
Structures, liability, personal property, additional living expenses — your homeowners policy has a lot of work to do. It’s essential to set it up so it can best protect your investment.
Medical expenses
Not all accidents result in a lawsuit. If a visitor were injured at your home and you wanted to make it right by paying the medical bills, some homeowners policies can help.
Most policies cap this kind of expense around $1,000, but you could opt for more coverage. Some insurers offer as much as $5,000 in coverage.
This coverage won’t pay for all kinds of medical expenses.
For example, if your friend caught the flu at your house and wanted your insurance to pay for the case of canned chicken soup he bought, that’s not going to happen.
It makes sense if you think about it from your insurer’s point of view: Could your friend really be certain she’d gotten the flu from your house?
Savers Beware: Scrimping on Homeowners Coverage Can Cost You!
Most of us like to save money and stretch our resources, especially on recurring expenses such as insurance.
A word of caution, though: Sacrificing homeowners coverage to ease the monthly budget can become very expensive in the long run.
If a tree limb fell through your kitchen, for example, and you didn’t have enough coverage to repair the roof, the wall, the windows, and the appliances — along with any water damage that may have also resulted — you’d need to pick up the tab after the insurance coverage stopped paying.
Talk about a budget buster!
And it could get worse: If it took two weeks to get your place up to code again, you may need to pay for a hotel or an apartment out of pocket if you didn’t have enough additional living expenses coverage in place.
This isn’t to say you should simply max out your coverage any more than you should jump at the lowest levels of coverage you can find.
Instead, you should take the smart and efficient approach: Determine your actual needs and build a coverage plan to maximize the coverages you need while spending less on coverages you won’t be relying on as much.
For example, if you live alone in a small condo with no yard and you seldom entertain guests, you might not need to max out your liability coverage.
If several of your neighbors have had break-ins, though, you may want to invest more in personal belongings coverage.
To save money while protecting your dream, customize your coverage so you’re not paying for what you don’t need.
Deductibles and Maximums: The Real Cost of Homeowners Coverage
You can also relieve some pressure on your monthly budget by opting for a higher homeowners insurance deductible.
A $2,000 deductible, for example, would give you access to premiums that are noticeably lower than a policy with a $500 deductible. Rates vary from state to state, so you’d need to get actual quotes to see how much you could save.
Before buying such a policy, though, give the decision some thought and make sure such a policy jibes with your lifestyle.
With a $2,000 deductible on property damage insurance, you’d be responsible for the first $2,000 in repairs to your home. Which is fine if you can come up with that $2,000.
If you know you couldn’t come up with the deductible, though, you may want to pay a higher premium in exchange for a lower deductible.
Meeting your deductible unlocks the coverage that your monthly premiums pay for, so if you can’t meet your deductible, your homeowners policy won’t be as useful as you seek to protect your dream.
On the other end of the spectrum, you can also save money with a policy that places a lower cap on payouts when you file a claim.
You can save a lot in premiums this way, but once again, be careful. Limiting how much your coverage will pay could put your home, and even your other property, at risk.
If you have only $50,000 in liability coverage, for example, and you own assets worth $100,000, you’d be leaving your assets unprotected.
If someone was injured in your yard and successfully sued you for damages, the court could order your other assets sold to pay for what your insurance won’t cover.
Nobody expects terrible things to happen to their property.
But bad things do happen — injuries, accidents, fires, dangerous weather.
Get a policy durable enough to help you weather the storm if the unexpected happens.
How Do You SAVE Money On Homeowners Coverage?
So far we’ve talked about how not to save money on homeowners insurance:
- Don’t opt for a higher deductible unless you can come up with the deductible.
- Don’t limit your coverage if it exposes your assets or can’t protect your investment.
Enough with the don’ts. Let’s get into how you can save on your coverage.
Compare quotes
The Internet has made home insurance shopping — like so much else — so much easier.
Just enter your information in a quote form, like the ones you’ll find on this page — and you’ll immediately get an idea what you’d pay for coverage from a variety of insurers.
Insurance rates vary from state to state, so be sure you’re putting in your ZIP code and other required information.
And keep in mind: a quote is only as good as the information you provide the insurer.
If it turns out your home is worth $50,000 more than you thought you may need more coverage than you thought and you’ll need new quotes.
If you’re not a huge fan of shopping online, find an independent insurance agent near you — one who will help you compare quotes from a variety of insurers.
An independent agent can also guide you through the nuances of homeowners policies.
Look for discounts
Chances are you already have another kind of insurance — auto, life, etc. If you’re happy with the company you’ve been dealing with, and if your existing insurer offers homeowners coverage, you may qualify for a multiple policy discount.
Lots of insurers give their best rates to existing customers.
Multiple policy discounts aren’t the only way to save. See if your employer or professional organization offers discounts on insurance.
And check with your insurer about whether installing a security system or completing certain kinds of renovations may save you some money on premiums.
Many insurers offer discounts for:
- Not smoking
- Getting a new roof
- Paying the policy up front in full
- Having a backup power generator
- Having a new (or newer) home.
Every insurance company has a different approach, so don’t expect to find each of these at every company.
Think twice before filing a claim
Yes, you pay insurance premiums so your policy will be there when you need it. But if you file too many claims, your insurer may increase your premiums.
It sounds counterproductive, but it’s still the reality: frequent fliers in the claims department often pay higher rates.
Changing insurance companies likely won’t protect you from this reality. If you move to another state and need a different insurer, the new company may access your claims history with your old company and charge higher premiums.
Let’s be clear: If you really need help from your insurance company, by all means, file a claim.
For example, if you have thousands of dollars worth of damage to your roof because of an ice storm, you’ll want to use your policy.
Or if someone breaks in and steals $10,000 worth of furniture, technology, or appliances, use your policy.
But if your washing machine leaks and you need to replace some floor tiles, consider paying that out of pocket.
Get coverage that’s just right
If you needed a new pickup truck and never hauled anything more than your recycling or an occasional sofa for a friend, a mid-size pickup would probably do the job.
You probably wouldn’t go shopping for moving vans or tractor-trailers.
Yet that’s what happens sometimes with insurance. Shoppers opt for more coverage than they need which means they pay more than they need to.
For example, if your home could be re-built for $175,000, you might not need $350,000 in coverage for your dwelling. If you have $75,000 in assets, $200,000 in liability coverage may be more than you need.
We mentioned this above, but it bears repeating: To find great coverage at a great price, go through your policy section by section and figure out whether each kind of coverage adequately protects your investment without over-protecting it.
Think of it like a new raincoat.
You won’t stay dry in a coat three sizes too small. But if it’s three sizes too large, you can create a new set of problems.
How Do You Know How Much Coverage You Really Need?
Pickup trucks and raincoats are one thing. It’s easy to find the right sizes when you’re shopping for durable products.
Insurance is different, though, right? It’s abstract and invisible. It’s just numbers with some probably’s and maybe’s mixed in.
Yes, abstractions and variables come with the territory, but you can still determine an ideal coverage amount.
You’ll just need to interject some reality into all the hypotheticals.
Let’s go through each component of a homeowners policy to explore this question some more.
Dwelling coverage
At first, this question seems simple enough. You need enough coverage to fix or replace your home in case a fire or a tornado, or some other unforeseen disaster destroys it.
But how much money would that actually take? How can you find out?
Your local real estate market can give you an idea. So can your local tax assessor’s office. Your mortgage company may have yet another number in mind.
You can get your home’s value from any of those sources, but keep in mind:
- Realtors base your assessment on comparable recent home sales in your area which may not reflect some of the nuances of your property.
- The tax assessor’s office calculates the value based on a formula so it can levy property taxes.
- Your mortgage company calculates a home’s value to avoid lending more money than the house could likely sell for.
In other words, all of these assessments have their own goals which may or may not be aligned with your goal.
So, the first question to ask yourself is this: What would be my goal if my home were destroyed?
If you wanted only to pay off your mortgage, a policy the size of your mortgage debt would suffice, and this plan would keep your lender happy.
However, this approach will not protect your investment, only your lender’s. If your policy pays only your lender, you’d be losing the equity you’d built up in the home, not to mention all the sweat equity and all the possibilities you’d dreamed of.
To protect you and your mortgage company, you’ll need a policy strong enough to rebuild your home if it were destroyed.
Your rebuilding costs would depend a lot on where you live. Construction costs vary widely from state to state since they depend on local labor and material costs, weather conditions, and local building codes.
On average, Home Advisor estimates a cost of $150 per square foot. At that rate, a 2,000-square-foot home would cost about $300,000 to build. You’d spend a lot more for custom features or a lot less if you’re building a modular home.
You can get a general idea about your local costs using a site like this one.
It’s up to you to make these decisions and get homeowners dwelling coverage that will protect your future if tragedy rears its ugly head.
After a disaster is not the time to find out you didn’t have adequate coverage.
Detached structures coverage
A standard homeowners policy will provide coverage for detached structures such as your garage, pool house, gazebo, and other non-business related buildings.
Usually, your coverage for these structures adds up to 10 percent of the coverage on your dwelling.
If you have $300,000 in coverage for your house, for example, you’d have $30,000 in coverage for detached buildings.
If you need more than this standard level of coverage, ask your insurance company about boosting this part of your policy. A lot of insurance companies call this Coverage B.
However, if you use a detached building as an office or a pottery store or a farmers market, consider getting a separate, business policy. Your homeowners policy won’t be built to protect your business, especially when it comes to liability coverage as customers come and go.
Personal property coverage
Insurers tend to calculate this part of your coverage — which covers your personal belongings such as electronics, appliances, furniture, books, musical instruments, etc. — as a percentage of your dwelling coverage.
Standard policies usually set this coverage between 20- and 50-percent of your dwelling coverage.
You may want to lean toward the higher end of the coverage scale if you buy top-of-the-line appliances or electronics which would cost more to replace.
You can save money on premiums by lowering this coverage some if you don’t own as many valuable items.
Personal belongings coverage provides some of the most versatile protection in the insurance industry. It can even protect your stuff when it’s outside your home.
Still, the coverage has some limits that you’ll want to know about:
- Jewelry: Most policies cap payouts on stolen or damaged jewelry, so if you have a lot of expensive, irreplaceable jewelry in your home, ask an agent about additional or separate coverage to protect it.
- Collectibles: Standard coverage will also put a limit on payouts for collectible items such as rare figurines or baseball cards or a bottle of Cheval Blanc 1947 worth $135,000 or so. You’d need to address this coverage separately.
- Named vs. Open Peril: Some policies pay on claims resulting from perils specifically named in the policy; others take the opposite approach, covering all risks not excluded in the policy. This sounds like petty semantics, but you’d discover its importance when filing a claim.
Create an inventory of your stuff
Making an inventory of your personal belongings takes time and attention to detail.
But if someone broke in and stole your computers, appliances, or stereo and TV, an inventory would make it easier for your insurance company to pay your claim. The inventory may also make it easier for police to find your belongings.
You can create an inventory in several ways. Many people still take the pencil-and-paper approach, writing down serial numbers and model numbers for their valuables. Be sure to take pictures, too.
Keep the inventory in a safe place — a fire-proof safe, a safety deposit box at your bank, or at least in a locked file cabinet or desk drawer at your office.
Sound too complicated? Now you can find smartphone apps that make the process easier. Apps can store photos, serial numbers, and descriptions on the cloud so your data won’t evaporate if the worst happens.
Liability coverage
Liability coverage protects you financially if a visitor gets injured on your property. It’s one of the more hypothetical aspects of your homeowners coverage, which makes it harder to gauge how much coverage to buy.
Anyone who’s been in a hospital and opened the bill knows you can rack up a five-figure balance in a hurry if an accident at your home required hospitalization.
Then, consider the legal fees if you get sued. Assuming a judge finds you liable, you’d be paying the plaintiff’s legal fees as well as your own.
A standard policy usually offers up to $100,000 in liability coverage, but you can increase that amount.
Should you?
Here’s a good rule of thumb: Get enough liability coverage to match your personal assets.
Let’s say, for example, you have $150,000 worth of assets — whether it’s in the form of money in the bank, property you own, or investments is up to your imagination.
Let’s also say your dog is having a bad day. He bites your neighbor who came to the door to borrow a couple eggs.
If that weren’t bad enough, the bite gets infected and your neighbor spends a night in the hospital, then has a bad reaction to an antibiotic and has to be hospitalized again.
A couple of weeks later you get served papers. Your neighbor is seeking lost wages, medical bills, legal expenses, compensation for pain and suffering. You get the idea.
If your personal assets valued at $150,000 exceed your liability coverage of $100,000 this whole experience could cost you a third of your net worth.
Sure, this scenario doesn’t happen everyday, but life is not always predictable. You’ve probably worked hard for what you’ve earned. Insurance provides an efficient way to protect it, but only if you have the right amount.
Had success? Consider an umbrella
If you’ve done well with earning and saving and your personal wealth exceeds the limits of your homeowners liability coverage, consider an umbrella policy.
Such a policy could provide extra liability coverage for your home and auto liability policies.
Additional living expenses coverage
Insurers also like to calculate additional living expenses (ALE) as a percentage of your dwelling or personal belongings coverage.
This coverage can help pay you back if you can’t live in your home because of an insured peril and you need to pay rent somewhere else for a while.
When you’re shopping for homeowners coverage, find out how the insurer you’re considering calculates this coverage.
Usually, your insurance company will want to make sure your temporary housing is comparable to your normal living conditions. If you live in a 3-bedroom ranch in the suburbs, for example, don’t expect your insurance company to put you up in a penthouse downtown.
However, you can submit receipts from restaurants or department stores to your insurance company as long as the expenses relate directly to your displacement from your home.
If you’re in a position to need your ALE coverage, you’d likely have an insurance adjuster available to answer specific questions about your reimbursements.
Some Important Either/Ors Within Your Homeowners Policy
Insurance policies include lots of fine print. It can be tempting to skip right past some of the details.
This approach may be fine when you’re agreeing to the newest iTunes terms of use, but when you’re protecting an asset as valuable as your home, reading the details is time well spent.
Some of the linguistic distinctions contained in your policy may determine when certain aspects of your coverage apply or even whether the disaster you’ve just experienced is even covered.
It’s no fun to learn about these distinctions while filing a claim:
Replacement Value vs. Cash Value
If you filed a successful claim, your policy would pay out either the cash value or the replacement value of your personal property.
- Replacement value: With this kind of coverage, also known as market value, your insurer would compensate you the amount you’d need to replace your property.
- Cash value: With this coverage, the insurer would consider whether your property had depreciated and pay an amount that reflects the change in value.
Not a huge deal, right? Let’s consider a real-life example to see how this rule applies.
If you bought a 55-inch TV five years ago, for example, and someone broke in and stole it, a replacement value policy could pay for a new 55-inch TV.
A cash value policy would reimburse you the value of a 5-year-old TV, which may or may not be enough to buy a new model.
If it were just the TV, this distinction may not matter as much. However, if it’s all of your personal property — or your structure itself — the problem would grow exponentially.
Generally speaking, replacement value policies cost more and provide more value to you, the insured, than cash value policies.
Even if you have replacement value coverage, expect some give and take with your insurance adjuster after a covered disaster.
Many companies pay cash value first, then, after you’ve replaced your property, they will reimburse you the remainder of the replacement value.
To make things as simple as possible, keep an inventory of your items and keep receipts, especially for big-ticket items such as appliances and electronics.
It’s much harder to determine the exact replacement cost for an entire home if yours were destroyed by a hurricane or a fire.
For this reason, some insurers still use what’s called the 80/20 rule: If your coverage amount would pay for at least 80 percent of the rebuilding cost, the insurance company will cover the remaining costs.
Ironically, it’s also possible this distinction wouldn’t matter as much if you lost your entire home. It matters if you want to rebuild just where you left off.
But, after a total loss, you may also decide to invest the insurance payout somewhere else or to build a new place that suits your current needs.
Named peril vs. Open peril
This important distinction can have a direct impact on whether the disaster that destroyed or damaged your home qualifies for insurance coverage.
- Named peril policies cover only damage from the perils listed in your policy.
- Open peril policies cover all damages unless from perils specifically excluded in the policy.
Typically, a named peril policy costs less because it’s up to the insured to prove damages resulted from a covered peril.
Open peril — also known as all risk — policies cost more because they can potentially cover a wider range of damages.
Open peril policies do not cover everything, though. They typically exclude damages from perils such as:
- War
- Nuclear disaster
- Pollution
- Government seizure
- Earthquakes or floods.
This means you’d likely need additional insurance policies to cover those sorts of damages or to ask your insurer to add riders or floaters to your policy that would also add more cost to your premiums.
If you live in a flood-prone area, you’ll need flood insurance separate from your homeowners policy. Floods can cause an incredible amount of damage to your property and your belongings.
Here’s a great place to start if you need flood coverage.
Products that don’t protect your home
The insurance marketplace includes a wide variety of products, and a new homeowner can get a little confused about what kind of insurance they actually have.
For example, if you have a new mortgage, your lender may require you to buy private mortgage insurance, also called PMI. This coverage has nothing to do with protecting your property.
Instead, it simply protects your lender from losses if you were to stop paying on the loan.
As a new homeowner you’ll probably get lots of offers for mortgage life insurance. This is another product that will not protect your actual property from losses.
Instead, it could pay off your loan if you died. Maybe that’s something you’d like to consider, but just know it won’t repair or replace your property after a disaster.
Our Favorite Homeowners Insurance Companies for 2018
Now that you know so much about building a homeowners policy that meets your specific needs, we can point out some insurers who do a great job putting all these pieces together.
Homeowners insurance has a local flare. Not all companies operate in all markets.
If one of the following companies protects property in your area, though, we’d recommend giving it a close look.
One more thing — any list of insurance companies will inevitably leave off some great companies, and this one’s no different. It isn’t all-inclusive, just some of our favorites.
Travelers
 We feel like you can’t go wrong with 160 years of consistency in a business as volatile as insurance.
Based in New York City, Travelers writes policies throughout the nation, which is an important factor with a homeowners policy.
With customers throughout the nation, a company can more easily absorb disasters such as hurricanes that create a large volume of claims in a short period of time.
The independent insurance rating agencies such as A.M. Best and Moody’s also like Travelers, giving it consistently high marks for stability.
Amica
 Amica doesn’t have the name recognition of some of our other favorites, but it keeps moving up the list because customers have so many positive things to say:
- Great customer service.
- Flexibility when you need to change coverage.
- Transparency in billing.
Like any insurance company, Amica gets some negative reviews. But unlike most, it responds to each one, seeking to resolve the customer’s issue.
Amica gets high marks for its financial stability, too. They may not do much when it comes to national advertising and brand management, but people throughout the country continue to hear about this century-old firm.
Liberty Mutual
 Liberty Mutual also has more than a century of service nationally. With 7 percent of the national homeowners insurance market, Liberty Mutual offers stability, durability, and lots of experience.
The independent ratings agencies give the company high marks for financial health. We like the company’s mobile apps and online customer experience.
When a company can offer stability and up-to-date ways to access and change your coverage, we think it’s worth a closer look.
U.S.A.A.
 Unless you’re on active duty, a veteran, or the family member of a military member or veteran, you won’t have access to U.S.A.A.’s rates and customer service.
But if you are already a U.S.A.A. member, you can find some of the best homeowners insurance and customer service on the market. Even with its limited pool of potential customers, we think highly enough of these guys to list them here.
Standard & Poor’s and A.M. Best think so, too, giving U.S.A.A. their highest ratings for financial stability.
Progressive
 In business since 1937, Progressive isn’t exactly new in the neighborhood. But it has grown steadily in reputation and market share in recent decades.
We like Progressive because it’s easy to access customer service representatives online or by phone if you prefer.
And, it goes without saying, the company has some of the highest grades from the independent agencies.
If you live in one of the 19 states Progressive serves, it’s worth a look.
Allied
 Allied Insurance, part of the Nationwide Insurance family, offers solid, flexible coverage at competitive rates.
If you prefer getting answers to questions by telephone, you’ll appreciate Allied’s approach to customer service.
Since policies are backed by Nationwide, which has nine decades of experience, Allied is a reliable and stable partner.
If you’re already a Nationwide customer, ask about multi-policy discounts and claim-free discounts.
Farmers
 Maybe you’re starting to see the trend. Companies with stable coverage and solid customer service continue to do well in the market and on our list.
Farmers is another nationwide company that fits the mold. Based in California, Farmers has been tested, and it continues to excel.
We’re particularly attracted to the discounts you can get by having newer safety features on your home or by living in a newly constructed home, which usually comes with up-to-date safety features.
Hippo
 All this talk about customer service and new approaches to coverage brings Hippo to mind. This start-up does business in California and Arizona, and we hope it’ll continue expanding.
Hippo excels at giving customers plain language and lots of access to information. Whether by text, online chat, or the ordinary Internet, Hippo customers can quickly and easily get help when they need it.
The company has been in business since 2015, so if you’re looking for a long history of stability, you won’t find it.
However, the company isn’t totally untested. Its coverage is underwritten by companies like TOPA, which has done well in California since 1981.
Eerie Home
 Eerie Home Insurance excels at customer service, and its coverage is strong, too.
With one of the lowest customer complaint ratios and an A+ rating from the Better Business Bureau, Eerie has the makings of a great homeowners insurance partner if you live in an area it serves.
A.M. Best gives Eerie an A+, one of its highest marks, for financial stability, too.
National General
 You know by now that a company wouldn’t be on this list without having earned great marks for customer service and quality of coverage.
That’s true for National General, but some other things caught our eye, too.
National General excels at helping policyholders who have experienced a total loss replace the value of their investment even if their coverage wasn’t quite up to the task.
Additionally, the company seeks to rebuild properties with more sustainable, environmentally friendly materials which can reduce the cost of energy and maintenance going forward.
Some More Terms And Types To Know
As you close in on the right policy, you’ll come across some terms and codes — insurance-speak, so to speak. Here’s a glossary to help as you come across some of these terms:
HO-1: A basic homeowners policy that protects you from named perils but does not cover you against perils not named in the policy. Perils included in a HO-1 policy include:
- fire and lightning
- windstorms and hail
- explosions
- riots and civil commotion
- aircraft
- vehicles
- smoke
- vandalism
- theft
- glass (if it’s part of the home)
- volcanic eruptions.
HO-2: Another named-peril policy that includes everything in the HO-1 but also adds:
- damage from falling objects
- water damage from an accidental overflow of plumbing, HVAC or appliances
HO-3: This is one of the most common policies because it covers a broad range of perils. It does not cover earthquakes, floods, nuclear accidents, sinkholes, or landslides/mudslides. Just because a policy protects your dwelling from these perils doesn’t mean it will cover your personal belongings from the same perils. Check on this distinction before buying your coverage.
HO-4: Renters coverage.
HO-5: This coverage is very similar to HO-3. It’s more likely to cover your belongings from the same perils that apply to your dwelling coverage.
HO-6: Specially designed coverage for condo or co-op owners who need some dwelling coverage but whose personal property coverage takes precedence.
HO-8: This is particularly useful when covering a historic home whose cash value is significantly less than its replacement value. A home that’s too old to qualify for an HO-3 policy may benefit from an HO-8 form.
Taming The Perils Keeps Your Dream Growing
There’s a reason homeownership and the American Dream are intertwined.
Owning your own home means you have a little slice of the country to call your own.
Keeping your property updated and looking great can add to your independence and personal wealth as the years go by.
Like any potential for reward, home ownership brings the potential for risk. Insurers call these risks perils.
Just remember: There’s no need to face all the perils alone. That’s why homeowners insurance exists.
We’d like to help.
We’ve worked with insurance companies for years and can help you find solid coverage, great rates, and ways to navigate the confusion. You can start by filling out the quote box on this page.
Whether it’s a new purchase or an ongoing labor of love, finding the right homeowners coverage means you can focus on what matters most: improving and enjoying your property.
The post Best Homeowners Insurance Companies | Our Top Picks for This Year appeared first on Good Financial Cents.


Source Good Financial Cents https://ift.tt/2taxIrU