

الجمعة، 3 أغسطس 2018

These Insider Inc. Internships Could Help You Launch Your Writing Career
This may be your chance to get your foot inside the door.
Insider Inc., a digital media website based in New York City, has internships across all of its platforms.
You could be the next lifestyle intern and write about celebrities, select the “deal of the day” as the Insider Picks commerce intern or be the video writing intern about pets.
What You Need to Know About Insider Internships
Pay
Less than half of the internships list “paid” in their job description.
However, the opportunities listed as paid include food and travel writing intern, finance editorial intern, social media intern and sports editorial internship.
Keep in mind that you do have rights and unpaid internships may be illegal.
Location
It’s the Big Apple or bust for all but two of these internships.
You can skip the skyscrapers and opt for the California coast instead as a tech editorial intern in San Francisco or as an evening news intern in Los Angeles.
Commitment
The majority of the internships run for six months with a preferred 40-hour workweek commitment.
Start and end dates are not specified.
Deadline to Apply
No deadlines are listed. But as with anything, the sooner the better. So if you’re interested, apply now.
Skills
Unlike some entry-level internships, most of these opportunities require experience, degrees and specific skills.
Prior experience and knowledge of the beat, as well as a strong portfolio will boost your application.
Opportunity
Insider Inc. says many of its writers and editors started out as interns, so this could really be your big break.
Get ready to hustle and be a cog that turns the media machine.
These gigs are fast-paced, and interns don’t get coffee, file or make copies. Instead, they’re expected to collaborate, generate content and get their hands dirty in meaningful work, according to the postings.
Tips When Applying for Internships
The best way to get an internship is to give potential employers everything they need up front.
Make sure your resume includes all relevant work experience and always include a cover letter.
During my interview at The Penny Hoarder, I was told my quirky cover letter piqued the editor’s interest. Cover letters will get you everywhere, so do not skip them.
Any story or blog links and portfolios of your relevant work give you credibility and help you stand out.
Include references, as some employers go full steam ahead and may contact references before they even call you.
Read the job description carefully and include every requested detail.
Remember, applying for an internship can’t hurt and if you don’t get it this time, you can always try again.
Stephanie Bolling is a staff writer at The Penny Hoarder. She prefers the Sunshine State to the Big Apple.
This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.
source The Penny Hoarder https://ift.tt/2LSCdmw
How to Design a Checkout Process That Generates High Conversion Rates
Ecommerce websites live and die by their conversions.
For those of you who have a high volume of traffic to your website, that’s great news. But traffic alone doesn’t generate sales.
Is your website traffic translating to conversions?
There are certain metrics you can use to measure this. Look at your bounce rates. Analyze your shopping cart abandonment rates.
If your website visitors aren’t converting, your ecommerce site won’t make money.
Don’t get me wrong: the products you’re selling might be amazing. That’s not necessarily the issue here.
The design of your website and the checkout process might be what’s hurting you.
For the most part, simple website designs have higher conversion rates. This same concept needs to be applied to your checkout process.
The information in this guide will help you identify any flaws with your checkout procedure that could be hindering your conversions.
If you have just launched a startup company and are in the process of designing your website for the first time, these useful tips and best practices will help you as well.
Here’s what you need to do to design a checkout process that converts.
Add multiple checkout buttons
For website visitors to make a purchase, they need to be able to navigate to your checkout page.
Once someone decides to buy, they’ll add the items they want to their shopping cart. In a perfect world, you want them to continue shopping so they spend more money.
But if the checkout buttons aren’t clearly labeled, the customer may ultimately leave the items in the cart without buying them.
This could be why your shopping cart abandonment rates are so high. Instead, include checkout buttons on both the top and bottom of the screen.
Check out this example from the Champs Sports website:
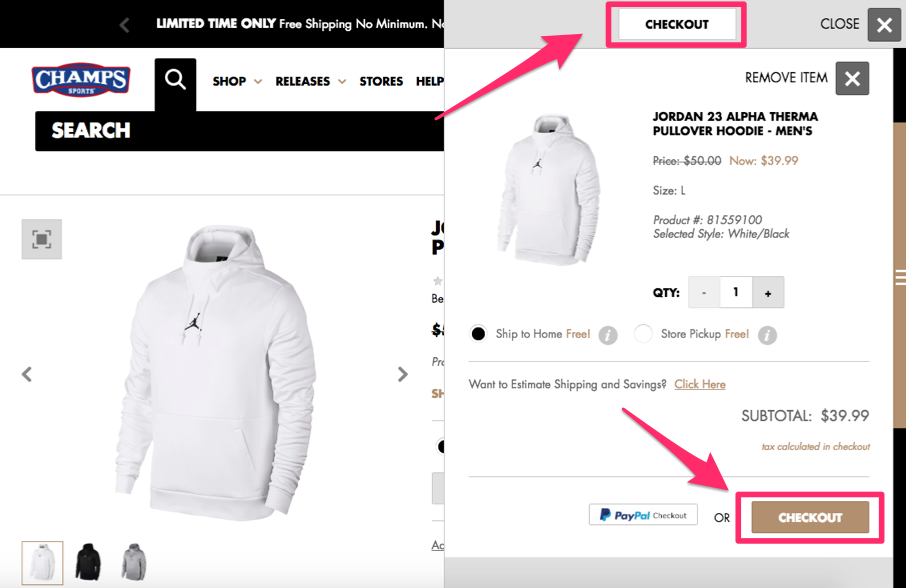
Positioning the checkout buttons in two places ensures the visitor will see and have access to both buttons.
The word “checkout” will stay in their line of vision, regardless of where they’re looking on the screen.
I also want you to notice that the location of the shopping cart on the right side of the screen allows the customer to continue shopping on the left.
This increases the likelihood that the average order amount will be higher and conversion rates remain high as well.
You can implement the same strategy on your ecommerce page to drive sales.
Secure the checkout process
Security needs to be a top priority for your ecommerce site. If your pages appear untrustworthy, people won’t want to buy anything.
In the past five years alone, 46% of people in the United States have been affected by credit card fraud.
There’s a high probability that nearly half of your website visitors have experienced this. Even if they haven’t personally fallen victims to fraud, I’m sure they know at least one person who has.
This puts people on high alert.
If your checkout process isn’t secure, people won’t feel safe entering their credit card information, which is ultimately what you need to make money.
You must understand and implement the top elements that add credibility to your website.
All pages of the checkout process must be secure. It’s also in your best interest to include security badges, such as Norton, McAfee, or whatever else you’re using to protect your customers.
Eliminate shipping costs
Here’s a common mentality I see from ecommerce sites all the time. If it costs you money to ship your products, that means you should charge your customers for shipping, right?
Wrong.
While this may sound like a reasonable justification to you, your customers don’t see it that way.
In fact, shipping costs play a major role in why shopping carts are abandoned in the United States:
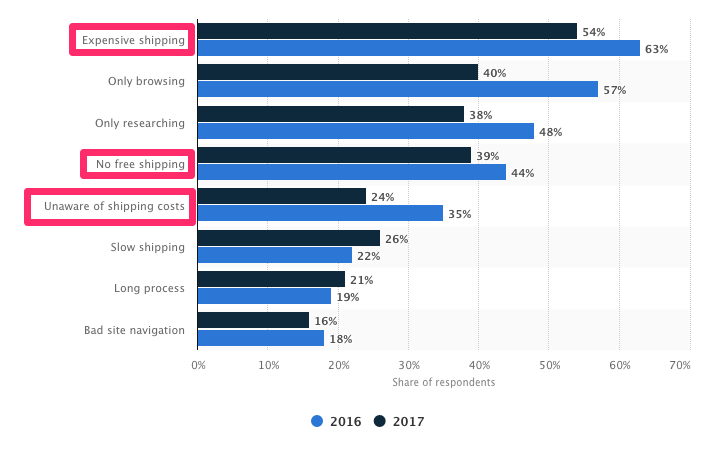
Do not charge your customers for shipping.
But you still need to make sure you’re turning a profit, even if you’re offering free shipping.
You’re better off raising the prices of your items so that the shipping costs are built into the base prices. Psychologically, this won’t impact your conversions.
That’s because customers won’t be surprised when they see additional charges when they check out. If your product is listed for $50 on the site, that’s what they expect to pay. But if the costs add up to $70 with taxes and shipping, it’ll hurt your conversions.
I’m not expecting you to be unrealistic here. Don’t ship your customers a piano overnight for free.
All I’m saying is you shouldn’t charge for standard ground shipping. If a customer wants the delivery to be expedited, you can let them pay an additional charge.
Reduce the number of form fields
A website visitor is ready to buy something. They’ve already made up their mind.
Don’t give them a chance to change their mind and abandon the cart. If your checkout process is long and complicated, you won’t have high conversion rates.
But if you can simplify the process by eliminating unneeded steps, you’ll make more money.
Ask yourself what information you really need from the customer to complete the purchase. Do you need the customer’s name?
Yes, but you don’t have to ask for it several times.
If a name is required to process the payment method or shipping information, don’t make them type those details twice.
Research shows that websites with fewer form fields have a higher performance rate during checkout:
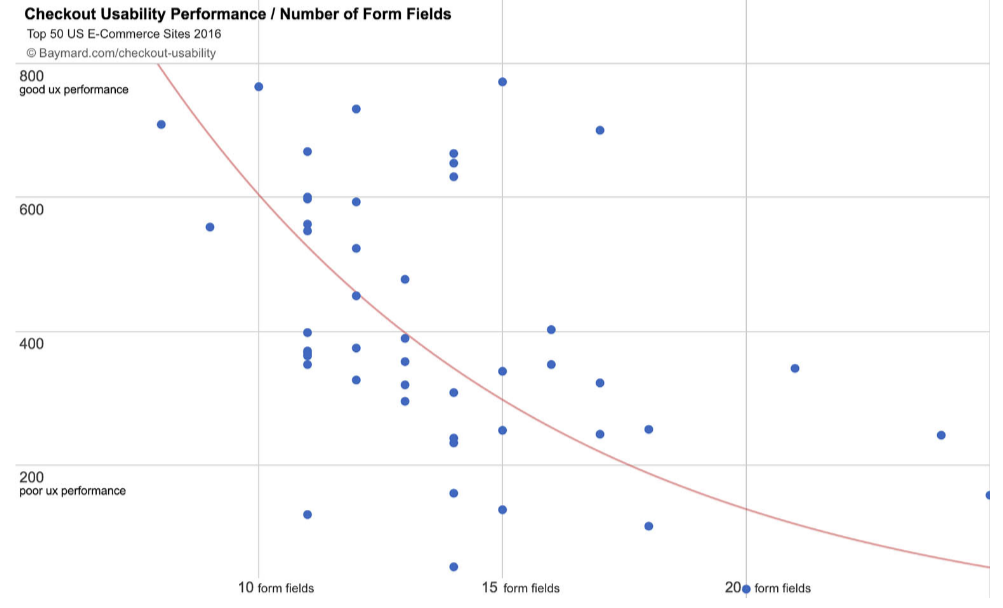
Only ask for information required to complete the transaction.
If the customer’s shipping and billing addresses are the same, they should be able to check off a box indicating that—instead of having to type their address twice, for shipping and billing.
That alone shaves an extra step off the process and significantly reduces the number of form fields.
Offer a guest checkout option
I get it. You want to learn as much information about your customers as possible.
In a perfect world, everyone who visits your site will create a customer profile. This allows you to monitor their browsing behavior and suggest items to them based on this behavior and their purchase history.
Customer profiles allow you to segment your audience based on the customers’ locations and make it easier for you to add subscribers to your ecommerce email list.
When a customer is browsing from their customer profile, they can also place repeat orders with just a couple of clicks.
Customers can save their payment information to their accounts, which reduces the number of steps in the checkout process and makes it easier for them to convert.
If you’re encouraging customers to create a profile, I’m all for it.
But there is a big difference between encouraging and forcing. Does a website visitor need to have a customer profile to convert? Absolutely not.
Forcing people to create a profile could be hurting your conversions.
People want to buy something. Let them give you their money.
Don’t prioritize your content marketing strategy over actual sales. Here’s an example of how a global giant Walmart implemented this strategy:
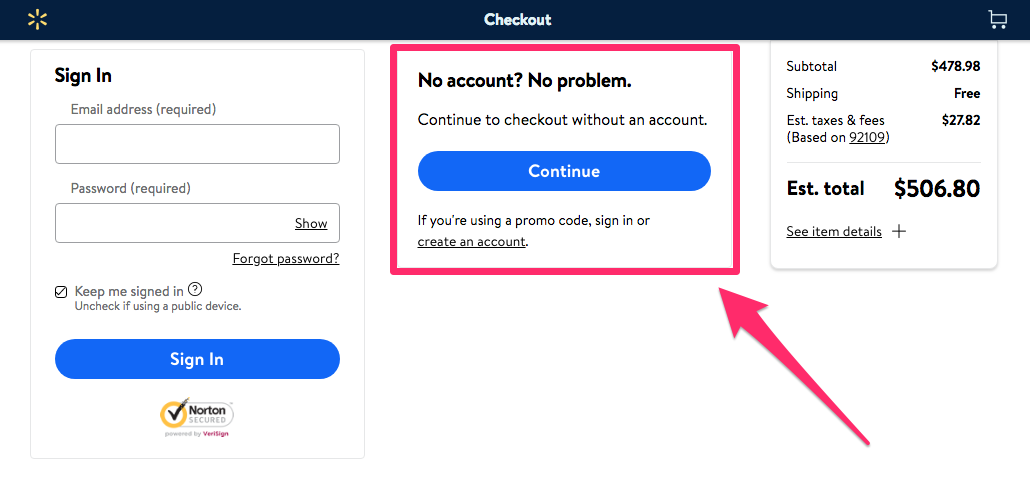
It’s always a good idea to follow the lead of the companies that have had major success in a particular space.
Offering a guest checkout is also reduces unnecessary steps, which I discussed earlier. Creating a customer profile is not necessary to complete a purchase, so don’t make it so. Otherwise it will turn some customers away.
Make it easy to shop from mobile devices
It’s no secret that we’re living in a mobile world. Ecommerce brands need to recognize this if they want to succeed.
In fact, 62% of people who own a smartphone used their devices to make purchases online within the last six months alone.
It’s estimated that in the next three years, mobile retail sales will control 54% of the ecommerce market share in the United States.
Why is this the case?
It’s because technology has made it more convenient to shop from mobile devices.
People aren’t walking around with laptops in their pockets all day. But phones are seemingly always within an arm’s reach, if they’re not already glued to the consumers’ hands.
If someone visits your ecommerce site from a mobile phone, they need to have a great experience.
If your site isn’t optimized for mobile devices, there’s a slim chance you’ll be able to generate conversions.
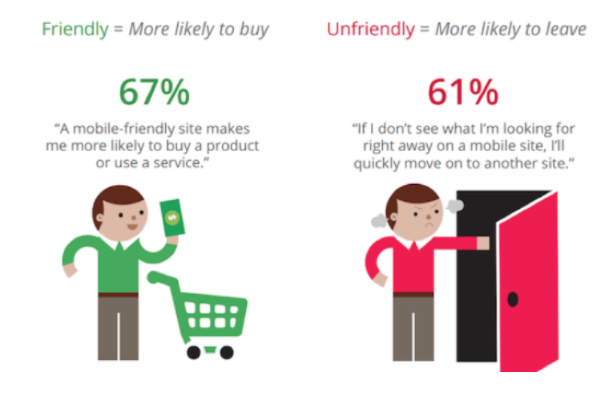
Just look at these numbers.
The design of your mobile site can be the difference between customers buying something or bouncing and buying from your competitors instead.
But 74% of mobile users are more likely to revisit websites that are mobile-friendly.
If your site is properly optimized, it will increase the chances of your website visitors not only converting but also coming back and buying again in the future.
A/B test the elements of your checkout process
You can never truly be sure your checkout process is designed for the maximum number of conversions unless you put your theory to the test.
The best way to determine which elements are driving the highest conversions is through A/B testing.
If you’ve never run an A/B test before, the concept is very simple. You start by identifying one element of the page you want to test.
Then 50% of your site traffic will see version A, while the other 50% will see version B. Compare the conversion rates between the two variations to see which one yielded the best results.
When testing the checkout page, it makes sense to start with the “purchase/buy now” button, or whatever your final CTA button is that completes the transaction.
There are lots of potential tests you can run on this button:
- size
- color
- placement
- wording
Test only one element at a time.
For example, let’s say you test the conversion button at the bottom right side of the screen compared to the bottom left side of the screen.
Once you have conclusive results, you can implement that change and then move on to testing the wording of the button, e.g., “purchase” versus “buy.”
Accept alternative forms of payment
Ultimately, the most important aspect of a checkout procedure is the payment step.
Without the payment step, transactions can’t happen.
From your perspective, you may think it’s in your best interest to accept only certain credit cards. I know you pay higher transaction fees for some cards compared to others.
That said, you need to accept as many payment methods as possible, including alternative forms of payment:
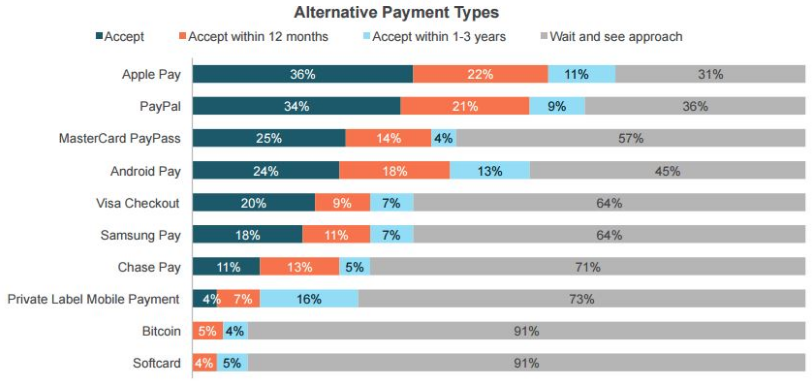
Let’s not get carried away here. In 2018, it’s probably not necessary to accept Bitcoin and other cryptocurrencies.
But in addition to all major credit cards, you need to accept alternatives such as Apple Pay and PayPal.
You don’t want your customers to leave your site without buying anything because you don’t accept the payment method they want to use.
Even if they have the options you accept, they still may go to one of your competitors instead so they can use their favorite method of payment.
The days of accepting only Visa and Mastercard are over. It’s time for you to adapt and add these other payment options to your checkout process.
Conclusion
If you’re driving lots of traffic to your ecommerce site but those visitors aren’t converting, you need to analyze the design of your checkout process.
Add multiple checkout buttons to different areas of the page.
Customers care about security, so the entire checkout procedure needs to be safe and secure.
Do not charge for shipping. Eliminate unnecessary steps, and reduce the number of form fields required to make a purchase.
Don’t force your site visitors to create customer profiles. Have a guest checkout option.
Optimize your ecommerce site for mobile devices.
Use A/B tests to see which design elements maximize your conversion rates.
And accept as many forms of payment as possible.
If you follow these best practices, your ecommerce checkout process will yield high conversions and, ultimately, increase your profits.
What elements of your checkout process do you need to change to drive higher ecommerce conversions?


Source Quick Sprout https://ift.tt/2Az7lSG
The Magic System for Getting Out of Debt and Building Wealth Quickly!
Whenever I’m on a road trip and I don’t happen to have an audiobook or a podcast available, I’ll spin the radio dial and listen for something interesting. I actually really like local radio shows that cover things that are actually going on in that area, so I’m usually seeking out things like that.
One thing I often hear as I’m spinning the radio dial are advertisements for all kinds of things: local restaurants and car dealerships and so on. I usually keep turning the dial, but for some reason, I always stop on the ads talking about people’s money.
You’ve heard them – they’re the kinds of ads that talk about getting out of debt really quickly or building wealth quickly or things like actually turning your debt into wealth.
I’m always amazed at the incredible claims that these programs make. They really do make it sound like all you have to do is sign up for this program or go to this seminar and suddenly all of your financial problems are solved.
The thing is, all of them are usually selling some minor variation on the same plan. It’s a super simple financial plan that I absolutely guarantee will get you out of debt really quickly and help you start building wealth faster than you know it. All you have to do is start following the plan.
Here it is – the core secret behind all of those “get out of debt quick” and “get rich quick” plans that sound enticing on the radio. Are you ready?
Spend less than you earn, make that gap as big as you can, and do something smart with that gap.
That’s it. That’s what every single one of those programs boils down to, with the “do something smart” varying a little bit but usually starting with “paying off your debts as fast as humanly possible starting with your highest interest debts.”
The truth is that this basic advice is also at the backbone of virtually every personal finance book you’ll check out at the library, too. Sure, they might vary a little in terms of what “do something smart” actually means, but the overall framework of spending way less than you earn and doing something smart with the difference is the key to all of it.
So, how do you make the magic happen?
You start by cutting your spending hard. That’s what all of these plans will end up suggesting to you, whether they do it subtly and lightly or they push it hard.
As I mentioned earlier, almost all financial plans you read or hear about or watch boil down to you having some freed-up resources to get rid of your debt and start saving for the future. How do you get those freed-up resources? There are two routes – earning more or spending less – and only one of them is immediately available to most people. You can always choose to spend less because that’s a choice you control, whereas your income is usually at least partially out of your control. Thus, cutting your spending is usually the first step, as you have to have some resources to start with.
Don’t get me wrong, there’s no question that earning more is a good thing when it comes to building lasting financial success, but you can’t just flip it on and off like a switch. If you could, everyone would be earning a mint… but that’s obviously not the case. Keep working toward improving your career and your earnings, but don’t use dreams of a big salary in the future as a justification to spend money today. If you want quick results, you’ve got to start with what you have, and what you have is the ability to cut back on your spending.
There are a lot of ways to do this. Switch to buying all store brand items when you go grocery shopping. Start shopping at a discount grocery store. Cut your cable and go with Netflix. Cut your landline. Switch cell phone carriers. Shop around for better insurance. Eat at home more often. The number of things that a person can do in their life to cut spending is practically infinite. You just need to find the things that you can cut hard that have a minimal impact on your life.
If you do that seriously, you’re going to suddenly have plenty of money to stop living paycheck to paycheck and start knocking down those debts rapidly and then, when the debts are gone, start building wealth.
The key to all of this is in the word “seriously.” If your “cuts” add up to stopping at Starbucks one less time this month, you’re not going to see any change in your life for a very long time. You have to cut and cut hard.
Every time you see a little extra in your checking account from those cuts, start paying down a debt. Start making extra payments on your highest interest rate credit card, as big as you can make them. When that’s gone, move on to the next one. When they’re all gone, celebrate… but keep going, because now you have the opportunity to build wealth. Start throwing a lot of money into your 401(k) or your Roth IRA. Start saving for a home. Start saving for whatever your goals are.
It is that simple. It’s kind of like magic. Just get a grip on your spending today and keep that grip and you’ll be in far, far better financial shape down the road.
If you’re sitting there thinking to yourself that this is obvious, you’re right. That doesn’t change the fact that 78% of Americans live paycheck to paycheck and much of the remaining 22% have some form of debt.
It might seem “obvious” and “simple,” but if that’s true, why isn’t everyone doing it?
It’s because although the strategy is “obvious” and “simple,” it’s hard to actually execute. It’s easy to talk the talk. It’s much harder to walk the walk.
If you can just start doing it, though, your life will change. If you can manage to spend less than you earn paycheck after paycheck, month after month, year after year, you will see profound changes in your financial life. Your debts will melt away like ice cream on a hot summer day. Your account coffers will start growing like a hungry twelve year old.
All it takes is spending a little less and sticking with that change, and then, maybe later, earning a little more. Then, take that money you’re not spending and that extra money you’re now earning and do something smart with it. Be patient and keep doing that and your life will change.
It’s amazing how something so simple, something that virtually anyone can do, can have such profound results, but that’s exactly how it works.
I should know. Several years ago, I was in debt up to my eyeballs, living in a tiny apartment, with tens of thousands of dollars in student loans, two car loans, and three maxed out credit cards. Today, I own my own home and have zero debt. The first step I took – and the only change I made in the first couple of years when I was making the debt vanish – was to simply cut back on my spending, cut back seriously, and stick with the cutbacks. That’s it. Eventually, I figured out how to improve my earnings a little, but by then, the snowball was already rolling down the mountain.
See? It’s magic. And you can do it, too. All you have to do is move from thinking about it to doing it.
Good luck!
Related Articles:
- How to Save Money: 100 Great Tips to Get You Started
- The Upside Down Reason So Many Americans Are Broke
- How Do I Even Start With Saving for Retirement?
The post The Magic System for Getting Out of Debt and Building Wealth Quickly! appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2O8wzsV
I’m Stressing Over My $40K Credit Card Debt and I’m Running Out of Options
It’s time to call in some backup and talk with a credit counselor. Not one of those credit repair scams you’ve probably seen or heard ads for — I’m talking about a reputable, nonprofit debt management agency.
After an initial call or visit, a credit counselor can assist you in disputing negative items on your report or help you manage your debt through a payoff plan. A legitimate debt management plan shouldn’t charge more than $50 per month.
The most nerve-wracking part is making the first appointment. I did this a few years ago when I was feeling crushed by my credit card, student loan and small-business debt.
My counselor asked me a ton of questions about my debt. Balances, interest rates, minimum payments. She asked about my checking and savings account balances, and what I was paying in estimated taxes each quarter because I was self-employed. She asked about my rent costs. My utilities. If I hadn’t signed up for this, I would have thought it was invasive.
She crunched some numbers and sighed a little. “You just need to keep going,” she said, explaining that my credit was good, my payment history was solid and my interest rates were fairly low. The best course of action would be to stay the course and keep making whatever payments I could.
This might be the same news you’ll get if you call a credit counselor. But you’ve likely been looking at this debt so much that you need an impartial third party to review your situation.
It was hard to accept that a debt management plan couldn’t help me then. Like you, I wanted a plan. An answer. Any answer.
The reality was that I had to form a plan on my own. I tackled small balances first to clear them away, and then moved on to debt that had higher interest rates. But the real key was to stay motivated. It’s going to be a long road out from under this debt, whether you work with a credit counselor or on your own. As you rebuild your payment history, your score will go up. The zero interest transfer offers will return. You can keep transferring the balance and throwing money at your debt for as long as you have to.
And for the next few years, that’s going to have to be OK. Because even if it takes years, there will be an end to that journey. If you can stay motivated, you’ll be well on your way to freedom from debt.
This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.
source The Penny Hoarder https://ift.tt/2v9zOth
الخميس، 2 أغسطس 2018
Airport lounges - serious money saving or a waste of cash?

Travelling abroad can be exhausting – so wouldn’t it be nice to get the VIP treatment and relax in a private space away from the crowds? From comfy seats to cocktails, Moneywise finds out what’s on offer at airport lounges and whether it’s worth investing
Airport lounges are no longer exclusive hideaways for high-flying executives and passengers travelling first- class – anyone can get some pre-flight peace for a few quid. Alongside the buffet, booze and free wi-fi, some airport lounges offer some swanky extras. The SkyTeam lounge at Heathrow Terminal 4, for example, has a Clarins Wellness area and PlayStation room, while Sleep ’n Fly in Dubai International has igloo-style sleep pods.
But when considering whether to book an airport lounge, it’s important to understand the difference between airline and airport lounges.
Airline lounges tend to offer the most exclusive facilities, with massages, sleeping areas and showers typically available alongside rest areas with unlimited food and drink. But most airline lounges are restricted to first- and business-class passengers, and frequent flyers.
Airport lounges, on the other hand, are much more accessible. Brands such as Plaza Premium, No1 Lounges, and Swissport run facilities in airports all over the world, and these are open to everyone – at a price. In general, you get what you pay for; prices range from about £20 to more than £45 a visit.
If you just fly a couple of times a year, you can buy a lounge pass for the airport or airports you’re travelling through on a one-off basis. But the big question is: is it worth it?
Tom Bourlet, travel blogger at Spaghettitraveller.com, reckons it is.
“The cost is normally around the £25 mark, which might sound steep, but as airport costs all start to add up, it seems to be worth it by the end,” he says.
“You get a private wi-fi connection, which is a lot faster than the basic free one everyone uses in the airport. You get a large range of food, both hot and cold, while there are unlimited drinks – not a bad perk if you are a few hours early. Depending on the airport, you can normally get much more comfy seating, plenty of space and your own private booth.”
Customers on lengthy layovers will arguably benefit from lounge access more than people who simply arrive early for their flight. You can normally pay for lounge entry on the door but, with lounges often capping the number of people admitted at any one time, it’s best to book ahead. This can save you money, too. For example, the No1 Lounge in Gatwick’s North Terminal costs £32 per adult and £18 per child if booked online, but £40 and £20 respectively if you just turn up.
You can save even more money if you buy a pass via a cashback site such as Quidco.com or TopCashback.co.uk. At the time of writing, Quidco pays 11% cashback on No1 Lounge passes, bringing the cost at Gatwick down to £28.48, while TopCashback pays 11.55%. Other offers on Quidco include 10% cashback on Lounge Pass sales and 8% cashback on Executive Lounges.
Sites such as LoungePass.com and LoungeBuddy.co.uk are a great way to compare the different lounges at any airport you will be flying to, from or through.

Manchester airport’s Aspire lounge (above)
“We provide customer reviews, photos, and other information to help travellers decide whether the lounge is right for them, whether they’re looking for a place to grab a bite, get some work done, relax, or all of the above,” says Brent Griffith, co-founder of LoungeBuddy.
“When you book lounge access with us, we save you a spot in the lounge so that you won’t be turned away. There are also certain lounges that you can purchase access to through LoungeBuddy that are not available to the general public elsewhere, such as the Lounge@B in Dubai and Lufthansa Business Lounges.”
Deals for frequent flyers
Regular travellers should investigate annual membership. There are two main options here – an annual pass for a particular lounge brand or schemes offering access to multiple lounge brands.
Aspire Lounge annual membership costs £259.99 (via Executivelounges.com) for unlimited access to any participating Aspire or Swissport lounges in the UK, Canada, Denmark, and the Netherlands. A big advantage of Aspire Lounge membership is that you can bring a guest each time for free.
However, Priority Pass membership (via Prioritypass.com) will be a better option for many people. It offers access to more than 1,200 lounges in more than 500 cities across 130 countries. The lounges are run by various brands, including Plaza Premium and No1 Lounges.
Standard membership costs £69 a year but you have to pay £15 per lounge visit. Standard Plus is better value – for £159 a year you get 10 free visits. If that’s not enough, Prestige membership costs £259 and offers unlimited lounge visits. Members can take a guest each time for £15. However, simply having a pass doesn't guarantee entry – if the lounge is busy, for example, you can still be refused access.
Jon White, director of marketing at Priority Pass’s parent company, Collinson, says that with individual lounge access costing up to £45 each time, frequent travellers can save money with annual membership.
“For example, our Priority Pass Standard Plus membership includes 10 free visits for a one-off cost of £159, which means you only need to make a couple of return trips each year to make it worthwhile,” he says, “With memberships, travellers are not only saving on lounge access – the selection of complimentary snacks and tipples available should be weighed up versus the cost of other food and beverage options in airports and transport hubs.”
There are a couple of ways to get Priority Pass membership for free – but you’ll need to be pretty well off. Membership is included with the £28 a month NatWest Reward Black current account, but this requires a sole income of at least £100,000, a NatWest mortgage of £500,000, or £100,000 saved or invested with NatWest. American Express’s Platinum card includes Priority Pass membership alongside worldwide travel insurance and hotel benefits – but it comes with a hefty £450 annual fee.
DragonPass (via En.dragonpass.com.cn) combines lounge access with discounts on airport dining, limousines, and meet-and-greet services. It covers about 970 lounges and has three membership options with its top-tier deal costing US$399 (£278) and offering unlimited lounge visits.
Before you book lounge access, check it’s a lounge at the same terminal you’re departing from -– unless it is accessible landside (before security). Some of the larger airports with multiple terminals have several lounges in each terminal.
If you fancy a visit to the best airport lounge in the world, you’ll need to go all the way to Jamaica. Club Kingston, at Jamaica’s Kingston Norman Manley International Airport, was the overall winner of Priority Pass’s Lounge of the Year Awards 2017. The lounge features Jamaican artwork and décor, local food and drink, signature cocktails, a conference facility and dedicated work stations.
EMMA LUNN is a freelance journalist who writes regularly for Moneywise, the Independent and The Telegraph
Section
Free Tag
Related stories
Source Moneywise https://ift.tt/2MeUIxx
Fidelity Is Now Offering Zero-Fee Index Funds. Here’s How It’ll Make Money
And you have a lot of options when deciding where to invest for retirement: 401(k)s, 403(b)s, traditional IRAs, Roth IRAs — all tax-advantaged accounts you can put mutual funds and exchange-traded funds in.
Unfortunately, that freedom can be paralyzing.
Many people can’t contribute more than a few hundred dollars per month, and with thousands of mutual funds and ETFs to choose from, sometimes it’s easier to just invest in a new car.
Well, Fidelity is trying to lower that barrier to entry for investors with something no major mutual fund company has ever done before.
On Friday, Aug. 3, Fidelity will begin offering two no-fee index funds with no minimum investment.
You’ll be able to invest in the Fidelity Zero Total Market Index Fund (FZROX) and Fidelity Zero International Index Fund (FZILX) with a zero expense ratio — the percentage of the fund that goes to fees associated with managing the fund — no account fees and no investment minimums.
These funds can go into a traditional or Roth IRA, 529 plan or any investment account when you purchase them through a Fidelity brokerage account.
Index mutual funds and ETFs are known for having the lowest fees in the investment world. Fidelity is just the first to cross the zero-fee finish line. Schwab’s lowest index funds have a 0.03% expense ratio, and Vanguard’s have a 0.04% ratio.
So you’d have to have a lot invested to see a significant difference.
How’s Fidelity Going to Make Money?
This looks like a classic “loss leader” strategy. A loss leader is a good or service that’s strategically sold at a loss to attract customers in hopes they’ll purchase other, more profitable products while they’re there.
Kind of like what MoviePass was (unsuccessfully) trying to do.
This is evidenced by the fact that Fidelity didn’t even let people take a breath before it also announced it’s dropping expense ratios on a number of other funds to as low as 0.015%.
Whether you stick with who you have or try out these new Fidelity funds, the most important takeaway is to consistently contribute to your retirement accounts. Lower fees typically translate to higher profits, but not if you don’t contribute.
This article contains general information and explains options you may have, but it is not intended to be investment advice or a personal recommendation. We can't personalize articles for our readers, so your situation may vary from the one discussed here. Please seek a licensed professional for tax advice, legal advice, financial planning advice or investment advice.
Jen Smith is a staff writer at The Penny Hoarder. She consistently invests in index funds and gives money-saving and debt-payoff tips on Instagram at @savingwithspunk.
This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.
source The Penny Hoarder https://ift.tt/2Mi2jv6
Would a Shorter Work-Week, Same Pay, Work in the USA?
Source CBNNews.com https://ift.tt/2AKjepd
Financial Fruit: Apple Becomes 1st Trillion-Dollar Company
Source CBNNews.com https://ift.tt/2n6dP23
Vote in the Moneywise Home Finances Awards 2018

The Moneywise Home Finances Awards survey is now live. Give your views and be in with the chance of winning a £500 prize.
Section
Source Moneywise https://ift.tt/2LL2ins
Index Funds Can Help You Get Rich (but It’s Not Going to Happen Overnight)
It’s getting started.
When you don’t have a ton of money, it’s nerve-wracking to put it in a metaphorical shoebox that you can’t access for decades, even when everyone’s telling you now is the best time to start.
When my husband and I started thinking about retirement last year, we were in the same place.
We went searching for information and found that everyone who knows anything about investing has a strong opinion about it, regardless of how much they actually know.
The easiest and most common options in 401(k) plans and IRAs are mutual funds, but there are still a plethora of funds to choose from.
After talking to a number of investment professionals and personal finance writers, we found one type of investment that nobody had anything bad to say about: index funds.
What’s So Great About Low-Cost Index Funds?
An index fund is a type of mutual fund or exchange-traded fund (ETF) designed to track the performance of an index by including the same individual stocks as the index.
You may have heard of the S&P 500 or Dow Jones Industrial Average. Those are examples of indexes that index funds try to match.
For example, the S&P 500 includes 500 of the largest publicly traded companies America, so an S&P 500 index fund will have all 500 — give or take a few — of those companies’ stocks in it.
People love index funds for two main reasons.
- The fees are really low. The goal is to pay as little in investment fees as possible. Index funds have some of the lowest fees of any investment vehicle.
Robert Farrington from TheCollegeInvestor.com helps millennials navigate investing for the first time and loves index funds for that reason.
“One of the biggest things that erodes your investment gains is fees. The less fees, the more money you can keep in your pocket,” he said. “What many people don’t realize is that non-index funds can charge fees upward of 1% per year or more. Index funds can have fees as low as 0.03% per year — that’s a huge savings and simply equates to more money in your portfolio.”
And you’ve heard of Warren Buffett, right? That famous businessman who invests for a living and has a net worth of over $84 billion?
While Buffett actively invests in single stocks, for the average citizen who doesn’t enjoy reading about that stuff all day, he recommends low-cost index funds.
Because index funds aren’t actively managed, the fees associated with them are super low. With low fees, more of your money can compound interest compared to actively managed funds with higher fees.
Buffett actually bet $1 million that he was right — by pitting an index fund against a basket of hedge funds for 10 years — and won by a landslide.
- They’re well-diversified. Erik Tozier, from The Mastermind Within, prefers index funds because they provide instant diversification for any portfolio size.
“It’s unfortunate, but it’s a fact that some companies will fail. It’s also a fact that some companies will outperform others,” he said. “Humans don’t have crystal balls, and to be able to select which ones will fail and which ones will perform well is nearly impossible.”
By having low-cost index funds, you own a little piece of a lot of companies, as opposed to an actively managed fund that typically includes fewer companies. So if one company fails, it’s backed up by many more successful companies. And on average, you’ll trend with whatever index your fund is tracking.
While some naysayers think index funds will kill the market, Camilo Maldonado of The Finance Twins said that index funds are still a small percentage of the overall stock market, and they’re likely to stay that way.
“Only about 40% of the stock market is owned by indexers, which is well below the 75-85% threshold that leading economists and investors, like Warren Buffett, warn against,” he said. “What this means is that investing in index funds will continue to be a viable investment for many years to come, since there's no certain indication that those levels will ever be reached. After all, there's always someone willing to bet that they can beat the market average.”
How to Invest in Index Funds
You can add index funds to almost any retirement or investment account. And because the funds are so broad, you don’t need many to diversify.
The easiest place to start is in your traditional or Roth IRA.
If you don’t already have one you can open an IRA brokerage account with a company like Vanguard, Charles Schwab, Fidelity or BlackRock. Each company has its own selection of index funds and minimum balances to open, so check each to find the company that’s right for you. You’ll want to look for fees that are less than 1%.
Your 401(k) may have more limited options.
Wherever you choose to put them, including low-cost index funds in your portfolio is likely to result in fewer fees flying out of your accounts and more money for you in retirement.
This article contains general information and explains options you may have, but it is not intended to be investment advice or a personal recommendation. We can't personalize articles for our readers, so your situation may vary from the one discussed here. Please seek a licensed professional for tax advice, legal advice, financial planning advice or investment advice.
Jen Smith is a staff writer at The Penny Hoarder and maxes out her 401(k) and Roth IRA contributions, all in index funds. She gives money saving and debt payoff tips on Instagram at @savingwithspunk.
This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.
source The Penny Hoarder https://ift.tt/2LS0kkx
The Wisdom of Frugality: The Environmentalist Case for Simple Living
 This is the seventh entry in an eight-part weekly series that provides a detailed look at the book The Wisdom of Frugality by Emrys Westacott. If you’re new to the series, feel free to hop back to the first entry.
This chapter of The Wisdom of Frugality takes direct aim at one of the biggest benefits often cited for living a simpler frugal life: it’s environmentally friendly. A frugal person, as the argument goes, uses far less resources than an affluent person and thus puts less of a strain on the global environment. Many people carry this concept forward and use it as a big part of their moral justification for frugality.
Historical Background
This part might not seem relevant to frugality, but bear with it.
Prior to the Industrial Revolution, there was no need for people to be concerned about the environment. The individual actions of humans in a pre-industrial society did not add up to nearly enough to cause environmental damage on a scale that could consistently cause significant and widespread harm.
Nature was seen as a wild force for man to exploit. It was far beyond the ability of man to control it or interfere with it in any significant way; rather, man found ways to accentuate the benefits of nature and minimize the negative impact on human life.
Over the centuries, humans gradually developed technologies that allowed them to exploit more and more of the earth’s resources, eventually leading to the Industrial Revolution and widespread exploitation of those resources.
Alongside the Industrial Revolution, a backlash of sorts arose in the form of Romanticims, which lauded natural untamed landscapes and distrusted artificial things. This eventually developed into a broad tradition, with people like Henry David Thoreau rejecting many aspects of technology and eventually growing into the modern environmental and political movement.
The Environmentalist Argument for Frugality
Frugality and environmentalism find a great deal of overlap because of similarity in tactics. Both of them find a great deal of value in minimizing one’s use of the Earth’s resources and getting as much value as possible out of the resources that we do use.
The idea of “reduce, reuse, recycle,” for example, is as much at home with an environmentalist as it is with a frugal person. Both will seek to get as much value out of things as possible, but for somewhat different core reasons. The environmentalist wants to reuse and reduce in order to minimize their impact on the Earth, while the frugality wants to reduce and reuse in order to minimize the expense.
The specific tactics that both groups use in their daily life tend to match up really well, too. Strategies like using less water, consuming fewer manufactured goods, using less electricity, and finding low impact things to do with one’s time are strategies that both frugal people and environmentalists share, even though they may be doing those things for different reasons. Often, frugal people and environmentalists are on the same page with broader initiatives in the community, like having an effective mass transit system, which lowers overall environmental impact (great for the environmentalist) while also lowering individual cost (great for the frugal person).
Objections to the Environmental Argument
However, a great deal of synergy in tactics doesn’t add up to full agreement. While there may be some overlap between the beliefs and tactics of the environmentalist and the frugal person, there isn’t perfect alignment.
First of all, ecological impacts are often difficult to articulate and evaluate. Things like biofuels and rechargeable batteries might seem to be environmentally friendly on the surface, but the full picture of their environmental impact often isn’t nearly as clear cut. For example, rechargeable batteries often require some very environmentally unfriendly practices and materials requirements to manufacture, for example. They may be frugal, but are they environmentally friendly? It’s a bit harder to tell for sure.
This is true for larger strategies that might seem like great synergy between frugality and environmentalism. Is it more environmentally friendly to install solar panels on your home than to keep buying from the grid? What about the manufacture of those panels – what kind of impact does that have? Figuring that out becomes very difficult, whereas crunching the numbers to determine the cost-effectiveness of such a choice is much more cut and dried.
The thing to remember when being skeptical of ecological impacts of individual choices is that it’s good to be skeptical of the individual practices, but recognize that the overall principle – reduction of environmental impact – is a good one.
The second issue to consider is the fact that simple living isn’t always green living. A great example of this came from the “burn barrel” we had when I was growing up. We didn’t have trash service and the only real option for trash removal was to haul it to a dump that was many miles away, so instead we had a “burn barrel” – an old barrel that my dad picked up somewhere – in which we burnt our trash. When the barrel became full of ash (and with a few unburnt items in there), then we’d pay to have it hauled away. It was far cheaper than actually having trash service, but far less environmentally friendly.
In retrospect, the environmental cost of services out in the country where I grew up was much higher than it would have been in the city. The environmental cost of running power lines, water lines, roadways, and other such services to us out in the country was enormous. Furthermore, to have access to other services, like grocery stores, we had to drive quite a few miles.
The idea of “simple living in the country” is really only environmentally friendly if you decide to completely go without a lot of basic services. Some people in rural areas do eschew a few services that people in urban or suburban areas might expect (such as speedy internet), but people in rural areas do expect an awful lot of the basic services that all Americans expect, like drivable roads, drinkable water, and so on, and those services have a pretty big environmental footprint when they’re offered in rural areas.
Another great example of how the frugal option isn’t always the most environmentally friendly option is the choices faced when buying fresh produce. Local, organically produced items are going to have a lower environmental impact than produce that came from a factory farm several thousand miles away… but the local organic produce is going to be more expensive because the factory farm methods squeeze a lot of cost out of the system.
How does a person decide what the right choice really is? It’s not an easy decision no matter what you choose. There ends up being several reasonable choices when it comes down to balancing various environmental factors, and often the “best” choice ends up being influenced by other factors like health benefits, the impact on the local community, and so forth. Often, this best choice does not end up being the least expensive choice, which can put a price conscious person at odds with an environmentally focused person.
Furthermore, it can be argued that the choices of individuals make no real difference. The actions of governments and corporations will make the real difference, not individual frugal choices. The things I do in my daily life have very, very little impact on the environment compared to the impact of large scale agricultural businesses and manufacturing businesses.
This is the reasoning that many people use for individual poor behavior. “I can’t possibly make an impact,” goes the logic, “so it doesn’t matter what I do.” Thus, people excuse their own unethical and damaging behavior.
The thing is, individual actions multiplied many times can make an enormous difference. Consider, for example, a community that has limited water in its reservoir that agrees to some general water use rules within the town. If everyone chooses to conserve a little, everyone has enough water for their needs. An individual person isn’t going to be able to fix the water issue through severe cutbacks or non-use, nor is that individual going to be able to singlehandedly drain the reservoir, but when lots and lots of individuals agree to limit their water use to merely meet their needs rather than all of their wants, there ends up being enough water for everyone to meet their needs.
This pops up over and over again. When people agree to use restraint when utilizing common resources like water and wood and other such things, there’s enough for everyone to have their needs and sometimes their more important wants met. If individuals assume they have no impact and then uses the resources recklessly, then simple arrangements where everyone has their needs met can never occur and some will be left without needed resources.
When lots of people take little steps, economies of scale kick in. For example, if everyone in America gave a single dime toward a cause, that cause would suddenly have $30 million dollars. Little efforts are only small when they’re seen in isolation – if they’re repeated by everyone and looked at from a distance, they appear enormous.
Another counterpoint is the idea that our best hope for fixing the environment lies in technological innovation.. Many of the tools that we have for keeping our environment healthy come from technological innovation – solar panels (and their steady improvement), wind power, algae power, tidal power, tools for environmental cleanup, and so on. As powerful as frugal living can be, it can’t fix the damage of the past and it can only somewhat alter our trajectory going forward. Technology has the capacity to fix our past mistakes and radically alter our path going forward.
The problem is that technological innovation, as it’s happening, often has a huge environmental impact itself. It can take a ton of resources to go from whiteboard idea to something that works, and that first version that works is usually very rough and takes a long time to refine. In other words, development of the technologies that we really need to make things better is going to require some significant short term environmental impact, and there’s not even a guarantee that those technologies will help. Furthermore, other technological innovations will likely continue to increase our use of resources while we stumble towards any kind of solution to the environmental impact of that resource use.
Stepping up activities that are causing the problem is illogical. It’s the equivalent of eating more when you’ve just been given a prescription for diabetes medication. Yet it’s essentially a requirement if we believe technology will just fix everything.
Many people hope that this research will happen as a result of the economic booms that have come from the development of earlier research into high-demand products. The reality is that the kind of research that’s done in the wake of a successful product is usually not in solving big societal problems, but in developing a follow-up product. Apple’s R&D department didn’t start trying to solve humanity’s deep questions once they developed the iPhone. Instead, they went to work on the iPhone 2 and the iPad.
Final Thoughts
Most of the arguments that people make in favor of frugality are individual arguments. They look at things purely in terms of the individual – how can I get the most value out of this situation, considering my needs and wants and my financial bottom line? The environmental angle is an attempt to move beyond that individual approach. How does frugality come into alignment with larger societal needs? It happens to line up well with being green.
When you start looking at frugality through the lens of what our moral obligations to others actually are and how we live them out, it’s clear that frugality can be a major part in terms of living out our obligations to our community and the world. If we live a less expensive and simpler lifestyle, we’re left with more resources with which to use to make the world a better place, plus we’re consuming fewer resources ourselves. There are a lot of ways we can use those resources to make the community and the world a better place.
In short, frugality is a powerful supplement to a public service oriented lifestyle. If volunteerism and other forms of public service and public work are a major part of your life and you want to actively work to make the world a better place, then frugality plays a strong complementary role in that because it reduces the amount of time and energy and money you need to commit to meeting your living expenses, which thus increases the amount of time and energy and money you have available to commit to the causes you care about.
There’s another interesting underlying issue in all of this: just because something feels right doesn’t mean that it is right. It might feel “right” (for an example that hits home here in Iowa) to buy ethanol-supplemented fuels, but the significant reduction in fuel efficiency plus the environmental cost in the conversion of plant matter into ethanol means that I’m not convinced that what “feels” right actually “is” right (the jury is still out for me on this one, to tell the truth). It takes a lot of work to move from what “feels” right to what actually “is” right, and that sometimes means giving up on some tightly-held beliefs. That’s a kind of effort that’s in short supply in the world, sadly enough.
Next week, we’ll tie up this book with some final thoughts on the book as a whole and what it means for people practicing frugality today.
The Wisdom of Frugality Series:
- Part 1: What Is Simplicity?
- Part 2: Why Simple Living Is Supposed to Improve Us
- Part 3: Why Simple Living Is Thought to Make Us Happier
- Part 4: Why the Philosophy of Frugality Is a Hard Sell
- Part 5: The Pros and Cons of Extravagance
- Part 6: The Philosophy of Frugality in a Modern Economy
The post The Wisdom of Frugality: The Environmentalist Case for Simple Living appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2n5unap
Tame the Lifestyle Inflation Beast Now… or It Will Devour Every Extra Cent
I seldom had more than a few bucks left over from my paychecks, so I had no savings, but at least I wasn’t accruing more debt. If I budgeted properly, I’d even have enough for a couple rounds of drinks with friends.
But several years and salary bumps later, my savings remained paltry — and I was still driving the green machine. So where was my extra cash going?
Well, there was the extra $30 a month to have a washer and dryer in my apartment. And the furniture that I gradually put in said apartment. And the takeout food that I substituted for mac and cheese. And the gym membership upgrade. And the drinks with friends that evolved into dinner and drinks.
None of these upgrades sounded like a big deal. But combined, they added up to major lifestyle inflation, and they ate away my potential savings.
What Is Lifestyle Inflation, and When Is It Bad?
Lifestyle inflation, also known as lifestyle creep, happens when your spending increases as your income rises. It does not include those unavoidable increases in your cost of living, like a rent hike or a rise in grocery and gas prices.
Lifestyle inflation is a choice. It happens when you upgrade to a fancier car or apartment because you have more money to spend. Or you start dining out more or buying slightly pricier clothing.
The tricky thing about lifestyle inflation is that it isn’t inherently bad. Lifestyle inflation is the reason I’m not shopping at Forever 21 at age 35. It’s the reason I have a real couch now. It’s the reason I was able to take on a car payment and send my old Corolla to scrap-metal heaven.
The danger of lifestyle creep comes when you don’t have long-term goals. Without a plan, you’re more likely to spend extra money mindlessly. You’ll stay broke even as the numbers on your W-2 soar.
7 Ways to Avoid Lifestyle Inflation
The good news is, by establishing priorities and good habits now, you can fight excess lifestyle inflation later.
1. Learn to Live Within Your Means While You’re Still Broke
If you’re in college or working in a low-paying job, just being able to pay your bills without taking on more debt is a win. Focus on spending no more than you bring in, so your future earnings won’t be eaten up by debt payments.
You might be surprised by how much a little grocery strategery can save you on food. Making small changes at home can add up to huge savings on utility bills.
2. Create a Budget ASAP
Accounting for every dollar you spend now will help you make smart decisions about how to allocate extra money in the future. Are you a budgeting novice? It’s OK — this easy guide to budgeting will get you started.
3. Spend More Money (but Only in Your Head)
How would you spend an extra $5,000? Maybe you’d pay down student loans, save more for retirement or sock it away to use toward a down payment on a home.
Imagining how you’d spend cash you don’t actually have may sound like a futile exercise in daydreaming — but identifying what you want now will help you decide what long-term goals to focus on. And having goals will help you avoid mindless spending when you actually have more cash in hand.
4. Got a Raise? Congrats, but Figure Out What You’ll Actually See
OK, suppose that $5,000 raise becomes reality. Nice! But hold on before you pop open the bubbly. Do you know how much of that money you’ll actually see?
First, calculate how much extra you’ll pay in taxes. Pro tip: Figure out how much you’ll owe now if you don’t want to pay at tax time, and adjust your withholdings accordingly.
Next, account for inflation — the kind you can’t avoid. As of May, the 12-month inflation rate was 2.8% in the U.S. That means if you were earning $50,000 a year as of May 2017, on average you’d now have to earn $51,400 annually just to maintain your lifestyle.
Also, if you contribute a certain percentage of your salary to your 401(k), you’ll need to account for that.
Once you’ve determined how much extra money you’ll take home, you’ll have a realistic picture of how much extra you can spend.
5. Pretend That Raise Never Happened for Now
Sure, you could spend that extra money on a pricier apartment. And if that’s your long-term goal and you can afford it, go for it. But maybe your ultimate goal is to buy a house. That’s when you might want to keep up the frugal habits you developed when you were broke, so you can save the extra money for a down payment.
Avoiding lifestyle creep is especially important if you’ve got credit card debt or student loans. Putting extra money toward what you owe will have a huge payoff, because you’ll save on interest payments.
Stashing extra income in a retirement account now, instead of spending it, is also a great way to build wealth. For example, if you’re 20 years old and put $5,000 in a Roth IRA now, it could be worth $180,000 by the time you’re 65, even if you never contribute another cent.
6. Ignore What You See on Instagram
Scroll through Instagram and it seems like everyone else just bought a five-bedroom house and spends their weekends sunbathing on a yacht in Martinique. But sometimes, avoiding lifestyle inflation is as simple as focusing on your own goals and ignoring everyone else. You know your goals, your budget and your values. You never know whether there’s a financial mess behind the fabulous lives you see.
7. … but Treat Yourself (Within Reason)
Fighting lifestyle inflation doesn’t mean you never get to treat yourself. You’ve put in hard work to score those raises or earn extra income. So if you can afford it, go ahead and take a vacation or splurge on a piece of clothing occasionally. Celebrating the wins can keep you focused as you strive toward your goals.
When Is Lifestyle Inflation OK?
Like I’ve said, lifestyle inflation isn’t a bad thing when you have a long-term plan. Here are a few examples of when it makes sense to let your lifestyle inflate.
Your needs change: You don’t want to automatically start blowing extra money on rent just because you can afford to do so. But when your needs change — say, you’re preparing to start a family and need more space, or you have a new job that you want to live closer to — it’s reasonable to consider spending more.
You’re spending on a long-term goal: Remember when I told you to imagine how you’d spend money you don’t have? If you’ve finally saved enough money to make that happen, you have permission to stop daydreaming.
You’re investing in yourself: When spending extra can help your professional development, or it’ll make you happier and healthier in the long term, it’s worth considering. If you’re starting your first real job after college, it probably makes sense to invest in a real adult wardrobe. Taking on a car payment might make sense if driving an old, not-so-faithful car is a constant source of stress.
We’ll even give you a pass to order takeout or have your groceries delivered if that little bit of lifestyle inflation means you have extra time to invest in your side hustle.
Robin Hartill is a senior editor at The Penny Hoarder.
This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.
source The Penny Hoarder https://ift.tt/2LRFrpD
How do you rate your providers?
Moneywise Home Finances Awards 2018
- £500 cash prize for one lucky winner
- £100 shopping vouchers for five others
- Free copy of Moneywise for the first 10,000 participants
Image

CTA
Legal
Section
Source Moneywise https://ift.tt/2O5JY5j
Secondhand Clothes from a Personal Stylist: I Tried ThredUP’s ‘Goody Box’ Service
Whether or not you enjoy shopping for clothes, sometimes a little assistance for time-saving or style-shifting purposes can be helpful. Until recently, companies that specialize in new apparel such as Stitch Fix and Nordstrom’s Trunk Club have cornered the online personal shopper market. The basic process works like this: You create a profile detailing your budget, style, and fit needs, and a stylist sends you a box full of clothing, accessories, and shoes for a fee. You choose the items you want to keep and send everything else back within a designated timeframe.
I’ve been intrigued by the concept, but as someone who keeps her wardrobe to a minimum, likes to host clothing swaps, and generally shops resale stores wherever possible to cut back on supporting the throw-away, fast-fashion industry, I’ve been hesitant to try such subscription crate services.
Enter ThredUP’s new customized “Goody Boxes,” and an excited me.
ThredUP’s Goody Box: New-to-me, just-for-me
ThredUP, the largest online thrift store, has been in the secondhand business for almost a decade. The company used to deal only in one-to-one buying and selling, but recently debuted its online customized curation program: the Goody Box. Instead of a getting a crate full of new clothes chosen by a personal stylist, you receive an array of custom-picked secondhand fashions.
The process will sound familiar. After setting up a profile, you have the opportunity to include additional notes to your stylist; I asked for no leather or fur, and wrote that I tend to wear a lot of black and would appreciate some bright color options. You can also share more details about your style by favoriting items currently available on the site, or by linking to a personal Pinterest board.
Right now, the fee for the service is $10, but it’s technically a non-refundable deposit: You receive $10 in credit toward whatever items you decide to keep. Once a box arrives at your doorstep, you have seven days to try everything on and return what you don’t want. ThredUP includes an itemized sheet that lists each piece and its price, along with a free USPS return label. They’ll also send you multiple reminder emails about the return deadline, so you don’t accidentally get stuck with everything if you don’t want to add all of it to your wardrobe.
I ordered my first box last month, and a second box immediately after receiving my first, and here’s what I found.You
You can get high-quality secondhand goods online.
My biggest worry about buying secondhand items online concerns quality. As a resale shopper, I’m used to rigorously checking every inch of each item I want to buy, and I still sometimes bring home pieces that are more used than I first expected.
And if I’m honest, while the ThredUP site is clean and user-friendly when it comes to filtering for sizes, colors, price, and the like, the photos of the clothing aren’t the most appealing. The clothing is secondhand… and it shows. It’s often floppy, wrinkled, and doesn’t quite fit the display mannequins. You only get two photos of each item, typically front and back, and the descriptions are fairly minimal.
However, all the clothing I received in my two Goody Boxes was in good shape — no tears, holes, stains, weird markings, or otherwise heavy use. A few items I received were brand new with the original tags still in place. I’ve also watched a handful of Goody Box unboxings online, and while some people had concerns with sizing and style, only one person complained about a quality issue. It’s given me more confidence in purchasing one-off resale items, at least from ThredUP.
I loved the element of surprise.
I don’t typically like a lot of surprises, but the possibility of finding something completely unexpected and perfect for me is one of the reasons I love resale shopping. Others may find digging through disorganized racks at their local Goodwill, Arc, or consignment shop tedious (like my husband), but the hunt has always been part of the appeal for me.
I was giddy when my Goody Box arrived, and I dove in with a treasure-hunting attitude. You can choose a theme for your box, such as “9 to 5 Styles,” “Take Me Out Outfits,” or “Tropical Getaway,” if you’d like a little more control, but you can also pick the “Just for You” custom mix and let your stylist go wild (or classic, or boho, or whatever you ask of them). As thredUP co-founder and CEO James Reinhart admits in a letter sent with my first box, “We know we won’t get it all right all the time,” but their mission is to “inspire a new generation of consumers to think secondhand first.”
When it came to my boxes, Reinhart’s quote hit it on the button. I did receive some of the brightly colored items I requested, but I also received two leather purses, a leather skirt, and a petite-size dress for my 5-foot 7-inch body. They went straight back into the box, and when they asked why I was returning these items, I made sure to let them know. (It is worth noting that a few weeks after giving this feedback to thredUP, the company sent me a “Second Chance” email. It explained that they had noticed I didn’t love many items in my box, and if I was willing, wanted to give me a deposit-free opportunity to try another. I get that they want to sell more product, but I did appreciate that someone noticed — and, of course, I said yes.)
The cost is low.
While ThredUP does charge that non-refundable, $10 upfront fee for its Goody Box service, you do get the 10 bucks back as a discount if you keep and spend at least that much on an item.
In the box, you get about 15 items in minimal packaging — each priced to fit the “ budget per item” cost you choose when you sign up. I selected the lowest possible, $20-$40, which seemed high to me, until I realized it’s really just a guide. About half of the designer label clothing and accessories I received came in around $12 an item. I felt like most of the prices were comparable to those I typically find at a locally owned boutique consignment shop I frequent.
A big cardboard box, cheery polka dot tissue paper, and some bubble wrap is the extent of what you’ll find around your nicely folded items — all of which you can reuse when packing up for returns. Shipping is free, as are returns, which are processed through the U.S. Postal Service. You’re not required to commit to a subscription plan, so you can order as many or as few times as you like, on your timeline.
Compared to Stitch Fix, which charges a creditable $20 stylist fee for items that average $55 apiece, or Trunk Club, which sends items in the $100-to-$300 range and charges a $25 creditable stylist fee, ThredUP’s Goody Boxes are a consignment-shop caliber bargain.
The impact is potentially high.
No, I don’t anticipate that a Goody Box will change your life. The impact I’m referring to here is the environmental one — which, of course, you can contribute to simply by buying secondhand locally or online. The Goody Boxes just offer another way to access the resale market and make an impact on the world around you.
“Fashion is the second-most polluting industry in the world surpassed only by petroleum,” wrote Emily Farra in Vogue last fall. “Basically, when you buy something old and previously-loved, you’re extending its lifespan and reducing its carbon footprint. Picking up brand-new clothes all the time (and disposing of them just as quickly) drives demand for nonstop manufacturing, which contributes to the fashion industry’s incredible waste.”
Cheers for more options.
Related Articles
- Here’s My Secret to Saving Money on Quality Clothes
- Some Thoughts on Subscription Crates and Monthly Delivery Clubs
- Five Reasons to Love a Clothing Swap (and How to Host Your Own)
- The Deceptively Tiny Wardrobe
The post Secondhand Clothes from a Personal Stylist: I Tried ThredUP’s ‘Goody Box’ Service appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2vw95pU