More than half a year after March storms ripped through the area, National Park Service employees are still trying to clean up the mess.While crews have managed to remove thousands of downed trees from the Delaware Water Gap National Recreation Area, they are still fighting an uphill battle that will last into 2019.“We got hit really, really hard with those nor’easters back in March and they brought down thousands upon thousands upon thousands of trees on trails [...]
Source Business - poconorecord.com https://ift.tt/2Ngurzp


الجمعة، 24 أغسطس 2018

Need a Ride to the Polls Nov. 6? Lyft’s Offering Free and Discounted Trips
That’s why Lyft announced it’ll offer free and discounted rides across the U.S. on Election Day.
The ride-hailing company will cut the cost of trips in half Nov. 6 for those with a special Election Day promo code. Lyft’s partnering with organizations including Vote.org, Nonprofit Vote and TurboVote, which will distribute the 50% off promo code nationwide.
Other partner organizations, like Voto Latino, the Urban League and the National Federation of the Blind, will help people in underserved communities get access to promo codes for free rides to the polls.
In a company blog post announcing the Election Day discounts, Lyft pointed out that an estimated 15 million registered voters didn’t vote in 2016 because of transportation issues. The blog post also cited a Pew Research Center report that shined a light on populations not likely to vote in advance of the 2014 midterm elections. Forty-six percent of people not likely to vote had annual household incomes of less than $30,000, and 43% were in racial and ethnic minority groups.
Offering transportation discounts on Election Day is not new for ride-hailing apps. Both Lyft and Uber — and the car-sharing company Zipcar — offered free and discounted trips during the 2016 presidential elections. We’ll be watching to see if other companies follow suit with Lyft this year.
Nicole Dow is a senior writer at The Penny Hoarder.
This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.
source The Penny Hoarder https://ift.tt/2LpbzMX
Here’s What a Required Minimum Distribution Is (and How It Affects You)
Something we don’t talk as much about is taking your money out when retirement comes.
Many people know you have to wait until a certain age to withdraw without penalty, but what you may not know is that there are penalties if you don’t withdraw by a certain age.
The government provides tax protection over your retirement accounts for what it considers your working years, but it doesn’t want to miss out on its cut forever. That’s why most retirement accounts have required minimum distributions, or RMDs for short.
An RMD is the minimum amount you are required to withdraw from your retirement account each year after you turn 70 and a half. You get the withdrawal, and Uncle Sam gets income tax on it.
6 Things You Need to Know About Required Minimum Distributions
RMDs aren’t inherently bad. Most of us want to use the money we spent years waiting for, and there’s no avoiding taxes on most accounts. But there are some important things you should know about them that will help you prioritize how you save now and how you withdraw later.
Laura Adams, host of the “Money Girl” podcast, told us the six rules every investor should know about RMDs on her Aug. 15 episode.
1. All Retirement Accounts Have RMDs… Except One
All tax-deferred retirement accounts, except for the Roth IRA, have RMDs. That means any retirement plan — whether individual or from an employer. Even a Roth 401(k) and Roth 403(b) are subject to minimum distributions once you’re 70 and a half.
That makes the Roth IRA a great tool for young investors, because you can let the money grow tax-free for the rest of your life.
2. Some Retirement Plans Have Exceptions
If you’re not sure how much to save for retirement, you’re likely to undersave. That means you could need to work beyond age 70 and a half.
If that’s you, as long as you’re working for an employer with a retirement plan such as a 401(k) or 403(b) that you’re contributing to, you can defer RMDs on that account. That would be a good reason to roll over any 401(k)s from past employers into your current 401(k).
3. Your RMD Amount Will Change Every Year
The amount you’re required to withdraw depends on a few variables, including how much is in your account and your life expectancy. It’s necessary to use an online calculator to get a clear prediction of yours.
Because these variables change every year, so does your RMD. Distribution requirements typically move on a bell curve, increasing for the predicted first half of your retirement and decreasing in the second. You can always withdraw beyond your RMD, but unfortunately, you can’t credit the excess toward the next year’s requirements.
4. Different Accounts Can be Subject to Different RMD Rules
If you have multiple retirement accounts, each will have its own RMD rules, so it’s important to calculate them separately.
RMDs from multiple IRAs can be combined for an aggregate RMD. However, if you have separate 401(k)s, you’ll need to withdraw separately for each one — again, a great reason to roll over your 401(k) to your current employer’s or a traditional IRA whenever you leave a job.
5. Rollovers Can Protect You From Some RMDs
While both the Roth 401(k) and Roth 403(b) are subject to RMDs, you can roll them into a Roth IRA tax-free.
You can also do a Roth IRA conversion from your traditional IRA. It preserves money you want to keep invested in the market, which is especially good if your retirement savings are low. But remember, you’ll pay tax on the conversion, so this might not be the best option if you’re in a high tax bracket.
6. There Are Fees For Not Complying
Depending on when your birthday is, your first RMD must be taken by Dec. 31 of the year you turn 70 and a half, or by April 1 of the following year. If you forget or decide you don’t want to comply, you’ll be charged income tax and a penalty equal to 50% of your unwithdrawn RMD.
This article contains general information and explains options you may have, but it is not intended to be investment advice or a personal recommendation. We can't personalize articles for our readers, so your situation may vary from the one discussed here. Please seek a licensed professional for tax advice, legal advice, financial planning advice or investment advice.
Jen Smith is a staff writer at The Penny Hoarder. She gives money-saving and debt-payoff tips on Instagram at @savingwithspunk.
This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.
source The Penny Hoarder https://ift.tt/2Pxegzr
Strategies To Get Life Insurance with High Cholesterol
High cholesterol can be sneaky dangerous for your health.
It can also hurt your chances of getting quality life insurance.
A high cholesterol ratio tells life insurance underwriters you’re more likely to get heart disease, have a heart attack, or have a stroke.
If this happened and you died, your insurer could end up paying your policy’s death benefit a lot sooner than they expected.
So underwriters respond to high cholesterol by either rejecting your application or charging higher premiums.
For a consumer, this trend can create a frustrating Catch-22: Your high cholesterol may mean you’re eager to have coverage in place, yet your high cholesterol is also the reason you can’t access the best coverage at the best rates.
Applying For Coverage With High Cholesterol: Your Insurance Company’s View
 I’ll share some strategies below to help insurance shoppers with high cholesterol.
First, though, let’s take a look at how insurance companies look at your cholesterol readings and how your readings fit into the bigger picture of the life insurance underwriting process.
Not Always High vs. Low
We think about cholesterol as high or low, and for good reason: That’s usually how our doctors talk about it.
Insurance companies tend to be more interested in your cholesterol ratio, though.
We have two main kinds of cholesterol:
- Good cholesterol: HDL (high-density lipoprotein) can actually help preserve your arteries.
- Bad cholesterol: LDL (low-density lipoprotein) tends to block arteries and strain your heart.
If the good kind of cholesterol drives up your readings, that’s not so bad, and your ratio of HDL vs. LDL will communicate the news to insurance underwriters.
Your ratio will normally be expressed as a low number.
For instance, a 2 is really good, whereas a score of 6 means you could use some work.
To find your ratio, divide your LDL number by your HDL number.
Different Rate Classifications
Cholesterol, of course, isn’t the only factor underwriters consider.
Here are some more considerations:
- Blood pressure
- Body mass index
- Resting pulse
- Age
- Family health history
- Occupation
- Driving record
- Credit score
- Other criteria (depending on your insurance company and your state’s regulations)
So unless cholesterol is your only area of concern, you need to consider several issues to improve your rate classification and access the best life insurance rates.
For now, though, we’ll stick with the topic at hand: high cholesterol.
Some Strategies to Make Finding Coverage Easier
Many people don’t know about their high cholesterol until they apply for life insurance and take a medical exam.
Which means you and your life insurance company learn about your high cholesterol simultaneously.
At that point, you have a decision to make: continue the insurance application process and pay more than you’d expected, or pump the brakes and consider other options.
You can avoid this dilemma by scheduling your own medical exam, including a standard lab panel, before applying for insurance.
This way you can see where you stand before your insurance company finds out.
No matter how you discovered your high cholesterol, use the strategies below to come up with your plan for getting the perfect coverage!
Strategy 1: Lower Your Cholesterol
I’m not a doctor, and I’ve never even played one on TV, but I think this is worth mentioning right out of the gate.
If high cholesterol is the primary barrier between you and affordable, medically underwritten coverage that can protect your family for decades, you could solve the problem by lowering your cholesterol.
Here are some practical tips for lowering your cholesterol:
- Cut back on the red meat, fried foods, etc., and eat more vegetables, fresh fruit, whole grains, and lean meats.
- Start exercising.
- Give it some time. A year from now, if you stick to your plan, you could feel better and have a lower cholesterol reading.
- Have your doctor prescribe medication to help your cholesterol. There are plenty of medications for managing high cholesterol.
I know, I know — this plan might not work.
Maybe you can’t wait a year before getting coverage…
Or high cholesterol runs in your family and there’s not enough broccoli in the world to help.
Pro Tip: While depending on medication may not look as attractive to underwriters, showing you’ve gotten a health problem under control works to your advantage.
Getting fit is one of the best tips for getting affordable life insurance.
And it’s not just your rates that will improve; you’ll be bettering your overall health.
Talk to a doctor to make a plan for your specific health needs.
Strategy 2: Insist on Medical Record Updates
If you’ve been diagnosed with high cholesterol but have gotten the problem under control, make sure your doctor’s office updates your medical records.
More and more insurance companies rely on electronic medical records, and if yours are out of date, you might not be getting credit for your improving health.
Pro Tip: If you’re young and pretty healthy other than the high cholesterol reading (and if you need a lot of coverage to protect your family’s financial future) this may be the strategy for you.
Read on for strategies not involving treadmills.
Strategy 3: Lower Your Standards for Coverage
Wouldn’t it be nice if insurance underwriters simply never found out about your high cholesterol?
It turns out that’s not a far-fetched idea.
Many life insurance companies offer no-exam life insurance policies, and they perform just the way you think.
You apply for coverage, answer a questionnaire about your health, and more often than not, get approved for coverage, often within a day or two.
Sound too good to be true?
It’s not, but (you knew this was coming, right?) there’s a catch, a few catches actually:
- Less coverage: Coverage amounts for no-exam policies tend to be significantly lower than medically underwritten (with exam) coverage. You can find medically underwritten coverage up to $2 million; no-exam coverage usually caps out around $250,000 to $350,000.
- Higher premiums: Despite the lower coverage amounts, premiums will be much higher for no-exam coverage. Medically underwritten term coverage offers some of the lowest rates out there. No-exam premiums live on the other end of the price spectrum.
- Delayed access: Some no-exam policies won’t pay the full death benefit if you died during the first couple years you have the policy. Instead, they’d pay a percentage or would simply refund the premiums you’d already paid.
Truth be told, no-exam coverage just isn’t as robust as medically underwritten coverage.
How could it be?
Underwriters base premiums on risk.
Without a medical exam, they know very little about the risk your policy would create to the company’s bottom line.
So if you have growing kids and want to fund their college career or a spouse who would need to pay off the house if you died, no-exam coverage probably won’t be up to the task.
This no-exam strategy would be best for older applicants who need less coverage.
Pro Tip: Use the no-exam option to buy time: You could get a no-exam policy to have at least some coverage while you work on lowering your cholesterol so you can access better medically underwritten rates in a year or two.
Strategy 4: A Sweet Spot in the Middle
So far we’ve talked about lowering your cholesterol, and we’ve talked about paying more for less coverage with a no-exam policy.
Both these strategies will leave many people out in the cold.
Isn’t there some middle ground?
Some way to get quality coverage without joining a health club and waiting a year?
The short answer is yes, but doing so requires some patience and inside knowledge.
Many insurance companies place your application in a category to help set your premiums:
- Preferred Premium
- Preferred
- Select
- Standard
Your cholesterol ratio is only one of dozens of factors that help determine your category.
If you can find an insurance company that tends to give applicants with higher cholesterol ratios more preferred rates, you could save a lot on premiums compared with a standard rate at another company.
The trouble is, these sweet spots can be moving targets as companies regularly change their underwriting criteria.
What works this year may not help an applicant next year.
Pro Tip: Work with an independent life insurance agent who can navigate these tight channels. Independent agents work with a variety of insurance companies, so they have a lot of inside information to guide you toward the right company at the right time.
Generally speaking, I’d recommend the following companies for applicants with a history of high cholesterol because, over the years, I’ve noticed applicants with high cholesterol have done well with these providers:
 Banner Life — Banner Life is a great company for a variety of reasons.
I’d recommend them for most any life insurance applicant.
More favorable rates for people with higher cholesterol ratios is a nice bonus.
 ING Reliastar — I like ING Reliastar’s approach because men and women have different criteria for cholesterol ratings.
Every little bit helps.
If you can squeeze into a better rating category, your bank account will thank you.
Prudential — Prudential is a rock-solid company which has been consistently less
picky about cholesterol ratios over the years.
Prudential is a great choice if you have any high-risk conditions which might hinder your access to affordable coverage with other popular providers.
Other Ways to Keep Life Insurance Costs Down
It’s easy to get hyper-focused on a problem area when shopping for life insurance.
While there’s nothing wrong with focusing on one area, such as your cholesterol ratio, remember: life insurance has dozens of moving parts, any of which could impact your premiums.
How Much Coverage You Need
This should be a no-brainer, but it’s easy to overlook: The more coverage you buy, the more you’ll pay.
If $500,000 in coverage would help your family pay off the house and put aside some money for future living expenses, stick with that coverage amount.
Increasing coverage to $1 million could mean you’re paying for more peace of mind than you need.
Not sure how much coverage you need?
Most people think 5 to 10 times your annual income should be enough, assuming you have people who depend on you financially for the foreseeable future.
Giving Up Tobacco Products
Yes, cholesterol and blood pressure impact your premiums, but tobacco really clouds things up, posing the biggest threat to affordable premiums.
If you smoke, quitting and making a long-term commitment to stay away from tobacco can save exponentially on your monthly premiums.
For a lot of people, quitting tobacco can lead to other health improvements, which will make your insurance rating even happier.
Term vs. Whole Coverage
Term life usually saves money because it lasts for only a specific period of time, usually ranging between 10 and 30 years.
When the policy expires you can reassess your needs and get a different policy, continue paying a higher rate, or do without coverage if you don’t need it.
A whole policy lasts the rest of your life, and your premiums also fund a cash account you can access later in life.
If you’re young and need a lot of coverage, keep things simple and save with a term policy.
Decide If You Even Need Coverage
What’s the most affordable life insurance?
That’s easy: The most affordable life insurance is not having to buy life insurance.
If you’re older, have a healthy financial portfolio, and feel confident your dependents could carry on just fine financially if you died, you may not need life insurance coverage.
That being said, life insurance is remarkably flexible.
You could use a policy to fund a scholarship in someone’s memory or get coverage simply to make sure your dependents have cash available while they liquify your assets.
Work with an estate planner or a financial advisor to make these plans, then make sure your family knows about them.
The Best Coverage is the Coverage Best for You
Your individual challenges — factors like high cholesterol, a dangerous occupation, or a tight monthly budget — can make getting quality life insurance coverage difficult.
Congratulations on sticking with it and looking for the best way to protect your family finances from the unexpected!
You must already know having the right life insurance coverage can make a tremendous difference for your family members.
If high cholesterol has prevented you from getting coverage, stick with it.
Try to control your cholesterol and look for other ways to save on premiums.
And don’t hesitate to ask for help!
Leave a comment below or find an independent agent in your area.
The post Strategies To Get Life Insurance with High Cholesterol appeared first on Good Financial Cents.


Source Good Financial Cents https://ift.tt/2w8MEsg
How to Run Contests That Encourage User-Generated Content
Are you looking for a new way to spice up your marketing strategy?
Your current promotions may be effective for now, but you need to mix things up. After a while, using the same marketing tactics over and over again gets stale.
Promotional contests are one of my favorite ways to keep an audience engaged.
This is a great opportunity for you to increase brand awareness and even build hype for a new product launch.
The best promotions give something away to participants.
There are a few different types of such promotions.
Contests require some type of skill. People who enter a contest will need to put forth some type of effort in order to win. The winner of a contest gets selected by judges or through a voting system.
This differs from a lottery or sweepstakes.
Sweepstakes do not require any skill whatsoever.
The winners of sweepstakes get drawn randomly, based on luck. For example, you could randomly select one of your Instagram followers as a winner just because they follow your brand’s account.
A lottery requires a participant to purchase something to be entered into a draw.
Today, I won’t focus on sweepstakes or lotteries.
Contests are a better alternative because if you set them up properly, they will encourage user-generated content (UGC).
User-generated content increases the chances that your audience will engage with your advertisements:
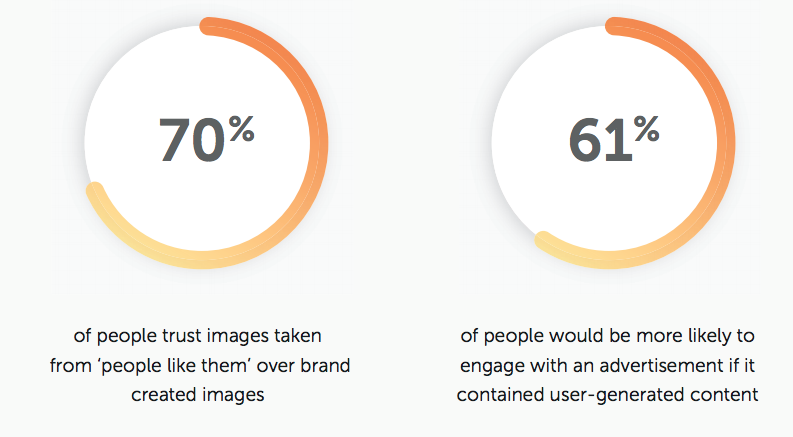
As you can see from these numbers, encouraging users to share images will be beneficial as well. It’s only natural to use this information to your advantage when you’re setting up a contest.
If you have never run a contest before, you may not know where to start. That was my inspiration for writing this guide.
I’ll explain how you can run a profitable contest that encourages user-generated content.
As a result, you’ll be able to generate more leads and ultimately increase your profits. Here’s what you need to do.
Pick a prize
The first step in running a contest is determining what the winner will get.
This may sound simple, but it still requires some thought on your end. The more valuable the product, the more likely people will participate.
For example, if you’re giving away a t-shirt, it won’t get anyone very excited. But if the contest winner receives something like a new camera, drone, or pair of sneakers, it’s much more enticing.
I’m not saying you need to give away the most expensive product your company sells, but make sure your prize is worth the time and effort required for people to enter.
This will help you get greater participation. Just look at how the value of your prize impacts the engagement rates:
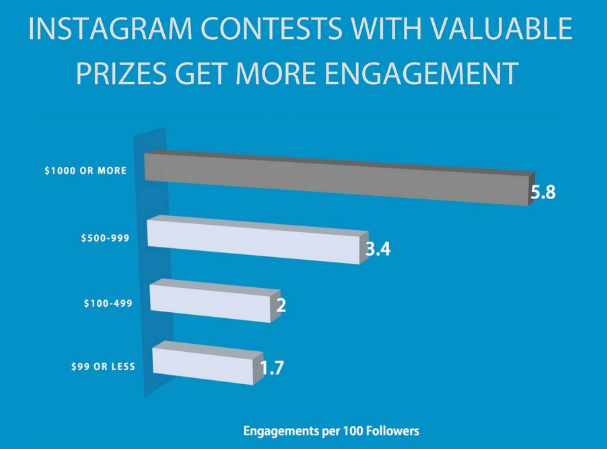
Your prize also needs to be appropriate. For example, let’s say you have a business that primarily targets teenagers. You probably shouldn’t be running a contest for a free trip to Las Vegas.
It’s not appropriate for your audience, and it doesn’t speak to them. Instead, giving away one of your newest products is a much more reasonable prize idea to consider.
Make sure your prize is related to your marketing goals.
Ask yourself what you’re trying to accomplish and promote with each contest: a product, service, or event. The prize should align with these goals as opposed to being a random giveaway item.
Establish the rules
Your contest needs to have clearly established rules.
Explain how people can enter to win. Come up with a deadline for entries.
Narrow down the eligibility of your contest, based on things such as age or location. For example, depending on the prize and your brand, you may be offering the prize only to residents of the United States who are at least 21 years old.
Let people know that purchases aren’t required to enter and that making a purchase does not increase the chances of winning the contest.
The criteria participants are being judged on need to be clear as well. Here are some examples to consider:
- best photo based on judges’ discussion
- photo with the most likes
- comment with the most likes
- highest number of retweets
- most number of shares
I like it when brands use criteria such as likes or shares to determine the winner as opposed to relying on a judge’s decision. That way it’s clear to everyone who won, and people won’t think you’re playing favorites. But I’ll leave that for you to decide.
You also need to share the odds of winning, privacy laws for revealing the identity of the contest winner, and the date and time the winner will be announced.
All of this needs to be clear so that it’s fair and everyone understands the rules. Otherwise, there could be some confusion.
For example, let’s say you run a contest in which the winner is determined by the comment with the highest number of likes. But you forget to set a deadline.
You pick a winner, but a few weeks later someone else gets more likes on a new comment. How will you handle that?
You won’t take a prize away from someone who already won. But you won’t want to tell the other person it’s too late because it could hurt your relationship with them.
You may be forced to give away multiple items. This confusion will be avoided if the rules are clearly established.
Select a platform
How will you run the contest?
- Snapchat
- Website
All these options may seem viable, but remember, you’re trying to encourage user-generated content. That’s why you need to choose platforms where participants can see submissions from other participants.
Social media works best for this purpose. Running a contest on social media will help your account grow faster.
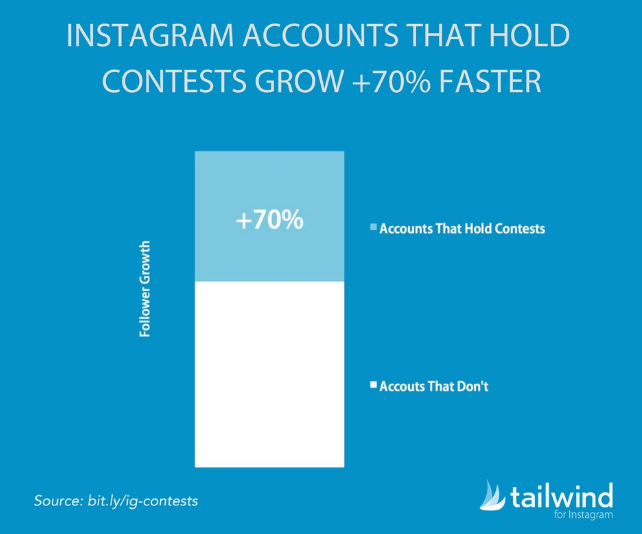
Platforms such as email and Snapchat wouldn’t be helpful for this type of contest.
You can still use your website to run a contest based on UGC. Just use the forums section or a dedicated landing page for user submissions.
Running the same contest on multiple platforms and selecting a winner from each one is also an option. Or you could run the contest on just one platform but promote it on all your distribution channels.
For example, if you’re running a Facebook contest, you can use Instagram, Twitter, your website, and email list to promote it.
You want to pick the platform that will generate the best response. If you have 1,000 Twitter followers and 20k Instagram followers, it obviously makes more sense to run your contest on Instagram.
Create a unique hashtag for the contest
Use hashtags as a promotional tool. It’s a great way for people to enter your contest.
For example, let’s say you’re running a contest on social media with user photos. You are encouraging participants to upload images to their personal profiles.
But how will you find them to judge them? By having the participants add a hashtag to the caption.
This strategy has many benefits. For starters, it will keep you organized so that you can run a fair and legitimate contest. It will be clear to everyone who enters.
But it also puts all those pictures in one place.
Now people who enter will see the photos submitted by other people who don’t follow your brand or follow people who submitted the photo.
This helps increase brand awareness and grow your social media following.
If you’re struggling to think of a good hashtag, you can use an online tool such as All Hashtag to help you generate one:
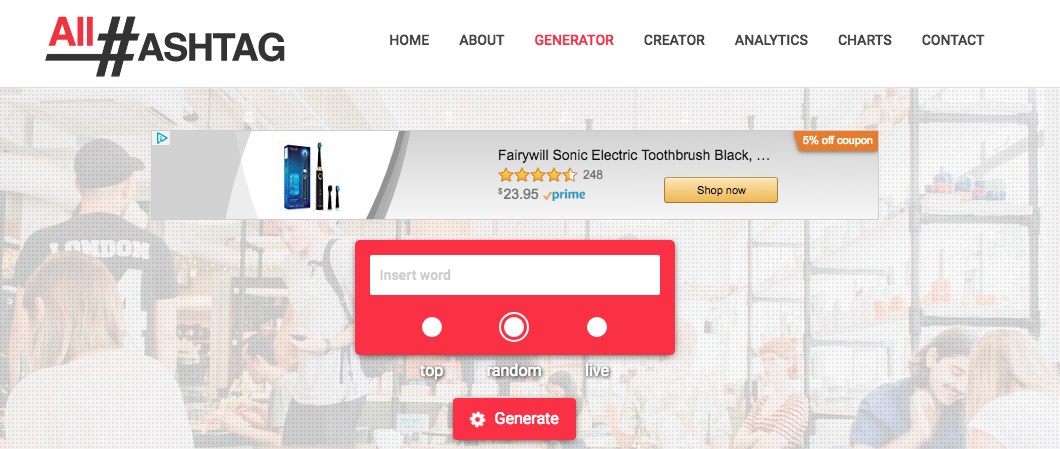
Be creative, but keep it simple.
Think about the readability of your hashtag. You can capitalize the first letter of each word to make it easier for people to read and understand.
Run contests encouraging likes, comments, and shares
This addresses the user-generated content aspect of contests—your ultimate goal.
If you run a contest on Instagram and tell your followers to enter by sending you a direct message, this action will not create UGC. But encouraging people to like, comment, and share will definitely do the trick.
You want them to complete these actions on your posts as well as their own.
Run photo contests or best comment contests. Reward people for getting the most likes or shares on their posts.
These are all great ways to encourage user-generated content.
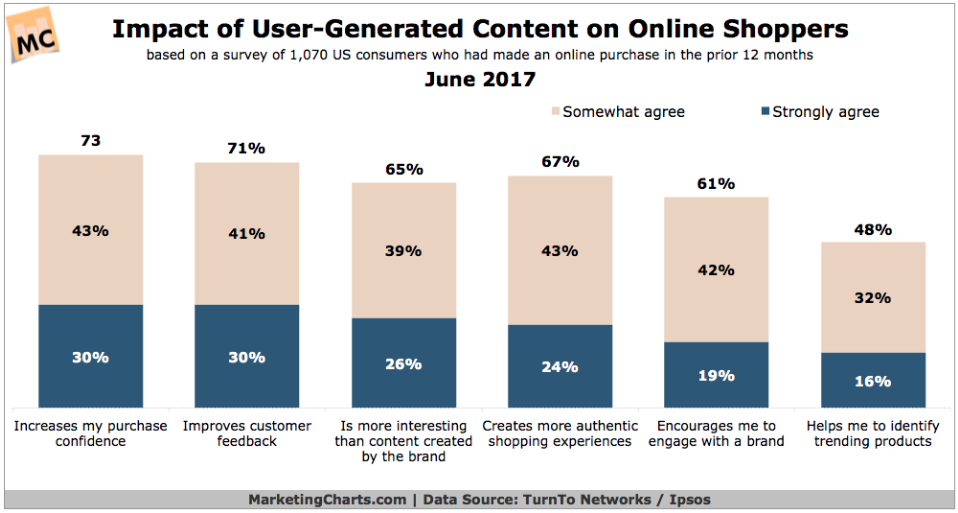
As you can see from these numbers, user-generated content will ultimately help you boost ecommerce sales on your website.
The numbers above show that UGC increases the chances of online shoppers making a purchase. That’s because your promotion stays on their minds.
They may not visit your website every day, but they’re active on social media.
The contest serves as a reminder of your brand. Even if people aren’t participating, they’ll still see it.
Promote your contest
You’ve launched your contest, posted the rules, and set a deadline. That’s great.
Now what?
Don’t just set it and forget it. Continue posting updates and reminders about the contest. Leverage all your distribution channels for this.
- Create a video promotion.
- Blog about it.
- Send an email to your subscribers.
- After someone makes a purchase on your website, direct them to a landing page promoting the contest.
- Use a live video promotion to build hype for your contest.
- Post daily reminders on your Instagram story.
Your followers may not have seen your original post from last week. But your story can serve as a countdown and constant reminder that you’re running the contest.
All this will help you get the highest number of participants and ultimately the most user-generated content.
Leverage relationships with social influencers
Influencers can help you promote your contests through their profiles.
Now your contest will be shown to a new audience, who may not know you or follow your brand on social media.
Have influencers promote contests the same way you did. Tell them to share the rules, set a deadline, and promote the hashtag.
The idea behind this strategy is to create social proof:
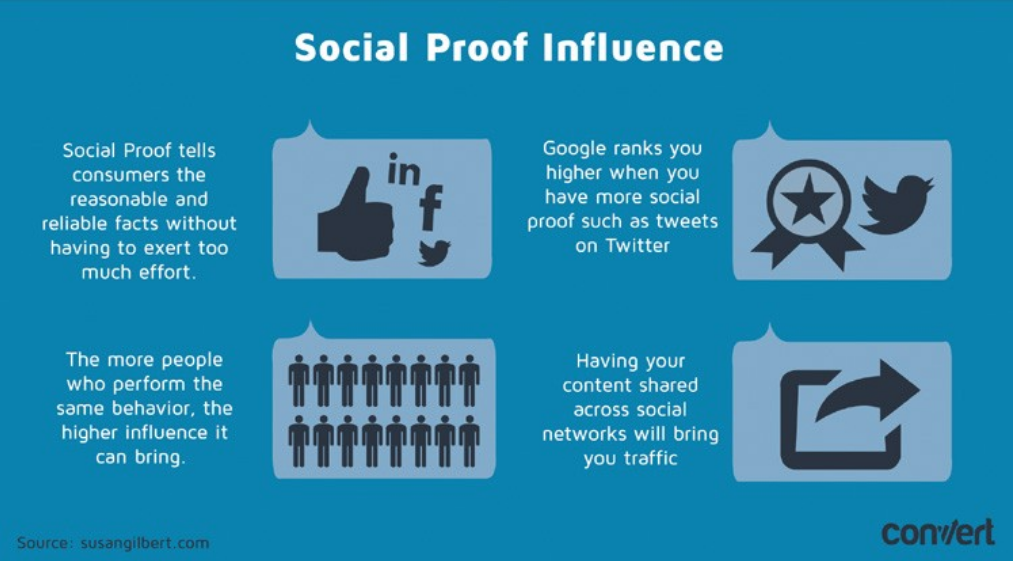
People are more likely to trust and follow recommendations from real people whom they follow on social media.
You can approach this strategy in a couple of ways:
- You could have influencers direct their followers to your page. They’ll use the same hashtag, entry rules, and deadline you’ve established.
- You could let the influencers run their own contests. Create a new hashtag, deadline, and prize for them to give away.
Now more people can participate even if they don’t want to follow your brand.
Running multiple contests increases the number of participants and the amount of user-generated content created for your company.
Pick a winner
When someone wins the contest, you need to take the time to announce it. Make this seem like a big deal.
Share the winning entry so everyone can see it. Tag the winner’s social media profile.
Just make sure to clearly describe all these aspects of your contest in your original rules. You don’t want to violate someone’s right to privacy without their permission.
Announcing the winner will have many benefits.
First of all, the winner will feel great, enjoying the praise. As a result, they will become a loyal customer and will be more likely to buy from you in the future.
They may even share a “thank you” post that will be seen by their followers.
Announcing the winner also shows people your contest is legitimate. Take a look at this Mint blog post, announcing a contest winner:
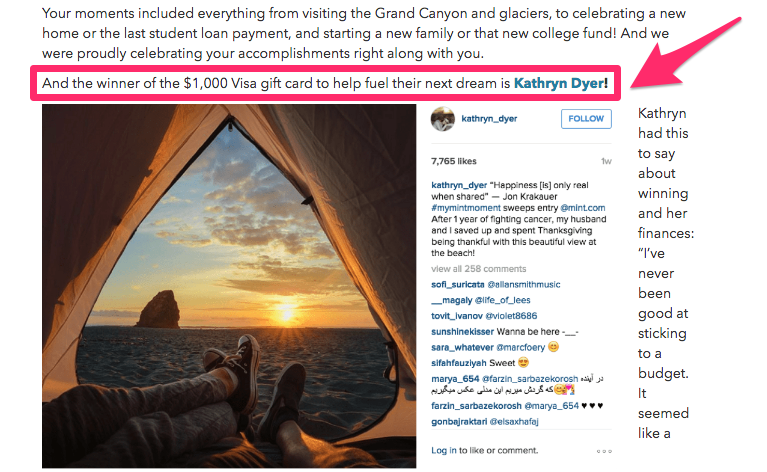
As you can see, Mint tagged the user profile and shared a screenshot of the winner’s post.
Now people know the contest was real and a real person won. Anyone can verify this by clicking the profile and referring to the entry.
This also gives more people an incentive to enter contests run by your company in the future. They’ll want to get the same praise and recognition for their efforts as this winner did.
Run contests on a regular basis
If you run lots of contests, you’ll generate tons of UGC.
Switch things up. Try running contests on different platforms to see which ones work the best.
Change your prizes.
After running several contests, you’ll be able to tell which ones had the highest participation.
I’d say it’s in your best interest to leverage your social media accounts for contests.
It’s a great place to encourage user-generated content, and it promotes brand loyalty: 53% of people who follow brands on social media are more loyal to those companies. Those are the types of people whom you want to target.
Once you figure out which contests were the most successful, you can continue running those.
Conclusion
Contests are a great way to build brand awareness.
But running contests that encourage user-generated content is even more effective because they can ultimately drive sales for your business.
Select a prize with a high value and relevance to your target audience. Otherwise, people won’t have an incentive to participate.
Explain the rules so everyone is on the same page. This will help you avoid confusion down the road.
Decide which platform you want to run the contest on. You could even run a contest on multiple platforms.
But no matter what you decide, you’ll need to promote it on all your distribution channels. Use social influencers to help spread the word as well.
Come up with a unique hashtag for each contest. Run contests that encourage likes, shares, and comments.
Make it seem like a big deal when you announce the winner.
Continue to run more contests in the future to get the most user-generated content for your brand.
What platforms does your brand use to run contests that encourage user-generated content?


Source Quick Sprout https://ift.tt/2PyIUZ9
“I’ll Never Catch Up”
It’s a feeling that a lot of us get after we spend our early adulthood not really worrying about our personal finances while some of our peers are actually making great moves. We finally wake up to the financial mess we’ve created (good) and take a bunch of steps to fix things (good), but then we look around at the financial state we’re in and recognize that we’re way behind where we “should be” (bad).
Sarah and I were once in our late twenties with more than $10,000 each in student loan debt, more than $10,000 each in car loans, somewhere around $20,000 in combined student loan debt, and several thousand dollars in additional debt for things like furniture. We barely had enough in our savings account to cover a meal at a restaurant, let alone an actual emergency, and we lived in a tiny apartment. The one good thing we both did in that era – our single good financial move – is that we signed up early on for our workplace retirement plans (something we’re incredibly grateful for today).
We woke up to our financial reality and we started fixing things as fast as possible. We eliminated all of that debt. We bought a house and then paid that off in less than five years.
Even then, we both had this underlying sense that we would never catch up to where we should be, that we would never catch up to where some of our friends were in their financial journey. We would never catch up to where we should be.
“I’ll never catch up” became a comfortable unspoken refrain, an understanding that we’ll never truly make up for our earlier financial mistakes, that we’ll always be behind the curve of where we could be.
There’s a core problem with that line of thinking, of course. It’s incredibly lazy. The idea that we’re “behind” and that we can’t “catch up” comes solely from benchmarks we invented in our own head.
We have this idea that we’re “behind,” right? What is it that we’re behind? Are we “behind” someone who’s earned a much higher income than us? Are we “behind” where some personal finance writer told us that we should be at our age without knowing a thing about our life? Are we “behind” our own ideal of where we should be based on unrealistic expectations of a perfect life?
Here’s the truth: our sense of being “behind” and “never being able to catch up” comes from benchmarks that are never actually based on reality. They’re entirely figments of our own imagination, based on comparing ourselves with the social media presence of others, with people who have had perfect lives and perfect support, with the ideals of personal finance writers who have nothing to do with us, and with completely unrealistic expectations. None of those things are real, at least not in the sense of actually understanding the reality of our life.
There is one – one – benchmark that matters: you.
Where were you financially a year ago? How about five years ago? Are you better off? Substantially better off? Then you’re doing well.
What if things aren’t going so well? Well, consider this: where would you be had you not been practicing good financial principles over the last year or two? How bad would the debt be then?
The idea of “catching up” is rooted in comparisons with the lives of others, people whose lives really have no complete meaningful overlap with your own. Trying to “catch up” to someone who has a different job than you, with different pay and benefits and different responsibilities and different time commitments and different stresses, is silly. Trying to “catch up” to someone who might have a spouse earning a lot more than you are is silly. Trying to “catch up” to someone who may have parents or others providing financial support – or who did provide financial support earlier in their lives – is silly.
I can name fifty reasons why trying to “catch up” to someone whose story you only partially know is utterly silly, but I think you get the idea. Comparing your life to someone else’s is pretty much impossible because the details are so different, even between people who might seem kind of similar at a quick glance.
The truth is that the only worthwhile comparison to you is you. No one else has the set of experiences that you have, for good or bad. You don’t know what’s going on backstage in other people’s lives. You don’t know how that compares to your own life. You just don’t have nearly enough information about anyone else’s life to make a good comparison to your own life.
So, before you spend even another ounce of energy comparing yourself to someone else and buying into the notion that you’ll “never catch up,” I have a few challenges for you.
First of all, sit down and take a snapshot of your financial life as it is right now. Make a big list of your significant assets – your home (if you have one), your cars (if you have any), your checking account, your savings account, any investment accounts you may have, and any other possessions you might have with significant value. Try to figure out what the value of those possessions are.
Then, make a big list of all of your debts – every business or person to whom you owe money. Write down the balance of each of those debts.
Then, add up the total value of all of the assets, then the total value of all of the debts, then take the total assets and subtract the total debts from that. This gives you a single number – your net worth. Save that.
After that, put a reminder on your calendar to calculate your net worth again in one year. Just put a new entry somewhere, whether it’s on your wall calendar or on Google Calendar or on the Reminders app on your phone. Just put it somewhere where you’ll see it in one year.
Now, for the next year, make a conscious effort to be more financially responsible. One easy way to do that is to open up a retirement account at work or open up a Roth IRA for yourself if your workplace doesn’t offer it and start funding that retirement account automatically by setting up a direct withdrawal from your paycheck or from your checking account. Consider an automatic transfer from your checking to your savings to fund an emergency fund, too.
Along the way, try to avoid accumulating more debt. Try to make your loan balances and credit card balances go down. Make an extra payment or two. Your goal should be, at the end of each month, to have a lower overall debt balance than at the start of the month unless there is a very good reason for it. Even if the change is small, you should be aiming to make it happen.
While you’re at it, try being a bit more careful with your spending. There’s no need to become a frugalista, but just move forward on some simple ways to save money. A good place to start is with the list of “frugal improvements” I wrote recently – money-saving tactics that were so beneficial in other ways that I would stick with them even if they didn’t save money.
Give it a year (if you have that much patience) or at least a few months and then calculate your net worth again. See how the total compares to your old one.
That’s “catching up.” That’s financial progress, the only kind you can meaningfully measure in this world. Everything else is a broken or unfair comparison.
If you’re doing well and making good financial choices, your net worth will be quite a bit bigger than the last time you measured it. If you’re not doing well, that net worth will shrink.
If it’s shrinking, make sure you know why. If it’s a big reason, like a big expense that couldn’t be avoided, that’s okay, but at all other times, your net worth should be growing. If it’s not growing and you can’t come up with a really good reason that’s about a fundamental need in your life (or, if you have a lot in retirement, a market downturn), then you’re making some big mistakes.
If it’s growing, take pride in it. Aim to keep that progress going and make the leap even bigger next time.
It’s that comparison to self that matters. There is no “catching up” with that comparison. There is no “I’ll never be able to do it” with that comparison, because virtually anyone can grow their own net worth with a little effort. The self-comparison numbers don’t lie.
Don’t worry about “catching up” to people besides yourself. Instead, worry about “beating” the pace you were on yesterday. You’ll end up in a good place if you do that consistently.
Good luck.
The post “I’ll Never Catch Up” appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2Ne5yEC
I Divorced Him a Year Ago, but I Can’t Get His Debt Out of My Life
Even once the divorce papers are signed, the act of uncoupling can remain stressful for years to come. It’s easy to look at the challenges before you and feel doomed. After all, divorce was supposed to make your life better, not complicate it further.
But even in these difficult days, it’s vital that you stay focused on acting in the best interest of your future self. Today you might want to hide and hope these problems go away. But your future self will be grateful you took charge.
Here are a few steps you can take to get as much of this straightened out as possible.
Depending on the time you have available and your energy levels, these tasks could take some time. Be kind to yourself as you formulate your best plan of action.
- If you haven’t already, pull your free credit report to determine exactly what debts are in your name versus which are still shared. See something that doesn’t make sense or that you swear was taken care of already? File a dispute with the credit reporting bureaus. Then keep track of those disputes until they’re resolved. It will be helpful to have your divorce paperwork handy — you may need to provide copies of it to the credit bureaus or any companies you contact to have your name removed from an account.
- Schedule an appointment to sit down with someone at your credit union. First, you’ll want to go over what you can do to be more creditworthy in their eyes. Developing a relationship with someone at your local branch can help you get questions answered more quickly — and it never hurts to have someone else looking out for your interests when it comes to your finances.
- You can also talk to your credit union about the possibility of refinancing your auto loan. Refinancing the car in your own name may not be an immediate option if you’re trying to rebuild your credit, but it could be an option down the line. In the meantime, be hypervigilant about your car loan, and make sure your payment history on it is spotless.
- Do not give up on paying down your debt. No matter how small your payments are, you are making progress. If you can only pay $20 per month toward your debt, do it. This may take years, but you are doing your best. Don’t forget that. Every day, you are doing your best.
The inbox is open. Submit a question or send your worries to dearpenny@thepennyhoarder.com, and I’ll see what I can do to help.
Disclaimer: Chosen questions and featured answers will appear in The Penny Hoarder's “Dear Penny” column. I won't be able to answer every single letter (I can only type so fast!). We reserve the right to edit and publish your questions. Don’t worry — your identity will remain anonymous. I don’t have a psychology, accounting, finance or legal degree, so my advice is for general informational purposes only. I do, however, promise to give you honest advice based on my own insights and real-life experiences.
Lisa Rowan is a senior writer at The Penny Hoarder.
This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.
source The Penny Hoarder https://ift.tt/2NhDMH5
Can You Score Better Travel Deals Using a VPN?
There’s an endless number of affordable vacation options you can piece together if you’re flexible and want to save some cash. You can sign up for travel credit cards to earn airline miles and hotel points, for example. You can book an inherently frugal vacation option such as a budget cruise or a rental condo on a beach. Heck, you can plan a frugal camping trip or a road trip and spend next to nothing on your next family vacation.
Still, there are a few other, trickier ways to save on travel if you’re hoping to game the system. One strategy involves installing a VPN on your computer with the goal of hiding your true location.
With a VPN, you may be able to access prices you couldn’t get on hotels and airfare where you live. And these savings may come a lot easier than you think.
What Is a VPN?
Before you consider using a VPN to scout for travel savings, it helps to understand the tools you’ll need and how they work. So, what is a VPN anyway?
VPN stands for virtual private network. With this in mind, having one basically grants you your own private connection to the internet. With a VPN, you can hide not only your online actions but also your true location. The VPN does this by using software that encrypts your data before anyone can see it.
With a VPN, any website you use will note your VPN and its location, not where you actually are. Further, your online actions will be hidden from prying eyes that may be able to access your network otherwise. That’s why many businesses and travelers often install a VPN on their computers. With a VPN, you can safely log into your corporate email, bank’s website, or other personal accounts without worrying about someone stealing your password or accessing sensitive personal information.
How Can Using a VPN Help You Save Money on Travel?
And this is where the travel savings can come in. According to Sarah Barnard of BestVPN.com, travel companies (airlines, hotel brands, travel discount websites, etc.) often provide you with a quote for your vacation that can vary based on where you reside and the local currency. Sometimes customers will see different prices for the same flight or hotel on the same dates depending on that information. Your browsing habits may even play a role in the price you’re quoted for travel — specifically, whether you’ve searched for the same trip or flight over and over again.
With that in mind, some experts say that using a VPN can help get you a better price. With a VPN that changes your location, you can search for flights and airfare as if you were a customer elsewhere in the world.
You may find better prices on flights if you search out of the country you’re visiting instead of your departure country, for example. This kind of strategy typically takes some research and trial and error, but the savings are often there for those who look.
How to Use a VPN to Save Money on Airfare and Hotels
Harold Li at ExpressVPN.com notes that using a VPN to check for lower prices on airfare, hotels, and vacation packages is an easy feat to master. “By changing server location through a VPN and researching prices, it’s possible to find better deals and save hundreds of dollars on certain travel purchases,” he says.
To save on travel with a VPN, Li suggests taking these steps:
- Clear your cookies on your preferred browser.
- Connect to a VPN server in a different city, state, or country.
- Open a private (Incognito) browser window, then shop for options and take notes.
- Repeat this process until you find the best price.
You may need to perform quite a few searches to find a discount on travel with a VPN, and you’ll obviously need to do some searching without your VPN on so you have a price to compare. While the savings may be worth it, trying to save on travel with a VPN is a lot like shooting arrows in the dark: You may hit a bullseye or be totally off the mark. But you’ll never know unless you try.
It’s also important to note that the process isn’t entirely foolproof. For example, Barnard notes that sometimes your cookies can give your location away, and that this can squash your chance at a discount.
“Cookies are used to track your online activity on any site, and if you’ve used the travel provider in the past, it’s likely they’ve already got a good idea of where in the world you are,” said Barnard. Like Li, Barnard suggests opening a private browser so you can disable your cookies before you search.
Also know that sometimes payment can be a challenge. Even if you find an affordable flight online, the website you’re booking with may ask for details you can’t supply.
“The site may ask for a local billing address or you might get stung by unfavorable exchange rates and fees,” says Barnard. A credit card that doesn’t charge foreign exchange fees may be of help here, but you may be out of luck if a travel vendor won’t let you book without a local address.
- Related: Best Travel Credit Cards
The Bottom Line
If your goal is saving money on travel and you have a VPN already, it can’t hurt to do some digging to see if you can find lower prices on airfare, hotels, and other types of travel. The worst that can happen is you’ll use your time and effort without getting any results.
Also remember that there are plenty of other ways you can save on travel, including travel rewards, shopping for deals, and choosing vacation options that are inherently frugal to begin with. With a little research and some out-of-the-box thinking, you can hopefully find the perfect trip — one that’s ideal for your vacation needs and your budget.
Holly Johnson is an award-winning personal finance writer and the author of Zero Down Your Debt. Johnson shares her obsession with frugality, budgeting, and travel at ClubThrifty.com.
More by Holly Johnson:
- My Seven Favorite Ways to Save Money on Travel
- Three Times Travel Deals Are Actually More Expensive
- Why I’ll Never Feel Bad About My Vacation Spending
The post Can You Score Better Travel Deals Using a VPN? appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2Nf2x6Z
الخميس، 23 أغسطس 2018
It’s Like Magic: Disney Will Pay Full Tuition Upfront for Hourly Workers
On Tuesday, The Walt Disney Company launched Disney Aspire. Disney Chairman and CEO Bob Iger announced the initial $50 million investment into the program back in January. This benefit is available to all hourly employees and offers a wide array of diplomas and courses with tuition paid upfront.
The program includes a network of schools offering college and master’s degrees, high school equivalency, vocational training and English-language classes. Plus, employees won’t have to worry about startup costs as Disney Aspire covers 100% of tuition upfront and reimburses application fees, books and materials.
The launch announcement states that the program is designed with working adults in mind, offering flexibility with their education. Disney Aspire does not require that the courses selected be tied to the employee’s role with the company.
So now is the time for the more than 80,000 hourly Disney workers and cast members in the U.S. to hit the books — Mickey’s picking up the bill.
Matt Reinstetle is a staff writer at The Penny Hoarder.
This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.
source The Penny Hoarder https://ift.tt/2MJiWDG
Download This App Before Aug. 26 for a Chance to Win $500 to Disney
It’s been super steamy down here in Florida, anyway, and California’s been going through a heat wave — downright miserable. Waiting until October or November will be way better.
Plus, you just might have a $500 Disney gift card in hand by then.
Enter to Win a $500 Disney Gift Card in Less Than 3 Minutes
Shopkick is a shopping rewards app. You can earn “kicks” each time you shop online or in store. You can even earn kicks when you walk into a store or scan an item’s barcode — without making a purchase.
You exchange those kicks for gift cards to popular retailers.
This weekend (Aug. 24 through 26), Shopkick will automatically enter you into its Disney giveaway when you download and use its app to earn qualified kicks.
Snag those kicks when you do any one of the following:
- Use your linked credit card to make a purchase at a qualified retailer. Popular ones include Target, Walmart, Best Buy and CVS.
- Take a photo of your receipt from a qualified retailer.
- Make a purchase online at Walmart, Groupon, Etsy, Overstock or any other qualified retailer, through your Shopkick app.
Shopkick will award a winner by Aug. 31. Winners will receive $500 worth of kicks, good for that Disney gift card.
And if you’re not keen on traveling to the parks, get a head start on holiday shopping. The gift card is good for The Disney Store, too.
Carson Kohler (carson@thepennyhoarder.com) is a staff writer at The Penny Hoarder. She hopes to visit Disney when the weather cools down, though that seems like a faraway dream right now.
This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.
source The Penny Hoarder https://ift.tt/2OWh8Vc
Score $100K Toward College by Winning the Dr Pepper Tuition Giveaway
Well, this might just be what the doctor ordered.
Dr Pepper will award five grand prizes of $100,000, five runner-up prizes of $25,000 and 10 consolation prizes of $2,500 as part of its annual collegiate giveaway.
The decade old scholarship has become a college football tradition, and winning it takes a combination of brains and brawn.
To take home one of the 20 prizes, all you have to do is share that world-altering goal in a video, get selected as a finalist and then compete against another finalist during a conference championship game halftime to see who can throw the most footballs into a giant Dr Pepper can in 30 seconds.
NBD.
(And if that seems like too much NOPE right now, be sure to like our college page on Facebook. We post awesome new scholarship opportunities there whenever we find them.)
Who Can Enter the Dr Pepper Tuition Giveaway?
You must be 18 to 24 years old by Nov. 30, 2018, and a legal resident of the United States to enter the giveaway.
If you’re not enrolled in an accredited college or school yet, no problem. The funds will be applied to your tuition once you enroll.
The finalist on-field showdown has to be fair, so applicants cannot be active NCAA athletes or have played professional or semiprofessional sports.
How to Submit an Entry for a Dr Pepper Scholarship
You’ll need to jump through some hoops before you start perfecting your pass. First, register an account with the Dr Pepper Tuition Giveaway.
Then, remember that goal we talked about?
Well, you’ll have 50 characters to tell the judges what it is and then another 350 characters to elaborate on it.
No pressure, amirite?
Fortunately, the next step is a 60-second video where you can let your personality shine and really woo them.
The video should be on topic, expand on your academic and professional goals and tell how winning the tuition giveaway will make an impact on your life, your community and the world.
Including a Dr Pepper product in the video and demonstrating creativity, passion and good presentation quality will go a long way with the judges.
A quick internet search will turn up the videos of past finalists so you can size up the competition.
Check out the official rules for all nitty gritty deets before you get rolling.
How to Win the $100K Dr Pepper Prize
We can’t help you land this one. If your video gets selected, you still have to battle it out on the field.
There’s debate about whether an overhand throw or a chest pass is better. Re-watch old halftime videos and you’ll see a combination of determination, luck and skill.
One thing is for sure: You need to practice.
The good news?
If you make it as a finalist, you get an all-expense-paid trip for you and a guest to one of the five conference championship games, and you’ll leave with at least a consolation prize.
The deadline to enter is 11:59 p.m. Pacific Time on Oct. 17, 2018, so start peppering up those videos right now.
Winners will be notified by email.
If you’re looking for even more scholarships to apply for, be sure to check out our list of 100 scholarships that will help you pay for college
Stephanie Bolling is a staff writer at The Penny Hoarder. She’s pretty good at Skee-Ball and air hockey.
This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.
source The Penny Hoarder https://ift.tt/2LokfTL
The Frugal Improvement: 15 Money-Saving Tactics I Ended Up Liking Better, Regardless of Dollars and Cents
One of the biggest reasons that I still like trying frugal tactics after many years of living a fairly frugal lifestyle is that finding a true “frugal improvement” still feels like a really big win to me.
So, what’s a “frugal improvement”? Frugal improvement is my term for any tactic I use that was originally implemented to save money but wound up being a noticeable improvement for non-money reasons. For example, let’s say I used to do something that cost $30 a month and I figured out how to trim it to $15 a month and I wound up being happier with the new way regardless of the money, such that if price weren’t a factor, I’d still choose the new way.
Here are 15 such “frugal improvements” I’ve brought into my life since our financial turnaround. Each of these has saved us significant money, but even if it were not for the money, I would not undo these changes because they’re strictly better than the more expensive option for non-financial reasons.
Switching to LED light bulbs
LED bulbs have hit a quality level such that they work well for pretty much every home use. I generally cannot tell the difference other than the slight pause that occurs right after hitting a light switch as an LED turns on – incandescents are instantaneous.
LEDs save money over incandescents due to their reduced energy use and long lifespan. A 60 watt incandescent bulb lasts about 1,000 hours. A 13 watt LED bulb has similar light output and lasts about 25,000 hours. If you assume that energy costs $0.12 per kilowatt hour, over the course of 25,000 hours, that single LED bulb consumes $39 in energy, whereas the 25 incandescent bulbs would consume $180 in energy. Even if an LED cost $100 you’d still save money on just energy consumption alone.
However, the big reason I’d stick with LEDs is time and convenience. Incandescent bulbs seem to burn out constantly – with a lifespan of only 1,000 hours, an incandescent bulb in a heavy use room burns out every few months. That means finding a new bulb, swapping them out, and disposing of the old one, and doing it every few months for years and years – a task that vanishes entirely if you use a LED bulb. This is even worse if the bulb is inconvenient at all to reach. Given this inconvenience, I’d stick with LEDs even if they didn’t save money on energy use at this point.
Making bulk meals in advance
Making a bunch of meals in advance and freezing the extras saves money because you can buy the ingredients in bulk and use them before they go bad. Tomatoes are on sale? Time to make lasagna with fresh tomatoes… and you can make a lot of lasagna with fresh tomatoes at that discounted tomato cost. That makes each pan of lasagna cheaper than it otherwise would be.
The real advantage, however, is that making a bunch of meals in advance and freezing them gives you the ability to quickly get a homemade meal on the table on inconvenient evenings. If I know that Thursday night is going to be really tight in terms of our family’s schedule, I can pull out a frozen lasagna on Tuesday and let it thaw for two days. Then, on Thursday, all I have to do is bake it for an hour – straight from the fridge into the oven, with no extra prep time. This reduces the meal prep time on that busy evening to virtually nothing – it’s actually easier than going to a restaurant at that point, with less time investment.
Make ahead meals are definitely a money saver compared to going out to eat, but it’s the time savings that makes it a real winner for us. I’d make meals in advance even if they didn’t save money.
Eating oatmeal for breakfast most mornings
When I was younger, I didn’t really like oatmeal much at all, and it turns out that the big reason for that is that I didn’t like the preprocessed “flavors” of instant oatmeal. They always tasted kind of off to me and thus I was unable to really appreciate oatmeal.
Fast forward to today and I eat oatmeal for breakfast most mornings. Sometimes I’ll just microwave a bowl for myself. Other times, I’ll make a batch of steel cut oats in the slow cooker for the whole family to eat for breakfast.
What changed? I figured out that the secret is flavoring it myself. “Fake maple” flavor is terrible – a few drops of real maple syrup is incredible. “Freeze dried” fruit bits are terrible – a bit of chopped-up banana is amazing. You can make your own things, too – I will often make a “savory” oatmeal with things like scrambled eggs and hot sauce instead of sweetener.
Oatmeal is now one of my favorite things to eat, period, and particularly for breakfast. It’s incredibly inexpensive, but it’s also healthy and tasty and has a lot of variety because it’s something of a food “blank slate.” I’m so glad that my frugal sensibilities convinced me to give it another chance.
Intentionally going back through my media collections (and Netflix series)
Over the last several months, I’ve slowly been re-watching Star Trek: The Next Generation in the late evenings while folding laundry. My oldest son and my wife have been slowly re-watching The Flash together.
One of my summer projects has been to pull out all of my old Pearl Jam CDs, accumulated since my high school days, and digitize and listen to all of them. This includes a lot of live concert CDs. I found myself listening to each album several times as I did this.
All of these things were part of media collections that have been around our house for a long while or part of an online subscription service that we use for other reasons. This slow practice of going back through those media collections have brought forth a new appreciation and a new joy for those things.
The thing is, this process has actually saved us some money on media expenses. We haven’t gone to the theater in months. We haven’t bought any new music in months and actually turned off our Spotify account. We finally “cut the cord” for our satellite not too long ago as well. Our media collection and our Netflix subscription sustains us because we’re recognizing how much great older content we have sitting around already.
Going on lots of hikes and walks
I used to view walking and hiking as a rather dull activity, but in the aftermath of our financial turnaround, my wife and I started taking lots of walks around our town, pushing our baby in a stroller. Soon after that, when he became a toddler, we started going to parks and hiking on trails.
For some reason, I found those things really peaceful. It was an opportunity to step out of the hubbub of life, get my body moving a little, and appreciate the natural world and the community around me.
Today, walking and hiking is a major part of my life. I go on a walk to clear my mind at least once or twice a day, and once a week I’ll go somewhere and go on a hike or a nature walk, spending a few hours in the woods with no distractions at all, just soaking it all in.
It started as something to fill the hours that didn’t cost anything. It turned into something that’s a big part of my life, refilling me in ways that many expensive hobbies simply failed to do.
Making an attempt to fix minor home repair issues myself before calling a repairman
After moving from an apartment to our current home, I was somewhat afraid to try to repair things myself. I used to just call the landlord for fixes, so the idea of doing something like fixing a leaky toilet or replacing a faucet or replacing a light fixture seemed really intimidating.
Of course, that meant that I would have to call in a repairperson to fix minor home issues – and that’s expensive. They charge by the hour and charge expensive rates for the items they use as well.
So… I tried to do it myself. I started with something simple – repairing a downstairs toilet that was constantly running at a very slow rate, which doesn’t seem like a big deal except for the constant noise and the constant water usage which amped up our water bill.
I watched YouTube videos, I assembled the tools and a couple of parts, I turned off the water… and lo and behold, I fixed it. It took me about half an hour, but that honestly is how much time I probably would have invested finding and contacting a plumber and paying them for the work.
This built some confidence, and then further successes built more confidence. This summer, Sarah and I have done a ton of little projects – replacing light fixtures, hanging doors, replacing faucets, dealing with a problematic pump, and so on.
Yes, sometimes I mess up my own attempted repair, but I can often recover from that, and when I can’t, I know how to turn off the water and the power so that nothing truly bad happens and I can always call a repairperson.
Even if it wasn’t for the money saving factor, I’d still try to do minor things myself. Why? It enables me to do them on my own time, and it makes me feel confident about doing gradually bigger and bigger projects around the house.
Using a cheap pump bottle for shampoo and conditioner in the shower
In the old days, if I had a bottle of shampoo that I bought at the store, I’d stick it in the shower. Then, when I needed to shampoo my hair during a shower, I’d grab the bottle, flip it over, squirt some arbitrary amount on my hand, put it back on the shelf, and wash my hair.
It turns out that this is actually an expensive way of doing things, mostly because of that “arbitrary amount” of shampoo. I’d almost always end up getting way too much, far more than was necessary.
I tried various ways of cutting down on the amount that I used, but they were more trouble than they were worth. Until, that is, I tried using a pump bottle.
The new process goes like this. When I need new shampoo, I buy a new bottle at the store. I get home and instead of just sticking it in the shower, I go in there, open up the shampoo pump bottle, and then turn the new shampoo bottle upside down, letting it run into my pump bottle. I let it sit like that, with the new shampoo bottle inverted and slowly pouring into my pump bottle. The next time I take a shower, it’s all poured out, so I screw the pump back onto the pump bottle and discard the emptied-out shampoo container from the store. Then, when I want to shampoo, I simply take a single pump from the bottle (it’s all I need for my perpetually short hair) and scrub down with it.
It takes just a little bit longer to “replace” a bottle, but it saves just a little bit of time when I’m actually in the shower, as getting a single pump on my hand is easier than grabbing the bottle and flipping it over. Given that this is a lot of pumps, it ends up being a time saver.
It’s also a money saver, because one pump of shampoo is a lot less than I can get straight out of the shampoo bottle from the store.
Still, even if it wasn’t for the money issue, I’d continue to do this because it makes morning showers more efficient, and since I’m often showering in the narrow window after my wife showers and before the kids are starting to get ready for school, a shorter shower is usually a good thing.
Using a slow cooker for a lot of meals
Our original driving reason to cook more meals at home was to save money. We fully believed that it was very time inefficient to make anything other than convenience foods at home, but that it was clearly a money saver to do so. We viewed this as an exchange of time for money – spend some time cooking supper at home and you save money compared to a restaurant. Easy enough, right?
Well, over time, we began to realize that the time thing isn’t entirely true. Going to a restaurant is a time commitment, even if it’s just a fast food drive thru. You are investing some amount of time there if you’re doing it. Similarly, cooking meals at home can often be really quick – I’ve made some stunningly fast pasta meals and other things at home.
The real game changer in this equation, though, was the realization that shifting the time for the meal preparation made a huge difference. As I noted earlier when talking about make ahead meals, by simply moving the work to another part of the day or the week or the month or the year, away from the super-busy evenings into the less pressured mornings and weekends, you end up really making cooking at home pretty convenient. Most of the time, on the really busy evenings, it’s far easier just to eat at home than to eat out if most of the prep work is done.
That’s where a slow cooker comes in. It moves the prep work from the busy evening to the less-busy morning (and even a bit into the night beforehand). I can just toss ingredients into the slow cooker in the morning, turn it on low, and supper is ready to go in the evening. I can even do some of the prep right before bed the night before – things like chopping up vegetables work well when I’m doing mindless chores just before bed.
Having a slow cooker meal ready to go whenever we need it makes evening planning on busy nights much easier, even easier than grabbing takeout or delivery. You just go home and serve it straight from the slow cooker whenever you want. That’s it. Throw everything in the sink and deal with it later.
This saves a ton of money over restaurant foods, but even better, it makes our evenings easier. Because of that, I’d still make slow cooker meals even if it didn’t save us money because of how the slow cooker smooths out difficult evenings for us.
Playing previous generation video and computer games
Rather than constantly buying new release video games and computer games, we wait around for four or five years and buy previous console generations and games for those consoles and buy top computer titles from a few years back instead of the latest ones. While video games aren’t a big part of my life, I do enjoy playing them on a rainy day or taking a turn in a big strategy game late at night every once in a while.
Doing this serves a bunch of purposes at once. For starters, it’s way cheaper than buying new releases. Games cost us more like $5 than $50. It’s the other reasons, though, that are real interesting.
Second, games that are mature have all of the bugs worked out of them. New releases often have problems and crash sometimes; those kinks are almost always gone a few years later.
Third, the games that are still respected and talked about several years later are almost universally great experiences. Mediocre games released with a bunch of hype are almost entirely forgotten three or four years later; great games are still around and they’re still great experiences.
Fourth, the system requirements for computer games that are a few years old are really easy to meet. I don’t need to keep upgrading computers to play games.
Finally, it’s really easy to find good strategic advice online if I want to find it when a game is mature. When a game is new, the info can be really shoddy and misleading; as a game matures, the information gets much better.
At this point, I don’t really even want to play new releases. Let the early adopters figure out what’s great and what isn’t. Let the kinks get worked out. Let the software age so I don’t need burning-edge hardware to play it. And, of course, let the price drop through the floor.
Shopping for many things at a thrift store or secondhand store first
When I need new clothes, I shop at secondhand stores and consignment shops first. When I need a minor kitchen appliance, I do the same. There are just lots of little things that I look for first at secondhand stores.
You might think that this is purely a money-saving tactic, but it’s not, particularly for the clothes. The biggest reason I do this is that I often find unusual stuff that I would have never found looking at a website or looking through the racks at stores I typically shop at. I actually get interesting things there.
Yes, you have to leaf through a bunch of crap to find it, and some secondhand stores are way better than others (shop at secondhand stores on the outskirts of expensive neighborhoods and you’ll find great stuff, for example). Having said that, two of my favorite shirts that I own came from secondhand stores where I dug through the racks for a while until I found something really interesting and nice. My single favorite sweater I own came from a secondhand store.
When I’m there, I usually look for other things, too. Our rice cooker came from there and it’s actually a better rice cooker than I would have bought for myself brand new.
You have to dig, but secondhand stores have treasures hidden away, and although money is certainly a motivation, there are many other reasons to shop there.
Buying a late model used car, then driving it until repairs become a problem
Growing up – and well into my twenties – my car-buying philosophy was to buy the nicest car you could afford and then swap it every few years before it “lost trade in value.” You should avoid driving an old car if you could possibly afford to do so.
The thing is, I would have never challenged that approach if it were not for my financial breakdown. This forced me to change my pattern, causing me to stick with my red truck for several more years than I intended. I then sold it for cash and bought an older SUV with cash.
What changed my perspective? I began to realize that the most important thing I got out of a car was reliability. If I couldn’t go out to the driveway and rely on that car to start, what’s the point? Cars exist, in the end, to convey people and things from point A to point B.
Does this car reliably get me to where I need to go? If yes, I’ll keep it. If no, it’s time to move on and get a car that will get me reliably to where I need to go for several years.
That’s the primary motivation behind our car purchasing strategy. I want to achieve that strategy with the lowest total cost possible, and the way to do that seems to be to buy late model used cars – the kind of cars that are recently coming off of leases or are cars put aside by habitual upgraders – and then drive them until they no longer seem reliable, then trade that in (or sell it) for a late model used replacement.
This is the strategy I would follow even if car prices didn’t matter. I would follow the strategy that kept a reliable car in the driveway and just do whatever version of that strategy made cars cost the least for me.
Sticking tightly to maintenance schedules
The obvious reason to follow a maintenance schedule for your expensive items (your car, your furnace, your big appliances, and so on) is that the cost of replacing a big item is pretty high and if, by following the maintenance schedule, you can postpone that expense, you’re saving money. That’s absolutely true.
However, the counterargument against that is that following a maintenance schedule takes time, which is why many people skimp on it and do the bare minimum.
I’ve found the opposite to be true. Every moment spent on preventive maintenance on anything – your car, your home, your appliances, yourself – isn’t a moment “wasted.” It’s a moment that’s more than made up for by delaying the experience of having to make a major purchase.
If proper car maintenance keeps my car running fine for longer and keeps it out of the repair shop for an extra couple of years, I’ve drastically reduced the amount of time dealing with repairs over the course of my life and also reduced the amount of time I’m shopping for a new car. I’m also reducing the time spent having to deal with the consequences of a car breakdown and of a major appliance breakdown. Those are big time wins.
Yes, maintenance takes a bit of time, but it’s pretty flexible time and it’s usually not much time. That time is more than recouped by not having to deal with repairs or replacements nearly as often.
I’d do maintenance even if it didn’t save money, just because it saves a little time and moves that time around to my convenience.
Making a lot of staple foods
My family likes eating sauerkraut. Most of us love the stuff and we use it in a lot of things – on sandwiches, in salads, or even as a side dish.
Sauerkraut can be expensive at the store, but the actual ingredients are cheap – it’s literally just cabbage (about as cheap as a vegetable gets) and salt and about 20 minutes of your time with a month long break in the middle of that 20 minutes. That’s all you need to make a gallon of sauerkraut – it’s way cheaper than buying it.
But that’s not the real reason I make it. The real reason I make my own sauerkraut – and a few other staple foods – is because the homemade version just tastes better. My favorite method of making sauerkraut is to use about 10% radish to 90% cabbage and put in some black pepper and a bit of garlic during fermentation. It creates a flavor that I dearly love that I’ve never matched anywhere else.
I make sauerkraut at home, not because it’s cheaper (though this is true), but because it tastes way better.
The same is true for a few other staples. I love making a big pan of homemade marshmallows on occasion, and I’ll save them for the world’s most amazing s’mores. I love making my own hot chocolate mix. I love making my own cold brew coffee in large quantities.
Although those things are all far cheaper than just buying them at the grocery store, I make them myself because they taste better and, honestly, they don’t really take very long at all to make.
Riding a bicycle for nearby errands
I live about a mile from the post office, a little more than a mile from a library, and about a mile and a half from a grocery store. I can reach these places on foot in reasonable time, and sometimes I do that, but it’s not exactly speedy. A round trip to any of those places can eat up almost half an hour (or more).
Driving a car there is much much faster, but it’s expensive. Doing it eats gas and puts miles on the odometer, bringing maintenance closer.
For me, the best balance is to just take a bike there. I pack what I need to take in my backpack, bike to where I need to go (which is almost as fast as taking the car), do what I need to do, bike home (again, almost as fast as the car), and I’m done. Not only did I do it without spending any money, I got some exercise along the way and it essentially didn’t eat up any time.
I bike to the library and the post office and the park and the store quite often, just because it’s an efficient way to get exercise. I’d do it even if I wasn’t saving a little money compared to using the car.
Drinking tap water
Drinking water is a healthy choice. Bottled water generally tastes good. Tap water… well, it depends on location. Here, it has just a bit of a chlorine taste.
However, there are two big disadvantages to bottled water. One, it costs way more than tap water. Two, it takes more effort than tap water – you have to bring home lots of bottles from the store. The advantage? No real chlorine taste.
So, how do I move the scale even more on the side of drinking tap water? I use two main tricks. One, we have a water filter attached to our sink that gets rid of the chlorine taste – but that’s not the big one. The other thing I do is that when I’m boiling water for tea or something, I boil a lot of water, let it cool in the kettle while drinking my tea, then pour that cooled water into a reusable bottle and stick it in the fridge with a bit of lemon juice.
That boiled then cooled water with a bit of lemon is the best water there is. I would rather drink it than virtually any bottled water I’ve ever tried. There’s no chlorine taste and just the slightest hint of lemon – and it’s dirt cheap.
I don’t boil water for the sole purpose of filling a water bottle, but I do drink tea fairly often and when I do, I just boil a bunch of extra water while I’m doing it – it doesn’t take any extra time or effort. Then, an hour later or so, I fill up a water bottle and stick it in the fridge – again, minimal effort. That “bottled water” is amazing and is practically free. I’d prefer it even if it cost the same as actually buying bottled water.
Final Thoughts
One of the best benefits of frugality is that it convinces you to try new ways of doing things that you might never have tried before. The benefit of doing that is sometimes you discover that there’s another way of doing things that’s just strictly better than the previous way in terms of aspects that have nothing to do with money.
That’s what “frugal improvements” are all about. Sure, it saves money, but that’s not the real reason I do some of these things. Saving money might have started me on the journey, but it’s the taste or the time or the convenience that becomes the real reason for keeping that strategy around.
To me, that’s the best kind of frugality. It doesn’t just save money, but provides other benefits in your life.
Good luck!
More by Trent Hamm:
- How Much Time Do Frugal Strategies Take? Five Time-Tested Techniques
- My Favorite ‘Little Wins’: 12 Simple Frugality Tips That Just Work
- 15 Things I Did This Year to Save Money
The post The Frugal Improvement: 15 Money-Saving Tactics I Ended Up Liking Better, Regardless of Dollars and Cents appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2o2yG6P
الاشتراك في:
الرسائل (Atom)