This Labor Day, test your labor "averageness" against some of these statistics available from Gallup and the Bureau of Labor Statistics.
Source CBNNews.com https://ift.tt/2LPUo7D


السبت، 1 سبتمبر 2018

Inspiration from Yo-Yo Ma, Benjamin Franklin, Brene Brown, and More
Once a month (or so), I share a dozen things that have inspired me to greater personal, professional, and financial success in my life. I hope they bring similar success to your life.
1. Mark Epstein on talking to your past self
“It’s one of my theories that when people give you advice, they’re really just talking to themselves in the past.” — Mark Epstein
I can certainly vouch for this. There are many, many posts on The Simple Dollar that are the result of me working through some financial (or other) issue in my life, trying out something, seeing if it works, and sharing the results. I’m writing it as much for myself as I am for anyone else.
That’s because, in the end, who else can I really advise? As a reader, all you can really do is take what I’ve found and shared and apply it to your own life if it fits. I can’t know whether it does or doesn’t fit – that’s up to you, and that’s a key part of all of this.
The best advice comes from someone who made a mistake, stepped back, figured out how to do things better, and moved forward. I think the best stuff I’ve shared on here follows that mold.
2. The Tables
From the description:
A look at the powerful connection between a pair of outdoor ping pong tables in the heart of New York City and the unlikely group of people they’ve brought together, from homeless people to investment bankers to gangbangers.
The Tables is a short documentary directed by Jon Bunning about a small community of people that developed around a couple of outdoor ping pong tables in a park in New York City.
This is a beautiful little film about how communities develop and grow and create a sense of belonging for people in those communities.
To me, finding a community like this for yourself, something that fills your time and brings you the joy of being engaged in something with like-minded people, is one of the most powerful things you can do in life. As long as that community is not consumer-oriented (meaning it’s not focused on the act of buying, or requires a constant purchase of new things), it’s also a great way to curb desires to constantly spend.
There are really few things better in life than walking into a room full of like-minded people who are all there for the same reason – some sort of shared interest or passion. You feel comfortable with being passionate about that thing in a way that you don’t get to in normal society without people looking at you oddly. You feel a quick natural bond with the other people there. They can quickly become friends.
Find your community. Start with Meetup if you don’t know where to go.
3. Robert Tew on self-respect
“Respect yourself enough to walk away from anything that no longer serves you, grows you, or makes you happy.” – Robert Tew
This is a quote I’ve tussled with in the past. On one level, it seems to indicate that you should just walk away from responsibilities if you decide you don’t want the burden any more. Walk away from parenting? From a loving marriage? What value is there in that?
The more I look at it, though, the more I see something different. I see a call to change things in your life that you’re unhappy with rather than just tolerating them. That doesn’t mean ending your marriage, but it does mean finding a different approach if it’s not going in a healthy direction. That doesn’t mean walking away from your kids, but it does mean trying to find new ways to be a good parent.
If you’re unhappy with some aspect of your life, find a new way to navigate that part of your life.
4. Sam Maher – New York Handpan 01
From the description:
It’s a Terratonz Handpan; or called a Terrapan. Scale: C, Aeolian. – Notes: (C#)-G#-A-B-C#-D#-E-F#-G#.
A handpan is a kind of percussion instrument that you play with your hand that can produce a wide variety of tones via gentle tapping. I had the chance to play around with one a year or two ago and I found that they’re surprisingly loud and surprisingly easy to approach, though making anything other than a very basic tapping rhythm takes skill. I found that I was drawn to playing around with it but anything beyond a very very basic rhythm sounded really awful. Skill and talent are the differences.
I really enjoy hearing people busking for dollars or pocket change. I’ll almost always throw a dollar in the jar for someone playing an instrument on the street somewhere because they just add a certain flavor to the moment.
This guy? I’d definitely drop a dollar or two in his jar if I heard him playing somewhere. That’s just amazing.
5. E.O. Wilson on humanity’s problem
“The real problem of humanity … we have Palaeolithic emotions; medieval institutions; and godlike technology.” — E. O. Wilson
This, I think, sums up some of the modern difficulties that humankind is having.
Our emotions were developed during an era in which lifespans were short and civilization was nonexistent as humans were small tribe hunter-gatherers. We apply those emotions today in a world where lifespans are much longer, most humans live in cities, and we do things that have profound and lasting impact on our environment.
All around us, technology is accelerating while our emotions remain in those ancient days on the steppe. Is it no wonder that so many people are unhappy? Is it no wonder that so many people are angry? We’re not emotionally prepared for much of what the modern world is like.
6. Arbitrary Stupid Goal by Tamara Shopsin
I love the beginning of this book:
The imaginary horizontal lines that circle the earth make sense. Our equator is 0°, the North and South Poles are 90°. Latitude’s order is airtight with clear and elegant motives. The earth has a top and a bottom. Longitude is another story. There isn’t a left and right to earth. Any line could have been called 0°. But Greenwich got first dibs on the prime meridian and as a result the world set clocks and ships by a British resort town that lies outside London.
It was an arbitrary choice that became the basis for precision. My father knew a family named Wolfawitz who wanted to go on vacation but didn’t know where.
It hit them. Take a two-week road trip driving to as many towns, parks, and counties as they could that contained their last name: Wolfpoint, Wolfville, Wolf Lake, etc.
They read up and found things to do on the way to these other Wolf spots: a hotel in a railroad car, an Alpine slide, a pretzel factory, etc.
The Wolfawitzes ended up seeing more than they planned. Lots of unexpected things popped up along the route.
When they came back from vacation, they felt really good. It was easily the best vacation of their lives, and they wondered why.
My father says it was because the Wolfawitzes stopped trying to accomplish anything. They just put a carrot in front of them and decided the carrot wasn’t that important but chasing it was.
The story of the Wolfawitzes’ vacation was told hundreds of times to hundreds of customers in the small restaurant that my mom and dad ran in Greenwich Village. Each time it was told, my dad would conclude that the vacation changed the Wolfawitzes’ whole life, and this was how they were going to live from now on — chasing a very, very small carrot.
The carrot wasn’t that important, but chasing it was. I can’t think of a better way to describe my feelings toward goals. It’s the journey that matters, not the destination. Set a big goal for yourself and you’re going to change some things in your life, and it’s those things that change that matter, not the big goal itself. Change enough things and the goal just becomes a matter of course.
7. Benjamin Franklin on persuasion
“If you want to persuade, appeal to interest, not to reason.” – Benjamin Franklin
Logical arguments work well internally, when you sit down and think things through on your own. They have a great role to play in books, where open-minded people are devoting time to understanding an argument.
They don’t work so well in the real world where you’re interacting with people in real time. People are giant balls of emotion, and it is through tapping into that emotion that you’re really able to persuade people.
This is actually a big part of how I write articles that are intended to persuade people to take better financial charge of their lives. I usually strive to hit a few emotional chords in the article that hopefully will hit home with people so that they can feel what I’m talking about, not just think it. (I do both, of course.)
8. Stephen Colbert connects Chance the Rapper, Gilbert & Sullivan, and Lord of the Rings
‘The Late Show’ host Stephen Colbert breaks down how Chance the Rapper’s “Favorite Song” feat. Childish Gambino are connected to J. R. R. Tolkien’s “Lord of the Rings”.
Why did I enjoy this so much? It’s about finding patterns, something I’m going to touch on again before the end of this article.
I enjoyed this because it demonstrated deep connections between 19th century stage musicals, 20th century literature, and 21st century rap. It’s that type of connection of ideas across a wide variety of areas that is the source of a lot of great ideas and connections that not only enhance appreciation of the individual works and the connection, but often spur one’s own ideas that riff on that connection.
These kinds of connections are one of the sublime joys in my life.
9. Yo-Yo Ma: NPR Music Tiny Desk Concert
From the description:
Why did Laurence Olivier return so often to Shakespeare’s Othello? Why did Ansel Adams keep photographing the Grand Canyon? Obsessed or awestruck, artists revisit great inspirations because they believe there is yet another story to tell – about life, about themselves.
Cellist Yo-Yo Ma brought his great inspiration, and in turn part of his own life story, to an enthusiastic audience packed around the Tiny Desk on a hot summer day. Ma is returning, yet again, to the Six Suites for Unaccompanied Cello by Johann Sebastian Bach, a Mount Everest for any cellist. He has just released his third studio recording of the complete set and is taking the music on a two-year, six-continent tour. Ma’s first recording of the Suites, released in 1983, earned him his first Grammy.
Ma has played the music for 58 years and along the way it’s become something of a practical guide to living, pulling him through hardships and celebrating times of joy. “It’s like forensic musicology,” Ma told the Tiny Desk audience. “Embedded in the way I play is actually, in many ways, everything I’ve experienced.”
The undulating “Prelude” from the Suite No. 1 was the very first music Ma ever played. He was four years old. The soulful “Sarabande” from the Sixth Suite has served dual purposes, Ma explained. “I’ve played this piece both at friends’ weddings, and unfortunately also at their memorial services.” And the exuberant “Gigue,” from the Third Suite, with its toe-tapping beat, reminds us that Bach was far from a stuffed wig. Such is this sturdy, versatile and benevolent music, offering a full range of the human condition.
And then there is Ma. Certainly one of the most brilliant cellists of modern times, he’s also a thoughtful, curious humanitarian, with an endless thirst to understand, celebrate, and connect disparate cultures of the world.
He’s also a true mensch. As soon as he arrived at our office to play, Ma unpacked his cello – a famed 1712 Stradivarius – and immediately handed it over, with his bow, and said, “Here play something.” It didn’t matter that I’d never held a cello. It was just another one of Yo-Yo Ma’s warm and welcoming gestures, another way to open up music to anyone and everyone.
This is amazing to listen to, both the music and the life lessons in between the performances.
10. Brene Brown on the Photoshop era
“It’s in our biology to trust what we see with our eyes. This makes living in a carefully edited, overproduced, and Photoshopped world very dangerous.” – Brene Brown
What we see isn’t the full picture. It’s often a mix of what we want to see and what the people showing us things want us to see. Usually, the other people want to show us things that make them appear good, while we have our own self-doubts. That’s not a good mix.
Don’t believe every detail of breaking news. Don’t believe the interpretations of that breaking news from talking heads. Unless you have to make a meaningful decision based on that news, wait until the facts all come out and cooler heads prevail.
Don’t believe that the lives of people you see on social media or reality television are the glossy perfection that they’re showing you. Those pictures are no different than a Penn and Teller stage act.
Rather, believe in yourself. Learn real, meaningful things that can actually change your mind. Make your life as good as you can.
11. The Algorithmic Trap
This is an article by David Perell about the idea that vacation planning today is often done by algorithm, where people select the well-lauded experiences using tools like Trip Advisor and thus miss out on quirky and serendipitous moments that are the magic of traveling to a new place.
One sentence stood out to me:
Algorithms are great at giving you something you like, but terrible at giving you something you love. Worse, by promoting familiarity, algorithms punish culture.
People use algorithms as a time saver to find good experiences, because algorithms are great at finding things that other people have given high ratings to. However, things other people have given high ratings to rarely translate into things that you love. They just translate into things that are pleasant.
Our family had a restaurant in our area that we loved. It was in a weird location, a bit out of the way of the usual places where people went looking for food. When we’d go there, there would always be a few people in there, but it was never packed. It never had a ton of ratings on Trip Advisor and thus never made it onto their lists of top eateries in the area. Sadly, it closed up shop about a year ago.
How do you find such places you love when traveling? I don’t know, but I do know that they’re generally not found by looking at Yelp or Trip Advisor lists. The best way I’ve found really great things is by talking to locals that I’m friendly with. Those have produced some of my best travel experiences, like the weird brewpub/restaurant that Sarah and I found on our tenth anniversary getaway together that, again, doesn’t even seem to be in business any more, but exists fondly in both of our memories.
12. Aaron Swartz on curiosity
“Be curious. Read widely. Try new things. What people call intelligence just boils down to curiosity.” – Aaron Swartz
Over the years, I’ve come to realize that the best ideas I’ve ever had were ones where I was able to take one element I learned in one environment, another element I learned in another environment, and perhaps a third or a fourth or a fifth, all from different places, and combine them into one overarching idea. Those combined ideas were powerful and often led to a personal or professional or financial breakthrough for me.
Those ideas were only able to be born because I am a lifetime learner. I am constantly reading and learning and absorbing new things from all sorts of different topics and sources. Reading a book is great, but being able to integrate it into ideas from many other books on many other subjects is so much better.
Be curious. Learn about things. Try new things. See how things fit together. You will fail a lot, but at the same time, you will be constantly rewarded in doing so.
The post Inspiration from Yo-Yo Ma, Benjamin Franklin, Brene Brown, and More appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2NDqAMZ
الجمعة، 31 أغسطس 2018
This is How to Tailgate Like a Hall of Famer — Even if You’re on a Budget
It’s time for some tailgating.
Time to throw down in the stadium parking lot. Time to play some sweet tunes and grill some meats. Time to enjoy an adult beverage or two. Or three. Or six. Hey, we don’t judge.
Now, it would be nice to tailgate like a king. Grill up some T-bone steaks and lobster tails and wash it all down with Dom Pérignon, barrel-aged bourbon or some Belgian craft beer that’s brewed with truffles and juniper berries.
But we’re not going to do that. Because we’re broke.
This is The Penny Hoarder, so we’re going to tailgate on a budget.
Through extensive and exhaustive research in the field — going to many, many tailgates — we’ve learned how to do it without breaking the bank. Yes, these are the kinds of sacrifices we make for our beloved readers.
Tailgating Like a Cheapskate — But in Style
Our secret strategy is this: Make sure to get cash back when you buy food and alcohol.
Use the cash-back app Ibotta to earn rebates on groceries. Search the app for rebates as you make your shopping list, then use the app to scan your receipt once you get home with the goods. The average user earns $30 per month, according to the company.
With tailgating, where Ibotta really comes in handy is with alcohol. The app has a ton of rebate offers for beer, wine and liquor, ranging from $5 back on a case of Bud Light to $3 back on a bottle of Jim Beam.
Here are a few other tips we learned from asking an expert, Joe Cahn, who bills himself as “The Commissioner of Tailgating.”
- One key to keeping tailgating costs reasonable is to invite your friends, then get them to chip in.
- Pro tip: Park one car at the stadium and have everyone else in your group park farther away, where it’s free. Then carpool, walk or take the bus or a game-day shuttle.
- This list of tailgating recipes that will cost you less than $1 per serving includes tasty black bean dip for chips and veggies, and caramel popcorn with peanuts.
- If you’ve got an 11 a.m. kickoff, head to the grocery store that morning and check out the day-old bread and pastry section. Most stores drop the prices of breakfast favorites like donuts and muffins — your friends won’t be able to taste the difference.
- Skip Starbucks and brew your own coffee at home, then bring it with you in a thermos.
Your Big-Ticket Item: The Grill
Sure, slow cookers are nice. But in order to tailgate like a real live red-blooded American, you need a grill. How else are you going to grill meat, I ask you?
Even if you buy a relatively affordable grill, it’s still a significant purchase. And like any significant purchase, you should figure out how to get the best possible deal.
Here’s something to try. Step by step:
- Go look at grills at Lowe’s or Home Depot. Check ‘em out.
- Join Swagbucks, a site that pays you to take surveys, watch TV and shop online. It can get you cash back on purchases. You get $5 just for signing up.
- Once you’re in, shop online for the grill you want at Lowe’s or Home Depot. Swagbucks has partnerships with both. You’ll earn one Swagbuck for every dollar you spend.
- On a significant purchase like a grill, that can add up to a lot of Swagbucks. The average propane gas grill costs $100-$400, with higher-end stainless steel ones going for $500-$1,500.
- You can exchange Swagbucks for gift cards. For context, 2,500 Swagbucks will get you a $25 PayPal gift card. Basically, you’re earning 1% cash back on your new grill.
We’ll leave you with more words of wisdom from Joe Cahn, the Commissioner of Tailgating:
Ultimately, tailgating is not about the food. It’s about the people, the atmosphere and the experience.
“Food tastes better with friends no matter what food it is,” he said. “Sharing hot dogs or peanut butter and jelly sandwiches with friends is a far better time than a 10-course meal with people you really don’t like.”
Mike Brassfield (mike@thepennyhoarder.com) is a senior writer at The Penny Hoarder. He likes to tailgate before attending a game because his favorite football team is so incredibly aggravating.
This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.
source The Penny Hoarder https://ift.tt/2vSD4vh
Get Ready to Pay More for a Better Seat on United and Southwest Airlines
United and Southwest are the latest airlines to add fees that will boost the cost of flying — if you are at all particular about where you sit.
Later this year, United plans to begin charging extra for seats toward the front and middle of the plane, just behind the extra-legroom seats the airline calls Economy Plus, company spokeswoman Maddie King said. This puts the airline on a par with rivals American and Delta, she pointed out.
The seats won’t have extra legroom, but they’re more desirable to many people because they’re closer to the exit.
Travelers can avoid the fees by choosing an economy seat farther back in the airplane. The fees also will be waived for high-level frequent fliers and some corporate customers in a “preferred” program that began this month.
“It’s just kind of giving more options to customers,” King said.
If any of the seats are available 24 hours before flight time, they’ll be up for grabs for free, she said. By that time, however, it’s less likely that rows of seats will be available for families and other traveling companions who want to sit together.
Once upon a time, not that long ago, coach passengers could select any seat in their section for no extra charge. (Southwest has always had a different system, but we’ll get to that in a moment.) Now, a dizzying array of choices is available that has enabled airlines to earn millions of dollars from fees.
Southwest, which doesn’t allow customers to choose their seats before they board, increased its EarlyBird Check-In price on Aug. 29. It went from a flat $15 to $15, $20 or $25 each way, depending in part on how popular Early Bird Check-In is on a particular route and the length of each flight. The price jump is the latest for Early Bird Check-In, which cost $10 when it was instituted in 2009, according to the airline.
The fee gives fliers a chance at a better seat by bumping them up in boarding position; Southwest boards passengers in groups. Those with EarlyBird Check-In will have their boarding positions reserved starting 36 hours before scheduled departure. Most passengers can reserve their boarding spot no more than 24 hours in advance.
In a statement, the company touted its policy of checking up to two bags for free, unlike its competitors who charge for checked baggage, and said EarlyBird allows the airline to avoid “nickel-and-diming” its customers.
Susan Jacobson is an editor at The Penny Hoarder.
This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.
source The Penny Hoarder https://ift.tt/2orypdV
Fetch That Ideal Veterinary Job at This Virtual Job Fair on Sept. 27
The Veterinary Career Network is hosting a virtual career fair on Thursday, Sept. 27 from 11 a.m. to 3 p.m. EST.
Registration for the career fair is free and allows participants to chat online with more than 100 employers from across the country, including Banfield Pet Hospital, Lap of Love Veterinary Hospice and Vetco Clinics.
Available positions include veterinarians, interns, vet techs, vet assistants and practice managers.
Animal-loving job seekers can search by employer name, location, position and species focus — perfect for all you cervid fans out there (a mammal of the deer family — yes, I had to look it up).
And if you’re not paws-itively sure you know what career you want, check out our guide to 20 jobs and side gigs for animal lovers.
Tiffany Wendeln Connors is a staff writer who covers interesting careers, job benefits and work-from-home opportunities for The Penny Hoarder. One of her favorite jobs is taking care of her dog, Bauer, who pays her in snuggles.
This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.
source The Penny Hoarder https://ift.tt/2PRWRBv
Mortgages and Loans: The Basics of Borrowing
Big loans make some people squeamish.
This used to surprise me.
I wondered how, for example, a client could talk openly about life insurance, with its end-of-life implications, then get sweaty palms over a mortgage refinance.
Another client might, after systematically considering the need for disability insurance, balk at a mortgage equity line of credit to pay for home renovations.
Why all the discomfort, I wondered?
Now I get it.
Borrowing money makes us feel vulnerable because it takes away some of our freedom.
Table of Contents
Mortgages, Loans, and Borrowing Money: The Basics
Taking out a $200,000 mortgage, for instance, means you’ll be factoring the burden into all your financial decisions for the foreseeable future.
As your family grows and the world changes around you, you’ll still be living with the same mortgage loan.
What if you lost your job?
What if the housing market crashed again?
How would you pay it all back?
Yet…
- without a mortgage, how could so many of us afford the home that becomes a sound and reliable financial asset?
- without student loans, how could we pay for the college degree that helps land a well-paying job?
- without a mortgage line of credit, how could we renovate the house to optimize its resale value?
You get the idea. It’s a bit of a Catch-22.
Hence the squeamishness.
Statistics say most of us will need to borrow money at some point in our lives. By understanding and controlling the borrowing process as much as possible, you can use credit as a key to unlock a more secure future.
You know that little voice in your head that grows more talkative when you’re thinking about borrowing money?
You can answer it with facts.
When Does it Make the Most Sense to Borrow Money?
 Do you know any new parents? Some of us remember being new parents.
What a scary place to be: responsible for that little life all of a sudden, for keeping her safe from strangers, and germs, and ridicule, and the like.
Some new parents have to fight the temptation to stay home all the time.
Staying home is safest, right?
So long as you have a few gallons of hand sanitizer and reliable child locks on the cabinets?
After a while, most of us learn we can’t parent in fear — sooner or later you have to get out and face the crowds and the cold germs. Otherwise, your child won’t learn how to live in society.
Sure, you still keep a close eye on your children, and you avoid unnecessary risks, but you also loosen the grip a little. You find the right balance.
Believe it or not, a similar balance can help when you’re borrowing money.
A reluctance to borrow money can be healthy when it prevents us from getting overextended by borrowing money unnecessarily.
The same reluctance, though, can stunt our financial growth by limiting our spending power to the size of our savings account.
What’s wrong with spending only what we have, you ask? Didn’t Grandpa say you should save up for what you want instead of using store credit?
Well, yes. And Grandpa was right, at least to a point.
If you’re using credit to buy dinner or a new car stereo or a trip to the spa, you may soon have a problem. Such things most likely will not help you build a more stable financial future. You’re taking risks without lining up a long-term reward.
Before taking out a loan of any size ask yourself what you’re gaining by making the purchase right now instead of waiting until you have the cash in hand.
In many cases, you’ll find there’s a lot to be gained by borrowing money to finance a purchase, like when you’re…
- buying a house: The average home costs $188,000. Could you save that much while paying rent in the meantime? If so, what will the house cost by the time you get the money saved? (Probably a good bit more than $188,000.) A mortgage loan can help get you into the housing market now.
- renovating your home: Realtors say homes with up-to-date kitchens and bathrooms sell more quickly and for a higher price than homes with outdated facilities. Updating your kitchen and bath can maximize your home’s value, so borrowing money for those renovations can have an immediate impact.
- starting a business: Got a great idea for a business? In a dynamic economy, your idea may have an expiration date. Borrowing start-up costs provides a huge spark to get your business off the ground while you still have time to corner the market.
- paying tuition: Grants, financial aid, and scholarships pave a smoother path for some students; others must take out student loans to finance the education required for higher earnings down the road.
- buying a car: Yes, cars depreciate in value, but if you can’t get back and forth to work without a reliable car, can you keep your job? For some of us, a car loan is a necessary evil.
Only you can know with certainty whether a loan can help you build a more certain financial future. The scenarios above affect people every day, but it’s not an exhaustive list because everybody faces different challenges.
If you already have access to a car or to reliable public transportation, maybe you shouldn’t finance a car.
On the other hand, a real estate agent may need a loan to fix her van’s air conditioner because it’s hard to keep clients when you’re driving them around in a sauna.
How Do You Go About Taking Out a Loan?
No matter why you’re borrowing, you can balance the risk-reward ratio more easily when you understand the borrowing process.
Different loans work different ways, so to keep things simple let’s take a look at the process of borrowing $200,000 to buy a house. A mortgage, after all, is among the more complex loans you can find and the most often used loans.
Would you simply walk into a bank and ask a teller if you can borrow a couple hundred grand?
You could, and if you happened upon a friendly and helpful teller, he may point you toward the loan officer back in her corner office.
It helps to have some knowledge going in, though, so you’ll know things like…
The Importance of Your Credit Score
If you were loaning someone $200,000 you might want to know a few things about the borrower:
- Does she tend to pay people back?
- Can he afford to make payments on the loan?
- Does he have a job?
- How many other people have loaned her money lately?
When you apply for a mortgage, your lender will wonder the same things about you, and it will find answers, in part, through your credit score.
A higher credit score means you present a lower risk for non-payment. As a result, a higher score means you, as the borrower, can have more control over the lending process.
When you have more control, good things can happen:
- You can get lower interest rates, potentially saving tens of thousands of dollars over the life of a mortgage.
- Lower interest charges can free you up to shop for more valuable homes, meaning your housing dollars can go farther.
- You can choose from a variety of loan types, and you may not need a federally subsidized loan which can lead to certain limitations.
In short, rather than having your mortgage loan choose you, you can choose the right mortgage loan for your specific needs and preferences.
So what does it take to get a higher credit score?
Patience, good decision making, and diligence. Pay your bills on time, keep a good balance of accounts open, and don’t borrow too much too often.
It’s easier than ever to keep an eye on your score. Apps like Credit Sesame and Credit Karma — two of my favorites — have taken the mystery out of your magic number.
Not only can you monitor your score for free on your smartphone or computer, these services also show you what kinds of new accounts could improve your score.
Efforts to improve your score may take a few months, or even a few years, to pay off. So it’s never too soon to start working on it.
The Importance of Interest Rates
As homebuyers we get caught up in the big numbers:
- property values
- tax values
- HOA fees
- insurance
But there’s a not-so-big number that will reverberate throughout the life of your loan, and it usually applies whether you’re borrowing money for a house, a car, or for school.
It’s your interest rate, of course.
Essentially, your interest rate determines how much you’ll pay for the privilege of borrowing. After all, banks do not lend money as a public service.
You might be surprised how much difference a single point on your interest rate can make over the life of a loan.
Take our 30-year mortgage of $200,000:
- At 5 percent interest, you would pay about $186,000 in interest charges in addition to repaying the $200,000 principal over the 30-year loan. (You’d have a monthly house payment of $1,074, not including insurance, taxes, or other fees.)
- At 4 percent interest, you would pay about $143,000 in interest charges in addition to the $200,000 principal ($955 per month payment).
- At 3 percent interest, you would pay about $103,000 in interest charges along with the $200,000 principal ($843 per month payment).
Longer term loans have more time to accrue interest, so a 5-year auto loan or a 12-year mortgage would require lower total interest payments than a 30-year mortgage, but rates still matter.
Financing a $35,000 car, for example, at 6 percent interest will result in about $5,600 in interest charges. If you can get a 5-percent interest loan, you’d pay only $4,600 or so in interest.
No matter what you’re financing, shopping around for the lowest interest rate you can qualify for will usually pay off.
You may even qualify for 0 percent interest on some purchases, though not cars or houses. Be careful with these sweet offers. They often bite back.
The 0 percent rate usually applies for only a short period of time. If you have not repaid the balance when the introductory period ends, you may face an exorbitant rate on the remaining balance.
Or worse, if the interest during the introductory period was deferred, it will all kick in retroactively.
The Importance of Down Payments
The vast majority of new mortgage loans require borrowers to put some money down, usually between 3 and 10 percent of the purchase price of the home.
A down payment creates a barrier to some borrowers. Putting 10 percent down on a $200,000 house, for example, means you’d need $20,000 in cash up front.
Borrowers who can’t afford a large down payment should look into a federally subsidized loan (FHA or USDA, for example). Subsidized loans tend to favor more financially challenged borrowers, but you could be giving up some freedom in the process.
- You couldn’t use an FHA loan to finance an investment property, for example.
- Many federal loans also require you to buy private mortgage insurance, which protects your lender if you default on the loan.
- Additionally, you may run into obstacles if you’re buying an older home with a federal loan because of the existence of lead paint or other out-of-date and potentially dangerous building materials.
If you can afford it, making a sizeable down payment helps you in the long run:
- You start the loan with equity, meaning you already own a chunk of the property even before making the first house payment.
- When you own at least 20 percent of the home’s value, you can cancel private mortgage insurance (PMI), which you pay not to protect your investment but your lender’s. A 10 percent down payment means you’ll reach that 20 percent threshold more quickly. A 20 percent down payment means you never need to buy PMI at all.
- Having 10 percent to put down opens a wider array of conventional loans which gives you more freedom to control the lending process.
What if you simply don’t have $15,000 or $20,000 to put down on a mortgage?
Should you wait until you do before shopping for a home?
Not necessarily.
Unless you can save a down payment within a couple years, you’d probably do better to apply for a subsidized loan which requires a lower down payment, or in some cases such as a Veterans Affairs loan, will not require a down payment at all.
Yes, you’d be starting home ownership in a more vulnerable position without a down payment.
But at least you’d be entering the housing market and investing your monthly house payments into your own future instead of your landlord’s future.
The Importance of Finding the Right Lender
As I said earlier, you could simply walk into the closest bank and ask for a loan. Most banks have knowledgeable staff and a wide variety of personal, auto, business, or mortgage loans.
Remember this, though:
When you need a loan, you should shop for one.
If you needed a new pair of dress shoes, would you walk into the closest department store and limit yourself to the local inventory?
No, you’d more likely do a little research first. If the closest department store specialized in outdoor gear and you needed dress flats, you probably wouldn’t even visit.
You should give your loan product the same level of scrutiny because not all lenders offer the same services.
Start by finding out exactly what you’re looking for:
- Will you need a subsidized mortgage?
- Do you have less-than-good credit?
- Are you a first-time homebuyer?
- Are you buying an investment property?
- Would you like to deal with someone face-to-face, or do you feel OK applying and providing loan documentation online?
- What’s more important: in-person customer service or lower interest rates?
- Would you like help to find a car, or just financing it?
The answers to these sorts of questions can help match you with the right lender.
Not all banks, for example, are authorized to issue a federally subsidized loan. An online-only bank can usually offer a better rate than your neighborhood bank. Many credit unions will help you find a specific kind of used car.
Borrowing: It’s Not Only About Mortgages, Of Course
We talk a lot about mortgages for several reasons:
- It’s a loan many of us will need at some point in life.
- When you know the nuances of getting a mortgage, other loans may seem easier to understand.
- A mortgage loan can be a key to a more stable financial future.
- For most of us, a mortgage may be our largest debt.
Naturally, though, the lending industry includes a wide and ever-growing array of products which extend well beyond home loans. I’ve alluded to several kinds of loans above, but let’s take a closer look at some other common products.
Types of Loans
Auto Loans
Unlike a home, which should appreciate in value as time passes, your car loses value over time.
Often, a new car’s value depreciates rapidly the minute you take ownership.
This creates a problem if you’ve financed the entire purchase price. You could never sell the car for enough to pay off what you owe. A lot of folks would say you’re “upside down” on the loan.
So if you can afford to buy a car without borrowing money, go for it. If not, I suggest keeping debt under control by spending only what you need.
You’ll also benefit from putting some money down and, of course, shopping around for the lowest interest rate you can find.
Consider arranging your financing before shopping for a car. That way you know your price range and will not have to negotiate financing while simultaneously negotiating the purchase of your car.
Student Loans
These are another necessary evil, but they may not be necessary for everyone.
Before resorting to student loans, apply for scholarships and grants. Even if you succeed in paying for only part of your annual tuition with scholarships or grants, you’ll be preemptively eliminating debt.
For many students, loans provide the only reliable way to finance higher education, which is why the average college graduate has about $39,000 in debt.
So before borrowing, take a few minutes to learn about the borrowing process:
- Subsidized vs. private loans: You can borrow money from the government or from a private lender. Government loans should always have a fixed interest rate and more flexible repayment terms. Still, private loans may offer flexible terms such as a variable interest rate which can save some short-term borrowers money.
- Borrow only what you need: When you’re in college, it can be tempting to borrow, say, $6,000 more than you need for university-related expenses. Why not have a little financial cushion? Cushions are nice, but they tend to grow less comfy when the loans come due after graduation.
- Be proactive about your debt, even if you can’t afford it: So long as you’re enrolled in college, federal student loan collectors will leave you alone. It can be a rude awakening when you graduate (or withdraw) and suddenly have debt hanging over your head. Federal loans usually include methods for lowering your payment based on your income, but only if you ask for help.
Business Loans
Starting a business can cost a fortune. Getting the right kind of business loan to pay start-up and initial operating costs may provide a huge piece of the puzzle.
Chances are you can find a business loan to meet your needs:
- Subsidized small business (SBA) loans offer tons of borrowing power since the government backs repayment.
- A traditional term loan works more like a conventional mortgage.
- A business line of credit behaves sort of like a credit card. You have a cap on what you can borrow, but you pay interest only on what you’ve spent.
- A personal business loan lets you leverage your personal credit score and borrowing power to help your new business get going. (You’re also personally responsible for repaying it.)
- Special programs like equipment financing let you buy expensive equipment while keeping that debt separate from other start-up expenses like rent and salaries.
- Short-term business loans are great for less cash-heavy business start-ups.
- A merchant cash advance allows you to repay your business loan gradually and automatically via deductions from your credit card revenue. This can help if you’re starting a retail business.
You can find even more specialized products for business borrowing.
Like any other kind of borrowing, be sure you have a plan for how to use the money and how you’ll repay it. And shop around for the best loan and the best terms.
Post-Mortgage Borrowing
When you already have a mortgage loan and you’re making the payments just fine, you may start wondering about a second mortgage.
These kinds of loans give you access to the equity — the portion of your home’s value you already have paid off — so you can spend it on home improvements.
A second mortgage can help keep your home updated so it’s easier to sell. When you take out a second mortgage, you’ll have two house payments: your original mortgage and the additional loan.
Another option: A home equity line of credit. These work more like a credit card funded by the equity in your home. Rather than borrowing a lump sum you can access your equity as needed.
Either way, be sure you’re spending your equity on your home and not on other living expenses. If you’re not reinvesting the equity into your home, you’re chipping away at the strong financial foundation your mortgage should be building.
Personal Loans
If you do have non-home related expenses to consider, a personal loan may be able to help.
Let’s say you miscalculated on your taxes and owe Uncle Sam $5,000, and he’s threatening to charge interest and late fees (then charge interest on your late fees).
In such a scenario you may need five grand in a hurry. Your bank or credit union likely has a personal loan program for non-collateral borrowing.
Sure, you could get a credit card for this purpose, but the interest on a personal loan will likely be much lower, and a personal loan has a payoff schedule, meaning you won’t risk carrying the debt indefinitely.
Consolidations and Refinancing
Let’s say you do wind up with some open-ended credit card debt along with an “upside down” car loan, more student loans than you’d intended, and a personal loan that seemed like a fine solution at the time… you get the idea.
In the midst of your worrying, let’s imagine you see one of those commercials for a loan consolidation program guaranteed to ease your troubles.
Should you do it?
If you’re deciding between paying off debt and paying your electricity bill, then you probably should consider the lower monthly payment a debt consolidation loan can offer.
This budget relief may cost you in the long run, though. The total interest paid on the debt consolidation loan may surpass the interest you would have paid without the consolidation.
Sometimes, in a no-win situation, you have to get immediate relief wherever you can find it. So if you’re thinking about a consolidation loan, look for one to match your needs:
- A non-secured consolidation loan does not require collateral and will probably cost more since it is riskier to the lender.
- A secured consolidation loan will tap into your home equity or other durable assets as collateral. You’ll likely get a lower interest rate, but you’re also tying up your assets.
You won’t find any simple, one-size-fits-all answers, so investigate your options thoroughly and try to find the right balance between your present challenges and your future needs.
About refinancing: Ultimately, a consolidation loan refinances multiple debts. You can also refinance one debt at a time. You may be able to save every month by refinancing your mortgage, for example, especially if…
- Your credit score has improved since you took out the original loan, meaning you’ll qualify for a significantly lower interest rate now.
- Interest rates, in general, have decreased since you got your mortgage.
- You have a variable interest rate mortgage whose low intro rate is about to expire, meaning your monthly payment is about to start increasing.
Often, you’ll need to pay some closing costs to refinance your mortgage. So be sure your monthly savings are worth the up-front costs.
It’s Not a Perfect World, But Knowledge Helps
In a perfect world, we’d all have the money we need to buy our houses and cars and to pay our tuition. And when we decided to start a business, we’d simply withdraw start-up costs from our savings accounts.
Wouldn’t that be something? I guess we can dream about it.
In the meantime, if you need to borrow money either to get ahead in life (or to rectify some previous mistakes), take heart: There’s an entire industry set up to help you.
But you can help yourself by knowing how financing works — by knowing…
- a good credit score opens more doors
- a low-interest rate and other favorable terms can give you more borrowing power
- you should use borrowing sparingly, only as needed
- how to shop around for the right loan.
Some of us have this kind of knowledge because we have made a lot of mistakes. I won’t mention any names, but someone I know once showed up at a car dealership and eagerly accepted a 16.99 percent interest rate on a used pickup truck.
He thought he’d learned his lesson about borrowing, but then he paid off the truck with a second mortgage, which made selling the house almost impossible the next year.
You don’t have to learn the hard way. Know the basics of borrowing and take control of the process.
When you’re in control your loans become tools to serve you. They will work to unlock a more secure financial future.
The post Mortgages and Loans: The Basics of Borrowing appeared first on Good Financial Cents.


Source Good Financial Cents https://ift.tt/2wqpfTh
How to Increase Sales by Personalizing the Customer Experience
Successful brands put the customer first.
They monitor their customers’ behaviors and leverage their needs to enhance the buying process. You can also boost your revenue by optimizing the customer experience.
If you want to take this concept one step further, you need to focus on one important element that will increase sales.
Personalization.
Personalizing the customer experience is a winning strategy. In fact, 96% of marketers agree that their efforts to personalize their customers’ experience advance their relationships with customers.
Furthermore, 88% of marketers say they’ve seen a measurable improvement in their businesses after implementing customer personalization tactics.
But only 33% of businesses feel confident they have the tools to properly personalize the customer experience.
That’s what inspired me to write this guide.
Some of you may already know you need to create a more personalized experience for your customers, but you just don’t know what to do. Or maybe you’re trying to improve your existing efforts.
Regardless of your situation, I’ll explain what you need to do.
These are the best ways to increase sales by accommodating the needs of your customers and personalizing their experience.
Encourage your customers to create profiles
One of the first things you need to do is allow your customers to create profiles on your platform. Those profiles will help you implement other strategies as we continue through this guide.
Once the accounts are created, you’ll be able to monitor the behaviors of your customers based on their profiles.
Your customers are perfectly comfortable with you tracking their habits as long as it’s improving their experience.
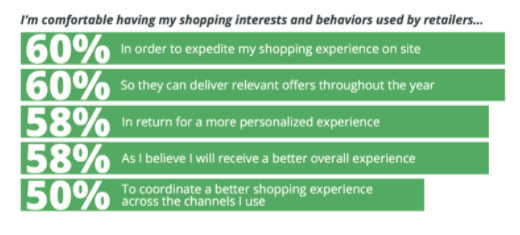
As you can see from these numbers, customers want you to:
- make it easier for them to shop
- give them relevant offers
- provide them with a more personalized experience
- improve their experience on multiple channels
Not only are your customers comfortable with you monitoring their behaviors through their profiles, but they actually expect it. In fact, more than half of consumers say they expect brands to anticipate their needs so they can receive relevant suggestions.
You’ll eventually be able to recommend products based on shopping and browsing behavior, but we’ll discuss that in greater detail later.
The best way to encourage your customers to create accounts is by making it as easy as possible for them.
They don’t want to take tons of unnecessary steps to set up their accounts. Make sure you limit your form fields needed for the account creation.
Think about what information you need from the customer that will help you personalize their experience.
Basically, anything they’d provide you with during an optimized checkout process is enough to create a profile.
Add a simple checkbox to the checkout that says something like “create a customer profile” to accomplish this.
Both you and your customers will benefit from this option. The personalized content on their profiles will improve their experience and ultimately drive more sales.
Segment your email subscribers
Collecting email addresses needs to be a priority for your business. But if you want to personalize the customer experience, you need to make sure you’re delivering relevant content to their inboxes.
The best way to do this is by segmenting your email lists:
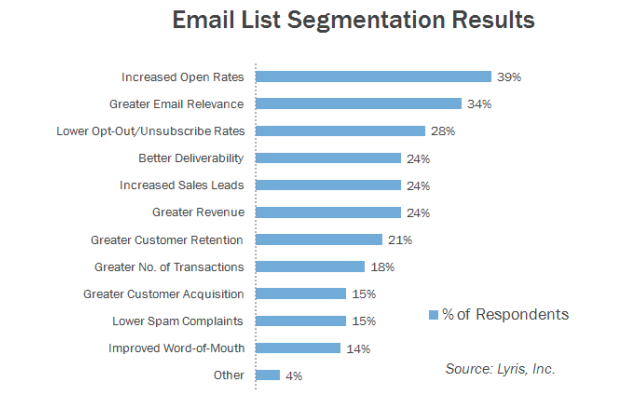
Although everyone who signs up to receive emails from your company might be interested in your brand, it doesn’t mean they have the same wants and needs.
You need to learn how to write marketing emails that don’t get marked as spam.
Grouping your subscribers into separate lists will ensure they don’t receive irrelevant information.
Let’s take customer profiles as an example. If a customer creates a profile during the checkout process, you’ll know their address because they need to provide you with shipping and billing information.
Your customers in Texas shouldn’t be getting the same emails as your customers in New Hampshire if your company is advertising a winter sale.
Those subscribers in Texas don’t care about discounted winter hats and ski pants.
That’s why segmented email campaigns can result in a 760% revenue increase.
Marketers say 58% of their revenue comes from emails that are properly segmented and targeted.
Recent studies show the differences between segmented emails compared to non-segmented campaigns.
Segmented emails have:
- 14.3% more opens
- 101% more clicks
- 4.7% fewer bounces
- 9.4% fewer unsubscribes
Higher opens and clicks paired with fewer bounces and unsubscribes put your company in a great position to increase sales.
Store information for faster checkouts
Again, customer profiles are important here.
Make sure you ask for the information required to complete a purchase only once. After that, you can store the information to expedite the purchasing process in the future.
Each step a customer has to take to buy something decreases the chances they’ll complete this action.
Having to enter their name, address, and credit card information into your platform every time is tedious. The whole reason why they created a profile was to improve their experience.
Take a look at how Delta uses this strategy:
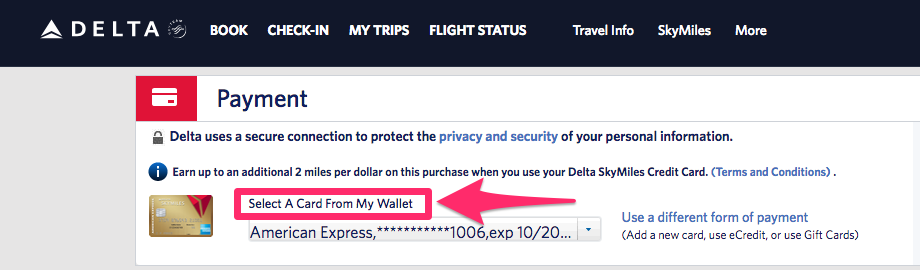
By saving credit card information in their customer profiles, people can book a flight fast and easily. They don’t even need to have their cards on them.
Every ecommerce company needs to incorporate this strategy.
Customers will be able to add items to their carts and complete transactions with just a few clicks. This will help you improve your conversion rates and drive more sales.
Implement geotargeting practices
As I explained earlier, you can use the customer’s location to personalize their experience.
In addition to segmenting your email lists by location, you can also tailor the content on your website based on the country your customers are browsing from.
Take a look at this example from the SAXX website:
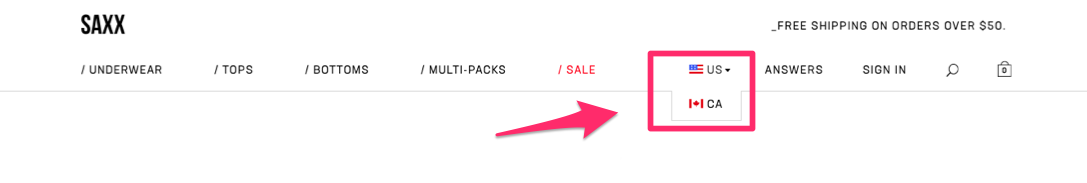
Their customers are primarily located in the United States and Canada.
While the two countries may be similar, the company still wants to offer tailored customer experience based on the location of their customers.
For example, Canadian customers will want to see measurements of clothing in centimeters since they use the metric system. And people browsing in the United States will see “color,” while the Canadians will see “colour.”
Yes, any English-speaking person can understand American English, but not having the site customized to the customer location can still hurt the company’s sales.
By allowing its website visitors to choose their country, SAXX ensures they’ll be shown the right content.
Those of you who have an international brand need to take this process one step further. Look at the options on the Nike website:
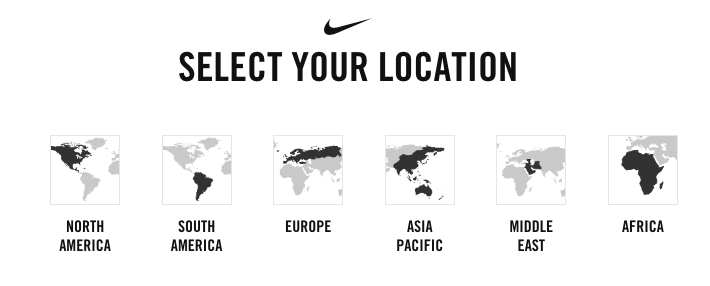
Your website isn’t the only platform that can be personalized based on location.
You can use your mobile app to pinpoint the exact location of your customers as opposed to broader locations, e.g., the state or country.
When someone downloads your app, ask them to agree to share their location with you so you can track it. Then, you can send them notifications using geofencing technology.
With geofencing, you can set up an area around one of your store locations. When an app user enters the location, they’ll get a notification that encourages them to make a purchase.
For example, let’s say you own a restaurant chain.
Someone with your mobile app walks within a block of one of your locations during lunch time. You can send them a discount off their lunch purchase that day.
Create a customer loyalty program
When you’re implementing customer personalization tactics, you shouldn’t aim to generate a one-time sale.
You want these efforts to lead to customer retention, resulting in recurring purchases. That’s why you should come up with an effective customer loyalty program.
Studies show 82% of consumers are more likely to buy from brands offering loyalty programs.
Plus, loyal customers spend more money. Just look at these numbers:
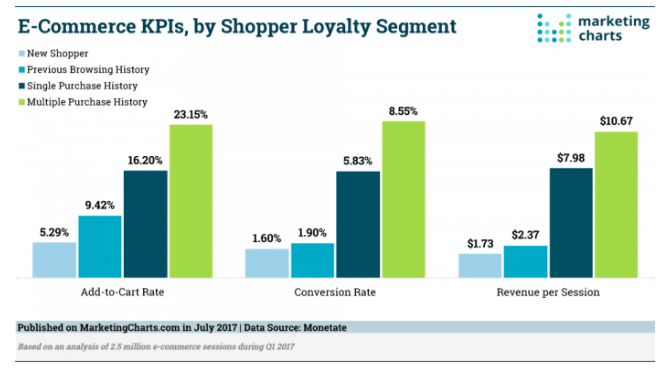
Customers who have purchased from your brand multiple times add items to their carts at a higher rate, have higher conversion rates, and generate more revenue per shopping session.
You can set up your loyalty program in a few different ways.
The most basic option would be to give your customers a reward after a predetermined number of visits or purchases. You’ve seen these before.
You may go to a local food truck outside of your office for lunch. They probably have some kind of a punch card that rewards you with a free sandwich on your tenth visit or some other reward scheme.
But the best customer loyalty programs reward their highest spending customers.
Set rewards based on spending tiers. This will give your customers an incentive to spend even more money.
Allowing them to track their progress on their customer profiles or from the mobile app will improve their personalized shopping experience.
Listen to customer feedback
According to research, 68% of consumers abandon a business because they don’t feel the brand cares about them.
That’s why you should use surveys and interviews to generate more money for your business. This will show your customers you value their opinions.
However, just asking your customers to provide feedback isn’t enough.
You actually need to make changes based on those suggestions.
But first, you need to analyze the results of the feedback. Don’t just implement changes for the sake of it—that won’t deliver a return on your investment.
But if you notice that a large percentage of your customers are providing similar feedback and suggestions to improve your process, you should take that very seriously.
Implementing these changes will make your customers realize they are part of your process and create a bond with your brand.
Recommend relevant products
I briefly mentioned this earlier, but I wanted to discuss it again in greater detail.
You already know you need to use the information provided in the customer profiles to personalize content for them. But there are certain pieces of extremely valuable information that you can’t get via a form field: what the customers are looking for and what they are buying.
But you can find out that information through the browsing and purchase histories of your customers. That information will allow you to suggest relevant products to them.
If you do, consumers will be more likely to buy from your brand, whether you operate online or in person:
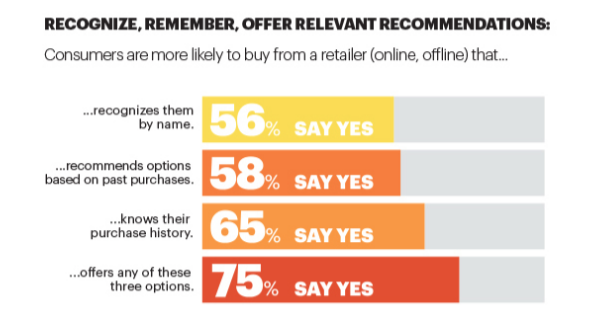
Recommending products to your customers also narrows their options.
Roughly 40% of consumers left a website to buy from a competitor instead because they felt overwhelmed by too many options. Don’t let this happen to you.
If one of your customers recently purchased a surfboard and a wetsuit, it’s safe to say they’ll be spending time at the beach and in the water. So you could suggest something like a paddleboard and sunscreen because it’s relevant to their purchase history.
Let your customers be part of the personalization process
Combine your personalization strategy with an interactive process.
If a customer doesn’t have a profile, you can still get more information from them to personalize the content they see.
For example, Warby Parker has a feature on its website I love. Obviously, glasses aren’t a one-size-fits-all product.
But with so many options, it can be overwhelming for consumers to find exactly what they’re looking for. To help narrow the results, the brand asks their customers some questions.
First, it asks if you’re browsing for men’s or women’s styles. Then, the questionnaire asks the type of fit you’re looking for.
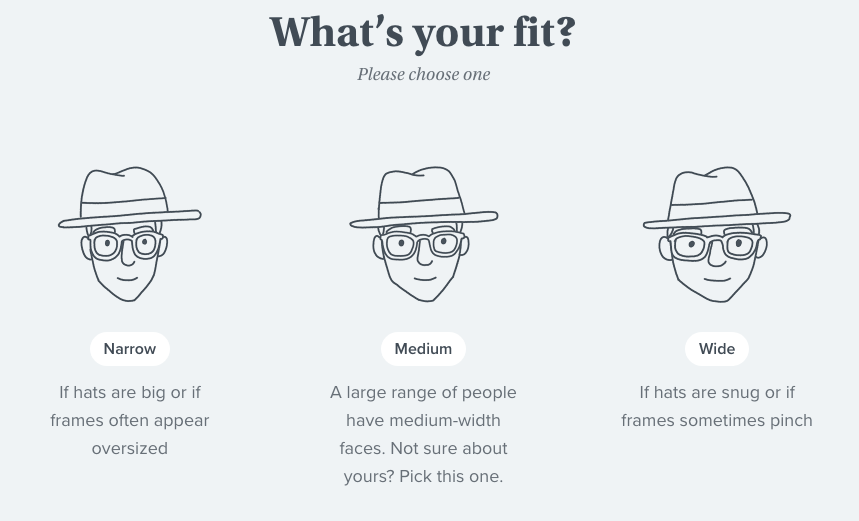
As you can see, the cartoon faces are all of men because that’s what I selected in the first step. It’s another subtle personalized touch.
Next, they want to know your color preferences for glasses.
After that, you need to provide them with the shapes of frames you prefer the most.
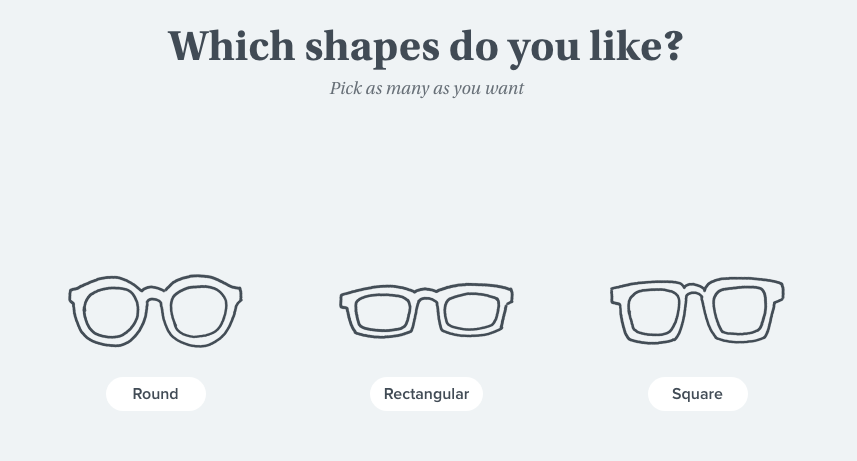
The questions get even more detailed.
Warby Parker asks when you had your last eye exam. It also wants to know if you’re interested in eyeglasses, sunglasses, or both.
This relates to my last point about narrowing down the results. You don’t want to overwhelm your customers.
Now the product results will be based on the preferences chosen by the customer.
Write content from the first person perspective
Try to establish a personal relationship with your customers.
In theory, this is much easier for small business owners who actually see their customers on a regular basis.
But even if you’re an ecommerce shop or a global brand, there are still ways for you to create this type of relationship based on how you communicate with your customers.
By writing content from the first person perspective, just like I do when I blog, you will make your customers feel more comfortable. Write as if you’re talking to a friend.
You don’t need to be formal all the time.
Don’t get me wrong: you should still write using proper grammar and avoiding slang terms. Just write as if you’re having a casual conversation.
Do this with your emails, blogs, and content on your website.
Sign emails using your name. Your emails should be coming from yourname@yourcompany.com.
Don’t send marketing emails from non-personalized addresses, like support@company123.com.
Craft personalized email subject lines and content
Let’s continue talking about your email marketing strategy.
In addition to segmenting your lists and writing content from the first person perspective, you need to learn how to craft subject lines that generate results.
After all, if nobody opens your emails, they’re useless.
Research shows that personalized subject lines have tons of benefits:
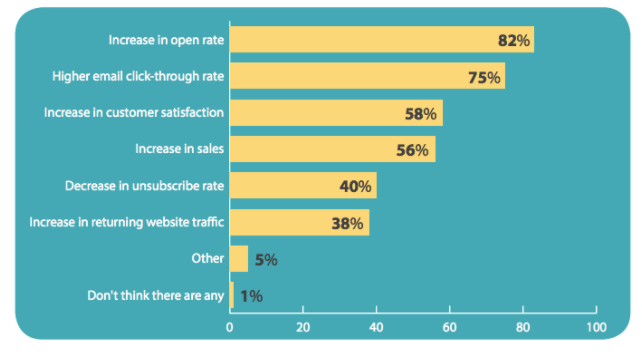
Your messages will get opened at higher rates and have more clicks.
As you can see from the graph, these clicks ultimately lead to improved customer satisfaction and higher sales as well.
Conclusion
Your customers want and expect a personalized shopping experience. It’s your job to deliver this to them.
Start by encouraging customers to create profiles on your website. When you add subscribers to your email list, segment them based on the information they provided you with.
Let customers store information in their accounts, expediting the checkout process.
Use geotargeting to show website visitors and app users personalized content based on their locations.
Implement a customer loyalty program. Listen to the feedback your customers give you.
Monitor their browsing and purchase histories to recommend relevant product suggestions.
Create an interactive personalization process to help your customers narrow product results.
Learn how to write content and email subject lines with a personal message.
Once you implement these personalization strategies, you’ll enhance the customer experience and ultimately drive more sales.
What strategies is your business using to personalize the customer experience?


Source Quick Sprout https://ift.tt/2PiYp6q
Here’s What Debt Collectors Are Allowed to Do… and What’s Totally Illegal
Once you understand how debt collection works, you can use that knowledge to find peace as you do the hard work of getting debt-free.
It starts with understanding the law that governs the agencies that want your money: the Fair Debt Collection Practices Act. This has the rules for everything about how your creditors and debt collectors can communicate with you.
What’s in the Fair Debt Collection Practices Act?
First things first: It’s time you take back your phone. That’s one of the things the Fair Debt Collection Practices Act lets you do.
There’s no reason you should be afraid to answer to a debt collector. And just because you don’t have the money to pay back what you owe as quickly as a debt collector would like, that doesn’t mean you have to suffer through a barrage of guilt-inducing calls.
The act allows you to slow or stop those annoying calls. Not only that, but it lets you dictate how debt collectors communicate with you. You can request that they only email you or mail physical notices to you.
You can even stop communication altogether and cut all ties to your debt collector. However, you may not want to take things that far, according to Bruce McClary, from the National Foundation for Credit Counseling.
“When you request to have communication completely cut off and you just want to drop off their radar, that sends them a signal that you have zero intention of paying ever, and it may accelerate some of their actions in trying to recover the debt in other ways,” McClary told The Penny Hoarder.
The point is that you have options beyond simply dodging debt collectors until you can find the money to pay. Other protections provided by the Fair Debt Collection Practices Act include:
- Debt collectors are required to provide proof that you owe the debt.
- They can’t call you before 8 a.m. or after 9 p.m.
- They can’t call you at work if you tell them it could put your job in jeopardy.
- While it’s legal for them to call a family member or friend to find you, a bill collector can’t give them details about your debt. And according to the CFPB, they can only call each family member or friend one time in most states.
Now that we’ve established that, let’s get a better understanding of those people who won’t stop calling you and what they do all day.
Everything You Need to Know About Debt Collection Agencies
When most of us talk about debt collectors, we’re not talking about employees of the bank or credit card company that initially extended the credit or provided a loan. Instead, we’re referring to people who work for a third-party company that regularly collects debts owed to other creditors.
By the time a third-party debt collection agency gets involved, the bill is usually past due.
Although that is the most common kind of debt collector, most financial institutions also have internal debt collectors. They usually work with borrowers who have recently become past due. Their goal is to help you get current quickly.
If they fail, your debt is often moved to the third-party collectors. If that company also can’t get you to pay up, your debt can move on to a third kind of collection agency: debt buyers.
According to ConsumerAffairs, debt buyers pay creditors a fraction of what you owe and then come after you for the full amount. Debt that has been sold to a buyer has usually gone unpaid for an extended period.
All three kinds of debt collectors — internal, third party and debt buyers — must follow the rules set by the Fair Debt Collection Practices Act.
According to the Federal Trade Commission (FTC), the world’s largest third-party debt collector is Expert Global Solutions.
However, it’s worth noting that no matter how big the company is, it’s not above the law laid out in the Fair Debt Collection Practices Act. The FTC forced Expert Global Solutions to pay a $3.2 million fine in 2013 after it was accused of harassing debtors with illegal collections calls.
How to Deal With a Debt Collection Agency, Step by Step
When it comes time to deal with debt collection agencies, the most important thing to note is that you shouldn’t ignore them.
That could lead to a gut punch to your credit score, a possible lawsuit that forces you to pay the debt and — if you still don’t pay — wage garnishment. That means, with approval from a judge, the creditor that you owe could take money out of your paycheck before it even gets to you. If you’re already on a tight budget, this will surely make things worse.
So what should you do if you owe debt? Here’s a step-by-step guide:
Step 1: Ask the Debt Collector to Verify That the Debt Is Yours
The Fair Debt Collection Practices Act requires a debt collector to prove that you really owe the debt. That can be done with documents from the original creditor that show how much you owe and when you accepted the loan or credit.
Step 2: Take Control of the Communication Process
If the calls are incessant and you want them to stop, be sure to request the change in writing. This can be via email or a physical letter. The Consumer Financial Protection Bureau provides a series of template letters to help you communicate with debt collectors in writing.
Step 3: Keep Detailed Records
It’s important to remember that debt collectors have a job to do. They are not your allies. It’s up to you to keep track of every letter, email and phone call.
You have a right to record phone calls with debt collectors; just make sure you notify them before you start recording. If they refuse to be recorded, hang up and reach out via email instead so that everything is in writing. If you forget to record a call, keep detailed notes about what you discussed. This will come in handy if you ever need to file a complaint against an abusive debt collector or have to fight in court to prove that the debt isn’t yours.
Step 4: Work With a Credit Counselor
Figuring out how to start repaying a mountain of debt can be daunting. Finding expert help can make the process a little easier. The Department of Justice has a list of approved credit counselors to choose from for those seeking help from a reputable company.
Step 5: If You’re Mistreated, File a Complaint
In most cases, dealing with a debt collector might be a little unpleasant, but in those situations when a collection agency violates the law with incessant phone calls or threats of violence, you’ll need to file a complaint.
Filing a complaint with the FTC or the CFPB will usually be enough. In extreme cases, you can either report the harassment to your local law enforcement agency or the FBI.
Your Questions About Debt Collection, Answered
Understanding the law is just the first step. We checked with the Consumer Financial Protection Bureau to answer frequently asked questions about dealing with debt collectors.
How Long Can a Collection Agency Attempt to Collect a Debt?
This depends on your state laws. In most cases, the creditor can come after you for as long as necessary for you to pay the debt you owe. However, the CFPB points out that in most states, the statute of limitations for debt is three to six years. If you’re sued over debt that is past the statute of limitations, you could get the case thrown out.
Can I Go to Jail for Being in Debt?
There are very few situations that could result in you getting arrested over an unpaid debt, according to the CFPB: first, if your debt is related to criminal activity — unpaid restitution for a crime, for example — and second, if you ignore a court order. In most other situations, you won’t be arrested for unpaid debt.
Further, it’s illegal for a debt collection agency to threaten you with arrest if jail time is not an actual punishment that could happen. If you were told you’d be arrested for unpaid debt and you later find out that was false, you can file a complaint.
Can I Ignore a Debt Collector?
Ignoring a debt collector won’t make the debt or the collector go away. In fact, it could make your financial problems even worse. It could force the debt collector to take more drastic actions like filing a lawsuit against you.
Can a Debt Collector Take Me to Court?
Yes. However, this usually happens as a last resort after attempts to collect payments through phone calls, emails and mailed notices. To avoid a lawsuit, try to work with your lawyer and the creditor to come up with a payment agreement.
What Should I Do if I Can’t Pay?
If you can’t pay the full amount you owe or the monthly minimum payment, work with your creditor to create a payment plan for the debt. If you still can’t pay, talk to an attorney about options like filing for bankruptcy.
Desiree Stennett (@desi_stennett) is a senior writer at The Penny Hoarder.
This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.
source The Penny Hoarder https://ift.tt/2PS2UGj
الاشتراك في:
الرسائل (Atom)