Thousands of courses for $10 728x90

الأحد، 23 سبتمبر 2018

How to Get Paid to Shop For Others

Getting paid to shop sounds too good to be true, right?!  Believe it or not, there are many companies that offer flexible and remote job opportunities where you can get paid to shop! From grocery shopping to clothes shopping, and mystery shopping, there are always a variety of gigs available. Ready to get started? Here […]

The post How to Get Paid to Shop For Others appeared first on The Work at Home Woman.


Source The Work at Home Woman https://ift.tt/2pxq7lh

Pennsylvania jobless rate hits 18-year low; payrolls slip

HARRISBURG, Pa. (AP) — Pennsylvania's unemployment rate hit a nearly two-decade low in August, even as payrolls slipped below July's record high.The state Department of Labor and Industry said Friday that Pennsylvania's unemployment rate dropped one-tenth of a percentage point to 4.1 percent in August, the lowest point since 2000.The national rate is 3.9 percent.A survey of households found Pennsylvania's civilian labor force grew by 9,000, as employment rose and [...]

Source Business - poconorecord.com https://ift.tt/2NAPWis

Farmers worry bailout won't be enough

WASHINGTON (AP) — Farmers across the United States will soon begin receiving government checks as part of a billion-dollar bailout to buoy growers experiencing financial strain from President Donald Trump's trade disputes with China.But even those poised for big payouts worry it won't be enough. And while support for Trump is near unwavering in the heartland, some growers say that with the November election nearing, such disappointing aid outcomes could potentially affect their [...]

Source Business - poconorecord.com https://ift.tt/2pxOUFQ

Seven Headwinds Threatening to Capsize Millennials’ Finances

(This is the first of a two-part series.)

We hear a lot about millennials and money these days. They’re chronically stressed about finances. They have a negative savings rate. They’re slammed with student debt repayment and aren’t earning enough or aren’t earning at all. They spend more on coffee than retirement.

The news isn’t always bad. For example, they’re investing for retirement (a little too conservatively, but they are investing). Still, popular culture and media have still tagged this generation as both profligate and entitled.

Generationally generalize much? Some of the millennials I know are both hard-working and forward-thinking. Some save not only for their own future but have also established education funds for their kids.

However, this generation does face some unique challenges.

1. Student Loans

On the bright side, a college degree could bring higher lifetime earnings. But record levels of student loan debt don’t help when you’re trying to save for the future or buy a home.

To get control of your debt, consider tactics like income-driven or income-based repayment plans, or refinancing the loans. Such options have pros and cons, so think it over carefully.

2. Pressure to Save for Retirement

Thanks to the magic of compound interest, the best time to start saving for retirement is in your 20s – which happens to be right when a lot of young workers are paying off student loans and also at the low end of the earnings spectrum.

But that’s also when you’re full of promise and of excitement about beginning your adult life. When better to travel, to party, to dream?

A balance between “live for today” and “build for tomorrow” is possible. It might not be easy, but it’s generally do-able. Some helpful tactics: taking full advantage of any 401(k) employer match, living with roommates or living at home for a few years, getting a side hustle, learning to cook, using “style challenges” to create a basic wardrobe rather than constantly buying more clothes, and paying yourself first (that is, paying Future You first by automating even a small amount of each paycheck to retirement).

Future You will judge Current You pretty severely. If one thing is certain, it’s that you probably won’t be able to make it on Social Security alone.

3. Dependence on Debit Cards

Millennials use debit cards for 28 percent of their purchases, according to a recent study from Visa. Choosing debit could actually be a good thing if you:

  • Want to stick to a budget (can’t spend what you don’t have in checking)
  • Already have debt (using the debit card keeps you from boosting that balance)
  • Have been known to miss payments or pay bills late (payment history represents 35 percent of your credit score)

However, paying with credit is usually a better choice. Chief among the reasons: It’s somebody else’s money. Your debit card is linked to your cash, and if the card is compromised then the fraudulent transactions siphon dollars from your checking account.

You’ll get the money back eventually, but that could take a long time – and if you’re living close to the bone, how will you manage until then?

By contrast, if someone steals your credit card you’ll be on the hook for only $50 worth, as long as you report it promptly. In fact, your card issuer might absorb that cost; my cards have been hacked more than once, and never have I been asked to pay that $50.

In addition, you can dispute an unauthorized charge on a credit card, and maybe get the money back for items that get damaged or lost during shipping. Some credit cards have other protections, too, such as basic rental car insurance and extended warranties.

Another huge issue is that debit cards do not help you build a good credit score – and that three-digit number has a big impact on how much interest you’ll pay on loans during your lifetime. (To say nothing of the fact that future landlords and/or employers might take a look at your score, too.)

Does this penalize hard-working folks who believe in paying cash? Pretty much. But that’s the way things work. A savvy consumer will learn to work within this system, even if it stinks.

(To see some of the best options, visit The Simple Dollar’s credit cards page.)

4. Delayed Marriage and Parenthood

Two incomes are better than one. If one spouse gets sick or laid off, there’s still some money coming in. When it’s time to think about homebuying, two people can qualify for a bigger mortgage.

One spouse might also have a superior health insurance plan, which comes in handy when it’s time to have or adopt a child. And those two incomes could also mean two sets of paid parental leave, which cuts the cost of child care.

The longer you stay single, the fewer of these advantages you’ll have.

5. Not Earning Enough

The poverty rate among young adult heads of household has steadily increased in the past 50 years. Millennials are no exception: Of the approximately 17 million impoverished U.S. households, an estimated 5.3 million were headed by millennials. Two likely reasons: millennials are more racially and ethnically diverse (and minorities tend toward higher poverty rates), and they’re also more likely to be unmarried.

6. Eating Habits

Millennials spend more of their food dollars at restaurants than in supermarkets, according to the U.S. Department of Agriculture. When they do shop, they tend to go for organic and/or exotic ingredients.

Organic food is almost always going to cost more. That doesn’t mean you shouldn’t buy it. What it does mean is that the extra money will have to come from somewhere else. Four possible workarounds:

  • Cook more from scratch. For example, a bag of organic dry beans (simple to prepare in a slow cooker or Instant Pot) will yield a lot more bang for the buck than canned ones. The money you save will help defray the cost of organic produce and meat.
  • Try batch cooking. If you spend part of one weekend per month making and freezing meals, you’ll be less likely to order (organic) takeout or to buy pricey organic frozen dinners because you’re too tired to cook.
  • Eat with less drama. Making elaborate organic dinners with multiple courses is going to cost a lot more than simpler (but still delicious) menus.
  • Cut something else from your budget. If eating organic is important to you, trim costs elsewhere to be able to afford the more expensive ingredients. (Find some good tips here.)

7. FOMO

That’s “fear of missing out,” and it’s ever-present in this ever-connected world in which we live. Celebs are Instagramming their newest bling. Friends put up Facebook videos of their vacations on white-sand beaches or their brand-new McMansions. Your BFF just texted a photo of his new iPhone X, while you’re stuck using a phone from four iterations ago.

The most insidious thing about FOMO? It keeps you from appreciating the good things you already have. Paid-off vehicle that gets good mileage and is easy to drive? (Yeah, but my brother-in-law has an awesome sports car!) Got a job that absorbs and delights you and also provides the flexibility to deal with family issues? (Well, that’s true, but my BFF makes $10,000 a year more – why can’t I earn like that?)

Work to defeat FOMO every time you feel it creep in. There’s nothing wrong with wanting to live your best life, but there’s plenty wrong with going deeply into debt to do so – especially since there’s no guarantee that what you get will keep you happy for the long term.

Tomorrow, the second part of this series will run – an article with nine secret weapons that millennials can use to take control of their cash.

Award-winning journalist and veteran personal finance writer Donna Freedman is the author of “Your Playbook for Tough Times: Living Large on Small Change, for the Short Term or the Long Haul” and “Your Playbook for Tough Times, Vol. 2: Needs AND Wants Edition.” 

More by Donna Freedman:

The post Seven Headwinds Threatening to Capsize Millennials’ Finances appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2PYtooB

السبت، 22 سبتمبر 2018

Finding Inspiration for Financial Success

At first glance, it can seem quite easy to find inspiration for financial success. Just turn on the television, right? You can’t even flip through the channels without finding some show with someone in their mansion or rolling around in their luxury car or going on some super-expensive and super-exclusive trip.

The problem is that such things aren’t actually financial inspiration – they’re consumption inspiration. The people spending $5 million on their home or $500,000 on their car or $300,000 on their destination wedding aren’t making decisions that will preserve or optimize their financial future. They’re making consumptive choices, spending money on luxury experiences that are over quickly or buying items that require tons of maintenance and taxes and still likely depreciate in value fairly rapidly.

Finding actual financial inspiration is a bit harder. Financial inspiration is inspiration and examples that encourage and lead you to build a strong financial foundation in your life, and that kind of example can be hard to find. It’s not nearly as flashy or shiny as the things one might see on reality television.

How does one seek out sources of inspiration on their financial journey? The key isn’t so much where to look, but to know what you’re looking for.

Be Inspired By People Who Achieve Things…

Make a conscious decision to seek out people based on their personal achievements – not what they were given or the possessions they have, but what they’ve actually done with their lives. Have they created things? Have they built things? Have they made the lives of people around them better? Have they worked hard and channeled that work into a good life for themselves and the people around them? Those are the people well worth looking at and using as your personal inspiration.

Read biographies and personal profiles. A great place to start with this type of inspiration is between the covers of well-written biographies. Read the stories of people have done these things. Find out how they started out, how they turned the little that they had to start with into something much greater, how they stuck to principles, and how they made hard personal sacrifices along the way.

Look at people like Howard Schultz, who started life in low income housing in the New York City Housing Authority, worked hard at sports to get into college, leveraged that college education into a career in sales, found himself selling equipment to a nascent Starbucks Coffee in the early 1980s, joined them as Director of Marketing, and eventually became their CEO, turning them over the decades from a tiny West Coast chain into a global phenomenon. Not bad for a kid from low income housing.

How did he do it? Being careful with every dime was a big part of that story, particularly up to the point where Starbucks really took off. Before that, he often didn’t have a dime to spare, and it was his care with those dimes that managed to make things work.

Schultz is just one example; there are many more. Find ones that click with you. Read lots of biographies of people who made things, built things, discovered things, and turned very little into something much more.

Build friendships with the pillars of your community. Often, some of the best financial inspirations exist already within your own community. They’re the people who seem to be on the board of every local event and in lots of organizations. They often run a local business. They’re the people everyone knows and virtually everyone thinks highly of.

Learn from those people. Make an effort to become their friend. Get involved with the community and work with them and, as you get to know each other, invite that person to lunch and pick their brain. Find out how they got from point A to point B. Listen. Be inspired.

Join civic groups. A big part of finding that local inspiration is simply getting involved in your community. It’s much easier to meet people in your community who have done amazing things if you actually get involved yourself.

Seek out civic groups who are doing positive things. Find out about joining up. Go to their meetings and see what they’re all about. Don’t just retreat into your turtle shell – stick your neck out a little bit. Volunteer for things. Get to know as many people as you can.

The people you meet in such organizations will surprise and inspire you, every single time. These are people who tend to have their lives organized and their hearts in the right place. They tend to be doing a lot of good things with their life, often starting in a difficult place. In short, they can be a real inspiration.

… and Not By People Who Possess Things

A big house might be a nice place to visit or live, but it makes very little commentary about the values and achievements and stability of the person living there. The same goes for a shiny car or an expensive suit. Such expensive trappings of wealth might be held by a wonderful person who has done much for society, or it might be held by an empty suit who cut every moral corner along the way.

Don’t value or devalue people by the house they live in or the clothes they wear or the car they drive or the gadgets they have or anything like that. That’s just an expression of how that person happened to use the money that happened to flow through their hands. Maybe they earned it through hard work. Maybe they were handed that money via inheritance. Maybe they committed nefarious acts to acquire it. Maybe they’re so leveraged in debt that their blood pressure is through the roof.

Look past the stuff. It’s irrelevant. Look at the person underneath the stuff.

Don’t pay attention to people who are primarily known simply for having wealth, particularly inherited wealth. There’s nothing whatsoever wrong with being wealthy, but when you have accomplished so little in your life that your wealth overshadows it, what have you really achieved?

Look for actual achievements. Consider how the person actually made the world a better place for those around him or her. Do you admire that person because of their big house and shiny car? Let go of that. Instead, admire the person because of the lives they improved and the self-discipline they exerted and the values they expressed through their actions.

When you feel jealous of someone else’s possession or experience, consider what effort that person had to put in to be able to earn that possession or experience. What did this person actually do to have the things that you’re feeling jealous of? Did that person do great things while practicing self-discipline? That’s something to be admired, but the admiration should be aimed at the person, not at the stuff.

On the other hand, maybe that person was simply handed those possessions or experiences and did little to earn them, or maybe they had to do things that would leave you feeling very uncomfortable or unhappy to get there. Perhaps the acquisition of those things was a bargain that you would never, ever want to make. Again, it comes back to the person inside, not the expensive stuff on the outside.

When reflecting on people, consider the words of Martin Luther King Jr. “I have a dream that my four little children will one day live in a nation where they will not be judged by the color of their skin, but by the content of their character.” Consider people first and foremost by the content of their character, not by their skin color or the clothes that they wear or the things that they have.

Remember, anyone can wear a fancy set of clothes, but few can win the respect of their community. Anyone can live in a nice house, but few can bring about positive change in lots of lives. Value the character, not what’s on the outside.

Be Inspired By People Who Have Less Than You…

On one hand, I’m talking about people who are making ends meet with less financial resources than you have. How exactly are they doing it? I’m also talking about people who have turned extremely humble backgrounds into personal and financial success. How did they do that?

On the other hand, I’m also talking about people, regardless of financial specifics, who have committed to a simpler and more minimal life, with fewer possessions and fewer distractions. What is their journey like? What values are they seeking? How are they resisting distraction and temptation?

There are valuable things to be learn and inspiration to be gained from people who make do with less, regardless of how they do it.

Do volunteer work. One great way to start down this path is to actually interact in meaningful ways with people who have to make do with very little in their lives. Volunteer work virtually always brings you in contact with the realities of life on the edge, and it quickly becomes clear that many of those people struggle with burdens far beyond what you might expect and yet still manage to make it through.

The first time you help a single mother with two jobs carry groceries out to her car from the food pantry, only to meet her very well mannered children and catch a glimpse of the careful organization of her life and how she’s always on stage, you can’t help but feel inspired.

Study minimalism and decluttering. Take a look at the lives of people who live with very few possessions. How do they do it? Why do they do it? What is their life like?

What you’ll often find is a surprising amount of joy in a life lived without a lot of stuff. Rather than seeking out more things to own (and more space to store them), they seek out experiences and relationships and learning to create fulfillment for themselves, and those things often are far less expensive and require far less maintenance than a big house full of stuff.

Study people who elicited great things with few possessions and little wealth. This circles back to the idea of reading biographies, particularly of people from very humble backgrounds. One of my favorite stories is that of Gregor Mendel, one of the most influential early geneticists for his discovery of independent assortment and genetic segregation. He was pretty close to poverty for much of his life, working as a low-paid friar and raising pea plants and bees both for his own food needs and for the faith community he served.

Yet, even with those very limited means, he was able to devote much time and thought to his studies of how pea plants inherited traits from their parents, and those studies ended up becoming a fundamental part of the field of genetics.

You don’t need a lot of stuff to explore what interests you. You don’t need much to have a mind forever voyaging. You don’t need a great number of possessions to change the people around you or to change the world.

… Rather Than People Who Have More Than You

It might be nice to daydream about having the big amazing house with lots of elegantly decorated rooms, but consider what that would actually mean for your life. How much upkeep would be required – vacuuming, dusting, cleaning, and so on? How much would the insurance and property taxes devour? When that much of your time and money is gulped down, what’s left?

The desire to have a big home full of lots of possessions is a treacherous one, because it’s actually just a short term desire. To own such a home in the long term would either devour a lot of your free time and a lot of money, or if you had to hire help to maintain it, it would gobble down incredible amounts of money, leaving you strapped and unable to do the many other things you might want to do in life.

A good way to cut down on those dreams is to simply stop focusing on the things in your life that are nudging you to have those kinds of dreams.

Avoid media that focuses on the possessions and homes of others. If you see television shows that include lots of long drawn out shots of houses and cars that you could never afford, and particularly if the show involves extensive discussions of those things, just skip them. You’re only missing out on a sliver of the content out there and you’re skipping a particularly pernicious set of programming in terms of helping you channel your inspiration in a healthy direction.

Remember, our aspirations and goals and desires are influenced greatly by who we surround ourselves with and what kind of media we take in. Cut back on the media that points us toward heavy spending.

Don’t spend your time in appreciation of other’s possessions. Watch yourself for situations where you find yourself staring longingly at a neighbor’s car or daydreaming about someone’s house or driving slowly through an expensive neighborhood. Those are daydreams focused on spending money rather than building a stable financial foundation.

Instead, spend your time in appreciation of personal freedom, of people who may not have an abundance of material items but have a strong foundation and can thus make a lot of different life choices that enable them to do what they want with their time without the constant pressure of work and money needs. Admire freedom, not stuff.

Focus on how your life might be improved by your own financial success. Consider what your life might be like if you no longer had any debt. What would it be like to not have that constant pressure? Think about what it would be like to have enough saved up that you no longer had to stay at your current job and could take one with lower pay and more meaningful work. Think about what your life would be like if you didn’t have to work at all.

A lot of stress would just disappear. You’d have much more freedom to do the things you want to do. You wouldn’t be tired all the time.

Keep that visual fresh in your mind. Reflect on it often. Let it inspire you to better choices.

Be Inspired By People Who Exhibit Self-Control…

Self-control is one of the most valuable traits that a person can have on the road to financial recovery and financial independence, but it’s not a trait typically lauded by popular culture or social media.

Self-control is what builds a financial foundation, not impulsiveness and hedonism. It’s the ability to recognize that, sure, you desire something, but there is more value in not giving into every desire.

There are actually a lot of inspirational tools for this kind of thinking.

Read books about stoicism. Books on stoic thought are incredibly valuable for this kind of thinking, as stoicism is all about reflecting on one’s desires and making more rational decisions.

I highly recommend Meditations by Marcus Aurelius as a starting point. Marcus Aurelius was one of the last great emperors of the Roman Empire and Meditations is his personal notebook, where he reflected on how to be a wise steward of the wealth of the empire and how to handle both his inner circle of advisors and the citizens of Rome.

For a more modern take on the idea, check out How to Be a Stoic by Massimo Pigliucci, by William Irvine, or my own article covering how stoicism’s principles can help you transform your financial life.

Fill your social circle and build friendships with people who practice self-control. Look for people who don’t regularly succumb to unhealthy routines like substance use, who don’t seem to constantly have a flood of new possessions, and seem to have a good grasp on their physical health (at least to the extent that it’s under their control in terms of lifestyle choices). People who exhibit self control in at least some areas of life often have some degree of self control in most areas of life.

Remember, as Jim Rohn said, you are the average of the five people you spend the most time with. Elevate people in your life who naturally practice self-control over their temptations and find other healthier and more productive channels to spend their time, money, and energy.

Study people who achieved successes through willpower and sustained effort. One great way to keep yourself focused over the long haul is to regularly remind yourself of how great things are achieved by people who give long-term sustained effort to something.

Michael Jordan didn’t wake up one day as the greatest basketball player in the world. He got there because of sustained effort over many years. Winston Churchill wasn’t born a legendary orator. He practiced his speeches constantly, tweaking his delivery style and seeking improvement in getting his message across. John D. Rockefeller didn’t stumble into the enormous success of Standard Oil – rather, he spent countless years running around oil fields in Pennsylvania, balancing ledgers, and tweaking manufacturing and extraction processes. Sustained effort and willpower led these people to success, not momentary luck.

Don’t confuse a single three point shot made at a key moment as the sign of success. Rather, consider all of the practice and effort that went into building that person up to the point where they would have the opportunity and courage and ability to take that shot.

… Rather Than People Who Revel in Hedonism

It can be fun on some level to watch a pleasure seeker buy endless piles of clothes, go out to clubs constantly, buy tons of expensive foods and meals, and so on. The problem is that when the cameras turn off and people look away, that person’s usually left with nothing at all.

If the joy in your life is centered around the fleeting joy of consumption right now or in the very near future, you’re going to struggle mightily when your bank account is empty and those opportunities aren’t there any more. If you find yourself falling into that cycle of joy based on the pleasures of the moment, especially when those pleasures cost your money and your health, consider backing away from that and from the influences that got you there.

Avoid reality television, especially centered around the lives of the wealthy. A large portion of reality television is centered around hedonistic living, where people chase the latest pleasures, whatever they might be. They go shopping for new clothes constantly, go out to the clubs constantly, gawk at expensive houses constantly.

Turn that stuff off. It makes up only the tiniest sliver of content available to you anyway. Look for something else – anything else – to watch.

Minimize your relationships with people who consume their money and time in wasteful and harmful ways and center their time and energy around further consumption. If you know people who rely on alcohol and drugs to enjoy anything, people who constantly turn to “retail therapy,” people who can’t seem to find any joy unless they’re going out to an expensive restaurant or bragging about their expensive stuff, they’re living a hedonistic lifestyle, one that’s in almost direct opposition to financial success, and that lifestyle and mindset is likely to rub off on you at least a little.

Rather than following along with it, intentionally seek to find other friendships and relationships in your life to accentuate and minimize your relationships with people who are strongly hedonistic.

Tune out of the social media of people who constantly post about their consumption and possessions. If you tune into the social media feeds of people who are always showing off their latest stuff and their latest expensive experience, tune out. Such feeds are less about the person themselves and rather about the stuff they’re buying and consuming. (Better yet, tune out of social media entirely.)

There can be value found on social media, but it involves following people who use social media, at least in part, as an act of self-reflection or as a method for sharing the things they’re doing to bring themselves closer to their life goals or their true internal values. Focus on those people, not the product placement people.

Be Inspired By Dreams of Achievement…

Often, the most powerful inspirations we have come out of our own head. We visualize things that we want in our own future and keep coming back to those visions, crystallizing them until they become a guide for our actions.

Let your own imagination and dreams inspire you and become the basis for your actions and choices.

Set meaningful goals for yourself and develop plans for achieving them. We all have daydreams, but it’s when we sit down, figure out which ones we can actually achieve, and then translate them into actionable goals for ourself that they become real and tangible.

What can you do this year to achieve something you really want? What part of that can you tackle this month? What part of that can you tackle this week? What part of that can you finish off today – right now, hopefully? Ask yourself that over and over again, because that’s a path connecting your dreams of achievement to your actions today, and you’ll feel inspired to take that action.

Study the goal-setting practices of others, particularly those who have a history of achievement, and see what you can emulate. I read a lot about goal setting and planning, not because I deeply enjoy productivity busy work, but because I want to deeply understand how others translate their big dreams into actionable goals and then into things they can do today to move toward those goals.

Spend time reading books and articles that are about that very subject – how different people organize the big goals they have for themselves and break them down into steps that they can actually follow. There are lots of different variations on this and I find each of them inspiring. Often, they end up helping me tweak what I myself do.

Practice envisioning a future for yourself where you’re doing things rather than possessing or consuming things. When you’re daydreaming about the future and transforming it into goals, focus not on the things you’ll own (or, if you do, keep them really modest) and instead focus on the things you want to be doing with your time that, for whatever reason, you can’t do right now.

What do you want to do in the future? It probably requires some skill building. It probably requires a financial foundation, too. Start figuring out how you get from where you are to where you can be doing that thing to the level that you dream of.

… Rather Than Dreams of Possession and Consumption

Even though some of our daydreams are very inspirational in terms of a “big picture” view of our lives, an awful lot of daydreams fall into the short term “desire” picture. We envision things that we want right away (for me, for example, those daydreams right now tend toward an Apple Watch and a pasta machine).

We all have those dreams. The key is to recognize them as false inspiration and figure out how to handle and de-emphasize them.

Avoid “retail therapy” or situations where you shop as a form of entertainment. Putting yourself in situations where you’re in retail or online stores for any purpose other than making a planned purchase is an exercise in whipping up material desires. Kill those financially damaging “inspirations” by simply avoiding them. Don’t engage in “retail therapy.” Don’t shop as a form of entertainment.

If you’re struggling with this, just consider things that you enjoy doing that don’t involve an outlay of money. What hobbies do you have? What things have you always wanted to try? Focus on those things, and strive to fill your spare time with them instead.

Avoid media that seems centered around the latest products. An astonishing portion of news coverage is centered around hyping new products: the newest Apple gadget, the newest car, the newest clothing trends, even stuff as ludicrous as the hottest paint color.

If you’re watching a television program or reading a website or checking out a social media posting and all it’s doing is telling you about a new product of some kind, check out. That “news story” isn’t helping you in any way; it’s just cultivating desires that aren’t helpful for your bigger goals in life.

When you find that you want something and are tempted to spend money on it, ask yourself what experience you hope to gain from that expense and then look for better ways to gain that experience or something similar. In other words, identify what things you actually want out of life, recognize that the product you’re tempted by probably won’t get you there, and then look for the actual ways you might get to that goal.

You’re shortchanging false desires and inspirations by seeing that they won’t actually get you to where you want to be. Don’t despair in that – instead, use that as fuel to find things that actually will take you to where you want to be.

Be Inspired By Meaningful Experiences…

Every single person’s life is made up of an infinite multitude of experiences. Most are pretty ordinary and relatively meaningless, but some of them provide deep meaning to us. They’re the experiences that stick in our minds, building up our motivation and convincing us to change how we act.

Meaningful experiences are valuable, and they come in all shapes and sizes. Many of them are absolutely free. Some cost just a pittance. Others, yes, are expensive. If you seek out experiences based on their meaning, first and foremost, you’re likely to gravitate toward the abundance of low cost and meaningful experiences that the world provides for us.

Check out free or low cost activities that many other individuals have described as deeply meaningful for them. For me, the most meaningful experiences I have regularly are times when I meditate, when I write meaningful things, when I exercise, and when I get lost in the moment of whatever I’m doing. During those times, it feels almost like a different switch flips on in my head, one that I can’t ordinarily access, and I feel somehow different, somehow better.

Try lots of ordinary experiences that others have identified as meaningful. Try meditation – it might click with you or it might not. Try getting more exercise. Try reading powerful books. Try going to a free concert and just getting lost in the music. Try going to a powerful religious service. Try things – there’s a wide variety of human experience out there and when something clicks, it can be incredibly inspiring and life changing. It can change almost everything you do.

Look for great experiences you can have closer to home that you may not have explored before. People often seek inspiration in experiences that go beyond the everyday of their life. They’ll go on trips or other adventures in order to seek out some meaningful peak experience.

The truth is that there are thousands of unexplored places relatively close to home that might provide meaningful or inspirational to you. You don’t have to travel halfway across the globe to find inspiration or a deep meaningful experience. You might find it on a backwoods trail at a nearby state or national park. You might find it at a religious meeting of some kind in your very community. You might find it on stage at a local theater. Great, novel, inspirational experiences can be found everywhere if you simply look a little closer to home.

Try lots of variations on experiences that you’ve found meaningful in the past. If you’ve found, say, prayer to be inspirational in the past and now it’s faded, try a new way of praying. Go from simply saying what’s in your heart to reciting a short prayer or a mantra many times. If you’ve found journaling your day to be meaningful in the past but that’s faded, try writing three morning pages.

You may just find that the new variation breathes life into the old practice or even carries it to a more meaningful level than before. Such new practices can inspire you onward to greater things in life.

… Rather Than By Expensive Ones

It’s often easy to fall into the trap that expensive experiences are inherently the most meaningful ones or the “best” ones, but that’s often not the case at all. You can pay hundreds of dollars to have a dreadful meal. You can pay thousands to go to a seminar that’s so dull you fall asleep. Even a toilet can be gold plated.

The trick is to not simply substitute “expensive” for “meaningful” or “inspirational” and instead look for what might actually have an impact without prejudging how great it is based on the price tag.

Skip over costly activities and experiences unless the evidence of their value is overwhelming. By default, I tend to skip expensive experiences unless it is extremely clear that there will be a great deal of value to be found there. Why? There are many, many, many inexpensive or free experiences that I know will be meaningful to me that I haven’t engaged with yet, so why throw money at expensive ones?

I find a great deal of inspiration from being in an amazing natural place. I’ve visited maybe 20% of our national parks at all and, out of those, I’ve spent enough time to truly explore and enjoy and be inspired by exactly zero of them. Why do I need to fly to Kilimanjaro to be inspired when there are so many opportunities at far less price closer to home?

Avoid travel media. Travel media is almost singularly designed to convince you that the only good experiences are in remote places with a hefty price tag, which isn’t true at all. It’s an illusion created by travel magazines and television shows and radio programs.

Turn those things off. Instead, look within yourself for what you’d like to see. Discover things by serendipity in the other things you read and hear about. Let those guide you, not glorified travel brochures.

When learning about the travels and experiences of others, look for how they grew, not what they specifically did and where they did it. I almost always ask people what the best part of their trip was – not the best thing they saw or the most amazing place they went, but what moments they’ll really remember from all of it. Often, it’s a moment spent with a travel companion, or an ordinary moment on an unfamiliar street.

Why is that so important? It reveals the truth of peak experiences – they’re all around us, in the people we spend time with and in the relatively ordinary places we go. Those moments of inspiration can strike anywhere; you don’t have to go to a sacred site in Bolivia to find them.

Look for the elements of meaningful but expensive experiences that you can replicate in a free or inexpensive way. What kinds of experiences are really being offered by those expensive experiences? An exquisite natural setting? An appreciation of the effort of humans past? A deep religious or spiritual experience? What’s drawing you to this?

Once you figure out what kind of experience is drawing you in, ask where else you can find a similar experience. Perhaps there’s something similar in the next state rather than halfway around the world. Perhaps there’s something similar for free if you head west rather than incredibly expensive at a tourist site in the east. Look for that inspirational experience you desire elsewhere.

Final Thoughts

People seek and find inspiration in a wide variety of ways, but, particularly with financial inspiration, it’s easy for that experience to be misguided or the sticker price of that inspiration to be incredibly high.

You don’t need a mountaintop on the other side of the world to be inspired. You don’t need a several thousand dollar seminar to believe you can do great things. You just need good material around you, good people in your life, and an open eye and an open heart.

Good luck!

The post Finding Inspiration for Financial Success appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2PTsbiz

Four Reasons Traveling in October Can Save You Money and Enhance Your Trip

You Don’t Have to Be Walt Whitman to Win This $1K Poetry Scholarship Contest


Roses are red, violets are blue, and you could win $1,000 by sharing what a mentor meant to you.

Is there someone in your life who has inspired or guided you along the way or assisted in your personal development?

Here’s a chance to pay that person homage and enter to win a $1,000 scholarship toward college.

Power Poetry is holding an “O Captain, My Captain Scholarship Slam” scholarship sweepstakes.

How to Enter the Poetry Scholarship Contest

The contest is open to all current and former high school students who are in college or will attend college within the U.S.  All entrants must be 25 years old or younger to enter.

Before you enter, you must register as a member of the Power Poetry community, which promotes the writing of poetry.

Once that’s done and you’ve composed an ode to your mentor, all you have to do is submit your original poem with a title. That’s it.

The $1,000 scholarship winner is chosen in a random drawing — which means this is more about luck than being a wordsmith. Just keep your submission original and cross your fingers.

The deadline to enter is Oct. 25, 2018.

Check out the contest rules and contact Power Poetry with any questions.

May the odds be ever in your favor.

Like our College page on Facebook to discover other scholarship opportunities.

And if you’re looking for even more scholarships to apply for, be sure to check out our list of 100 scholarships that will help you pay for college.

Stephanie Bolling is a staff writer at The Penny Hoarder. She’ll always be thankful for the wisdom and compassion of her mentors.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder https://ift.tt/2QRoJ9x

Here Are a Few Ways Around Those Rising Airline Baggage Fees


JetBlue did it first. Then United did it. And now, Delta and American have joined their competitors in hiking fees for checked baggage.

It now costs $30 each way for the first checked bag and $40 for the second bag — up from $25 and $35, respectively.

In a statement, American Airlines said it hadn’t raised the fees since 2010.

That’s cold comfort to passengers, said Douglas Kidd, executive director of the National Association of Airline Passengers. He said Wall Street is pressuring the airlines, whose stocks are publicly traded, to ratchet up fees to maximize profits.

In the first six months of 2018, United reaped nearly $603,000 from baggage fees, according to the Bureau of Transportation Statistics. United took in more than $411,000, Delta $375,000 and JetBlue $150,000.

“Wall Street wants them to upsell,” said Kidd, whose nonprofit advocates for passengers. “We say charge what you need to charge [for a ticket], and don’t nickel-and-dime the passenger to death.”

What You Can Do to Avoid Checked-Baggage Fees

Short of driving or taking a train or bus, passengers have a few options:

  1. Fly Southwest, which still allows passengers to check two bags for free. “Southwest is very proud to offer our Bags Fly Free program,” company spokesman Dan Landson said. “We have no current plans to start charging for checked bags.”
  2. Apply for an airline-branded credit card. Some cards include waived baggage fees. But the terms vary from card to card and annual fees are required, so you’ll have to do the math to make sure the trade-off makes sense for you.
  3. Buy an airline baggage subscription. These pricy plans — United’s start at $349 a year, plus a $50 initiation fee that currently is being waived — are best for people who fly often. For that price, United allows a traveler and up to eight companions on the same reservation to check two bags each.
  4. Travel light. This obviously is the most practical choice for budget travelers. As a general rule, airlines allow one free carry-on bag small enough to fit in an overhead bin and one personal item such as a purse, computer bag or briefcase, Kidd said. (In basic economy class on American, only a personal item is allowed.) He advises flyers to always pack a change of clothes, clean underwear and a few toiletries in a carry-on bag even if they do check other luggage —  just in case it gets lost.
  5. If you need a large bag, price the parcel rate and ship it a few days in advance if it’s cheaper.
  6. Buy stock in the airline you fly (it doesn’t have to be a lot) and complain to shareholder relations as well as consumer relations. Shareholders have more clout, Kidd said.

“Traveling today is enough to test the patience and equanimity of most passengers,” he said

Susan Jacobson is an editor at The Penny Hoarder.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder https://ift.tt/2xIX8hJ

الجمعة، 21 سبتمبر 2018

Discover it ® Business Credit Card Review

How to Become Profitable with Instagram Ads

I’m sure by now you recognize the importance of staying active on social media to promote your business.

Your Instagram marketing campaigns need to be a priority.

If you’re not using Instagram to reach your customers, there is a good chance your competitors are doing so. In fact, more than 70% of businesses in the United States are using Instagram.

Furthermore, 70% of hashtags on this platform are branded.

That’s why it’s so important for you to leverage your Instagram profile to connect with your current customers and target prospective consumers as well.

Believe it or not, consumers want to interact with brands on social media. We know that 80% of Instagram accounts follow at least one business profile.

If you’re getting lots of followers, that’s great. However, you need to learn how to convert your social media followers into customers, or your efforts won’t pay off.

But what about the consumers who don’t follow your business on Instagram?

They might be interested in your products, services, and content, but they won’t see any of your promotions if they’re not following your profile.

That’s where Instagram ads come into play.

Buying ads on Instagram will help give you a huge advantage over your competitors who aren’t willing to spend the money.

That said, any time you’re spending valuable marketing dollars, it’s important to make sure those efforts yield a high ROI. You don’t want to blindly buy ads without making sure they’re profitable.

If you’re new to Instagram ads or if your current ones need improvement, you’ll benefit tremendously from this guide.

I’ll explain how to drive sales with your Instagram marketing strategy, get more followers, and expand your reach. Here’s what you need to know.

Determine your marketing objective

Instagram is owned by Facebook. You’ll be using the same platform you used to generate leads with Facebook ads.

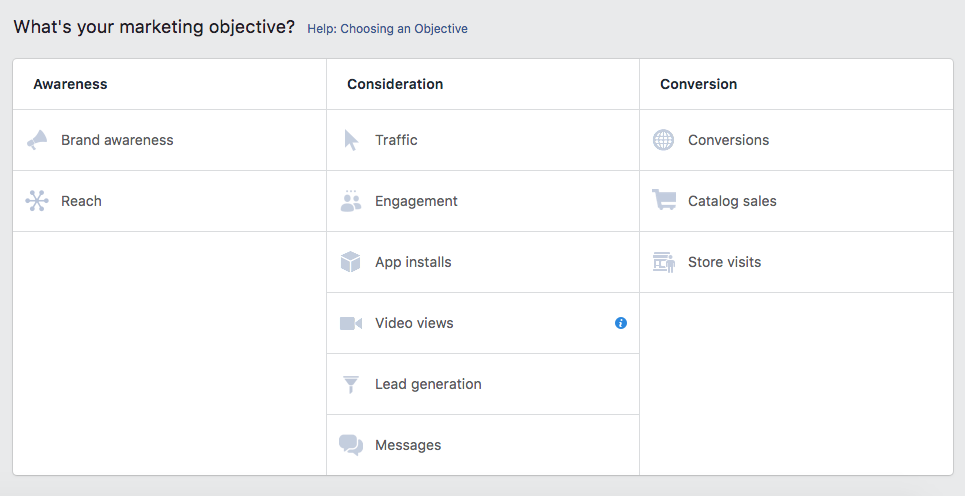
The first thing you’ll need to do is select your marketing objective:

marketing objective

The goals are broken down into three main categories:

  • awareness
  • consideration
  • conversion

Truthfully, there is no right or wrong answer here when it comes to making this selection.

Any choice can lead to profits. For example, if your goal is to generate website traffic, that traffic can eventually lead to conversions.

If you are trying to increase your brand awareness, extend your reach or generate leads, those campaigns can end up creating sales in the future.

But if you’re trying to get instant sales, you’ll want to select conversions, catalog sales, or store visits as your marketing objective.

These types of ads will have actionable CTAs to drive sales. But we’ll discuss that in greater detail shortly.

Again, your ads will be effective no matter what you choose. Everyone’s brand is different. Don’t expect your goals to mirror those of other companies.

If you have the budget, you can even run multiple campaigns with different goals to see which ones are the most beneficial for your business.

Then, you can continue running the most successful ones.

Identify your target audience

Next, you’ll need to determine the audience you want to target.

There are different approaches to this step, depending on the overall marketing goals of your company and each campaign.

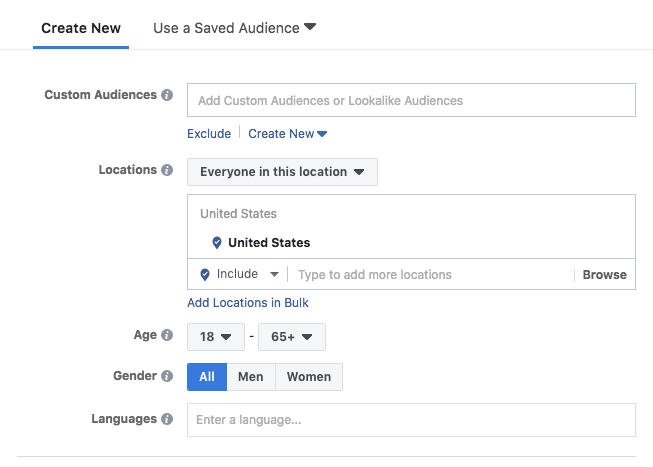
target audience

You’re able to select your audience based on factors such as:

  • location
  • age
  • gender
  • language

Again, this will change based on each campaign. For example, let’s say your brand sells sports equipment to consumers in the United States.

That doesn’t mean all your ads will be relevant to every location.

An ad that promotes a sale on surfboards won’t appeal to someone who lives in Colorado. Ads for women’s golf clubs should be seen only by, you guessed it, women.

I know this sounds basic, but you’d be surprised how often I see businesses make such simple mistakes. They try to target as many people as possible, which isn’t a profitable strategy.

Another cool feature you should keep in mind when you’re selecting your target market is the ability to create a custom audience.

This allows you to set your ads to reach users who have interacted with you before.

For example, a person who doesn’t follow you can still see one of your posts on the Instagram “explore” page, also known as the “popular page.” That’s a custom audience you could target.

You can also set a custom lookalike audience. These ads will target users similar to your current followers.

Set a budget

I don’t recommend spending every dollar in your marketing budget on Instagram ads, especially if this is your first time using this strategy.

Get your feet wet before you dive in head first.

Everyone’s budget is different. But let’s keep things simple for now and say that your company has allocated $5,000 to spend on Instagram ads.

That’s great.

However, it doesn’t mean you should dump all $5,000 into one campaign. Mix it up.

As I said before, you’ll want to experiment to see which types of ads benefit your brand the most based on your goals.

Try running five campaigns at $1,000 each.

Don’t run them all simultaneously. Not everyone who sees your advertisements will convert. But if they see three ads over the course of a couple of months, it might get the job done.

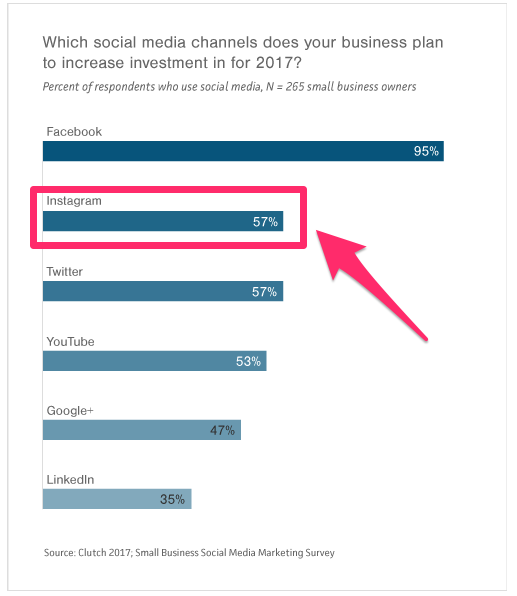
While it’s important for you to spend within your means, it’s worth noting that even small business owners are planning to increase their Instagram marketing budgets.

increase investment

As you can see, Instagram is second only to Facebook in the list of all social media networks small businesses plan to spend more money on in the coming years.

If you don’t have the funds to spend much money on Instagram ads right now, you should budget accordingly for the future.

The last thing you want is to let your competitors beat you to new leads. Or even worse, lose your current customers to the competition because they ran ads and you didn’t.

Choose which types of ads you want to run

There are a bunch of different types of ads you can run on Instagram. That’s because the platform is versatile. These are all the options for you to consider:

  • photos
  • videos
  • carousel
  • stories

One of the best parts about Instagram ads is that your content appears naturally within the rest of the content seen by users.

Such posts are clearly labeled as sponsored ads, but they still look like any other content from any other account an Instagram user might follow.

For example, let’s say a user is browsing through the stories of the accounts they follow. If you run a story ad, your story will be presented between two stories posted by profiles they follow.

Sure, a user may recognize they’re seeing an ad. But that won’t necessarily stop them from consuming your content.

In fact, 60% of users say they use Instagram to discover new products. And 75% of that group follow through with an action after that discovery.

The action may not be a purchase—it could be a click to find out more. But that should give you a chance to get these users to convert.

Use an actionable CTA

Your CTA will have a big impact on how users react to the sponsored content they’re presented with.

Let’s assume you accurately selected your target market and your ad is being displayed to those interested in your product and willing to buy. How can you get them to convert?

Invite them to buy with action verbs. Get right to the point.

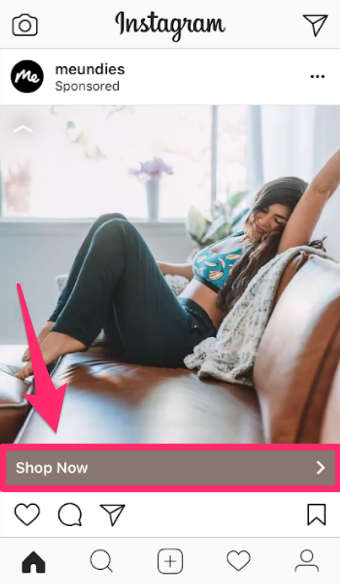
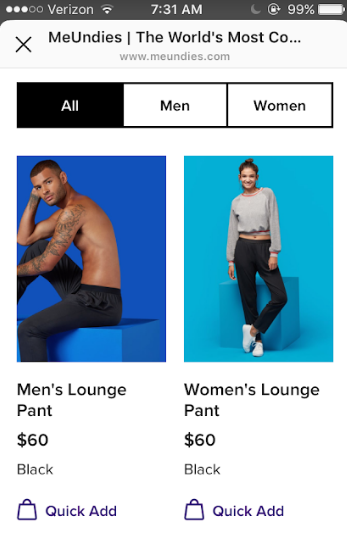
Check out this CTA example from a MeUndies advertisement on Instagram:

meundies

Shop now.

There is nothing ambiguous about this CTA. It’s much more actionable than something like “find out more information here.”

That type of CTA won’t drive sales.

But with a call-to-action such as “shop now,” users who see this advertisement will know exactly what to expect when they click on the button.

meundies2

As expected, this CTA brings you directly to the brand’s ecommerce shop.

Take a look at this landing page to see how MeUndies is able to drive sales with its advertisement.

It’s very simple.

Since people are viewing these ads on their mobile devices, don’t try to cram too many products onto the screen at the same time.

Here, when users scroll, they see only two products at a time.

Now, take a minute to scroll back up to the original post. It featured a model wearing sweatpants.

Naturally, the first two products displayed on the landing page are sweatpants. It makes sense and should promote conversions.

Let’s say your Instagram advertisement is promoting a new backpack, but your CTA brings them to a page selling water bottles.

Sure, the users might be interested in that product as well. However, they clicked on your CTA because they wanted to see the product in your original ad. Make sure the two match.

We’ll discuss your landing page in greater detail shortly.

Showcase your top benefits

You need to realize how people use Instagram.

They’re scrolling through posts at a fairly rapid rate. Don’t expect people to stop to analyze your ad if it’s overly complicated.

If your benefits can’t be identified right away, the user has no reason to click your CTA button.

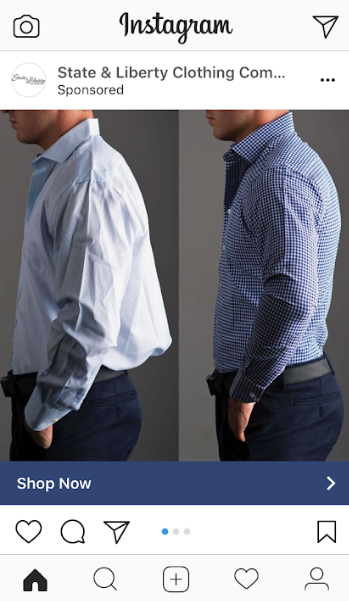
You’ve got to come up with ads that are easy to recognize at a quick glance. Here’s a great example of how State and Liberty is able to accomplish this with its advertisement:

state and liberty

It’s very clear what the carousel ad is trying to convey.

Same model, two different shirts.

The shirt on the left looks messy, coming untucked. Many guys can relate to that.

But the shirt on the right looks great. It fits the model perfectly, which makes him look sharp.

Combining two images in one picture is much more effective than showing one shirt without anything to compare it to.

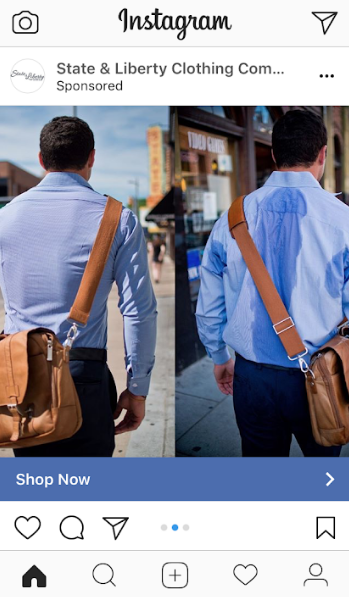
Once a user sees this, they may be interested enough to keep swiping through the rest of the carousel ad.

state and liberty 2

The next image of the ad uses the same strategy.

One shirt is neat, fits properly, and doesn’t cause the model to sweat. While the other shirt is messy, loose, coming untucked, and covered in sweat.

Even if the differences are embellished, that’s okay. It’s still an extremely effective way to promote the brand.

In just two pictures, this company is able to showcase how it differs from the competition by highlighting the top benefits of its product.

This campaign paired with an actionable CTA is a great way to drive sales.

Create a landing page that drives conversions

Your advertisement might be great.

You were able to pick the right marketing objective and target the perfect audience, and the content of your ad is getting people to click on your CTA.

However, all of this is useless if your landing page isn’t set up to drive conversions.

When a user clicks a CTA that says something like “shop now,” they shouldn’t land on your blog or homepage. You want to bring them directly to your ecommerce shop.

Make it easy for them to complete the checkout process with just a few clicks.

However, depending on your marketing goal, you can set up other types of landing pages to drive conversions, even if those conversions aren’t sales.

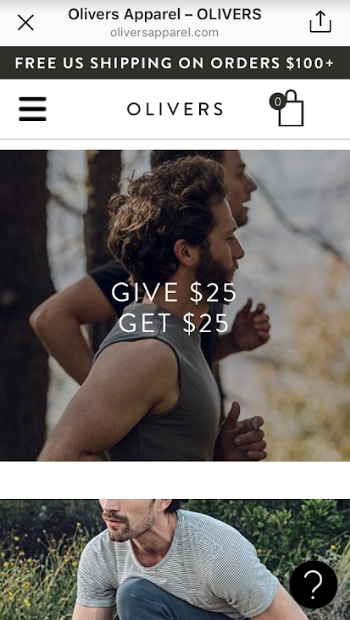
Check out this example of a landing page from Olivers Apparel:

oliver appearal

The company encourages users to recommend its brand to other people.

By sending $25 to a friend, they’ll get $25 in return. It’s a very enticing offer for a user exposed to a new brand for the first time.

You might be hesitant to spend money on a product you’ve never used before.

But $25 off your order may be a good enough reason for you to buy.

This strategy is a great example of a customer referral program that drives sales.

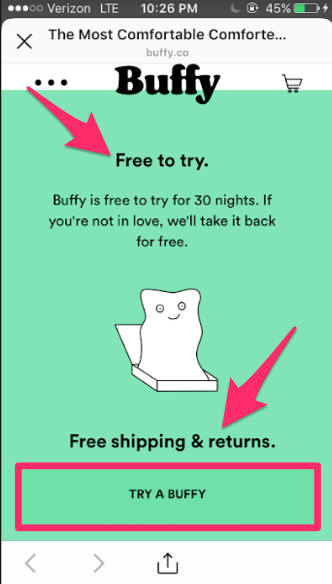
Let’s look at another landing page strategy from Buffy. You might want to consider using it in your marketing:

buffy

Instead of turning its prospective customers away with expensive prices, the brand’s landing page gives them an offer they can’t refuse.

You can try this product for 30 days at no cost.

They’ll ship it to you free, and if you’re not happy with it after a month, you can send it back—free too.

Instead of a CTA that says “buy,” the company used “try.”

Further, 30 days is plenty of time for prospective customers to decide whether they like the product or not.

Since Buffy offers such an enticing deal, I’m assuming the team is confident in the quality of its product, expecting the customers to be satisfied.

Sending Instagram users directly to your ecommerce shop is a great way to drive sales. But as you can see from these last two examples, you can use other types of landing pages that convert.

Highlight what makes your brand unique

This concept is similar to the idea of showing off your top benefits.

However, you and other brands may have similar benefits. If you can explain what makes your brand unique, you can have a competitive advantage.

For example, let’s say you sell athletic footwear. Some of its top benefits may be related to comfort, durability, style, and performance.

But does that really separate you from the crowd?

Something that makes your brand unique may be that a portion of your sales goes to a particular charity. That’s unique.

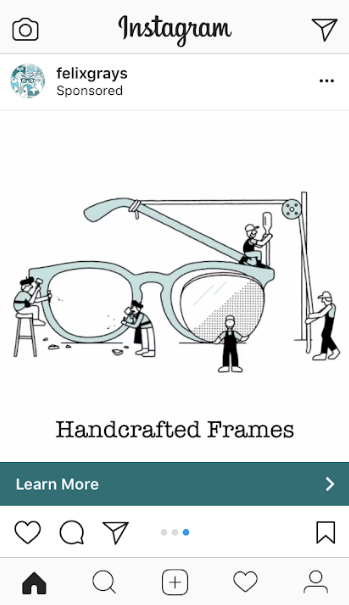
Here’s a more specific example from a Felix Gray Instagram ad:

felix grey

The company sells different types of glasses.

But does that make them unique? Not really.

However, this advertisement says that its frames are crafted by hand. That’s worth mentioning as part of a differentiation strategy.

Conclusion

Your company needs to have an Instagram marketing strategy.

While you can use Instagram free, running ads can give you the competitive advantage you’ve been looking for. This will help you target new customers outside of your existing followers.

Start by identifying your marketing objectives. Then, decide what audience you want to target with each campaign.

Choose which type of ad you want to run. Budget your ads accordingly.

Make sure your CTA is actionable.

Create an ad that showcases the top benefits of your products. Explain what makes your brand unique.

Design a landing page that drives conversions.

If you’re able to accomplish everything I’ve explained in this guide, your Instagram ads will be effective and profitable.

What types of ads is your brand using to drive sales on Instagram?


Source Quick Sprout https://ift.tt/2O2JlwK

Why I Don’t Recommend Individual Stock Picking

One frequent question that readers ask me is advice on whether or not they should invest in the stock of a particular company.

“Is it a good time to buy Google?”

“Should I invest in Amazon?”

“Thinking of putting some of my retirement money into Citibank shares. Thoughts?”

Almost universally, I respond to such folks like this:

“No.”

“No.”

“No.”

Why? What do I have against investing in individual stocks?

It’s simple. Unless you are investing with money that you are literally never going to need in your life, the risk of individual stock investing is simply too high for me to recommend it, no matter how amazing the company seems. There are a lot of sources of risk in individual stock investing and they add up to too much risk for the vast majority of individuals to use as an investment strategy.

Let’s walk through some of the many issues of investing in individual stocks.

First, you’re probably behind the curve of when you should invest in a company or sell shares. By the time a piece of information becomes general public knowledge so that an individual investor can act on it, it’s already been acted upon by large scale investors and the market price has already been adjusted.

Let’s say the company issues a really good quarterly earnings report and it seems like that company is hitting on all cylinders. By the time you’re even aware of this, the value of that company’s stock has already taken off.

Similarly, let’s say some minor bad news comes out about a company and you think it’s time to sell. By the time you can even take action on it as an individual, the company’s stock will have already fallen in value.

Why? Not only do large scale investors often hear such info before you do, their computer systems react to such news instantaneously. You have no chance whatsoever of beating them.

In short, you’re not going to be able to take advantage of information in any real way, because by the time you hear about it, the company’s share price will already account for it.

Second, you can’t predict the future. You have no way of knowing if the economy is going to keep rolling like it is or if it’s going to fall off the tracks in the next two years. You have no way of knowing if a company has a great product about to come out of R&D or if they’re running on eggshells and about to collapse. You have no idea whether some other company is about to revolutionize that sector and push your company aside, or if your company’s going to be the one to revolutionize it. You just don’t know.

Investing broadly takes care of these kinds of risks. By investing in lots and lots of companies at once, you’re going to have some shares that are taking off like a rocket, some that are kind of idling in place, and some that are dropping. On average, throughout history, they’ve gone up at a pace between 7% and 10% over the long haul, but there have certainly been years during economic downturns where the average value has dropped.

On the other hand, individual shares have years where they triple in value and years where they lose all value, and as an individual, you have little ability to tell which is which. In late 2000, Enron looked like a great investment in one of the biggest companies in the world. By late 2001, it was a penny stock.

Why is this bad? In general, individual investors can’t really afford to lose their entire investment unless they’re already financially set for life and they’re investing with the excess. If you don’t have a financial fortress of at least enough to keep food on the table for yourself and your immediate dependents, you shouldn’t be taking on extreme risk with that money.

Third, it takes time to do this well. To actually invest and not just gamble based on what you heard on CNBC or from your buddy at work, you have to spend time reading earnings reports and SEC filings and other things like that. (If you’re not doing that, you’re going to be eaten alive by those who do because those who do that extra work are going to blow you away in terms of knowledge.) If you’re invested in a number of companies, that’s going to be a lot of time and effort.

Let’s say, however, that you still think it’s fine to invest in individual stocks because you still believe it’s financially prudent. There are still several mechanical reasons why it’s a bad idea.

For starters, it’s expensive to invest in individual stocks. To do this as an individual, you’re going to have to work through a brokerage. A brokerage is going to charge you for each and every buy and sell that you make. If you buy shares, you have to pay a fee. If you sell shares, you have to pay a fee.

Now, if you’re buying and selling shares in large quantities, the fees aren’t a big deal. If you’re buying $100,000 worth of shares of a single company, a $9.99 buy fee is only 0.01% of your investment. However, if you’re not dealing with such large sums of money, the percentage shoots right up. If you buy $1,000 in shares of a company, that $9.95 fee is 1% of your investment gone, right there, and then if you sell those shares later, that’s another 1% of your initial investment that vanishes. You have to get a 2% return on your investment just to break even. Similarly, if you wish to diversify your investment at all, you’re now executing multiple buys and sells, each of which comes with a brokerage fee.

Another issue is emotional attachment. When you’re investing in individual stocks, it’s incredibly easy to get emotionally attached to one company. You likely know a lot about this company. You probably believe in this company – or else why would you be investing your hard-earned money in them? When you have those kinds of connections, it’s very easy to believe that genuinely bad news is just a speed jump and minor good news is huge, great news.

Because of this, it’s often really hard to see when you should be dropping an investment in a company. Individual investors will often stick with a company long past the point where they should have sold their shares because they know that company and they believe in that company and that often blinds you to warning signs and little problems. We’re human. We can’t help but wear rose-colored glasses sometimes.

Finally, diversification is really, really hard. A single investment in the shares of an individual company is a really really risky move. You can mitigate that risk by investing in lots of companies in different industries, but by doing so, you multiply the amount of time you have to invest in studying all of those companies (the annual reports and quarterly reports and SEC filings and other materials mentioned earlier). You are also multiplying the fees you’re paying at your brokerage.

Again, as I said earlier, you could simply skip all of that work and just trust your “gut” or the advice of some guy at work. If you do that, though, you’re going to be eaten alive by those who are very informed on the subject and actually do the homework. You’re hoping your “gut” beats them. Hint: you won’t unless you’re incredibly lucky.

Now, multiply all of that effort across lots of companies.

What you’re looking at is something that’s akin to a full time job. It might be enjoyable, but it is going to gobble up a lot of time and energy. Even then, you’re still not going to be able to get ahead of the large scale institutional investors.

Given these factors, I simply can’t advise individual investors to put any money into individual stocks. Instead, I point individual investors toward index funds, which basically amount to investing in the stock market as a whole (or, as I like to think of it, an investment in capitalism in general). By doing this, you’re basically buying all the companies, which means there’s no real need to study individual companies at all. Put your actual investment money into things like the Total Stock Market Index, not into individual shares of Google.

But what if this whole thing just seems really exciting to you and you really want to invest in individual stocks? If you feel that way, I strongly encourage you to find other ways to channel that energy. Seek out a local investment club where people will discuss investing. Look for online stock picking forums. Look for stock picking contests to enter. What you’ll quickly see is that while it can be quite fun, it’s also incredibly risky, the type of risky that you don’t want to commit your life savings to.

If you really insist on investing, budget for it and treat it solely as entertainment, not as an investment. I buy things with my entertainment budget that retain value and sometimes increase in value, plus I get to enjoy them as entertainment. Treat your stock picking in the same way. If money goes in, budget it as entertainment. If it comes out, great! Use it for something useful or else just reinvest it.

If you’re not extremely wealthy and you’re thinking of buying individual stocks as a genuine part of your future investment portfolio, don’t. Instead, invest in something more diverse or, even better, clean up your financial life by eliminating debt or saving for upcoming big expenses. Your life will be in much better shape if you choose that path.

The post Why I Don’t Recommend Individual Stock Picking appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2xDiPjy

11 of Our Favorite Money Apps — and Their Most Surprising Features

How This Woman Went From Almost Homeless to Flipping RVs for a Living

My Boss Is Nagging Me to Get a New Car… and She Knows How Little I Make


Dear Broke,

Let’s look at the good first, because everyone needs some encouragement: You graduated college (yay!), got a job (excellent work!) and are living within your means (wahoo!). You have a lot to be proud of right now. There are moments when you feel underpaid, and there are moments when your car will sputter out on you, but overall, you’re holding the reins on your life with good control. Don’t lose sight of that.

The reason I’m reminding you about all the good things you have going for you is that I have serious doubts you’ll be able to get your boss off your back. Since you’re a reasonable person who wants to stay employed, I vote for the humorous approach. Practice a few not-so-snappy comebacks for when your boss starts to nag about your wheels. Here are a few suggestions:

“Look, it’s not pretty, but it gets me around.”

“I’m committed to a lifestyle of only unshiny, old wheels.”

“I know it’s not much to look at, but I’m pretty attached to that car.”

“I’m actually in a bet for how long the car can last. You don’t want me to lose, do you?”

Look, some of them may not be true, but the broken record of lighthearted brush-offs will eventually get old for your boss. It sounds like you work at a small company and can’t avoid interacting with your supervisor, but you can choose not to engage further.

Even if your life at home were filled with puppy dogs and rainbows right now instead of stress, I still wouldn’t want you to have to justify your financial choices to anyone but yourself.

Have a tricky money question? Write to Dear Penny at https://www.thepennyhoarder.com/?aff_id=178&aff_sub3=MainFeed__smart-money/budgeting/dear-penny-beater-car/dear-penny/?aff_id=178&aff_sub3=MainFeed__smart-money/budgeting/dear-penny-beater-car/.

Lisa Rowan is a personal finance expert and senior writer at The Penny Hoarder, and the voice behind Dear Penny. For more practical money tips, visit www.thepennyhoarder.com.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder https://ift.tt/2pqW6TX

الخميس، 20 سبتمبر 2018

Dismal customer service adds to woes over British Gas complaint

Teletubbies

Some of your queries are relatively easy to sort out. They usually involve a problem or mistake and once I point it out to a company, it usually tries to respond positively.

But then there are the complaints that go on for months and often don’t even make it to this column as I can’t persuade a firm to see sense and play fair.

DF sent me a long and impassioned email back in April in which he reported: “Our daughter has almost been driven to a nervous breakdown over all this”.

He wrote: “I am writing to you as I have run out of options to help us with a dispute with British Gas.”

He told me his daughter applied for a green deal grant offered by British Gas in partnership with the local authority to insulate her Plymouth house in 2015. Things began to go wrong right from the beginning, he said, as workers put up scaffolding that perforated a flat roof. That led to water pouring in, ruining a recently plastered ceiling.

He continued: “Over the past three years, there has been a whole catalogue of incidents and accidents that our daughter has documented relating to poor and shoddy workmanship, from workmen falling through a window and shattering the glass and then replacing it with glass that didn’t fit properly to pouring surplus concrete down drains and then denying culpability.”

He said that in the past year damp has appeared in many of the rooms “and despite the fact we have tried to contact British Gas to discuss this, we never seem to get the same person twice.”

“I spoke to Laa-Laa, the customer service manager, then to Dipsy”

I got in touch with British Gas and, after an investigation, the company told me: “We have repeatedly engaged with [DF’s daughter] to address her concerns, which have been ongoing since 2015. We have attempted to agree a fair resolution with her, even though at times we have struggled to recognise some of the facts and circumstances portrayed.

“An independent third party has also assessed the issues referred to but, regretfully, their recommendations and conclusions were also declined by her. We will continue to do all we can to help bring this matter to a close.”

That was back in May. The good news is that after my intervention the family was contacted by the firm. The bad news is that it was just the beginning of another sequence of merry dances, which have so far led to no positive conclusions.

DF takes up the story (I’ve changed the names of the British Gas workers to Teletubbies as their actions seem symptomatic of the company).

“We were contacted almost immediately after your intervention by [Tinky Winky]. He gave many assurances and said he’d call within a week to report what was happening. After we emailed and phoned him several times with no response I spoke to [Laa-Laa], the customer service manager, who promised to look into things.

“In June we had a telephone call from [Dipsy] saying he was now taking over and was definitely going to sort it out. Hearing nothing, in mid-July I wrote outlining our concerns. At the end of July, I had a call from [Po], saying she was now dealing with it!”

By August, DF was talking about taking legal action, which he’s still considering. I thought the company’s actions since I had been in touch had been dismal, so made a last appeal to British Gas, telling it: “I can’t see that I have any other option than to list the terrible customer service DF has experienced on top of the original problems as a warning for other customers, unless you can come up with a more positive solution.”

Sadly, British Gas didn’t respond. You have therefore been duly warned.

OUTCOME: A series of disasters worsened by British Gas’s dismal response


Section

Free Tag

Related stories

Twitter


Source Moneywise https://ift.tt/2DhM1lX