Thousands of courses for $10 728x90

الأربعاء، 31 أكتوبر 2018

Apple’s New Models Are Here. That Means You’ll Get Great Deals on Used Ones


It’s the second most wonderful time of the year: new iPad and MacBook season! (The first obviously being new iPhone season.)

Since Apple unveiled the iPhone XS and iPhone XR in September, we’ve been waiting with bated breath for the next generation of iPad Pro, MacBook Air and Mac Mini.

Well, that day has come, and it means one thing to Penny Hoarders: deals on gently used and refurbished Apple products.

That’s right. Those of us who don’t care about having the latest and greatest tech can catch some great deals on upgrading our slow-as-molasses MacBooks and first-generation iPad Bricks.

How to Find Deals on Used Apple Laptops, iPads and More

But before you buy the first MacBook you find in an unmarked van, there are some simple but important steps you need to follow if you want to avoid the duds and get yourself a deal.

1. Know Where to Look

New Apple products are never cheap, so most people will try to sell their old models on sites like Facebook Marketplace, Craigslist or OfferUp, because it’s where they can make the most money.

If you meet a seller one-on-one, always meet in a public place, like a police station or Starbucks. You should feel safe, and there should be other people around.

You can find deals at pawn shops or online trade-in shops like Gazelle. If you want to buy from Apple, you’ll start to notice newer models on its “certified refurbished” page. As of this writing, you can find refurbished MacBook Air models made as recently as June 2017.

2. Research the Product You Want

There’s no store associate to guide your Craigslist journey. You’ll need to do your own research on what you want, what you don’t need and what’s a fair price for it.

There are some great guides online that can help you decide between Apple’s lineup of MacBooks, iPads, Apple Watches, etc.

Ultimately, you’ll probably have to be a little flexible on your desired specs if you want the best deal. But who knows, you could get lucky.

3. Test It Out

This is the single most important part of buying used or refurbished Apple products. On sites like Facebook Marketplace, you should always try before you buy. If you’re buying online, always get a warranty and try all these features ASAP:

  • Turn the device on and off.
  • Test the camera.
  • Test the sound.
  • Test internet connectivity and browsing.
  • Test the ports with a USB drive, headphones, etc.
  • Check out the tightness of the hinge.

You’ll also want to make sure the model and specs listed are accurate by checking the serial number on the product.

4. Make a Call (or Two)

Give Apple a call to see if the product you’re buying is refurbished or has been reported stolen. You’ll find suggestions online to call Apple store customer service at 800-676-2775 to find out if your product is refurbished.

When I tried it with a laptop I purchased recently, the customer service representative couldn’t answer my question, but he was able to talk to someone who could confirm my laptop wasn’t refurbished. So be persistent, even if the first person you talk to doesn’t know what you want.

You may also want to call the local police station to make sure the serial number doesn’t match with an item that’s been reported stolen.

5. Make Sure the Product Is Restored and Removed From Account

Once you’ve decided you want to buy the product, it’s your responsibility to make sure the product is restored to factory settings.

If you’re purchasing an iPhone, iPad, Apple Watch or even an iPod Touch, you’ll also need to make sure the seller removes the product from their Apple account so that you’ll be able to add it to yours.

6. Don’t Bring Cash

And finally, never bring big wads of cash to a one-on-one sale. If you’re buying anything that costs more than a couple hundred dollars, get a free money order from Amscot.

Pro tip: If you want to negotiate the price, get multiple money orders so you’re not tied down to the asking price.

Jen Smith is a staff writer at The Penny Hoarder. She gives money-saving and debt-payoff tips on Instagram at @savingwithspunk.

The Penny Hoarder Promise: We provide accurate, reliable information. Here’s why you can trust us and how we make money.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder https://ift.tt/2yIGkcd

JOBS BOOM: US Companies Add a Robust 227,000 Jobs in October

U.S. companies added 227,000 jobs in October, according to a private survey, a healthy gain that suggests businesses can still find workers even with the unemployment rate striking 49-year lows.

Source CBNNews.com https://ift.tt/2ADT1Xh

New Job Not What You Expected? Here’s How to Decide When to Leave


Before punching out on the first day of my new job, all I wanted to do was go and not come back.

It was a marketing position with a company in an industry I knew nothing about. I felt like a fish out of water, ill-equipped to do what they needed. My gut told me to find something else immediately. But my brain told me to stick it out for six months to a year — otherwise, I’d look like a job-hopper on my resume. So which was right, my gut or my brain?

If your new position isn’t panning out the way you expected, what should you do? To find out, I asked some experts: How soon is too soon to start looking for a new job?

Evaluate the Situation Before You Put in Your Notice

When times get tough and there seems to be no hope in sight, it’s easy to consider packing up your desk and never returning to that cube farm. But before you hit the eject button, evaluate the pros and cons of your current job.

Timothy Wiedman is a retired associate professor of management and human resources at Doane University in Nebraska. Before getting into academia, he spent 13 years hiring, training and supervising employees at different companies.

He advises anyone thinking about departing a position they recently started to ask themselves these questions before beginning a new search.

Have I Been Here Long Enough to Understand the Company?

First, ask yourself if you’ve been at the company long enough to evaluate its long-term potential. “That’s pretty much a case-by-case basis,” Wiedman says. For newbies, it can take some time to learn the dynamics within your department and figure out whether or not you’re in a dead-end gig.

Have I Discussed My Career Path With My Boss?

If your boss hasn’t already asked you about your long-term professional goals, set up a time to talk. During that meeting, Wiedman suggests, share with your manager your aspirations and where you want to be professionally in five years. Your boss might have some insight that can help.

Do I Need Additional Training?

If you find yourself not understanding your work, maybe it’s time to consider improving on your weaknesses instead of jumping ship. Wiedman says that many industry groups offer classes, seminars and certifications to help improve your skills.

“A lot of times companies will even pay for that if they realize you're serious about working for them,” he says.

Do I Have Enough Experience in This Field?

Given your current education and skills, do you foresee the same problems reappearing at another company? You might have the right college degree to get your foot in the door but lack sufficient work experience. If you’ve yet to learn some things your boss expects you to know, you’re probably going to run into the same problem after you leave.

“If you job hop, you may find open doors to get in, but you may not be any better off,” Wiedman says.

The Sooner You Get Out, the Better

If after doing some soul-searching all signs still tell you to go, then do it. Wiedman doesn’t recommend staying at the job any longer than needed. Even if you think it’ll look good on a resume to hit an arbitrary time, such as six months or a year, bad stuff can happen.

“What if you become bitter or, if you have friction with your boss in the first place, end up getting fired?” Wiedman says. “Well, that doesn't look good on a resume.”

But how will your resume be viewed when it has a job on it that’s less than a year old? Fear not, because your resume shouldn’t be discounted as long as it’s an isolated occurrence, says Robin Schwartz.

Schwartz is a managing partner of MFG Jobs, a manufacturing jobs and career advice site. One of her primary roles is handling internal recruiting for her clients. She understands things happen and a position may not turn out the way it was promised to a candidate. So as long as your resume shows positions with multiple years of tenure or an upward career trajectory, you’ll be fine.

One short-lived position on an overall strong resume is not going to hold you back, she says.

Consider Leaving Short-Term Jobs Off Your Resume

When deciding whether or not to include a short-term job on your resume, ask if the position helps tell your work story. Elissa Unton, the CEO of the career guidance company ArcVida, advises young professionals to leave off positions that lasted less than six months.

The only time you should include short-term employment is if you gained something, like learning a software program or foreign language — basically, anything that may add value to your prospective employer. If you’re departing a short-term job because it wasn’t a good fit, leave it off.

If you do include the short-term job, she says, be prepared for the hiring manager to ask about it.

“There's a narrative behind that question of ‘Why did you take this job and leave so quickly?’ that is ‘Are you going to take my job and then leave right away?’” she says. “So leaving it off is better than including it.”

If you do stay at your position longer than six months, keep it on your resume, she says. A gap longer than six months will lead to questions of why you were out of work instead of discussing the skills you can bring to your new employer.

If they ask about your resume gap, Unton says to talk “clearly and honestly but not at length” about why the job wasn’t a great fit and what you learned from it. Spin it in a positive way without throwing your former company, co-workers or boss under the bus.

Before You Eject, Find a New Job

When you’ve had enough of a bad situation, it can be tempting to tell your boss “I quit!” But don’t do that. Do your best to have something lined up prior to leaving.

It’s a lot harder to network and job hunt when you’re unemployed. Unton warns that finding the right position sometimes takes longer than you think. Some of her more diligent job hunters may find a new gig in five weeks, but for other people it can take three months or longer.

“If you have a paycheck,” she says, “you can take the time to be thoughtful, considerate and make sure you do find the right fit.”

Matt Reinstetle is a staff writer at The Penny Hoarder. He covers career advice and is always looking for new ways to help people make sense of the workplace.

The Penny Hoarder Promise: We provide accurate, reliable information. Here’s why you can trust us and how we make money.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder https://ift.tt/2OYMZZO

Fill ‘Er Up: How This Family Business Delivers Water to Homes in Alaska

‘The Price Is Right’ Is Searching for a New Model — Apply Online Now


If you aspire to showcasing the features of laundry detergent before handing players their Plinko chips, have I got the dream job for you.

That’s right, game show fans, “The Price Is Right” is holding an online search for a new model.

If you haven’t been sick in the past few years — because that’s the only time you watch, right? — the show may look a little different. Drew Carey is now the host, and the daytime stalwart has incorporated a mix of male and female models.

The online casting call states the show is looking for a model who is charismatic, upbeat and energetic — which shouldn’t come as a surprise considering the audience behaves like pure oxygen is being pumped into the studio.

The online application asks for you to include photos and videos, as well as your acting experience — the models are classified as SAG-AFTRA union positions.

Pay is listed as SAG-AFTRA minimum, which according to 2018 SAG rates is $2,460 per week — not too shabby for holding that can of Dinty Moore Stew.

You must be available for callback auditions and filming in Los Angeles through April 2019.

But perhaps you can drive there in a BRAND… NEW… CAR! Sorry, got carried away there — you actually have to cover your own transportation.

Tiffany Wendeln Connors is a staff writer at The Penny Hoarder. Whenever she’s home sick, she loves to play a pricing game.

The Penny Hoarder Promise: We provide accurate, reliable information. Here’s why you can trust us and how we make money.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.


source The Penny Hoarder https://ift.tt/2qlrBPZ

Savings update: Average rates are rising across the board for first time in seven years.

Savings rates across the board continue to rise, while Nottiingham Building Society has launched a market-beating easy-access account.

The top easy-access deal is the Nottingham Building Society eSaver Instant Issue 9 with a 1.55% rate.

Other good deals include the Goldman Sachs Marcus account at 1.5% and Shawbrook’s Easy Access account paying 1.4%, while Paragon Bank Limited Edition Easy Access account and French-owned RCI Bank’s Freedom account pay 1.37%.

The Marcus account comes with a bonus of 0.15 percentage points for a year, but you can renew for another 12 months. Virgin Money pays 1.42% to new savers on its Double Take E-Saver, but it limits you to two withdrawals a year.

On fixed-rate bonds, OakNorth pays 1.8% for six months, while the top one-year rate is 2.03% from Shawbrook Bank followed by OakNorth Bank at 2.02%.

Charter Savings Bank pays the top 18-month rate at 2.11%, while the best two-year rate is 2.3% from OakNorth.

On easy-access tax-free cash Isas, Leeds Building Society’s Limited Issue Online Access Isa pays 1.38%, but the account runs only until December next year.

Virgin Money Double Take E-Isa also pays 1.38%, although you are restricted to two withdrawals a year. Paragon Bank’s Limited Edition Cash Isa pays 1.37% with no withdrawal restrictions or end date.

On one-year fixed-rate cash Isas, Paragon Bank offers 1.55%, and Charter Savings Bank and Bank of Cyprus UK both pay 1.54%.

The top two-year deals are 1.82% from Bank of Cyprus UK, or 1.81% from Charter Savings Bank.

Section

Free Tag

Related stories

Twitter


Source Moneywise https://www.moneywise.co.uk/saving-banking/savings-cash-isas/savings-update-average-rates-are-rising-across-the-board-first-time

How to Repurpose Your Content Across Multiple Marketing Platforms

Quality content takes time and effort to produce. I am sure you know this if you regularly publish content on all your distribution channels.

But many brands lose quality in pursuit of higher quantities of content.

While I agree that quantity is important as well, your quality can’t suffer as a result of this strategy. You need to learn how to avoid stale content.

I work with many businesses that run into this problem. They want to publish at least one piece of content a day on all their distribution channels.

Among their websites, blogs, and social media pages, it’s a lot of content. Before you know it, that’s upward of 30 posts per week across these platforms.

However, that doesn’t mean you need to come up with 30 unique pieces of content. This approach will take too long and ultimately hurt your quality.

That’s why you need to learn how to effectively repurpose your content across multiple marketing platforms.

First, you need to learn the top ways to come up with new content ideas.

Once you have an idea, you can turn it into multiple posts on each channel. In fact, sometimes you won’t even need to come up with a new idea. You can use old content to your advantage here as well.

Worker smarter, not harder.

As we continue through this guide, I’ll explain how you can repurpose your content across all your distribution channels and give you some ideas to try.

Identify your most popular content

Before you spend time producing new content, I recommend re-using older publications and posts.

After all, you already spent time working on these. Why let them go to waste?

But don’t just use any content. Start with your most popular pieces.

Identify your content with the highest engagement rates. Look for:

  • Facebook likes
  • retweets
  • posts with the most page views
  • email newsletters with the highest click-through rates

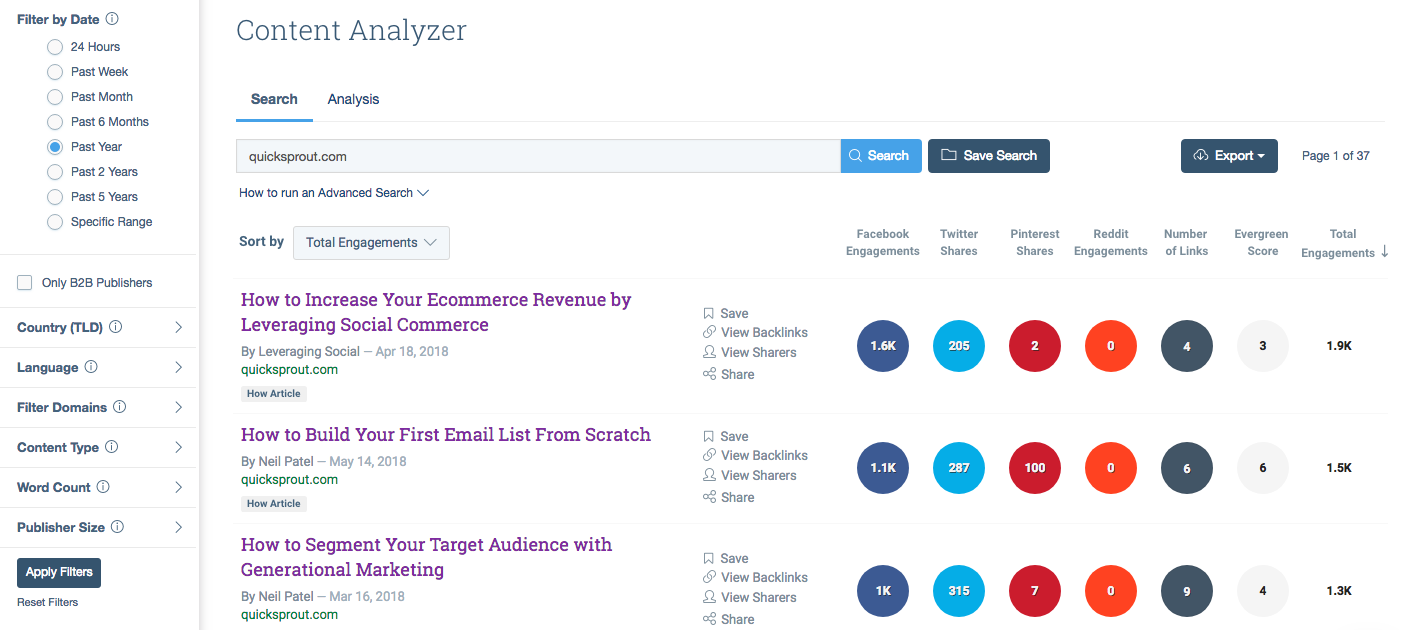
If you’re struggling to find what you need, try using Buzzsumo to see which content had the highest engagement on social media. Here’s what the content analyzer tool found when I put quicksprout.com into it:
buzzsumo

It shows me which posts from the past year were the most popular. But you can filter the time based on your needs.

In addition to Buzzsumo, you can use Google Analytics to see which pages on your website are the most popular.

After you analyze your content with these tools, make a list of your top performing publications and posts.

This will be your starting point. You’ll use this list to repurpose content.

For example, if you had a high performing blog post, you can turn it into a YouTube video. You could use a Facebook post with the highest number of likes on your Instagram story.

The ideas are seemingly endless. As we continue, I’ll give you some more examples of how you can proceed.

Build custom infographics

Going through your old posts, you want to find ways to repurpose them for even more engagement.

Here’s what I mean.

If you take an email newsletter that had the highest number of opens, click-throughs, and conversions and turn it into a blog post, the idea is that the blog post will be high-performing as well.

Otherwise, what’s the point? You don’t want to publish content just for the sake of publishing.

Your content needs to be actionable and drive engagement.

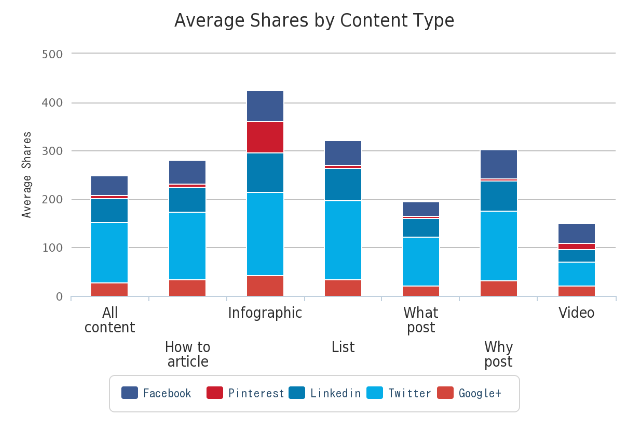
That’s why infographics are ideal for this strategy. Infographics are the most shared types of content across social platforms:
infographics

People are visual learners.

The graph above is a perfect example of that. Sure, I can tell you infographics get shared the most. But when I show you, it really sinks in and makes it easier for you to process.

Scan through all your top performing posts you identified earlier. Look for facts, statistics, or anything else that could be turned into a visual representation of the concept.

If you have never built an infographic before, don’t be intimidated. It’s not that difficult.

Refer to my post on how to enhance your content by building infographics for a list of tools that will make this process easy for you.

Once you create these infographics, you’ll have many options.

The same infographic can be used in different ways. You can:

  • add it to the original blog post, which can be republished
  • share it on social media
  • add it to your email newsletter
  • place it on your website
  • use it in a video slideshow

The list goes on and on.

Leverage your social media platforms

Your social media profiles have lots of benefits. They expose your brand to a wider audience and help you engage with your followers and customers alike.

Posting content on social media also helps you drive traffic to your website.

Anything you create gives you an excuse to post on social media.

If you haven’t been doing this, you need to do so moving forward. All your videos, infographics, and pictures are a must.

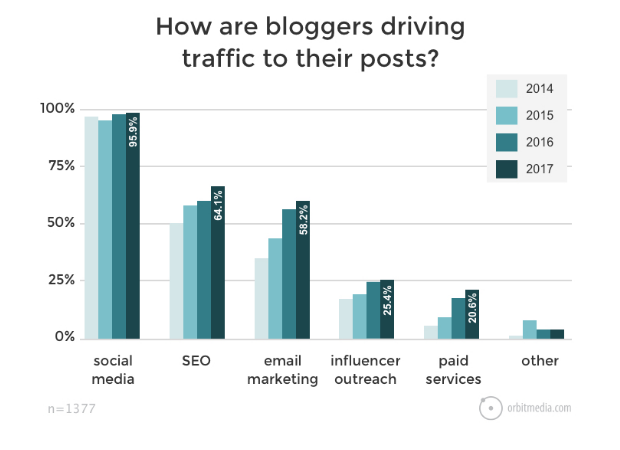
Social media is the number one way for publishers to drive traffic to their blog posts:
blogs social media

If you look at my Facebook page and my Twitter profile, you’ll see I use this strategy for all my blog posts.

It’s easy. Plus, it gives you an excuse to post something every day.

I’m shocked whenever I see businesses not using this tactic. They publish three or four blogs per week but struggle to come up with social media posts.

When you implement this strategy, plan your posts accordingly.

For example, there’s no reason to share the same blog post on all your social platforms simultaneously.

Spread out those promotions throughout the week. This will maximize your exposure and increase the chances of driving more traffic to your site.

Create more evergreen content

You can’t repurpose old content forever. At some point, you’ll need to create new pieces.

But you can make repurposing easier by creating evergreen content.

Are you familiar with this concept? Allow me to explain.

Simply put, evergreen content stays relevant for longer periods of time than regular content. Ideally, the majority of your content will be evergreen.

But it’s not realistic or likely that this will be the case for everything you create.

For example, last year, I wrote a post on top marketing trends to look for in 2018. Once 2019 comes, this post will lose its freshness.

When you write your evergreen content, you want to be as broad as possible. This post was fresh for an entire year. That wouldn’t be the case if it was the top trends to look for in January 2018. Do you see the difference?

Extremely specific content will only be relevant for a short period of time. Therefore, it’s more difficult for you to repurpose it.

Here’s another example. If you write a post about the Apple’s latest iOS update, it’s fresh only until a new version of the software is released. That’s not evergreen.

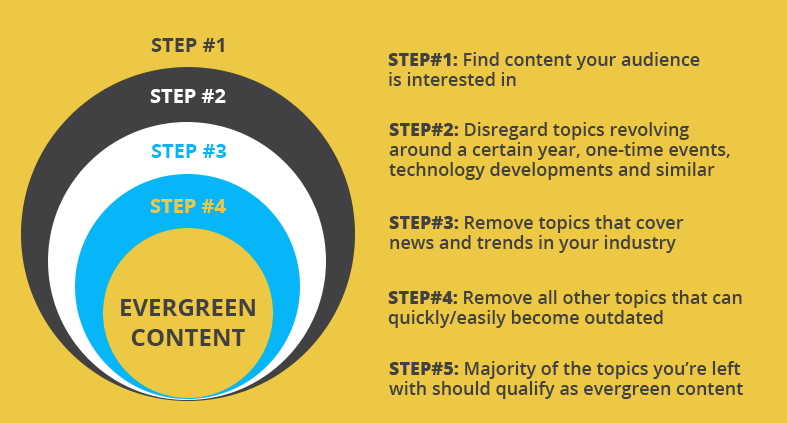
Here are some tips to help you find an evergreen topic:
evergreen

FAQ sheets are great for evergreen content.

Produce how-to guides or videos on topics that won’t be changing for years.

Clarify industry terms and concepts.

Again, I’m not saying you should be producing only evergreen content. That’s not realistic.

But if you publish an evergreen topic tomorrow, you could potentially repurpose it on another platform next year. That’s the idea.

Find the most interesting statistics you published

If you’re like me, you use statistics in your content all the time. Stats are a great way to back up any claims you’re making.

I recommend doing this because it proves your legitimacy and lets your audience know you’re not making things up.

But if you’re not repurposing content, those statistics get buried in your posts after they are published, never to be seen again.

Go back, and find the most interesting ones. In the future, keep a list of all statistics when you find them.

Then you can use them on other platforms.

Earlier, I talked about creating infographics. But that’s not the only way you can repurpose data.

Tweet a statistic. Use them in your Instagram captions. Include a stat in your email subject line. Post the most relevant ones on your website.

Get creative with this strategy.

Start a podcast

Podcasts are another great way to repurpose your content.

That’s because you have many different resources to work with there. All your blog posts and YouTube videos are viable options for a podcast.

You can summarize this content, nearly word for word, with your podcasts.

Since podcasts are growing in popularity, it’s a great way to reach an audience that doesn’t want to read blog posts or watch videos:
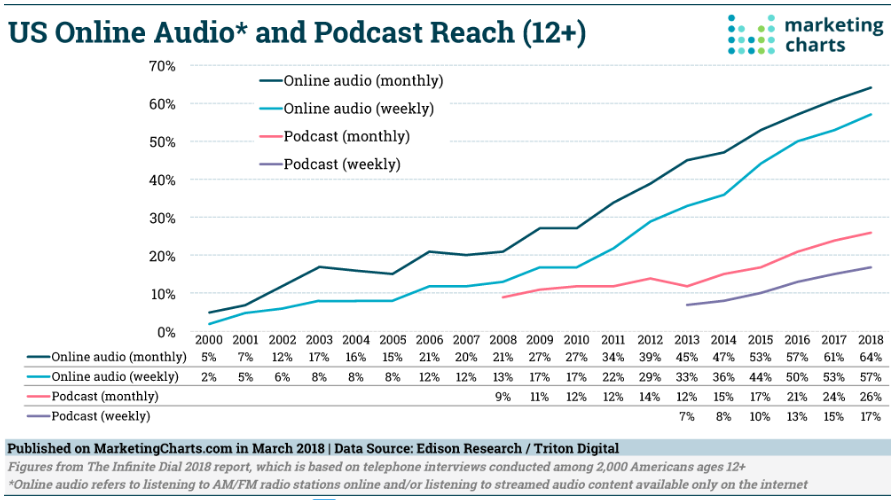
podcasts

Consider bringing a guest on your podcast to make things more interesting.

Have some fun with it. I try to keep this in mind with all my podcasts.

Fine-tune your writing skills

If you’ve got lots of audio, video, and visual content, you need to learn how to turn that into written content.

Start blogging more often. Write every day if you can.

It’s like anything else. The more you do something, the better you’ll get at it.

I wasn’t born a great blogger. It’s a learned skill.

Are some people better writers than others? Absolutely.

If you can’t find the time to write or can’t figure out how to write quality content, find someone on your team who can handle these responsibilities.

Once you’re able to write better, you can write a blog post about one of your YouTube videos, for example.

Keep things simple. Make your content easy for people to read and understand.

These are just some examples of things you can turn into written content:

  • webinars
  • podcasts
  • speeches from industry events
  • interviews

Encourage user-generated content

Your content isn’t the only type you can repurpose.

If you can find creative ways to encourage user-generated content, it will be easy for you to use this to your advantage as well.

Then all you have to do is sort through that user content and find the best pieces to repurpose for your needs.

Here’s an example of how GoPro encourages UGC on its website:
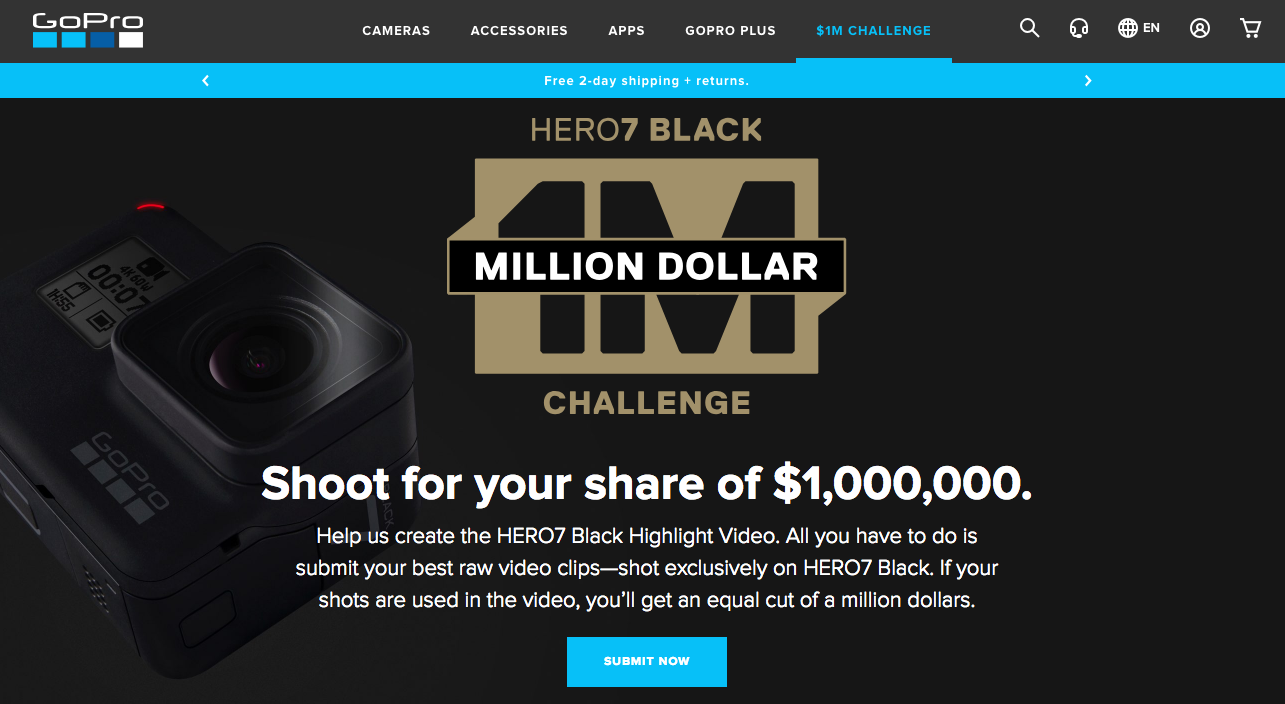
gopro

As you can see, it offers an incentive for people to submit their own content.

GoPro is giving away a million dollars, split between anyone who submits content that the company uses in a promotional video.

This saves the team a ton of time.

Instead of going out to different locations all over the world to shoot videos on their latest camera model, they put their customers to work instead.

Plus, they’ll be able to get way more footage this way as opposed to trying to do this on their own.

Once the videos are submitted, GoPro can repurpose them in a bunch of different ways. They can be used for advertisements, social media posts, YouTube videos, website content, and they can even be embedded in emails.

Come up with a similar strategy, and encourage your customers to submit pictures and videos.

I recommend using social media as a distribution platform for your UGC campaigns.

You can also find UGC without asking for it.

Sift through your comments.

Look at the comments on your social media pages and blog posts to see which ones can be repurposed.

If you notice similar comments or questions, use them to create an FAQ page.

Find your strongest introductions

Sometimes, all you need to do is repurpose a portion of your previously published content.

If you want to repurpose a short form of written content, I recommend using your post introductions.

If you need help with this, learn how to write blog post introductions that make the rest of your post irresistible.

Once you identified these top introductions, it’s easy to repurpose them.

Use an introduction from a blog post in an email newsletter. Use the same text in a YouTube video description.

Preview your introductions on social media. Here’s an example of how Conversion XL uses this strategy:
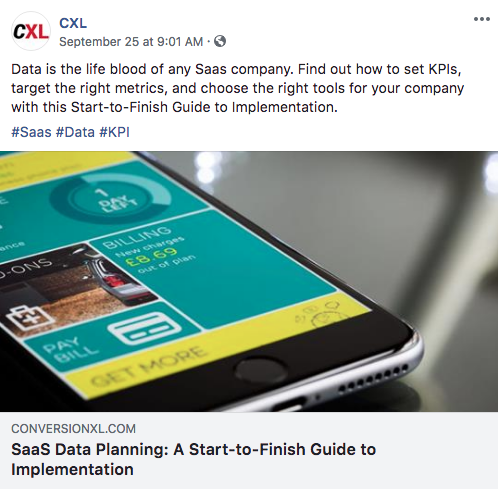
conversion XL

This also connects to one of my previous topics about leveraging your social media platforms.

Rather than posting a link with a CTA such as “check out my latest blog post,” consider using this strategy instead.

The text associated with the link would be the opening lines of the blog post introduction.

Conclusion

You don’t need to create new content every time you want to publish something new.

There are ways for you to use your existing content to your advantage. Just repurpose the work you’ve already done across all your distribution channels.

Start by identifying your best content. You’ll want to use that to increase your engagement metrics.

Build infographics. Share statistics. Post everything on social media.

Moving forward, create as much evergreen content as possible. This will make it easier for you to repurpose your content in the future.

Turn blog posts into podcasts. Use videos and other audio files to create posts.

Encourage user-generated content so you can repurpose it.

As you implement these strategies, you’ll realize you’re currently sitting on enough content to last you for months to come, as long as you can repurpose it effectively.

Use this guide as a reference to steer you in the right direction.

What type of content is your business repurposing on your distribution channels?


Source Quick Sprout https://ift.tt/2CQmE90

You Don’t Need to Buy Something to Change Yourself

At various points in my life, I’ve been really into the idea of getting myself into shape. I bought gym memberships. I bought exercise equipment. I bought workout videos. I bought exercise clothes.

In the end, the single most successful thing I’ve ever done in terms of personal fitness is to go on walks, to stretch, and to do some bodyweight exercises, like holding my body in a plank position or doing some squats.

At various points in my life, I’ve been really into studying the bible as a way to figure out my spiritual yearnings. I bought bible translations. I bought study guides. I bought notebooks. I bought pens. I bought highlighters.

In the end, the single most successful thing I’ve ever done in terms of bible study is to simply sit down and read a few chapters each day and share my thoughts on them in a private social media group.

All throughout my life, I’ve been a voracious reader. I bought countless books. I bought countless magazines. I stuffed my shelves with them.

In the end, the single most successful thing I’ve ever done in terms of actually enjoying reading is to check out a pile from the library, stick them on my bedside table, and start reading them.

At various points in my life, I tried to improve my social skills. I bought books and took classes and bought clothing and hygiene products and all kinds of things that I believed would boost my social acumen.

In the end, the single most successful thing I’ve ever done in terms of improving my social skills is to simply ask questions of people and listen with sincerity to their answers. I got that from a book I originally bought for fifty cents at a used book shop. Buying a bunch of stuff didn’t help one little bit.

There’s a thread here. You don’t need to buy something to change yourself. If there’s something you want to change about yourself, the purchase of a product won’t initiate that change. What will initiate that change is your action. All that a product can possibly do is make an action that you’re already doing more effective. If you’re not already doing that action, then that purchase is a waste of money.

If you want to lose weight, simply watch your calories. Count them with a free calorie counting app on your phone. There’s no need to buy diet programs or diet pills or anything like that. Just watch what you eat with care.

If you want to be more fit, simply start moving around more and leveraging your body weight. Go on walks. Do some pushups. Do some planks. You don’t need gym memberships or exercise gear or videos. You don’t need anything else until long walks and planks and pushups and situps become trivially easy.

If you want to learn about something, you don’t need to go buy class materials or books or anything like that. Just go to the library, check out a few books, sit them on your bedside table, and read. If you want an overview of a topic to start with, look it up on Wikipedia and read the entry.

If you want to do something, do it. If you need equipment to do it on any level, go get the absolute minimum equipment you need (preferably by borrowing it, like a library book, or by buying used or very low end, if you absolutely have to) and then just do it.

You don’t need items to do something.

You don’t need new shoes to take up walking. Just go walk around your block.

You don’t need new exercise clothes to start doing yoga. Just start doing downward dog in your living room.

You don’t need new exercise equipment to get fit. Just start doing planks and pushups and squats in your living room.

You don’t need to buy a bunch of new books to read. Go check out a book from the library and curl up in a chair.

You don’t need a bunch of new kitchen equipment to get better at cooking. Get a cheap kitchen knife and a cheap spatula from the local department store or dollar store and used pot and a used skillet and a used baking pan from Goodwill and that’s all you need – you probably already have that stuff. Just go in the kitchen and cook something. Then, do it again the next day, and the day after that.

You don’t need a bunch of discs to take up disc golf. Take one frisbee and try it out. Work on throwing that one disc until you can throw it accurately at a long distance.

You don’t need a fancy pen and a fancy notebook to take up journaling. Grab a cheap pen you probably already have and a $0.25 composition notebook from the dollar store and start writing.

It goes on and on and on like this. You just don’t need a bunch of stuff to take up a hobby or learn a new skill or improve yourself. You don’t need to spend that money. You don’t need to have to find a place to store those new items.

You just need to get out there and do it.

Better yet, do it today.

Thinking about taking up walking as a healthy hobby? Don’t wait until you can afford walking shoes or some such nonsense. Go outside today and walk around the block. If that feels good, do it again. Save the shoes for when you’re walking a lot and feel like you might need them.

Thinking about getting in shape? Don’t put it off until you can afford a gym membership. Instead, do jumping jacks until you’re panting, take a two minute break, then do a plank until you’re panting and have to drop to your knees, then take another break, then do squats until your legs tell you to stop. Do that every day until it’s easy, then you’ll have a good sense of what else you might want to work on.

Thinking about reading more? Stop at the library on the way home, grab a couple of books, and then start reading one. Turn off your phone while you’re reading and sit in a room without a television or a computer and try to lose yourself in the book.

Thinking about taking up journaling? Find a cheap pen and any old notebook and just dump out whatever’s on your mind.

Do. Don’t buy. Do.

You don’t need to buy something to change yourself. Buy something because you actually need it due to the person that you are, not the person you think you might be someday. Instead, do something. Doing something doesn’t cost much of anything and it actually achieves results without draining your wallet.

“But there’s this thing I really want to do that absolutely REQUIRES spending!” Does it really? Are you sure there’s not a way to borrow items or use trial memberships until you are absolutely dead sure that this is going to be a lasting part of your life? Or are you just putting another barrier in front of yourself to keep yourself from doing it?

Give yourself a thirty day challenge that’s centered around doing the thing you want to do. The calendar page is turning, so make it your goal for this coming month. Each day, you’re going to actually do something regarding the thing you’ve been thinking about. You’re not going to buy stuff for it. You’re not going to put it off because you’re going to buy stuff for it “someday.” You’re going to do it.

While you might not find that the thing you’re doing is right for you, you will find something that’s perhaps even more important: that you don’t need to buy stuff to do stuff.

Good luck!

The post You Don’t Need to Buy Something to Change Yourself appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2ACqxgu

Do You Need Pet Insurance? Here’s How to Decide

Most people who love their pets go the extra mile to make sure they receive the highest quality of care possible. This includes taking the time to get them to the veterinarian’s office for wellness checkups and shots, making sure they have nutritious food and fresh water, and providing them with a cozy place to sleep. None of these basics are cheap, but most animal-lovers believe their furry friend is well worth the cost.

Unfortunately, the price tag for keeping a pet can surge dramatically if your pet becomes ill or is diagnosed with a chronic condition. And, many times, these costs can creep up with little or no warning, meaning you have no time to prepare your finances for the expense. The American Veterinary Medical Foundation also notes that, as veterinary medicine becomes more technologically advanced, costs can and will increase even more.

One way animal-lovers can defray these costs is by purchasing a pet insurance policy similar to health insurance you buy for humans. With pet insurance, you typically pay a monthly premium for a certain level of coverage along with a deductible if you need to file a claim. While pet insurance isn’t cheap, it can often save you from covering exorbitant medical bills when your pet suddenly becomes ill or injured.

And, like it or not, none of us knows if our pet will one day get hit by a car, get sick with cancer, or swallow a sock.

Do You Need Pet Insurance?

While it seems at least some people don’t believe pet insurance could possibly provide a good value, we wanted to ask people who have actually purchased pet insurance and filed claims. Sylvia Inks of Raleigh, N.C., is one such consumer, having filed $3,300 in claims through her ASPCA pet insurance policy for her dog since 2011.

Inks says her ASPCA Level 2 coverage covers accidents and illnesses with a $100 annual deductible, $3,000 limit per incident, and 20% co-insurance requirement. However, her policy does not cover congenital and hereditary care, continuing care, or wellness care.

When Inks originally bought her policy in 2008, she says she had heard and read about people who were unhappy with their plans. As a result, she asked her veterinarian which insurance companies they work with and have faith in. That’s how she ended up buying a policy through the ASPCA.

While Inks only has $3,000 in coverage per incident, which is fairly limiting, she says this coverage has been perfect for her needs and a “great experience.” Almost every time she has filed a claim, she’s been reimbursed in around 30 days. Plus, the process is infinitely easier and faster now than when she first bought her policy in 2008. Where you used to have to mail the claim form and vet receipt to the ASPCA, you can now file the entire claim online.

“I just need to provide information including where my pet received treatment, when my pet was treated, how much I am claiming, what type of claim, describe why I took my pet to the veterinarian, and upload the invoice file and medical records,” she says.

Unfortunately, not every consumer has a positive experience with their pet insurance like Inks — and even with the same insurer. Some people who use ASPCA pet insurance and other providers complain online that service is poor or that claims were paid extremely slowly. Across pretty much every pet insurance provider, there are consumers who rage on about “fine print” they didn’t read in their policies, and about how their coverage didn’t kick in to help with their pet’s medical bills.

For that reason and others, it pays to be diligent about the details when you shop for a pet insurance policy.

How to Shop for Pet Insurance

According to Sa El, co-founder of Simply Insurance, an online company that provides pet insurance as well as other insurance products, there are a wide range of details to explore as you compare pet insurance policies to find the right option for your needs. Cost should play a role in the policy you buy, but you also need to conduct due diligence so you know what your policy actually covers. Here are the factors to consider as you shop around:

  • Pre-existing conditions: El says the most important detail to note is whether your pet has any pre-existing conditions. If your pet is older and has had multiple surgeries or has a chronic medical condition, then pet insurance is probably not going to help you, since pet insurance companies do not cover pre-existing medical conditions.
  • Age: If your pet is older and in good health, however, you can buy pet insurance — just at a higher cost, since your premiums will be adjusted to make up for increased risk associated with your pet’s age.
  • Coverage limits: “Some companies have unlimited benefits while others limit you to $5,000 or $10,000 a year in covered benefits,” says El. While you will likely pay more for a policy with an unlimited benefit, these beefier policies can be a life-saver if your pet winds up needing especially expensive veterinarian care.
  • Coverage exclusions: While pet insurance companies don’t cover pre-existing conditions, most also have a list of excluded conditions they don’t cover under any circumstances. Some may cover wellness care while others do not, and it’s up to you to know what your policy includes and excludes. According to the AMVA, the insurance provider should “clearly spell out to you the details, including the limitations and exclusions, of coverage for routine and/or wellness care as well as emergency treatments and conditions that require extensive care.”
  • Reimbursement level: While some pet insurance policies reimburse you for 100% of your pet’s medical bills after your deductible up to your policy’s limit, others offer an 80/20 or 70/30 reimbursement structure. Make sure you know this ahead of time so you know how much you’re liable for.
  • Claims process: El says you want to be sure you find a company that will either pay the vet bill directly or one that has a very fast claims process for sending out your reimbursement when you have to file a claim. If you don’t, you could be stuck in a situation where you pay your vet bills upfront and wait for what seems like forever to be reimbursed.
  • Monthly premiums: Once you’ve compared the above criteria, you’ll also want to make sure to compare monthly premiums to find the best deal. With this in mind, it makes sense to compare policies and the cost of coverage with at least three or four different providers.

The Bottom Line

If you believe your pet could need expensive medical care one day and worry you won’t have the funds to cover the bills, pet insurance could provide you with some peace of mind. Before you purchase a policy, however, make sure you understand what is and isn’t covered, any policy limits you have, reimbursement levels, and any other fees you’ll need to pay if you use your plan. That way, you can save up some money to cover these costs if the worst-case scenario were to happen.

And if you’re unable to get coverage for your pet due to pre-existing conditions or you can’t find a policy you like, you can also self-insure against potential problems with a special savings account for your pet. Like any other savings goal,  you will open a high-interest savings account, set up automatic direct deposits for every month or every payday, and start saving. Then you can pull money from that account to pay any big, unexpected veterinarian bills — but hopefully, you’ll never need it.

Related Articles:

The post Do You Need Pet Insurance? Here’s How to Decide appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2ACexvt

Chancellor sneaks in hidden National Insurance hike with personal allowance increases

Image

Hidden National Insurance rise will undermine gains from personal allowance rise to £50,000 for higher earners

Higher earners with incomes approaching £50,000 have been dealt a backhanded blow by chancellor Philip Hammond in the Budget small print.

In Monday’s Budget, he announced that the basic (20%) rate tax threshold will rise from £11,850 to £12,500 and the starting level for higher rate (40%) tax will increase from £46,350 to £50,000 in April 2018.

That should mean that people taking home between £46,350 and £50,000 will pay half as much income tax on that chunk of their earnings. For a £50,000 earner, that amounts to a tax cut worth £60.83 a month.

However, Royal London trawled through the Budget small print and has highlighted the fact that the National Insurance contribution (NIC) limits have also moved in line with the change in the income tax threshold. As a consequence, higher earners are losing half their newfound tax gains on that marginal chunk of income.

At present, people earning more than £46,350 pay 12% NICs on earnings up to that level (the so-called upper earnings limit) but only 2% NICs on earnings above it. But from April next year they will pay the full 12% rate of NICs on everything up to £50,000, as the upper earnings limit is hiked up. The 2% rate will kick in on earnings above £50,000.

As a consequence, while tax payable on that slice will be reduced by 20%, NICs will go up by 10%, so the net gain is only 10%.

Alignment of the tax and NIC thresholds makes sense in terms of streamlining, but there was no mention of the NIC implications in the Budget speech.

Steve Webb, director of policy at Royal London, comments: “The chancellor is well within his rights to increase the bands over which the full rate of NI contributions is payable.

“But as this wipes out half of the gain for higher earners of raising the starting point for higher rate income tax, he should have come clean and mentioned this in the Budget speech rather than leave it in the Budget small print.”

Steven Cameron, pensions director at Aegon, points out that it’s a worse situation for Scottish residents. “The Scottish government sets its own threshold for higher rate tax, which is currently £43,000. We will need to wait until the Scottish Budget on 12 December to see if they will unfreeze this. But the changes to National Insurance apply across the UK. This means someone in Scotland earning £50,000 will pay an extra £30.41 a month in NICs without saving anything in income tax.”

This article first appeared on our sister website Money Observer.

Section

Work & family Pay less tax

Free Tag

national insurance Autumn Budget 2018 tax

Related stories


Source Moneywise https://ift.tt/2ADigsp

Investment myths debunked

Myths or facts

Whether you are a novice or seasoned investor, you will come across many clichés about how to succeed.

From diversification to taking on more risk for higher returns, there is a whole host of investment beliefs that it’s good to question.

If you are wary of the myths below, carry out careful research and use your common sense; investing can open up a world of financial opportunities.

1. Diversification is key to investment success

The dangers of being insufficiently diversified when investing has been written about at great length. Put simply, have all your eggs in one basket and you stand a greater chance of seeing big losses if something goes wrong. But is this belief watertight?

While spreading your risk generally makes a lot of sense, there are caveats.

Firstly, by buying too many different things, you risk having no oversight to ensure that your portfolio does actually have a good balance.

Secondly, by holding too much, you are likely to do insufficient research and could fail to keep abreast of developments in the businesses or funds you have bought.

Back in 1958, legendary US investor Philip Fisher wrote in his book, Common Stocks and Uncommon Profits: “Investors have been so oversold on diversification that fear of having too many eggs in one basket has caused them to put far too little into companies they thoroughly know and far too much in others about which they know nothing at all.”

There is so much received wisdom around investing, but do we need to take it with a pinch of salt? We look at some commonly held investment ideas and ask whether they stand up to scrutiny

2. No one ever went broke taking a profit

There is a patent logic to this statement. Selling investments when they are up guarantees that you make a profit – using this strategy can’t leave you with nothing or worse.

But following this logic too far could lead to bad investment decisions where you sell your best-performing stocks and keep your losers, hoping they will eventually come back up.

Max Ward, manager of the Independent Investment Trust, explains: “As an investor, the hardest lesson to learn is that you will be wrong an awful lot of the time (I reckon the best investors are wrong 40% of the time), so you need to get good at recognising more quickly than others when you are wrong and act accordingly.”

3. The market knows best

When judging the value of a company, many people simply look at the market consensus, as if it is a wise entity whose view should be respected.

But what if other investors are wrong ? Perhaps they are more optimistic or pessimistic than they need to be or their view is affected by other things that are going on.

Legendary investor Warren Buffett questioned this view in his annual letter to Berkshire Hathaway’s shareholders in 1987: “Mr Market is there to serve you, not to guide you. It is his pocketbook, not his wisdom, that you will find useful.

“If he shows up some day in a particularly foolish mood, you are free to either ignore him or to take advantage of him, but it will be disastrous if you fall under his influence. Indeed, if you aren’t certain that you understand and can value your business far better than Mr Market, you don’t belong in the game.”

4. You can anticipate short-term market movements

Many investors have tried to make ‘buy’ and ‘sell’ decisions on financial assets, usually stocks, by attempting to predict future price movements.

This is something many people do almost instinctively when their view of economic matters determines where and how they invest. For example, they might sell their stocks in a house builder, based on the view that there is a housing bubble and it is about to burst, instead of looking at the specific company fundamentals – whether it is well run, generates cash and has a strong balance sheet. Alternatively, they might move out of stocks into cash in the belief a stock market crash is coming.

John Bogle, founder of The Vanguard Group, says: “Timing the market is impossible. Even if you sold stocks just before a decline (a rare occurrence!), where on earth would you ever get the insight that tells you the right time to get back in? One correct decision is tough enough. Two correct decisions are nigh on impossible.”

What has proved a more practicable and very much more successful strategy than market timing is buying good shares or funds cheaply and then holding them for the long term.

As Philip Fisher notes: “Short-term price movements are so inherently tricky to predict that I do not believe it is possible to play the in-and-out game and still make the enormous profits that have accrued again and again to the long-term holder of the right stocks.”

Buying ‘boring’ quality shares or funds can at times prove more lucrative

5. For higher returns, you need to take on more risk

Is it always true that taking on more risk leads to higher returns? Over the long term, buying ‘boring’ quality shares or funds can sometimes prove more lucrative.

Terry Smith, fund manager of the top-performing Fundsmith fund, says: “Rather than seeking superior portfolio performance by buying high-risk stocks, investors should seek out ‘boring’ quality companies that have predictable returns and superior fundamental financial performance, and take advantage of their persistent under-valuation relative to those returns to buy and hold them.”

6. Brokers and their price targets must be taken seriously

Investment notes written by analysts can be useful. Their arguments and analysis can help form your own ideas about the prospects for a quoted company.

But their predictions are not always right.

You should treat projected price targets with caution, especially if they are predicated upon complex maths and estimated earnings far into the future.

In 1958, Benjamin Graham, the father of value investing wrote in his classic book, The Intelligent Investor: “The combination of precise formulas with highly precise assumptions can be used to establish or rather to justify practically any value one wished, however high.”

Some analysts may not be impartial, which can affect their views. This is worth considering when deciding to go with their recommendations.

7. Markets are efficient

Many private investors assume that the markets are efficient, and the price of a stock accurately reflects its value or intrinsic worth. But there can be factors at play that distort the price of different shares.

Fund Manager Neil Woodford explains: “The best financial lesson I learnt was to question the notion that markets are efficient. Economics is the study of human behaviour as much as anything else, and I’m not sure this can be explained in the same way that you can describe how ice crystals are formed.

“I believe the best way to add value is to focus on fundamentals (by which I mean the real performance of a business and the real activity in the economy) and focus on value, not price. In the short term, the market can be profoundly inefficient and obsessed with things that have very little relevance to the long-term success of a company or an economy.”

Chris Menon is a freelance journalist and runs the Safestocks blog

Section

Free Tag

Related stories

Twitter


Source Moneywise https://ift.tt/2AB4A17

الثلاثاء، 30 أكتوبر 2018

When Is It Time to Spend More on Something?

I’ve long been an advocate for getting the most value for your dollar. I am very price conscious when I shop for most things. I constantly joke with my kids about how I’m a “store brand connoisseur,” and when they go to the store with me, they know I’m going to inevitably swap their breakfast cereal choice for the store brand version and that half of our cart will have store brand labels on it. I buy lots of small appliances and sporting goods used. I’m just generally very careful about how I spend my money.

However, I don’t go for the cheapest version of everything that I buy. There are many things for which I don’t buy the cheapest version or go the cheapest route.

For me, this isn’t a case-by-case basis situation. There are a handful of principles that guide me toward choosing a higher quality item than the minimal cost entry level version.

Here are six categories of items that nudge me personally to seek out higher quality but higher cost solutions.

Basic Life Maintenance Items

Here, I’m talking about things that ensure that I’m practicing good hygiene, getting a good night of sleep, and so on. Here are five items that fall into this category.

Mattress and pillow If I wake up sore from a night of sleep on a consistent basis on my home mattress or pillow, then there’s a problem. That’s unacceptable, because it interferes with virtually everything I want to do that day.

I’m willing to overlook the occasional night of sleep where I wake up sore – I assume I slept in a bad position. However, if it happens consistently, I’m flipping the mattress or getting a new pillow, and if it continues, I’m replacing our mattress. A good night of sleep is fundamental to my life.

Soap and shampoo I buy inexpensive soap and shampoo, but if the soap irritates my skin, I don’t continue to buy it. The same goes for shampoo – if it gives me dandruff or leaves my hair feeling or looking greasy, I’m not buying it again. Fortunately, I have good success with some inexpensive bar soaps (a wide variety work for me, but I avoid Lever 2000) and shampoos (Pert Plus always works). They’re not the absolute cheapest, but they’re inexpensive and they do the job for me.

Toothbrush, toothpaste, and floss I want to keep my teeth pain free and in good working order for as long as I can, and that means caring for them as well as I can. Here, I follow my dentist’s recommendations pretty strictly.

Maintenance visits to the doctor and dentist It’s far cheaper to just skip these kinds of visits and only visit when something is wrong, but by doing this, I’m keeping myself healthy for the long term and nipping potential problems in the bud. You’re far better off going in for a tooth cleaning every six months or an annual wellness visit than having some nasty dental or medical problem sneak up on you, especially if your insurance covers wellness visits.

Food items There are some ingredients in food items that I will pay extra to avoid, simply because those ingredients are almost strictly unhealthy and will lead to serious health issues down the road. I avoid anything that has trans fats. I avoid anything that has high fructose corn syrup. I avoid anything that has added sugar unless I am strictly using it as a dessert item.

Those standards sometimes cause me to pay more for basic food items, like pasta sauce or salsa, for example. It’s a simple step I can take to ensure that I’m eating at least somewhat healthier and avoiding some of the worst things I could be eating.

Daily Use Items

If this is an item I’m going to be using every day – particularly if it’s an item that I’m going to be using several times a day – I tend to go for items that are highly reliable and do the task as efficiently as possible, and I’m willing to spend more for that. Here are four items that fall into that category.

Cell phone My cell phone must be sturdy (meaning it won’t break if I drop it from arm height when in a case) and must run the key apps that I use. That means that “freebie phones” simply don’t cut the mustard in either regard. I have no need for the latest and greatest phone, but I do need a phone that’s reasonably sturdy and can run things like Evernote.

Part of the difficulty is that there are several iOS-only apps that I use on a daily basis, so this restricts me to an iOS device. Thus, what I typically do is buy a lower-end Apple phone, put it in a sturdy case, use it until there are no longer OS updates for it, and then replace it with a newer-but-still-not-high-end Apple phone. This is decidedly not the cheapest route, but I’ve found that I’ve never seriously damaged an Apple phone in a decent case, even after years of use. (I’m still using an iPhone 6, for those curious.)

Automobile maintenance I follow the maintenance schedule in my car’s manual to the absolute letter, getting each and every maintenance task done within 1,000 miles or so of the recommended mileage. I can do some of the simpler tasks myself, like changing oil, and I have a local mechanic that I trust with the rest of the tasks.

Yes, some of the items could be delayed to “save” a few dollars, but on the other hand, sticking to that schedule has managed to get every single car Sarah and I have ever owned as a married couple well above the 200,000 mile mark. It’s one of those things that costs more up front but results in savings over the long run.

Basic kitchen items There are some items in our kitchen that receive daily use (or very close to it) – a couple of key knives, a pot for making soup or boiling water for pasta, a 9″ by 13″ baking dish, and a spatula are on that short list.

When I use a tool that often, I spend time researching the tools a little to see which ones are reliable and which ones do the job with minimal effort. I use a chef’s knife and a paring knife for virtually everything, so I spend a little more on them (I have a Global chef’s knife I received as a gift and a Victorinox paring knife, both of which I’ve used for years and years, and they do a fantastic job if they’re honed and very occasionally sharpened). I have a couple of older Pyrex baking dishes that seem to be indestructible – again, I could have bought cheaper ones, but these do the job. Our pots are Le Creuset enameled cast iron – again, basically indestructible and they do the job well (we found these during a going out of business sale). None of those are the cheapest low end option.

Pocket notebooks I write in my pocket notebook several times a day, so for me it’s pretty important that it stays together in my pocket, doesn’t lose pages, and doesn’t have any metal edges that can snag or scratch as it goes in and out of my pocket several times daily. I used to use Mead top-spiraled notebooks until I cut myself on the spiral and then ripped up a pair of dress pants with loose metal on the top spiral.

Now, I use Field Notes (or similar notebooks). Field Notes are a little expensive, but they last and last and last in my pocket without falling apart. I can get through a full notebook carrying it in my pocket constantly and pulling it out several times a day without the notebook falling apart or losing pages or scratching me or damaging my pants.

Items That Protect My Safety or My Family’s Safety

Another class of items that I don’t skimp on are items that protect my family’s safety. If it’s an item that will keep family members safe, I’m going to make sure I get high quality items. Here are four examples of items that I spend more on to keep my family safe.

Automobiles There are three key metrics I use to judge a car I’m considering buying. One, can my whole family fit in there? Two, is it reliable, meaning does the model have a good reliability history? Three, is it safe, meaning does it rate as a IIHS top safety pick?

Those factors mean that I do end up paying more for a late model used car than if I chased price alone, but having a car that’s reliable and that keeps my family as safe as possible on the roadways is worth a higher price to me.

First aid items and medical items If someone is injured in some way, we get what is recommended to heal them the fastest based on the doctor’s recommendation. It’s as simple as that. We don’t take shortcuts when it comes to first aid or medical items. Recovering from illness or injury isn’t a situation where we cut corners.

Car seats Although our children are too old for car seats, these were not items that we bought used. Rather, we researched them for safety ratings and bought ones that would maximize their safety in the event of an accident. Used car seats are often weakened due to extended exposure to sunlight and the negative effect it can have on plastics.

Life insurance Obviously, in terms of monthly expenses, it’s cheaper to go without life insurance. For Sarah and I, however, making sure that our children are safe and well cared for in the event of either one of us passing away before our time is vital, so we both carry sizable term life insurance policies, enough so that our children could enter adulthood without a notable decline in standard of living if Sarah or I suddenly passed away.

Items That Prevent Injury or Consistent Pain

If “going cheap” on an item has a significant chance of creating consistent pain or causing injury, then Sarah and I spend more on an item to ensure that such a thing doesn’t happen. Here are two examples of this.

Shoes Neither Sarah nor I go cheap when it comes to shoes. Sore feet or injured feet are not fun. Both of us enjoy walking and hiking, and Sarah walks a lot at work, so we both have motivation to keep our feet injury and pain free. This extends to the point that we will stop wearing fairly new shoes if they’re causing consistent discomfort or other problems.

In general, we both buy New Balance shoes and Keen sandals, as they have shown in the past that they minimize injury and maximize comfort for our feet when walking a lot.

Sporting protective gear While this might also follow under “safety” equipment, many sporting gear items exist to also minimize unnecessary pain. We don’t skimp on things like protective cups, helmets, knee pads, headgear for sparring, or other such items. The goal isn’t just to prevent injury, but to prevent short term pain as well. I’d rather spend a little more and get well made sparring gear, for example, than sustain extra bruises from sparring.

Items With Lower Total Cost of Ownership

I will almost always pay more up front for something that has a lower total cost of ownership over the lifetime of the item. I’d rather pay more now and have a lower maintenance cost while using the item. Here are three examples of that.

Fuel efficient cars As I mentioned earlier, reliability and safety are our two main concerns with automobiles, but when we’re actually deciding between different models that meet our needs, we’ll pay more for a model that’s more fuel efficient because we’ll end up saving money over the long haul.

Typically, we calculate the rough fuel cost of the vehicle over 100,000 or 150,000 miles and then tack that onto the price, then go for whichever car represents the lowest total. It was this type of calculation that persuaded us to buy a Prius back in 2010.

Lighting We have not purchased a non-LED light for our home in years. LED bulbs blow away other options in terms of total cost of ownership because of how long they last and how low the cost per hour of lighting is. Nothing else is even close. LED bulbs are relatively expensive up front, but they last so long and are really easy on the energy bill along the way.

Socks This probably also falls under “daily use” and “life maintenance” (as well as the next “worn out from use” category) but I’ve learned over the years that a good pair of socks will last for a very, very long time, whereas cheap socks will fall apart at the toe seams after a surprisingly small number of wears. Socks aren’t going to last forever, but if you invest in a good pair, they can and do last for many years of banging and beating.

For me, the preferred sock is a Darn Tough merino wool sock. They’re expensive per pair, but I’ve got pairs of these that have lasted for literally hundreds of washings, something that cheap athletic socks have never done. They’re warm in the winter, comfortable, and breathe surprisingly well, too, meaning my foot stays warm but doesn’t really get hot. One pair of these might cost as much as six cheaper pairs, but those six cheaper pairs will be long gone before these wear out. (They also make a nice practical gift.)

Items I’ve Literally Worn Out From Use

One final category is made up of things that I’ve literally worn out from use over the years. If I have an item that I’ve used until it has worn out and failed, I’m generally very interested in buying a quality durable replacement. Here are four examples of this.

Kitchen tools, especially a skillet I’ve had several kitchen tools wear out from overuse over the years. Most notably, I’ve had skillets give up the ghost, particularly nonstick skillets where the Teflon coating began to peel. We invested in good cast iron skillets as replacements and once they have a patina, they’re fantastic.

Wallet I used to buy a wallet every two years or so because the stitching would consistently rip out of the relatively cheap wallets I was buying. I switched to a well-made wallet from Recycled Firefighter that has now lasted me for six years and basically looks like new along the seams at least. The single wallet cost more, but it’s lasted longer than two or three of the older wallets that I once used.

Backpack I have a hiking backpack that I need to be very rugged, which is a Goruck that literally looks new (and which I use as “luggage” for short trips), and I also have a “portable office” backpack (a North Face) that I use when working away from home. Both of them have been used by me for years and barely look as if they’ve been used at all. I swear that the Goruck literally looks new, although I know what it has already been through. The North Face looks worn a little, but only if you look for it. Compare that to the cheap Jansport backpack I used before this, which failed with a similar load as my “portable office” within three years.

Belt I used to buy $10 belts from department stores and they would inevitably fail within a year, usually with the buckle becoming detached from the belt or the buckle falling apart. I spent $50 on a belt from Orion and it has lasted for several years now. It does look a bit worn, but it’s fully functional and by every measure I can tell it will continue to be functional for a long time.

Final Thoughts

Although I pay a little more for these items than I would if I were going for the cheapest version, they often end up saving me money in other ways. They have a low cost of ownership, or they do the job reliably without having to be replaced for a long time, or they help me to avoid pain and discomfort and poor sleep that would slow me down.

Buying the cheapest item isn’t always the best value.

Good luck!

The post When Is It Time to Spend More on Something? appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2P0nAPB

Physical Over Digital: Why Some People Prefer Paper Planners Over Apps

Public Service Loan Forgiveness: How to Qualify (and Why So Few People Do)

The U.S. Department of Education recently released some startling and sobering statistics regarding its Public Service Loan Forgiveness program: Of the 29,000 applications for student loan forgiveness that have been filed thus far, an astounding 99% of them were denied.

As one news organization pointed out, you have better odds of getting accepted into an Ivy League school than getting a Public Service Loan Forgiveness application approved.

Created in 2007, the Public Service Loan Forgiveness (PSLF) program was designed to reward those who spend at least 10 years working in the public sector – in other words, a thank-you to teachers, public defenders, nurses, firefighters, and cops, for example.

The deal is supposed to work like this: After 10 years of paying student loans faithfully, and making 120 qualifying payments, whatever remains of your federal student loan debt is forgiven by the government. But for many public service workers, that promise appears to have been less then genuine.

There are many explanations for the program’s dismal approval numbers. The Department of Education has attributed it to applications simply “not meeting program requirements,” according to an NPR report.

However, the Government Accountability Office (GAO) launched its own investigation into the matter and found that both individual borrowers and the companies that manage student loans for the federal government remain confused about the program’s requirements.

That’s a critical point. The program’s employment and qualifying repayment requirements can and have tripped up applicants with devastating consequences.

“There are three key elements necessary to qualify for Public Student Loan Forgiveness and they’re complicated, which is why tens of thousands of applicants did something wrong and received denial letters,” said Tobin Van Ostern, a student loan policy expert who has written several reports on the student debt crisis and co-founded Savi, a start-up focused on student loan optimization and enrollment support. “I’ve talked to the Department of Education about the program and was, unfortunately, not surprised to see the denial rate.”

With that in mind, here’s a closer look at the requirements for Public Service Loan Forgiveness, and how to avoid landing in that giant rejection pile.

Eligible Loans

There’s one specific type of federal student loan that qualifies for the PSLF program, and that’s a Direct Loan. Those who do not have a Direct Loan will be rejected when applying for forgiveness.

“This is the most common issue I see people have,” began Van Ostern.

The complication here is tied to the fact that those who obtained a student loan before July 1, 2010 may have received money through older federal student loan offerings, among them the Family Education Loan (FFEL) Program or the Federal Perkins Loan Program. Neither of those loans is eligible for the PSLF program.

“One of the most unfortunate cases is people who have the wrong loan type. They have an FFEL or a Perkins Loan, so they’re not eligible. These are still federal loans, but they’re different kinds of federal loans,” continued Van Ostern. “It’s really unfortunate when you have the right type of employer, and you’ve been making all of your payments on time, but unfortunately you have FFEL loans, so people think they’re on track for forgiveness, but end up being rejected.”

If you’re among those with an older loan product, don’t despair. There are actions you can take to make your loans eligible for forgiveness, such as rolling those older loans into a Direct Consolidation Loan.

There is a drawback however. Remember the rule stipulating that in order to be eligible for the PSLF program you must make 120 qualifying payments toward your loan?

If you’ve been paying for years on your Perkins or FFEL loan, all the while thinking you’re closing in on that 120 mark, be prepared for a setback. Those payments are not considered eligible payments, and thus will not be counted toward the 120-payment minimum. In other words, you’ll be starting from scratch again. Only the new payments being made toward the Direct Consolidation Loan will count toward that 120 figure.

Qualifying Employers

Yet another primary reason applicants are unwittingly being denied loan forgiveness is they do not work for what the program defines as a qualified employer.

Qualifying employment is not about the specific job you do for your employer (it doesn’t matter whether you work in the manufacturing or marketing department); rather, the requirement is tied to the type of employer you work for. Eligible employers include:

  • Government organizations at any level — whether it be federal, state, local, or tribal — are qualifying employers. That includes state employees and public school teachers, for example, among many others, but for-profit government contractors are not eligible.
  • Nonprofit organizations that are tax-exempt under Section 501(c)(3) of the Internal Revenue Code are also qualifying employers. These typically include charitable, religious, educational, and scientific organizations, among others — such as a college or the Red Cross — but not political groups or labor unions.
  • Some nonprofits that are not tax-exempt 501(c)(3) organizations also qualify — if they provide certain specific services. Examples include organizations that provide preschool education, emergency management, library services, public safety, law enforcement, and more.
  • Service as a full-time AmeriCorps or Peace Corps volunteer also counts as qualifying employment for PSLF purposes.

The key here is to find out early on whether your employer qualifies for the program — before you invest years of your life, or make major life decisions, with the expectation that your loan is going to be forgiven.

To be sure your employer qualifies, complete and submit the Employment Certification for Public Service Loan Forgiveness form long before you intend to apply for loan forgiveness. In fact, says Samuel Deane, a financial advisor who has worked with numerous millennial clients on the PSLF program, you should be submitting that form every year and every time you change jobs.

“A good number of applicants submitted the form, but didn’t submit annually, or submitted it incomplete,” explained Deane, who says the recent flurry of news about the PSLF rejection rate has sparked concern among his clients. “When you switch employers, make sure to keep submitting that form, so that the Department of Education is aware of your employment and to make sure you’re still on the right track.”

Yet another important note about that form: It does far more than simply certify where you work.

“What makes the form misleading is that it’s called an Employment Certification Form, but it does a lot more than that,” said Michael Lux, an Indiana attorney and founder of Student Loan Sherpa, a website dedicated to student loan education, strategy, and borrower advocacy. “It triggers a review of your account and they will also look at your loans to make sure you have an eligible loan.”

Qualifying Repayment Plans

The third big challenge applicants face is the requirement that they be part of a qualified repayment plan, and that each and every one of their 120 payments be made on time.

Let’s start first with what constitutes a qualified repayment plan: Only income-driven repayment plans are eligible for public service loan forgiveness. Those include the Pay As You Earn and the Revised Pay As You Earn repayment plans, the Income-Based Repayment Plan, and the Income-Contingent Repayment Plan.

Loans on a standard repayment plan are not eligible — so if you intend to seek loan forgiveness, it’s worth changing to an income-based repayment plan as soon as you can.

As for the 120 on-time payments, the program is very specific that each one of them must have been submitted by its due date. “If you make a late payment once during those 120 payments, you will be denied,” said Van Ostern.

But to be clear, that’s not a permanent rejection, Van Ostern stressed — you don’t need a perfect, consecutive streak, just 120 on-tie payments in total. So you can apply for forgiveness again once you’ve made more on-time payments, reaching a cumulative total of 120 payments made by the due date.

How to Qualify for Public Service Loan Forgiveness

To recap, here’s how to make sure you’re actually eligible for student loan forgiveness when the time comes:

  1. Check your loan type: Only Federal Direct Loans are eligible for PSLF.
  2. Verify employer eligibility: Government organizations at all levels and 503(c)(3) tax-exempt nonprofits are qualifying employers. If your work email ends in .edu, .gov, or .org, there’s a good chance you’re eligible – but you should submit an employer certification form to be certain.
  3. Enroll in an income-based repayment plan: Only loans that are on income-based repayment plans are eligible for public service loan forgiveness.
  4. Make 120 total on-time payments: They don’t have to consecutive, but you need to make a total of 120 on-time monthly payments to qualify.

Don’t Rely on Your Loan Servicer to Provide Correct Information

One of the findings that resulted from the GAO investigation into the PSLF program was that there’s a communication breakdown between the Education Department and the many student loan servicers contracted by the government to handle loan repayment processing.

One loan servicer in particular, FedLoan, has been the focus of much of the challenges. FedLoan is the contractor that officially handles PSLF. The company’s representatives have apparently declined to tell borrowers whether or not their jobs qualify as public service, according the GAO investigation. FedLoan has said they do not have a list of eligible employers.

But the FedLoan issue is just one concerning example. Experts who have been following the PSLF program and its many challenges say there’s a general lack of education and training among many loan servicers with regard to PSLF requirements.

“I have spoken to a number of people who were told by their loan servicer that they were on the right track, and then a few years later they found out they were not,” said Lux.

A Word to the Wise

As if those applying for the PSLF program don’t have enough red tape and confusion to sort through, there’s also unfortunately a great deal of fraud in this space, noted Van Ostern.

When you jump onto Google and begin searching “How to enroll in Public Student Loan Forgiveness” or “Certification for Public Student Loan Forgiveness,” there are plenty of less-than-ethical companies that will pop up, many of which are looking to make a quick buck at your expense.

“People often get scammed when they go somewhere and think that they’re getting certified,” Van Ostern explained.

The alternative? If you have an existing financial advisor, someone you trust, he or she might be a good source. But even that’s no guarantee.

“This program is so unique and so new, it can be hard to find experts,” said Van Ostern.

Mia Taylor is an award-winning journalist with more than two decades of experience. She has worked for some of the nation’s best-known news organizations, including the Atlanta Journal-Constitution and the San Diego Union-Tribune. 

More by Mia Taylor:

The post Public Service Loan Forgiveness: How to Qualify (and Why So Few People Do) appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2SuR863