Thousands of courses for $10 728x90

الخميس، 22 نوفمبر 2018

I don’t know why PayPal has closed my account

PayPal

Moneywise helps a reader whose PayPal account was shut without explanation

In September, PayPal closed my account, which I had been using for about 10 years. The reason given was “activity that contravenes our terms and conditions”.

Three days before it was closed, I received a message from PayPal advising me that I was within a few hundred pounds of the amount that its terms and conditions allowed to pass through my account in one year. It suggested I upgrade to a business account so that I could continue using their facility with a higher limit. This struck me as very convenient and I sent them a valid passport and a utility bill proving that I resided at the address listed on my account.

After submitting my ID evidence, I received an email saying that I could no longer use my PayPal account. No reason was given for this. I have not been involved in any fraudulent or dishonest activity.

TS/Manchester

This does seem to happen all too often and I’ve written several times in the past about people who have had their account shut with no explanation and no access to their cash for months. The good news is that when I intervened on your behalf, PayPal responded quickly and positively. The problem turned out to be your proof-of-identity photograph, although goodness knows why the company couldn’t have sorted it out earlier.

Here is PayPal’s explanation: “EU anti-money laundering and ‘Know Your Customer’ regulations require that we verify the identity of our customers before they send, receive or withdraw receive €2,500 (or the equivalent in other currencies) through their PayPal account. To remove these limits and to comply with EU law, we will ask a customer to provide more information about themselves before they reach this amount. These are very important regulations intended to prevent criminals and terrorists from using financial products or services to store and move their money.

“TS’s account was approaching this threshold in September 2018. As a result, we asked him to provide the necessary proof of identity, which he did in the form of a scan of his passport and proof of address.

“Unfortunately, the passport scan was not of a high enough quality for us to use it to confirm proof of identity and, as a result, we placed limitations on his account. For the purposes of verification under anti-money laundering regulations, we cannot release funds without a valid proof of identity.

“We have reviewed the account and the information provided and have now been able to verify the account. TS can once again send and receive money through his PayPal account. We are sorry that we did not respond to his concerns earlier.”

PayPal offered you a £50 goodwill payment, which you asked to be donated to my chosen charity, the Indonesia Tsunami Appeal.

OUTCOME: PayPal account restored plus £50 donated to charity

Section

Free Tag

Twitter


Source Moneywise https://ift.tt/2r1eKCT

2018 Black Friday and Cyber Monday Deals For Work-at-Home Women

Did you know that there are a TON of great Black Friday and Cyber Monday deals for work-at-home women?! Yes, even the work-at-home realm is in on the holiday sales rush — which is an excellent opportunity for you to lay the groundwork or boost your work-at-home career this year and beyond. Here are some […]

The post 2018 Black Friday and Cyber Monday Deals For Work-at-Home Women appeared first on The Work at Home Woman.


Source The Work at Home Woman https://ift.tt/2DIeujN

How to Know When to Use Chatbots vs Live Chat

How are you currently communicating with your customers?

If calling, emailing, or submitting a form on your website are the only means for your customers to reach you, you need to get with the times and make some changes.

Offering live chat on your website is a better way to provide customer service.

According to studies, 73% of consumers say live chat is their most preferred method of communication.

This ranked highest compared to other methods. In fact, 61% of consumers said they preferred email, 48% preferred social media and only 44% preferred phone.

Furthermore, live chat had a 92% satisfaction rating.

This was also the highest satisfaction rating compared to other forms of customer support.

It’s clear your company needs to have this feature on your website. But how do you implement it? You’ve got two choices: chatbots or live chat representatives.

Chatbots are computer-generated responses. They allow customers to receive answers to their questions via AI software.

Experts predict that by 2020, 85% of consumers will be able to manage their relationships with brands without human interaction.

And 80% of businesses are either currently using AI or planning to use AI for customer service in the next two years. Further, 45% of customers say they prefer chatbots for customer service inquiries.

With this technology on the rise, you need to have marketing skills to survive in the age of AI.

Grand View Research expects the global market size for chatbots to hit $1.25 billion by the year 2025, with a 24.3% compounded annual growth rate.

You need to decide whether you will use chatbots or an actual human to type responses to customers on your website.

People ask me which option is better all the time. The reality is each one has its pros and cons.

Chatbots and live chat representatives work well together. I’ll explain when it’s best to use one over the other in this guide.

I’ll go through some factors and scenarios to help you decide the best fit for your website.

Response time

You don’t want to make your customers wait. That’s a big problem when it comes to customer service.

We’ve all been there—sitting on hold on the phone for what feels like a lifetime waiting to talk to someone.

Live chat drastically reduces wait times. In fact, 79% of consumers say they prefer live chat because they get their questions answered immediately.

Just look at these average response times of live chat compared to social media and email:
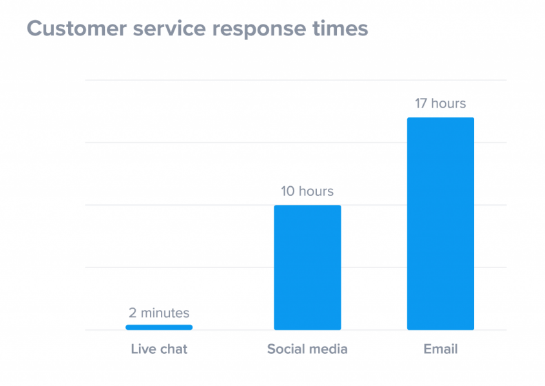
response time

Live chat blows these other methods out of the water in terms of speed.

But it’s still not perfect.

Believe it or not, 21% of live chat support requests are ignored by businesses.

While live chat has a fast response time, it can still be improved.

On the other hand, chatbots have an instant response. Upon a customer posting an inquiry, a chatbot can generate an answer within seconds. This gets the conversation going right away.

If you’re looking for the fastest response times, chatbots win. But live chat will still be faster than the other options you’re using.

My recommendation is to use a combination of the two options.

When a customer begins a chat session, start with a chatbot to give them an instant reply. This bot can gather preliminary information about the inquiry until a representative becomes available.

Chatbots can also make sure the customer gets transferred to the right representative who is qualified to answer their question.

I’ll talk more about how chatbots and live chat representatives can work together further in this guide.

Cost efficiency

Your business decisions need to be cost-effective. Live chat will help reduce costs compared to phone support.

In fact, studies show that it’s 17-33% less expensive to communicate with a customer via live chat than phone calls.

Live chat agents have the ability to multitask and help several customers at the same time. This can’t be done over the phone.

Implementing live chat will improve your operational efficiency.

You’ve got to determine how much this new technology will cost you. Here’s a look at some average prices to give you an idea of what to expect:
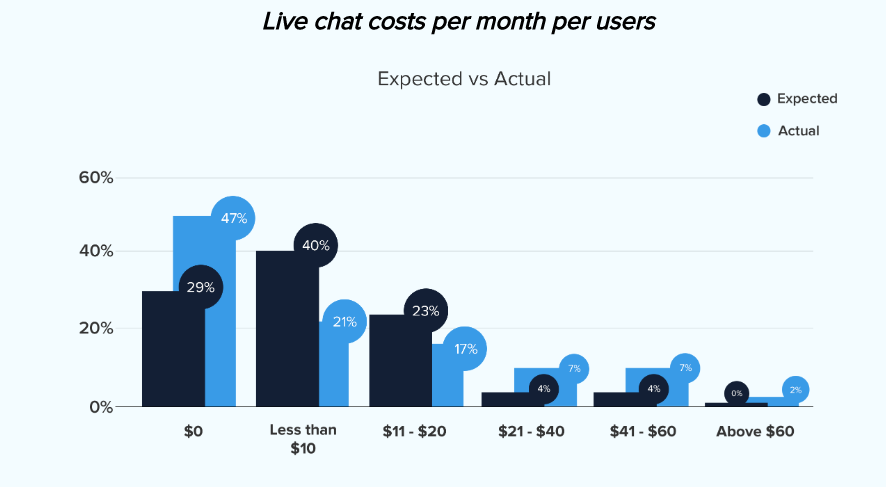
cost

The pricing will depend on many factors, such as the number of agents you’re paying and the times they’re available.

It will also vary depending on whether you’re paying staff in-house to handle these inquiries or outsourcing this service to a general customer service agency.

If you’re paying more than $20 per month per user, I’d say that’s expensive.

Outsourcing support to a customer service agency will be cheaper, but you may lose some quality of the responses compared to those given by one of your own employees.

How many employees will you need to handle your live chat communication?

Research shows 51% of businesses have just one agent dedicated to live chat. And 39% of companies have between two and five agents.

That’s not surprising, considering 70% of brands that implement live chat have less than 5,000 unique website visitors each month.

And we know that 52% of companies say price is the most important factor influencing their decisions to use live chat.

Chatbots will lower these costs.

Sure, you’ll need to pay for the AI software. But this will definitely cost you less in the long run compared to paying employees in addition to the cost of the live chat software.

If you’re looking for the cheapest option, you’re better off with chatbots.

But using human reps to respond via live chat is still cheaper than phone support.

Human touch

Artificial intelligence is definitely advancing.

Responses by chatbots can mimic human answers. In some instances, customers won’t even notice they talk to a robot.

That said, chatbots can’t replace that human touch.

There is still some resistance from customers when it comes to using chatbots:
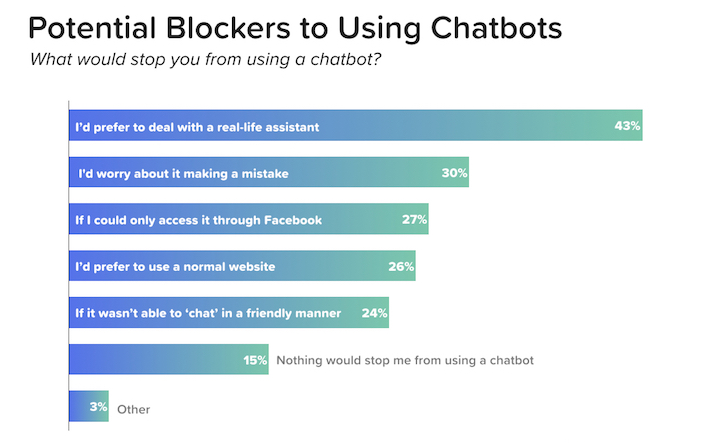
blockers

As you can see, people have their reservations about using this new technology.

There are times when customers would rather deal with an actual person. Consumers are also worried about chatbots making a mistake.

About 37% of consumers expect to use a chatbot for getting a quick answer in an emergency.

For example, a chatbot could help someone determine whether an item is in stock or help track the shipping of their package.

And 34% of people say they would use a chatbot to help them find a customer service associate. This echos my earlier point about the two options working well together.

Based on what the customer is looking for, the chatbot can appropriately direct them to an agent. For example, a sales inquiry may go to one department, and a question about technical support may go to a different department.

Start with a chatbot, then transfer the customer to a live chat session with an actual human.

Availability

If you’re going to use humans on your website to chat with customers, they’re probably not going to be available 24/7.

This is especially true if you’re planning to use your employees to handle these chats. Your costs will be significantly higher if you’re paying for human support 24/7, 365.

Giant global corporations such as Apple can afford this, but smaller businesses cannot.

That’s when you’ll need chatbots.

The number one potential benefit of using chatbots is 24-hour customer service.
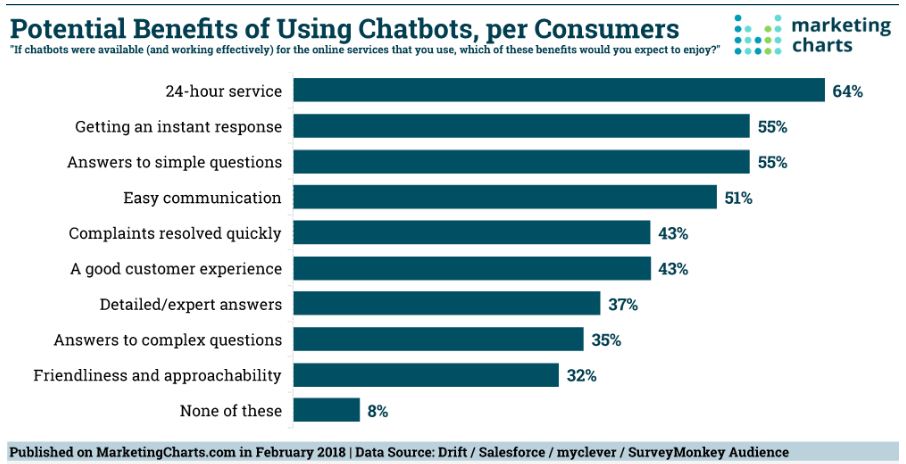
availability

Chatbots can respond to customers in the middle of the night as well as on weekends.

That’s because chatbots don’t need to eat, sleep, or take bathroom breaks.

To maximize your availability and provide 24-hour service without paying extreme labor costs, use chatbots.

Even if you use human representatives during business hours, you can switch to chatbots when your customer support agents are offline.

Resolving inquiries

Fast response times are important. Being able to get an answer at any time of the day or night is a great benefit as well.

But these are useless if the customer inquiry isn’t resolved.

That’s why they’re reaching out in the first place. The customer has a question or a problem that needs to be addressed.

Most people would assume a human representative is the only way to solve a customer problem. However, that’s not always the case.

Research shows that eight out of ten chat sessions can be resolved by a chatbot.
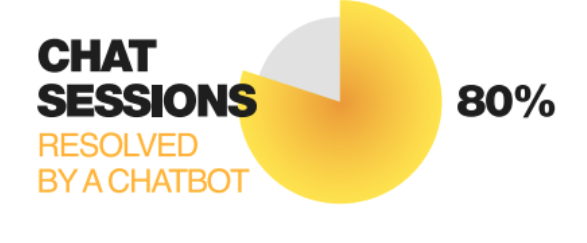
80

Chatbots aren’t perfect: 20% of these sessions don’t end in a resolution.

It’s nearly impossible to please 100% of your customers. However, you want that number to be as close to 100% as possible.

In some instances, a chatbot can transfer the conversation to a customer service representative.

Those agents will be able to do things that chatbots aren’t capable of yet, emphasizing the need for the human touch.

Chatbots can’t feel empathy or convey a specific tone the same way a human can.

A chatbot won’t give customers the right response if it doesn’t understand what they’re asking.

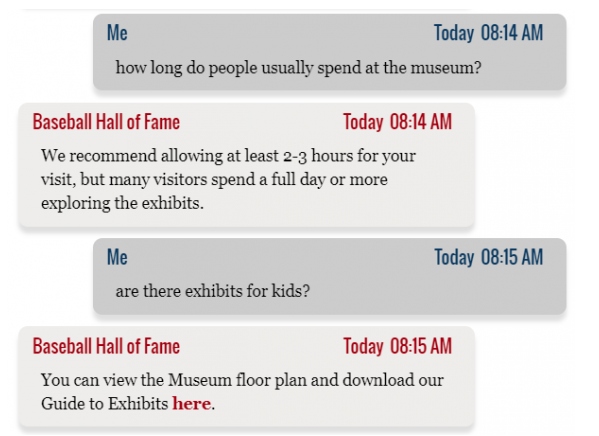
Here’s an example of that:
HOF

As you can see, the chatbot provides useful information. The first question gets answered appropriately.

But the second question doesn’t get answered properly.

Chatbots could also run into problems if the customer’s query has spelling and grammar issues.

If a customer is looking for help with something like custom pricing based on their unique situation, a chatbot may not be able to provide them with the assistance offered by an actual person.

Can a chatbot resolve inquiries? Absolutely.

However, at times you’ll need to transfer those inquiries to a human.

Again, this highlights the fact that chatbots and live chat work well when paired together.

Conversions

Ultimately, you want your customers to convert after reaching out to your customer support via whatever option they choose.

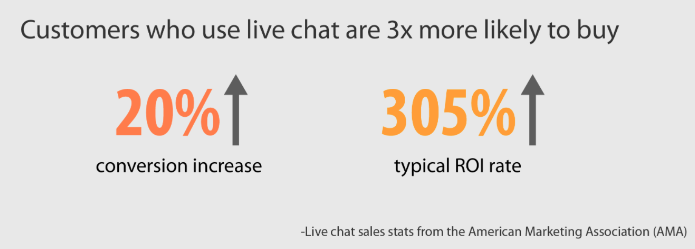
Live chat increases the chances that people will buy:
conversions 1

In fact, 38% of consumers will make purchases on ecommerce websites as a direct result of their live chat sessions.

Live chat is a great way to drive conversions. That said, live chat isn’t proactive.

Allow me to explain.

Once a site visitor determines they want to use live chat to solve their problem, they need to make an effort to reach out. As a result of the conversation, they’ll be more likely to convert.

But the visitor needs to make that initial step.

It’s obviously unreasonable for a human agent to reach out to every person who lands on your website.

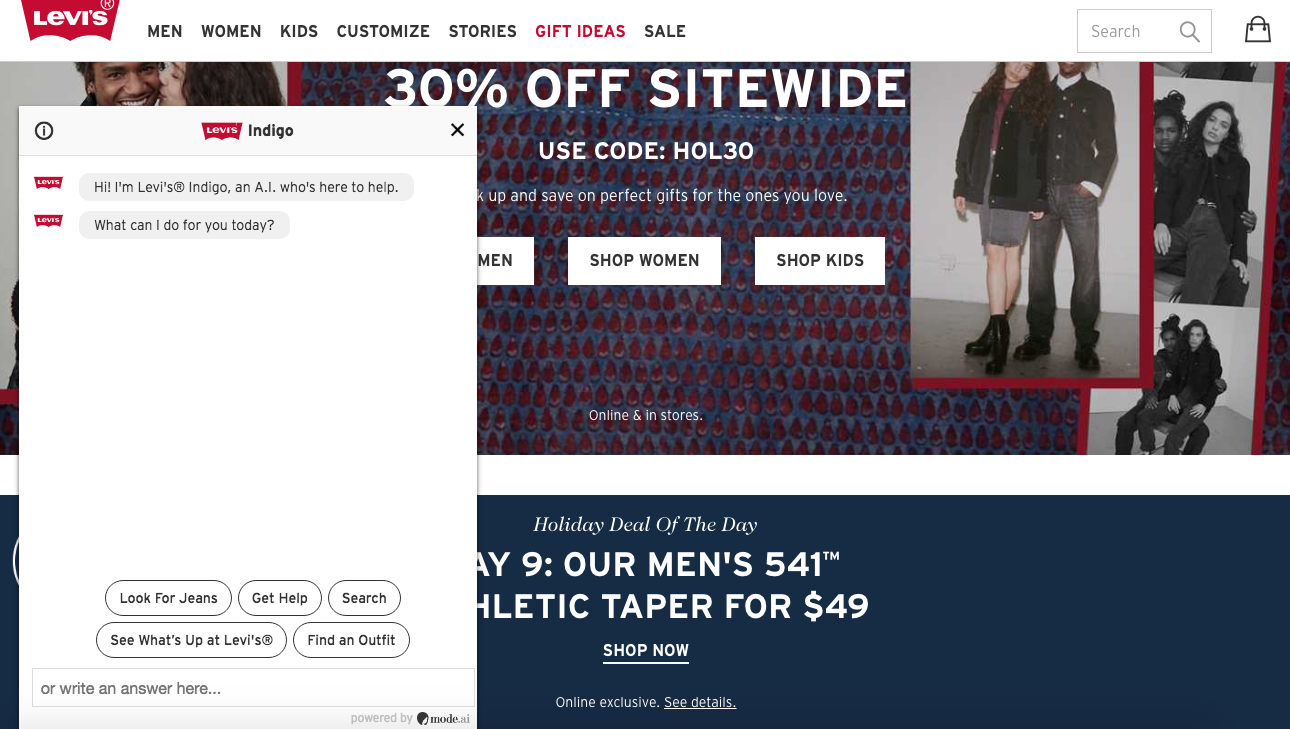
That’s when you can use a chatbot to be proactive. Here’s an example from the Levi’s website:
levi

When a customer lands on this website, an AI chatbot automatically starts a chat session.

This is proactive.

Now, if a customer has an inquiry, they’ll be more inclined to take advantage of this feature. If the chatbot is unable to resolve the problem, the chat can be transferred to a human representative.

Conclusion

Your business can provide better customer service by implementing live chat.

Now you just need to determine whether you’re going to use human representatives or chatbots to handle this communication.

Chatbots will provide an instant response, but live chat agents are still faster than your current methods of customer support.

Live chat representatives are less expensive than phone calls from customers, but chatbots will be cheaper in the long run.

However, chatbots don’t add a human touch to the conversation.

Chatbots are available 24/7, which won’t be the case for actual agents.

Surprisingly, bots are able to resolve the majority of customer inquiries. Both live chat agents and chatbots increase the chances of getting customers to convert.

Ultimately, live chat and chatbots work best when they’re implemented together.

I recommend you use both of these on your website to maximize efficiency and get the best results.

Are you planning to use chatbots, live chat agents, or a combination of both to improve customer communication on your website?


Source Quick Sprout https://ift.tt/2Koxl4t

Giving Thanks

The açt of giving thanks isn’t something that comes natural for most of us. Most of the people reading this article have a life that’s absolutely chock full of things to be thankful for, and yet our minds come back to the negatives, the regrets, the things that we wish could be better rather than the things that are great.

It is really easy to overlook all of those things in our lives that really are great in an effort to seek out more and more and more.

Let today be a call to be thankful for the many, many things that we have in our life that we often take for granted, so that we might see the abundance we already have and be a little less driven to excess and perhaps use the gifts we have to secure our own prosperity and gifts instead.

It is easy sometimes to get caught up in the things that aren’t right, the pains, the problems, the mistakes, the regrets, the things left undone. Today, I’m turning my eyes away from that and looking at the bounty that I have.

With that, here are some of the many thing I am thankful for today.

* * *

I am thankful for my family, particularly my wife Sarah and my three children, as well as the numerous extended family members that I’ll be seeing over the coming days. I am incredibly lucky to have an abundance of family members who care about me and choose to spend some of their free time with me. I’m incredibly greatful that those opportunities we have to spend time together tend to be peaceful and joyous and full of laughter.

I am thankful for my close friends, both present and past, who are both local and spread out all over the world. I have had people come into my life from all walks of life and profoundly change me in untold ways, mostly for the better. I am thankful for the opportunities I have to spend time with them in conversation and laughter and do many things together.

I am thankful for my own health, both mental and physical. I’m incredibly lucky to be able to get up in the morning and largely feel quite good in terms of my health and my mental state. I am particularly thankful for having discovered taekwondo and yoga over the past two years, as they have had a profound positive impact on my life.

I am thankful for the opportunity to write for various organizations and cobble together enough income to make a nice living and adequately care for my family and prepare for a wonderful future together with Sarah. There are moments when the work is incredibly challenging, but it brings me joy and meaning on an amazingly consistent basis, and that I also make a living doing it sometimes feels like a miracle.

I am thankful for the simple pleasures of nature: the warmth of sunlight on my skin, the smell of fresh air, the rustle of leaves, the colors of the fields and the forest.

I am thankful for countless little things in my life that add up to so much: reading a good book, playing a tabletop game with friends, making a great meal, tasting a really flavorful full-bodied craft beer, feeling my legs really stretch out when I’m warming up for exercise, holding my wife close to me, getting into a comfortable bed after a long and busy day… those little things really add up.

* * *

I could go on and on and fill up thousands of words listing things like this that I’m thankful for. As I write one of them down, two more pop into my mind, and the article could continue on like that forever.

I write down things I’m grateful for almost every day and even though my life is incredibly full of things to be thankful for, there are still some days where it’s a challenge to even list a few. This used to mystify me – I know that there are many good things in my life, so why does it feel hard and awkward to list them?

The reason is that our minds are conditioned to look not at the good things, but at the bad. We don’t think about what we’re good at most of the time. Instead, we look at our flaws. We don’t consider the many things that are good in the world. Instead, we focus on what’s bad.

Sure, one could point a finger at the media for this, as they breathlessly report every bad thing that’s happening in the world without giving half a second to the good things, and constantly strive to make ordinary people seem menacing and evil. However, the media reports such things because they get ratings, and such things get ratings because we are drawn to watch them. We’re drawn to look at the negative, to strain our neck to see the car accident, to look at our own flaws and the flaws of others.

It is often because of those negative feelings and those perceived flaws that we end up feeling like our lives are emptier than they really are, and we respond to that by wanting more and more and more.

In that process, we often wind up neglecting many of the wonderful things we already have in our life. We start taking things for granted. Our spouse. Our children. That gorgeous view out of our back door. The taste of coffee in the morning. The warm touch of our spouse’s hand on our back. The good things we’ve done. The good traits we have. We just take all of it for granted and turn our eyes to the negatives.

The singular best antidote I’ve found to that is the simple daily routine of stopping and giving thanks and gratitude to a handful of things in my life, things I haven’t been grateful for lately. That simple act reminds me of how incredibly much I do have in my life, and how silly it really is to keep chasing more and more and more.

Giving thanks shouldn’t be cordoned off to just one day a year. Rather, it should be a daily part of our lives, a routine that reminds us of how much we have in our lives. It should be an intentional thing, because, as I noted above, we have a great tendency to turn our eyes toward the painful and negative things in our lives – the things left undone, the things we want but do not have, the things we see as flawed in ourselves.

In truth, every one of us has great things about ourselves that we often don’t give even the most fleeting thought about. Every one of us has done a lot of worthwhile things in our lives. Every one of us already has an overwhelming abundance of good things in our lives, far more than we can count and far more than we probably ever realize.

Rather than looking at the bad in our lives and in the world, make a conscious effort to spend some time each day reflecting on the good things in our lives and in the world.

* * *

So, here’s what I propose to you, starting with this Thanksgiving Day and repeating for each day forward.

Spend just a minute or two today thinking intentionally about the good things in your life and how you’re grateful to have them. Make this into a daily routine, and try not to repeat anything for a week.

I find it useful to actually write them down, though you don’t need to keep a journal per se. I just find that the act of writing something down helps me to really focus on it. I usually aim to name five things each day, and they can’t be things I’ve named in the last few days. They have to be new things.

I find that this practice achieves several things that make my finances better and, frankly, my whole life better.

It forces me to look at the positives in my life. I am so often drawn to my flaws and the things I don’t have in life. I think about my character flaws. I think about the mistakes I’ve made. I think about the things I wish I had. I think about how people have treated me poorly.

Those thoughts lead to a pretty awful place. They lead to a place where it’s very easy to convince myself that I need more in my life, when I really don’t. It’s a place where I want to believe that a product can change some flaw about me, when it really can’t. It’s a place where I’m driven in my decisions by emotion, not choice.

Looking at the positives in my life in a careful and deliberate fashion, if only for a couple of moments, is like lighting up a lantern in a dark cave. It pushes away a lot of those critical negative feelings in a subconscious way. I simply don’t think about them for a while.

Furthermore, chaining together many days of being thankful tends to improve my overall worldview and perspective on myself. It becomes harder and harder to believe that I’m inherently flawed if my life has such abundance. It becomes harder and harder to believe that I’m missing out if I have so many good things around me. It becomes harder and harder to believe the world is such a bad place if there are such good things going on.

It’s that constant chain, that incessant flood of reflecting on those good things, that brings sunshine into the darkness. It’s like installing track lighting in the dark cave of your soul, and when you’re able to look around, you begin to see that there’s plenty already there and there’s no need to want more and more and more.

It’s not an immediate overnight change. It takes time and repetition, but it builds on itself. You begin to feel better about what you have and what your place in the world is like, and the desire to have more and more and more grows less and less.

* * *

As powerful as being thankful and reflecting on gratitude is when it’s a thing that you do privately, it’s perhaps even more powerful when you share those thoughts with others.

Telling someone thank you for what they mean to you or what they’ve done for you or the impact they’ve had on you is a powerful act, not just for you, but for the person receiving the thanks as well.

For you, it’s a way to deeply connect with someone who has lifted you up in some way. It’s a way to repay in a small way what they’ve given you, and for you to bring something valuable into their life without cost to you.

That’s important: thanking someone for what they’ve done for you really has no cost to you. It’s one of those acts that has only upside.

For them… well, few things in life are more powerful than hearing someone tell you sincerely that you changed their life in a positive way. It means a ton to them, even if they have lived a life such that they’ve heard such things before from others. It’s one of those things that is always powerful and never gets old. It’s powerful for everyone.

There are many ways to give thanks one on one. A conversation. A lunch together. A phone call. Even a text or an email.

My preferred way of doing this is by sending a handwritten thank you note. It costs less than a dollar to do this and it becomes something permanent that they can hold onto as a reminder that they’ve done something valuable.

If you want to step out even further, thanking someone publicly is an incredibly powerful act. Speaking in front of others while thanking someone for all that they’ve done for you is a wonderful way to honor and give credit to someone in a truly humble way. It’s one of those acts that leaves almost everyone involved feeling good – you feel good for being able to thank someone for what they’ve done for you, the recipient feels honored by your words, and everyone else feels good because of their connection to the two of you.

You can even write up such a tribute and share it on social media or other public places so that your words can be read by a very wide audience.

Beyond that, I’ve found that sincerely and specifically giving thanks to someone else has a very long tail of positive feeling in both the giver and the recipient. You feel incredibly good about having done it, while the other person feels incredibly good for having received it, and it costs nothing. It’s the power of thankfulness.

Today, give that kind of thanks to someone. Look for someone you’re spending some time today with and tell that person thank you for how they’ve helped you in the past. Do it one-on-one if that feels most comfortable to you, or do it in front of others so they can hear it. Regardless of what you choose, do it. Give thanks.

Furthermore, try to make it into a habit. Writing a thank you note to all of the people in your life that have helped you is a great thirty day challenge, one per day. See if you can fill the next month with this.

* * *

Giving thanks, particularly when done regularly, often boils down to revealing one fundamental truth about your life: you have an abundance of truly good things in your life. The reality is that you don’t need more – in fact, more is often overkill as it can push out many of the wonderful things you already have.

In those moments when you feel empty and you feel somehow drawn to try to buy something to fill that perceived empty space, step back for a moment and think about the abundance of things you have in your life. The people. The experiences. The personal pleasures. The memories. The little things. The big things. Remember how full your life really is, and give thanks for those things, either alone or directly to someone else or to a wide group of people.

What you’ll find is that such thoughts, particularly when practiced with regularity and sincerity, are a powerful tool for washing away a sense of being unfulfilled in life, and it’s that sense of being unfulfilled that often drives some of our worst impulses and financial mistakes.

Give thanks. You won’t regret it.

The post Giving Thanks appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2QbTXKV

The 60-20-20 Budget Puts Needs Before Wants. Here’s How to Try It


I always thought the right budget breakdown was the tried-and-true 50-30-20 method, where 50% of my monthly take-home pay goes toward living expenses, 20% toward savings and 30% toward whatever I want.

But when I finally got a financial advisor, I was surprised to hear that his recommendation wasn’t 50-30-20 after all — it was the 60-20-20 budget.

During our first meeting, we discussed all of my finances. I explained to him that I own a home in a costly state (hello, New Jersey), commute to work in New York City, aim to save a large amount every month and have little debt.

With all of this and more in mind, his recommendation of the 60-20-20 budget made perfect sense. I immediately became a huge fan of how the money I save and spend on whatever I want is equal — each 20%. Plus, knowing I was allowed 60% of my monthly budget for my living expenses, I had a little more flexibility over my fluctuating bills like groceries and electric.

Why the 60-20-20 Budget?

In reality, you can budget your take-home pay any way you want, but the 60-20-20 budget is great place to begin.

Let’s say your monthly take-home pay is $4,000. According to the 60-20-20 budget, you should allot 60% (or $2,400) to your monthly living expenses, 20% (or $800) to savings and then 20% (another $800) to your personal wants.

My financial advisor, Northwestern Mutual insurance agent Nicholas Verard Zanoni, said this method can help you build structure into your budget and learn how to save.

“With this rule, 60% of your [take-home pay] will typically go toward your lifestyle expenses,” Zanoni said. “These are your needs — food, water, shelter and standard of living. Things like your fixed expenses. Then 20% is for your discretionary spending. This is your fun money — traveling, drinks, sporting events, concerts, eating out, etc. And the last 20% is to be saved or invested.”

It’s not much different than the 50-30-20 budget, but it puts more of a focus on fixed expenses and savings than personal wants and spending.

“This is a rule-of-thumb guideline to start out with and visualize,” Zanoni said. “Whether it’s 50/30 or 60/20, it’s really just splitting hairs in a lot of ways. Ultimately, my goal is to help coach my clients at first to spend 80% and save 20%.”

When you take a step back and look at how much of your take-home pay goes into each of these three buckets, you can better analyze your spending in order to make smarter savings decisions.

How to Get Started With the 60-20-20 Budget

If you’re ready to utilize the 60-20-20 budget, start by taking inventory of your finances. Write down every monthly expense you can think of and keep track of them in a spreadsheet. Then look at how much you’re spending through the lens of the 60-20-20 budget.

From there, consider using a financial app to help you find ways to cut back and save even more.

“People should focus on treating their savings like a bill, an obligation and not so much of an option,” Zanoni said. “Focusing on fixed expenses and saving helps identify the money that might be being spent unnecessarily or without much recognition. More often than not, most individuals are not aware of all of the things they spend money on.”

This budget could help you be more aware of your spending habits, especially when you’re doling out the dough for things you don’t really need (hi, super cute sweater from H&M) or that you’re not using (hello, monthly streaming subscriptions).

Instead of equally spending $800 on savings and $800 on your personal wants, perhaps you’d want to put $1,000 toward your savings and only spend $600 on your personal wants. That would shift the 60-20-20 budget to 60-25-15, and you’d be saving more.

“In order to reach the goals we have for ourselves, we very typically find that we need to increase savings to 25 or 30% over time to reach those goals,” Zanoni said. “People may not be able to start out at 20%, but that’s what we want to help them achieve and work toward at first. Over time, we will need to be saving more as we continue to progress in life every single year.”

Lastly, Zanoni said to keep your goals in mind and consider working with a financial advisor who can help you stay on track.

“Focusing on that budget and making sure that they work with someone to help optimize that budget for all of their goals is really the most important part,” Zanoni said.

Budgeting is all about finding ways to set yourself up for financial freedom. Starting now can really make a difference in the future.

Northwestern Mutual is the marketing name for The Northwestern Mutual Life Insurance Company, Milwaukee, WI (NM) and its subsidiaries. Nicholas Verard Zanoni is an insurance agent of NM.

Hilarey Wojtowicz is the senior career and finance editor at Swirled, a lifestyle newsletter and website that helps millennials learn everything they need to know in order to truly start adulting.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.

The Penny Hoarder Promise: We provide accurate, reliable information. Here’s why you can trust us and how we make money.


source The Penny Hoarder https://ift.tt/2TAiQi3

Don’t Lose Your Home. Fight Eviction With These 4 Strategies

الأربعاء، 21 نوفمبر 2018

Land A Holiday Job: How to Fatten Your Wallet this Holiday Season

Are you entering the holiday season short of cash? Learn the best ways to search for a seasonal job.

Source CBNNews.com https://ift.tt/2PKki3r

9 Holiday Shopping Tips: Be Festive While Saving Big Bucks

The holiday season is here! Discover a few simple shopping tips that will increase your holiday cheer and your savings account simultaneously.

Source CBNNews.com https://ift.tt/2TzrgpW

Here Are the Best (and Worst) Reasons People Take out Personal Loans

How to Borrow Money: Our Step-by-Step Guide to Getting a Personal Loan

Americans Added $18 Billion in Personal Loan Debt in 2018. This Could Be Why


While you weren’t looking, personal loans have quietly become more popular than they’ve ever been before.

In fact, they’ve surged to an all-time high in the United States, with Americans taking out a whopping $125 billion in personal loans as of 2018. That’s a huge jump from $76 billion as recently as 2015.

Personal loans are now the fastest-growing consumer-lending category in the U.S., outpacing the growth of auto loans, mortgages or credit cards, according to an analysis by the credit bureau TransUnion.

Why so many loans?

Online Lenders Now Account for 36% of Loans

In a nutshell, we’re attracted to the eye-popping convenience of getting a loan online.

“Nowadays you can go online, input your information and within minutes find out how much of a loan you qualify for and the possible rate,” Greg Palmieri, a financial planner with the online lender SoFi, told The Penny Hoarder via email.

“Before, you would have had to wait on hold over the phone with your bank or physically go into your bank’s branch, fill out an application and wait to find out if you were eligible and then approved.”

Innovative financial technology — “fintech” — companies are driving the growth in personal loans, according to TransUnion’s data. Online loan marketplaces and peer-to-peer lending platforms have changed the game by serving up quick and easy credit.

Consider the following:  

  • Fintech companies originated more than a third of all U.S. personal loans in 2017, compared with less than 1% of them in 2010. That’s a huge change in only seven years.
  • When the total balance of all U.S. personal loans hit a record $125 billion in 2018, it was an 18% rise from the year before. That’s a big increase!

1 in 17 Americans Have a Personal Loan

It also helps that you can get these loans more or less anonymously.

“It’s far less intimidating than walking into a bank, sitting down with a personal banker and having to deal with the stress of not knowing whether you’re approved,” says J.R. Duren, a personal finance analyst and editor at consumer reviews website HighYa.

“It can be pretty embarrassing to sit across the desk from someone who tells you they can’t approve your loan.”

At this point, roughly 6% of U.S. consumers have an open personal loan, according to TransUnion’s data.

That’s about one out of every 17 Americans.

Why so many loans?

Some experts say that, in this era of rising costs and stagnant wages, more people are taking out personal loans because they have to. It’s their best option.

“Very simply, people are overextended. They have no margin in their finances, so when the unexpected happens, they have no cushion,” says Len Hayduchok, a certified financial planner and CEO of Dedicated Financial Services in Hamilton, New Jersey.

“Between house payments, school loans for themselves or children, medical expenses for parents and increases in health insurance premiums, people need more money to meet their needs and wants — and wages have not kept up with inflation.”

Freedom Is Spending Your Loan on What You Want

Others view it differently.

Lending expert Joe Toms, president of online lender FreedomPlus, believes personal loans are becoming more popular simply because of the freedom they offer — borrowers can use the loans for whatever they want.

Many borrowers, wary of credit card debt that can linger for years, are attracted by a personal loan’s ironclad payment schedule of 36 to 60 months, Toms says. It means they’ll have to stay on track, making sure they eliminate their debt.

Maybe that’s why more and more Americans are taking out loans.

“More consumers than ever are seeing value in a personal loan,” said Jason Laky, senior VP of consumer lending at TransUnion, “whether for debt consolidation or home improvement finance.”

Mike Brassfield (mike@thepennyhoarder.com) is a senior writer at The Penny Hoarder. Can you loan him some money?

Enter Your Info Below to See Your Rates

Apply for a personal loan online through our new personal loans marketplace powered by our trusted partner Fiona.


This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.

The Penny Hoarder Promise: We provide accurate, reliable information. Here’s why you can trust us and how we make money.


source The Penny Hoarder https://ift.tt/2FBbNTE

This Company Offers Life Insurance That Actually Responds to Your Changing Needs


Pop quiz time. What do you think about when you think about buying life insurance?

Time’s up! Did you think of pushy salespeople? Or maybe your mind went to the dreaded thought of getting locked into a 20-year policy that isn’t right for you even five years down the road.

Your life is constantly changing, and that’s a good thing. What you really want is life insurance that can change along with you.

According to the Insurance Information Institute, an independent resource for information on all things insurance, 44% of consumers overestimate the cost of life insurance, and more than half of them say they’d get it if they could just get it priced without a physical exam.

If you think you’re ready for a term life insurance plan to help protect your family, check out Ladder. You’ll find that you can get life insurance that is easy to get and easy to change when your life takes a new path.

My Life Changes. What About My Policy?

One of the hardest parts about choosing a life insurance policy is trying to figure out just what kind of policy is the best fit for you and your life. What if you sign a 15-year policy and your life situation changes?

People get married, buy houses, have kids and then, eventually, those kids move out and do their own thing.

Ladder gets it. Your life is dynamic, and your life insurance coverage should be able to change with it. That’s why it offers flexible coverage.

Sign up for the coverage you need, but when your life takes a new path, Ladder lets you add more or even reduce your coverage without dealing with high-pressure agents or even tedious paperwork.

Back up — What Is Term Life Insurance?

Simply put, term life insurance is a life insurance policy that pays out a benefit upon the death of the policy holder. The policy is purchased for a certain term, for example 10 or 20 years, and the policy holder can choose to renew their policy once it expires.

The biggest determining factors in the cost of a term life insurance policy are the amount of coverage (the amount left to the family) and the age, gender and health of the person insured.

The primary benefit is the ability to leave money for loved ones for things like funeral and living expenses.

For example, imagine a man who is 35 years old, married and has two kids. He may choose to purchase term life insurance. If he should die unexpectedly, the insurance policy would leave a predetermined amount of money to his wife and kids to help pay funeral costs. It would also help them get by without his income, so they could continue to pay their bills, stay in their home and continue their education.

Keep Life Simple

You can use Ladder’s coverage calculator to figure out how much coverage you should have. Then your online application only takes a few steps:

  • Take about five minutes to answer a few questions about your life and health, such as your income.
  • You’ll get an instant decision on coverage, and there’s no risk. You won’t even have to go get a full physical. Some simple lab work might be required, but that’s easy, right?
  • You’ll need to enter your driver’s license and social security number, which is true for any life insurance application. The company needs this information to verify your identity and prevent fraud,. It uses a secure website and will not sell your private information.
  • You’ll pay no policy fees, and you can cancel anytime. You even get a 30-day money-back guarantee.

Your life is full of changes. Make sure your life insurance can change with you.

Life can be hard, and making decisions about it can seem even harder. Ladder makes life insurance easy to get and easy to change.

Tyler Omoth is a senior writer at The Penny Hoarder who loves soaking up the sun and finding creative ways to help others. Catch him on Twitter at @Tyomoth.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.

The Penny Hoarder Promise: We provide accurate, reliable information. Here’s why you can trust us and how we make money.


source The Penny Hoarder https://ift.tt/2A9xnbP

Best Personal Finance Software

Managing your money isn’t easy, so it’s no wonder that only 41% of Americans have a budget, according to the National Foundation for Credit Counseling.

A budget is the most fundamental financial planning tool out there, and with one, you’ll have a better chance of reaching your short- and long-term financial goals. And if the “b word” makes you bristle, don’t worry: The best personal finance software can make it surprisingly painless.

“Online banking is a great tool to pay bills and reduce paper statements,” says Dan Crimmins, New Jersey-based financial coach at Crimmins Wealth Management. “However, it cannot establish a budget or categorize your expenses. A financial tracking software gives you the ability to review how you are spending your money.”

Several personal finance apps and websites can help you plan and keep track of your spending. No one service is best for everyone, though, so it’s important to compare several options to find the one that works best for you.

To help, we’ve put together a list of the top three personal finance software options and how they can help you achieve your goals.

Best Personal Finance Software: The Simple Dollar’s Top Picks

  • Mint: Comprehensive, free, and easy-to-navigate software; great for beginners.
  • You Need a Budget: Hardcore budgeting for people who want to know where every dollar is going.
  • Albert: Does a lot of the legwork for you and provides you with timely and actionable advice.

Mint

Mint has more than 20 million users, and it’s easy to see why. For starters, the software is free to use, and it automatically syncs your financial accounts so you can budget and track your spending all in one place.

Budgeting isn’t the only service Mint offers, though. You can also:

  • Monitor your Equifax credit score.
  • Stay on top of your bills.
  • Track your investment accounts.
  • Get alerts when you’re being charged fees or going over budget.
  • View your home’s value (courtesy of Zillow) and track your overall net worth.

For budgeters, Mint’s most valuable feature is its automatic syncing. Just sign into your bank and credit card accounts through Mint’s platform, and you’ll get updates on each account every time you make a transaction.

When transactions come through, Mint will automatically categorize them based on their details. If the assigned category is wrong, you can update it and even split transactions into more than one category online or on the mobile app.

Based on your spending, Mint will also create a budget for you. But as with the transactions, you can customize your budget based on your needs and spending habits.

If you want a bird’s eye view of your spending habits, Mint has a Trends feature that shows you how you’ve spent your money by category over a set period. You can also compare two periods to see how your current spending compares with spending in the past.

While the service is free to use, Mint makes its money by recommending targeted financial products to its users. Depending on your tolerance for such ads, it can be frustrating to feel bombarded with the unsolicited advice.

“Most free financial softwares make money by providing product recommendations or having advertisements within the software or app,” says Dominique Broadway, CEO and personal finance expert at Finances Demystified.

Mint is a great option for:

  • Beginners who are overwhelmed with the idea of budgeting.
  • Hands-off budgeters who want everything in one place.
  • People who don’t mind the ads.

You Need a Budget

You Need a Budget, or YNAB for short, is an intensive budgeting software with the goal of giving every dollar a job. The software is also designed to help users get out of the paycheck-to-paycheck cycle and live off of the previous month’s income.

When you first sign up, YNAB provides you with some general budgeting categories to start with, like Rent/Mortgage, Electric, Groceries, and other essential expenses. You can add or change categories based on your spending habits.

As you continue setting up your budget — either online or with the mobile app — you can add individual accounts and clarify whether each is a budget account or just an account you’re tracking, such as an investment account or auto loan.

While YNAB allows you to connect your financial accounts for automatic transaction importing, it doesn’t require it, allowing you to choose how hands-on you want to be.

As you use YNAB over time, you’ll have access to a few reports to help you make better financial decisions:

  • Spending report: This gives you a snapshot of how much you’ve spent in each category over a set period. You can also view how your spending in each category has changed over time.
  • Income and expenses report: With this report, you’ll get a detailed breakdown of every source of income, plus exactly how much you spent in each category by month.
  • Net worth report: You’ll not only get to see what your current net worth is but also how it’s changed over time. This is valuable because your net worth is a good measure of your overall financial health.

If you have a specific financial goal you’re working toward, you can monitor your progress using YNAB’s goal tracking feature. Choose a target balance or a monthly funding goal, and the software will track your progress and give you some tips along the way.

In addition to giving you a platform to budget, YNAB also offers free, live workshops to give you advice on budgeting, paying off debt, saving and more.

The biggest drawback to YNAB is that it’s not free. When you first sign up, you’ll get a 34-day free trial. But after that, you’ll pay $83.99 per year, which comes out to about $6.99 per month.

YNAB is a great option for:

  • Experienced budgeters who want a more hands-on approach.
  • People who like to analyze their spending using reports.
  • People who don’t mind paying for budgeting software.

Albert

If you prefer mobile over using your computer, both Mint and YNAB have mobile apps. But with Albert, all you get is a mobile app.

Like the other software we’ve listed, Albert allows you to connect your financial accounts when you first get started. From there, though, it does most of the work for you.

For starters, the app will automatically create a budget for you based on your spending, bills, and income. You’ll also get a personalized financial plan, which can help you spot ways to save more and meet other financial goals. If it spots something out of the ordinary, you’ll get an alert.

If you opt in, Albert will automatically set aside a portion of your money into a savings account each week based on what it thinks you won’t miss. Albert even helps you negotiate your bills, which can save you money on ongoing monthly expenses like your phone, cable, security, or other bills.

If you want more personalized service, you can sign up for Albert Genius, which allows you to text the app’s human financial experts and get advice. There’s a fee for this service, but Albert allows you to choose how much to pay. According to its website, most customers pay $6 per month or more for the Genius service, while the minimum cost to operate it is $4 per month.

Albert is a great option for:

  • People who want to make better financial decisions but don’t have the time or desire to do it all alone.
  • Budgeters who want to automate every aspect of their financial lives.
  • People who like the idea of getting personalized advice whenever they need it.

How to Pick the Best Personal Finance Software For You

The best personal finance software is easy to use and helps you improve your money management. But with so many options out there, no single app or website is best for everyone.

As a result, it’s important for you to research these and other options and pick one that best serves your needs. Specifically, ask yourself how hands-on you want to be with the process and what kinds of tools and resources you’d need to make better decisions and stick with the program.

If you’re new to budgeting and feel overwhelmed by the process, it may be better to pick software that does a lot of the work for you. On the flip side, if you’re an experienced budgeter and enjoy getting into the weeds, choose an option that gives you more control.

Whatever you choose, expect to put in a bit of time at the outset to get yourself up and running. “Investing time in the initial setup is crucial to having the system work for you,” says Crimmins.

After you get started, you may think your work is done. But the real challenge becomes checking in with your budget software regularly, even if the app does most of the work for you. “Once you’re all set up, make sure you actually look at the software,” Broadway explains. “Many people will take the time to set it up and never look at it again.”

Most importantly, it’s crucial to understand that while the best personal finance software can help you make better decisions, it won’t, by itself, change your habits. As you take advantage of the different tools and resources available to you, use them to help you develop better spending and savings habits — so that eventually, making wise spending choices and sticking to a budget becomes second nature. It can take some time, but it’s time well spent.

Related Articles:

The post Best Personal Finance Software appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2Aba3dP

'Keep the Faith': Trump Admin Confident About Economy Despite Big Stock Losses

Stocks plummeted across the board yet again on Tuesday, dropping 551 points, wiping out all the gains the market made in 2018.

Source CBNNews.com https://ift.tt/2Dz3UeO

Don’t Get Scammed on Black Friday: How to Identify Deals vs. Duds


If you wake up at 3 a.m. to line up in front of Walmart or combat your turkey coma to spend an hour propped up in bed clicking around Target’s website, it’s for a good reason.

Even if your spouse looks at you strangely from the other side of the mattress, you know you’re getting the best deal possible on something you need and would buy anyway. (Because that’s the only reason you’re spending money on Black Friday, right?)

These deals aren’t going to repeat themselves, and they’re too good to miss… Or are they?

Not Every Black Friday Deal Is a Bargain

Turns out, maybe not.

While some Black Friday deals are unbeatable, some are just OK. You might already be able to get an item for the sale price, or cheaper, on Amazon.

Some vendors even have the items listed at the same discounted price in stores right now. But in the Black Friday ads, they list the MSRP (manufacturer’s suggested retail price) in bright red to inflate savings percentages. More like MSRPointless.

In fact, many “deals” are actually complete rip-offs: Did you know some companies create custom items just for Black Friday sales? And I don’t mean exclusive limited editions.

Some retailers flood their sales floors with “derivative products” that look like the real deal. Think TVs with screens with fewer pixels or computers with slower processors.

“Black Friday is about cheap stuff at cheap prices,” DealNews.com’s CEO, Daniel de Grandpre, told BankRate in 2015. Manufacturers can make these slightly less-awesome items more cheaply and sell them at a jaw-dropping discount. They get consumers in the door, but burden them with subpar stuff.

Even the good deals aren’t necessarily “one time only.” If you think you’re seeing the same Black Friday deals year after year, you probably are. Retailers rerun the same (or even better!) deals each year — which means waiting an extra year might save you a few extra bucks, due to inflation and a potentially lower sale price.

How to Spot the Best Black Friday Deals

So how do you know if it’s a deal or a dud?

Know the Likely Suspects

It turns out there are some noticeable trends regarding which deals are bogus. (Notice the same things popping up from year to year.)

Doorbuster TVs, tablets and laptops are more likely to be derivatives with fewer HDMI ports or lackluster specs, and tools for Dad are offered at a better discount in June.

Seasonal items, like winter clothing and decorations, or easy and popular gifts, like chocolate, flowers or vacation packages, also won’t be as steeply discounted. Vendors know you need those items right now and are willing to pay for them.

Beware of Repeat Deals

Need a new cookware set? I bet Rachel Ray’s 20-piece set is going to be available this year for $89. Just an educated guess.

Before you pull out your credit card, check last year’s ads, Amazon or current in-store prices for the item you’re eyeing — is that Black Friday deal really so special?

Creating pressure to purchase right now is a standard psychological trick in the sales industry. How many “limited-time offers” are still on infomercials three years later? Ever been subject to a landlord’s claim that the potential next tenant is coming with cash in hand, so you’d better sign now?

Keep informed and shop around. That knowledge could mean cash in your pocket.

Check the Model Number

Want to make sure that new laptop is really the one you want? Check the model number.

Manufacturers may create new derivative products for Black Friday, but they have to use a unique model number to differentiate the product. Those numbers can’t lie.

Check Reviews

If you’re like me, you exhaustively — or annoyingly — check reviews every time you purchase anything, even a lamp or a dress. I check reviews before I go out for ice cream.

You should probably not try to be like me.

But when it comes to Black Friday, reviews are your friend.

Before you blindly buy the laptop or TV at the biggest discount — you know, the one proudly displayed on the first page of the flyer — check its reviews online. Even a great sale price is too much to pay for a bad product.

Plus, if there are no reviews or the product doesn’t exist yet, that’s a good hint (though no guarantee) the item might be a derivative.

Avoid Rebates… or Make Sure You Actually Use Them

That bold-print sale price might have a fine-print catch: It might include a mail-in rebate. Or maybe the discount isn’t that great, but the purchase of a specific item comes with coupons or gift cards for future use.

Of course, we Penny Hoarders love rebates, cash-back sites, free gift cards and other easy ways to save a few bucks.

But vendors love them for a different reason: Research has shown that statistically, you’re unlikely to follow through with mailing in a rebate. They get the marketing benefit of a shocking sale price with none of the profit cut.

So make sure you’re taking retailers up on those well-advertised offers! If you know you’ll probably forget, skip these deals in favor of regular, discounted prices.

Be vigilant this season, and make sure your Black Friday deals are worth your while. Anything less is a waste of time and money.

Jamie Cattanach is a writer whose work has been featured at The Write Life, Word Riot, Nashville Review and elsewhere. Find @JamieCattanach on Twitter to wave hello.

This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.

The Penny Hoarder Promise: We provide accurate, reliable information. Here’s why you can trust us and how we make money.


source The Penny Hoarder https://ift.tt/2Qj77WJ

These 13 Holiday Gift Ideas Make Personal Finance Fun for Kids

Intentionality

I absolutely love hot sauce.

I put hot sauce on everything. If it’s savory and I have some hot sauce around, I’ll put hot sauce on it. Pizza. Burritos. Scrambled eggs. Grilled vegetables. Beans and rice. All of it gets hot sauce.

Even dishes where you wouldn’t expect hot sauce are dishes where you’ll often find me doling out the hot sauce. I have a savory oatmeal recipe that I often make for myself in the mornings that I consistently add hot sauce to (it’s not sweet at all – much different than the pre-sweetened oatmeal packets from the store).

There are many times where my love for hot sauce has become so routine and automatic that I just put hot sauce directly on things without even really thinking about it. That can backfire if someone has already put some in the dish before serving it, which makes the dish extremely spicy. Sometimes, it can result in me not really appreciating the dish itself because I just drown it in hot sauce without even really considering the food itself.

In those moments, I’m operating pretty much on autopilot. If I see a savory dish, I reach for the hot sauce almost without thinking about it.

Sometimes, however, I’ll find myself at a restaurant where there’s no hot sauce available, or I’ll find myself at the dinner table and we’re out of hot sauce.

It’s in those moments that I eat am meal without it being slathered in hot sauce… and, usually, I end up discovering that I quite like the flavor of something when it’s not bathed in hot sauce.

In recent months, I’ve even chosen not to put hot sauce on a lot of meals that I once smothered with the stuff.

It turned out that somewhere along the line, my use of hot sauce had gone from an active decision to something I did on pure autopilot.

Of course, it’s not just hot sauce. There are many, many, many things that I do – and that we all do – that were once decisions that were taken so regularly that they gradually moved to a state of “autopilot.” It’s no longer really a decision – rather, it’s just something you do in a given situation without thinking.

I see a savory meal in front of me. I drown it in hot sauce. There wasn’t even really a decision making process there.

Autopilot mode has its advantages. It basically subtracts an active decision away from our busy lives so that we don’t run into decision fatigue too quickly, theoretically saving our actual decisions for something more important.

The problem is that autopilot mode can easily run amok, as with my hot sauce usage. You start relying on it for things like buying a coffee on your way to work or going out to eat instead of making food at home and before long, it’s adding up to a pretty hefty expense. It’s taking away from other things you might enjoy. It’s putting pressure on your financial life.

And, yet, autopilot kind of blinds you from the consequences. You’re doing something automatically that’s worked for a long time, so it seems like this thing should be “safe.” The troubles must be coming from elsewhere. You don’t even put that “autopilot” decision on the table when looking at things to change.

That’s where intentionality steps in.

Intentionality is the power of the mind to direct itself toward that which it finds meaningful and take action toward that end. It’s essentially the opposite of autopilot. It’s all about having a clear purpose for every action that you take, one that you can clearly explain.

Do you know why you’re doing what you’re doing? That’s the question that intentionality is always asking you.

I find that taking an intentional approach to the things I’m doing – really focusing on what I’m doing with each step and why and only doing it if it’s sensible and justified – melts away a lot of spending and helps me discover new things in life.

Being intentional let me really enjoy the flavor of several dishes that I hadn’t really considered in years, just by backing off the automatic hot sauce.

Being intentional causes me to order less food when I go out to eat, choosing a small portion rather than a regular one, which is less expensive and healthier for me (and less likely to waste food).

Being intentional means that I don’t go to the coffee shop or stop by any coffee kiosks that often, because I think about whether I really want that coffee and it’s usually the most fleeting of desires. I’m better off money-wise and health-wise to just keep going.

Being intentional isn’t really that difficult. It just means really thinking about everything you’re doing and taking your time with it. Stop and ask yourself why you’re doing this, or why you’re doing that. Is it a really good reason? Or is it just something you’re doing on autopilot?

I find that being intentional with my actions usually leads to me “undoing” some of my worst autopilot decisions. If I’m being carefully intentional about what I’m doing and I bump up on an autopilot decision that really isn’t a good choice, I’ll not only make a different choice in that moment, but I’ve usually smashed down that autopilot decision (or taken a big step toward doing so).

The thing is, once I intentionally knock down an “autopilot” decision a few times, it ceases to be an autopilot decision. It moves back into a conscious decision, and if I’ve already recognized it’s a bad one, I’m often choosing “no.” Often, it begins to fade completely into the background of an option I don’t even consider, like when you’re walking by a bunch of stores on the way to your destination and you don’t actually even consider going into them.

Simply being very intentional about your actions is a powerful personal finance strategy, but it’s difficult to do constantly, if for nothing else the decision fatigue factor. Making decisions is like a muscle – you can make it stronger through certain practices, but it still gets tired and needs rest, and it’s through being automatic about a lot of our decisions that we have the mental energy to make good decisions sometimes.

So, what can we do about this? How can we use intentionality to break down some of our worst automatic decisions to live a financially, physically, and emotionally healthier life? Here are some things that I personally do.

Be intentional at certain moments. Try to be intentional at the grocery store, for example. Think carefully about every decision you make when you’re there rather than just throwing the old familiar items into the cart. Be intentional when you’re going out to eat so that you choose a healthy meal that’s appropriate for your hunger level and don’t spend money on relatively thoughtless decisions. Make a point to be careful and intentional at those moments when you might be spending money, and then let it rest afterwards.

Be intentional about everything for short periods of time. I often practice this for short periods in everyday life, just to get used to it. I’ll just be very intentional with my choices for, say, 15 minutes. I’ll try to think carefully and live in the moment with literally everything I do for 15 minutes.

Practice good “mental hygiene.” This is kind of a catch-all term I’ve started to use for things like getting a good night of sleep, writing in my journal, meditating, and trying to get in a flow state when working. Doing those things tends to decrease my overall decision fatigue, making it easier to be intentional about the things you’re doing.

Autopilot decisions are incredibly helpful in getting us through everyday life, but it can lead us into routines that actually work against what we want most out of life. Being intentional about our choices, even over short periods, can reveal poor autopilot decisions and give us an opportunity to fix them.

Good luck!

More by Trent Hamm:

The post Intentionality appeared first on The Simple Dollar.


Source The Simple Dollar https://ift.tt/2qWp0vQ

In Denial About Your Finances? 8 Steps to Face Reality — Painlessly

How to invest in artificial intelligence

Artificial intelligence

Artificial intelligence is dramatically transforming our lives, by learning to perform tasks that hitherto required human intelligence

It is filtering into all areas of work and life, and is emerging as one of the mega trends of the coming decades.

But how do investors get involved? There are both actively managed and cheaper passive funds available that invest in AI technology.

However, the opportunities still come with a high level of uncertainty and, as well as the possibility of strong gains, you could lose money. AI should only be a small proportion of your investment portfolio for most people and should not be money that you can’t afford to lose.

While change is happening at an almost frantic pace, it still can’t be viewed as a get-rich-quick scheme.

As John Gladwyn, investment manager at Pictet Asset Management, explains: “We are long-term investors and encourage investors seeking exposure to these markets to take a long-term view; it will take a long time for these mega trends to play out fully.”

From PAs, such as Siri, to self-drive cars, AI is already changing our lives

Investing in different types of AI

Researchers at the cutting edge of AI are working on ‘general AI’, which aims to develop intelligent computers that can think and plan across broad areas, teaching themselves just like humans.

Yet the most promising near-term uses are in ‘narrow AI systems’ such as stock-trading algorithms.

Its uses are growing fast. IDC, a US Market intelligence firm, forecasts cognitive and AI spending will grow to US$52.2 billion in 2021, achieving a compound annual growth rate of 46.2% over the 2016-2021 period.

Sheridan Admans, investment manager at The Share Centre, says: “Artificial intelligence systems are becoming entrenched, operating silently in the background… From personal assistants such as Siri to self-driving cars, AI – which is often depicted in fiction as taking on a human form – today manifests itself as search algorithms, such as those used by Google, news generation often referred to as ‘news bots’, medical diagnoses and minimally invasive prostatectomies,plus cybersecurity and autonomous weapons systems.”

AI funds

For those investors seeking to profit from this nascent technological revolution, probably the safest way is via a collective investment vehicle. In recent years, a number of funds have been launched that provide explicit exposure and some diversification in what is still a very high-risk area.

One such fund identified by Ms Admans is the Pictet Robotics fund, which was launched in 2015.

Senior investment managers Peter Lingen and John Gladwyn jointly manage this fund, and Mr Lingen told Moneywise: “We focus our investments in robotics, automation and AI, and we are extremely excited by the potential of these three markets. Given the breadth of use-case/adoption, we do not want to be constrained to the traditional tech sector, parts of which address legacy end markets.

“Similarly, we also want to have breadth across our investment universe so that if one area becomes overheated we are able to allocate assets away from this area into investments where we see better return potential.”

While the fund holds some stocks that could be found in most tech funds, one that isn’t to be found in many and yet offers exposure to AI is Siemens Healthineers.

“Healthineers is a market leader in imaging, diagnostics and advanced therapies. Its new Atellica Solution is leading the automation of the diagnostic lab. Furthermore, Healthineers is taking advantage of its unique position to enable ‘algorithm-supported solutions’, which will both improve patient outcomes and help reduce costs in healthcare,” says Mr Lingen.

An AI-badged fund was launched by Smith & Williamson in June 2017 and, unsurprisingly, its manager Chris Ford is keen to stress the advantages of a specialist AI-focused fund.

“A traditional technology fund will be somewhat hidebound within the sector it is designed to invest in, and as a result is probably missing out on the AI opportunities that exist in sectors such as consumer services, healthcare, energy, financial services and industrials,” he says.


Change is at a frantic pace, but it’s not a get-rich-quick scheme

Offering some exposure to ‘narrow’ AI, AXA Framlington has a Robotech fund that was launched in February 2017, run by Tom Riley. It offers exposure to a robotics market that is estimated to grow 10% to 15% a year until 2025, with what it claims is “a focus on the investable area of the robotics market such as industrial automation, robotics-assisted surgery, driverless vehicles and the underlying intelligence that supports robotic technologies”.

Most recently, Polar Capital also launched an AI-themed fund in October 2017.

The Polar Capital Automation and Artificial Intelligence fund, is run jointly by Ben Rogoff, Nick Evans and Xuesong Zhao. With approximately £350 million funds under management, it is dwarfed by the £1.9 billion Polar Capital Technology Trust, also run by Mr Rogoff, whose share price is up by approximately 1150% over the past 10 years.

Mr Rogoff admits to being hugely excited by AI, but cautions: “I think that for the bulk of the decade to come AI will remain narrow in focus and will be used primarily to augment human decision-making,” he says.

“The exposure in our AI fund today is largely limited to the technology enablers, primarily in the same stocks that the investment trust will invest in. But the long-term plan is very much that as we can identify companies that benefit from AI, we can buy those companies within it. While cloud computing and ubiquitous mobile internet have been core themes within our portfolios over the past decade, we expect adoption of AI to be the driver of the next technology cycle – although we are early in the adoption cycle,” he adds.

Mr Rogoff’s funds hold companies that are enabling AI, such as Nvidia and Xilinx, which are computer-chip companies, and Google, Amazon and Microsoft, which are providing platforms for other companies to access neural networks (computer systems modelled on the human brain and nervous system).

One more general technology trust that Mr Admans suggests for exposure is AXA Framlington Global Technology, which is in The Share Centre’s preferred range of funds. Run by Jeremy Gleeson, it numbers among its top three holdings Alphabet, Apple and Facebook.

Passive investing

For those willing to invest in AI via an exchange traded fund (ETF – a fund that can be bought and sold like a share), there are a couple of options cited by Mr Admans.

“Investors with a preference for index trackers might consider the iShares Automation & Robotics ETF, which seeks to track the performance of an index composed of developed and emerging market companies that are generating significant revenues from specific sectors associated with the development of autonomous and robotic technology.

“Another suitable option could be the GO Units Solutions Robo Global Robotics & Auto (ROBG), which tracks the performance of the ROBO Global Robotics and Automation UCITS Index.”

Chris Menon is a financial journalist and runs the investing blog Safestocks.co.uk

Section

Free Tag

Twitter


Source Moneywise https://ift.tt/2OQckQV